
Subjective Real Estate Valuation G. Jason Goddard

Description: Subjective Real Estate Valuation G. Jason Goddard Chapter 9 Outline Chapter Highlights Types of Mortgage Backed Securities Residential MBS and Subjectivity Commercial MBS and Subjectivity MBS and Investor Preference Chapter Definitions
Related Topics
Download Presentation
"Subjective Real Estate Valuation G. Jason Goddard" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Subjective Real Estate Valuation G. Jason Goddard<br>
slide3. Chapter 9 Outline Chapter Highlights
Types of Mortgage Backed Securities
Residential MBS and Subjectivity
Commercial MBS and Subjectivity
MBS and Investor Preference<br>
slide4. Chapter Definitions Agency Guarantees: external credit enhancement for mortgage pools where the government explicitly or implicitly guarantees the credit offering.
CDO: Collateralized Debt Obligation
CMBS: Commercial Mortgage Backed Securities.
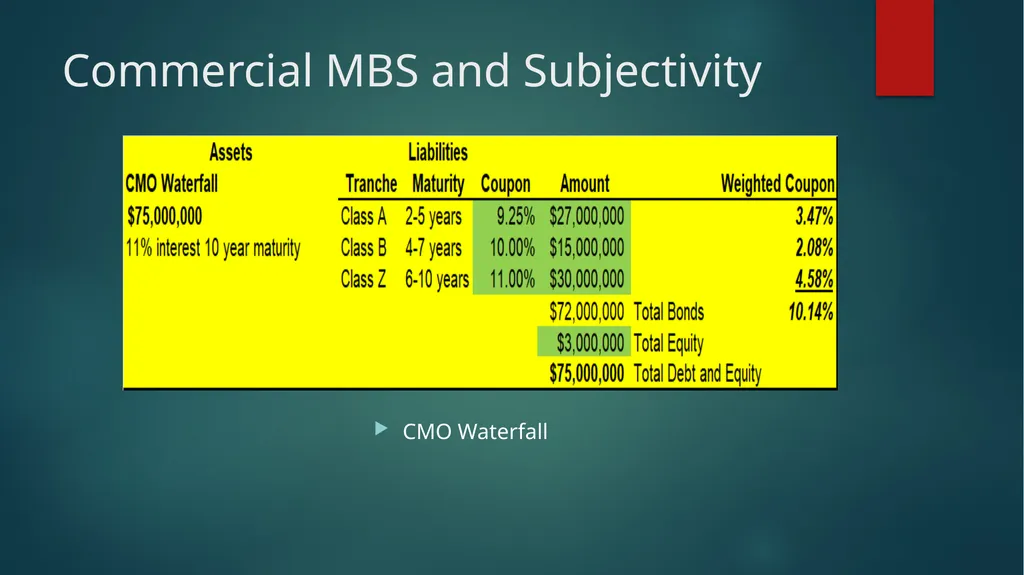
Collateralized Mortgage Obligation (CMO) – A mortgage-backed security that generates separate cash flows for different classes of securities called tranches. Tranches have varying loan maturities and prepayment risks and offer varying expected returns for investors.
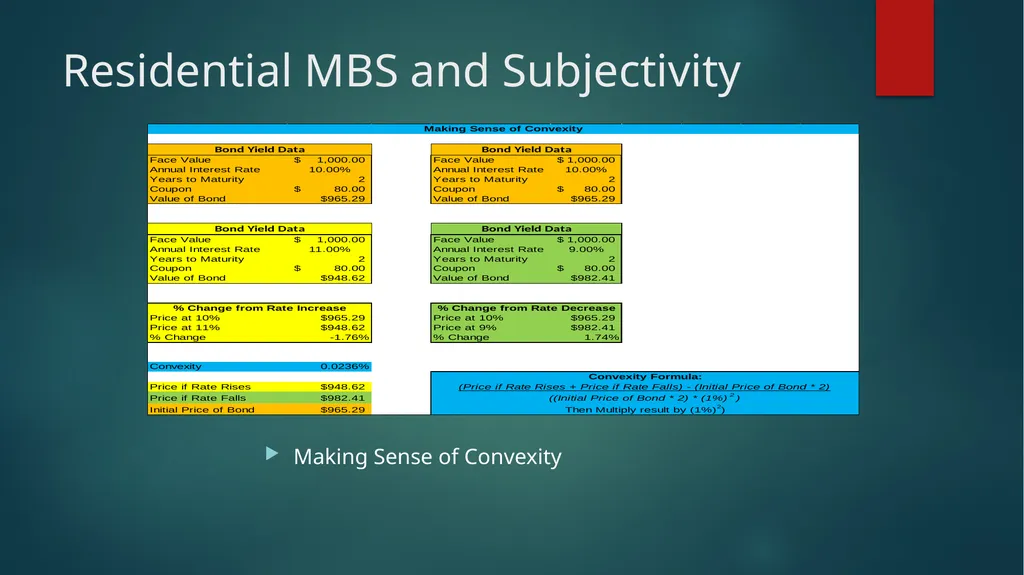
Convexity: Measure of the non-linear relationship of bond prices to changes in interest rates.
Covered bonds: Securitization model utilized in Europe and Asia whereby the lender keeps the loans on their balance sheet and has the flexibility to change the loans within the portfolio which is eligible for investment.<br>
slide5. Chapter Definitions Credit Enhancement: Techniques used to improve the creditworthiness of a borrower.
External Credit Enhancements: Techniques used to enhance a borrower’s, or securitization structures creditworthiness that involves third party guarantees such as a Letter of Credit or Monoline Insurance.
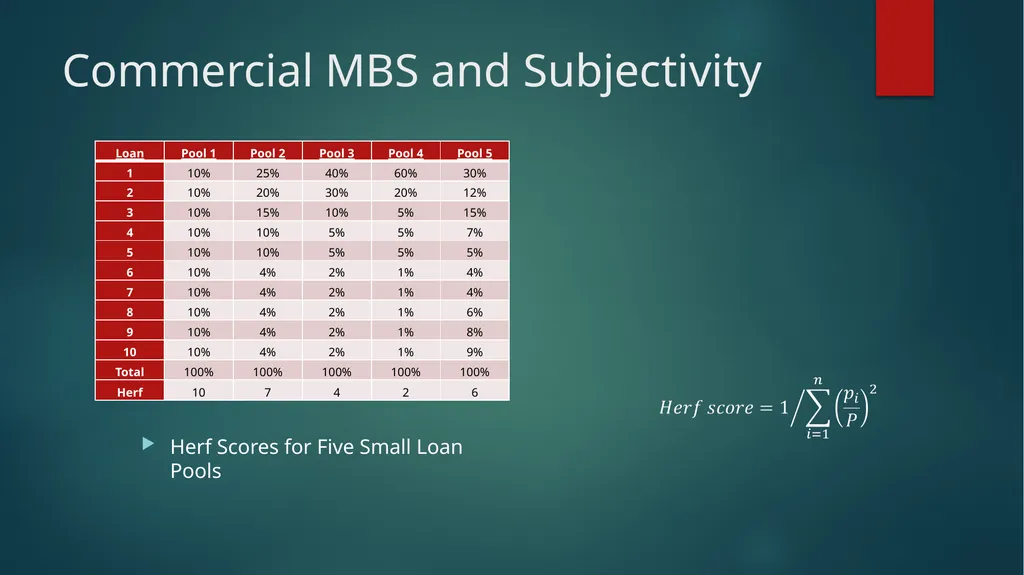
Herfindahl Index: effective loan count concentration measure in CMBS; also known as Herf score.
Internal Credit Enhancements: Techniques used to enhance securitization structure’s creditworthiness that involves injections of capital by the securities’ issuer or originator.
Non-recourse financing: Where no personal liability is available to the lender for a loan.<br>
slide6. Chapter Definitions Over-collateralization: An internal credit enhancement technique in which the originator transfers a pool of collateral loans to the SPV that has a higher par value (usually 5 to 10%) than that of the issued securities. This means that the SPV holds a larger pool of assets than would be necessary if the loans in the pool pay as expected.
Private-Label Securities: A mortgage-backed security or other bond created and sold by a company other than a Government Sponsored Enterprise (GSE).The security frequently is collateralized by loans that are ineligible for purchase by Freddie Mac or Fannie Mae.
Real Estate Mortgage Investment Conduit (REMIC): A type of special purpose vehicle, created by the Tax Reform Act of 1986, that holds commercial and residential mortgages in trust and issues interests in these mortgages in the form of securities to investors.<br>
slide7. Chapter Definitions RMBS: Residential mortgage backed securities.
Structural Credit Enhancements: Techniques used by securitizations to distribute risk among Bonds, such that some of them provide protection to those that enjoy a higher priority.
Underwriter: banks, investment banks and brokers that sell the securities in a public offering or place them privately, often retaining a portion of the issuance for their own account.<br>
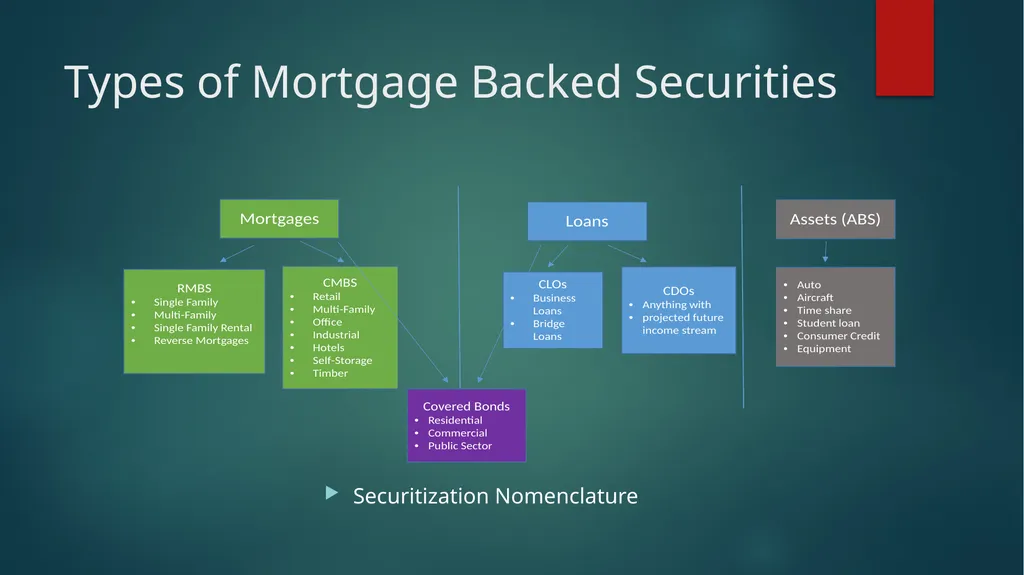
slide8. Types of Mortgage Backed Securities Securitization Nomenclature<br>
slide9. Residential MBS and Subjectivity Agency Guarantees vs. Private Label Issuance
Implied impact on underwriting to achieve agency acceptance
Tranches of various asset class within MBS
Waterfall repayment structure
Mix of regions, property values, and underwriting criterion<br>
slide10. Residential MBS and Subjectivity Making Sense of Convexity<br>
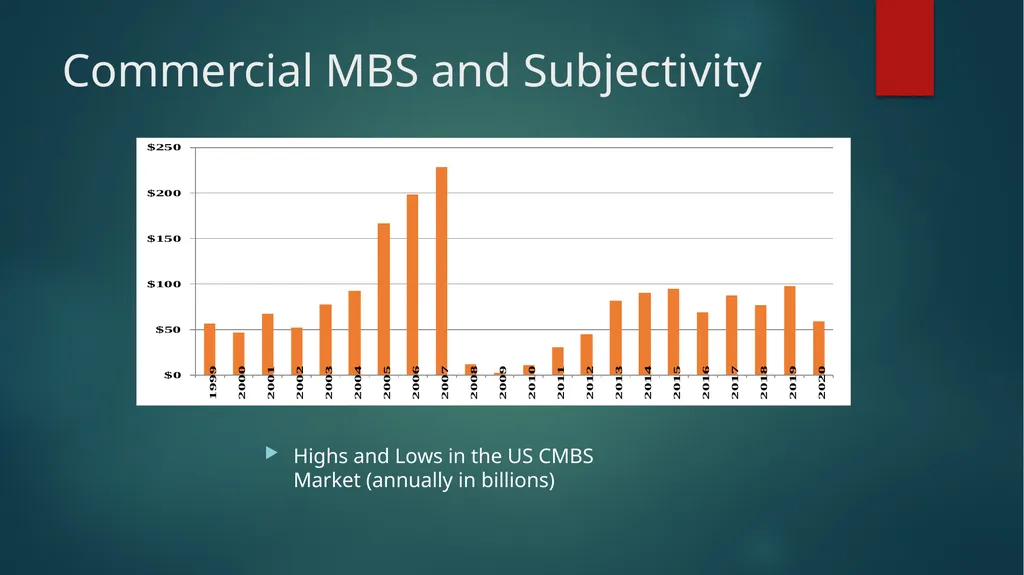
slide11. Commercial MBS and Subjectivity Highs and Lows in the US CMBS Market (annually in billions)<br>
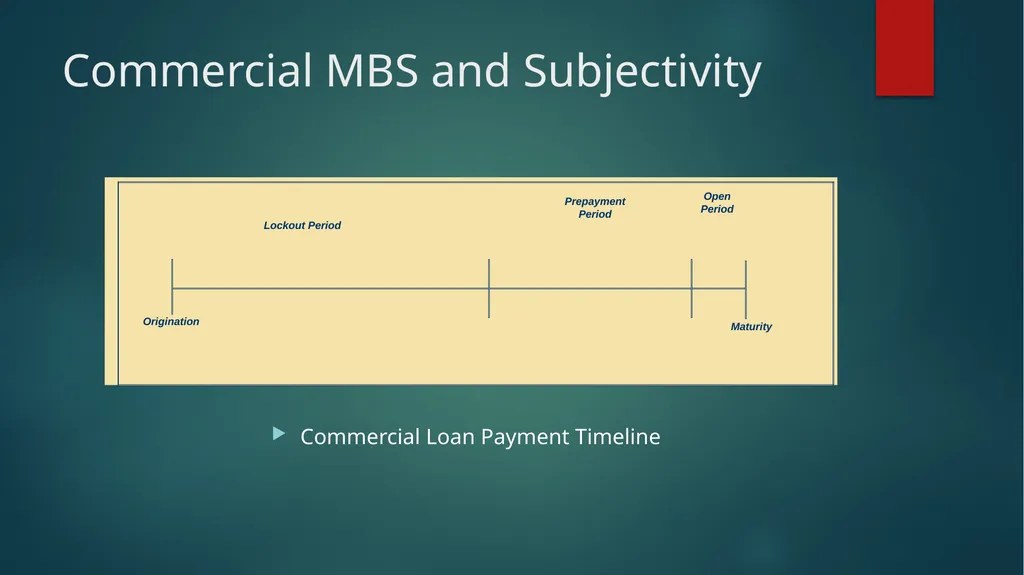
slide12. Commercial MBS and Subjectivity Commercial Loan Payment Timeline<br>
slide13. Commercial MBS and Subjectivity CMO Waterfall<br>
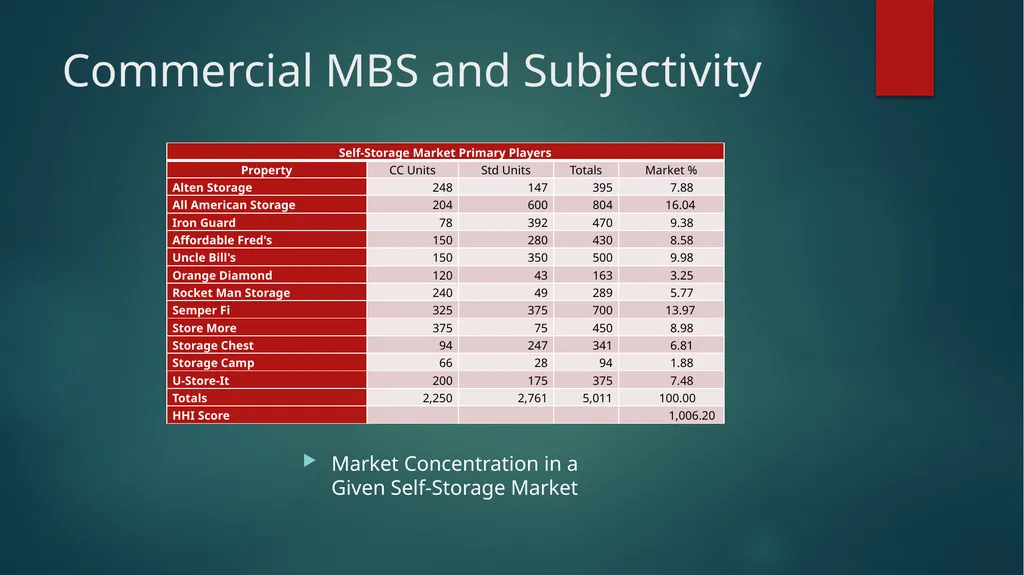
slide14. Commercial MBS and Subjectivity Market Concentration in a Given Self-Storage Market<br>
slide15. Commercial MBS and Subjectivity Herf Scores for Five Small Loan Pools<br>
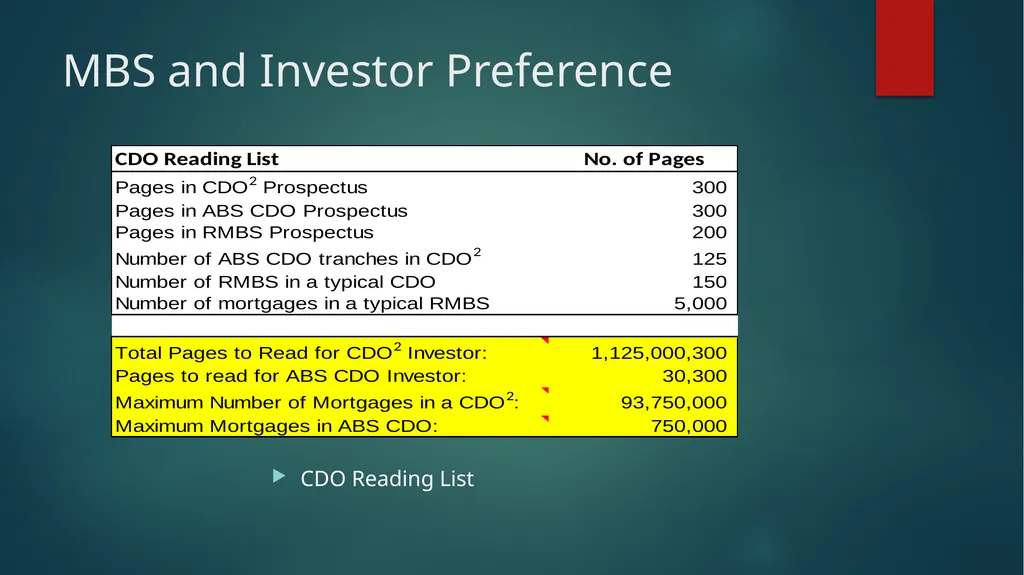
slide16. MBS and Investor Preference CDO Reading List<br>
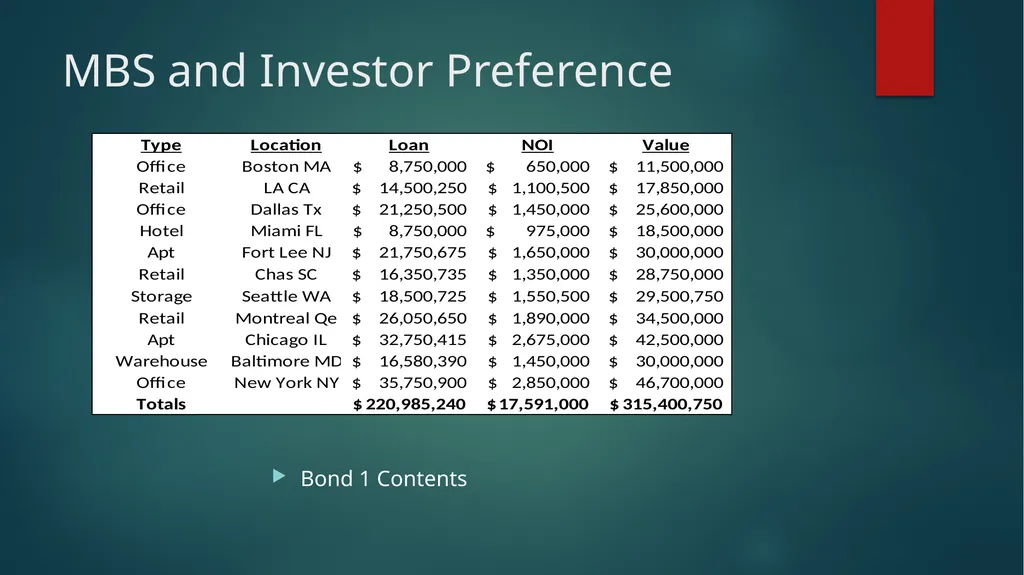
slide17. MBS and Investor Preference Bond 1 Contents<br>
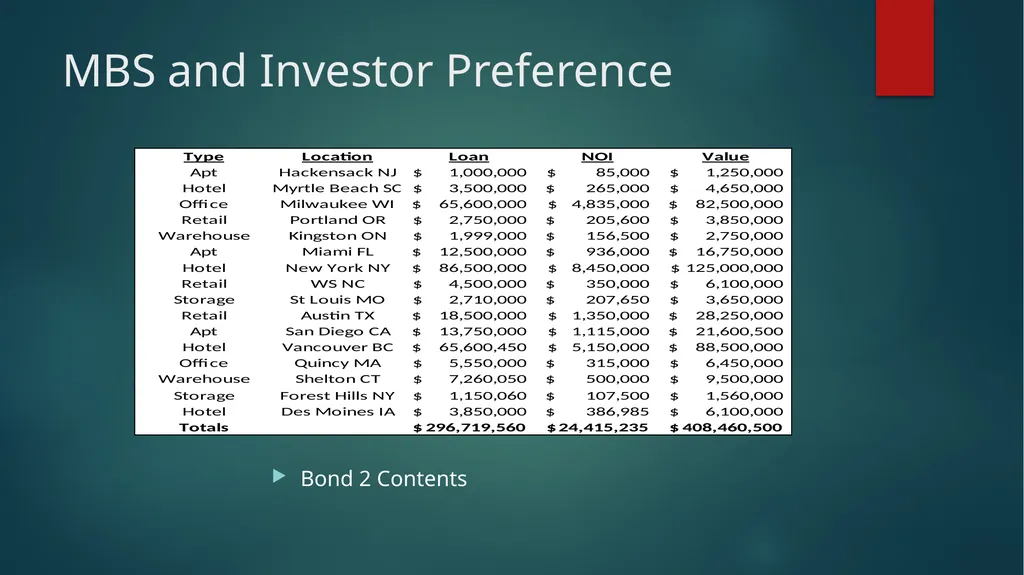
slide18. MBS and Investor Preference Bond 2 Contents<br>
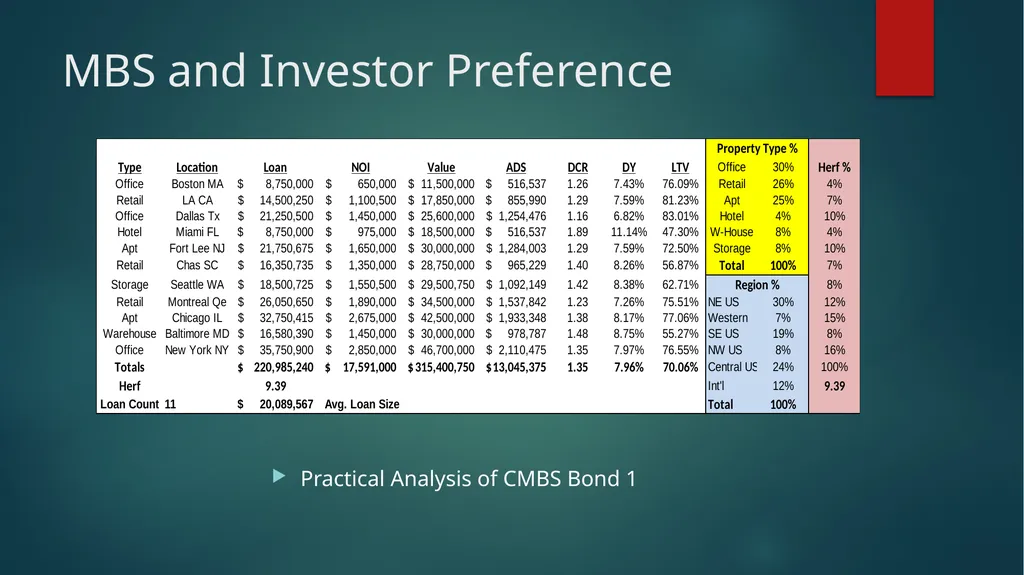
slide19. MBS and Investor Preference Practical Analysis of CMBS Bond 1<br>
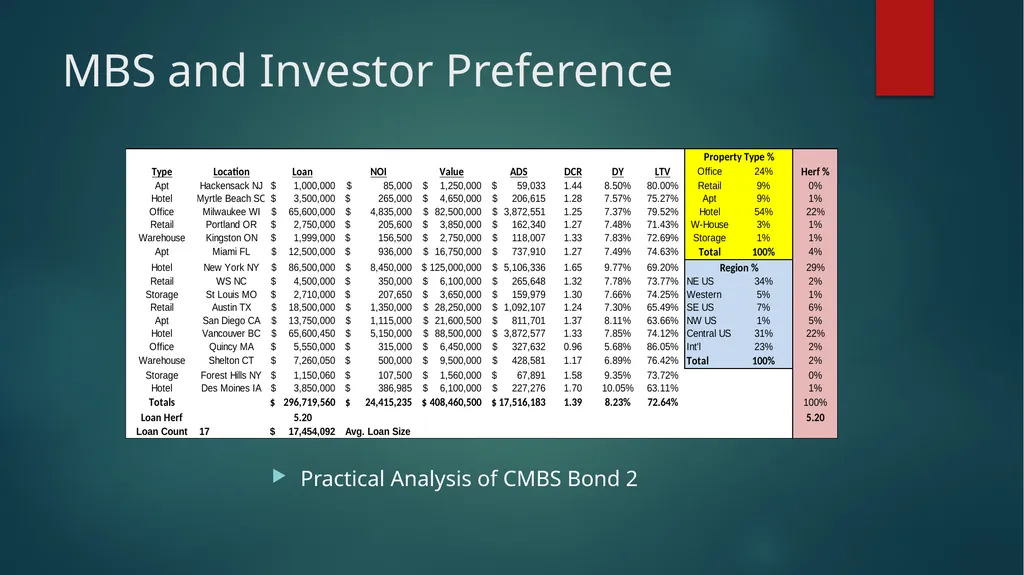
slide20. MBS and Investor Preference Practical Analysis of CMBS Bond 2<br>
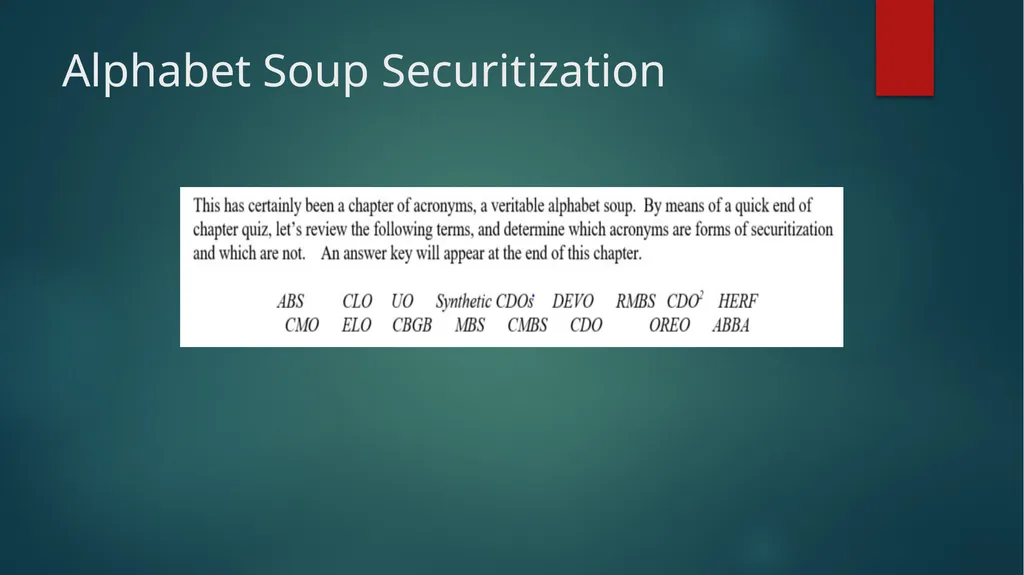
slide21. Alphabet Soup Securitization<br>
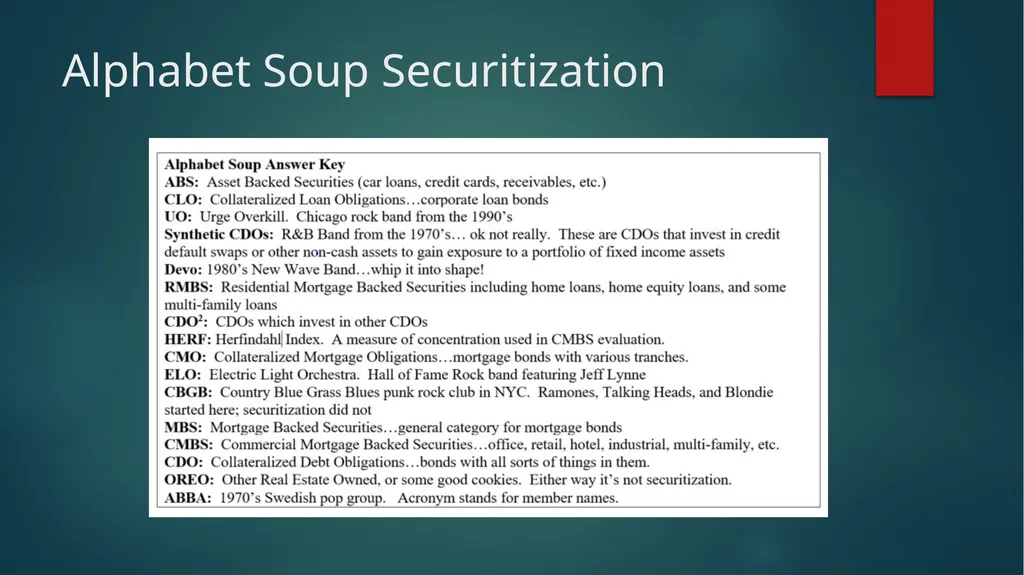
slide22. Alphabet Soup Securitization<br>
slide23. Chapter 9 Questions Questions for Discussion
Discuss the primary differences between RMBS and CMBS loans.
Describe how the Herfindahl Index can be helpful in determining the risk of a mortgage bond pool.
Elaborate on the benefits and pitfalls of pari passu loans within CMBS loan structures.
Explain how did the CMBS structures change after the crash of the market after 2008?
Describe negative convexity and how it might impact RMBS risk assessment.<br>
slide24. Chapter 9 Questions Questions for Discussion
What is a “CMBS vintage” and how can it be used for comparison purposes?
Explain the basic difference between covered bonds and RMBS/CMBS structures.
Outline other areas of finance and economics where the Herf score could be helpful.
Describe the CMO waterfall concept and how it pertains to investor cash flows.
What is an agency guarantee and why are they only present in RMBS vs. CMBS?<br>
slide25. Chapter 9 Market Vignette Questions for Discussion
Would a higher or lower Herf score be desirable from a bond ratings perspective and why?
Discuss the strategy for creating this new CMBS offering. Are there any improvements that you would suggest?
What are some weaknesses of the approach discussed in this market vignette?
What might Daffy and Lucy be missing in their assessment of the large loan exposure being included in the mortgage bond?
What additional questions might you have when contemplating purchasing a mortgage bond?<br>
slide3. Chapter 9 Outline Chapter Highlights
Types of Mortgage Backed Securities
Residential MBS and Subjectivity
Commercial MBS and Subjectivity
MBS and Investor Preference<br>
slide4. Chapter Definitions Agency Guarantees: external credit enhancement for mortgage pools where the government explicitly or implicitly guarantees the credit offering.
CDO: Collateralized Debt Obligation
CMBS: Commercial Mortgage Backed Securities.
Collateralized Mortgage Obligation (CMO) – A mortgage-backed security that generates separate cash flows for different classes of securities called tranches. Tranches have varying loan maturities and prepayment risks and offer varying expected returns for investors.
Convexity: Measure of the non-linear relationship of bond prices to changes in interest rates.
Covered bonds: Securitization model utilized in Europe and Asia whereby the lender keeps the loans on their balance sheet and has the flexibility to change the loans within the portfolio which is eligible for investment.<br>
slide5. Chapter Definitions Credit Enhancement: Techniques used to improve the creditworthiness of a borrower.
External Credit Enhancements: Techniques used to enhance a borrower’s, or securitization structures creditworthiness that involves third party guarantees such as a Letter of Credit or Monoline Insurance.
Herfindahl Index: effective loan count concentration measure in CMBS; also known as Herf score.
Internal Credit Enhancements: Techniques used to enhance securitization structure’s creditworthiness that involves injections of capital by the securities’ issuer or originator.
Non-recourse financing: Where no personal liability is available to the lender for a loan.<br>
slide6. Chapter Definitions Over-collateralization: An internal credit enhancement technique in which the originator transfers a pool of collateral loans to the SPV that has a higher par value (usually 5 to 10%) than that of the issued securities. This means that the SPV holds a larger pool of assets than would be necessary if the loans in the pool pay as expected.
Private-Label Securities: A mortgage-backed security or other bond created and sold by a company other than a Government Sponsored Enterprise (GSE).The security frequently is collateralized by loans that are ineligible for purchase by Freddie Mac or Fannie Mae.
Real Estate Mortgage Investment Conduit (REMIC): A type of special purpose vehicle, created by the Tax Reform Act of 1986, that holds commercial and residential mortgages in trust and issues interests in these mortgages in the form of securities to investors.<br>
slide7. Chapter Definitions RMBS: Residential mortgage backed securities.
Structural Credit Enhancements: Techniques used by securitizations to distribute risk among Bonds, such that some of them provide protection to those that enjoy a higher priority.
Underwriter: banks, investment banks and brokers that sell the securities in a public offering or place them privately, often retaining a portion of the issuance for their own account.<br>
slide8. Types of Mortgage Backed Securities Securitization Nomenclature<br>
slide9. Residential MBS and Subjectivity Agency Guarantees vs. Private Label Issuance
Implied impact on underwriting to achieve agency acceptance
Tranches of various asset class within MBS
Waterfall repayment structure
Mix of regions, property values, and underwriting criterion<br>
slide10. Residential MBS and Subjectivity Making Sense of Convexity<br>
slide11. Commercial MBS and Subjectivity Highs and Lows in the US CMBS Market (annually in billions)<br>
slide12. Commercial MBS and Subjectivity Commercial Loan Payment Timeline<br>
slide13. Commercial MBS and Subjectivity CMO Waterfall<br>
slide14. Commercial MBS and Subjectivity Market Concentration in a Given Self-Storage Market<br>
slide15. Commercial MBS and Subjectivity Herf Scores for Five Small Loan Pools<br>
slide16. MBS and Investor Preference CDO Reading List<br>
slide17. MBS and Investor Preference Bond 1 Contents<br>
slide18. MBS and Investor Preference Bond 2 Contents<br>
slide19. MBS and Investor Preference Practical Analysis of CMBS Bond 1<br>
slide20. MBS and Investor Preference Practical Analysis of CMBS Bond 2<br>
slide21. Alphabet Soup Securitization<br>
slide22. Alphabet Soup Securitization<br>
slide23. Chapter 9 Questions Questions for Discussion
Discuss the primary differences between RMBS and CMBS loans.
Describe how the Herfindahl Index can be helpful in determining the risk of a mortgage bond pool.
Elaborate on the benefits and pitfalls of pari passu loans within CMBS loan structures.
Explain how did the CMBS structures change after the crash of the market after 2008?
Describe negative convexity and how it might impact RMBS risk assessment.<br>
slide24. Chapter 9 Questions Questions for Discussion
What is a “CMBS vintage” and how can it be used for comparison purposes?
Explain the basic difference between covered bonds and RMBS/CMBS structures.
Outline other areas of finance and economics where the Herf score could be helpful.
Describe the CMO waterfall concept and how it pertains to investor cash flows.
What is an agency guarantee and why are they only present in RMBS vs. CMBS?<br>
slide25. Chapter 9 Market Vignette Questions for Discussion
Would a higher or lower Herf score be desirable from a bond ratings perspective and why?
Discuss the strategy for creating this new CMBS offering. Are there any improvements that you would suggest?
What are some weaknesses of the approach discussed in this market vignette?
What might Daffy and Lucy be missing in their assessment of the large loan exposure being included in the mortgage bond?
What additional questions might you have when contemplating purchasing a mortgage bond?<br>