
Unit 3: Valuation Of Fixed Income Securities

Description: Unit 3: Valuation Of Fixed Income Securities Prepared by: Arjun Yadav (Research Scholar) Guided by: Dr. Ambrish (Assitant Professor) Characteristics Of Fixed Income Securities (Debt And Preferred Stock) Meaning: Fixed income securities are
Related Topics
Download Presentation
"Unit 3: Valuation Of Fixed Income Securities" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Unit 3:
Valuation Of Fixed Income Securities Prepared by:
Arjun Yadav
(Research Scholar) Guided by:
Dr. Ambrish
(Assitant Professor)<br>
slide2. Characteristics Of Fixed Income Securities (Debt And Preferred Stock) Meaning:
Fixed income securities are financial claim with promised cash flows of fixed amount paid at fixed dates. Unlike variable income securities, where payments change based on short term interest rates, payments of a fixed income securities are known in advance.
Features:
Fixed income securities have lowest risk.
Fixed rate of return.
These fixed income securities are n0t for the capital appreciation.
These securities are liquid in nature.<br>
slide3. Capitalization of cash flows from the asset and risk free rate When a security is to be valued on the capitalised value, we need to first derive the required rate of return at which investor value its security.
The minimum rate of return that the investor wishes to earn is known as required rate. It consists of:
The risk free rate(equal for each security)
The risk premium(adjusted according to the risk)
Req. rate of return(k)=Ir + rp ,where Ir=risk free rate ,rp=risk premium, k=the required rate of return<br>
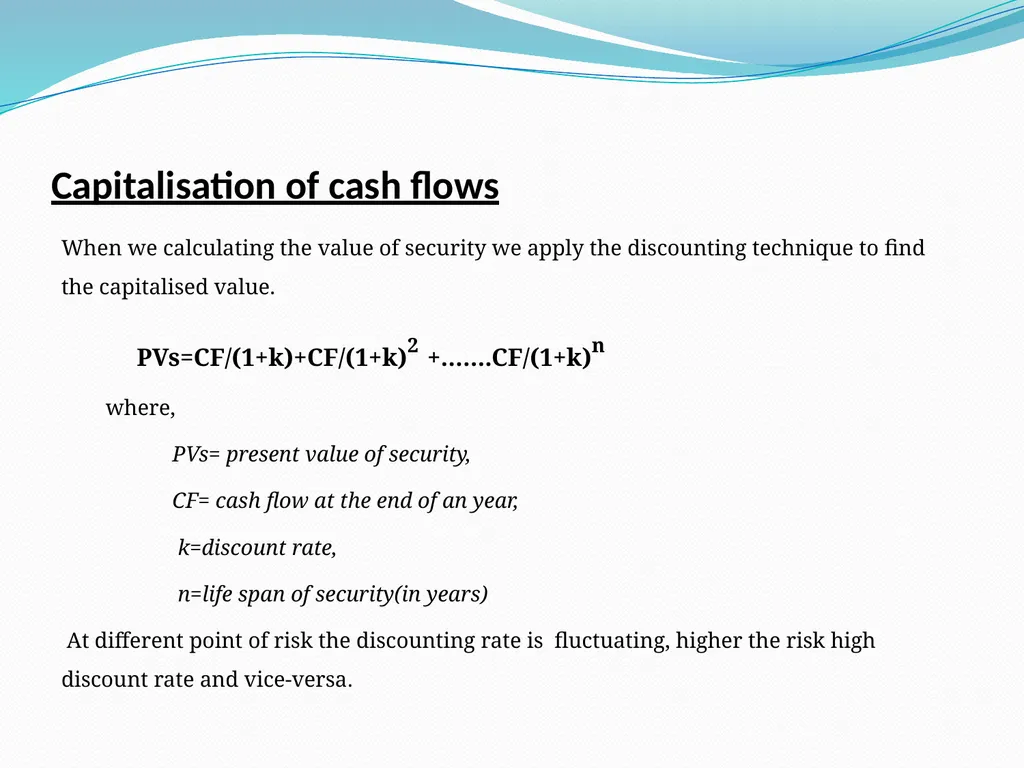
slide4. Capitalisation of cash flows When we calculating the value of security we apply the discounting technique to find the capitalised value.
PVs=CF/(1+k)+CF/(1+k)2 +…….CF/(1+k)n
where,
PVs= present value of security,
CF= cash flow at the end of an year,
k=discount rate,
n=life span of security(in years)
At different point of risk the discounting rate is fluctuating, higher the risk high discount rate and vice-versa.<br>
slide5. Valuation of bonds Meaning of Bond: It is a agreement between investor and Govt. or company or Financial institution, where investor lend a certain amount at a certain rate. It is a financial instrument which creates liability over the institution, bonds rate of return is based on its risk associated.
Features of bonds:
Face value
Redemption value
Maturity period
Rate of Interest
Market value<br>
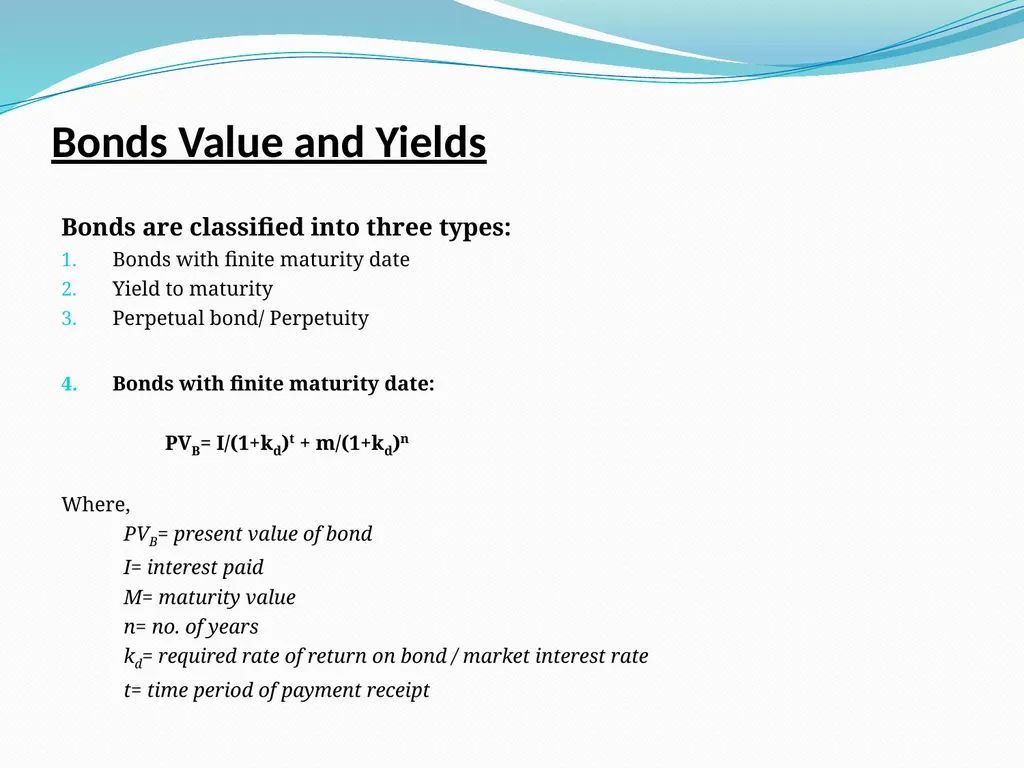
slide6. Bonds Value and Yields Bonds are classified into three types:
Bonds with finite maturity date
Yield to maturity
Perpetual bond/ Perpetuity
Bonds with finite maturity date:
PVB= I/(1+kd)t + m/(1+kd)n
Where,
PVB= present value of bond
I= interest paid
M= maturity value
n= no. of years
kd= required rate of return on bond / market interest rate
t= time period of payment receipt<br>
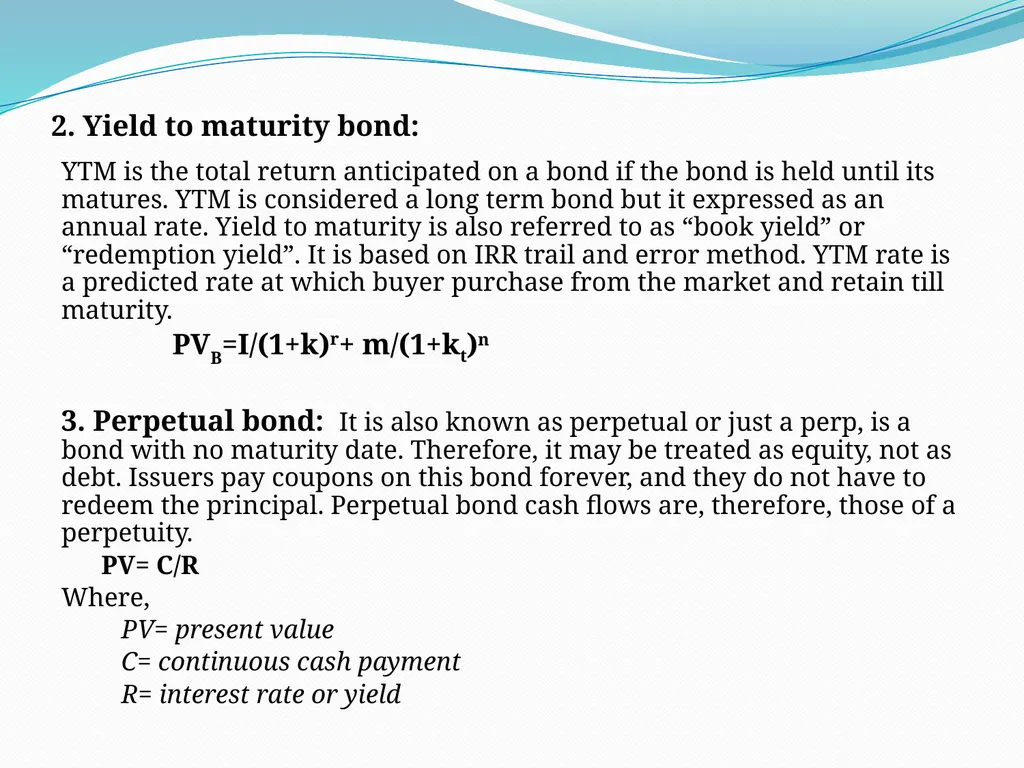
slide7. 2. Yield to maturity bond: YTM is the total return anticipated on a bond if the bond is held until its matures. YTM is considered a long term bond but it expressed as an annual rate. Yield to maturity is also referred to as “book yield” or “redemption yield”. It is based on IRR trail and error method. YTM rate is a predicted rate at which buyer purchase from the market and retain till maturity.
PVB=I/(1+k)r+ m/(1+kt)n
3. Perpetual bond: It is also known as perpetual or just a perp, is a bond with no maturity date. Therefore, it may be treated as equity, not as debt. Issuers pay coupons on this bond forever, and they do not have to redeem the principal. Perpetual bond cash flows are, therefore, those of a perpetuity.
PV= C/R
Where,
PV= present value
C= continuous cash payment
R= interest rate or yield<br>
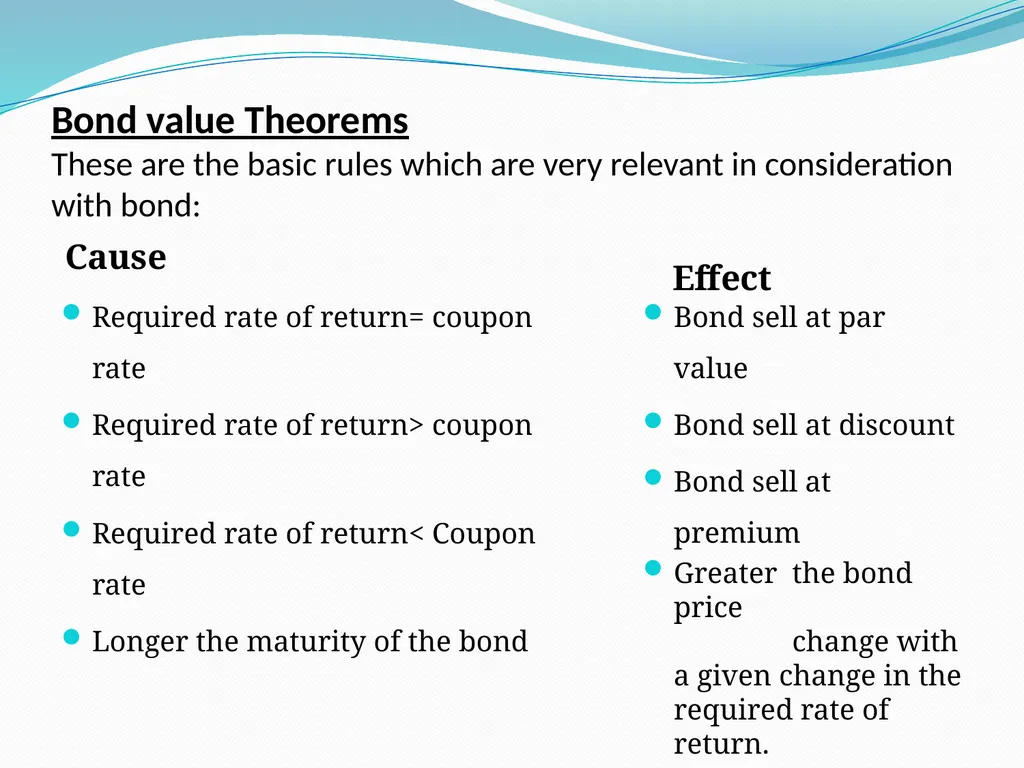
slide8. Bond value Theorems These are the basic rules which are very relevant in consideration with bond: Cause Effect Required rate of return= coupon rate
Required rate of return> coupon rate
Required rate of return< Coupon rate
Longer the maturity of the bond Bond sell at par value
Bond sell at discount
Bond sell at premium
Greater the bond price change with a given change in the required rate of return.<br>
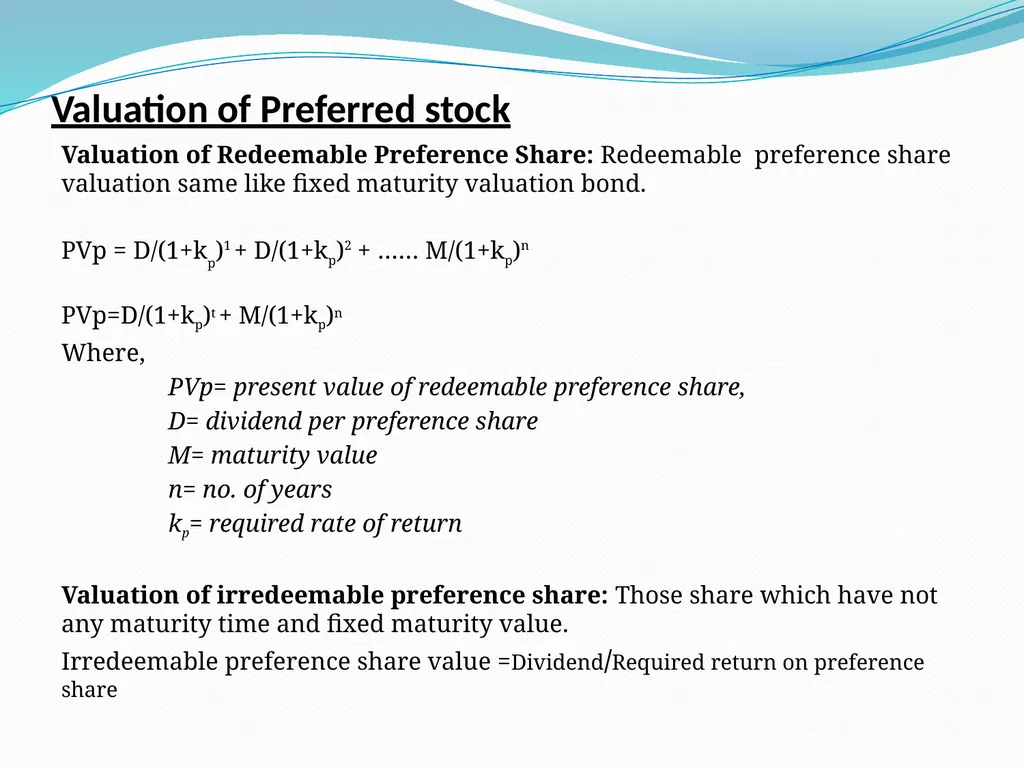
slide9. Valuation of Preferred stock Valuation of Redeemable Preference Share: Redeemable preference share valuation same like fixed maturity valuation bond.
PVp = D/(1+kp)1 + D/(1+kp)2 + …… M/(1+kp)n
PVp=D/(1+kp)t + M/(1+kp)n
Where,
PVp= present value of redeemable preference share,
D= dividend per preference share
M= maturity value
n= no. of years
kp= required rate of return
Valuation of irredeemable preference share: Those share which have not any maturity time and fixed maturity value.
Irredeemable preference share value =Dividend/Required return on preference share<br>
Arjun Yadav
(Research Scholar) Guided by:
Dr. Ambrish
(Assitant Professor)<br>
slide2. Characteristics Of Fixed Income Securities (Debt And Preferred Stock) Meaning:
Fixed income securities are financial claim with promised cash flows of fixed amount paid at fixed dates. Unlike variable income securities, where payments change based on short term interest rates, payments of a fixed income securities are known in advance.
Features:
Fixed income securities have lowest risk.
Fixed rate of return.
These fixed income securities are n0t for the capital appreciation.
These securities are liquid in nature.<br>
slide3. Capitalization of cash flows from the asset and risk free rate When a security is to be valued on the capitalised value, we need to first derive the required rate of return at which investor value its security.
The minimum rate of return that the investor wishes to earn is known as required rate. It consists of:
The risk free rate(equal for each security)
The risk premium(adjusted according to the risk)
Req. rate of return(k)=Ir + rp ,where Ir=risk free rate ,rp=risk premium, k=the required rate of return<br>
slide4. Capitalisation of cash flows When we calculating the value of security we apply the discounting technique to find the capitalised value.
PVs=CF/(1+k)+CF/(1+k)2 +…….CF/(1+k)n
where,
PVs= present value of security,
CF= cash flow at the end of an year,
k=discount rate,
n=life span of security(in years)
At different point of risk the discounting rate is fluctuating, higher the risk high discount rate and vice-versa.<br>
slide5. Valuation of bonds Meaning of Bond: It is a agreement between investor and Govt. or company or Financial institution, where investor lend a certain amount at a certain rate. It is a financial instrument which creates liability over the institution, bonds rate of return is based on its risk associated.
Features of bonds:
Face value
Redemption value
Maturity period
Rate of Interest
Market value<br>
slide6. Bonds Value and Yields Bonds are classified into three types:
Bonds with finite maturity date
Yield to maturity
Perpetual bond/ Perpetuity
Bonds with finite maturity date:
PVB= I/(1+kd)t + m/(1+kd)n
Where,
PVB= present value of bond
I= interest paid
M= maturity value
n= no. of years
kd= required rate of return on bond / market interest rate
t= time period of payment receipt<br>
slide7. 2. Yield to maturity bond: YTM is the total return anticipated on a bond if the bond is held until its matures. YTM is considered a long term bond but it expressed as an annual rate. Yield to maturity is also referred to as “book yield” or “redemption yield”. It is based on IRR trail and error method. YTM rate is a predicted rate at which buyer purchase from the market and retain till maturity.
PVB=I/(1+k)r+ m/(1+kt)n
3. Perpetual bond: It is also known as perpetual or just a perp, is a bond with no maturity date. Therefore, it may be treated as equity, not as debt. Issuers pay coupons on this bond forever, and they do not have to redeem the principal. Perpetual bond cash flows are, therefore, those of a perpetuity.
PV= C/R
Where,
PV= present value
C= continuous cash payment
R= interest rate or yield<br>
slide8. Bond value Theorems These are the basic rules which are very relevant in consideration with bond: Cause Effect Required rate of return= coupon rate
Required rate of return> coupon rate
Required rate of return< Coupon rate
Longer the maturity of the bond Bond sell at par value
Bond sell at discount
Bond sell at premium
Greater the bond price change with a given change in the required rate of return.<br>
slide9. Valuation of Preferred stock Valuation of Redeemable Preference Share: Redeemable preference share valuation same like fixed maturity valuation bond.
PVp = D/(1+kp)1 + D/(1+kp)2 + …… M/(1+kp)n
PVp=D/(1+kp)t + M/(1+kp)n
Where,
PVp= present value of redeemable preference share,
D= dividend per preference share
M= maturity value
n= no. of years
kp= required rate of return
Valuation of irredeemable preference share: Those share which have not any maturity time and fixed maturity value.
Irredeemable preference share value =Dividend/Required return on preference share<br>