
Value of Supply in GST Presented by PAMS

Description: Value of Supply in GST Presented by PAMS Professional Group 1 Section and Rules Section 15 of CGST Act, 2017 provides the provisions for determining the value of goods and services. It provides the mechanism to know how to calculate the
Related Topics
Download Presentation
"Value of Supply in GST Presented by PAMS" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Value of Supply in GST Presented by
PAMS Professional Group 1<br>
slide2. Section and Rules Section 15 of CGST Act, 2017 provides the provisions for determining the value of goods and services.
It provides the mechanism to know how to calculate the value of goods or services when supply of goods and services is made between unrelated persons and when the price is the sole consideration of the supply.
Provisions of the value of supply under CGST act have also been made applicable to IGST Act vide Section 20 of the IGST Act.
Valuation Rules are prescribed under Chapter IV of the Central Goods & Services Tax Rules, 2017 from Rule 27 to Rule 35. 2<br>
slide3. Section 15- Value of Supply 15(1)- The value of a supply of goods or services or both shall be the transaction value, which is the price actually paid or payable for the said supply of goods or services or both where the supplier and the recipient of the supply are not related and the price is the sole consideration for the supply.
So we can say that if the supplier and recipient are not related and the price is the sole consideration then the value of taxable supply is the Transaction Value. 3<br>
slide4. Related Person The term related person would include the following :-
Such persons are officers or directors of one another’s businesses;
Persons legally recognized as partners in business;
Such persons are employer and employee;
Any person directly or indirectly owns, controls or holds twenty-five per- cent. or more of the outstanding voting stock or shares of both of them;
One of them directly or indirectly controls the other;
A third person directly or indirectly controls both of them;
Together they directly or indirectly control a third person;
They are members of the same family;
The term person includes legal persons
Persons who are associated in the business of one another would also deem to be related 4<br>
slide5. Inclusions in the Value of supply 15 (2)- The value of supply shall include:
(a) any taxes, duties, cesses, fees and charges levied under any law for the time being in force other than the GST Act, if charged separately by the supplier;
(b) any amount that the supplier is liable to pay in relation to such supply but which has been incurred by the recipient, but not included in the price;
(c) incidental expenses, including commission and packing, charged by the supplier to the recipient and any amount charged for anything done by the supplier in respect of the supply until delivery of goods or supply of services;
(d) interest or late fee or penalty for delayed payment of any consideration for any supply; and
(e) subsidies directly linked to the price excluding subsidies provided by the Central Government and State Governments. 5<br>
slide6. Analysis of inclusions Taxes levied under any other law(s)- this clause provides for exclusion of GST from the value and therefore all other taxes charged must be included in the value before quantifying GST. For example- In case of import of goods IGST is charged on value of goods including basic custom duty.
Any amounts paid by recipient that are obligation of supplier to pay- identify any costs where supplier is obligated to pay but recipient makes the payment for that. For example– Free on road contract where transportation charges paid by recipient and value to be paid to the supplier is reduced to that extent. In this case, the transportation charge which was reduced from the price payable will be added back to the taxable value. Another example can be taken is ‘buying commission’’ –obligation is always of recipient and does not included in value of supply but if selling commission then the obligation to pay the agent being that of the supplier is required to be included in the value of supply. 6<br>
slide7. Analysis of inclusions Incidental expenses and amount charged for activities done before delivery:
It means any amount charged by supplier for anything done by him for the supply of goods or services or both. Incidental expenses includes:-
Commission:- Any commission paid to an agent by the supplier and recovered from the recipient for supply of goods or services or both will be the part of the value of taxable supply
Inspection or certificate charges:- This is another element that may be added to the value , if billed to the recipient of supply
Packing:- If the packing charges are charged by the supplier to the recipient then it is to be included in the value of supply
Freight and other charges:- Where the supplier agrees to deliver the goods to the recipient and facilitate the transportation then the charges of freight will be the part of value of supply. 7<br>
slide8. Analysis of inclusions Interest, late fee or penalty for delayed payment– Interest or late fee or any penalty for delayed payment of any consideration for supply of goods or services is required to be included in the value of supply. For Example: Mr. X enters into a contract for supply of goods worth ` 2,00,000 on 15th March 2018. As per the said contract, a payment of the said amount was required to be made within 2 months of the sale. If the complete payment is not made within this time period, a late penalty of` 10,000 will be chargeable. Let us assume that the payment is not made within the said period. In this situation, ` 10,000 will be includible in the taxable value.
Subsidy realized by supplier on the supply: Any subsidy which is direct link to the supply will be the part of value of supply except subsidies provided by the central government and state government. 8<br>
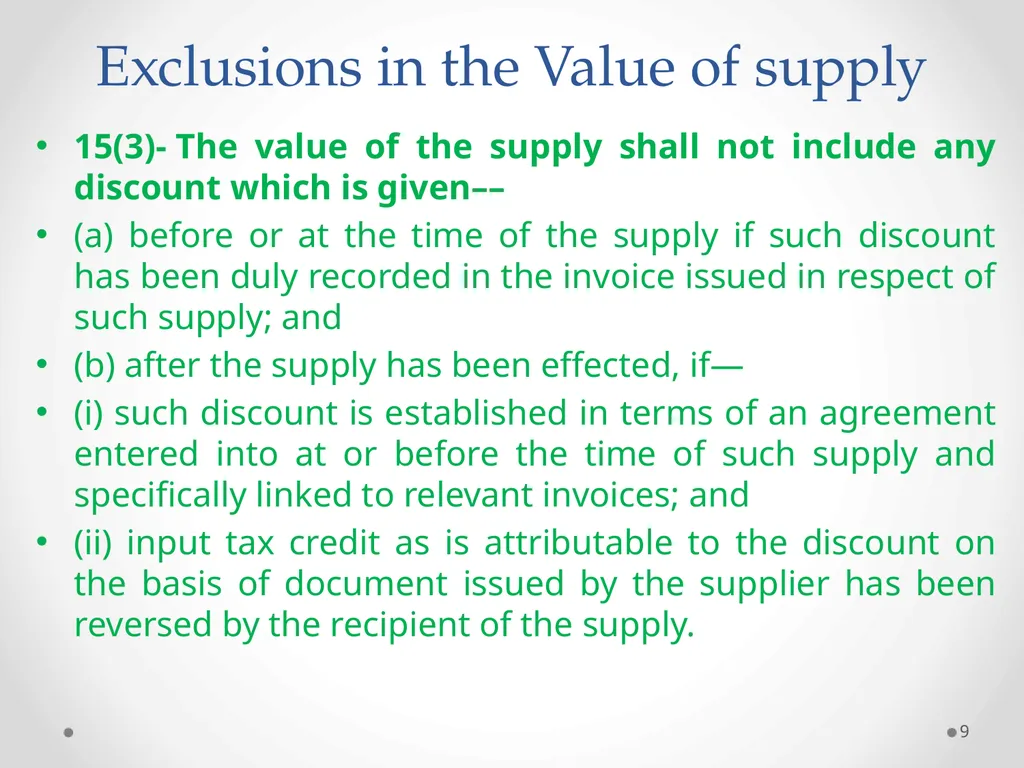
slide9. Exclusions in the Value of supply 15(3)- The value of the supply shall not include any discount which is given––
(a) before or at the time of the supply if such discount has been duly recorded in the invoice issued in respect of such supply; and
(b) after the supply has been effected, if—
(i) such discount is established in terms of an agreement entered into at or before the time of such supply and specifically linked to relevant invoices; and
(ii) input tax credit as is attributable to the discount on the basis of document issued by the supplier has been reversed by the recipient of the supply. 9<br>
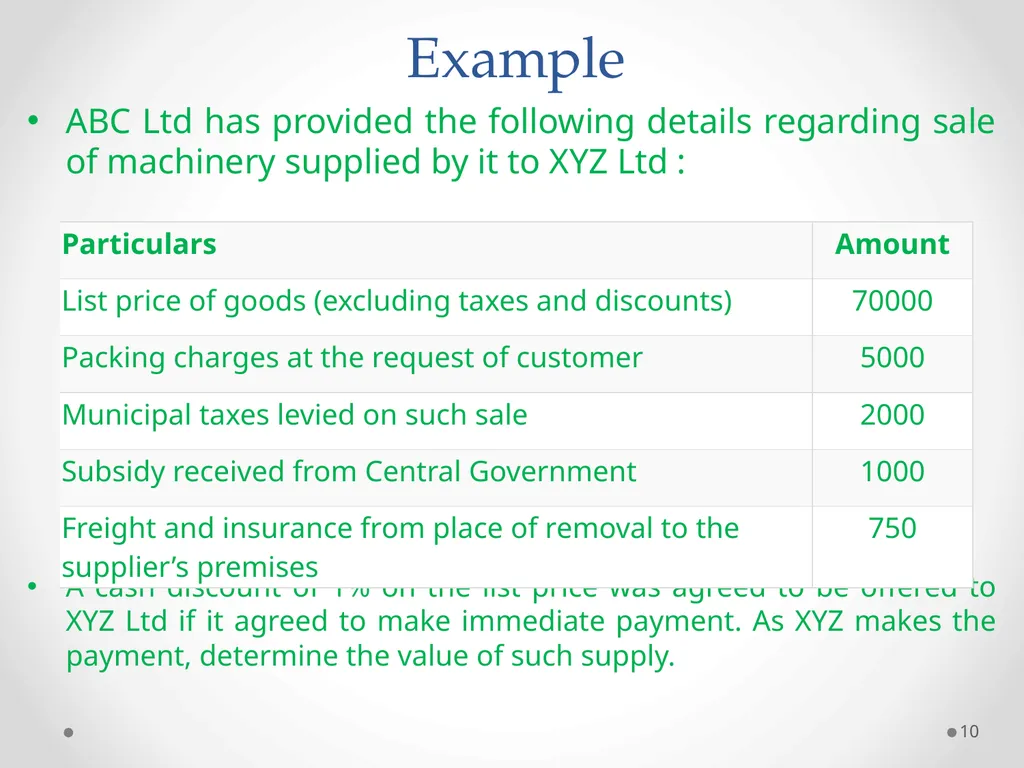
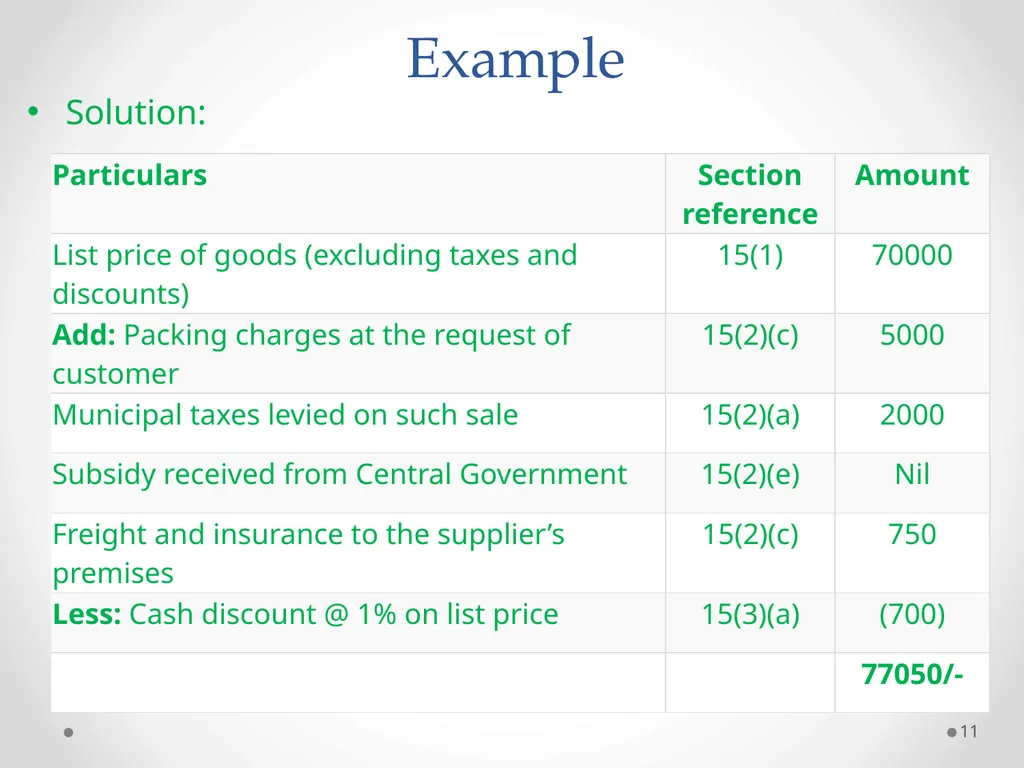
slide10. Example ABC Ltd has provided the following details regarding sale of machinery supplied by it to XYZ Ltd :
A cash discount of 1% on the list price was agreed to be offered to XYZ Ltd if it agreed to make immediate payment. As XYZ makes the payment, determine the value of such supply. 10<br>
slide11. Example Solution: 11<br>
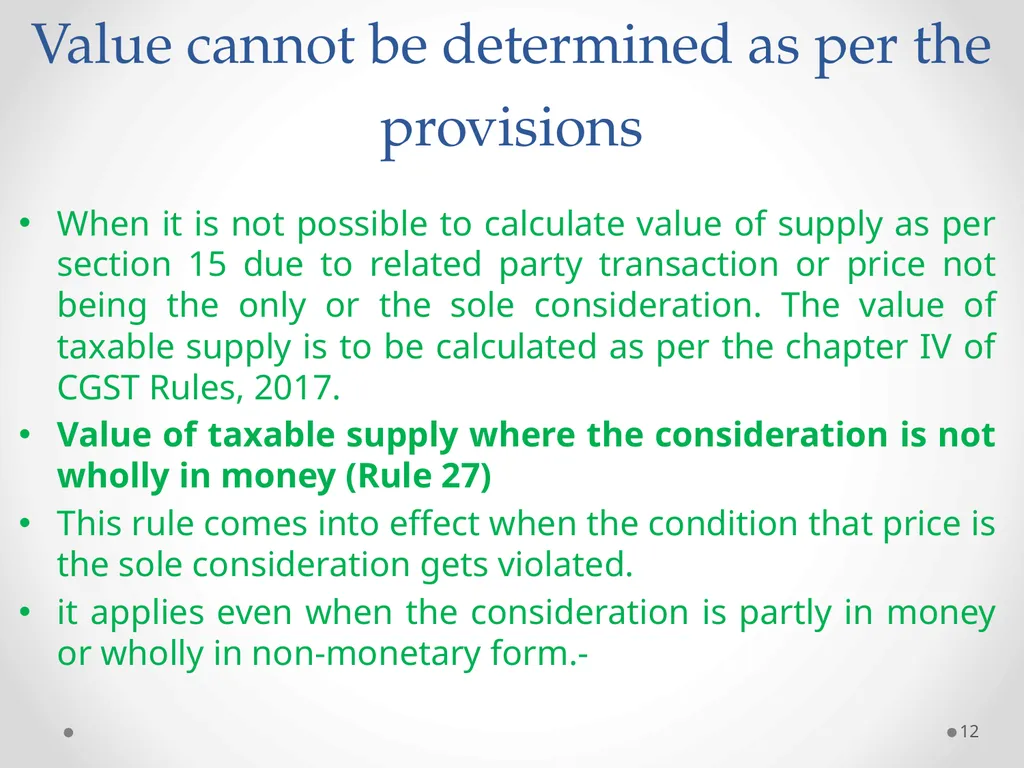
slide12. Value cannot be determined as per the provisions When it is not possible to calculate value of supply as per section 15 due to related party transaction or price not being the only or the sole consideration. The value of taxable supply is to be calculated as per the chapter IV of CGST Rules, 2017.
Value of taxable supply where the consideration is not wholly in money (Rule 27)
This rule comes into effect when the condition that price is the sole consideration gets violated.
it applies even when the consideration is partly in money or wholly in non-monetary form.- 12<br>
slide13. Rule 27 The value of supply shall be-
i. Open Market Value- which is the full value in money payable by an unrelated person as its sole consideration at the same time as the supply under inquiry.
ii. if the open market value is not available then the sum total of consideration in money and any such further amount in money as is equivalent to the consideration not in money.
For instance, an old antique art of work is sold against which consideration is partly in the form of money of 20,000 and partly in the form of a new furniture whose value known at the time of supply is 35,000. Then the value for the purpose of GST will be the monetary consideration combined with the equivalent money value of the new furniture i.e. 55,000. 13<br>
slide14. Rule 27 iii. Value of supply of ‘like kind and quality’ – here again two aspects are involved – one, to establish that clause (i) and (ii) are not determinable and two, to identify ‘likeness’ of kind and quality.
For Example: a customized air conditioning unit whose open market value is not available is installed at an office wherein the consideration is paid in the form of money of 40,000 and an old air conditioning unit whose price is not available at the time of supply. A similar air conditioning unit in terms of characteristics, quality, quantity, functional components, materials and reputation etc. has been installed by the company at another client’s premises for 60,000. Since, the value of goods of like kind and quality is available, the value of 60,000 will be taken under Rule 27.
iv. Value is not determinable under any of clause above, be the sum total of consideration in money and such further amount in money that is equivalent to consideration not in money as determined by the application of rule 30 or rule 31 in that order. 14<br>
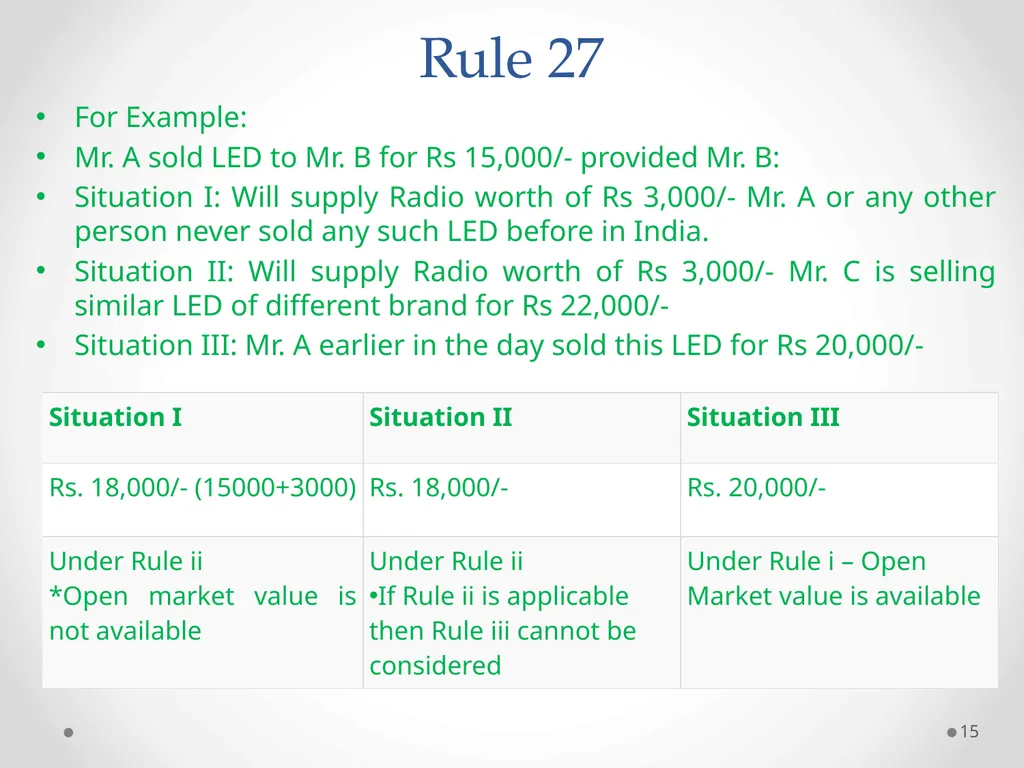
slide15. Rule 27 For Example:
Mr. A sold LED to Mr. B for Rs 15,000/- provided Mr. B:
Situation I: Will supply Radio worth of Rs 3,000/- Mr. A or any other person never sold any such LED before in India.
Situation II: Will supply Radio worth of Rs 3,000/- Mr. C is selling similar LED of different brand for Rs 22,000/-
Situation III: Mr. A earlier in the day sold this LED for Rs 20,000/- 15<br>
slide16. Rule 28 Value of taxable supply where supply between distinct or related persons other than agent ( Rule 28)
The value of taxable supply between distinct persons or where the recipient and supplier are related other than in case of supply being made through agent then value is :
(a) Open market value
(b) If the open market value is not available then the value of supply of goods or services of like kind and quality
(c) if the value is not determinable under clause (a) or (b), be the value as determined by the application of rule 30 or rule 31, in that order:
Note:
The above rule shall be applicable for supply made with consideration or without consideration. 16<br>
slide17. Rule 28 A person who has obtained or is required to obtain more than one registration, whether in one State or Union territory or more than one State or Union territory shall, in respect of each such registration, be treated as distinct persons for the purposes of this Act.
For Example:
Mr. Ram proprietor of Sri Krishna Manufactures supplied certain goods costing Rs. 75,000/- to it’s employees at Rs. 60,000/-. In such a case, as both the assessee and it’s employee come under the definition of related parties under the GST Act, open market value as per Rule 28 if available will be applicable. The open market value of the goods were Rs. 75,000/- which would constitute to be the value of supply in such a case. 17<br>
slide18. Rule 29 Value of taxable supply where supply made through an agent (Rule 29)
The value of supply of goods between the principal and his agent shall:
(a) be the open market value of the goods being supplied,
Or at the option of the supplier, be ninety per cent. of the price charged for the supply of goods of like kind and quality by the recipient to his customer not being a related person, where the goods are intended for further supply by the said recipient.
(b) where the value of a supply is not determinable under clause (a), the same shall be determined by the application of rule 30 or rule 31 in that order.
Note:
The above rule shall be applicable for supply made only when selling or buying agent issues his own invoice or when the agent receives supply on behalf of the principal. 18<br>
slide19. Rule 29 For better understanding let us consider the following example:
Whirlpool Ltd, a manufacturer of washing machines, had several selling agents across the country. It supplied the washing machines on the basis of orders received from it’s agents. The agents further supplied the machines under their own name at an MRP of Rs. 70000 per unit. Whirlpool received an order of 20 machines from one of it’s agents based in Kolkata. Whirlpool also supplies the same machines to it’s retailers in Bangalore at Rs. 90000 per unit.
In the above scenario, as the agents are supplying machines in their own name and issues it’s own invoice, it would constitute to be supply. Thus, Whirlpool Ltd, has 2 options :-
Open market value=Rs. 90000*20 =Rs. 18,00,000/-
90% of value of both like kind and quality that the recipient would charge from his customer = 90% *70000*20 = Rs. 12,60,000/- 19<br>
slide20. Rule 30 Value of supply as per rule 30
Where value of taxable supply is not determinable as per rules 27,28,29 than it will be calculated as per Rule 30. As per this rule the value shall be 110% of the:
Cost of production or manufacture or acquisition
Cost of provision of such service
For Example: XYZ Private Limited has 2 establishments. One in Delhi and another in West Bengal. It manufactured product ‘X’ with customizations as required for Kolkata Branch. ‘X’ being a customized product, the same was not sold to the public at large. Thus, open market value of the same is not determinable. However, cost of production for product ‘X’ would be Rs. 15000. The establishment at the Kolkata branch would sell the same after further customization as demanded by the consumers.
Thus, in the above scenario, value is determinable as per Rule 28. However, due to absence of open market value and value for like kind and quality, Valuation as per Rule no. 30 would be adopted.
Value = 110% of Cost of production i.e. 110% * 15000 = Rs. 16,500 20<br>
slide21. Rule 31 Value of supply as per rule 31
Residual method for determination of value of supply of goods or services or both:
Where the value of supply of goods or services or both cannot be determined under rules 27 to 30, the same shall be determined using reasonable means consistent with the principles and the general provisions of section 15 and the provisions of this Chapter:
Note:
However, in case of supply of service the supplier may opt for this rule, ignoring rule 30 21<br>
slide22. Rule 31A Value of supply in case of lottery, betting, gambling and horse racing Rule 31A
Irrespective of the above mentioned rules and other provisions of the act, the value shall determined be as follows :-
Actionable claim in the form of chance to win in betting, gambling or horse racing in a race club:
100% of Face value of the bet
For better understanding let us consider the following example:
A lottery was organized by West Bengal Government. The ticket price was Rs. 500 per ticket as notified in the Gazette by the organizing State as authorized by the government.
Thus, value of supply of lottery as authorized by State Governments = 100*500/128 = Rs. 390.50/- 22<br>
slide23. Rule 32 Determination of value in respect of certain supplies Rule 32:
(1) Notwithstanding anything contained in the provisions of this Chapter, the value in respect of supplies specified below shall, at the option of the supplier, be determined in the manner provided hereinafter.
(2) The value of supply of services in relation to the purchase or sale of foreign currency, including money changing, shall be determined by the supplier of services in the following manner, namely:- Rule 32(2)
Option 1.
When exchanged from, or to, Indian Rupees
Where RBI reference rate is available :-
Difference in the buying rate or the selling rate, and the Reserve Bank of India reference rate for that currency at that time, multiplied by the total units of currency.
Where RBI reference rate is not available :-
1%. of the gross amount of Indian Rupees given or received 23<br>
slide24. Rule 32 When exchanged from one foreign currency to another.
1% of lower of :-
Converting foreign currency 1 with RBI reference rate into Indian Rupee
Converting foreign currency 2 with RBI reference rate into Indian Rupee
Option 2.
When exchanged from, or to, Indian Rupees or from one foreign currency to another.
Amount up to 1 lacs: 1% of the gross amount of currency exchanged subject to a minimum amount of Rs. 250/-
Amount above 1 lacs up to 10 lacs : Rs. 1000 + 0.5% of the gross amount of currency exchanged on such excessive amount
Amount above 10 lacs : Rs. 5500 + 0.1% of the gross amount of currency exchanged on such excessive amount Subject to a maximum of Rs. 60000 24<br>
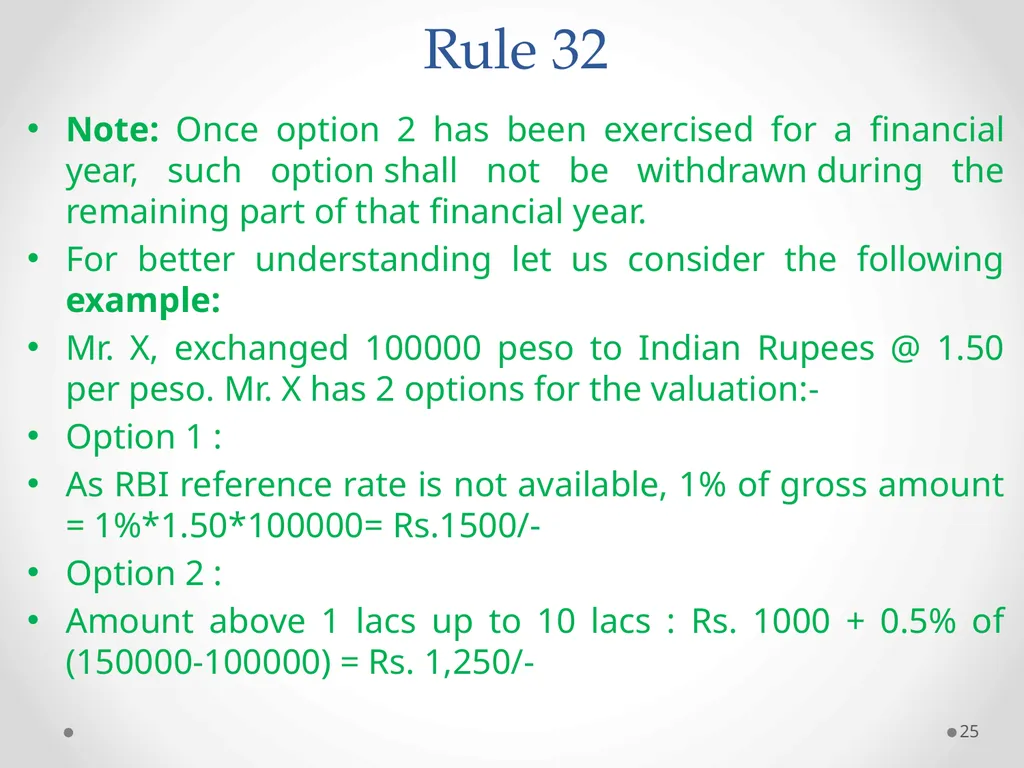
slide25. Rule 32 Note: Once option 2 has been exercised for a financial year, such option shall not be withdrawn during the remaining part of that financial year.
For better understanding let us consider the following example:
Mr. X, exchanged 100000 peso to Indian Rupees @ 1.50 per peso. Mr. X has 2 options for the valuation:-
Option 1 :
As RBI reference rate is not available, 1% of gross amount = 1%*1.50*100000= Rs.1500/-
Option 2 :
Amount above 1 lacs up to 10 lacs : Rs. 1000 + 0.5% of (150000-100000) = Rs. 1,250/- 25<br>
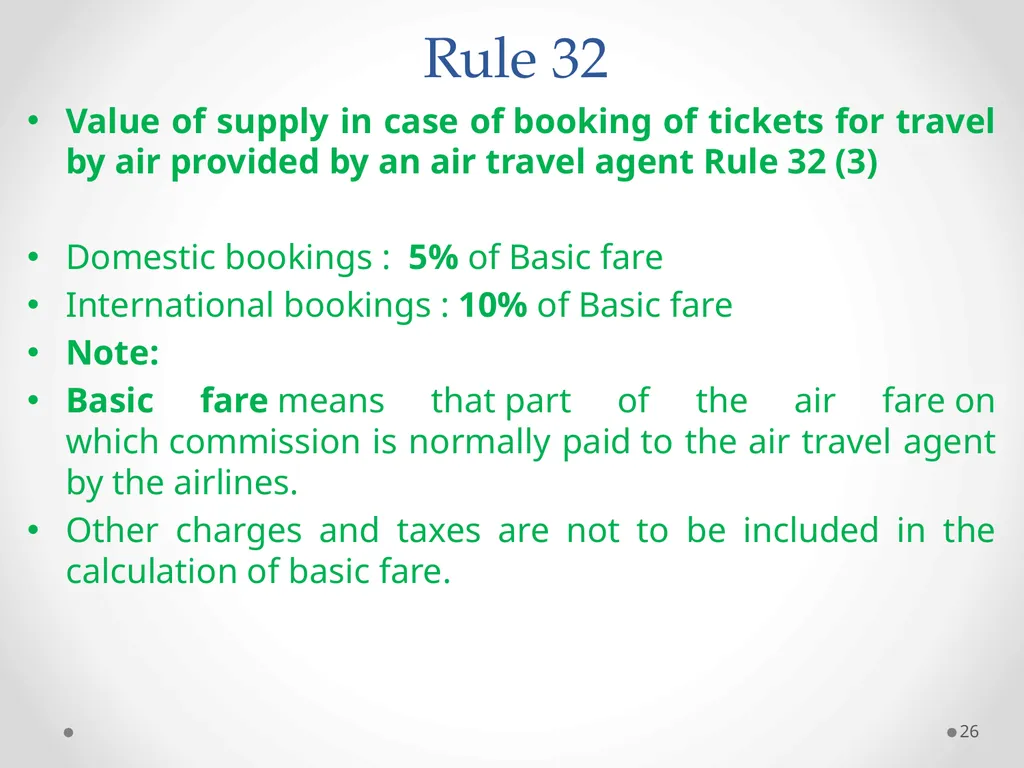
slide26. Rule 32 Value of supply in case of booking of tickets for travel by air provided by an air travel agent Rule 32 (3)
Domestic bookings : 5% of Basic fare
International bookings : 10% of Basic fare
Note:
Basic fare means that part of the air fare on which commission is normally paid to the air travel agent by the airlines.
Other charges and taxes are not to be included in the calculation of basic fare. 26<br>
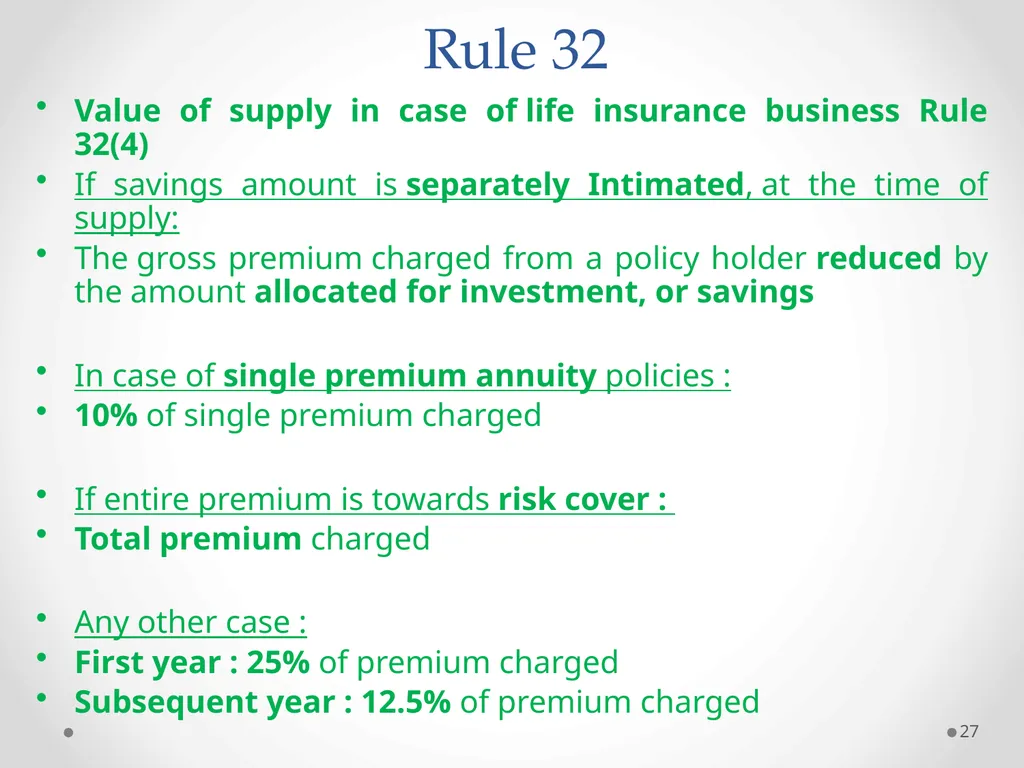
slide27. Rule 32 Value of supply in case of life insurance business Rule 32(4)
If savings amount is separately Intimated, at the time of supply:
The gross premium charged from a policy holder reduced by the amount allocated for investment, or savings
In case of single premium annuity policies :
10% of single premium charged
If entire premium is towards risk cover :
Total premium charged
Any other case :
First year : 25% of premium charged
Subsequent year : 12.5% of premium charged 27<br>
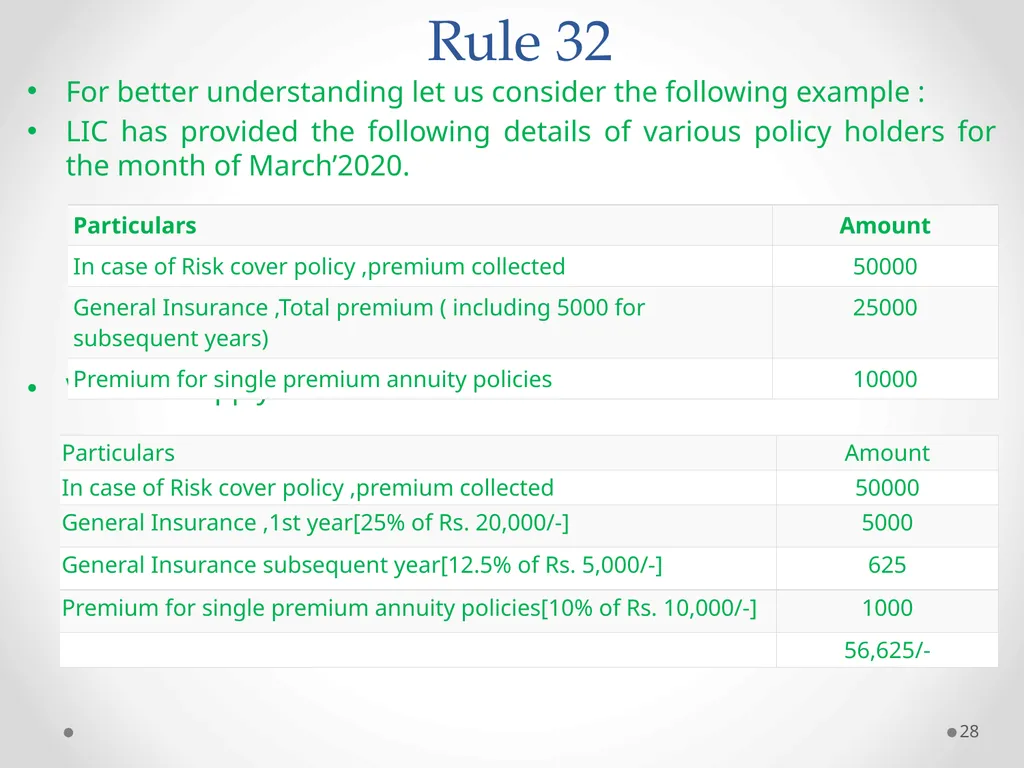
slide28. Rule 32 For better understanding let us consider the following example :
LIC has provided the following details of various policy holders for the month of March’2020.
Value of Supply as determined in the above case would be : 28<br>
slide29. Rule 32 Value of supply in case of a person dealing in buying and selling of second hand goods Rule 32 (5)
If No ITC has been taken by the Person :
Selling price -Purchase price (Ignore if negative.)
If ITC has been taken :
Value as per Transaction value u/s 15
In case of selling of repossessed goods from a defaulting unregistered borrower:
Purchase price as reduced by 5% for every quarter or part thereof, between the date of purchase and the date of disposal. 29<br>
slide30. Rule 32 For better understanding let us consider the following example:
Mr. Honey a dealer in second hand cars purchases the cars and sells them after painting and some repair. He does not take credit of any of the purchases. He sold one car at Rs. 90000 which was purchased by him at Rs. 85000.
In the above scenario, value of supply would be Rs. 90000-85000 = Rs. 5000/-.
However if in the above scenario, the purchase price would have been Rs. Above 90000, value of supply would be Nil. 30<br>
slide31. Rule 32 Value of supply in case of a value of a token, or a voucher, or a coupon, or a stamp (other than postage stamp) which is redeemable Rule 32 (6)
Value of Supply would be Money value of the goods or services or both redeemable against such token, voucher etc.
For Example:
Easy Coupons Ltd. Sells coupons that are redeemable against specified luxury food products at retail outlets. Each coupon has a face value of Rs. 900 but is redeemable for supplies worth Rs. 1000.
So, in this case as value of the coupon is the money value of the goods redeemable against it. Therefore though the coupon is sold for Rs. 900 but its value is Rs. 1000. 31<br>
slide32. Rule 33 As per Rule 33, Irrespective of any provisions of this Chapter, the expenditure or costs incurred by a supplier as a pure agent of the recipient of supply will be excluded from the value of Supply, if all the following conditions are satisfied :-
the supplier acts as a pure agent of the recipient of the supply, when he makes the payment to the third party on authorization by such recipient;
the payment made by the pure agent on behalf of the recipient of supply has been separately indicated in the invoice issued by the pure agent to the recipient of service; and
the supplies procured by the pure agent from the third party as a pure agent of the recipient of supply are in addition to the services he supplies on his own account.
For better understanding let us consider the following example :
Mr. Ram (a CA) makes payment of GST, TDS and ROC on behalf of it’s clients. He later recovers the same from his client in addition to this service charges.
Accordingly, as Mr. Ram is acting as a pure agent, the same would not be added to the value of supply in the invoice made by Mr. Ram. 32<br>
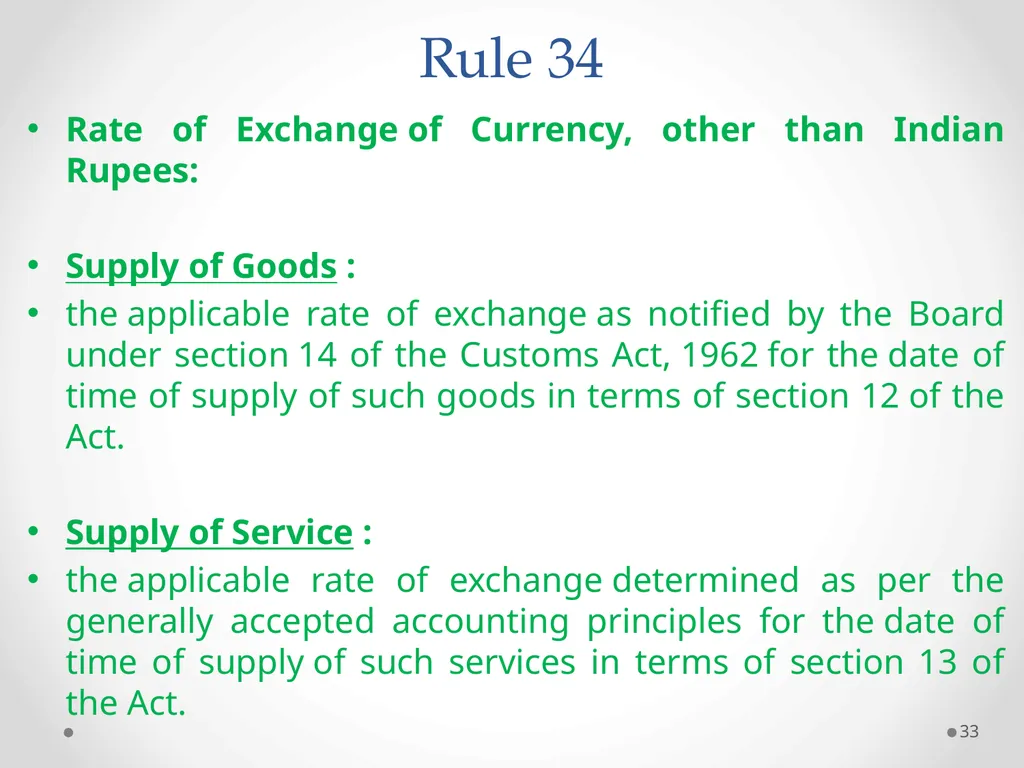
slide33. Rule 34 Rate of Exchange of Currency, other than Indian Rupees:
Supply of Goods :
the applicable rate of exchange as notified by the Board under section 14 of the Customs Act, 1962 for the date of time of supply of such goods in terms of section 12 of the Act.
Supply of Service :
the applicable rate of exchange determined as per the generally accepted accounting principles for the date of time of supply of such services in terms of section 13 of the Act. 33<br>
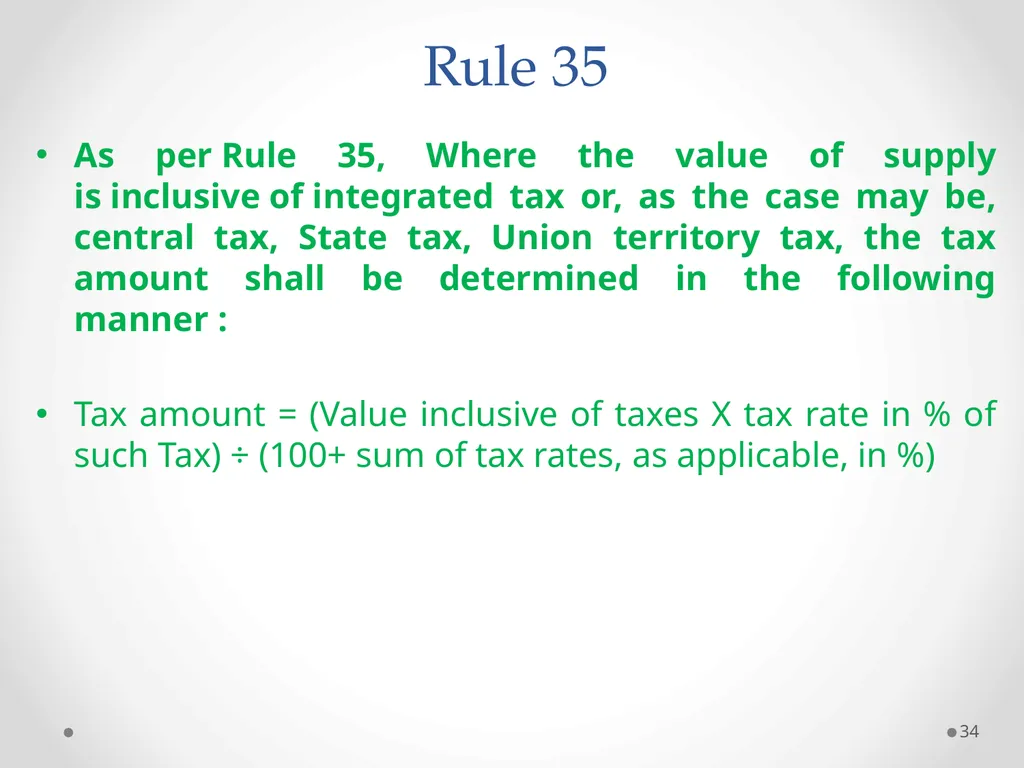
slide34. Rule 35 As per Rule 35, Where the value of supply is inclusive of integrated tax or, as the case may be, central tax, State tax, Union territory tax, the tax amount shall be determined in the following manner :
Tax amount = (Value inclusive of taxes X tax rate in % of such Tax) ÷ (100+ sum of tax rates, as applicable, in %) 34<br>
slide35. Thank You So Much PAMS Professional Group 35<br>
PAMS Professional Group 1<br>
slide2. Section and Rules Section 15 of CGST Act, 2017 provides the provisions for determining the value of goods and services.
It provides the mechanism to know how to calculate the value of goods or services when supply of goods and services is made between unrelated persons and when the price is the sole consideration of the supply.
Provisions of the value of supply under CGST act have also been made applicable to IGST Act vide Section 20 of the IGST Act.
Valuation Rules are prescribed under Chapter IV of the Central Goods & Services Tax Rules, 2017 from Rule 27 to Rule 35. 2<br>
slide3. Section 15- Value of Supply 15(1)- The value of a supply of goods or services or both shall be the transaction value, which is the price actually paid or payable for the said supply of goods or services or both where the supplier and the recipient of the supply are not related and the price is the sole consideration for the supply.
So we can say that if the supplier and recipient are not related and the price is the sole consideration then the value of taxable supply is the Transaction Value. 3<br>
slide4. Related Person The term related person would include the following :-
Such persons are officers or directors of one another’s businesses;
Persons legally recognized as partners in business;
Such persons are employer and employee;
Any person directly or indirectly owns, controls or holds twenty-five per- cent. or more of the outstanding voting stock or shares of both of them;
One of them directly or indirectly controls the other;
A third person directly or indirectly controls both of them;
Together they directly or indirectly control a third person;
They are members of the same family;
The term person includes legal persons
Persons who are associated in the business of one another would also deem to be related 4<br>
slide5. Inclusions in the Value of supply 15 (2)- The value of supply shall include:
(a) any taxes, duties, cesses, fees and charges levied under any law for the time being in force other than the GST Act, if charged separately by the supplier;
(b) any amount that the supplier is liable to pay in relation to such supply but which has been incurred by the recipient, but not included in the price;
(c) incidental expenses, including commission and packing, charged by the supplier to the recipient and any amount charged for anything done by the supplier in respect of the supply until delivery of goods or supply of services;
(d) interest or late fee or penalty for delayed payment of any consideration for any supply; and
(e) subsidies directly linked to the price excluding subsidies provided by the Central Government and State Governments. 5<br>
slide6. Analysis of inclusions Taxes levied under any other law(s)- this clause provides for exclusion of GST from the value and therefore all other taxes charged must be included in the value before quantifying GST. For example- In case of import of goods IGST is charged on value of goods including basic custom duty.
Any amounts paid by recipient that are obligation of supplier to pay- identify any costs where supplier is obligated to pay but recipient makes the payment for that. For example– Free on road contract where transportation charges paid by recipient and value to be paid to the supplier is reduced to that extent. In this case, the transportation charge which was reduced from the price payable will be added back to the taxable value. Another example can be taken is ‘buying commission’’ –obligation is always of recipient and does not included in value of supply but if selling commission then the obligation to pay the agent being that of the supplier is required to be included in the value of supply. 6<br>
slide7. Analysis of inclusions Incidental expenses and amount charged for activities done before delivery:
It means any amount charged by supplier for anything done by him for the supply of goods or services or both. Incidental expenses includes:-
Commission:- Any commission paid to an agent by the supplier and recovered from the recipient for supply of goods or services or both will be the part of the value of taxable supply
Inspection or certificate charges:- This is another element that may be added to the value , if billed to the recipient of supply
Packing:- If the packing charges are charged by the supplier to the recipient then it is to be included in the value of supply
Freight and other charges:- Where the supplier agrees to deliver the goods to the recipient and facilitate the transportation then the charges of freight will be the part of value of supply. 7<br>
slide8. Analysis of inclusions Interest, late fee or penalty for delayed payment– Interest or late fee or any penalty for delayed payment of any consideration for supply of goods or services is required to be included in the value of supply. For Example: Mr. X enters into a contract for supply of goods worth ` 2,00,000 on 15th March 2018. As per the said contract, a payment of the said amount was required to be made within 2 months of the sale. If the complete payment is not made within this time period, a late penalty of` 10,000 will be chargeable. Let us assume that the payment is not made within the said period. In this situation, ` 10,000 will be includible in the taxable value.
Subsidy realized by supplier on the supply: Any subsidy which is direct link to the supply will be the part of value of supply except subsidies provided by the central government and state government. 8<br>
slide9. Exclusions in the Value of supply 15(3)- The value of the supply shall not include any discount which is given––
(a) before or at the time of the supply if such discount has been duly recorded in the invoice issued in respect of such supply; and
(b) after the supply has been effected, if—
(i) such discount is established in terms of an agreement entered into at or before the time of such supply and specifically linked to relevant invoices; and
(ii) input tax credit as is attributable to the discount on the basis of document issued by the supplier has been reversed by the recipient of the supply. 9<br>
slide10. Example ABC Ltd has provided the following details regarding sale of machinery supplied by it to XYZ Ltd :
A cash discount of 1% on the list price was agreed to be offered to XYZ Ltd if it agreed to make immediate payment. As XYZ makes the payment, determine the value of such supply. 10<br>
slide11. Example Solution: 11<br>
slide12. Value cannot be determined as per the provisions When it is not possible to calculate value of supply as per section 15 due to related party transaction or price not being the only or the sole consideration. The value of taxable supply is to be calculated as per the chapter IV of CGST Rules, 2017.
Value of taxable supply where the consideration is not wholly in money (Rule 27)
This rule comes into effect when the condition that price is the sole consideration gets violated.
it applies even when the consideration is partly in money or wholly in non-monetary form.- 12<br>
slide13. Rule 27 The value of supply shall be-
i. Open Market Value- which is the full value in money payable by an unrelated person as its sole consideration at the same time as the supply under inquiry.
ii. if the open market value is not available then the sum total of consideration in money and any such further amount in money as is equivalent to the consideration not in money.
For instance, an old antique art of work is sold against which consideration is partly in the form of money of 20,000 and partly in the form of a new furniture whose value known at the time of supply is 35,000. Then the value for the purpose of GST will be the monetary consideration combined with the equivalent money value of the new furniture i.e. 55,000. 13<br>
slide14. Rule 27 iii. Value of supply of ‘like kind and quality’ – here again two aspects are involved – one, to establish that clause (i) and (ii) are not determinable and two, to identify ‘likeness’ of kind and quality.
For Example: a customized air conditioning unit whose open market value is not available is installed at an office wherein the consideration is paid in the form of money of 40,000 and an old air conditioning unit whose price is not available at the time of supply. A similar air conditioning unit in terms of characteristics, quality, quantity, functional components, materials and reputation etc. has been installed by the company at another client’s premises for 60,000. Since, the value of goods of like kind and quality is available, the value of 60,000 will be taken under Rule 27.
iv. Value is not determinable under any of clause above, be the sum total of consideration in money and such further amount in money that is equivalent to consideration not in money as determined by the application of rule 30 or rule 31 in that order. 14<br>
slide15. Rule 27 For Example:
Mr. A sold LED to Mr. B for Rs 15,000/- provided Mr. B:
Situation I: Will supply Radio worth of Rs 3,000/- Mr. A or any other person never sold any such LED before in India.
Situation II: Will supply Radio worth of Rs 3,000/- Mr. C is selling similar LED of different brand for Rs 22,000/-
Situation III: Mr. A earlier in the day sold this LED for Rs 20,000/- 15<br>
slide16. Rule 28 Value of taxable supply where supply between distinct or related persons other than agent ( Rule 28)
The value of taxable supply between distinct persons or where the recipient and supplier are related other than in case of supply being made through agent then value is :
(a) Open market value
(b) If the open market value is not available then the value of supply of goods or services of like kind and quality
(c) if the value is not determinable under clause (a) or (b), be the value as determined by the application of rule 30 or rule 31, in that order:
Note:
The above rule shall be applicable for supply made with consideration or without consideration. 16<br>
slide17. Rule 28 A person who has obtained or is required to obtain more than one registration, whether in one State or Union territory or more than one State or Union territory shall, in respect of each such registration, be treated as distinct persons for the purposes of this Act.
For Example:
Mr. Ram proprietor of Sri Krishna Manufactures supplied certain goods costing Rs. 75,000/- to it’s employees at Rs. 60,000/-. In such a case, as both the assessee and it’s employee come under the definition of related parties under the GST Act, open market value as per Rule 28 if available will be applicable. The open market value of the goods were Rs. 75,000/- which would constitute to be the value of supply in such a case. 17<br>
slide18. Rule 29 Value of taxable supply where supply made through an agent (Rule 29)
The value of supply of goods between the principal and his agent shall:
(a) be the open market value of the goods being supplied,
Or at the option of the supplier, be ninety per cent. of the price charged for the supply of goods of like kind and quality by the recipient to his customer not being a related person, where the goods are intended for further supply by the said recipient.
(b) where the value of a supply is not determinable under clause (a), the same shall be determined by the application of rule 30 or rule 31 in that order.
Note:
The above rule shall be applicable for supply made only when selling or buying agent issues his own invoice or when the agent receives supply on behalf of the principal. 18<br>
slide19. Rule 29 For better understanding let us consider the following example:
Whirlpool Ltd, a manufacturer of washing machines, had several selling agents across the country. It supplied the washing machines on the basis of orders received from it’s agents. The agents further supplied the machines under their own name at an MRP of Rs. 70000 per unit. Whirlpool received an order of 20 machines from one of it’s agents based in Kolkata. Whirlpool also supplies the same machines to it’s retailers in Bangalore at Rs. 90000 per unit.
In the above scenario, as the agents are supplying machines in their own name and issues it’s own invoice, it would constitute to be supply. Thus, Whirlpool Ltd, has 2 options :-
Open market value=Rs. 90000*20 =Rs. 18,00,000/-
90% of value of both like kind and quality that the recipient would charge from his customer = 90% *70000*20 = Rs. 12,60,000/- 19<br>
slide20. Rule 30 Value of supply as per rule 30
Where value of taxable supply is not determinable as per rules 27,28,29 than it will be calculated as per Rule 30. As per this rule the value shall be 110% of the:
Cost of production or manufacture or acquisition
Cost of provision of such service
For Example: XYZ Private Limited has 2 establishments. One in Delhi and another in West Bengal. It manufactured product ‘X’ with customizations as required for Kolkata Branch. ‘X’ being a customized product, the same was not sold to the public at large. Thus, open market value of the same is not determinable. However, cost of production for product ‘X’ would be Rs. 15000. The establishment at the Kolkata branch would sell the same after further customization as demanded by the consumers.
Thus, in the above scenario, value is determinable as per Rule 28. However, due to absence of open market value and value for like kind and quality, Valuation as per Rule no. 30 would be adopted.
Value = 110% of Cost of production i.e. 110% * 15000 = Rs. 16,500 20<br>
slide21. Rule 31 Value of supply as per rule 31
Residual method for determination of value of supply of goods or services or both:
Where the value of supply of goods or services or both cannot be determined under rules 27 to 30, the same shall be determined using reasonable means consistent with the principles and the general provisions of section 15 and the provisions of this Chapter:
Note:
However, in case of supply of service the supplier may opt for this rule, ignoring rule 30 21<br>
slide22. Rule 31A Value of supply in case of lottery, betting, gambling and horse racing Rule 31A
Irrespective of the above mentioned rules and other provisions of the act, the value shall determined be as follows :-
Actionable claim in the form of chance to win in betting, gambling or horse racing in a race club:
100% of Face value of the bet
For better understanding let us consider the following example:
A lottery was organized by West Bengal Government. The ticket price was Rs. 500 per ticket as notified in the Gazette by the organizing State as authorized by the government.
Thus, value of supply of lottery as authorized by State Governments = 100*500/128 = Rs. 390.50/- 22<br>
slide23. Rule 32 Determination of value in respect of certain supplies Rule 32:
(1) Notwithstanding anything contained in the provisions of this Chapter, the value in respect of supplies specified below shall, at the option of the supplier, be determined in the manner provided hereinafter.
(2) The value of supply of services in relation to the purchase or sale of foreign currency, including money changing, shall be determined by the supplier of services in the following manner, namely:- Rule 32(2)
Option 1.
When exchanged from, or to, Indian Rupees
Where RBI reference rate is available :-
Difference in the buying rate or the selling rate, and the Reserve Bank of India reference rate for that currency at that time, multiplied by the total units of currency.
Where RBI reference rate is not available :-
1%. of the gross amount of Indian Rupees given or received 23<br>
slide24. Rule 32 When exchanged from one foreign currency to another.
1% of lower of :-
Converting foreign currency 1 with RBI reference rate into Indian Rupee
Converting foreign currency 2 with RBI reference rate into Indian Rupee
Option 2.
When exchanged from, or to, Indian Rupees or from one foreign currency to another.
Amount up to 1 lacs: 1% of the gross amount of currency exchanged subject to a minimum amount of Rs. 250/-
Amount above 1 lacs up to 10 lacs : Rs. 1000 + 0.5% of the gross amount of currency exchanged on such excessive amount
Amount above 10 lacs : Rs. 5500 + 0.1% of the gross amount of currency exchanged on such excessive amount Subject to a maximum of Rs. 60000 24<br>
slide25. Rule 32 Note: Once option 2 has been exercised for a financial year, such option shall not be withdrawn during the remaining part of that financial year.
For better understanding let us consider the following example:
Mr. X, exchanged 100000 peso to Indian Rupees @ 1.50 per peso. Mr. X has 2 options for the valuation:-
Option 1 :
As RBI reference rate is not available, 1% of gross amount = 1%*1.50*100000= Rs.1500/-
Option 2 :
Amount above 1 lacs up to 10 lacs : Rs. 1000 + 0.5% of (150000-100000) = Rs. 1,250/- 25<br>
slide26. Rule 32 Value of supply in case of booking of tickets for travel by air provided by an air travel agent Rule 32 (3)
Domestic bookings : 5% of Basic fare
International bookings : 10% of Basic fare
Note:
Basic fare means that part of the air fare on which commission is normally paid to the air travel agent by the airlines.
Other charges and taxes are not to be included in the calculation of basic fare. 26<br>
slide27. Rule 32 Value of supply in case of life insurance business Rule 32(4)
If savings amount is separately Intimated, at the time of supply:
The gross premium charged from a policy holder reduced by the amount allocated for investment, or savings
In case of single premium annuity policies :
10% of single premium charged
If entire premium is towards risk cover :
Total premium charged
Any other case :
First year : 25% of premium charged
Subsequent year : 12.5% of premium charged 27<br>
slide28. Rule 32 For better understanding let us consider the following example :
LIC has provided the following details of various policy holders for the month of March’2020.
Value of Supply as determined in the above case would be : 28<br>
slide29. Rule 32 Value of supply in case of a person dealing in buying and selling of second hand goods Rule 32 (5)
If No ITC has been taken by the Person :
Selling price -Purchase price (Ignore if negative.)
If ITC has been taken :
Value as per Transaction value u/s 15
In case of selling of repossessed goods from a defaulting unregistered borrower:
Purchase price as reduced by 5% for every quarter or part thereof, between the date of purchase and the date of disposal. 29<br>
slide30. Rule 32 For better understanding let us consider the following example:
Mr. Honey a dealer in second hand cars purchases the cars and sells them after painting and some repair. He does not take credit of any of the purchases. He sold one car at Rs. 90000 which was purchased by him at Rs. 85000.
In the above scenario, value of supply would be Rs. 90000-85000 = Rs. 5000/-.
However if in the above scenario, the purchase price would have been Rs. Above 90000, value of supply would be Nil. 30<br>
slide31. Rule 32 Value of supply in case of a value of a token, or a voucher, or a coupon, or a stamp (other than postage stamp) which is redeemable Rule 32 (6)
Value of Supply would be Money value of the goods or services or both redeemable against such token, voucher etc.
For Example:
Easy Coupons Ltd. Sells coupons that are redeemable against specified luxury food products at retail outlets. Each coupon has a face value of Rs. 900 but is redeemable for supplies worth Rs. 1000.
So, in this case as value of the coupon is the money value of the goods redeemable against it. Therefore though the coupon is sold for Rs. 900 but its value is Rs. 1000. 31<br>
slide32. Rule 33 As per Rule 33, Irrespective of any provisions of this Chapter, the expenditure or costs incurred by a supplier as a pure agent of the recipient of supply will be excluded from the value of Supply, if all the following conditions are satisfied :-
the supplier acts as a pure agent of the recipient of the supply, when he makes the payment to the third party on authorization by such recipient;
the payment made by the pure agent on behalf of the recipient of supply has been separately indicated in the invoice issued by the pure agent to the recipient of service; and
the supplies procured by the pure agent from the third party as a pure agent of the recipient of supply are in addition to the services he supplies on his own account.
For better understanding let us consider the following example :
Mr. Ram (a CA) makes payment of GST, TDS and ROC on behalf of it’s clients. He later recovers the same from his client in addition to this service charges.
Accordingly, as Mr. Ram is acting as a pure agent, the same would not be added to the value of supply in the invoice made by Mr. Ram. 32<br>
slide33. Rule 34 Rate of Exchange of Currency, other than Indian Rupees:
Supply of Goods :
the applicable rate of exchange as notified by the Board under section 14 of the Customs Act, 1962 for the date of time of supply of such goods in terms of section 12 of the Act.
Supply of Service :
the applicable rate of exchange determined as per the generally accepted accounting principles for the date of time of supply of such services in terms of section 13 of the Act. 33<br>
slide34. Rule 35 As per Rule 35, Where the value of supply is inclusive of integrated tax or, as the case may be, central tax, State tax, Union territory tax, the tax amount shall be determined in the following manner :
Tax amount = (Value inclusive of taxes X tax rate in % of such Tax) ÷ (100+ sum of tax rates, as applicable, in %) 34<br>
slide35. Thank You So Much PAMS Professional Group 35<br>