
Volatility in Energy Prices Bahattin Buyuksahin



Description: Volatility in Energy Prices Bahattin Buyuksahin IEA, OIMD Global oil demand: exceeding 95 mbd Global oil product demand rises from 88.0 mbd in 2010 to 95.3 mbd in 2016 A total increase of 7.3 mbd equivalent to an average yearly growth
Related Topics
Download Presentation
"Volatility in Energy Prices Bahattin Buyuksahin" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Volatility in Energy Prices Bahattin Buyuksahin IEA, OIMD<br>
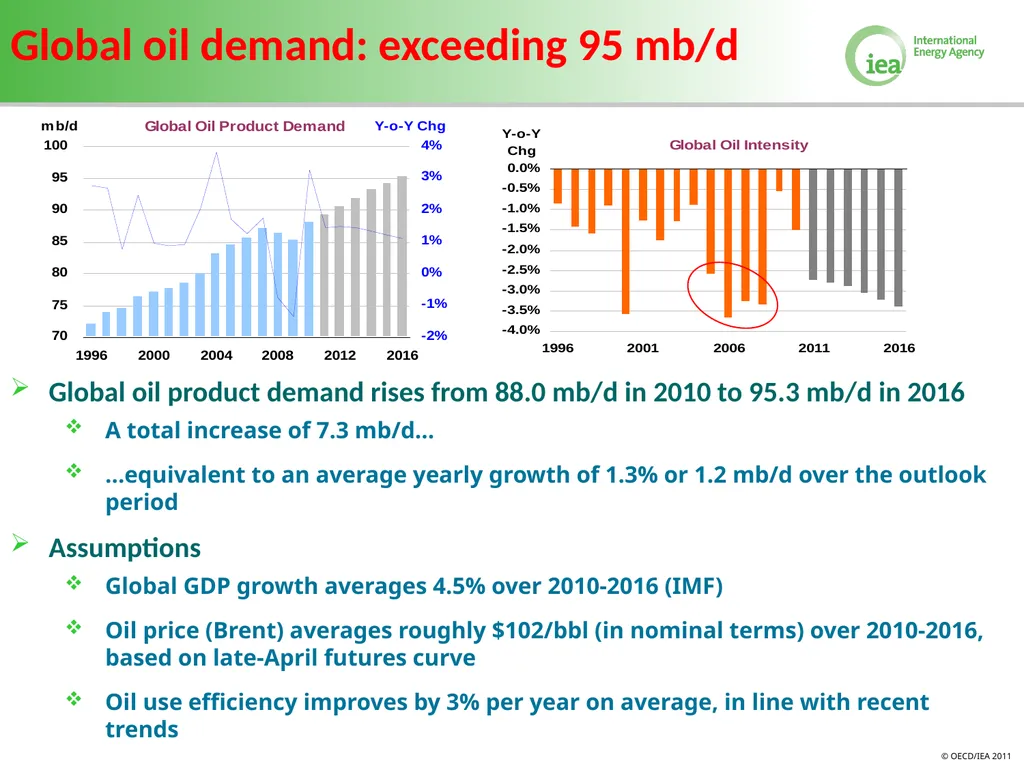
slide2. Global oil demand: exceeding 95 mb/d Global oil product demand rises from 88.0 mb/d in 2010 to 95.3 mb/d in 2016
A total increase of 7.3 mb/d…
…equivalent to an average yearly growth of 1.3% or 1.2 mb/d over the outlook period
Assumptions
Global GDP growth averages 4.5% over 2010-2016 (IMF)
Oil price (Brent) averages roughly $102/bbl (in nominal terms) over 2010-2016, based on late-April futures curve
Oil use efficiency improves by 3% per year on average, in line with recent trends<br>
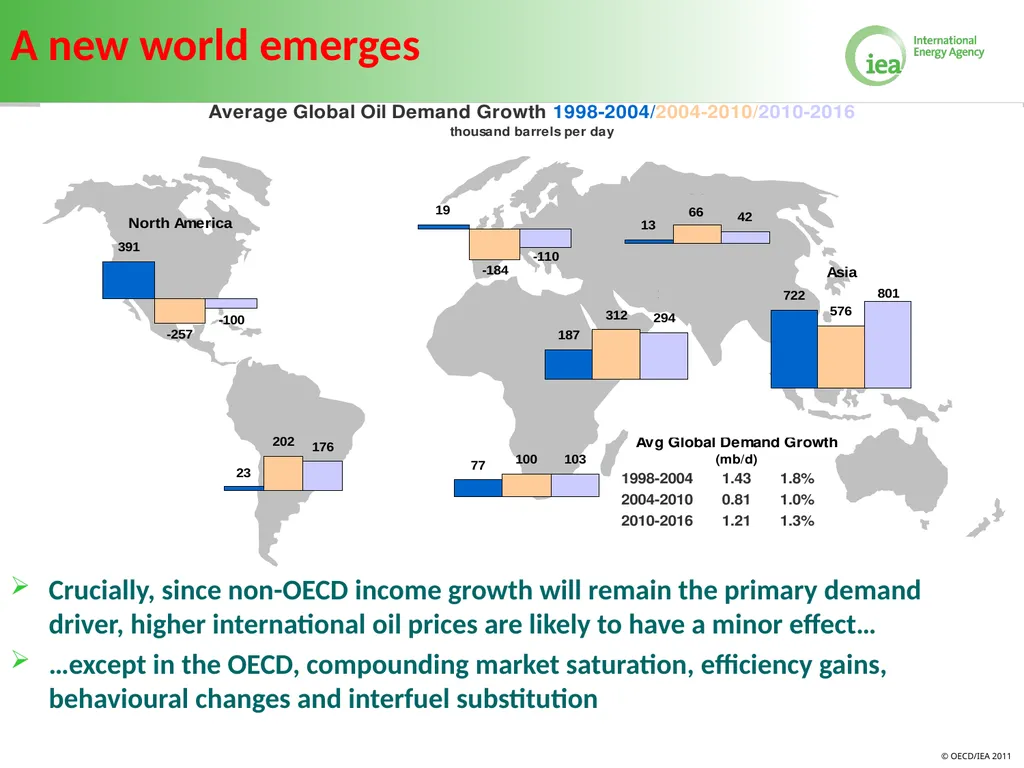
slide3. A new world emerges Crucially, since non-OECD income growth will remain the primary demand driver, higher international oil prices are likely to have a minor effect…
…except in the OECD, compounding market saturation, efficiency gains, behavioural changes and interfuel substitution<br>
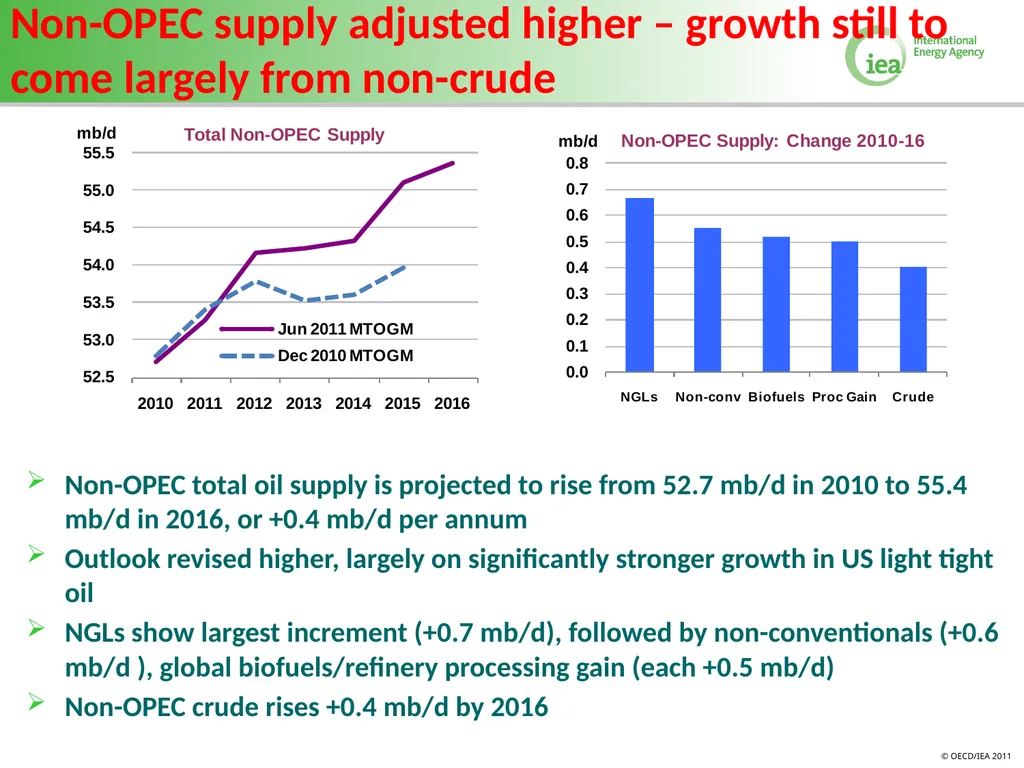
slide4. Non-OPEC supply adjusted higher – growth still to come largely from non-crude Non-OPEC total oil supply is projected to rise from 52.7 mb/d in 2010 to 55.4 mb/d in 2016, or +0.4 mb/d per annum
Outlook revised higher, largely on significantly stronger growth in US light tight oil
NGLs show largest increment (+0.7 mb/d), followed by non-conventionals (+0.6 mb/d ), global biofuels/refinery processing gain (each +0.5 mb/d)
Non-OPEC crude rises +0.4 mb/d by 2016<br>
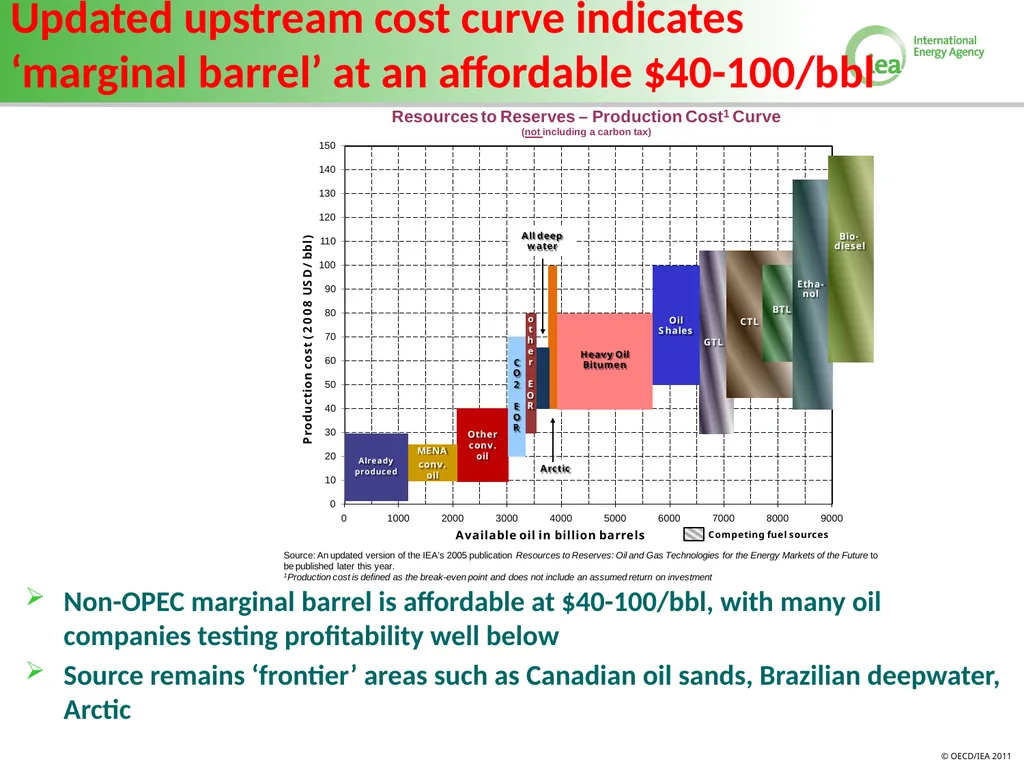
slide5. Updated upstream cost curve indicates ‘marginal barrel’ at an affordable $40-100/bbl Non-OPEC marginal barrel is affordable at $40-100/bbl, with many oil companies testing profitability well below
Source remains ‘frontier’ areas such as Canadian oil sands, Brazilian deepwater, Arctic<br>
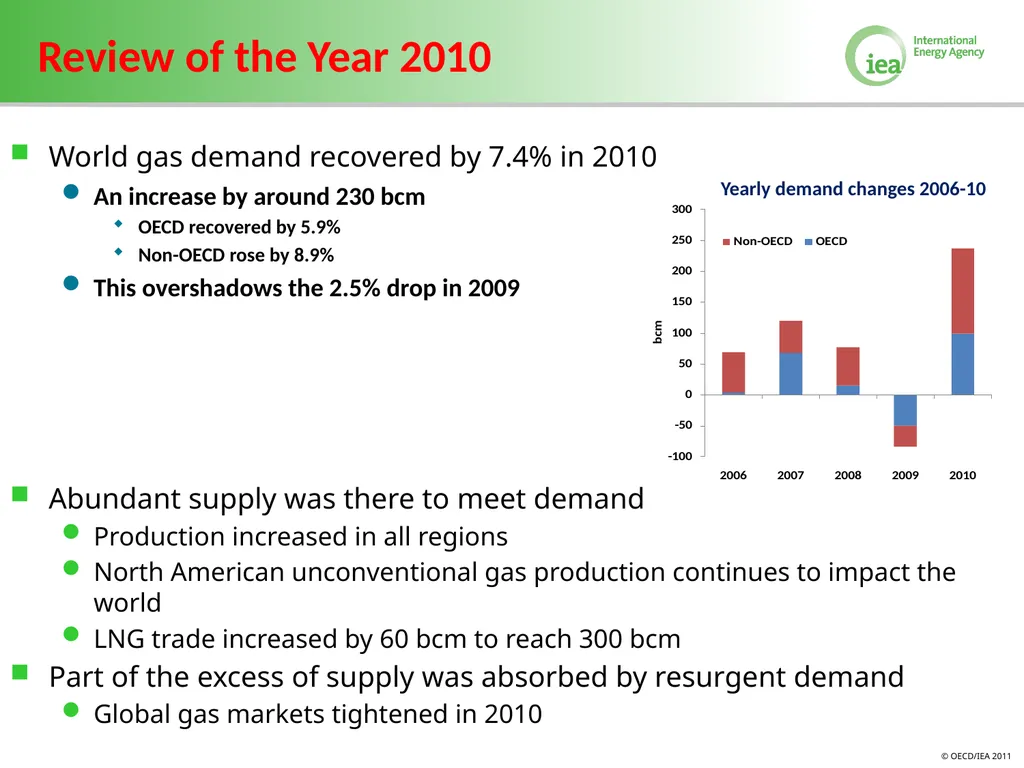
slide6. Review of the Year 2010 World gas demand recovered by 7.4% in 2010
Abundant supply was there to meet demand
Production increased in all regions
North American unconventional gas production continues to impact the world
LNG trade increased by 60 bcm to reach 300 bcm
Part of the excess of supply was absorbed by resurgent demand
Global gas markets tightened in 2010 Yearly demand changes 2006-10 An increase by around 230 bcm
OECD recovered by 5.9%
Non-OECD rose by 8.9%
This overshadows the 2.5% drop in 2009<br>
slide7. But the recovery in the OECD is partially an illusion As it is mostly driven by exceptional weather OECD gas demand has recovered to levels 3% above 2008
OECD Europe gas demand reached record levels - 568 bcm (40 bcm above 2009)
Growth in North America also driven by low gas prices
But demand was actually driven by very cold weather in Europe and OECD Pacific and a hot summer in OECD Pacific Incremental Gas demand 2010 over 2009 568 bcm 841 bcm 185 bcm Demand in 2010<br>
slide8. China – higher than all OECD countries except the US China’s gas demand was above any European or Asian gas market in 2010, reaching 106 bcm
Gas demand increased by 22% in 2010, could reach 130 bcm in 2011
According to the first drafts of the next 5-year plan, Chinese gas demand could reach 260 bcm by 2015
China has been investing to secure new supplies
Investments in domestic gas production (incl. shale gas/CBM)
LNG imports reached 13 bcm in 2010 (+67%)
The Turkmenistan-China pipeline started in December 2009 (4 bcm in 2010)
Myanmar-China pipeline is under construction (12 bcm, to start in 2013)
New LNG long-term contracts (Australia, Qatar, PNG)
Influence on global markets
Coal price setter – second coal importer and they became net importer only in 2009!
Competes for LNG, and has won Turkmen supplies<br>
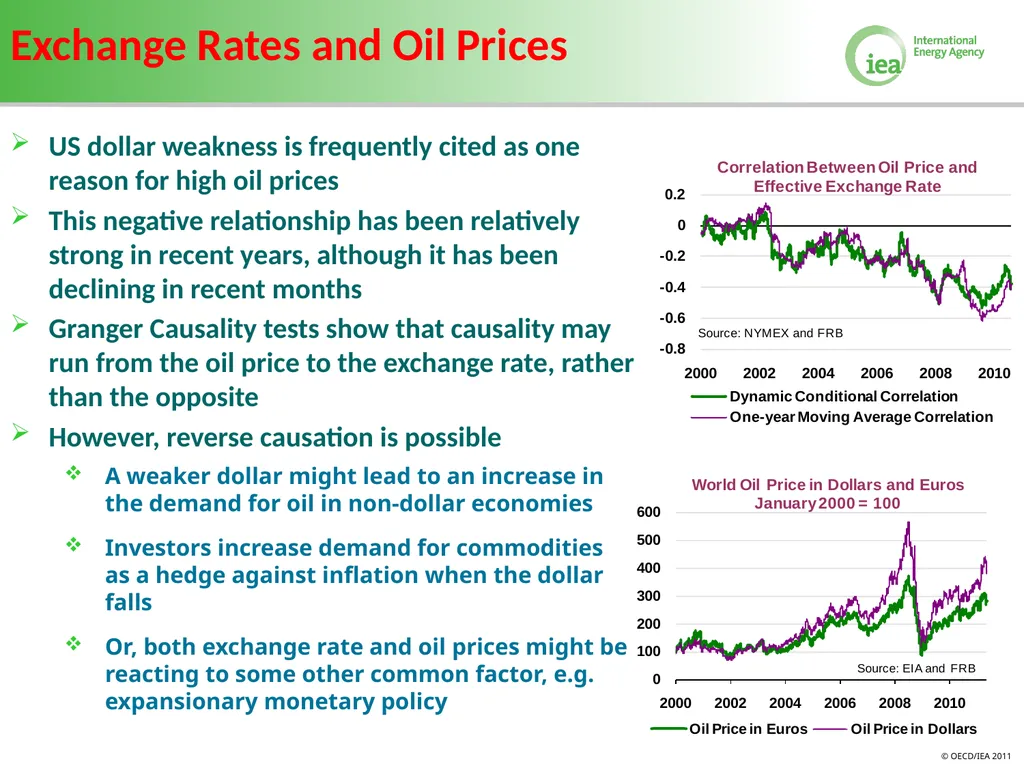
slide9. Exchange Rates and Oil Prices US dollar weakness is frequently cited as one reason for high oil prices
This negative relationship has been relatively strong in recent years, although it has been declining in recent months
Granger Causality tests show that causality may run from the oil price to the exchange rate, rather than the opposite
However, reverse causation is possible A weaker dollar might lead to an increase in the demand for oil in non-dollar economies
Investors increase demand for commodities as a hedge against inflation when the dollar falls
Or, both exchange rate and oil prices might be reacting to some other common factor, e.g. expansionary monetary policy<br>
slide10. Microeconomics: price volatility is determined by price elasticity and the size of supply – demand shocks<br>
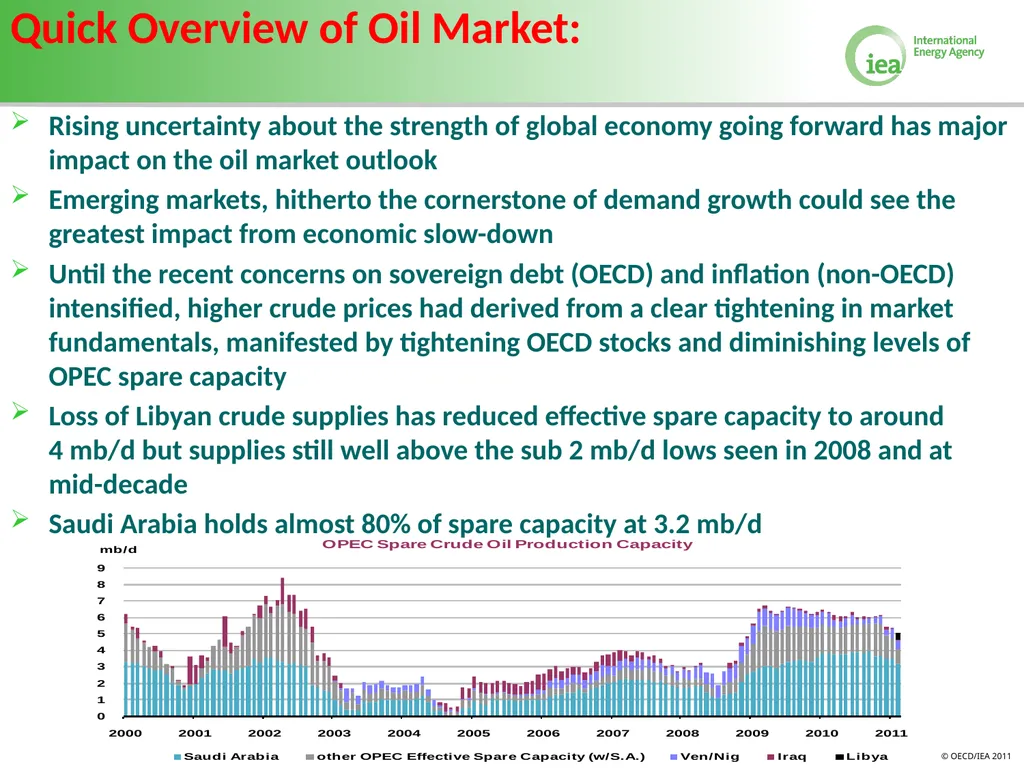
slide11. Quick Overview of Oil Market: Rising uncertainty about the strength of global economy going forward has major impact on the oil market outlook
Emerging markets, hitherto the cornerstone of demand growth could see the greatest impact from economic slow-down
Until the recent concerns on sovereign debt (OECD) and inflation (non-OECD) intensified, higher crude prices had derived from a clear tightening in market fundamentals, manifested by tightening OECD stocks and diminishing levels of OPEC spare capacity
Loss of Libyan crude supplies has reduced effective spare capacity to around 4 mb/d but supplies still well above the sub 2 mb/d lows seen in 2008 and at mid-decade
Saudi Arabia holds almost 80% of spare capacity at 3.2 mb/d<br>
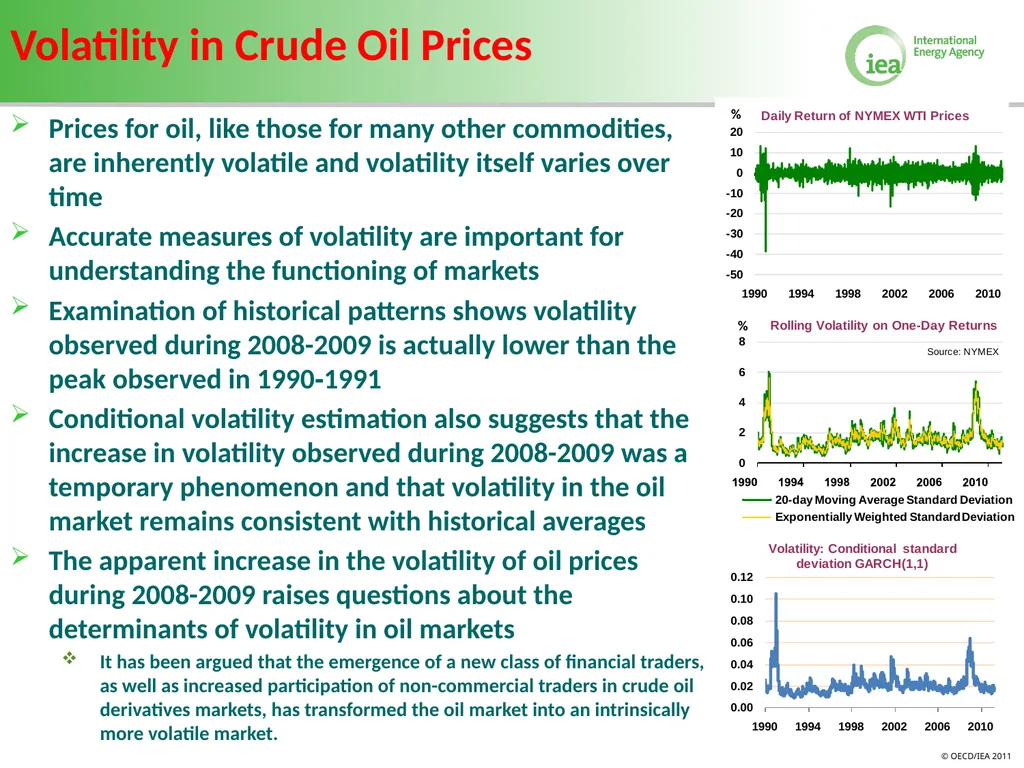
slide12. Volatility in Crude Oil Prices Prices for oil, like those for many other commodities, are inherently volatile and volatility itself varies over time
Accurate measures of volatility are important for understanding the functioning of markets
Examination of historical patterns shows volatility observed during 2008-2009 is actually lower than the peak observed in 1990‑1991
Conditional volatility estimation also suggests that the increase in volatility observed during 2008-2009 was a temporary phenomenon and that volatility in the oil market remains consistent with historical averages
The apparent increase in the volatility of oil prices during 2008-2009 raises questions about the determinants of volatility in oil markets
It has been argued that the emergence of a new class of financial traders, as well as increased participation of non-commercial traders in crude oil derivatives markets, has transformed the oil market into an intrinsically more volatile market.<br>
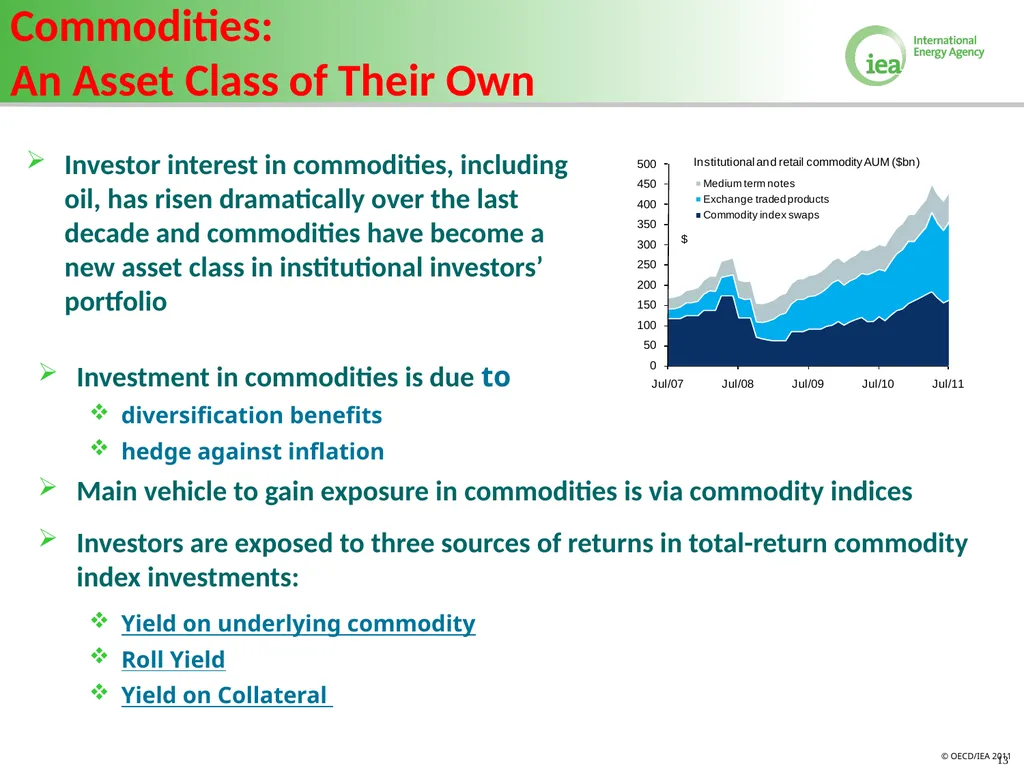
slide13. Commodities: An Asset Class of Their Own Investment in commodities is due to
diversification benefits
hedge against inflation
Main vehicle to gain exposure in commodities is via commodity indices
Investors are exposed to three sources of returns in total-return commodity index investments:
Yield on underlying commodity
Roll Yield
Yield on Collateral 13 Investor interest in commodities, including oil, has risen dramatically over the last decade and commodities have become a new asset class in institutional investors’ portfolio<br>
slide14. Commodities: An Asset Class of Their Own Coincident rise in commodity prices and commodity index investment:
Some argue that index traders’ strategic allocation changed the way in which commodity prices behave
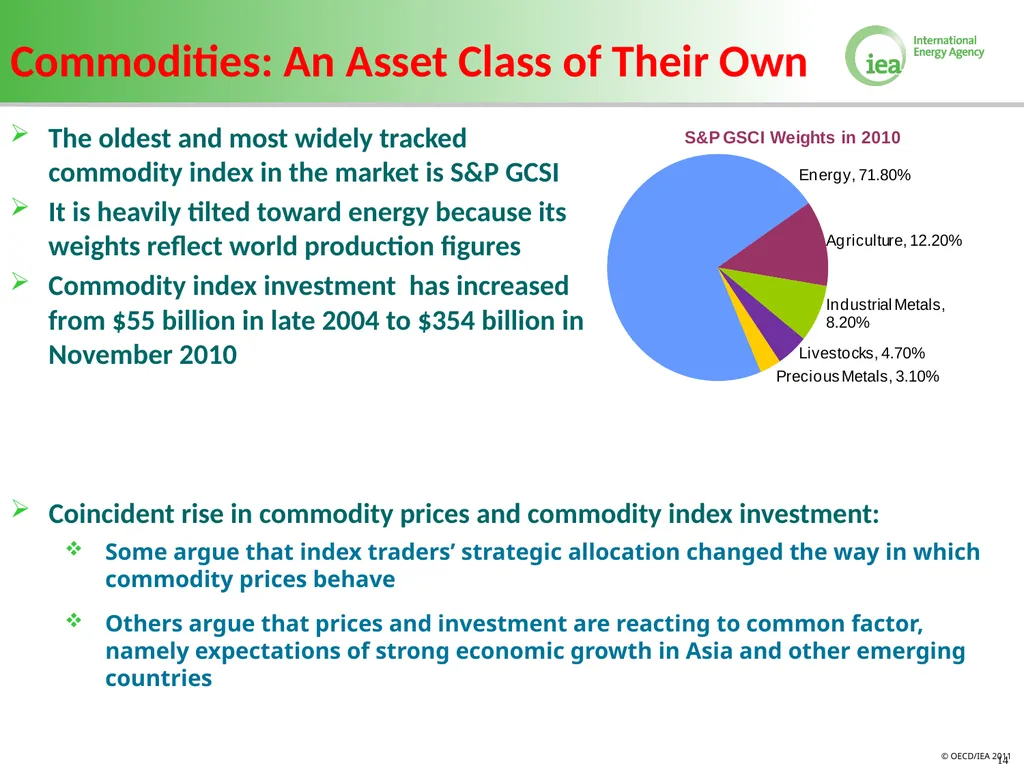
Others argue that prices and investment are reacting to common factor, namely expectations of strong economic growth in Asia and other emerging countries 14 The oldest and most widely tracked commodity index in the market is S&P GCSI
It is heavily tilted toward energy because its weights reflect world production figures
Commodity index investment has increased from $55 billion in late 2004 to $354 billion in November 2010<br>
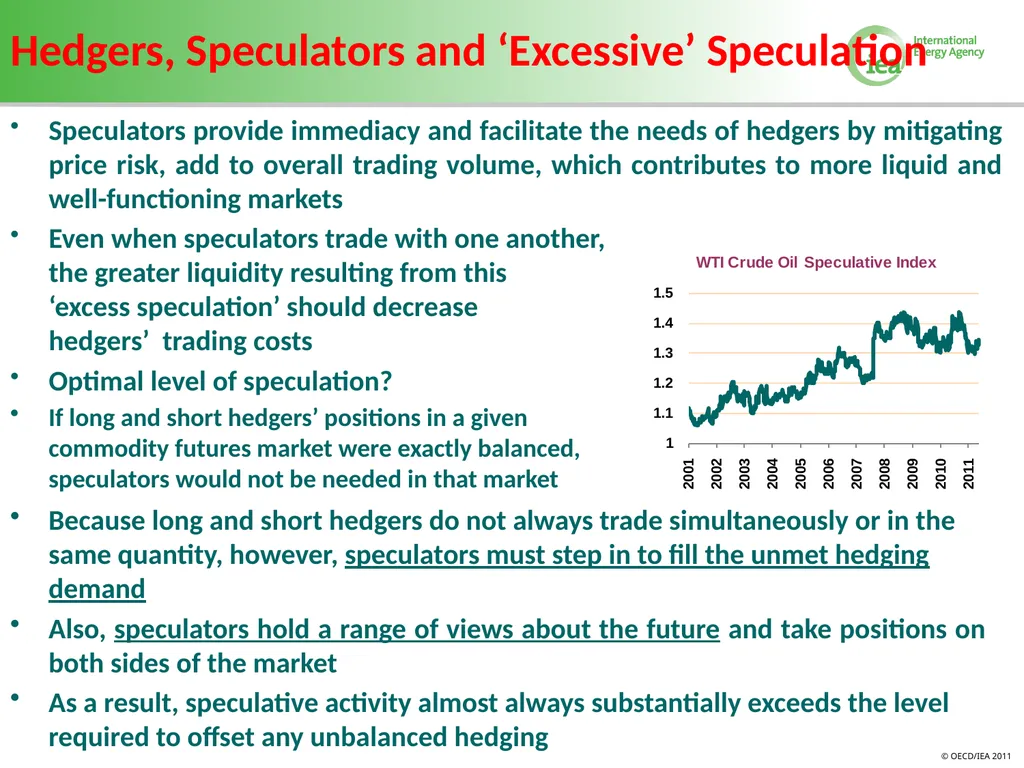
slide15. Hedgers, Speculators and ‘Excessive’ Speculation Speculators provide immediacy and facilitate the needs of hedgers by mitigating price risk, add to overall trading volume, which contributes to more liquid and well-functioning markets
Even when speculators trade with one another, the greater liquidity resulting from this ‘excess speculation’ should decrease hedgers’ trading costs
Optimal level of speculation? If long and short hedgers’ positions in a given commodity futures market were exactly balanced, speculators would not be needed in that market Because long and short hedgers do not always trade simultaneously or in the same quantity, however, speculators must step in to fill the unmet hedging demand
Also, speculators hold a range of views about the future and take positions on both sides of the market
As a result, speculative activity almost always substantially exceeds the level required to offset any unbalanced hedging<br>
slide16. Hedgers, Speculators and ‘Excessive’ Speculation The “Working” speculative index value has risen over time to an average of 1.40 in 2008, implying that speculation in excess of minimal short and long hedging needs reached 40%
While this rise in the speculative index to 1.40 may appear alarming, in fact it is comparable to historical index numbers observed in other commodity markets
Further, while a sharp rise in the speculative index was visible at the time crude prices rose to record highs in 2008, such a relationship is much less apparent for the 2010/2011 period
Academic opinion remains highly polarised on the respective roles of hedgers and speculators, and on the concept of ‘excessive’ speculation in the crude oil market
Some argue that speculative activity in crude oil futures markets does not lead price changes, but reduces volatility by enhancing market liquidity.
Others find significant impact of investment flows by non-user participants on prices and volatility of commodities.
However, both groups agree on the fact that cross-market linkages (commodity-commodity, commodity-equity) have remained very high or exceptionally strong since autumn 2008<br>
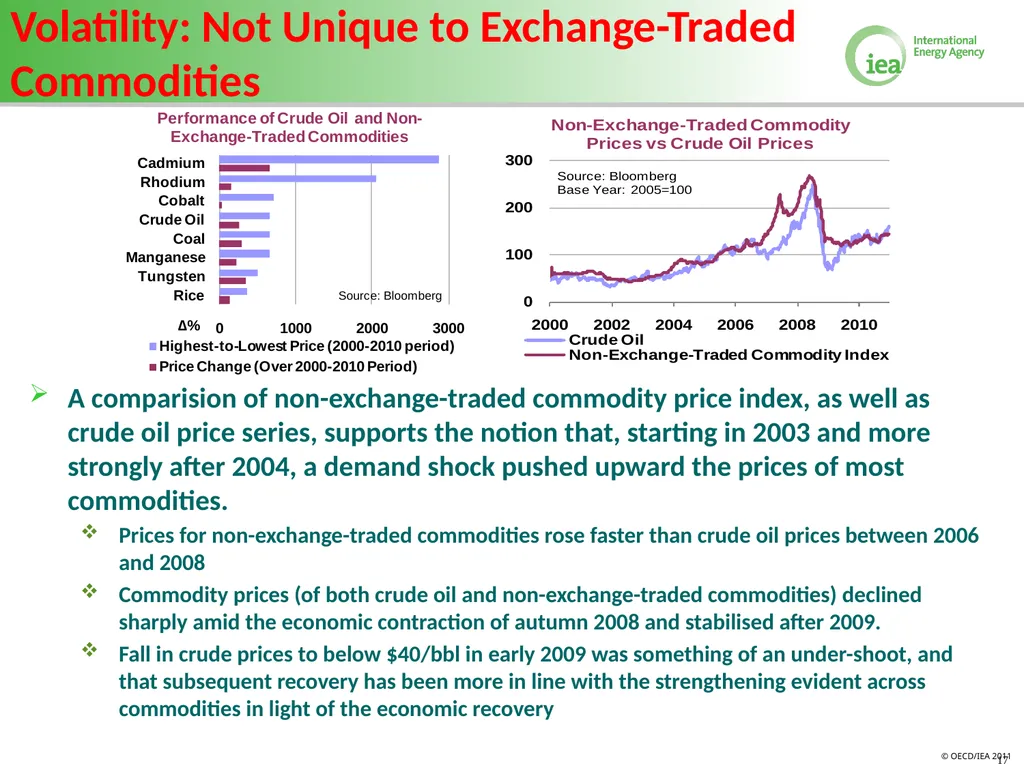
slide17. Volatility: Not Unique to Exchange-Traded Commodities A comparision of non-exchange-traded commodity price index, as well as crude oil price series, supports the notion that, starting in 2003 and more strongly after 2004, a demand shock pushed upward the prices of most commodities.
Prices for non-exchange-traded commodities rose faster than crude oil prices between 2006 and 2008
Commodity prices (of both crude oil and non-exchange-traded commodities) declined sharply amid the economic contraction of autumn 2008 and stabilised after 2009.
Fall in crude prices to below $40/bbl in early 2009 was something of an under-shoot, and that subsequent recovery has been more in line with the strengthening evident across commodities in light of the economic recovery 17<br>
slide18. Volatility in commodities rose sharply after 2006 Non-exchange-traded commodities’ index volatility experienced a large spike in early 2007 while crude oil prices were still relatively stable
Unusually high volatility in commodity markets post-2007 does not appear unique to crude oil traded on exchanges
Other commodities that are not traded in exchanges experienced similar fluctuations and price surges in the second part of 2000s.
Volatility declined for both crude and non exchange-traded commodities once again through 2010.
This is not to say that the trading of futures and derivatives contracts on exchanges has no impact on price levels and volatility.
However, it does suggest that a more holistic and refined set of policy responses than simply ‘driving out the speculator’ may be needed to achieve more stable and predictable markets. 18<br>
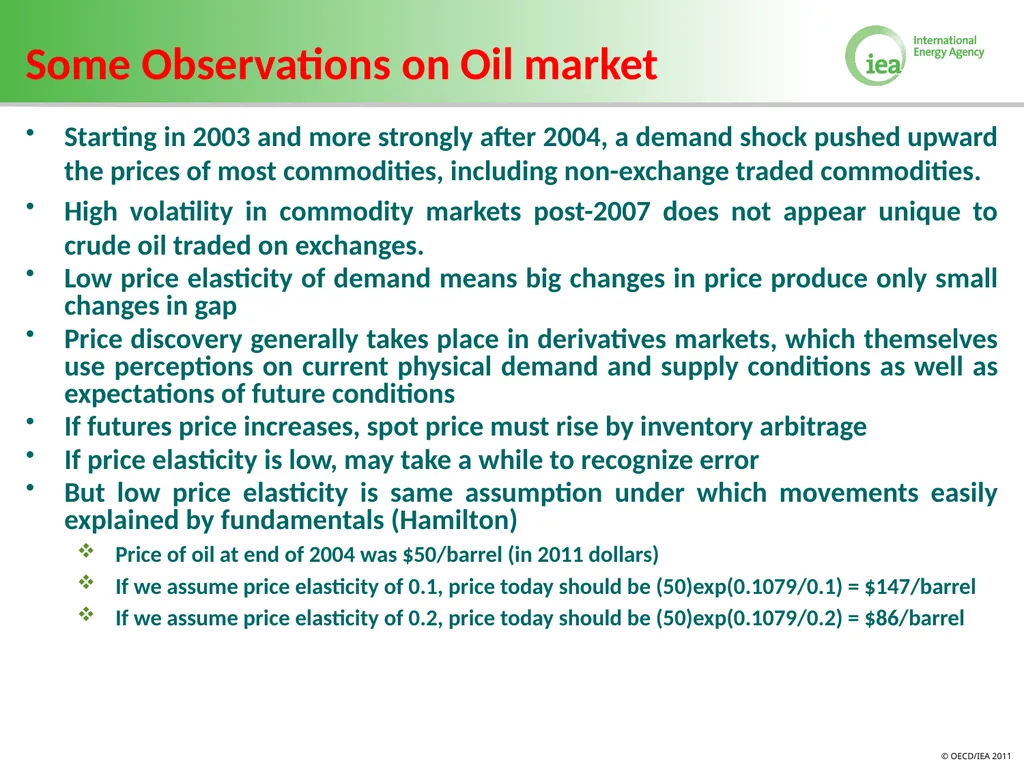
slide19. Some Observations on Oil market Starting in 2003 and more strongly after 2004, a demand shock pushed upward the prices of most commodities, including non-exchange traded commodities.
High volatility in commodity markets post-2007 does not appear unique to crude oil traded on exchanges.
Low price elasticity of demand means big changes in price produce only small changes in gap
Price discovery generally takes place in derivatives markets, which themselves use perceptions on current physical demand and supply conditions as well as expectations of future conditions
If futures price increases, spot price must rise by inventory arbitrage
If price elasticity is low, may take a while to recognize error
But low price elasticity is same assumption under which movements easily explained by fundamentals (Hamilton)
Price of oil at end of 2004 was $50/barrel (in 2011 dollars)
If we assume price elasticity of 0.1, price today should be (50)exp(0.1079/0.1) = $147/barrel
If we assume price elasticity of 0.2, price today should be (50)exp(0.1079/0.2) = $86/barrel<br>
slide20. Gas and Coal: Stylised facts, supply Supply
Gas: large exploration costs and lead times, rigid infrastructure leads to inelastic supply
Shale gas production technology is more elastic due to scaleability
Open pit coal mining is reasonably elastic due to high share of cash costs
Infrastructure bottlenecks in general lead to inelastic supply
Demand
Coal: mainly used in baseload power generation – low price elasticity of demand
Gas: Inelastic demand in heating, power is the key demand driver
Relative utilisation of coal and gas plants provide subsititution, elasticity depends on infrastructure and power market efficiency, elasticity between<br>
slide21. Oil and gas Demand side substitution (HFO in power and industry) now minimal in OECD, some in petrochemicals
LNG + Shale gas lead to different supply fundamentals
More competition for gas in power than for oil in transport
BUT: long-term contracts create rigidity and powerful support for oil indexation (Gazprom, Sonatrach, Qatar)<br>
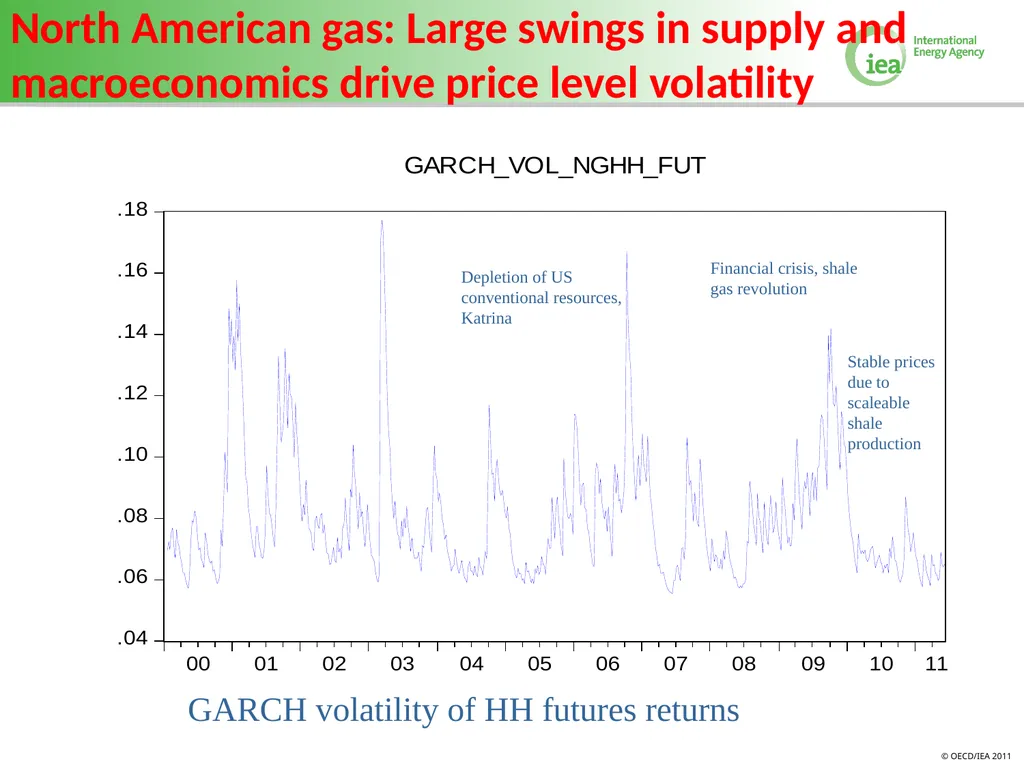
slide22. North American gas: Large swings in supply and macroeconomics drive price level volatility Depletion of US conventional resources, Katrina Financial crisis, shale gas revolution Stable prices due to scaleable shale production GARCH volatility of HH futures returns<br>
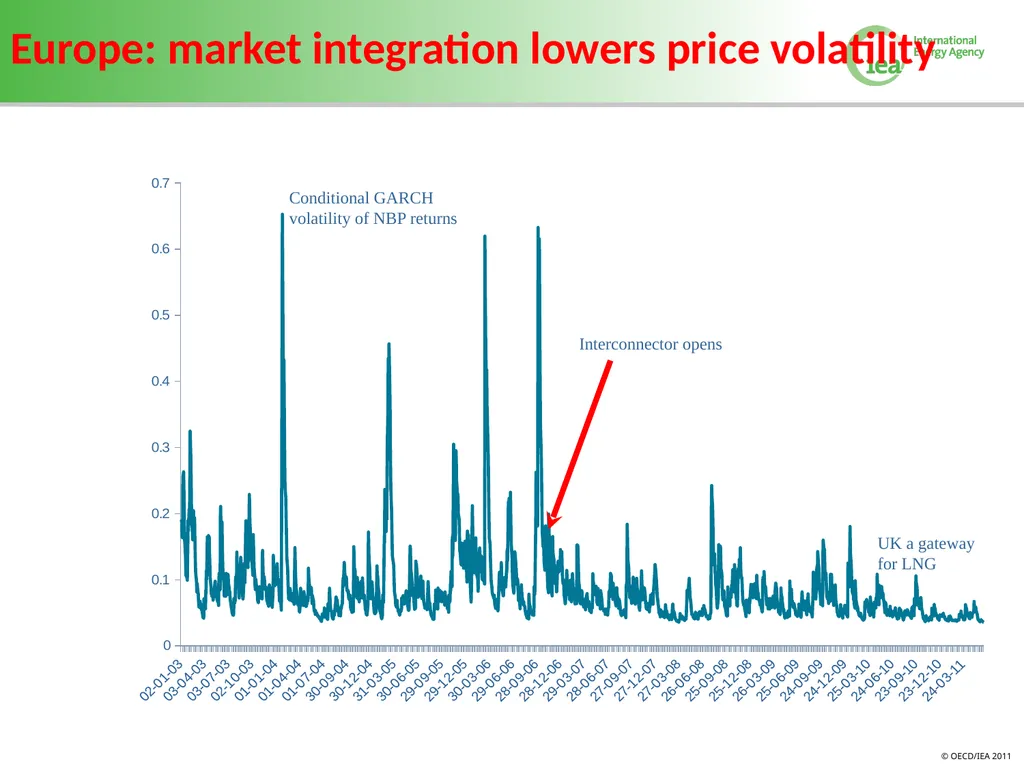
slide23. Europe: market integration lowers price volatility Conditional GARCH volatility of NBP returns Interconnector opens UK a gateway for LNG<br>
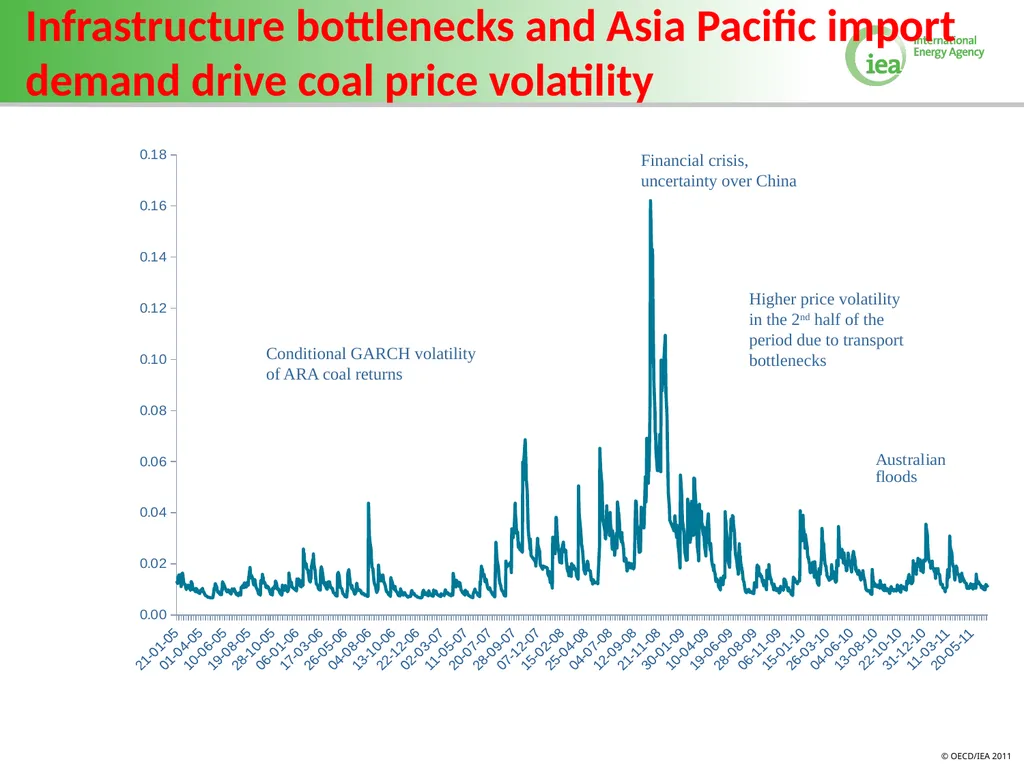
slide24. Infrastructure bottlenecks and Asia Pacific import demand drive coal price volatility Financial crisis, uncertainty over China Higher price volatility in the 2nd half of the period due to transport bottlenecks Conditional GARCH volatility of ARA coal returns<br>
slide25. Some Observations on Gas and Coal market No sign of financial speculation having and effect on price volatility
The fundamentals WERE very volatile: depletion in conventional US and North Sea gas, Chinese coal, macroeconomics
European and Asian gas and coal in general would benefit from more rather than less derivatives trading
Market integration reduces volatility
Adequate infrastructure reduces volatility<br>
slide26. How Transparent Are Crude Oil Markets? Limited publicly available data in both physical and financial markets makes it very hard to provide a definitive answer to the question of role of financial players on crude oil prices.
Understanding the linkages between physical and financial markets on price formation requires more complete information on both than is currently available.
Traders in derivatives markets rely on signals from current and expected physical fundamentals, but these signals can be distorted by imperfect or delayed information flows.
It is crucial to have more timely and reliable information from physical markets in order to address the observed volatility as well as to determine the influence of different market participants on prices.
Data limitations are not restricted to physical oil markets. Energy derivatives markets are also partially opaque.
The best available data comes from the US Commodity Futures Trading Commission’s (CFTC) Commitments of Traders Report, which is not perfect to analyse the role of financial players on crude prices. 26 Source: IEA Oil Market Report<br>
slide27. Shortcomings of CFTC COT Reports The distinction between hedging and speculation in futures markets is less clear than it may appear.
CFTC’s public reports fail to differentiate between traditional and non-traditional hedgers in the commercial category, due to active non-traditional commodity speculative activity by some commercial traders in the same commodity market.
The public reports do not provide any indication of the intraday activities of many traders, including scalpers and day-traders.
CFTC should consider re-classifying some of the commercial traders based on their trading patterns (as well as their hedging exemptions or their cash positions)
It may be advisable to publish the cash positions held by commercial traders to understand the size of their true hedging needs.
More frequent (daily) release of the end of day positions held in the aggregate by different trader groups, as well as more refined information by contract maturity (rather than the current aggregation of all maturity contracts), are needed 27 Source: IEA Oil Market Report<br>
slide28. Transparency in Other Derivatives Markets Activities that occur in other markets and other instruments can also affect futures markets: (i) the trading of OTC derivatives contracts; (ii) the trading on exempt commercial markets (ECMs); and (iii) the trading on foreign boards of trade.
Since transactions on the OTC market primarily deal with privately‐negotiated contracts, the OTC derivatives market is essentially opaque.
Some participants argue that hiding volumes in OTC markets is very difficult since traders know their counterparties.
Recent regulatory proposals require mandatory reporting of almost all OTC transactions to trade repositories or regulators. More transparency in OTC derivatives is to be welcomed in order to understand the role of financial traders on prices.
The 2010 Dodd-Frank Act eliminates the category of ECM from the US Commodity Exchange Act (CEA), which will lead to full dissemination of positions established in any contract by traders in these markets.
Foreign boards of trade should also be encouraged to start providing detailed information on large trader positions in order to increase market transparency. This is crucial, since some similar contracts are traded in more than one exchange in different countries. 28 Source: IEA Oil Market Report<br>
slide29. Transparency in Price Reporting Agencies The G20 Seoul Summit Leaders' Declaration in November 11 – 12, 2010 requested "the IEF, IEA, OPEC and IOSCO to produce a joint report, by the April 2011 Finance Ministers’ meeting, on how the oil spot market prices are assessed by oil price reporting agencies (“PRAs”) and how this affects the transparency and functioning of oil markets".
Terms of Reference
What is a price-reporting agency? Ownership, control, organization, activities, etc.
How does the physical price assessment process work?
Who is able to participate (and under what conditions)?
How representative are the data?
What is the potential for manipulation and/or collusion?
How transparent are price reporter benchmarks?
How are complaints about the benchmark and methodology handled?
What is the value (notional and real) or financial derivatives that are based off of the leverage price?
Range of benchmarks and appropriateness in Asian markets?
What is the impact of selective reporting<br>
slide30. PRAs PRAs are privately owned publishers and information providers who report oil prices transacted in physical and some derivative oil markets, give an assessment of what oil price levels actually are at particular points in time, even when no actual deals have been transacted, and report news stories relevant to the oil market.
The methodologies used by the PRAs analysed in this report (APPI, Argus, ICIS and Platts) show considerable variation. The two most significant PRAs in the oil market, Argus and Platts, use a combination of mechanistic analysis and judgement.
PRAs attempt to minimize the possibility that market participants use fraudulent or other manipulative procedures to influence prices. PRAs argue that their methodologies and their judgments are intended to weed out questionable transactions, trades that are not truly “arm’s length”, and bids or offers that do not legitimately represent market prices.
The different methodologies used by the PRAs can cause the price reported by one PRA to differ from that reported by another PRA for the same crude oil benchmark
Some companies consider that some of the PRAs exercise too much power over the market. Some market participants expressed frustration that there is no one to whom they can appeal when they believe a PRA’s judgement is wrong.
Amongst the PRAs, Platts prices are firmly entrenched in the contractual fabric of the industry and it holds a dominant position.
There is considerable inertia in the industry that sees even companies that are highly critical of Platts and its methodologies continuing to use it as a price reference source in their deals, because they have long term legacy contracts based on Platts’ assessments and the short and long term derivative instruments trading in the market are also based on Platts assessments. Adopting a different price source, they say, would give the company, or more often the individual trader concerned, contractual basis risk when hedging physical contract prices in the derivative markets.
The possibility of whether the Platts eWindow can be characterized as a trading platform, thereby act as avenue for price discovery<br>
slide2. Global oil demand: exceeding 95 mb/d Global oil product demand rises from 88.0 mb/d in 2010 to 95.3 mb/d in 2016
A total increase of 7.3 mb/d…
…equivalent to an average yearly growth of 1.3% or 1.2 mb/d over the outlook period
Assumptions
Global GDP growth averages 4.5% over 2010-2016 (IMF)
Oil price (Brent) averages roughly $102/bbl (in nominal terms) over 2010-2016, based on late-April futures curve
Oil use efficiency improves by 3% per year on average, in line with recent trends<br>
slide3. A new world emerges Crucially, since non-OECD income growth will remain the primary demand driver, higher international oil prices are likely to have a minor effect…
…except in the OECD, compounding market saturation, efficiency gains, behavioural changes and interfuel substitution<br>
slide4. Non-OPEC supply adjusted higher – growth still to come largely from non-crude Non-OPEC total oil supply is projected to rise from 52.7 mb/d in 2010 to 55.4 mb/d in 2016, or +0.4 mb/d per annum
Outlook revised higher, largely on significantly stronger growth in US light tight oil
NGLs show largest increment (+0.7 mb/d), followed by non-conventionals (+0.6 mb/d ), global biofuels/refinery processing gain (each +0.5 mb/d)
Non-OPEC crude rises +0.4 mb/d by 2016<br>
slide5. Updated upstream cost curve indicates ‘marginal barrel’ at an affordable $40-100/bbl Non-OPEC marginal barrel is affordable at $40-100/bbl, with many oil companies testing profitability well below
Source remains ‘frontier’ areas such as Canadian oil sands, Brazilian deepwater, Arctic<br>
slide6. Review of the Year 2010 World gas demand recovered by 7.4% in 2010
Abundant supply was there to meet demand
Production increased in all regions
North American unconventional gas production continues to impact the world
LNG trade increased by 60 bcm to reach 300 bcm
Part of the excess of supply was absorbed by resurgent demand
Global gas markets tightened in 2010 Yearly demand changes 2006-10 An increase by around 230 bcm
OECD recovered by 5.9%
Non-OECD rose by 8.9%
This overshadows the 2.5% drop in 2009<br>
slide7. But the recovery in the OECD is partially an illusion As it is mostly driven by exceptional weather OECD gas demand has recovered to levels 3% above 2008
OECD Europe gas demand reached record levels - 568 bcm (40 bcm above 2009)
Growth in North America also driven by low gas prices
But demand was actually driven by very cold weather in Europe and OECD Pacific and a hot summer in OECD Pacific Incremental Gas demand 2010 over 2009 568 bcm 841 bcm 185 bcm Demand in 2010<br>
slide8. China – higher than all OECD countries except the US China’s gas demand was above any European or Asian gas market in 2010, reaching 106 bcm
Gas demand increased by 22% in 2010, could reach 130 bcm in 2011
According to the first drafts of the next 5-year plan, Chinese gas demand could reach 260 bcm by 2015
China has been investing to secure new supplies
Investments in domestic gas production (incl. shale gas/CBM)
LNG imports reached 13 bcm in 2010 (+67%)
The Turkmenistan-China pipeline started in December 2009 (4 bcm in 2010)
Myanmar-China pipeline is under construction (12 bcm, to start in 2013)
New LNG long-term contracts (Australia, Qatar, PNG)
Influence on global markets
Coal price setter – second coal importer and they became net importer only in 2009!
Competes for LNG, and has won Turkmen supplies<br>
slide9. Exchange Rates and Oil Prices US dollar weakness is frequently cited as one reason for high oil prices
This negative relationship has been relatively strong in recent years, although it has been declining in recent months
Granger Causality tests show that causality may run from the oil price to the exchange rate, rather than the opposite
However, reverse causation is possible A weaker dollar might lead to an increase in the demand for oil in non-dollar economies
Investors increase demand for commodities as a hedge against inflation when the dollar falls
Or, both exchange rate and oil prices might be reacting to some other common factor, e.g. expansionary monetary policy<br>
slide10. Microeconomics: price volatility is determined by price elasticity and the size of supply – demand shocks<br>
slide11. Quick Overview of Oil Market: Rising uncertainty about the strength of global economy going forward has major impact on the oil market outlook
Emerging markets, hitherto the cornerstone of demand growth could see the greatest impact from economic slow-down
Until the recent concerns on sovereign debt (OECD) and inflation (non-OECD) intensified, higher crude prices had derived from a clear tightening in market fundamentals, manifested by tightening OECD stocks and diminishing levels of OPEC spare capacity
Loss of Libyan crude supplies has reduced effective spare capacity to around 4 mb/d but supplies still well above the sub 2 mb/d lows seen in 2008 and at mid-decade
Saudi Arabia holds almost 80% of spare capacity at 3.2 mb/d<br>
slide12. Volatility in Crude Oil Prices Prices for oil, like those for many other commodities, are inherently volatile and volatility itself varies over time
Accurate measures of volatility are important for understanding the functioning of markets
Examination of historical patterns shows volatility observed during 2008-2009 is actually lower than the peak observed in 1990‑1991
Conditional volatility estimation also suggests that the increase in volatility observed during 2008-2009 was a temporary phenomenon and that volatility in the oil market remains consistent with historical averages
The apparent increase in the volatility of oil prices during 2008-2009 raises questions about the determinants of volatility in oil markets
It has been argued that the emergence of a new class of financial traders, as well as increased participation of non-commercial traders in crude oil derivatives markets, has transformed the oil market into an intrinsically more volatile market.<br>
slide13. Commodities: An Asset Class of Their Own Investment in commodities is due to
diversification benefits
hedge against inflation
Main vehicle to gain exposure in commodities is via commodity indices
Investors are exposed to three sources of returns in total-return commodity index investments:
Yield on underlying commodity
Roll Yield
Yield on Collateral 13 Investor interest in commodities, including oil, has risen dramatically over the last decade and commodities have become a new asset class in institutional investors’ portfolio<br>
slide14. Commodities: An Asset Class of Their Own Coincident rise in commodity prices and commodity index investment:
Some argue that index traders’ strategic allocation changed the way in which commodity prices behave
Others argue that prices and investment are reacting to common factor, namely expectations of strong economic growth in Asia and other emerging countries 14 The oldest and most widely tracked commodity index in the market is S&P GCSI
It is heavily tilted toward energy because its weights reflect world production figures
Commodity index investment has increased from $55 billion in late 2004 to $354 billion in November 2010<br>
slide15. Hedgers, Speculators and ‘Excessive’ Speculation Speculators provide immediacy and facilitate the needs of hedgers by mitigating price risk, add to overall trading volume, which contributes to more liquid and well-functioning markets
Even when speculators trade with one another, the greater liquidity resulting from this ‘excess speculation’ should decrease hedgers’ trading costs
Optimal level of speculation? If long and short hedgers’ positions in a given commodity futures market were exactly balanced, speculators would not be needed in that market Because long and short hedgers do not always trade simultaneously or in the same quantity, however, speculators must step in to fill the unmet hedging demand
Also, speculators hold a range of views about the future and take positions on both sides of the market
As a result, speculative activity almost always substantially exceeds the level required to offset any unbalanced hedging<br>
slide16. Hedgers, Speculators and ‘Excessive’ Speculation The “Working” speculative index value has risen over time to an average of 1.40 in 2008, implying that speculation in excess of minimal short and long hedging needs reached 40%
While this rise in the speculative index to 1.40 may appear alarming, in fact it is comparable to historical index numbers observed in other commodity markets
Further, while a sharp rise in the speculative index was visible at the time crude prices rose to record highs in 2008, such a relationship is much less apparent for the 2010/2011 period
Academic opinion remains highly polarised on the respective roles of hedgers and speculators, and on the concept of ‘excessive’ speculation in the crude oil market
Some argue that speculative activity in crude oil futures markets does not lead price changes, but reduces volatility by enhancing market liquidity.
Others find significant impact of investment flows by non-user participants on prices and volatility of commodities.
However, both groups agree on the fact that cross-market linkages (commodity-commodity, commodity-equity) have remained very high or exceptionally strong since autumn 2008<br>
slide17. Volatility: Not Unique to Exchange-Traded Commodities A comparision of non-exchange-traded commodity price index, as well as crude oil price series, supports the notion that, starting in 2003 and more strongly after 2004, a demand shock pushed upward the prices of most commodities.
Prices for non-exchange-traded commodities rose faster than crude oil prices between 2006 and 2008
Commodity prices (of both crude oil and non-exchange-traded commodities) declined sharply amid the economic contraction of autumn 2008 and stabilised after 2009.
Fall in crude prices to below $40/bbl in early 2009 was something of an under-shoot, and that subsequent recovery has been more in line with the strengthening evident across commodities in light of the economic recovery 17<br>
slide18. Volatility in commodities rose sharply after 2006 Non-exchange-traded commodities’ index volatility experienced a large spike in early 2007 while crude oil prices were still relatively stable
Unusually high volatility in commodity markets post-2007 does not appear unique to crude oil traded on exchanges
Other commodities that are not traded in exchanges experienced similar fluctuations and price surges in the second part of 2000s.
Volatility declined for both crude and non exchange-traded commodities once again through 2010.
This is not to say that the trading of futures and derivatives contracts on exchanges has no impact on price levels and volatility.
However, it does suggest that a more holistic and refined set of policy responses than simply ‘driving out the speculator’ may be needed to achieve more stable and predictable markets. 18<br>
slide19. Some Observations on Oil market Starting in 2003 and more strongly after 2004, a demand shock pushed upward the prices of most commodities, including non-exchange traded commodities.
High volatility in commodity markets post-2007 does not appear unique to crude oil traded on exchanges.
Low price elasticity of demand means big changes in price produce only small changes in gap
Price discovery generally takes place in derivatives markets, which themselves use perceptions on current physical demand and supply conditions as well as expectations of future conditions
If futures price increases, spot price must rise by inventory arbitrage
If price elasticity is low, may take a while to recognize error
But low price elasticity is same assumption under which movements easily explained by fundamentals (Hamilton)
Price of oil at end of 2004 was $50/barrel (in 2011 dollars)
If we assume price elasticity of 0.1, price today should be (50)exp(0.1079/0.1) = $147/barrel
If we assume price elasticity of 0.2, price today should be (50)exp(0.1079/0.2) = $86/barrel<br>
slide20. Gas and Coal: Stylised facts, supply Supply
Gas: large exploration costs and lead times, rigid infrastructure leads to inelastic supply
Shale gas production technology is more elastic due to scaleability
Open pit coal mining is reasonably elastic due to high share of cash costs
Infrastructure bottlenecks in general lead to inelastic supply
Demand
Coal: mainly used in baseload power generation – low price elasticity of demand
Gas: Inelastic demand in heating, power is the key demand driver
Relative utilisation of coal and gas plants provide subsititution, elasticity depends on infrastructure and power market efficiency, elasticity between<br>
slide21. Oil and gas Demand side substitution (HFO in power and industry) now minimal in OECD, some in petrochemicals
LNG + Shale gas lead to different supply fundamentals
More competition for gas in power than for oil in transport
BUT: long-term contracts create rigidity and powerful support for oil indexation (Gazprom, Sonatrach, Qatar)<br>
slide22. North American gas: Large swings in supply and macroeconomics drive price level volatility Depletion of US conventional resources, Katrina Financial crisis, shale gas revolution Stable prices due to scaleable shale production GARCH volatility of HH futures returns<br>
slide23. Europe: market integration lowers price volatility Conditional GARCH volatility of NBP returns Interconnector opens UK a gateway for LNG<br>
slide24. Infrastructure bottlenecks and Asia Pacific import demand drive coal price volatility Financial crisis, uncertainty over China Higher price volatility in the 2nd half of the period due to transport bottlenecks Conditional GARCH volatility of ARA coal returns<br>
slide25. Some Observations on Gas and Coal market No sign of financial speculation having and effect on price volatility
The fundamentals WERE very volatile: depletion in conventional US and North Sea gas, Chinese coal, macroeconomics
European and Asian gas and coal in general would benefit from more rather than less derivatives trading
Market integration reduces volatility
Adequate infrastructure reduces volatility<br>
slide26. How Transparent Are Crude Oil Markets? Limited publicly available data in both physical and financial markets makes it very hard to provide a definitive answer to the question of role of financial players on crude oil prices.
Understanding the linkages between physical and financial markets on price formation requires more complete information on both than is currently available.
Traders in derivatives markets rely on signals from current and expected physical fundamentals, but these signals can be distorted by imperfect or delayed information flows.
It is crucial to have more timely and reliable information from physical markets in order to address the observed volatility as well as to determine the influence of different market participants on prices.
Data limitations are not restricted to physical oil markets. Energy derivatives markets are also partially opaque.
The best available data comes from the US Commodity Futures Trading Commission’s (CFTC) Commitments of Traders Report, which is not perfect to analyse the role of financial players on crude prices. 26 Source: IEA Oil Market Report<br>
slide27. Shortcomings of CFTC COT Reports The distinction between hedging and speculation in futures markets is less clear than it may appear.
CFTC’s public reports fail to differentiate between traditional and non-traditional hedgers in the commercial category, due to active non-traditional commodity speculative activity by some commercial traders in the same commodity market.
The public reports do not provide any indication of the intraday activities of many traders, including scalpers and day-traders.
CFTC should consider re-classifying some of the commercial traders based on their trading patterns (as well as their hedging exemptions or their cash positions)
It may be advisable to publish the cash positions held by commercial traders to understand the size of their true hedging needs.
More frequent (daily) release of the end of day positions held in the aggregate by different trader groups, as well as more refined information by contract maturity (rather than the current aggregation of all maturity contracts), are needed 27 Source: IEA Oil Market Report<br>
slide28. Transparency in Other Derivatives Markets Activities that occur in other markets and other instruments can also affect futures markets: (i) the trading of OTC derivatives contracts; (ii) the trading on exempt commercial markets (ECMs); and (iii) the trading on foreign boards of trade.
Since transactions on the OTC market primarily deal with privately‐negotiated contracts, the OTC derivatives market is essentially opaque.
Some participants argue that hiding volumes in OTC markets is very difficult since traders know their counterparties.
Recent regulatory proposals require mandatory reporting of almost all OTC transactions to trade repositories or regulators. More transparency in OTC derivatives is to be welcomed in order to understand the role of financial traders on prices.
The 2010 Dodd-Frank Act eliminates the category of ECM from the US Commodity Exchange Act (CEA), which will lead to full dissemination of positions established in any contract by traders in these markets.
Foreign boards of trade should also be encouraged to start providing detailed information on large trader positions in order to increase market transparency. This is crucial, since some similar contracts are traded in more than one exchange in different countries. 28 Source: IEA Oil Market Report<br>
slide29. Transparency in Price Reporting Agencies The G20 Seoul Summit Leaders' Declaration in November 11 – 12, 2010 requested "the IEF, IEA, OPEC and IOSCO to produce a joint report, by the April 2011 Finance Ministers’ meeting, on how the oil spot market prices are assessed by oil price reporting agencies (“PRAs”) and how this affects the transparency and functioning of oil markets".
Terms of Reference
What is a price-reporting agency? Ownership, control, organization, activities, etc.
How does the physical price assessment process work?
Who is able to participate (and under what conditions)?
How representative are the data?
What is the potential for manipulation and/or collusion?
How transparent are price reporter benchmarks?
How are complaints about the benchmark and methodology handled?
What is the value (notional and real) or financial derivatives that are based off of the leverage price?
Range of benchmarks and appropriateness in Asian markets?
What is the impact of selective reporting<br>
slide30. PRAs PRAs are privately owned publishers and information providers who report oil prices transacted in physical and some derivative oil markets, give an assessment of what oil price levels actually are at particular points in time, even when no actual deals have been transacted, and report news stories relevant to the oil market.
The methodologies used by the PRAs analysed in this report (APPI, Argus, ICIS and Platts) show considerable variation. The two most significant PRAs in the oil market, Argus and Platts, use a combination of mechanistic analysis and judgement.
PRAs attempt to minimize the possibility that market participants use fraudulent or other manipulative procedures to influence prices. PRAs argue that their methodologies and their judgments are intended to weed out questionable transactions, trades that are not truly “arm’s length”, and bids or offers that do not legitimately represent market prices.
The different methodologies used by the PRAs can cause the price reported by one PRA to differ from that reported by another PRA for the same crude oil benchmark
Some companies consider that some of the PRAs exercise too much power over the market. Some market participants expressed frustration that there is no one to whom they can appeal when they believe a PRA’s judgement is wrong.
Amongst the PRAs, Platts prices are firmly entrenched in the contractual fabric of the industry and it holds a dominant position.
There is considerable inertia in the industry that sees even companies that are highly critical of Platts and its methodologies continuing to use it as a price reference source in their deals, because they have long term legacy contracts based on Platts’ assessments and the short and long term derivative instruments trading in the market are also based on Platts assessments. Adopting a different price source, they say, would give the company, or more often the individual trader concerned, contractual basis risk when hedging physical contract prices in the derivative markets.
The possibility of whether the Platts eWindow can be characterized as a trading platform, thereby act as avenue for price discovery<br>