Search Results for 'time volatility'
time volatility published presentations and documents on DocSlides.
Derivatives Lecture 22 Volatility
by calandra-battersby
Only non-observable variable. Historical volatili...
THE VOLATILITY OUTLOOK FOR COMMODITIES
by ellena-manuel
ROBERT ENGLE. DIRECTOR VOLATILITY INSTITUTE AT NY...
The paradox of leading for stability during volatile times
by debby-jeon
Rajnandini. “Raj” . Pillai. California State...
Credit and Counterparty Risk Systems That Read
by augustine796
Dan . diBartolomeo. . QWAFAFEW Boston. June 2015....
Forecasting Energy Market Series Using Econometric Models and Machine Learning Techniques
by finley941
Spyridon Mastrodimitris Gounaropoulos. Supervised ...
MODELING COMMODITY PRICES WITH DYNAMIC CONDITIONAL BETA
by test
ROBERT ENGLE. DIRECTOR: VOLATILITY INSTITUTE AT N...

Is London a consistently safe haven for UK Real Estate during times of instability
by adler839
Lynne Michael . London South Bank University. ERES...
The macroeconomics of time-varying uncertainty
by olivia-moreira
Nick Bloom (Stanford & NBER). Harvard, April ...
Price Discovery, Volatility Spillovers and Adequacy of Spec
by natalia-silvester
Marin Bozic. University of Minnesota-Twin Cities....
Short-term market reaction after extreme price changes of l
by lindy-dunigan
Introduction. price evolution of . liquid. stock...
The macroeconomics of time-varying uncertainty
by jane-oiler
Nick Bloom (Stanford & NBER). Harvard, April ...
Selecting The Ideal Option Strike Price Using Fibonacci
by celsa-spraggs
Part II – October 1. st. , 2015 . PART II – O...
The macroeconomics of time-varying uncertainty
by lindy-dunigan
Nick Bloom (Stanford & NBER). IMF Lectures, J...
Temporal Query Log Profiling to Improve Web Search Ranking
by alexa-scheidler
Alexander . Kotov. (UIUC). . Pranam. . Kolari....
Determinants of Credit Default Swap Spread:
by tatyana-admore
Evidence . from the Japanese Credit Derivative . ...
Path integrals for option pricing
by faustina-dinatale
Theory of . Quantum and. Complex systems. Statist...
Volatility of container ocean freight
by pamella-moone
Volatility of container ocean freight. 1. The b...
Value -at-Risk on a portfolio of Options, Futures and Equities
by stefany-barnette
Radhesh. . Agarwal (Ral13001) . Shashank Agarwal...
Term Structure Model Implementation, Calibration, and Validation
by trish-goza
2016 MFM WINTER MODELING . WORKSHOP, Master of F...
THE KEY TO SUCCESSFUL INVESTING ISN’T PREDICTING THE FUTURE, IT’S LEARNING FROM THE PAST AND UN
by karlyn-bohler
“PRINCIPLES FOR SUCCESSFUL LONG-TERM INVESTING,...
Fundamental Concept Option prices don’t move in a linear way compared to their underlying stocks
by dailyno
Using the Greeks we can understand what will happe...
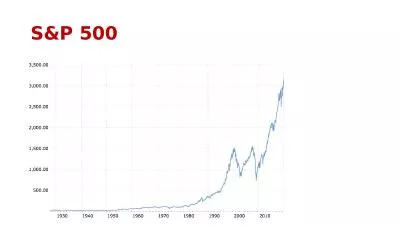
S&P 500 S&P 500, logarithmic scale
by paige
Asset price model assumption. S(t) = Asset price a...

Credit and Counterparty Risk Systems That Read Dan
by kittie-lecroy
Credit and Counterparty Risk Systems That Read Dan...