
1 THE REPUBLIC OF SOUTH AFRICA Investor

Description: 1 THE REPUBLIC OF SOUTH AFRICA Investor Presentation December 2014 Table of contents 1) Overview 3 2) Macro economic developments 8 2 3) Public finance 14 4) Financing of borrowing requirement 21 5) Holdings of government bonds 27 Slide 6)
Related Topics
Download Presentation
"1 THE REPUBLIC OF SOUTH AFRICA Investor" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. 1 THE REPUBLIC OF SOUTH AFRICA Investor Presentation
December 2014<br>
slide2. Table of contents 1) Overview 3 2) Macro economic developments 8 2 3) Public finance 14 4) Financing of borrowing requirement 21 5) Holdings of government bonds 27 Slide 6) Monetary policy 30 7) Banking sector stability 36<br>
slide3. 3 1. Overview<br>
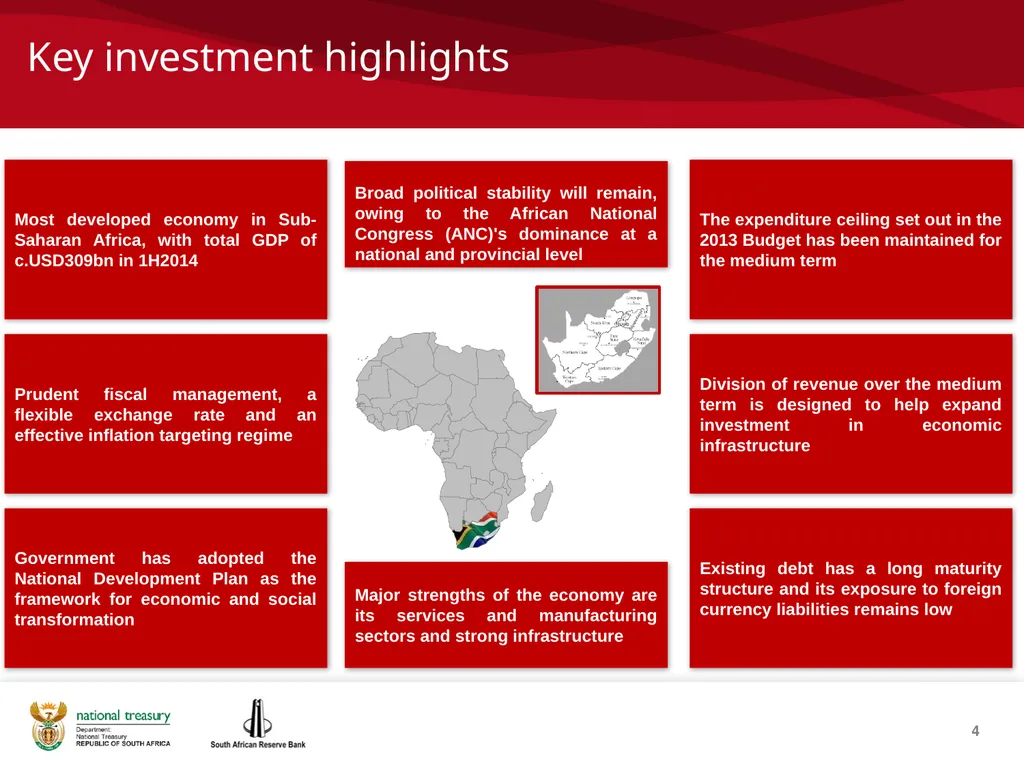
slide4. Key investment highlights 4 Broad political stability will remain, owing to the African National Congress (ANC)'s dominance at a national and provincial level<br>
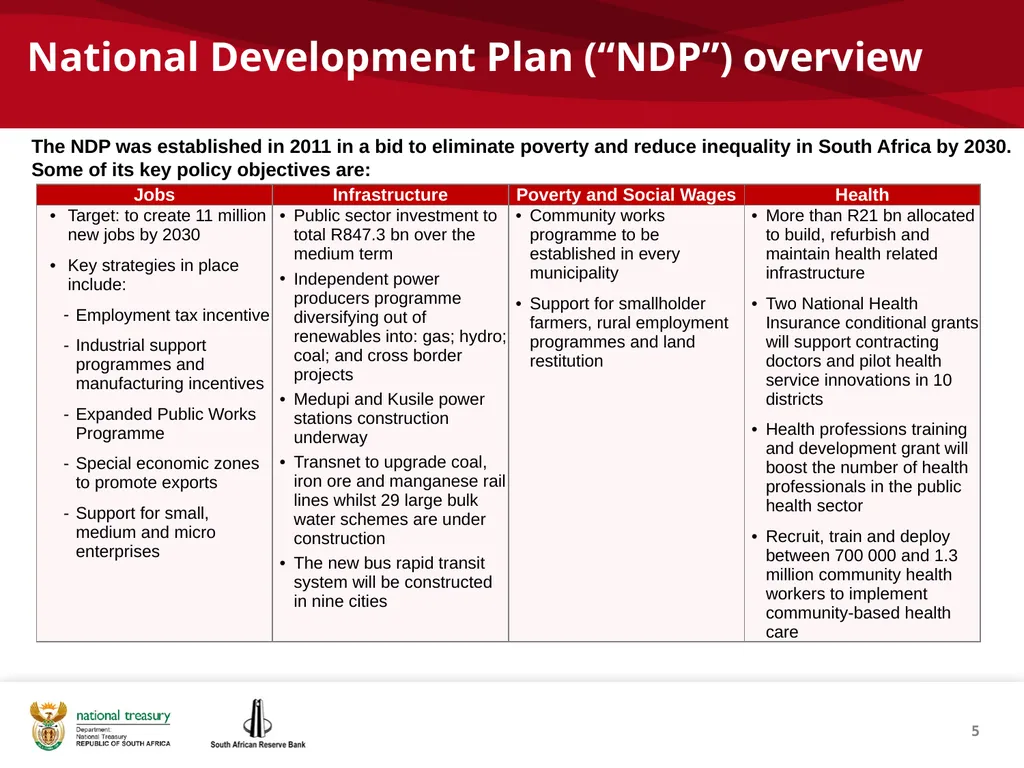
slide5. National Development Plan (“NDP”) overview 5 The NDP was established in 2011 in a bid to eliminate poverty and reduce inequality in South Africa by 2030. Some of its key policy objectives are:<br>
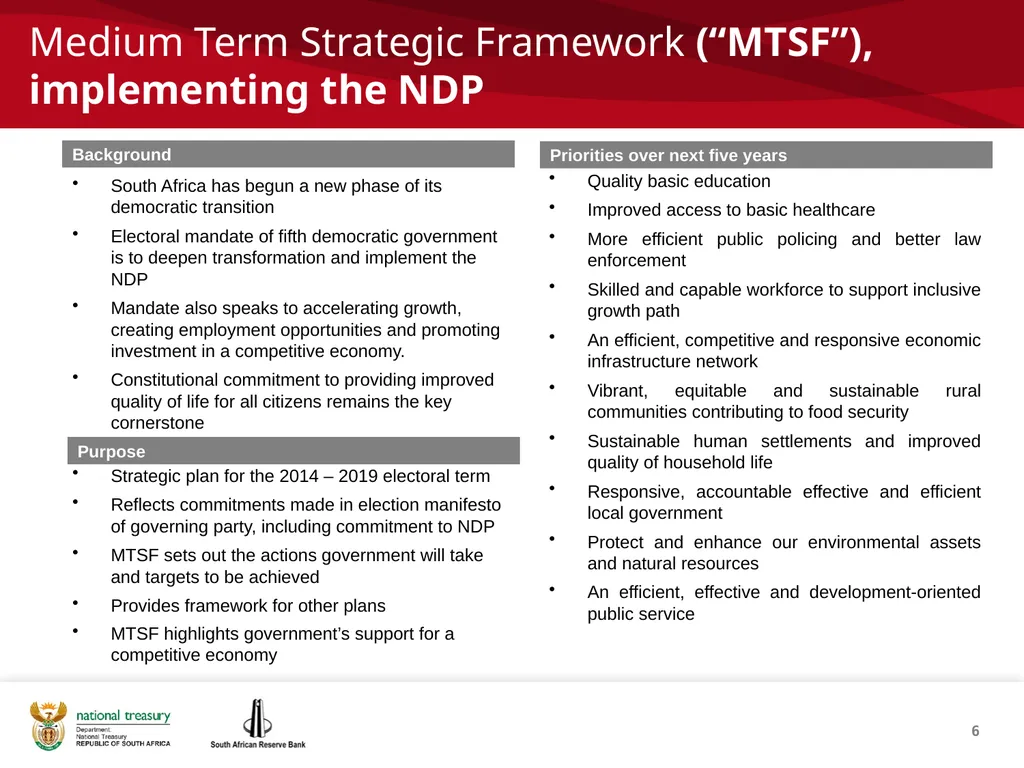
slide6. Medium Term Strategic Framework (“MTSF”), implementing the NDP South Africa has begun a new phase of its democratic transition
Electoral mandate of fifth democratic government is to deepen transformation and implement the NDP
Mandate also speaks to accelerating growth, creating employment opportunities and promoting investment in a competitive economy.
Constitutional commitment to providing improved quality of life for all citizens remains the key cornerstone
Strategic plan for the 2014 – 2019 electoral term
Reflects commitments made in election manifesto of governing party, including commitment to NDP
MTSF sets out the actions government will take and targets to be achieved
Provides framework for other plans
MTSF highlights government’s support for a competitive economy Quality basic education
Improved access to basic healthcare
More efficient public policing and better law enforcement
Skilled and capable workforce to support inclusive growth path
An efficient, competitive and responsive economic infrastructure network
Vibrant, equitable and sustainable rural communities contributing to food security
Sustainable human settlements and improved quality of household life
Responsive, accountable effective and efficient local government
Protect and enhance our environmental assets and natural resources
An efficient, effective and development-oriented public service 6 Background Priorities over next five years Purpose<br>
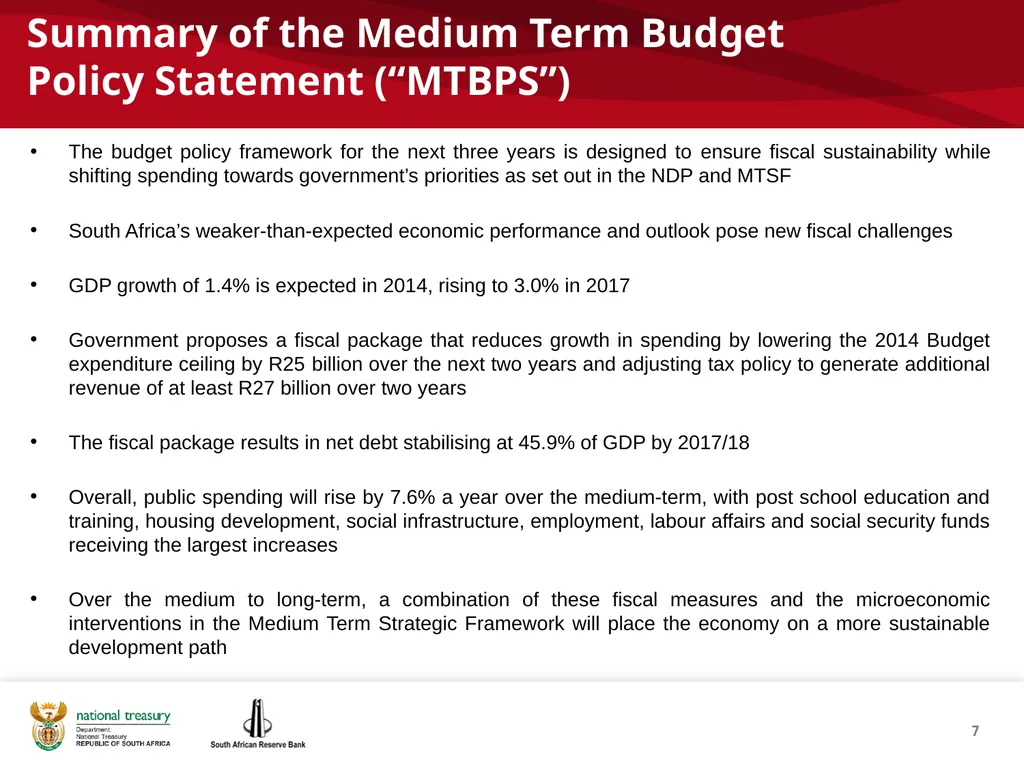
slide7. Summary of the Medium Term Budget Policy Statement (“MTBPS”) The budget policy framework for the next three years is designed to ensure fiscal sustainability while shifting spending towards government’s priorities as set out in the NDP and MTSF
South Africa’s weaker-than-expected economic performance and outlook pose new fiscal challenges
GDP growth of 1.4% is expected in 2014, rising to 3.0% in 2017
Government proposes a fiscal package that reduces growth in spending by lowering the 2014 Budget expenditure ceiling by R25`billion over the next two years and adjusting tax policy to generate additional revenue of at least R27 billion over two years
The fiscal package results in net debt stabilising at 45.9% of GDP by 2017/18
Overall, public spending will rise by 7.6% a year over the medium-term, with post school education and training, housing development, social infrastructure, employment, labour affairs and social security funds receiving the largest increases
Over the medium to long-term, a combination of these fiscal measures and the microeconomic interventions in the Medium Term Strategic Framework will place the economy on a more sustainable development path 7<br>
slide8. 8 2. Macro economic developments<br>
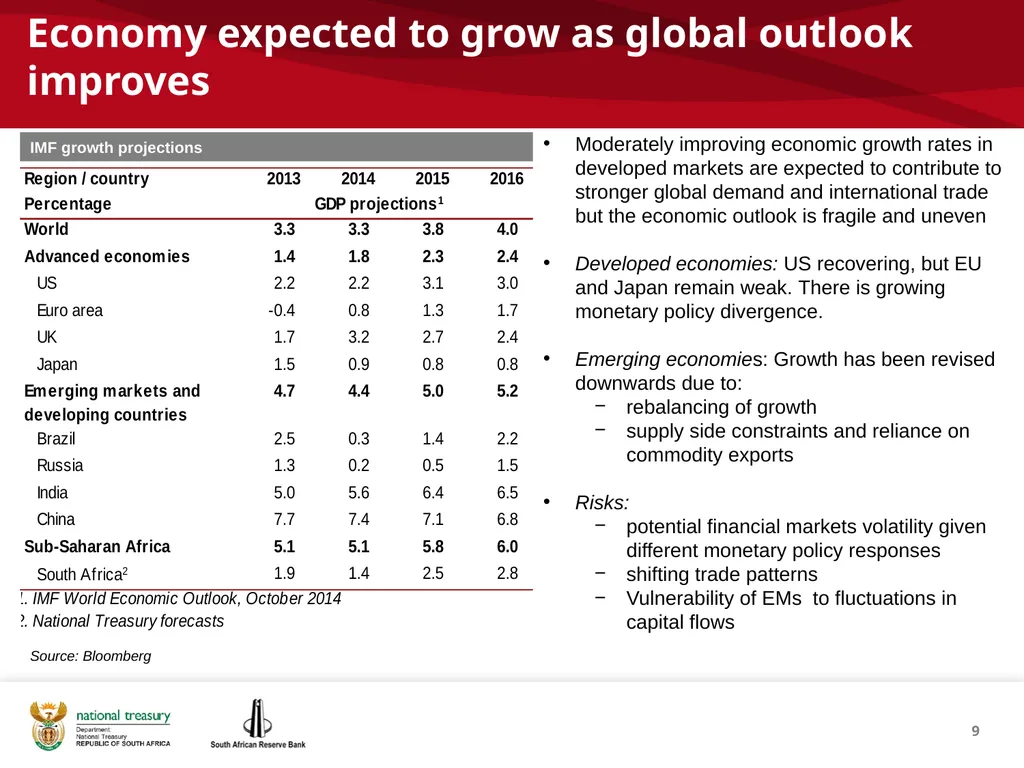
slide9. Economy expected to grow as global outlook improves Moderately improving economic growth rates in developed markets are expected to contribute to stronger global demand and international trade but the economic outlook is fragile and uneven
Developed economies: US recovering, but EU and Japan remain weak. There is growing monetary policy divergence.
Emerging economies: Growth has been revised downwards due to:
rebalancing of growth
supply side constraints and reliance on commodity exports
Risks:
potential financial markets volatility given different monetary policy responses
shifting trade patterns
Vulnerability of EMs to fluctuations in capital flows IMF growth projections Source: Bloomberg 9<br>
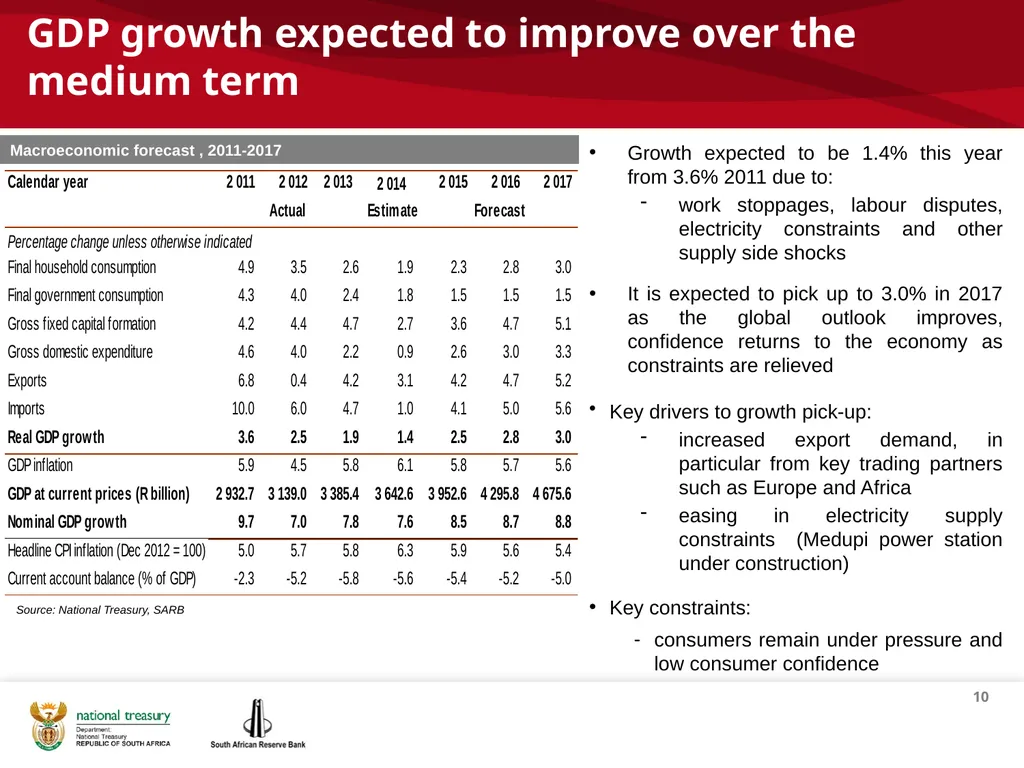
slide10. GDP growth expected to improve over the medium term 10 Growth expected to be 1.4% this year from 3.6% 2011 due to:
work stoppages, labour disputes, electricity constraints and other supply side shocks
It is expected to pick up to 3.0% in 2017 as the global outlook improves, confidence returns to the economy as constraints are relieved
Key drivers to growth pick-up:
increased export demand, in particular from key trading partners such as Europe and Africa
easing in electricity supply constraints (Medupi power station under construction)
Key constraints:
consumers remain under pressure and low consumer confidence Macroeconomic forecast , 2011-2017 Source: National Treasury, SARB<br>
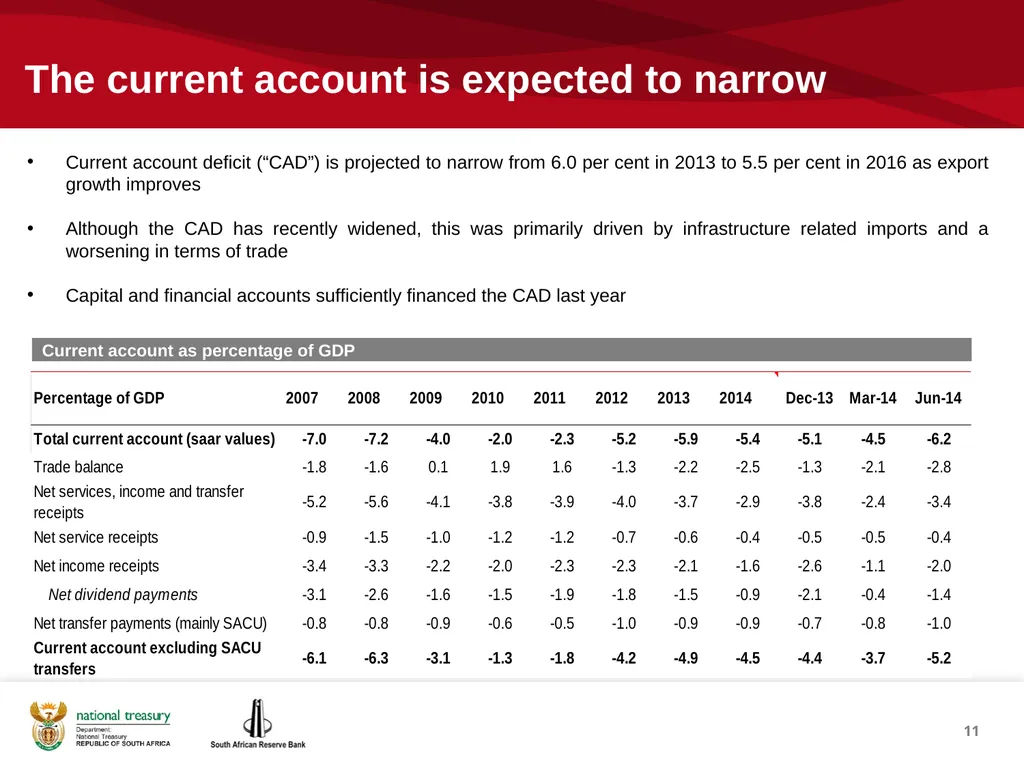
slide11. 11 The current account is expected to narrow Current account as percentage of GDP Current account deficit (“CAD”) is projected to narrow from 6.0 per cent in 2013 to 5.5 per cent in 2016 as export growth improves
Although the CAD has recently widened, this was primarily driven by infrastructure related imports and a worsening in terms of trade
Capital and financial accounts sufficiently financed the CAD last year<br>
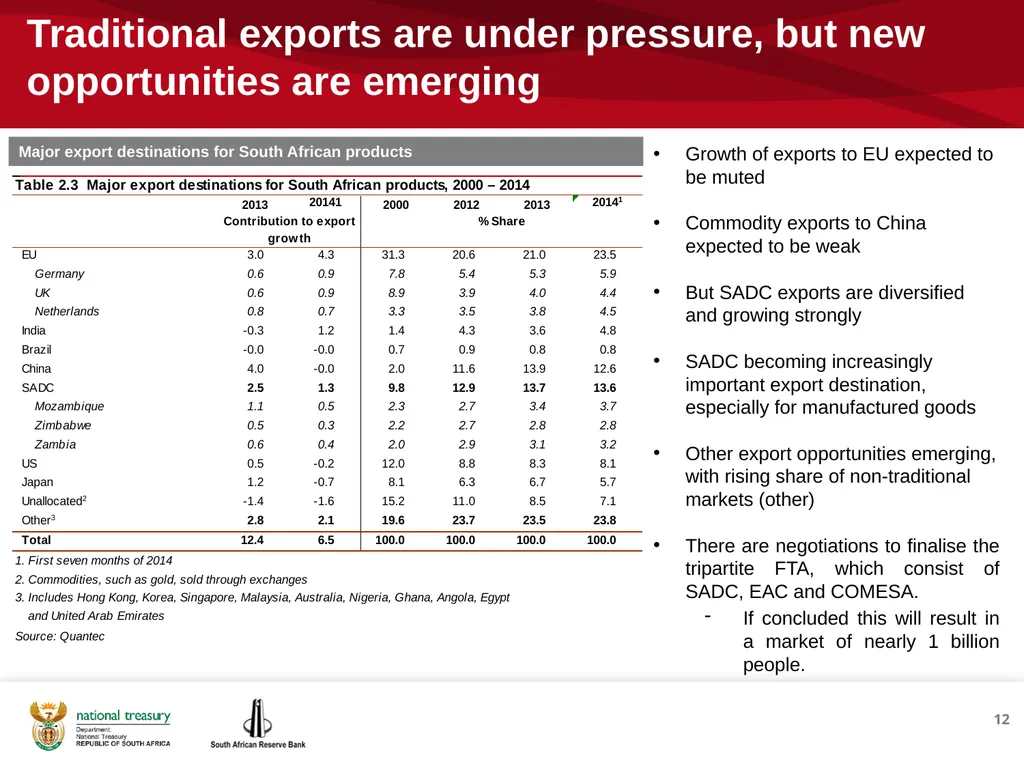
slide12. Traditional exports are under pressure, but new opportunities are emerging Growth of exports to EU expected to be muted
Commodity exports to China expected to be weak
But SADC exports are diversified and growing strongly
SADC becoming increasingly important export destination, especially for manufactured goods
Other export opportunities emerging, with rising share of non-traditional markets (other)
There are negotiations to finalise the tripartite FTA, which consist of SADC, EAC and COMESA.
If concluded this will result in a market of nearly 1 billion people. Major export destinations for South African products 12<br>
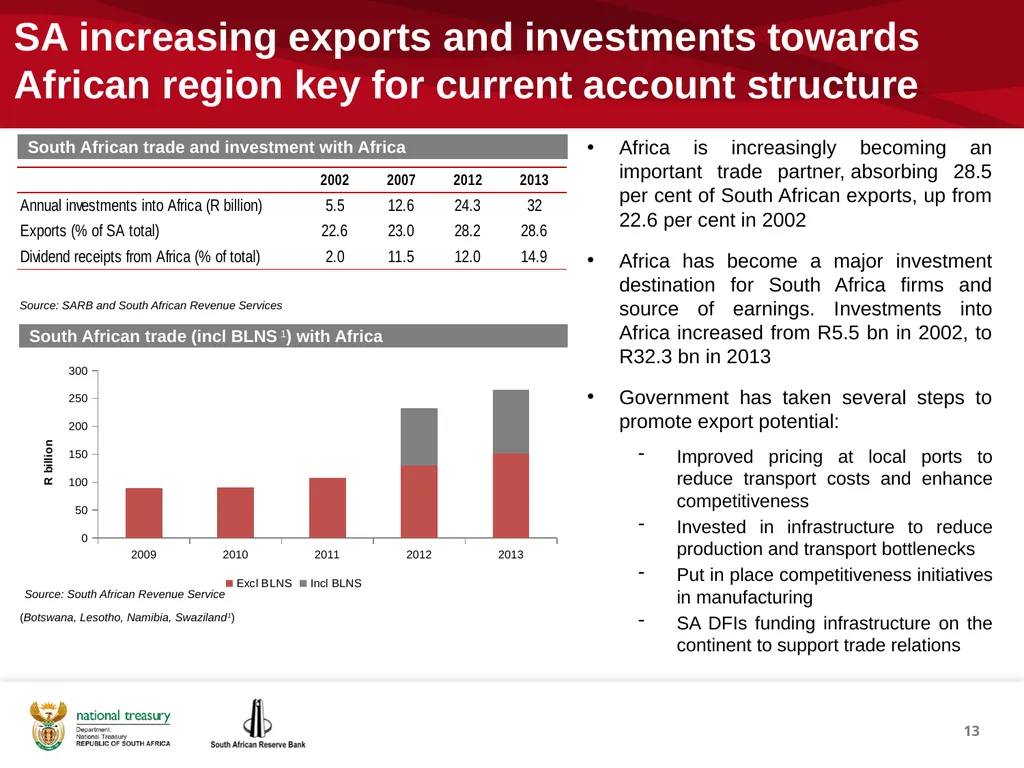
slide13. SA increasing exports and investments towards African region key for current account structure 13 Africa is increasingly becoming an important trade partner, absorbing 28.5 per cent of South African exports, up from 22.6 per cent in 2002
Africa has become a major investment destination for South Africa firms and source of earnings. Investments into Africa increased from R5.5 bn in 2002, to R32.3 bn in 2013
Government has taken several steps to promote export potential:
Improved pricing at local ports to reduce transport costs and enhance competitiveness
Invested in infrastructure to reduce production and transport bottlenecks
Put in place competitiveness initiatives in manufacturing
SA DFIs funding infrastructure on the continent to support trade relations Source: South African Revenue Service 1 (Botswana, Lesotho, Namibia, Swaziland1) South African trade (incl BLNS 1) with Africa Source: SARB and South African Revenue Services South African trade and investment with Africa<br>
slide14. 14 3. Public Finance<br>
slide15. Fiscal framework remains sound and transparent Overview Fiscal framework grounded in sustainable, countercyclical approach to managing revenue and expenditure
Government intends to balance continued support for economic recovery with fiscal consolidation
Key social and economic programmes are expected to be maintained, complemented by efforts to improve value for money
Spending is expected to be contained over the medium term expenditure framework period
Reduction of the deficit will be a combined result of government’s expenditure ceiling and revenue measures
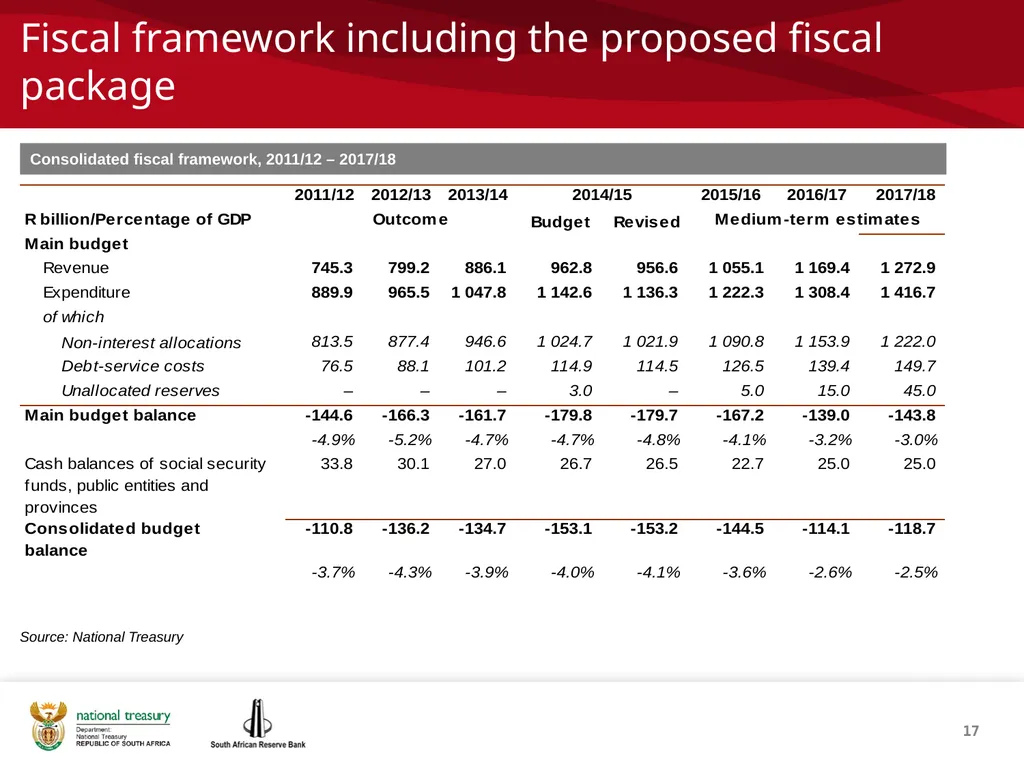
As economic growth improves and spending limits stay in place, the budget deficit is projected to narrow to 2.5 per cent of GDP by 2017/18 Fiscal priorities Maintaining the expenditure ceiling
Reducing the budget deficit
Stabilisation of debt over the medium term
Improving the composition and efficiency of spending
Cost-containment measures announ-ced by the Minister of Finance in October 2013 limit expenditure on conferences, travel, entertainment and other non-essential items
The National Treasury and Department of Performance Monitoring and Evaluation have launched a series of expenditure reviews
Tax Review Committee is investigating all aspects of the tax system to improve equity and efficiency 15<br>
slide16. Proposed fiscal package to reinforce sustainability In order to narrow the deficit and stabilise debt over the medium term, government proposes a fiscal package with the following five elements:
Reduce growth in spending by lowering the 2014 Budget expenditure ceiling by R25`billion over the next two fiscal years
Adjust tax policy and administration. Proposals will be introduced in the 2015 Budget to generate additional revenue of at least R27 billion over the next two fiscal years
Place greater emphasis on longer-term planning and efficient resource allocation, within a framework that links expenditure and economic growth beyond the medium term
Freeze government personnel headcount. Government will also review funded vacancies
Adopt a deficit-neutral approach to the financing requirements of state-owned companies over the next two fiscal years 16<br>
slide17. Fiscal framework including the proposed fiscal package 17 Consolidated fiscal framework, 2011/12 – 2017/18 Source: National Treasury<br>
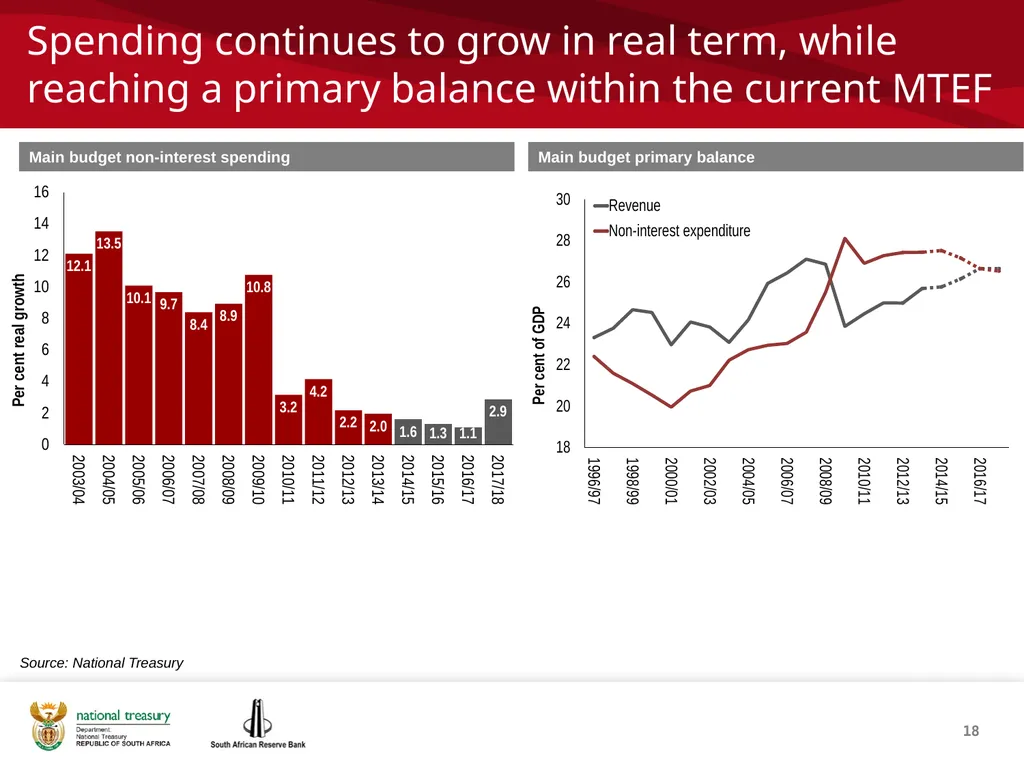
slide18. Spending continues to grow in real term, while reaching a primary balance within the current MTEF 18 Main budget non-interest spending Main budget primary balance Source: National Treasury<br>
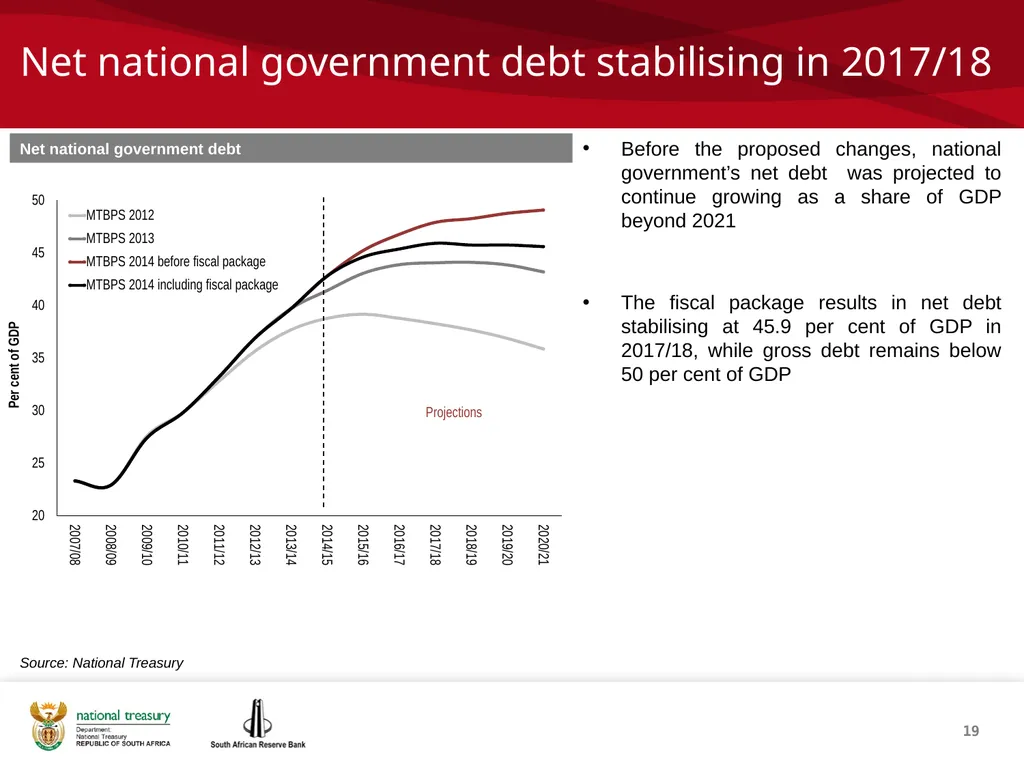
slide19. Net national government debt stabilising in 2017/18 19 Before the proposed changes, national government’s net debt was projected to continue growing as a share of GDP beyond 2021
The fiscal package results in net debt stabilising at 45.9 per cent of GDP in 2017/18, while gross debt remains below 50 per cent of GDP Net national government debt Source: National Treasury<br>
slide20. Risks to the proposed fiscal framework Economic outlook:
Rising global interest-rate cycle likely to place pressure on domestic interest rates, increasing the costs of issuing debt
The current account deficit remains persistently high, making SA more vulnerable to shifts in investment flows and market sentiment
A further deterioration in the GDP would require consideration of additional measures
Electricity constraints impact on growth
Government’s wage bill:
Budgets assume CPI cost-of-living adjustments and headcount numbers at current levels
Current constraints suggest limited scope for additional resources
Deviations from CPI-linked cost-of-living adjustments will require either a reallocation of resources or a reduction in government employment
A new framework for funding of SOCs and public entities will focus on:
Distinguishing purely commercial activities from the costs of exercising their developmental mandates
Close monitoring to ensure efficient delivery on government priorities, while simultaneously promoting improved commercial performance
Introducing more stringent financial reporting requirements for public entities
Capitalisation will be funded from sale of non-strategic state assets, and will not be drawn from tax revenue 20<br>
slide21. 21 4. Financing of borrowing requirement<br>
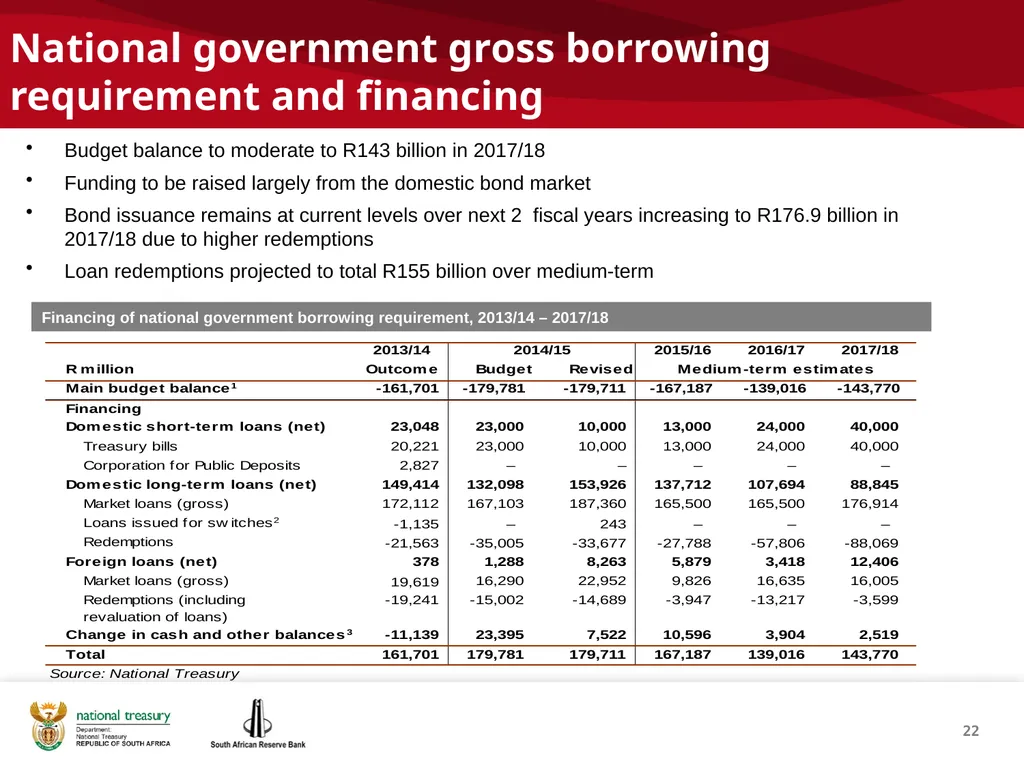
slide22. National government gross borrowing requirement and financing 22 Financing of national government borrowing requirement, 2013/14 – 2017/18 Budget balance to moderate to R143 billion in 2017/18
Funding to be raised largely from the domestic bond market
Bond issuance remains at current levels over next 2 fiscal years increasing to R176.9 billion in 2017/18 due to higher redemptions
Loan redemptions projected to total R155 billion over medium-term<br>
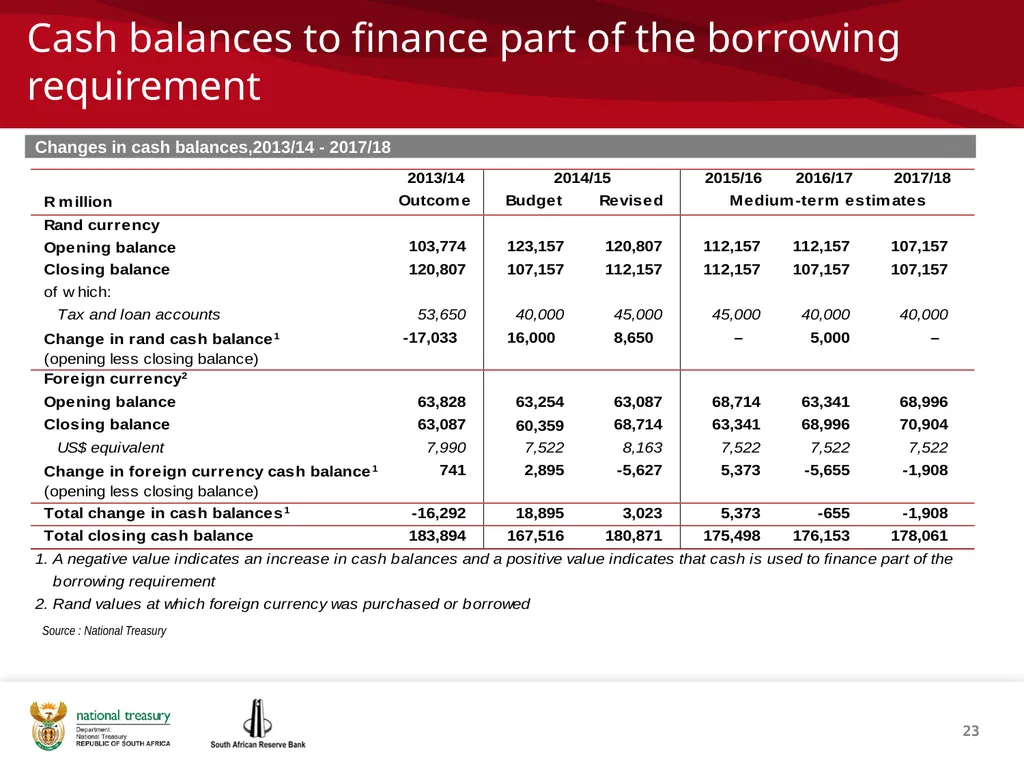
slide23. Cash balances to finance part of the borrowing requirement 23 Source : National Treasury Changes in cash balances,2013/14 - 2017/18<br>
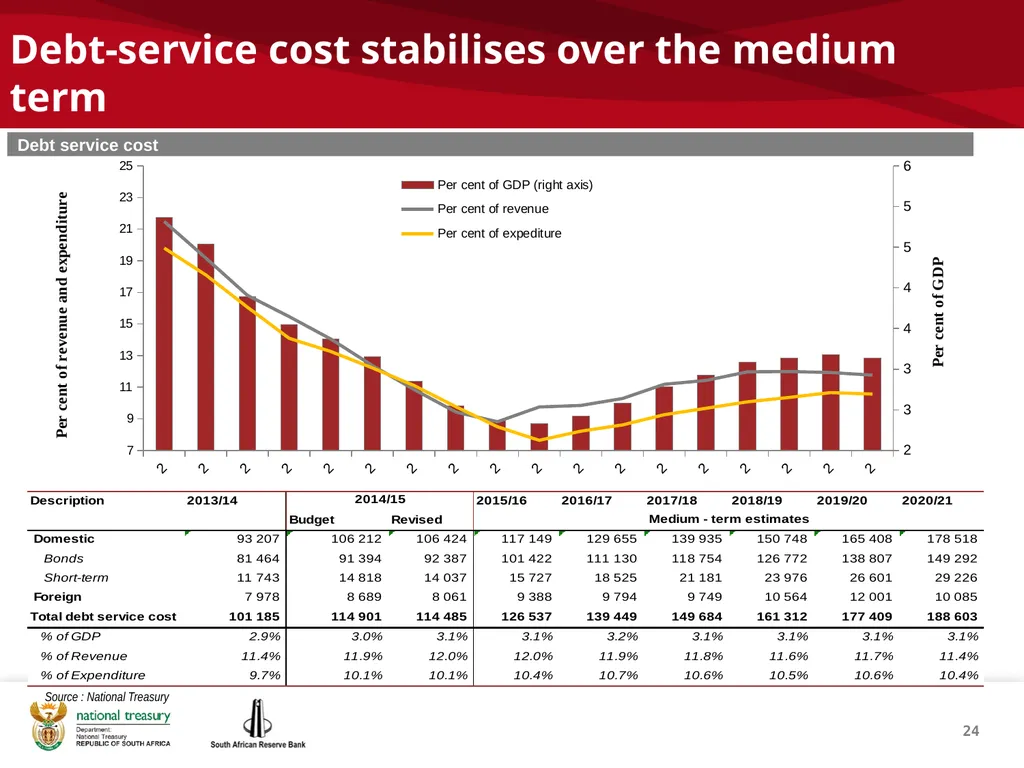
slide24. Debt-service cost stabilises over the medium term Source : National Treasury Debt service cost 24<br>
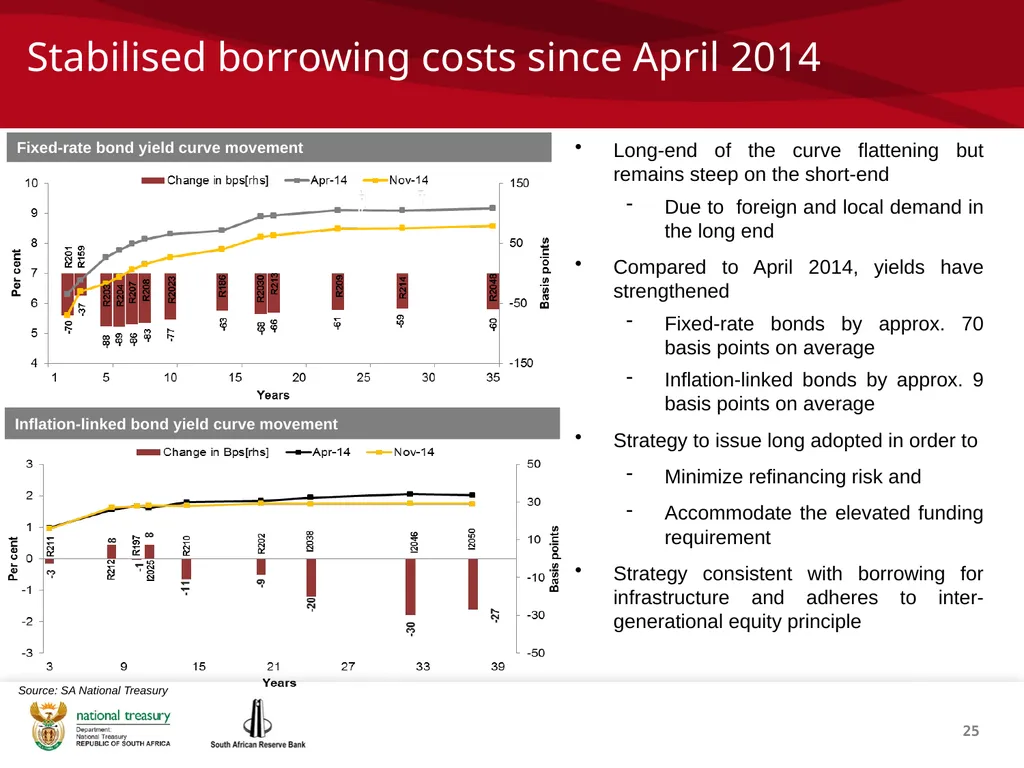
slide25. Fixed-rate bond yield curve movement 25 Source: SA National Treasury R208 R2023 R186 Long-end of the curve flattening but remains steep on the short-end
Due to foreign and local demand in the long end
Compared to April 2014, yields have strengthened
Fixed-rate bonds by approx. 70 basis points on average
Inflation-linked bonds by approx. 9 basis points on average
Strategy to issue long adopted in order to
Minimize refinancing risk and
Accommodate the elevated funding requirement
Strategy consistent with borrowing for infrastructure and adheres to inter-generational equity principle Inflation-linked bond yield curve movement Stabilised borrowing costs since April 2014<br>
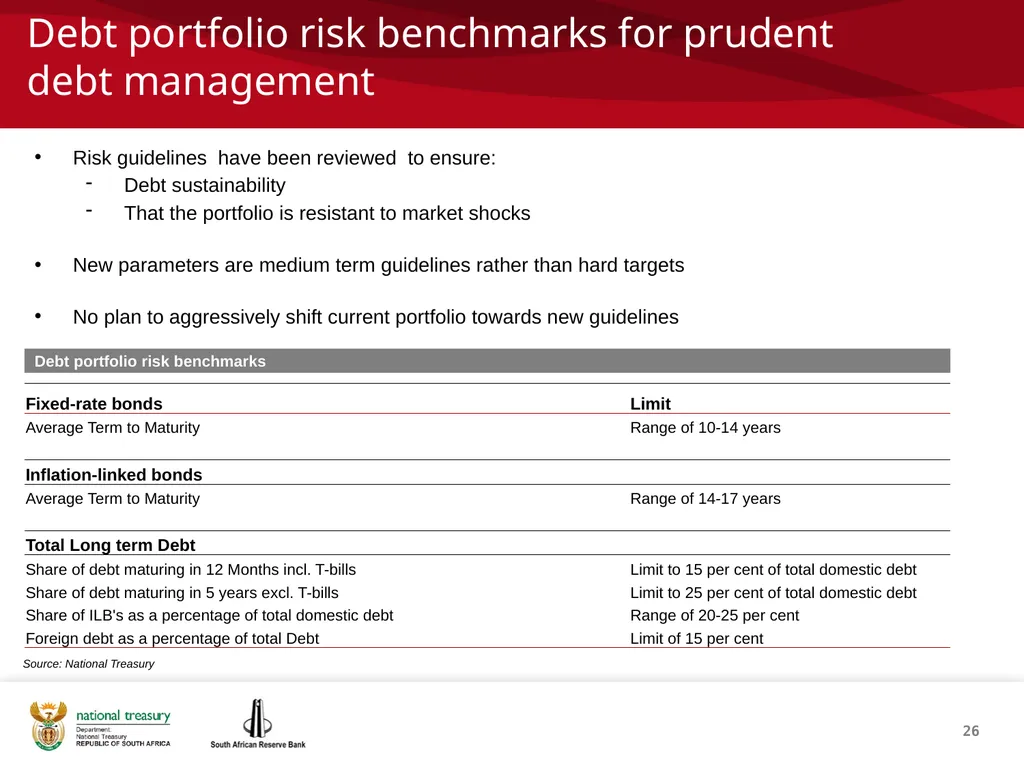
slide26. Debt portfolio risk benchmarks for prudent debt management 26 Risk guidelines have been reviewed to ensure:
Debt sustainability
That the portfolio is resistant to market shocks
New parameters are medium term guidelines rather than hard targets
No plan to aggressively shift current portfolio towards new guidelines Debt portfolio risk benchmarks Source: National Treasury<br>
slide27. 27 5. Holdings of government bonds<br>
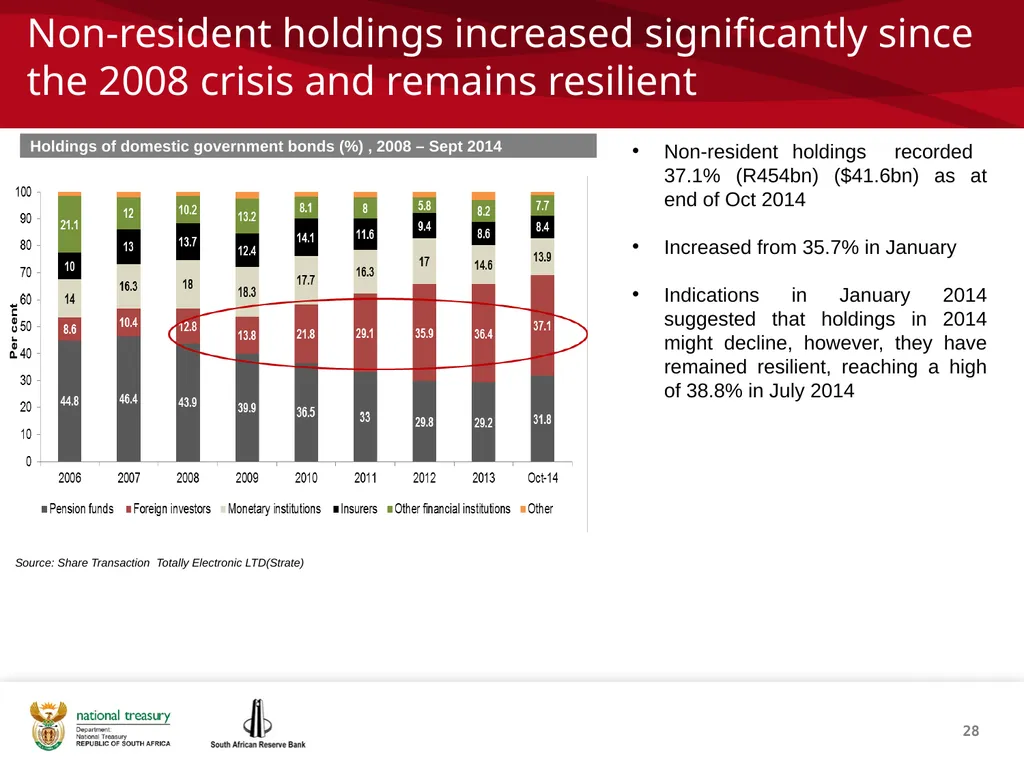
slide28. Non-resident holdings increased significantly since the 2008 crisis and remains resilient Non-resident holdings recorded 37.1% (R454bn) ($41.6bn) as at end of Oct 2014
Increased from 35.7% in January
Indications in January 2014 suggested that holdings in 2014 might decline, however, they have remained resilient, reaching a high of 38.8% in July 2014 Holdings of domestic government bonds (%) , 2008 – Sept 2014 Source: Share Transaction Totally Electronic LTD(Strate) 28<br>
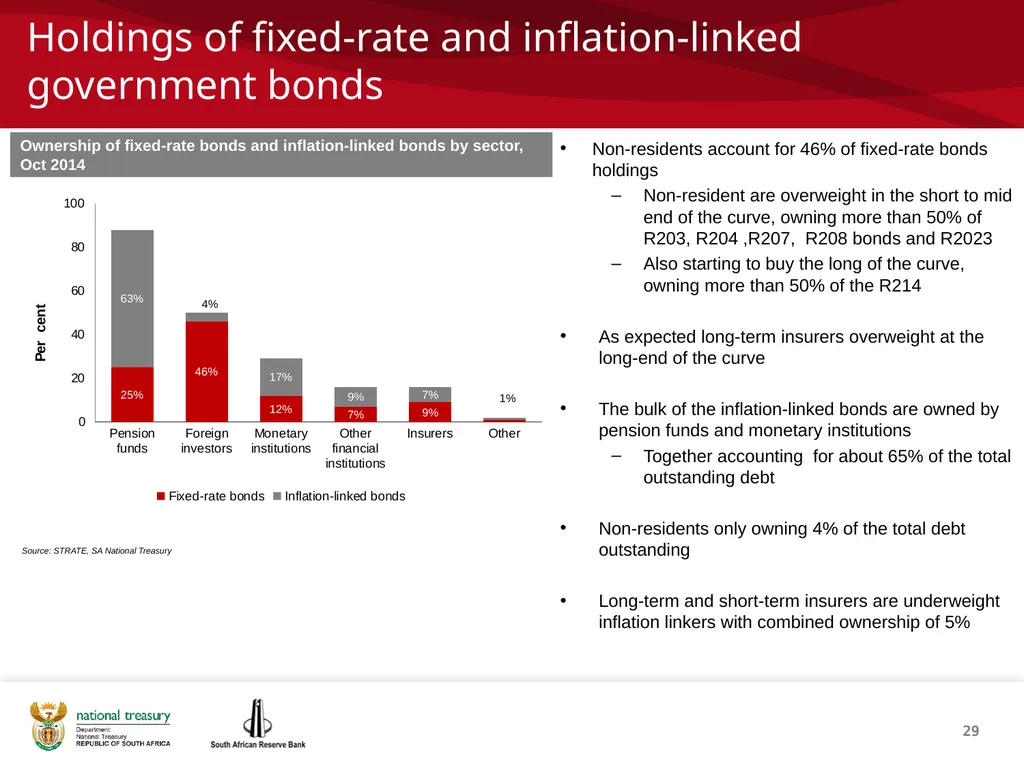
slide29. Holdings of fixed-rate and inflation-linked government bonds Source: STRATE, SA National Treasury Ownership of fixed-rate bonds and inflation-linked bonds by sector, Oct 2014 Non-residents account for 46% of fixed-rate bonds holdings
Non-resident are overweight in the short to mid end of the curve, owning more than 50% of R203, R204 ,R207, R208 bonds and R2023
Also starting to buy the long of the curve, owning more than 50% of the R214
As expected long-term insurers overweight at the long-end of the curve
The bulk of the inflation-linked bonds are owned by pension funds and monetary institutions
Together accounting for about 65% of the total outstanding debt
Non-residents only owning 4% of the total debt outstanding
Long-term and short-term insurers are underweight inflation linkers with combined ownership of 5% 29<br>
slide30. 30 6. Monetary Policy<br>
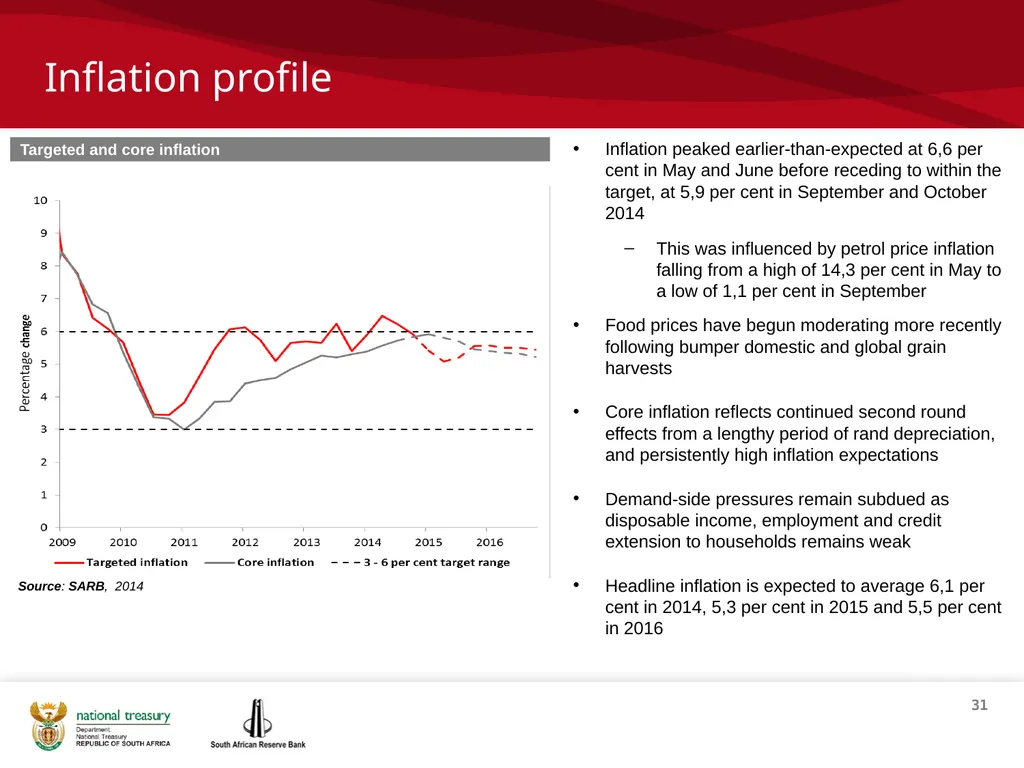
slide31. Inflation profile Inflation peaked earlier-than-expected at 6,6 per cent in May and June before receding to within the target, at 5,9 per cent in September and October 2014
This was influenced by petrol price inflation falling from a high of 14,3 per cent in May to a low of 1,1 per cent in September
Food prices have begun moderating more recently following bumper domestic and global grain harvests
Core inflation reflects continued second round effects from a lengthy period of rand depreciation, and persistently high inflation expectations
Demand-side pressures remain subdued as disposable income, employment and credit extension to households remains weak
Headline inflation is expected to average 6,1 per cent in 2014, 5,3 per cent in 2015 and 5,5 per cent in 2016 31 Targeted and core inflation Source: SARB, 2014<br>
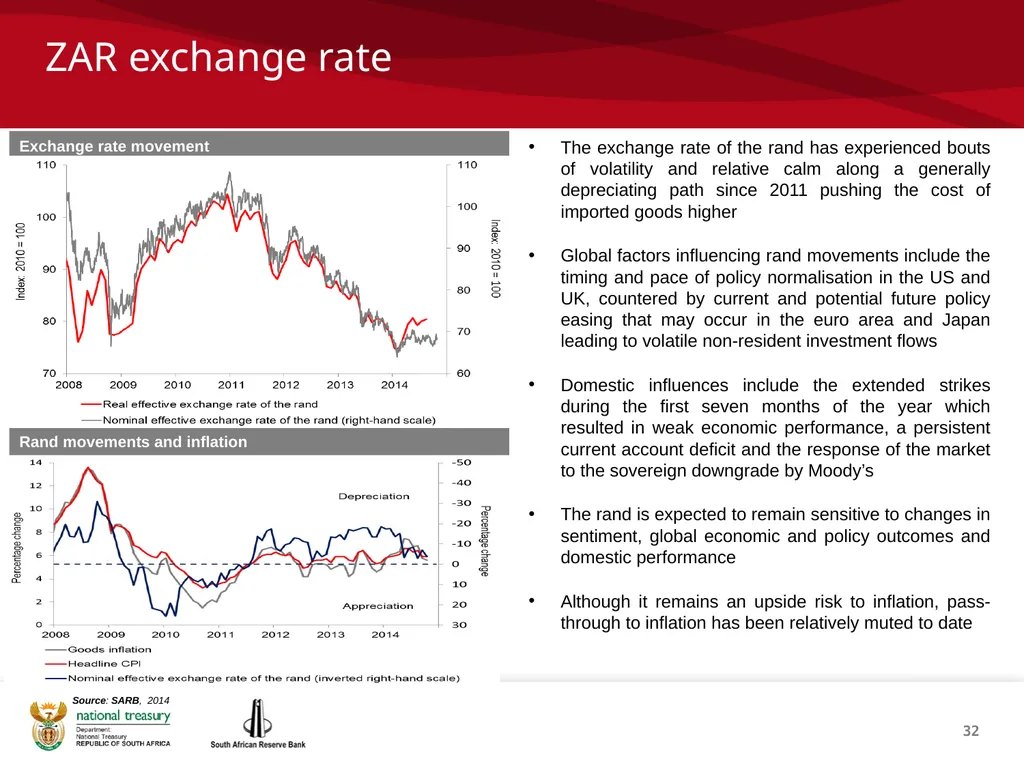
slide32. ZAR exchange rate The exchange rate of the rand has experienced bouts of volatility and relative calm along a generally depreciating path since 2011 pushing the cost of imported goods higher
Global factors influencing rand movements include the timing and pace of policy normalisation in the US and UK, countered by current and potential future policy easing that may occur in the euro area and Japan leading to volatile non-resident investment flows
Domestic influences include the extended strikes during the first seven months of the year which resulted in weak economic performance, a persistent current account deficit and the response of the market to the sovereign downgrade by Moody’s
The rand is expected to remain sensitive to changes in sentiment, global economic and policy outcomes and domestic performance
Although it remains an upside risk to inflation, pass-through to inflation has been relatively muted to date 32 Exchange rate movement Rand movements and inflation Source: SARB, 2014<br>
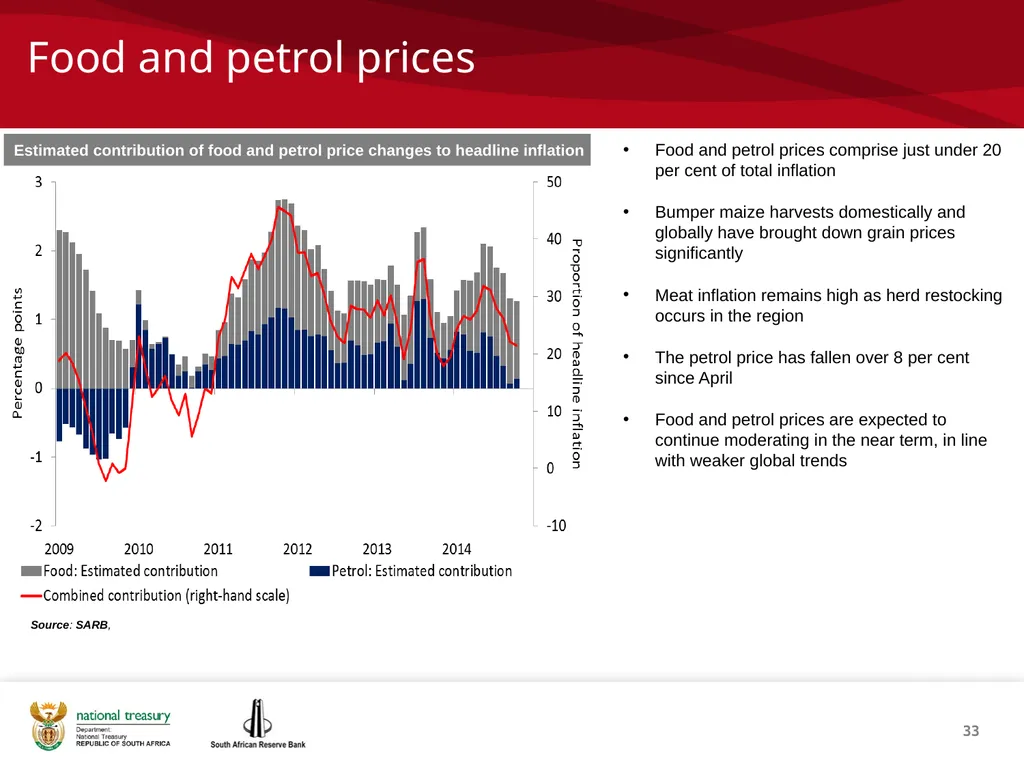
slide33. Food and petrol prices 33 Estimated contribution of food and petrol price changes to headline inflation Food and petrol prices comprise just under 20 per cent of total inflation
Bumper maize harvests domestically and globally have brought down grain prices significantly
Meat inflation remains high as herd restocking occurs in the region
The petrol price has fallen over 8 per cent since April
Food and petrol prices are expected to continue moderating in the near term, in line with weaker global trends Source: SARB,<br>
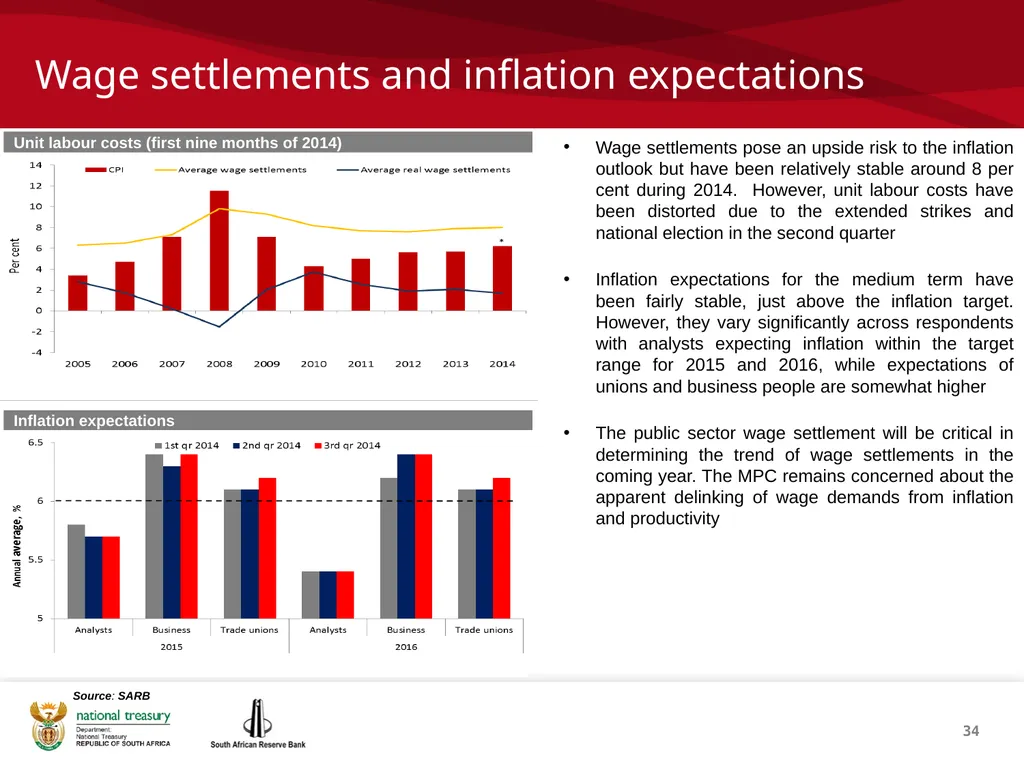
slide34. Wage settlements and inflation expectations Wage settlements pose an upside risk to the inflation outlook but have been relatively stable around 8 per cent during 2014. However, unit labour costs have been distorted due to the extended strikes and national election in the second quarter
Inflation expectations for the medium term have been fairly stable, just above the inflation target. However, they vary significantly across respondents with analysts expecting inflation within the target range for 2015 and 2016, while expectations of unions and business people are somewhat higher
The public sector wage settlement will be critical in determining the trend of wage settlements in the coming year. The MPC remains concerned about the apparent delinking of wage demands from inflation and productivity 34 Unit labour costs (first nine months of 2014) Inflation expectations Source: SARB<br>
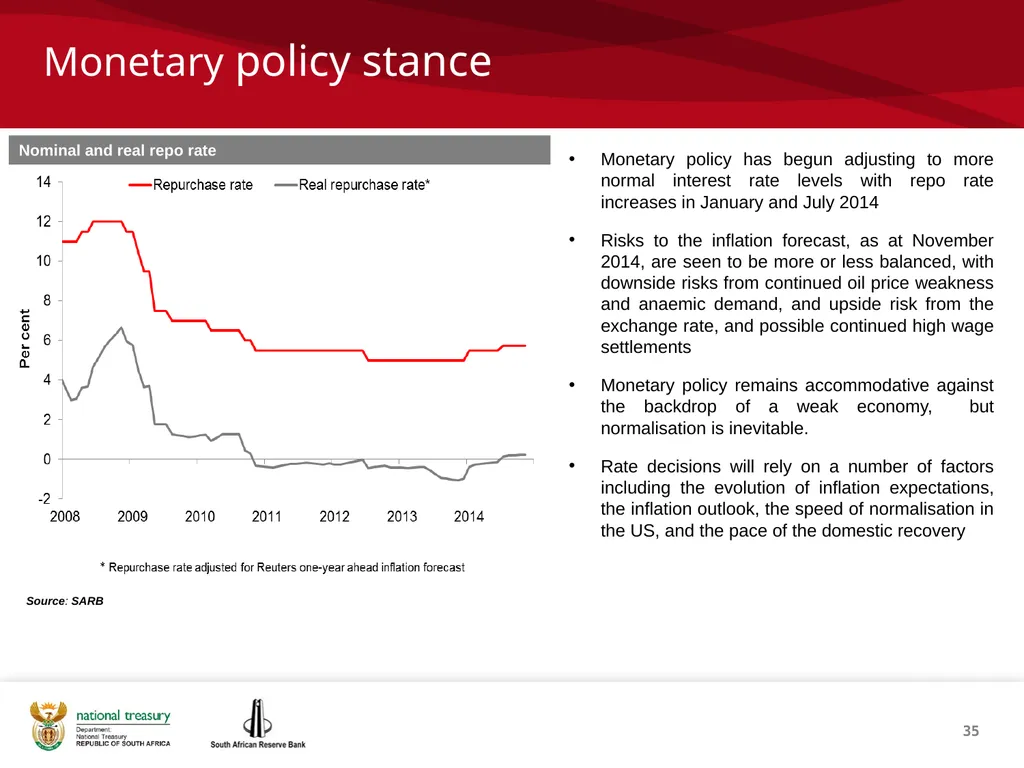
slide35. Monetary policy stance Monetary policy has begun adjusting to more normal interest rate levels with repo rate increases in January and July 2014
Risks to the inflation forecast, as at November 2014, are seen to be more or less balanced, with downside risks from continued oil price weakness and anaemic demand, and upside risk from the exchange rate, and possible continued high wage settlements
Monetary policy remains accommodative against the backdrop of a weak economy, but normalisation is inevitable.
Rate decisions will rely on a number of factors including the evolution of inflation expectations, the inflation outlook, the speed of normalisation in the US, and the pace of the domestic recovery 35 Nominal and real repo rate Source: SARB<br>
slide36. 36 7. Banking sector stability<br>
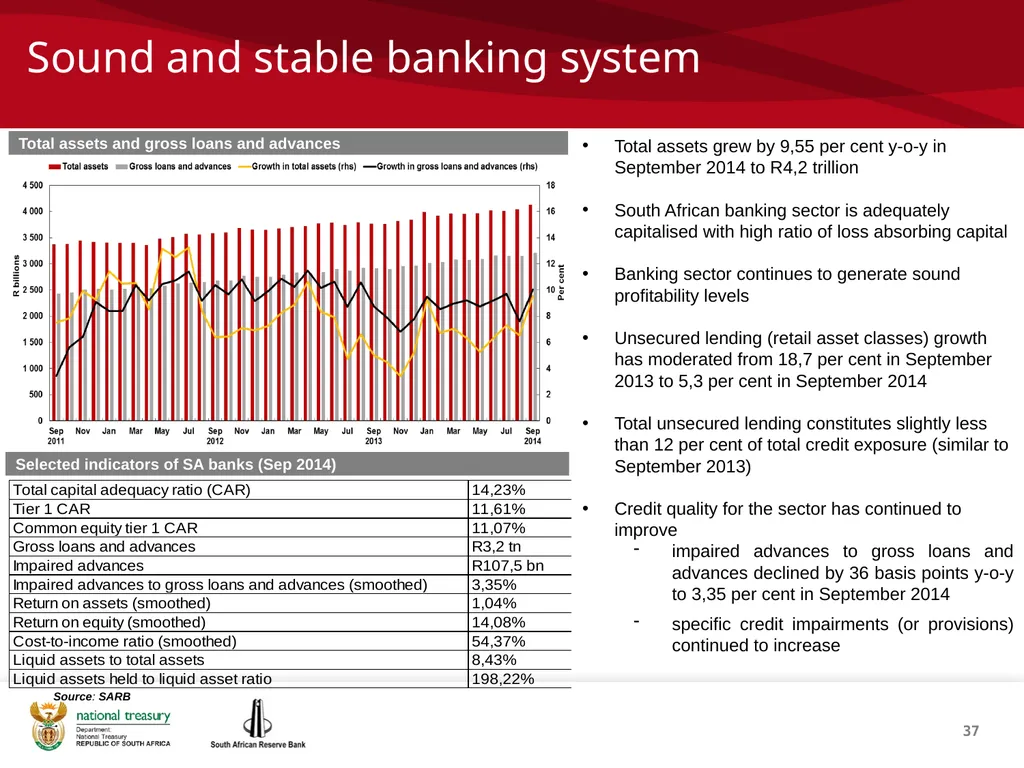
slide37. Sound and stable banking system Total assets grew by 9,55 per cent y-o-y in September 2014 to R4,2 trillion
South African banking sector is adequately capitalised with high ratio of loss absorbing capital
Banking sector continues to generate sound profitability levels
Unsecured lending (retail asset classes) growth has moderated from 18,7 per cent in September 2013 to 5,3 per cent in September 2014
Total unsecured lending constitutes slightly less than 12 per cent of total credit exposure (similar to September 2013)
Credit quality for the sector has continued to improve
impaired advances to gross loans and advances declined by 36 basis points y-o-y to 3,35 per cent in September 2014
specific credit impairments (or provisions) continued to increase Source: SARB Total assets and gross loans and advances Selected indicators of SA banks (Sep 2014) 37<br>
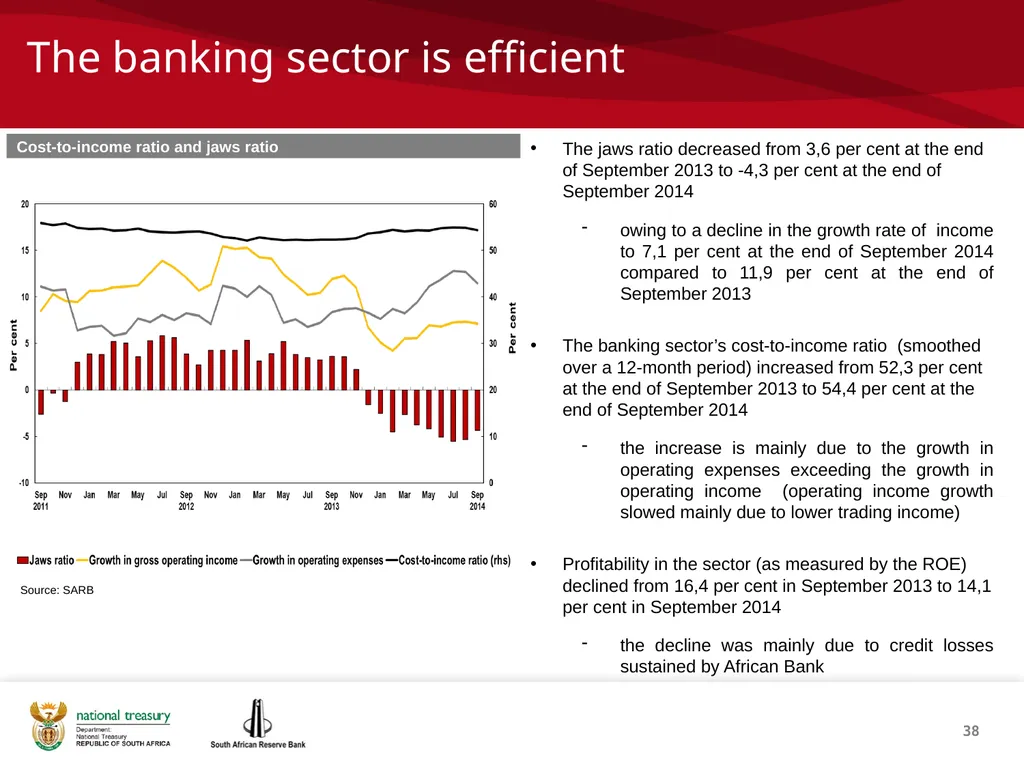
slide38. The banking sector is efficient The jaws ratio decreased from 3,6 per cent at the end of September 2013 to -4,3 per cent at the end of September 2014
owing to a decline in the growth rate of income to 7,1 per cent at the end of September 2014 compared to 11,9 per cent at the end of September 2013
The banking sector’s cost-to-income ratio (smoothed over a 12-month period) increased from 52,3 per cent at the end of September 2013 to 54,4 per cent at the end of September 2014
the increase is mainly due to the growth in operating expenses exceeding the growth in operating income (operating income growth slowed mainly due to lower trading income)
Profitability in the sector (as measured by the ROE) declined from 16,4 per cent in September 2013 to 14,1 per cent in September 2014
the decline was mainly due to credit losses sustained by African Bank Cost-to-income ratio and jaws ratio Source: SARB 38<br>
slide39. Sound and stable banking system Total assets and gross loans and advances of the banking sector are growing at sustainable levels
South African banking sector remained adequately capitalised
The sector is profitable with higher quality of assets
Impaired advances ratio is lower
Provisions have been increasing
The sector’s total unsecured gross retail credit exposure was approximately 12 per cent of total gross credit exposure
The Regulations relating to Banks include the phased-in requirements contained in the Basel III framework
the sector is on track to implement the Liquidity Coverage Ratio (LCR) from January 2015 39<br>
slide40. THANK YOU 40<br>
December 2014<br>
slide2. Table of contents 1) Overview 3 2) Macro economic developments 8 2 3) Public finance 14 4) Financing of borrowing requirement 21 5) Holdings of government bonds 27 Slide 6) Monetary policy 30 7) Banking sector stability 36<br>
slide3. 3 1. Overview<br>
slide4. Key investment highlights 4 Broad political stability will remain, owing to the African National Congress (ANC)'s dominance at a national and provincial level<br>
slide5. National Development Plan (“NDP”) overview 5 The NDP was established in 2011 in a bid to eliminate poverty and reduce inequality in South Africa by 2030. Some of its key policy objectives are:<br>
slide6. Medium Term Strategic Framework (“MTSF”), implementing the NDP South Africa has begun a new phase of its democratic transition
Electoral mandate of fifth democratic government is to deepen transformation and implement the NDP
Mandate also speaks to accelerating growth, creating employment opportunities and promoting investment in a competitive economy.
Constitutional commitment to providing improved quality of life for all citizens remains the key cornerstone
Strategic plan for the 2014 – 2019 electoral term
Reflects commitments made in election manifesto of governing party, including commitment to NDP
MTSF sets out the actions government will take and targets to be achieved
Provides framework for other plans
MTSF highlights government’s support for a competitive economy Quality basic education
Improved access to basic healthcare
More efficient public policing and better law enforcement
Skilled and capable workforce to support inclusive growth path
An efficient, competitive and responsive economic infrastructure network
Vibrant, equitable and sustainable rural communities contributing to food security
Sustainable human settlements and improved quality of household life
Responsive, accountable effective and efficient local government
Protect and enhance our environmental assets and natural resources
An efficient, effective and development-oriented public service 6 Background Priorities over next five years Purpose<br>
slide7. Summary of the Medium Term Budget Policy Statement (“MTBPS”) The budget policy framework for the next three years is designed to ensure fiscal sustainability while shifting spending towards government’s priorities as set out in the NDP and MTSF
South Africa’s weaker-than-expected economic performance and outlook pose new fiscal challenges
GDP growth of 1.4% is expected in 2014, rising to 3.0% in 2017
Government proposes a fiscal package that reduces growth in spending by lowering the 2014 Budget expenditure ceiling by R25`billion over the next two years and adjusting tax policy to generate additional revenue of at least R27 billion over two years
The fiscal package results in net debt stabilising at 45.9% of GDP by 2017/18
Overall, public spending will rise by 7.6% a year over the medium-term, with post school education and training, housing development, social infrastructure, employment, labour affairs and social security funds receiving the largest increases
Over the medium to long-term, a combination of these fiscal measures and the microeconomic interventions in the Medium Term Strategic Framework will place the economy on a more sustainable development path 7<br>
slide8. 8 2. Macro economic developments<br>
slide9. Economy expected to grow as global outlook improves Moderately improving economic growth rates in developed markets are expected to contribute to stronger global demand and international trade but the economic outlook is fragile and uneven
Developed economies: US recovering, but EU and Japan remain weak. There is growing monetary policy divergence.
Emerging economies: Growth has been revised downwards due to:
rebalancing of growth
supply side constraints and reliance on commodity exports
Risks:
potential financial markets volatility given different monetary policy responses
shifting trade patterns
Vulnerability of EMs to fluctuations in capital flows IMF growth projections Source: Bloomberg 9<br>
slide10. GDP growth expected to improve over the medium term 10 Growth expected to be 1.4% this year from 3.6% 2011 due to:
work stoppages, labour disputes, electricity constraints and other supply side shocks
It is expected to pick up to 3.0% in 2017 as the global outlook improves, confidence returns to the economy as constraints are relieved
Key drivers to growth pick-up:
increased export demand, in particular from key trading partners such as Europe and Africa
easing in electricity supply constraints (Medupi power station under construction)
Key constraints:
consumers remain under pressure and low consumer confidence Macroeconomic forecast , 2011-2017 Source: National Treasury, SARB<br>
slide11. 11 The current account is expected to narrow Current account as percentage of GDP Current account deficit (“CAD”) is projected to narrow from 6.0 per cent in 2013 to 5.5 per cent in 2016 as export growth improves
Although the CAD has recently widened, this was primarily driven by infrastructure related imports and a worsening in terms of trade
Capital and financial accounts sufficiently financed the CAD last year<br>
slide12. Traditional exports are under pressure, but new opportunities are emerging Growth of exports to EU expected to be muted
Commodity exports to China expected to be weak
But SADC exports are diversified and growing strongly
SADC becoming increasingly important export destination, especially for manufactured goods
Other export opportunities emerging, with rising share of non-traditional markets (other)
There are negotiations to finalise the tripartite FTA, which consist of SADC, EAC and COMESA.
If concluded this will result in a market of nearly 1 billion people. Major export destinations for South African products 12<br>
slide13. SA increasing exports and investments towards African region key for current account structure 13 Africa is increasingly becoming an important trade partner, absorbing 28.5 per cent of South African exports, up from 22.6 per cent in 2002
Africa has become a major investment destination for South Africa firms and source of earnings. Investments into Africa increased from R5.5 bn in 2002, to R32.3 bn in 2013
Government has taken several steps to promote export potential:
Improved pricing at local ports to reduce transport costs and enhance competitiveness
Invested in infrastructure to reduce production and transport bottlenecks
Put in place competitiveness initiatives in manufacturing
SA DFIs funding infrastructure on the continent to support trade relations Source: South African Revenue Service 1 (Botswana, Lesotho, Namibia, Swaziland1) South African trade (incl BLNS 1) with Africa Source: SARB and South African Revenue Services South African trade and investment with Africa<br>
slide14. 14 3. Public Finance<br>
slide15. Fiscal framework remains sound and transparent Overview Fiscal framework grounded in sustainable, countercyclical approach to managing revenue and expenditure
Government intends to balance continued support for economic recovery with fiscal consolidation
Key social and economic programmes are expected to be maintained, complemented by efforts to improve value for money
Spending is expected to be contained over the medium term expenditure framework period
Reduction of the deficit will be a combined result of government’s expenditure ceiling and revenue measures
As economic growth improves and spending limits stay in place, the budget deficit is projected to narrow to 2.5 per cent of GDP by 2017/18 Fiscal priorities Maintaining the expenditure ceiling
Reducing the budget deficit
Stabilisation of debt over the medium term
Improving the composition and efficiency of spending
Cost-containment measures announ-ced by the Minister of Finance in October 2013 limit expenditure on conferences, travel, entertainment and other non-essential items
The National Treasury and Department of Performance Monitoring and Evaluation have launched a series of expenditure reviews
Tax Review Committee is investigating all aspects of the tax system to improve equity and efficiency 15<br>
slide16. Proposed fiscal package to reinforce sustainability In order to narrow the deficit and stabilise debt over the medium term, government proposes a fiscal package with the following five elements:
Reduce growth in spending by lowering the 2014 Budget expenditure ceiling by R25`billion over the next two fiscal years
Adjust tax policy and administration. Proposals will be introduced in the 2015 Budget to generate additional revenue of at least R27 billion over the next two fiscal years
Place greater emphasis on longer-term planning and efficient resource allocation, within a framework that links expenditure and economic growth beyond the medium term
Freeze government personnel headcount. Government will also review funded vacancies
Adopt a deficit-neutral approach to the financing requirements of state-owned companies over the next two fiscal years 16<br>
slide17. Fiscal framework including the proposed fiscal package 17 Consolidated fiscal framework, 2011/12 – 2017/18 Source: National Treasury<br>
slide18. Spending continues to grow in real term, while reaching a primary balance within the current MTEF 18 Main budget non-interest spending Main budget primary balance Source: National Treasury<br>
slide19. Net national government debt stabilising in 2017/18 19 Before the proposed changes, national government’s net debt was projected to continue growing as a share of GDP beyond 2021
The fiscal package results in net debt stabilising at 45.9 per cent of GDP in 2017/18, while gross debt remains below 50 per cent of GDP Net national government debt Source: National Treasury<br>
slide20. Risks to the proposed fiscal framework Economic outlook:
Rising global interest-rate cycle likely to place pressure on domestic interest rates, increasing the costs of issuing debt
The current account deficit remains persistently high, making SA more vulnerable to shifts in investment flows and market sentiment
A further deterioration in the GDP would require consideration of additional measures
Electricity constraints impact on growth
Government’s wage bill:
Budgets assume CPI cost-of-living adjustments and headcount numbers at current levels
Current constraints suggest limited scope for additional resources
Deviations from CPI-linked cost-of-living adjustments will require either a reallocation of resources or a reduction in government employment
A new framework for funding of SOCs and public entities will focus on:
Distinguishing purely commercial activities from the costs of exercising their developmental mandates
Close monitoring to ensure efficient delivery on government priorities, while simultaneously promoting improved commercial performance
Introducing more stringent financial reporting requirements for public entities
Capitalisation will be funded from sale of non-strategic state assets, and will not be drawn from tax revenue 20<br>
slide21. 21 4. Financing of borrowing requirement<br>
slide22. National government gross borrowing requirement and financing 22 Financing of national government borrowing requirement, 2013/14 – 2017/18 Budget balance to moderate to R143 billion in 2017/18
Funding to be raised largely from the domestic bond market
Bond issuance remains at current levels over next 2 fiscal years increasing to R176.9 billion in 2017/18 due to higher redemptions
Loan redemptions projected to total R155 billion over medium-term<br>
slide23. Cash balances to finance part of the borrowing requirement 23 Source : National Treasury Changes in cash balances,2013/14 - 2017/18<br>
slide24. Debt-service cost stabilises over the medium term Source : National Treasury Debt service cost 24<br>
slide25. Fixed-rate bond yield curve movement 25 Source: SA National Treasury R208 R2023 R186 Long-end of the curve flattening but remains steep on the short-end
Due to foreign and local demand in the long end
Compared to April 2014, yields have strengthened
Fixed-rate bonds by approx. 70 basis points on average
Inflation-linked bonds by approx. 9 basis points on average
Strategy to issue long adopted in order to
Minimize refinancing risk and
Accommodate the elevated funding requirement
Strategy consistent with borrowing for infrastructure and adheres to inter-generational equity principle Inflation-linked bond yield curve movement Stabilised borrowing costs since April 2014<br>
slide26. Debt portfolio risk benchmarks for prudent debt management 26 Risk guidelines have been reviewed to ensure:
Debt sustainability
That the portfolio is resistant to market shocks
New parameters are medium term guidelines rather than hard targets
No plan to aggressively shift current portfolio towards new guidelines Debt portfolio risk benchmarks Source: National Treasury<br>
slide27. 27 5. Holdings of government bonds<br>
slide28. Non-resident holdings increased significantly since the 2008 crisis and remains resilient Non-resident holdings recorded 37.1% (R454bn) ($41.6bn) as at end of Oct 2014
Increased from 35.7% in January
Indications in January 2014 suggested that holdings in 2014 might decline, however, they have remained resilient, reaching a high of 38.8% in July 2014 Holdings of domestic government bonds (%) , 2008 – Sept 2014 Source: Share Transaction Totally Electronic LTD(Strate) 28<br>
slide29. Holdings of fixed-rate and inflation-linked government bonds Source: STRATE, SA National Treasury Ownership of fixed-rate bonds and inflation-linked bonds by sector, Oct 2014 Non-residents account for 46% of fixed-rate bonds holdings
Non-resident are overweight in the short to mid end of the curve, owning more than 50% of R203, R204 ,R207, R208 bonds and R2023
Also starting to buy the long of the curve, owning more than 50% of the R214
As expected long-term insurers overweight at the long-end of the curve
The bulk of the inflation-linked bonds are owned by pension funds and monetary institutions
Together accounting for about 65% of the total outstanding debt
Non-residents only owning 4% of the total debt outstanding
Long-term and short-term insurers are underweight inflation linkers with combined ownership of 5% 29<br>
slide30. 30 6. Monetary Policy<br>
slide31. Inflation profile Inflation peaked earlier-than-expected at 6,6 per cent in May and June before receding to within the target, at 5,9 per cent in September and October 2014
This was influenced by petrol price inflation falling from a high of 14,3 per cent in May to a low of 1,1 per cent in September
Food prices have begun moderating more recently following bumper domestic and global grain harvests
Core inflation reflects continued second round effects from a lengthy period of rand depreciation, and persistently high inflation expectations
Demand-side pressures remain subdued as disposable income, employment and credit extension to households remains weak
Headline inflation is expected to average 6,1 per cent in 2014, 5,3 per cent in 2015 and 5,5 per cent in 2016 31 Targeted and core inflation Source: SARB, 2014<br>
slide32. ZAR exchange rate The exchange rate of the rand has experienced bouts of volatility and relative calm along a generally depreciating path since 2011 pushing the cost of imported goods higher
Global factors influencing rand movements include the timing and pace of policy normalisation in the US and UK, countered by current and potential future policy easing that may occur in the euro area and Japan leading to volatile non-resident investment flows
Domestic influences include the extended strikes during the first seven months of the year which resulted in weak economic performance, a persistent current account deficit and the response of the market to the sovereign downgrade by Moody’s
The rand is expected to remain sensitive to changes in sentiment, global economic and policy outcomes and domestic performance
Although it remains an upside risk to inflation, pass-through to inflation has been relatively muted to date 32 Exchange rate movement Rand movements and inflation Source: SARB, 2014<br>
slide33. Food and petrol prices 33 Estimated contribution of food and petrol price changes to headline inflation Food and petrol prices comprise just under 20 per cent of total inflation
Bumper maize harvests domestically and globally have brought down grain prices significantly
Meat inflation remains high as herd restocking occurs in the region
The petrol price has fallen over 8 per cent since April
Food and petrol prices are expected to continue moderating in the near term, in line with weaker global trends Source: SARB,<br>
slide34. Wage settlements and inflation expectations Wage settlements pose an upside risk to the inflation outlook but have been relatively stable around 8 per cent during 2014. However, unit labour costs have been distorted due to the extended strikes and national election in the second quarter
Inflation expectations for the medium term have been fairly stable, just above the inflation target. However, they vary significantly across respondents with analysts expecting inflation within the target range for 2015 and 2016, while expectations of unions and business people are somewhat higher
The public sector wage settlement will be critical in determining the trend of wage settlements in the coming year. The MPC remains concerned about the apparent delinking of wage demands from inflation and productivity 34 Unit labour costs (first nine months of 2014) Inflation expectations Source: SARB<br>
slide35. Monetary policy stance Monetary policy has begun adjusting to more normal interest rate levels with repo rate increases in January and July 2014
Risks to the inflation forecast, as at November 2014, are seen to be more or less balanced, with downside risks from continued oil price weakness and anaemic demand, and upside risk from the exchange rate, and possible continued high wage settlements
Monetary policy remains accommodative against the backdrop of a weak economy, but normalisation is inevitable.
Rate decisions will rely on a number of factors including the evolution of inflation expectations, the inflation outlook, the speed of normalisation in the US, and the pace of the domestic recovery 35 Nominal and real repo rate Source: SARB<br>
slide36. 36 7. Banking sector stability<br>
slide37. Sound and stable banking system Total assets grew by 9,55 per cent y-o-y in September 2014 to R4,2 trillion
South African banking sector is adequately capitalised with high ratio of loss absorbing capital
Banking sector continues to generate sound profitability levels
Unsecured lending (retail asset classes) growth has moderated from 18,7 per cent in September 2013 to 5,3 per cent in September 2014
Total unsecured lending constitutes slightly less than 12 per cent of total credit exposure (similar to September 2013)
Credit quality for the sector has continued to improve
impaired advances to gross loans and advances declined by 36 basis points y-o-y to 3,35 per cent in September 2014
specific credit impairments (or provisions) continued to increase Source: SARB Total assets and gross loans and advances Selected indicators of SA banks (Sep 2014) 37<br>
slide38. The banking sector is efficient The jaws ratio decreased from 3,6 per cent at the end of September 2013 to -4,3 per cent at the end of September 2014
owing to a decline in the growth rate of income to 7,1 per cent at the end of September 2014 compared to 11,9 per cent at the end of September 2013
The banking sector’s cost-to-income ratio (smoothed over a 12-month period) increased from 52,3 per cent at the end of September 2013 to 54,4 per cent at the end of September 2014
the increase is mainly due to the growth in operating expenses exceeding the growth in operating income (operating income growth slowed mainly due to lower trading income)
Profitability in the sector (as measured by the ROE) declined from 16,4 per cent in September 2013 to 14,1 per cent in September 2014
the decline was mainly due to credit losses sustained by African Bank Cost-to-income ratio and jaws ratio Source: SARB 38<br>
slide39. Sound and stable banking system Total assets and gross loans and advances of the banking sector are growing at sustainable levels
South African banking sector remained adequately capitalised
The sector is profitable with higher quality of assets
Impaired advances ratio is lower
Provisions have been increasing
The sector’s total unsecured gross retail credit exposure was approximately 12 per cent of total gross credit exposure
The Regulations relating to Banks include the phased-in requirements contained in the Basel III framework
the sector is on track to implement the Liquidity Coverage Ratio (LCR) from January 2015 39<br>
slide40. THANK YOU 40<br>