
11 November 2016 Travel Trade Research TABLE OF



Description: 11 November 2016 Travel Trade Research TABLE OF CONTENTS: Formulating the Trade Strategy Project Objective and Status Update Global Travellers Purchase Process Tourism Value Chain: Products and Services Providers Productsservices
Related Topics
Download Presentation
"11 November 2016 Travel Trade Research TABLE OF" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. 11 November 2016 Travel Trade Research<br>
slide2. TABLE OF CONTENTS: Formulating the Trade Strategy Project Objective and Status Update
Global Travellers’ Purchase Process
Tourism Value Chain: Products and Services Providers<br>
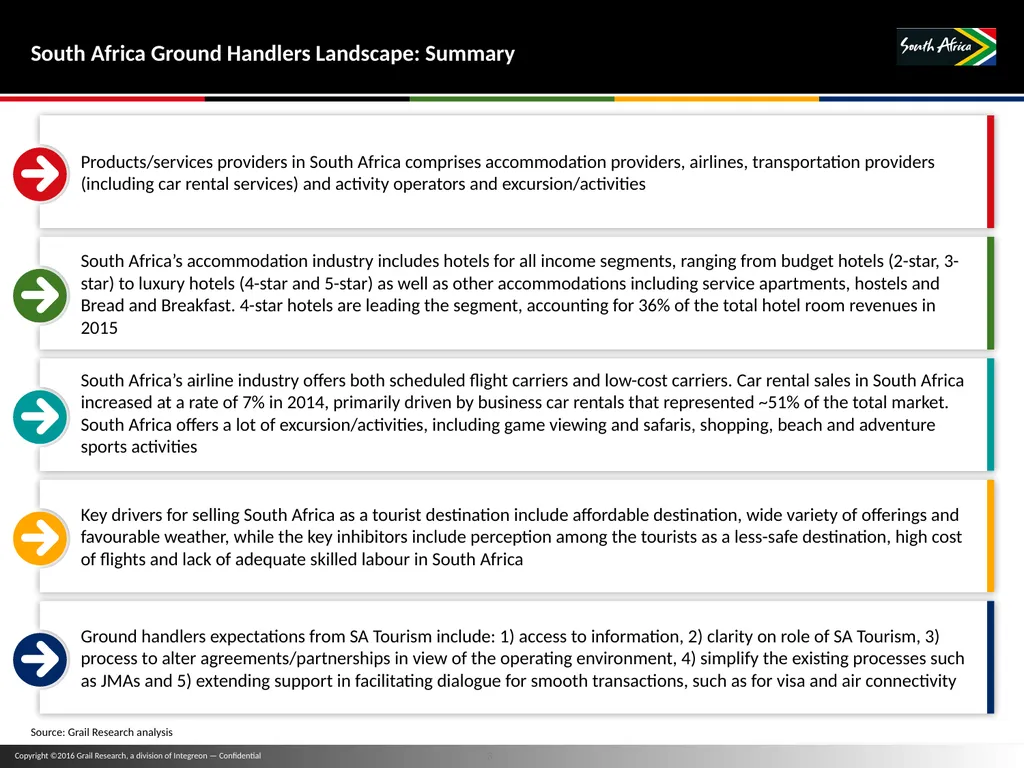
slide3. Products/services providers in South Africa comprises accommodation providers, airlines, transportation providers (including car rental services) and activity operators and excursion/activities South Africa Ground Handlers Landscape: Summary Source: Grail Research analysis South Africa’s accommodation industry includes hotels for all income segments, ranging from budget hotels (2-star, 3-star) to luxury hotels (4-star and 5-star) as well as other accommodations including service apartments, hostels and Bread and Breakfast. 4-star hotels are leading the segment, accounting for 36% of the total hotel room revenues in 2015 South Africa’s airline industry offers both scheduled flight carriers and low-cost carriers. Car rental sales in South Africa increased at a rate of 7% in 2014, primarily driven by business car rentals that represented ~51% of the total market. South Africa offers a lot of excursion/activities, including game viewing and safaris, shopping, beach and adventure sports activities Key drivers for selling South Africa as a tourist destination include affordable destination, wide variety of offerings and favourable weather, while the key inhibitors include perception among the tourists as a less-safe destination, high cost of flights and lack of adequate skilled labour in South Africa Ground handlers expectations from SA Tourism include: 1) access to information, 2) clarity on role of SA Tourism, 3) process to alter agreements/partnerships in view of the operating environment, 4) simplify the existing processes such as JMAs and 5) extending support in facilitating dialogue for smooth transactions, such as for visa and air connectivity<br>
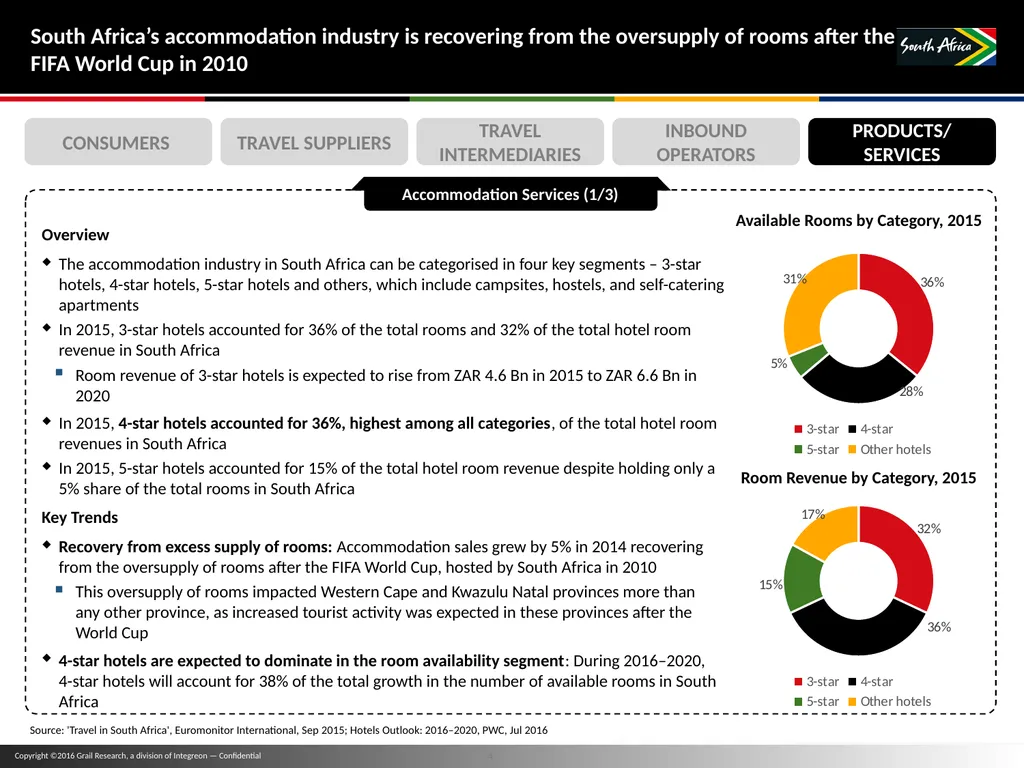
slide4. South Africa’s accommodation industry is recovering from the oversupply of rooms after the FIFA World Cup in 2010 Available Rooms by Category, 2015 Source: 'Travel in South Africa', Euromonitor International, Sep 2015; Hotels Outlook: 2016–2020, PWC, Jul 2016 Overview
The accommodation industry in South Africa can be categorised in four key segments – 3-star hotels, 4-star hotels, 5-star hotels and others, which include campsites, hostels, and self-catering apartments
In 2015, 3-star hotels accounted for 36% of the total rooms and 32% of the total hotel room revenue in South Africa
Room revenue of 3-star hotels is expected to rise from ZAR 4.6 Bn in 2015 to ZAR 6.6 Bn in 2020
In 2015, 4-star hotels accounted for 36%, highest among all categories, of the total hotel room revenues in South Africa
In 2015, 5-star hotels accounted for 15% of the total hotel room revenue despite holding only a 5% share of the total rooms in South Africa Key Trends
Recovery from excess supply of rooms: Accommodation sales grew by 5% in 2014 recovering from the oversupply of rooms after the FIFA World Cup, hosted by South Africa in 2010
This oversupply of rooms impacted Western Cape and Kwazulu Natal provinces more than any other province, as increased tourist activity was expected in these provinces after the World Cup
4-star hotels are expected to dominate in the room availability segment: During 2016–2020, 4-star hotels will account for 38% of the total growth in the number of available rooms in South Africa Room Revenue by Category, 2015<br>
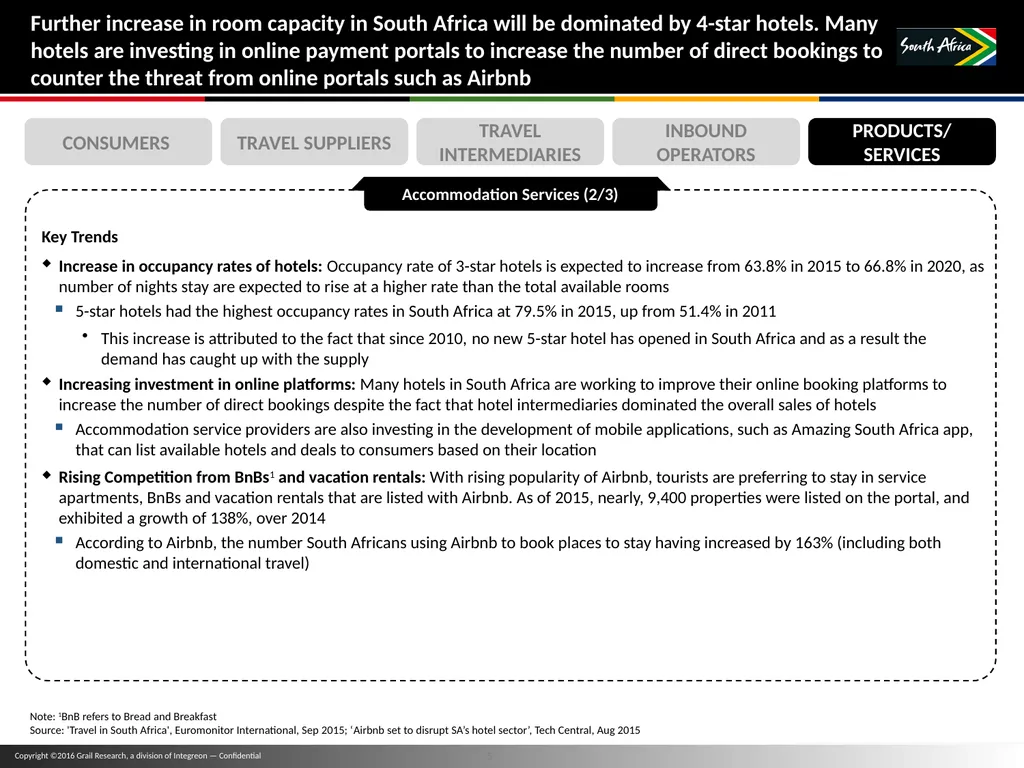
slide5. 5 Further increase in room capacity in South Africa will be dominated by 4-star hotels. Many hotels are investing in online payment portals to increase the number of direct bookings to counter the threat from online portals such as Airbnb Note: 1BnB refers to Bread and Breakfast
Source: 'Travel in South Africa', Euromonitor International, Sep 2015; ‘Airbnb set to disrupt SA’s hotel sector’, Tech Central, Aug 2015 Key Trends
Increase in occupancy rates of hotels: Occupancy rate of 3-star hotels is expected to increase from 63.8% in 2015 to 66.8% in 2020, as number of nights stay are expected to rise at a higher rate than the total available rooms
5-star hotels had the highest occupancy rates in South Africa at 79.5% in 2015, up from 51.4% in 2011
This increase is attributed to the fact that since 2010, no new 5-star hotel has opened in South Africa and as a result the demand has caught up with the supply
Increasing investment in online platforms: Many hotels in South Africa are working to improve their online booking platforms to increase the number of direct bookings despite the fact that hotel intermediaries dominated the overall sales of hotels
Accommodation service providers are also investing in the development of mobile applications, such as Amazing South Africa app, that can list available hotels and deals to consumers based on their location
Rising Competition from BnBs1 and vacation rentals: With rising popularity of Airbnb, tourists are preferring to stay in service apartments, BnBs and vacation rentals that are listed with Airbnb. As of 2015, nearly, 9,400 properties were listed on the portal, and exhibited a growth of 138%, over 2014
According to Airbnb, the number South Africans using Airbnb to book places to stay having increased by 163% (including both domestic and international travel)<br>
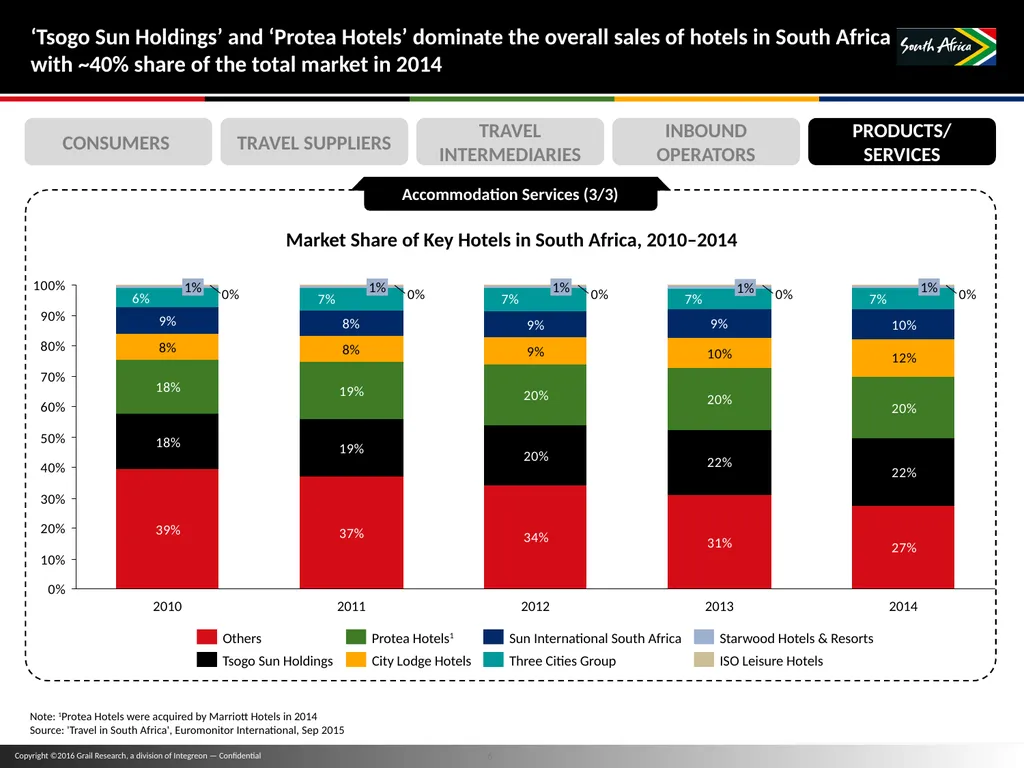
slide6. 6 ‘Tsogo Sun Holdings’ and ‘Protea Hotels’ dominate the overall sales of hotels in South Africa with ~40% share of the total market in 2014 Note: 1Protea Hotels were acquired by Marriott Hotels in 2014
Source: 'Travel in South Africa', Euromonitor International, Sep 2015 Market Share of Key Hotels in South Africa, 2010–2014 2012 1% 2010 2013 2014 1% 1% 2011 1% 1% Others Tsogo Sun Holdings Protea Hotels1 City Lodge Hotels Sun International South Africa Three Cities Group Starwood Hotels & Resorts ISO Leisure Hotels<br>
slide7. South Africa’s aviation industry can be categorised into two segments – ‘Scheduled Flight Carriers’ and ‘Low-cost Carriers’. Online bookings dominated the overall bookings of flights, with ~50% of tourists booking directly with the airline carriers Source: 'Travel in South Africa', Euromonitor International, Sep 2015 Low-Cost Carriers Scheduled Flight Carriers Overview
The airline industry in South Africa can be categorised into two segments – ‘Scheduled Flight Carriers’ – airlines that have scheduled departures and ‘Low-cost Carriers’ – airlines that offer tickets at a lower price than scheduled flight carriers
The market of both scheduled airlines and low-cost airlines in South Africa is imperfectly competitive as only a few players operate in the market
Key Trends
Online channels dominate airline bookings: 56% of the total airline bookings in 2014 were through online channels as consumers were more comfortable booking airline tickets online than any other travel provider
This trend was driven by increased efforts of airline carriers to increase the security of online payments
Increase in direct airline bookings: In 2014, ~50% of the online airline sales generated from direct bookings as airlines offered discounts to consumers for direct bookings
Despite these efforts from airlines, some consumers interested in booking a complete package, still believed that travel retailers can provide value for money deals to them
To counter this trend airlines partnered with other travel service providers, such as car rental companies and hotels, to provide consumers with packaged deals
Scheduled flight carriers rely on corporate tourists: Due to the high fares of scheduled flight carriers, corporate bookings are more happening than the leisure bookings<br>
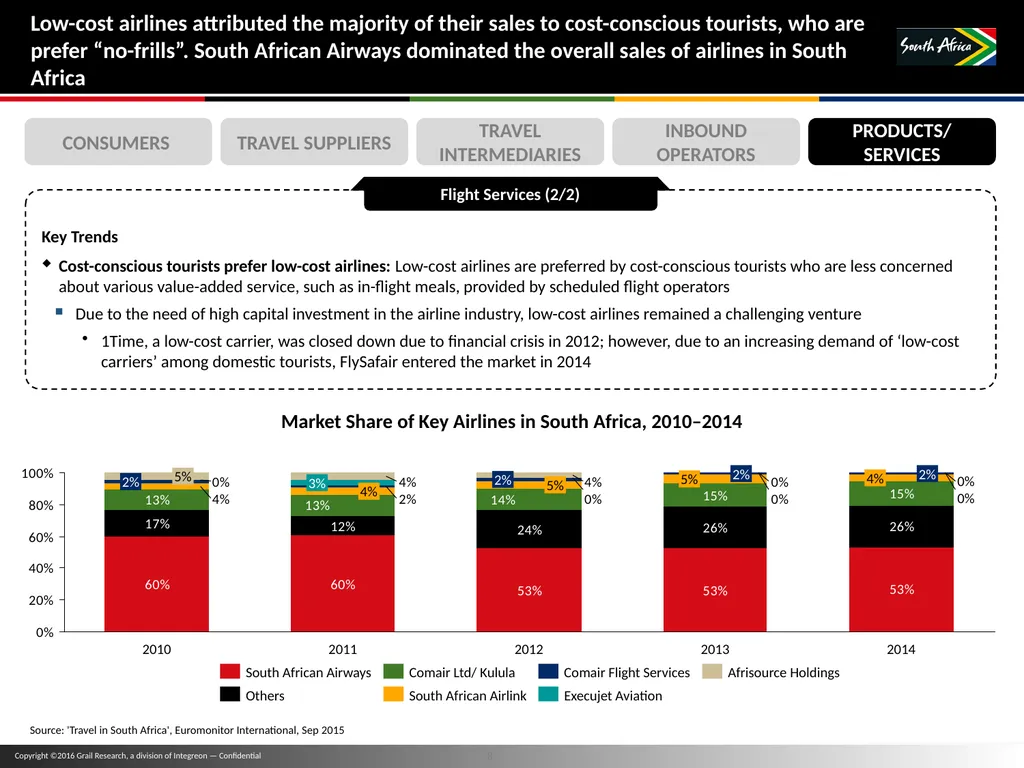
slide8. 8 Low-cost airlines attributed the majority of their sales to cost-conscious tourists, who are prefer “no-frills”. South African Airways dominated the overall sales of airlines in South Africa Source: 'Travel in South Africa', Euromonitor International, Sep 2015 Key Trends
Cost-conscious tourists prefer low-cost airlines: Low-cost airlines are preferred by cost-conscious tourists who are less concerned about various value-added service, such as in-flight meals, provided by scheduled flight operators
Due to the need of high capital investment in the airline industry, low-cost airlines remained a challenging venture
1Time, a low-cost carrier, was closed down due to financial crisis in 2012; however, due to an increasing demand of ‘low-cost carriers’ among domestic tourists, FlySafair entered the market in 2014 5% 2012 2% 2014 0% 0% 2% 4% 2013 4% 2010 5% 2% 2% 5% 2011 3% Comair Ltd/ Kulula South African Airlink Comair Flight Services Execujet Aviation Afrisource Holdings Others South African Airways Market Share of Key Airlines in South Africa, 2010–2014<br>
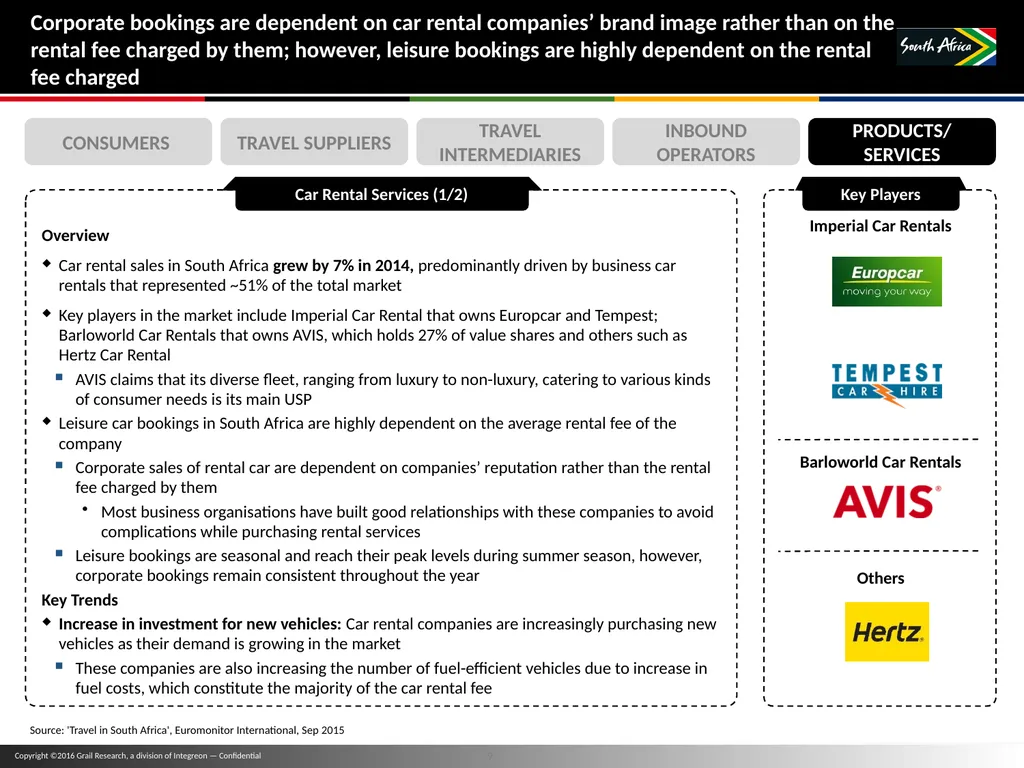
slide9. Corporate bookings are dependent on car rental companies’ brand image rather than on the rental fee charged by them; however, leisure bookings are highly dependent on the rental fee charged Source: 'Travel in South Africa', Euromonitor International, Sep 2015 Overview
Car rental sales in South Africa grew by 7% in 2014, predominantly driven by business car rentals that represented ~51% of the total market
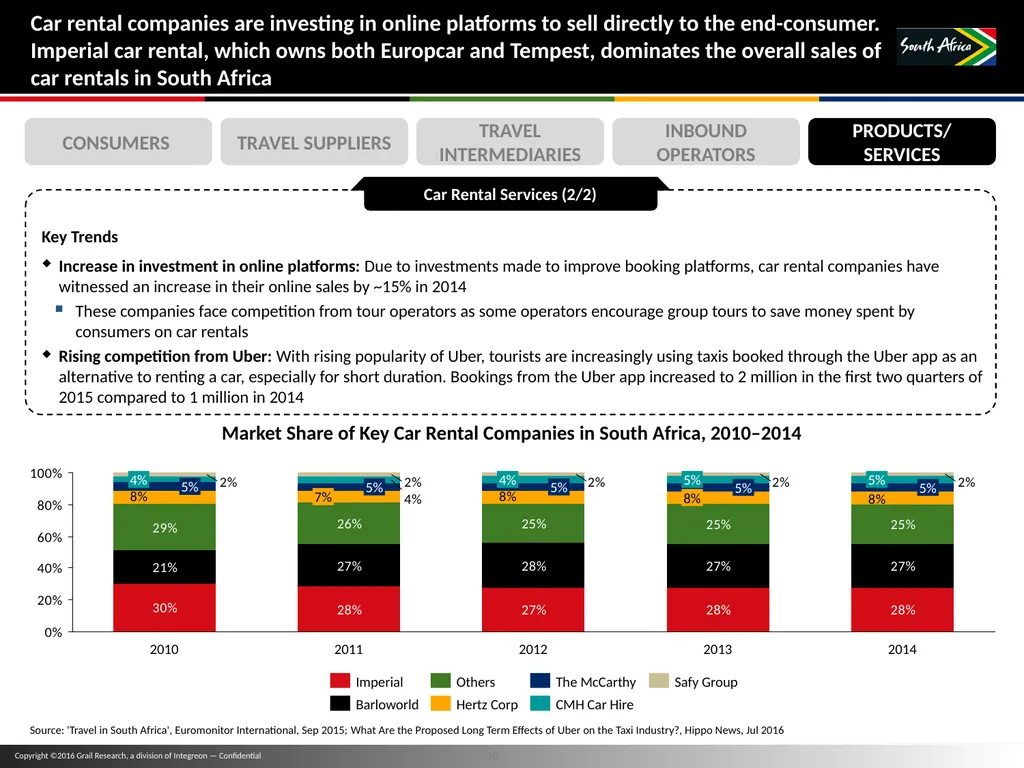
Key players in the market include Imperial Car Rental that owns Europcar and Tempest; Barloworld Car Rentals that owns AVIS, which holds 27% of value shares and others such as Hertz Car Rental
AVIS claims that its diverse fleet, ranging from luxury to non-luxury, catering to various kinds of consumer needs is its main USP
Leisure car bookings in South Africa are highly dependent on the average rental fee of the company
Corporate sales of rental car are dependent on companies’ reputation rather than the rental fee charged by them
Most business organisations have built good relationships with these companies to avoid complications while purchasing rental services
Leisure bookings are seasonal and reach their peak levels during summer season, however, corporate bookings remain consistent throughout the year
Key Trends
Increase in investment for new vehicles: Car rental companies are increasingly purchasing new vehicles as their demand is growing in the market
These companies are also increasing the number of fuel-efficient vehicles due to increase in fuel costs, which constitute the majority of the car rental fee Imperial Car Rentals Barloworld Car Rentals Others<br>
slide10. 10 Car rental companies are investing in online platforms to sell directly to the end-consumer. Imperial car rental, which owns both Europcar and Tempest, dominates the overall sales of car rentals in South Africa Source: 'Travel in South Africa', Euromonitor International, Sep 2015; What Are the Proposed Long Term Effects of Uber on the Taxi Industry?, Hippo News, Jul 2016 Key Trends
Increase in investment in online platforms: Due to investments made to improve booking platforms, car rental companies have witnessed an increase in their online sales by ~15% in 2014
These companies face competition from tour operators as some operators encourage group tours to save money spent by consumers on car rentals
Rising competition from Uber: With rising popularity of Uber, tourists are increasingly using taxis booked through the Uber app as an alternative to renting a car, especially for short duration. Bookings from the Uber app increased to 2 million in the first two quarters of 2015 compared to 1 million in 2014 5% 8% 2014 4% 5% 5% 5% 2013 5% 2011 2010 7% 5% 4% 2012 5% Hertz Corp Barloworld Imperial Others The McCarthy CMH Car Hire Safy Group Market Share of Key Car Rental Companies in South Africa, 2010–2014<br>
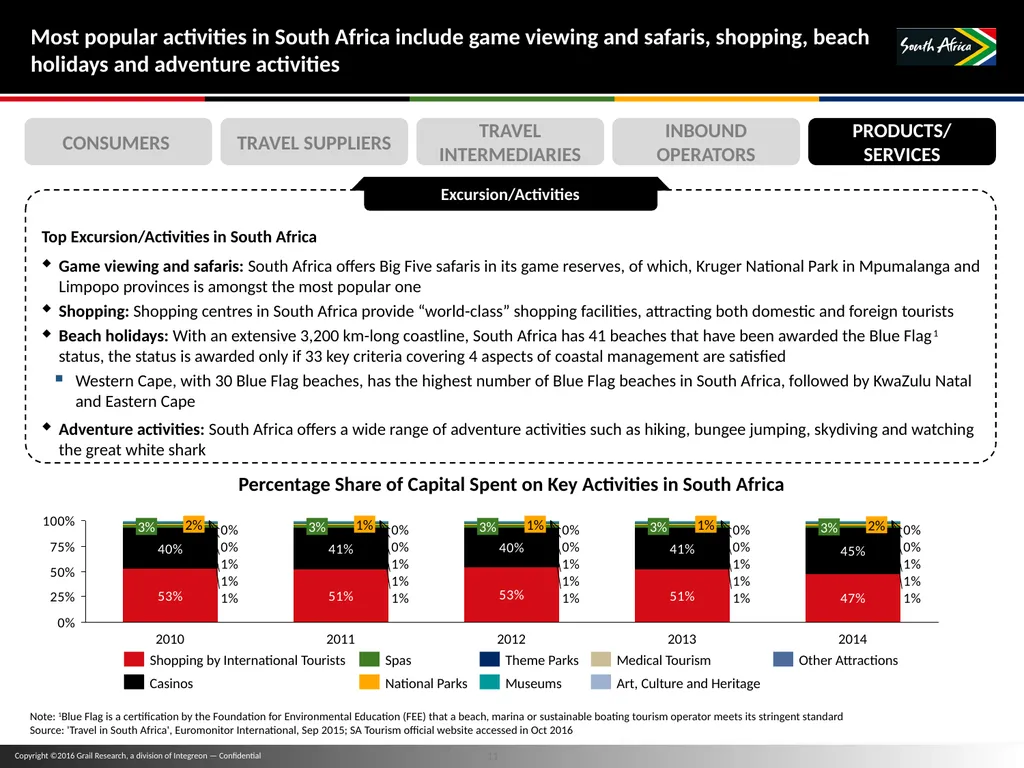
slide11. 11 Most popular activities in South Africa include game viewing and safaris, shopping, beach holidays and adventure activities Top Excursion/Activities in South Africa
Game viewing and safaris: South Africa offers Big Five safaris in its game reserves, of which, Kruger National Park in Mpumalanga and Limpopo provinces is amongst the most popular one
Shopping: Shopping centres in South Africa provide “world-class” shopping facilities, attracting both domestic and foreign tourists
Beach holidays: With an extensive 3,200 km-long coastline, South Africa has 41 beaches that have been awarded the Blue Flag1 status, the status is awarded only if 33 key criteria covering 4 aspects of coastal management are satisfied
Western Cape, with 30 Blue Flag beaches, has the highest number of Blue Flag beaches in South Africa, followed by KwaZulu Natal and Eastern Cape
Adventure activities: South Africa offers a wide range of adventure activities such as hiking, bungee jumping, skydiving and watching the great white shark 3% 2010 2011 1% 1% 3% 2012 2013 3% 2% 3% 1% 3% 2% 2014 Art, Culture and Heritage Other Attractions Shopping by International Tourists Casinos Spas Medical Tourism Museums National Parks Theme Parks Percentage Share of Capital Spent on Key Activities in South Africa Note: 1Blue Flag is a certification by the Foundation for Environmental Education (FEE) that a beach, marina or sustainable boating tourism operator meets its stringent standard
Source: 'Travel in South Africa', Euromonitor International, Sep 2015; SA Tourism official website accessed in Oct 2016<br>
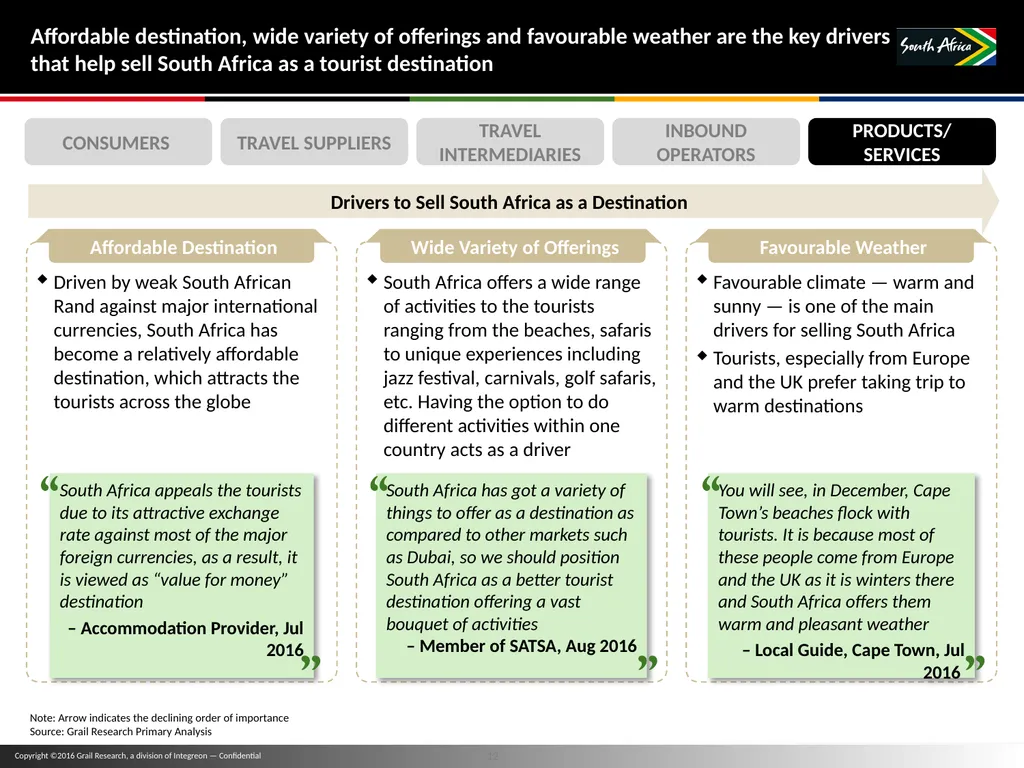
slide12. Affordable destination, wide variety of offerings and favourable weather are the key drivers that help sell South Africa as a tourist destination Driven by weak South African Rand against major international currencies, South Africa has become a relatively affordable destination, which attracts the tourists across the globe South Africa offers a wide range of activities to the tourists ranging from the beaches, safaris to unique experiences including jazz festival, carnivals, golf safaris, etc. Having the option to do different activities within one country acts as a driver Favourable climate — warm and sunny — is one of the main drivers for selling South Africa
Tourists, especially from Europe and the UK prefer taking trip to warm destinations South Africa appeals the tourists due to its attractive exchange rate against most of the major foreign currencies, as a result, it is viewed as “value for money” destination
– Accommodation Provider, Jul 2016 South Africa has got a variety of things to offer as a destination as compared to other markets such as Dubai, so we should position South Africa as a better tourist destination offering a vast bouquet of activities
– Member of SATSA, Aug 2016 You will see, in December, Cape Town’s beaches flock with tourists. It is because most of these people come from Europe and the UK as it is winters there and South Africa offers them warm and pleasant weather
– Local Guide, Cape Town, Jul 2016 Drivers to Sell South Africa as a Destination Note: Arrow indicates the declining order of importance
Source: Grail Research Primary Analysis CONSUMERS TRAVEL SUPPLIERS TRAVEL INTERMEDIARIES INBOUND OPERATORS PRODUCTS/ SERVICES<br>
slide13. Perception of South Africa as a ‘less safe destination’, expensive flights and lack of sufficient knowledge and skills are the factors hindering outbound travel to South Africa Tourists perceive South Africa as a ‘less-safe’ destination, which acts as key barrier While in-destination products and services are affordable in South Africa, the flights are expensive due to its geographic location and therefore tourists prefer to travel to other destinations Lack of sufficient knowledge and skill-set for selling South Africa, including lack of foreign language speaking guides, lack of training among the ground handlers, etc. may affect the number of tourists arrivals to South Africa Tourists perceive South Africa as an unsafe destination, we’ve got to find positive ways to create awareness among the tourists about South Africa being a safe place
–Member of SATSA, Jul 2016 Airport tax is a big barrier, it’s too high, and that’s why airlines are not flying…if we reduce that, it would be good for South Africa
–Member of SATSA, Aug 2016 One of the industry challenges is the lack of skills. Everybody is looking for staff with right skill set; however, there is shortage of skilled people to promote and sell South Africa
–Member of SATSA, Aug 2016 High Cost of Flights Barriers to Sell South Africa as a Destination Lack of Adequate Skills Note: Arrow indicates the declining order of importance
Source: Grail Research Primary Analysis CONSUMERS TRAVEL SUPPLIERS TRAVEL INTERMEDIARIES INBOUND OPERATORS PRODUCTS/ SERVICES Lack of Safety and Security<br>
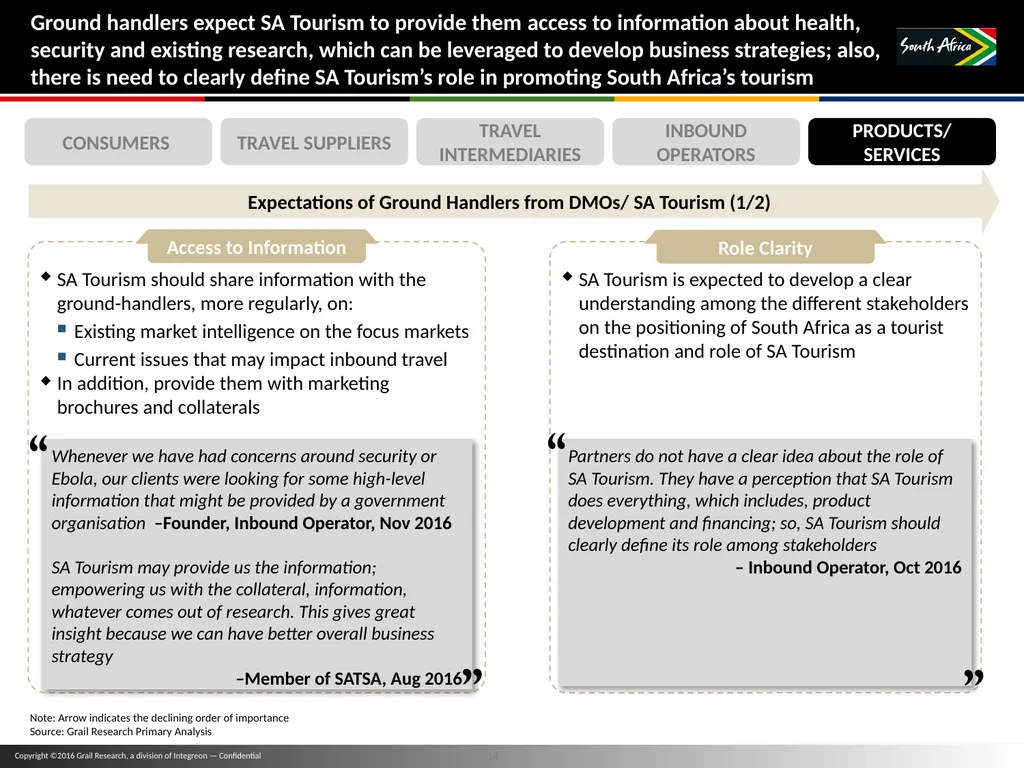
slide14. Ground handlers expect SA Tourism to provide them access to information about health, security and existing research, which can be leveraged to develop business strategies; also, there is need to clearly define SA Tourism’s role in promoting South Africa’s tourism Note: Arrow indicates the declining order of importance
Source: Grail Research Primary Analysis CONSUMERS TRAVEL SUPPLIERS TRAVEL INTERMEDIARIES INBOUND OPERATORS PRODUCTS/ SERVICES Expectations of Ground Handlers from DMOs/ SA Tourism (1/2) SA Tourism should share information with the ground-handlers, more regularly, on:
Existing market intelligence on the focus markets
Current issues that may impact inbound travel
In addition, provide them with marketing brochures and collaterals Whenever we have had concerns around security or Ebola, our clients were looking for some high-level information that might be provided by a government organisation –Founder, Inbound Operator, Nov 2016
SA Tourism may provide us the information; empowering us with the collateral, information, whatever comes out of research. This gives great insight because we can have better overall business strategy
–Member of SATSA, Aug 2016 Access to Information SA Tourism is expected to develop a clear understanding among the different stakeholders on the positioning of South Africa as a tourist destination and role of SA Tourism Partners do not have a clear idea about the role of SA Tourism. They have a perception that SA Tourism does everything, which includes, product development and financing; so, SA Tourism should clearly define its role among stakeholders
– Inbound Operator, Oct 2016 Role Clarity<br>
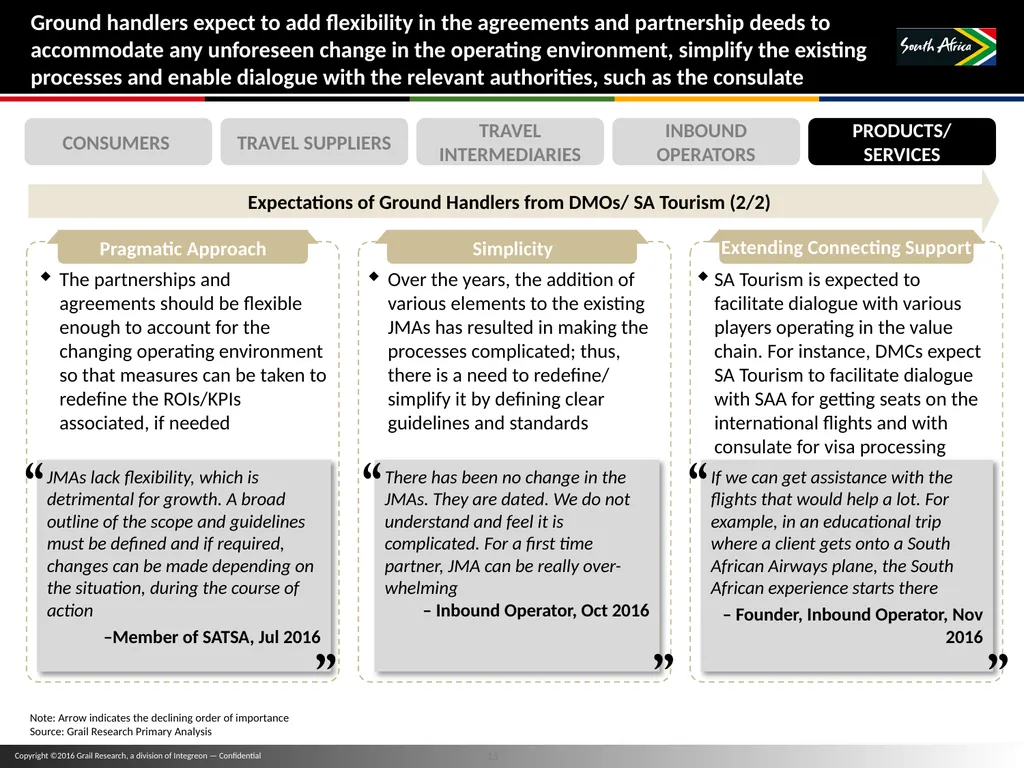
slide15. Ground handlers expect to add flexibility in the agreements and partnership deeds to accommodate any unforeseen change in the operating environment, simplify the existing processes and enable dialogue with the relevant authorities, such as the consulate CONSUMERS TRAVEL SUPPLIERS TRAVEL INTERMEDIARIES INBOUND OPERATORS PRODUCTS/ SERVICES Expectations of Ground Handlers from DMOs/ SA Tourism (2/2) The partnerships and agreements should be flexible enough to account for the changing operating environment so that measures can be taken to redefine the ROIs/KPIs associated, if needed JMAs lack flexibility, which is detrimental for growth. A broad outline of the scope and guidelines must be defined and if required, changes can be made depending on the situation, during the course of action
–Member of SATSA, Jul 2016 Pragmatic Approach Over the years, the addition of various elements to the existing JMAs has resulted in making the processes complicated; thus, there is a need to redefine/ simplify it by defining clear guidelines and standards There has been no change in the JMAs. They are dated. We do not understand and feel it is complicated. For a first time partner, JMA can be really over-whelming
– Inbound Operator, Oct 2016 Simplicity SA Tourism is expected to facilitate dialogue with various players operating in the value chain. For instance, DMCs expect SA Tourism to facilitate dialogue with SAA for getting seats on the international flights and with consulate for visa processing If we can get assistance with the flights that would help a lot. For example, in an educational trip where a client gets onto a South African Airways plane, the South African experience starts there
– Founder, Inbound Operator, Nov 2016 Extending Connecting Support Note: Arrow indicates the declining order of importance
Source: Grail Research Primary Analysis<br>
slide16. For more information, please contact: www.integreon.com © 2016 Grail Research, a division of Integreon
No part of this publication may be reproduced, stored in a retrieval system, or transmitted in any form or by any means — electronic, mechanical, photocopying, recording, or otherwise — without the permission of Integreon.
This document provides an outline of a presentation and is incomplete without the accompanying oral commentary and discussion.
COMPANY CONFIDENTIAL<br>
slide2. TABLE OF CONTENTS: Formulating the Trade Strategy Project Objective and Status Update
Global Travellers’ Purchase Process
Tourism Value Chain: Products and Services Providers<br>
slide3. Products/services providers in South Africa comprises accommodation providers, airlines, transportation providers (including car rental services) and activity operators and excursion/activities South Africa Ground Handlers Landscape: Summary Source: Grail Research analysis South Africa’s accommodation industry includes hotels for all income segments, ranging from budget hotels (2-star, 3-star) to luxury hotels (4-star and 5-star) as well as other accommodations including service apartments, hostels and Bread and Breakfast. 4-star hotels are leading the segment, accounting for 36% of the total hotel room revenues in 2015 South Africa’s airline industry offers both scheduled flight carriers and low-cost carriers. Car rental sales in South Africa increased at a rate of 7% in 2014, primarily driven by business car rentals that represented ~51% of the total market. South Africa offers a lot of excursion/activities, including game viewing and safaris, shopping, beach and adventure sports activities Key drivers for selling South Africa as a tourist destination include affordable destination, wide variety of offerings and favourable weather, while the key inhibitors include perception among the tourists as a less-safe destination, high cost of flights and lack of adequate skilled labour in South Africa Ground handlers expectations from SA Tourism include: 1) access to information, 2) clarity on role of SA Tourism, 3) process to alter agreements/partnerships in view of the operating environment, 4) simplify the existing processes such as JMAs and 5) extending support in facilitating dialogue for smooth transactions, such as for visa and air connectivity<br>
slide4. South Africa’s accommodation industry is recovering from the oversupply of rooms after the FIFA World Cup in 2010 Available Rooms by Category, 2015 Source: 'Travel in South Africa', Euromonitor International, Sep 2015; Hotels Outlook: 2016–2020, PWC, Jul 2016 Overview
The accommodation industry in South Africa can be categorised in four key segments – 3-star hotels, 4-star hotels, 5-star hotels and others, which include campsites, hostels, and self-catering apartments
In 2015, 3-star hotels accounted for 36% of the total rooms and 32% of the total hotel room revenue in South Africa
Room revenue of 3-star hotels is expected to rise from ZAR 4.6 Bn in 2015 to ZAR 6.6 Bn in 2020
In 2015, 4-star hotels accounted for 36%, highest among all categories, of the total hotel room revenues in South Africa
In 2015, 5-star hotels accounted for 15% of the total hotel room revenue despite holding only a 5% share of the total rooms in South Africa Key Trends
Recovery from excess supply of rooms: Accommodation sales grew by 5% in 2014 recovering from the oversupply of rooms after the FIFA World Cup, hosted by South Africa in 2010
This oversupply of rooms impacted Western Cape and Kwazulu Natal provinces more than any other province, as increased tourist activity was expected in these provinces after the World Cup
4-star hotels are expected to dominate in the room availability segment: During 2016–2020, 4-star hotels will account for 38% of the total growth in the number of available rooms in South Africa Room Revenue by Category, 2015<br>
slide5. 5 Further increase in room capacity in South Africa will be dominated by 4-star hotels. Many hotels are investing in online payment portals to increase the number of direct bookings to counter the threat from online portals such as Airbnb Note: 1BnB refers to Bread and Breakfast
Source: 'Travel in South Africa', Euromonitor International, Sep 2015; ‘Airbnb set to disrupt SA’s hotel sector’, Tech Central, Aug 2015 Key Trends
Increase in occupancy rates of hotels: Occupancy rate of 3-star hotels is expected to increase from 63.8% in 2015 to 66.8% in 2020, as number of nights stay are expected to rise at a higher rate than the total available rooms
5-star hotels had the highest occupancy rates in South Africa at 79.5% in 2015, up from 51.4% in 2011
This increase is attributed to the fact that since 2010, no new 5-star hotel has opened in South Africa and as a result the demand has caught up with the supply
Increasing investment in online platforms: Many hotels in South Africa are working to improve their online booking platforms to increase the number of direct bookings despite the fact that hotel intermediaries dominated the overall sales of hotels
Accommodation service providers are also investing in the development of mobile applications, such as Amazing South Africa app, that can list available hotels and deals to consumers based on their location
Rising Competition from BnBs1 and vacation rentals: With rising popularity of Airbnb, tourists are preferring to stay in service apartments, BnBs and vacation rentals that are listed with Airbnb. As of 2015, nearly, 9,400 properties were listed on the portal, and exhibited a growth of 138%, over 2014
According to Airbnb, the number South Africans using Airbnb to book places to stay having increased by 163% (including both domestic and international travel)<br>
slide6. 6 ‘Tsogo Sun Holdings’ and ‘Protea Hotels’ dominate the overall sales of hotels in South Africa with ~40% share of the total market in 2014 Note: 1Protea Hotels were acquired by Marriott Hotels in 2014
Source: 'Travel in South Africa', Euromonitor International, Sep 2015 Market Share of Key Hotels in South Africa, 2010–2014 2012 1% 2010 2013 2014 1% 1% 2011 1% 1% Others Tsogo Sun Holdings Protea Hotels1 City Lodge Hotels Sun International South Africa Three Cities Group Starwood Hotels & Resorts ISO Leisure Hotels<br>
slide7. South Africa’s aviation industry can be categorised into two segments – ‘Scheduled Flight Carriers’ and ‘Low-cost Carriers’. Online bookings dominated the overall bookings of flights, with ~50% of tourists booking directly with the airline carriers Source: 'Travel in South Africa', Euromonitor International, Sep 2015 Low-Cost Carriers Scheduled Flight Carriers Overview
The airline industry in South Africa can be categorised into two segments – ‘Scheduled Flight Carriers’ – airlines that have scheduled departures and ‘Low-cost Carriers’ – airlines that offer tickets at a lower price than scheduled flight carriers
The market of both scheduled airlines and low-cost airlines in South Africa is imperfectly competitive as only a few players operate in the market
Key Trends
Online channels dominate airline bookings: 56% of the total airline bookings in 2014 were through online channels as consumers were more comfortable booking airline tickets online than any other travel provider
This trend was driven by increased efforts of airline carriers to increase the security of online payments
Increase in direct airline bookings: In 2014, ~50% of the online airline sales generated from direct bookings as airlines offered discounts to consumers for direct bookings
Despite these efforts from airlines, some consumers interested in booking a complete package, still believed that travel retailers can provide value for money deals to them
To counter this trend airlines partnered with other travel service providers, such as car rental companies and hotels, to provide consumers with packaged deals
Scheduled flight carriers rely on corporate tourists: Due to the high fares of scheduled flight carriers, corporate bookings are more happening than the leisure bookings<br>
slide8. 8 Low-cost airlines attributed the majority of their sales to cost-conscious tourists, who are prefer “no-frills”. South African Airways dominated the overall sales of airlines in South Africa Source: 'Travel in South Africa', Euromonitor International, Sep 2015 Key Trends
Cost-conscious tourists prefer low-cost airlines: Low-cost airlines are preferred by cost-conscious tourists who are less concerned about various value-added service, such as in-flight meals, provided by scheduled flight operators
Due to the need of high capital investment in the airline industry, low-cost airlines remained a challenging venture
1Time, a low-cost carrier, was closed down due to financial crisis in 2012; however, due to an increasing demand of ‘low-cost carriers’ among domestic tourists, FlySafair entered the market in 2014 5% 2012 2% 2014 0% 0% 2% 4% 2013 4% 2010 5% 2% 2% 5% 2011 3% Comair Ltd/ Kulula South African Airlink Comair Flight Services Execujet Aviation Afrisource Holdings Others South African Airways Market Share of Key Airlines in South Africa, 2010–2014<br>
slide9. Corporate bookings are dependent on car rental companies’ brand image rather than on the rental fee charged by them; however, leisure bookings are highly dependent on the rental fee charged Source: 'Travel in South Africa', Euromonitor International, Sep 2015 Overview
Car rental sales in South Africa grew by 7% in 2014, predominantly driven by business car rentals that represented ~51% of the total market
Key players in the market include Imperial Car Rental that owns Europcar and Tempest; Barloworld Car Rentals that owns AVIS, which holds 27% of value shares and others such as Hertz Car Rental
AVIS claims that its diverse fleet, ranging from luxury to non-luxury, catering to various kinds of consumer needs is its main USP
Leisure car bookings in South Africa are highly dependent on the average rental fee of the company
Corporate sales of rental car are dependent on companies’ reputation rather than the rental fee charged by them
Most business organisations have built good relationships with these companies to avoid complications while purchasing rental services
Leisure bookings are seasonal and reach their peak levels during summer season, however, corporate bookings remain consistent throughout the year
Key Trends
Increase in investment for new vehicles: Car rental companies are increasingly purchasing new vehicles as their demand is growing in the market
These companies are also increasing the number of fuel-efficient vehicles due to increase in fuel costs, which constitute the majority of the car rental fee Imperial Car Rentals Barloworld Car Rentals Others<br>
slide10. 10 Car rental companies are investing in online platforms to sell directly to the end-consumer. Imperial car rental, which owns both Europcar and Tempest, dominates the overall sales of car rentals in South Africa Source: 'Travel in South Africa', Euromonitor International, Sep 2015; What Are the Proposed Long Term Effects of Uber on the Taxi Industry?, Hippo News, Jul 2016 Key Trends
Increase in investment in online platforms: Due to investments made to improve booking platforms, car rental companies have witnessed an increase in their online sales by ~15% in 2014
These companies face competition from tour operators as some operators encourage group tours to save money spent by consumers on car rentals
Rising competition from Uber: With rising popularity of Uber, tourists are increasingly using taxis booked through the Uber app as an alternative to renting a car, especially for short duration. Bookings from the Uber app increased to 2 million in the first two quarters of 2015 compared to 1 million in 2014 5% 8% 2014 4% 5% 5% 5% 2013 5% 2011 2010 7% 5% 4% 2012 5% Hertz Corp Barloworld Imperial Others The McCarthy CMH Car Hire Safy Group Market Share of Key Car Rental Companies in South Africa, 2010–2014<br>
slide11. 11 Most popular activities in South Africa include game viewing and safaris, shopping, beach holidays and adventure activities Top Excursion/Activities in South Africa
Game viewing and safaris: South Africa offers Big Five safaris in its game reserves, of which, Kruger National Park in Mpumalanga and Limpopo provinces is amongst the most popular one
Shopping: Shopping centres in South Africa provide “world-class” shopping facilities, attracting both domestic and foreign tourists
Beach holidays: With an extensive 3,200 km-long coastline, South Africa has 41 beaches that have been awarded the Blue Flag1 status, the status is awarded only if 33 key criteria covering 4 aspects of coastal management are satisfied
Western Cape, with 30 Blue Flag beaches, has the highest number of Blue Flag beaches in South Africa, followed by KwaZulu Natal and Eastern Cape
Adventure activities: South Africa offers a wide range of adventure activities such as hiking, bungee jumping, skydiving and watching the great white shark 3% 2010 2011 1% 1% 3% 2012 2013 3% 2% 3% 1% 3% 2% 2014 Art, Culture and Heritage Other Attractions Shopping by International Tourists Casinos Spas Medical Tourism Museums National Parks Theme Parks Percentage Share of Capital Spent on Key Activities in South Africa Note: 1Blue Flag is a certification by the Foundation for Environmental Education (FEE) that a beach, marina or sustainable boating tourism operator meets its stringent standard
Source: 'Travel in South Africa', Euromonitor International, Sep 2015; SA Tourism official website accessed in Oct 2016<br>
slide12. Affordable destination, wide variety of offerings and favourable weather are the key drivers that help sell South Africa as a tourist destination Driven by weak South African Rand against major international currencies, South Africa has become a relatively affordable destination, which attracts the tourists across the globe South Africa offers a wide range of activities to the tourists ranging from the beaches, safaris to unique experiences including jazz festival, carnivals, golf safaris, etc. Having the option to do different activities within one country acts as a driver Favourable climate — warm and sunny — is one of the main drivers for selling South Africa
Tourists, especially from Europe and the UK prefer taking trip to warm destinations South Africa appeals the tourists due to its attractive exchange rate against most of the major foreign currencies, as a result, it is viewed as “value for money” destination
– Accommodation Provider, Jul 2016 South Africa has got a variety of things to offer as a destination as compared to other markets such as Dubai, so we should position South Africa as a better tourist destination offering a vast bouquet of activities
– Member of SATSA, Aug 2016 You will see, in December, Cape Town’s beaches flock with tourists. It is because most of these people come from Europe and the UK as it is winters there and South Africa offers them warm and pleasant weather
– Local Guide, Cape Town, Jul 2016 Drivers to Sell South Africa as a Destination Note: Arrow indicates the declining order of importance
Source: Grail Research Primary Analysis CONSUMERS TRAVEL SUPPLIERS TRAVEL INTERMEDIARIES INBOUND OPERATORS PRODUCTS/ SERVICES<br>
slide13. Perception of South Africa as a ‘less safe destination’, expensive flights and lack of sufficient knowledge and skills are the factors hindering outbound travel to South Africa Tourists perceive South Africa as a ‘less-safe’ destination, which acts as key barrier While in-destination products and services are affordable in South Africa, the flights are expensive due to its geographic location and therefore tourists prefer to travel to other destinations Lack of sufficient knowledge and skill-set for selling South Africa, including lack of foreign language speaking guides, lack of training among the ground handlers, etc. may affect the number of tourists arrivals to South Africa Tourists perceive South Africa as an unsafe destination, we’ve got to find positive ways to create awareness among the tourists about South Africa being a safe place
–Member of SATSA, Jul 2016 Airport tax is a big barrier, it’s too high, and that’s why airlines are not flying…if we reduce that, it would be good for South Africa
–Member of SATSA, Aug 2016 One of the industry challenges is the lack of skills. Everybody is looking for staff with right skill set; however, there is shortage of skilled people to promote and sell South Africa
–Member of SATSA, Aug 2016 High Cost of Flights Barriers to Sell South Africa as a Destination Lack of Adequate Skills Note: Arrow indicates the declining order of importance
Source: Grail Research Primary Analysis CONSUMERS TRAVEL SUPPLIERS TRAVEL INTERMEDIARIES INBOUND OPERATORS PRODUCTS/ SERVICES Lack of Safety and Security<br>
slide14. Ground handlers expect SA Tourism to provide them access to information about health, security and existing research, which can be leveraged to develop business strategies; also, there is need to clearly define SA Tourism’s role in promoting South Africa’s tourism Note: Arrow indicates the declining order of importance
Source: Grail Research Primary Analysis CONSUMERS TRAVEL SUPPLIERS TRAVEL INTERMEDIARIES INBOUND OPERATORS PRODUCTS/ SERVICES Expectations of Ground Handlers from DMOs/ SA Tourism (1/2) SA Tourism should share information with the ground-handlers, more regularly, on:
Existing market intelligence on the focus markets
Current issues that may impact inbound travel
In addition, provide them with marketing brochures and collaterals Whenever we have had concerns around security or Ebola, our clients were looking for some high-level information that might be provided by a government organisation –Founder, Inbound Operator, Nov 2016
SA Tourism may provide us the information; empowering us with the collateral, information, whatever comes out of research. This gives great insight because we can have better overall business strategy
–Member of SATSA, Aug 2016 Access to Information SA Tourism is expected to develop a clear understanding among the different stakeholders on the positioning of South Africa as a tourist destination and role of SA Tourism Partners do not have a clear idea about the role of SA Tourism. They have a perception that SA Tourism does everything, which includes, product development and financing; so, SA Tourism should clearly define its role among stakeholders
– Inbound Operator, Oct 2016 Role Clarity<br>
slide15. Ground handlers expect to add flexibility in the agreements and partnership deeds to accommodate any unforeseen change in the operating environment, simplify the existing processes and enable dialogue with the relevant authorities, such as the consulate CONSUMERS TRAVEL SUPPLIERS TRAVEL INTERMEDIARIES INBOUND OPERATORS PRODUCTS/ SERVICES Expectations of Ground Handlers from DMOs/ SA Tourism (2/2) The partnerships and agreements should be flexible enough to account for the changing operating environment so that measures can be taken to redefine the ROIs/KPIs associated, if needed JMAs lack flexibility, which is detrimental for growth. A broad outline of the scope and guidelines must be defined and if required, changes can be made depending on the situation, during the course of action
–Member of SATSA, Jul 2016 Pragmatic Approach Over the years, the addition of various elements to the existing JMAs has resulted in making the processes complicated; thus, there is a need to redefine/ simplify it by defining clear guidelines and standards There has been no change in the JMAs. They are dated. We do not understand and feel it is complicated. For a first time partner, JMA can be really over-whelming
– Inbound Operator, Oct 2016 Simplicity SA Tourism is expected to facilitate dialogue with various players operating in the value chain. For instance, DMCs expect SA Tourism to facilitate dialogue with SAA for getting seats on the international flights and with consulate for visa processing If we can get assistance with the flights that would help a lot. For example, in an educational trip where a client gets onto a South African Airways plane, the South African experience starts there
– Founder, Inbound Operator, Nov 2016 Extending Connecting Support Note: Arrow indicates the declining order of importance
Source: Grail Research Primary Analysis<br>
slide16. For more information, please contact: www.integreon.com © 2016 Grail Research, a division of Integreon
No part of this publication may be reproduced, stored in a retrieval system, or transmitted in any form or by any means — electronic, mechanical, photocopying, recording, or otherwise — without the permission of Integreon.
This document provides an outline of a presentation and is incomplete without the accompanying oral commentary and discussion.
COMPANY CONFIDENTIAL<br>