
2026 OBL/NCBA Annual Convention Beyond the Hype
TG
Published · 20 slides · 0 views

1 / 1


Description
2026 OBLNCBA Annual Convention Beyond the Hype The GENIUS Act and Stablecoin Settlement Solutions for Community Banks Presented by Daniel Farra Chief Technology Officer ClearTrust , LLC 2026 OBLNCBA Annual Convention Presented by:
Related Topics
Share
Embed code
Download this presentation From Below
"2026 OBL/NCBA Annual Convention Beyond the Hype" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
2026 OBL/NCBA Annual Convention Beyond the Hype The GENIUS Act and Stablecoin Settlement Solutions
for Community Banks Presented by · Daniel Farra · Chief Technology Officer ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
for Community Banks Presented by · Daniel Farra · Chief Technology Officer ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
02
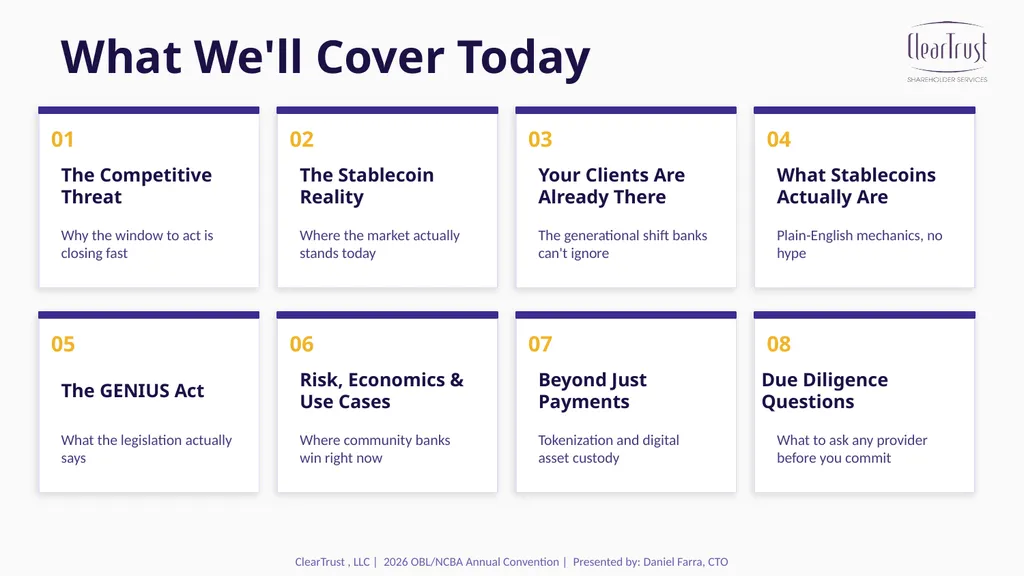
What We'll Cover Today 01 The Competitive Threat Why the window to act is closing fast 02 The Stablecoin Reality Where the market actually stands today 03 Your Clients Are Already There The generational shift banks can't ignore 04 What Stablecoins Actually Are Plain-English mechanics, no hype 05 The GENIUS Act What the legislation actually says 06 Risk, Economics & Use Cases Where community banks win right now 07 Beyond Just Payments Tokenization and digital asset custody 08 Due Diligence Questions What to ask any provider before you commit ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
03
The Threat You Haven't Priced In Fintech companies are actively pursuing Fed master accounts. If granted, they work OT to take your customers. What's Happening Right Now Fed Gov. Waller announced skinny master accounts in Oct 2025 direct Fed rail access for fintechs and stablecoin companies, bypassing the need for a bank partner. Fed is targeting Q4 2026 for operational rollout. Circle (USDC), Stripe, and others are already filing or have chartered. 11+ companies are actively racing for federal OCC national banking licenses right now. (FinTech Weekly, March 2026) Stripe acquired Bridge and launched the Tempo L1 blockchain (March 2026). Visa, Mastercard, PayPal, and major payment networks have announced integrated stablecoin rails coming. Payment Revenue Cannibalized Remittances, ACH wires, FX fees. Core community bank revenue are the first targets. Faster, cheaper, 24/7. Deposit Relationships At Risk If clients move payment flows to a fintech stablecoin wallet, operating account relationships follow. Deposits leave with them. Business Clients Are Next B2B invoice settlement and treasury management are already in fintech crosshairs. Without stablecoin capability, you become a passthrough custodian. The question is no longer whether to engage with stablecoins.
It's whether you engage on your terms or on theirs. ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
It's whether you engage on your terms or on theirs. ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
04
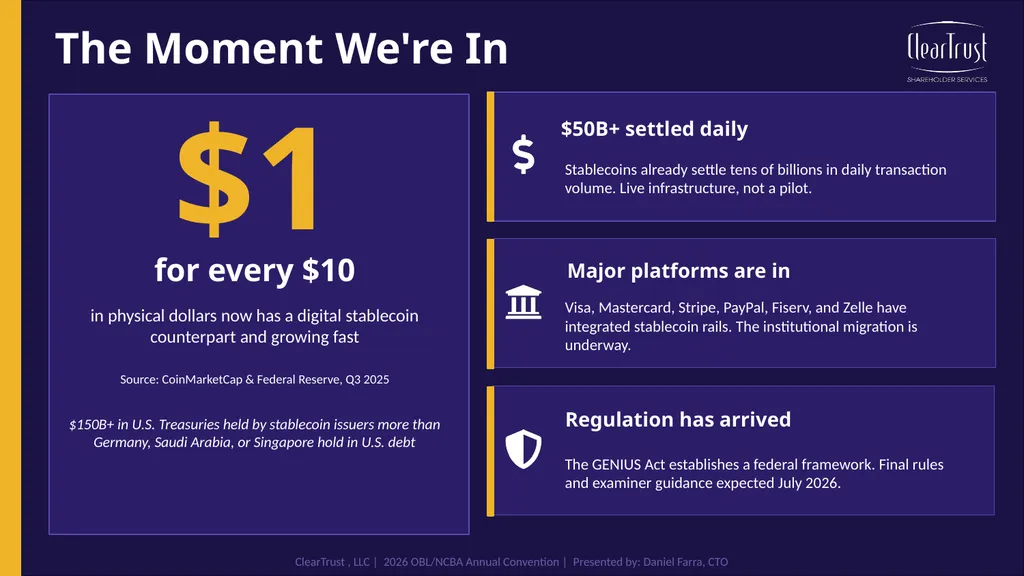
The Moment We're In $1 for every $10 in physical dollars now has a digital stablecoin counterpart and growing fast Source: CoinMarketCap & Federal Reserve, Q3 2025 $150B+ in U.S. Treasuries held by stablecoin issuers more than Germany, Saudi Arabia, or Singapore hold in U.S. debt $50B+ settled daily Stablecoins already settle tens of billions in daily transaction volume. Live infrastructure, not a pilot. Major platforms are in Visa, Mastercard, Stripe, PayPal, Fiserv, and Zelle have integrated stablecoin rails. The institutional migration is underway. Regulation has arrived The GENIUS Act establishes a federal framework. Final rules and examiner guidance expected July 2026. ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
05
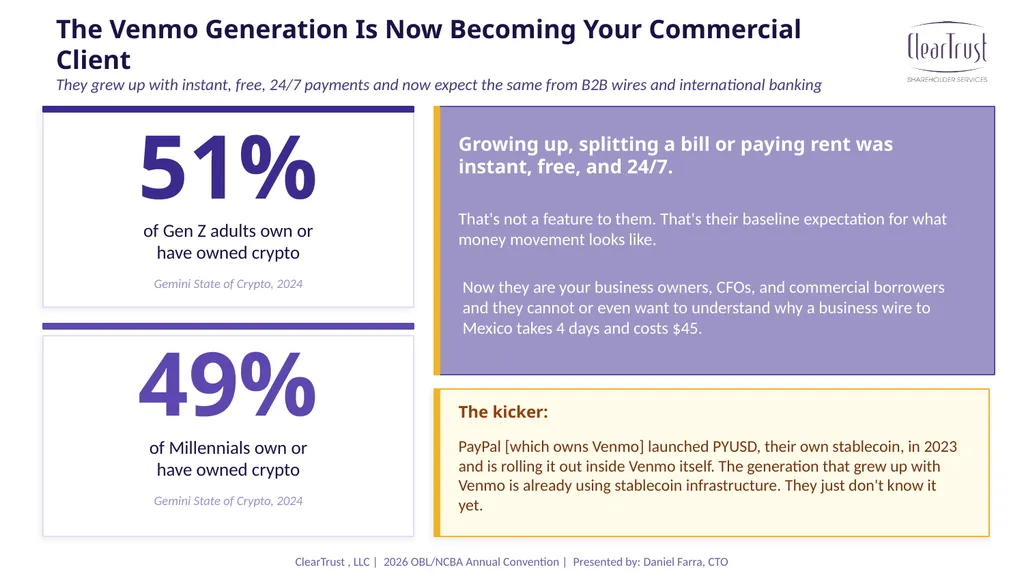
The Venmo Generation Is Now Becoming Your Commercial Client They grew up with instant, free, 24/7 payments and now expect the same from B2B wires and international banking 51% of Gen Z adults own or
have owned crypto Gemini State of Crypto, 2024 49% of Millennials own or
have owned crypto Gemini State of Crypto, 2024 Growing up, splitting a bill or paying rent was instant, free, and 24/7. That's not a feature to them. That's their baseline expectation for what money movement looks like. Now they are your business owners, CFOs, and commercial borrowers and they cannot or even want to understand why a business wire to Mexico takes 4 days and costs $45. The kicker: PayPal [which owns Venmo] launched PYUSD, their own stablecoin, in 2023 and is rolling it out inside Venmo itself. The generation that grew up with Venmo is already using stablecoin infrastructure. They just don't know it yet. ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
06
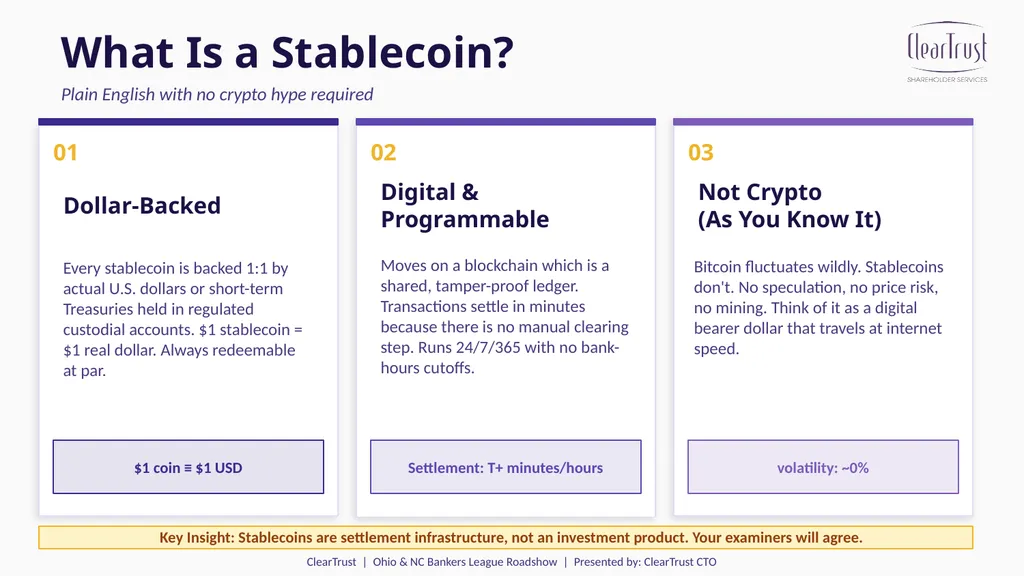
What Is a Stablecoin? Plain English with no crypto hype required 01 Dollar-Backed Every stablecoin is backed 1:1 by actual U.S. dollars or short-term Treasuries held in regulated custodial accounts. $1 stablecoin = $1 real dollar. Always redeemable at par. $1 coin ≡ $1 USD 02 Digital & Programmable Moves on a blockchain which is a shared, tamper-proof ledger. Transactions settle in minutes because there is no manual clearing step. Runs 24/7/365 with no bank-hours cutoffs. Settlement: T+ minutes/hours 03 Not Crypto
(As You Know It) Bitcoin fluctuates wildly. Stablecoins don't. No speculation, no price risk, no mining. Think of it as a digital bearer dollar that travels at internet speed. volatility: ~0% Key Insight: Stablecoins are settlement infrastructure, not an investment product. Your examiners will agree. ClearTrust | Ohio & NC Bankers League Roadshow | Presented by: ClearTrust CTO<br>
(As You Know It) Bitcoin fluctuates wildly. Stablecoins don't. No speculation, no price risk, no mining. Think of it as a digital bearer dollar that travels at internet speed. volatility: ~0% Key Insight: Stablecoins are settlement infrastructure, not an investment product. Your examiners will agree. ClearTrust | Ohio & NC Bankers League Roadshow | Presented by: ClearTrust CTO<br>
07
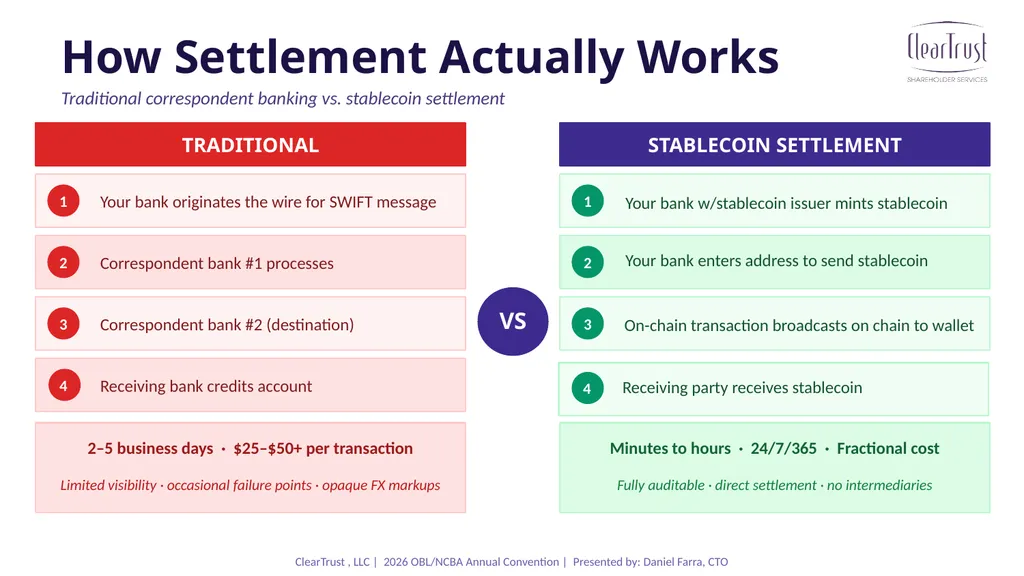
How Settlement Actually Works Traditional correspondent banking vs. stablecoin settlement TRADITIONAL 1 Your bank originates the wire for SWIFT message 2 Correspondent bank #1 processes 3 Correspondent bank #2 (destination) 4 Receiving bank credits account 2–5 business days · $25–$50+ per transaction Limited visibility · occasional failure points · opaque FX markups VS STABLECOIN SETTLEMENT 1 Your bank enters address to send stablecoin 2 On-chain transaction broadcasts on chain to wallet 3 Receiving party receives stablecoin Minutes to hours · 24/7/365 · Fractional cost Fully auditable · direct settlement · no intermediaries ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO Your bank w/stablecoin issuer mints stablecoin 4<br>
08
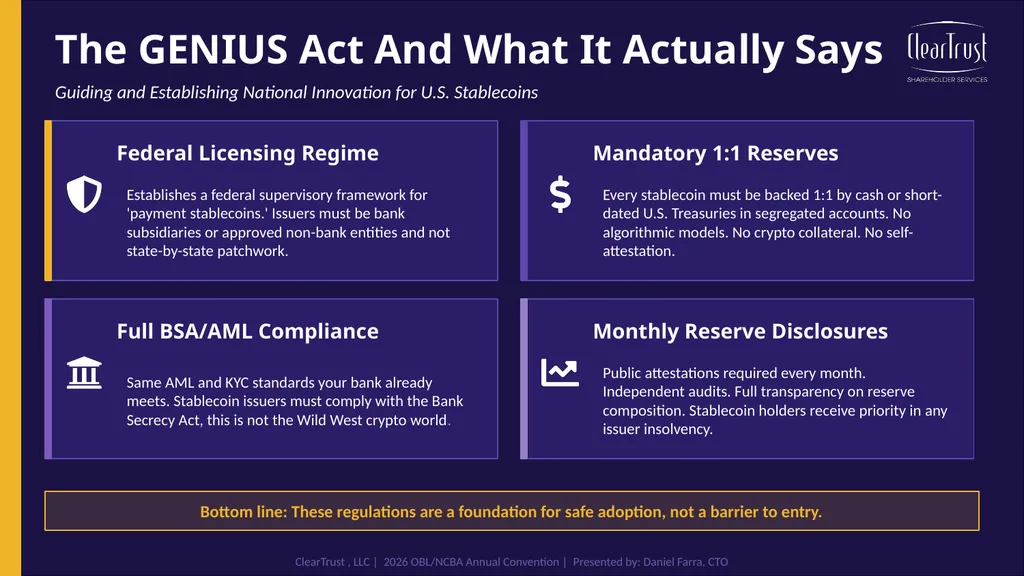
The GENIUS Act And What It Actually Says Guiding and Establishing National Innovation for U.S. Stablecoins Federal Licensing Regime Establishes a federal supervisory framework for 'payment stablecoins.' Issuers must be bank subsidiaries or approved non-bank entities and not state-by-state patchwork. Mandatory 1:1 Reserves Every stablecoin must be backed 1:1 by cash or short-dated U.S. Treasuries in segregated accounts. No algorithmic models. No crypto collateral. No self-attestation. Full BSA/AML Compliance Same AML and KYC standards your bank already meets. Stablecoin issuers must comply with the Bank Secrecy Act, this is not the Wild West crypto world. Monthly Reserve Disclosures Public attestations required every month. Independent audits. Full transparency on reserve composition. Stablecoin holders receive priority in any issuer insolvency. Bottom line: These regulations are a foundation for safe adoption, not a barrier to entry. ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
09
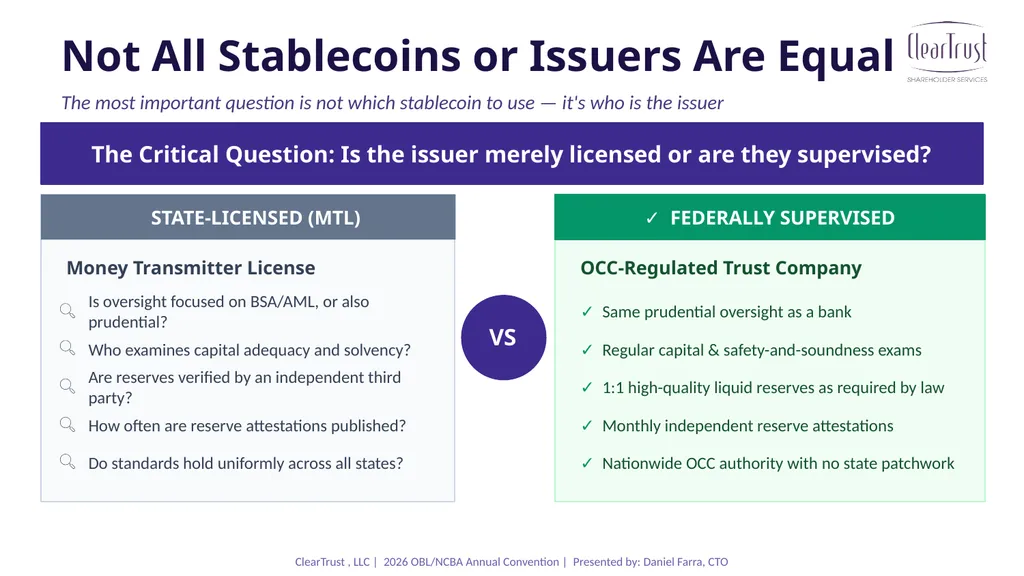
Not All Stablecoins or Issuers Are Equal The most important question is not which stablecoin to use — it's who is the issuer The Critical Question: Is the issuer merely licensed or are they supervised? STATE-LICENSED (MTL) Money Transmitter License Is oversight focused on BSA/AML, or also prudential? Who examines capital adequacy and solvency? Are reserves verified by an independent third party? How often are reserve attestations published? Do standards hold uniformly across all states? VS ✓ FEDERALLY SUPERVISED OCC-Regulated Trust Company ✓ Same prudential oversight as a bank ✓ Regular capital & safety-and-soundness exams ✓ 1:1 high-quality liquid reserves as required by law ✓ Monthly independent reserve attestations ✓ Nationwide OCC authority with no state patchwork ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
10
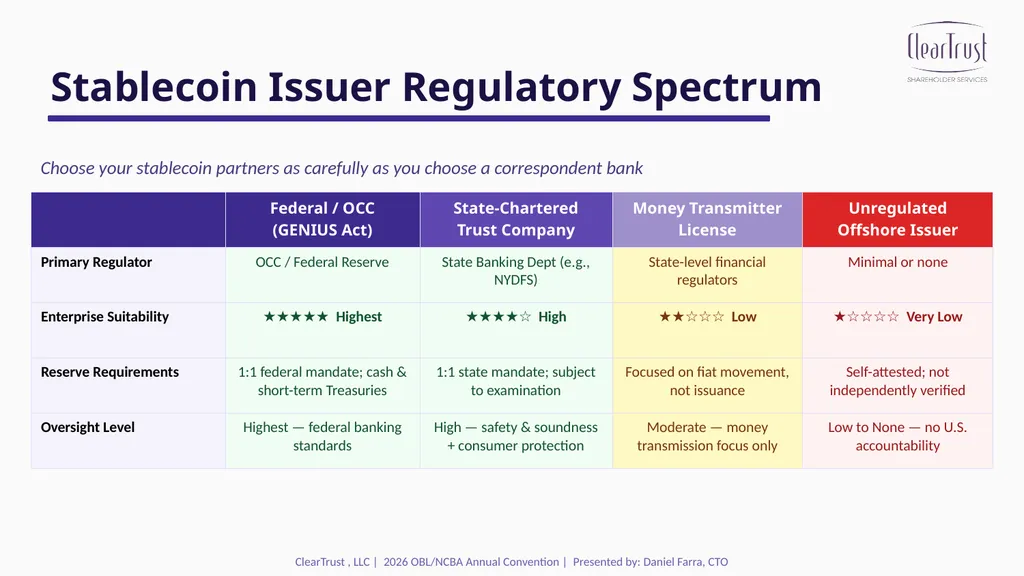
Stablecoin Issuer Regulatory Spectrum Choose your stablecoin partners as carefully as you choose a correspondent bank ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
11
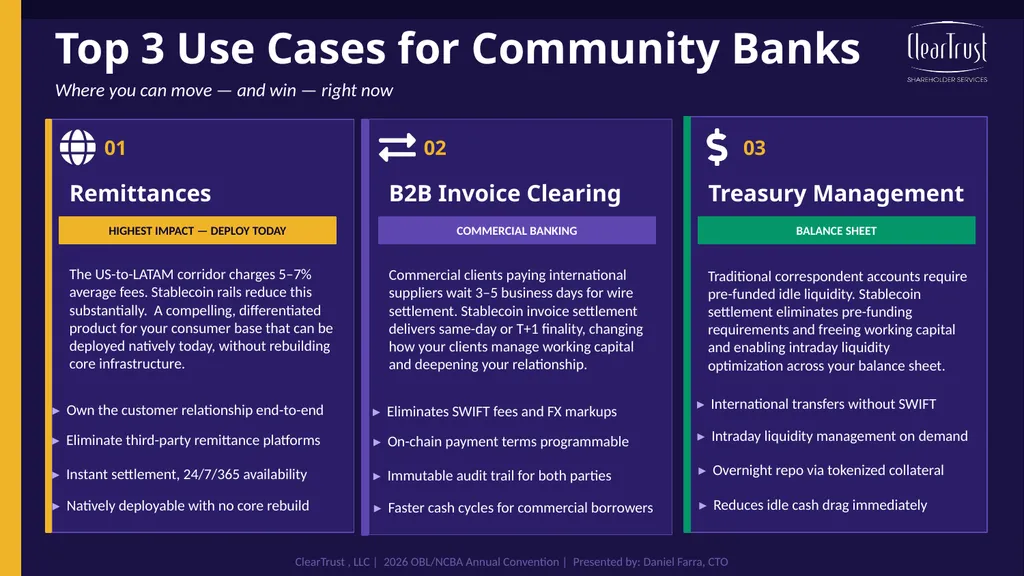
Top 3 Use Cases for Community Banks Where you can move — and win — right now 01 Remittances HIGHEST IMPACT — DEPLOY TODAY The US-to-LATAM corridor charges 5–7% average fees. Stablecoin rails reduce this substantially. A compelling, differentiated product for your consumer base that can be deployed natively today, without rebuilding core infrastructure. ▸ Own the customer relationship end-to-end ▸ Eliminate third-party remittance platforms ▸ Instant settlement, 24/7/365 availability ▸ Natively deployable with no core rebuild 02 B2B Invoice Clearing COMMERCIAL BANKING Commercial clients paying international suppliers wait 3–5 business days for wire settlement. Stablecoin invoice settlement delivers same-day or T+1 finality, changing how your clients manage working capital and deepening your relationship. ▸ Eliminates SWIFT fees and FX markups ▸ On-chain payment terms programmable ▸ Immutable audit trail for both parties ▸ Faster cash cycles for commercial borrowers 03 Treasury Management BALANCE SHEET Traditional correspondent accounts require pre-funded idle liquidity. Stablecoin settlement eliminates pre-funding requirements and freeing working capital and enabling intraday liquidity optimization across your balance sheet. ▸ International transfers without SWIFT ▸ Intraday liquidity management on demand ▸ Overnight repo via tokenized collateral ▸ Reduces idle cash drag immediately ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
12
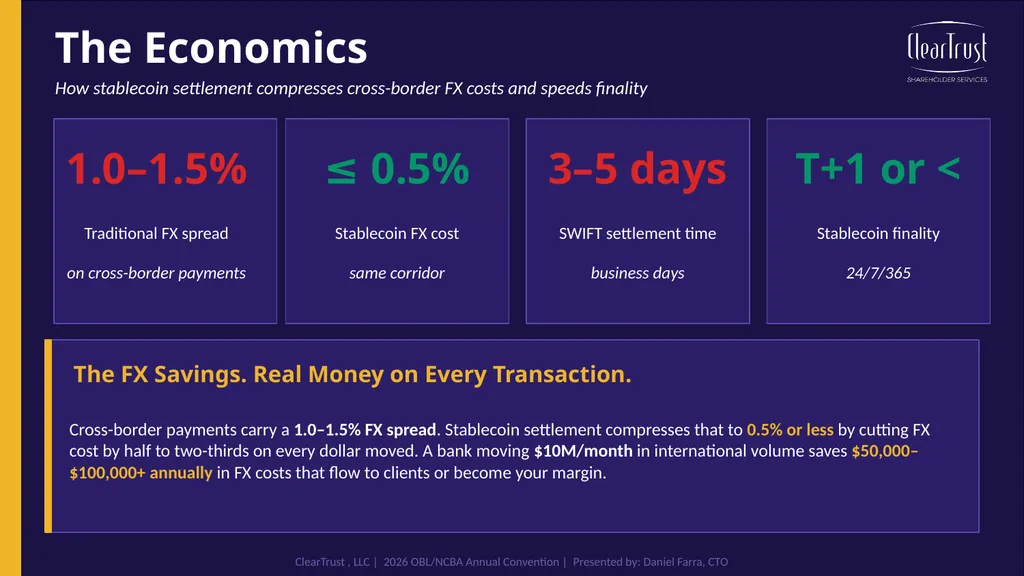
The Economics How stablecoin settlement compresses cross-border FX costs and speeds finality 1.0–1.5% Traditional FX spread on cross-border payments ≤ 0.5% Stablecoin FX cost same corridor 3–5 days SWIFT settlement time business days T+1 or < Stablecoin finality 24/7/365 The FX Savings. Real Money on Every Transaction. Cross-border payments carry a 1.0–1.5% FX spread. Stablecoin settlement compresses that to 0.5% or less by cutting FX cost by half to two-thirds on every dollar moved. A bank moving $10M/month in international volume saves $50,000–$100,000+ annually in FX costs that flow to clients or become your margin. ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
13
Stablecoin Payment Example This is an actual transaction tied to a Stablecoin Issuer Testnet on the blockchain ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
14
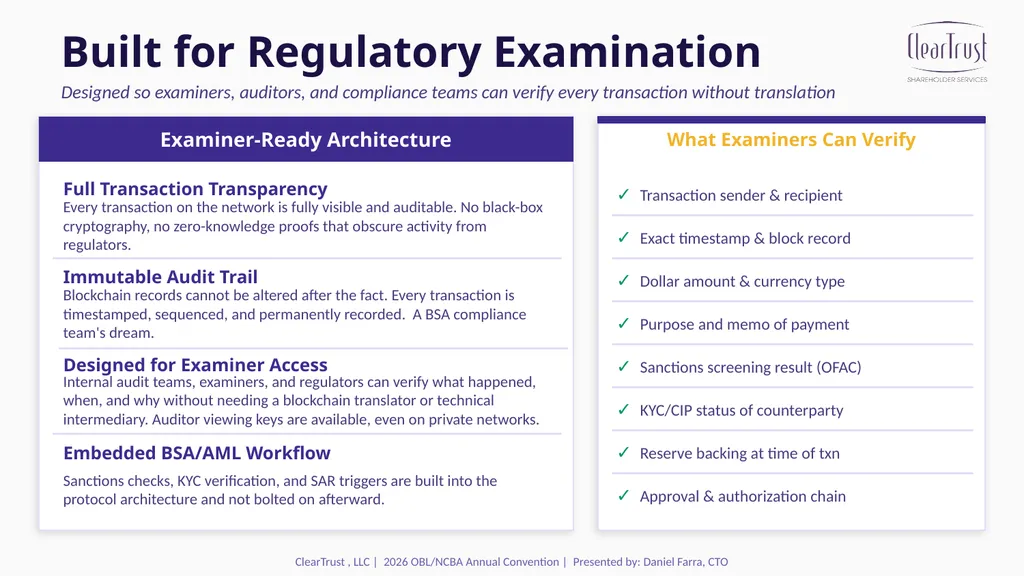
Built for Regulatory Examination Designed so examiners, auditors, and compliance teams can verify every transaction without translation Examiner-Ready Architecture Full Transaction Transparency Every transaction on the network is fully visible and auditable. No black-box cryptography, no zero-knowledge proofs that obscure activity from regulators. Immutable Audit Trail Blockchain records cannot be altered after the fact. Every transaction is timestamped, sequenced, and permanently recorded. A BSA compliance team's dream. Designed for Examiner Access Internal audit teams, examiners, and regulators can verify what happened, when, and why without needing a blockchain translator or technical intermediary. Auditor viewing keys are available, even on private networks. Embedded BSA/AML Workflow Sanctions checks, KYC verification, and SAR triggers are built into the protocol architecture and not bolted on afterward. What Examiners Can Verify ✓ Transaction sender & recipient ✓ Exact timestamp & block record ✓ Dollar amount & currency type ✓ Purpose and memo of payment ✓ Sanctions screening result (OFAC) ✓ KYC/CIP status of counterparty ✓ Reserve backing at time of txn ✓ Approval & authorization chain ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
15
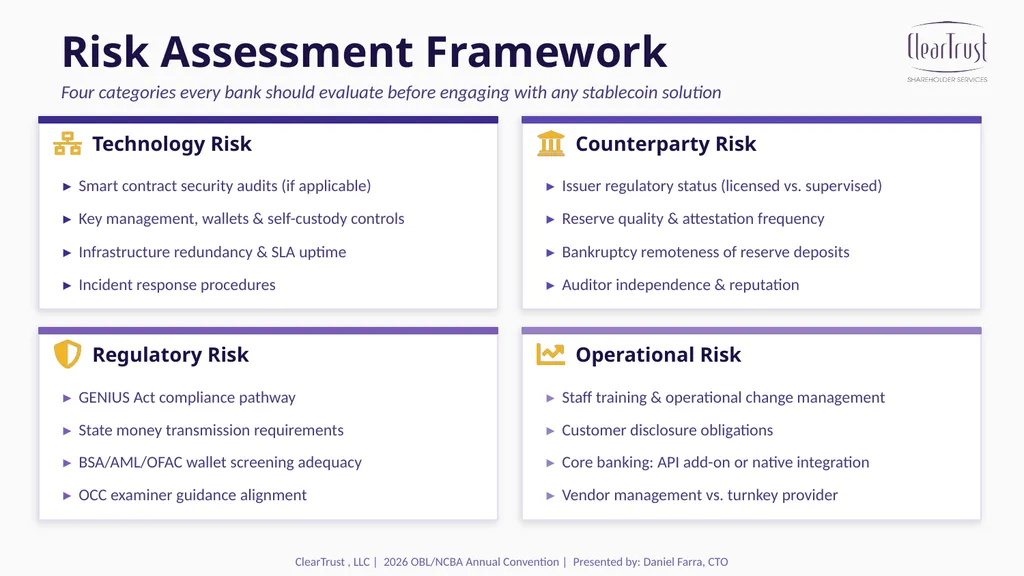
Risk Assessment Framework Four categories every bank should evaluate before engaging with any stablecoin solution Technology Risk ▸ Smart contract security audits (if applicable) ▸ Key management, wallets & self-custody controls ▸ Infrastructure redundancy & SLA uptime ▸ Incident response procedures Counterparty Risk ▸ Issuer regulatory status (licensed vs. supervised) ▸ Reserve quality & attestation frequency ▸ Bankruptcy remoteness of reserve deposits ▸ Auditor independence & reputation Regulatory Risk ▸ GENIUS Act compliance pathway ▸ State money transmission requirements ▸ BSA/AML/OFAC wallet screening adequacy ▸ OCC examiner guidance alignment Operational Risk ▸ Staff training & operational change management ▸ Customer disclosure obligations ▸ Core banking: API add-on or native integration ▸ Vendor management vs. turnkey provider ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
16
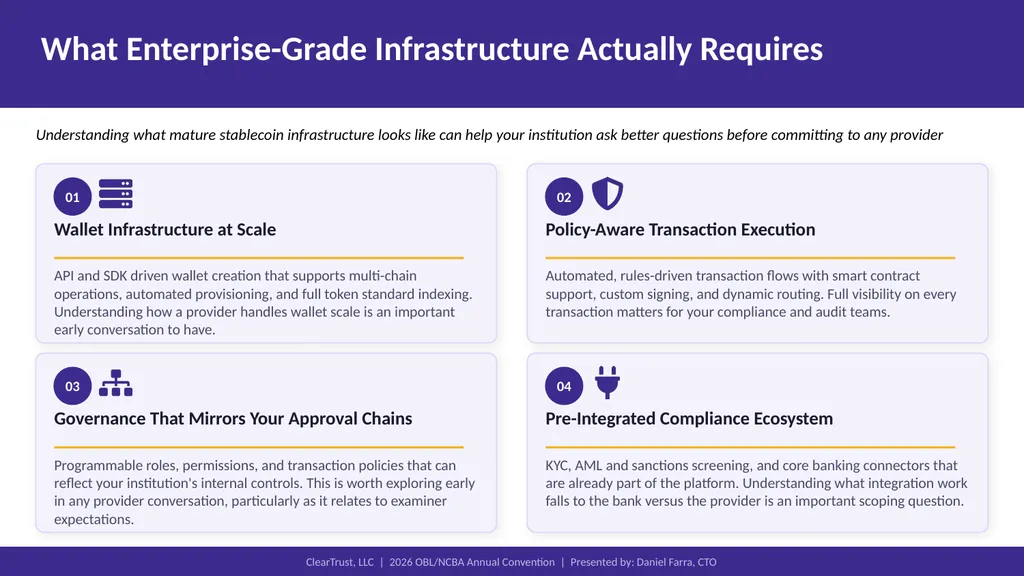
What Enterprise-Grade Infrastructure Actually Requires Understanding what mature stablecoin infrastructure looks like can help your institution ask better questions before committing to any provider 01 Wallet Infrastructure at Scale API and SDK driven wallet creation that supports multi-chain operations, automated provisioning, and full token standard indexing. Understanding how a provider handles wallet scale is an important early conversation to have. 02 Policy-Aware Transaction Execution Automated, rules-driven transaction flows with smart contract support, custom signing, and dynamic routing. Full visibility on every transaction matters for your compliance and audit teams. 03 Governance That Mirrors Your Approval Chains Programmable roles, permissions, and transaction policies that can reflect your institution's internal controls. This is worth exploring early in any provider conversation, particularly as it relates to examiner expectations. 04 Pre-Integrated Compliance Ecosystem KYC, AML and sanctions screening, and core banking connectors that are already part of the platform. Understanding what integration work falls to the bank versus the provider is an important scoping question. ClearTrust, LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
17
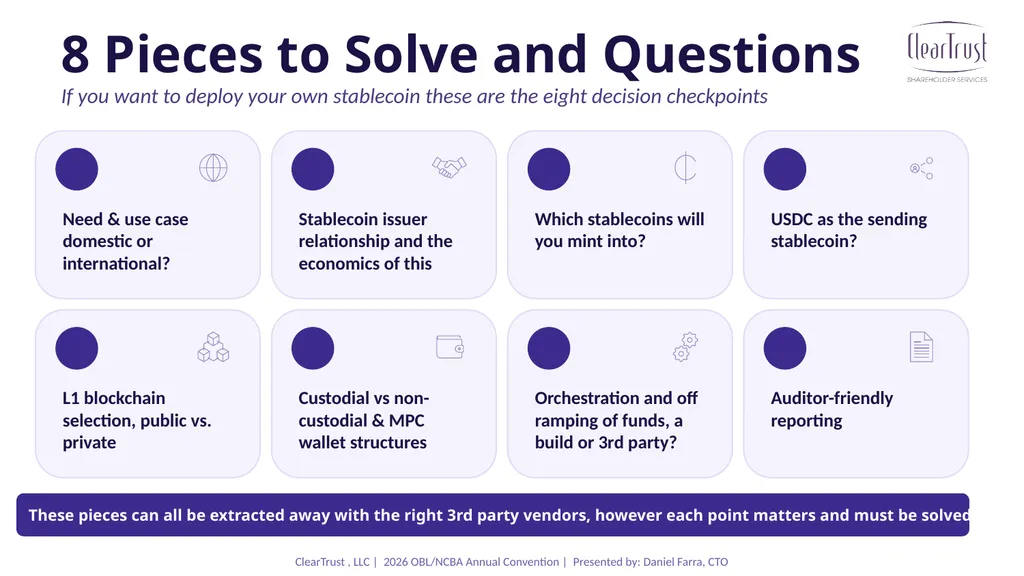
8 Pieces to Solve and Questions If you want to deploy your own stablecoin these are the eight decision checkpoints ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO 1 2 3 4 5 6 7 8 Need & use case domestic or international? Stablecoin issuer relationship and the economics of this Which stablecoins will you mint into? USDC as the sending stablecoin? L1 blockchain selection, public vs. private Custodial vs non-custodial & MPC wallet structures Orchestration and off ramping of funds, a build or 3rd party? Auditor-friendly reporting These pieces can all be extracted away with the right 3rd party vendors, however each point matters and must be solved<br>
18
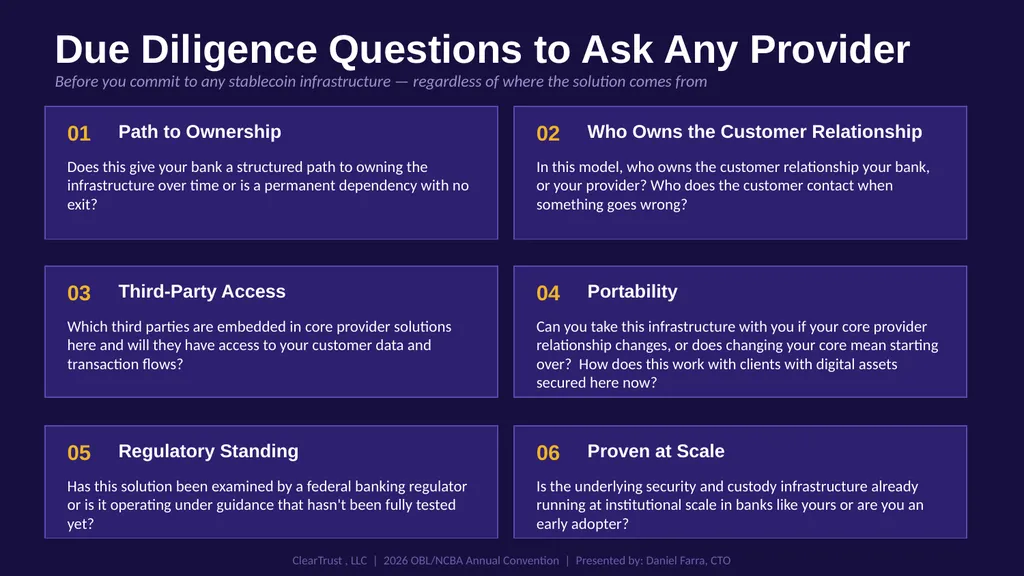
Due Diligence Questions to Ask Any Provider Before you commit to any stablecoin infrastructure — regardless of where the solution comes from 01 Path to Ownership Does this give your bank a structured path to owning the infrastructure over time or is a permanent dependency with no exit? 02 Who Owns the Customer Relationship In this model, who owns the customer relationship your bank, or your provider? Who does the customer contact when something goes wrong? 03 Third-Party Access Which third parties are embedded in core provider solutions here and will they have access to your customer data and transaction flows? 04 Portability Can you take this infrastructure with you if your core provider relationship changes, or does changing your core mean starting over? How does this work with clients with digital assets secured here now? 05 Regulatory Standing Has this solution been examined by a federal banking regulator or is it operating under guidance that hasn't been fully tested yet? 06 Proven at Scale Is the underlying security and custody infrastructure already running at institutional scale in banks like yours or are you an early adopter? ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
19
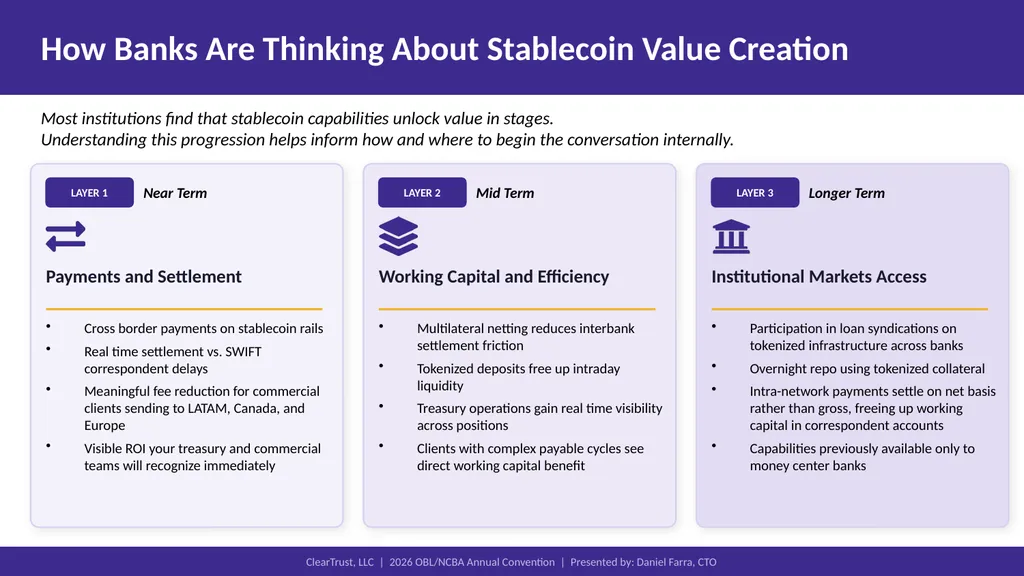
How Banks Are Thinking About Stablecoin Value Creation Most institutions find that stablecoin capabilities unlock value in stages.
Understanding this progression helps inform how and where to begin the conversation internally. LAYER 1 Near Term Payments and Settlement Cross border payments on stablecoin rails
Real time settlement vs. SWIFT correspondent delays
Meaningful fee reduction for commercial clients sending to LATAM, Canada, and Europe
Visible ROI your treasury and commercial teams will recognize immediately LAYER 2 Mid Term Working Capital and Efficiency Multilateral netting reduces interbank settlement friction
Tokenized deposits free up intraday liquidity
Treasury operations gain real time visibility across positions
Clients with complex payable cycles see direct working capital benefit LAYER 3 Longer Term Institutional Markets Access Participation in loan syndications on tokenized infrastructure across banks
Overnight repo using tokenized collateral
Intra-network payments settle on net basis rather than gross, freeing up working capital in correspondent accounts
Capabilities previously available only to money center banks ClearTrust, LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>
20
The conversation
starts here. The GENIUS Act has opened a real door for community banks. The institutions that move thoughtfully with the right architecture and the right partners will own the payment relationships of the next decade. MARK YOUR CALENDAR: Webinar July 23 at 2 PM ET Stablecoins & Digital Asset Strategy
for Community Banking Scan to register Q&A Daniel Farra Chief Technology Officer Let’s talk solutions!
Email tammy@cleartrusttransfer.com for meetings with Daniel & Kara ClearTrust , LLC | 2026 OBL/NCBA Annual Convention | Presented by: Daniel Farra, CTO<br>