
Agriculture and Food in International Trade G.


Description: Agriculture and Food in International Trade G. Cornelis van Kooten Professor and Canada Research Chair Department of Economics University of Victoria and Senior Research Fellow Agricultural Economics Institute (LEI) The Hague, The
Related Topics
Download Presentation
"Agriculture and Food in International Trade G." is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Agriculture and Food in International Trade G. Cornelis van Kooten
Professor and Canada Research Chair
Department of Economics
University of Victoria
and
Senior Research Fellow
Agricultural Economics Institute (LEI)
The Hague, The Netherlands<br>
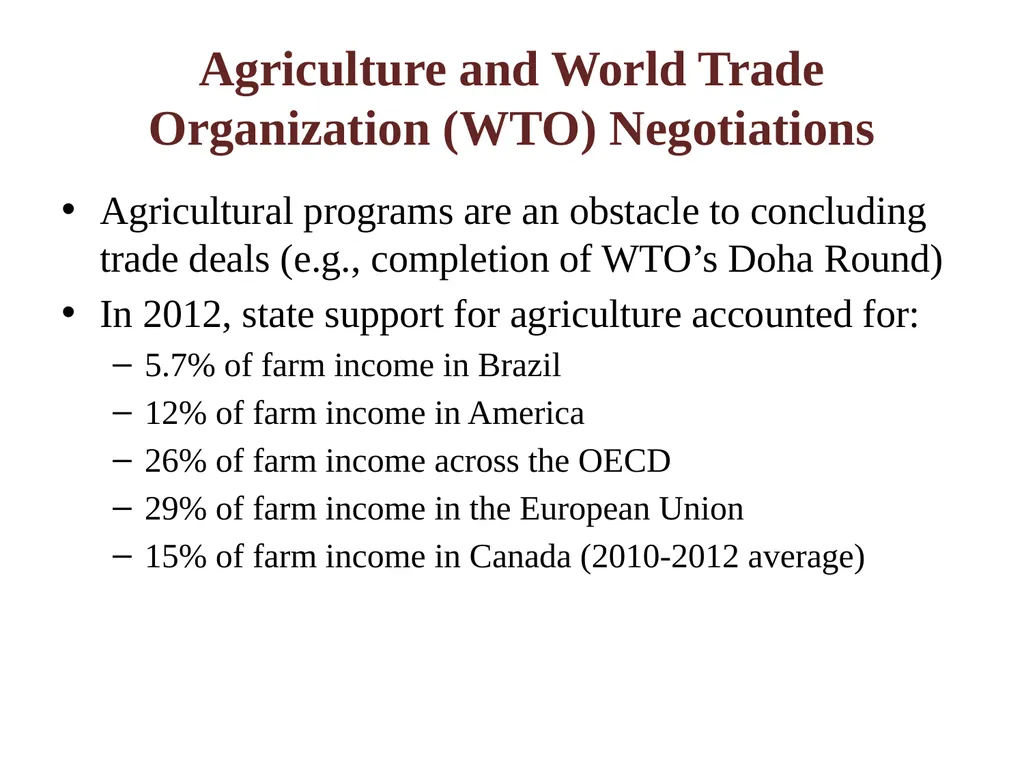
slide2. Agriculture and World Trade Organization (WTO) Negotiations Agricultural programs are an obstacle to concluding trade deals (e.g., completion of WTO’s Doha Round)
In 2012, state support for agriculture accounted for:
5.7% of farm income in Brazil
12% of farm income in America
26% of farm income across the OECD
29% of farm income in the European Union
15% of farm income in Canada (2010-2012 average)<br>
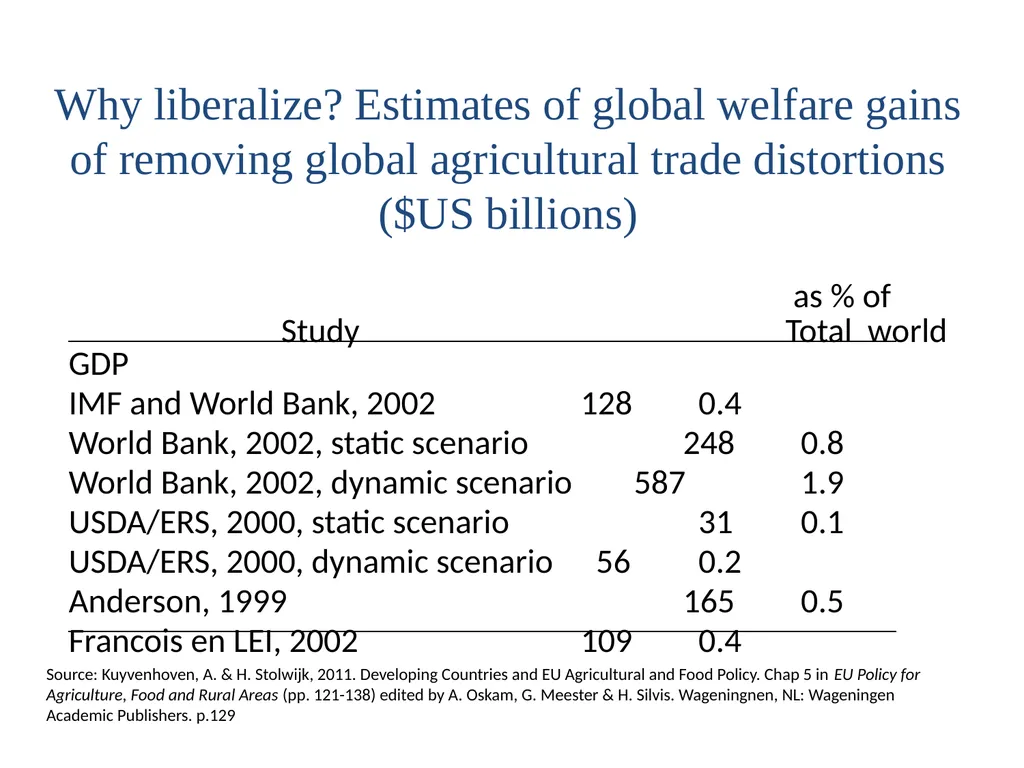
slide3. as % of Study Total world GDP
IMF and World Bank, 2002 128 0.4
World Bank, 2002, static scenario 248 0.8
World Bank, 2002, dynamic scenario 587 1.9
USDA/ERS, 2000, static scenario 31 0.1
USDA/ERS, 2000, dynamic scenario 56 0.2
Anderson, 1999 165 0.5
Francois en LEI, 2002 109 0.4 Why liberalize? Estimates of global welfare gains of removing global agricultural trade distortions ($US billions) Source: Kuyvenhoven, A. & H. Stolwijk, 2011. Developing Countries and EU Agricultural and Food Policy. Chap 5 in EU Policy for Agriculture, Food and Rural Areas (pp. 121-138) edited by A. Oskam, G. Meester & H. Silvis. Wageningnen, NL: Wageningen Academic Publishers. p.129<br>
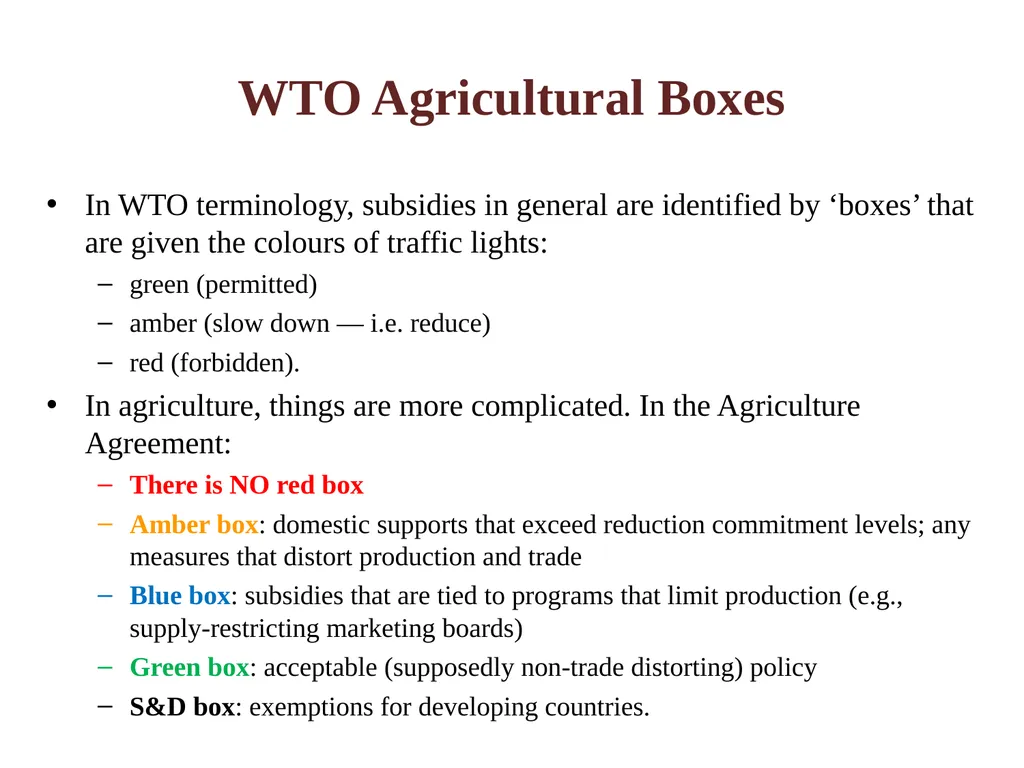
slide4. WTO Agricultural Boxes In WTO terminology, subsidies in general are identified by ‘boxes’ that are given the colours of traffic lights:
green (permitted)
amber (slow down — i.e. reduce)
red (forbidden).
In agriculture, things are more complicated. In the Agriculture Agreement:
There is NO red box
Amber box: domestic supports that exceed reduction commitment levels; any measures that distort production and trade
Blue box: subsidies that are tied to programs that limit production (e.g., supply-restricting marketing boards)
Green box: acceptable (supposedly non-trade distorting) policy
S&D box: exemptions for developing countries.<br>
slide5. Amber Box All domestic support measures considered to distort production and trade (with some exceptions) fall into the amber box, which is defined (Article 6 of the Agriculture Agreement) as all domestic supports except those in the blue and green boxes. These include measures to support prices or subsidies directly related to production quantities.
These supports are subject to limits: ‘de minimis’ (minimal) supports are allowed (5% of agricultural production for developed countries, 10% for developing countries); the 30 WTO members that had larger subsidies than the de minimis levels at the beginning of the post-Uruguay Round reform period are committed to reduce these subsidies.<br>
slide6. Blue Box Created in 1995
This is the ‘amber box with conditions’ – conditions designed to reduce distortions. Any support that would normally be in the amber box is placed in the blue box if the support also requires farmers to limit production (see Paragraph 5 of Article 6 of the Agriculture Agreement).
Set aside programs/cross compliance
Supply management (?)
At present there are no limits on spending on blue box subsidies. In the current negotiations, some countries want to keep the blue box as it is because they see it as a crucial means of moving away from distorting amber box subsidies without causing too much hardship.<br>
slide7. Green Box Defined in Annex 2 of the Agriculture Agreement
To qualify, green box subsidies must not distort trade, or at most cause minimal distortion (paragraph 1). They have to be government-funded (not by charging consumers higher prices) and must not involve price support.
Tend to be programs not targeted at particular products, and include direct income supports for farmers not related to (i.e., decoupled from) current production levels or prices.
Include environmental protection and regional development programs. “Green box” subsidies are therefore allowed without limits, but comply with other criteria in Annex 2.<br>
slide8. Green Box: Summary To be eligible to be categorized as “green box”, a support measure must meet two basic criteria:
The support must be government funded
The support must not have the effect of providing price support to producers as price support is viewed as distorting production and trade
Example: Safety Nets such as Single Farm Payment, Whole Farm Insurance<br>
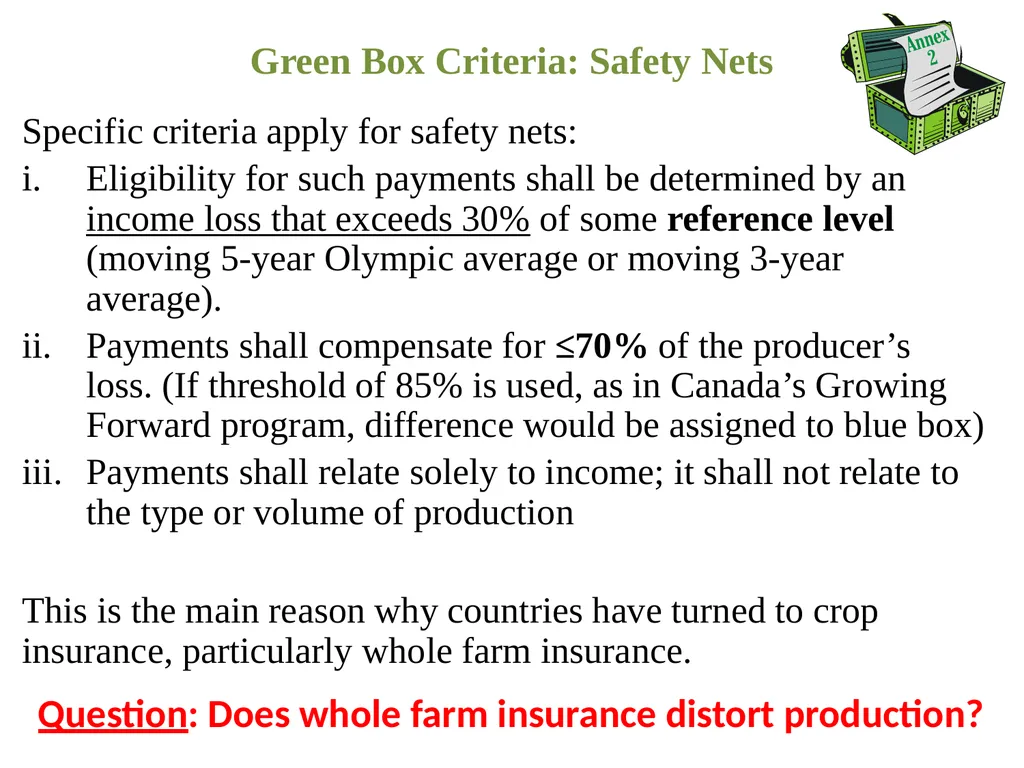
slide9. Green Box Criteria: Safety Nets Specific criteria apply for safety nets:
Eligibility for such payments shall be determined by an income loss that exceeds 30% of some reference level (moving 5-year Olympic average or moving 3-year average).
Payments shall compensate for ≤70% of the producer’s loss. (If threshold of 85% is used, as in Canada’s Growing Forward program, difference would be assigned to blue box)
Payments shall relate solely to income; it shall not relate to the type or volume of production
This is the main reason why countries have turned to crop insurance, particularly whole farm insurance. Question: Does whole farm insurance distort production?<br>
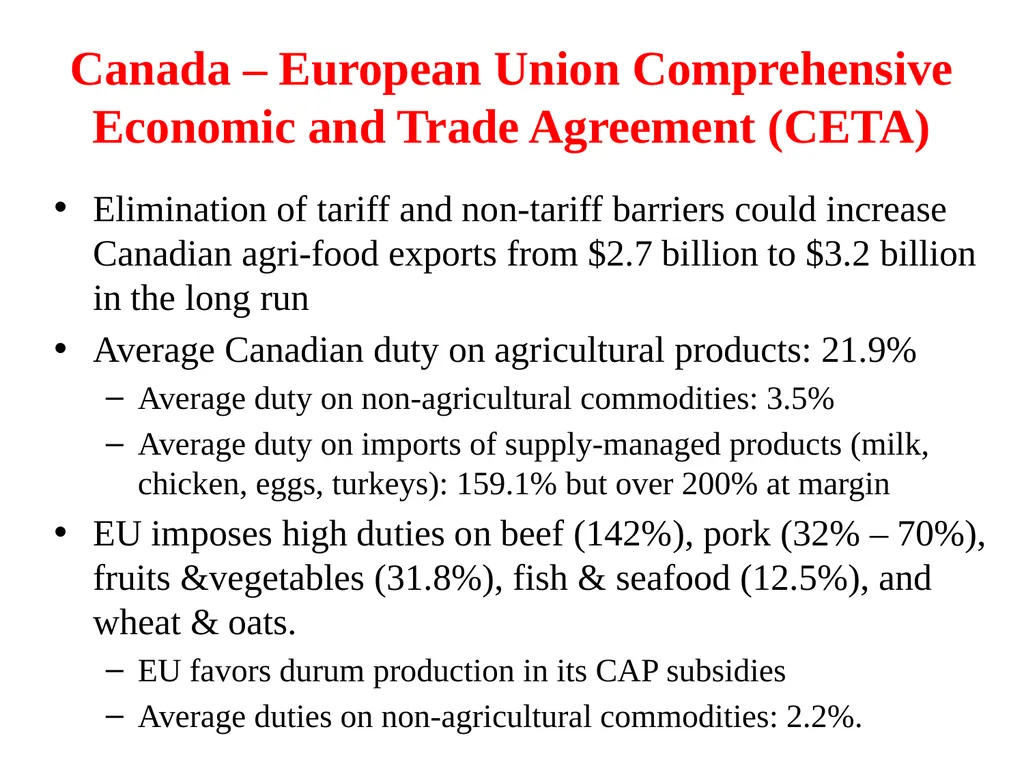
slide10. Canada – European Union Comprehensive Economic and Trade Agreement (CETA) Elimination of tariff and non-tariff barriers could increase Canadian agri-food exports from $2.7 billion to $3.2 billion in the long run
Average Canadian duty on agricultural products: 21.9%
Average duty on non-agricultural commodities: 3.5%
Average duty on imports of supply-managed products (milk, chicken, eggs, turkeys): 159.1% but over 200% at margin
EU imposes high duties on beef (142%), pork (32% – 70%), fruits &vegetables (31.8%), fish & seafood (12.5%), and wheat & oats.
EU favors durum production in its CAP subsidies
Average duties on non-agricultural commodities: 2.2%.<br>
slide11. Canada’s Agri-food Trade Balance with the European Union, 2001–2010 Source: http://www.parl.gc.ca/content/lop/researchpublications/cei-25-e.htm?Param=ce5<br>
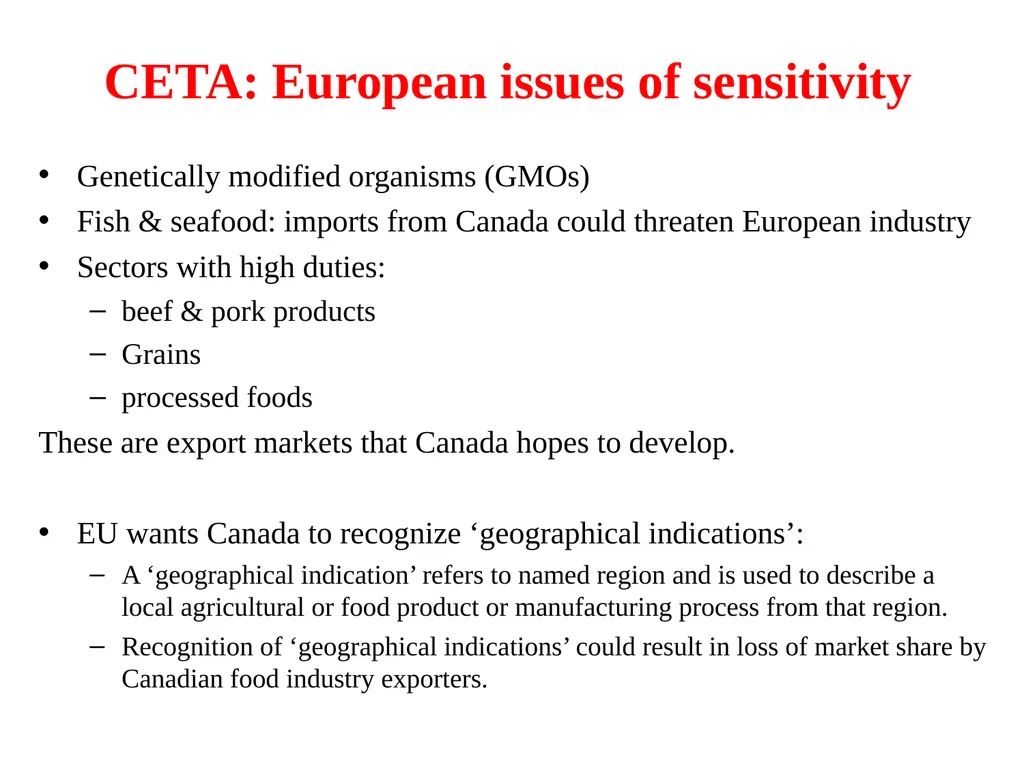
slide12. CETA: European issues of sensitivity Genetically modified organisms (GMOs)
Fish & seafood: imports from Canada could threaten European industry
Sectors with high duties:
beef & pork products
Grains
processed foods
These are export markets that Canada hopes to develop.
EU wants Canada to recognize ‘geographical indications’:
A ‘geographical indication’ refers to named region and is used to describe a local agricultural or food product or manufacturing process from that region.
Recognition of ‘geographical indications’ could result in loss of market share by Canadian food industry exporters.<br>
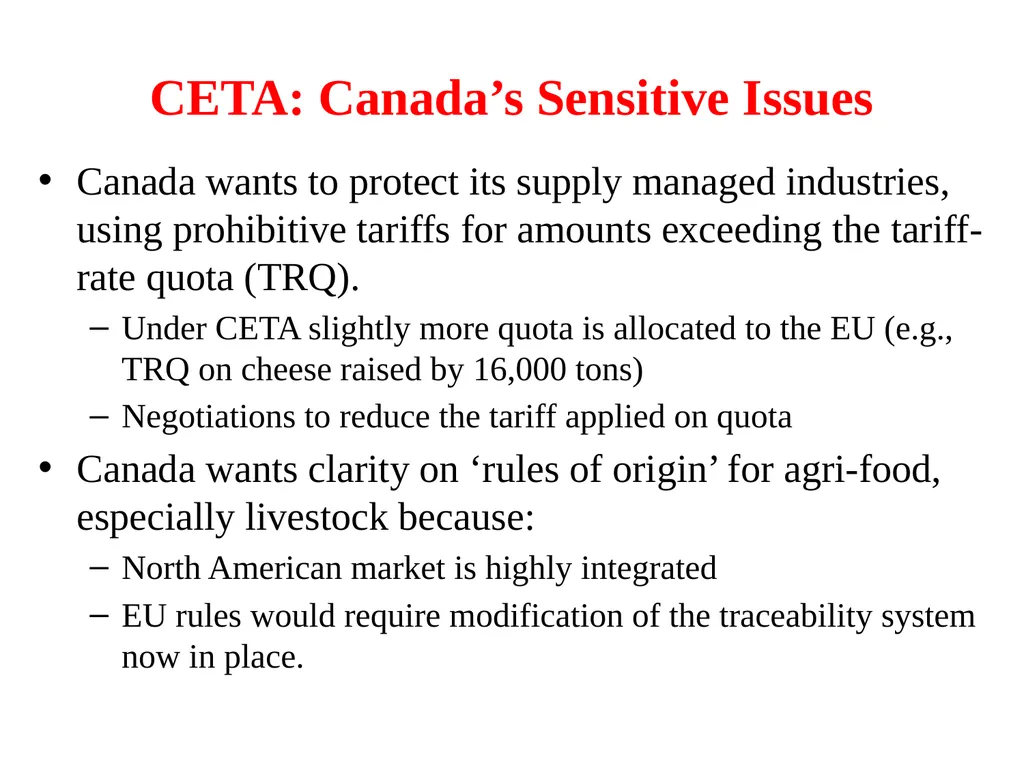
slide13. CETA: Canada’s Sensitive Issues Canada wants to protect its supply managed industries, using prohibitive tariffs for amounts exceeding the tariff-rate quota (TRQ).
Under CETA slightly more quota is allocated to the EU (e.g., TRQ on cheese raised by 16,000 tons)
Negotiations to reduce the tariff applied on quota
Canada wants clarity on ‘rules of origin’ for agri-food, especially livestock because:
North American market is highly integrated
EU rules would require modification of the traceability system now in place.<br>
slide14. CETA: Non-tariff Barriers European issues:
length of Canada’s process for approving new veterinary drugs
delays in processing applications for authorization of food additives
Canadian standards on the composition of cheeses
Canadian issues:
European regulations on beef, including ban on growth hormones
delays in approval process for genetically modified organisms (GMOs)
GMO traceability and labelling requirements<br>
slide15. Agricultural Programs and Subsidies Agricultural subsidies and farm programs are an obstacle to free trade, both with regards to CETA and WTO
Slow convergence of programs through the WTO process mentioned earlier<br>
slide16. European Policy After WWII, it was easy to establish an agricultural policy regime that provided farmers with large subsidies
Experience with shortages during and shortly after WWII
Large rural population with political clout
Program continued despite large costs to consumers and/or taxpayers and declining farm population
Rent seeking: fewer farmers with more to gain have greater incentive to lobby politicians
Consumers/taxpayers are less concerned with costs of farm programs as proportion of income spent on food declines
Consumers increasingly concerned with food safety (e.g., BSE crisis, pig flu, hoof & mouth disease, etc.): Rationale for continued government support of food and agriculture<br>
slide17. European Policy: Issues with CAP From beginning of CAP: High and increasing costs
Growing stocks of wine, butter, etc.
Growing international resentment of export subsidies
Need to reform CAP to facilitate trade negotiations
Desire to have budget to pursue objectives other than agriculture<br>
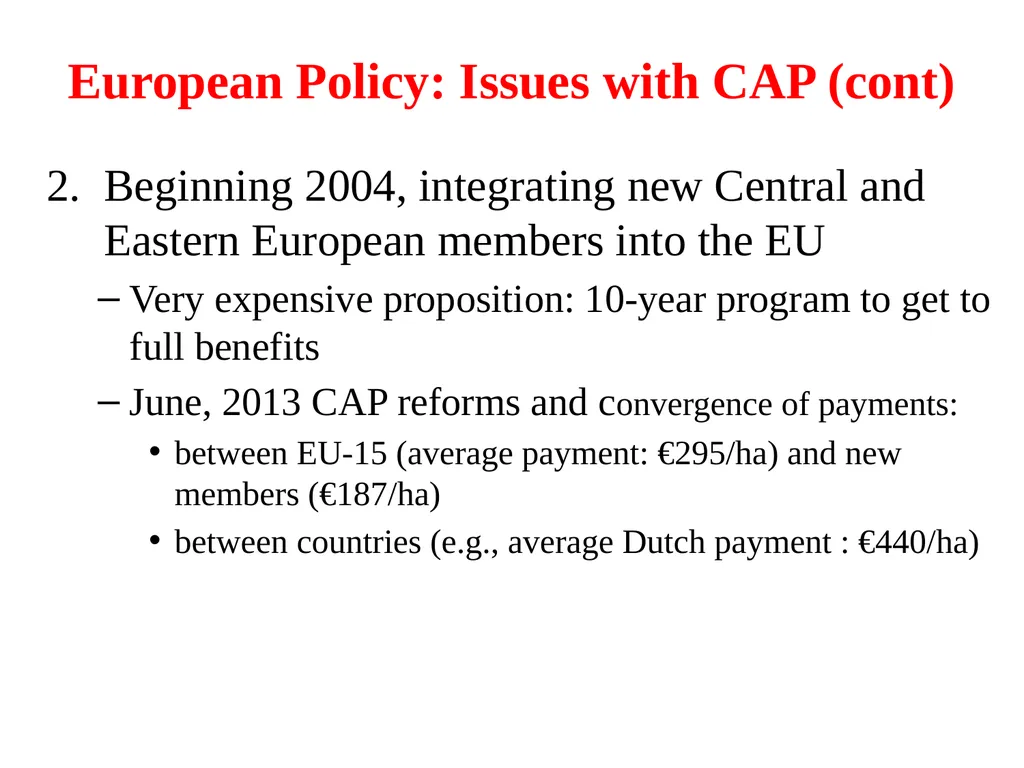
slide18. European Policy: Issues with CAP (cont) Beginning 2004, integrating new Central and Eastern European members into the EU
Very expensive proposition: 10-year program to get to full benefits
June, 2013 CAP reforms and convergence of payments:
between EU-15 (average payment: €295/ha) and new members (€187/ha)
between countries (e.g., average Dutch payment : €440/ha)<br>
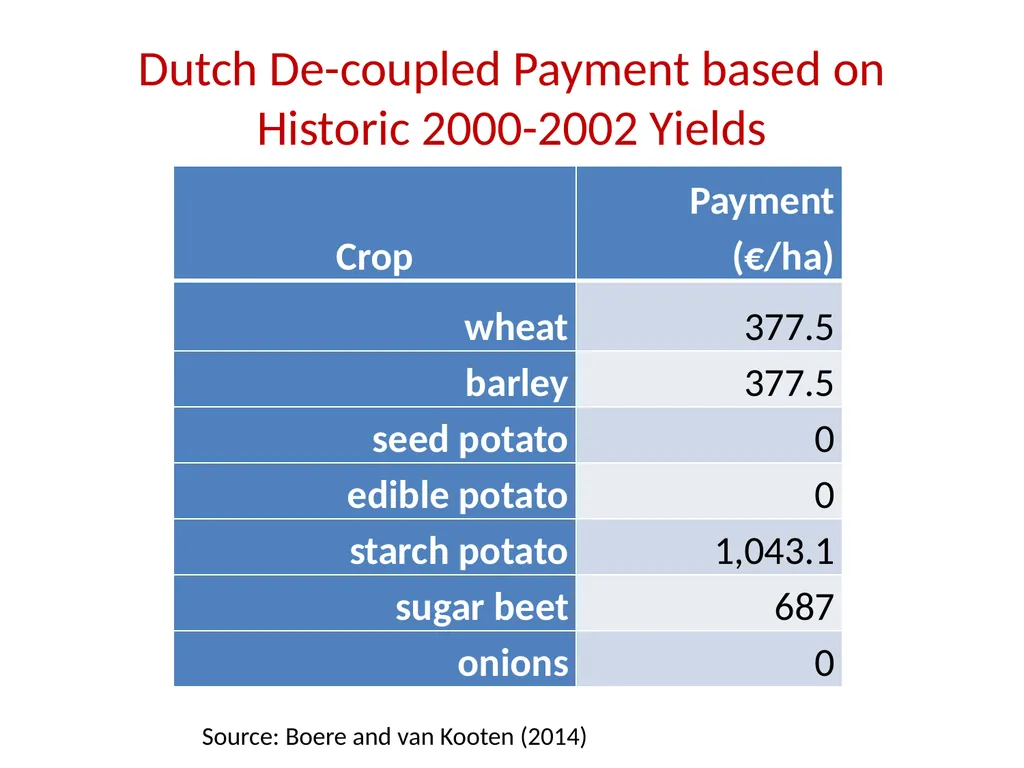
slide19. Dutch De-coupled Payment based on Historic 2000-2002 Yields Source: Boere and van Kooten (2014)<br>
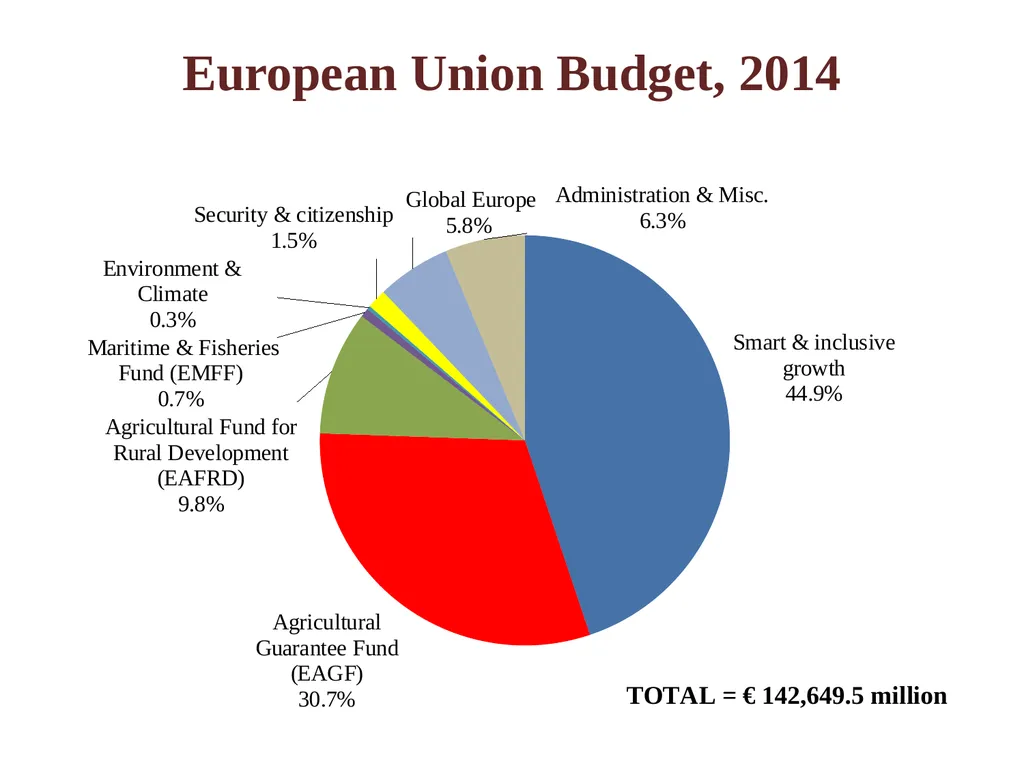
slide20. European Union Budget, 2014<br>
slide21. European Policy: Issues with CAP Environmental concerns
Shift of lands out of forestry into agriculture unless prohibited by other laws
Soil depletion
Chemical pollution from agriculture<br>
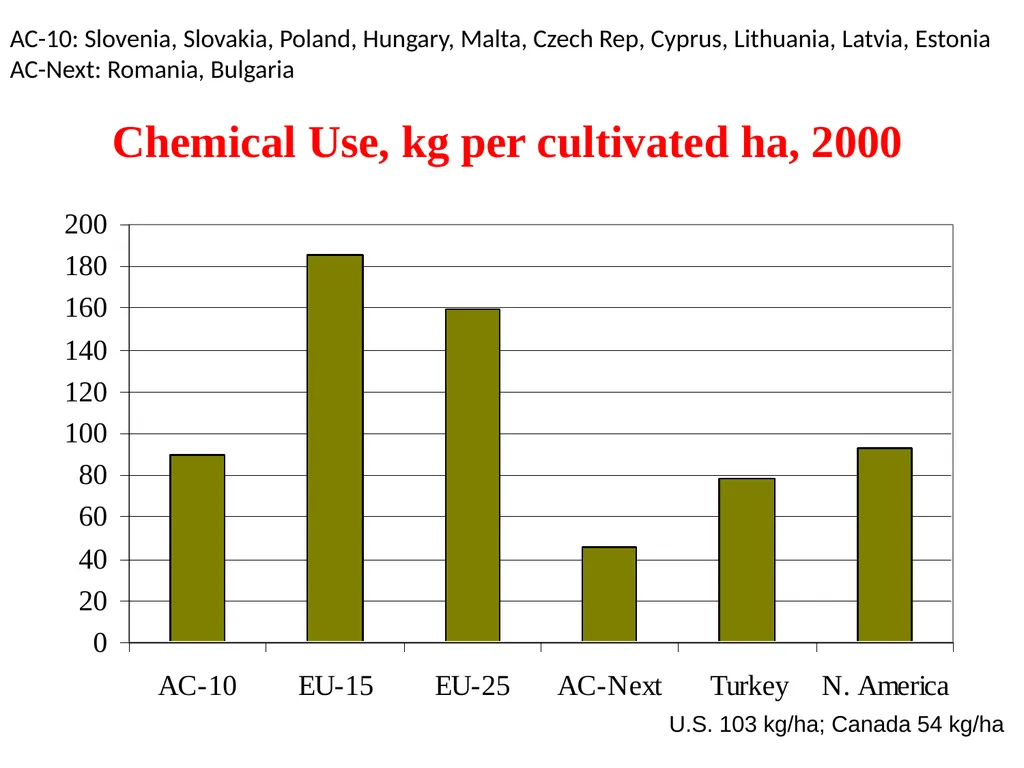
slide22. Chemical Use, kg per cultivated ha, 2000 U.S. 103 kg/ha; Canada 54 kg/ha AC-10: Slovenia, Slovakia, Poland, Hungary, Malta, Czech Rep, Cyprus, Lithuania, Latvia, Estonia
AC-Next: Romania, Bulgaria<br>
slide23. Is Canada Falling Behind? Who Needs CETA Most? A Tale of Two Countries Canada thinks of itself as a large exporter of agricultural commodities but we are outdone by the Netherlands.
Many years the Netherlands is the largest exporter of agricultural products by value after the United States
Let’s look at some statistics and see what Canada might aspire to:<br>
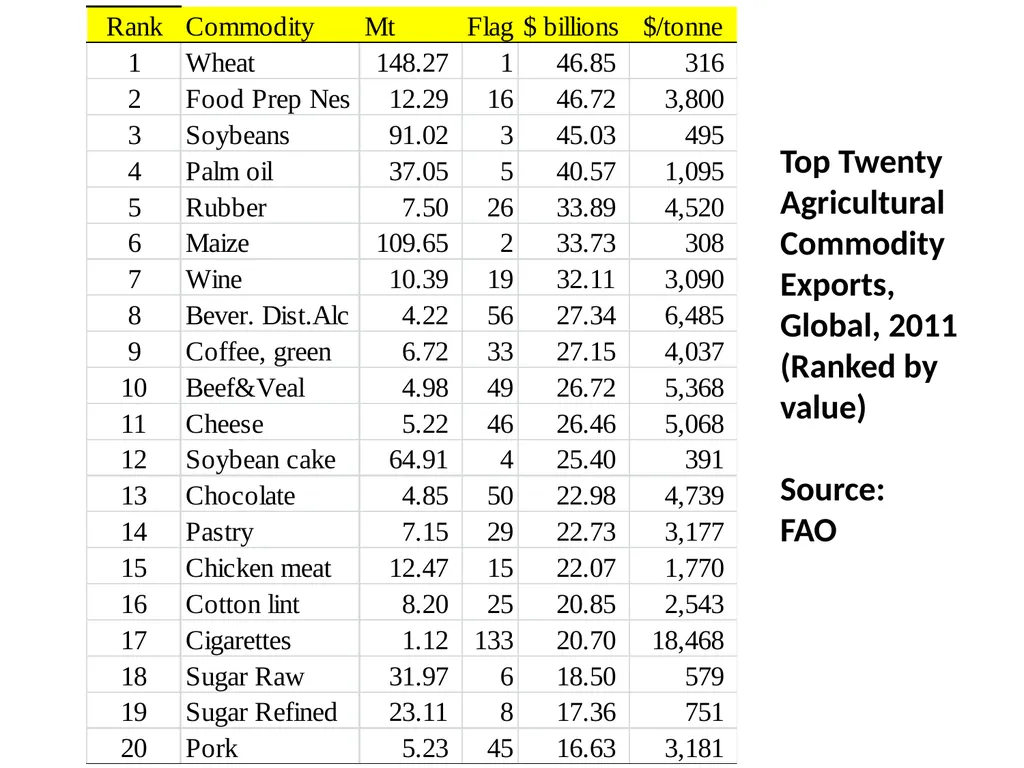
slide24. Top Twenty Agricultural Commodity Exports, Global, 2011
(Ranked by value)
Source:
FAO<br>
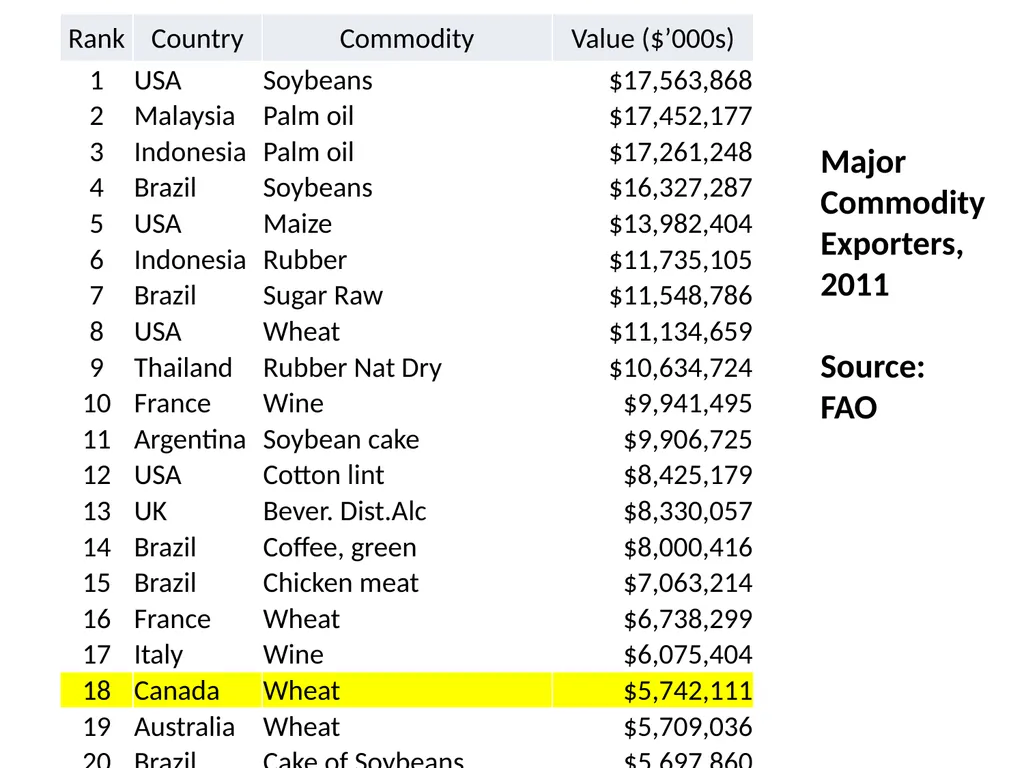
slide25. Major Commodity Exporters, 2011
Source:
FAO<br>
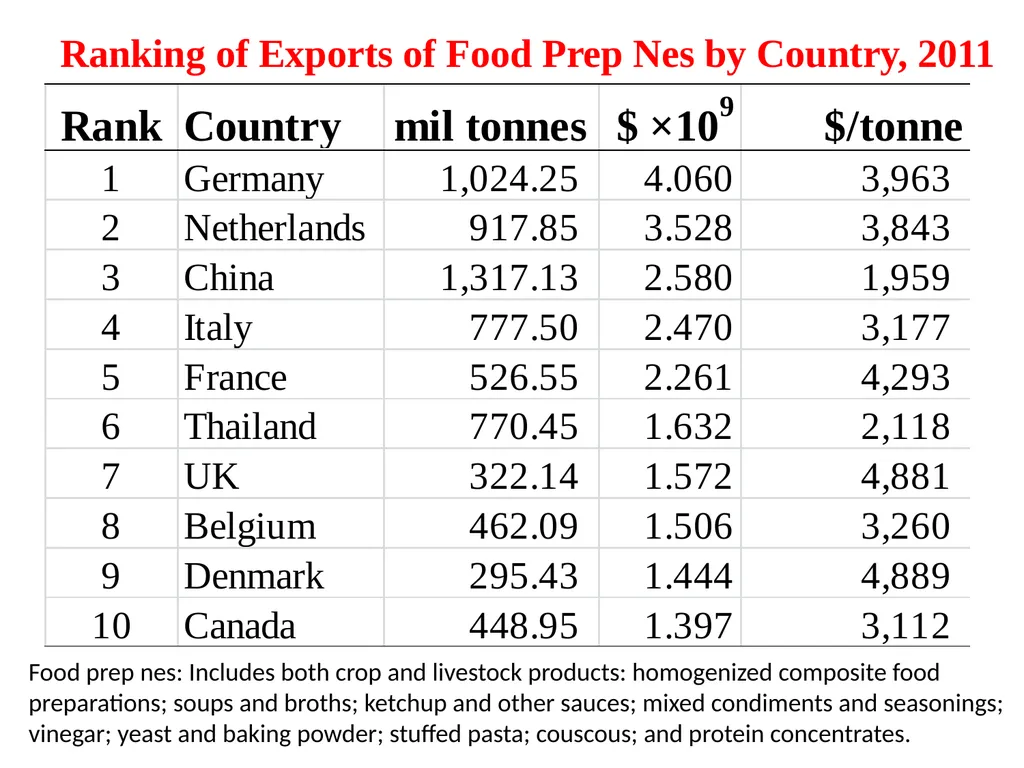
slide26. Ranking of Exports of Food Prep Nes by Country, 2011 Food prep nes: Includes both crop and livestock products: homogenized composite food preparations; soups and broths; ketchup and other sauces; mixed condiments and seasonings; vinegar; yeast and baking powder; stuffed pasta; couscous; and protein concentrates.<br>
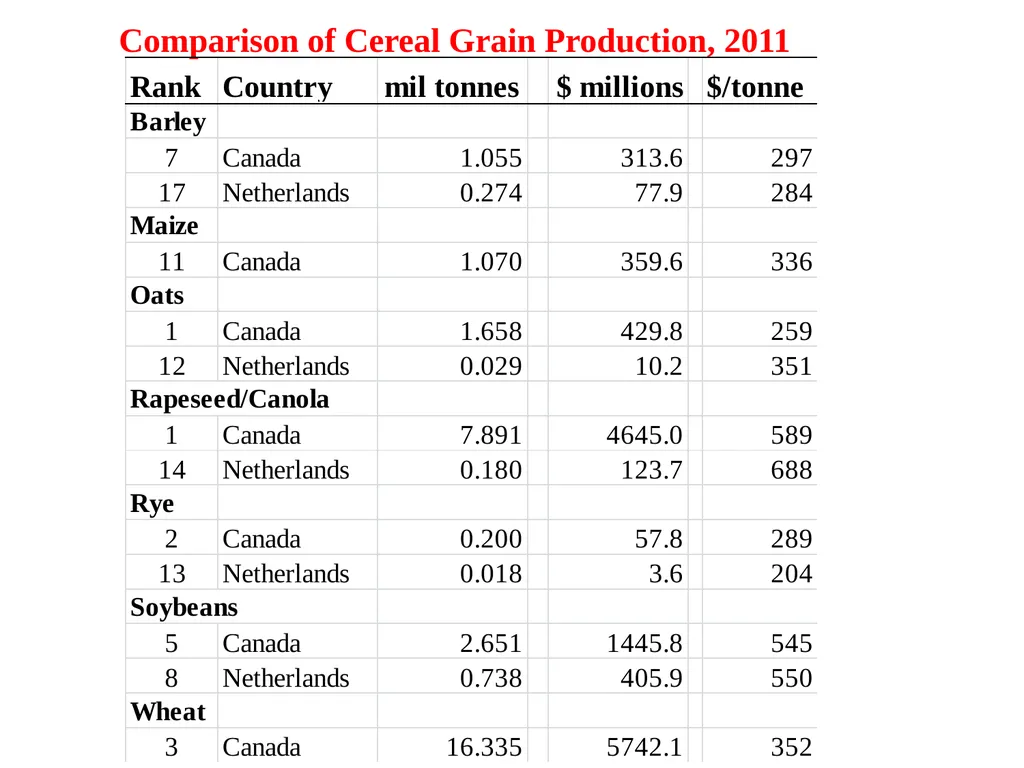
slide27. Comparison of Cereal Grain Production, 2011<br>
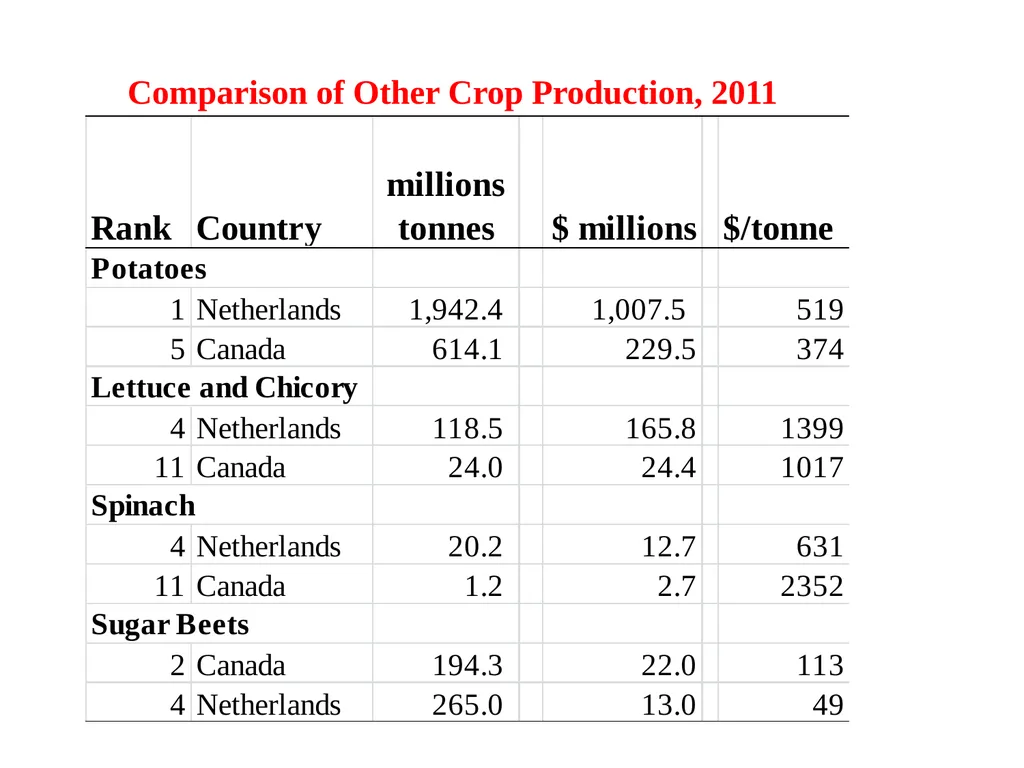
slide28. Comparison of Other Crop Production, 2011<br>
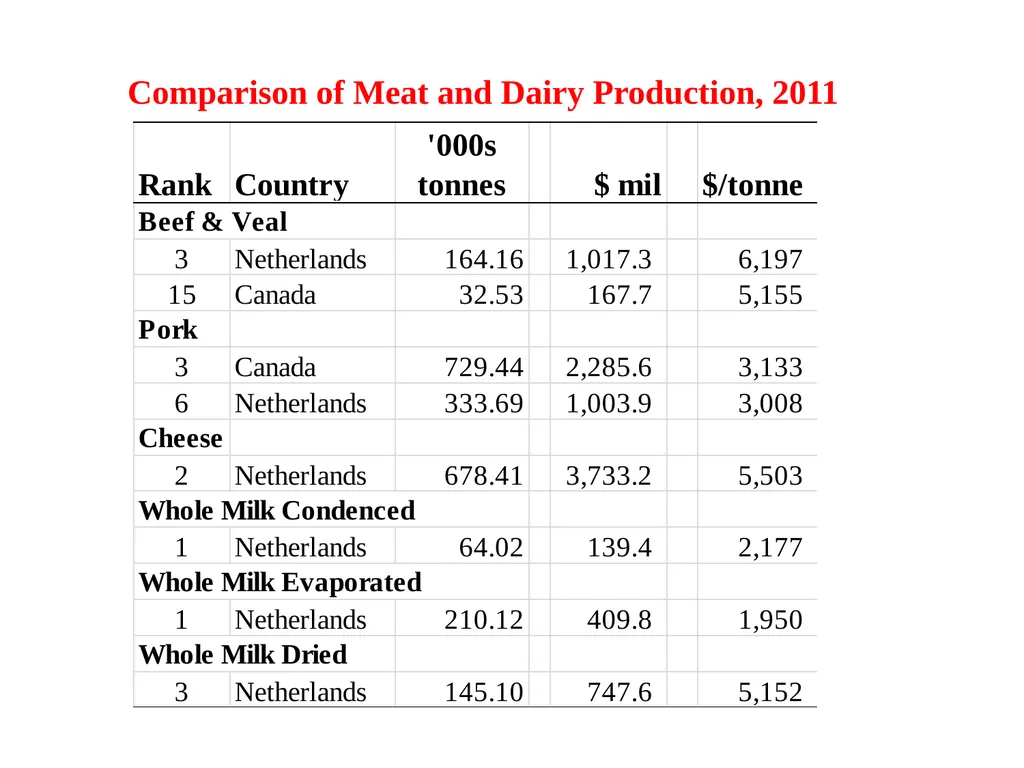
slide29. Comparison of Meat and Dairy Production, 2011<br>
Professor and Canada Research Chair
Department of Economics
University of Victoria
and
Senior Research Fellow
Agricultural Economics Institute (LEI)
The Hague, The Netherlands<br>
slide2. Agriculture and World Trade Organization (WTO) Negotiations Agricultural programs are an obstacle to concluding trade deals (e.g., completion of WTO’s Doha Round)
In 2012, state support for agriculture accounted for:
5.7% of farm income in Brazil
12% of farm income in America
26% of farm income across the OECD
29% of farm income in the European Union
15% of farm income in Canada (2010-2012 average)<br>
slide3. as % of Study Total world GDP
IMF and World Bank, 2002 128 0.4
World Bank, 2002, static scenario 248 0.8
World Bank, 2002, dynamic scenario 587 1.9
USDA/ERS, 2000, static scenario 31 0.1
USDA/ERS, 2000, dynamic scenario 56 0.2
Anderson, 1999 165 0.5
Francois en LEI, 2002 109 0.4 Why liberalize? Estimates of global welfare gains of removing global agricultural trade distortions ($US billions) Source: Kuyvenhoven, A. & H. Stolwijk, 2011. Developing Countries and EU Agricultural and Food Policy. Chap 5 in EU Policy for Agriculture, Food and Rural Areas (pp. 121-138) edited by A. Oskam, G. Meester & H. Silvis. Wageningnen, NL: Wageningen Academic Publishers. p.129<br>
slide4. WTO Agricultural Boxes In WTO terminology, subsidies in general are identified by ‘boxes’ that are given the colours of traffic lights:
green (permitted)
amber (slow down — i.e. reduce)
red (forbidden).
In agriculture, things are more complicated. In the Agriculture Agreement:
There is NO red box
Amber box: domestic supports that exceed reduction commitment levels; any measures that distort production and trade
Blue box: subsidies that are tied to programs that limit production (e.g., supply-restricting marketing boards)
Green box: acceptable (supposedly non-trade distorting) policy
S&D box: exemptions for developing countries.<br>
slide5. Amber Box All domestic support measures considered to distort production and trade (with some exceptions) fall into the amber box, which is defined (Article 6 of the Agriculture Agreement) as all domestic supports except those in the blue and green boxes. These include measures to support prices or subsidies directly related to production quantities.
These supports are subject to limits: ‘de minimis’ (minimal) supports are allowed (5% of agricultural production for developed countries, 10% for developing countries); the 30 WTO members that had larger subsidies than the de minimis levels at the beginning of the post-Uruguay Round reform period are committed to reduce these subsidies.<br>
slide6. Blue Box Created in 1995
This is the ‘amber box with conditions’ – conditions designed to reduce distortions. Any support that would normally be in the amber box is placed in the blue box if the support also requires farmers to limit production (see Paragraph 5 of Article 6 of the Agriculture Agreement).
Set aside programs/cross compliance
Supply management (?)
At present there are no limits on spending on blue box subsidies. In the current negotiations, some countries want to keep the blue box as it is because they see it as a crucial means of moving away from distorting amber box subsidies without causing too much hardship.<br>
slide7. Green Box Defined in Annex 2 of the Agriculture Agreement
To qualify, green box subsidies must not distort trade, or at most cause minimal distortion (paragraph 1). They have to be government-funded (not by charging consumers higher prices) and must not involve price support.
Tend to be programs not targeted at particular products, and include direct income supports for farmers not related to (i.e., decoupled from) current production levels or prices.
Include environmental protection and regional development programs. “Green box” subsidies are therefore allowed without limits, but comply with other criteria in Annex 2.<br>
slide8. Green Box: Summary To be eligible to be categorized as “green box”, a support measure must meet two basic criteria:
The support must be government funded
The support must not have the effect of providing price support to producers as price support is viewed as distorting production and trade
Example: Safety Nets such as Single Farm Payment, Whole Farm Insurance<br>
slide9. Green Box Criteria: Safety Nets Specific criteria apply for safety nets:
Eligibility for such payments shall be determined by an income loss that exceeds 30% of some reference level (moving 5-year Olympic average or moving 3-year average).
Payments shall compensate for ≤70% of the producer’s loss. (If threshold of 85% is used, as in Canada’s Growing Forward program, difference would be assigned to blue box)
Payments shall relate solely to income; it shall not relate to the type or volume of production
This is the main reason why countries have turned to crop insurance, particularly whole farm insurance. Question: Does whole farm insurance distort production?<br>
slide10. Canada – European Union Comprehensive Economic and Trade Agreement (CETA) Elimination of tariff and non-tariff barriers could increase Canadian agri-food exports from $2.7 billion to $3.2 billion in the long run
Average Canadian duty on agricultural products: 21.9%
Average duty on non-agricultural commodities: 3.5%
Average duty on imports of supply-managed products (milk, chicken, eggs, turkeys): 159.1% but over 200% at margin
EU imposes high duties on beef (142%), pork (32% – 70%), fruits &vegetables (31.8%), fish & seafood (12.5%), and wheat & oats.
EU favors durum production in its CAP subsidies
Average duties on non-agricultural commodities: 2.2%.<br>
slide11. Canada’s Agri-food Trade Balance with the European Union, 2001–2010 Source: http://www.parl.gc.ca/content/lop/researchpublications/cei-25-e.htm?Param=ce5<br>
slide12. CETA: European issues of sensitivity Genetically modified organisms (GMOs)
Fish & seafood: imports from Canada could threaten European industry
Sectors with high duties:
beef & pork products
Grains
processed foods
These are export markets that Canada hopes to develop.
EU wants Canada to recognize ‘geographical indications’:
A ‘geographical indication’ refers to named region and is used to describe a local agricultural or food product or manufacturing process from that region.
Recognition of ‘geographical indications’ could result in loss of market share by Canadian food industry exporters.<br>
slide13. CETA: Canada’s Sensitive Issues Canada wants to protect its supply managed industries, using prohibitive tariffs for amounts exceeding the tariff-rate quota (TRQ).
Under CETA slightly more quota is allocated to the EU (e.g., TRQ on cheese raised by 16,000 tons)
Negotiations to reduce the tariff applied on quota
Canada wants clarity on ‘rules of origin’ for agri-food, especially livestock because:
North American market is highly integrated
EU rules would require modification of the traceability system now in place.<br>
slide14. CETA: Non-tariff Barriers European issues:
length of Canada’s process for approving new veterinary drugs
delays in processing applications for authorization of food additives
Canadian standards on the composition of cheeses
Canadian issues:
European regulations on beef, including ban on growth hormones
delays in approval process for genetically modified organisms (GMOs)
GMO traceability and labelling requirements<br>
slide15. Agricultural Programs and Subsidies Agricultural subsidies and farm programs are an obstacle to free trade, both with regards to CETA and WTO
Slow convergence of programs through the WTO process mentioned earlier<br>
slide16. European Policy After WWII, it was easy to establish an agricultural policy regime that provided farmers with large subsidies
Experience with shortages during and shortly after WWII
Large rural population with political clout
Program continued despite large costs to consumers and/or taxpayers and declining farm population
Rent seeking: fewer farmers with more to gain have greater incentive to lobby politicians
Consumers/taxpayers are less concerned with costs of farm programs as proportion of income spent on food declines
Consumers increasingly concerned with food safety (e.g., BSE crisis, pig flu, hoof & mouth disease, etc.): Rationale for continued government support of food and agriculture<br>
slide17. European Policy: Issues with CAP From beginning of CAP: High and increasing costs
Growing stocks of wine, butter, etc.
Growing international resentment of export subsidies
Need to reform CAP to facilitate trade negotiations
Desire to have budget to pursue objectives other than agriculture<br>
slide18. European Policy: Issues with CAP (cont) Beginning 2004, integrating new Central and Eastern European members into the EU
Very expensive proposition: 10-year program to get to full benefits
June, 2013 CAP reforms and convergence of payments:
between EU-15 (average payment: €295/ha) and new members (€187/ha)
between countries (e.g., average Dutch payment : €440/ha)<br>
slide19. Dutch De-coupled Payment based on Historic 2000-2002 Yields Source: Boere and van Kooten (2014)<br>
slide20. European Union Budget, 2014<br>
slide21. European Policy: Issues with CAP Environmental concerns
Shift of lands out of forestry into agriculture unless prohibited by other laws
Soil depletion
Chemical pollution from agriculture<br>
slide22. Chemical Use, kg per cultivated ha, 2000 U.S. 103 kg/ha; Canada 54 kg/ha AC-10: Slovenia, Slovakia, Poland, Hungary, Malta, Czech Rep, Cyprus, Lithuania, Latvia, Estonia
AC-Next: Romania, Bulgaria<br>
slide23. Is Canada Falling Behind? Who Needs CETA Most? A Tale of Two Countries Canada thinks of itself as a large exporter of agricultural commodities but we are outdone by the Netherlands.
Many years the Netherlands is the largest exporter of agricultural products by value after the United States
Let’s look at some statistics and see what Canada might aspire to:<br>
slide24. Top Twenty Agricultural Commodity Exports, Global, 2011
(Ranked by value)
Source:
FAO<br>
slide25. Major Commodity Exporters, 2011
Source:
FAO<br>
slide26. Ranking of Exports of Food Prep Nes by Country, 2011 Food prep nes: Includes both crop and livestock products: homogenized composite food preparations; soups and broths; ketchup and other sauces; mixed condiments and seasonings; vinegar; yeast and baking powder; stuffed pasta; couscous; and protein concentrates.<br>
slide27. Comparison of Cereal Grain Production, 2011<br>
slide28. Comparison of Other Crop Production, 2011<br>
slide29. Comparison of Meat and Dairy Production, 2011<br>