
AKUNTANSI MANAJEMEN LANJUTAN PENENTUAN HARGA POKOK


Description: AKUNTANSI MANAJEMEN LANJUTAN PENENTUAN HARGA POKOK PRODUK DAN PEMBUATAN KEPUTUSAN DALAM LINGKUNGAN PEMANUFAKTURAN MAJU rowland.pasaribugmail.com PERTEMUAN II, 28 OKTOBER 2013 ACTIVITY BASED COSTING ACTIVITY BASED MANAGEMENT INVENTORY
Related Topics
Download Presentation
"AKUNTANSI MANAJEMEN LANJUTAN PENENTUAN HARGA POKOK" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. AKUNTANSI MANAJEMEN LANJUTAN PENENTUAN HARGA POKOK PRODUK DAN PEMBUATAN KEPUTUSAN DALAM LINGKUNGAN PEMANUFAKTURAN MAJU rowland.pasaribu@gmail.com<br>
slide2. PERTEMUAN II, 28 OKTOBER 2013 ACTIVITY BASED COSTING
ACTIVITY BASED MANAGEMENT
INVENTORY MANAGEMENT<br>
slide3. 4 - 3 Learning Objective 1 Describe the purposes of
cost management systems.<br>
slide4. 4 - 4 Cost Management System A cost-management system (CMS) is a
collection of tools and techniques that
identifies how management’s decisions
affect costs.<br>
slide5. 4 - 5 What is Cost Accounting? Cost accounting is that part of the
accounting system that measures costs
for the purposes of management decision
making and financial reporting.<br>
slide6. 4 - 6 Learning Objective 2 Explain the relationships
among cost, cost objective,
cost accumulation, and
cost allocation.<br>
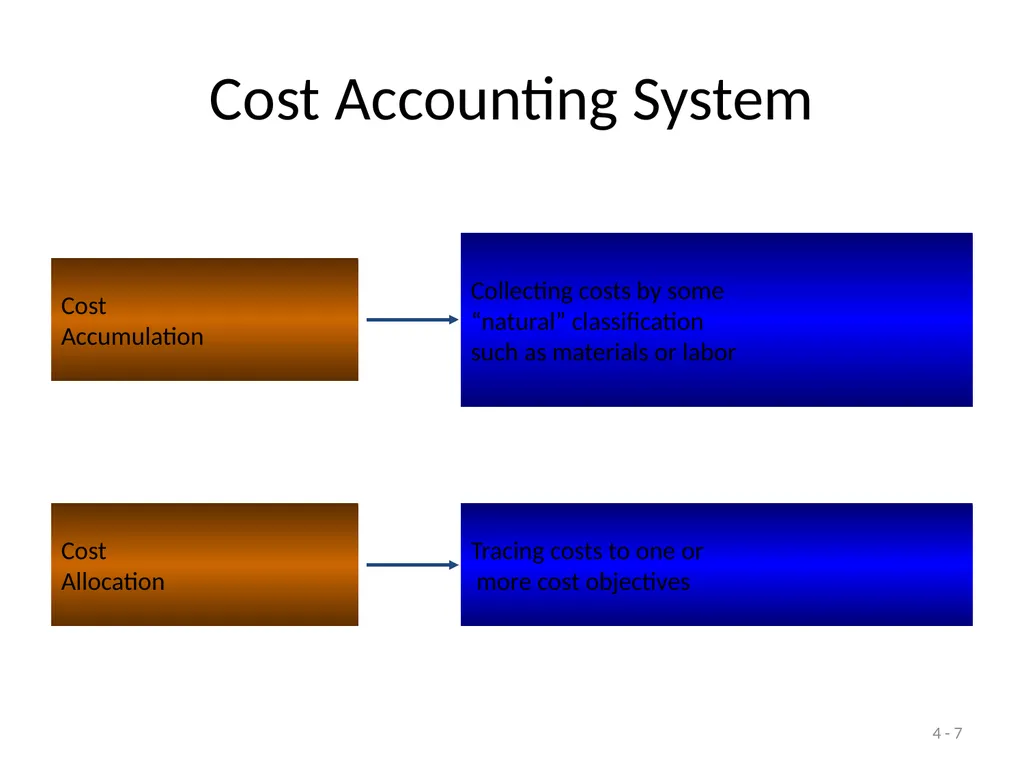
slide7. 4 - 7 Cost Accounting System Cost
Accumulation Collecting costs by some
“natural” classification
such as materials or labor Cost
Allocation Tracing costs to one or
more cost objectives<br>
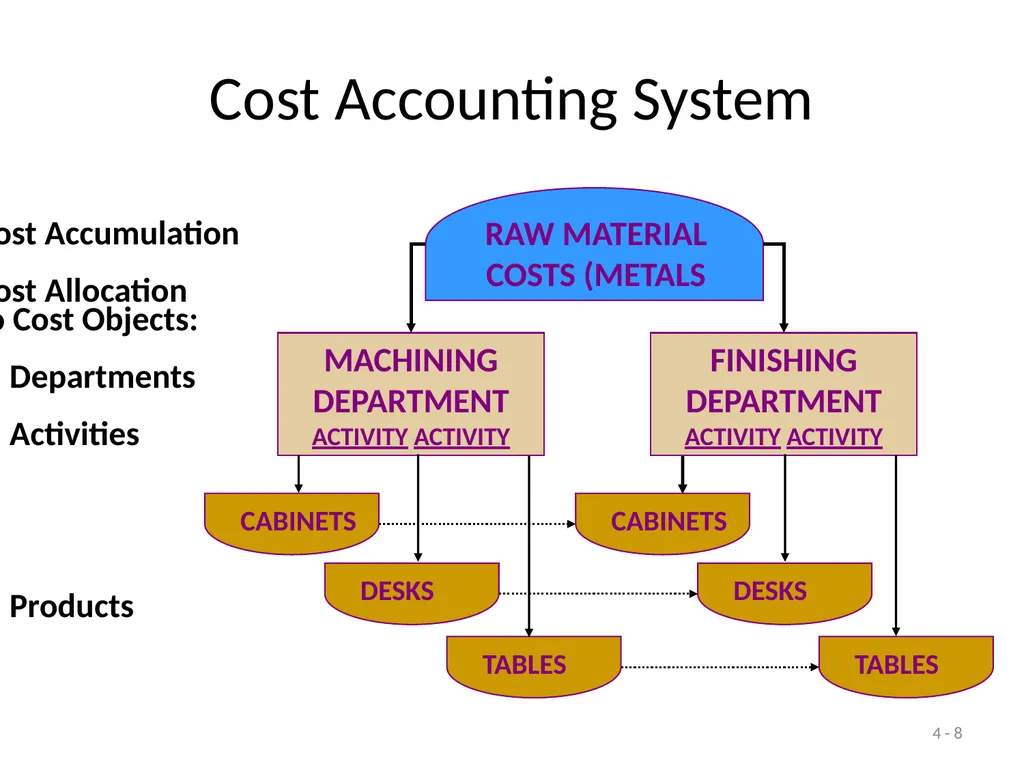
slide8. 4 - 8 Cost Accounting System MACHINING
DEPARTMENT
ACTIVITY ACTIVITY FINISHING
DEPARTMENT
ACTIVITY ACTIVITY RAW MATERIAL
COSTS (METALS CABINETS CABINETS DESKS DESKS TABLES TABLES Cost Accumulation
Cost Allocation
to Cost Objects:
1. Departments
2. Activities
3. Products<br>
slide9. 4 - 9 Cost A cost may be defined as a sacrifice or giving up of resources for a particular purpose.
Costs are frequently measured by the monetary units that must be paid for goods and services.<br>
slide10. 4 - 10 Cost Objective What is a cost object or cost objective? It is anything for which a separate measurement
of costs is desired.<br>
slide11. 4 - 11 Learning Objective 3 Distinguish among direct,
indirect, and unallocated costs.<br>
slide12. 4 - 12 Direct Costs Direct costs can be identified specifically
and exclusively with a given cost
objective in an economically
feasible way. What are direct costs?<br>
slide13. 4 - 13 Indirect Costs Indirect costs cannot be identified
specifically and exclusively with a
given cost objective in an economically
feasible way. What are indirect costs?<br>
slide14. 4 - 14 What Distinguishes Direct and Indirect Costs? Managers prefer to classify costs as direct rather than indirect whenever it is “economically feasible” or “cost effective.”
Other factors also influence whether a cost is considered direct or indirect.
The key is the particular cost objective.<br>
slide15. 4 - 15 Categories of Manufacturing Costs Any raw material, labor, or other input
used by any organization could,
in theory, be identified as a
direct or indirect cost
depending on the
cost objective.<br>
slide16. 4 - 16 Categories of Manufacturing Costs All costs which are eventually allocated to products are classified as either…
direct materials,
direct labor, or
indirect manufacturing.<br>
slide17. 4 - 17 Direct Material Costs... include the acquisition costs of all materials that are physically identified as a part of the manufactured goods and that may be traced to the manufactured goods in an economically feasible way.<br>
slide18. 4 - 18 Direct Labor Costs... include the wages of all labor that can be traced specifically and exclusively to the manufactured goods in an economically feasible way.<br>
slide19. 4 - 19 Indirect Manufacturing Costs... or factory overhead, include all costs associated with the manufacturing process that cannot be traced to the manufactured goods in an economically feasible way.<br>
slide20. 4 - 20 Product Costs... are costs identified with goods produced or purchased for resale.
Product costs are initially identified as part of the inventory on hand.
These costs, inventoriable costs, become expenses (in the form of cost of goods sold) only when the inventory is sold.<br>
slide21. 4 - 21 Period Costs... are costs that are deducted as expenses during the current period without going through an inventory stage.<br>
slide22. 4 - 22 Period or Product Costs In merchandising accounting, insurance, depreciation, and wages are period costs (expenses of the current period).
In manufacturing accounting, many of these items are related to production activities and thus, as indirect manufacturing, are product costs.<br>
slide23. 4 - 23 Period Costs – Merchandising and Manufacturing In both merchandising and manufacturing accounting, selling and general administrative costs are period costs.<br>
slide24. 4 - 24 Learning Objective 4 Explain how the financial
statements of merchandisers
and manufacturers differ
because of the types of goods
they sell.<br>
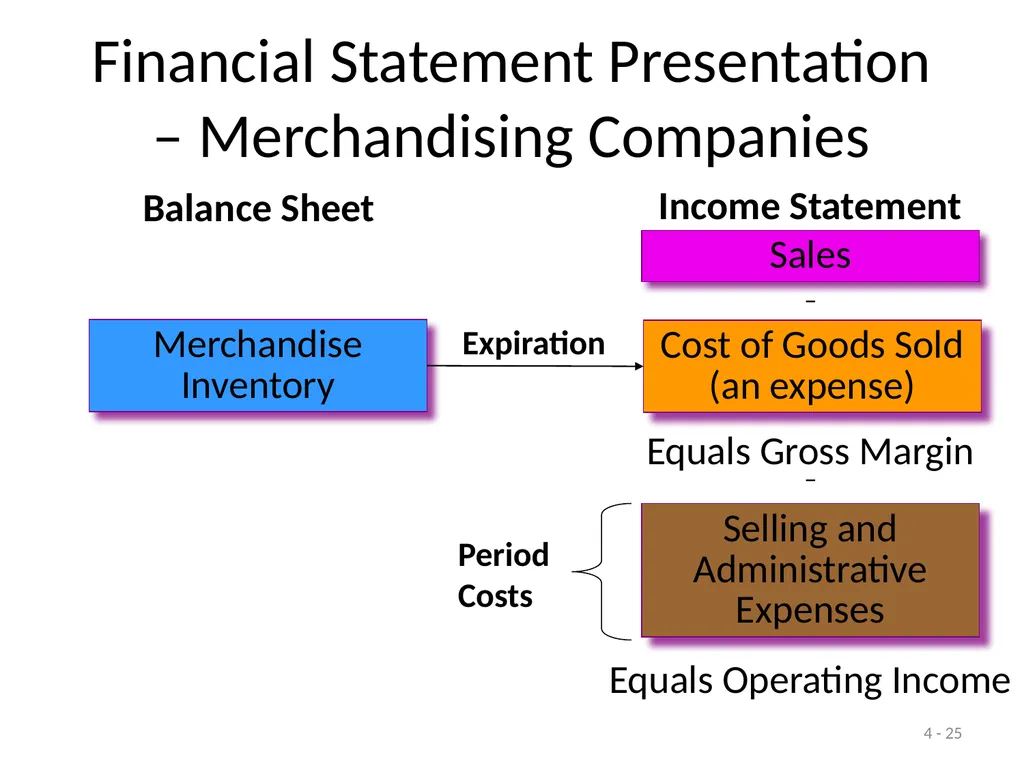
slide25. 4 - 25 Financial Statement Presentation – Merchandising Companies Merchandise
Inventory Sales Cost of Goods Sold
(an expense) Selling and
Administrative
Expenses Balance Sheet Income Statement – Equals Gross Margin Equals Operating Income – Expiration Period
Costs<br>
slide26. 4 - 26 Financial Statement Presentation – Manufacturing Companies Finished
Goods
Inventory Sales Cost of Goods Sold
(an expense) Selling and
Administrative
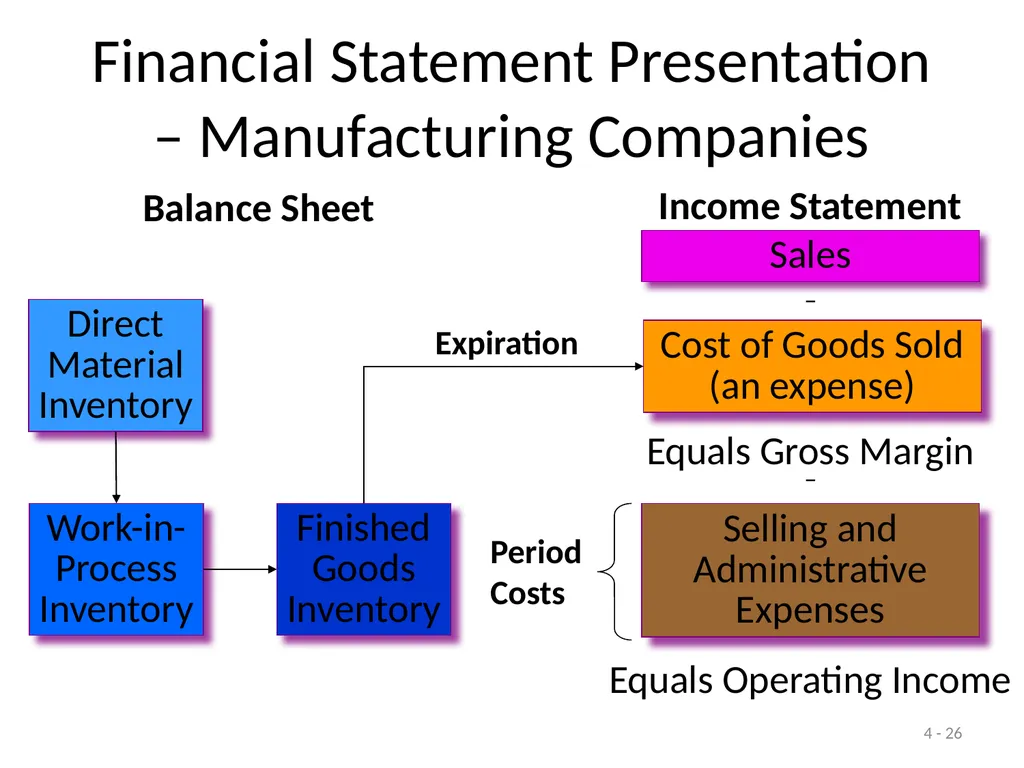
Expenses Balance Sheet Income Statement – Equals Gross Margin Equals Operating Income – Expiration Period
Costs Direct
Material
Inventory Work-in-
Process
Inventory<br>
slide27. 4 - 27 Costs and Income Statements On income statements, the detailed reporting of selling and administrative expenses is typically the same for manufacturing and merchandising organizations, but the cost of goods sold is different.<br>
slide28. 4 - 28 Cost of Goods Sold for a Manufacturer The manufacturer’s cost of goods produced and then sold is usually composed of the three major categories of cost:
Direct materials
Direct labor
Indirect manufacturing<br>
slide29. 4 - 29 Cost of Goods Sold for a Retailer or Wholesaler The merchandiser’s cost of goods sold is usually composed of the purchase cost of items, including freight-in, that are acquired and then resold.<br>
slide30. 4 - 30 Learning Objective 5 Understand the main
differences between traditional
and activity-based costing
systems and why ABC systems
provide value to managers.<br>
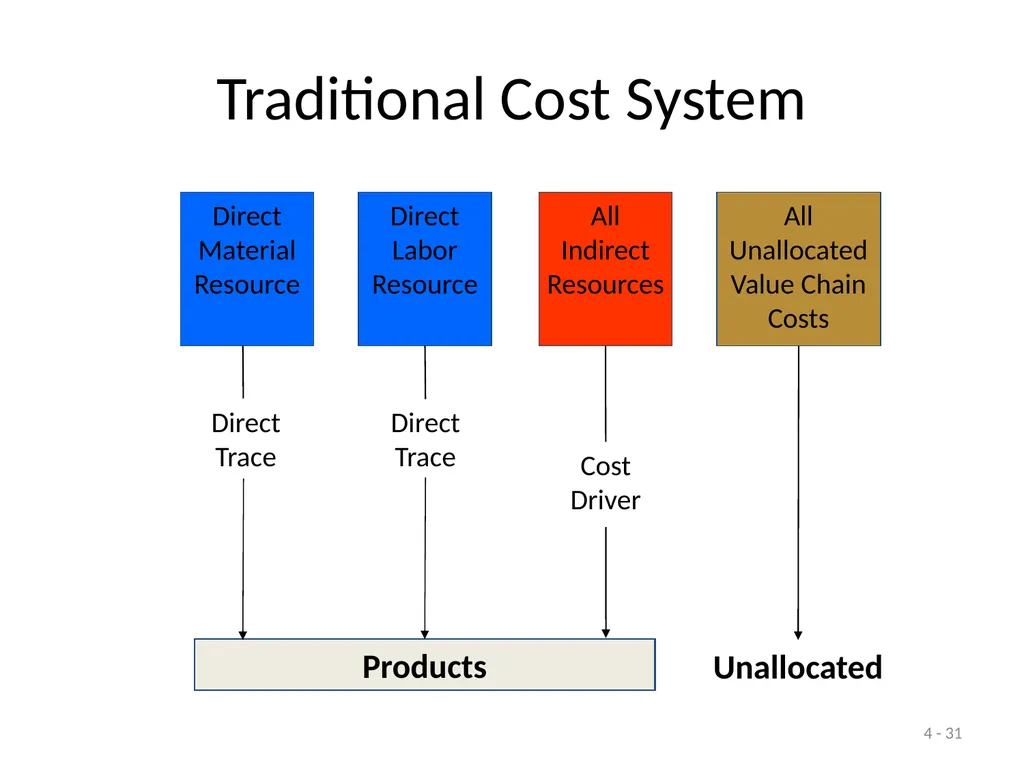
slide31. 4 - 31 Traditional Cost System All
Unallocated
Value Chain
Costs Direct
Material
Resource Direct
Labor
Resource All
Indirect
Resources Products Direct
Trace Direct
Trace Cost
Driver Unallocated<br>
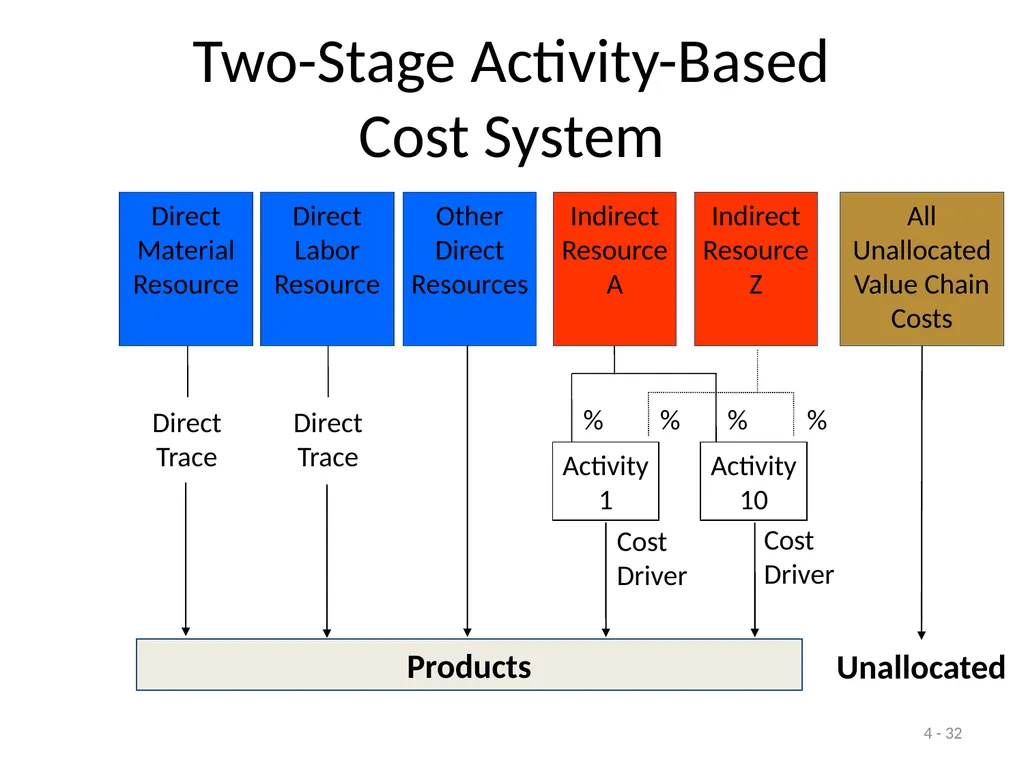
slide32. 4 - 32 Two-Stage Activity-Based Cost System All
Unallocated
Value Chain
Costs Direct
Material
Resource Direct
Labor
Resource Indirect
Resource
A Products Direct
Trace Direct
Trace Activity
1 Unallocated Other
Direct
Resources Indirect
Resource
Z Activity
10 % % % % Cost
Driver Cost
Driver<br>
slide33. 4 - 33 Activity-Based Costing Understanding the relationships among activities, resources, costs, and cost drivers is the key to understanding ABC and how ABC facilitates managers’ understanding of operations.<br>
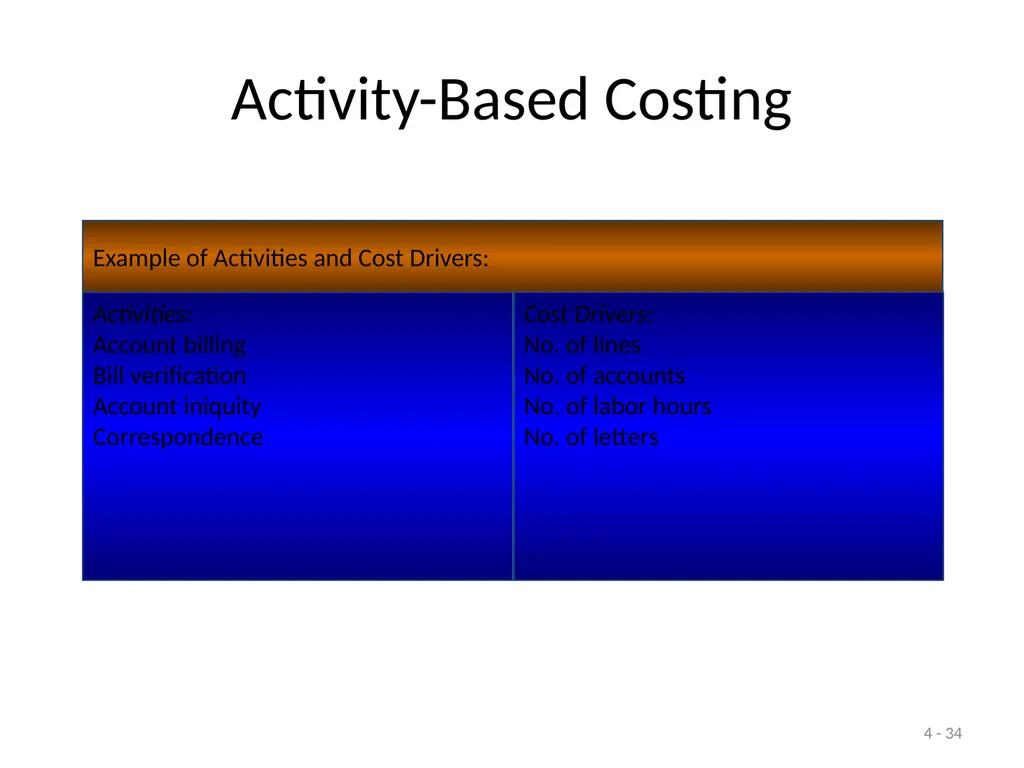
slide34. 4 - 34 Example of Activities and Cost Drivers: Activities:
Account billing
Bill verification
Account iniquity
Correspondence Cost Drivers:
No. of lines
No. of accounts
No. of labor hours
No. of letters Activity-Based Costing<br>
slide35. 4 - 35 Learning Objective 6 Identify the steps involved in the
design and implementation
of an activity-based
costing system.<br>
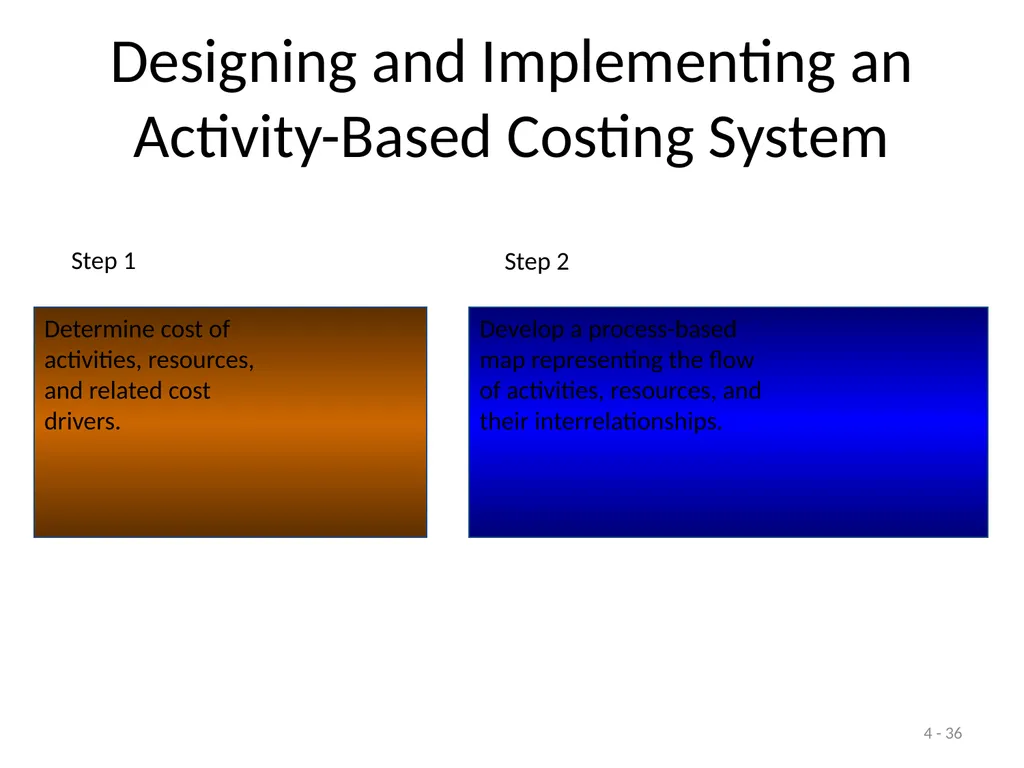
slide36. 4 - 36 Designing and Implementing an Activity-Based Costing System Determine cost of
activities, resources,
and related cost
drivers. Develop a process-based
map representing the flow
of activities, resources, and
their interrelationships. Step 1 Step 2<br>
slide37. 4 - 37 Designing and Implementing an Activity-Based Costing System Collect relevant data concerning costs
and the physical flow of the cost-driver
units among resources and activities. Step 3<br>
slide38. 4 - 38 Designing and Implementing an Activity-Based Costing System Calculate and interpret the new
activity-based information. Using an activity-based costing system to
improve the operations of an organization
is activity-based management (ABM). Step 4<br>
slide39. 4 - 39 Activity-Based Management Activity-based management aims to improve the value received by customers and to improve profits by identifying opportunities for improvements in strategy and operations.<br>
slide40. 4 - 40 Activity-Based Management A value-added cost is the cost of an activity that cannot be eliminated without affecting a product’s value to the customer.
In contrast, non-value-added costs are costs that can be eliminated without affecting a product’s value to the customer.<br>
slide41. 4 - 41 Learning Objective 7 Use activity-based cost
information to improve the
operations of an organization.<br>
slide42. 4 - 42 Using ABC Information Activity-based management… provides costs of value-added and
non-value-added activities. improves managers’ understanding of operations.<br>
slide43. 4 - 43 Learning Objective 8 Understand cost accounting’s
role in a company’s
improvement efforts across
the value chain.<br>
slide44. 4 - 44 Cost Accounting and the Value Chain A good cost accounting system is critical to
all value-chain functions from research and
development through customer service.<br>
slide45. Activity Based Management<br>
slide46. Activity-Based Management (ABM) Activity-based management (ABM) is a systemwide, integrated approach that focuses management’s attention on activities with the objective of improving customer value and the profit achieved by providing this value.
Activity-based management encompasses both product costing and process value analysis.<br>
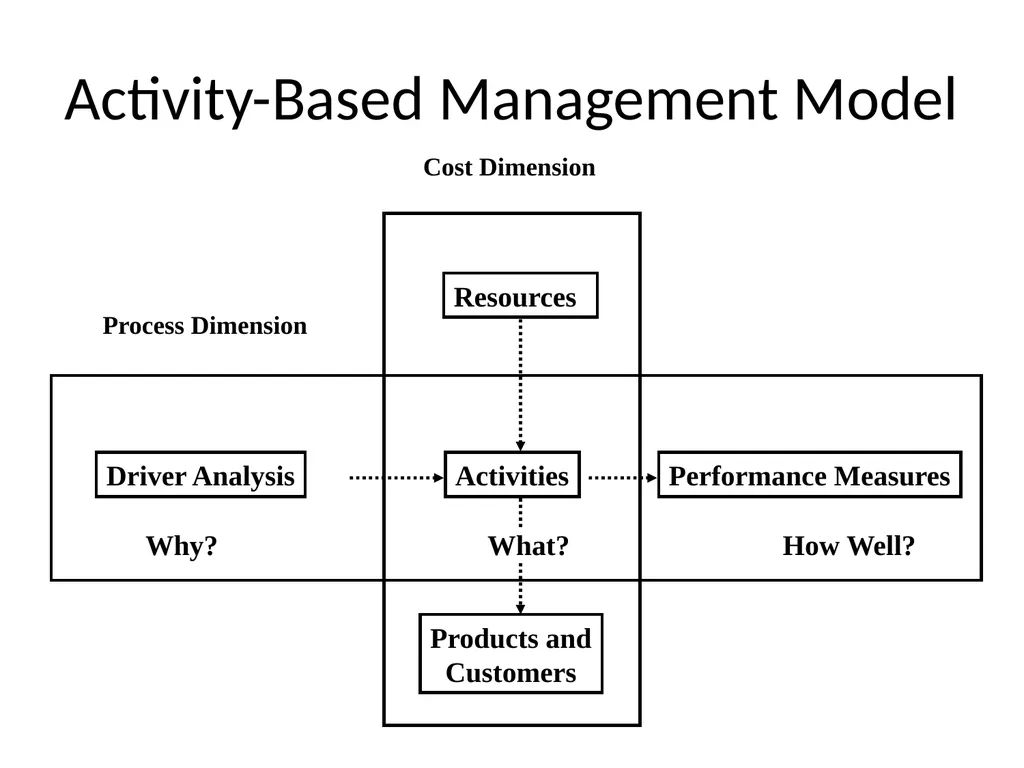
slide47. Cost Dimension Process Dimension Driver Analysis Activities Performance Measures Resources Products and
Customers Why? What? How Well? Activity-Based Management Model<br>
slide48. Process Value Analysis Process value analysis is fundamental to activity-based responsibility accounting, focuses on accountability for activities rather than costs, and emphasizes the maximization of systemwide performance instead of individual performance.
Process value analysis is concerned with:
Driver analysis
Activity analysis
Performance measurement<br>
slide49. Activity Analysis Activity analysis should produce four outcomes:
What activities are performed?
How many people perform the activities?
The time and resources required to perform the activities.
An assessment of the value of the activities to the organization, including a recommendation to select and keep only those that add value.<br>
slide50. Value-Added Activities A discretionary activity is classified as value-added provided it simultaneously satisfies three conditions:
The activity produces a change of state.
The change of state was not achievable by preceding activities.
The activity enables other activities to be performed.<br>
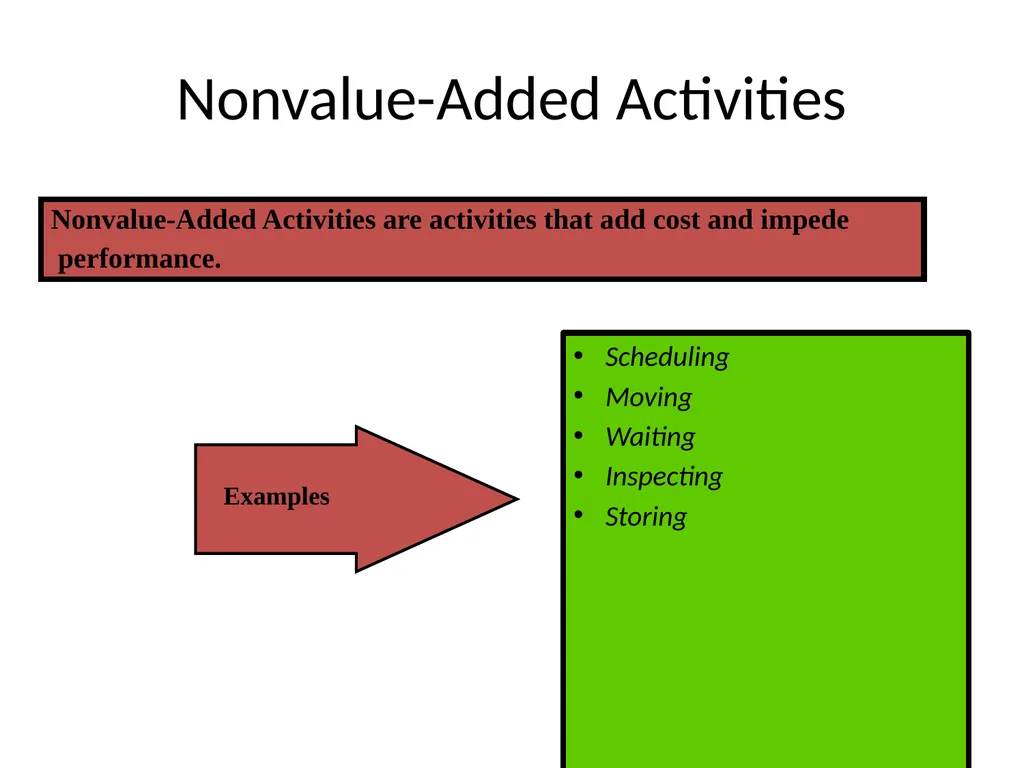
slide51. Nonvalue-Added Activities Nonvalue-Added Activities are activities that add cost and impede
performance. Scheduling
Moving
Waiting
Inspecting
Storing Examples<br>
slide52. Activity Analysis Activity elimination
Activity selection
Activity reduction
Activity sharing Activity Analysis Can Reduce Costs in Four Ways:<br>
slide53. Activity Performance Measurement Efficiency
Quality
Time Three Dimensions of Activity Performance<br>
slide54. Measures of Activity Performance Financial measures of activity efficiency include:
Value and nonvalue-added activity cost reports
Trends in activity cost reports
Kaizen standard setting
Benchmarking<br>
slide55. 55 Economic Order Quantity, JIT, and the Theory of Contraints INVENTORY MANAGEMENT<br>
slide56. 56 Learning Objectives Describe the traditional inventory management model.
Describe JIT inventory management.
Explain the basic concepts of constrained optimization.
Describe the theory of constraints, and explain how it can be used to manage inventory.<br>
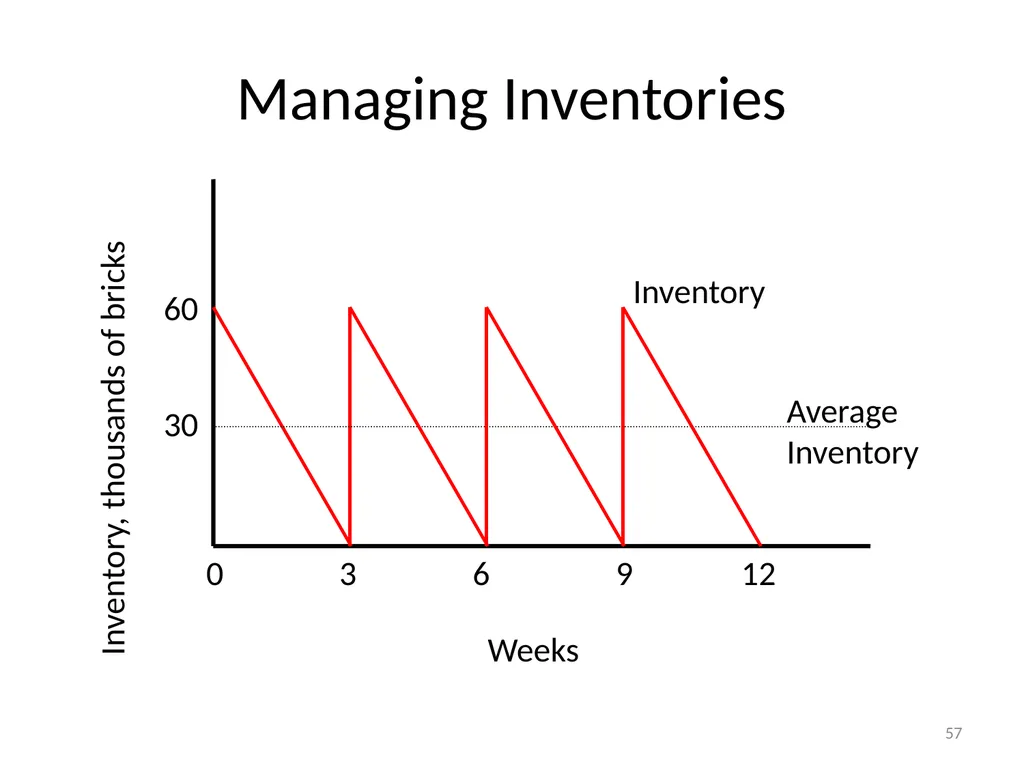
slide57. 57 Managing Inventories 0 3 6 9 12 Inventory Average Inventory Weeks Inventory, thousands of bricks 60
30<br>
slide58. 58 The Appropriate Inventory Policy Two Basic Questions Must be Addressed How much should be ordered or produced?
When should the order be placed or the setup be performed?<br>
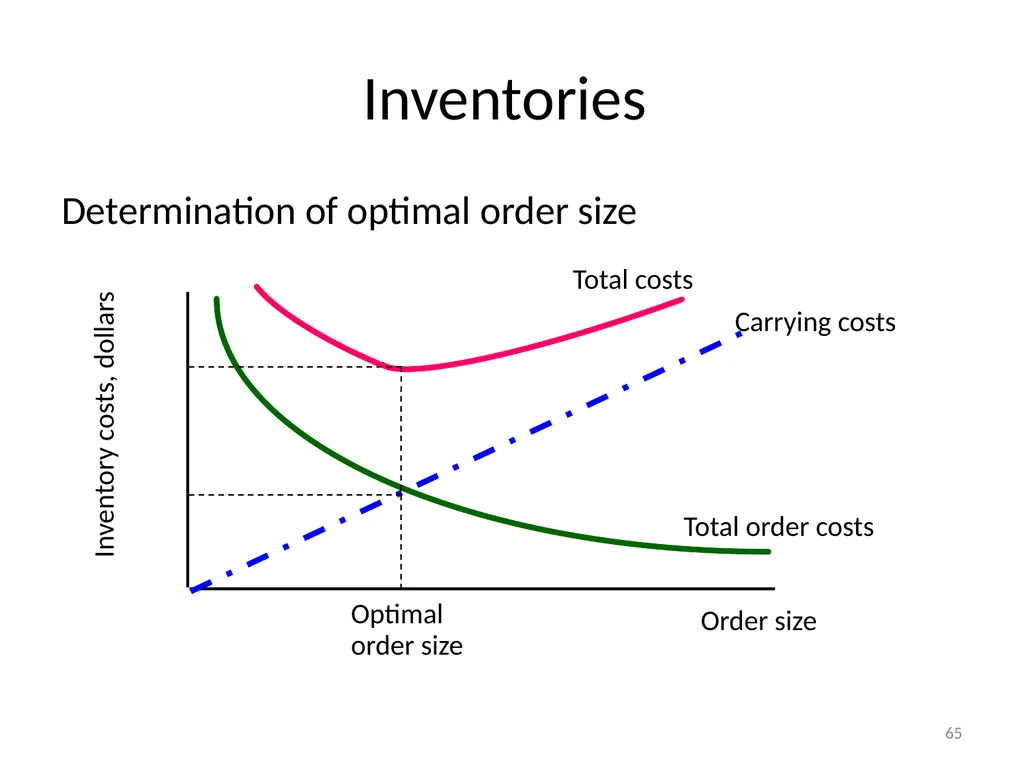
slide59. 59 Inventories As the firm increases its order size, the number of orders falls and therefore the order costs decline. However, an increase in order size also increases the average amount in inventory, so that the carrying cost of inventory rises. The trick is to strike a balance between these two costs.<br>
slide60. 60 Ordering or Setup Costs
Carrying Costs
Stockout Costs Inventory Costs Basics of Traditional Inventory Management<br>
slide61. 61 Inventory Costs Ordering Costs: The costs of placing and receiving an order
Examples: clerical costs, documents, insurance for shipment, and unloading.
Carrying Costs: The costs of carrying inventory
Examples: insurance, inventory taxes, obsolescence, opportunity cost of capital tied up in inventory, and storage.<br>
slide62. 62 Inventory Costs (continued) 3. Stock-Out Costs: The costs of not having sufficient inventory
Examples: lost sales, costs of expediting (extra setup, transportation, etc.) and the costs of interrupted production.
4. Setup Costs: The costs of preparing equipment and facilities so they can be used to produce a particular product or component
Examples: setup labor, lost income (from idled facilities), and test runs. When a firm produces the goods internally, ordering costs are replaced by setup costs.<br>
slide63. 63 Traditional Reasons for Carrying Inventory 1. To balance ordering or setup costs and carrying costs
2. To satisfy customer demand (e.g., meet delivery dates)
3. To avoid shutting down manufacturing facilities because of:
a. machine failure
b. defective parts
c. unavailable parts
d. late delivery of parts<br>
slide64. 64 Traditional Reasons for Carrying Inventory (continued) 4. Unreliable production processes
5. To take advantage of discounts
6. To hedge against future price increases<br>
slide65. 65 Inventories Determination of optimal order size Inventory costs, dollars Order size Total costs Carrying costs Total order costs Optimal
order size<br>
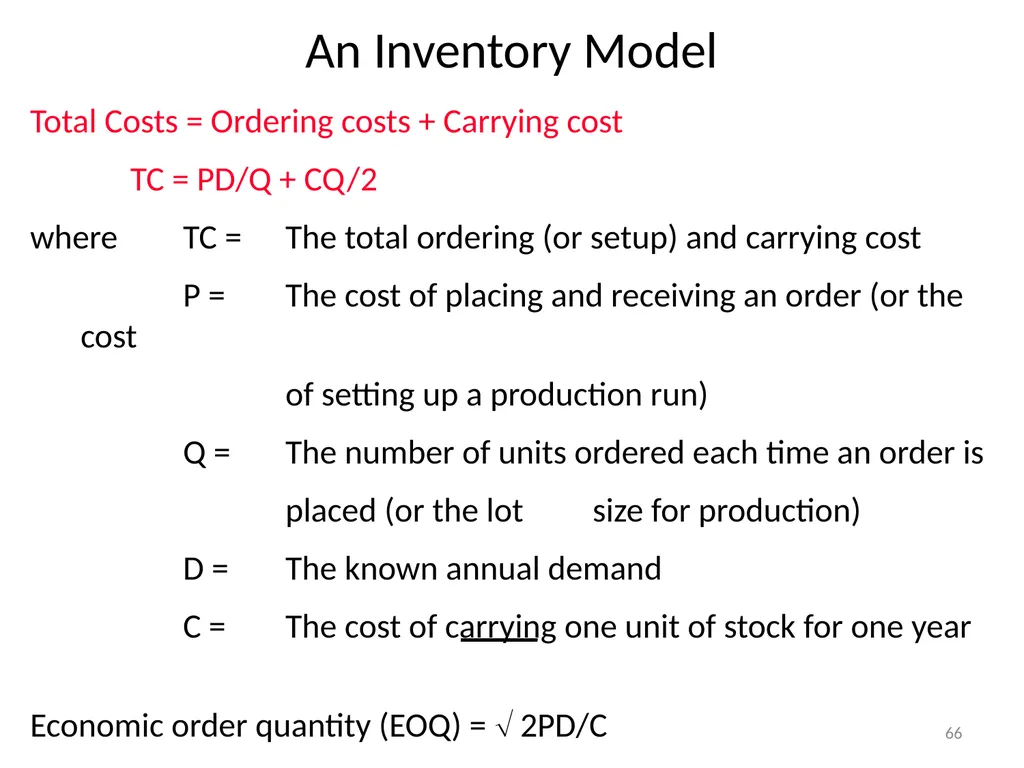
slide66. 66 Total Costs = Ordering costs + Carrying cost
TC = PD/Q + CQ/2
where TC = The total ordering (or setup) and carrying cost
P = The cost of placing and receiving an order (or the cost
of setting up a production run)
Q = The number of units ordered each time an order is
placed (or the lot size for production)
D = The known annual demand
C = The cost of carrying one unit of stock for one year
Economic order quantity (EOQ) = 2PD/C An Inventory Model<br>
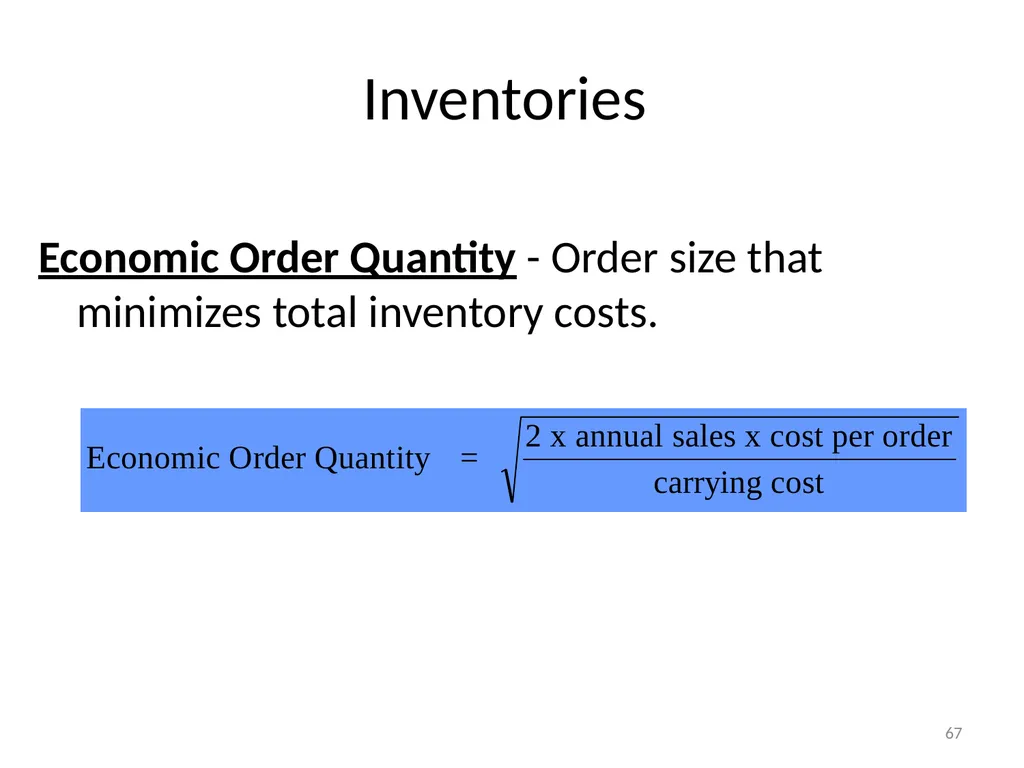
slide67. 67 Inventories Economic Order Quantity - Order size that minimizes total inventory costs.<br>
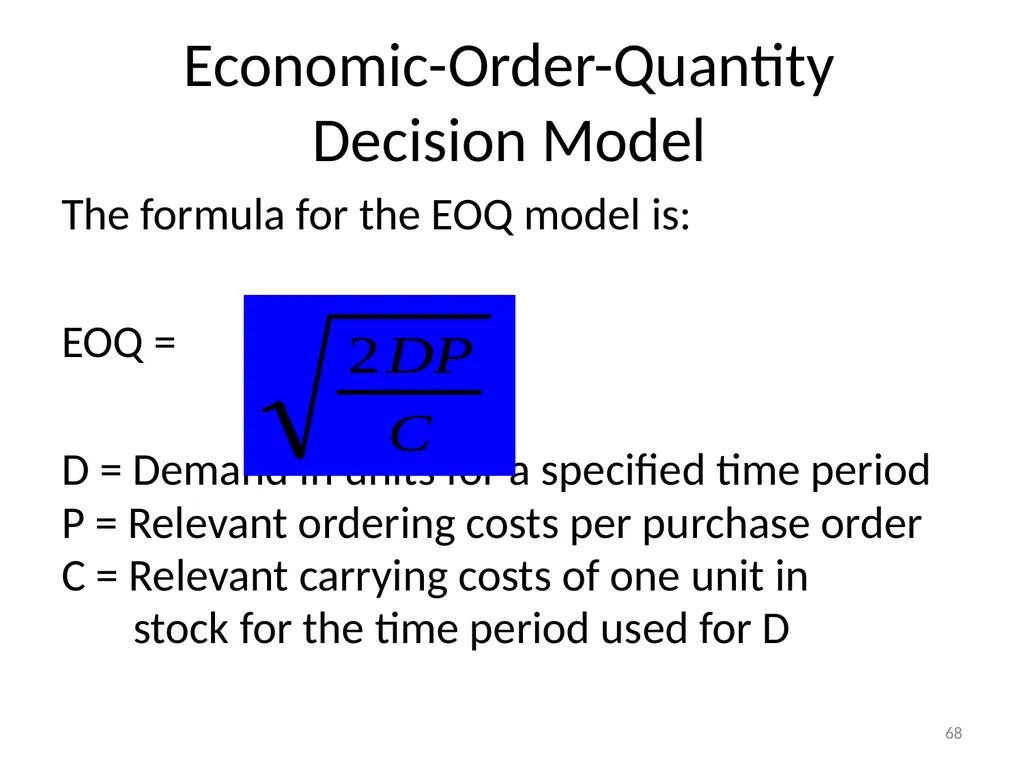
slide68. 68 Economic-Order-Quantity Decision Model The formula for the EOQ model is:
EOQ =
D = Demand in units for a specified time period
P = Relevant ordering costs per purchase order
C = Relevant carrying costs of one unit in
stock for the time period used for D<br>
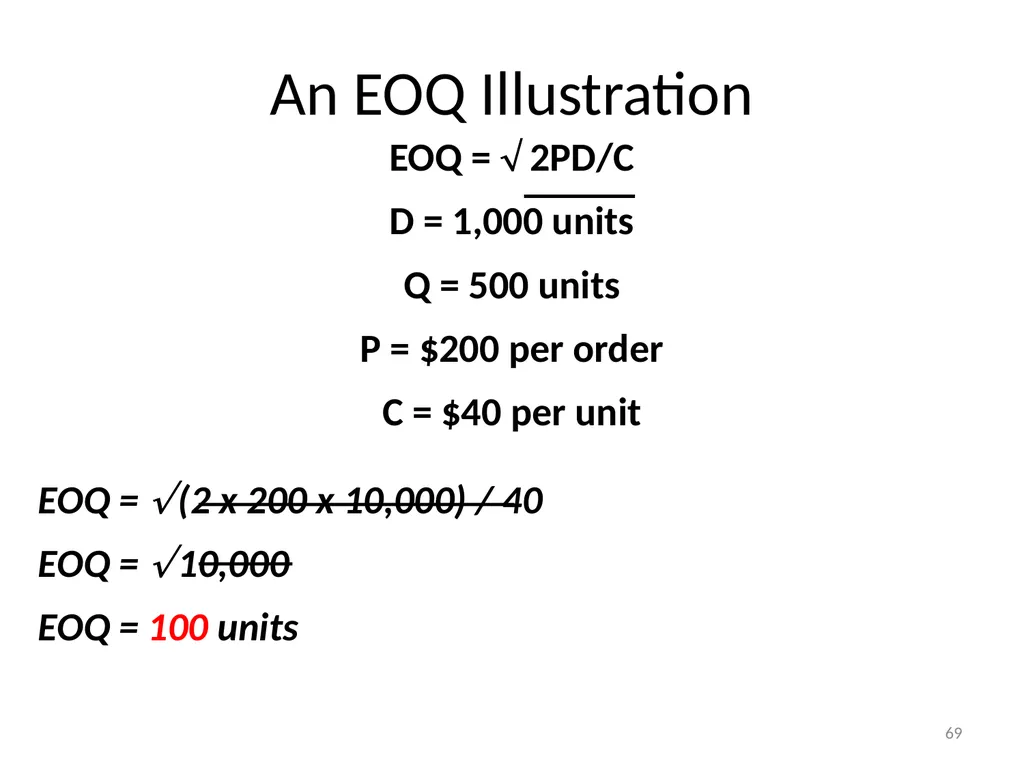
slide69. 69 An EOQ Illustration EOQ = 2PD/C
D = 1,000 units
Q = 500 units
P = $200 per order
C = $40 per unit
EOQ = (2 x 200 x 10,000) / 40
EOQ = 10,000
EOQ = 100 units<br>
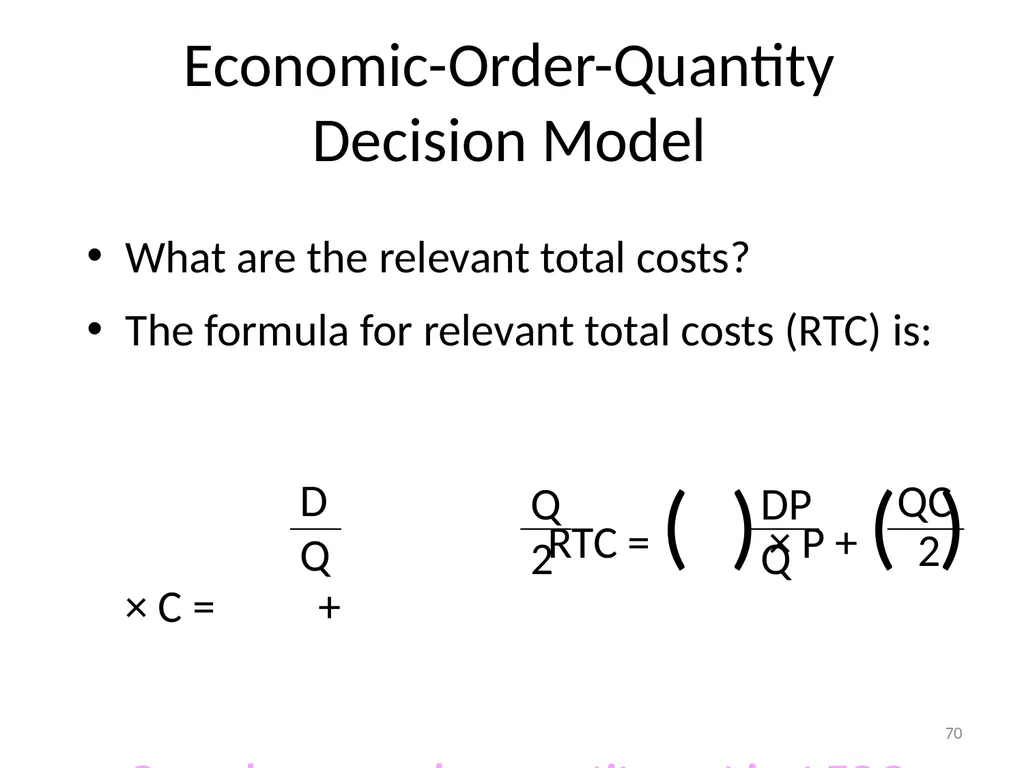
slide70. 70 Economic-Order-Quantity Decision Model What are the relevant total costs?
The formula for relevant total costs (RTC) is: RTC = Annual relevant ordering costs + Annual relevant carrying costs RTC = ( ) × P + ( ) × C = +
Q can be any order quantity, not just EOQ. D
Q Q 2 DP Q QC
2<br>
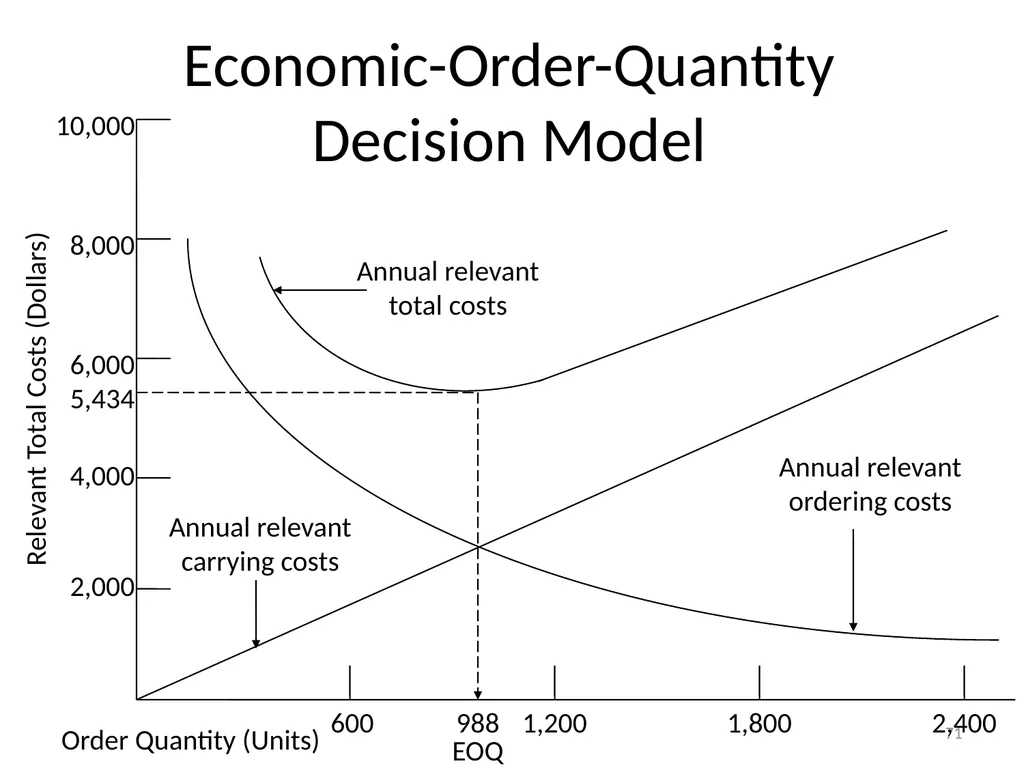
slide71. 71 Economic-Order-Quantity Decision Model Relevant Total Costs (Dollars) 2,000 4,000 6,000 8,000 10,000 5,434 600 1,200 1,800 2,400 988
EOQ Annual relevant carrying costs Annual relevant total costs Annual relevant ordering costs Order Quantity (Units)<br>
slide72. 72 Considerations in Obtaining Estimates of Relevant Costs Obtaining accurate estimates of the cost parameters used in the EOQ decision model is a challenging task.
What are the relevant incremental costs of carrying inventory?
Only those costs of the purchasing company that change with the quantity of inventory held<br>
slide73. 73 Considerations in Obtaining Estimates of Relevant Costs What is the relevant opportunity cost of capital?
It is the return forgone by investing capital in inventory rather than elsewhere.
It is calculated as the required rate of return multiplied by those costs per unit that vary with the number of units purchased and that are incurred at the time the units are received.<br>
slide74. 74 Costs Associated with Goods for Sale Five categories of costs associated with goods for sale are:
. Purchasing costs
. Ordering costs
. Carrying costs
. Stockout costs
. Quality costs<br>
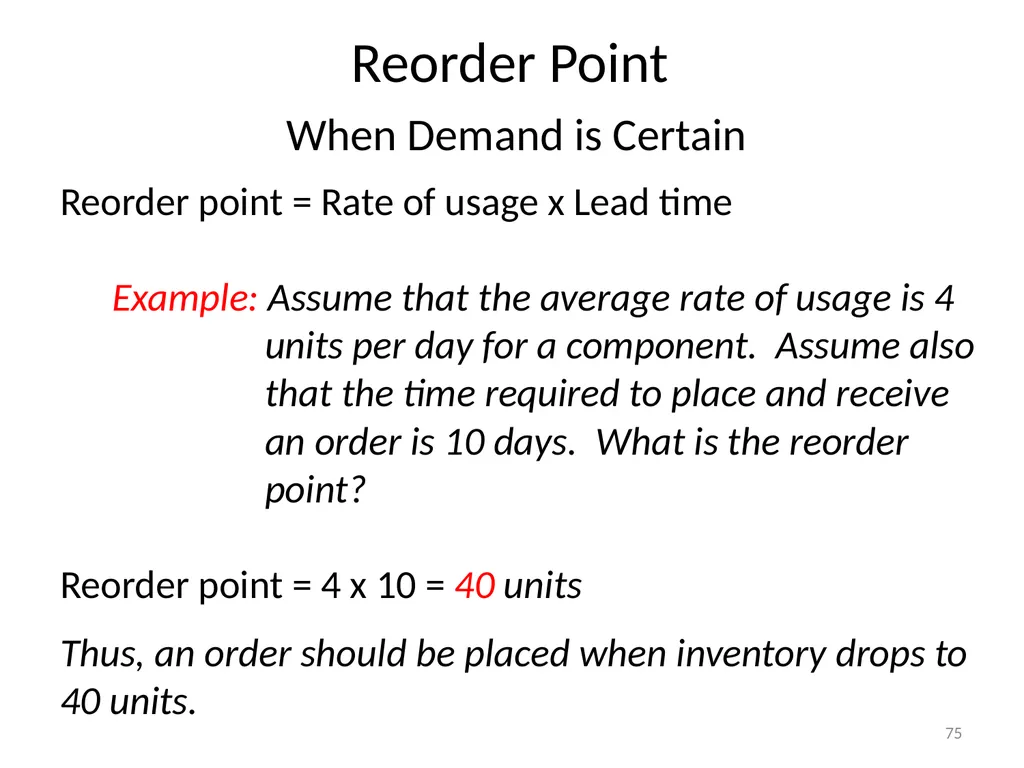
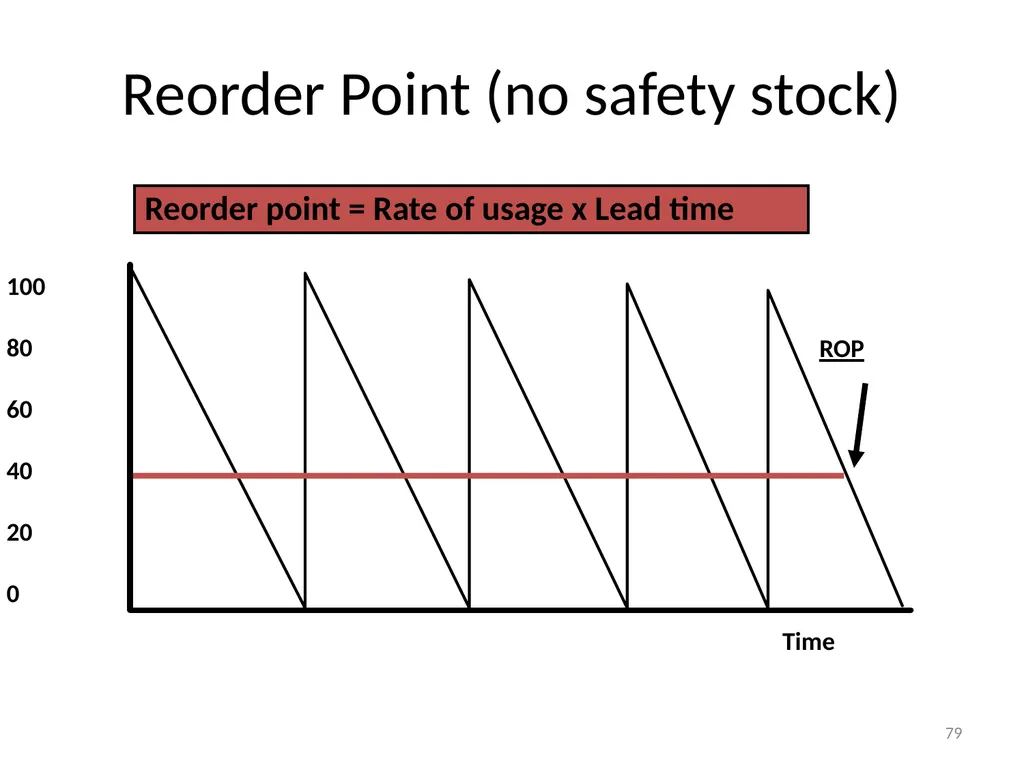
slide75. 75 Reorder Point When Demand is Certain Reorder point = Rate of usage x Lead time
Example: Assume that the average rate of usage is 4 units per day for a component. Assume also that the time required to place and receive an order is 10 days. What is the reorder point?
Reorder point = 4 x 10 = 40 units
Thus, an order should be placed when inventory drops to 40 units.<br>
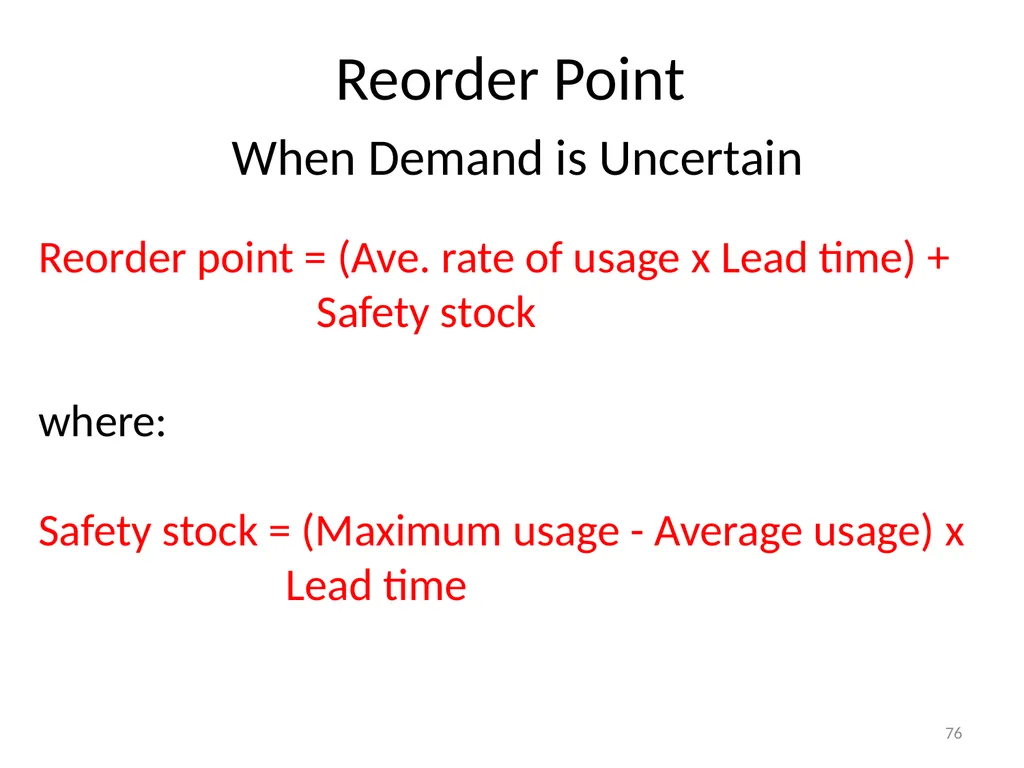
slide76. 76 Reorder Point When Demand is Uncertain Reorder point = (Ave. rate of usage x Lead time) +
Safety stock
where:
Safety stock = (Maximum usage - Average usage) x
Lead time<br>
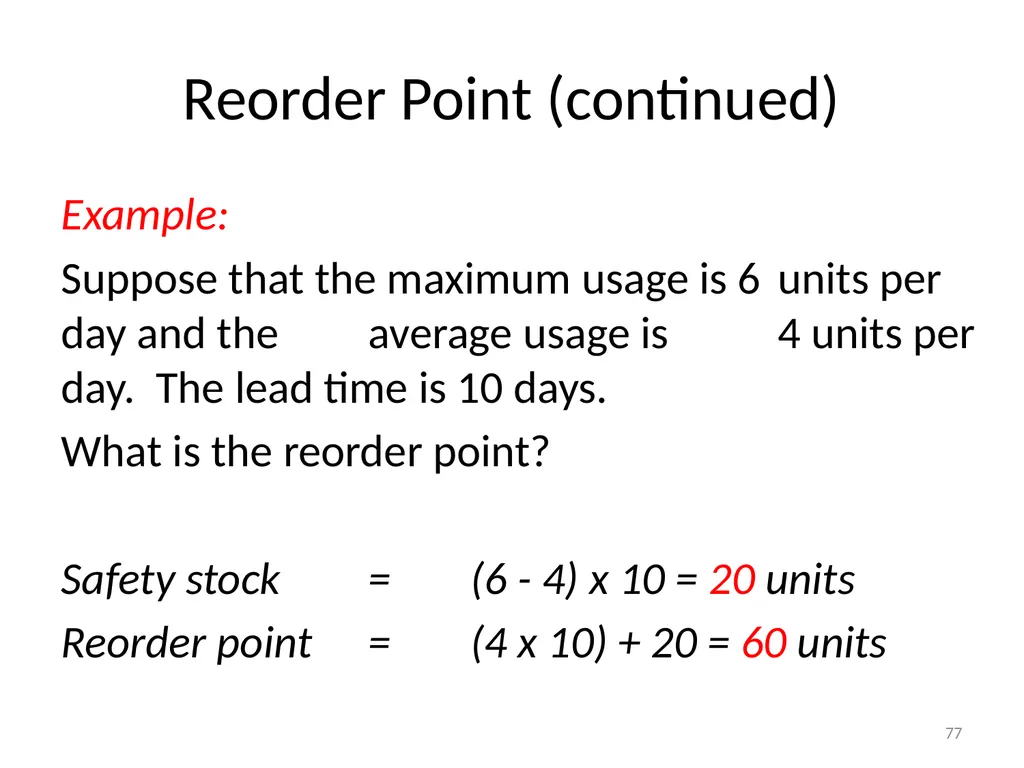
slide77. 77 Reorder Point (continued) Example:
Suppose that the maximum usage is 6 units per day and the average usage is 4 units per day. The lead time is 10 days.
What is the reorder point?
Safety stock = (6 - 4) x 10 = 20 units
Reorder point = (4 x 10) + 20 = 60 units<br>
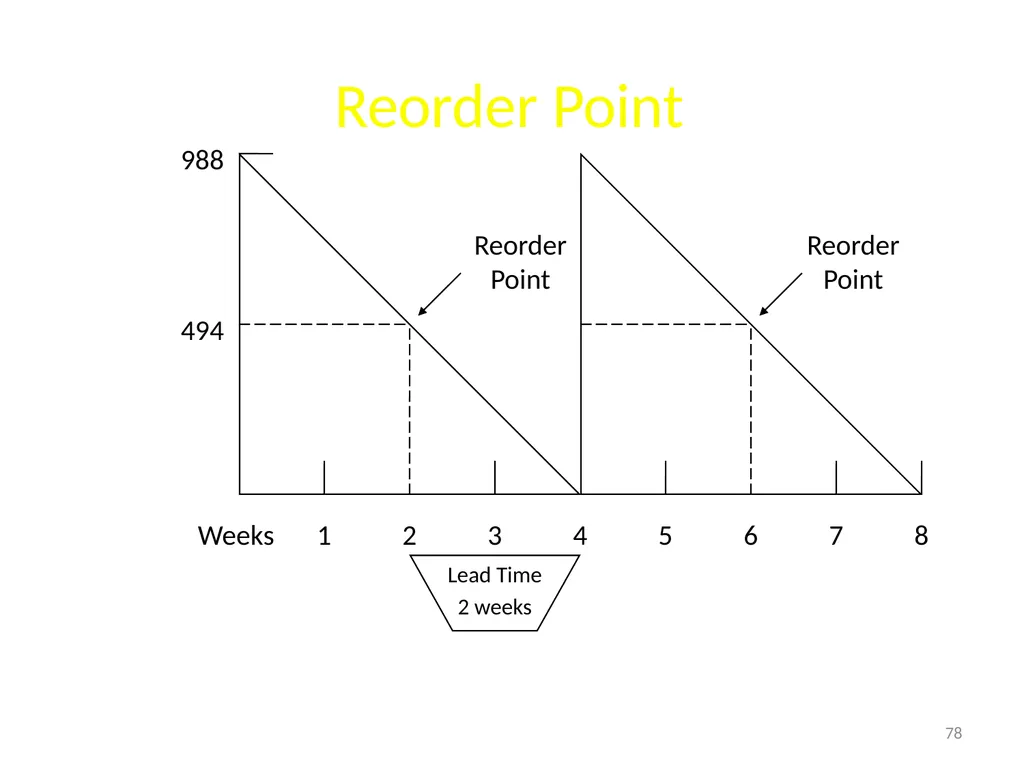
slide78. 78 Reorder Point 988 494 Weeks 1 2 3 4 5 6 7 8 Reorder Point Reorder Point Lead Time
2 weeks<br>
slide79. 79 Reorder Point (no safety stock) Reorder point = Rate of usage x Lead time 100
80
60
40
20
0 Time ROP<br>
slide80. 80 Safety Stock Safety stock is inventory held at all times regardless of the quantity of inventory ordered using the EOQ model.
Safety stock is used as a buffer against unexpected increases in demand or lead time and unavailability of stock from suppliers.<br>
slide81. 81 Evaluating Managers and Goal-Congruence Issues Goal-congruence issues can arise when there is an inconsistency between the EOQ decision model and the model used to evaluate the performance of the manager implementing the inventory management decisions.<br>
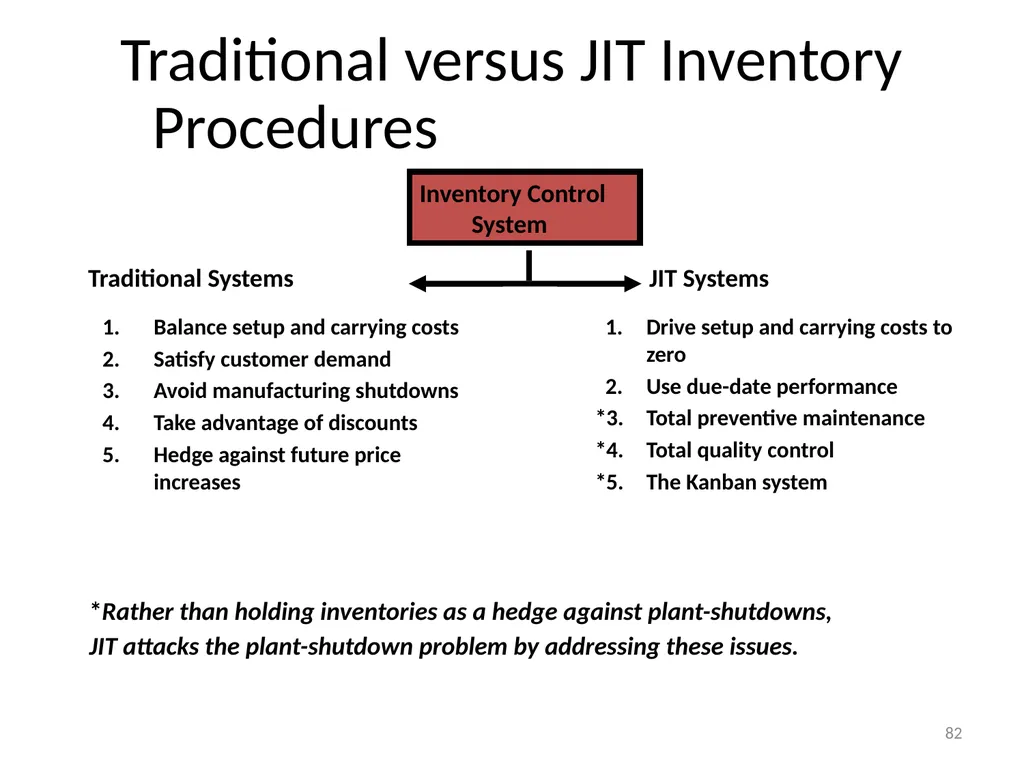
slide82. 82 Traditional versus JIT Inventory Procedures Inventory Control
System 1. Balance setup and carrying costs
2. Satisfy customer demand
3. Avoid manufacturing shutdowns
4. Take advantage of discounts
5. Hedge against future price increases 1. Drive setup and carrying costs to zero
2. Use due-date performance
*3. Total preventive maintenance
*4. Total quality control
*5. The Kanban system Traditional Systems JIT Systems *Rather than holding inventories as a hedge against plant-shutdowns,
JIT attacks the plant-shutdown problem by addressing these issues.<br>
slide83. 83 Just-In-Time Production Systems Just-in-time (JIT) production systems take a “demand pull” approach in which goods are only manufactured to satisfy customer orders.
Demand triggers each step of the production process, starting with customer demand for a finished product at the end of the process, to the demand for direct materials at the beginning of the process.<br>
slide84. 84 Materials Requirement Planning (MRP) Materials requirements planning (MRP) systems take a “push-through” approach that manufactures finished goods for inventory on the basis of demand forecasts.
MRP predetermines the necessary outputs at each stage of production.
Inventory management is a key challenge in an MRP system.<br>
slide85. 85 JIT And Inventory Management Setup and Carrying Costs: The JIT Approach JIT reduces the costs of acquiring inventory to insignificant levels by:
1. Drastically reducing setup time
2. Using long-term contracts for outside purchases
Carrying costs are reduced to insignificant levels by reducing inventories to insignificant levels<br>
slide86. 86 JIT And Inventory Management Due-Date Performance: The JIT Solution Lead times are reduced so that the company can meet requested delivery dates and to respond quickly to customer demand.
Lead times are reduced by:
reducing setup times
improving quality
using cellular manufacturing<br>
slide87. 87 JIT And Inventory Management Avoidance of Shutdown: The JIT Approach Total preventive maintenance to reduce machine failures
Total quality control to reduce defective parts
Cultivation of supplier relationships to ensure availability of quality raw materials and subassemblies
The use of the Kanban system is also essential<br>
slide88. 88 JIT And Inventory Management Discounts and Price Increases: JIT Purchasing Versus Holding Inventories Careful vendor selection
Long-term contracts with vendors
Prices are stipulated (usually producing a significant savings)
Quality is stipulated
The number of orders placed are reduced<br>
slide89. 89 Major Features of a JIT System The five major features of a JIT system are:
Organizing production in manufacturing cells
Hiring and retaining multi-skilled workers
Emphasizing total quality management
Reducing manufacturing lead time and setup Time
Building strong supplier relationships<br>
slide90. 90 Benefits of JIT Systems Benefits of JIT production:
Lower carrying costs of inventory
Eliminating the root causes of rework, scrap, waste, and manufacturing lead time.<br>
slide91. 91 Performance Measures and Control in JIT Production To manage and reduce inventories, the management accountant must design performance measures to control and evaluate JIT production.
What information may management accountants use?
Personal observation by production line workers and managers
Financial performance measures, such as inventory turnover ratios<br>
slide92. 92 Performance Measures and Control in JIT Production What are nonfinancial performance measures of time, inventory, and quality?
Manufacturing lead time
Units produced per hour
Days’ inventory on hand
Total setup time for machines/Total manufacturing time
Number of units requiring rework or scrap/Total number of units started and completed<br>
slide93. 93 Backflush Costing A unique production system such as JIT often leads to its own unique costing system.
Organizing manufacturing in cells, reducing defects and manufacturing lead time, and ensuring timely delivery of materials enables purchasing, production, and sales to occur in quick succession with minimal inventories.<br>
slide94. 94 Backflush Costing Where journal entries for one or more stages in the cycle are omitted, the journal entries for a subsequent stage use normal or standard costs to work backward to flush out the costs in the cycle for which journal entries were not made.<br>
slide95. 95 Trigger Points Stage A: Purchase of direct materials
Stage B: Production resulting in work in process
Stage C: Completion of a good finished unit or
product
Stage D: Sale of finished goods<br>
slide96. 96 Trigger Points Assume trigger points A, C, and D.
This company would have two inventory accounts:
Type Account Title 1. Combined materials Inventory: Material and materials in work-in- and In-Process process inventory Control
2. Finished goods Finished Goods Control<br>
slide97. 97 Trigger Points Assume trigger points A and D.
This company would have one inventory account:
Type Account Title Combines direct materials Inventory inventory and any direct Control materials in work-in-process and finished goods inventories<br>
slide98. 98 Special Considerations in Backflush Costing Backflush costing does not necessarily comply with GAAP
However, inventory levels may be immaterial, negating the necessity for compliance
Backflush costing does not leave a good audit trail – the ability of the accounting system to pinpoint the uses of resources at each step of the production process<br>
slide99. 99 What is the Kanban System? A Card System is used to monitor work-in-process A withdrawal Kanban
A production Kanban
A vendor Kanban<br>
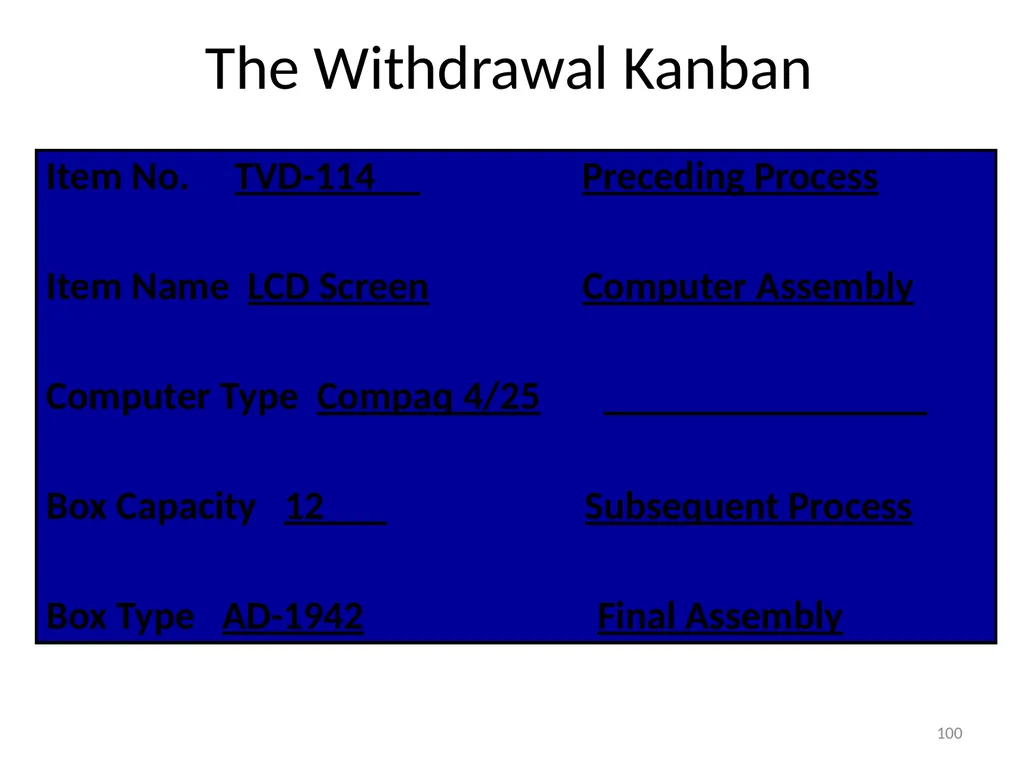
slide100. 100 The Withdrawal Kanban Item No. TVD-114 Preceding Process
Item Name LCD Screen Computer Assembly
Computer Type Compaq 4/25
Box Capacity 12 Subsequent Process
Box Type AD-1942 Final Assembly<br>
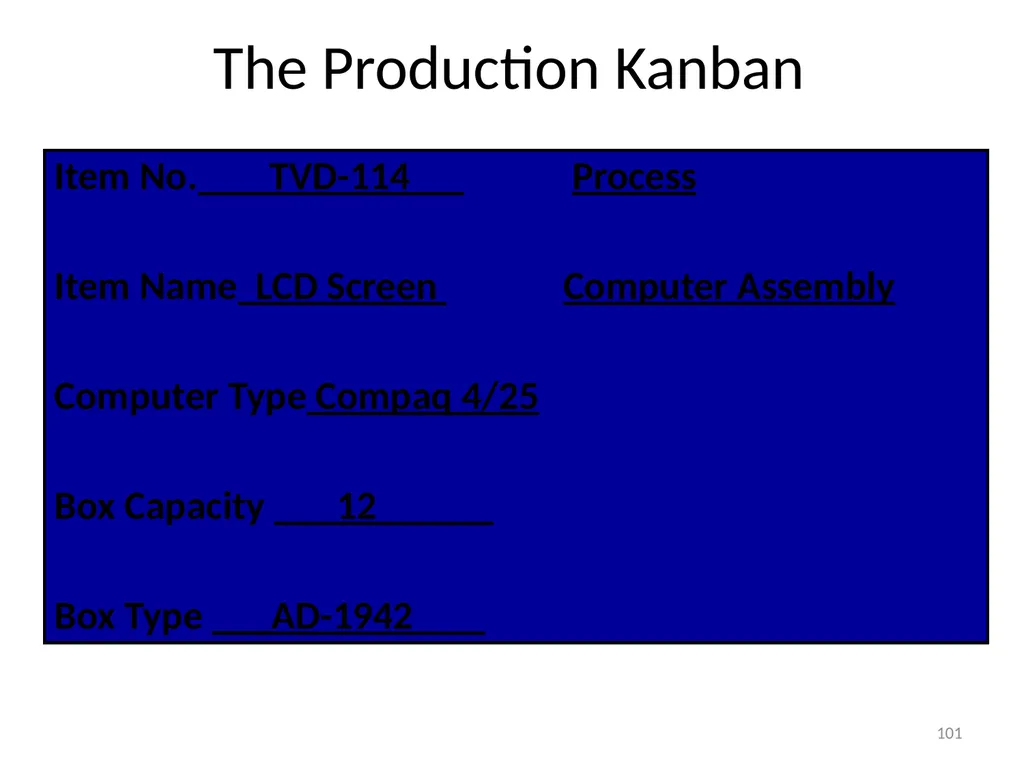
slide101. 101 The Production Kanban Item No. TVD-114 Process
Item Name LCD Screen Computer Assembly
Computer Type Compaq 4/25
Box Capacity 12
Box Type ___AD-1942<br>
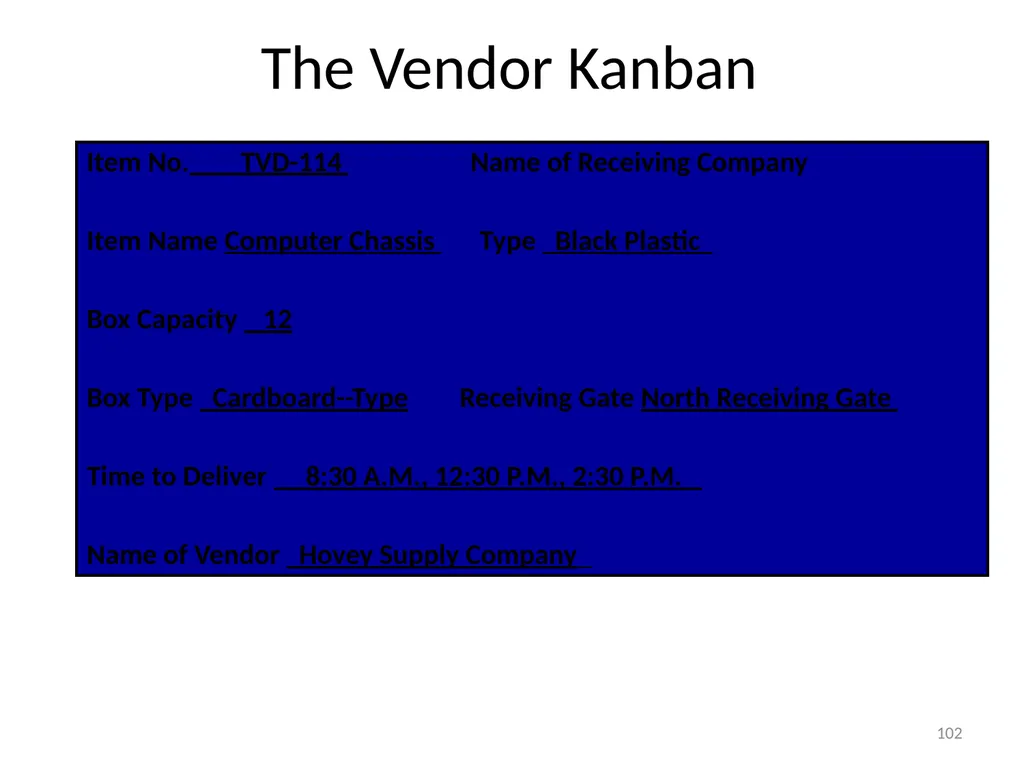
slide102. 102 The Vendor Kanban Item No. TVD-114 Name of Receiving Company
Item Name Computer Chassis Type Black Plastic
Box Capacity 12
Box Type Cardboard--Type Receiving Gate North Receiving Gate
Time to Deliver 8:30 A.M., 12:30 P.M., 2:30 P.M.
Name of Vendor Hovey Supply Company<br>
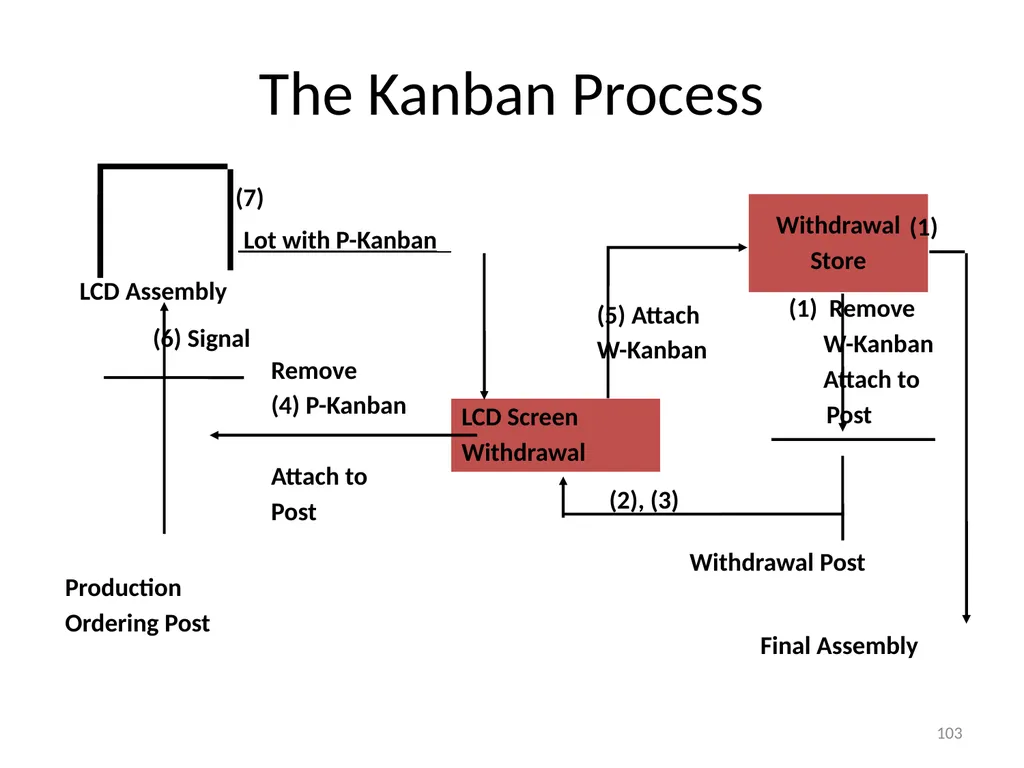
slide103. 103 The Kanban Process Withdrawal
Store LCD Screen
Withdrawal Lot with P-Kanban Production
Ordering Post (6) Signal LCD Assembly Remove
(4) P-Kanban
Attach to
Post (5) Attach
W-Kanban (1) Remove
W-Kanban
Attach to
Post Withdrawal Post (2), (3) (7) Final Assembly (1)<br>
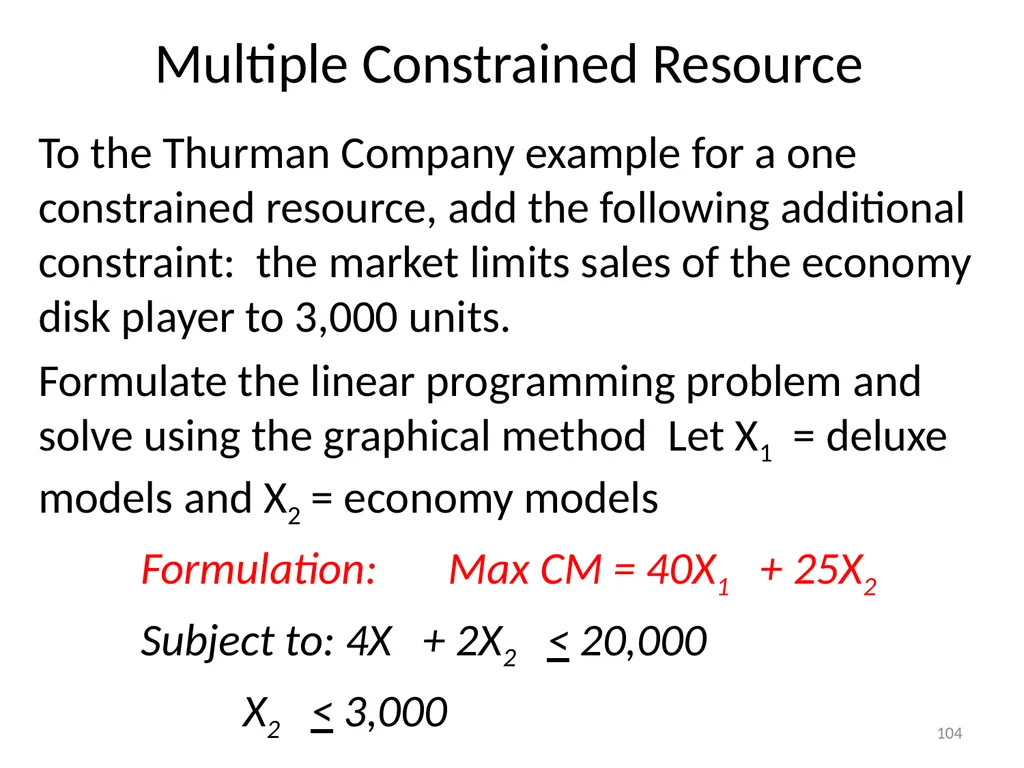
slide104. 104 Multiple Constrained Resource To the Thurman Company example for a one constrained resource, add the following additional constraint: the market limits sales of the economy disk player to 3,000 units.
Formulate the linear programming problem and solve using the graphical method Let X1 = deluxe models and X2 = economy models
Formulation: Max CM = 40X1 + 25X2
Subject to: 4X + 2X2 < 20,000
X2 < 3,000<br>
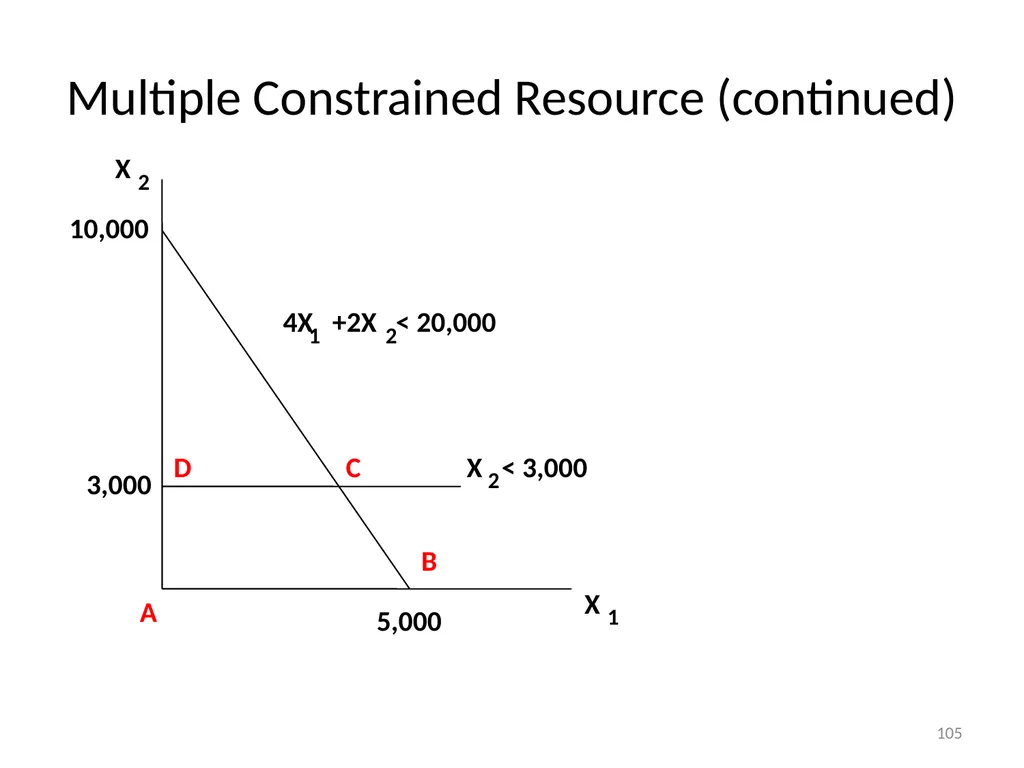
slide105. 105 Multiple Constrained Resource (continued) 10,000 3,000 A 5,000 D C B X X 4X +2X < 20,000 X < 3,000 1 1 2 2 2<br>
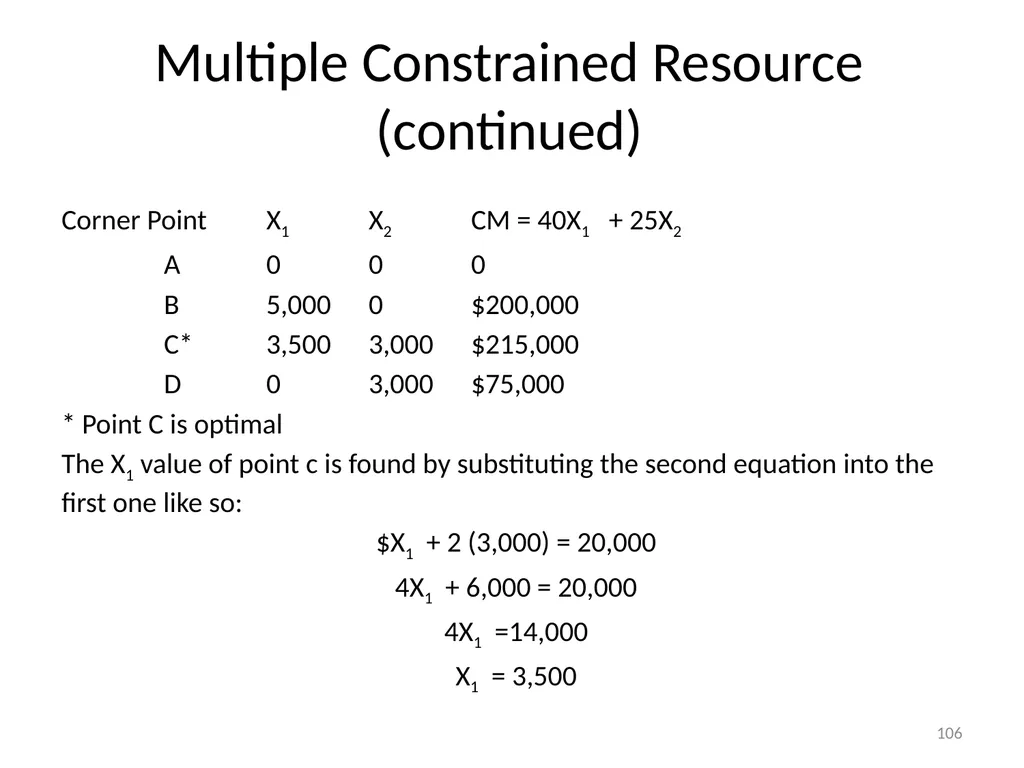
slide106. 106 Multiple Constrained Resource (continued) Corner Point X1 X2 CM = 40X1 + 25X2
A 0 0 0
B 5,000 0 $200,000
C* 3,500 3,000 $215,000
D 0 3,000 $75,000
* Point C is optimal
The X1 value of point c is found by substituting the second equation into the first one like so:
$X1 + 2 (3,000) = 20,000
4X1 + 6,000 = 20,000
4X1 =14,000
X1 = 3,500<br>
slide107. 107 Throughput
Inventory
Operating expenses Three Measures of Systems Performance Theory of Constraints<br>
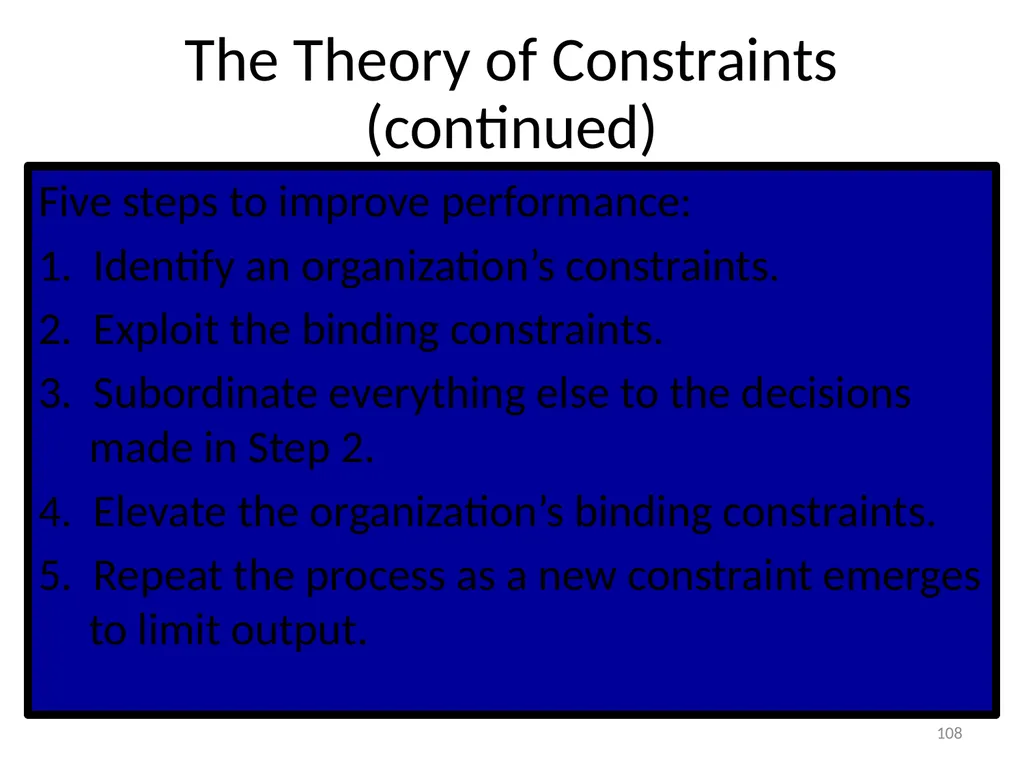
slide108. 108 The Theory of Constraints (continued) Five steps to improve performance:
1. Identify an organization’s constraints.
2. Exploit the binding constraints.
3. Subordinate everything else to the decisions made in Step 2.
4. Elevate the organization’s binding constraints.
5. Repeat the process as a new constraint emerges to limit output.<br>
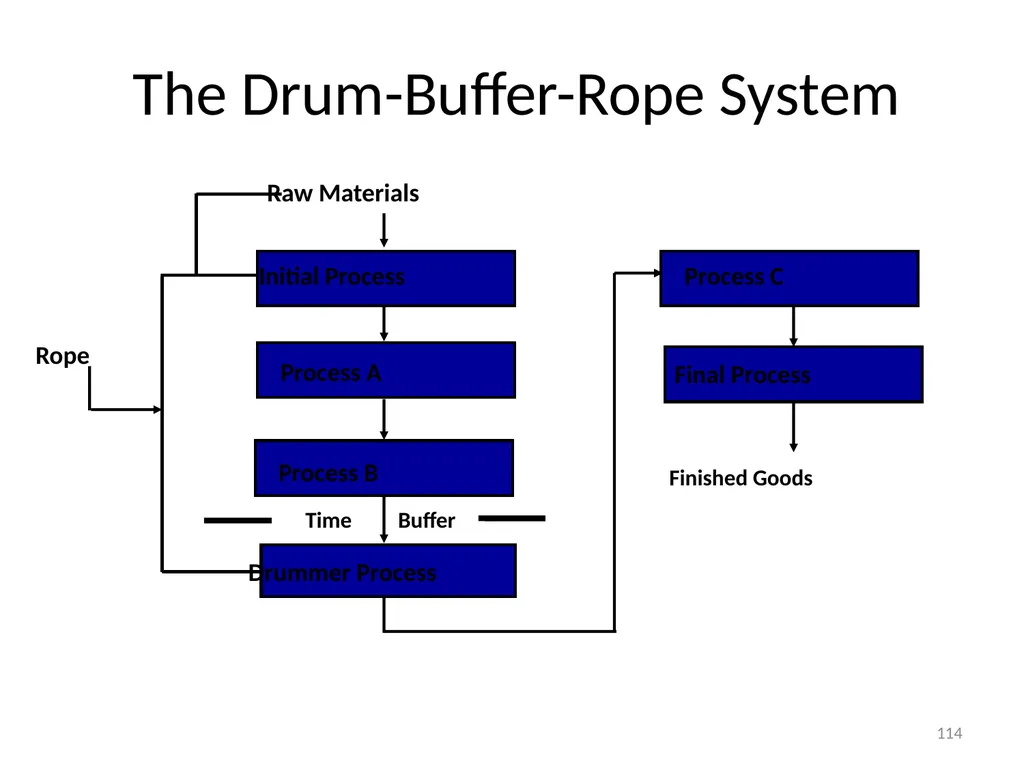
slide109. 109 Theory of Constraints A sequential process of identifying and removing constraints in a system. Restrictions or barriers that impede progress toward an objective<br>
slide110. 110 Theory of Constraints The theory of constraints emphasizes the management of bottlenecks as the key to improving the performance of the production system as a whole.<br>
slide111. 111 Methods to Relieve Bottlenecks Eliminate idle time at the bottleneck operation
Process only those parts or products that increase throughput contribution, not parts or products that will remain in finished goods or spare parts inventories
Shift products that do not have to be made on the bottleneck operation to nonbottleneck processes, or to outside processing facilities<br>
slide112. 112 Methods to Relieve Bottlenecks Reduce setup time and processing time at bottleneck operations
Improve the quality of parts or products manufactured at the bottleneck operation<br>
slide113. 113 Theory of Constraints The objective of TOC is to increase throughput contribution while decreasing investments and operating costs.
TOC considers a short-run time horizon and assumes operating costs to be fixed costs.<br>
slide114. 114 The Drum-Buffer-Rope System Initial Process Process A Process B Drummer Process Raw Materials Process C Final Process Rope Time Buffer Finished Goods<br>
slide115. 115 The Management of Capacity Managers can reduce capacity-based fixed costs by measuring and managing unused capacity
Unused Capacity is the amount of productive capacity available over and above the productive capacity employed to meet consumer demand in the current period<br>
slide116. 116 Analysis of Unused Capacity Two Important Features:
Engineered Costs result from a cause-and-effect relationship between output and the resources used to produce that output
Discretionary Costs have two parts:
They arise from periodic (annual) decisions regarding the maximum amount to be incurred
They have no measurable cause-and-effect relationship between output and resources used<br>
slide117. 117 Managing Unused Capacity Downsizing (Rightsizing) is an integrated approach of configuring processes, products, and people to match costs to the activities that need to be performed to operate effectively and efficiently in the present and future
Because identifying unused capacity for discretionary costs is difficult, downsizing, or otherwise managing this unused capacity, is also difficult.<br>
slide118. 118 End of Week<br>
slide2. PERTEMUAN II, 28 OKTOBER 2013 ACTIVITY BASED COSTING
ACTIVITY BASED MANAGEMENT
INVENTORY MANAGEMENT<br>
slide3. 4 - 3 Learning Objective 1 Describe the purposes of
cost management systems.<br>
slide4. 4 - 4 Cost Management System A cost-management system (CMS) is a
collection of tools and techniques that
identifies how management’s decisions
affect costs.<br>
slide5. 4 - 5 What is Cost Accounting? Cost accounting is that part of the
accounting system that measures costs
for the purposes of management decision
making and financial reporting.<br>
slide6. 4 - 6 Learning Objective 2 Explain the relationships
among cost, cost objective,
cost accumulation, and
cost allocation.<br>
slide7. 4 - 7 Cost Accounting System Cost
Accumulation Collecting costs by some
“natural” classification
such as materials or labor Cost
Allocation Tracing costs to one or
more cost objectives<br>
slide8. 4 - 8 Cost Accounting System MACHINING
DEPARTMENT
ACTIVITY ACTIVITY FINISHING
DEPARTMENT
ACTIVITY ACTIVITY RAW MATERIAL
COSTS (METALS CABINETS CABINETS DESKS DESKS TABLES TABLES Cost Accumulation
Cost Allocation
to Cost Objects:
1. Departments
2. Activities
3. Products<br>
slide9. 4 - 9 Cost A cost may be defined as a sacrifice or giving up of resources for a particular purpose.
Costs are frequently measured by the monetary units that must be paid for goods and services.<br>
slide10. 4 - 10 Cost Objective What is a cost object or cost objective? It is anything for which a separate measurement
of costs is desired.<br>
slide11. 4 - 11 Learning Objective 3 Distinguish among direct,
indirect, and unallocated costs.<br>
slide12. 4 - 12 Direct Costs Direct costs can be identified specifically
and exclusively with a given cost
objective in an economically
feasible way. What are direct costs?<br>
slide13. 4 - 13 Indirect Costs Indirect costs cannot be identified
specifically and exclusively with a
given cost objective in an economically
feasible way. What are indirect costs?<br>
slide14. 4 - 14 What Distinguishes Direct and Indirect Costs? Managers prefer to classify costs as direct rather than indirect whenever it is “economically feasible” or “cost effective.”
Other factors also influence whether a cost is considered direct or indirect.
The key is the particular cost objective.<br>
slide15. 4 - 15 Categories of Manufacturing Costs Any raw material, labor, or other input
used by any organization could,
in theory, be identified as a
direct or indirect cost
depending on the
cost objective.<br>
slide16. 4 - 16 Categories of Manufacturing Costs All costs which are eventually allocated to products are classified as either…
direct materials,
direct labor, or
indirect manufacturing.<br>
slide17. 4 - 17 Direct Material Costs... include the acquisition costs of all materials that are physically identified as a part of the manufactured goods and that may be traced to the manufactured goods in an economically feasible way.<br>
slide18. 4 - 18 Direct Labor Costs... include the wages of all labor that can be traced specifically and exclusively to the manufactured goods in an economically feasible way.<br>
slide19. 4 - 19 Indirect Manufacturing Costs... or factory overhead, include all costs associated with the manufacturing process that cannot be traced to the manufactured goods in an economically feasible way.<br>
slide20. 4 - 20 Product Costs... are costs identified with goods produced or purchased for resale.
Product costs are initially identified as part of the inventory on hand.
These costs, inventoriable costs, become expenses (in the form of cost of goods sold) only when the inventory is sold.<br>
slide21. 4 - 21 Period Costs... are costs that are deducted as expenses during the current period without going through an inventory stage.<br>
slide22. 4 - 22 Period or Product Costs In merchandising accounting, insurance, depreciation, and wages are period costs (expenses of the current period).
In manufacturing accounting, many of these items are related to production activities and thus, as indirect manufacturing, are product costs.<br>
slide23. 4 - 23 Period Costs – Merchandising and Manufacturing In both merchandising and manufacturing accounting, selling and general administrative costs are period costs.<br>
slide24. 4 - 24 Learning Objective 4 Explain how the financial
statements of merchandisers
and manufacturers differ
because of the types of goods
they sell.<br>
slide25. 4 - 25 Financial Statement Presentation – Merchandising Companies Merchandise
Inventory Sales Cost of Goods Sold
(an expense) Selling and
Administrative
Expenses Balance Sheet Income Statement – Equals Gross Margin Equals Operating Income – Expiration Period
Costs<br>
slide26. 4 - 26 Financial Statement Presentation – Manufacturing Companies Finished
Goods
Inventory Sales Cost of Goods Sold
(an expense) Selling and
Administrative
Expenses Balance Sheet Income Statement – Equals Gross Margin Equals Operating Income – Expiration Period
Costs Direct
Material
Inventory Work-in-
Process
Inventory<br>
slide27. 4 - 27 Costs and Income Statements On income statements, the detailed reporting of selling and administrative expenses is typically the same for manufacturing and merchandising organizations, but the cost of goods sold is different.<br>
slide28. 4 - 28 Cost of Goods Sold for a Manufacturer The manufacturer’s cost of goods produced and then sold is usually composed of the three major categories of cost:
Direct materials
Direct labor
Indirect manufacturing<br>
slide29. 4 - 29 Cost of Goods Sold for a Retailer or Wholesaler The merchandiser’s cost of goods sold is usually composed of the purchase cost of items, including freight-in, that are acquired and then resold.<br>
slide30. 4 - 30 Learning Objective 5 Understand the main
differences between traditional
and activity-based costing
systems and why ABC systems
provide value to managers.<br>
slide31. 4 - 31 Traditional Cost System All
Unallocated
Value Chain
Costs Direct
Material
Resource Direct
Labor
Resource All
Indirect
Resources Products Direct
Trace Direct
Trace Cost
Driver Unallocated<br>
slide32. 4 - 32 Two-Stage Activity-Based Cost System All
Unallocated
Value Chain
Costs Direct
Material
Resource Direct
Labor
Resource Indirect
Resource
A Products Direct
Trace Direct
Trace Activity
1 Unallocated Other
Direct
Resources Indirect
Resource
Z Activity
10 % % % % Cost
Driver Cost
Driver<br>
slide33. 4 - 33 Activity-Based Costing Understanding the relationships among activities, resources, costs, and cost drivers is the key to understanding ABC and how ABC facilitates managers’ understanding of operations.<br>
slide34. 4 - 34 Example of Activities and Cost Drivers: Activities:
Account billing
Bill verification
Account iniquity
Correspondence Cost Drivers:
No. of lines
No. of accounts
No. of labor hours
No. of letters Activity-Based Costing<br>
slide35. 4 - 35 Learning Objective 6 Identify the steps involved in the
design and implementation
of an activity-based
costing system.<br>
slide36. 4 - 36 Designing and Implementing an Activity-Based Costing System Determine cost of
activities, resources,
and related cost
drivers. Develop a process-based
map representing the flow
of activities, resources, and
their interrelationships. Step 1 Step 2<br>
slide37. 4 - 37 Designing and Implementing an Activity-Based Costing System Collect relevant data concerning costs
and the physical flow of the cost-driver
units among resources and activities. Step 3<br>
slide38. 4 - 38 Designing and Implementing an Activity-Based Costing System Calculate and interpret the new
activity-based information. Using an activity-based costing system to
improve the operations of an organization
is activity-based management (ABM). Step 4<br>
slide39. 4 - 39 Activity-Based Management Activity-based management aims to improve the value received by customers and to improve profits by identifying opportunities for improvements in strategy and operations.<br>
slide40. 4 - 40 Activity-Based Management A value-added cost is the cost of an activity that cannot be eliminated without affecting a product’s value to the customer.
In contrast, non-value-added costs are costs that can be eliminated without affecting a product’s value to the customer.<br>
slide41. 4 - 41 Learning Objective 7 Use activity-based cost
information to improve the
operations of an organization.<br>
slide42. 4 - 42 Using ABC Information Activity-based management… provides costs of value-added and
non-value-added activities. improves managers’ understanding of operations.<br>
slide43. 4 - 43 Learning Objective 8 Understand cost accounting’s
role in a company’s
improvement efforts across
the value chain.<br>
slide44. 4 - 44 Cost Accounting and the Value Chain A good cost accounting system is critical to
all value-chain functions from research and
development through customer service.<br>
slide45. Activity Based Management<br>
slide46. Activity-Based Management (ABM) Activity-based management (ABM) is a systemwide, integrated approach that focuses management’s attention on activities with the objective of improving customer value and the profit achieved by providing this value.
Activity-based management encompasses both product costing and process value analysis.<br>
slide47. Cost Dimension Process Dimension Driver Analysis Activities Performance Measures Resources Products and
Customers Why? What? How Well? Activity-Based Management Model<br>
slide48. Process Value Analysis Process value analysis is fundamental to activity-based responsibility accounting, focuses on accountability for activities rather than costs, and emphasizes the maximization of systemwide performance instead of individual performance.
Process value analysis is concerned with:
Driver analysis
Activity analysis
Performance measurement<br>
slide49. Activity Analysis Activity analysis should produce four outcomes:
What activities are performed?
How many people perform the activities?
The time and resources required to perform the activities.
An assessment of the value of the activities to the organization, including a recommendation to select and keep only those that add value.<br>
slide50. Value-Added Activities A discretionary activity is classified as value-added provided it simultaneously satisfies three conditions:
The activity produces a change of state.
The change of state was not achievable by preceding activities.
The activity enables other activities to be performed.<br>
slide51. Nonvalue-Added Activities Nonvalue-Added Activities are activities that add cost and impede
performance. Scheduling
Moving
Waiting
Inspecting
Storing Examples<br>
slide52. Activity Analysis Activity elimination
Activity selection
Activity reduction
Activity sharing Activity Analysis Can Reduce Costs in Four Ways:<br>
slide53. Activity Performance Measurement Efficiency
Quality
Time Three Dimensions of Activity Performance<br>
slide54. Measures of Activity Performance Financial measures of activity efficiency include:
Value and nonvalue-added activity cost reports
Trends in activity cost reports
Kaizen standard setting
Benchmarking<br>
slide55. 55 Economic Order Quantity, JIT, and the Theory of Contraints INVENTORY MANAGEMENT<br>
slide56. 56 Learning Objectives Describe the traditional inventory management model.
Describe JIT inventory management.
Explain the basic concepts of constrained optimization.
Describe the theory of constraints, and explain how it can be used to manage inventory.<br>
slide57. 57 Managing Inventories 0 3 6 9 12 Inventory Average Inventory Weeks Inventory, thousands of bricks 60
30<br>
slide58. 58 The Appropriate Inventory Policy Two Basic Questions Must be Addressed How much should be ordered or produced?
When should the order be placed or the setup be performed?<br>
slide59. 59 Inventories As the firm increases its order size, the number of orders falls and therefore the order costs decline. However, an increase in order size also increases the average amount in inventory, so that the carrying cost of inventory rises. The trick is to strike a balance between these two costs.<br>
slide60. 60 Ordering or Setup Costs
Carrying Costs
Stockout Costs Inventory Costs Basics of Traditional Inventory Management<br>
slide61. 61 Inventory Costs Ordering Costs: The costs of placing and receiving an order
Examples: clerical costs, documents, insurance for shipment, and unloading.
Carrying Costs: The costs of carrying inventory
Examples: insurance, inventory taxes, obsolescence, opportunity cost of capital tied up in inventory, and storage.<br>
slide62. 62 Inventory Costs (continued) 3. Stock-Out Costs: The costs of not having sufficient inventory
Examples: lost sales, costs of expediting (extra setup, transportation, etc.) and the costs of interrupted production.
4. Setup Costs: The costs of preparing equipment and facilities so they can be used to produce a particular product or component
Examples: setup labor, lost income (from idled facilities), and test runs. When a firm produces the goods internally, ordering costs are replaced by setup costs.<br>
slide63. 63 Traditional Reasons for Carrying Inventory 1. To balance ordering or setup costs and carrying costs
2. To satisfy customer demand (e.g., meet delivery dates)
3. To avoid shutting down manufacturing facilities because of:
a. machine failure
b. defective parts
c. unavailable parts
d. late delivery of parts<br>
slide64. 64 Traditional Reasons for Carrying Inventory (continued) 4. Unreliable production processes
5. To take advantage of discounts
6. To hedge against future price increases<br>
slide65. 65 Inventories Determination of optimal order size Inventory costs, dollars Order size Total costs Carrying costs Total order costs Optimal
order size<br>
slide66. 66 Total Costs = Ordering costs + Carrying cost
TC = PD/Q + CQ/2
where TC = The total ordering (or setup) and carrying cost
P = The cost of placing and receiving an order (or the cost
of setting up a production run)
Q = The number of units ordered each time an order is
placed (or the lot size for production)
D = The known annual demand
C = The cost of carrying one unit of stock for one year
Economic order quantity (EOQ) = 2PD/C An Inventory Model<br>
slide67. 67 Inventories Economic Order Quantity - Order size that minimizes total inventory costs.<br>
slide68. 68 Economic-Order-Quantity Decision Model The formula for the EOQ model is:
EOQ =
D = Demand in units for a specified time period
P = Relevant ordering costs per purchase order
C = Relevant carrying costs of one unit in
stock for the time period used for D<br>
slide69. 69 An EOQ Illustration EOQ = 2PD/C
D = 1,000 units
Q = 500 units
P = $200 per order
C = $40 per unit
EOQ = (2 x 200 x 10,000) / 40
EOQ = 10,000
EOQ = 100 units<br>
slide70. 70 Economic-Order-Quantity Decision Model What are the relevant total costs?
The formula for relevant total costs (RTC) is: RTC = Annual relevant ordering costs + Annual relevant carrying costs RTC = ( ) × P + ( ) × C = +
Q can be any order quantity, not just EOQ. D
Q Q 2 DP Q QC
2<br>
slide71. 71 Economic-Order-Quantity Decision Model Relevant Total Costs (Dollars) 2,000 4,000 6,000 8,000 10,000 5,434 600 1,200 1,800 2,400 988
EOQ Annual relevant carrying costs Annual relevant total costs Annual relevant ordering costs Order Quantity (Units)<br>
slide72. 72 Considerations in Obtaining Estimates of Relevant Costs Obtaining accurate estimates of the cost parameters used in the EOQ decision model is a challenging task.
What are the relevant incremental costs of carrying inventory?
Only those costs of the purchasing company that change with the quantity of inventory held<br>
slide73. 73 Considerations in Obtaining Estimates of Relevant Costs What is the relevant opportunity cost of capital?
It is the return forgone by investing capital in inventory rather than elsewhere.
It is calculated as the required rate of return multiplied by those costs per unit that vary with the number of units purchased and that are incurred at the time the units are received.<br>
slide74. 74 Costs Associated with Goods for Sale Five categories of costs associated with goods for sale are:
. Purchasing costs
. Ordering costs
. Carrying costs
. Stockout costs
. Quality costs<br>
slide75. 75 Reorder Point When Demand is Certain Reorder point = Rate of usage x Lead time
Example: Assume that the average rate of usage is 4 units per day for a component. Assume also that the time required to place and receive an order is 10 days. What is the reorder point?
Reorder point = 4 x 10 = 40 units
Thus, an order should be placed when inventory drops to 40 units.<br>
slide76. 76 Reorder Point When Demand is Uncertain Reorder point = (Ave. rate of usage x Lead time) +
Safety stock
where:
Safety stock = (Maximum usage - Average usage) x
Lead time<br>
slide77. 77 Reorder Point (continued) Example:
Suppose that the maximum usage is 6 units per day and the average usage is 4 units per day. The lead time is 10 days.
What is the reorder point?
Safety stock = (6 - 4) x 10 = 20 units
Reorder point = (4 x 10) + 20 = 60 units<br>
slide78. 78 Reorder Point 988 494 Weeks 1 2 3 4 5 6 7 8 Reorder Point Reorder Point Lead Time
2 weeks<br>
slide79. 79 Reorder Point (no safety stock) Reorder point = Rate of usage x Lead time 100
80
60
40
20
0 Time ROP<br>
slide80. 80 Safety Stock Safety stock is inventory held at all times regardless of the quantity of inventory ordered using the EOQ model.
Safety stock is used as a buffer against unexpected increases in demand or lead time and unavailability of stock from suppliers.<br>
slide81. 81 Evaluating Managers and Goal-Congruence Issues Goal-congruence issues can arise when there is an inconsistency between the EOQ decision model and the model used to evaluate the performance of the manager implementing the inventory management decisions.<br>
slide82. 82 Traditional versus JIT Inventory Procedures Inventory Control
System 1. Balance setup and carrying costs
2. Satisfy customer demand
3. Avoid manufacturing shutdowns
4. Take advantage of discounts
5. Hedge against future price increases 1. Drive setup and carrying costs to zero
2. Use due-date performance
*3. Total preventive maintenance
*4. Total quality control
*5. The Kanban system Traditional Systems JIT Systems *Rather than holding inventories as a hedge against plant-shutdowns,
JIT attacks the plant-shutdown problem by addressing these issues.<br>
slide83. 83 Just-In-Time Production Systems Just-in-time (JIT) production systems take a “demand pull” approach in which goods are only manufactured to satisfy customer orders.
Demand triggers each step of the production process, starting with customer demand for a finished product at the end of the process, to the demand for direct materials at the beginning of the process.<br>
slide84. 84 Materials Requirement Planning (MRP) Materials requirements planning (MRP) systems take a “push-through” approach that manufactures finished goods for inventory on the basis of demand forecasts.
MRP predetermines the necessary outputs at each stage of production.
Inventory management is a key challenge in an MRP system.<br>
slide85. 85 JIT And Inventory Management Setup and Carrying Costs: The JIT Approach JIT reduces the costs of acquiring inventory to insignificant levels by:
1. Drastically reducing setup time
2. Using long-term contracts for outside purchases
Carrying costs are reduced to insignificant levels by reducing inventories to insignificant levels<br>
slide86. 86 JIT And Inventory Management Due-Date Performance: The JIT Solution Lead times are reduced so that the company can meet requested delivery dates and to respond quickly to customer demand.
Lead times are reduced by:
reducing setup times
improving quality
using cellular manufacturing<br>
slide87. 87 JIT And Inventory Management Avoidance of Shutdown: The JIT Approach Total preventive maintenance to reduce machine failures
Total quality control to reduce defective parts
Cultivation of supplier relationships to ensure availability of quality raw materials and subassemblies
The use of the Kanban system is also essential<br>
slide88. 88 JIT And Inventory Management Discounts and Price Increases: JIT Purchasing Versus Holding Inventories Careful vendor selection
Long-term contracts with vendors
Prices are stipulated (usually producing a significant savings)
Quality is stipulated
The number of orders placed are reduced<br>
slide89. 89 Major Features of a JIT System The five major features of a JIT system are:
Organizing production in manufacturing cells
Hiring and retaining multi-skilled workers
Emphasizing total quality management
Reducing manufacturing lead time and setup Time
Building strong supplier relationships<br>
slide90. 90 Benefits of JIT Systems Benefits of JIT production:
Lower carrying costs of inventory
Eliminating the root causes of rework, scrap, waste, and manufacturing lead time.<br>
slide91. 91 Performance Measures and Control in JIT Production To manage and reduce inventories, the management accountant must design performance measures to control and evaluate JIT production.
What information may management accountants use?
Personal observation by production line workers and managers
Financial performance measures, such as inventory turnover ratios<br>
slide92. 92 Performance Measures and Control in JIT Production What are nonfinancial performance measures of time, inventory, and quality?
Manufacturing lead time
Units produced per hour
Days’ inventory on hand
Total setup time for machines/Total manufacturing time
Number of units requiring rework or scrap/Total number of units started and completed<br>
slide93. 93 Backflush Costing A unique production system such as JIT often leads to its own unique costing system.
Organizing manufacturing in cells, reducing defects and manufacturing lead time, and ensuring timely delivery of materials enables purchasing, production, and sales to occur in quick succession with minimal inventories.<br>
slide94. 94 Backflush Costing Where journal entries for one or more stages in the cycle are omitted, the journal entries for a subsequent stage use normal or standard costs to work backward to flush out the costs in the cycle for which journal entries were not made.<br>
slide95. 95 Trigger Points Stage A: Purchase of direct materials
Stage B: Production resulting in work in process
Stage C: Completion of a good finished unit or
product
Stage D: Sale of finished goods<br>
slide96. 96 Trigger Points Assume trigger points A, C, and D.
This company would have two inventory accounts:
Type Account Title 1. Combined materials Inventory: Material and materials in work-in- and In-Process process inventory Control
2. Finished goods Finished Goods Control<br>
slide97. 97 Trigger Points Assume trigger points A and D.
This company would have one inventory account:
Type Account Title Combines direct materials Inventory inventory and any direct Control materials in work-in-process and finished goods inventories<br>
slide98. 98 Special Considerations in Backflush Costing Backflush costing does not necessarily comply with GAAP
However, inventory levels may be immaterial, negating the necessity for compliance
Backflush costing does not leave a good audit trail – the ability of the accounting system to pinpoint the uses of resources at each step of the production process<br>
slide99. 99 What is the Kanban System? A Card System is used to monitor work-in-process A withdrawal Kanban
A production Kanban
A vendor Kanban<br>
slide100. 100 The Withdrawal Kanban Item No. TVD-114 Preceding Process
Item Name LCD Screen Computer Assembly
Computer Type Compaq 4/25
Box Capacity 12 Subsequent Process
Box Type AD-1942 Final Assembly<br>
slide101. 101 The Production Kanban Item No. TVD-114 Process
Item Name LCD Screen Computer Assembly
Computer Type Compaq 4/25
Box Capacity 12
Box Type ___AD-1942<br>
slide102. 102 The Vendor Kanban Item No. TVD-114 Name of Receiving Company
Item Name Computer Chassis Type Black Plastic
Box Capacity 12
Box Type Cardboard--Type Receiving Gate North Receiving Gate
Time to Deliver 8:30 A.M., 12:30 P.M., 2:30 P.M.
Name of Vendor Hovey Supply Company<br>
slide103. 103 The Kanban Process Withdrawal
Store LCD Screen
Withdrawal Lot with P-Kanban Production
Ordering Post (6) Signal LCD Assembly Remove
(4) P-Kanban
Attach to
Post (5) Attach
W-Kanban (1) Remove
W-Kanban
Attach to
Post Withdrawal Post (2), (3) (7) Final Assembly (1)<br>
slide104. 104 Multiple Constrained Resource To the Thurman Company example for a one constrained resource, add the following additional constraint: the market limits sales of the economy disk player to 3,000 units.
Formulate the linear programming problem and solve using the graphical method Let X1 = deluxe models and X2 = economy models
Formulation: Max CM = 40X1 + 25X2
Subject to: 4X + 2X2 < 20,000
X2 < 3,000<br>
slide105. 105 Multiple Constrained Resource (continued) 10,000 3,000 A 5,000 D C B X X 4X +2X < 20,000 X < 3,000 1 1 2 2 2<br>
slide106. 106 Multiple Constrained Resource (continued) Corner Point X1 X2 CM = 40X1 + 25X2
A 0 0 0
B 5,000 0 $200,000
C* 3,500 3,000 $215,000
D 0 3,000 $75,000
* Point C is optimal
The X1 value of point c is found by substituting the second equation into the first one like so:
$X1 + 2 (3,000) = 20,000
4X1 + 6,000 = 20,000
4X1 =14,000
X1 = 3,500<br>
slide107. 107 Throughput
Inventory
Operating expenses Three Measures of Systems Performance Theory of Constraints<br>
slide108. 108 The Theory of Constraints (continued) Five steps to improve performance:
1. Identify an organization’s constraints.
2. Exploit the binding constraints.
3. Subordinate everything else to the decisions made in Step 2.
4. Elevate the organization’s binding constraints.
5. Repeat the process as a new constraint emerges to limit output.<br>
slide109. 109 Theory of Constraints A sequential process of identifying and removing constraints in a system. Restrictions or barriers that impede progress toward an objective<br>
slide110. 110 Theory of Constraints The theory of constraints emphasizes the management of bottlenecks as the key to improving the performance of the production system as a whole.<br>
slide111. 111 Methods to Relieve Bottlenecks Eliminate idle time at the bottleneck operation
Process only those parts or products that increase throughput contribution, not parts or products that will remain in finished goods or spare parts inventories
Shift products that do not have to be made on the bottleneck operation to nonbottleneck processes, or to outside processing facilities<br>
slide112. 112 Methods to Relieve Bottlenecks Reduce setup time and processing time at bottleneck operations
Improve the quality of parts or products manufactured at the bottleneck operation<br>
slide113. 113 Theory of Constraints The objective of TOC is to increase throughput contribution while decreasing investments and operating costs.
TOC considers a short-run time horizon and assumes operating costs to be fixed costs.<br>
slide114. 114 The Drum-Buffer-Rope System Initial Process Process A Process B Drummer Process Raw Materials Process C Final Process Rope Time Buffer Finished Goods<br>
slide115. 115 The Management of Capacity Managers can reduce capacity-based fixed costs by measuring and managing unused capacity
Unused Capacity is the amount of productive capacity available over and above the productive capacity employed to meet consumer demand in the current period<br>
slide116. 116 Analysis of Unused Capacity Two Important Features:
Engineered Costs result from a cause-and-effect relationship between output and the resources used to produce that output
Discretionary Costs have two parts:
They arise from periodic (annual) decisions regarding the maximum amount to be incurred
They have no measurable cause-and-effect relationship between output and resources used<br>
slide117. 117 Managing Unused Capacity Downsizing (Rightsizing) is an integrated approach of configuring processes, products, and people to match costs to the activities that need to be performed to operate effectively and efficiently in the present and future
Because identifying unused capacity for discretionary costs is difficult, downsizing, or otherwise managing this unused capacity, is also difficult.<br>
slide118. 118 End of Week<br>