
Bond Valuation Global Financial Management


Description: Bond Valuation Global Financial Management Campbell R. Harvey Fuqua School of Business Duke University charveymail.duke.edu http:www.duke.educharvey Definition of a Bond A bond is a security that obligates the issuer to make specified
Related Topics
Download Presentation
"Bond Valuation Global Financial Management" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Bond Valuation Global Financial Management
Campbell R. Harvey
Fuqua School of Business
Duke University
charvey@mail.duke.edu
http://www.duke.edu/~charvey<br>
slide2. Definition of a Bond A bond is a security that obligates the issuer to make specified interest and principal payments to the holder on specified dates.
Coupon rate
Face value (or par)
Maturity (or term)
Bonds are sometimes called fixed income securities.<br>
slide3. Types of Bonds Pure Discount or Zero-Coupon Bonds
Pay no coupons prior to maturity.
Pay the bond’s face value at maturity.
Coupon Bonds
Pay a stated coupon at periodic intervals prior to maturity.
Pay the bond’s face value at maturity.
Perpetual Bonds (Consols)
No maturity date.
Pay a stated coupon at periodic intervals.<br>
slide4. Types of Bonds Self-Amortizing Bonds
Pay a regular fixed amount each payment period over the life of the bond.
Principal repaid over time rather than at maturity.<br>
slide5. Bond Issuers Federal Government and its Agencies
Local Municipalities
Corporations<br>
slide6. U.S. Government Bonds Treasury Bills
No coupons (zero coupon security)
Face value paid at maturity
Maturities up to one year
Treasury Notes
Coupons paid semiannually
Face value paid at maturity
Maturities from 2-10 years<br>
slide7. U.S. Government Bonds Treasury Bonds
Coupons paid semiannually
Face value paid at maturity
Maturities over 10 years
The 30-year bond is called the long bond.
Treasury Strips
Zero-coupon bond
Created by “stripping” the coupons and principal from Treasury bonds and notes.<br>
slide8. Agencies Bonds Mortgage-Backed Bonds
Bonds issued by U.S. Government agencies that are backed by a pool of home mortgages.
Self-amortizing bonds.
Maturities up to 20 years.<br>
slide9. U.S. Government Bonds No default risk. Considered to be riskfree.
Exempt from state and local taxes.
Sold regularly through a network of primary dealers.
Traded regularly in the over-the-counter market.<br>
slide10. Municipal Bonds Maturities from one month to 40 years.
Exempt from federal, state, and local taxes.
Generally two types:
Revenue bonds
General Obligation bonds
Riskier than U.S. Government bonds.<br>
slide11. Corporate Bonds Secured Bonds (Asset-Backed)
Secured by real property
Ownership of the property reverts to the bondholders upon default.
Debentures
General creditors
Have priority over stockholders, but are subordinate to secured debt.<br>
slide12. Common Features of Corporate Bonds Senior versus subordinated bonds
Convertible bonds
Callable bonds
Putable bonds
Sinking funds<br>
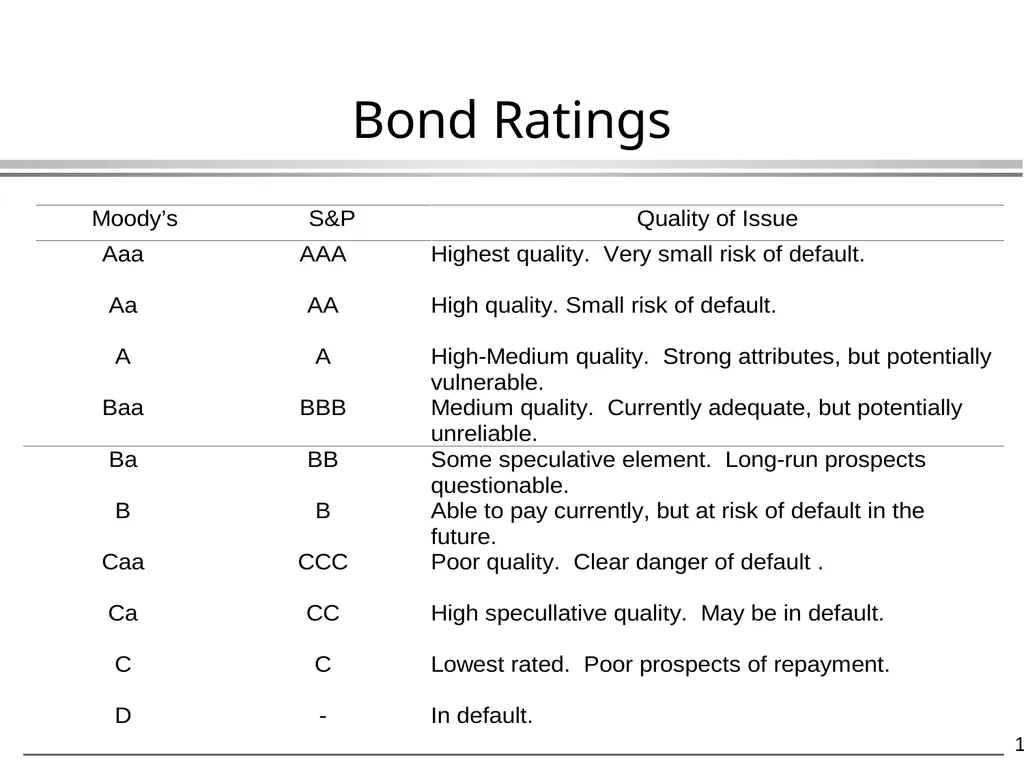
slide13. Bond Ratings<br>
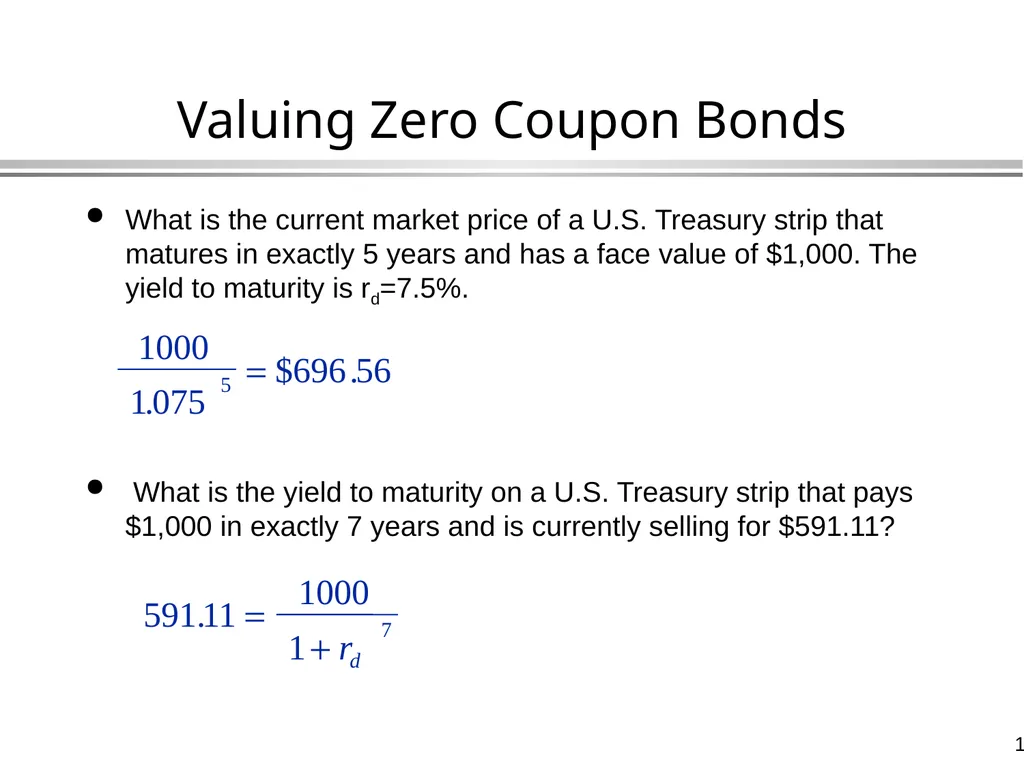
slide14. Valuing Zero Coupon Bonds What is the current market price of a U.S. Treasury strip that matures in exactly 5 years and has a face value of $1,000. The yield to maturity is rd=7.5%.
What is the yield to maturity on a U.S. Treasury strip that pays $1,000 in exactly 7 years and is currently selling for $591.11?<br>
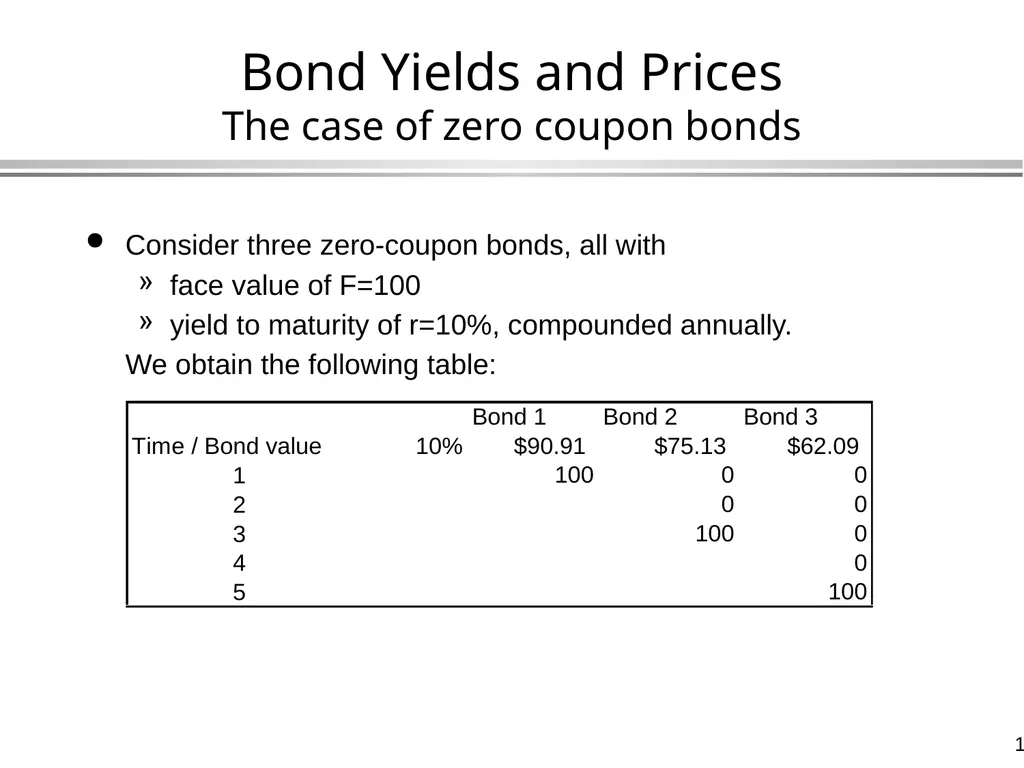
slide15. Bond Yields and Prices The case of zero coupon bonds Consider three zero-coupon bonds, all with
face value of F=100
yield to maturity of r=10%, compounded annually.
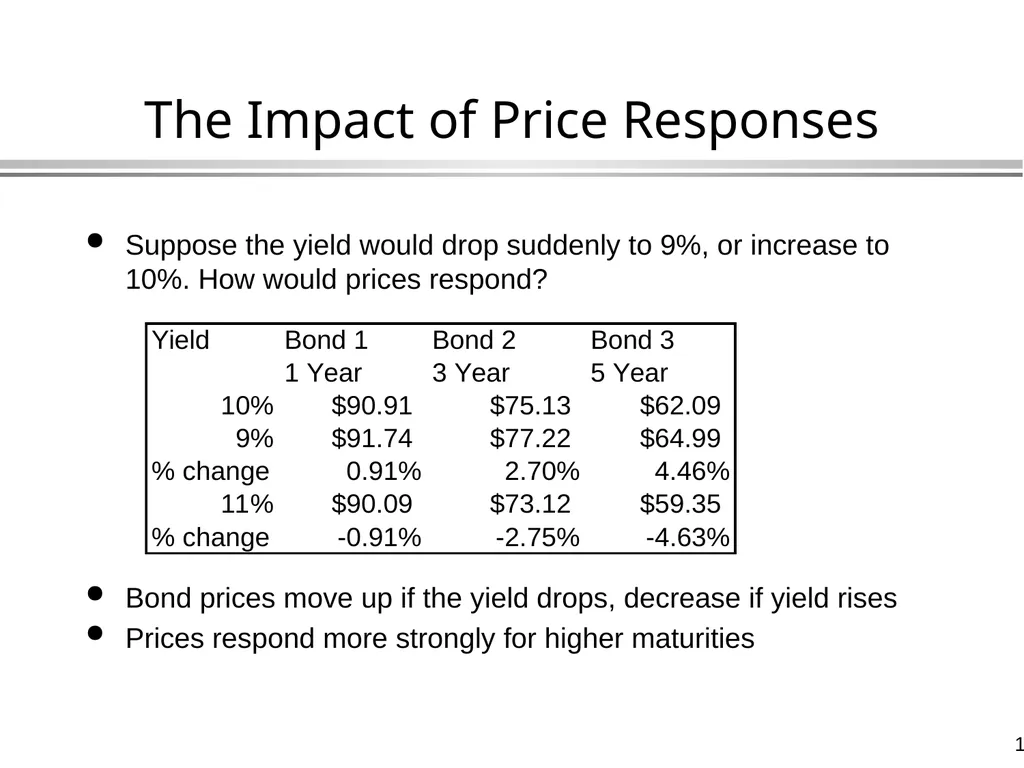
We obtain the following table:<br>
slide16. Suppose the yield would drop suddenly to 9%, or increase to 10%. How would prices respond?
Bond prices move up if the yield drops, decrease if yield rises
Prices respond more strongly for higher maturities The Impact of Price Responses<br>
slide17. What is the market price of a U.S. Treasury bond that has a coupon rate of 9%, a face value of $1,000 and matures exactly 10 years from today if the required yield to maturity is 10% compounded semiannually?
0 6 12 18 24 ... 120 Months
45 45 45 45 1045 Bond Valuation: An Example<br>
slide18. What is the market price of a U.S. Treasury bond that has a coupon rate of 9%, a face value of $1,000 and matures exactly 10 years from today if the required yield to maturity is 10% compounded semiannually?
0 1 2 3 4 ... n
C C C C C+F Valuing Coupon Bonds The General Formula<br>
slide19. Bond Yields and Prices The case of coupon bonds Suppose you purchase the U.S. Treasury bond described earlier and immediately thereafter interest rates fall so that the new yield to maturity on the bond is 8% compounded semiannually. What is the bond’s new market price?
Suppose the interest rises, so that the new yield is 12% compounded semiannually. What is the market price now?
Suppose the interest equals the coupon rate of 9%. What do you observe?
Note:
Coupon bonds can be regarded as portfolios of zero-coupon bonds (how?)
What implication does this have for price responses?<br>
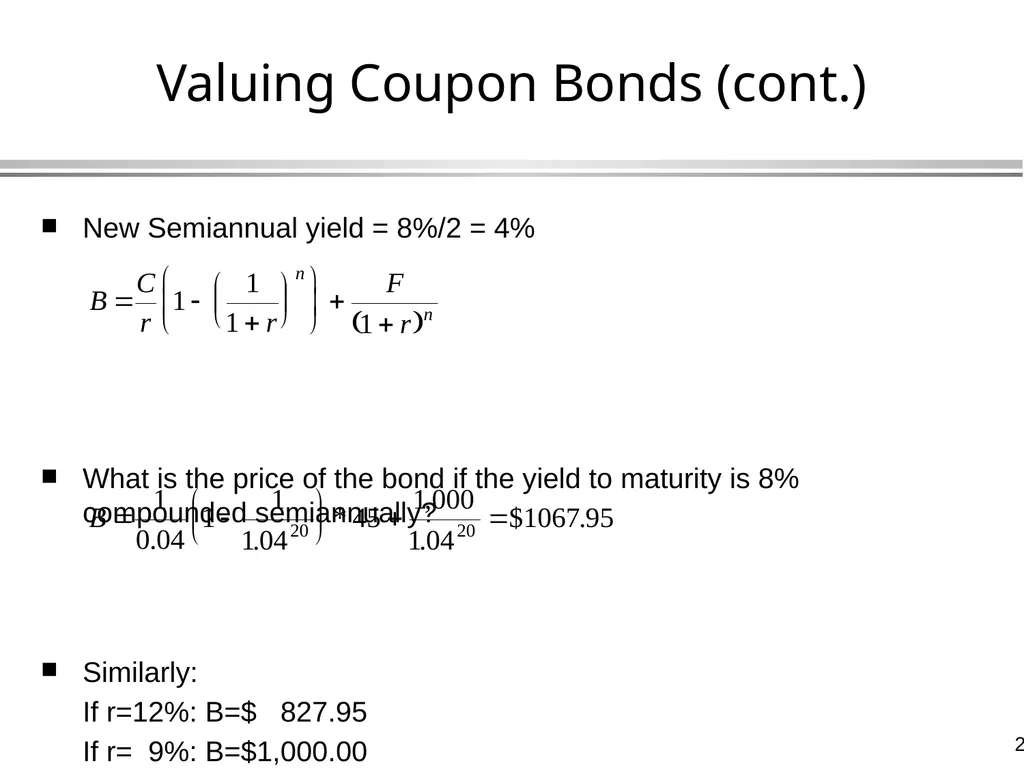
slide20. New Semiannual yield = 8%/2 = 4%
What is the price of the bond if the yield to maturity is 8% compounded semiannually?
Similarly:
If r=12%: B=$ 827.95
If r= 9%: B=$1,000.00 Valuing Coupon Bonds (cont.)<br>
slide21. Relationship Between Bond Prices and Yields Bond prices are inversely related to interest rates (or yields).
A bond sells at par only if its coupon rate equals the coupon rate
A bond sells at a premium if its coupon is above the coupon rate.
A bond sells a a discount if its coupon is below the coupon rate.<br>
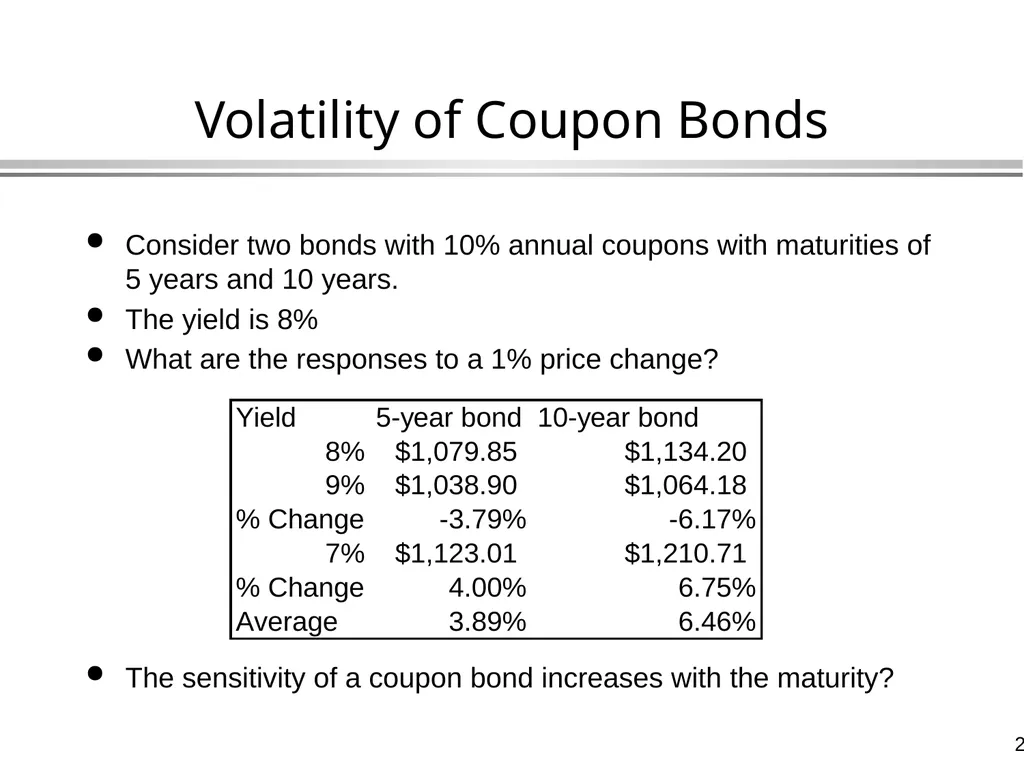
slide22. Volatility of Coupon Bonds Consider two bonds with 10% annual coupons with maturities of 5 years and 10 years.
The yield is 8%
What are the responses to a 1% price change?
The sensitivity of a coupon bond increases with the maturity?<br>
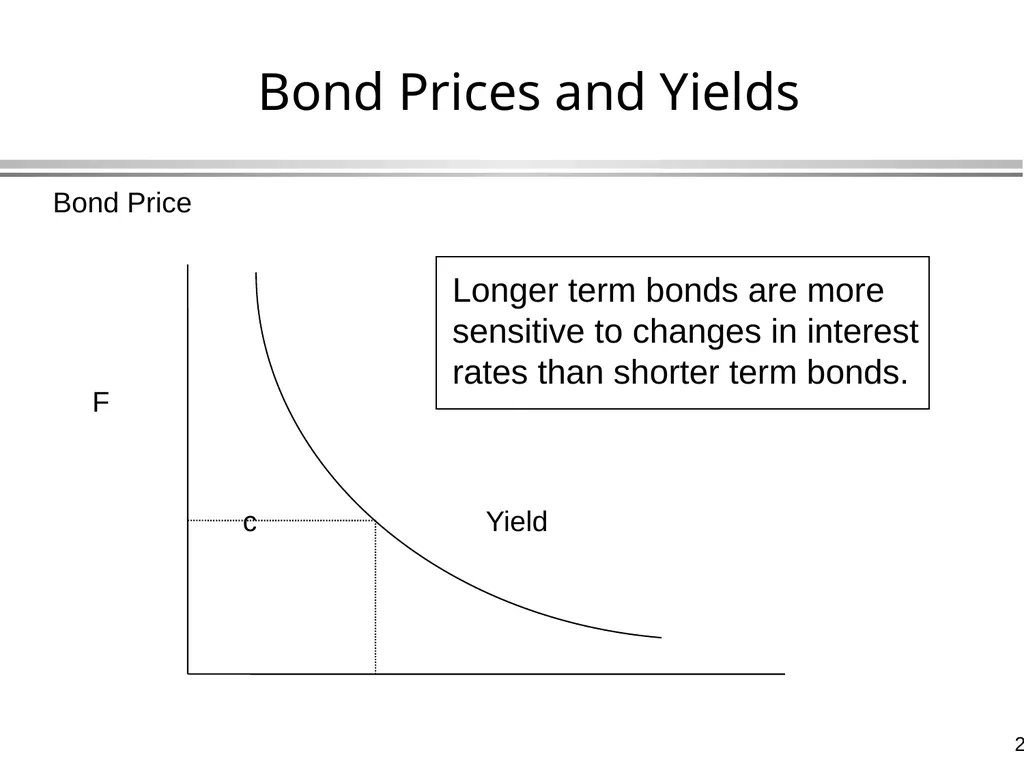
slide23. Bond Prices and Yields Bond Price
F
c Yield Longer term bonds are more
sensitive to changes in interest
rates than shorter term bonds.<br>
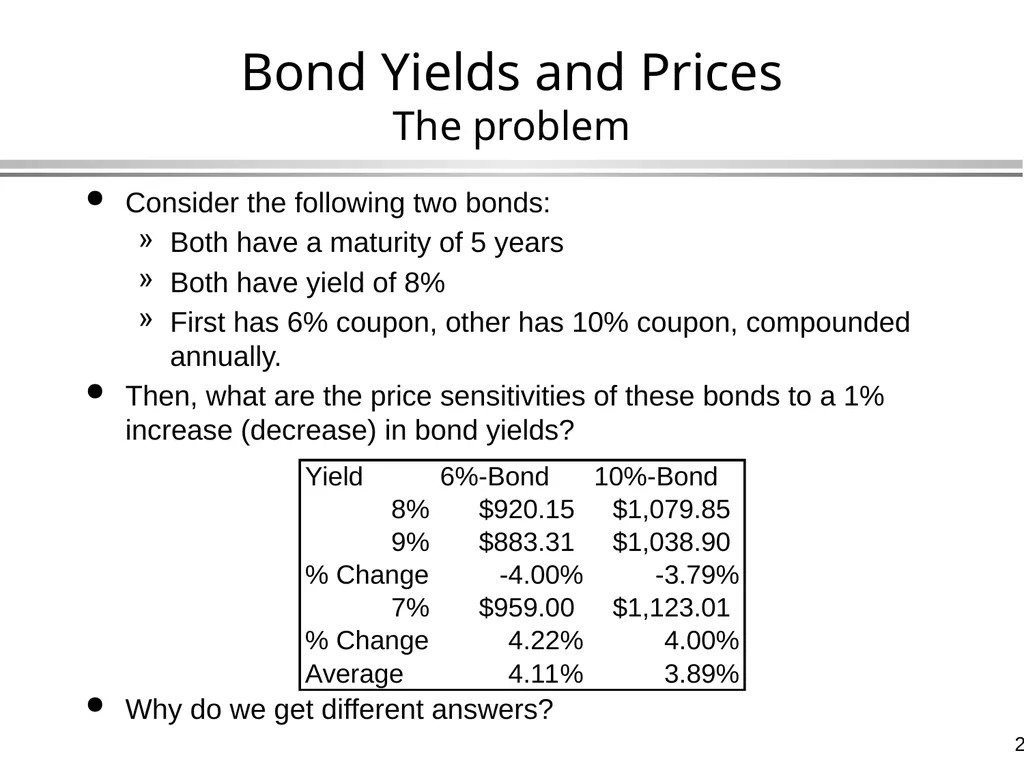
slide24. Consider the following two bonds:
Both have a maturity of 5 years
Both have yield of 8%
First has 6% coupon, other has 10% coupon, compounded annually.
Then, what are the price sensitivities of these bonds to a 1% increase (decrease) in bond yields?
Why do we get different answers? Bond Yields and Prices The problem<br>
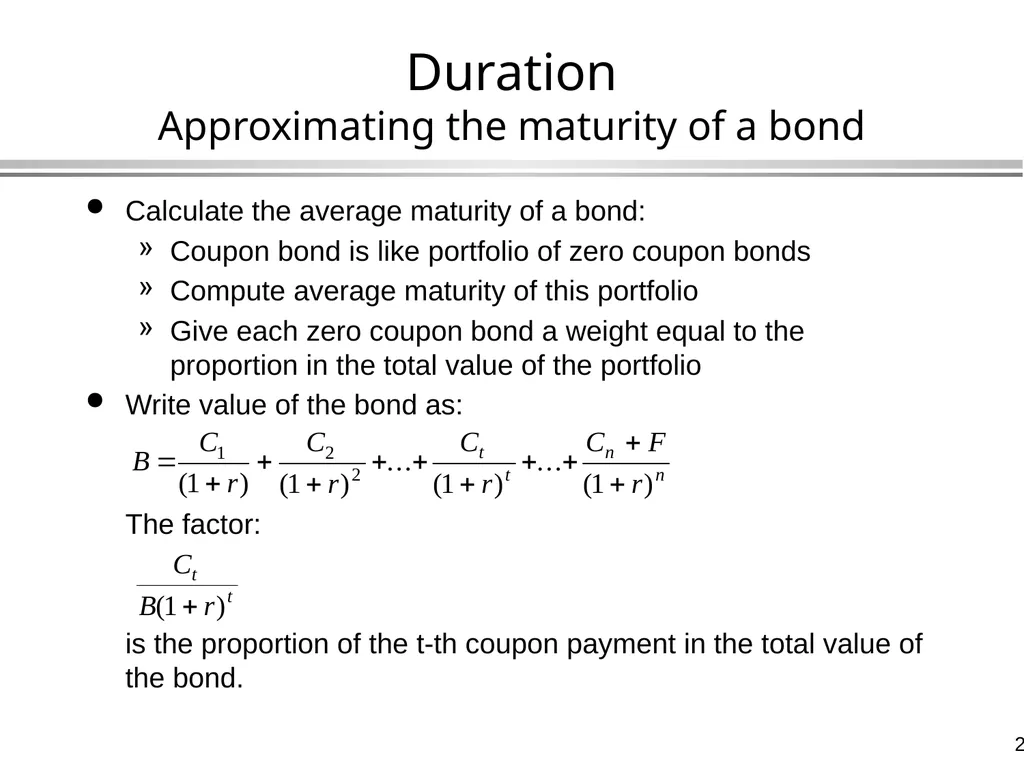
slide25. Calculate the average maturity of a bond:
Coupon bond is like portfolio of zero coupon bonds
Compute average maturity of this portfolio
Give each zero coupon bond a weight equal to the proportion in the total value of the portfolio
Write value of the bond as:
The factor:
is the proportion of the t-th coupon payment in the total value of the bond. Duration Approximating the maturity of a bond<br>
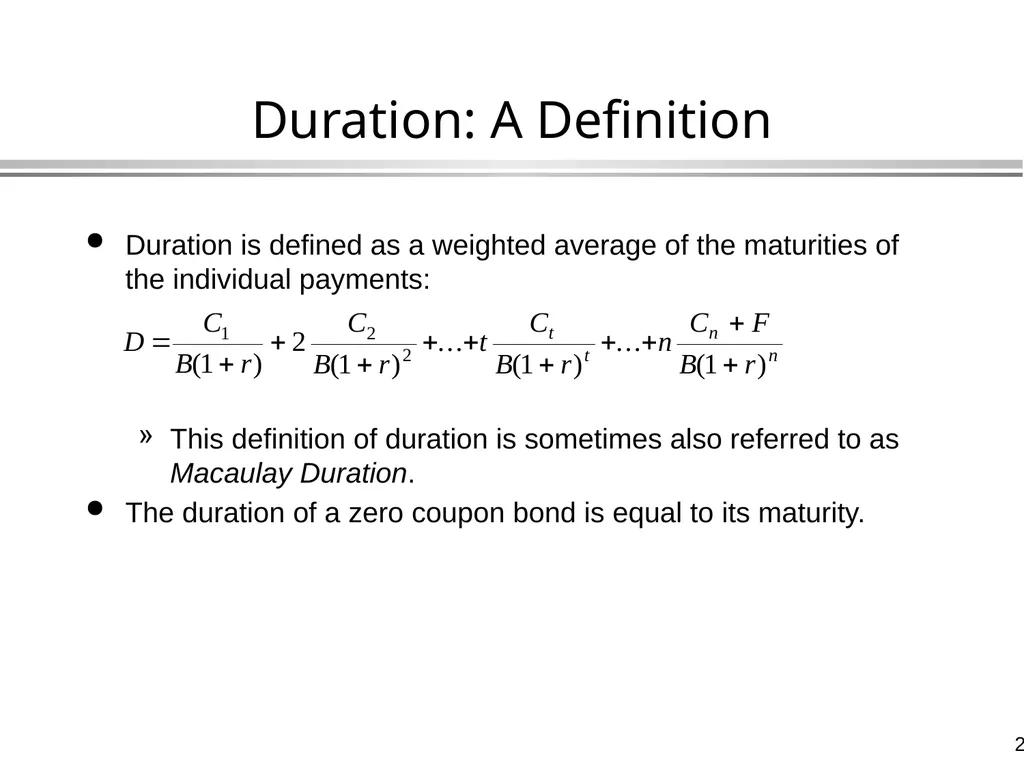
slide26. Duration is defined as a weighted average of the maturities of the individual payments:
This definition of duration is sometimes also referred to as Macaulay Duration.
The duration of a zero coupon bond is equal to its maturity. Duration: A Definition<br>
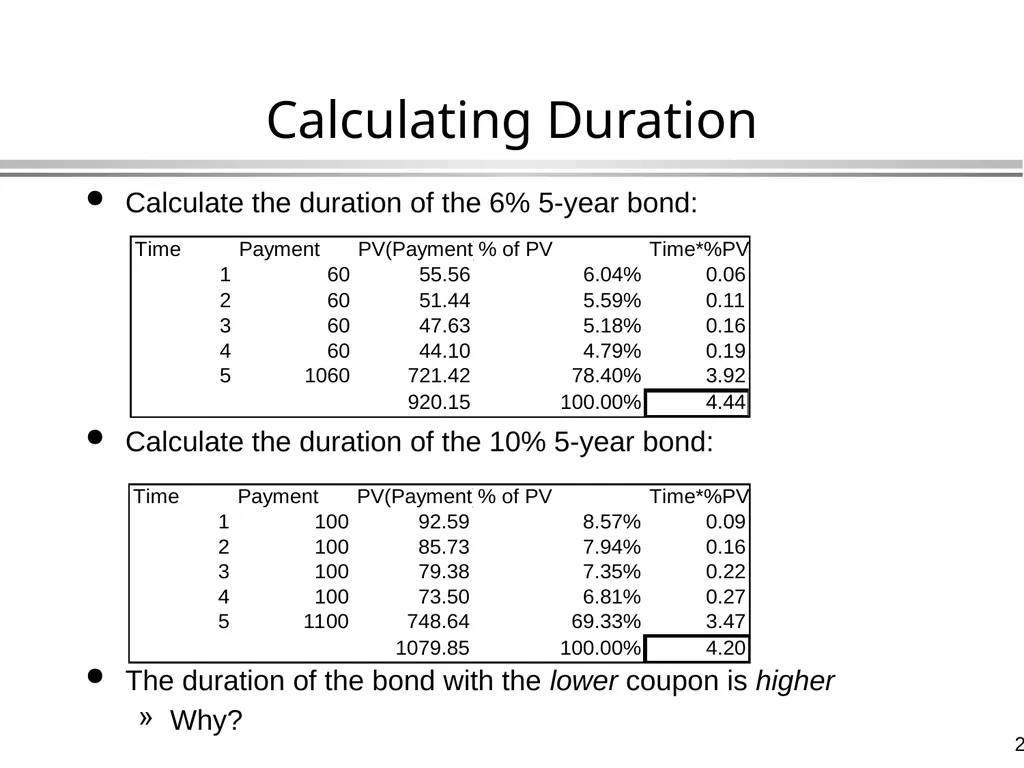
slide27. Calculate the duration of the 6% 5-year bond:
Calculate the duration of the 10% 5-year bond:
The duration of the bond with the lower coupon is higher
Why? Calculating Duration<br>
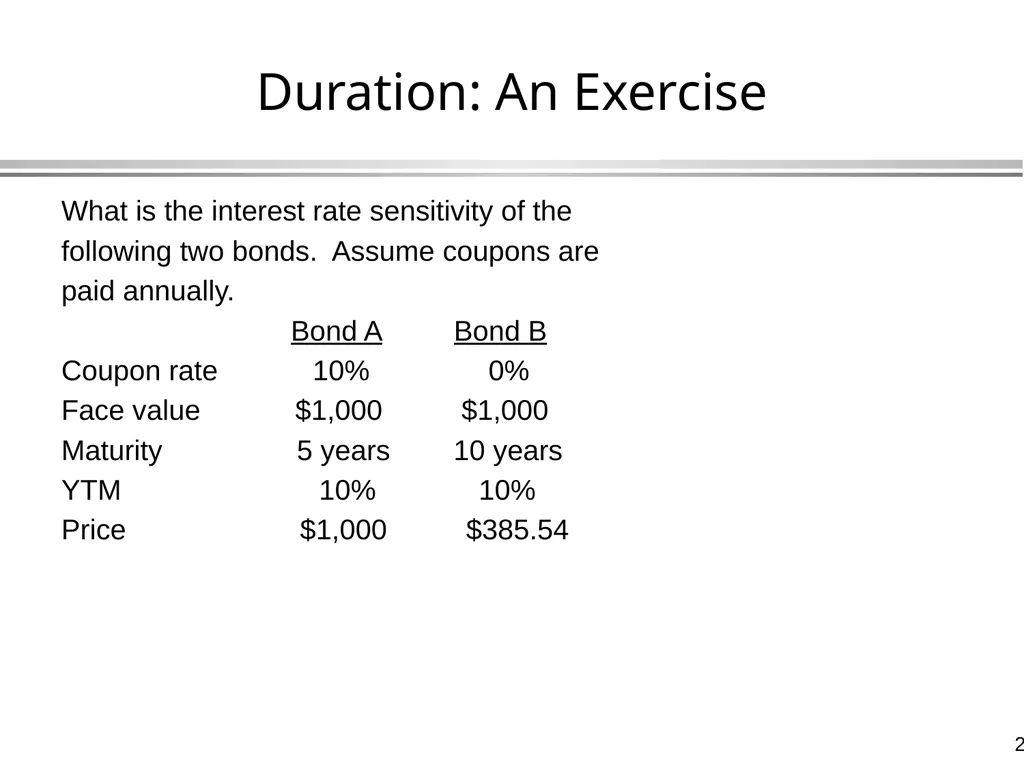
slide28. Duration: An Exercise What is the interest rate sensitivity of the
following two bonds. Assume coupons are
paid annually.
Bond A Bond B
Coupon rate 10% 0%
Face value $1,000 $1,000
Maturity 5 years 10 years
YTM 10% 10%
Price $1,000 $385.54<br>
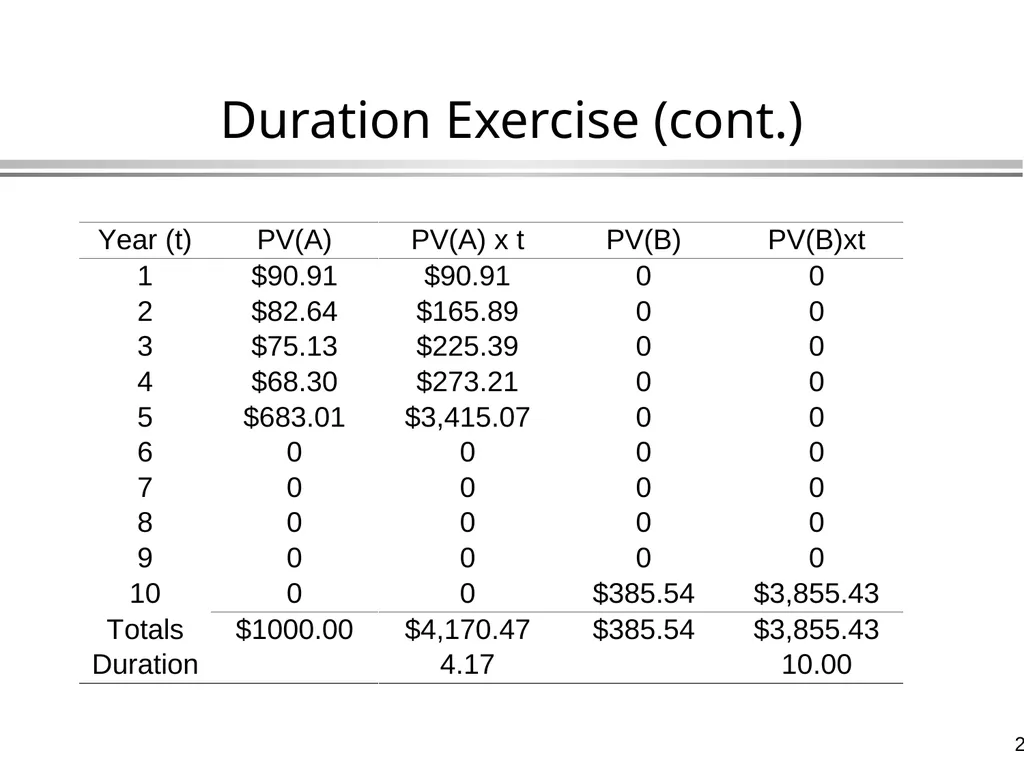
slide29. Duration Exercise (cont.)<br>
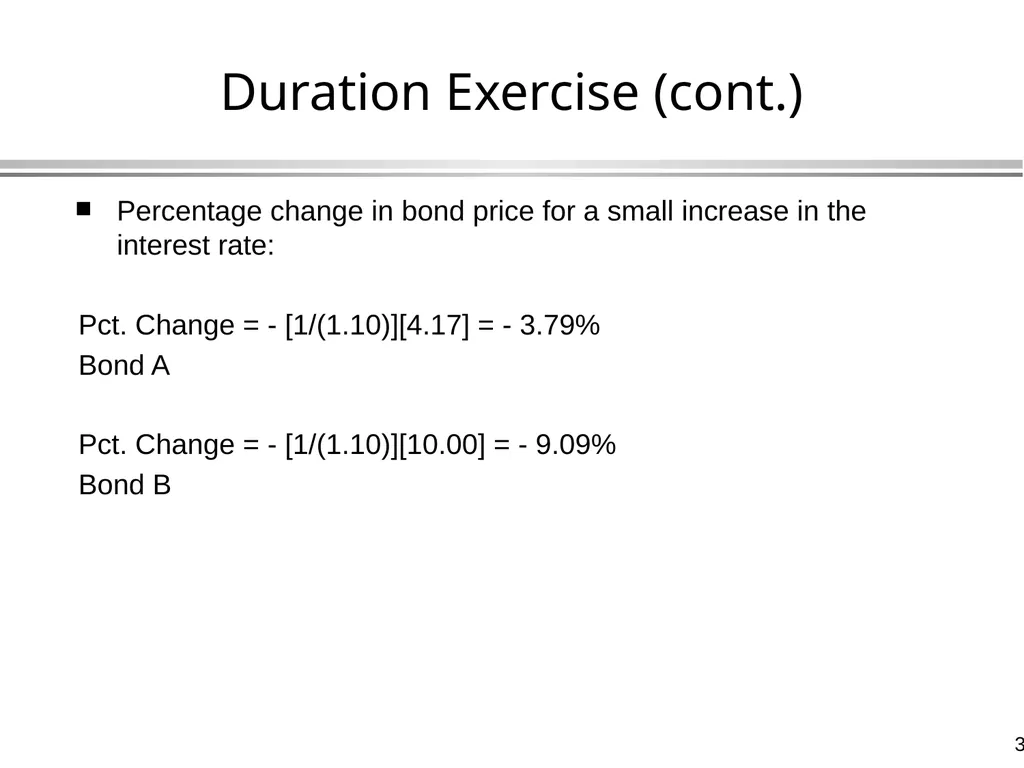
slide30. Duration Exercise (cont.) Percentage change in bond price for a small increase in the interest rate:
Pct. Change = - [1/(1.10)][4.17] = - 3.79%
Bond A
Pct. Change = - [1/(1.10)][10.00] = - 9.09%
Bond B<br>
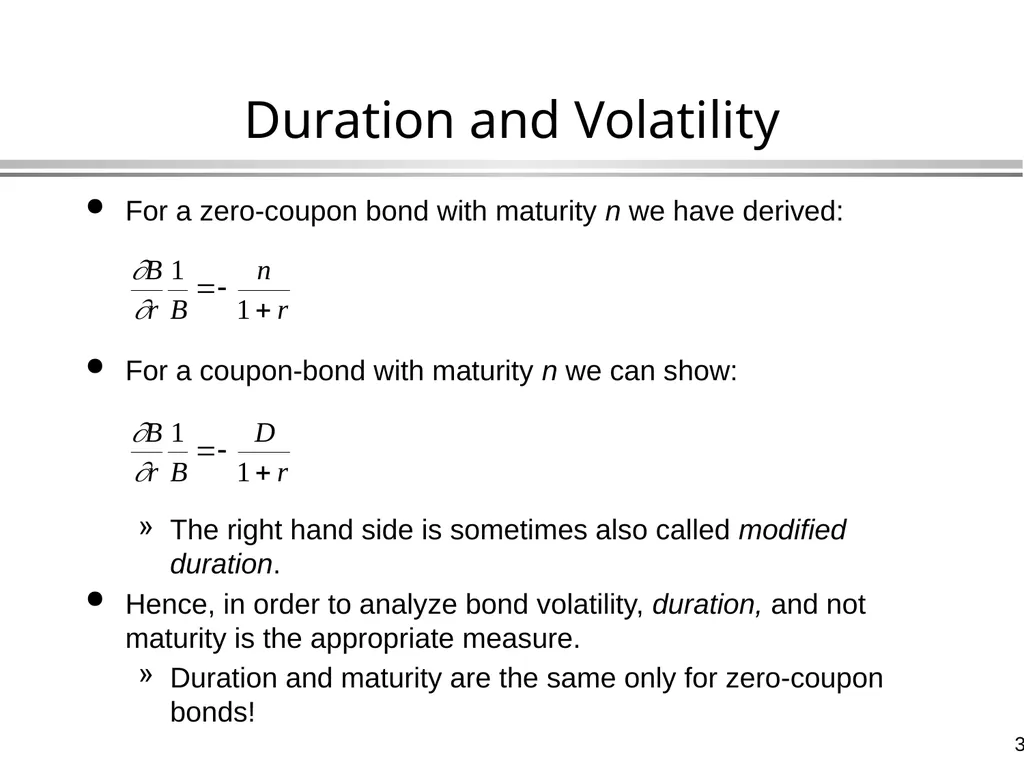
slide31. For a zero-coupon bond with maturity n we have derived:
For a coupon-bond with maturity n we can show:
The right hand side is sometimes also called modified duration.
Hence, in order to analyze bond volatility, duration, and not maturity is the appropriate measure.
Duration and maturity are the same only for zero-coupon bonds! Duration and Volatility<br>
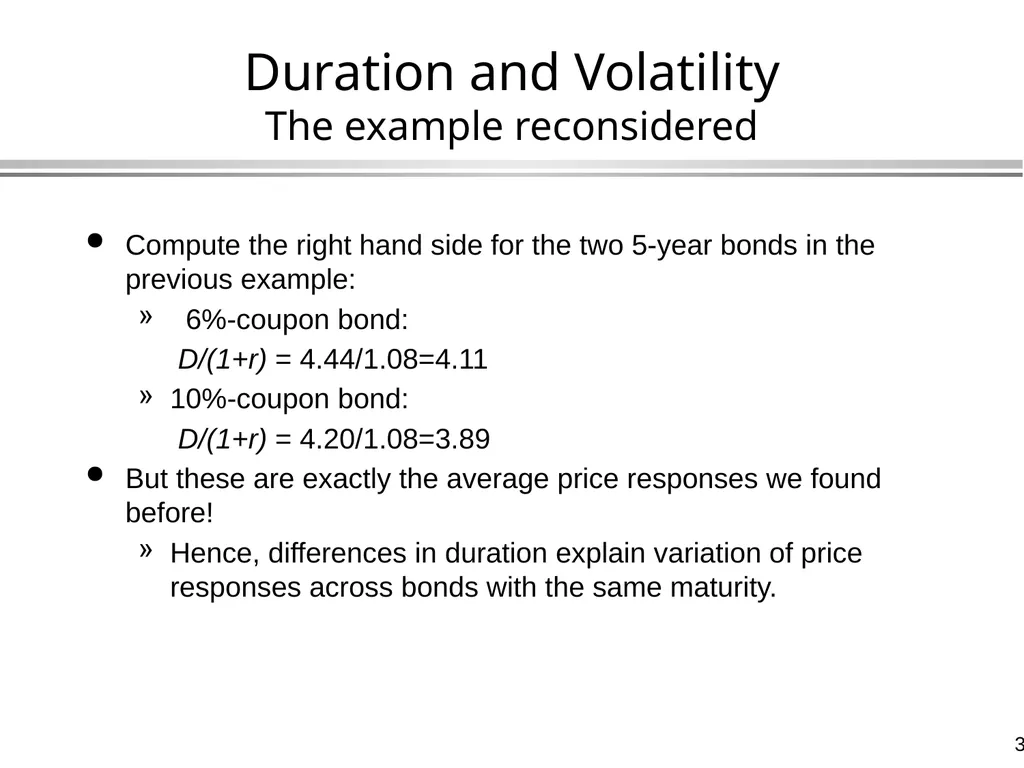
slide32. Duration and Volatility The example reconsidered Compute the right hand side for the two 5-year bonds in the previous example:
6%-coupon bond:
D/(1+r) = 4.44/1.08=4.11
10%-coupon bond:
D/(1+r) = 4.20/1.08=3.89
But these are exactly the average price responses we found before!
Hence, differences in duration explain variation of price responses across bonds with the same maturity.<br>
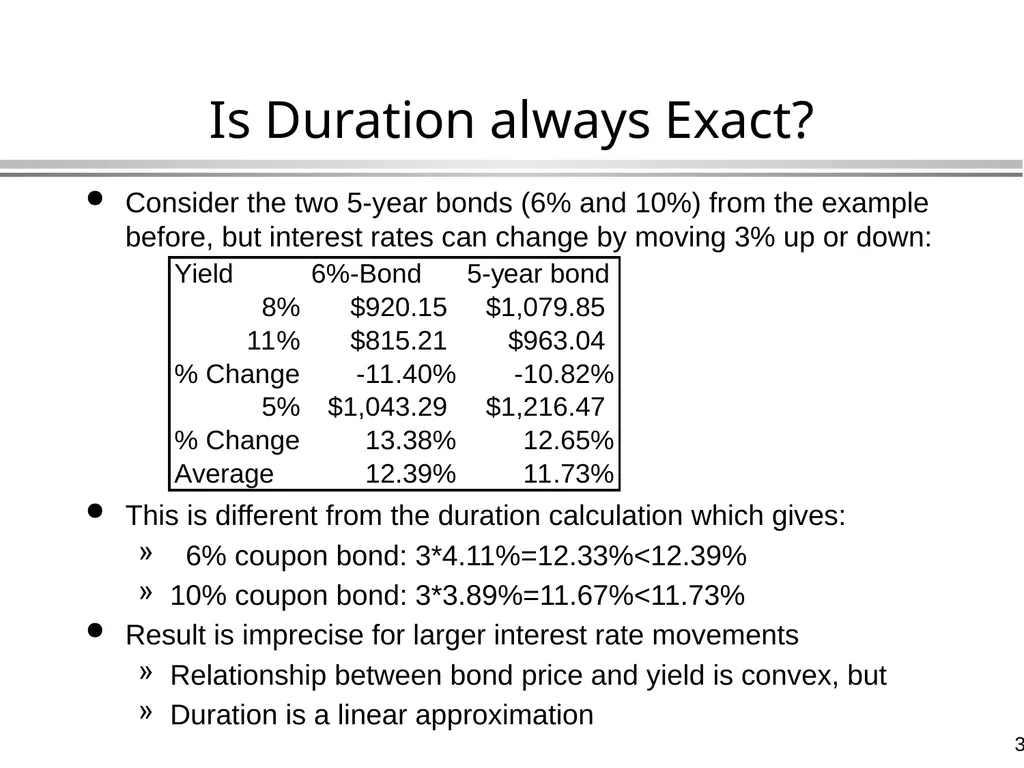
slide33. Is Duration always Exact? Consider the two 5-year bonds (6% and 10%) from the example before, but interest rates can change by moving 3% up or down:
This is different from the duration calculation which gives:
6% coupon bond: 3*4.11%=12.33%<12.39%
10% coupon bond: 3*3.89%=11.67%<11.73%
Result is imprecise for larger interest rate movements
Relationship between bond price and yield is convex, but
Duration is a linear approximation<br>
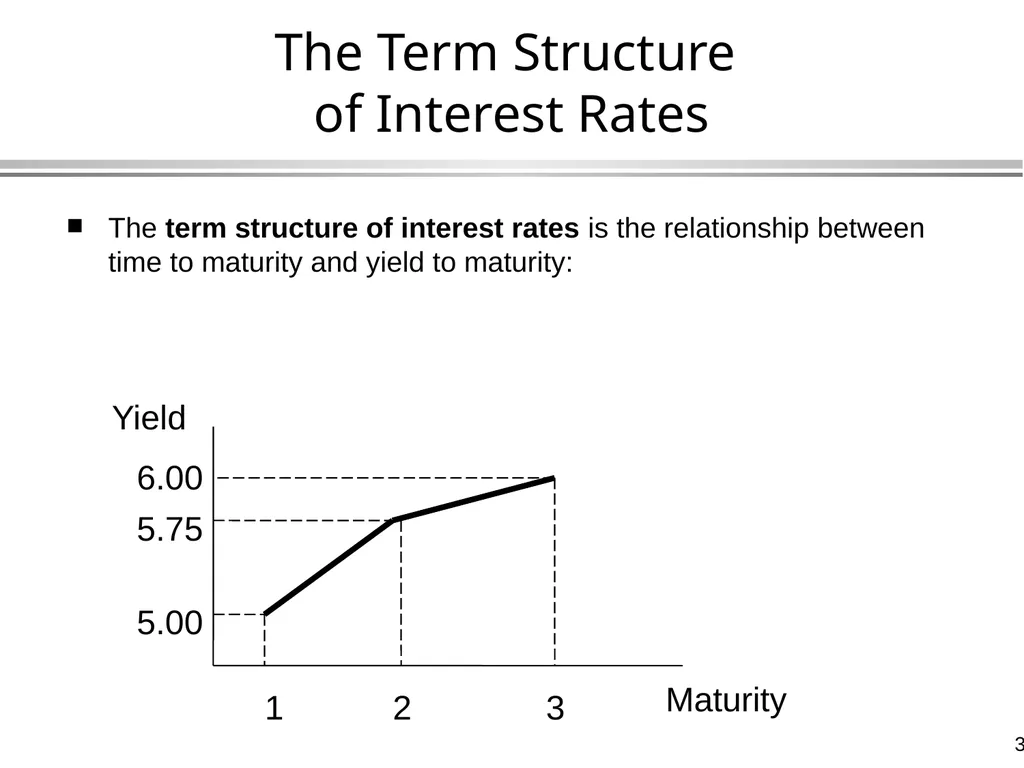
slide34. The Term Structure of Interest Rates The term structure of interest rates is the relationship between time to maturity and yield to maturity: Yield Maturity 1 2 3 5.00 5.75 6.00<br>
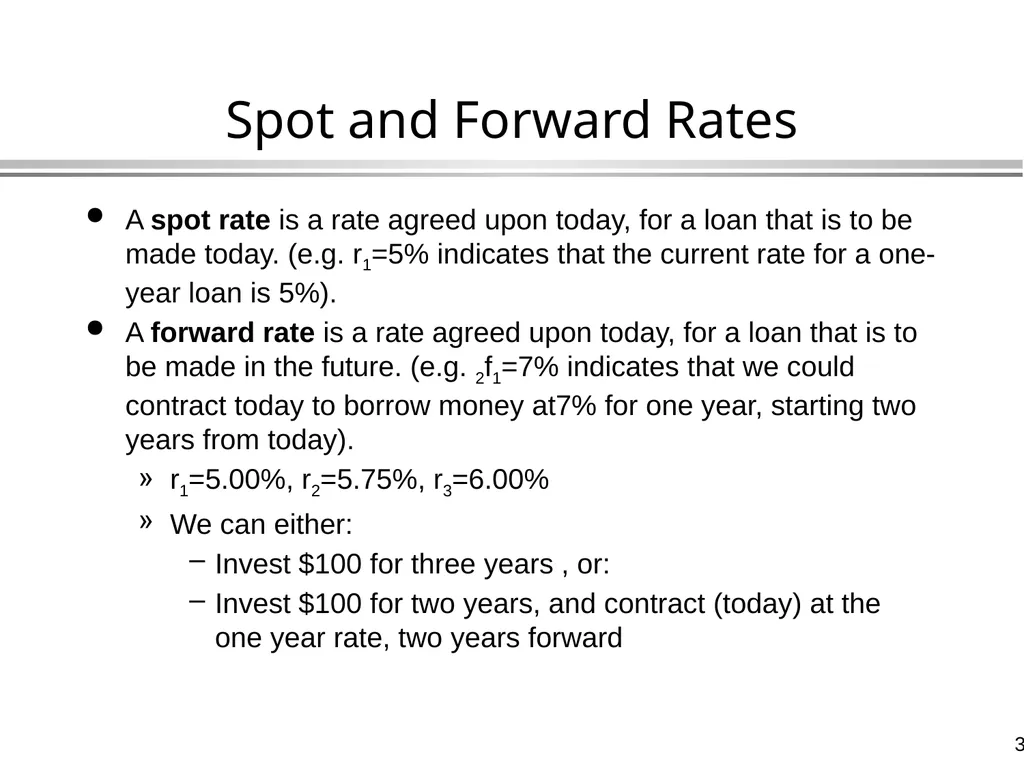
slide35. Spot and Forward Rates A spot rate is a rate agreed upon today, for a loan that is to be made today. (e.g. r1=5% indicates that the current rate for a one-year loan is 5%).
A forward rate is a rate agreed upon today, for a loan that is to be made in the future. (e.g. 2f1=7% indicates that we could contract today to borrow money at7% for one year, starting two years from today).
r1=5.00%, r2=5.75%, r3=6.00%
We can either:
Invest $100 for three years , or:
Invest $100 for two years, and contract (today) at the one year rate, two years forward<br>
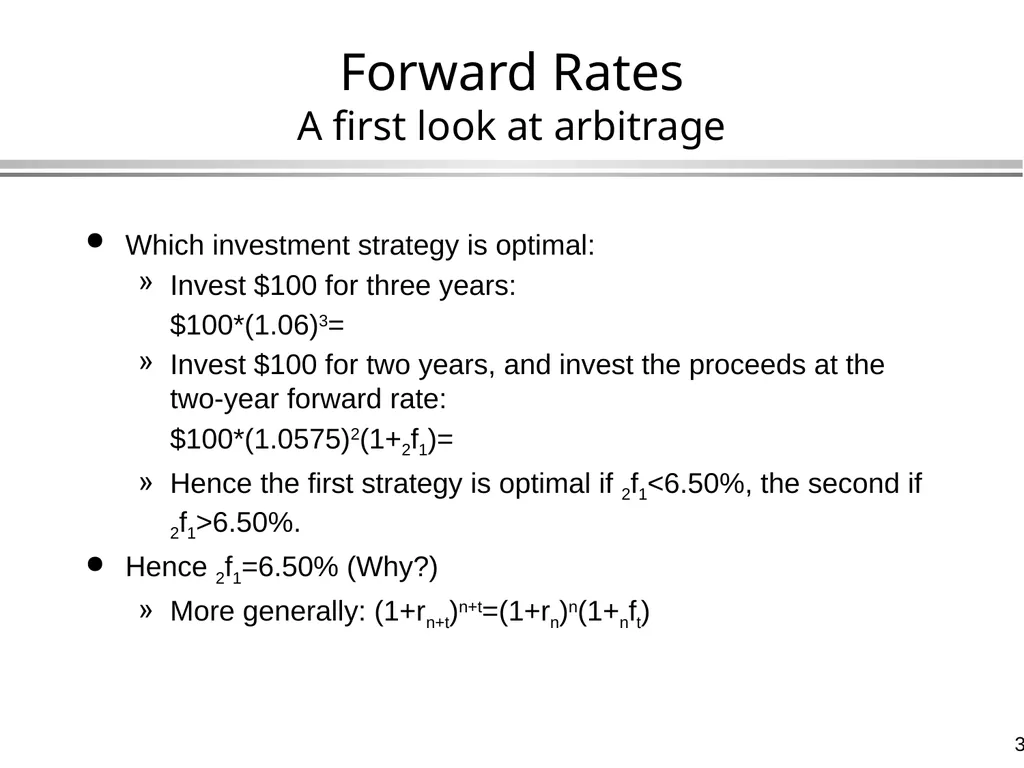
slide36. Forward Rates A first look at arbitrage Which investment strategy is optimal:
Invest $100 for three years:
$100*(1.06)3=
Invest $100 for two years, and invest the proceeds at the two-year forward rate:
$100*(1.0575)2(1+2f1)=
Hence the first strategy is optimal if 2f1<6.50%, the second if 2f1>6.50%.
Hence 2f1=6.50% (Why?)
More generally: (1+rn+t)n+t=(1+rn)n(1+nft)<br>
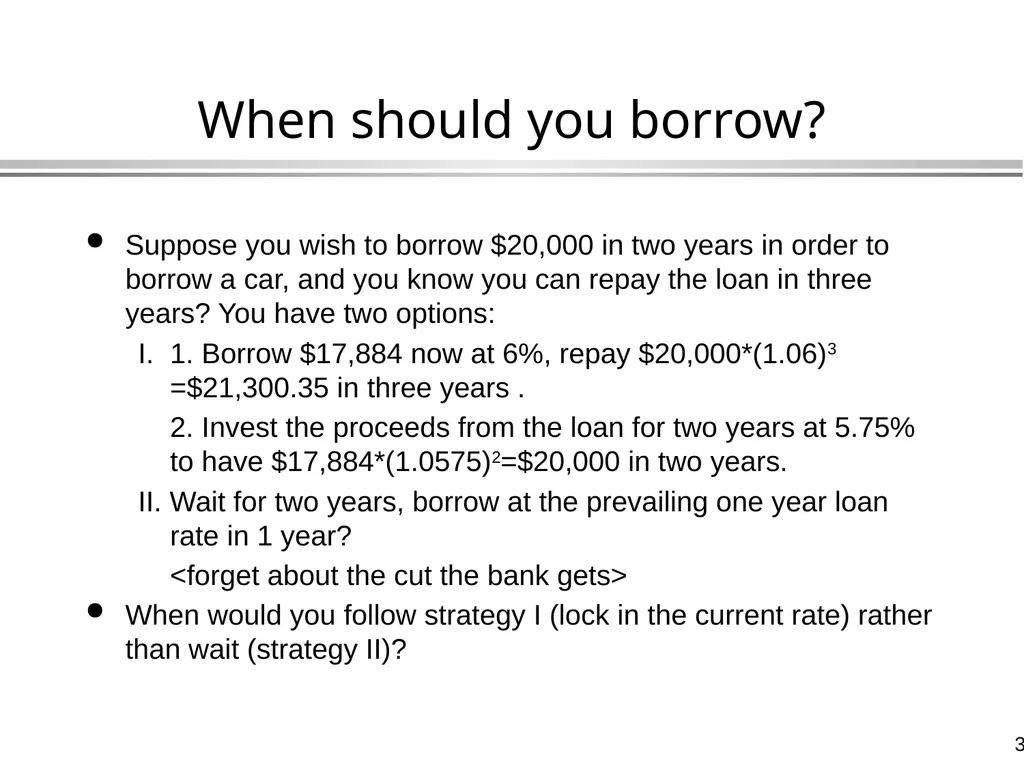
slide37. When should you borrow? Suppose you wish to borrow $20,000 in two years in order to borrow a car, and you know you can repay the loan in three years? You have two options:
I. 1. Borrow $17,884 now at 6%, repay $20,000*(1.06)3 =$21,300.35 in three years .
2. Invest the proceeds from the loan for two years at 5.75% to have $17,884*(1.0575)2=$20,000 in two years.
II. Wait for two years, borrow at the prevailing one year loan rate in 1 year?
<forget about the cut the bank gets>
When would you follow strategy I (lock in the current rate) rather than wait (strategy II)?<br>
slide38. When to borrow (cont.) If you lock in the current rate, then you secure a borrowing rate of:
$ 21,300.35/$20,000=1.065, i. e. 6.5%
This is exactly the forward rate we calculated above
Why?
Hence, you would borrow and lock in rates now, if you expect that the one-year interest rate is going to be higher than 6.5% i 1999.
When would you set the cut-off rate for waiting higher? (lower?)
If everybody invests this way, then the forward rate equals the expected future spot rate.
Why?<br>
slide39. Summary Bonds can be valued by discounting future cash flows at the yield to maturity
Bond prices changes inverse with yield
Price response of bond to interest rates depends on term to maturity.
Works well for zero-coupon bond
Coupon bonds are like portfolios of zero-coupon bonds
Need duration as “average maturity” for coupon bonds
Only an approximation
The term structure implies terms for future borrowing:
Forward rates
Compare with expected future spot rates<br>
Campbell R. Harvey
Fuqua School of Business
Duke University
charvey@mail.duke.edu
http://www.duke.edu/~charvey<br>
slide2. Definition of a Bond A bond is a security that obligates the issuer to make specified interest and principal payments to the holder on specified dates.
Coupon rate
Face value (or par)
Maturity (or term)
Bonds are sometimes called fixed income securities.<br>
slide3. Types of Bonds Pure Discount or Zero-Coupon Bonds
Pay no coupons prior to maturity.
Pay the bond’s face value at maturity.
Coupon Bonds
Pay a stated coupon at periodic intervals prior to maturity.
Pay the bond’s face value at maturity.
Perpetual Bonds (Consols)
No maturity date.
Pay a stated coupon at periodic intervals.<br>
slide4. Types of Bonds Self-Amortizing Bonds
Pay a regular fixed amount each payment period over the life of the bond.
Principal repaid over time rather than at maturity.<br>
slide5. Bond Issuers Federal Government and its Agencies
Local Municipalities
Corporations<br>
slide6. U.S. Government Bonds Treasury Bills
No coupons (zero coupon security)
Face value paid at maturity
Maturities up to one year
Treasury Notes
Coupons paid semiannually
Face value paid at maturity
Maturities from 2-10 years<br>
slide7. U.S. Government Bonds Treasury Bonds
Coupons paid semiannually
Face value paid at maturity
Maturities over 10 years
The 30-year bond is called the long bond.
Treasury Strips
Zero-coupon bond
Created by “stripping” the coupons and principal from Treasury bonds and notes.<br>
slide8. Agencies Bonds Mortgage-Backed Bonds
Bonds issued by U.S. Government agencies that are backed by a pool of home mortgages.
Self-amortizing bonds.
Maturities up to 20 years.<br>
slide9. U.S. Government Bonds No default risk. Considered to be riskfree.
Exempt from state and local taxes.
Sold regularly through a network of primary dealers.
Traded regularly in the over-the-counter market.<br>
slide10. Municipal Bonds Maturities from one month to 40 years.
Exempt from federal, state, and local taxes.
Generally two types:
Revenue bonds
General Obligation bonds
Riskier than U.S. Government bonds.<br>
slide11. Corporate Bonds Secured Bonds (Asset-Backed)
Secured by real property
Ownership of the property reverts to the bondholders upon default.
Debentures
General creditors
Have priority over stockholders, but are subordinate to secured debt.<br>
slide12. Common Features of Corporate Bonds Senior versus subordinated bonds
Convertible bonds
Callable bonds
Putable bonds
Sinking funds<br>
slide13. Bond Ratings<br>
slide14. Valuing Zero Coupon Bonds What is the current market price of a U.S. Treasury strip that matures in exactly 5 years and has a face value of $1,000. The yield to maturity is rd=7.5%.
What is the yield to maturity on a U.S. Treasury strip that pays $1,000 in exactly 7 years and is currently selling for $591.11?<br>
slide15. Bond Yields and Prices The case of zero coupon bonds Consider three zero-coupon bonds, all with
face value of F=100
yield to maturity of r=10%, compounded annually.
We obtain the following table:<br>
slide16. Suppose the yield would drop suddenly to 9%, or increase to 10%. How would prices respond?
Bond prices move up if the yield drops, decrease if yield rises
Prices respond more strongly for higher maturities The Impact of Price Responses<br>
slide17. What is the market price of a U.S. Treasury bond that has a coupon rate of 9%, a face value of $1,000 and matures exactly 10 years from today if the required yield to maturity is 10% compounded semiannually?
0 6 12 18 24 ... 120 Months
45 45 45 45 1045 Bond Valuation: An Example<br>
slide18. What is the market price of a U.S. Treasury bond that has a coupon rate of 9%, a face value of $1,000 and matures exactly 10 years from today if the required yield to maturity is 10% compounded semiannually?
0 1 2 3 4 ... n
C C C C C+F Valuing Coupon Bonds The General Formula<br>
slide19. Bond Yields and Prices The case of coupon bonds Suppose you purchase the U.S. Treasury bond described earlier and immediately thereafter interest rates fall so that the new yield to maturity on the bond is 8% compounded semiannually. What is the bond’s new market price?
Suppose the interest rises, so that the new yield is 12% compounded semiannually. What is the market price now?
Suppose the interest equals the coupon rate of 9%. What do you observe?
Note:
Coupon bonds can be regarded as portfolios of zero-coupon bonds (how?)
What implication does this have for price responses?<br>
slide20. New Semiannual yield = 8%/2 = 4%
What is the price of the bond if the yield to maturity is 8% compounded semiannually?
Similarly:
If r=12%: B=$ 827.95
If r= 9%: B=$1,000.00 Valuing Coupon Bonds (cont.)<br>
slide21. Relationship Between Bond Prices and Yields Bond prices are inversely related to interest rates (or yields).
A bond sells at par only if its coupon rate equals the coupon rate
A bond sells at a premium if its coupon is above the coupon rate.
A bond sells a a discount if its coupon is below the coupon rate.<br>
slide22. Volatility of Coupon Bonds Consider two bonds with 10% annual coupons with maturities of 5 years and 10 years.
The yield is 8%
What are the responses to a 1% price change?
The sensitivity of a coupon bond increases with the maturity?<br>
slide23. Bond Prices and Yields Bond Price
F
c Yield Longer term bonds are more
sensitive to changes in interest
rates than shorter term bonds.<br>
slide24. Consider the following two bonds:
Both have a maturity of 5 years
Both have yield of 8%
First has 6% coupon, other has 10% coupon, compounded annually.
Then, what are the price sensitivities of these bonds to a 1% increase (decrease) in bond yields?
Why do we get different answers? Bond Yields and Prices The problem<br>
slide25. Calculate the average maturity of a bond:
Coupon bond is like portfolio of zero coupon bonds
Compute average maturity of this portfolio
Give each zero coupon bond a weight equal to the proportion in the total value of the portfolio
Write value of the bond as:
The factor:
is the proportion of the t-th coupon payment in the total value of the bond. Duration Approximating the maturity of a bond<br>
slide26. Duration is defined as a weighted average of the maturities of the individual payments:
This definition of duration is sometimes also referred to as Macaulay Duration.
The duration of a zero coupon bond is equal to its maturity. Duration: A Definition<br>
slide27. Calculate the duration of the 6% 5-year bond:
Calculate the duration of the 10% 5-year bond:
The duration of the bond with the lower coupon is higher
Why? Calculating Duration<br>
slide28. Duration: An Exercise What is the interest rate sensitivity of the
following two bonds. Assume coupons are
paid annually.
Bond A Bond B
Coupon rate 10% 0%
Face value $1,000 $1,000
Maturity 5 years 10 years
YTM 10% 10%
Price $1,000 $385.54<br>
slide29. Duration Exercise (cont.)<br>
slide30. Duration Exercise (cont.) Percentage change in bond price for a small increase in the interest rate:
Pct. Change = - [1/(1.10)][4.17] = - 3.79%
Bond A
Pct. Change = - [1/(1.10)][10.00] = - 9.09%
Bond B<br>
slide31. For a zero-coupon bond with maturity n we have derived:
For a coupon-bond with maturity n we can show:
The right hand side is sometimes also called modified duration.
Hence, in order to analyze bond volatility, duration, and not maturity is the appropriate measure.
Duration and maturity are the same only for zero-coupon bonds! Duration and Volatility<br>
slide32. Duration and Volatility The example reconsidered Compute the right hand side for the two 5-year bonds in the previous example:
6%-coupon bond:
D/(1+r) = 4.44/1.08=4.11
10%-coupon bond:
D/(1+r) = 4.20/1.08=3.89
But these are exactly the average price responses we found before!
Hence, differences in duration explain variation of price responses across bonds with the same maturity.<br>
slide33. Is Duration always Exact? Consider the two 5-year bonds (6% and 10%) from the example before, but interest rates can change by moving 3% up or down:
This is different from the duration calculation which gives:
6% coupon bond: 3*4.11%=12.33%<12.39%
10% coupon bond: 3*3.89%=11.67%<11.73%
Result is imprecise for larger interest rate movements
Relationship between bond price and yield is convex, but
Duration is a linear approximation<br>
slide34. The Term Structure of Interest Rates The term structure of interest rates is the relationship between time to maturity and yield to maturity: Yield Maturity 1 2 3 5.00 5.75 6.00<br>
slide35. Spot and Forward Rates A spot rate is a rate agreed upon today, for a loan that is to be made today. (e.g. r1=5% indicates that the current rate for a one-year loan is 5%).
A forward rate is a rate agreed upon today, for a loan that is to be made in the future. (e.g. 2f1=7% indicates that we could contract today to borrow money at7% for one year, starting two years from today).
r1=5.00%, r2=5.75%, r3=6.00%
We can either:
Invest $100 for three years , or:
Invest $100 for two years, and contract (today) at the one year rate, two years forward<br>
slide36. Forward Rates A first look at arbitrage Which investment strategy is optimal:
Invest $100 for three years:
$100*(1.06)3=
Invest $100 for two years, and invest the proceeds at the two-year forward rate:
$100*(1.0575)2(1+2f1)=
Hence the first strategy is optimal if 2f1<6.50%, the second if 2f1>6.50%.
Hence 2f1=6.50% (Why?)
More generally: (1+rn+t)n+t=(1+rn)n(1+nft)<br>
slide37. When should you borrow? Suppose you wish to borrow $20,000 in two years in order to borrow a car, and you know you can repay the loan in three years? You have two options:
I. 1. Borrow $17,884 now at 6%, repay $20,000*(1.06)3 =$21,300.35 in three years .
2. Invest the proceeds from the loan for two years at 5.75% to have $17,884*(1.0575)2=$20,000 in two years.
II. Wait for two years, borrow at the prevailing one year loan rate in 1 year?
<forget about the cut the bank gets>
When would you follow strategy I (lock in the current rate) rather than wait (strategy II)?<br>
slide38. When to borrow (cont.) If you lock in the current rate, then you secure a borrowing rate of:
$ 21,300.35/$20,000=1.065, i. e. 6.5%
This is exactly the forward rate we calculated above
Why?
Hence, you would borrow and lock in rates now, if you expect that the one-year interest rate is going to be higher than 6.5% i 1999.
When would you set the cut-off rate for waiting higher? (lower?)
If everybody invests this way, then the forward rate equals the expected future spot rate.
Why?<br>
slide39. Summary Bonds can be valued by discounting future cash flows at the yield to maturity
Bond prices changes inverse with yield
Price response of bond to interest rates depends on term to maturity.
Works well for zero-coupon bond
Coupon bonds are like portfolios of zero-coupon bonds
Need duration as “average maturity” for coupon bonds
Only an approximation
The term structure implies terms for future borrowing:
Forward rates
Compare with expected future spot rates<br>