
BRITACOM Virtual Seminar Improving and expanding
Description: BRITACOM Virtual Seminar Improving and expanding tax treaty rules on international transport June, 24 2021 Guglielmo Maisto BRITACOM Advisory Board Professor of International and Comparative Tax Law Università Cattolica di Piacenza Founding
Related Topics
Download Presentation
"BRITACOM Virtual Seminar Improving and expanding" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. BRITACOM Virtual Seminar
Improving and expanding tax treaty rules on international transport
June, 24 2021 Guglielmo Maisto
BRITACOM Advisory Board
Professor of International and Comparative Tax Law
Università Cattolica di Piacenza
Founding Partner of Maisto e Associati<br>
slide2. The international transport tax landscape The key role of transport within the Belt and Road Initiative (BRI)
- Six Economic transport corridors connecting Asia with Europe
- Investment in roads, railways, ports and other infrastructures
- Taxation of transport and the impact on supply chains
- Difficulty of apportioning income from international transportation
Special domestic tax regimes
Tax treaties rules (Art. 8 OECD and UN Model Tax Conventions)
Exception to the general distributive rule on business profits 2<br>
slide3. Issues arising under article 8 of the OECD and UN Model Conventions Taxation of transportation by railway and road not covered by tax treaties
Income from intermodal transportation (i.e. derived from the combined use of different means of transport) not covered
Multilateral transport situations are not covered
Scope of transportation income covered by treaties is either unclear or not consistent (e.g. leasing of containers) 3<br>
slide4. Issues arising under article 8 of the OECD and UN Model Conventions Domestic privileged tax regimes are generally limited to shipping and not applied to road or railway transport
Privileged tax regimes may prevent treaty eligibility (“liability to tax” condition)
Treaty relief may be subject to burdensome formalities 4<br>
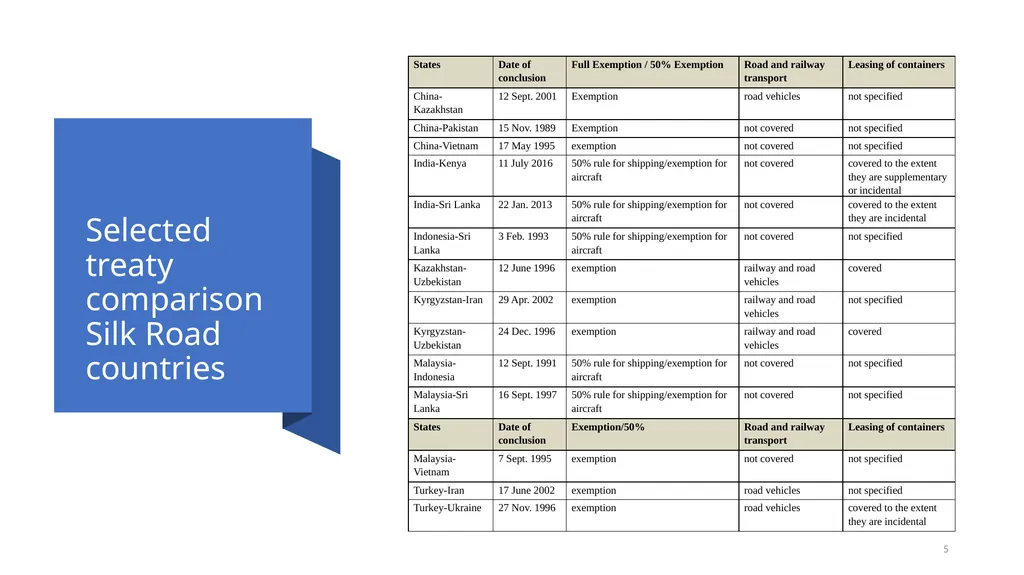
slide5. Selected treaty comparison Silk Road countries 5<br>
slide6. Proposals for improvement Administrative Cooperation
board set up by BRITACOM
to address treaty issues relating to international transportation
to provide a platform for implementing dispute resolutions mechanisms including mediation 6<br>
slide7. Proposals for improvement Revision of Model Conventions and bilateral treaties
Include income from rail and road transport
Extend them to intermodal transport
Cover other taxes and charges which affect transportation (especially by road and railway) which impact on the cost of transport and create disincentives to the growth of the business activities 7<br>
BRITACOM Advisory Board
Professor of International and Comparative Tax Law
Università Cattolica di Piacenza
Founding Partner of Maisto e Associati<br>
slide2. The international transport tax landscape The key role of transport within the Belt and Road Initiative (BRI)
- Six Economic transport corridors connecting Asia with Europe
- Investment in roads, railways, ports and other infrastructures
- Taxation of transport and the impact on supply chains
- Difficulty of apportioning income from international transportation
Special domestic tax regimes
Tax treaties rules (Art. 8 OECD and UN Model Tax Conventions)
Exception to the general distributive rule on business profits 2<br>
slide3. Issues arising under article 8 of the OECD and UN Model Conventions Taxation of transportation by railway and road not covered by tax treaties
Income from intermodal transportation (i.e. derived from the combined use of different means of transport) not covered
Multilateral transport situations are not covered
Scope of transportation income covered by treaties is either unclear or not consistent (e.g. leasing of containers) 3<br>
slide4. Issues arising under article 8 of the OECD and UN Model Conventions Domestic privileged tax regimes are generally limited to shipping and not applied to road or railway transport
Privileged tax regimes may prevent treaty eligibility (“liability to tax” condition)
Treaty relief may be subject to burdensome formalities 4<br>
slide5. Selected treaty comparison Silk Road countries 5<br>
slide6. Proposals for improvement Administrative Cooperation
board set up by BRITACOM
to address treaty issues relating to international transportation
to provide a platform for implementing dispute resolutions mechanisms including mediation 6<br>
slide7. Proposals for improvement Revision of Model Conventions and bilateral treaties
Include income from rail and road transport
Extend them to intermodal transport
Cover other taxes and charges which affect transportation (especially by road and railway) which impact on the cost of transport and create disincentives to the growth of the business activities 7<br>