
By: CA. Kamal Garg [B. Com(H), FCA, DISA (ICAI),



Description: By: CA. Kamal Garg B. Com(H), FCA, DISA (ICAI), M. Com Insolvency Professional Theme Peer Review refers to an examination of a professionals performance or practices in a particular area by other experienced professionals in the same
Related Topics
Download Presentation
"By: CA. Kamal Garg [B. Com(H), FCA, DISA (ICAI)," is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. By:
CA. Kamal Garg
[B. Com(H), FCA, DISA (ICAI), M. Com]
Insolvency Professional<br>
slide2. Theme Peer Review refers to an examination of a professional’s performance or practices in a particular area by other experienced professionals in the same area.
However, it is not a hearing by a superior body but discussion among equals, which makes it a flexible tool.
The policy relies heavily on mutual trust among the professional involved, as well as their shared confidence in the process.<br>
slide3. Mindset The concept of peer review is quite old. A competent professional always thinks that there is a scope for improvement in his performance. Naturally, the source of improvement can be another professional from his own field.
Practical examples of peer review are generally seen in the field of education and medicine although they are referred to differently:
In the field of education, when a moderator rechecks the answer papers evaluated by one paper checker, what the moderator is doing is nothing but a peer review;
Secondly, it is not uncommon for a senior teacher to sit in the last row and evaluate the performance of the new teacher. These are commonly seen examples of peer review, although not termed that way;
In the field of medicine also, such examples are seen. When a doctor refers a patient to another doctor for second opinion, what the second doctor is doing is nothing but peer review;
In the field of medicine and scientific research, peer review is very commonly done in case of professional journals before publishing any article or research paper. Before the article is published, it is subjected to review by a panel of reviewers<br>
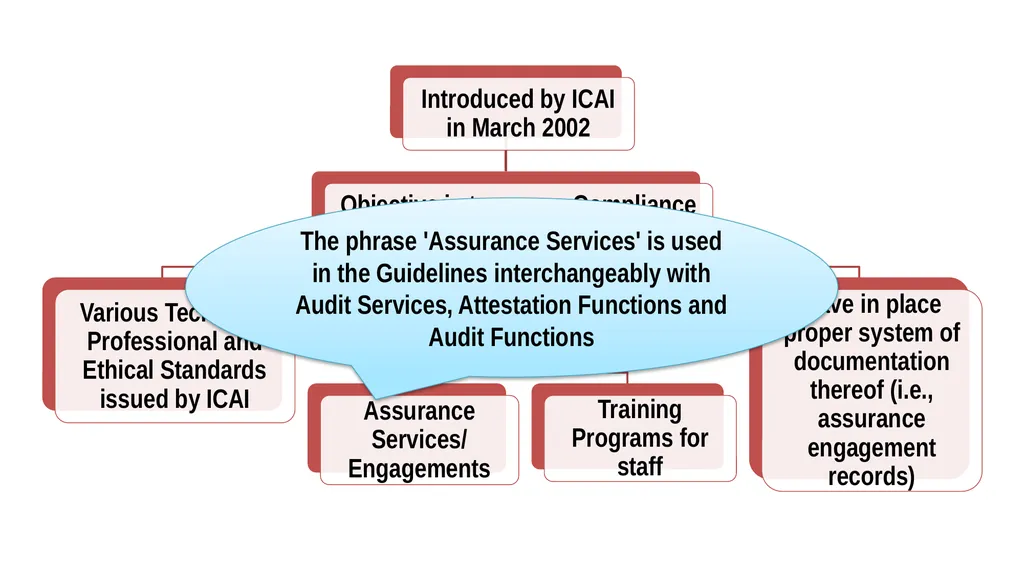
slide5. The phrase 'Assurance Services' is used in the Guidelines interchangeably with Audit Services, Attestation Functions and Audit Functions<br>
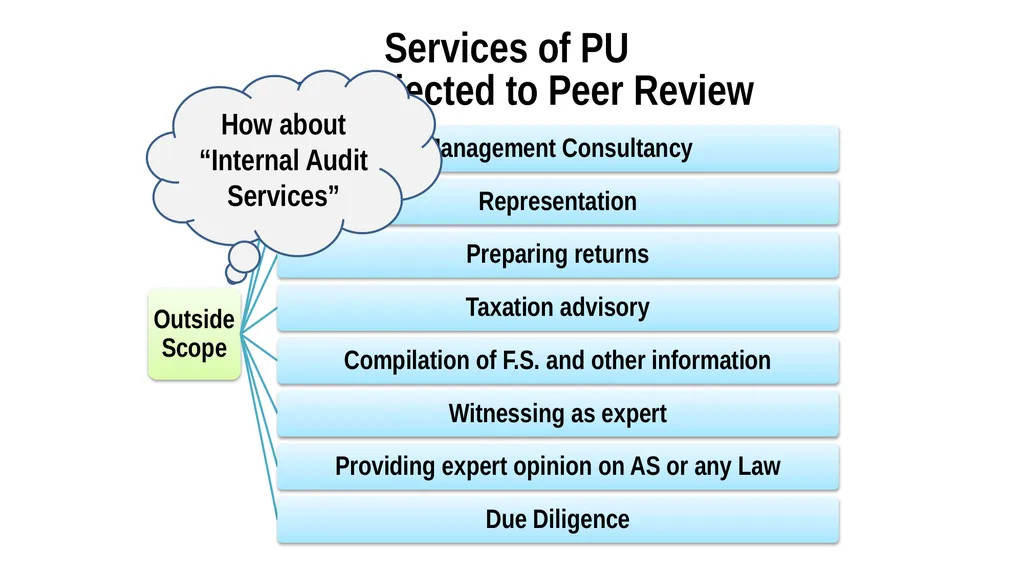
slide7. Services of PU not subjected to Peer Review How about “Internal Audit Services”<br>
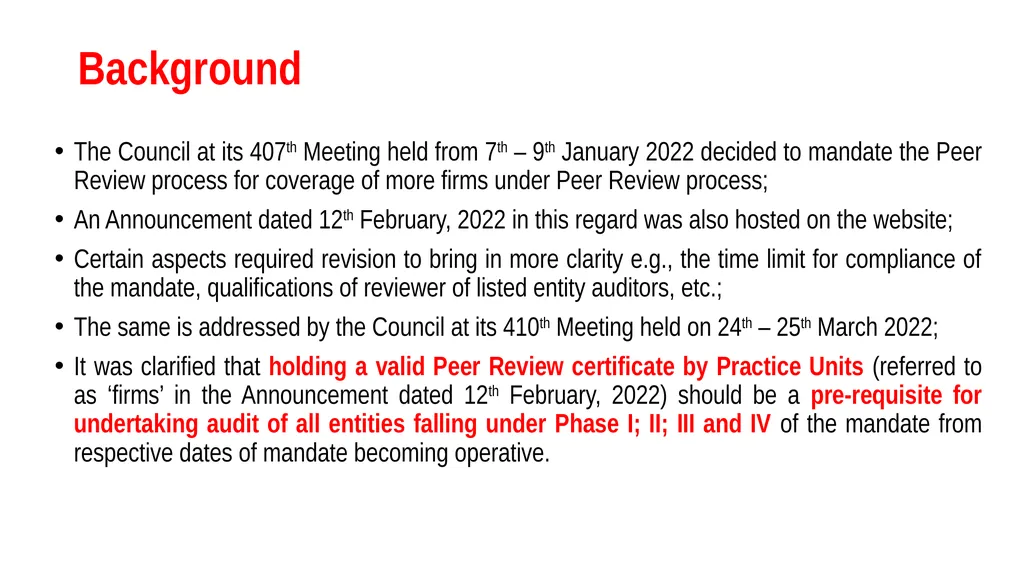
slide10. Background The Council at its 407th Meeting held from 7th – 9th January 2022 decided to mandate the Peer Review process for coverage of more firms under Peer Review process;
An Announcement dated 12th February, 2022 in this regard was also hosted on the website;
Certain aspects required revision to bring in more clarity e.g., the time limit for compliance of the mandate, qualifications of reviewer of listed entity auditors, etc.;
The same is addressed by the Council at its 410th Meeting held on 24th – 25th March 2022;
It was clarified that holding a valid Peer Review certificate by Practice Units (referred to as ‘firms’ in the Announcement dated 12th February, 2022) should be a pre-requisite for undertaking audit of all entities falling under Phase I; II; III and IV of the mandate from respective dates of mandate becoming operative.<br>
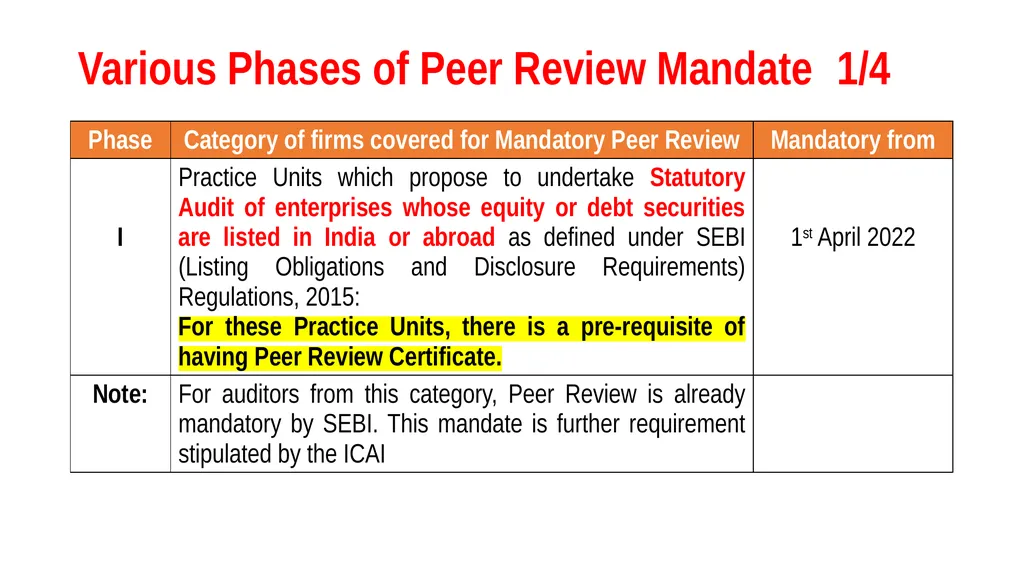
slide11. Various Phases of Peer Review Mandate 1/4<br>
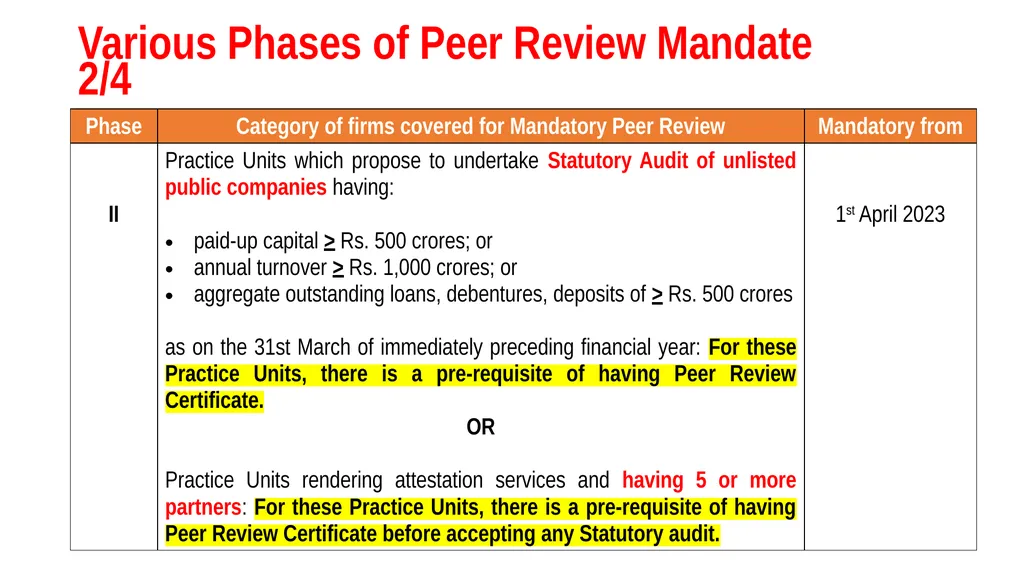
slide12. Various Phases of Peer Review Mandate 2/4<br>
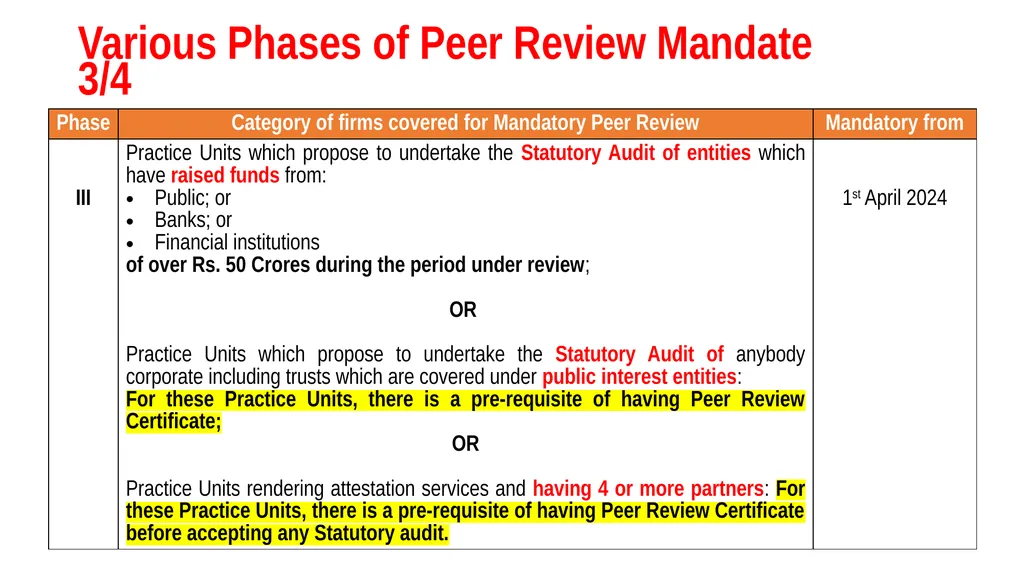
slide13. Various Phases of Peer Review Mandate 3/4<br>
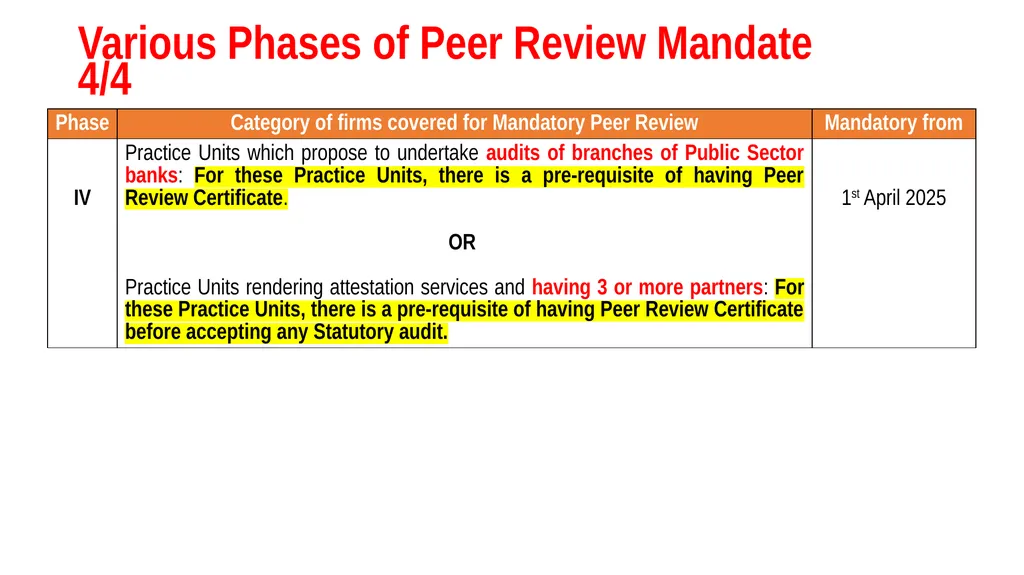
slide14. Various Phases of Peer Review Mandate 4/4<br>
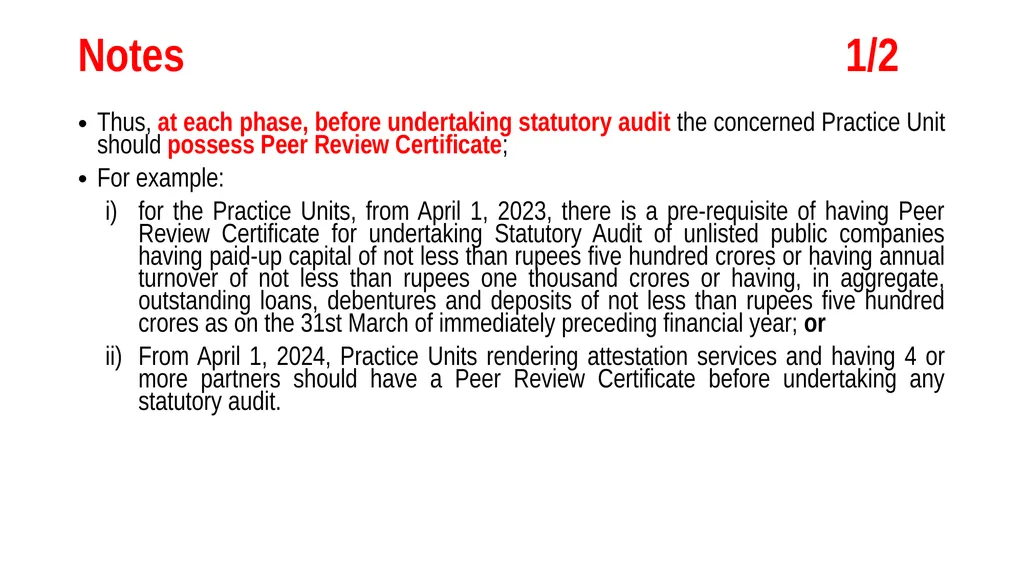
slide15. Notes 1/2 Thus, at each phase, before undertaking statutory audit the concerned Practice Unit should possess Peer Review Certificate;
For example:
for the Practice Units, from April 1, 2023, there is a pre-requisite of having Peer Review Certificate for undertaking Statutory Audit of unlisted public companies having paid-up capital of not less than rupees five hundred crores or having annual turnover of not less than rupees one thousand crores or having, in aggregate, outstanding loans, debentures and deposits of not less than rupees five hundred crores as on the 31st March of immediately preceding financial year; or
From April 1, 2024, Practice Units rendering attestation services and having 4 or more partners should have a Peer Review Certificate before undertaking any statutory audit.<br>
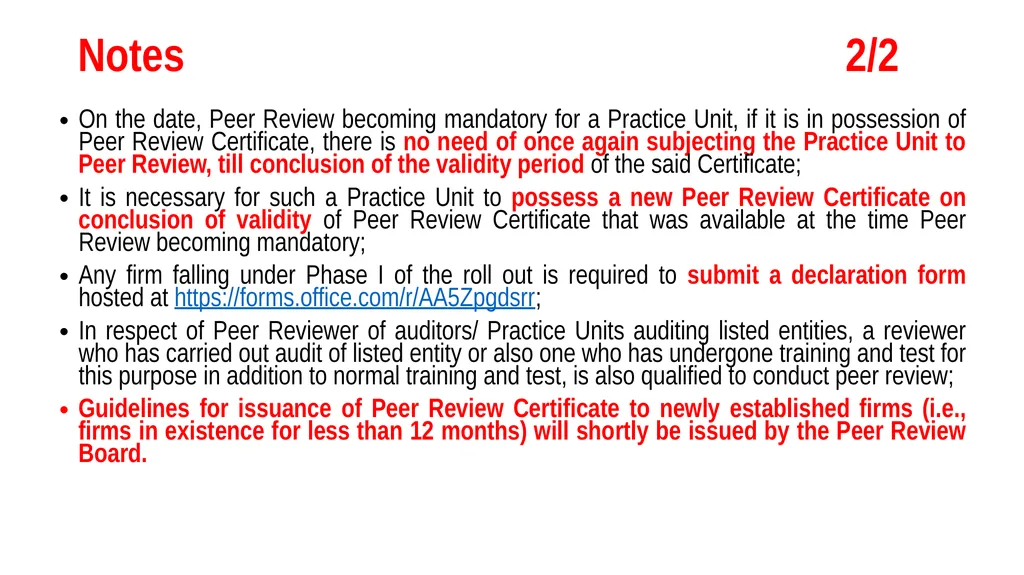
slide16. Notes 2/2 On the date, Peer Review becoming mandatory for a Practice Unit, if it is in possession of Peer Review Certificate, there is no need of once again subjecting the Practice Unit to Peer Review, till conclusion of the validity period of the said Certificate;
It is necessary for such a Practice Unit to possess a new Peer Review Certificate on conclusion of validity of Peer Review Certificate that was available at the time Peer Review becoming mandatory;
Any firm falling under Phase I of the roll out is required to submit a declaration form hosted at https://forms.office.com/r/AA5Zpgdsrr;
In respect of Peer Reviewer of auditors/ Practice Units auditing listed entities, a reviewer who has carried out audit of listed entity or also one who has undergone training and test for this purpose in addition to normal training and test, is also qualified to conduct peer review;
Guidelines for issuance of Peer Review Certificate to newly established firms (i.e., firms in existence for less than 12 months) will shortly be issued by the Peer Review Board.<br>
slide21. Factors on which the number of assurance service engagements to be reviewed depend The standard of quality controls generally prevailing;
The size and nature of assurance service engagements undertaken by the Practice Unit;
The methodology generally adopted by the Practice Unit in providing assurance services;
The number of partners/ members involved in assurance service engagements in the Practice Unit;
The number of locations / branch offices of the Practice Unit;
The Fees charged / received / GST paid by the Practice unit<br>
slide22. Compliance Review The Reviewer is required to carry out a Compliance Review of the following general controls for evaluating the degree of reliance to be placed upon them for effective Review:
Independence
Maintenance of Professional Skills and Standards
Outside Consultation
Staff recruitment, Supervision and Development
Office Administration<br>
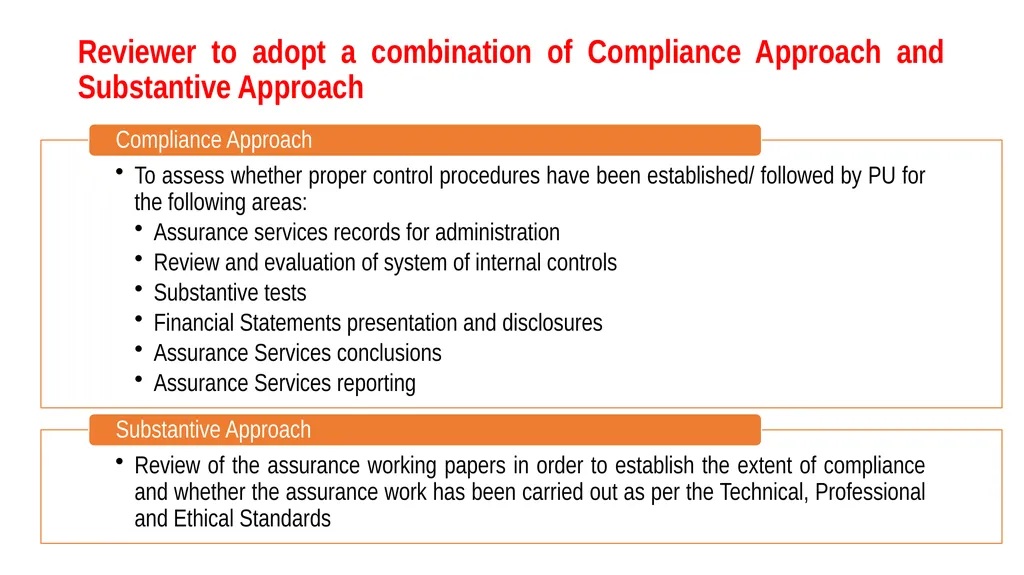
slide23. Reviewer to adopt a combination of Compliance Approach and Substantive Approach<br>
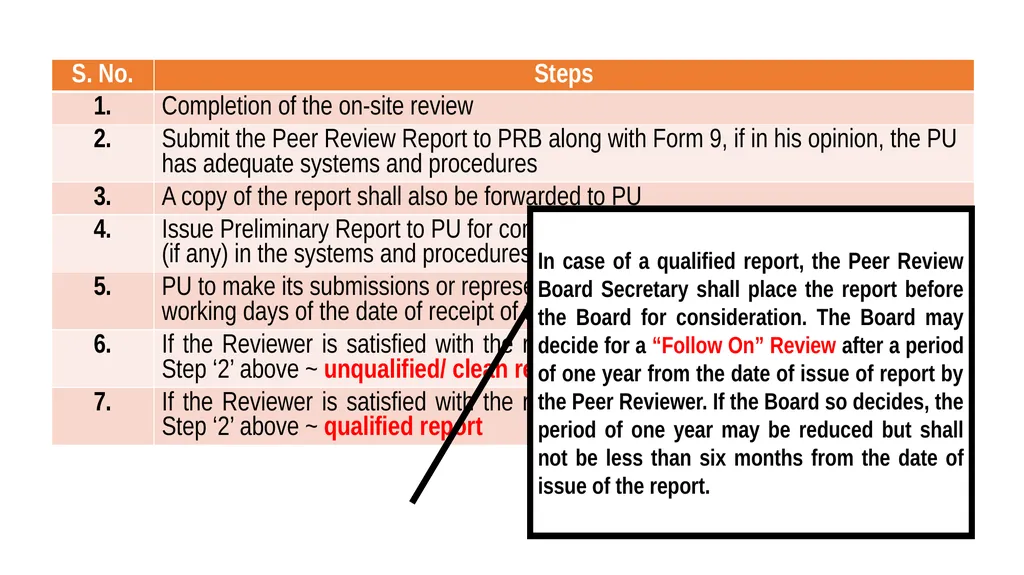
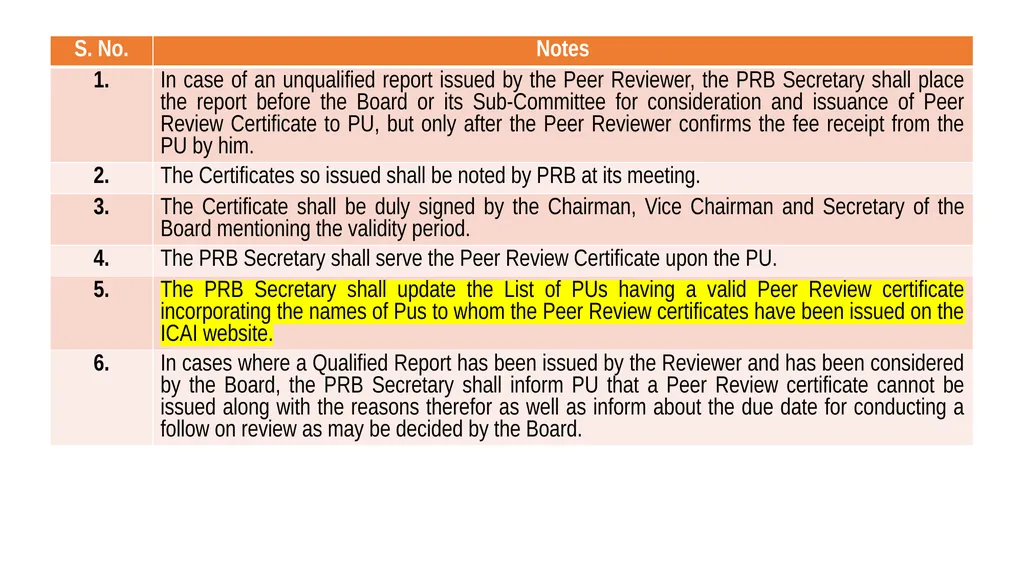
slide27. In case of a qualified report, the Peer Review Board Secretary shall place the report before the Board for consideration. The Board may decide for a “Follow On” Review after a period of one year from the date of issue of report by the Peer Reviewer. If the Board so decides, the period of one year may be reduced but shall not be less than six months from the date of issue of the report.<br>
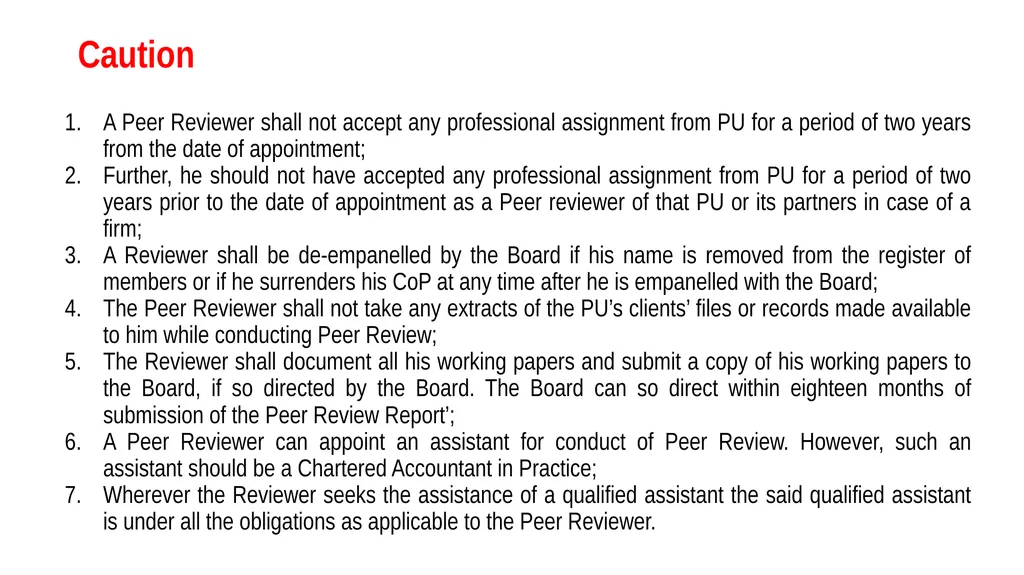
slide41. Caution A Peer Reviewer shall not accept any professional assignment from PU for a period of two years from the date of appointment;
Further, he should not have accepted any professional assignment from PU for a period of two years prior to the date of appointment as a Peer reviewer of that PU or its partners in case of a firm;
A Reviewer shall be de-empanelled by the Board if his name is removed from the register of members or if he surrenders his CoP at any time after he is empanelled with the Board;
The Peer Reviewer shall not take any extracts of the PU’s clients’ files or records made available to him while conducting Peer Review;
The Reviewer shall document all his working papers and submit a copy of his working papers to the Board, if so directed by the Board. The Board can so direct within eighteen months of submission of the Peer Review Report’;
A Peer Reviewer can appoint an assistant for conduct of Peer Review. However, such an assistant should be a Chartered Accountant in Practice;
Wherever the Reviewer seeks the assistance of a qualified assistant the said qualified assistant is under all the obligations as applicable to the Peer Reviewer.<br>
slide44. IFRS I Corporate Laws I Due Diligence I Forensic Audits
Thank you
Kamal Garg & Associates<br>
CA. Kamal Garg
[B. Com(H), FCA, DISA (ICAI), M. Com]
Insolvency Professional<br>
slide2. Theme Peer Review refers to an examination of a professional’s performance or practices in a particular area by other experienced professionals in the same area.
However, it is not a hearing by a superior body but discussion among equals, which makes it a flexible tool.
The policy relies heavily on mutual trust among the professional involved, as well as their shared confidence in the process.<br>
slide3. Mindset The concept of peer review is quite old. A competent professional always thinks that there is a scope for improvement in his performance. Naturally, the source of improvement can be another professional from his own field.
Practical examples of peer review are generally seen in the field of education and medicine although they are referred to differently:
In the field of education, when a moderator rechecks the answer papers evaluated by one paper checker, what the moderator is doing is nothing but a peer review;
Secondly, it is not uncommon for a senior teacher to sit in the last row and evaluate the performance of the new teacher. These are commonly seen examples of peer review, although not termed that way;
In the field of medicine also, such examples are seen. When a doctor refers a patient to another doctor for second opinion, what the second doctor is doing is nothing but peer review;
In the field of medicine and scientific research, peer review is very commonly done in case of professional journals before publishing any article or research paper. Before the article is published, it is subjected to review by a panel of reviewers<br>
slide5. The phrase 'Assurance Services' is used in the Guidelines interchangeably with Audit Services, Attestation Functions and Audit Functions<br>
slide7. Services of PU not subjected to Peer Review How about “Internal Audit Services”<br>
slide10. Background The Council at its 407th Meeting held from 7th – 9th January 2022 decided to mandate the Peer Review process for coverage of more firms under Peer Review process;
An Announcement dated 12th February, 2022 in this regard was also hosted on the website;
Certain aspects required revision to bring in more clarity e.g., the time limit for compliance of the mandate, qualifications of reviewer of listed entity auditors, etc.;
The same is addressed by the Council at its 410th Meeting held on 24th – 25th March 2022;
It was clarified that holding a valid Peer Review certificate by Practice Units (referred to as ‘firms’ in the Announcement dated 12th February, 2022) should be a pre-requisite for undertaking audit of all entities falling under Phase I; II; III and IV of the mandate from respective dates of mandate becoming operative.<br>
slide11. Various Phases of Peer Review Mandate 1/4<br>
slide12. Various Phases of Peer Review Mandate 2/4<br>
slide13. Various Phases of Peer Review Mandate 3/4<br>
slide14. Various Phases of Peer Review Mandate 4/4<br>
slide15. Notes 1/2 Thus, at each phase, before undertaking statutory audit the concerned Practice Unit should possess Peer Review Certificate;
For example:
for the Practice Units, from April 1, 2023, there is a pre-requisite of having Peer Review Certificate for undertaking Statutory Audit of unlisted public companies having paid-up capital of not less than rupees five hundred crores or having annual turnover of not less than rupees one thousand crores or having, in aggregate, outstanding loans, debentures and deposits of not less than rupees five hundred crores as on the 31st March of immediately preceding financial year; or
From April 1, 2024, Practice Units rendering attestation services and having 4 or more partners should have a Peer Review Certificate before undertaking any statutory audit.<br>
slide16. Notes 2/2 On the date, Peer Review becoming mandatory for a Practice Unit, if it is in possession of Peer Review Certificate, there is no need of once again subjecting the Practice Unit to Peer Review, till conclusion of the validity period of the said Certificate;
It is necessary for such a Practice Unit to possess a new Peer Review Certificate on conclusion of validity of Peer Review Certificate that was available at the time Peer Review becoming mandatory;
Any firm falling under Phase I of the roll out is required to submit a declaration form hosted at https://forms.office.com/r/AA5Zpgdsrr;
In respect of Peer Reviewer of auditors/ Practice Units auditing listed entities, a reviewer who has carried out audit of listed entity or also one who has undergone training and test for this purpose in addition to normal training and test, is also qualified to conduct peer review;
Guidelines for issuance of Peer Review Certificate to newly established firms (i.e., firms in existence for less than 12 months) will shortly be issued by the Peer Review Board.<br>
slide21. Factors on which the number of assurance service engagements to be reviewed depend The standard of quality controls generally prevailing;
The size and nature of assurance service engagements undertaken by the Practice Unit;
The methodology generally adopted by the Practice Unit in providing assurance services;
The number of partners/ members involved in assurance service engagements in the Practice Unit;
The number of locations / branch offices of the Practice Unit;
The Fees charged / received / GST paid by the Practice unit<br>
slide22. Compliance Review The Reviewer is required to carry out a Compliance Review of the following general controls for evaluating the degree of reliance to be placed upon them for effective Review:
Independence
Maintenance of Professional Skills and Standards
Outside Consultation
Staff recruitment, Supervision and Development
Office Administration<br>
slide23. Reviewer to adopt a combination of Compliance Approach and Substantive Approach<br>
slide27. In case of a qualified report, the Peer Review Board Secretary shall place the report before the Board for consideration. The Board may decide for a “Follow On” Review after a period of one year from the date of issue of report by the Peer Reviewer. If the Board so decides, the period of one year may be reduced but shall not be less than six months from the date of issue of the report.<br>
slide41. Caution A Peer Reviewer shall not accept any professional assignment from PU for a period of two years from the date of appointment;
Further, he should not have accepted any professional assignment from PU for a period of two years prior to the date of appointment as a Peer reviewer of that PU or its partners in case of a firm;
A Reviewer shall be de-empanelled by the Board if his name is removed from the register of members or if he surrenders his CoP at any time after he is empanelled with the Board;
The Peer Reviewer shall not take any extracts of the PU’s clients’ files or records made available to him while conducting Peer Review;
The Reviewer shall document all his working papers and submit a copy of his working papers to the Board, if so directed by the Board. The Board can so direct within eighteen months of submission of the Peer Review Report’;
A Peer Reviewer can appoint an assistant for conduct of Peer Review. However, such an assistant should be a Chartered Accountant in Practice;
Wherever the Reviewer seeks the assistance of a qualified assistant the said qualified assistant is under all the obligations as applicable to the Peer Reviewer.<br>
slide44. IFRS I Corporate Laws I Due Diligence I Forensic Audits
Thank you
Kamal Garg & Associates<br>