
Chapter 1 The Nature of Real Estate and Real


Description: Chapter 1 The Nature of Real Estate and Real Estate Markets Real Estate FIN 331 Spring 2020 Getting through the Course Skim read assignments prior to class Real Estate related articles frequently appear in the media and will be sent to
Related Topics
Download Presentation
"Chapter 1 The Nature of Real Estate and Real" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Chapter 1
The Nature of Real Estate and Real Estate Markets Real Estate
FIN 331 Spring 2020<br>
slide2. Getting through the Course Skim read assignments prior to class
Real Estate related articles frequently appear in the media and will be sent to class as supplemental readings – check your email regularly.
Attendance Policy: I take attendance. More than 2 unexcused absences will result in the loss of one point for each additional absence.<br>
slide3. Getting through the Course Homework will be collected at exam time. H/W counts for 10% of our grade.
Exam Issues:
Please don’t kill your grandmothers. If you cannot make the scheduled exam, email me BEFORE the exam. We’ll schedule a later time. HOWEVER, the later time must be before the next class period.
The Alternative is the “SOB” exam. Spare yourself the grief. No one has passed the SOB exam.<br>
slide4. Any Questions? If not…Let’s start<br>
slide5. FIN 331 Course Objectives Extend a student's basic awareness of real estate;
real estate ownership,
real estate value
purchase and sale of varied interests in real estate
real estate law and property rights
fundamentals of finance as they apply to real estate values<br>
slide6. “Real estate is the single largest component of wealth in the global economy. The importance of real estate is highlighted in terms of its roles in the global and domestic economies, as well as its prominence in the investment portfolios of U.S. households.” [Ling & Archer, Real Estate 4th ed]<br>
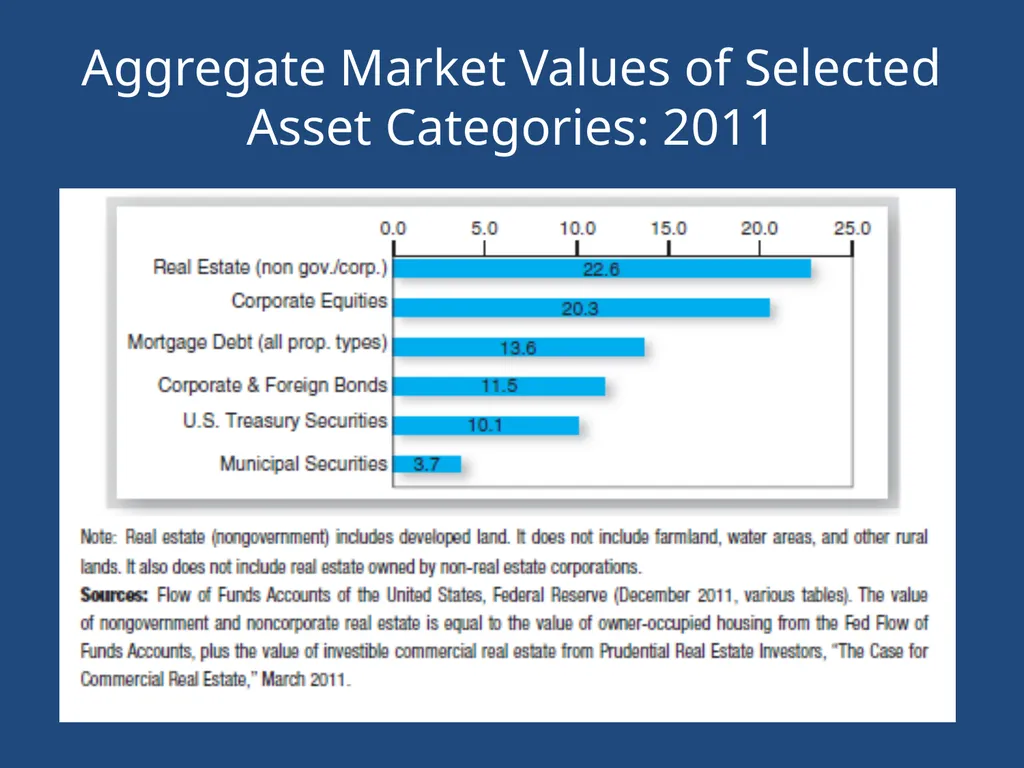
slide7. Aggregate Market Values of Selected Asset Categories: 2011<br>
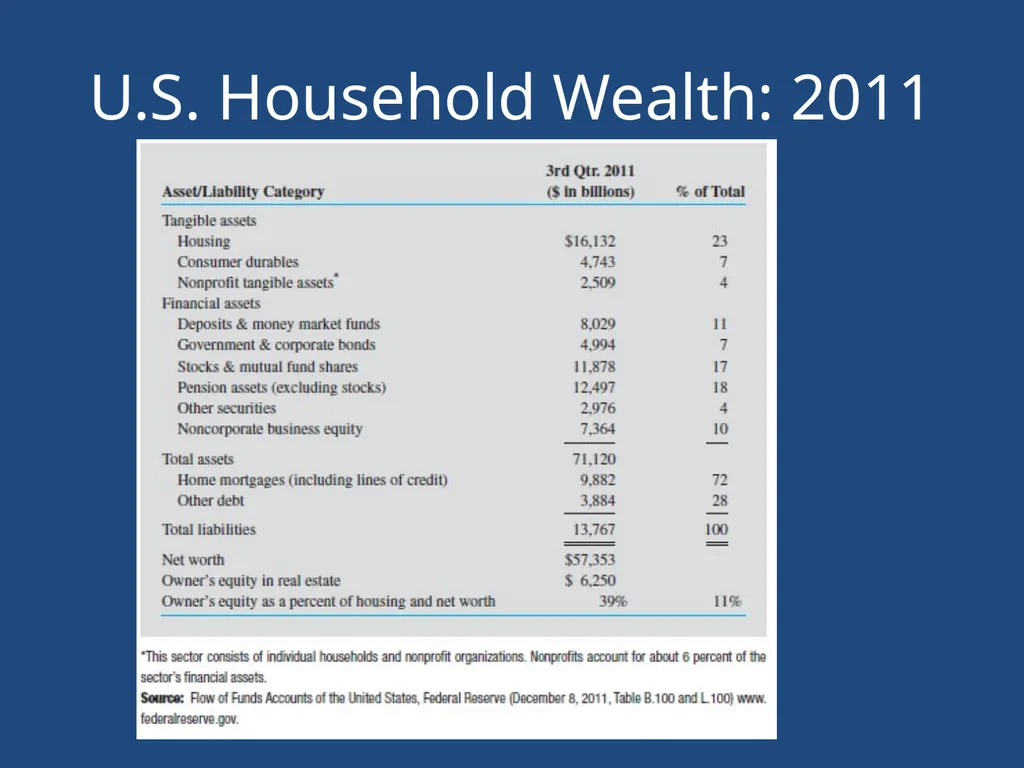
slide8. U.S. Household Wealth: 2011<br>
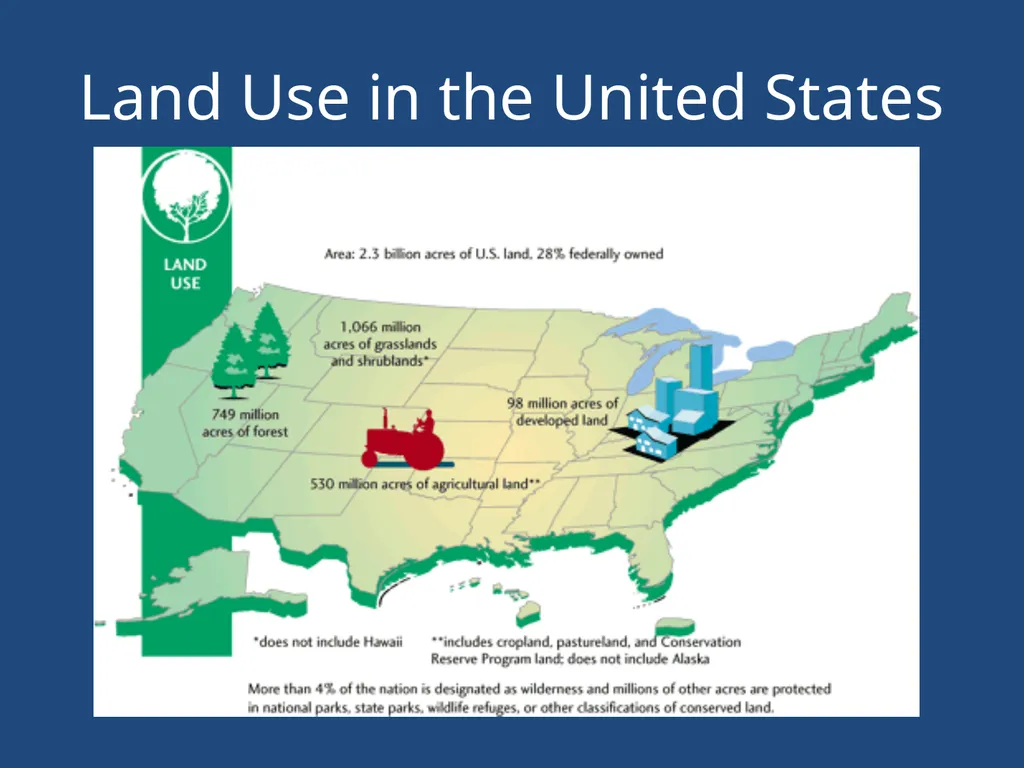
slide9. Land Use in the United States<br>
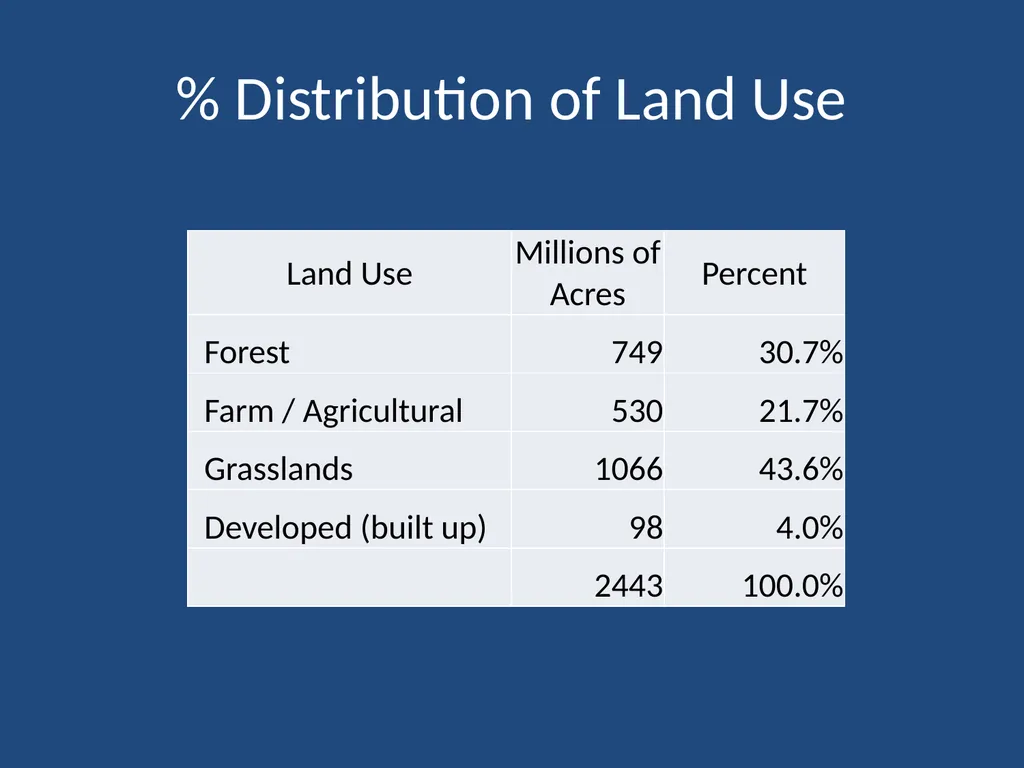
slide10. % Distribution of Land Use<br>
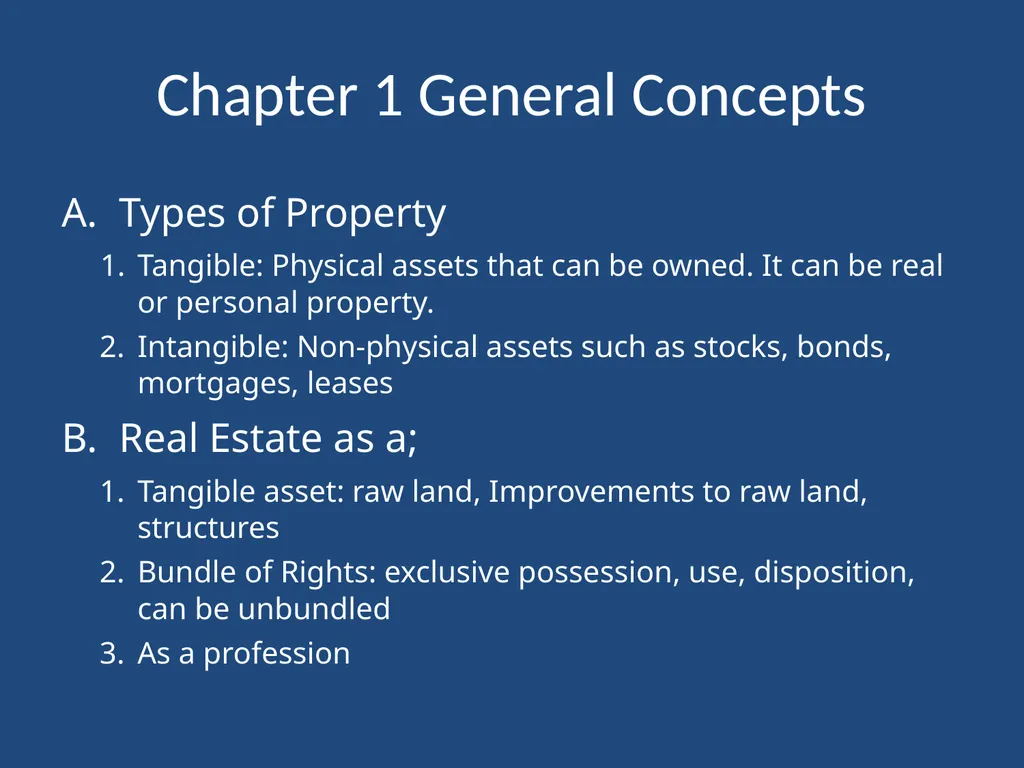
slide11. Chapter 1 General Concepts Types of Property
Tangible: Physical assets that can be owned. It can be real or personal property.
Intangible: Non-physical assets such as stocks, bonds, mortgages, leases
Real Estate as a;
Tangible asset: raw land, Improvements to raw land, structures
Bundle of Rights: exclusive possession, use, disposition, can be unbundled
As a profession<br>
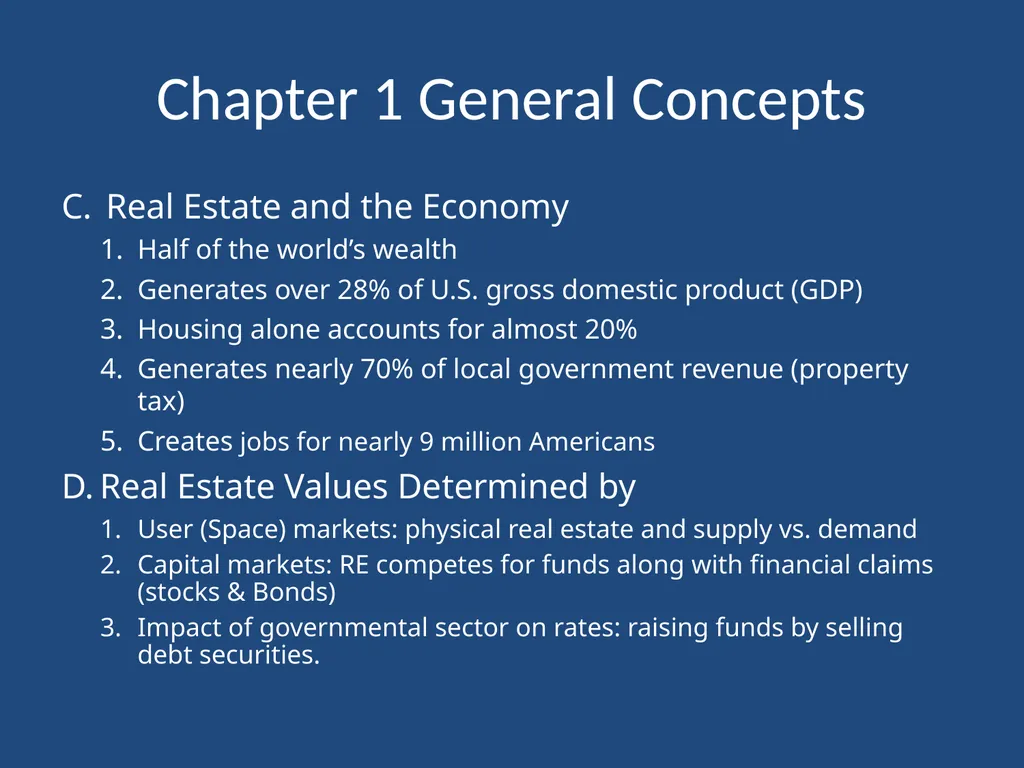
slide12. Chapter 1 General Concepts Real Estate and the Economy
Half of the world’s wealth
Generates over 28% of U.S. gross domestic product (GDP)
Housing alone accounts for almost 20%
Generates nearly 70% of local government revenue (property tax)
Creates jobs for nearly 9 million Americans
Real Estate Values Determined by
User (Space) markets: physical real estate and supply vs. demand
Capital markets: RE competes for funds along with financial claims (stocks & Bonds)
Impact of governmental sector on rates: raising funds by selling debt securities.<br>
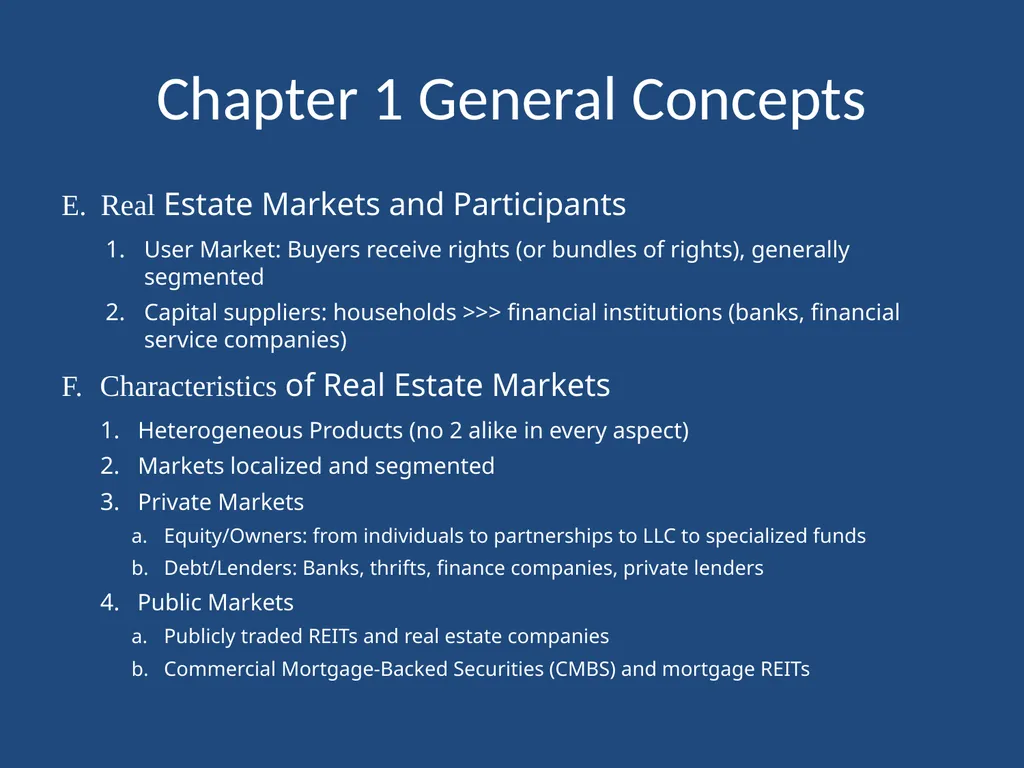
slide13. Chapter 1 General Concepts Real Estate Markets and Participants
User Market: Buyers receive rights (or bundles of rights), generally segmented
Capital suppliers: households >>> financial institutions (banks, financial service companies)
Characteristics of Real Estate Markets
Heterogeneous Products (no 2 alike in every aspect)
Markets localized and segmented
Private Markets
Equity/Owners: from individuals to partnerships to LLC to specialized funds
Debt/Lenders: Banks, thrifts, finance companies, private lenders
Public Markets
Publicly traded REITs and real estate companies
Commercial Mortgage-Backed Securities (CMBS) and mortgage REITs<br>
slide14. Wall Street: Money Never Sleeps Gecko’s talk on Financial Crisis<br>
slide15. Real estate as an industry and profession Brokerage
Development
Leasing
Property management
Asset management
Real Estate Law
Appraisal
Market consulting
Counseling Planning
Government regulation and taxation
Housing assistance
Mortgage finance
Construction finance
Long-term finance
Investment management<br>
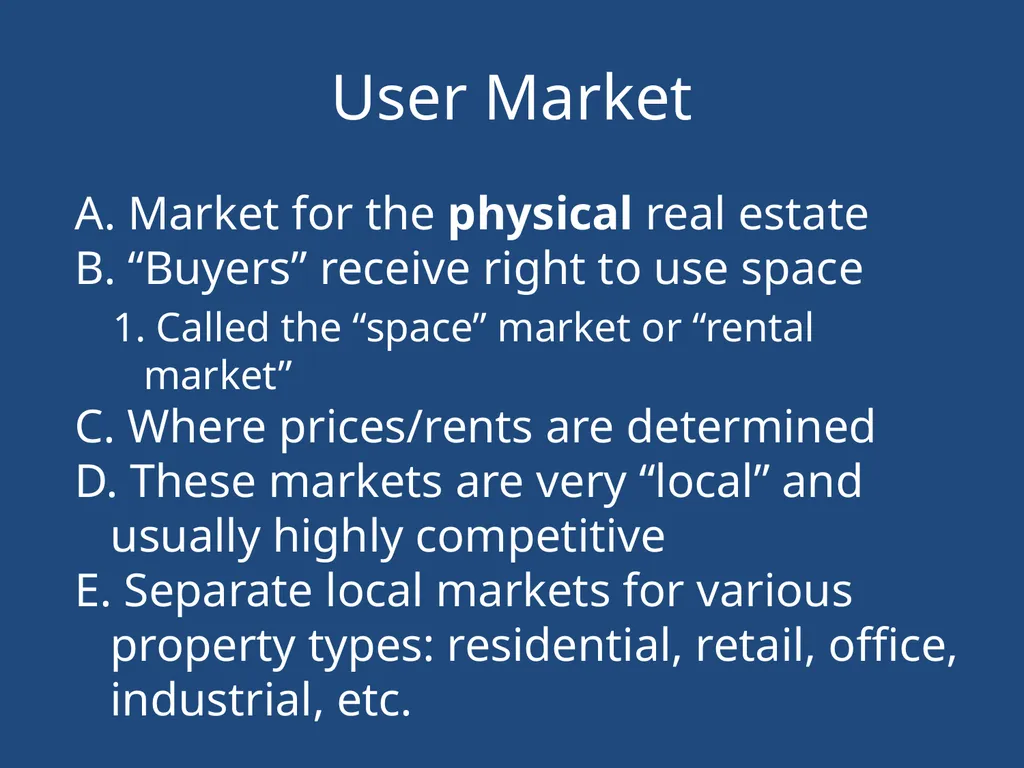
slide16. User Market Market for the physical real estate
“Buyers” receive right to use space
Called the “space” market or “rental market”
Where prices/rents are determined
These markets are very “local” and usually highly competitive
Separate local markets for various property types: residential, retail, office, industrial, etc.<br>
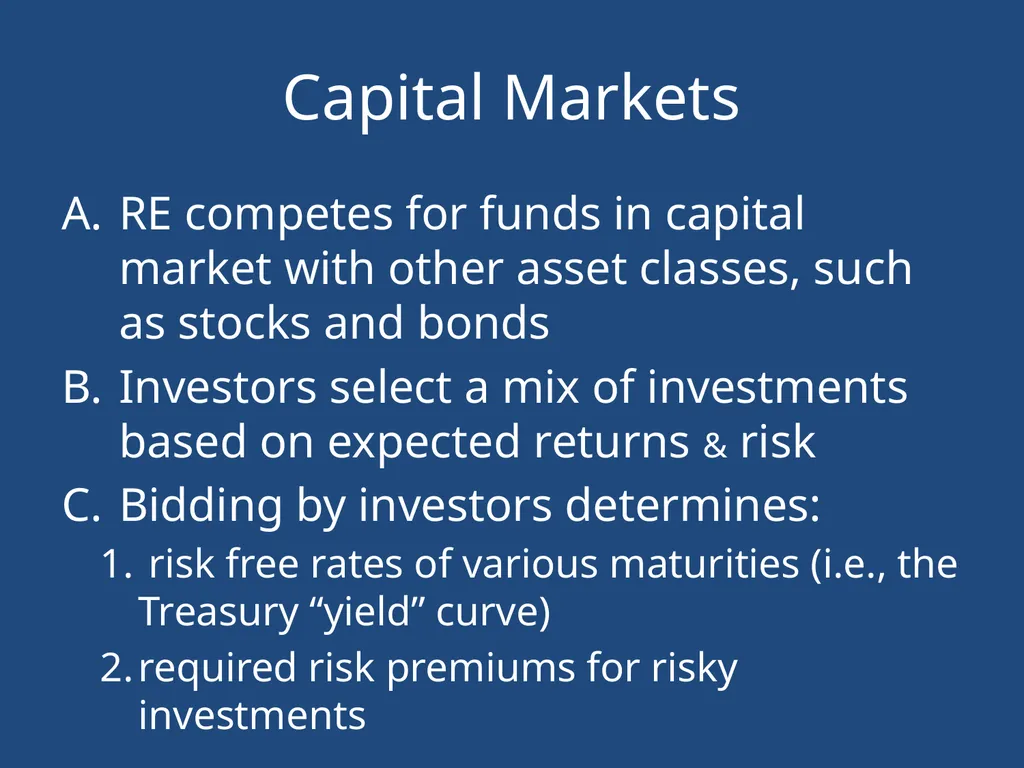
slide17. Capital Markets RE competes for funds in capital market with other asset classes, such as stocks and bonds
Investors select a mix of investments based on expected returns & risk
Bidding by investors determines:
risk free rates of various maturities (i.e., the Treasury “yield” curve)
required risk premiums for risky investments<br>
slide18. Public Capital Markets Small homogeneous units (shares) of ownership in assets trade in public exchanges
Many buyers and sellers
Price quotes available for all to see
Characterized by a high degree of liquidity
Informationally efficient<br>
slide19. Private Capital/Property Markets Absence of centralized market (or even price lists)
Assets trade infrequently in private transactions (thus a lack of transparency)
Common for “whole” assets to be traded in a single transaction (indivisibility)
Less liquidity than public markets
Higher transaction costs<br>
slide20. Property (Asset) Market Market for ownership claims to RE assets
Buyers/owners receive rights to cash flows generated by leasing space to tenants
Demand (supply) side of property market is made up of investors wanting to buy (sell) property
Property market is integrated, not segmented like space market
i.e., investment capital can come from anywhere<br>
slide21. homework assignment Important Key terms: Real Estate, Capital Markets, User Markets, Property Markets, Capitalization Rates, Tangible & Intangible Assets, Real Property
Study Questions: 1, 3, 4, 5, 7<br>
slide22. The great real estate value melT-down The Community Reinvestment Act (1977) [CRA]
Principle Objective: Increase home ownership in the US
Related Objectives: end practice of “redlining” by commercial banks
Requirements of the Act:
The Act requires banks and thrifts to make loans throughout their entire market, operate depository facilities in certain neighborhoods, and collect data about lending habits to be periodically reported to federal supervisory agencies. These agencies use CRA ratings when evaluating applications for mergers and acquisitions.<br>
slide23. The great real estate value melT-down CRA Act modified in 1995
Letter from General Council to Comptroller of the Currency
In Re Small Business Loans
Furthermore, the CRA regulations do not require an institution to verify revenue amounts; thus, the institution may rely on the gross annual revenue amount provided by the borrower in the ordinary course of business.
In Re Consumer Loans
The CRA regulations do not require an institution to verify income amounts; thus, the institution may rely on the income amounts provided by the borrower on the loan application.
The beginning of NINJA loans (No Income, No Job, No Assets)<br>
slide24. The great real estate value melT-down Michelle Minton (Competitive Enterprise Institute) on Negative Results of CRA
Increased risk to banks: as CRA rankings increased, bank risk increased as measured by CAMEL ratings (Capital adequacy, Asset quality, Management, Earnings, Liquidity).
Increased costs to small lenders: includes the cumulative costs of writing riskier loans (e.g.; to buyers with low FICO scores).
Cites study by George Benston (Emory U) suggesting that larger banks made loans in low and middle income markets (LMI) at a loss.
Rent Seeking opportunity for activist organizations: e.g., ACORN received hundreds of thousands of dollars from JP Morgan and Chase Manhattan Bank in exchange for ACORN’s approval of proposed mergers.<br>
FIN 331 Spring 2020<br>
slide2. Getting through the Course Skim read assignments prior to class
Real Estate related articles frequently appear in the media and will be sent to class as supplemental readings – check your email regularly.
Attendance Policy: I take attendance. More than 2 unexcused absences will result in the loss of one point for each additional absence.<br>
slide3. Getting through the Course Homework will be collected at exam time. H/W counts for 10% of our grade.
Exam Issues:
Please don’t kill your grandmothers. If you cannot make the scheduled exam, email me BEFORE the exam. We’ll schedule a later time. HOWEVER, the later time must be before the next class period.
The Alternative is the “SOB” exam. Spare yourself the grief. No one has passed the SOB exam.<br>
slide4. Any Questions? If not…Let’s start<br>
slide5. FIN 331 Course Objectives Extend a student's basic awareness of real estate;
real estate ownership,
real estate value
purchase and sale of varied interests in real estate
real estate law and property rights
fundamentals of finance as they apply to real estate values<br>
slide6. “Real estate is the single largest component of wealth in the global economy. The importance of real estate is highlighted in terms of its roles in the global and domestic economies, as well as its prominence in the investment portfolios of U.S. households.” [Ling & Archer, Real Estate 4th ed]<br>
slide7. Aggregate Market Values of Selected Asset Categories: 2011<br>
slide8. U.S. Household Wealth: 2011<br>
slide9. Land Use in the United States<br>
slide10. % Distribution of Land Use<br>
slide11. Chapter 1 General Concepts Types of Property
Tangible: Physical assets that can be owned. It can be real or personal property.
Intangible: Non-physical assets such as stocks, bonds, mortgages, leases
Real Estate as a;
Tangible asset: raw land, Improvements to raw land, structures
Bundle of Rights: exclusive possession, use, disposition, can be unbundled
As a profession<br>
slide12. Chapter 1 General Concepts Real Estate and the Economy
Half of the world’s wealth
Generates over 28% of U.S. gross domestic product (GDP)
Housing alone accounts for almost 20%
Generates nearly 70% of local government revenue (property tax)
Creates jobs for nearly 9 million Americans
Real Estate Values Determined by
User (Space) markets: physical real estate and supply vs. demand
Capital markets: RE competes for funds along with financial claims (stocks & Bonds)
Impact of governmental sector on rates: raising funds by selling debt securities.<br>
slide13. Chapter 1 General Concepts Real Estate Markets and Participants
User Market: Buyers receive rights (or bundles of rights), generally segmented
Capital suppliers: households >>> financial institutions (banks, financial service companies)
Characteristics of Real Estate Markets
Heterogeneous Products (no 2 alike in every aspect)
Markets localized and segmented
Private Markets
Equity/Owners: from individuals to partnerships to LLC to specialized funds
Debt/Lenders: Banks, thrifts, finance companies, private lenders
Public Markets
Publicly traded REITs and real estate companies
Commercial Mortgage-Backed Securities (CMBS) and mortgage REITs<br>
slide14. Wall Street: Money Never Sleeps Gecko’s talk on Financial Crisis<br>
slide15. Real estate as an industry and profession Brokerage
Development
Leasing
Property management
Asset management
Real Estate Law
Appraisal
Market consulting
Counseling Planning
Government regulation and taxation
Housing assistance
Mortgage finance
Construction finance
Long-term finance
Investment management<br>
slide16. User Market Market for the physical real estate
“Buyers” receive right to use space
Called the “space” market or “rental market”
Where prices/rents are determined
These markets are very “local” and usually highly competitive
Separate local markets for various property types: residential, retail, office, industrial, etc.<br>
slide17. Capital Markets RE competes for funds in capital market with other asset classes, such as stocks and bonds
Investors select a mix of investments based on expected returns & risk
Bidding by investors determines:
risk free rates of various maturities (i.e., the Treasury “yield” curve)
required risk premiums for risky investments<br>
slide18. Public Capital Markets Small homogeneous units (shares) of ownership in assets trade in public exchanges
Many buyers and sellers
Price quotes available for all to see
Characterized by a high degree of liquidity
Informationally efficient<br>
slide19. Private Capital/Property Markets Absence of centralized market (or even price lists)
Assets trade infrequently in private transactions (thus a lack of transparency)
Common for “whole” assets to be traded in a single transaction (indivisibility)
Less liquidity than public markets
Higher transaction costs<br>
slide20. Property (Asset) Market Market for ownership claims to RE assets
Buyers/owners receive rights to cash flows generated by leasing space to tenants
Demand (supply) side of property market is made up of investors wanting to buy (sell) property
Property market is integrated, not segmented like space market
i.e., investment capital can come from anywhere<br>
slide21. homework assignment Important Key terms: Real Estate, Capital Markets, User Markets, Property Markets, Capitalization Rates, Tangible & Intangible Assets, Real Property
Study Questions: 1, 3, 4, 5, 7<br>
slide22. The great real estate value melT-down The Community Reinvestment Act (1977) [CRA]
Principle Objective: Increase home ownership in the US
Related Objectives: end practice of “redlining” by commercial banks
Requirements of the Act:
The Act requires banks and thrifts to make loans throughout their entire market, operate depository facilities in certain neighborhoods, and collect data about lending habits to be periodically reported to federal supervisory agencies. These agencies use CRA ratings when evaluating applications for mergers and acquisitions.<br>
slide23. The great real estate value melT-down CRA Act modified in 1995
Letter from General Council to Comptroller of the Currency
In Re Small Business Loans
Furthermore, the CRA regulations do not require an institution to verify revenue amounts; thus, the institution may rely on the gross annual revenue amount provided by the borrower in the ordinary course of business.
In Re Consumer Loans
The CRA regulations do not require an institution to verify income amounts; thus, the institution may rely on the income amounts provided by the borrower on the loan application.
The beginning of NINJA loans (No Income, No Job, No Assets)<br>
slide24. The great real estate value melT-down Michelle Minton (Competitive Enterprise Institute) on Negative Results of CRA
Increased risk to banks: as CRA rankings increased, bank risk increased as measured by CAMEL ratings (Capital adequacy, Asset quality, Management, Earnings, Liquidity).
Increased costs to small lenders: includes the cumulative costs of writing riskier loans (e.g.; to buyers with low FICO scores).
Cites study by George Benston (Emory U) suggesting that larger banks made loans in low and middle income markets (LMI) at a loss.
Rent Seeking opportunity for activist organizations: e.g., ACORN received hundreds of thousands of dollars from JP Morgan and Chase Manhattan Bank in exchange for ACORN’s approval of proposed mergers.<br>