
Class 4 Asian Capital Markets (FIN579) Stephan

Description: Class 4 Asian Capital Markets (FIN579) Stephan Siegel 2 Admin Topic Write-up: Update Name Tents Panel Discussion: February 10 Keith Ferguson, CIO, University of Washington Mark Whitmore, CEO, Whitmore Capital Management Gerard Fitzpatrick,
Related Topics
Download Presentation
"Class 4 Asian Capital Markets (FIN579) Stephan" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Class 4
Asian Capital Markets (FIN579) Stephan Siegel<br>
slide2. 2 Admin Topic Write-up: Update
Name Tents
Panel Discussion: February 10
Keith Ferguson, CIO, University of Washington
Mark Whitmore, CEO, Whitmore Capital Management
Gerard Fitzpatrick, CIO, Fixed-income Portfolios, Russell
Prepare questions for panelists. Email me your “best” question by Sunday (for participation credit).<br>
slide3. 3 Class 4 Guest Speaker: Brian Ingram, Head of Investments, PingAn Russell, Shanghai
Lecture in preparation of Classes 6, 7, and 8
Class 6: Private Equity and Frontier Markets
Class 7: Credit Markets and Regulation Risk
Class 8: Real Estate
Next Class<br>
slide4. 4 Today’s guest speaker Guest Speaker: Brian Ingram, Head of Investments, PingAn Russell, Shanghai
PAR is a joint venture between Russell Investments and the Chinese financial services conglomerate Ping An Group. PAR focuses exclusively on mainland Chinese public capital markets, including A-share equity and inter-bank fixed income. PAR’s primary international clients are QFII and RQFII institutional investors. As of November 2013, the firm manages about USD $480 million on behalf of domestic and international institutional clients.
Until 2010 Brian was a Senior Research Analyst with Russell in London
Brian is a graduate of Yale University.<br>
slide5. Class 6: Private Equity and Frontier Markets Private equity (PE) investments are equity (or equity-like) investments that are not traded on public exchanges.
Forms of PE:
Venture capital
LBO
Special situations (distressed investing)
Shared characteristics:
great uncertainty
difficult to value
asymmetric information
illiquid<br>
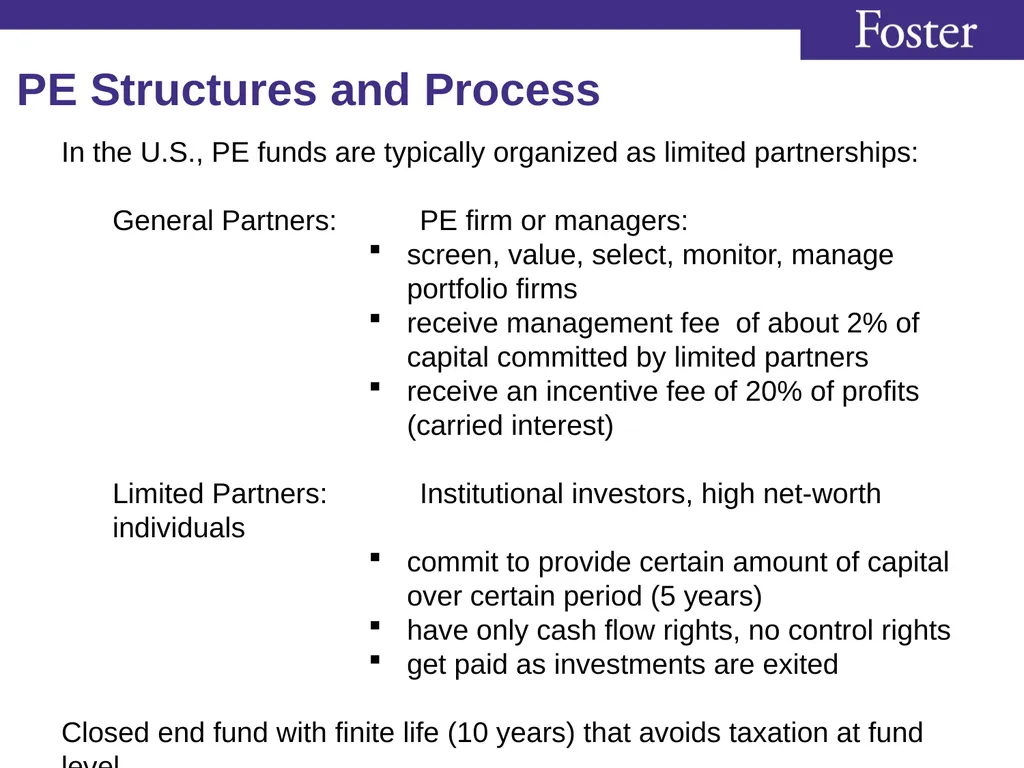
slide6. PE Structures and Process In the U.S., PE funds are typically organized as limited partnerships:
General Partners: PE firm or managers:
screen, value, select, monitor, manage portfolio firms
receive management fee of about 2% of capital committed by limited partners
receive an incentive fee of 20% of profits (carried interest)
Limited Partners: Institutional investors, high net-worth individuals
commit to provide certain amount of capital over certain period (5 years)
have only cash flow rights, no control rights
get paid as investments are exited
Closed end fund with finite life (10 years) that avoids taxation at fund level<br>
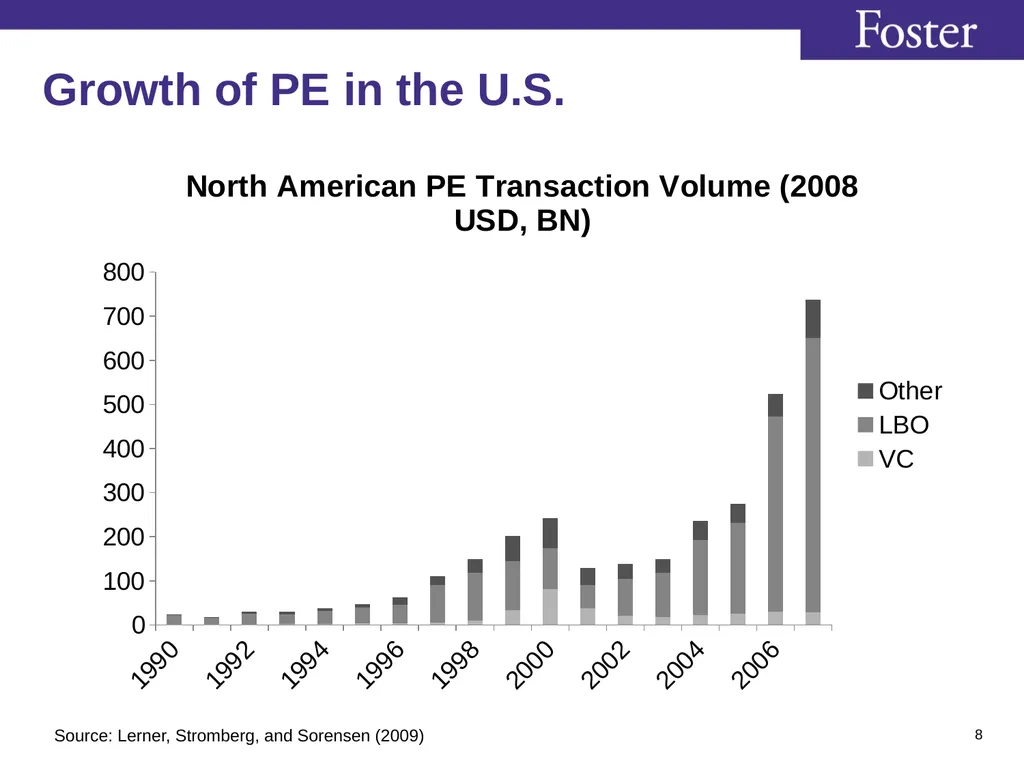
slide7. Growth of PE in the U.S. 7<br>
slide8. Growth of PE in the U.S. 8 Source: Lerner, Stromberg, and Sorensen (2009)<br>
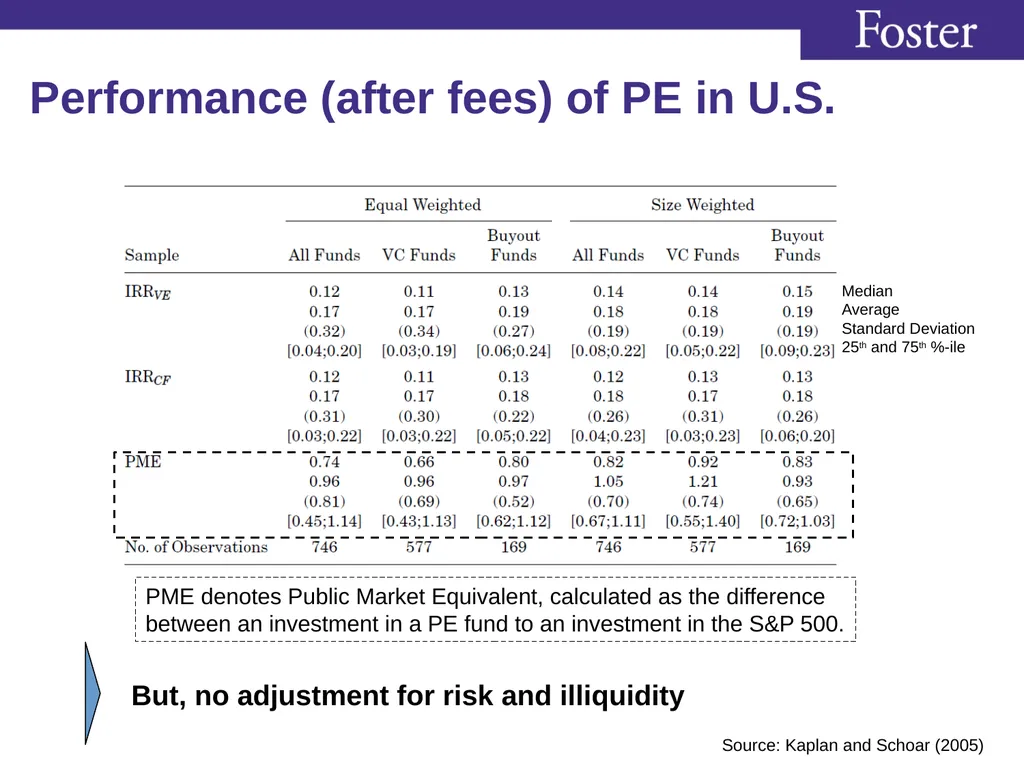
slide9. Performance (after fees) of PE in U.S. Median
Average
Standard Deviation
25th and 75th %-ile PME denotes Public Market Equivalent, calculated as the difference
between an investment in a PE fund to an investment in the S&P 500. But, no adjustment for risk and illiquidity Source: Kaplan and Schoar (2005)<br>
slide10. Performance (after fees) of PE in U.S. Risk might be higher than benchmark (S&P 500)
VC funds essentially invest in growth firms. Growth firms have betas > 1.
LBO use substantial leverage
Using an industry- and size-matched benchmark, performance drops by about 3 percentage point (to underperformance of 6% in study by Phalippou and Gottschlage (2008))<br>
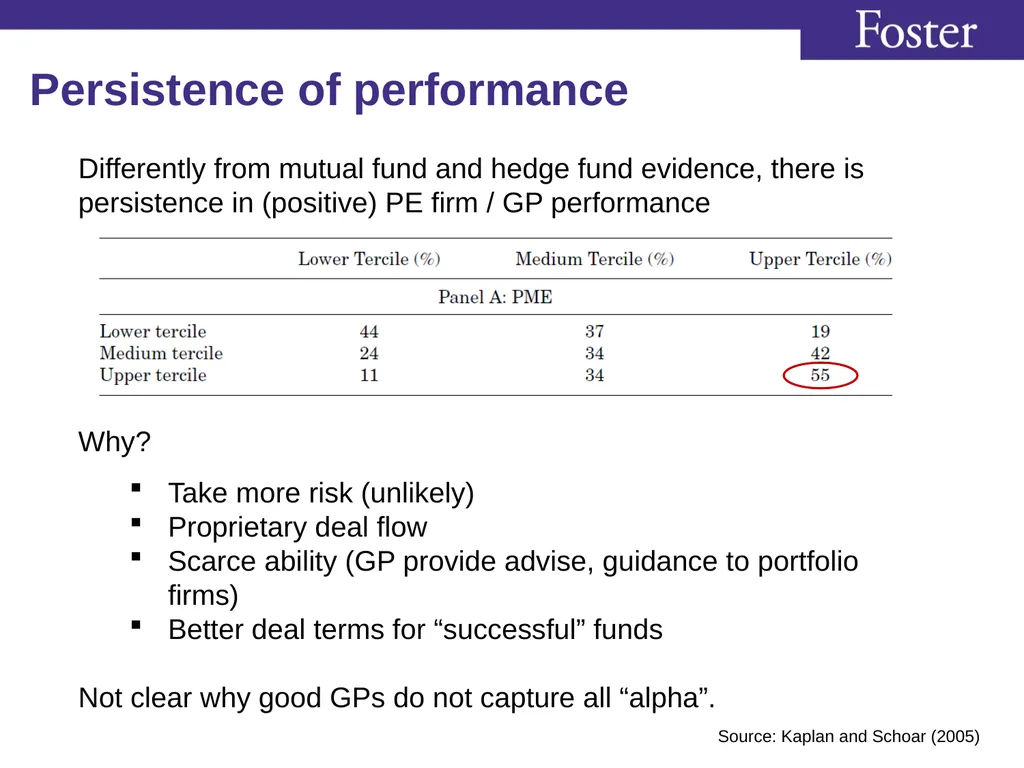
slide11. Persistence of performance Differently from mutual fund and hedge fund evidence, there is persistence in (positive) PE firm / GP performance
Why?
Take more risk (unlikely)
Proprietary deal flow
Scarce ability (GP provide advise, guidance to portfolio firms)
Better deal terms for “successful” funds
Not clear why good GPs do not capture all “alpha”. Source: Kaplan and Schoar (2005)<br>
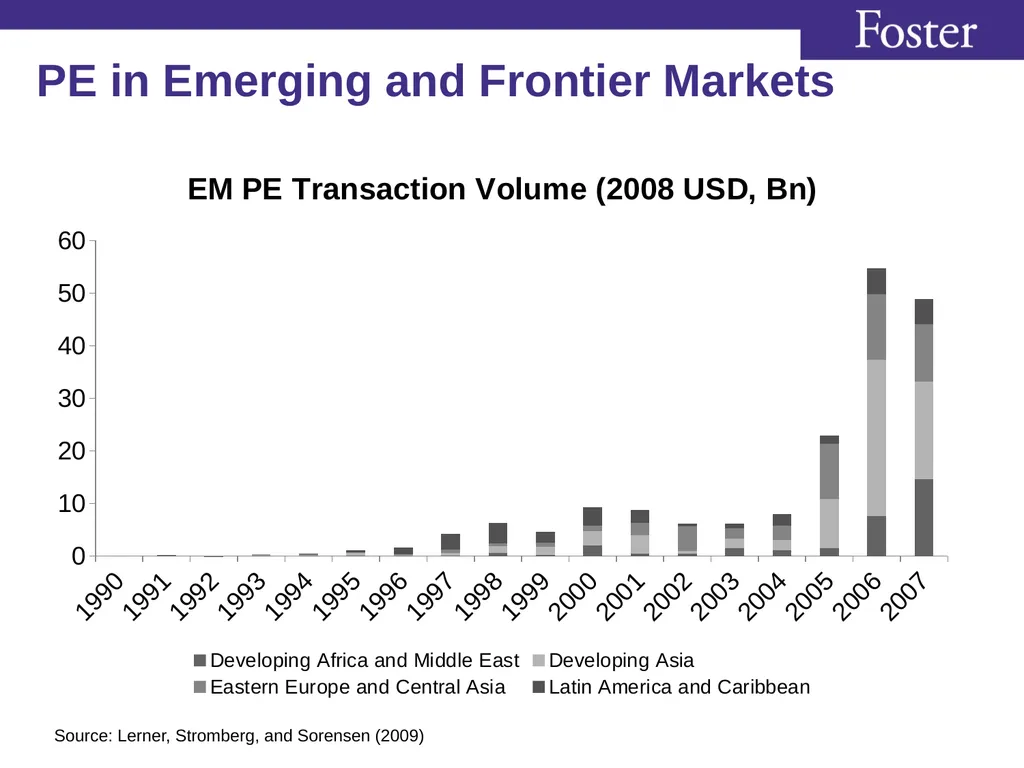
slide12. PE in Emerging and Frontier Markets Source: Lerner, Stromberg, and Sorensen (2009)<br>
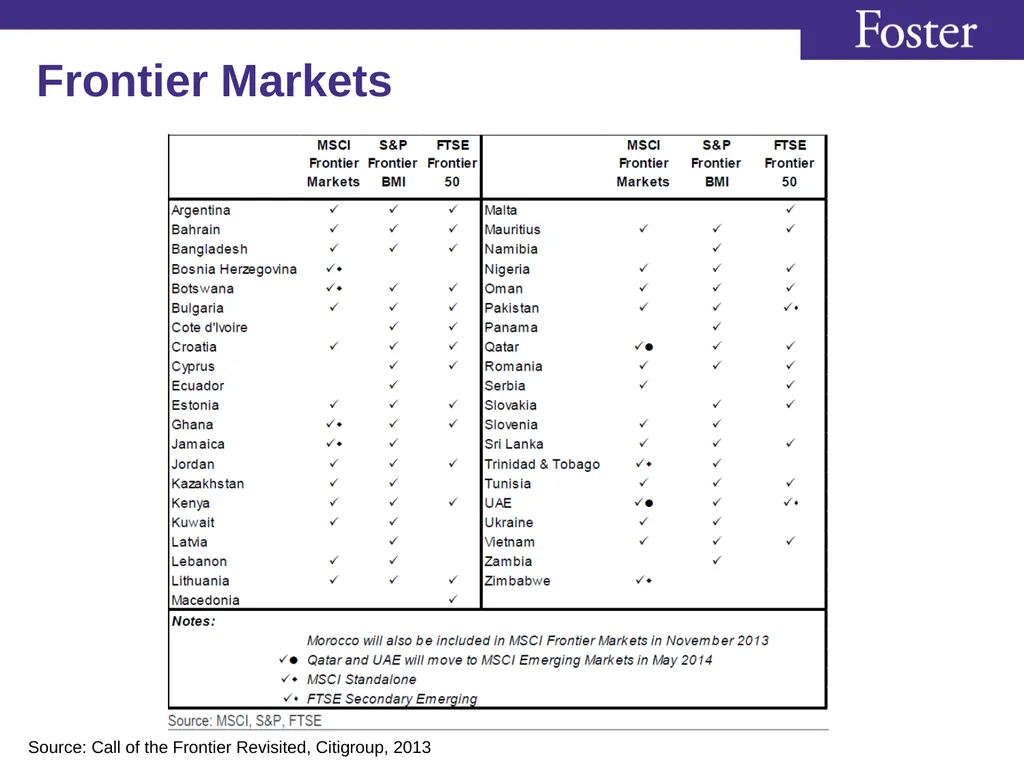
slide13. Frontier Markets Source: Call of the Frontier Revisited, Citigroup, 2013<br>
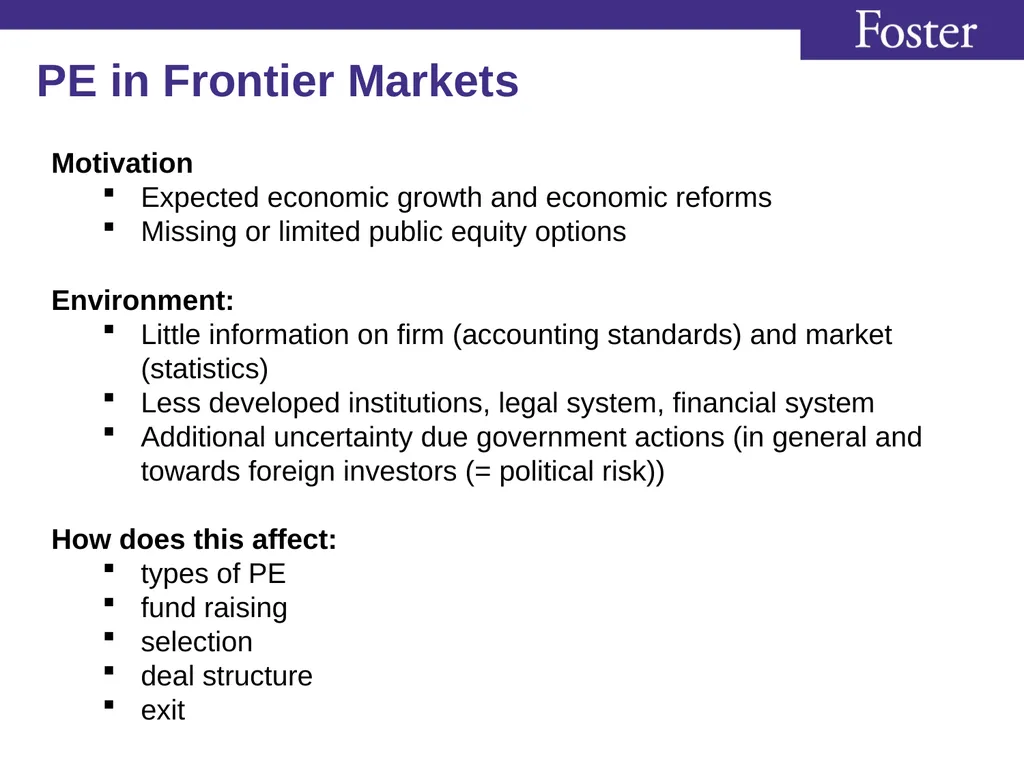
slide14. PE in Frontier Markets Motivation
Expected economic growth and economic reforms
Missing or limited public equity options
Environment:
Little information on firm (accounting standards) and market (statistics)
Less developed institutions, legal system, financial system
Additional uncertainty due government actions (in general and towards foreign investors (= political risk))
How does this affect:
types of PE
fund raising
selection
deal structure
exit<br>
slide15. Class 7: Credit Markets and Regulation Risk Debt Securities Government bonds
Corporate bonds
Investment grade
High yield
Structured finance (eg CDOs) Financial Institutions Banks
Shadow banks
Microfinance institutions<br>
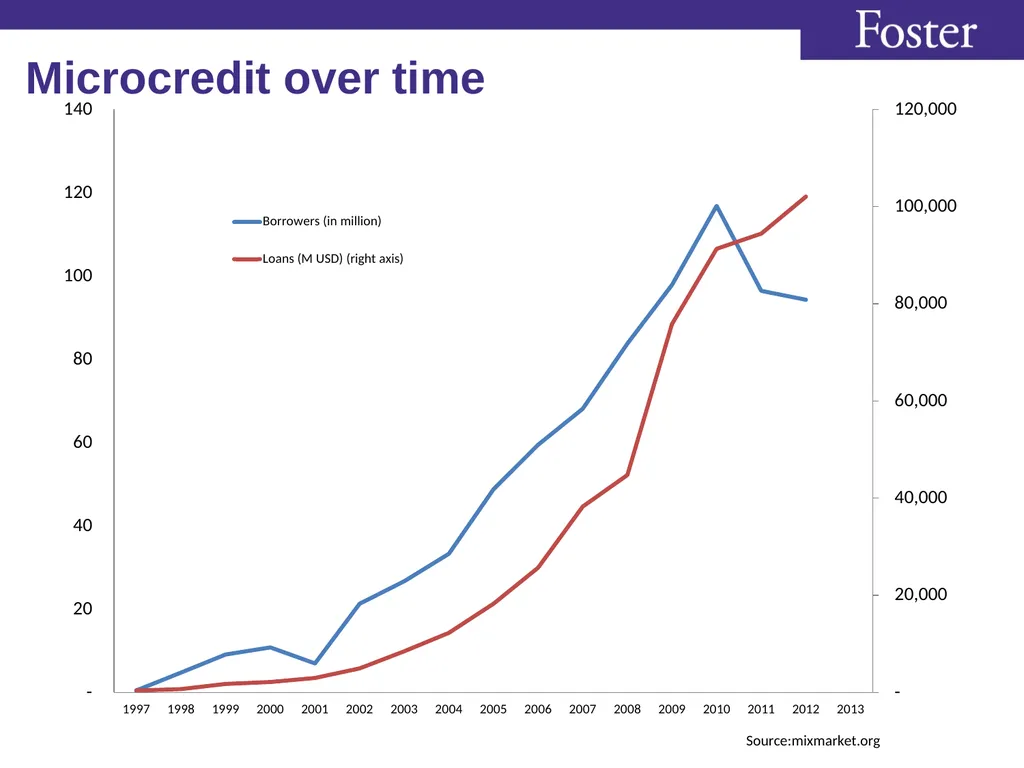
slide16. Microcredit over time<br>
slide17. Microfinance as an asset class Microfinance institutions (MFI) started as non-for profit organization providing credit to poor people.
Today, increasingly for profit, providing many financial services, including savings tools.
Investors can get exposure to MFI at least in two ways:
Microfinance Investment Vehicles (MIVs) (at least 90 globally, with about USD 8 B in AUM (end of 2012)
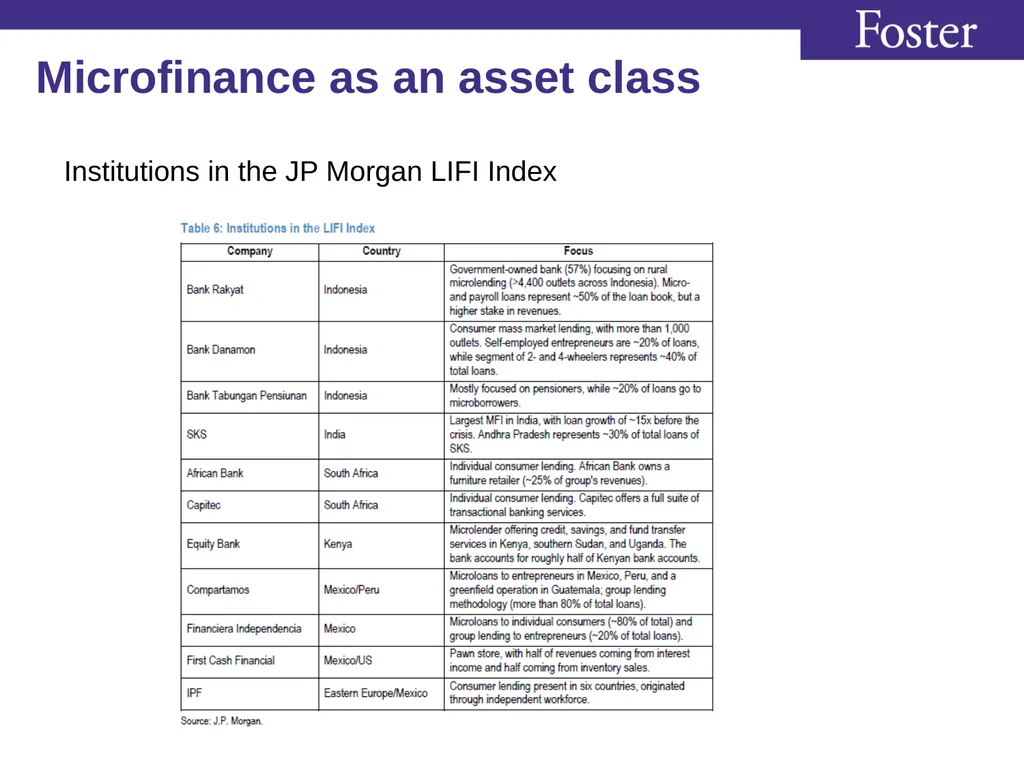
Equity of eleven publicly traded financial firms that target low income customers (JP Morgan LIFI (Lower Income Finance) Index)<br>
slide18. Microfinance as an asset class Institutions in the JP Morgan LIFI Index<br>
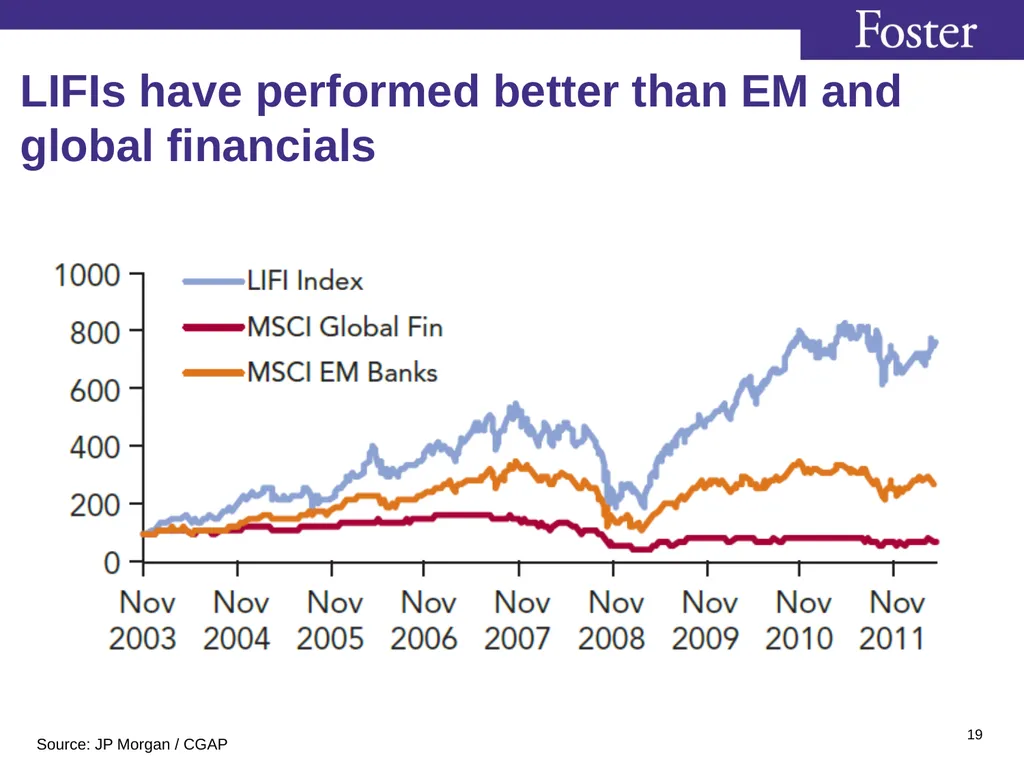
slide19. 19 LIFIs have performed better than EM and global financials Source: JP Morgan / CGAP<br>
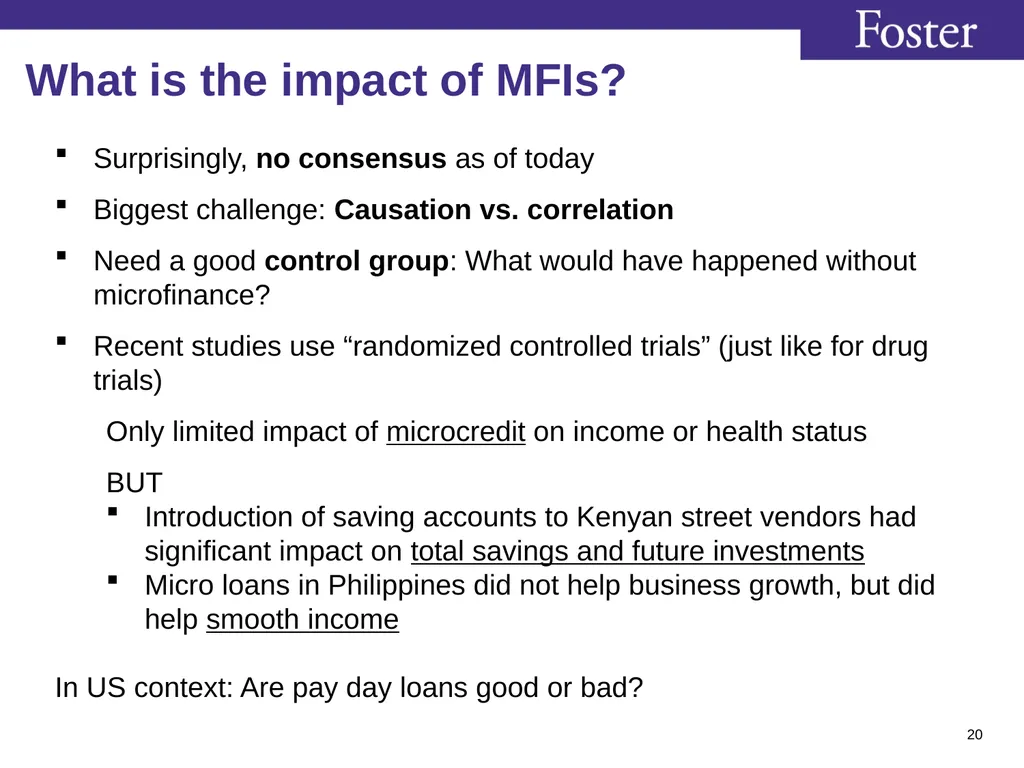
slide20. 20 What is the impact of MFIs? Surprisingly, no consensus as of today
Biggest challenge: Causation vs. correlation
Need a good control group: What would have happened without microfinance?
Recent studies use “randomized controlled trials” (just like for drug trials)
Only limited impact of microcredit on income or health status
BUT
Introduction of saving accounts to Kenyan street vendors had significant impact on total savings and future investments
Micro loans in Philippines did not help business growth, but did help smooth income
In US context: Are pay day loans good or bad?<br>
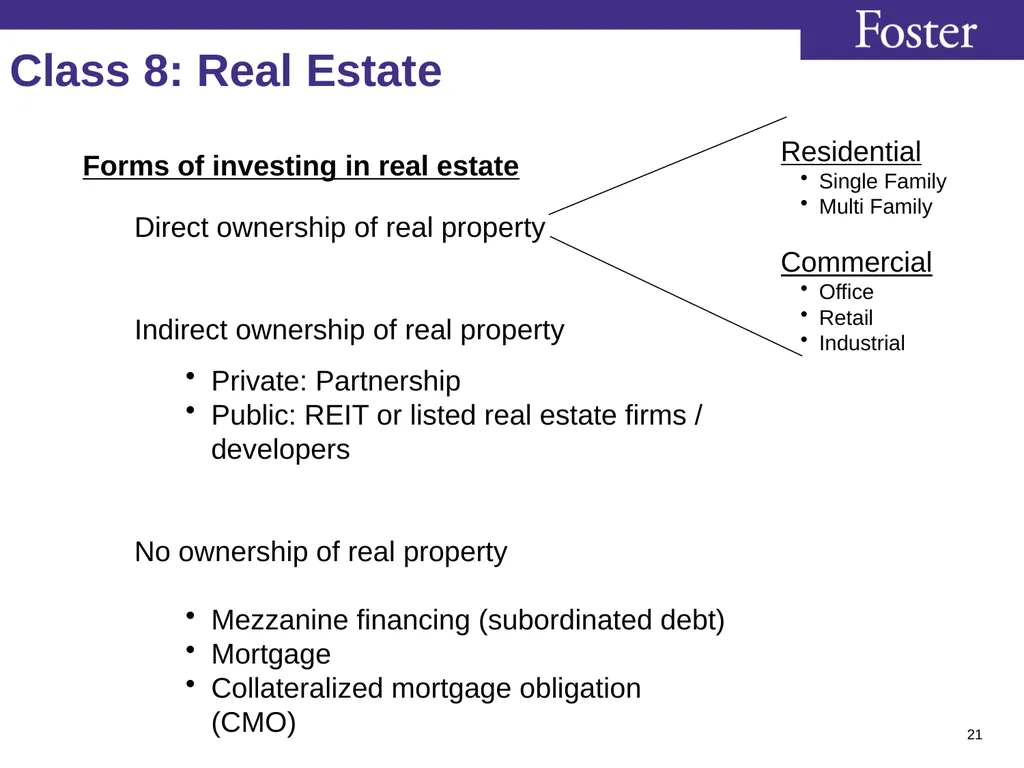
slide21. 21 Forms of investing in real estate Direct ownership of real property
Indirect ownership of real property
Private: Partnership
Public: REIT or listed real estate firms / developers
No ownership of real property
Mezzanine financing (subordinated debt)
Mortgage
Collateralized mortgage obligation (CMO) Residential
Single Family
Multi Family
Commercial
Office
Retail
Industrial Class 8: Real Estate<br>
slide22. 22 Diversification Price of any asset = Why do prices move? discount rate changes
expected FCF changes Why do prices of different assets co-move? Discount rates and / or free cash flows share common component and change in a related fashion<br>
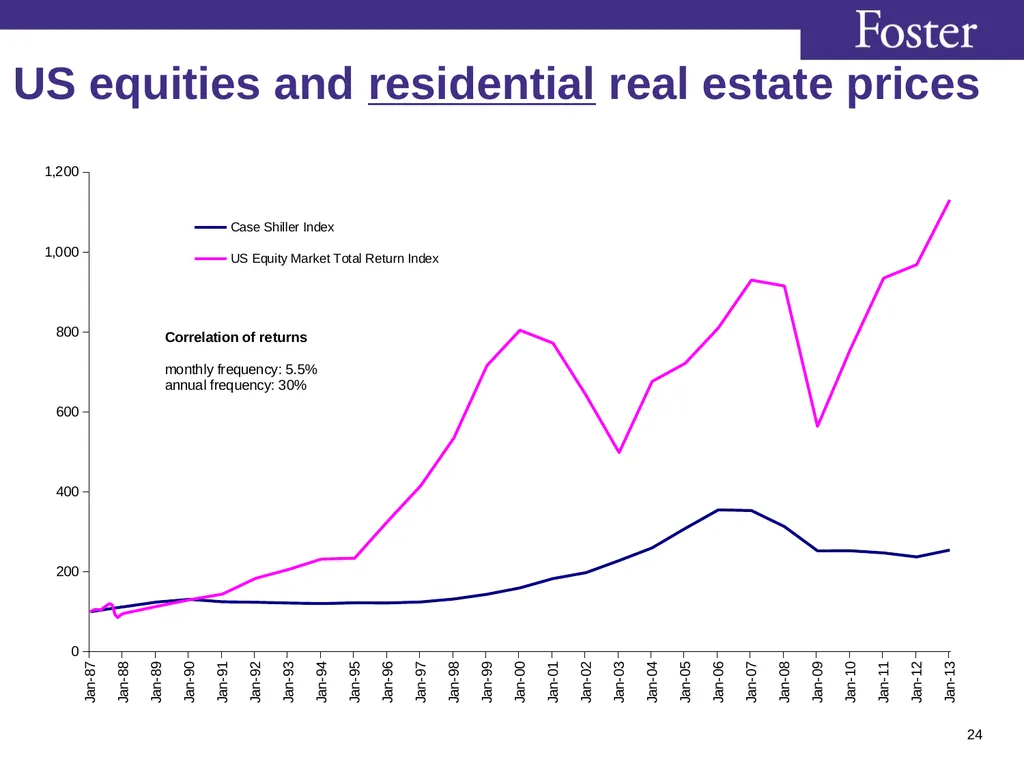
slide23. 23 Local equity and local real estate returns Do you think equity and real estate returns are correlated? common business cycle effect on earnings / rents
real interest rates
risk aversion drives risk premia that enter both discount rates Are they correlated? mixed evidence:
early studies found zero correlation between annual equity returns and annual commercial or residential real estate returns
Quan and Titman (1999) use 14 years of returns for 17 countries and find a correlation of 38% (for commercial real estate).<br>
slide24. 24 US equities and residential real estate prices<br>
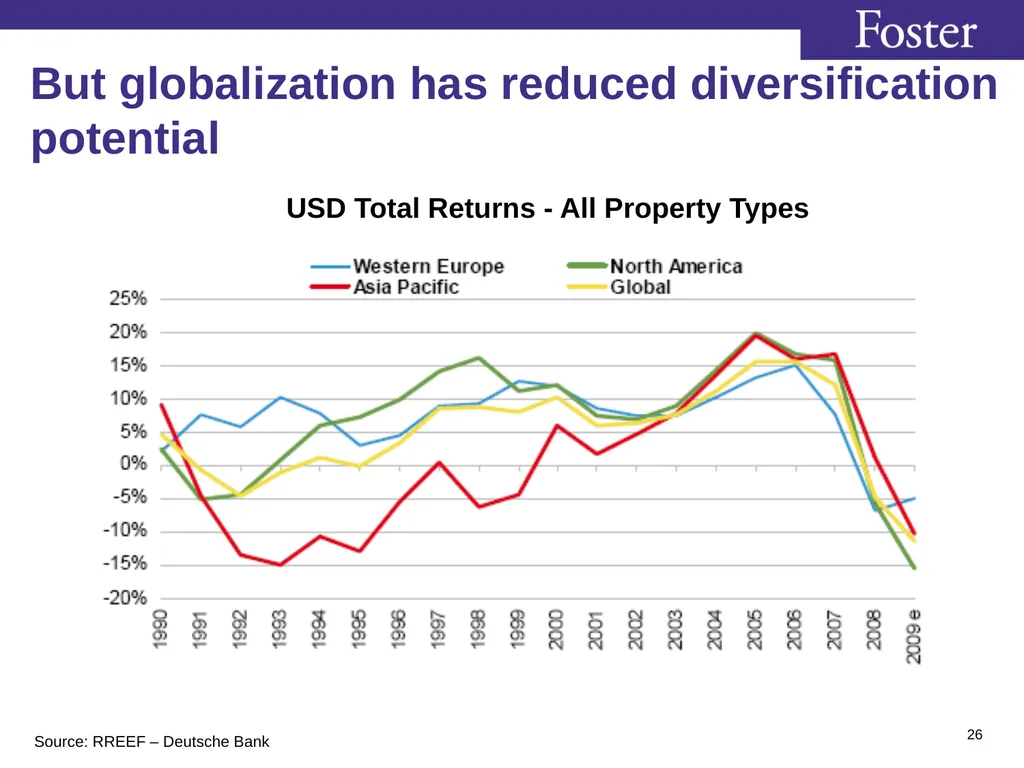
slide25. 25 Diversification potential in international real estate Are (commercial) real estate returns correlated across countries?
NO
markets are segmented
asset is immobile
short-term arbitrage is not possible
YES
GDP is correlated across countries
financial markets are (partially) integrated, discount rates are correlated
Empirical Evidence?
Average correlation between 21 countries 1987–1997:
Office: 44% Retail: 36% Industrial 33%<br>
slide26. 26 But globalization has reduced diversification potential USD Total Returns - All Property Types Source: RREEF – Deutsche Bank<br>
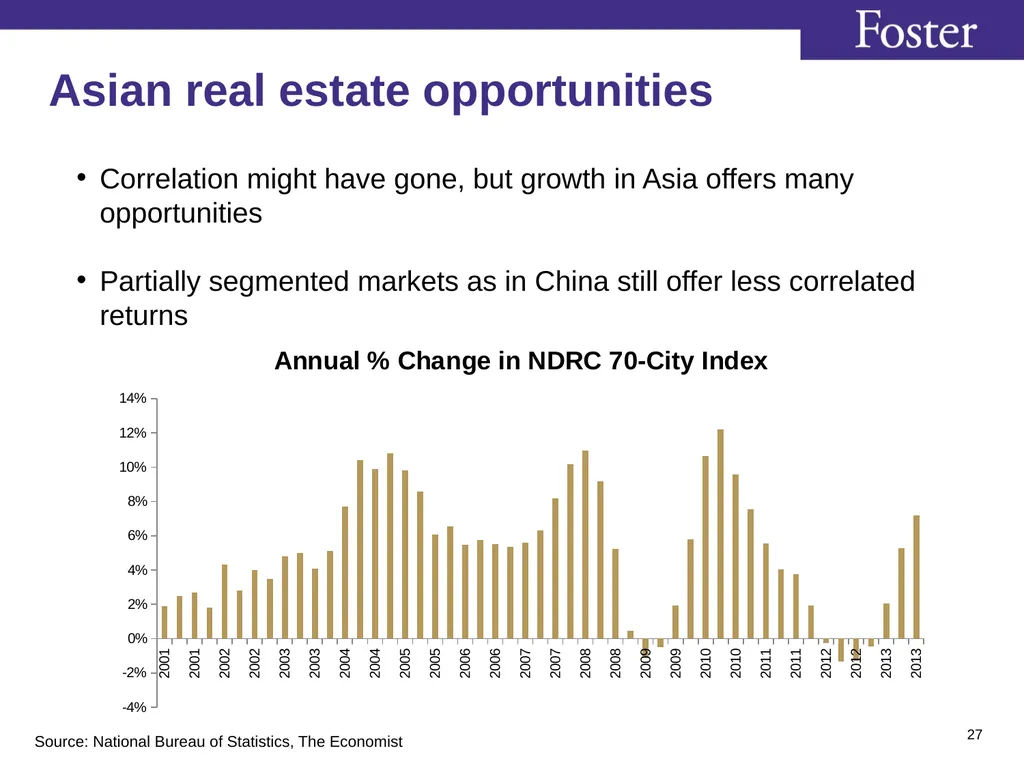
slide27. 27 Asian real estate opportunities Correlation might have gone, but growth in Asia offers many opportunities
Partially segmented markets as in China still offer less correlated returns Source: National Bureau of Statistics, The Economist<br>
slide28. Class 5: Panel Discussion Guests:
Keith Ferguson, CIO, University of Washington
Mark Whitmore, CEO, Whitmore Capital Management
Gerard Fitzpatrick, CIO, Fixed-income Portfolios, Russell
Prepare questions for panelists. Email me your “best” question by Sunday (for participation credit).<br>
Asian Capital Markets (FIN579) Stephan Siegel<br>
slide2. 2 Admin Topic Write-up: Update
Name Tents
Panel Discussion: February 10
Keith Ferguson, CIO, University of Washington
Mark Whitmore, CEO, Whitmore Capital Management
Gerard Fitzpatrick, CIO, Fixed-income Portfolios, Russell
Prepare questions for panelists. Email me your “best” question by Sunday (for participation credit).<br>
slide3. 3 Class 4 Guest Speaker: Brian Ingram, Head of Investments, PingAn Russell, Shanghai
Lecture in preparation of Classes 6, 7, and 8
Class 6: Private Equity and Frontier Markets
Class 7: Credit Markets and Regulation Risk
Class 8: Real Estate
Next Class<br>
slide4. 4 Today’s guest speaker Guest Speaker: Brian Ingram, Head of Investments, PingAn Russell, Shanghai
PAR is a joint venture between Russell Investments and the Chinese financial services conglomerate Ping An Group. PAR focuses exclusively on mainland Chinese public capital markets, including A-share equity and inter-bank fixed income. PAR’s primary international clients are QFII and RQFII institutional investors. As of November 2013, the firm manages about USD $480 million on behalf of domestic and international institutional clients.
Until 2010 Brian was a Senior Research Analyst with Russell in London
Brian is a graduate of Yale University.<br>
slide5. Class 6: Private Equity and Frontier Markets Private equity (PE) investments are equity (or equity-like) investments that are not traded on public exchanges.
Forms of PE:
Venture capital
LBO
Special situations (distressed investing)
Shared characteristics:
great uncertainty
difficult to value
asymmetric information
illiquid<br>
slide6. PE Structures and Process In the U.S., PE funds are typically organized as limited partnerships:
General Partners: PE firm or managers:
screen, value, select, monitor, manage portfolio firms
receive management fee of about 2% of capital committed by limited partners
receive an incentive fee of 20% of profits (carried interest)
Limited Partners: Institutional investors, high net-worth individuals
commit to provide certain amount of capital over certain period (5 years)
have only cash flow rights, no control rights
get paid as investments are exited
Closed end fund with finite life (10 years) that avoids taxation at fund level<br>
slide7. Growth of PE in the U.S. 7<br>
slide8. Growth of PE in the U.S. 8 Source: Lerner, Stromberg, and Sorensen (2009)<br>
slide9. Performance (after fees) of PE in U.S. Median
Average
Standard Deviation
25th and 75th %-ile PME denotes Public Market Equivalent, calculated as the difference
between an investment in a PE fund to an investment in the S&P 500. But, no adjustment for risk and illiquidity Source: Kaplan and Schoar (2005)<br>
slide10. Performance (after fees) of PE in U.S. Risk might be higher than benchmark (S&P 500)
VC funds essentially invest in growth firms. Growth firms have betas > 1.
LBO use substantial leverage
Using an industry- and size-matched benchmark, performance drops by about 3 percentage point (to underperformance of 6% in study by Phalippou and Gottschlage (2008))<br>
slide11. Persistence of performance Differently from mutual fund and hedge fund evidence, there is persistence in (positive) PE firm / GP performance
Why?
Take more risk (unlikely)
Proprietary deal flow
Scarce ability (GP provide advise, guidance to portfolio firms)
Better deal terms for “successful” funds
Not clear why good GPs do not capture all “alpha”. Source: Kaplan and Schoar (2005)<br>
slide12. PE in Emerging and Frontier Markets Source: Lerner, Stromberg, and Sorensen (2009)<br>
slide13. Frontier Markets Source: Call of the Frontier Revisited, Citigroup, 2013<br>
slide14. PE in Frontier Markets Motivation
Expected economic growth and economic reforms
Missing or limited public equity options
Environment:
Little information on firm (accounting standards) and market (statistics)
Less developed institutions, legal system, financial system
Additional uncertainty due government actions (in general and towards foreign investors (= political risk))
How does this affect:
types of PE
fund raising
selection
deal structure
exit<br>
slide15. Class 7: Credit Markets and Regulation Risk Debt Securities Government bonds
Corporate bonds
Investment grade
High yield
Structured finance (eg CDOs) Financial Institutions Banks
Shadow banks
Microfinance institutions<br>
slide16. Microcredit over time<br>
slide17. Microfinance as an asset class Microfinance institutions (MFI) started as non-for profit organization providing credit to poor people.
Today, increasingly for profit, providing many financial services, including savings tools.
Investors can get exposure to MFI at least in two ways:
Microfinance Investment Vehicles (MIVs) (at least 90 globally, with about USD 8 B in AUM (end of 2012)
Equity of eleven publicly traded financial firms that target low income customers (JP Morgan LIFI (Lower Income Finance) Index)<br>
slide18. Microfinance as an asset class Institutions in the JP Morgan LIFI Index<br>
slide19. 19 LIFIs have performed better than EM and global financials Source: JP Morgan / CGAP<br>
slide20. 20 What is the impact of MFIs? Surprisingly, no consensus as of today
Biggest challenge: Causation vs. correlation
Need a good control group: What would have happened without microfinance?
Recent studies use “randomized controlled trials” (just like for drug trials)
Only limited impact of microcredit on income or health status
BUT
Introduction of saving accounts to Kenyan street vendors had significant impact on total savings and future investments
Micro loans in Philippines did not help business growth, but did help smooth income
In US context: Are pay day loans good or bad?<br>
slide21. 21 Forms of investing in real estate Direct ownership of real property
Indirect ownership of real property
Private: Partnership
Public: REIT or listed real estate firms / developers
No ownership of real property
Mezzanine financing (subordinated debt)
Mortgage
Collateralized mortgage obligation (CMO) Residential
Single Family
Multi Family
Commercial
Office
Retail
Industrial Class 8: Real Estate<br>
slide22. 22 Diversification Price of any asset = Why do prices move? discount rate changes
expected FCF changes Why do prices of different assets co-move? Discount rates and / or free cash flows share common component and change in a related fashion<br>
slide23. 23 Local equity and local real estate returns Do you think equity and real estate returns are correlated? common business cycle effect on earnings / rents
real interest rates
risk aversion drives risk premia that enter both discount rates Are they correlated? mixed evidence:
early studies found zero correlation between annual equity returns and annual commercial or residential real estate returns
Quan and Titman (1999) use 14 years of returns for 17 countries and find a correlation of 38% (for commercial real estate).<br>
slide24. 24 US equities and residential real estate prices<br>
slide25. 25 Diversification potential in international real estate Are (commercial) real estate returns correlated across countries?
NO
markets are segmented
asset is immobile
short-term arbitrage is not possible
YES
GDP is correlated across countries
financial markets are (partially) integrated, discount rates are correlated
Empirical Evidence?
Average correlation between 21 countries 1987–1997:
Office: 44% Retail: 36% Industrial 33%<br>
slide26. 26 But globalization has reduced diversification potential USD Total Returns - All Property Types Source: RREEF – Deutsche Bank<br>
slide27. 27 Asian real estate opportunities Correlation might have gone, but growth in Asia offers many opportunities
Partially segmented markets as in China still offer less correlated returns Source: National Bureau of Statistics, The Economist<br>
slide28. Class 5: Panel Discussion Guests:
Keith Ferguson, CIO, University of Washington
Mark Whitmore, CEO, Whitmore Capital Management
Gerard Fitzpatrick, CIO, Fixed-income Portfolios, Russell
Prepare questions for panelists. Email me your “best” question by Sunday (for participation credit).<br>