Credit unions, big data and analytics Paul A Jones PhD Research Unit for Financial Inclusion Personal Indebtedness in the EU Wednesday 7th December 2016 EU Parliament, Brussels Traditional CU credit assessment Saving and credit history in
"Credit unions, big data and analytics Paul A Jones" is the property of its rightful owner. Permission is granted to
download and print the materials on this website for personal, non-commercial use only, and to display it
on your personal computer provided you do not modify the materials and that you retain all copyright
notices contained in the materials. By downloading content from our website, you accept the terms of this
agreement.
Presentation Transcript
01
Credit unions, big data and analytics Paul A Jones PhD
Research Unit for Financial Inclusion
Personal Indebtedness in the EU
Wednesday 7th December 2016
EU Parliament, Brussels<br>
02
Traditional CU credit assessment Saving and credit history in the CU
Knowing the member – social and family networks
Character and good standing
Income and expenditure analysis
Bank statements
Affordabilty check<br>
03
Move to Automated Lending Decisioning Use of external credit reference agency
Credit history - positive and negative
Utility company repayments
Mobile phone contracts
Court judgements
Which also increasingly capture data from:
Many high-cost alternative lenders
Rent payments in some social housing<br>
Would greater use of big data scoring help? For people with thick credit history data
Probably not – credit history is best guide to future credit affordability
For people with thin credit history data
BD offers insight into behaviour and lifestyle
Perhaps would give confidence to lend
Alternative credit scoring approaches
Based on data voluntarily provided
Sometimes psychological and attitudinal profiling
Claimed can improve credit score<br>
06
Concerns about use of big data Consent
Transparency and right to know
Value judgements on lifestyle – who is making the judgements and to what end?
Intrusion – e.g. use of telephone logs
Few industry standards
Regulation and compliance
But clearly will be increasingly an issue<br>
07
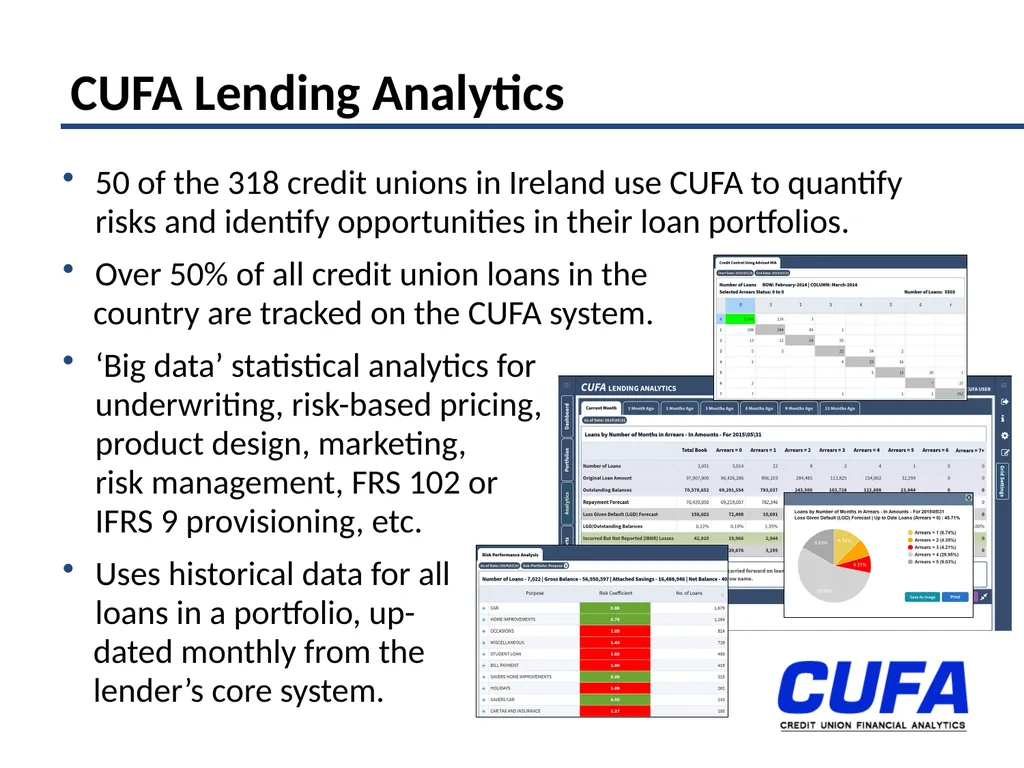
CUFA Lending Analytics 50 of the 318 credit unions in Ireland use CUFA to quantify risks and identify opportunities in their loan portfolios.
Over 50% of all credit union loans in the
country are tracked on the CUFA system.
‘Big data’ statistical analytics for
underwriting, risk-based pricing,
product design, marketing,
risk management, FRS 102 or
IFRS 9 provisioning, etc.
Uses historical data for all
loans in a portfolio, up-
dated monthly from the
lender’s core system.<br>