
Currency Wars? Unconventional Monetary Policy Does
Description: Currency Wars? Unconventional Monetary Policy Does Not Stimulate Exports Andrew K. Rose Berkeley-Haas, ABFER, CEPR,NBER Motivation: What are the Export Effects of Unconventional Monetary Policy (UMP)? Were in the midst of an international
Related Topics
Download Presentation
"Currency Wars? Unconventional Monetary Policy Does" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Currency Wars?
Unconventional Monetary Policy Does Not Stimulate Exports Andrew K. Rose
Berkeley-Haas, ABFER, CEPR,NBER<br>
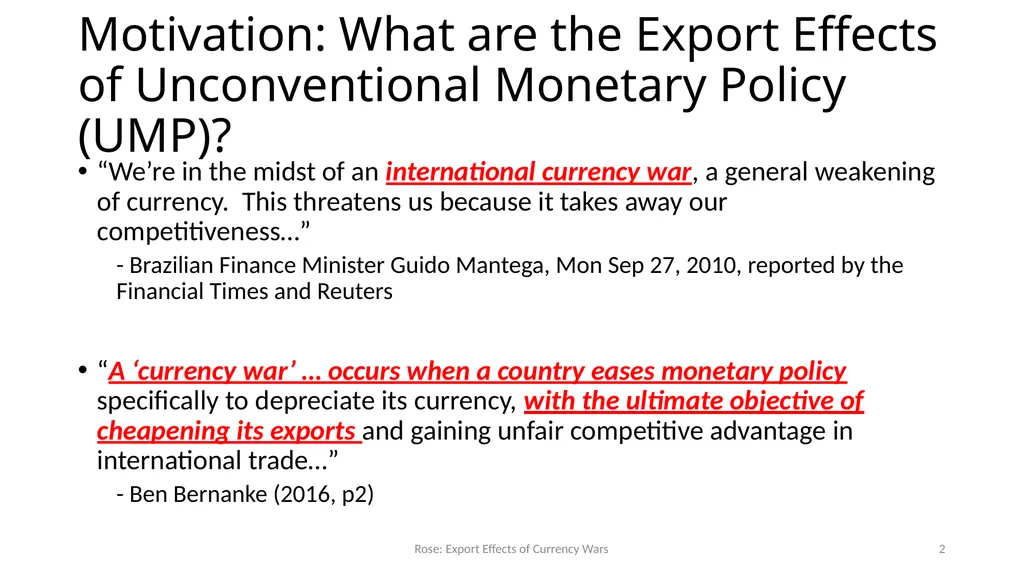
slide2. Motivation: What are the Export Effects of Unconventional Monetary Policy (UMP)? “We’re in the midst of an international currency war, a general weakening of currency. This threatens us because it takes away our competitiveness…”
- Brazilian Finance Minister Guido Mantega, Mon Sep 27, 2010, reported by the Financial Times and Reuters
“A ‘currency war’ … occurs when a country eases monetary policy specifically to depreciate its currency, with the ultimate objective of cheapening its exports and gaining unfair competitive advantage in international trade…”
- Ben Bernanke (2016, p2) 2 Rose: Export Effects of Currency Wars<br>
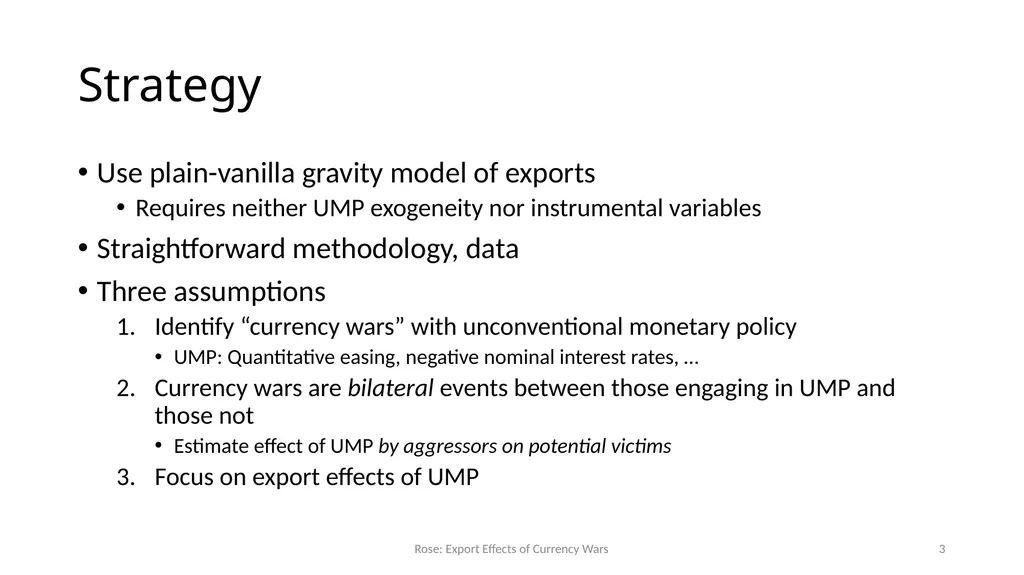
slide3. Strategy Use plain-vanilla gravity model of exports
Requires neither UMP exogeneity nor instrumental variables
Straightforward methodology, data
Three assumptions
Identify “currency wars” with unconventional monetary policy
UMP: Quantitative easing, negative nominal interest rates, …
Currency wars are bilateral events between those engaging in UMP and those not
Estimate effect of UMP by aggressors on potential victims
Focus on export effects of UMP 3 Rose: Export Effects of Currency Wars<br>
slide4. Preview of Findings Countries that engage in UMP experience drop in exports vis-à-vis countries that did not engage in UMP, ceteris paribus
Quantitative easing associated with drop in exports ≈10%
Highly statistically significant
Negative nominal interest rates have similar effect
No effect from conditional forward guidance policies
Any currency wars have been lost by aggressors! 4 Rose: Export Effects of Currency Wars<br>
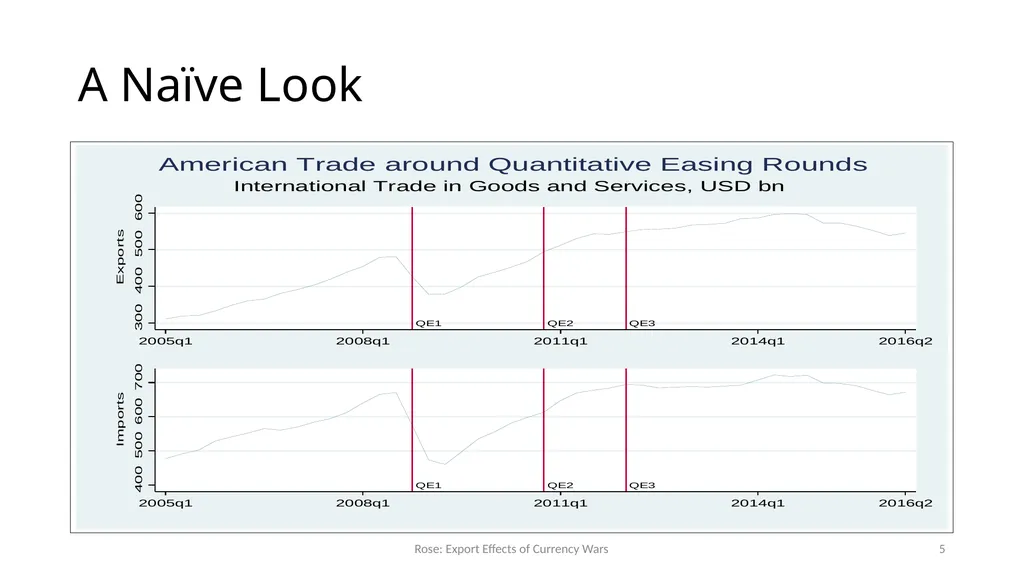
slide5. A Naïve Look 5 Rose: Export Effects of Currency Wars<br>
slide6. But that’s … Simplistic No obvious pattern:
Both exports and imports continue to drop following QE1, trends unaffected by QE2, stagnation unaffected by QE3
But …
Only US considered
Multilateral blurs American exports to importers engaged in their own UMP (EMU, Japan, UK, Switzerland, …) with exports to importers not engaged in UMP
No controls at all 6 Rose: Export Effects of Currency Wars<br>
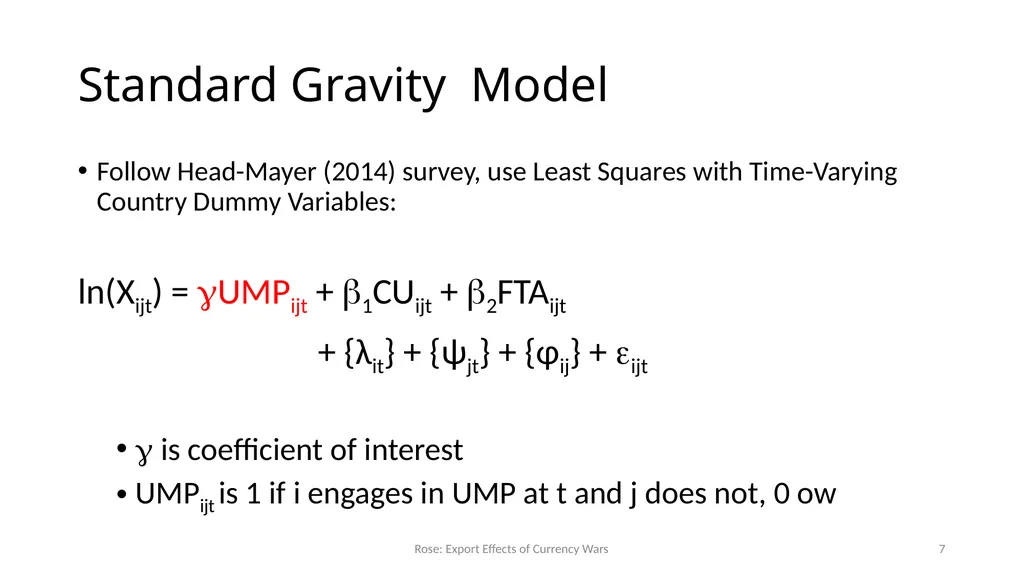
slide7. Standard Gravity Model Follow Head-Mayer (2014) survey, use Least Squares with Time-Varying Country Dummy Variables:
ln(Xijt) = UMPijt + 1CUijt + 2FTAijt
+ {λit} + {ψjt} + {φij} + ijt
is coefficient of interest
UMPijt is 1 if i engages in UMP at t and j does not, 0 ow 7 Rose: Export Effects of Currency Wars<br>
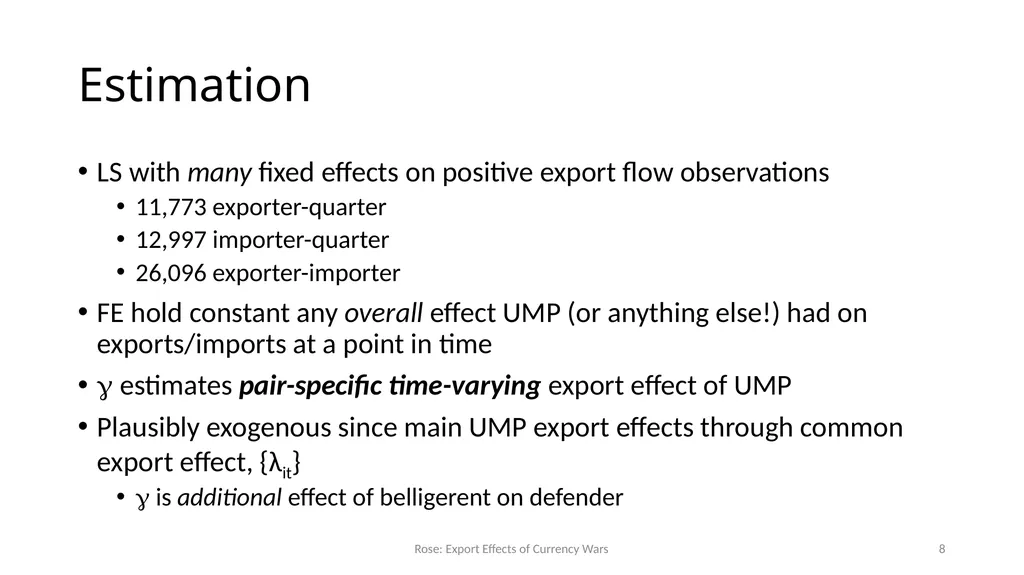
slide8. Estimation LS with many fixed effects on positive export flow observations
11,773 exporter-quarter
12,997 importer-quarter
26,096 exporter-importer
FE hold constant any overall effect UMP (or anything else!) had on exports/imports at a point in time
estimates pair-specific time-varying export effect of UMP
Plausibly exogenous since main UMP export effects through common export effect, {λit}
is additional effect of belligerent on defender 8 Rose: Export Effects of Currency Wars<br>
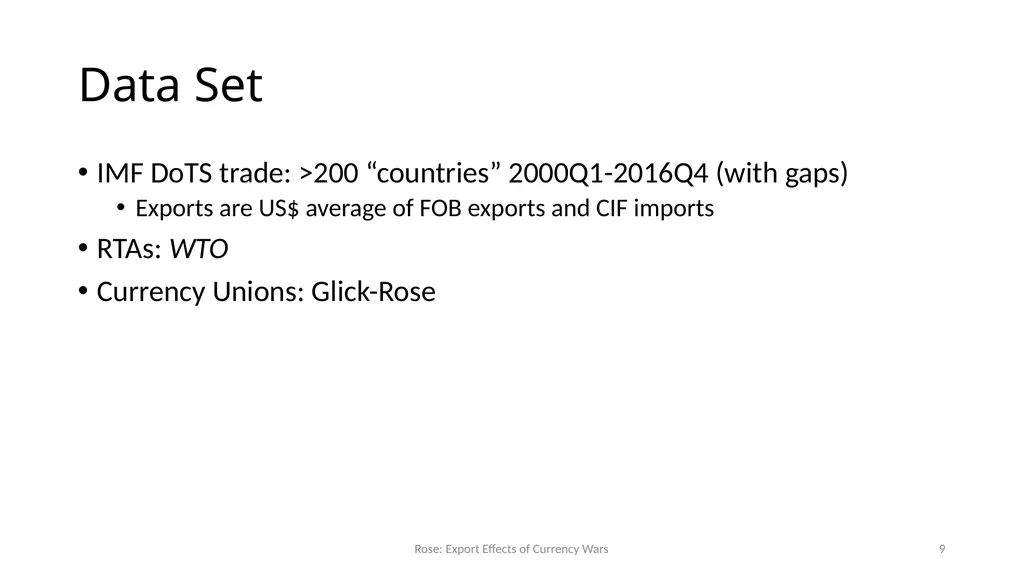
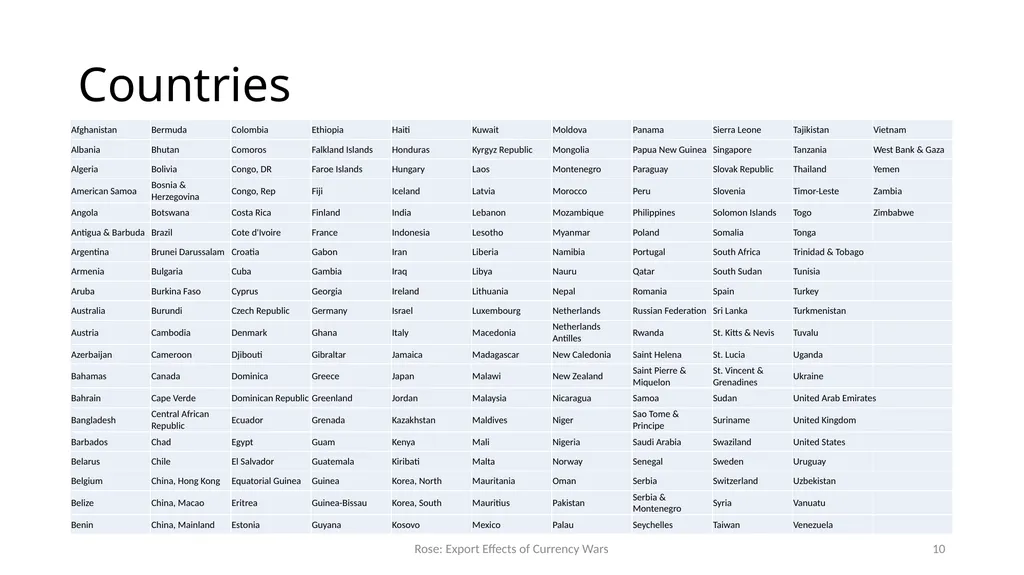
slide9. Data Set IMF DoTS trade: >200 “countries” 2000Q1-2016Q4 (with gaps)
Exports are US$ average of FOB exports and CIF imports
RTAs: WTO
Currency Unions: Glick-Rose 9 Rose: Export Effects of Currency Wars<br>
slide10. Countries 10 Rose: Export Effects of Currency Wars<br>
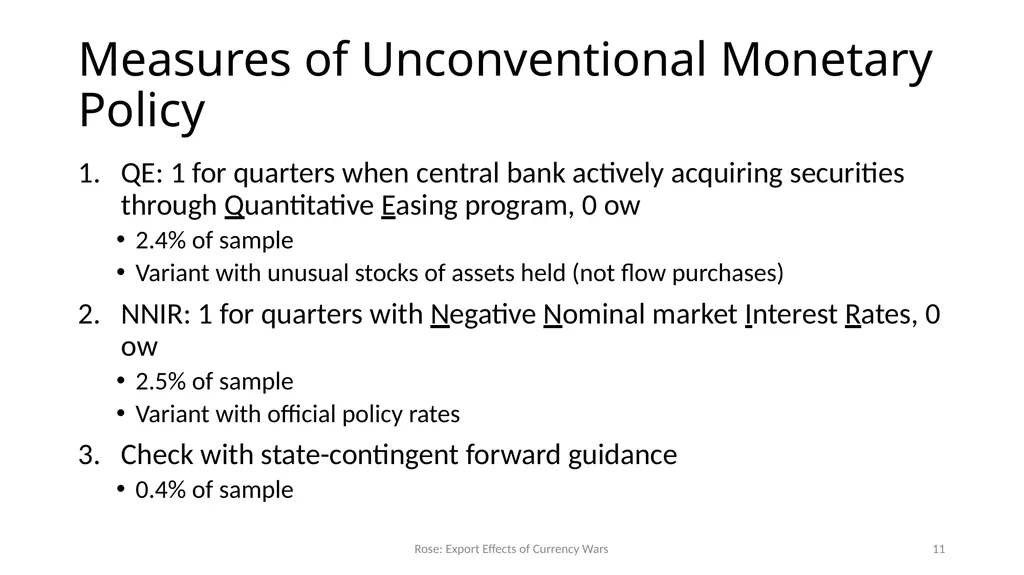
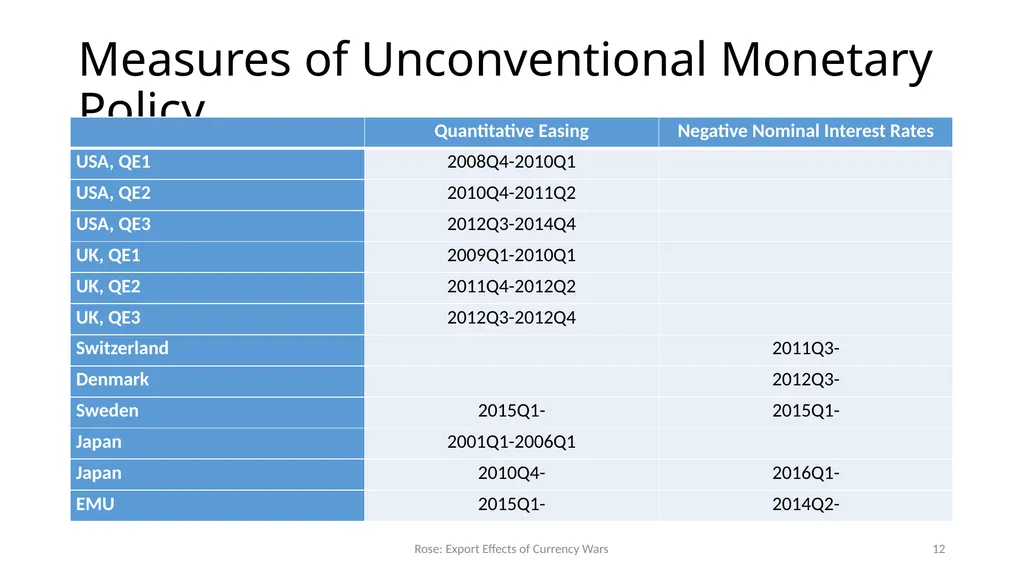
slide11. Measures of Unconventional Monetary Policy QE: 1 for quarters when central bank actively acquiring securities through Quantitative Easing program, 0 ow
2.4% of sample
Variant with unusual stocks of assets held (not flow purchases)
NNIR: 1 for quarters with Negative Nominal market Interest Rates, 0 ow
2.5% of sample
Variant with official policy rates
Check with state-contingent forward guidance
0.4% of sample 11 Rose: Export Effects of Currency Wars<br>
slide12. Measures of Unconventional Monetary Policy 12 Rose: Export Effects of Currency Wars<br>
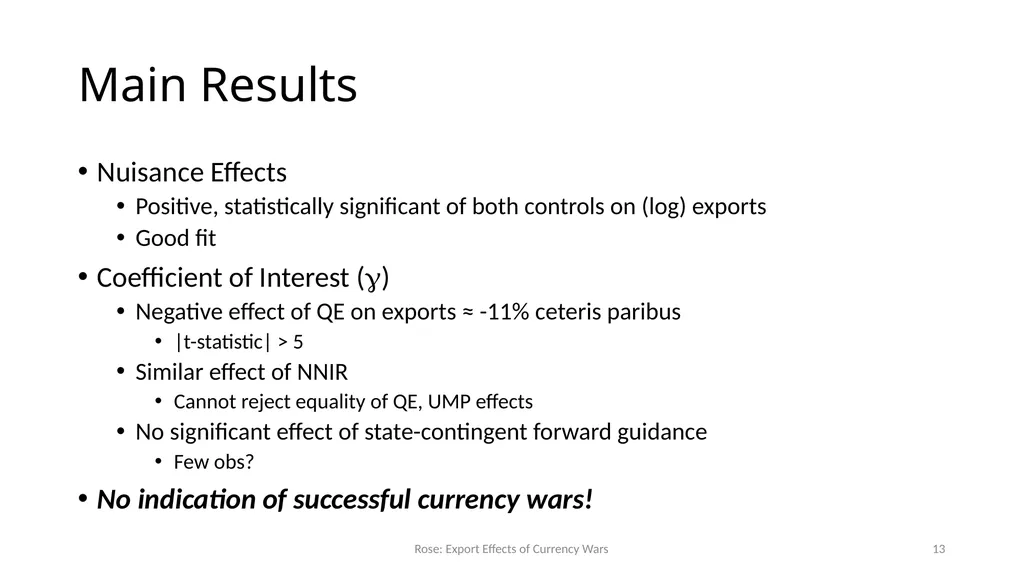
slide13. Main Results Nuisance Effects
Positive, statistically significant of both controls on (log) exports
Good fit
Coefficient of Interest ()
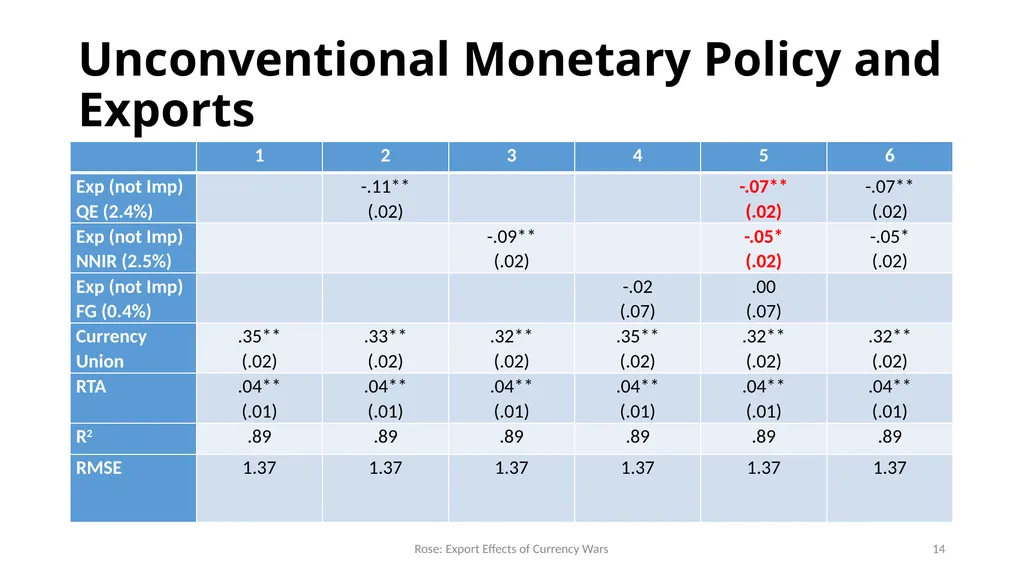
Negative effect of QE on exports ≈ -11% ceteris paribus
|t-statistic| > 5
Similar effect of NNIR
Cannot reject equality of QE, UMP effects
No significant effect of state-contingent forward guidance
Few obs?
No indication of successful currency wars! 13 Rose: Export Effects of Currency Wars<br>
slide14. Unconventional Monetary Policy and Exports 14 Rose: Export Effects of Currency Wars<br>
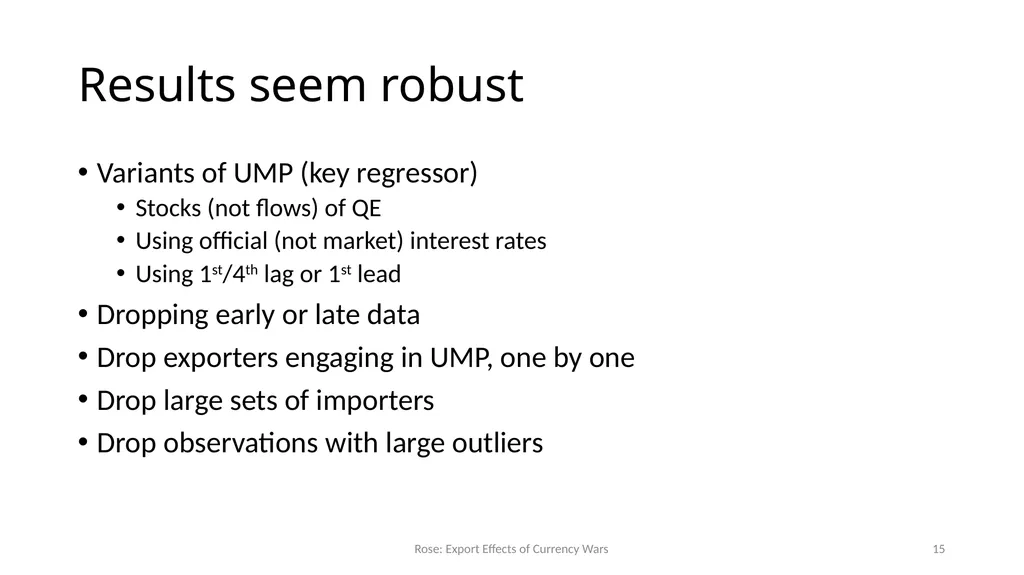
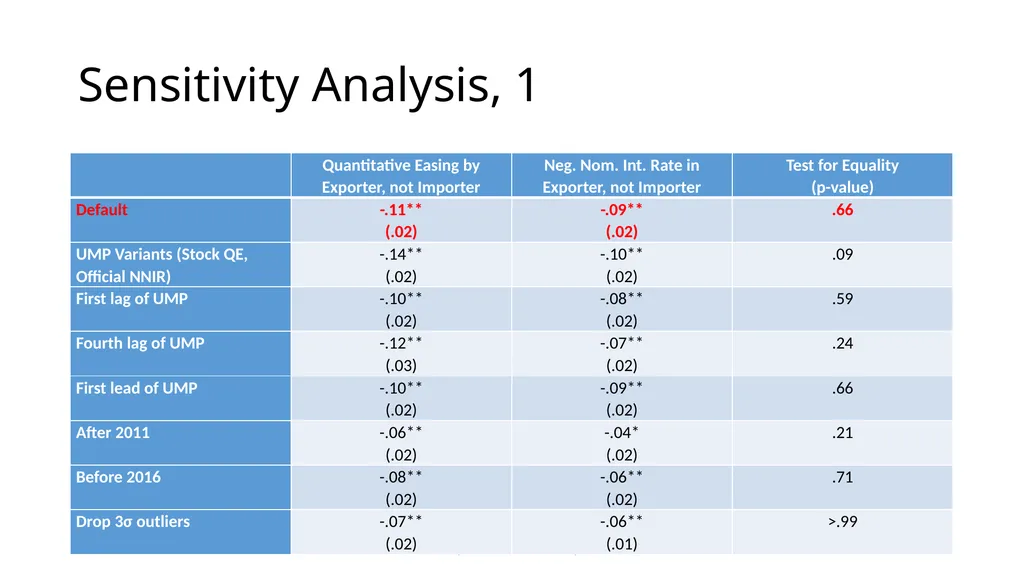
slide15. Results seem robust Variants of UMP (key regressor)
Stocks (not flows) of QE
Using official (not market) interest rates
Using 1st/4th lag or 1st lead
Dropping early or late data
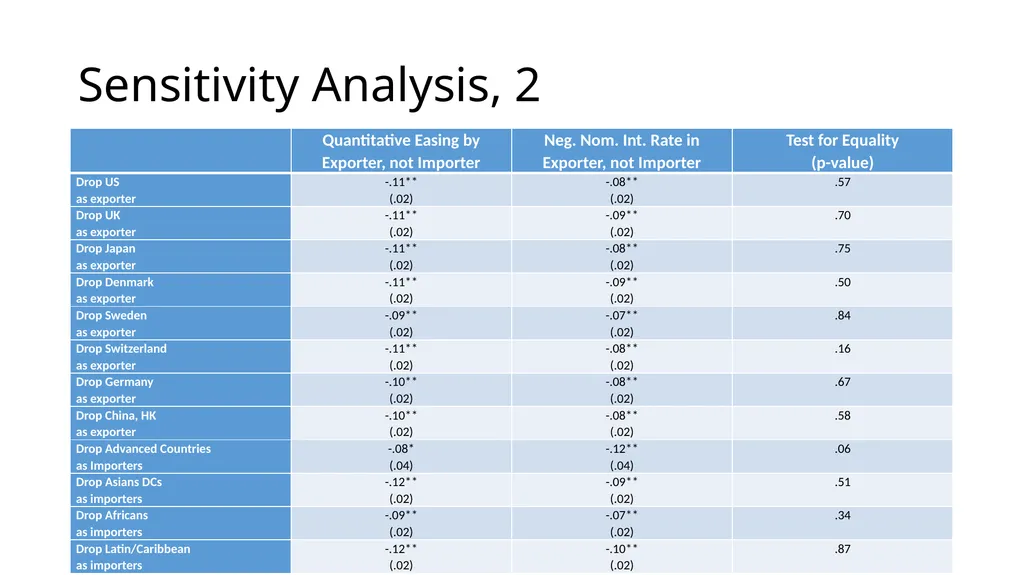
Drop exporters engaging in UMP, one by one
Drop large sets of importers
Drop observations with large outliers 15 Rose: Export Effects of Currency Wars<br>
slide16. Sensitivity Analysis, 1 16 Rose: Export Effects of Currency Wars<br>
slide17. Sensitivity Analysis, 2 17 Rose: Export Effects of Currency Wars<br>
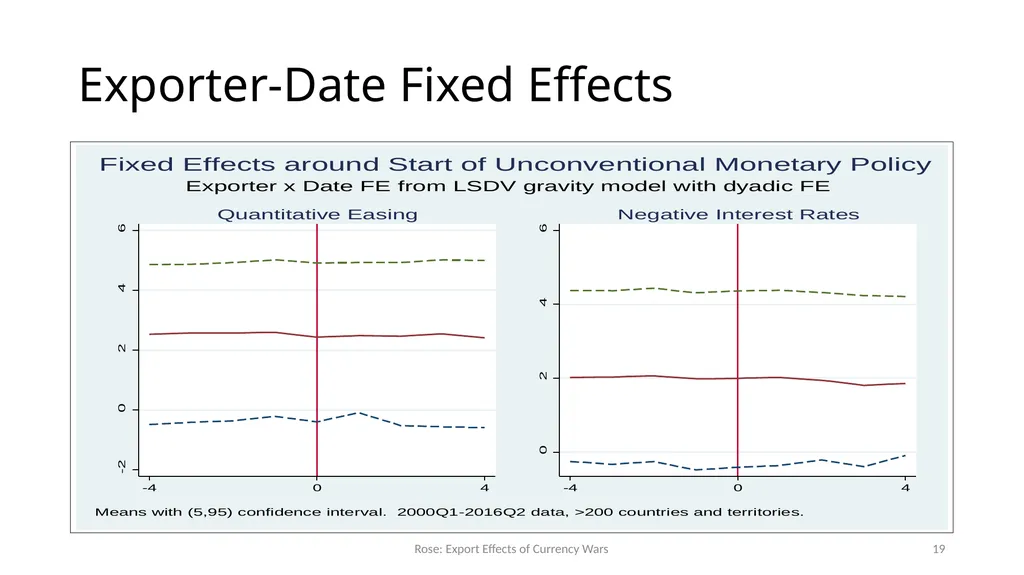
slide18. Monadic Fixed Effect Event Studies Currency war effect buried within exporter-quarter FE, {λit}?
Can examine {λit} directly
Very little movement when country begins to engage in UMP, either QE or NNIR 18 Rose: Export Effects of Currency Wars<br>
slide19. Exporter-Date Fixed Effects 19 Rose: Export Effects of Currency Wars<br>
slide20. Conclusion Q: Did use of Unconventional Monetary Policy (UMP), deliberately or inadvertently, raise exports to countries that did not use UMP?
A: No!
Countries using quantitative easing and/or negative nominal interest rates did *not* experience export booms
If anything, their exports fell, ceteris paribus 20 Rose: Export Effects of Currency Wars<br>
Berkeley-Haas, ABFER, CEPR,NBER<br>
slide2. Motivation: What are the Export Effects of Unconventional Monetary Policy (UMP)? “We’re in the midst of an international currency war, a general weakening of currency. This threatens us because it takes away our competitiveness…”
- Brazilian Finance Minister Guido Mantega, Mon Sep 27, 2010, reported by the Financial Times and Reuters
“A ‘currency war’ … occurs when a country eases monetary policy specifically to depreciate its currency, with the ultimate objective of cheapening its exports and gaining unfair competitive advantage in international trade…”
- Ben Bernanke (2016, p2) 2 Rose: Export Effects of Currency Wars<br>
slide3. Strategy Use plain-vanilla gravity model of exports
Requires neither UMP exogeneity nor instrumental variables
Straightforward methodology, data
Three assumptions
Identify “currency wars” with unconventional monetary policy
UMP: Quantitative easing, negative nominal interest rates, …
Currency wars are bilateral events between those engaging in UMP and those not
Estimate effect of UMP by aggressors on potential victims
Focus on export effects of UMP 3 Rose: Export Effects of Currency Wars<br>
slide4. Preview of Findings Countries that engage in UMP experience drop in exports vis-à-vis countries that did not engage in UMP, ceteris paribus
Quantitative easing associated with drop in exports ≈10%
Highly statistically significant
Negative nominal interest rates have similar effect
No effect from conditional forward guidance policies
Any currency wars have been lost by aggressors! 4 Rose: Export Effects of Currency Wars<br>
slide5. A Naïve Look 5 Rose: Export Effects of Currency Wars<br>
slide6. But that’s … Simplistic No obvious pattern:
Both exports and imports continue to drop following QE1, trends unaffected by QE2, stagnation unaffected by QE3
But …
Only US considered
Multilateral blurs American exports to importers engaged in their own UMP (EMU, Japan, UK, Switzerland, …) with exports to importers not engaged in UMP
No controls at all 6 Rose: Export Effects of Currency Wars<br>
slide7. Standard Gravity Model Follow Head-Mayer (2014) survey, use Least Squares with Time-Varying Country Dummy Variables:
ln(Xijt) = UMPijt + 1CUijt + 2FTAijt
+ {λit} + {ψjt} + {φij} + ijt
is coefficient of interest
UMPijt is 1 if i engages in UMP at t and j does not, 0 ow 7 Rose: Export Effects of Currency Wars<br>
slide8. Estimation LS with many fixed effects on positive export flow observations
11,773 exporter-quarter
12,997 importer-quarter
26,096 exporter-importer
FE hold constant any overall effect UMP (or anything else!) had on exports/imports at a point in time
estimates pair-specific time-varying export effect of UMP
Plausibly exogenous since main UMP export effects through common export effect, {λit}
is additional effect of belligerent on defender 8 Rose: Export Effects of Currency Wars<br>
slide9. Data Set IMF DoTS trade: >200 “countries” 2000Q1-2016Q4 (with gaps)
Exports are US$ average of FOB exports and CIF imports
RTAs: WTO
Currency Unions: Glick-Rose 9 Rose: Export Effects of Currency Wars<br>
slide10. Countries 10 Rose: Export Effects of Currency Wars<br>
slide11. Measures of Unconventional Monetary Policy QE: 1 for quarters when central bank actively acquiring securities through Quantitative Easing program, 0 ow
2.4% of sample
Variant with unusual stocks of assets held (not flow purchases)
NNIR: 1 for quarters with Negative Nominal market Interest Rates, 0 ow
2.5% of sample
Variant with official policy rates
Check with state-contingent forward guidance
0.4% of sample 11 Rose: Export Effects of Currency Wars<br>
slide12. Measures of Unconventional Monetary Policy 12 Rose: Export Effects of Currency Wars<br>
slide13. Main Results Nuisance Effects
Positive, statistically significant of both controls on (log) exports
Good fit
Coefficient of Interest ()
Negative effect of QE on exports ≈ -11% ceteris paribus
|t-statistic| > 5
Similar effect of NNIR
Cannot reject equality of QE, UMP effects
No significant effect of state-contingent forward guidance
Few obs?
No indication of successful currency wars! 13 Rose: Export Effects of Currency Wars<br>
slide14. Unconventional Monetary Policy and Exports 14 Rose: Export Effects of Currency Wars<br>
slide15. Results seem robust Variants of UMP (key regressor)
Stocks (not flows) of QE
Using official (not market) interest rates
Using 1st/4th lag or 1st lead
Dropping early or late data
Drop exporters engaging in UMP, one by one
Drop large sets of importers
Drop observations with large outliers 15 Rose: Export Effects of Currency Wars<br>
slide16. Sensitivity Analysis, 1 16 Rose: Export Effects of Currency Wars<br>
slide17. Sensitivity Analysis, 2 17 Rose: Export Effects of Currency Wars<br>
slide18. Monadic Fixed Effect Event Studies Currency war effect buried within exporter-quarter FE, {λit}?
Can examine {λit} directly
Very little movement when country begins to engage in UMP, either QE or NNIR 18 Rose: Export Effects of Currency Wars<br>
slide19. Exporter-Date Fixed Effects 19 Rose: Export Effects of Currency Wars<br>
slide20. Conclusion Q: Did use of Unconventional Monetary Policy (UMP), deliberately or inadvertently, raise exports to countries that did not use UMP?
A: No!
Countries using quantitative easing and/or negative nominal interest rates did *not* experience export booms
If anything, their exports fell, ceteris paribus 20 Rose: Export Effects of Currency Wars<br>