
Dallas Homebuyer Assistance Program Tammi
CM
Published · 18 slides · 0 views

1 / 1
Description
Dallas Homebuyer Assistance Program Tammi Southall, Housing Program Manager Housing Neighborhood Revitalization City of Dallas Presentation Overview 2 BackgroundHistory Purpose Applicant Requirements Property Requirements Funding
Related Topics
Share
Embed code
Download this presentation From Below
"Dallas Homebuyer Assistance Program Tammi" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
Dallas Homebuyer Assistance Program Tammi Southall, Housing Program Manager
Housing & Neighborhood Revitalization
City of Dallas<br>
Housing & Neighborhood Revitalization
City of Dallas<br>
02
Presentation Overview 2 Background/History
Purpose
Applicant Requirements
Property Requirements
Funding Determination and Requirements
How to apply<br>
Purpose
Applicant Requirements
Property Requirements
Funding Determination and Requirements
How to apply<br>
03
Background/History 3 The City of Dallas has provided homebuyer assistance for over 33 years.
Increase availability for affordable housing opportunities.
Support neighborhood and community-based preservation and revitalization efforts.<br>
Increase availability for affordable housing opportunities.
Support neighborhood and community-based preservation and revitalization efforts.<br>
04
Purpose 4 Provide homeownership opportunities for
low to moderate income families.
Assist with down payment, closing costs and principal reduction for home purchases in the City of Dallas.
Stabilize neighborhoods.<br>
Assist with down payment, closing costs and principal reduction for home purchases in the City of Dallas.
Stabilize neighborhoods.<br>
05
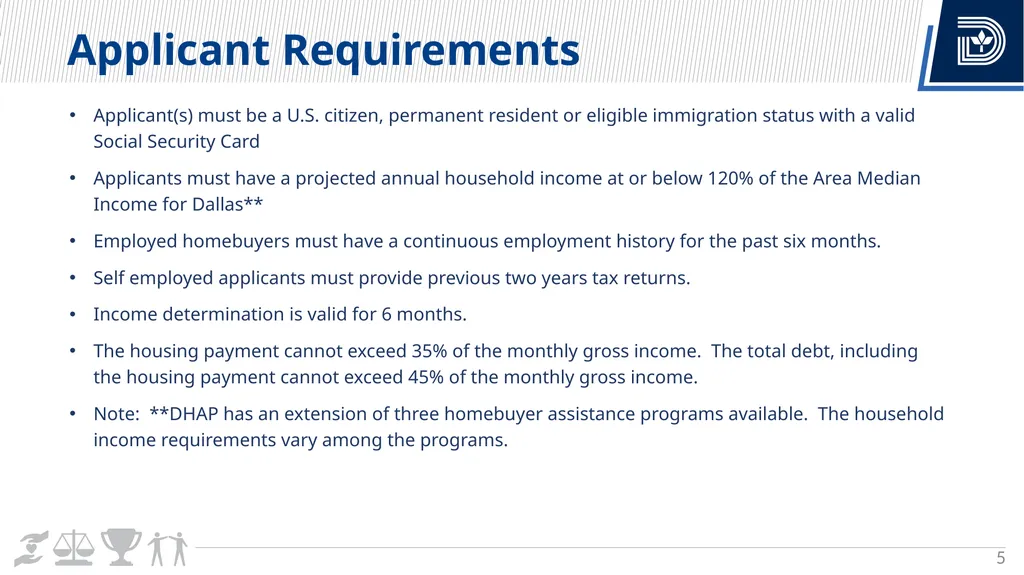
Applicant Requirements 5 Applicant(s) must be a U.S. citizen, permanent resident or eligible immigration status with a valid Social Security Card
Applicants must have a projected annual household income at or below 120% of the Area Median Income for Dallas**
Employed homebuyers must have a continuous employment history for the past six months.
Self employed applicants must provide previous two years tax returns.
Income determination is valid for 6 months.
The housing payment cannot exceed 35% of the monthly gross income. The total debt, including the housing payment cannot exceed 45% of the monthly gross income.
Note: **DHAP has an extension of three homebuyer assistance programs available. The household income requirements vary among the programs.<br>
06
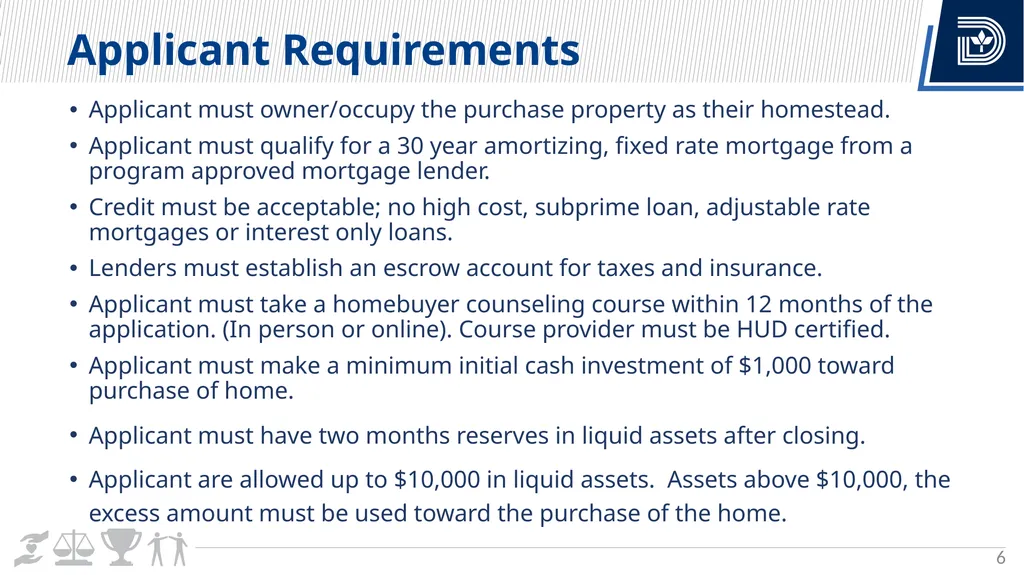
Applicant Requirements 6 Applicant must owner/occupy the purchase property as their homestead.
Applicant must qualify for a 30 year amortizing, fixed rate mortgage from a program approved mortgage lender.
Credit must be acceptable; no high cost, subprime loan, adjustable rate mortgages or interest only loans.
Lenders must establish an escrow account for taxes and insurance.
Applicant must take a homebuyer counseling course within 12 months of the application. (In person or online). Course provider must be HUD certified.
Applicant must make a minimum initial cash investment of $1,000 toward purchase of home.
Applicant must have two months reserves in liquid assets after closing.
Applicant are allowed up to $10,000 in liquid assets. Assets above $10,000, the excess amount must be used toward the purchase of the home.<br>
07
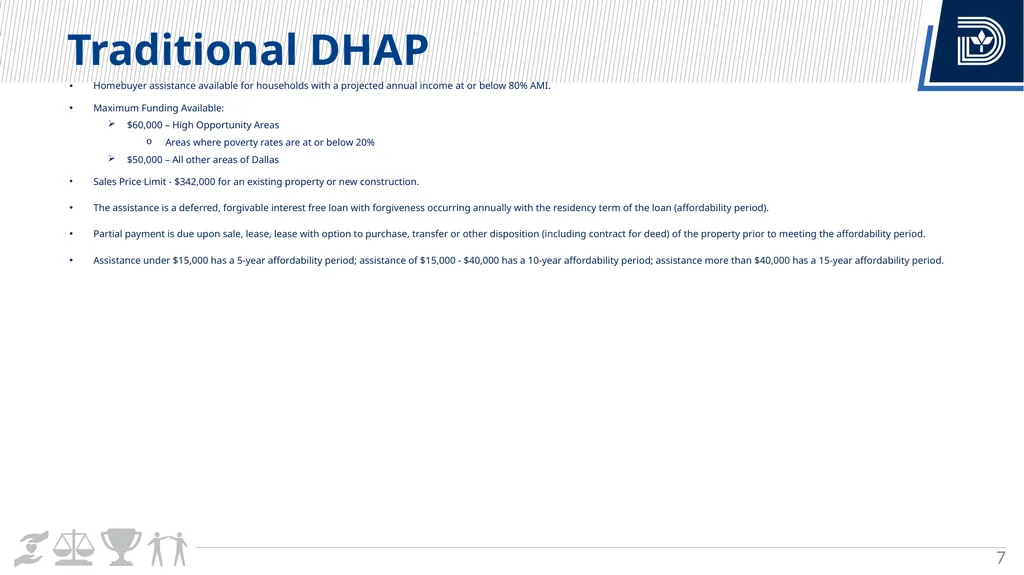
Traditional DHAP 7 Homebuyer assistance available for households with a projected annual income at or below 80% AMI.
Maximum Funding Available:
$60,000 – High Opportunity Areas
Areas where poverty rates are at or below 20%
$50,000 – All other areas of Dallas
Sales Price Limit - $342,000 for an existing property or new construction.
The assistance is a deferred, forgivable interest free loan with forgiveness occurring annually with the residency term of the loan (affordability period).
Partial payment is due upon sale, lease, lease with option to purchase, transfer or other disposition (including contract for deed) of the property prior to meeting the affordability period.
Assistance under $15,000 has a 5-year affordability period; assistance of $15,000 - $40,000 has a 10-year affordability period; assistance more than $40,000 has a 15-year affordability period.<br>
08
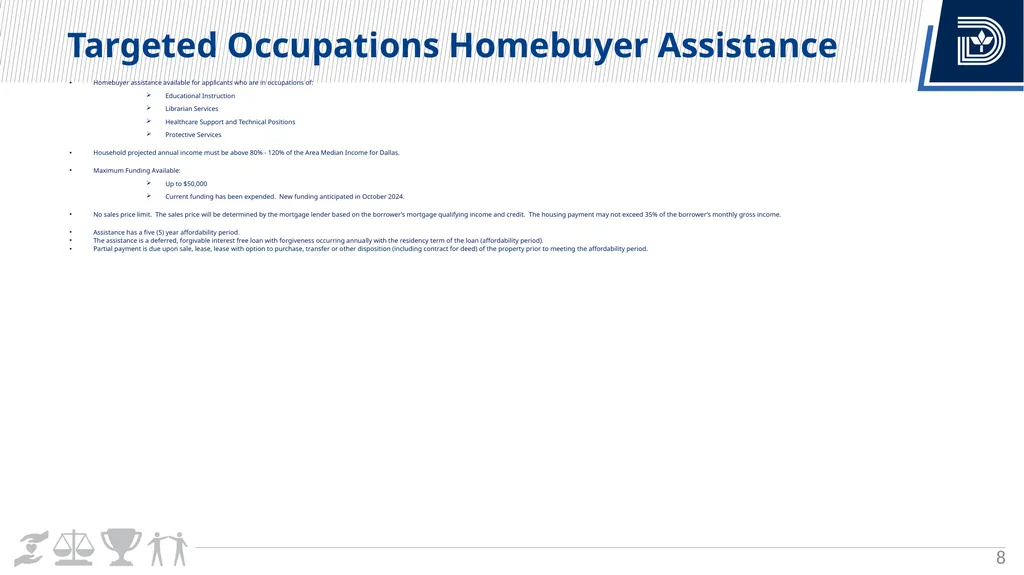
Targeted Occupations Homebuyer Assistance 8 Homebuyer assistance available for applicants who are in occupations of:
Educational Instruction
Librarian Services
Healthcare Support and Technical Positions
Protective Services
Household projected annual income must be above 80% - 120% of the Area Median Income for Dallas.
Maximum Funding Available:
Up to $50,000
Current funding has been expended. New funding anticipated in October 2024.
No sales price limit. The sales price will be determined by the mortgage lender based on the borrower’s mortgage qualifying income and credit. The housing payment may not exceed 35% of the borrower’s monthly gross income.
Assistance has a five (5) year affordability period.
The assistance is a deferred, forgivable interest free loan with forgiveness occurring annually with the residency term of the loan (affordability period).
Partial payment is due upon sale, lease, lease with option to purchase, transfer or other disposition (including contract for deed) of the property prior to meeting the affordability period.<br>
09
Anti-Displacement Homebuyer Assistance – (DHAP10) 9 Homebuyer assistance available for applicants who are current residents of Dallas who have at least 10 years of residency in Dallas. The 10 year residency requirement does not have to be consecutive.
Household projected annual income must be 50% - 120% of the Area Median Income for Dallas.
Maximum Funding Available:
Up to $50,000
No sales price limit. The sales price will be determined by the mortgage lender based on the borrower’s mortgage qualifying income and credit. The housing payment may not exceed 35% of the borrower’s monthly gross income.
Assistance has a five (5) year affordability period.
The assistance is a deferred, forgivable interest free loan with forgiveness occurring annually with the residency term of the loan (affordability period).
Partial payment is due upon sale, lease, lease with option to purchase, transfer or other disposition (including contract for deed) of the property prior to meeting the affordability period.<br>
10
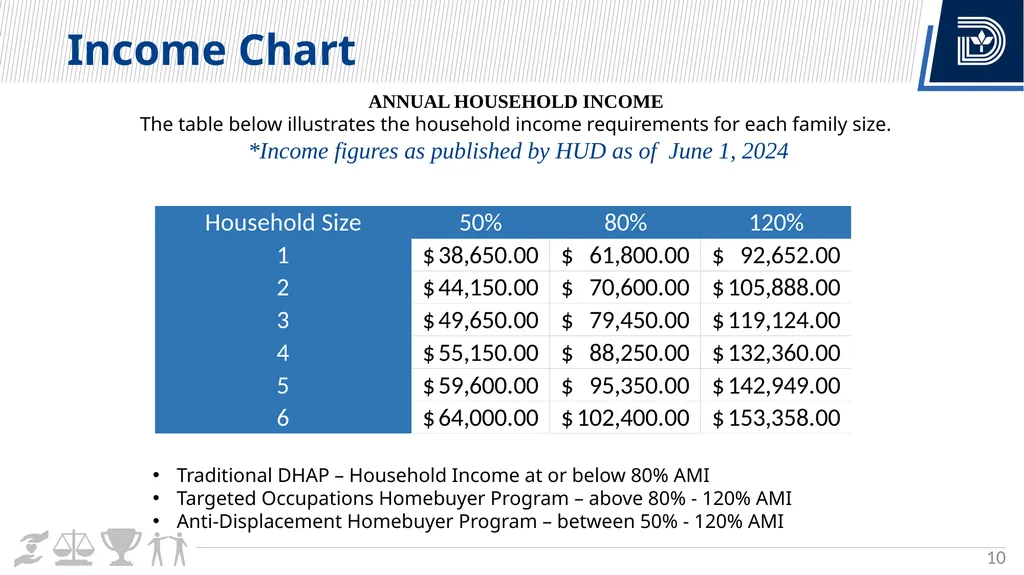
Income Chart 10 ANNUAL HOUSEHOLD INCOME
The table below illustrates the household income requirements for each family size.
*Income figures as published by H*Income figures as published by HUD as of June 1, 2024 Traditional DHAP – Household Income at or below 80% AMI
Targeted Occupations Homebuyer Program – above 80% - 120% AMI
Anti-Displacement Homebuyer Program – between 50% - 120% AMI<br>
11
Property Requirements 11 Properties must be located within the City Limits of Dallas.
This may be verified by entering the property address at http://gis.dallascityhall.com. This property search system will provide the Dallas City Council District that covers such property.
Properties must appraise for at least 100 percent of the sales price.
Properties can be single-family, detached structures; condominium units; town houses; or one-to-four-unit developments.
Properties may be occupied by the owner or borrower. If tenant occupied, owners may not enter into a contract for a period of at least 60 days after tenant vacates the property.<br>
12
Property Requirements 12 Properties must meet City of Dallas Minimum Housing Standards (MHS), including lead- based paint regulations at time of closing. Inspections should occur during the contract option period. MHS repairs must be completed prior to closing.
The Borrower must sign Notification: Watch Out for Lead-Based Paint Poisoning.
Borrower must receive a copy of Protect Your Family from Lead in Your Home, EPA747-K- 99-001 available at www.hud.gov/offices/lead. The booklet may also be reproduced from the DHAP web site.
Borrower must deliver to Seller, who must sign “Notice to Real Property Owner/Seller.”<br>
13
Property Requirements 13 HUD Real Estate Owned (REO) Properties built after January 1, 1978 are eligible for DHAP subsidy.
HUD Homes must meet all DHAP guidelines.
All MHS required repairs must be completed prior to submission of DHAP loan file.
FHA 203K loans are not eligible for DHAP funding.<br>
HUD Homes must meet all DHAP guidelines.
All MHS required repairs must be completed prior to submission of DHAP loan file.
FHA 203K loans are not eligible for DHAP funding.<br>
14
Funding Determination & Requirements 14 The actual amount of assistance is based on need as determined by the sales price, an approved primary mortgage loan and closing costs. A preliminary closing disclosure from the mortgage lender is required with an estimate of all closing costs (lender/title fees), escrows, prepaids and applicable credits.
The primary mortgage loan must meet the following debt to income ratios:
Housing Expense to Income Ratio (front ratio) – not to exceed 35%
Total Debt to Income Ratio (back ratio) – not to exceed 45%<br>
The primary mortgage loan must meet the following debt to income ratios:
Housing Expense to Income Ratio (front ratio) – not to exceed 35%
Total Debt to Income Ratio (back ratio) – not to exceed 45%<br>
15
Funding Determination & Requirements 15 Homebuyers are required to sign homebuyer written agreements for the assistance provided.
These loans are secured by a second lien on the property.
Funding will be provided at closing at an approved title company.
Source of funding is provided by HOME Investment Partnership Program, Community Development Block Grant Program and General Funds.<br>
These loans are secured by a second lien on the property.
Funding will be provided at closing at an approved title company.
Source of funding is provided by HOME Investment Partnership Program, Community Development Block Grant Program and General Funds.<br>
16
Funding Determination & Requirements 16 Subsidies are subject to fund availability on a first-come, first-served basis. Acceptance of an application for DHAP in no way constitutes a commitment or obligation on the part of the City of Dallas.
No commitment is made or implied until the City of Dallas has approved funding for each application.
Due to funding limitations, no applicant should assume any commitment even when an applicant must expend personal funds to meet application requirements.<br>
No commitment is made or implied until the City of Dallas has approved funding for each application.
Due to funding limitations, no applicant should assume any commitment even when an applicant must expend personal funds to meet application requirements.<br>
17
How to Apply 17 Prequalification is required.
Visit our website, www.dallascityhall.com/DHAP
Call us at 214-670-3644 for information<br>
Visit our website, www.dallascityhall.com/DHAP
Call us at 214-670-3644 for information<br>
18
18 Questions???<br>