Developing an Accounting System for your VE firm Tuesday, July 11, 11:00 AM Presented by: Teri Jones Chi Zhang Agenda Accounting Journals (Reference Files, Accounting Journals) Cash Budget (Task 1 2) Making Projections Income
"Developing an Accounting System for your VE firm" is the property of its rightful owner. Permission is granted to
download and print the materials on this website for personal, non-commercial use only, and to display it
on your personal computer provided you do not modify the materials and that you retain all copyright
notices contained in the materials. By downloading content from our website, you accept the terms of this
agreement.
Presentation Transcript
01
Developing an Accounting System for your VE firm Tuesday, July 11, 11:00 AM
Presented by: Teri Jones & Chi Zhang<br>
02
Agenda Accounting Journals (Reference Files, Accounting Journals)
Cash Budget (Task 1 & 2)
Making Projections Income Statement
Financing the Business Balance Sheet
Cash vs. Accrual Basis
Beginning of the Year Financing<br>
03
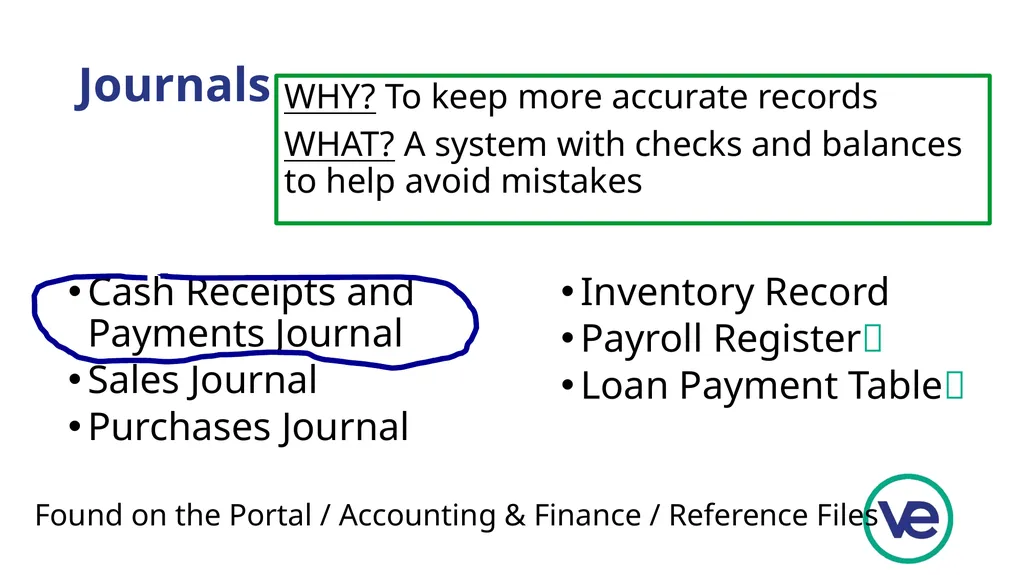
Journals WHY? To keep more accurate records
WHAT? A system with checks and balances to help avoid mistakes Cash Receipts and Payments Journal
Sales Journal
Purchases Journal
Inventory Record
Payroll Register
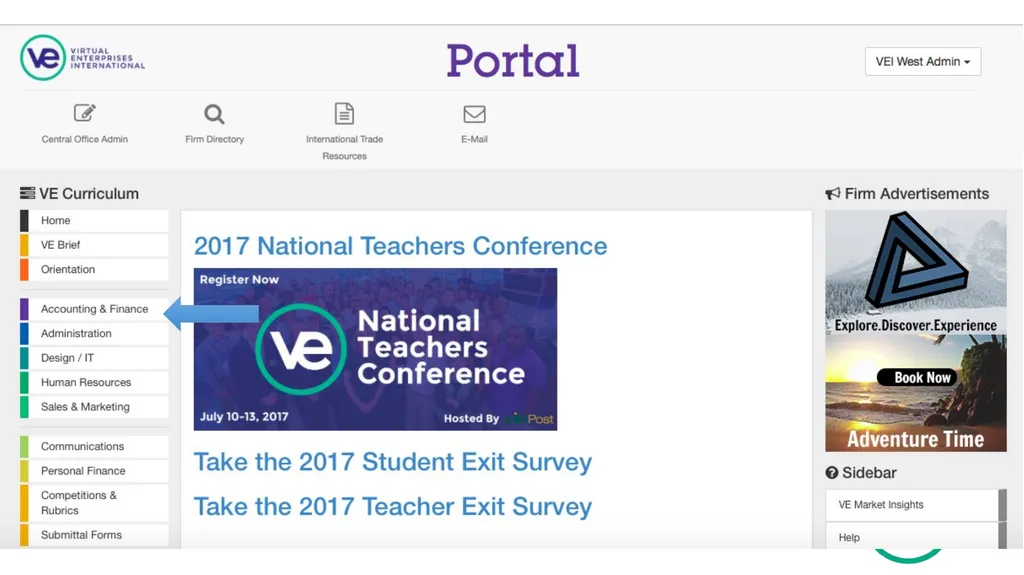
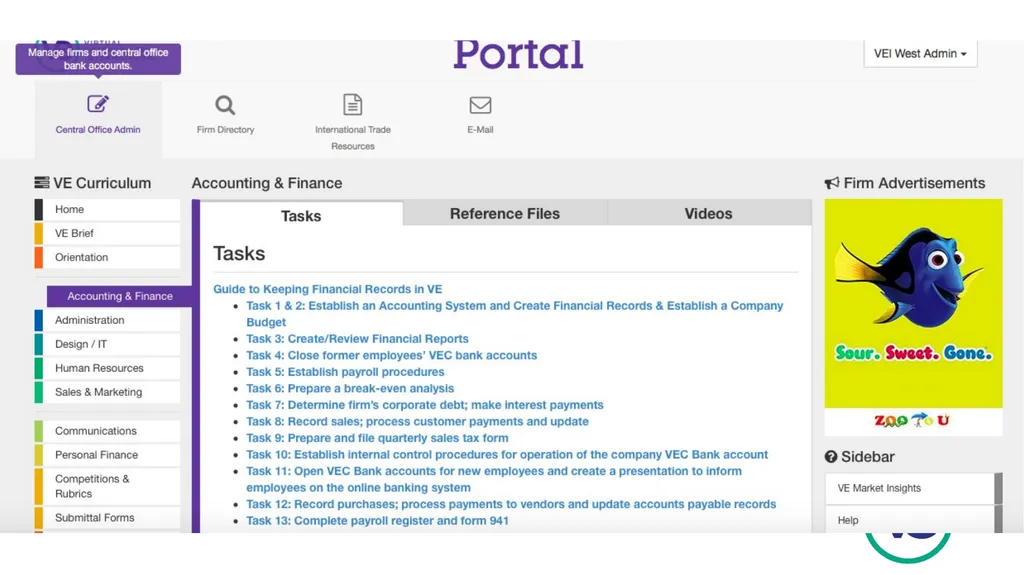
Loan Payment Table Found on the Portal / Accounting & Finance / Reference Files<br>
04
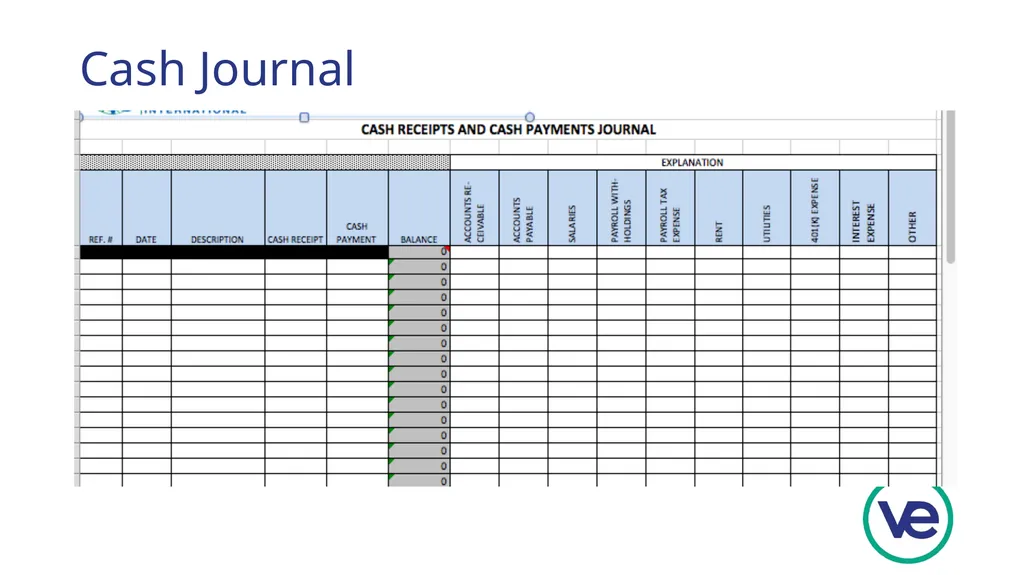
Cash Journal<br>
05
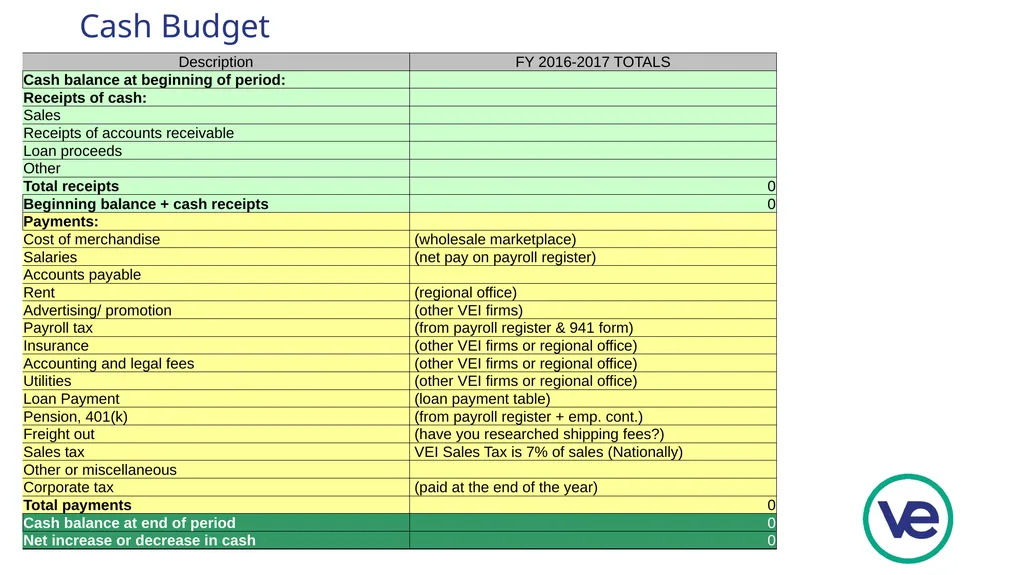
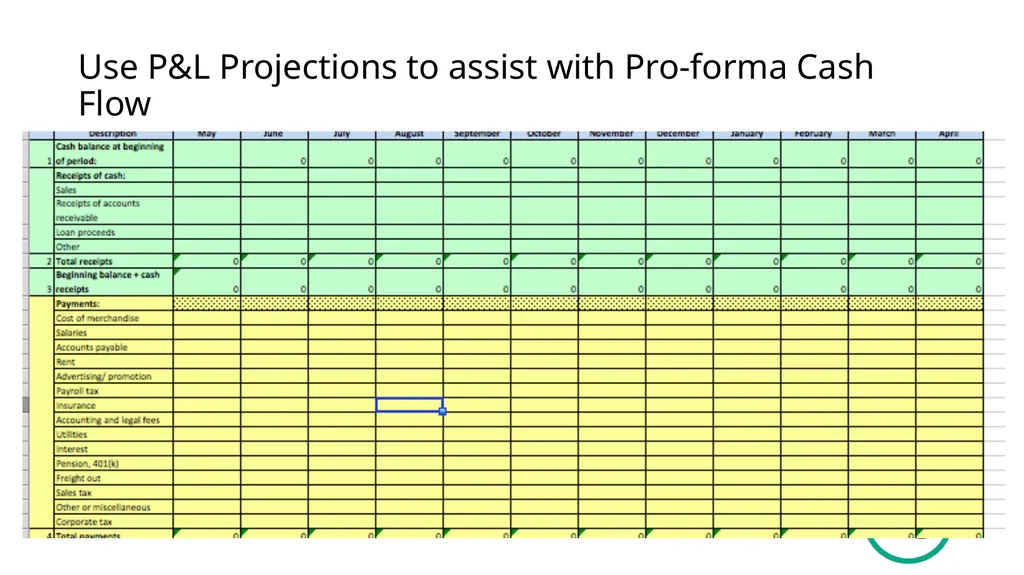
Cash Task: Cash Receipts and Payments
Prepare a record of all money coming in and going out of the bank account
Itemized by type (See “Cash Budget”) WHY? To determine if cash balance is sufficient for operations.
WHAT? Basic Sections of Financial Statement are:
Beginning Balance,
cash in,
cash out,
ending balance<br>
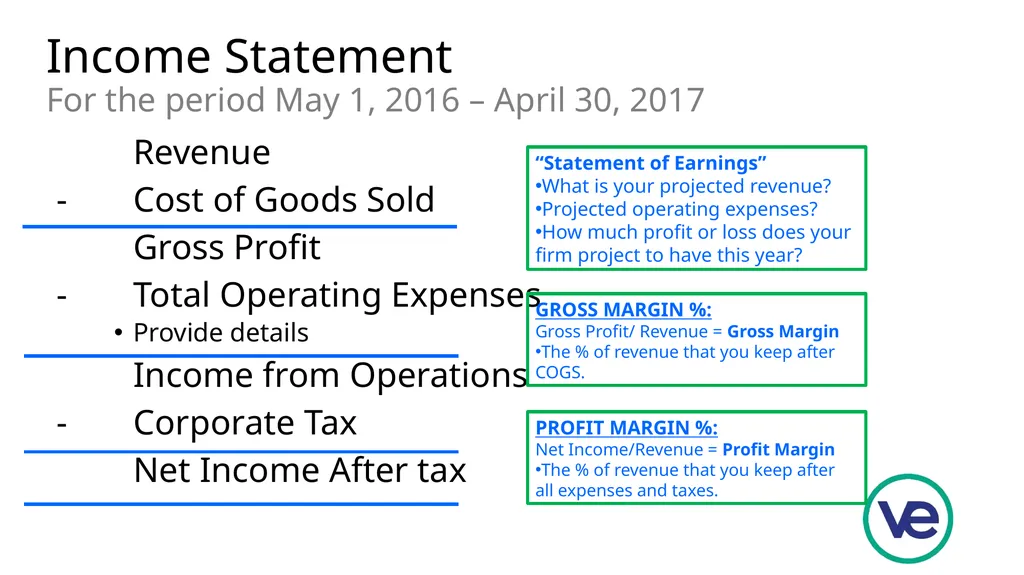
Income Statement For the period May 1, 2016 – April 30, 2017 Revenue
- Cost of Goods Sold
Gross Profit
- Total Operating Expenses
Provide details
Income from Operations
- Corporate Tax
Net Income After tax “Statement of Earnings”
What is your projected revenue?
Projected operating expenses?
How much profit or loss does your firm project to have this year? GROSS MARGIN %:
Gross Profit/ Revenue = Gross Margin
The % of revenue that you keep after COGS. PROFIT MARGIN %:
Net Income/Revenue = Profit Margin
The % of revenue that you keep after all expenses and taxes.<br>
09
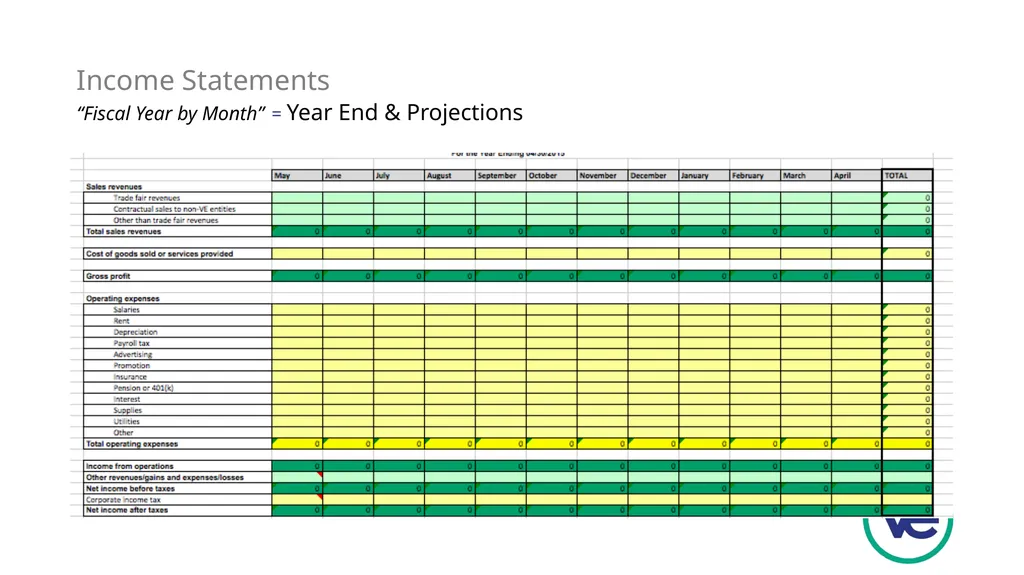
Income Statements “Fiscal Year by Month” = Year End & Projections<br>
10
Use P&L Projections to assist with Pro-forma Cash Flow<br>
11
Financing the Enterprise Debt vs. Equity Financing
Non-VE Sales
The Balance Sheet
COMPLETE THE BUSINESS REGISTRATION FORM TO APPLY FOR STARTUP FUNDING
VE PORTAL / SUBMITTAL FORMS WHY? To assure enough cash is on hand for successful operations
WHAT? Borrowing money or increasing owner’s equity (or out-of-network sales for VE)<br>
12
Finance Beginning of the Year Business Registration Form
Startup Budget Worksheet
Monthly expenses & One-time expenses
Seed Money
All new firms receive $20,000 in seed funding from the VE National Office in exchange for 2,000 shares of company stock ($10 par value per share).
Create Initial Balance Sheet
Additional Cash to Support Operations
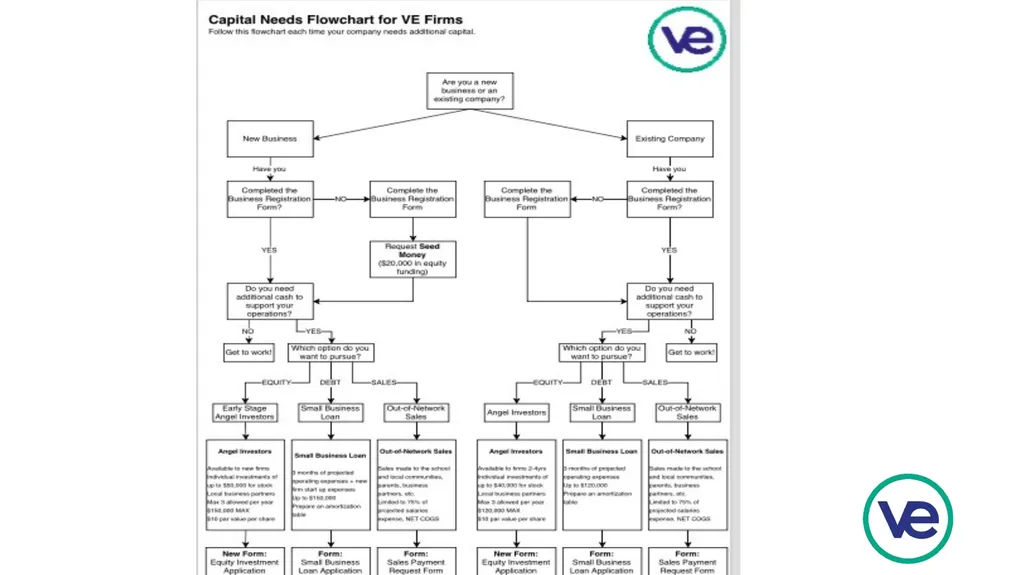
Use Capital Needs Flowchart & Fulfill requirements and Submit request
As the Year Continues:
Update Balance Sheet
Manage the Bank Account
Monitor and Record Cash Received
Make and Record Cash Payments<br>
13
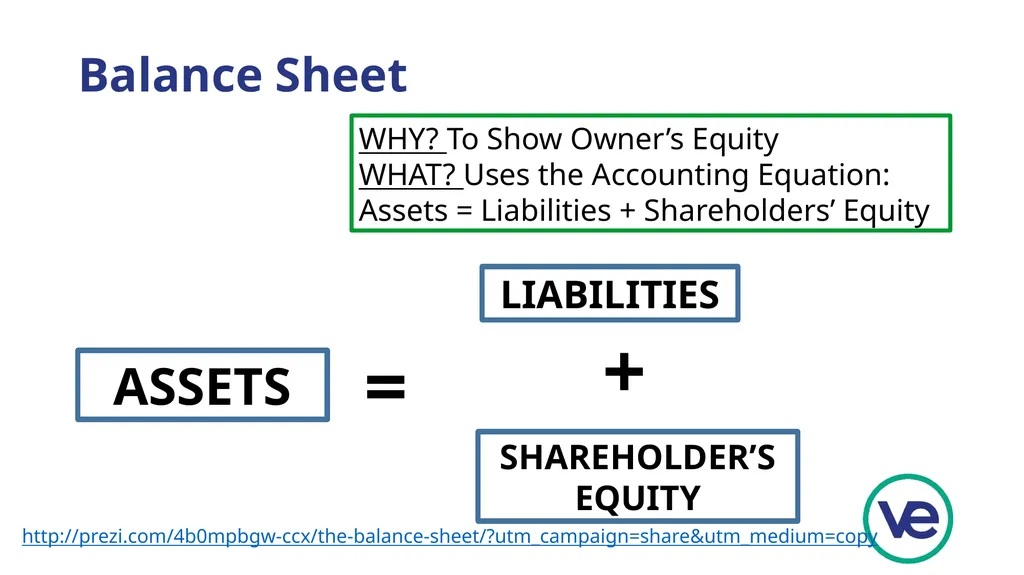
Balance Sheet WHY? To Show Owner’s Equity
WHAT? Uses the Accounting Equation:
Assets = Liabilities + Shareholders’ Equity ASSETS LIABILITIES SHAREHOLDER’S
EQUITY = + http://prezi.com/4b0mpbgw-ccx/the-balance-sheet/?utm_campaign=share&utm_medium=copy<br>
14
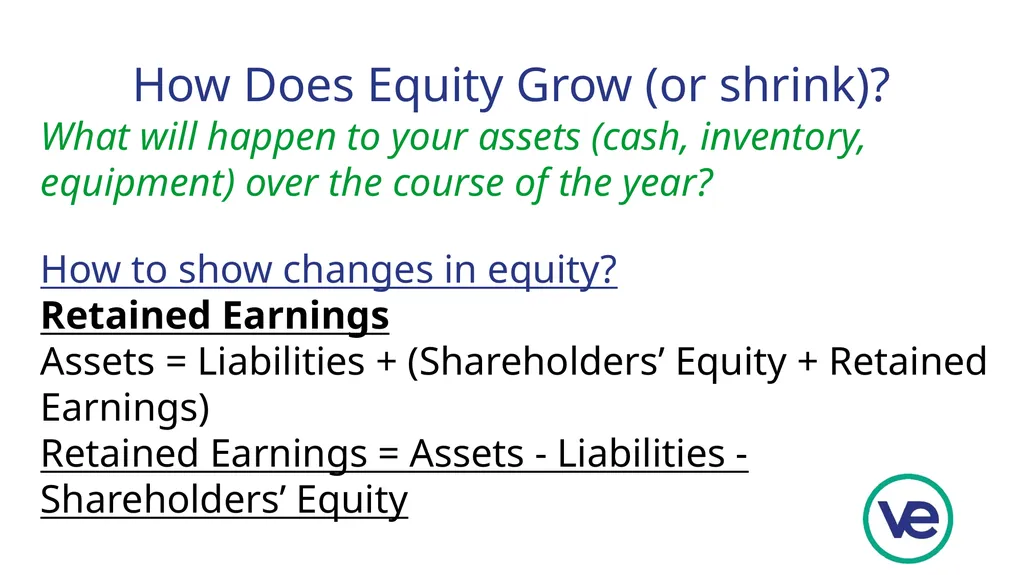
How Does Equity Grow (or shrink)? What will happen to your assets (cash, inventory, equipment) over the course of the year?
How to show changes in equity?
Retained Earnings
Assets = Liabilities + (Shareholders’ Equity + Retained Earnings)
Retained Earnings = Assets - Liabilities - Shareholders’ Equity<br>
15
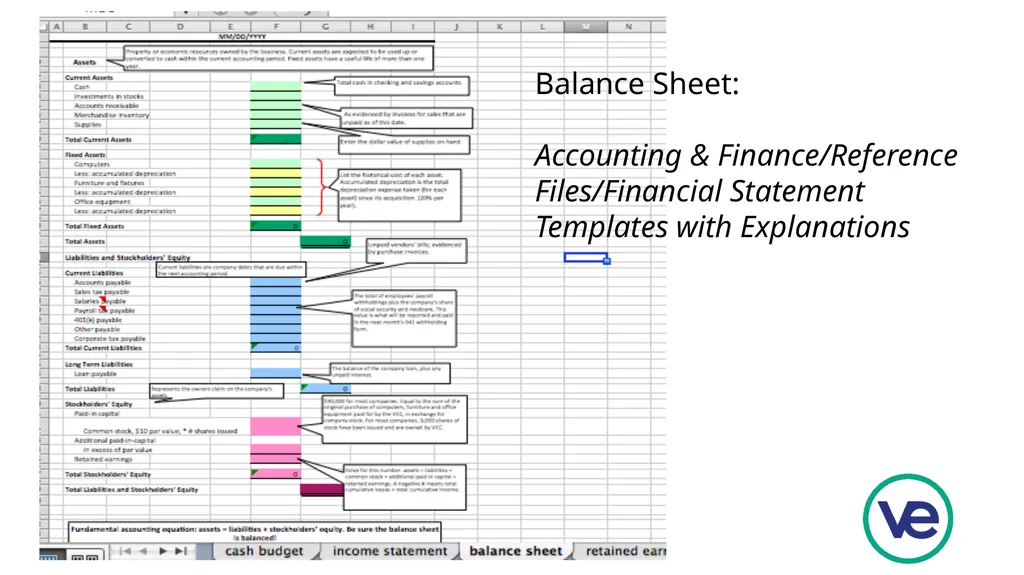
Balance Sheet:
Accounting & Finance/Reference Files/Financial Statement Templates with Explanations<br>
16
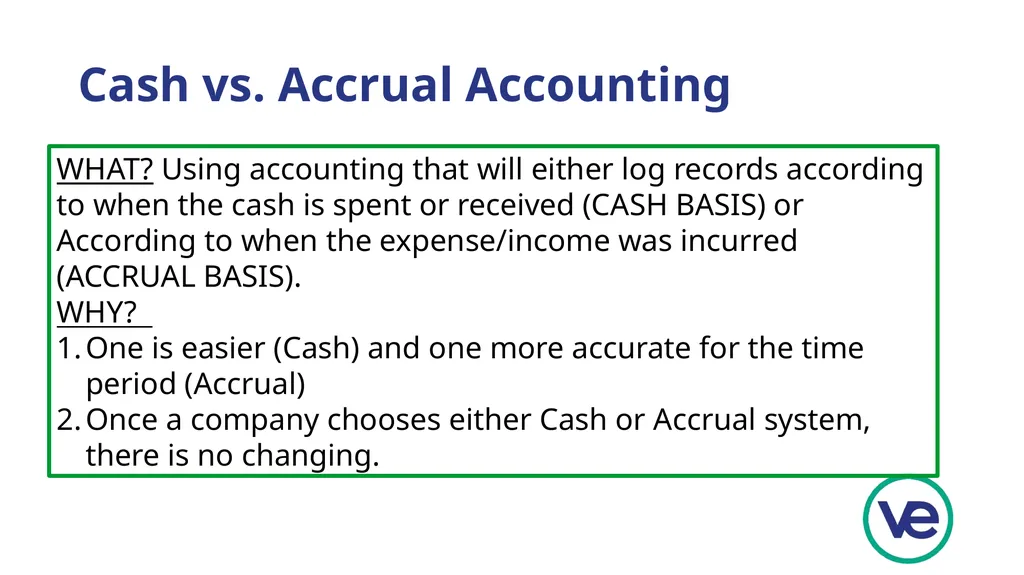
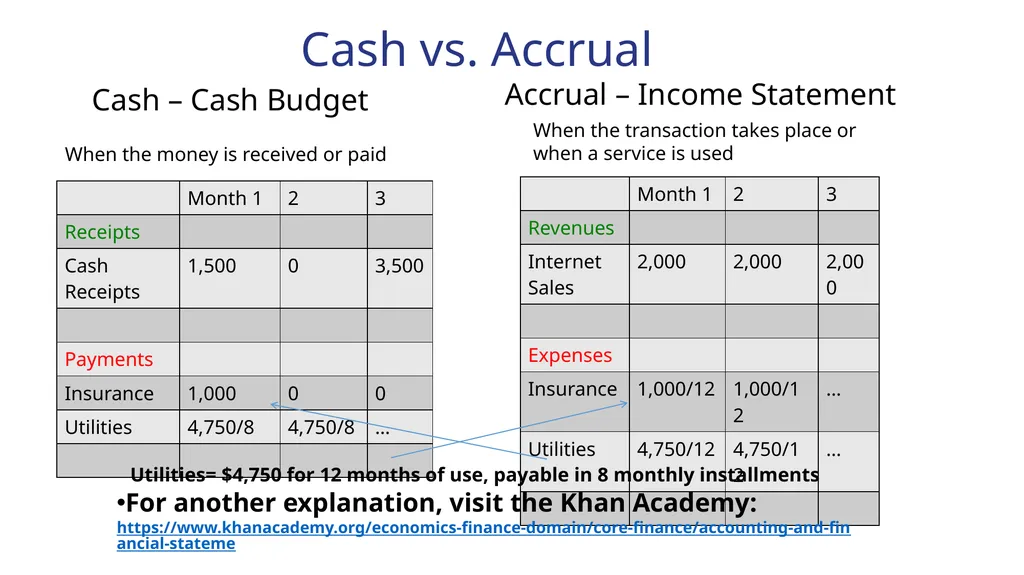
Cash vs. Accrual Accounting WHAT? Using accounting that will either log records according to when the cash is spent or received (CASH BASIS) or According to when the expense/income was incurred (ACCRUAL BASIS).
WHY?
One is easier (Cash) and one more accurate for the time period (Accrual)
Once a company chooses either Cash or Accrual system, there is no changing.<br>
17
Cash vs. Accrual Cash – Cash Budget Accrual – Income Statement For another explanation, visit the Khan Academy:
https://www.khanacademy.org/economics-finance-domain/core-finance/accounting-and-financial-stateme When the money is received or paid When the transaction takes place or when a service is used Utilities= $4,750 for 12 months of use, payable in 8 monthly installments<br>
18
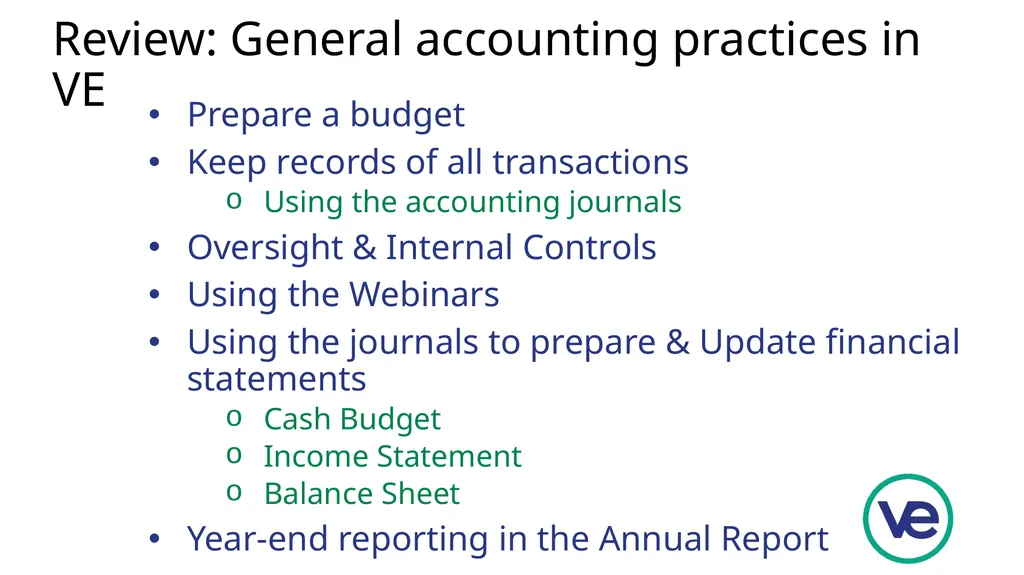
Review: General accounting practices in VE Prepare a budget
Keep records of all transactions
Using the accounting journals
Oversight & Internal Controls
Using the Webinars
Using the journals to prepare & Update financial statements
Cash Budget
Income Statement
Balance Sheet
Year-end reporting in the Annual Report<br>
19
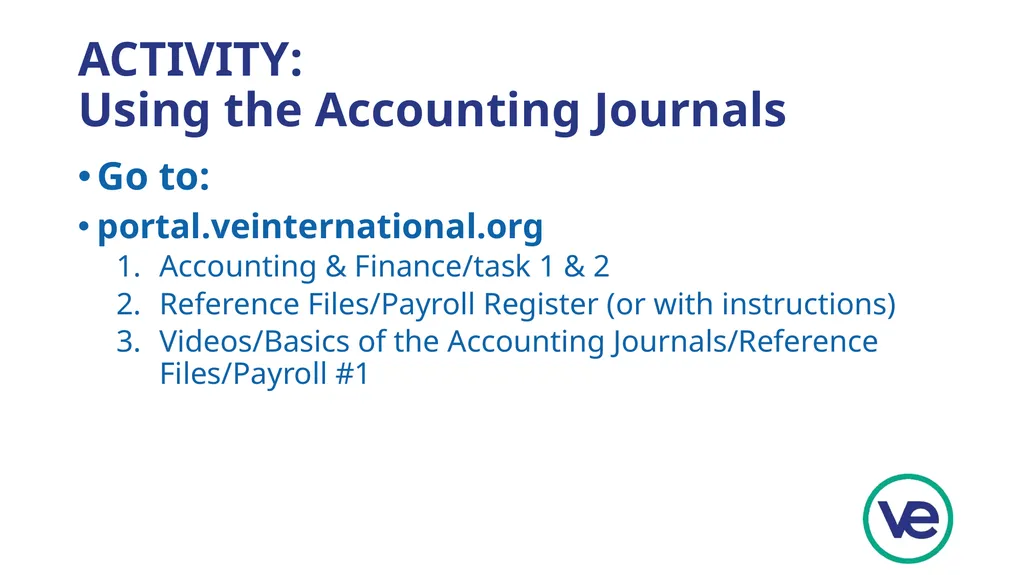
ACTIVITY: Using the Accounting Journals Go to:
portal.veinternational.org
Accounting & Finance/task 1 & 2
Reference Files/Payroll Register (or with instructions)
Videos/Basics of the Accounting Journals/Reference Files/Payroll #1<br>
20
Engage Various Company Departments: Cash Payments and Receipts Journal (Finance Dept.)
Payroll Register (w/ HR Dept.)
Sales Journal (w/ Sales & Marketing)