
ECON 602 Macroeconomic theory and policy: TEXTBOOK










Description: ECON 602 Macroeconomic theory and policy: TEXTBOOK SLIDES FOR Introduction Sep. 1, 2022 Sep. 8, 2022 Copyright This work is protected by United States copyright laws and is provided solely for the use of instructors in teaching their
Related Topics
Download Presentation
"ECON 602 Macroeconomic theory and policy: TEXTBOOK" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. ECON 602
Macroeconomic theory and policy:
TEXTBOOK SLIDES FOR Introduction Sep. 1, 2022
Sep. 8, 2022<br>
slide2. Copyright This work is protected by United States copyright laws and is provided solely for the use of instructors in teaching their courses and assessing student learning. Dissemination or sale of any part of this work (including on the World Wide Web) will destroy the integrity of the work and is not permitted. The work and materials from it should never be made available to students except by instructors using the accompanying text in their classes. All recipients of this work are expected to abide by these restrictions and to honor the intended pedagogical purposes and the needs of other instructors who rely on these materials.<br>
slide3. Macroeconomics Eighth Edition Chapter 1 A Tour of the World Copyright © 2021, 2017, 2013 Pearson Education, Inc. All Rights Reserved<br>
slide4. A Tour of the World What is macroeconomics? The best way to answer this question is to take you on an economic tour of the world.
The goal of this chapter is to give you a sense of these recent events and of some of the macroeconomic issues confronting different countries today.<br>
slide5. 1.1 The Crisis (1 of 3) From 2000 to 2007, the world economy had a sustained expansion.
In 2007, U.S. housing prices started declining, leading to a major financial crisis.
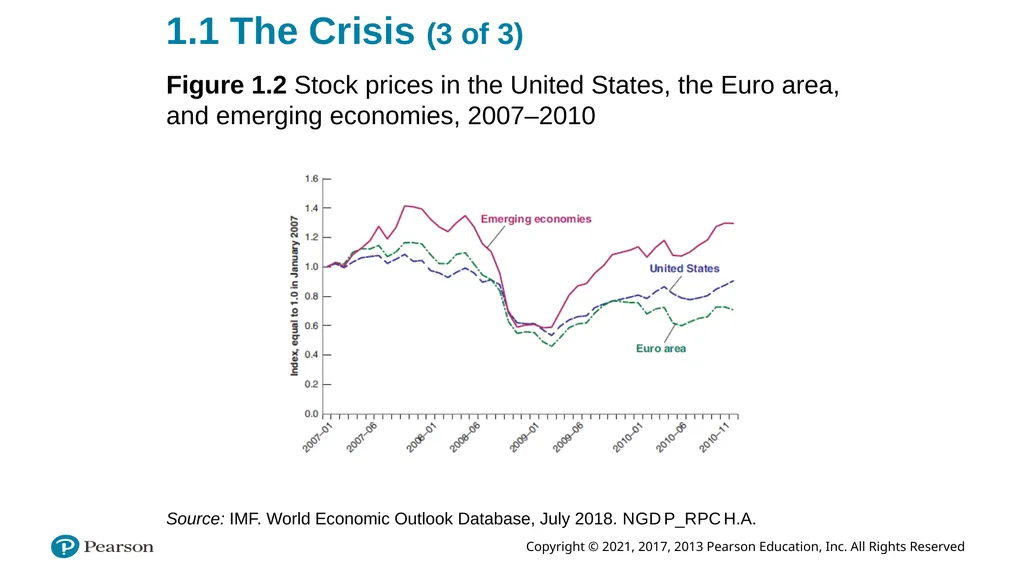
The financial crisis turned into a major economic crisis with falling stock prices.
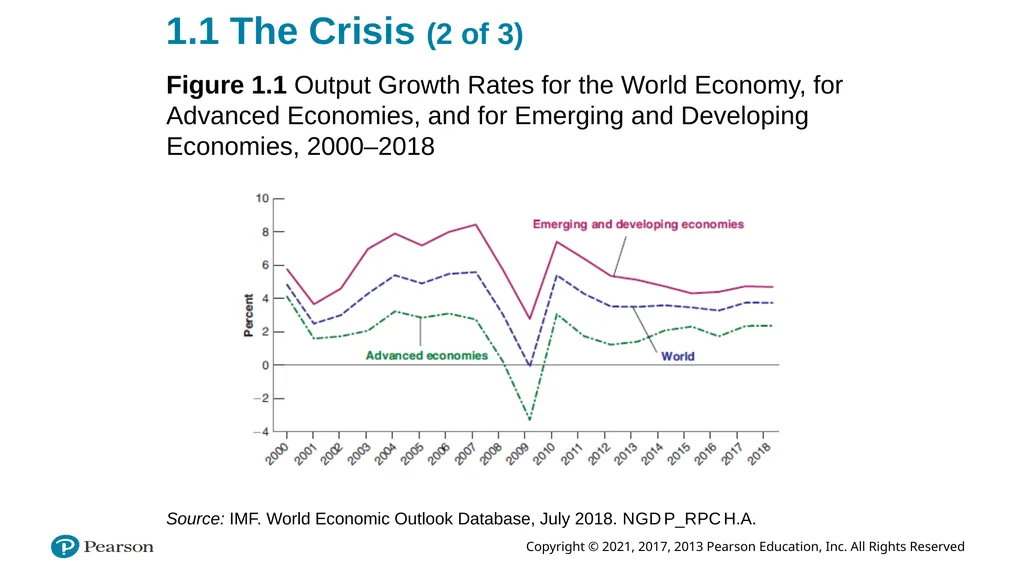
In the third quarter of 2008, U.S. output growth turned negative and remained so in 2009.
Through the trade and financial channels, the U.S. crisis quickly became a world crisis.<br>
slide6. 1.1 The Crisis (2 of 3) Figure 1.1 Output Growth Rates for the World Economy, for Advanced Economies, and for Emerging and Developing Economies, 2000–2018 Source: IMF. World Economic Outlook Database, July 2018. N G D P_R P C H.A.<br>
slide7. 1.1 The Crisis (3 of 3) Figure 1.2 Stock prices in the United States, the Euro area, and emerging economies, 2007–2010 Source: IMF. World Economic Outlook Database, July 2018. N G D P_R P C H.A.<br>
slide8. 1.2 The United States (1 of 6) The United States is big
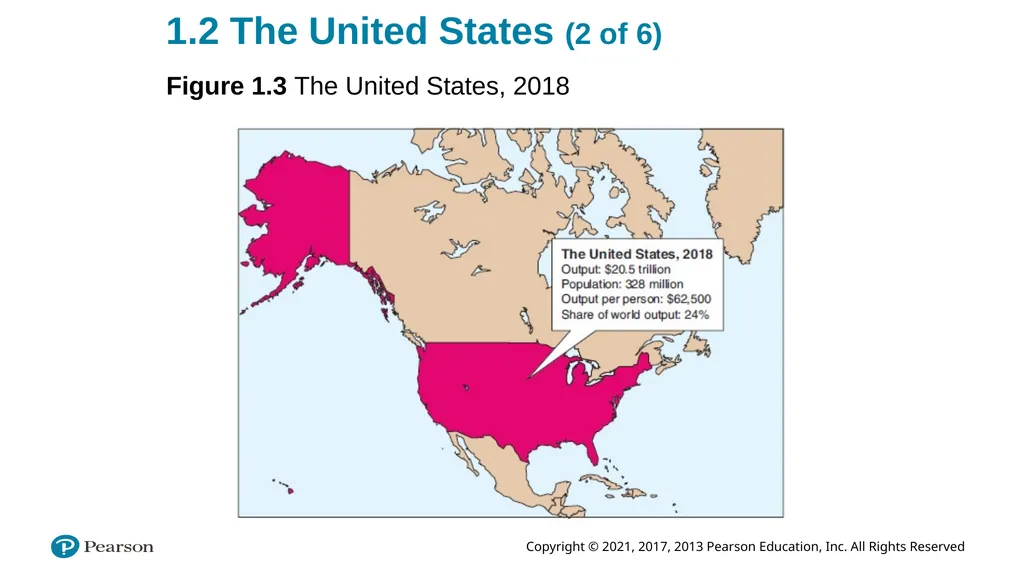
With an output of $20.5 trillion in 2018, it accounted for 24% of world output.
The U.S. standard of living is high
Output per capita is $62,500, close to the highest in the world.
Economists also look at:
Output growth
Unemployment rate
Inflation rate<br>
slide9. 1.2 The United States (2 of 6) Figure 1.3 The United States, 2018<br>
slide10. 1.2 The United States (3 of 6) The U.S. economy in 2018 was in good shape, leaving the effects of the 2008-2009 crisis behind with one of the longest economic expansions on record. Table 1.1 Growth, Unemployment, and Inflation in the United States, 1990–2018 Output growth rate: annual rate of growth of output (G D P). Unemployment rate: average over the year. Inflation rate: annual rate of change of the price level (G D P deflator). Source: I M F, World Economic Outlook, October 2018.<br>
slide11. 1.2 The United States (4 of 6) The federal funds rate—the interest rate the Fed controls—went from 2.5% in July 2007 to nearly 0% in December 2008. Figure 1.4 The U.S. Federal Funds Rate since 2000 Source: Haver Analytics.<br>
slide12. 1.2 The United States (5 of 6) Why did the Federal Funds rate stop at zero?
This constraint is known as the zero lower bound.
If it were negative, then everyone would hold cash rather than bonds.
Why are low interest rates a potential issue?
Low interest rates limit the Fed’s ability to respond to further negative shocks.
Low interest rates may lead to excessive risk taking by investors to increase their returns.<br>
slide13. 1.2 The United States (6 of 6) Productivity growth is important for a sustained increase in income per person, but since 2010, it has been only about half as it was in the 1990s.
The slowdown in productivity growth is worrisome because the standard of living especially for the poor may not increase. Table 1.2 Labor Productivity Growth, by Decade, 1990-2018 Source: FRED database. PRS85006092, MPU490063.<br>
slide14. 1.3 The Euro Area (1 of 6) The European Union (E U) is a group of 28 European countries with a common market.
In 1999, the E U formed a common currency area called the Euro area, which replaced national currencies in 2002 with the euro.
The Euro area faces two main issues today:
How to reduce unemployment?
How to function efficiently as a common currency area?<br>
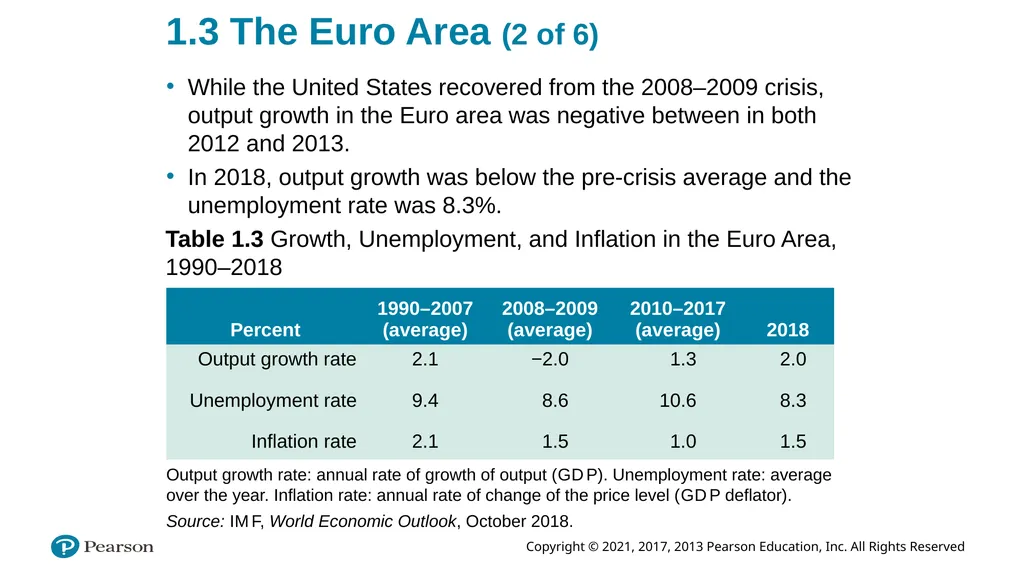
slide15. 1.3 The Euro Area (2 of 6) While the United States recovered from the 2008–2009 crisis, output growth in the Euro area was negative between in both 2012 and 2013.
In 2018, output growth was below the pre-crisis average and the unemployment rate was 8.3%. Table 1.3 Growth, Unemployment, and Inflation in the Euro Area, 1990–2018 Output growth rate: annual rate of growth of output (G D P). Unemployment rate: average over the year. Inflation rate: annual rate of change of the price level (G D P deflator). Source: I M F, World Economic Outlook, October 2018.<br>
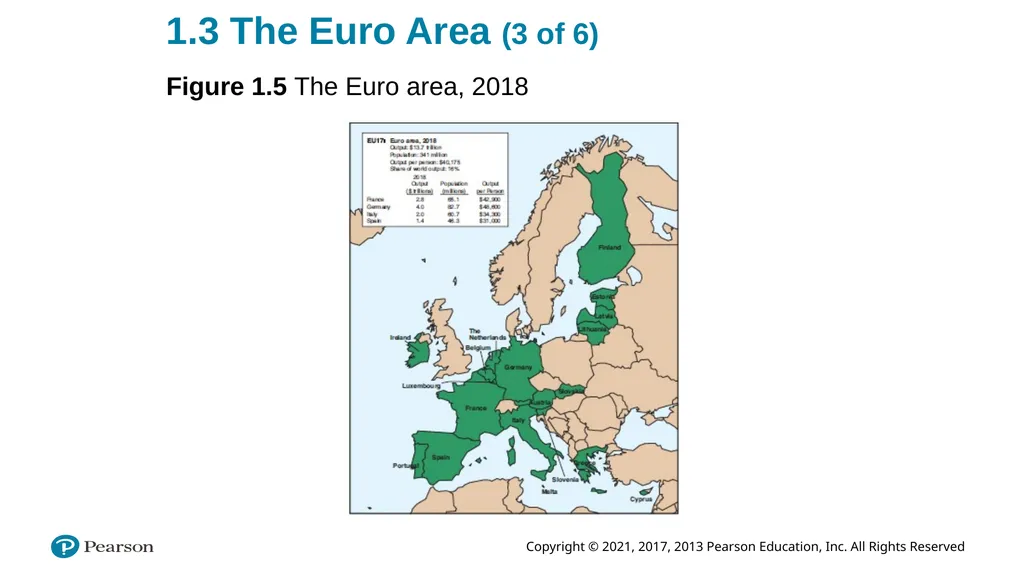
slide16. 1.3 The Euro Area (3 of 6) Figure 1.5 The Euro area, 2018<br>
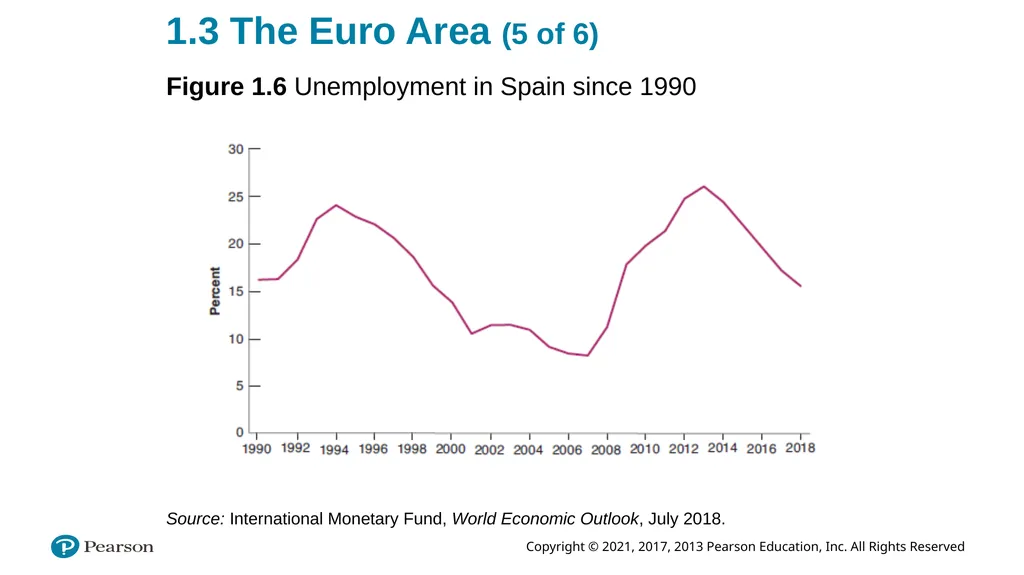
slide17. 1.3 The Euro Area (4 of 6) While the average unemployment rate for the Euro area was 8.3% in 2018, countries like Spain had an unemployment rate of 15%.
Much of the high unemployment rate was the result of the crisis.
Even when Spain had its lowest unemployment rate of 8%, it was nearly three times that of the Germany today.
Some economists believe labor market rigidities with too much protection for workers are the main problem.<br>
slide18. 1.3 The Euro Area (5 of 6) Figure 1.6 Unemployment in Spain since 1990 Source: International Monetary Fund, World Economic Outlook, July 2018.<br>
slide19. 1.3 The Euro Area (6 of 6) Supporters of the euro argue:
economic advantages due to no more changes in exchange rates to worry about
its contribution to the creation of a large economic power
Others argue:
the drawback of a common monetary policy across euro countries
the loss of the exchange rate as an adjustment instrument within the euro area<br>
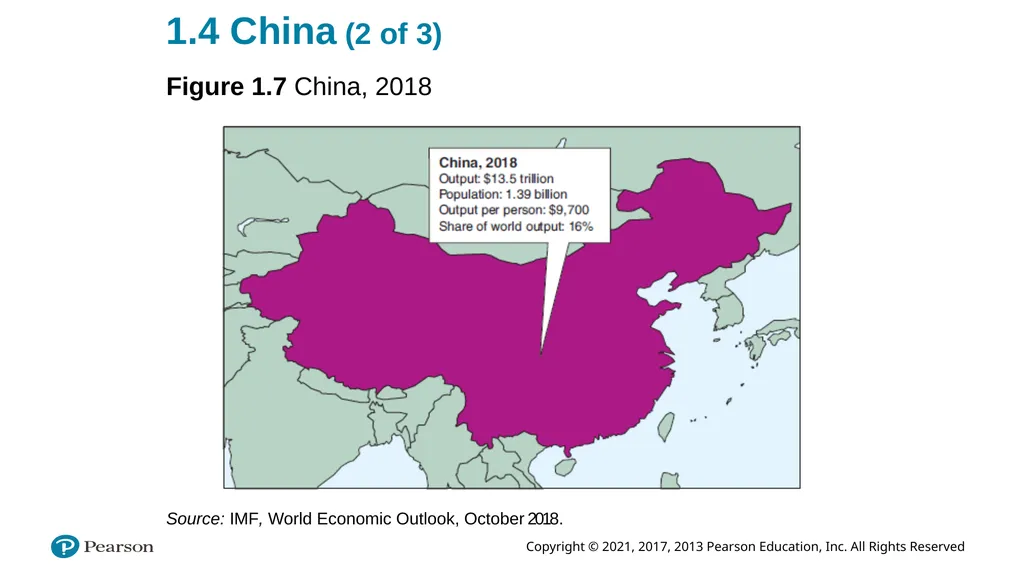
slide20. 1.4 China (1 of 3) China is in the news every day.
Its population is more than four times that of the United States.
But its output at $13.5 trillion is only about 60% of the United States.
Output per person is roughly 15% of that of the United States.
China has been growing very rapidly for more than three decades.<br>
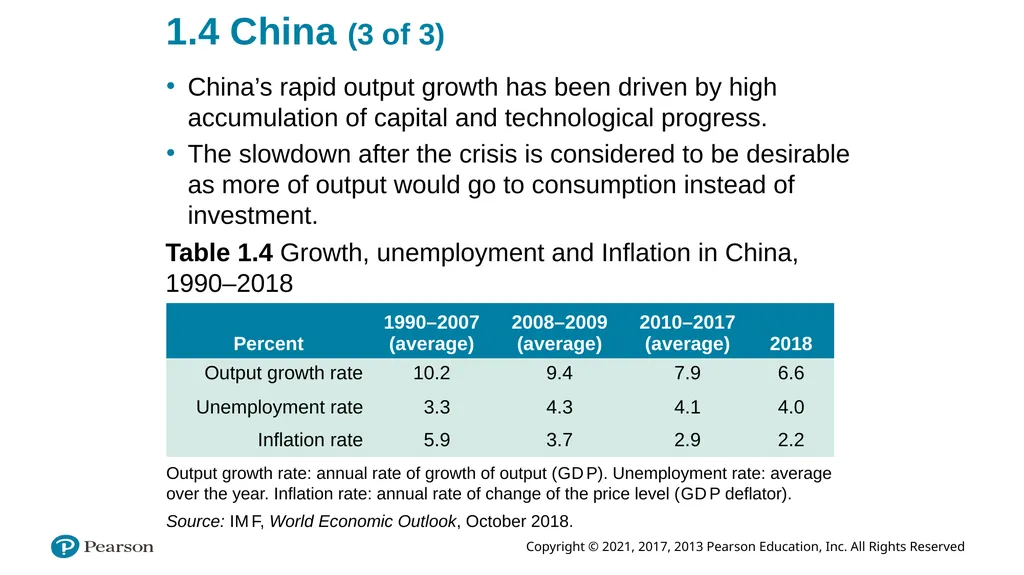
slide21. 1.4 China (2 of 3) Figure 1.7 China, 2018 Source: IMF, World Economic Outlook, October 2018.<br>
slide22. 1.4 China (3 of 3) China’s rapid output growth has been driven by high accumulation of capital and technological progress.
The slowdown after the crisis is considered to be desirable as more of output would go to consumption instead of investment. Table 1.4 Growth, unemployment and Inflation in China, 1990–2018 Output growth rate: annual rate of growth of output (G D P). Unemployment rate: average over the year. Inflation rate: annual rate of change of the price level (G D P deflator). Source: I M F, World Economic Outlook, October 2018.<br>
slide23. 1.5 Looking Ahead We could have also looked at other regions like India, Japan, Latin America, Central and Eastern Europe, and Africa.
You could have also thought about the issues triggered by the crisis, how monetary and fiscal policies can be used to avoid recessions, and why growth rates differ so much across countries.
The purpose of this book is to give you a way of thinking about these issues.<br>
slide24. Macroeconomics Eighth Edition Chapter 2 A Tour of the Book Copyright © 2021, 2017, 2013 Pearson Education, Inc. All Rights Reserved Slide in this Presentation Contain Hyperlinks. JAWS users should be able to get a list of links by using INSERT+F7<br>
slide25. A Tour of the Book The words output, unemployment, and inflation appear daily in newspapers and on the evening news.
In this chapter, we define these words more precisely.
The chapter also introduces concepts around which the book is organized: the short run, the medium run, and the long run.<br>
slide26. 2.1 Aggregate Output (1 of 11) National income and product accounts were developed at the end of World War Ⅱ as measures of aggregate output.
The measure of aggregate output is called gross domestic product (G D P).
How would you define aggregate output in the economy?<br>
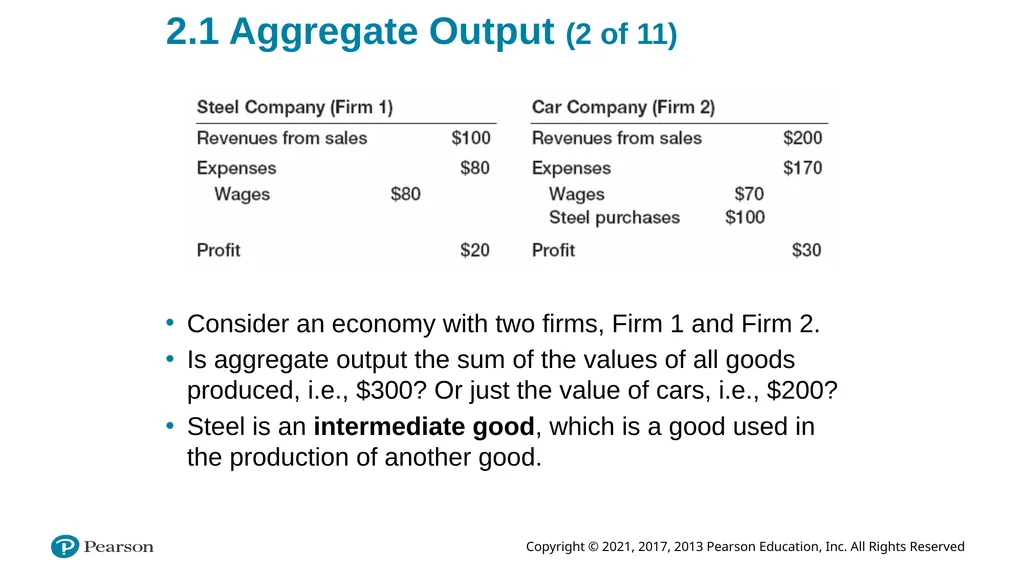
slide27. 2.1 Aggregate Output (2 of 11) Consider an economy with two firms, Firm 1 and Firm 2.
Is aggregate output the sum of the values of all goods produced, i.e., $300? Or just the value of cars, i.e., $200?
Steel is an intermediate good, which is a good used in the production of another good.<br>
slide28. 2.1 Aggregate Output (3 of 11) G D P is the value of the final goods and services produced in the economy during a given period. We want to count only final goods, not intermediate goods.
If we merge the two firms in the previous example, the revenues of the new firm equal $200.<br>
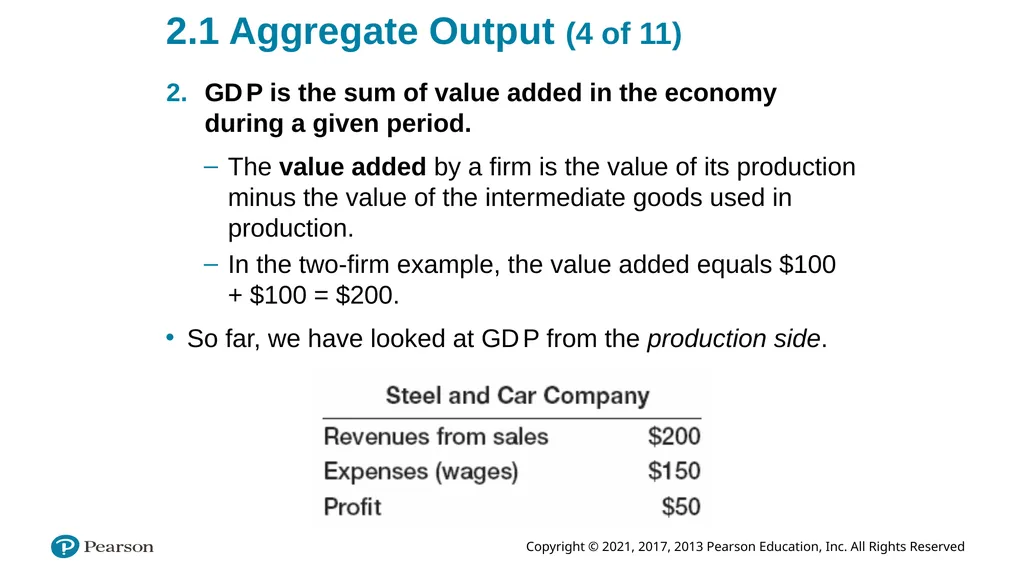
slide29. 2.1 Aggregate Output (4 of 11) G D P is the sum of value added in the economy during a given period. The value added by a firm is the value of its production minus the value of the intermediate goods used in production.
In the two-firm example, the value added equals $100 + $100 = $200.
So far, we have looked at G D P from the production side.<br>
slide30. 2.1 Aggregate Output (5 of 11) G D P is the sum of incomes in the economy during a given period. Aggregate production and aggregate income are always equal.
From the income side, valued added in the two-firm example is equal to the sum of labor income ($150) and capital or profit income ($50), i.e., $200.<br>
slide31. 2.1 Aggregate Output (6 of 11) Nominal G D P is the sum of the quantities of final goods produced times their current price.
Nominal G D P increases for two reasons:
The production of most goods increases over time
The price of most goods increases over time
Our goal is to measure production and its change over time.
Real G D P is the sum of quantities of final goods times constant (not current) prices.<br>
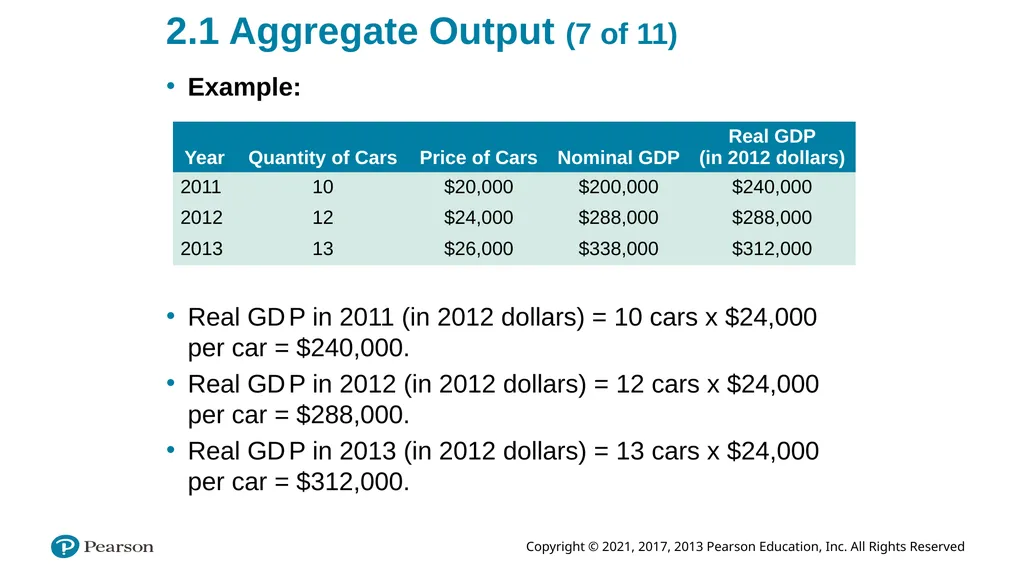
slide32. 2.1 Aggregate Output (7 of 11) Example: Real G D P in 2011 (in 2012 dollars) = 10 cars x $24,000 per car = $240,000.
Real G D P in 2012 (in 2012 dollars) = 12 cars x $24,000 per car = $288,000.
Real G D P in 2013 (in 2012 dollars) = 13 cars x $24,000 per car = $312,000.<br>
slide33. 2.1 Aggregate Output (8 of 11) For more than one good, relative prices of the goods are natural weights for constructed the weighted average of the output of all final goods.
Real G D P in chained (2012) dollars reflects relative prices that change over time.
The year used to construct prices is called the base year.<br>
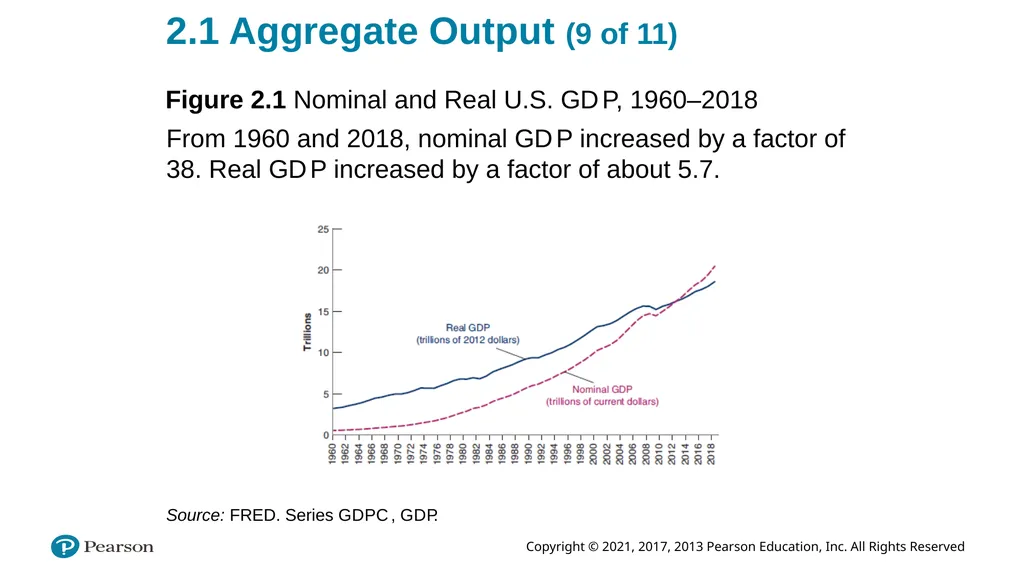
slide34. 2.1 Aggregate Output (9 of 11) Figure 2.1 Nominal and Real U.S. G D P, 1960–2018 From 1960 and 2018, nominal G D P increased by a factor of 38. Real G D P increased by a factor of about 5.7. Source: FRED. Series G D P C , G D P.<br>
slide35. 2.1 Aggregate Output (10 of 11) Nominal G D P is also called dollar G D P, or G D P in current dollars.
Real G D P is also called G D P in terms of goods, G D P in constant dollars, G D P adjusted for inflation, or G D P in chained (2012) dollars, or G D P in 2012 dollars.
G D P will refer to real G D P.
Yt will denote real G D P in year t.
Nominal G D P and variables in current dollars will be denoted by a dollar sign in front of them, e.g., $Yt<br>
slide36. 1.2 The United States (4 of 6) Figure 2.2 Growth Rate of U.S. G D P, 1960–2018 G D P growth in year t is (Yt − Yt-1)/Yt-1.
Since 1960, the U.S. economy has gone through a series of expansions, interrupted by short recessions. The 2008−2009 recession was the most severe recession in the period from 1960 to 2018. Source: Calculated using series G D P C in Figure 2.1.<br>
slide37. FOCUS: Real G D P, Technological Progress, and the Price of Computers The Department of Commerce deals with changes in the quality of existing goods like computers with an approach called hedonic pricing, which treats goods as providing a collection of characteristics.
The quality of new laptops (computing services) has increased on average by 20% a year since 1999.
The dollar price of a typical laptop has also declined by about 7% a year since 1999.
This implies that laptops’ quality-adjusted price has fallen at an average rate of 20% + 7% = 27% per year.<br>
slide38. 2.2 The Unemployment Rate (1 of 6) Employment is the number of people who have a job.
Unemployment is the number of people who do not have a job but are looking for one.
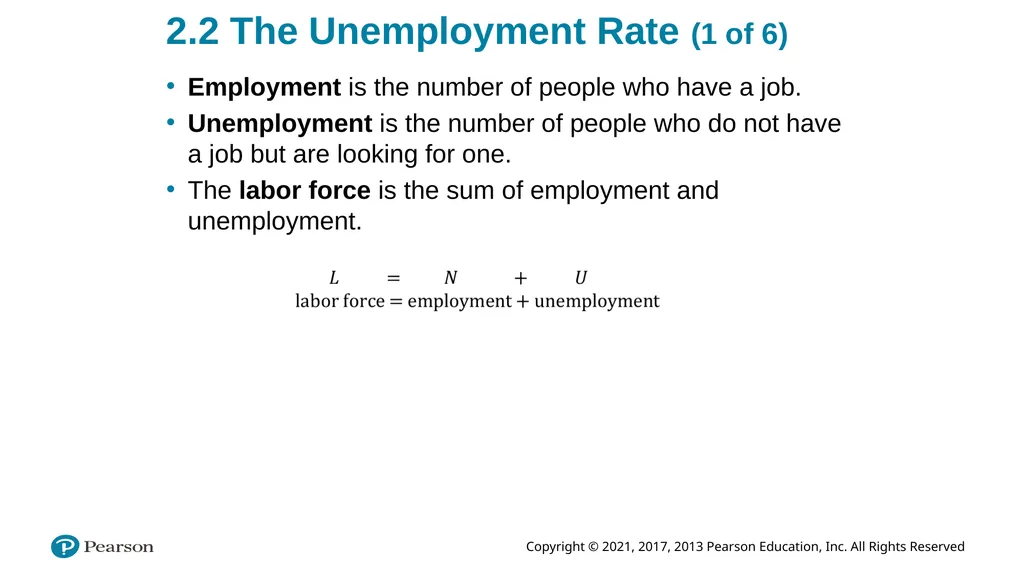
The labor force is the sum of employment and unemployment.<br>
slide39. 2.2 The Unemployment Rate (2 of 6) The unemployment rate is the ratio of the number of people who are unemployed to the number of people in the labor force.<br>
slide40. 2.2 The Unemployment Rate (3 of 6) Most rich countries rely on large surveys of households to compute the unemployment rate.
The U.S. Current Population Survey (C P S) relies on interviews of 60,000 households every month.
A person is unemployed if he or she does not have a job and has been looking for a job in the last four weeks.
Those who do not have a job and are not looking for one are counted as not in the labor force.<br>
slide41. 2.2 The Unemployment Rate (4 of 6) Discouraged workers are those persons who give up looking for a job and so no longer count as unemployed.
The participation rate is the ratio of the labor force to the total population of working age.
Because of discouraged workers, a higher unemployment rate is typically associated with a lower participation rate.<br>
slide42. 2.2 The Unemployment Rate (5 of 6) Why Do Economists Care about Unemployment?
Because of its direct effect on the welfare of the unemployed, especially those remaining unemployed for long periods of time.
It is a signal that the economy is not using its human resources efficiently. Very low unemployment can also be a problem as the economy runs into labor shortages.<br>
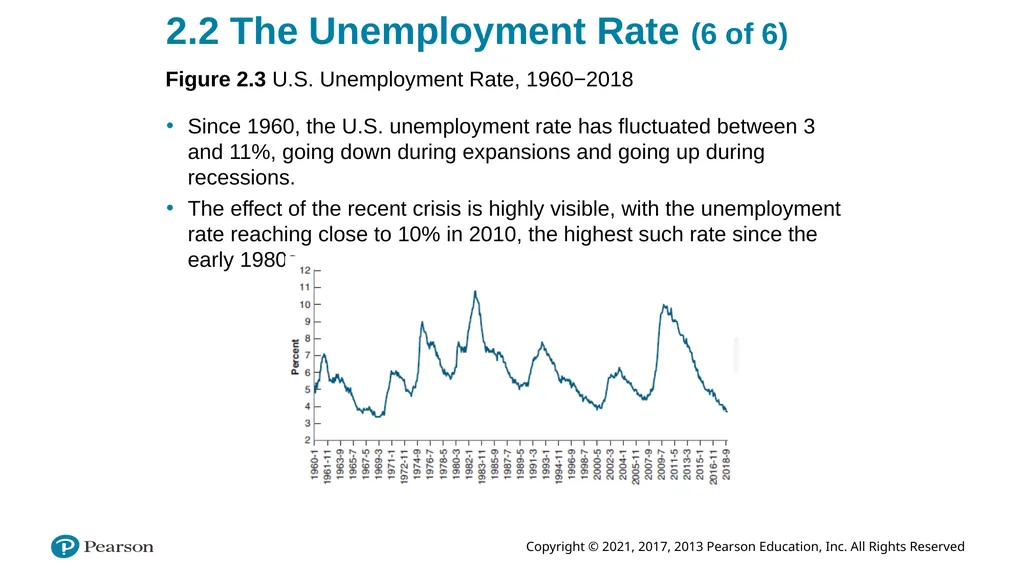
slide43. 2.2 The Unemployment Rate (6 of 6) Figure 2.3 U.S. Unemployment Rate, 1960−2018 Since 1960, the U.S. unemployment rate has fluctuated between 3 and 11%, going down during expansions and going up during recessions.
The effect of the recent crisis is highly visible, with the unemployment rate reaching close to 10% in 2010, the highest such rate since the early 1980s.<br>
slide44. FOCUS: Unemployment and Happiness Results of the German Socio-Economic Panel survey suggest that (1) becoming unemployed leads to a large decrease in happiness, (2) happiness declines before the actual unemployment spell, and (3) happiness does not fully recover even four years later. Figure 1 Effects of Unemployment on Happiness Source: Winkelmann 2014.<br>
slide45. 2.3 The Inflation Rate (1 of 8) Inflation is a sustained rise in the general level of prices—the price level.
The inflation rate is the rate at which the price level increases.
Deflation is a sustained decline in the price level (negative inflation rate).<br>
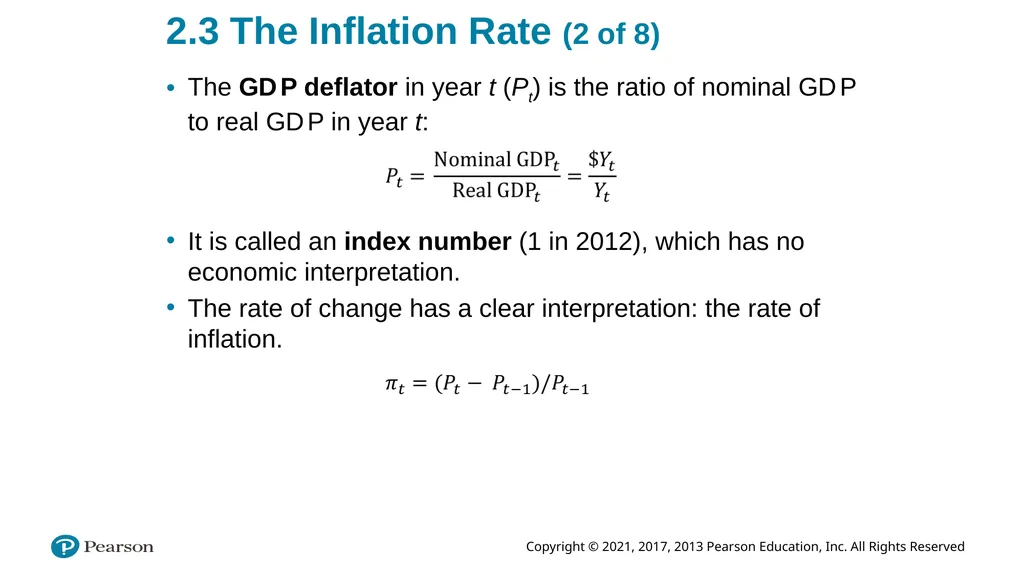
slide46. 2.3 The Inflation Rate (2 of 8) The G D P deflator in year t (Pt) is the ratio of nominal G D P to real G D P in year t: It is called an index number (1 in 2012), which has no economic interpretation.
The rate of change has a clear interpretation: the rate of inflation.<br>
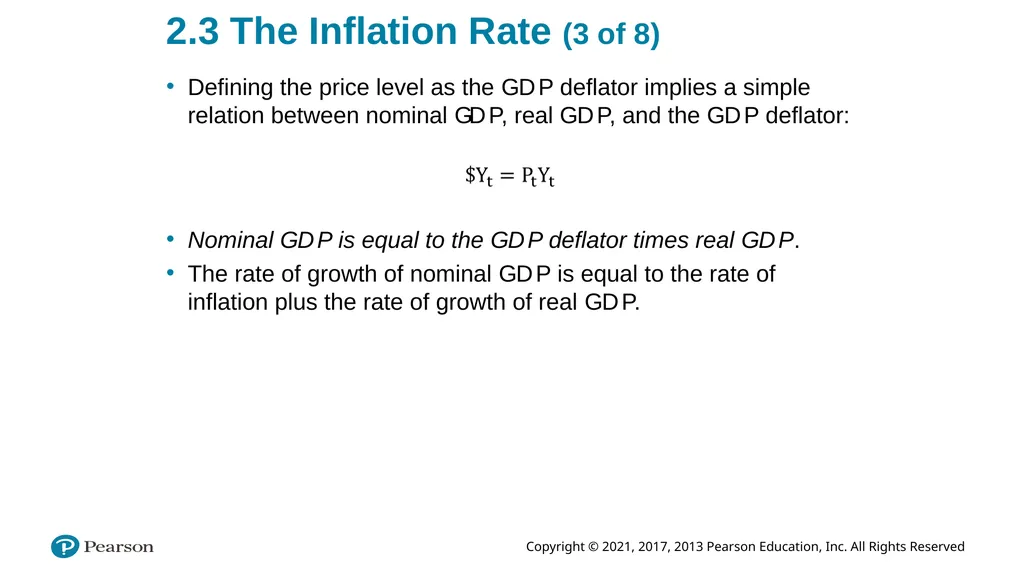
slide47. 2.3 The Inflation Rate (3 of 8) Defining the price level as the G D P deflator implies a simple relation between nominal GD P, real G D P, and the G D P deflator: Nominal G D P is equal to the G D P deflator times real G D P.
The rate of growth of nominal G D P is equal to the rate of inflation plus the rate of growth of real G D P.<br>
slide48. 2.3 The Inflation Rate (4 of 8) The set of goods produced in the economy is not the same as the set of goods purchased by consumers because:
Some of the goods in G D P are sold not to consumers but to firms, to the government, or to foreigners.
Some of the goods bought by consumers are not produced domestically but are imported from abroad.
The Consumer Price Index (C P I) is a measure of the cost of living.
The C P I is published monthly by the Bureau of Labor Statistics (B L S), which collects price data for 211 items in 38 cities.
The C P I gives the cost in dollars of a specific list of goods and services over time.<br>
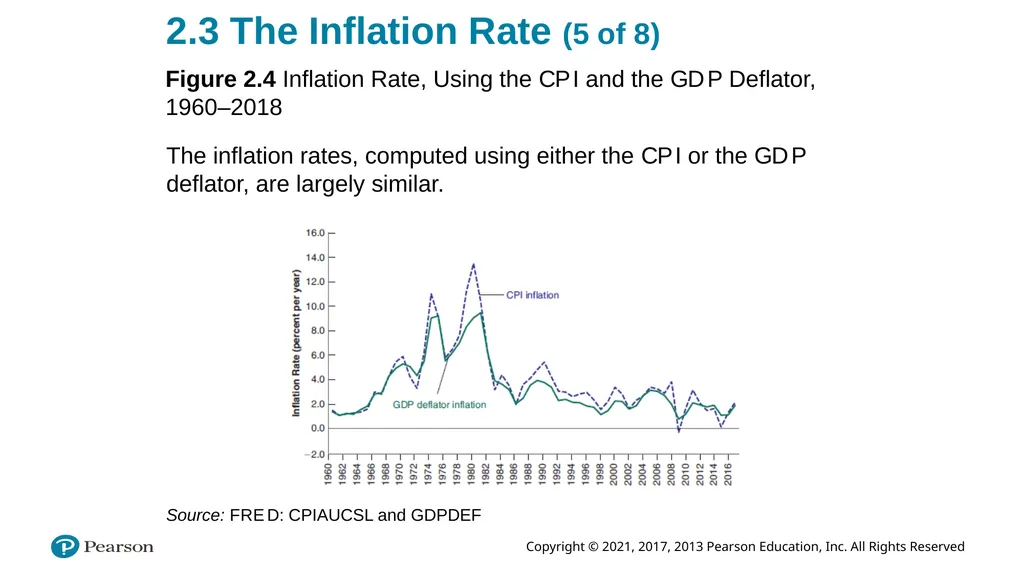
slide49. 2.3 The Inflation Rate (5 of 8) Figure 2.4 Inflation Rate, Using the C P I and the G D P Deflator, 1960–2018 The inflation rates, computed using either the C P I or the G D P deflator, are largely similar. Source: F R E D: CPIAUCSL and GDPDEF<br>
slide50. 2.3 The Inflation Rate (6 of 8) The C P I and G D P deflator moved together most of the time.
Exception: In 1979 and 1980, the increase in the C P I was significantly larger than the increase in the G D P deflator due to the price of imported goods increasing relative to the price of domestically produced goods.<br>
slide51. 2.3 The Inflation Rate (7 of 8) Pure inflation is proportional increase in all prices and wages.
This type of inflation causes only a minor inconvenience as relative prices are unaffected.
Real wage (wage measured by goods rather than dollars) would be unaffected.
There is no such thing as pure inflation.<br>
slide52. 2.3 The Inflation Rate (8 of 8) Why Do Economists Care about Inflation?
Inflation affects income distribution when not all prices and wages rise proportionally.
Inflation leads to distortions due to uncertainty, some prices that are fixed by law or by regulation, and its interaction with taxation (bracket creep in taxes).
Most economists believe the “best” rate of inflation to be a low and stable rate of inflation between 1 and 4%.<br>
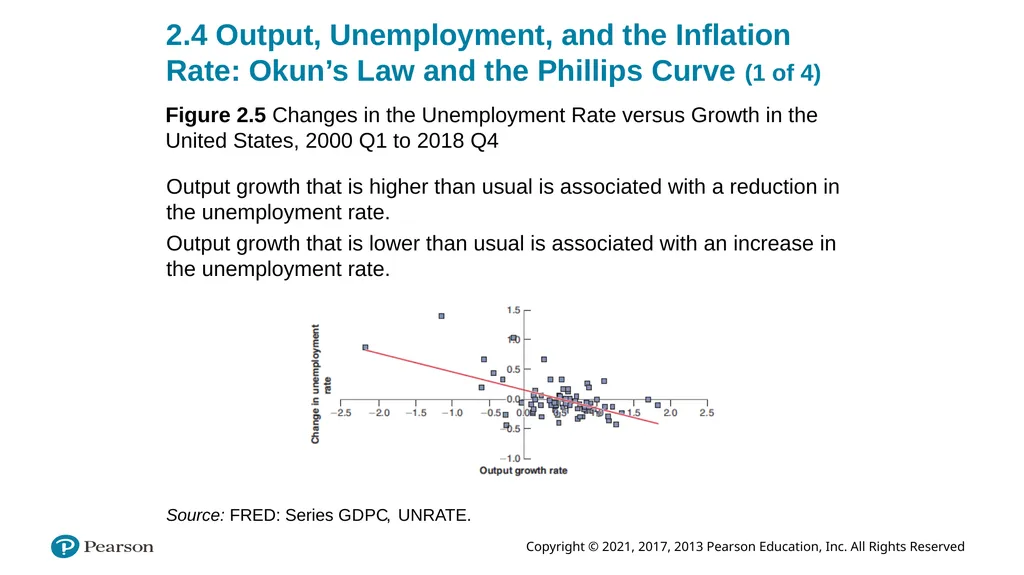
slide53. 2.4 Output, Unemployment, and the Inflation Rate: Okun’s Law and the Phillips Curve (1 of 4) Figure 2.5 Changes in the Unemployment Rate versus Growth in the United States, 2000 Q1 to 2018 Q4 Output growth that is higher than usual is associated with a reduction in the unemployment rate.
Output growth that is lower than usual is associated with an increase in the unemployment rate. Source: FRED: Series G D P C, UNRATE.<br>
slide54. 2.4 Output, Unemployment, and the Inflation Rate: Okun’s Law and the Phillips Curve (2 of 4) Okun’s law is a relation first examined by U.S. economist Arthur Okun.
In Figure 2-5, the line that best fits the points is downward sloping.
The slope of the line is –0.3, which implies that, on average, an increase in the growth rate of 1% decreases the unemployment rate by –0.3%.
The line crosses the horizontal axis where output growth is 0.5%, meaning that it takes a growth rate of 2% to keep unemployment constant.<br>
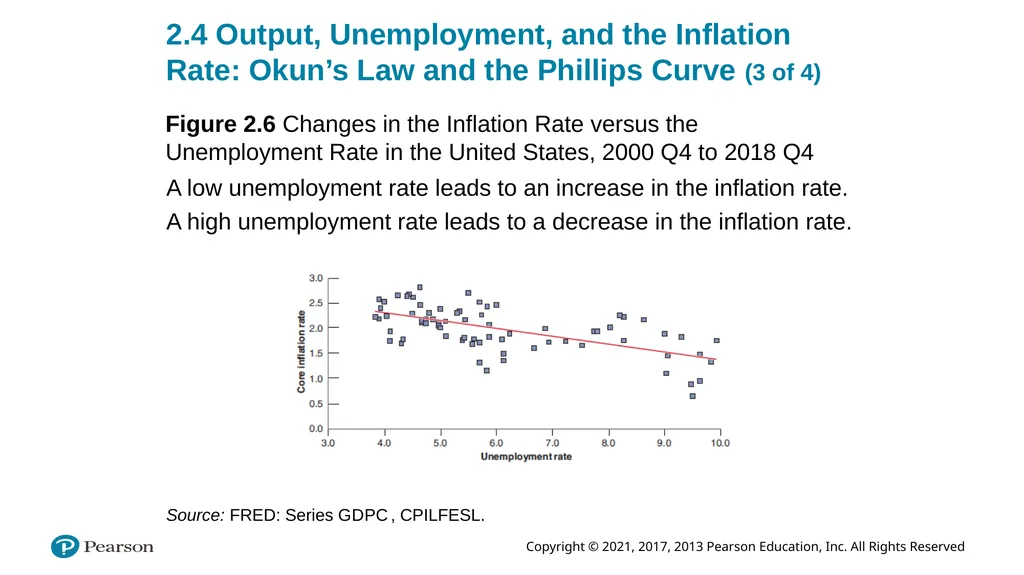
slide55. 2.4 Output, Unemployment, and the Inflation Rate: Okun’s Law and the Phillips Curve (3 of 4) Figure 2.6 Changes in the Inflation Rate versus the Unemployment Rate in the United States, 2000 Q4 to 2018 Q4 A low unemployment rate leads to an increase in the inflation rate.
A high unemployment rate leads to a decrease in the inflation rate. Source: FRED: Series G D P C , CPILFESL.<br>
slide56. 2.4 Output, Unemployment, and the Inflation Rate: Okun’s Law and the Phillips Curve (4 of 4) The Phillips curve is a relation first explored in 1958 by New Zealand economist A.W. Phillips.
Figure 2-6 plots the change in the inflation rate against the unemployment rate, along with the line that best fits the points.
The line is downward sloping, meaning that higher unemployment leads, on average, to a decrease in inflation, and vice versa.
When unemployment has been above 5%, inflation has typically been above 2%.<br>
slide57. 2.5 The Short Run, the Medium Run, and the Long Run In the short run (e.g., a few years), year-to-year movements in output are primarily driven by movements in demand.
In the medium run (e.g., a decade), the economy tends to return to the level of output determined by supply factors, such as the capital stock, the level of technology, and the size of the labor force.
In the long run (e.g., a few decades or more), the economy depends on its ability to innovate and introduce new technologies, and how much people save, the quality of the country’s education system, the quality of the government, and so on.<br>
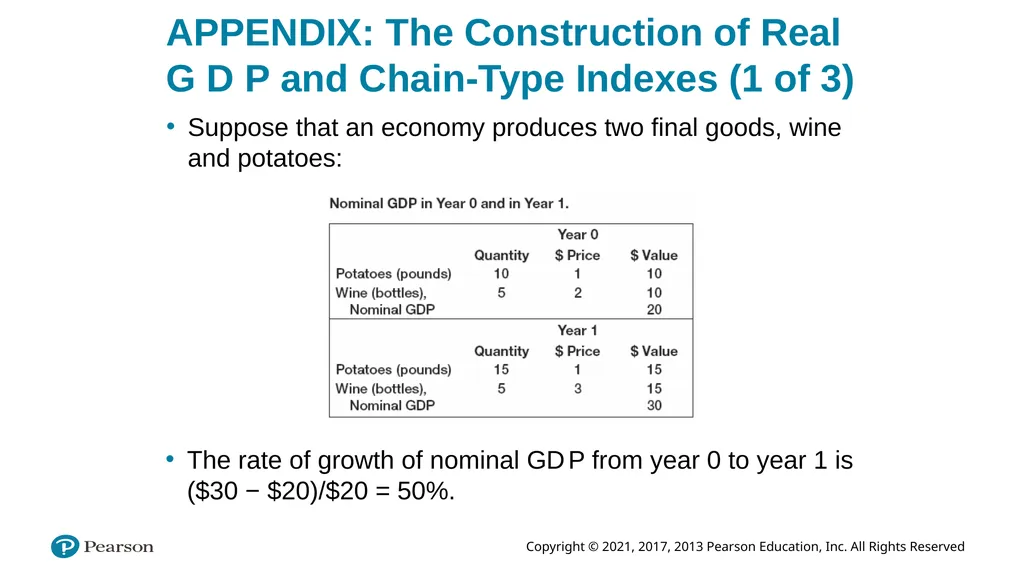
slide58. APPENDIX: The Construction of Real G D P and Chain-Type Indexes (1 of 3) Suppose that an economy produces two final goods, wine and potatoes: The rate of growth of nominal G D P from year 0 to year 1 is ($30 − $20)/$20 = 50%.<br>
slide59. APPENDIX: The Construction of Real G D P and Chain-Type Indexes (2 of 3) Suppose year 0 is the base year:
Real G D P in year 0: (10 x $1) + (5 x $2) = $20
Real G D P in year 1: (15 x $1) + (5 x $2) = $25
The rate of growth of real G D P from year 0 to year 1 is ($25 − $20)/$20 = 25%.
Suppose year 1 is the base year:
Real G D P in year 0: (10 x $1) + (5 x $3) = $25
Real G D P in year 1: (15 x $1) + (5 x $3) = $30
The rate of growth of real G D P from year 0 to year 1 is ($30 − $25)/$25 = 20%.
Problem: Which base year should one choose?<br>
slide60. APPENDIX: The Construction of Real G D P and Chain-Type Indexes (3 of 3) In December 1995, the U.S. Bureau of Economic Analysis shifted to a new method with four steps:
Construct the rate of change of real G D P between two years in two different ways: Using the price from year t as the set of common prices
Using the price from year t+1 as the set of common prices Construct the rate of change of real G D P as the average of these two rates of change
Construct an index of the level of real G D P by linking or chaining the constructed rates of change for each year
Multiply this index by nominal G D P to derive real G D P in chained dollars<br>
slide61. Macroeconomics Eighth Edition Chapter 3 The Goods Market Copyright © 2021, 2017, 2013 Pearson Education, Inc. All Rights Reserved Slide in this Presentation Contain Hyperlinks. JAWS users should be able to get a list of links by using INSERT+F7<br>
slide62. 3.1 The Composition of G D P (1 of 3) Consumption (C): goods and services purchased by consumers
Investment (I) or fixed investment: the sum of nonresidential investment and residential investment
Government spending (G): purchases of goods and services by the federal, state, and local governments; excluding government transfers<br>
slide63. 3.1 The Composition of G D P (2 of 3)<br>
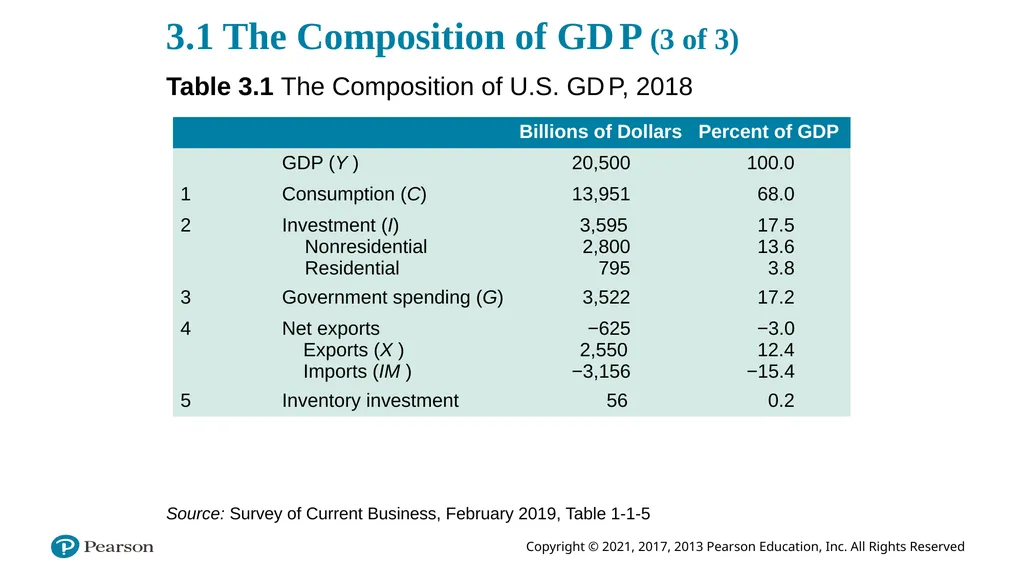
slide64. 3.1 The Composition of G D P (3 of 3) Table 3.1 The Composition of U.S. G D P, 2018 Source: Survey of Current Business, February 2019, Table 1-1-5<br>
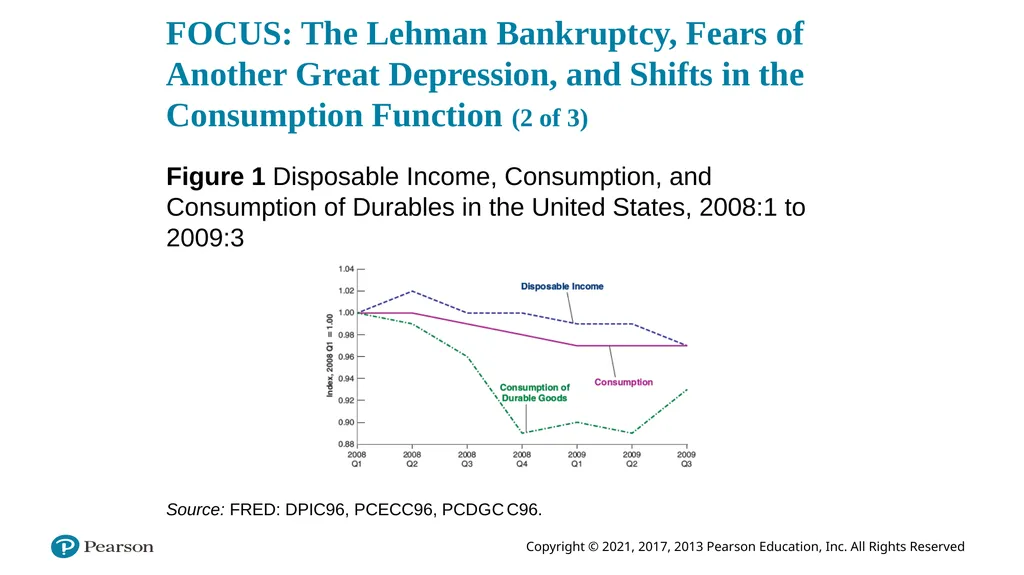
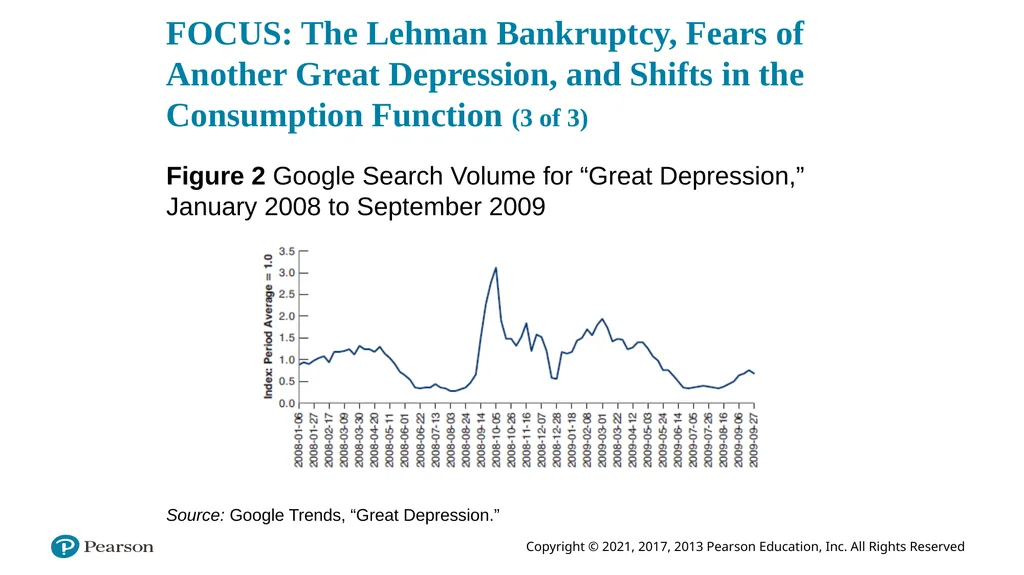
slide65. FOCUS: The Lehman Bankruptcy, Fears of Another Great Depression, and Shifts in the Consumption Function (1 of 3) When people start worrying about the future, they decide to save more even if their current income has not changed.
News about Lehman Brothers going bankrupt in September 2008 reminded people of the Great Depression, as confirmed by the number of searches for “Great Depression” in Google.
Consumption fell even if disposable income had not yet changed.<br>
slide66. FOCUS: The Lehman Bankruptcy, Fears of Another Great Depression, and Shifts in the Consumption Function (2 of 3) Figure 1 Disposable Income, Consumption, and Consumption of Durables in the United States, 2008:1 to 2009:3 Source: FRED: DPIC96, PCECC96, PCDG C C96.<br>
slide67. FOCUS: The Lehman Bankruptcy, Fears of Another Great Depression, and Shifts in the Consumption Function (3 of 3) Figure 2 Google Search Volume for “Great Depression,” January 2008 to September 2009 Source: Google Trends, “Great Depression.”<br>
slide68. 3.4 Investment Equals Saving: An Alternative Way of Thinking about Goods—Market Equilibrium (1 of 5) John Maynard Keynes articulated an alternative model that focuses instead on investment and saving in the General Theory of Employment, Interest and Money in 1936.
Private saving (S) is<br>
slide69. 3.4 Investment Equals Saving: An Alternative Way of Thinking about Goods—Market Equilibrium (2 of 5) In equilibrium: Subtract T from both sides and move C to the left side: The left side of the equation is simply S, so Or equivalently This is the I S relation, which stands for “Investment equals Saving”.<br>
slide70. 3.4 Investment Equals Saving: An Alternative Way of Thinking about Goods—Market Equilibrium (3 of 5) Two equivalent ways of stating the condition for equilibrium in the goods market: Production = Demand
Investment = Saving<br>
slide71. 3.5 Is the Government Omnipotent? A Warning Equation (3.8) implies that the government can choose the level of G or T to affect the level of output it wants.
However, there are many aspects of reality that we have not incorporated in our model:
Changing G or T is not easy.
Investment and imports may change, making it hard for governments to assess the effects of their policies (Chapters 5, 9, and 18 to 20).
Expectations are likely to matter (Chapters 14 to 16).
The effects on output may be unsustainable in the medium run (Chapter 9).
Cutting T or increasing G can lead to large budget deficits and public debt in the long run (Chapters 9, 11, 16 and 22).<br>
slide72. Macroeconomics Eighth Edition Chapter 4 Financial Markets Ⅰ Copyright © 2021, 2017, 2013 Pearson Education, Inc. All Rights Reserved<br>
slide73. Financial Markets Financial markets are intimidating, but they play an essential role in the economy.
In this chapter, we focus on the role of the central bank in affecting these interest rates.
We learn how the interest rate on bonds is determined, and the role of the central bank (Federal Reserve Bank, or the Fed, in the United States) in this determination.<br>
slide74. FOCUS: Semantic Traps: Money, Income, and Wealth Money is what can be used to pay for transactions.
Income is what you earn, and it is a flow.
Saving is the part of after-tax income that you do not spend, and it is also a flow.
Savings is the value of what you have accumulated over time.
Financial wealth, or wealth, is the value of all your financial assets minus all your financial liabilities, and it is a stock variable.
Investment is what economists refer to as the purchase of new capital goods.
Financial investment is the purchase of shares or other financial assets.<br>
slide75. 4.1 The Demand for Money (1 of 5) Suppose you only have a choice between two assets: money and bonds.
Money are used for transactions, but it pays no interest.
Two types of money: currency and checkable deposits.
Bonds pay a positive interest rate, i (the rate of interest), but cannot be used for transactions.<br>
slide76. 4.1 The Demand for Money (2 of 5) The holding of money and bonds depends on:
Your level of transactions
The interest rate on bonds
You can hold bonds indirectly through money market funds, or money market mutual funds.
In the early 1980s, the interest rate on money market funds reached 14% per year, so people earned more interest by moving their wealth from checking accounts to these funds.<br>
slide77. 4.1 The Demand for Money (3 of 5) Demand for money (Md) is equal to nominal income $Y (a measure of level of transactions in the economy) times a decreasing function of the interest rate i: An increase in the interest rate decreases the demand for money, as people put more of their wealth into bonds.<br>
slide78. 4.1 The Demand for Money (4 of 5) Equation (4.1) means that the demand for money:
increases in proportion to nominal income, and
depends negatively on the interest rate.
The relation between the demand for money and interest rate for a given level of income $Y is represented by the Md curve.<br>
slide79. 4.1 The Demand for Money (5 of 5) Figure 4.1 The Demand for Money For a given level of nominal income, a lower interest rate increases the demand for money.
At a given interest rate, an increase in nominal income shifts the demand for money to the right.<br>
slide80. FOCUS: Who Holds U.S. Currency The amount of currency in circulation in 2006 was $750 billion.
U.S. households together held $170 billion in currency.
U.S. firms held another $80 billion.
Foreigners abroad held $500 billion, or 66% of the total, for transactions, especially in countries suffering from high inflation in the past.<br>
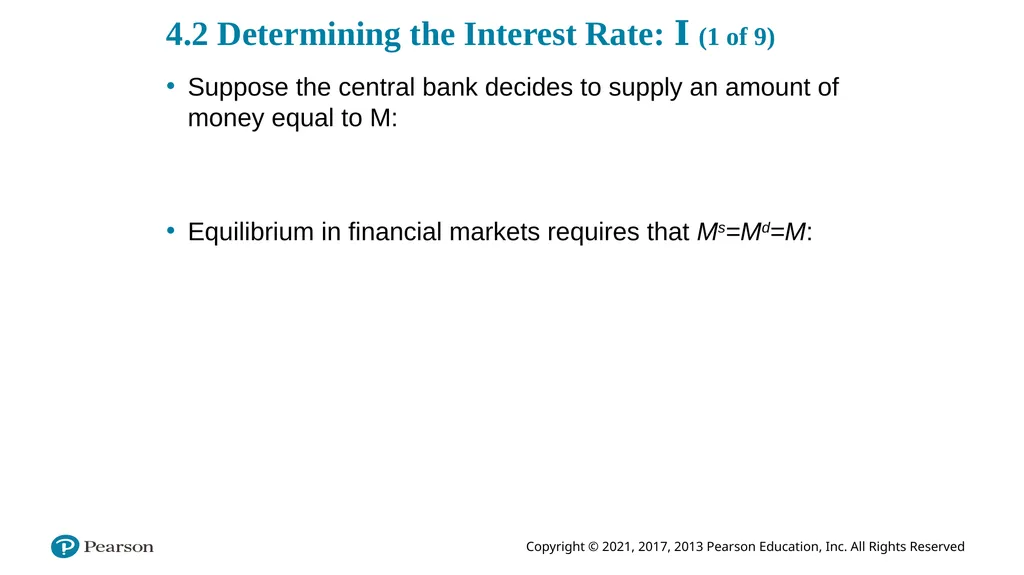
slide81. 4.2 Determining the Interest Rate: Ⅰ (1 of 9) Suppose the central bank decides to supply an amount of money equal to M: Equilibrium in financial markets requires that Ms=Md=M:<br>
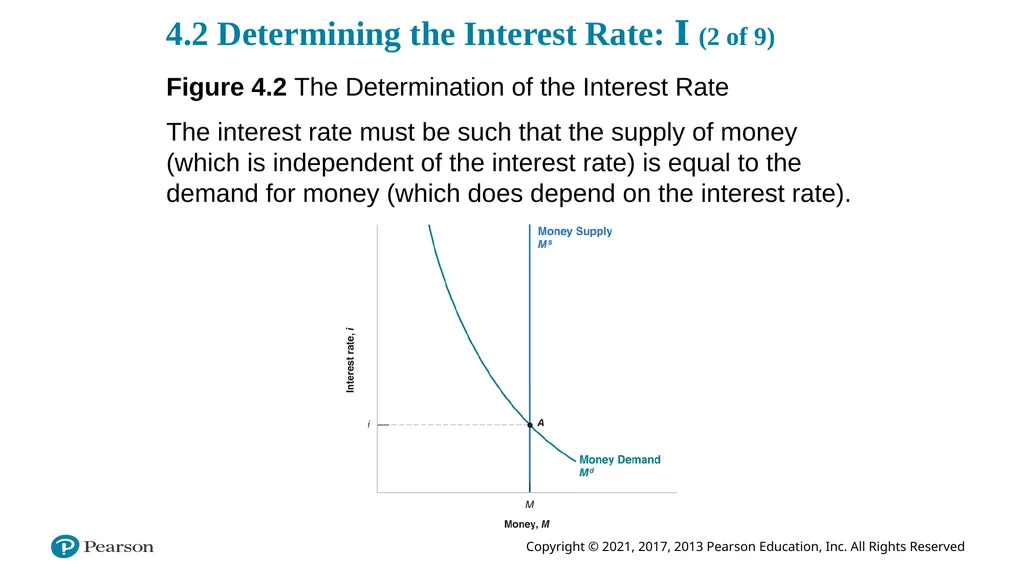
slide82. 4.2 Determining the Interest Rate: Ⅰ (2 of 9) Figure 4.2 The Determination of the Interest Rate The interest rate must be such that the supply of money (which is independent of the interest rate) is equal to the demand for money (which does depend on the interest rate).<br>
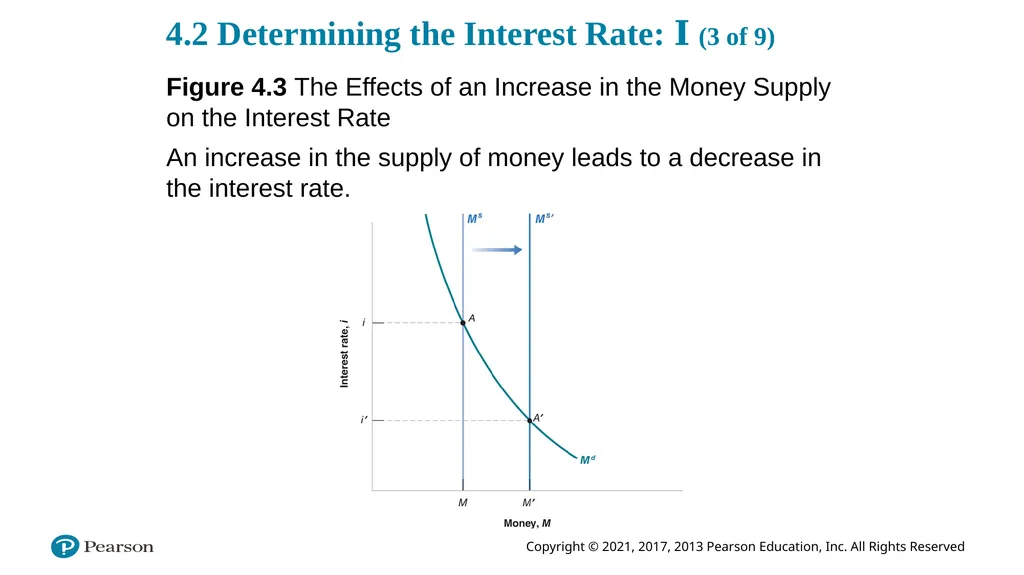
slide83. 4.2 Determining the Interest Rate: Ⅰ (3 of 9) Figure 4.3 The Effects of an Increase in the Money Supply on the Interest Rate An increase in the supply of money leads to a decrease in the interest rate.<br>
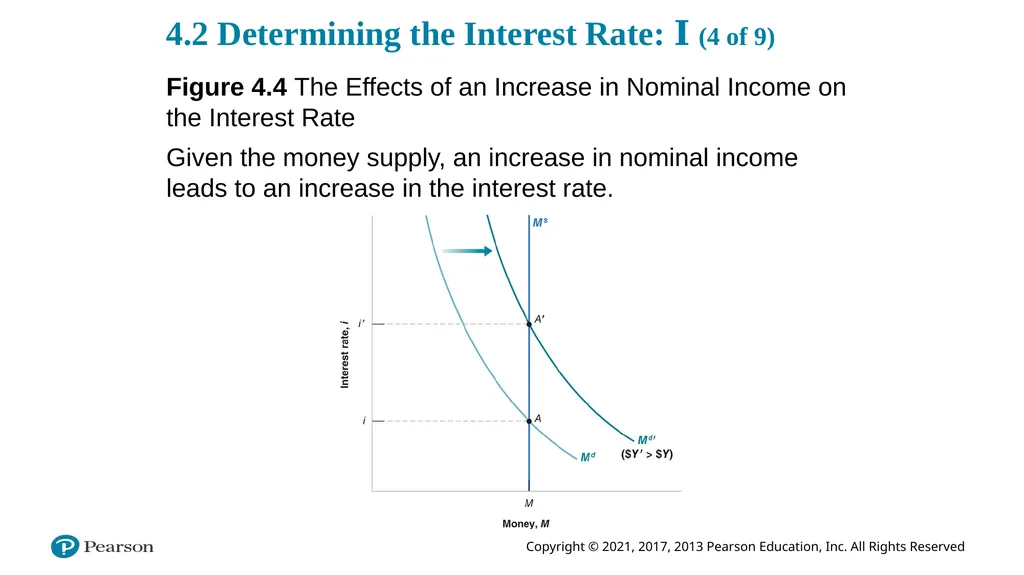
slide84. 4.2 Determining the Interest Rate: Ⅰ (4 of 9) Figure 4.4 The Effects of an Increase in Nominal Income on the Interest Rate Given the money supply, an increase in nominal income leads to an increase in the interest rate.<br>
slide85. 4.2 Determining the Interest Rate: Ⅰ (5 of 9) For a given money supply, an increase in nominal income leads to an increase in the interest rate.
An increase in the supply of money by the central bank leads to a decrease in the interest rate.<br>
slide86. 4.2 Determining the Interest Rate: Ⅰ (6 of 9) Central banks typically change the supply of money by buying or selling bonds in the bond market—open market operations.
Expansionary open market operation: the central bank expands the supply of money by buying bonds.
Contractionary open market operation: the central bank contracts the supply of money by selling bonds.<br>
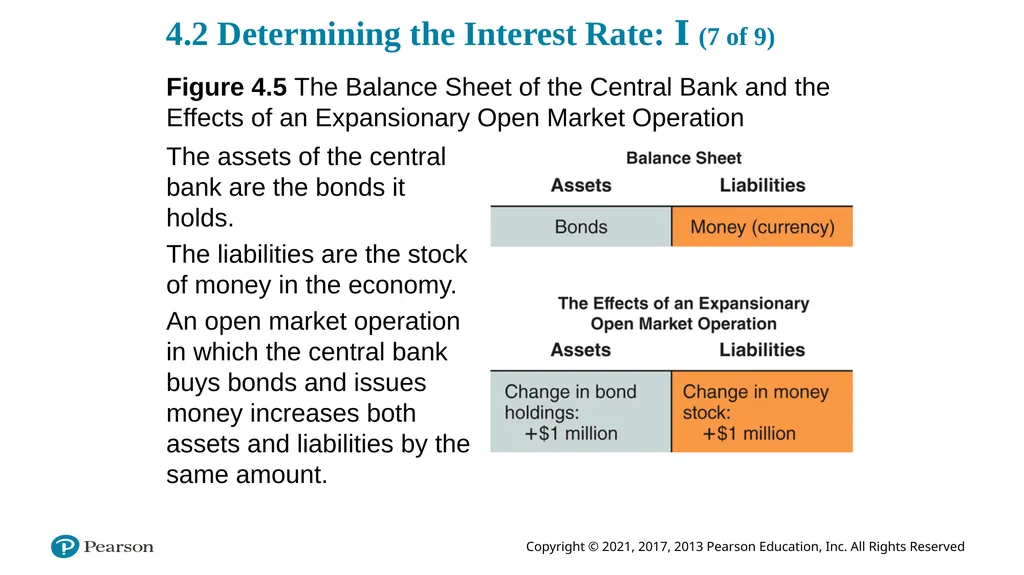
slide87. 4.2 Determining the Interest Rate: Ⅰ (7 of 9) Figure 4.5 The Balance Sheet of the Central Bank and the Effects of an Expansionary Open Market Operation The assets of the central bank are the bonds it holds.
The liabilities are the stock of money in the economy.
An open market operation in which the central bank buys bonds and issues money increases both assets and liabilities by the same amount.<br>
slide88. 4.2 Determining the Interest Rate: Ⅰ (8 of 9) Suppose a bond such as a Treasury bill, or T-bill, promises to pay $100 a year from now.
If the price of the bond today is $P B, then the interest rate on the bond is: The higher the price of the bond, the lower the interest rate.
The higher the interest rate, the lower the price today.<br>
slide89. 4.2 Determining the Interest Rate: Ⅰ (9 of 9) Rather than the money supply, the central bank could have chosen the interest rate and then adjusted the money supply so as to achieve the interest rate it had chosen.
Choosing the interest rate, instead of the money supply, is what modern central banks, including the Fed, typically do.<br>
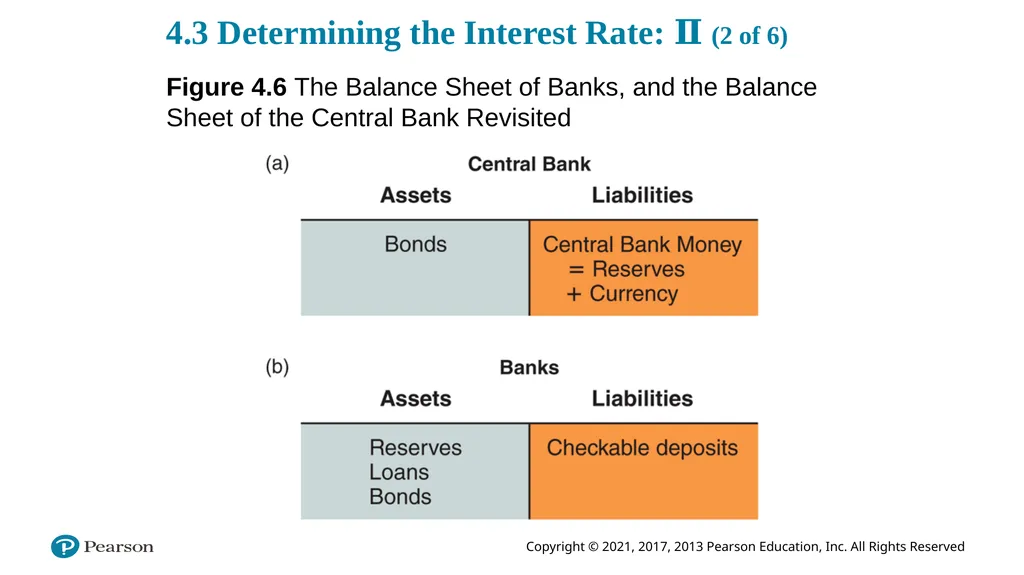
slide90. 4.3 Determining the Interest Rate: Ⅱ (1 of 6) Financial intermediaries: Institutions that receive funds from people and firms and use these funds to buy financial assets or to make loans to other people and firms.
Banks are financial intermediaries that have money, in the form of checkable deposits, as their liabilities.
Banks keep as reserves some of the funds they receive.
The liabilities of the central bank are the money it has issued, called central bank money.<br>
slide91. 4.3 Determining the Interest Rate: Ⅱ (2 of 6) Figure 4.6 The Balance Sheet of Banks, and the Balance Sheet of the Central Bank Revisited<br>
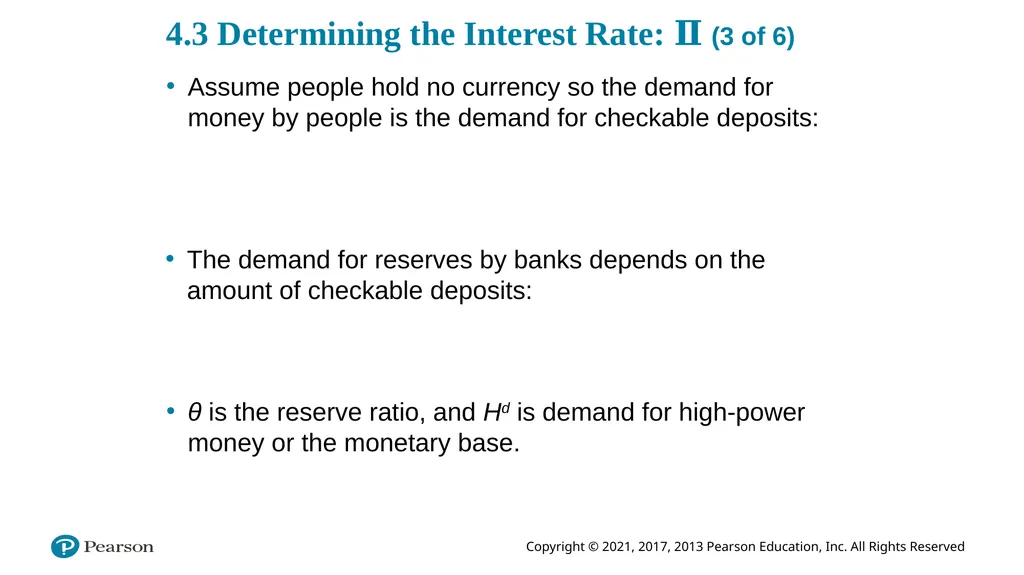
slide92. 4.3 Determining the Interest Rate: Ⅱ (3 of 6) Assume people hold no currency so the demand for money by people is the demand for checkable deposits: The demand for reserves by banks depends on the amount of checkable deposits: θ is the reserve ratio, and Hd is demand for high-power money or the monetary base.<br>
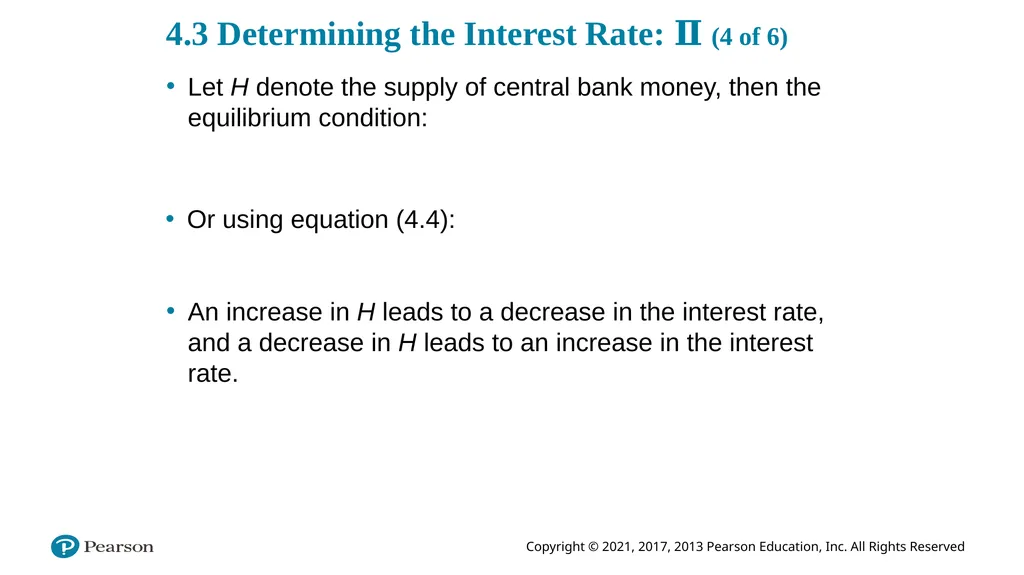
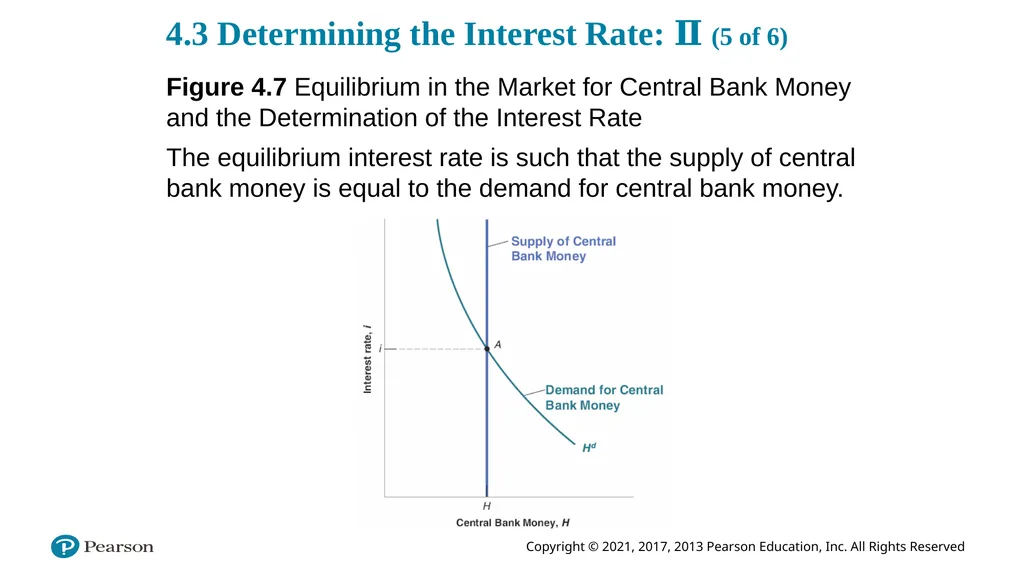
slide93. 4.3 Determining the Interest Rate: Ⅱ (4 of 6) Let H denote the supply of central bank money, then the equilibrium condition: Or using equation (4.4): An increase in H leads to a decrease in the interest rate, and a decrease in H leads to an increase in the interest rate.<br>
slide94. 4.3 Determining the Interest Rate: Ⅱ (5 of 6) Figure 4.7 Equilibrium in the Market for Central Bank Money and the Determination of the Interest Rate The equilibrium interest rate is such that the supply of central bank money is equal to the demand for central bank money.<br>
slide95. 4.3 Determining the Interest Rate: Ⅱ (6 of 6) The federal funds market is an actual market for bank reserves.
The federal funds rate is the interest rate determined in the federal funds market.
The federal funds rate is the main indicator of U.S. monetary policy because the Fed can choose the federal funds rate it wants by changing H.<br>
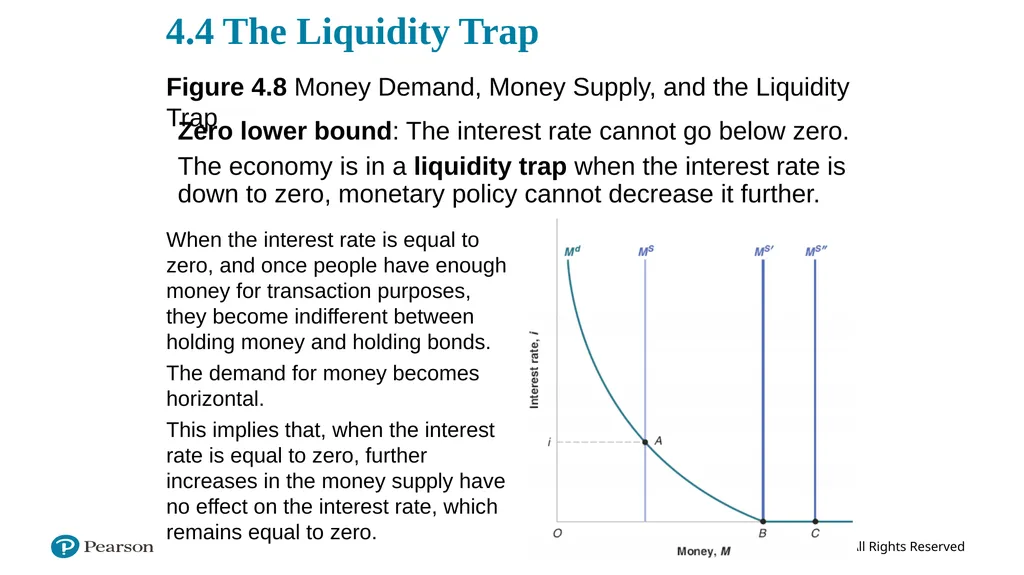
slide96. 4.4 The Liquidity Trap Figure 4.8 Money Demand, Money Supply, and the Liquidity Trap When the interest rate is equal to zero, and once people have enough money for transaction purposes, they become indifferent between holding money and holding bonds.
The demand for money becomes horizontal.
This implies that, when the interest rate is equal to zero, further increases in the money supply have no effect on the interest rate, which remains equal to zero. Zero lower bound: The interest rate cannot go below zero.
The economy is in a liquidity trap when the interest rate is down to zero, monetary policy cannot decrease it further.<br>
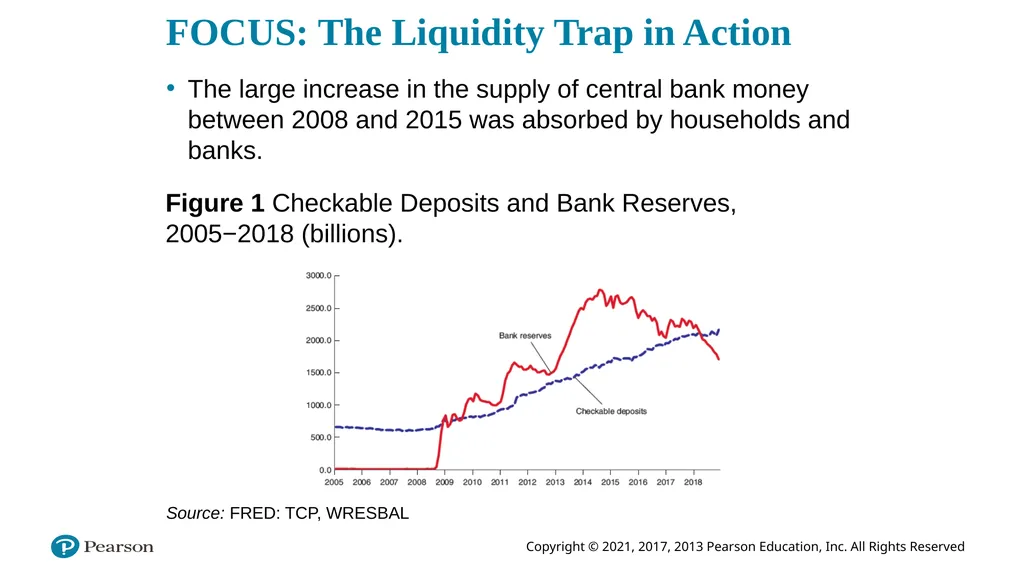
slide97. FOCUS: The Liquidity Trap in Action The large increase in the supply of central bank money between 2008 and 2015 was absorbed by households and banks. Figure 1 Checkable Deposits and Bank Reserves, 2005−2018 (billions). Source: FRED: TCP, WRESBAL<br>
Sep. 8, 2022<br>
slide2. Copyright This work is protected by United States copyright laws and is provided solely for the use of instructors in teaching their courses and assessing student learning. Dissemination or sale of any part of this work (including on the World Wide Web) will destroy the integrity of the work and is not permitted. The work and materials from it should never be made available to students except by instructors using the accompanying text in their classes. All recipients of this work are expected to abide by these restrictions and to honor the intended pedagogical purposes and the needs of other instructors who rely on these materials.<br>
slide3. Macroeconomics Eighth Edition Chapter 1 A Tour of the World Copyright © 2021, 2017, 2013 Pearson Education, Inc. All Rights Reserved<br>
slide4. A Tour of the World What is macroeconomics? The best way to answer this question is to take you on an economic tour of the world.
The goal of this chapter is to give you a sense of these recent events and of some of the macroeconomic issues confronting different countries today.<br>
slide5. 1.1 The Crisis (1 of 3) From 2000 to 2007, the world economy had a sustained expansion.
In 2007, U.S. housing prices started declining, leading to a major financial crisis.
The financial crisis turned into a major economic crisis with falling stock prices.
In the third quarter of 2008, U.S. output growth turned negative and remained so in 2009.
Through the trade and financial channels, the U.S. crisis quickly became a world crisis.<br>
slide6. 1.1 The Crisis (2 of 3) Figure 1.1 Output Growth Rates for the World Economy, for Advanced Economies, and for Emerging and Developing Economies, 2000–2018 Source: IMF. World Economic Outlook Database, July 2018. N G D P_R P C H.A.<br>
slide7. 1.1 The Crisis (3 of 3) Figure 1.2 Stock prices in the United States, the Euro area, and emerging economies, 2007–2010 Source: IMF. World Economic Outlook Database, July 2018. N G D P_R P C H.A.<br>
slide8. 1.2 The United States (1 of 6) The United States is big
With an output of $20.5 trillion in 2018, it accounted for 24% of world output.
The U.S. standard of living is high
Output per capita is $62,500, close to the highest in the world.
Economists also look at:
Output growth
Unemployment rate
Inflation rate<br>
slide9. 1.2 The United States (2 of 6) Figure 1.3 The United States, 2018<br>
slide10. 1.2 The United States (3 of 6) The U.S. economy in 2018 was in good shape, leaving the effects of the 2008-2009 crisis behind with one of the longest economic expansions on record. Table 1.1 Growth, Unemployment, and Inflation in the United States, 1990–2018 Output growth rate: annual rate of growth of output (G D P). Unemployment rate: average over the year. Inflation rate: annual rate of change of the price level (G D P deflator). Source: I M F, World Economic Outlook, October 2018.<br>
slide11. 1.2 The United States (4 of 6) The federal funds rate—the interest rate the Fed controls—went from 2.5% in July 2007 to nearly 0% in December 2008. Figure 1.4 The U.S. Federal Funds Rate since 2000 Source: Haver Analytics.<br>
slide12. 1.2 The United States (5 of 6) Why did the Federal Funds rate stop at zero?
This constraint is known as the zero lower bound.
If it were negative, then everyone would hold cash rather than bonds.
Why are low interest rates a potential issue?
Low interest rates limit the Fed’s ability to respond to further negative shocks.
Low interest rates may lead to excessive risk taking by investors to increase their returns.<br>
slide13. 1.2 The United States (6 of 6) Productivity growth is important for a sustained increase in income per person, but since 2010, it has been only about half as it was in the 1990s.
The slowdown in productivity growth is worrisome because the standard of living especially for the poor may not increase. Table 1.2 Labor Productivity Growth, by Decade, 1990-2018 Source: FRED database. PRS85006092, MPU490063.<br>
slide14. 1.3 The Euro Area (1 of 6) The European Union (E U) is a group of 28 European countries with a common market.
In 1999, the E U formed a common currency area called the Euro area, which replaced national currencies in 2002 with the euro.
The Euro area faces two main issues today:
How to reduce unemployment?
How to function efficiently as a common currency area?<br>
slide15. 1.3 The Euro Area (2 of 6) While the United States recovered from the 2008–2009 crisis, output growth in the Euro area was negative between in both 2012 and 2013.
In 2018, output growth was below the pre-crisis average and the unemployment rate was 8.3%. Table 1.3 Growth, Unemployment, and Inflation in the Euro Area, 1990–2018 Output growth rate: annual rate of growth of output (G D P). Unemployment rate: average over the year. Inflation rate: annual rate of change of the price level (G D P deflator). Source: I M F, World Economic Outlook, October 2018.<br>
slide16. 1.3 The Euro Area (3 of 6) Figure 1.5 The Euro area, 2018<br>
slide17. 1.3 The Euro Area (4 of 6) While the average unemployment rate for the Euro area was 8.3% in 2018, countries like Spain had an unemployment rate of 15%.
Much of the high unemployment rate was the result of the crisis.
Even when Spain had its lowest unemployment rate of 8%, it was nearly three times that of the Germany today.
Some economists believe labor market rigidities with too much protection for workers are the main problem.<br>
slide18. 1.3 The Euro Area (5 of 6) Figure 1.6 Unemployment in Spain since 1990 Source: International Monetary Fund, World Economic Outlook, July 2018.<br>
slide19. 1.3 The Euro Area (6 of 6) Supporters of the euro argue:
economic advantages due to no more changes in exchange rates to worry about
its contribution to the creation of a large economic power
Others argue:
the drawback of a common monetary policy across euro countries
the loss of the exchange rate as an adjustment instrument within the euro area<br>
slide20. 1.4 China (1 of 3) China is in the news every day.
Its population is more than four times that of the United States.
But its output at $13.5 trillion is only about 60% of the United States.
Output per person is roughly 15% of that of the United States.
China has been growing very rapidly for more than three decades.<br>
slide21. 1.4 China (2 of 3) Figure 1.7 China, 2018 Source: IMF, World Economic Outlook, October 2018.<br>
slide22. 1.4 China (3 of 3) China’s rapid output growth has been driven by high accumulation of capital and technological progress.
The slowdown after the crisis is considered to be desirable as more of output would go to consumption instead of investment. Table 1.4 Growth, unemployment and Inflation in China, 1990–2018 Output growth rate: annual rate of growth of output (G D P). Unemployment rate: average over the year. Inflation rate: annual rate of change of the price level (G D P deflator). Source: I M F, World Economic Outlook, October 2018.<br>
slide23. 1.5 Looking Ahead We could have also looked at other regions like India, Japan, Latin America, Central and Eastern Europe, and Africa.
You could have also thought about the issues triggered by the crisis, how monetary and fiscal policies can be used to avoid recessions, and why growth rates differ so much across countries.
The purpose of this book is to give you a way of thinking about these issues.<br>
slide24. Macroeconomics Eighth Edition Chapter 2 A Tour of the Book Copyright © 2021, 2017, 2013 Pearson Education, Inc. All Rights Reserved Slide in this Presentation Contain Hyperlinks. JAWS users should be able to get a list of links by using INSERT+F7<br>
slide25. A Tour of the Book The words output, unemployment, and inflation appear daily in newspapers and on the evening news.
In this chapter, we define these words more precisely.
The chapter also introduces concepts around which the book is organized: the short run, the medium run, and the long run.<br>
slide26. 2.1 Aggregate Output (1 of 11) National income and product accounts were developed at the end of World War Ⅱ as measures of aggregate output.
The measure of aggregate output is called gross domestic product (G D P).
How would you define aggregate output in the economy?<br>
slide27. 2.1 Aggregate Output (2 of 11) Consider an economy with two firms, Firm 1 and Firm 2.
Is aggregate output the sum of the values of all goods produced, i.e., $300? Or just the value of cars, i.e., $200?
Steel is an intermediate good, which is a good used in the production of another good.<br>
slide28. 2.1 Aggregate Output (3 of 11) G D P is the value of the final goods and services produced in the economy during a given period. We want to count only final goods, not intermediate goods.
If we merge the two firms in the previous example, the revenues of the new firm equal $200.<br>
slide29. 2.1 Aggregate Output (4 of 11) G D P is the sum of value added in the economy during a given period. The value added by a firm is the value of its production minus the value of the intermediate goods used in production.
In the two-firm example, the value added equals $100 + $100 = $200.
So far, we have looked at G D P from the production side.<br>
slide30. 2.1 Aggregate Output (5 of 11) G D P is the sum of incomes in the economy during a given period. Aggregate production and aggregate income are always equal.
From the income side, valued added in the two-firm example is equal to the sum of labor income ($150) and capital or profit income ($50), i.e., $200.<br>
slide31. 2.1 Aggregate Output (6 of 11) Nominal G D P is the sum of the quantities of final goods produced times their current price.
Nominal G D P increases for two reasons:
The production of most goods increases over time
The price of most goods increases over time
Our goal is to measure production and its change over time.
Real G D P is the sum of quantities of final goods times constant (not current) prices.<br>
slide32. 2.1 Aggregate Output (7 of 11) Example: Real G D P in 2011 (in 2012 dollars) = 10 cars x $24,000 per car = $240,000.
Real G D P in 2012 (in 2012 dollars) = 12 cars x $24,000 per car = $288,000.
Real G D P in 2013 (in 2012 dollars) = 13 cars x $24,000 per car = $312,000.<br>
slide33. 2.1 Aggregate Output (8 of 11) For more than one good, relative prices of the goods are natural weights for constructed the weighted average of the output of all final goods.
Real G D P in chained (2012) dollars reflects relative prices that change over time.
The year used to construct prices is called the base year.<br>
slide34. 2.1 Aggregate Output (9 of 11) Figure 2.1 Nominal and Real U.S. G D P, 1960–2018 From 1960 and 2018, nominal G D P increased by a factor of 38. Real G D P increased by a factor of about 5.7. Source: FRED. Series G D P C , G D P.<br>
slide35. 2.1 Aggregate Output (10 of 11) Nominal G D P is also called dollar G D P, or G D P in current dollars.
Real G D P is also called G D P in terms of goods, G D P in constant dollars, G D P adjusted for inflation, or G D P in chained (2012) dollars, or G D P in 2012 dollars.
G D P will refer to real G D P.
Yt will denote real G D P in year t.
Nominal G D P and variables in current dollars will be denoted by a dollar sign in front of them, e.g., $Yt<br>
slide36. 1.2 The United States (4 of 6) Figure 2.2 Growth Rate of U.S. G D P, 1960–2018 G D P growth in year t is (Yt − Yt-1)/Yt-1.
Since 1960, the U.S. economy has gone through a series of expansions, interrupted by short recessions. The 2008−2009 recession was the most severe recession in the period from 1960 to 2018. Source: Calculated using series G D P C in Figure 2.1.<br>
slide37. FOCUS: Real G D P, Technological Progress, and the Price of Computers The Department of Commerce deals with changes in the quality of existing goods like computers with an approach called hedonic pricing, which treats goods as providing a collection of characteristics.
The quality of new laptops (computing services) has increased on average by 20% a year since 1999.
The dollar price of a typical laptop has also declined by about 7% a year since 1999.
This implies that laptops’ quality-adjusted price has fallen at an average rate of 20% + 7% = 27% per year.<br>
slide38. 2.2 The Unemployment Rate (1 of 6) Employment is the number of people who have a job.
Unemployment is the number of people who do not have a job but are looking for one.
The labor force is the sum of employment and unemployment.<br>
slide39. 2.2 The Unemployment Rate (2 of 6) The unemployment rate is the ratio of the number of people who are unemployed to the number of people in the labor force.<br>
slide40. 2.2 The Unemployment Rate (3 of 6) Most rich countries rely on large surveys of households to compute the unemployment rate.
The U.S. Current Population Survey (C P S) relies on interviews of 60,000 households every month.
A person is unemployed if he or she does not have a job and has been looking for a job in the last four weeks.
Those who do not have a job and are not looking for one are counted as not in the labor force.<br>
slide41. 2.2 The Unemployment Rate (4 of 6) Discouraged workers are those persons who give up looking for a job and so no longer count as unemployed.
The participation rate is the ratio of the labor force to the total population of working age.
Because of discouraged workers, a higher unemployment rate is typically associated with a lower participation rate.<br>
slide42. 2.2 The Unemployment Rate (5 of 6) Why Do Economists Care about Unemployment?
Because of its direct effect on the welfare of the unemployed, especially those remaining unemployed for long periods of time.
It is a signal that the economy is not using its human resources efficiently. Very low unemployment can also be a problem as the economy runs into labor shortages.<br>
slide43. 2.2 The Unemployment Rate (6 of 6) Figure 2.3 U.S. Unemployment Rate, 1960−2018 Since 1960, the U.S. unemployment rate has fluctuated between 3 and 11%, going down during expansions and going up during recessions.
The effect of the recent crisis is highly visible, with the unemployment rate reaching close to 10% in 2010, the highest such rate since the early 1980s.<br>
slide44. FOCUS: Unemployment and Happiness Results of the German Socio-Economic Panel survey suggest that (1) becoming unemployed leads to a large decrease in happiness, (2) happiness declines before the actual unemployment spell, and (3) happiness does not fully recover even four years later. Figure 1 Effects of Unemployment on Happiness Source: Winkelmann 2014.<br>
slide45. 2.3 The Inflation Rate (1 of 8) Inflation is a sustained rise in the general level of prices—the price level.
The inflation rate is the rate at which the price level increases.
Deflation is a sustained decline in the price level (negative inflation rate).<br>
slide46. 2.3 The Inflation Rate (2 of 8) The G D P deflator in year t (Pt) is the ratio of nominal G D P to real G D P in year t: It is called an index number (1 in 2012), which has no economic interpretation.
The rate of change has a clear interpretation: the rate of inflation.<br>
slide47. 2.3 The Inflation Rate (3 of 8) Defining the price level as the G D P deflator implies a simple relation between nominal GD P, real G D P, and the G D P deflator: Nominal G D P is equal to the G D P deflator times real G D P.
The rate of growth of nominal G D P is equal to the rate of inflation plus the rate of growth of real G D P.<br>
slide48. 2.3 The Inflation Rate (4 of 8) The set of goods produced in the economy is not the same as the set of goods purchased by consumers because:
Some of the goods in G D P are sold not to consumers but to firms, to the government, or to foreigners.
Some of the goods bought by consumers are not produced domestically but are imported from abroad.
The Consumer Price Index (C P I) is a measure of the cost of living.
The C P I is published monthly by the Bureau of Labor Statistics (B L S), which collects price data for 211 items in 38 cities.
The C P I gives the cost in dollars of a specific list of goods and services over time.<br>
slide49. 2.3 The Inflation Rate (5 of 8) Figure 2.4 Inflation Rate, Using the C P I and the G D P Deflator, 1960–2018 The inflation rates, computed using either the C P I or the G D P deflator, are largely similar. Source: F R E D: CPIAUCSL and GDPDEF<br>
slide50. 2.3 The Inflation Rate (6 of 8) The C P I and G D P deflator moved together most of the time.
Exception: In 1979 and 1980, the increase in the C P I was significantly larger than the increase in the G D P deflator due to the price of imported goods increasing relative to the price of domestically produced goods.<br>
slide51. 2.3 The Inflation Rate (7 of 8) Pure inflation is proportional increase in all prices and wages.
This type of inflation causes only a minor inconvenience as relative prices are unaffected.
Real wage (wage measured by goods rather than dollars) would be unaffected.
There is no such thing as pure inflation.<br>
slide52. 2.3 The Inflation Rate (8 of 8) Why Do Economists Care about Inflation?
Inflation affects income distribution when not all prices and wages rise proportionally.
Inflation leads to distortions due to uncertainty, some prices that are fixed by law or by regulation, and its interaction with taxation (bracket creep in taxes).
Most economists believe the “best” rate of inflation to be a low and stable rate of inflation between 1 and 4%.<br>
slide53. 2.4 Output, Unemployment, and the Inflation Rate: Okun’s Law and the Phillips Curve (1 of 4) Figure 2.5 Changes in the Unemployment Rate versus Growth in the United States, 2000 Q1 to 2018 Q4 Output growth that is higher than usual is associated with a reduction in the unemployment rate.
Output growth that is lower than usual is associated with an increase in the unemployment rate. Source: FRED: Series G D P C, UNRATE.<br>
slide54. 2.4 Output, Unemployment, and the Inflation Rate: Okun’s Law and the Phillips Curve (2 of 4) Okun’s law is a relation first examined by U.S. economist Arthur Okun.
In Figure 2-5, the line that best fits the points is downward sloping.
The slope of the line is –0.3, which implies that, on average, an increase in the growth rate of 1% decreases the unemployment rate by –0.3%.
The line crosses the horizontal axis where output growth is 0.5%, meaning that it takes a growth rate of 2% to keep unemployment constant.<br>
slide55. 2.4 Output, Unemployment, and the Inflation Rate: Okun’s Law and the Phillips Curve (3 of 4) Figure 2.6 Changes in the Inflation Rate versus the Unemployment Rate in the United States, 2000 Q4 to 2018 Q4 A low unemployment rate leads to an increase in the inflation rate.
A high unemployment rate leads to a decrease in the inflation rate. Source: FRED: Series G D P C , CPILFESL.<br>
slide56. 2.4 Output, Unemployment, and the Inflation Rate: Okun’s Law and the Phillips Curve (4 of 4) The Phillips curve is a relation first explored in 1958 by New Zealand economist A.W. Phillips.
Figure 2-6 plots the change in the inflation rate against the unemployment rate, along with the line that best fits the points.
The line is downward sloping, meaning that higher unemployment leads, on average, to a decrease in inflation, and vice versa.
When unemployment has been above 5%, inflation has typically been above 2%.<br>
slide57. 2.5 The Short Run, the Medium Run, and the Long Run In the short run (e.g., a few years), year-to-year movements in output are primarily driven by movements in demand.
In the medium run (e.g., a decade), the economy tends to return to the level of output determined by supply factors, such as the capital stock, the level of technology, and the size of the labor force.
In the long run (e.g., a few decades or more), the economy depends on its ability to innovate and introduce new technologies, and how much people save, the quality of the country’s education system, the quality of the government, and so on.<br>
slide58. APPENDIX: The Construction of Real G D P and Chain-Type Indexes (1 of 3) Suppose that an economy produces two final goods, wine and potatoes: The rate of growth of nominal G D P from year 0 to year 1 is ($30 − $20)/$20 = 50%.<br>
slide59. APPENDIX: The Construction of Real G D P and Chain-Type Indexes (2 of 3) Suppose year 0 is the base year:
Real G D P in year 0: (10 x $1) + (5 x $2) = $20
Real G D P in year 1: (15 x $1) + (5 x $2) = $25
The rate of growth of real G D P from year 0 to year 1 is ($25 − $20)/$20 = 25%.
Suppose year 1 is the base year:
Real G D P in year 0: (10 x $1) + (5 x $3) = $25
Real G D P in year 1: (15 x $1) + (5 x $3) = $30
The rate of growth of real G D P from year 0 to year 1 is ($30 − $25)/$25 = 20%.
Problem: Which base year should one choose?<br>
slide60. APPENDIX: The Construction of Real G D P and Chain-Type Indexes (3 of 3) In December 1995, the U.S. Bureau of Economic Analysis shifted to a new method with four steps:
Construct the rate of change of real G D P between two years in two different ways: Using the price from year t as the set of common prices
Using the price from year t+1 as the set of common prices Construct the rate of change of real G D P as the average of these two rates of change
Construct an index of the level of real G D P by linking or chaining the constructed rates of change for each year
Multiply this index by nominal G D P to derive real G D P in chained dollars<br>
slide61. Macroeconomics Eighth Edition Chapter 3 The Goods Market Copyright © 2021, 2017, 2013 Pearson Education, Inc. All Rights Reserved Slide in this Presentation Contain Hyperlinks. JAWS users should be able to get a list of links by using INSERT+F7<br>
slide62. 3.1 The Composition of G D P (1 of 3) Consumption (C): goods and services purchased by consumers
Investment (I) or fixed investment: the sum of nonresidential investment and residential investment
Government spending (G): purchases of goods and services by the federal, state, and local governments; excluding government transfers<br>
slide63. 3.1 The Composition of G D P (2 of 3)<br>
slide64. 3.1 The Composition of G D P (3 of 3) Table 3.1 The Composition of U.S. G D P, 2018 Source: Survey of Current Business, February 2019, Table 1-1-5<br>
slide65. FOCUS: The Lehman Bankruptcy, Fears of Another Great Depression, and Shifts in the Consumption Function (1 of 3) When people start worrying about the future, they decide to save more even if their current income has not changed.
News about Lehman Brothers going bankrupt in September 2008 reminded people of the Great Depression, as confirmed by the number of searches for “Great Depression” in Google.
Consumption fell even if disposable income had not yet changed.<br>
slide66. FOCUS: The Lehman Bankruptcy, Fears of Another Great Depression, and Shifts in the Consumption Function (2 of 3) Figure 1 Disposable Income, Consumption, and Consumption of Durables in the United States, 2008:1 to 2009:3 Source: FRED: DPIC96, PCECC96, PCDG C C96.<br>
slide67. FOCUS: The Lehman Bankruptcy, Fears of Another Great Depression, and Shifts in the Consumption Function (3 of 3) Figure 2 Google Search Volume for “Great Depression,” January 2008 to September 2009 Source: Google Trends, “Great Depression.”<br>
slide68. 3.4 Investment Equals Saving: An Alternative Way of Thinking about Goods—Market Equilibrium (1 of 5) John Maynard Keynes articulated an alternative model that focuses instead on investment and saving in the General Theory of Employment, Interest and Money in 1936.
Private saving (S) is<br>
slide69. 3.4 Investment Equals Saving: An Alternative Way of Thinking about Goods—Market Equilibrium (2 of 5) In equilibrium: Subtract T from both sides and move C to the left side: The left side of the equation is simply S, so Or equivalently This is the I S relation, which stands for “Investment equals Saving”.<br>
slide70. 3.4 Investment Equals Saving: An Alternative Way of Thinking about Goods—Market Equilibrium (3 of 5) Two equivalent ways of stating the condition for equilibrium in the goods market: Production = Demand
Investment = Saving<br>
slide71. 3.5 Is the Government Omnipotent? A Warning Equation (3.8) implies that the government can choose the level of G or T to affect the level of output it wants.
However, there are many aspects of reality that we have not incorporated in our model:
Changing G or T is not easy.
Investment and imports may change, making it hard for governments to assess the effects of their policies (Chapters 5, 9, and 18 to 20).
Expectations are likely to matter (Chapters 14 to 16).
The effects on output may be unsustainable in the medium run (Chapter 9).
Cutting T or increasing G can lead to large budget deficits and public debt in the long run (Chapters 9, 11, 16 and 22).<br>
slide72. Macroeconomics Eighth Edition Chapter 4 Financial Markets Ⅰ Copyright © 2021, 2017, 2013 Pearson Education, Inc. All Rights Reserved<br>
slide73. Financial Markets Financial markets are intimidating, but they play an essential role in the economy.
In this chapter, we focus on the role of the central bank in affecting these interest rates.
We learn how the interest rate on bonds is determined, and the role of the central bank (Federal Reserve Bank, or the Fed, in the United States) in this determination.<br>
slide74. FOCUS: Semantic Traps: Money, Income, and Wealth Money is what can be used to pay for transactions.
Income is what you earn, and it is a flow.
Saving is the part of after-tax income that you do not spend, and it is also a flow.
Savings is the value of what you have accumulated over time.
Financial wealth, or wealth, is the value of all your financial assets minus all your financial liabilities, and it is a stock variable.
Investment is what economists refer to as the purchase of new capital goods.
Financial investment is the purchase of shares or other financial assets.<br>
slide75. 4.1 The Demand for Money (1 of 5) Suppose you only have a choice between two assets: money and bonds.
Money are used for transactions, but it pays no interest.
Two types of money: currency and checkable deposits.
Bonds pay a positive interest rate, i (the rate of interest), but cannot be used for transactions.<br>
slide76. 4.1 The Demand for Money (2 of 5) The holding of money and bonds depends on:
Your level of transactions
The interest rate on bonds
You can hold bonds indirectly through money market funds, or money market mutual funds.
In the early 1980s, the interest rate on money market funds reached 14% per year, so people earned more interest by moving their wealth from checking accounts to these funds.<br>
slide77. 4.1 The Demand for Money (3 of 5) Demand for money (Md) is equal to nominal income $Y (a measure of level of transactions in the economy) times a decreasing function of the interest rate i: An increase in the interest rate decreases the demand for money, as people put more of their wealth into bonds.<br>
slide78. 4.1 The Demand for Money (4 of 5) Equation (4.1) means that the demand for money:
increases in proportion to nominal income, and
depends negatively on the interest rate.
The relation between the demand for money and interest rate for a given level of income $Y is represented by the Md curve.<br>
slide79. 4.1 The Demand for Money (5 of 5) Figure 4.1 The Demand for Money For a given level of nominal income, a lower interest rate increases the demand for money.
At a given interest rate, an increase in nominal income shifts the demand for money to the right.<br>
slide80. FOCUS: Who Holds U.S. Currency The amount of currency in circulation in 2006 was $750 billion.
U.S. households together held $170 billion in currency.
U.S. firms held another $80 billion.
Foreigners abroad held $500 billion, or 66% of the total, for transactions, especially in countries suffering from high inflation in the past.<br>
slide81. 4.2 Determining the Interest Rate: Ⅰ (1 of 9) Suppose the central bank decides to supply an amount of money equal to M: Equilibrium in financial markets requires that Ms=Md=M:<br>
slide82. 4.2 Determining the Interest Rate: Ⅰ (2 of 9) Figure 4.2 The Determination of the Interest Rate The interest rate must be such that the supply of money (which is independent of the interest rate) is equal to the demand for money (which does depend on the interest rate).<br>
slide83. 4.2 Determining the Interest Rate: Ⅰ (3 of 9) Figure 4.3 The Effects of an Increase in the Money Supply on the Interest Rate An increase in the supply of money leads to a decrease in the interest rate.<br>
slide84. 4.2 Determining the Interest Rate: Ⅰ (4 of 9) Figure 4.4 The Effects of an Increase in Nominal Income on the Interest Rate Given the money supply, an increase in nominal income leads to an increase in the interest rate.<br>
slide85. 4.2 Determining the Interest Rate: Ⅰ (5 of 9) For a given money supply, an increase in nominal income leads to an increase in the interest rate.
An increase in the supply of money by the central bank leads to a decrease in the interest rate.<br>
slide86. 4.2 Determining the Interest Rate: Ⅰ (6 of 9) Central banks typically change the supply of money by buying or selling bonds in the bond market—open market operations.
Expansionary open market operation: the central bank expands the supply of money by buying bonds.
Contractionary open market operation: the central bank contracts the supply of money by selling bonds.<br>
slide87. 4.2 Determining the Interest Rate: Ⅰ (7 of 9) Figure 4.5 The Balance Sheet of the Central Bank and the Effects of an Expansionary Open Market Operation The assets of the central bank are the bonds it holds.
The liabilities are the stock of money in the economy.
An open market operation in which the central bank buys bonds and issues money increases both assets and liabilities by the same amount.<br>
slide88. 4.2 Determining the Interest Rate: Ⅰ (8 of 9) Suppose a bond such as a Treasury bill, or T-bill, promises to pay $100 a year from now.
If the price of the bond today is $P B, then the interest rate on the bond is: The higher the price of the bond, the lower the interest rate.
The higher the interest rate, the lower the price today.<br>
slide89. 4.2 Determining the Interest Rate: Ⅰ (9 of 9) Rather than the money supply, the central bank could have chosen the interest rate and then adjusted the money supply so as to achieve the interest rate it had chosen.
Choosing the interest rate, instead of the money supply, is what modern central banks, including the Fed, typically do.<br>
slide90. 4.3 Determining the Interest Rate: Ⅱ (1 of 6) Financial intermediaries: Institutions that receive funds from people and firms and use these funds to buy financial assets or to make loans to other people and firms.
Banks are financial intermediaries that have money, in the form of checkable deposits, as their liabilities.
Banks keep as reserves some of the funds they receive.
The liabilities of the central bank are the money it has issued, called central bank money.<br>
slide91. 4.3 Determining the Interest Rate: Ⅱ (2 of 6) Figure 4.6 The Balance Sheet of Banks, and the Balance Sheet of the Central Bank Revisited<br>
slide92. 4.3 Determining the Interest Rate: Ⅱ (3 of 6) Assume people hold no currency so the demand for money by people is the demand for checkable deposits: The demand for reserves by banks depends on the amount of checkable deposits: θ is the reserve ratio, and Hd is demand for high-power money or the monetary base.<br>
slide93. 4.3 Determining the Interest Rate: Ⅱ (4 of 6) Let H denote the supply of central bank money, then the equilibrium condition: Or using equation (4.4): An increase in H leads to a decrease in the interest rate, and a decrease in H leads to an increase in the interest rate.<br>
slide94. 4.3 Determining the Interest Rate: Ⅱ (5 of 6) Figure 4.7 Equilibrium in the Market for Central Bank Money and the Determination of the Interest Rate The equilibrium interest rate is such that the supply of central bank money is equal to the demand for central bank money.<br>
slide95. 4.3 Determining the Interest Rate: Ⅱ (6 of 6) The federal funds market is an actual market for bank reserves.
The federal funds rate is the interest rate determined in the federal funds market.
The federal funds rate is the main indicator of U.S. monetary policy because the Fed can choose the federal funds rate it wants by changing H.<br>
slide96. 4.4 The Liquidity Trap Figure 4.8 Money Demand, Money Supply, and the Liquidity Trap When the interest rate is equal to zero, and once people have enough money for transaction purposes, they become indifferent between holding money and holding bonds.
The demand for money becomes horizontal.
This implies that, when the interest rate is equal to zero, further increases in the money supply have no effect on the interest rate, which remains equal to zero. Zero lower bound: The interest rate cannot go below zero.
The economy is in a liquidity trap when the interest rate is down to zero, monetary policy cannot decrease it further.<br>
slide97. FOCUS: The Liquidity Trap in Action The large increase in the supply of central bank money between 2008 and 2015 was absorbed by households and banks. Figure 1 Checkable Deposits and Bank Reserves, 2005−2018 (billions). Source: FRED: TCP, WRESBAL<br>