Elements of cost And Classification MATERIAL DIRECT-SPECIALLY PURCHASED VISIBLE IN FINAL PRODUCT PRIMARY PACKING MATERIAL PARTS PURCHASED FOR PRODUCTS EXAMPLESWOOD IN FURNITURE CLOTH IN GARMENTS INDIRECT-NOT VISIBLE EXAMPLESADHESIVE IN
Related Topics
Share
Embed code
Download this presentation From Below
"Elements of cost And Classification MATERIAL" is the property of its rightful owner. Permission is granted to
download and print the materials on this website for personal, non-commercial use only, and to display it
on your personal computer provided you do not modify the materials and that you retain all copyright
notices contained in the materials. By downloading content from our website, you accept the terms of this
agreement.
Presentation Transcript
01
Elements of cost And Classification<br>
02
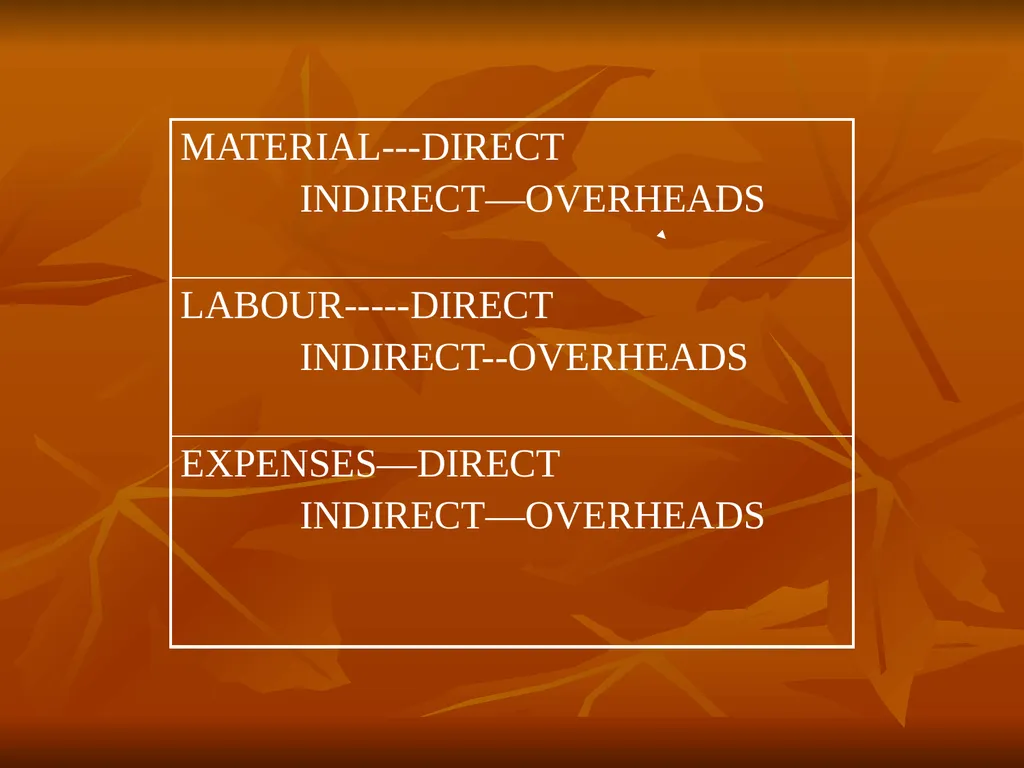
MATERIAL DIRECT-SPECIALLY PURCHASED
VISIBLE IN FINAL PRODUCT
PRIMARY PACKING MATERIAL
PARTS PURCHASED FOR PRODUCTS
EXAMPLES—WOOD IN FURNITURE
CLOTH IN GARMENTS
INDIRECT-NOT VISIBLE
EXAMPLES—ADHESIVE IN FURNITURE
GLUE IN BOOK BINDING<br>
03
LABOUR DIRECT-DIRECTLY INVOLVED IN PRODUCTION
LABOUR ENGAGED IN PRODUCTION
LABOUR IN TOOL SETTING OR REPAIRS
INDIRECT—NOT DIRECTLY INVOLVED
PROVIDING SERVICE TO LABOUR
EXAMPLES—WATCHMAN,ELECTRICIAN,SWEEPERS.<br>
04
EXPENSES DIRECT—EXPENSES DIRECTLY RELATED TO A PRODUCT
INDIRECT—COMMEN EXPENSES NOT RELATED TO A PARTICULAR JOB AND CAN BE APPORTIONED TO VARIOUS JOBS.<br>
05
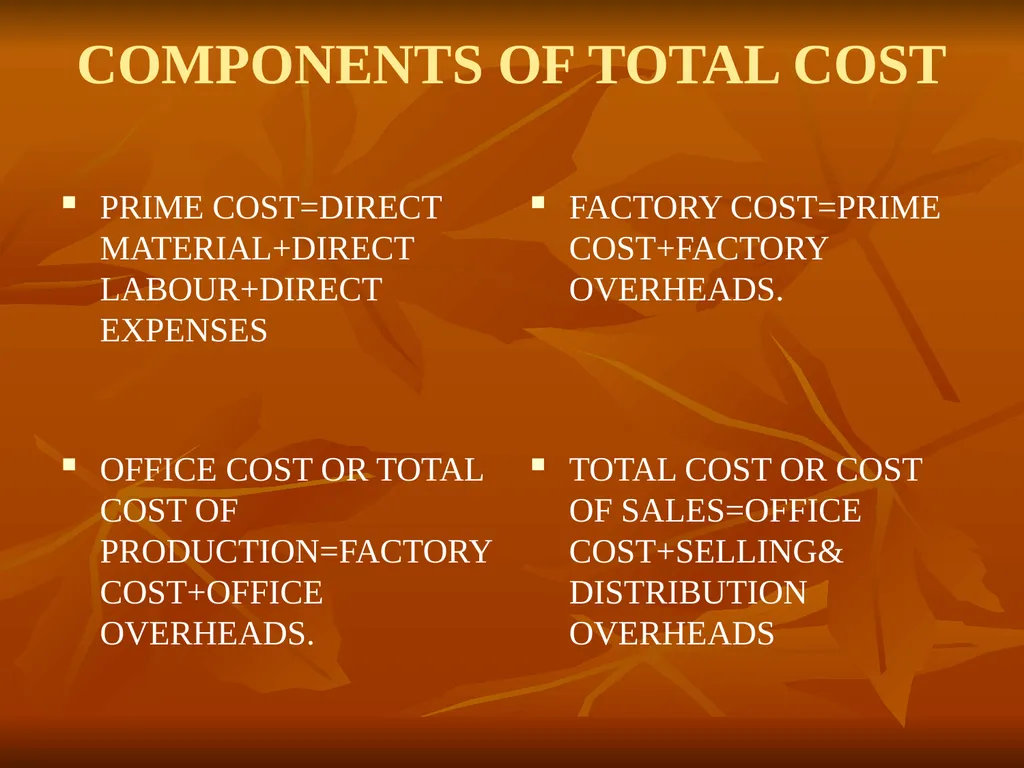
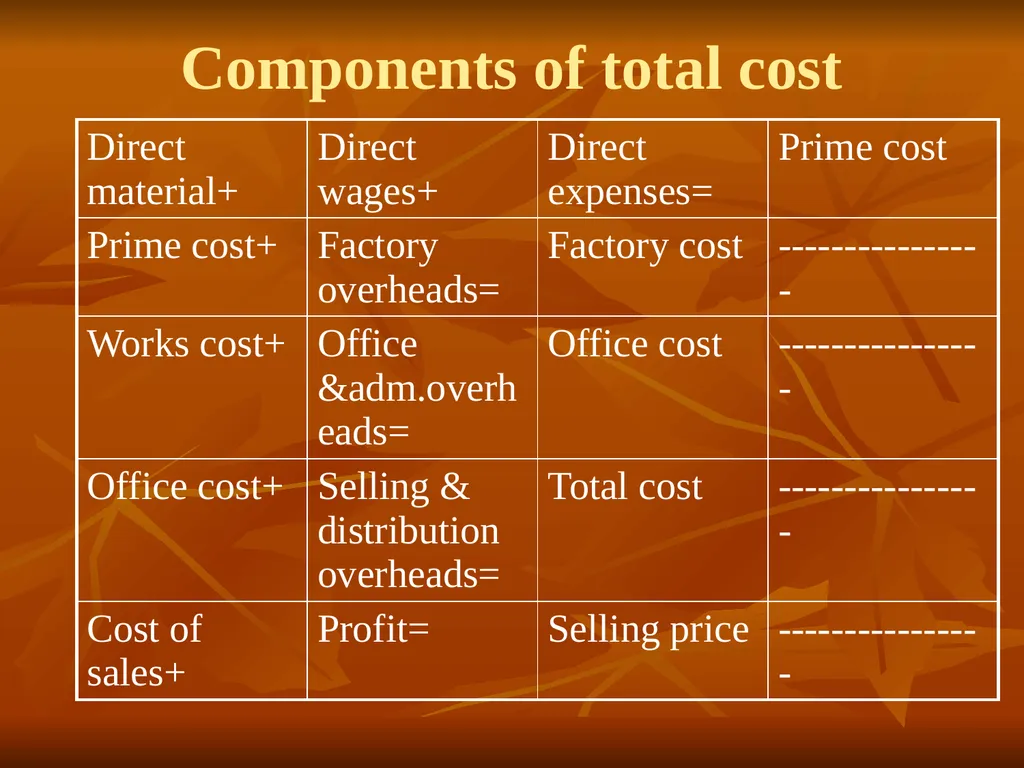
COMPONENTS OF TOTAL COST PRIME COST=DIRECT MATERIAL+DIRECT LABOUR+DIRECT EXPENSES FACTORY COST=PRIME COST+FACTORY OVERHEADS. OFFICE COST OR TOTAL COST OF PRODUCTION=FACTORY COST+OFFICE OVERHEADS. TOTAL COST OR COST OF SALES=OFFICE COST+SELLING& DISTRIBUTION OVERHEADS<br>
06
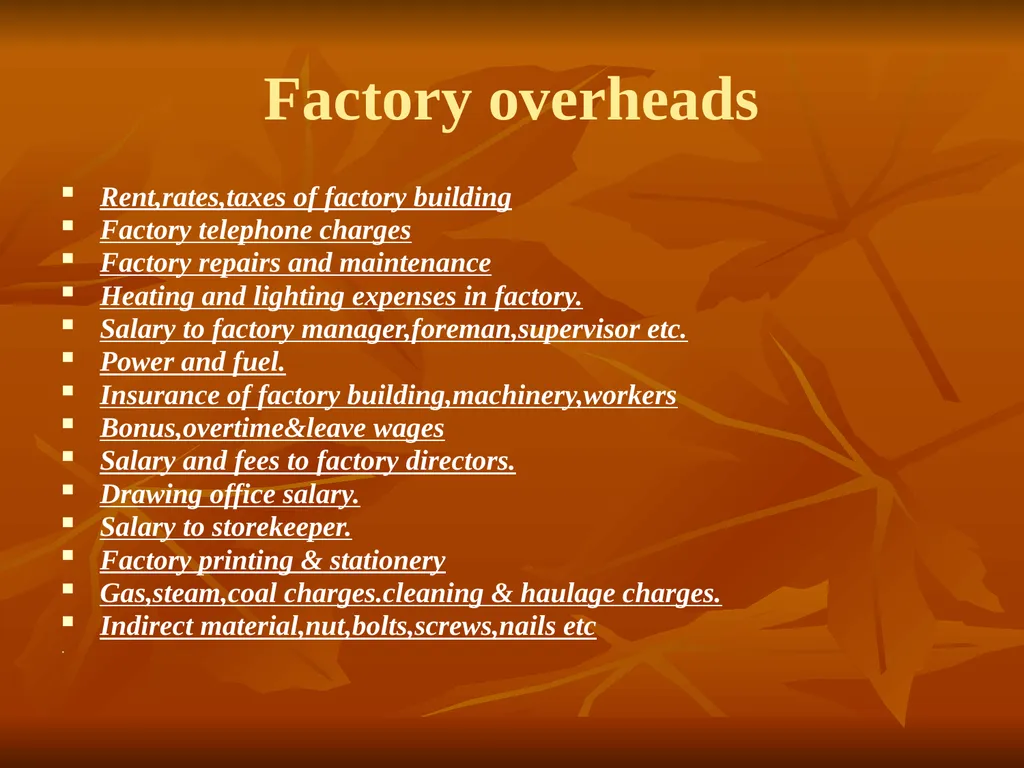
Factory overheads Rent,rates,taxes of factory building
Factory telephone charges
Factory repairs and maintenance
Heating and lighting expenses in factory.
Salary to factory manager,foreman,supervisor etc.
Power and fuel.
Insurance of factory building,machinery,workers
Bonus,overtime&leave wages
Salary and fees to factory directors.
Drawing office salary.
Salary to storekeeper.
Factory printing & stationery
Gas,steam,coal charges.cleaning & haulage charges.
Indirect material,nut,bolts,screws,nails etc
.<br>
07
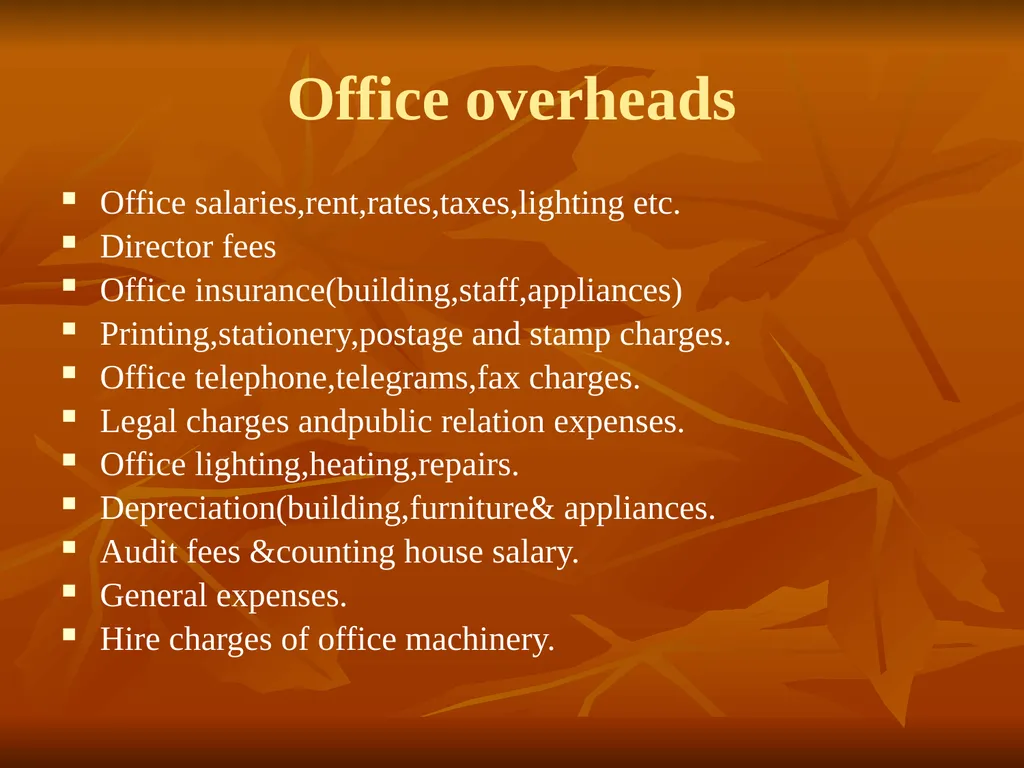
Office overheads Office salaries,rent,rates,taxes,lighting etc.
Director fees
Office insurance(building,staff,appliances)
Printing,stationery,postage and stamp charges.
Office telephone,telegrams,fax charges.
Legal charges andpublic relation expenses.
Office lighting,heating,repairs.
Depreciation(building,furniture& appliances.
Audit fees &counting house salary.
General expenses.
Hire charges of office machinery.<br>
08
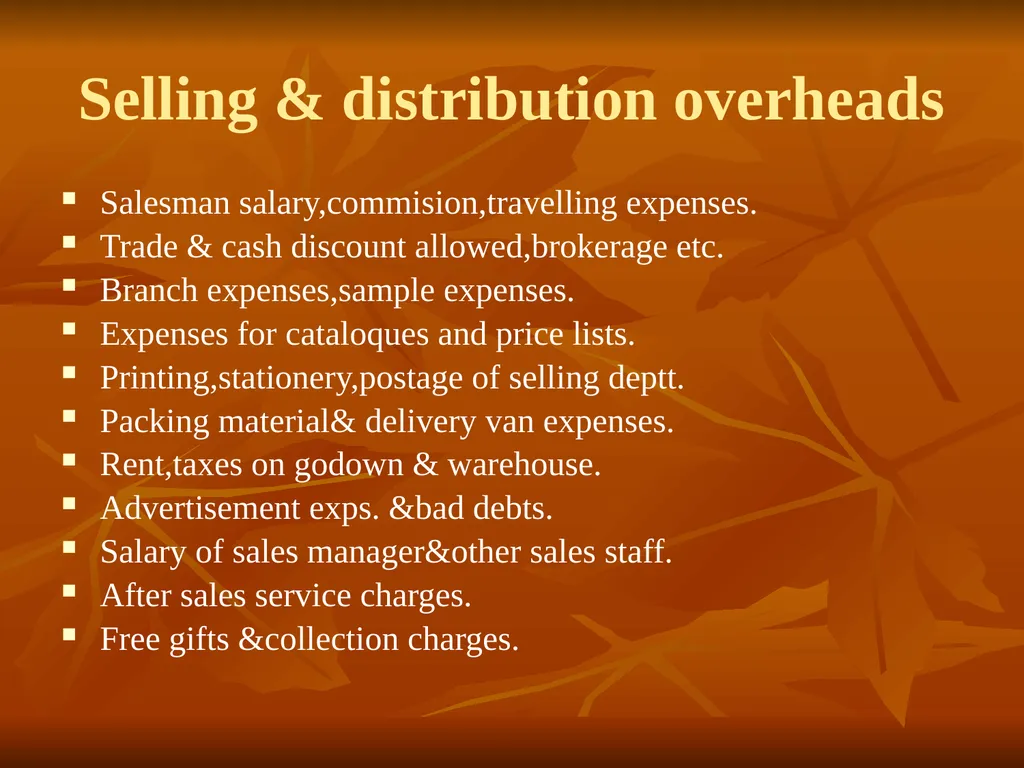
Selling & distribution overheads Salesman salary,commision,travelling expenses.
Trade & cash discount allowed,brokerage etc.
Branch expenses,sample expenses.
Expenses for cataloques and price lists.
Printing,stationery,postage of selling deptt.
Packing material& delivery van expenses.
Rent,taxes on godown & warehouse.
Advertisement exps. &bad debts.
Salary of sales manager&other sales staff.
After sales service charges.
Free gifts &collection charges.<br>
09
Components of total cost<br>
10
Classification of cost According to elements-material,labour &expenses.
According to functions-manufacturing,administrative,selling &distribution, & research &devlpt.
According to controllability-controllable,& uncontrollable.
According to normality- normal & abnormal.<br>
11
According to behaviour or variability<br>
12
According to behaviour or variability Fixed cost----------costs which remain same at every level of output.these cost are related to time and not to production.
Variable cost-------costs which increase in volume with increase in volume of production.the per unit cost remains constant at every level of output.
Semi – variable cost—these are fixed as well as variable. Upto a particular level these costs are fixed but once the level is crossed even slightly these costs shift to the next higher level and so on.<br>
13
Cost center-a smallest segment of activity or area or responsibility for which costs are accumulated.
Profit center-a center whose performance is measured both in terms of expenses incurred and revenues earned by it.
----------------//////////////////////--------------------- Cost center & profit center<br>