
Federal Chamber of Automotive Industries The



Description: Federal Chamber of Automotive Industries The Australian automotive industry and a changing competitive environment December 2011 Disclaimer This report has been prepared by PwC at the request of the Federal Chamber of Automotive Industries
Related Topics
Download Presentation
"Federal Chamber of Automotive Industries The" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Federal Chamber of Automotive Industries The Australian automotive industry and a changing competitive environment December 2011<br>
slide2. Disclaimer This report has been prepared by PwC at the request of the Federal Chamber of Automotive Industries (FCAI), according to the terms of our Engagement Contract with FCAI.
The information, statements, statistics and commentary (together the “Information”) contained in this report have been prepared by PwC from publically available sources. PwC does not express an opinion as to the accuracy or completeness of the information, the assumptions made by the parties that provided the information or any conclusions reached by those parties. PwC may at its absolute discretion, but without being under any obligation to do so, update, amend or supplement this document. PwC disclaims any and all liability arising from actions taken in response to this report. PwC disclaims any and all liability for any investment or strategic decisions made as a consequence of information contained in this report. PwC, its employees and any persons associated with the preparation of the enclosed documents are in no way responsible for any errors or omissions in the enclosed document resulting from any inaccuracy, mis-description or incompleteness of the information provided or from assumptions made or opinions reached by the parties that provided Information.
"PwC" refers to the network of member firms of PricewaterhouseCoopers International Limited (PwCIL), or, as the context requires, individual member firms of the PwC network. Each member firm is a separate legal entity and does not act as agent of PwCIL or any other member firm. PwCIL does not provide any services to clients. PwCIL is not responsible or liable for the acts or omissions of any of its member firms nor can it control the exercise of their professional judgment or bind them in any way. No member firm is responsible or liable for the acts or omissions of any other member firm nor can it control the exercise of another member firm's professional judgment or bind another member firm or PwCIL in any way.
Liability is limited by a Scheme approved under Professional Standards Legislation. Draft<br>
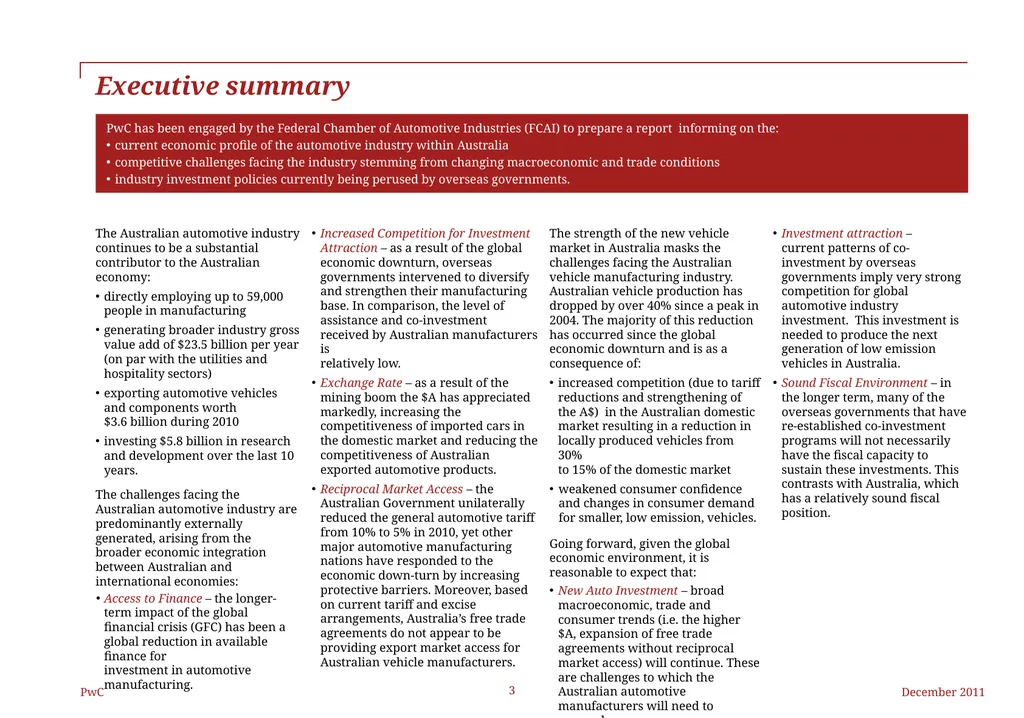
slide3. Executive summary PwC has been engaged by the Federal Chamber of Automotive Industries (FCAI) to prepare a report informing on the:
current economic profile of the automotive industry within Australia
competitive challenges facing the industry stemming from changing macroeconomic and trade conditions
industry investment policies currently being perused by overseas governments. Investment attraction – current patterns of co-investment by overseas governments imply very strong competition for global automotive industry investment. This investment is needed to produce the next generation of low emission vehicles in Australia.
Sound Fiscal Environment – in the longer term, many of the overseas governments that have re-established co-investment programs will not necessarily have the fiscal capacity to sustain these investments. This contrasts with Australia, which has a relatively sound fiscal position. – Increased Competition for Investment Attraction – as a result of the global economic downturn, overseas governments intervened to diversify and strengthen their manufacturing base. In comparison, the level of assistance and co-investment received by Australian manufacturers is relatively low.
Exchange Rate – as a result of the mining boom the $A has appreciated markedly, increasing the competitiveness of imported cars in the domestic market and reducing the competitiveness of Australian exported automotive products.
Reciprocal Market Access – the Australian Government unilaterally reduced the general automotive tariff from 10% to 5% in 2010, yet other major automotive manufacturing nations have responded to the economic down-turn by increasing protective barriers. Moreover, based on current tariff and excise arrangements, Australia’s free trade agreements do not appear to be providing export market access for Australian vehicle manufacturers. The Australian automotive industry continues to be a substantial contributor to the Australian economy:
directly employing up to 59,000 people in manufacturing
generating broader industry gross value add of $23.5 billion per year (on par with the utilities and hospitality sectors)
exporting automotive vehicles and components worth $3.6 billion during 2010
investing $5.8 billion in research and development over the last 10 years.
The challenges facing the Australian automotive industry are predominantly externally generated, arising from the broader economic integration between Australian and international economies:
Access to Finance – the longer-term impact of the global financial crisis (GFC) has been a global reduction in available finance for investment in automotive manufacturing. The strength of the new vehicle market in Australia masks the challenges facing the Australian vehicle manufacturing industry. Australian vehicle production has dropped by over 40% since a peak in 2004. The majority of this reduction has occurred since the global economic downturn and is as a consequence of:
increased competition (due to tariff reductions and strengthening of the A$) in the Australian domestic market resulting in a reduction in locally produced vehicles from 30% to 15% of the domestic market
weakened consumer confidence and changes in consumer demand for smaller, low emission, vehicles.
Going forward, given the global economic environment, it is reasonable to expect that:
New Auto Investment – broad macroeconomic, trade and consumer trends (i.e. the higher $A, expansion of free trade agreements without reciprocal market access) will continue. These are challenges to which the Australian automotive manufacturers will need to respond with new investment and increased productivity.<br>
slide4. Table of contents – Industry profile 5
Macroeconomic trends 11
Government support 15
Industry outlook 24<br>
slide5. Industry profile: Role in the economy Automotive manufacturing provides significant economic benefits in terms of employment, value adding, R&D and exporting. The industry is the largest contributor to manufacturing output, employment and R&D.
The automotive industry provides employment for high-value design and engineering skills and builds capability in Australia that has spillover benefits for other industry sectors.
The industry also requires a large and stable workforce that can be located around major employment centres.<br>
slide6. Economic output The Global Financial Crisis (GFC) in 2008 re-intensified the debate around the importance of a diversified economy underpinned by a strong manufacturing base.
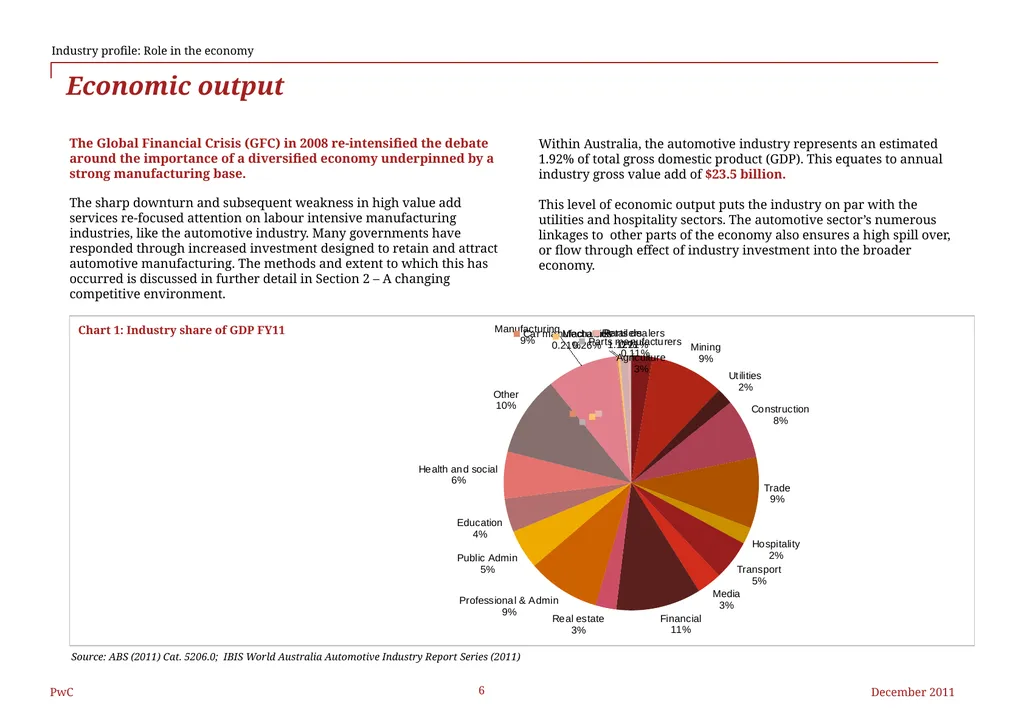
The sharp downturn and subsequent weakness in high value add services re-focused attention on labour intensive manufacturing industries, like the automotive industry. Many governments have responded through increased investment designed to retain and attract automotive manufacturing. The methods and extent to which this has occurred is discussed in further detail in Section 2 – A changing competitive environment. Industry profile: Role in the economy Within Australia, the automotive industry represents an estimated 1.92% of total gross domestic product (GDP). This equates to annual industry gross value add of $23.5 billion.
This level of economic output puts the industry on par with the utilities and hospitality sectors. The automotive sector’s numerous linkages to other parts of the economy also ensures a high spill over, or flow through effect of industry investment into the broader economy. Source: ABS (2011) Cat. 5206.0; IBIS World Australia Automotive Industry Report Series (2011) Chart 1: Industry share of GDP FY11<br>
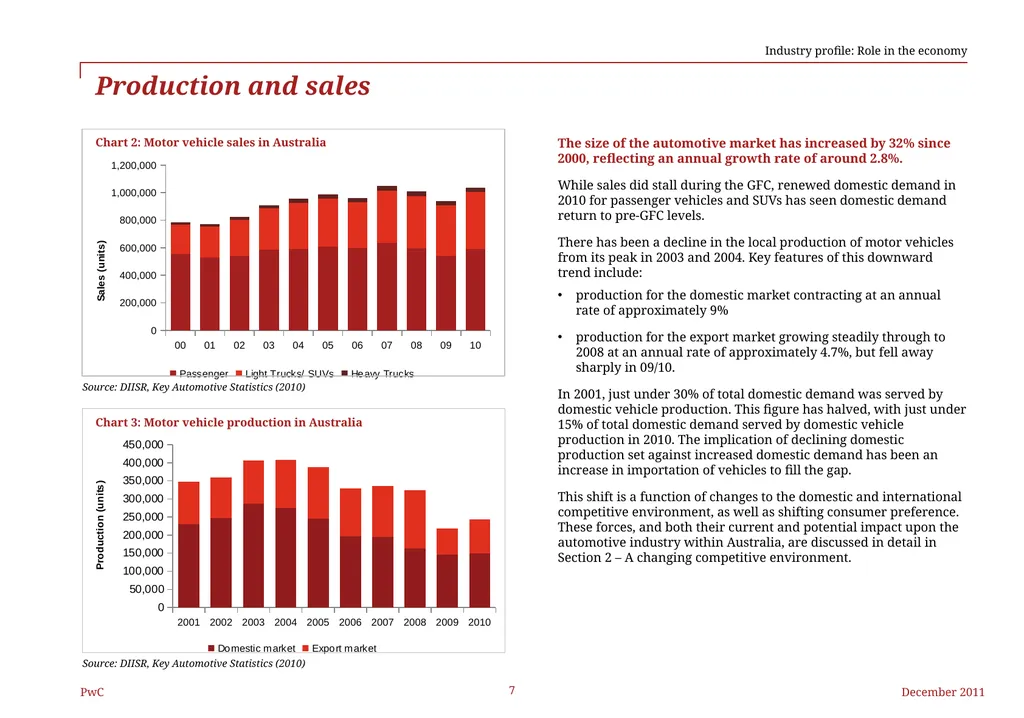
slide7. Production and sales The size of the automotive market has increased by 32% since 2000, reflecting an annual growth rate of around 2.8%.
While sales did stall during the GFC, renewed domestic demand in 2010 for passenger vehicles and SUVs has seen domestic demand return to pre-GFC levels.
There has been a decline in the local production of motor vehicles from its peak in 2003 and 2004. Key features of this downward trend include:
production for the domestic market contracting at an annual rate of approximately 9%
production for the export market growing steadily through to 2008 at an annual rate of approximately 4.7%, but fell away sharply in 09/10.
In 2001, just under 30% of total domestic demand was served by domestic vehicle production. This figure has halved, with just under 15% of total domestic demand served by domestic vehicle production in 2010. The implication of declining domestic production set against increased domestic demand has been an increase in importation of vehicles to fill the gap.
This shift is a function of changes to the domestic and international competitive environment, as well as shifting consumer preference. These forces, and both their current and potential impact upon the automotive industry within Australia, are discussed in detail in Section 2 – A changing competitive environment. Industry profile: Role in the economy Chart 2: Motor vehicle sales in Australia Source: DIISR, Key Automotive Statistics (2010) Chart 3: Motor vehicle production in Australia Source: DIISR, Key Automotive Statistics (2010)<br>
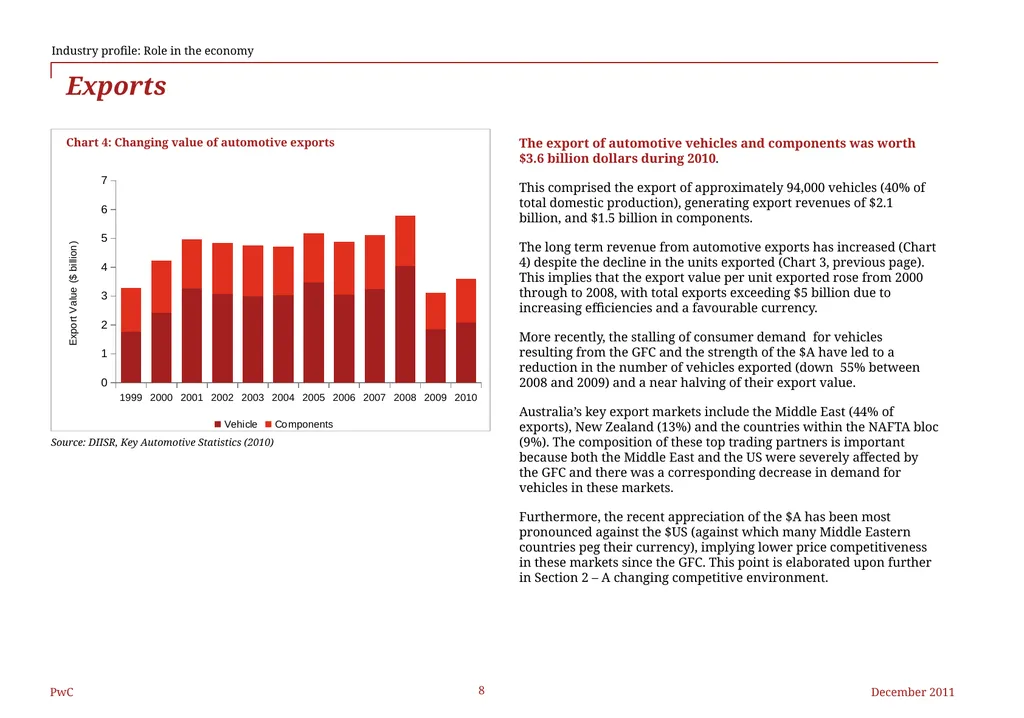
slide8. Exports The export of automotive vehicles and components was worth $3.6 billion dollars during 2010.
This comprised the export of approximately 94,000 vehicles (40% of total domestic production), generating export revenues of $2.1 billion, and $1.5 billion in components.
The long term revenue from automotive exports has increased (Chart 4) despite the decline in the units exported (Chart 3, previous page). This implies that the export value per unit exported rose from 2000 through to 2008, with total exports exceeding $5 billion due to increasing efficiencies and a favourable currency.
More recently, the stalling of consumer demand for vehicles resulting from the GFC and the strength of the $A have led to a reduction in the number of vehicles exported (down 55% between 2008 and 2009) and a near halving of their export value.
Australia’s key export markets include the Middle East (44% of exports), New Zealand (13%) and the countries within the NAFTA bloc (9%). The composition of these top trading partners is important because both the Middle East and the US were severely affected by the GFC and there was a corresponding decrease in demand for vehicles in these markets.
Furthermore, the recent appreciation of the $A has been most pronounced against the $US (against which many Middle Eastern countries peg their currency), implying lower price competitiveness in these markets since the GFC. This point is elaborated upon further in Section 2 – A changing competitive environment. Source: DIISR, Key Automotive Statistics (2010) Industry profile: Role in the economy Chart 4: Changing value of automotive exports<br>
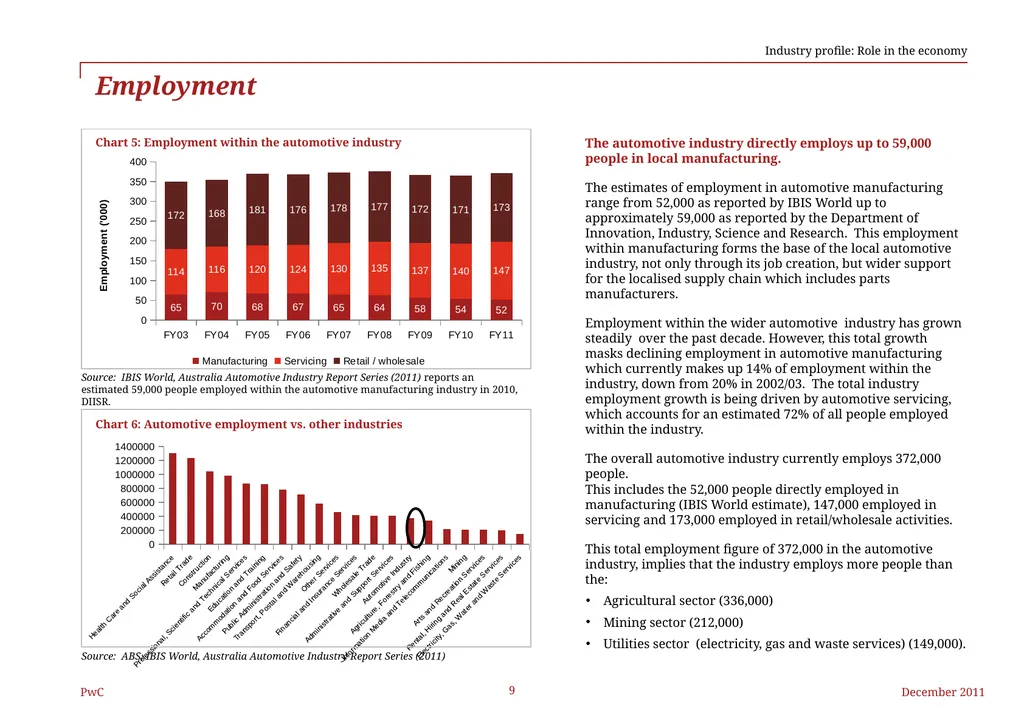
slide9. Employment Chart 5: Employment within the automotive industry The automotive industry directly employs up to 59,000 people in local manufacturing.
The estimates of employment in automotive manufacturing range from 52,000 as reported by IBIS World up to approximately 59,000 as reported by the Department of Innovation, Industry, Science and Research. This employment within manufacturing forms the base of the local automotive industry, not only through its job creation, but wider support for the localised supply chain which includes parts manufacturers.
Employment within the wider automotive industry has grown steadily over the past decade. However, this total growth masks declining employment in automotive manufacturing which currently makes up 14% of employment within the industry, down from 20% in 2002/03. The total industry employment growth is being driven by automotive servicing, which accounts for an estimated 72% of all people employed within the industry.
The overall automotive industry currently employs 372,000 people. This includes the 52,000 people directly employed in manufacturing (IBIS World estimate), 147,000 employed in servicing and 173,000 employed in retail/wholesale activities.
This total employment figure of 372,000 in the automotive industry, implies that the industry employs more people than the:
Agricultural sector (336,000)
Mining sector (212,000)
Utilities sector (electricity, gas and waste services) (149,000). Chart 6: Automotive employment vs. other industries Source: IBIS World, Australia Automotive Industry Report Series (2011) reports an estimated 59,000 people employed within the automotive manufacturing industry in 2010, DIISR. Source: ABS, IBIS World, Australia Automotive Industry Report Series (2011) Industry profile: Role in the economy<br>
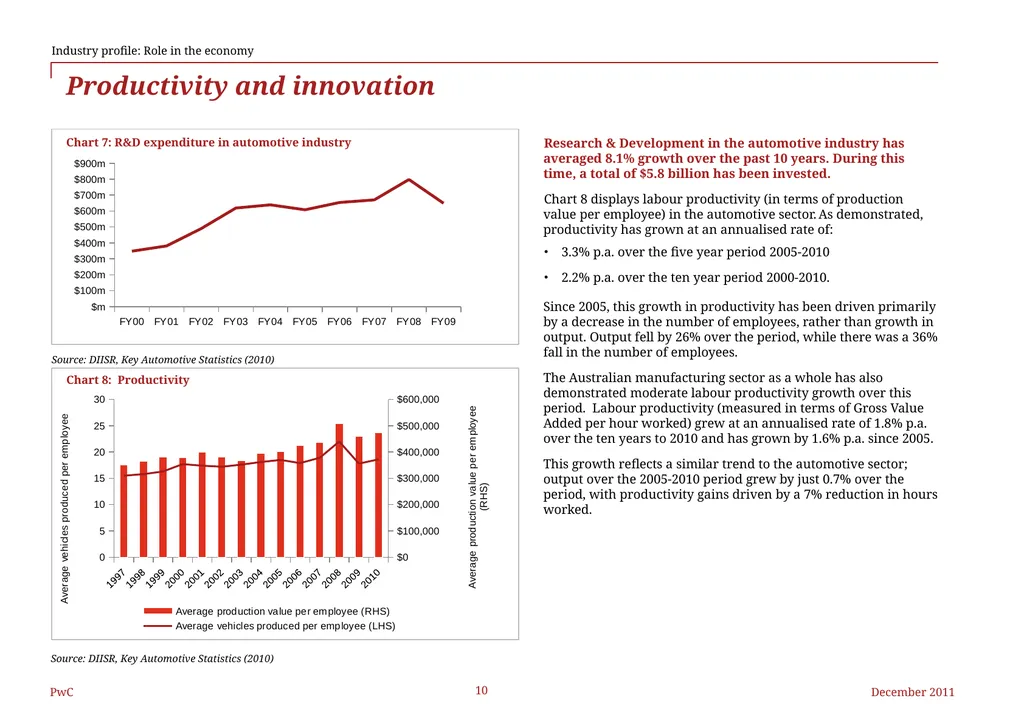
slide10. Productivity and innovation Chart 7: R&D expenditure in automotive industry Research & Development in the automotive industry has averaged 8.1% growth over the past 10 years. During this time, a total of $5.8 billion has been invested.
Chart 8 displays labour productivity (in terms of production value per employee) in the automotive sector. As demonstrated, productivity has grown at an annualised rate of:
3.3% p.a. over the five year period 2005-2010
2.2% p.a. over the ten year period 2000-2010.
Since 2005, this growth in productivity has been driven primarily by a decrease in the number of employees, rather than growth in output. Output fell by 26% over the period, while there was a 36% fall in the number of employees.
The Australian manufacturing sector as a whole has also demonstrated moderate labour productivity growth over this period. Labour productivity (measured in terms of Gross Value Added per hour worked) grew at an annualised rate of 1.8% p.a. over the ten years to 2010 and has grown by 1.6% p.a. since 2005.
This growth reflects a similar trend to the automotive sector; output over the 2005-2010 period grew by just 0.7% over the period, with productivity gains driven by a 7% reduction in hours worked. Source: DIISR, Key Automotive Statistics (2010) Source: DIISR, Key Automotive Statistics (2010) Chart 8: Productivity Industry profile: Role in the economy<br>
slide11. Macroeconomic trends<br>
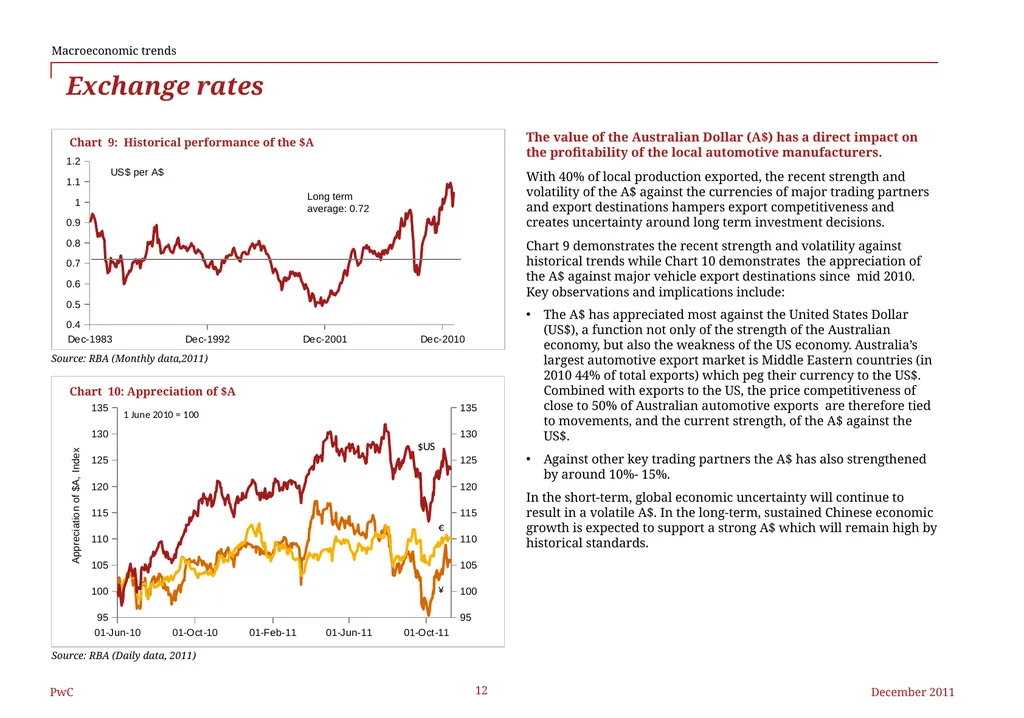
slide12. Exchange rates Chart 9: Historical performance of the $A The value of the Australian Dollar (A$) has a direct impact on the profitability of the local automotive manufacturers.
With 40% of local production exported, the recent strength and volatility of the A$ against the currencies of major trading partners and export destinations hampers export competitiveness and creates uncertainty around long term investment decisions.
Chart 9 demonstrates the recent strength and volatility against historical trends while Chart 10 demonstrates the appreciation of the A$ against major vehicle export destinations since mid 2010. Key observations and implications include:
The A$ has appreciated most against the United States Dollar (US$), a function not only of the strength of the Australian economy, but also the weakness of the US economy. Australia’s largest automotive export market is Middle Eastern countries (in 2010 44% of total exports) which peg their currency to the US$. Combined with exports to the US, the price competitiveness of close to 50% of Australian automotive exports are therefore tied to movements, and the current strength, of the A$ against the US$.
Against other key trading partners the A$ has also strengthened by around 10%- 15%.
In the short-term, global economic uncertainty will continue to result in a volatile A$. In the long-term, sustained Chinese economic growth is expected to support a strong A$ which will remain high by historical standards. Chart 10: Appreciation of $A Source: RBA (Daily data, 2011) Source: RBA (Monthly data,2011) Long term average: 0.72 Macroeconomic trends<br>
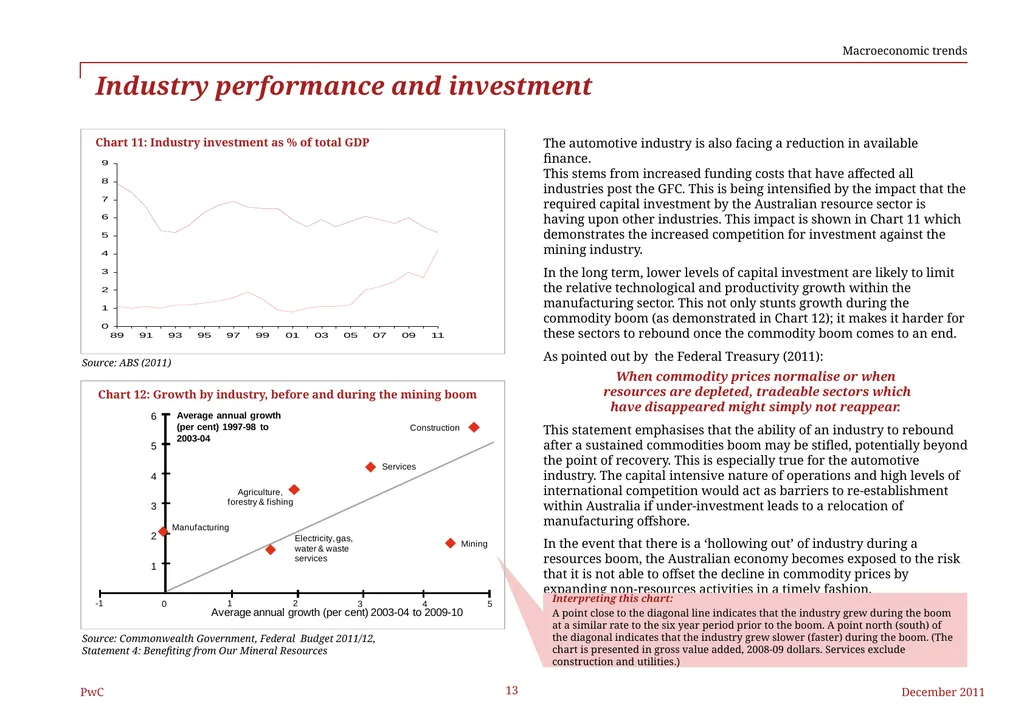
slide13. Industry performance and investment Chart 11: Industry investment as % of total GDP The automotive industry is also facing a reduction in available finance. This stems from increased funding costs that have affected all industries post the GFC. This is being intensified by the impact that the required capital investment by the Australian resource sector is having upon other industries. This impact is shown in Chart 11 which demonstrates the increased competition for investment against the mining industry.
In the long term, lower levels of capital investment are likely to limit the relative technological and productivity growth within the manufacturing sector. This not only stunts growth during the commodity boom (as demonstrated in Chart 12); it makes it harder for these sectors to rebound once the commodity boom comes to an end.
As pointed out by the Federal Treasury (2011):
When commodity prices normalise or when resources are depleted, tradeable sectors which have disappeared might simply not reappear.
This statement emphasises that the ability of an industry to rebound after a sustained commodities boom may be stifled, potentially beyond the point of recovery. This is especially true for the automotive industry. The capital intensive nature of operations and high levels of international competition would act as barriers to re-establishment within Australia if under-investment leads to a relocation of manufacturing offshore.
In the event that there is a ‘hollowing out’ of industry during a resources boom, the Australian economy becomes exposed to the risk that it is not able to offset the decline in commodity prices by expanding non-resources activities in a timely fashion. Chart 12: Growth by industry, before and during the mining boom Source: ABS (2011) Source: Commonwealth Government, Federal Budget 2011/12, Statement 4: Benefiting from Our Mineral Resources Interpreting this chart:
A point close to the diagonal line indicates that the industry grew during the boom at a similar rate to the six year period prior to the boom. A point north (south) of the diagonal indicates that the industry grew slower (faster) during the boom. (The chart is presented in gross value added, 2008-09 dollars. Services exclude construction and utilities.) Macroeconomic trends<br>
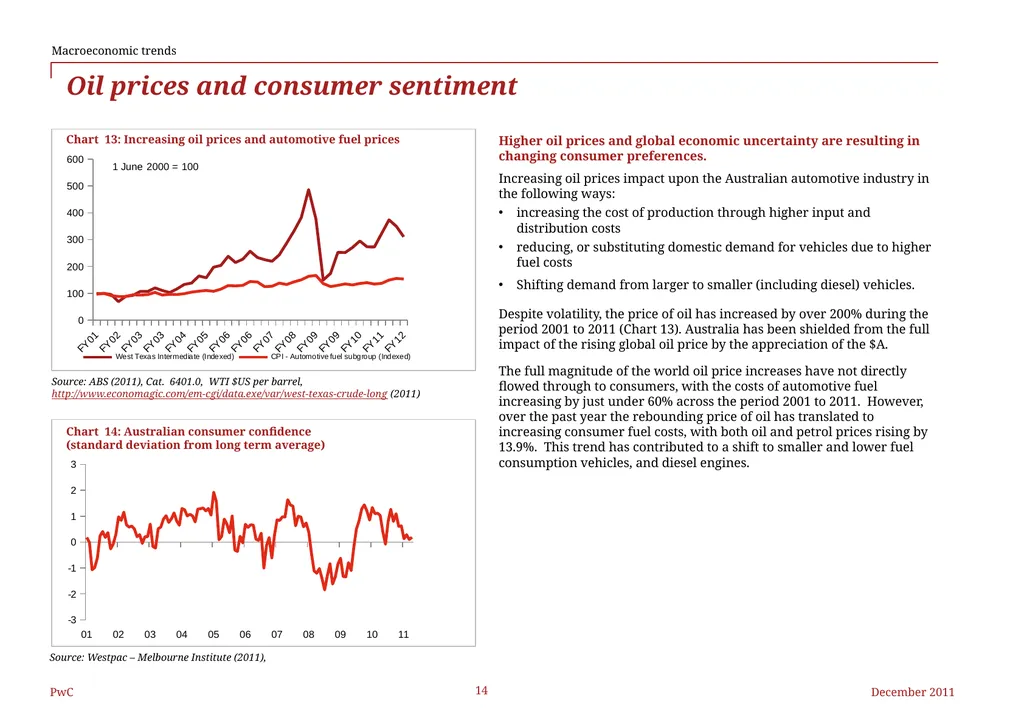
slide14. Chart 13: Increasing oil prices and automotive fuel prices Higher oil prices and global economic uncertainty are resulting in changing consumer preferences.
Increasing oil prices impact upon the Australian automotive industry in the following ways:
increasing the cost of production through higher input and distribution costs
reducing, or substituting domestic demand for vehicles due to higher fuel costs
Shifting demand from larger to smaller (including diesel) vehicles.
Despite volatility, the price of oil has increased by over 200% during the period 2001 to 2011 (Chart 13). Australia has been shielded from the full impact of the rising global oil price by the appreciation of the $A.
The full magnitude of the world oil price increases have not directly flowed through to consumers, with the costs of automotive fuel increasing by just under 60% across the period 2001 to 2011. However, over the past year the rebounding price of oil has translated to increasing consumer fuel costs, with both oil and petrol prices rising by 13.9%. This trend has contributed to a shift to smaller and lower fuel consumption vehicles, and diesel engines. Oil prices and consumer sentiment Source: ABS (2011), Cat. 6401.0, WTI $US per barrel, http://www.economagic.com/em-cgi/data.exe/var/west-texas-crude-long (2011) Chart 14: Australian consumer confidence (standard deviation from long term average) Source: Westpac – Melbourne Institute (2011), Macroeconomic trends<br>
slide15. Government support “Governments are increasingly trying to influence conditions in the job-intensive automotive industry, using mechanisms such as loans, incentives and premiums. At the same time, protectionism is growing. Seventeen of the G20 countries have introduced protectionist measures since the financial crisis 2008/2009, distorting global trade in goods by an estimated USD 50 billion per year.” Roland Berger (2011) Around the world, Governments have responded to decreasing access to finance and deteriorating market conditions by focusing on investment attraction, or co-investment. Co-investment can take the form of funding, grants, partnership arrangements or incentives designed to attract the investment required for the design and production of the next generation of vehicles and strengthen the ability of the local industry to compete both domestically and globally. Competition between countries to attract this investment is significant.
These policies can be viewed as a response by governments to (re)diversify and strengthen their manufacturing base in the face of weakening high value add services industries such as finance and insurance.
Concurrent to co-investment policies are tariff barriers and free trade agreements (FTAs) which shape the international trade environment. Within Australia, the retail market for cars is one of the most open and competitive in the world.
This has been driven by the Australian Government’s unilateral reduction applied to general automotive tariff from 10% to 5% in 2010. Yet other major automotive manufacturing nations have responded to the economic down-turn by increasing protective barriers. Moreover, Australia’s free trade agreements do not appear to be providing reciprocal market access for Australian vehicle manufacturers.<br>
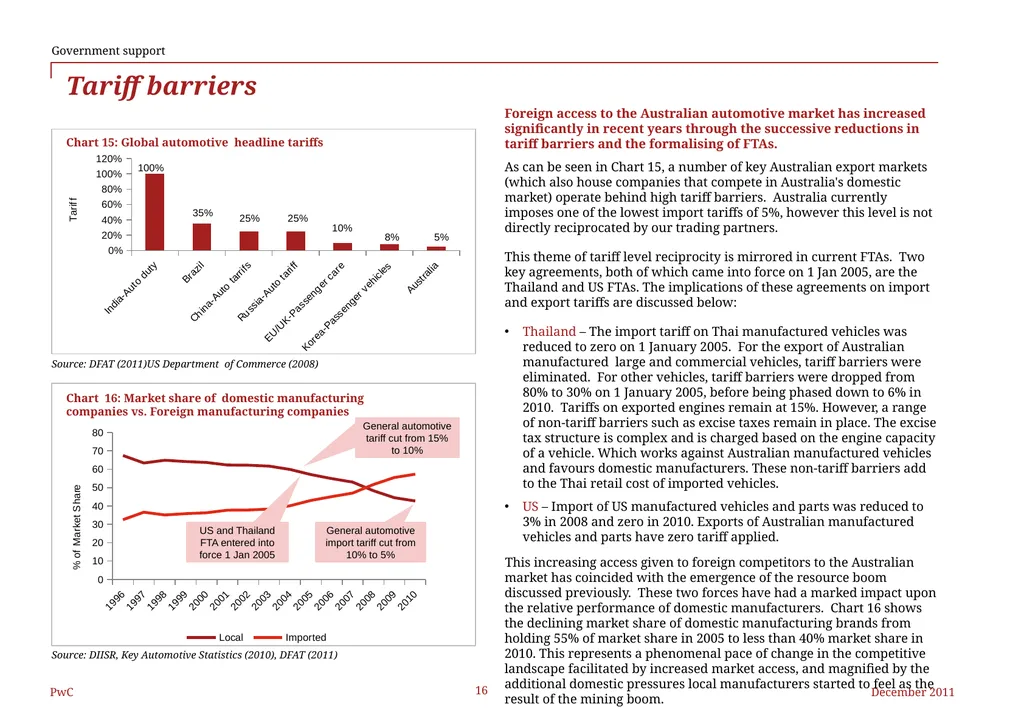
slide16. Tariff barriers Chart 15: Global automotive headline tariffs Foreign access to the Australian automotive market has increased significantly in recent years through the successive reductions in tariff barriers and the formalising of FTAs.
As can be seen in Chart 15, a number of key Australian export markets (which also house companies that compete in Australia's domestic market) operate behind high tariff barriers. Australia currently imposes one of the lowest import tariffs of 5%, however this level is not directly reciprocated by our trading partners.
This theme of tariff level reciprocity is mirrored in current FTAs. Two key agreements, both of which came into force on 1 Jan 2005, are the Thailand and US FTAs. The implications of these agreements on import and export tariffs are discussed below:
Thailand – The import tariff on Thai manufactured vehicles was reduced to zero on 1 January 2005. For the export of Australian manufactured large and commercial vehicles, tariff barriers were eliminated. For other vehicles, tariff barriers were dropped from 80% to 30% on 1 January 2005, before being phased down to 6% in 2010. Tariffs on exported engines remain at 15%. However, a range of non-tariff barriers such as excise taxes remain in place. The excise tax structure is complex and is charged based on the engine capacity of a vehicle. Which works against Australian manufactured vehicles and favours domestic manufacturers. These non-tariff barriers add to the Thai retail cost of imported vehicles.
US – Import of US manufactured vehicles and parts was reduced to 3% in 2008 and zero in 2010. Exports of Australian manufactured vehicles and parts have zero tariff applied.
This increasing access given to foreign competitors to the Australian market has coincided with the emergence of the resource boom discussed previously. These two forces have had a marked impact upon the relative performance of domestic manufacturers. Chart 16 shows the declining market share of domestic manufacturing brands from holding 55% of market share in 2005 to less than 40% market share in 2010. This represents a phenomenal pace of change in the competitive landscape facilitated by increased market access, and magnified by the additional domestic pressures local manufacturers started to feel as the result of the mining boom. Source: DFAT (2011)US Department of Commerce (2008) Chart 16: Market share of domestic manufacturing companies vs. Foreign manufacturing companies Source: DIISR, Key Automotive Statistics (2010), DFAT (2011) General automotive tariff cut from 15% to 10% Government support US and Thailand FTA entered into force 1 Jan 2005 General automotive import tariff cut from 10% to 5%<br>
slide17. Government investment attraction policies The focus of overseas Governments on co-investment policies has resulted in intense competition, from both countries and smaller jurisdictions within these countries, to attract and retain investment in automotive design and manufacturing.
Following the GFC, intervention in the market by overseas governments has increasingly taken the form of investment attraction (or co-investment) policies.
This can be viewed as a response by governments to (re)diversify and strengthen their manufacturing base in the face of weakening high value added services industries such as finance and insurance. The protection or attraction of automotive vehicle design and manufacturing has been seen by governments to not only secure or directly stimulate employment growth, but also secure the employment and value added associated with the supply chain that accompanies these industries.
The following case studies highlight:
the varied nature of investment attraction policies adopted by governments around the world and the benefits these provide to automotive manufacturers
the outcomes of these policies to governments in terms of retaining and attracting both foreign and domestic investment
the often opaque nature of the policies.
The implication of these policies is intense competition, from both countries and smaller jurisdictions within these countries, to attract and retain investment in automotive design and manufacturing. These government policies recognise the value, in terms of jobs and economic output, to the local economy. They also provide a competitive advantage to companies based in overseas markets: companies against which local manufacturers not only compete against in export markets, but also increasingly compete against in the domestic market. Government support * Full case study sources provided on pages 26-27<br>
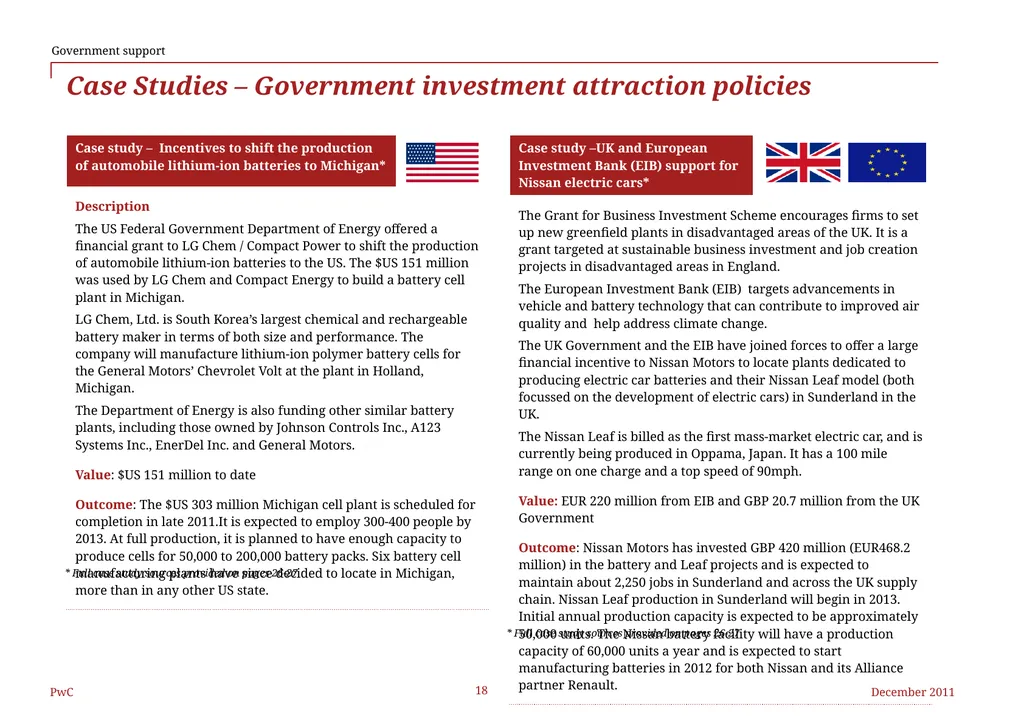
slide18. Case Studies – Government investment attraction policies Government support * Full case study sources provided on pages 26-27 * Full case study sources provided on pages 26-27<br>
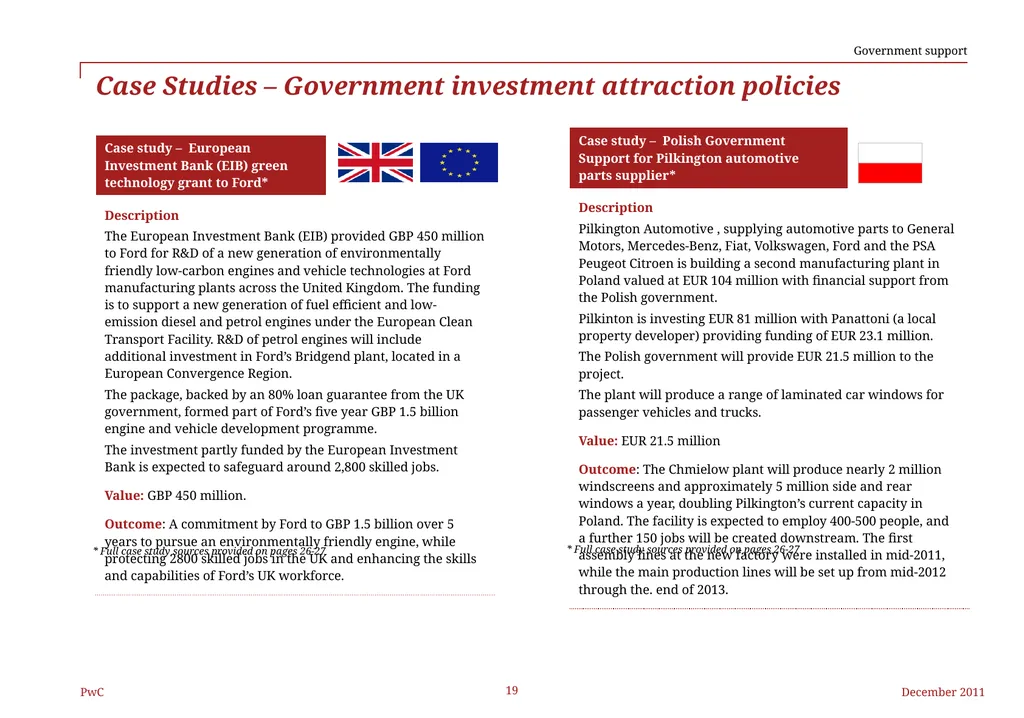
slide19. Case Studies – Government investment attraction policies Government support * Full case study sources provided on pages 26-27 * Full case study sources provided on pages 26-27<br>
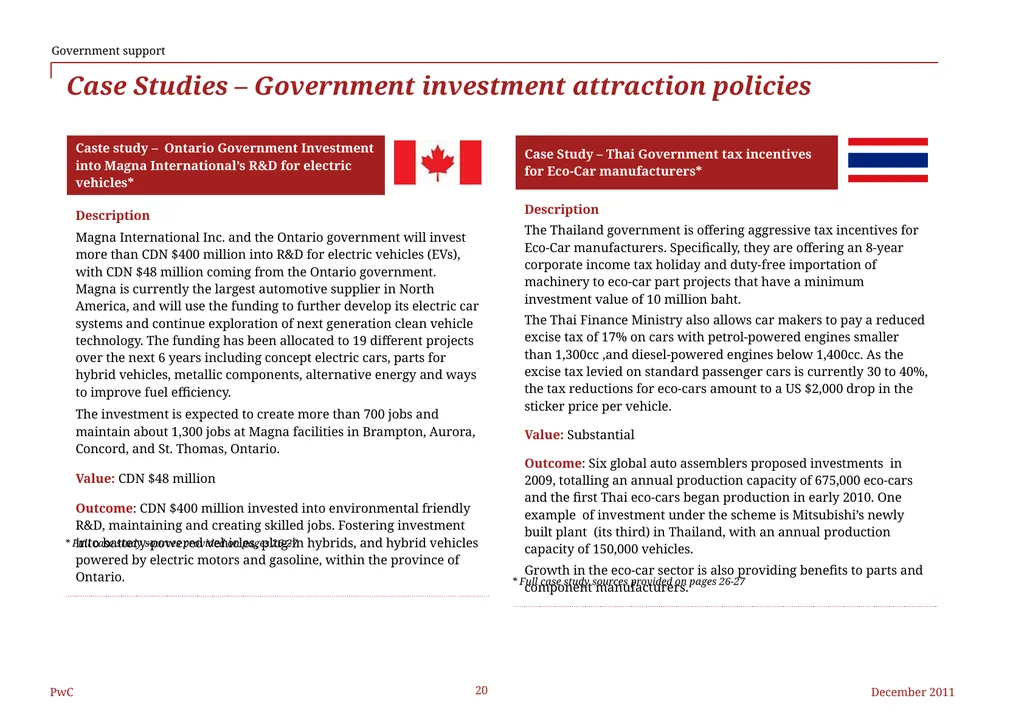
slide20. Case Studies – Government investment attraction policies Government support * Full case study sources provided on pages 26-27 * Full case study sources provided on pages 26-27<br>
slide21. The longevity of co-investment policies The longer term capacity of many developed countries to support wide scale co-investment policies should be questioned.
It is expected that while economic uncertainty and market volatility continue in the short to medium term, governments will continue to promote co-investment policies as a way to secure jobs, diversify their economic base and attract investment.
However, many developed countries potentially lack the long-term fiscal capacity to continue support of co-investment policies. Chart 19 indicates countries’ net borrowings (ie. current budget position) on the vertical axis, and general government (ie. public sector) debt as a percentage of annual GDP on the horizontal axis. There are two important points to note about his chart:
A debt to GDP ratio greater than 90% is generally considered unsustainable.* At this level the increased burden of servicing the debt hampers economic growth, leading to a spiralling deterioration in economic performance.
A number of major EU countries have already surpassed this level, with others such as Spain, France, the UK and US expected to move closer, or surpass this threshold in the coming years. Countries in this position will find it increasingly difficult to support co-investment schemes as austerity measures will be required (or as currently seen in the EU forcefully imposed) to bring public sector debt back to manageable levels.
Compared to other developed nations, Australia does not have either a budget deficit or public debt issue. Furthermore, Australia’s ability to leverage the benefits of the resource boom implies this position is likely to strengthen rather than deteriorate relative to other developed countries. Chart 19: Government borrowing and net debt, 2011 Source: IMF World Economic Outlook April 2011 database. * Public debt figures for China, India and Russia are gross, not net debt Government support * Reinhart, Rogoff, Growth in a Time of Debt, 2010<br>
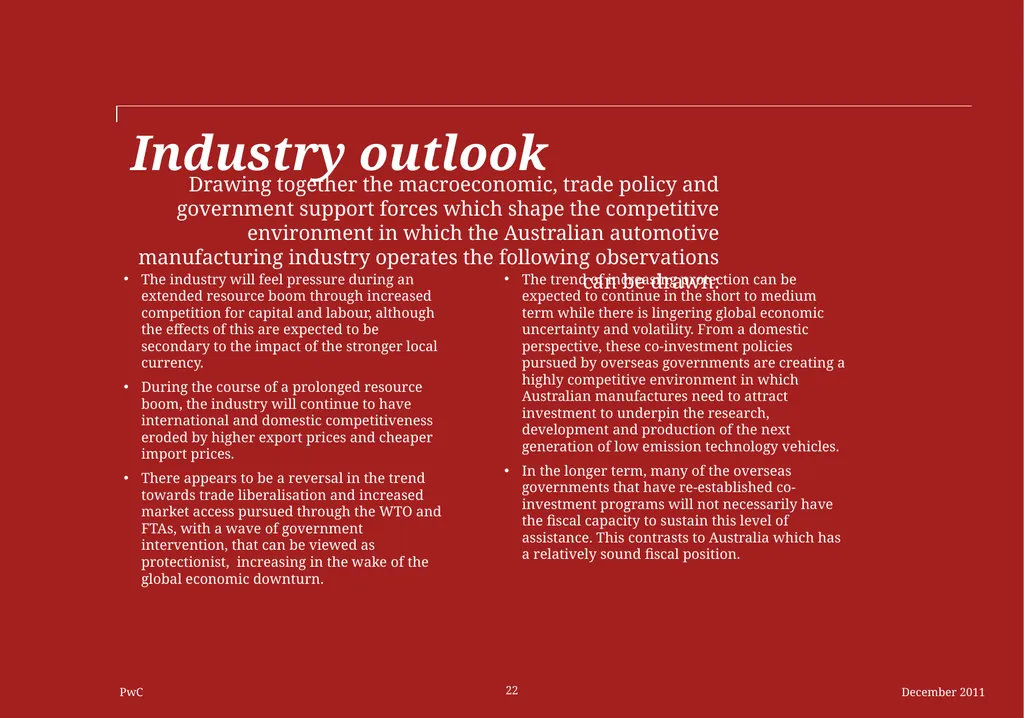
slide22. Industry outlook Drawing together the macroeconomic, trade policy and government support forces which shape the competitive environment in which the Australian automotive manufacturing industry operates the following observations can be drawn: The trend of increasing protection can be expected to continue in the short to medium term while there is lingering global economic uncertainty and volatility. From a domestic perspective, these co-investment policies pursued by overseas governments are creating a highly competitive environment in which Australian manufactures need to attract investment to underpin the research, development and production of the next generation of low emission technology vehicles.
In the longer term, many of the overseas governments that have re-established co-investment programs will not necessarily have the fiscal capacity to sustain this level of assistance. This contrasts to Australia which has a relatively sound fiscal position. The industry will feel pressure during an extended resource boom through increased competition for capital and labour, although the effects of this are expected to be secondary to the impact of the stronger local currency.
During the course of a prolonged resource boom, the industry will continue to have international and domestic competitiveness eroded by higher export prices and cheaper import prices.
There appears to be a reversal in the trend towards trade liberalisation and increased market access pursued through the WTO and FTAs, with a wave of government intervention, that can be viewed as protectionist, increasing in the wake of the global economic downturn.<br>
slide23. Sources Case Study 1 – Incentive Package to draw investment into the state of Tennessee
Al.com (2011), Volkswagen’s new $1 billion plant up and running in Chattanooga, accessed 30th November 2011 at: http://blog.al.com/breaking/2011/05/volkswagens_new_1_billion_plan.html
Examiner.com (2011), Volkswagen receives $570 million in tax incentives for new plant in Tennessee, accessed 30th November 2011 at: http://www.examiner.com/finance-examiner-in-national/volkswagon-receives-570-million-tax-incentives-for-new-plant-tennessee
Knoxvillebiz.com (2011), Chattanooga Volkswagen plant up and running, making fuel-efficient Passat model, accessed 30th November 2011 at: http://www.knoxnews.com/news/2011/may/25/volkswagen-up-and-running/
Case Study 2 – Incentives to shift the production of automobile lithium-ion batteries to Michigan.
Argonne (2011), LG Chem, Argonne sign licensing deal to make, commercialize advanced battery material, accessed 30th November 2011 at: http://www.anl.gov/Media_Center/News/2011/news110106a.html
Green Car Congress (2011), GM, LG Chem licensing Argonne Lab’s layered-layered composite cathode material for Li-ion batteries; substantial increase in energy capacity and safety, accessed 30th November 2011 at: http://www.greencarcongress.com/2011/01/anlgm-20110106.html
Mlive.com (2011), Construction complete at LG Chem battery plant, 300 employees expected in 2012, accessed 30th November 2011 at: http://www.mlive.com/business/west-michigan/index.ssf/2011/09/construction_complete_at_lg_ch.html Case study 3 – UK and European Investment Bank (EIB) support for Nissan electric cars
Automotive Business Review (2011), Nissan to build Leaf in UK from 2013, accessed 30th November 2011 at: http://www.automotive-business-review.com/news/nissan-to-build-leaf-in-uk-from-2013-101111
Nebusiness.co.uk (2011), £188m deal to support Nissan Leaf production, accessed 30th November 2011 at: http://www.nebusiness.co.uk/business-news/latest-business-news/2011/11/10/188m-deal-to-support-nissan-leaf-production-51140-29750770/
The engineer (2011), European fund supports production of Nissan LEAF, accessed 30th November 2011 at: http://www.theengineer.co.uk/sectors/automotive/news/european-fund-supports-production-of-nissan-leaf/1010852.article
Case study 4 – European Investment Bank (EIB) green technology grant to Ford
Financial Times (2010), UK pledges £381m support package for Ford and Nissan projects, accessed 30th November 2011 at: http://www.ft.com/cms/s/0/c14677da-32f6-11df-bf5f-00144feabdc0.html#axzz1fGer011V
Nine News (2010), UK backs Ford on green technologies, accessed 30th November 2011 at: http://202.58.48.79/article.aspx?id=1029231<br>
slide24. Sources Case study 5 – Polish Government Support for Pilkington automotive parts supplier
Adamowski, J (2011), Poland: Pilkington to invest 350m zloty in new plant, accessed 24th November 2011 at: http://www.automotiveworld.com/news/suppliers/86419-poland-pilkington-to-invest-z-350m-in-new-plant
Ceramic Industry (2011), NSG Group Announces Automotive Glazing Expansion, accessed 30th November 2011 at: http://www.ceramicindustry.com/Articles/Todays_Headlines/BNP_GUID_9-5-2006_A_10000000000001016601
NSG Group (2011), NSG Group Announces Major Expansion of Automotive Glazing Capacity and Capability in Poland, accessed 30th November 2011 at http://www.pilkington.com/websitev2/both/subsites/nsgcom/iframes/media-pr-2011-10032011.htm
Case study 6 – Ontario Government Investment into Magna International’s R&D for electric vehicles
Canadian Manufacturing (2011), Magna makes $400 million investment in EVs, accessed 24th November 2011 at: http://www.canadianmanufacturing.com/design-engineering/news/magna-makes-400-million-investment-in-evs-40656
CTV News (2011), Magna, Ontario to invest in electric vehicle research, accessed 30th November 2011 at: http://www.ctv.ca/CTVNews/Canada/20110829/ontario-magna-announcing-e-vehicle-research-funding-110829/
Electric Vehicle Update (2011), Canada: Ontario government emerging as EV hub, accessed 30th November 2011 at: http://analysis.evupdate.com/industry-insight/canada-ontario-government-emerging-ev-hub Case Study 7 – Thai Government tax incentives for Eco-Car manufacturers
Bangkok Post Auto (2011), Nissan launches second eco-car, wants higher tax rebate, accessed 30th November 2011 at: http://www.bangkokpost.com/auto/autoscoop/260304/nissan-launches-second-eco-car-wants-higher-tax-rebate
Business in Asia (2009), Thailand’s automotive industry to see growth accelerate, accessed 30th November 2011 at: http://www.business-in-asia.com/automotive/thailand_automotive.html
Go Auto.com.au (2009), Suzuki commits $251 million to building eco compact car in Thailand from 2012, accessed 30th November 2011 at: http://www.goauto.com.au/mellor/mellor.nsf/story2/FB061B9E87C26D63CA25767E001070C2<br>
slide25. pwc.com.au © 2011 PwC. All rights reserved. Not for further distribution without the permission of PwC. "PwC" refers to the network of member firms of PricewaterhouseCoopers International Limited (PwCIL), or, as the context requires, individual member firms of the PwC network. Each member firm is a separate legal entity and does not act as agent of PwCIL or any other member firm. PwCIL does not provide any services to clients. PwCIL is not responsible or liable for the acts or omissions of any of its member firms nor can it control the exercise of their professional judgment or bind them in any way. No member firm is responsible or liable for the acts or omissions of any other member firm nor can it control the exercise of another member firm's professional judgment or bind another member firm or PwCIL in any way.
Liability is limited by a Scheme approved under Professional Standards Legislation.<br>
slide2. Disclaimer This report has been prepared by PwC at the request of the Federal Chamber of Automotive Industries (FCAI), according to the terms of our Engagement Contract with FCAI.
The information, statements, statistics and commentary (together the “Information”) contained in this report have been prepared by PwC from publically available sources. PwC does not express an opinion as to the accuracy or completeness of the information, the assumptions made by the parties that provided the information or any conclusions reached by those parties. PwC may at its absolute discretion, but without being under any obligation to do so, update, amend or supplement this document. PwC disclaims any and all liability arising from actions taken in response to this report. PwC disclaims any and all liability for any investment or strategic decisions made as a consequence of information contained in this report. PwC, its employees and any persons associated with the preparation of the enclosed documents are in no way responsible for any errors or omissions in the enclosed document resulting from any inaccuracy, mis-description or incompleteness of the information provided or from assumptions made or opinions reached by the parties that provided Information.
"PwC" refers to the network of member firms of PricewaterhouseCoopers International Limited (PwCIL), or, as the context requires, individual member firms of the PwC network. Each member firm is a separate legal entity and does not act as agent of PwCIL or any other member firm. PwCIL does not provide any services to clients. PwCIL is not responsible or liable for the acts or omissions of any of its member firms nor can it control the exercise of their professional judgment or bind them in any way. No member firm is responsible or liable for the acts or omissions of any other member firm nor can it control the exercise of another member firm's professional judgment or bind another member firm or PwCIL in any way.
Liability is limited by a Scheme approved under Professional Standards Legislation. Draft<br>
slide3. Executive summary PwC has been engaged by the Federal Chamber of Automotive Industries (FCAI) to prepare a report informing on the:
current economic profile of the automotive industry within Australia
competitive challenges facing the industry stemming from changing macroeconomic and trade conditions
industry investment policies currently being perused by overseas governments. Investment attraction – current patterns of co-investment by overseas governments imply very strong competition for global automotive industry investment. This investment is needed to produce the next generation of low emission vehicles in Australia.
Sound Fiscal Environment – in the longer term, many of the overseas governments that have re-established co-investment programs will not necessarily have the fiscal capacity to sustain these investments. This contrasts with Australia, which has a relatively sound fiscal position. – Increased Competition for Investment Attraction – as a result of the global economic downturn, overseas governments intervened to diversify and strengthen their manufacturing base. In comparison, the level of assistance and co-investment received by Australian manufacturers is relatively low.
Exchange Rate – as a result of the mining boom the $A has appreciated markedly, increasing the competitiveness of imported cars in the domestic market and reducing the competitiveness of Australian exported automotive products.
Reciprocal Market Access – the Australian Government unilaterally reduced the general automotive tariff from 10% to 5% in 2010, yet other major automotive manufacturing nations have responded to the economic down-turn by increasing protective barriers. Moreover, based on current tariff and excise arrangements, Australia’s free trade agreements do not appear to be providing export market access for Australian vehicle manufacturers. The Australian automotive industry continues to be a substantial contributor to the Australian economy:
directly employing up to 59,000 people in manufacturing
generating broader industry gross value add of $23.5 billion per year (on par with the utilities and hospitality sectors)
exporting automotive vehicles and components worth $3.6 billion during 2010
investing $5.8 billion in research and development over the last 10 years.
The challenges facing the Australian automotive industry are predominantly externally generated, arising from the broader economic integration between Australian and international economies:
Access to Finance – the longer-term impact of the global financial crisis (GFC) has been a global reduction in available finance for investment in automotive manufacturing. The strength of the new vehicle market in Australia masks the challenges facing the Australian vehicle manufacturing industry. Australian vehicle production has dropped by over 40% since a peak in 2004. The majority of this reduction has occurred since the global economic downturn and is as a consequence of:
increased competition (due to tariff reductions and strengthening of the A$) in the Australian domestic market resulting in a reduction in locally produced vehicles from 30% to 15% of the domestic market
weakened consumer confidence and changes in consumer demand for smaller, low emission, vehicles.
Going forward, given the global economic environment, it is reasonable to expect that:
New Auto Investment – broad macroeconomic, trade and consumer trends (i.e. the higher $A, expansion of free trade agreements without reciprocal market access) will continue. These are challenges to which the Australian automotive manufacturers will need to respond with new investment and increased productivity.<br>
slide4. Table of contents – Industry profile 5
Macroeconomic trends 11
Government support 15
Industry outlook 24<br>
slide5. Industry profile: Role in the economy Automotive manufacturing provides significant economic benefits in terms of employment, value adding, R&D and exporting. The industry is the largest contributor to manufacturing output, employment and R&D.
The automotive industry provides employment for high-value design and engineering skills and builds capability in Australia that has spillover benefits for other industry sectors.
The industry also requires a large and stable workforce that can be located around major employment centres.<br>
slide6. Economic output The Global Financial Crisis (GFC) in 2008 re-intensified the debate around the importance of a diversified economy underpinned by a strong manufacturing base.
The sharp downturn and subsequent weakness in high value add services re-focused attention on labour intensive manufacturing industries, like the automotive industry. Many governments have responded through increased investment designed to retain and attract automotive manufacturing. The methods and extent to which this has occurred is discussed in further detail in Section 2 – A changing competitive environment. Industry profile: Role in the economy Within Australia, the automotive industry represents an estimated 1.92% of total gross domestic product (GDP). This equates to annual industry gross value add of $23.5 billion.
This level of economic output puts the industry on par with the utilities and hospitality sectors. The automotive sector’s numerous linkages to other parts of the economy also ensures a high spill over, or flow through effect of industry investment into the broader economy. Source: ABS (2011) Cat. 5206.0; IBIS World Australia Automotive Industry Report Series (2011) Chart 1: Industry share of GDP FY11<br>
slide7. Production and sales The size of the automotive market has increased by 32% since 2000, reflecting an annual growth rate of around 2.8%.
While sales did stall during the GFC, renewed domestic demand in 2010 for passenger vehicles and SUVs has seen domestic demand return to pre-GFC levels.
There has been a decline in the local production of motor vehicles from its peak in 2003 and 2004. Key features of this downward trend include:
production for the domestic market contracting at an annual rate of approximately 9%
production for the export market growing steadily through to 2008 at an annual rate of approximately 4.7%, but fell away sharply in 09/10.
In 2001, just under 30% of total domestic demand was served by domestic vehicle production. This figure has halved, with just under 15% of total domestic demand served by domestic vehicle production in 2010. The implication of declining domestic production set against increased domestic demand has been an increase in importation of vehicles to fill the gap.
This shift is a function of changes to the domestic and international competitive environment, as well as shifting consumer preference. These forces, and both their current and potential impact upon the automotive industry within Australia, are discussed in detail in Section 2 – A changing competitive environment. Industry profile: Role in the economy Chart 2: Motor vehicle sales in Australia Source: DIISR, Key Automotive Statistics (2010) Chart 3: Motor vehicle production in Australia Source: DIISR, Key Automotive Statistics (2010)<br>
slide8. Exports The export of automotive vehicles and components was worth $3.6 billion dollars during 2010.
This comprised the export of approximately 94,000 vehicles (40% of total domestic production), generating export revenues of $2.1 billion, and $1.5 billion in components.
The long term revenue from automotive exports has increased (Chart 4) despite the decline in the units exported (Chart 3, previous page). This implies that the export value per unit exported rose from 2000 through to 2008, with total exports exceeding $5 billion due to increasing efficiencies and a favourable currency.
More recently, the stalling of consumer demand for vehicles resulting from the GFC and the strength of the $A have led to a reduction in the number of vehicles exported (down 55% between 2008 and 2009) and a near halving of their export value.
Australia’s key export markets include the Middle East (44% of exports), New Zealand (13%) and the countries within the NAFTA bloc (9%). The composition of these top trading partners is important because both the Middle East and the US were severely affected by the GFC and there was a corresponding decrease in demand for vehicles in these markets.
Furthermore, the recent appreciation of the $A has been most pronounced against the $US (against which many Middle Eastern countries peg their currency), implying lower price competitiveness in these markets since the GFC. This point is elaborated upon further in Section 2 – A changing competitive environment. Source: DIISR, Key Automotive Statistics (2010) Industry profile: Role in the economy Chart 4: Changing value of automotive exports<br>
slide9. Employment Chart 5: Employment within the automotive industry The automotive industry directly employs up to 59,000 people in local manufacturing.
The estimates of employment in automotive manufacturing range from 52,000 as reported by IBIS World up to approximately 59,000 as reported by the Department of Innovation, Industry, Science and Research. This employment within manufacturing forms the base of the local automotive industry, not only through its job creation, but wider support for the localised supply chain which includes parts manufacturers.
Employment within the wider automotive industry has grown steadily over the past decade. However, this total growth masks declining employment in automotive manufacturing which currently makes up 14% of employment within the industry, down from 20% in 2002/03. The total industry employment growth is being driven by automotive servicing, which accounts for an estimated 72% of all people employed within the industry.
The overall automotive industry currently employs 372,000 people. This includes the 52,000 people directly employed in manufacturing (IBIS World estimate), 147,000 employed in servicing and 173,000 employed in retail/wholesale activities.
This total employment figure of 372,000 in the automotive industry, implies that the industry employs more people than the:
Agricultural sector (336,000)
Mining sector (212,000)
Utilities sector (electricity, gas and waste services) (149,000). Chart 6: Automotive employment vs. other industries Source: IBIS World, Australia Automotive Industry Report Series (2011) reports an estimated 59,000 people employed within the automotive manufacturing industry in 2010, DIISR. Source: ABS, IBIS World, Australia Automotive Industry Report Series (2011) Industry profile: Role in the economy<br>
slide10. Productivity and innovation Chart 7: R&D expenditure in automotive industry Research & Development in the automotive industry has averaged 8.1% growth over the past 10 years. During this time, a total of $5.8 billion has been invested.
Chart 8 displays labour productivity (in terms of production value per employee) in the automotive sector. As demonstrated, productivity has grown at an annualised rate of:
3.3% p.a. over the five year period 2005-2010
2.2% p.a. over the ten year period 2000-2010.
Since 2005, this growth in productivity has been driven primarily by a decrease in the number of employees, rather than growth in output. Output fell by 26% over the period, while there was a 36% fall in the number of employees.
The Australian manufacturing sector as a whole has also demonstrated moderate labour productivity growth over this period. Labour productivity (measured in terms of Gross Value Added per hour worked) grew at an annualised rate of 1.8% p.a. over the ten years to 2010 and has grown by 1.6% p.a. since 2005.
This growth reflects a similar trend to the automotive sector; output over the 2005-2010 period grew by just 0.7% over the period, with productivity gains driven by a 7% reduction in hours worked. Source: DIISR, Key Automotive Statistics (2010) Source: DIISR, Key Automotive Statistics (2010) Chart 8: Productivity Industry profile: Role in the economy<br>
slide11. Macroeconomic trends<br>
slide12. Exchange rates Chart 9: Historical performance of the $A The value of the Australian Dollar (A$) has a direct impact on the profitability of the local automotive manufacturers.
With 40% of local production exported, the recent strength and volatility of the A$ against the currencies of major trading partners and export destinations hampers export competitiveness and creates uncertainty around long term investment decisions.
Chart 9 demonstrates the recent strength and volatility against historical trends while Chart 10 demonstrates the appreciation of the A$ against major vehicle export destinations since mid 2010. Key observations and implications include:
The A$ has appreciated most against the United States Dollar (US$), a function not only of the strength of the Australian economy, but also the weakness of the US economy. Australia’s largest automotive export market is Middle Eastern countries (in 2010 44% of total exports) which peg their currency to the US$. Combined with exports to the US, the price competitiveness of close to 50% of Australian automotive exports are therefore tied to movements, and the current strength, of the A$ against the US$.
Against other key trading partners the A$ has also strengthened by around 10%- 15%.
In the short-term, global economic uncertainty will continue to result in a volatile A$. In the long-term, sustained Chinese economic growth is expected to support a strong A$ which will remain high by historical standards. Chart 10: Appreciation of $A Source: RBA (Daily data, 2011) Source: RBA (Monthly data,2011) Long term average: 0.72 Macroeconomic trends<br>
slide13. Industry performance and investment Chart 11: Industry investment as % of total GDP The automotive industry is also facing a reduction in available finance. This stems from increased funding costs that have affected all industries post the GFC. This is being intensified by the impact that the required capital investment by the Australian resource sector is having upon other industries. This impact is shown in Chart 11 which demonstrates the increased competition for investment against the mining industry.
In the long term, lower levels of capital investment are likely to limit the relative technological and productivity growth within the manufacturing sector. This not only stunts growth during the commodity boom (as demonstrated in Chart 12); it makes it harder for these sectors to rebound once the commodity boom comes to an end.
As pointed out by the Federal Treasury (2011):
When commodity prices normalise or when resources are depleted, tradeable sectors which have disappeared might simply not reappear.
This statement emphasises that the ability of an industry to rebound after a sustained commodities boom may be stifled, potentially beyond the point of recovery. This is especially true for the automotive industry. The capital intensive nature of operations and high levels of international competition would act as barriers to re-establishment within Australia if under-investment leads to a relocation of manufacturing offshore.
In the event that there is a ‘hollowing out’ of industry during a resources boom, the Australian economy becomes exposed to the risk that it is not able to offset the decline in commodity prices by expanding non-resources activities in a timely fashion. Chart 12: Growth by industry, before and during the mining boom Source: ABS (2011) Source: Commonwealth Government, Federal Budget 2011/12, Statement 4: Benefiting from Our Mineral Resources Interpreting this chart:
A point close to the diagonal line indicates that the industry grew during the boom at a similar rate to the six year period prior to the boom. A point north (south) of the diagonal indicates that the industry grew slower (faster) during the boom. (The chart is presented in gross value added, 2008-09 dollars. Services exclude construction and utilities.) Macroeconomic trends<br>
slide14. Chart 13: Increasing oil prices and automotive fuel prices Higher oil prices and global economic uncertainty are resulting in changing consumer preferences.
Increasing oil prices impact upon the Australian automotive industry in the following ways:
increasing the cost of production through higher input and distribution costs
reducing, or substituting domestic demand for vehicles due to higher fuel costs
Shifting demand from larger to smaller (including diesel) vehicles.
Despite volatility, the price of oil has increased by over 200% during the period 2001 to 2011 (Chart 13). Australia has been shielded from the full impact of the rising global oil price by the appreciation of the $A.
The full magnitude of the world oil price increases have not directly flowed through to consumers, with the costs of automotive fuel increasing by just under 60% across the period 2001 to 2011. However, over the past year the rebounding price of oil has translated to increasing consumer fuel costs, with both oil and petrol prices rising by 13.9%. This trend has contributed to a shift to smaller and lower fuel consumption vehicles, and diesel engines. Oil prices and consumer sentiment Source: ABS (2011), Cat. 6401.0, WTI $US per barrel, http://www.economagic.com/em-cgi/data.exe/var/west-texas-crude-long (2011) Chart 14: Australian consumer confidence (standard deviation from long term average) Source: Westpac – Melbourne Institute (2011), Macroeconomic trends<br>
slide15. Government support “Governments are increasingly trying to influence conditions in the job-intensive automotive industry, using mechanisms such as loans, incentives and premiums. At the same time, protectionism is growing. Seventeen of the G20 countries have introduced protectionist measures since the financial crisis 2008/2009, distorting global trade in goods by an estimated USD 50 billion per year.” Roland Berger (2011) Around the world, Governments have responded to decreasing access to finance and deteriorating market conditions by focusing on investment attraction, or co-investment. Co-investment can take the form of funding, grants, partnership arrangements or incentives designed to attract the investment required for the design and production of the next generation of vehicles and strengthen the ability of the local industry to compete both domestically and globally. Competition between countries to attract this investment is significant.
These policies can be viewed as a response by governments to (re)diversify and strengthen their manufacturing base in the face of weakening high value add services industries such as finance and insurance.
Concurrent to co-investment policies are tariff barriers and free trade agreements (FTAs) which shape the international trade environment. Within Australia, the retail market for cars is one of the most open and competitive in the world.
This has been driven by the Australian Government’s unilateral reduction applied to general automotive tariff from 10% to 5% in 2010. Yet other major automotive manufacturing nations have responded to the economic down-turn by increasing protective barriers. Moreover, Australia’s free trade agreements do not appear to be providing reciprocal market access for Australian vehicle manufacturers.<br>
slide16. Tariff barriers Chart 15: Global automotive headline tariffs Foreign access to the Australian automotive market has increased significantly in recent years through the successive reductions in tariff barriers and the formalising of FTAs.
As can be seen in Chart 15, a number of key Australian export markets (which also house companies that compete in Australia's domestic market) operate behind high tariff barriers. Australia currently imposes one of the lowest import tariffs of 5%, however this level is not directly reciprocated by our trading partners.
This theme of tariff level reciprocity is mirrored in current FTAs. Two key agreements, both of which came into force on 1 Jan 2005, are the Thailand and US FTAs. The implications of these agreements on import and export tariffs are discussed below:
Thailand – The import tariff on Thai manufactured vehicles was reduced to zero on 1 January 2005. For the export of Australian manufactured large and commercial vehicles, tariff barriers were eliminated. For other vehicles, tariff barriers were dropped from 80% to 30% on 1 January 2005, before being phased down to 6% in 2010. Tariffs on exported engines remain at 15%. However, a range of non-tariff barriers such as excise taxes remain in place. The excise tax structure is complex and is charged based on the engine capacity of a vehicle. Which works against Australian manufactured vehicles and favours domestic manufacturers. These non-tariff barriers add to the Thai retail cost of imported vehicles.
US – Import of US manufactured vehicles and parts was reduced to 3% in 2008 and zero in 2010. Exports of Australian manufactured vehicles and parts have zero tariff applied.
This increasing access given to foreign competitors to the Australian market has coincided with the emergence of the resource boom discussed previously. These two forces have had a marked impact upon the relative performance of domestic manufacturers. Chart 16 shows the declining market share of domestic manufacturing brands from holding 55% of market share in 2005 to less than 40% market share in 2010. This represents a phenomenal pace of change in the competitive landscape facilitated by increased market access, and magnified by the additional domestic pressures local manufacturers started to feel as the result of the mining boom. Source: DFAT (2011)US Department of Commerce (2008) Chart 16: Market share of domestic manufacturing companies vs. Foreign manufacturing companies Source: DIISR, Key Automotive Statistics (2010), DFAT (2011) General automotive tariff cut from 15% to 10% Government support US and Thailand FTA entered into force 1 Jan 2005 General automotive import tariff cut from 10% to 5%<br>
slide17. Government investment attraction policies The focus of overseas Governments on co-investment policies has resulted in intense competition, from both countries and smaller jurisdictions within these countries, to attract and retain investment in automotive design and manufacturing.
Following the GFC, intervention in the market by overseas governments has increasingly taken the form of investment attraction (or co-investment) policies.
This can be viewed as a response by governments to (re)diversify and strengthen their manufacturing base in the face of weakening high value added services industries such as finance and insurance. The protection or attraction of automotive vehicle design and manufacturing has been seen by governments to not only secure or directly stimulate employment growth, but also secure the employment and value added associated with the supply chain that accompanies these industries.
The following case studies highlight:
the varied nature of investment attraction policies adopted by governments around the world and the benefits these provide to automotive manufacturers
the outcomes of these policies to governments in terms of retaining and attracting both foreign and domestic investment
the often opaque nature of the policies.
The implication of these policies is intense competition, from both countries and smaller jurisdictions within these countries, to attract and retain investment in automotive design and manufacturing. These government policies recognise the value, in terms of jobs and economic output, to the local economy. They also provide a competitive advantage to companies based in overseas markets: companies against which local manufacturers not only compete against in export markets, but also increasingly compete against in the domestic market. Government support * Full case study sources provided on pages 26-27<br>
slide18. Case Studies – Government investment attraction policies Government support * Full case study sources provided on pages 26-27 * Full case study sources provided on pages 26-27<br>
slide19. Case Studies – Government investment attraction policies Government support * Full case study sources provided on pages 26-27 * Full case study sources provided on pages 26-27<br>
slide20. Case Studies – Government investment attraction policies Government support * Full case study sources provided on pages 26-27 * Full case study sources provided on pages 26-27<br>
slide21. The longevity of co-investment policies The longer term capacity of many developed countries to support wide scale co-investment policies should be questioned.
It is expected that while economic uncertainty and market volatility continue in the short to medium term, governments will continue to promote co-investment policies as a way to secure jobs, diversify their economic base and attract investment.
However, many developed countries potentially lack the long-term fiscal capacity to continue support of co-investment policies. Chart 19 indicates countries’ net borrowings (ie. current budget position) on the vertical axis, and general government (ie. public sector) debt as a percentage of annual GDP on the horizontal axis. There are two important points to note about his chart:
A debt to GDP ratio greater than 90% is generally considered unsustainable.* At this level the increased burden of servicing the debt hampers economic growth, leading to a spiralling deterioration in economic performance.
A number of major EU countries have already surpassed this level, with others such as Spain, France, the UK and US expected to move closer, or surpass this threshold in the coming years. Countries in this position will find it increasingly difficult to support co-investment schemes as austerity measures will be required (or as currently seen in the EU forcefully imposed) to bring public sector debt back to manageable levels.
Compared to other developed nations, Australia does not have either a budget deficit or public debt issue. Furthermore, Australia’s ability to leverage the benefits of the resource boom implies this position is likely to strengthen rather than deteriorate relative to other developed countries. Chart 19: Government borrowing and net debt, 2011 Source: IMF World Economic Outlook April 2011 database. * Public debt figures for China, India and Russia are gross, not net debt Government support * Reinhart, Rogoff, Growth in a Time of Debt, 2010<br>
slide22. Industry outlook Drawing together the macroeconomic, trade policy and government support forces which shape the competitive environment in which the Australian automotive manufacturing industry operates the following observations can be drawn: The trend of increasing protection can be expected to continue in the short to medium term while there is lingering global economic uncertainty and volatility. From a domestic perspective, these co-investment policies pursued by overseas governments are creating a highly competitive environment in which Australian manufactures need to attract investment to underpin the research, development and production of the next generation of low emission technology vehicles.
In the longer term, many of the overseas governments that have re-established co-investment programs will not necessarily have the fiscal capacity to sustain this level of assistance. This contrasts to Australia which has a relatively sound fiscal position. The industry will feel pressure during an extended resource boom through increased competition for capital and labour, although the effects of this are expected to be secondary to the impact of the stronger local currency.
During the course of a prolonged resource boom, the industry will continue to have international and domestic competitiveness eroded by higher export prices and cheaper import prices.
There appears to be a reversal in the trend towards trade liberalisation and increased market access pursued through the WTO and FTAs, with a wave of government intervention, that can be viewed as protectionist, increasing in the wake of the global economic downturn.<br>
slide23. Sources Case Study 1 – Incentive Package to draw investment into the state of Tennessee
Al.com (2011), Volkswagen’s new $1 billion plant up and running in Chattanooga, accessed 30th November 2011 at: http://blog.al.com/breaking/2011/05/volkswagens_new_1_billion_plan.html
Examiner.com (2011), Volkswagen receives $570 million in tax incentives for new plant in Tennessee, accessed 30th November 2011 at: http://www.examiner.com/finance-examiner-in-national/volkswagon-receives-570-million-tax-incentives-for-new-plant-tennessee
Knoxvillebiz.com (2011), Chattanooga Volkswagen plant up and running, making fuel-efficient Passat model, accessed 30th November 2011 at: http://www.knoxnews.com/news/2011/may/25/volkswagen-up-and-running/
Case Study 2 – Incentives to shift the production of automobile lithium-ion batteries to Michigan.
Argonne (2011), LG Chem, Argonne sign licensing deal to make, commercialize advanced battery material, accessed 30th November 2011 at: http://www.anl.gov/Media_Center/News/2011/news110106a.html
Green Car Congress (2011), GM, LG Chem licensing Argonne Lab’s layered-layered composite cathode material for Li-ion batteries; substantial increase in energy capacity and safety, accessed 30th November 2011 at: http://www.greencarcongress.com/2011/01/anlgm-20110106.html
Mlive.com (2011), Construction complete at LG Chem battery plant, 300 employees expected in 2012, accessed 30th November 2011 at: http://www.mlive.com/business/west-michigan/index.ssf/2011/09/construction_complete_at_lg_ch.html Case study 3 – UK and European Investment Bank (EIB) support for Nissan electric cars
Automotive Business Review (2011), Nissan to build Leaf in UK from 2013, accessed 30th November 2011 at: http://www.automotive-business-review.com/news/nissan-to-build-leaf-in-uk-from-2013-101111
Nebusiness.co.uk (2011), £188m deal to support Nissan Leaf production, accessed 30th November 2011 at: http://www.nebusiness.co.uk/business-news/latest-business-news/2011/11/10/188m-deal-to-support-nissan-leaf-production-51140-29750770/
The engineer (2011), European fund supports production of Nissan LEAF, accessed 30th November 2011 at: http://www.theengineer.co.uk/sectors/automotive/news/european-fund-supports-production-of-nissan-leaf/1010852.article
Case study 4 – European Investment Bank (EIB) green technology grant to Ford
Financial Times (2010), UK pledges £381m support package for Ford and Nissan projects, accessed 30th November 2011 at: http://www.ft.com/cms/s/0/c14677da-32f6-11df-bf5f-00144feabdc0.html#axzz1fGer011V
Nine News (2010), UK backs Ford on green technologies, accessed 30th November 2011 at: http://202.58.48.79/article.aspx?id=1029231<br>
slide24. Sources Case study 5 – Polish Government Support for Pilkington automotive parts supplier
Adamowski, J (2011), Poland: Pilkington to invest 350m zloty in new plant, accessed 24th November 2011 at: http://www.automotiveworld.com/news/suppliers/86419-poland-pilkington-to-invest-z-350m-in-new-plant
Ceramic Industry (2011), NSG Group Announces Automotive Glazing Expansion, accessed 30th November 2011 at: http://www.ceramicindustry.com/Articles/Todays_Headlines/BNP_GUID_9-5-2006_A_10000000000001016601
NSG Group (2011), NSG Group Announces Major Expansion of Automotive Glazing Capacity and Capability in Poland, accessed 30th November 2011 at http://www.pilkington.com/websitev2/both/subsites/nsgcom/iframes/media-pr-2011-10032011.htm
Case study 6 – Ontario Government Investment into Magna International’s R&D for electric vehicles
Canadian Manufacturing (2011), Magna makes $400 million investment in EVs, accessed 24th November 2011 at: http://www.canadianmanufacturing.com/design-engineering/news/magna-makes-400-million-investment-in-evs-40656
CTV News (2011), Magna, Ontario to invest in electric vehicle research, accessed 30th November 2011 at: http://www.ctv.ca/CTVNews/Canada/20110829/ontario-magna-announcing-e-vehicle-research-funding-110829/
Electric Vehicle Update (2011), Canada: Ontario government emerging as EV hub, accessed 30th November 2011 at: http://analysis.evupdate.com/industry-insight/canada-ontario-government-emerging-ev-hub Case Study 7 – Thai Government tax incentives for Eco-Car manufacturers
Bangkok Post Auto (2011), Nissan launches second eco-car, wants higher tax rebate, accessed 30th November 2011 at: http://www.bangkokpost.com/auto/autoscoop/260304/nissan-launches-second-eco-car-wants-higher-tax-rebate
Business in Asia (2009), Thailand’s automotive industry to see growth accelerate, accessed 30th November 2011 at: http://www.business-in-asia.com/automotive/thailand_automotive.html
Go Auto.com.au (2009), Suzuki commits $251 million to building eco compact car in Thailand from 2012, accessed 30th November 2011 at: http://www.goauto.com.au/mellor/mellor.nsf/story2/FB061B9E87C26D63CA25767E001070C2<br>
slide25. pwc.com.au © 2011 PwC. All rights reserved. Not for further distribution without the permission of PwC. "PwC" refers to the network of member firms of PricewaterhouseCoopers International Limited (PwCIL), or, as the context requires, individual member firms of the PwC network. Each member firm is a separate legal entity and does not act as agent of PwCIL or any other member firm. PwCIL does not provide any services to clients. PwCIL is not responsible or liable for the acts or omissions of any of its member firms nor can it control the exercise of their professional judgment or bind them in any way. No member firm is responsible or liable for the acts or omissions of any other member firm nor can it control the exercise of another member firm's professional judgment or bind another member firm or PwCIL in any way.
Liability is limited by a Scheme approved under Professional Standards Legislation.<br>