
Financial Management and Budgeting Sandra Banas

Description: Financial Management and Budgeting Sandra Banas Meredith Davison New Program Directors Retreat Objectives Define: budget, accrual, capital expense, direct expense, indirect expense, discount rate, encumbered, FTE, fixed expense, variable
Related Topics
Download Presentation
"Financial Management and Budgeting Sandra Banas" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Financial Management and Budgeting Sandra Banas
Meredith Davison New Program Directors Retreat<br>
slide2. Objectives Define: budget, accrual, capital expense, direct expense, indirect expense, discount rate, encumbered, FTE, fixed expense, variable expense, variance & YTD
Describe the purpose of budgeting
List, compare and analyze different budget systems
List and describe the three types of budgets
Explain the budget cycle and its relationship with planning
Identify internal and external resources to designing office / classroom space 2<br>
slide3. Initial Considerations Expectations of the middle manager
Limitations
Control
Resources
Variability: institutional 3<br>
slide4. Definitions Budget
Financial plan of expenses & revenue used for planning & control purposes
Developed using goals, objectives and priorities 4<br>
slide5. Definitions Accrual
Expense or revenue that increases with the passage of time
Accrual-based accounting
Income posted when earned
Expenses posted when they occur
Cash-based accounting
Expense recognized when money actually spent
Income credited when it is received 5<br>
slide6. Definitions Capital expense
Investment that is useful for more than one accounting period
Depreciation
Direct expense
Expenses which are completely related to core business operations
Controlled by the program director 6<br>
slide7. Definitions Discount rate
Average percentage of tuition amount decreased by in-house scholarship awards
Encumbered
Outstanding financial obligation not yet dispersed
FTE
Full time equivalent. Example: 1.0, 0.5 etc. 7<br>
slide8. Purpose of the Budget Planning Tool
Monitoring Tool
Evaluation Tool
Control Tool
Quality Improvement Tool 8<br>
slide9. Budget Systems Incremental
Prior year’s budget serves as a base
Based on
Previous year’s budget performance
% increase or decrease Zero-Based
Each cycle starts with clean slate
Based on
Justification of activities
Objectives 9<br>
slide10. Budget Systems Line-item
Divided into:
Organizational units
Cost centers or academic departments
Expenditure categories Formula budgeting
Formulas for allocation
Workload formula
Student enrollment or credit hours x $ = $$ budgeted 10<br>
slide11. Questions to Think About What are the major issues and challenges faced by the Program?
What are the major opportunities for the Program in the next 3 to 5 years?
What are possible areas for cost reduction for the Program?
What are the possible areas for revenue generation for the Program? 11<br>
slide12. Components of a Budget Revenue
Allocated for maintenance and growth
Tuition, grants and other revenue projections
State appropriations Revenue
Based on
Past performance
New factors
Class size changes
External circumstances
Reported in student head count or cash
Should be realistic
Avoid high and low estimates 12<br>
slide13. Components of a Budget Capital Expense
Large investments
Equipment
Renovations
Usually centralized
Depreciation Operating Expense
Daily operational expenses
Salary
Phone
Supplies<br>
slide14. What Are Some Other Components of Your Budget ?<br>
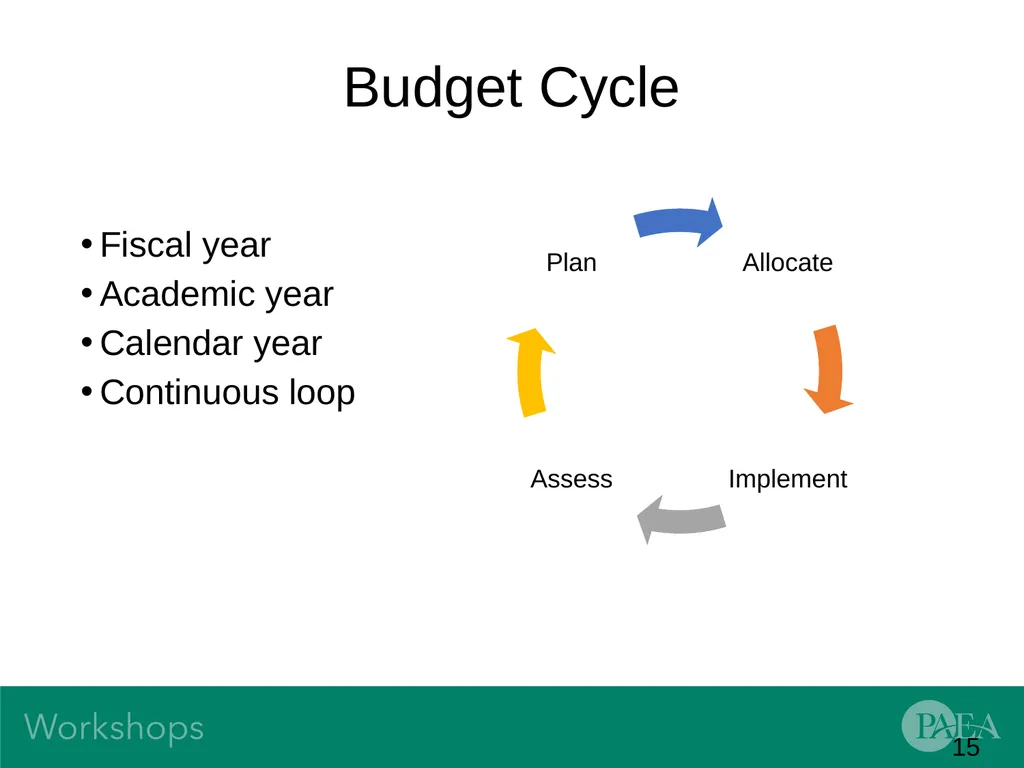
slide15. Budget Cycle Fiscal year
Academic year
Calendar year
Continuous loop 15<br>
slide16. Budget Roles Authority to create, change & approve expenditures
Role:
Spender: PD
Cutter: Dean
Controller: CFO 16<br>
slide17. Is Your Budget Cycle & Planning Similar or Different ?<br>
slide18. Developing a Budget Program mission, goals and objectives
Use goals and objectives to when creating budget
Strategic Planning / Scenario Planning
Budget Assumptions<br>
slide19. Anatomy of a Budget Representation of:
Past: Spending history (usually 1-2 years)
Present: Current YTD spending
Future: Projections
Spreadsheet format quantitative
Detailed breakdown of costs
Assumptions
Justifications (the narrative) 19<br>
slide20. Preparing the Budget Request Understand your system & follow the format
New (3-4 year) vs. existing (1 year)
Tools:
Policies (guidelines)
Spreadsheet
Last 1-3 year’s budget reports
Revenue expectations (Admissions)
University objectives, strategic plan. Put “first things first” Stephen Covey
Benchmarking data (PAEA report) 20<br>
slide21. Benchmarking Total Budget:
$1,899,411 (mean)
Range: $563K – $3.7m
Approximately 50% salaries (faculty & staff)
Class Size Average: Total- 110, 1st Year- 46
Mean Program Length: 26 months
Faculty/Student Ratio: (15.3 students/faculty academic year)
Source: 31st Annual Report on Physician Assistant Educational Programs in the Untied States, 2014-2015; PAEA, 2016 21<br>
slide22. Preparing the Budget Request Setting Priorities
Expenditure categories
Salaries, Natural , Functional , Matrix
Justifications/ narrative
Summary
Negotiation 22<br>
slide23. Budget Expenditure Categories Salaries
Benefits (various lines)
Honorarium
Student assistants
Telephone
Postage
Subscriptions
Membership dues
Travel
Accreditation Entertainment
Professional development
Office supplies
Instructional supplies
Photocopying
Equipment repair, maintenance, & service contracts
Minor equipment
Contractual services
Housekeeping 23<br>
slide24. Increased Costs Benefits
Facilities & deferred maintenance
Technology & IT
Journals
Security 24<br>
slide25. Increased Costs Clinical Sites !!<br>
slide26. Budget Negotiation PREPARATION, PREPARATION, PREPARATION !!
Collection & lobbying are year-round activities
Frequent contact with the Dean
Be persistent not annoying
Review the presentation
Question your assumptions 26<br>
slide27. Budget Negotiation Respect the chain of command
Establish credibility with the Dean by avoiding budget “padding” and “wish lists”
Use institutional & industry benchmarks
Don’t be P in the A
Prioritize !! 27<br>
slide28. Budget Negotiation Have clear justifications & communication
Anticipate questions:
Why is an expense needed?
What are the consequences if not funded?
How will a new expense be funded?
What are the department’s contribution to the University?
Accreditation use this card wisely 28<br>
slide29. Budget Approval Process Program Director
Dean
VPAA/Provost
VP-Finance
President
Board of Trustees or Directors
State: Executive & legislative 29<br>
slide30. Budget Evaluation Performance/Variance reports
Evaluate minimally monthly
Explain variance & unexpected costs
Shift money if permitted
Adjust money or behavior
Use in developing next year’s request 30<br>
slide31. Budget Evaluation Monthly reports
Budgeted
YTD spent
YTD encumbered
Variance (favorable, unfavorable)
Available
Prior year closeout 31<br>
slide32. Potential Budgeting Problems Program Director ignores budget
All levels of organization not involved or invested in budget process
Continued unfavorable variances that remain uncorrected
Budget & financial managers that don’t understand the daily operations
Budget does not take into account macroeconomic issues 32<br>
slide33. Potential Budgeting Problems Program Director does not understand budget or how allowances were determined
No improvement action from process
Budget measures not reviewed or analyzed on a timely basis
Budget etched in stone 33<br>
slide34. Budget Games Cut everything by ___%
Padded budget
End of Budget Year syndrome
The President wants it
The ARC requires it
Do what you want
It’s not in the budget
It’s in their budget (ex. brochures) 34<br>
slide35. New Program 3-5 year cost & revenue budget
Start-up costs
Front load vs. incremental
Break even analysis 35<br>
slide36. Important Take-Aways Do not be afraid of budgeting
Always ask questions; do not assume!
Do not ignore the budget
Make friends with people in the financial offices at your university
Basic Finances 101 for managers in your institution<br>
slide37. Acknowledgements Special thanks to the following colleague for his contributions to this presentation:
Robert Philpot PhD, PA-C<br>
slide38. References College & University Budgeting: An Introduction for Faculty and Academic Administrators. Larry Goldstein. NACUBO
Budgets and Financial Management in Higher Education. Margaret J. Barr. George S. McClellan. 2011. Jossey-Bass 38<br>
Meredith Davison New Program Directors Retreat<br>
slide2. Objectives Define: budget, accrual, capital expense, direct expense, indirect expense, discount rate, encumbered, FTE, fixed expense, variable expense, variance & YTD
Describe the purpose of budgeting
List, compare and analyze different budget systems
List and describe the three types of budgets
Explain the budget cycle and its relationship with planning
Identify internal and external resources to designing office / classroom space 2<br>
slide3. Initial Considerations Expectations of the middle manager
Limitations
Control
Resources
Variability: institutional 3<br>
slide4. Definitions Budget
Financial plan of expenses & revenue used for planning & control purposes
Developed using goals, objectives and priorities 4<br>
slide5. Definitions Accrual
Expense or revenue that increases with the passage of time
Accrual-based accounting
Income posted when earned
Expenses posted when they occur
Cash-based accounting
Expense recognized when money actually spent
Income credited when it is received 5<br>
slide6. Definitions Capital expense
Investment that is useful for more than one accounting period
Depreciation
Direct expense
Expenses which are completely related to core business operations
Controlled by the program director 6<br>
slide7. Definitions Discount rate
Average percentage of tuition amount decreased by in-house scholarship awards
Encumbered
Outstanding financial obligation not yet dispersed
FTE
Full time equivalent. Example: 1.0, 0.5 etc. 7<br>
slide8. Purpose of the Budget Planning Tool
Monitoring Tool
Evaluation Tool
Control Tool
Quality Improvement Tool 8<br>
slide9. Budget Systems Incremental
Prior year’s budget serves as a base
Based on
Previous year’s budget performance
% increase or decrease Zero-Based
Each cycle starts with clean slate
Based on
Justification of activities
Objectives 9<br>
slide10. Budget Systems Line-item
Divided into:
Organizational units
Cost centers or academic departments
Expenditure categories Formula budgeting
Formulas for allocation
Workload formula
Student enrollment or credit hours x $ = $$ budgeted 10<br>
slide11. Questions to Think About What are the major issues and challenges faced by the Program?
What are the major opportunities for the Program in the next 3 to 5 years?
What are possible areas for cost reduction for the Program?
What are the possible areas for revenue generation for the Program? 11<br>
slide12. Components of a Budget Revenue
Allocated for maintenance and growth
Tuition, grants and other revenue projections
State appropriations Revenue
Based on
Past performance
New factors
Class size changes
External circumstances
Reported in student head count or cash
Should be realistic
Avoid high and low estimates 12<br>
slide13. Components of a Budget Capital Expense
Large investments
Equipment
Renovations
Usually centralized
Depreciation Operating Expense
Daily operational expenses
Salary
Phone
Supplies<br>
slide14. What Are Some Other Components of Your Budget ?<br>
slide15. Budget Cycle Fiscal year
Academic year
Calendar year
Continuous loop 15<br>
slide16. Budget Roles Authority to create, change & approve expenditures
Role:
Spender: PD
Cutter: Dean
Controller: CFO 16<br>
slide17. Is Your Budget Cycle & Planning Similar or Different ?<br>
slide18. Developing a Budget Program mission, goals and objectives
Use goals and objectives to when creating budget
Strategic Planning / Scenario Planning
Budget Assumptions<br>
slide19. Anatomy of a Budget Representation of:
Past: Spending history (usually 1-2 years)
Present: Current YTD spending
Future: Projections
Spreadsheet format quantitative
Detailed breakdown of costs
Assumptions
Justifications (the narrative) 19<br>
slide20. Preparing the Budget Request Understand your system & follow the format
New (3-4 year) vs. existing (1 year)
Tools:
Policies (guidelines)
Spreadsheet
Last 1-3 year’s budget reports
Revenue expectations (Admissions)
University objectives, strategic plan. Put “first things first” Stephen Covey
Benchmarking data (PAEA report) 20<br>
slide21. Benchmarking Total Budget:
$1,899,411 (mean)
Range: $563K – $3.7m
Approximately 50% salaries (faculty & staff)
Class Size Average: Total- 110, 1st Year- 46
Mean Program Length: 26 months
Faculty/Student Ratio: (15.3 students/faculty academic year)
Source: 31st Annual Report on Physician Assistant Educational Programs in the Untied States, 2014-2015; PAEA, 2016 21<br>
slide22. Preparing the Budget Request Setting Priorities
Expenditure categories
Salaries, Natural , Functional , Matrix
Justifications/ narrative
Summary
Negotiation 22<br>
slide23. Budget Expenditure Categories Salaries
Benefits (various lines)
Honorarium
Student assistants
Telephone
Postage
Subscriptions
Membership dues
Travel
Accreditation Entertainment
Professional development
Office supplies
Instructional supplies
Photocopying
Equipment repair, maintenance, & service contracts
Minor equipment
Contractual services
Housekeeping 23<br>
slide24. Increased Costs Benefits
Facilities & deferred maintenance
Technology & IT
Journals
Security 24<br>
slide25. Increased Costs Clinical Sites !!<br>
slide26. Budget Negotiation PREPARATION, PREPARATION, PREPARATION !!
Collection & lobbying are year-round activities
Frequent contact with the Dean
Be persistent not annoying
Review the presentation
Question your assumptions 26<br>
slide27. Budget Negotiation Respect the chain of command
Establish credibility with the Dean by avoiding budget “padding” and “wish lists”
Use institutional & industry benchmarks
Don’t be P in the A
Prioritize !! 27<br>
slide28. Budget Negotiation Have clear justifications & communication
Anticipate questions:
Why is an expense needed?
What are the consequences if not funded?
How will a new expense be funded?
What are the department’s contribution to the University?
Accreditation use this card wisely 28<br>
slide29. Budget Approval Process Program Director
Dean
VPAA/Provost
VP-Finance
President
Board of Trustees or Directors
State: Executive & legislative 29<br>
slide30. Budget Evaluation Performance/Variance reports
Evaluate minimally monthly
Explain variance & unexpected costs
Shift money if permitted
Adjust money or behavior
Use in developing next year’s request 30<br>
slide31. Budget Evaluation Monthly reports
Budgeted
YTD spent
YTD encumbered
Variance (favorable, unfavorable)
Available
Prior year closeout 31<br>
slide32. Potential Budgeting Problems Program Director ignores budget
All levels of organization not involved or invested in budget process
Continued unfavorable variances that remain uncorrected
Budget & financial managers that don’t understand the daily operations
Budget does not take into account macroeconomic issues 32<br>
slide33. Potential Budgeting Problems Program Director does not understand budget or how allowances were determined
No improvement action from process
Budget measures not reviewed or analyzed on a timely basis
Budget etched in stone 33<br>
slide34. Budget Games Cut everything by ___%
Padded budget
End of Budget Year syndrome
The President wants it
The ARC requires it
Do what you want
It’s not in the budget
It’s in their budget (ex. brochures) 34<br>
slide35. New Program 3-5 year cost & revenue budget
Start-up costs
Front load vs. incremental
Break even analysis 35<br>
slide36. Important Take-Aways Do not be afraid of budgeting
Always ask questions; do not assume!
Do not ignore the budget
Make friends with people in the financial offices at your university
Basic Finances 101 for managers in your institution<br>
slide37. Acknowledgements Special thanks to the following colleague for his contributions to this presentation:
Robert Philpot PhD, PA-C<br>
slide38. References College & University Budgeting: An Introduction for Faculty and Academic Administrators. Larry Goldstein. NACUBO
Budgets and Financial Management in Higher Education. Margaret J. Barr. George S. McClellan. 2011. Jossey-Bass 38<br>