
Financial Reporting and Regulation in a World of

Description: Financial Reporting and Regulation in a World of Financial Engineering: Accounting and the Global Financial Crisis Shyam Sunder, Yale University Journal of Accounting and Public Policy Conference on Accounting and the World Economic Crisis
Related Topics
Download Presentation
"Financial Reporting and Regulation in a World of" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Financial Reporting and Regulation in a World of Financial Engineering: Accounting and the Global Financial Crisis Shyam Sunder, Yale University
Journal of Accounting and Public Policy Conference on
Accounting and the World Economic Crisis
IE University, June 14, 2013
Segovia, Spain 1/18/2013 1 Sunder: Financial Regulation & Engineering<br>
slide2. An Overview Great efforts made to write effective regulatory standards—accounting as well as prudential—for financial services industry.
Events of the recent decade show that these efforts have largely failed to achieve their stated objectives, both globally as well as in major economies of the world.
Why?
What can be done? 1/18/2013 2 Sunder: Financial Regulation & Engineering<br>
slide3. Overview (Contd.) A root cause of these regulatory weaknesses and failures lies in inability of regulation to deal with the challenge presented by financial engineering.
Regulators, constrained by governments, business and profession, take years to write the rules and standards.
Their labor of love—carefully drafted regulations—is soon rendered ineffective when financial engineers and lawyers design of new instruments, transactions and organizations to bypass the regulations.
No amount of wisdom and hard work by regulators, whether located in Basel, Norwalk, or London, has or can overcome this disadvantage. 1/18/2013 3 Sunder: Financial Regulation & Engineering<br>
slide4. Overview (Contd.) Modern mathematical finance and financial engineering can bypass just about all written regulations without difficulty.
Written regulations, as an instrument of regulating financial services industry, do not work.
What are the alternatives, and their pros and cons?
No easy solutions. 1/18/2013 4 Sunder: Financial Regulation & Engineering<br>
slide5. Some Maintained Premises of Financial Reporting and Regulation 1/18/2013 5 Sunder: Financial Regulation & Engineering<br>
slide6. 1. Global Standards General standards of financial reporting and regulation applied across time, economies, industries and corporate size and organizational forms best serve the society (e.g., Basel, IFRS, FAS).
Standardization does save costs and effort, (electrical plugs, clothing, cars, street grids, commercial codes)
Becomes counterproductive beyond certain limits when environments to which they are applied are diverse
How do we know the limit of standardization?
Rhetoric of universal accounting standards and universal language (Esperanto?) 1/18/2013 6 Sunder: Financial Regulation & Engineering<br>
slide7. 2. Written Standards It is fair and efficient to write down the regulatory standards for everyone to know and comply with (e.g., the Code of Hamurabi).
Written standards promote our sense of fair play in a democratic society to avoid arbitrariness and partiality
But all contingencies cannot be anticipated and written down.
Written standards constrain discretion in enforcement
They also serve as “road maps for evasion” and gaming to take advantage of the rules 1/18/2013 7 Sunder: Financial Regulation & Engineering<br>
slide8. 3. Clear Standards Clear standards make it easier to know what is permitted and what is not permitted.
No standard can be made “perfectly clear”
No matter how much detail we put in the rules, there will always be demand for further clarification and “guidance”; rule books grow
Do additional details in standards reduce or increase the loopholes?
3 percent rule for Special Purpose Entities => Enron 1/18/2013 8 Sunder: Financial Regulation & Engineering<br>
slide9. 4. The Static Ideal There exists an ideal set of written reporting and regulatory standards that, once discovered and implemented, will induce corporations and banks to function efficiently in conformity with the regulations
Dynamics of the game between managers and standard setters makes any such static ideal all but impossible
Regulatees see standards as constraints and modify their decisions to seek their own goals 1/18/2013 9 Sunder: Financial Regulation & Engineering<br>
slide10. 5. People or Structure If we select knowledgeable, experienced, self-less, public-spirited, and wise individuals to constitute bodies that devise regulatory standards through deliberation and due process, we can improve the functioning of the economy.
Yes, but individuals stand where they sit.
We place much emphasis on the quality of individuals;
Insufficient attention given to the structure of game that regulators and regulatees play 1/18/2013 10 Sunder: Financial Regulation & Engineering<br>
slide11. 6. Crafting Standards through Deliberation It is possible to construct or discover better written regulatory standards through deliberation in properly organized corporate entities (Basel Committee, Federal Reserve, IASB, etc.).
Assumes that such bodies can know the consequences of their actions (Cartesian perspective on the problem)
Little evidence in history to support this proposition
Written standards by authoritative bodies have repeatedly failed to yield their stated outcomes (e.g., global financial crisis) 1/18/2013 11 Sunder: Financial Regulation & Engineering<br>
slide12. 7. Specialization in Setting Standards Specialist standard setting bodies, standing ready to address new problems, inquiries and requests for clarifications help improve regulation
Their existence encourages a new “clarification” game targeted at them
They must keep a full agenda (performance)
Revenue and budget pressures
Over time, their written output must accumulate to a thick rule book (e.g., Basel I, II, III; IFRS) 1/18/2013 12 Sunder: Financial Regulation & Engineering<br>
slide13. 8. Distinguishing Good from Bad? Standard setters can tell which written standards are better, and why; and what would happen if a rule were left unwritten
Little evidence that they know, or can know
For example, cost-of-capital is the result of complex interactions among many factors
These influences cannot be sorted out by ex ante analysis
Ex post analysis of data to assess the impact of regulatory standards is confounded with other factors which may have changed simultaneously (collinearity) 1/18/2013 13 Sunder: Financial Regulation & Engineering<br>
slide14. 9. Regulatory Monopolies Granting monopoly power in a given jurisdiction to standards written by a given body can help improve regulation
Informational disadvantage of a monopoly
No opportunity for experimentation
No opportunity to learn from the experience of alternatives; arrogance
No pressure to do better, or to correct errors
Pros and cons of regulatory competition 1/18/2013 14 Sunder: Financial Regulation & Engineering<br>
slide15. 11. Competition and Race to the Bottom A regime that encourages reporting entities to choose among the standards written by competing organizations (and paying them a royalty for the privilege) induces a “race to the bottom” to devise less demanding standards
Many counter examples (Stock exchanges, bond rating services, appliance standards, college accreditation, bank regulation, corporate charters across 50 states in U.S., etc.) 1/18/2013 15 Sunder: Financial Regulation & Engineering<br>
slide16. 12. Force and Effectiveness Increase in the power of enforcement behind authoritative standards improves compliance and quality of regulation and reporting
Increased enforcement also increases resources devoted to evasion
Draconian punishments do not necessarily induce better behavior
Crime, alcohol and drug abuse (recent report on failure of the War on Drugs)
Cutting hands of thieves may not be an efficient way to reduce theft 1/18/2013 16 Sunder: Financial Regulation & Engineering<br>
slide17. 13. Statutory Approach Dominates Common Law The quasi-statutory approach to setting regulatory standards (writing everything down) dominates a common law approach to financial reporting (leave significant parts unwritten, and subject to professional judgment)
Evidence?
Constitution (U.K., U.S., Singapore) 1/18/2013 17 Sunder: Financial Regulation & Engineering<br>
slide18. 14. Written Standards are Better than Social Norms Written standards backed by power of enforcement work better than unwritten social norms backed only by internal and external informal sanctions
Social norms govern great parts of our lives including many aspects of law
Insider trading example
Guilty beyond reasonable doubt
Private commercial codes (cotton, diamond trades in U.S.) 1/18/2013 18 Sunder: Financial Regulation & Engineering<br>
slide19. 15. Who defends the middle ground? The ideal regulatory regime consists of either all written standards or all social norms
Easier to make the extreme cases for standards or norms alone
Difficulty of defending the middle ground where both written and unwritten standards may co-exist, as they do in many other aspects of our lives 1/18/2013 19 Sunder: Financial Regulation & Engineering<br>
slide20. 16. Financial Regulation and Reporting is Improving 100 years of U.S. federal bank regulation and 80 years of federal regulation of securities and financial reporting has helped improve the quality of regulation.
Evidence?
Is a thicker rulebook indication of better regulation?
Perfect correlation between financial reports and stock returns?
How do we judge if regulations are getting better? 1/18/2013 20 Sunder: Financial Regulation & Engineering<br>
slide21. 17. Permitting Fewer Alternatives Yield Better Outcomes Fewer the alternatives permitted to the regulatees, the better the quality of regulation.
Fewer alternatives also tie the hands of the management of well-run companies who may wish to signal their confidence, competence and prospects by choosing reporting practices others find difficult to emulate.
Permitting fewer choices reduce information through signaling 1/18/2013 21 Sunder: Financial Regulation & Engineering<br>
slide22. 18. Monitor’s Bargaining Power Well-specified standards enhance the bargaining power of the monitor/auditor vis-à-vis the regulated organization
Standards also encourage regulatee to demand: show me the rule
Reduced reliance on judgment
More detailed the standards, greater the part of monitor’s work that can be replaced by a computer, and lower the value of the service 1/18/2013 22 Sunder: Financial Regulation & Engineering<br>
slide23. 19. Individual responsibility Written regulatory standards strengthen the individual responsibility of managers, regulators, auditors, and investment bankers for fair representation
On the contrary, they may undermine individual responsibility for fair representation and the big picture by shifting attention to meeting the letter, not spirit, of the specific provisions and their wording; check-box mentality 1/18/2013 23 Sunder: Financial Regulation & Engineering<br>
slide24. 20. Education Written standards help improve education and attract talent to the profession
Written standards degrade the class room from reasoning and intellectual debate to rote memorization
They make it less attractive to young talent 1/18/2013 24 Sunder: Financial Regulation & Engineering<br>
slide25. Emphasis on Written Regulations Reasonable arguments for written regulations
But also, reasonable limitations and criticisms of excessive dependence on written regulations
Examine some consequences of increasing dependence 1/18/2013 25 Sunder: Financial Regulation & Engineering<br>
slide26. Credit Rating Agency Reforms Efforts to reform credit agencies: require shift from issuer to investor pays model.
“Rocked by public and political distaste for the role they played in the global crisis, the big three credit rating agencies were expected to make profound changes—but efforts to reform have come unstuck.”
Stephen Foley in “Outlook Unchanged,” The Financial Times, p. 5, January 15, 2013 1/18/2013 26 Sunder: Financial Regulation & Engineering<br>
slide27. Taxation of Multinational Firms Tax rates of multinational have dropped in the recent decades far more than the drop in national tax rates.
“Governments want to close loopholes that help multinationals avoid tax but will have to balance any crackdown against their need to attract big foreign investors.”
Venessa Houlder, “Unsafe Offshore,” The Financial Times, p. 5, January 14, 2013. 1/18/2013 27 Sunder: Financial Regulation & Engineering<br>
slide28. Yen Libor Manipulation If you keep the six-month Japanese yen Libor unchanged for the day, “I’ll pay you $50,000, $100,000 …whatever you want …I’m a man of my word.” Hayes of UBS AG.
“I dun mind helping on your fixings, but I am not setting libor 7 points away from the truth (69 points). I’ll get UBS banned if I do that.” Darin
He submitted 67.
William D. Cohan, UBS Libor Manipulation Deserves the Death Penalty,” in Bloomberg News, December 23, 2012. 1/18/2013 28 Sunder: Financial Regulation & Engineering<br>
slide29. No Free Lunch in Bank Capital Regulation Basel II raised the bank capital requirement
Bank responded by getting their loans off their books through securitization so they will have to hold less capital (and earn a higher return on it)
“Capital regulation based on risk-weighted assets encourages innovation designed to circumvent regulatory requirements and shifts banks' focus away from their core economic functions.” "Systemically Important Banks and Capital Regulation Challenges". OECD Publishing. December 2011.
Banks misclassified the risk of their assets to avoid holding more capital 1/18/2013 29 Sunder: Financial Regulation & Engineering<br>
slide30. Basel II Bank Capital Regulation 2007: Capital was 11 percent of risk-weighted assets for 10 largest US banks
But if you excluded goodwill, intangibles and deferred tax assets (which tend to become worthless under financial stress), their capital was only 2.8 percent 1/18/2013 30 Sunder: Financial Regulation & Engineering<br>
slide31. How Does Basel III Address this Problem? More arcane and complex rules for calculating bank capital (opening more loopholes for financial engineering your way around the capital standards
Set the capital/asset requirement to 3 percent (about the same as the actual 2007 level) 1/18/2013 31 Sunder: Financial Regulation & Engineering<br>
slide32. Basel I, II, III, … and Counting “Each new Basel (bank capital) standard attempts to correct the errors and unintended consequences of earlier versions. But instead of resulting in better outcomes, each do-over has been more complicated and less effective than the last. Most disturbingly, each fails to provide enough real capital to absorb unexpected shocks to the economy.”
Thomas M. Hoenig (Vice-Chairman FDIC), “Get Basel III Right and Avoid Basel IV,” The Financial Times, December 12, 2012. 1/18/2013 32 Sunder: Financial Regulation & Engineering<br>
slide33. Consequences of Deposit Insurance Shifted the burden of ensuring bank capital adequacy to regulators from depositors
Regulators must have written rules to avoid appearing arbitrary or biased
Written rules also serve as “roadmaps for evasion”
Post-FDIC, depositor disinterest in monitoring cut bank capital from an average of 10 to about 3 percent (about 2 percent for some large EU banks)
Is it better to shift some (e.g., 50%) or all of the responsibility for monitoring banks back to depositors 1/18/2013 33 Sunder: Financial Regulation & Engineering<br>
slide34. Financial Engineering and Financial Regulation These are just a few examples of the conflict between financial regulation and financial engineering.
How long can the regulatory walls hold?
Basel I proposed in 1988, and lasted for 16 years
Basel II proposed in 2004 and lasted less than half-a-dozen years (until the financial crisis 2007-10)
Basel III proposed in 2010, and has already been hollowed under industry pressure by the end of 2012, even before its implementation began 1/18/2013 34 Sunder: Financial Regulation & Engineering<br>
slide35. Regulation as a Social Phenomenon Social phenomena exist macroeconomic, organizational, and individual levels
At each level, agents (individuals, organizations, and government):
Interact with one another,
Learn over time,
Resulting in feedback and endogeneity (X affects Y, as well as Y affects X)
I would like to discuss one aspect of such interactions between financial regulation and financial engineering, and its consequences 1/18/2013 35 Sunder: Financial Regulation & Engineering<br>
slide36. Why Regulation of Financial Services? Financial regulation is a form of regulation or supervision, which subjects financial institutions to certain requirements, restrictions and guidelines, aiming to maintain the integrity of the financial system:
to sustain systemic stability,
to maintain the safety and soundness of financial institutions, and
to protect the consumer. 1/18/2013 36 Sunder: Financial Regulation & Engineering<br>
slide37. Regulatory Performance Lindgren et al., 1996: In recent years, bank failures around the world have been common, large and expensive.
Llewellyn (1998a) concludes that three common elements emerge in banking crises: bad incentive structures, weak management and control systems within banks, and poor regulation, monitoring and supervision.
Why such poor performance?
Because of interplay with financial engineering 1/18/2013 37 Sunder: Financial Regulation & Engineering<br>
slide38. Objectives of Financial Engineering Objective in corporate financial engineering: to design transactions to optimize from the point of view of the organization, e.g., increase assessed creditworthiness and lower risk based on facts and appearances of its financial reports 1/18/2013 38 Sunder: Financial Regulation & Engineering<br>
slide39. Objectives in Financial Engineering “The Financial Engineering Concentration encompasses the design, analysis, and construction of financial contracts to meet the needs of enterprises.” (Cornell’s ORIE M.S. concentration in financial engineering)
What are these needs?
In at least some cases, these needs consist of finding ways of
Reducing indebtedness on the balance sheet, or
Reducing expense on income statement, or
Increasing revenue on income statement, or
Increasing deductions on tax returns 1/18/2013 39 Sunder: Financial Regulation & Engineering<br>
slide40. Securitization • A form of off-balance sheet financing which involves the pooling of financial assets
• Risk transfer mechanism that allows loan originators to optimize balance sheet management
• Allows highly rated securities to be created from less credit worthy assets
• Can be in local or foreign currency, depending on client needs
• A rapidly growing asset class with proven benefit for emerging market borrowers
• For summaries of prior deals, please visit www.ifc.org/structured finance
International Finance Corporation 1/18/2013 40 Sunder: Financial Regulation & Engineering<br>
slide41. What is Off-Balance Sheet Financing • Borrow money in such a way so under the regulatory standards, it does not show up as a liability on the balance sheet.
That is, find a way around written standards so an obligation to pay does not show up as a liability in the financial reports. 1/18/2013 41 Sunder: Financial Regulation & Engineering<br>
slide42. How and Why Do Loan Originators Optimize Balance Sheet Management • Loan originators (e.g., banks) are exposed to risk when they give loans
Inclusion of the loan in assets of the firm reflects this exposure to risk, and limits bank’s ability to make further loans under prudential regulation
By devising securitization so the risk exposure is reduced just below the written regulatory threshold, bank can exclude the asset from the balance sheet
This exclusion allows the bank to more more loans than prudential regulation would otherwise permit
This is the risk transfer mechanism that allows loan originators to optimize balance sheet management 1/18/2013 42 Sunder: Financial Regulation & Engineering<br>
slide43. Does Financial Engineering Create Value • Allows highly rated securities to be created from less credit worthy assets
•Payoffs of any asset can be partitioned into parts, some of which are more risky (and yield high return) and others are less risky and yield lower return
Can the sum of the values of these parts systematically exceed the value of the unpartitioned asset in absence of mis-information, mis-estimation, or extraneous cash consequences such as taxes? 1/18/2013 43 Sunder: Financial Regulation & Engineering<br>
slide44. Financial Regulatory Standards as Constraints on Financial Optimization In such optimization, standards of financial regulation are treated as constraints
Most optimization problems have hard constraints—their violation brings well-specified penalties (dual prices)
With optimization confined by the production possibilities set and other such physical limitations, external constraints make a real difference to the final actions and outcomes
What kind of constraints do standards offer?
I am going to argue that these standards offer softer constraints because the forms of contracts, transactions, as well as organizational forms that businessmen can devise and use are beyond the scope of accounting standards 1/18/2013 44 Sunder: Financial Regulation & Engineering<br>
slide45. Redesigning Contracts A manufacturer needs to buy a machine for the factory
Borrowing is an option, but the manufacturer does not want more debt on its balance sheet
The leasing subsidiary of a bank buys the machine and gives it to the manufacturer on a long term lease—machine is in the factory but no debt on balance sheet!
FASB writes Standard 13: leases >90%V and >75%T must be treated as capital leases (debt is back on BS)
The bank revises the lease to levels below the thresholds specified in the standard (debt is off the BS)
FASB goes back to work, and so on … until the leases rulebook grows to over a 1,000 pages with no end to this growth in sight 1/18/2013 45 Sunder: Financial Regulation & Engineering<br>
slide46. Redesigning Transactions Depending on the current standards of financial reporting, transactions can be redesigned to achieve the desired consequences for revenues, expenses and taxes 1/18/2013 46 Sunder: Financial Regulation & Engineering<br>
slide47. Redesigning the Organization When design of contracts and transactions is not sufficient, organizations themselves can be redesigned, or new ones created in order to have the desired consequences for balance sheets, income statements and tax returns
Special purpose entities (SPEs and SPVs) are examples of organizations created for this purpose (see Klee and Butler 2002 and Gorton and Souleles 2005)
“Hundreds of respected U.S. companies are ferreting away trillions of dollars in debt in off-balance sheet subsidiaries, partnerships, and assorted obligations” (Henry et al. 2002) 1/18/2013 47 Sunder: Financial Regulation & Engineering<br>
slide48. Asymmetric Game Note that financial reporting standards neither have, nor can have, any say in any of these “business” decisions of the management
The role of the accountant and auditor is limited to preparing financial reports given all these decisions
While these decisions clearly consider what the accounting standards are, accountants have little freedom to take into account how and why these decisions were taken in the first place
There is great asymmetry between the freedom available to the business decision makers and constraints on the accountant who must abide by relatively rigid written standards in deciding how to report the performance and financial status of an organization 1/18/2013 48 Sunder: Financial Regulation & Engineering<br>
slide49. The Net Effect The decision to write an accounting standard is a matter of social policy that calls for a deliberative due process; it typically takes years to determine which rules might best serve investors and others. Inevitably, these standards are written on the assumption that the current forms of contracts, transactions, and organizations will continue to be used in the future when these standards are applied
The decision to change contracts, transactions and organization is an individual decision that may be taken within days if not hours. Further, the scope of these decisions is virtually unbounded (except by the imagination of the businessmen). Soon after the standards are issued, the environment to which they are applied changes relative to the what the standards were written for
The net effect: Financial reporting standards serve as relatively weak constraints (if at all) on what businesses can do and on what they report (relative to their underlying economics) 1/18/2013 49 Sunder: Financial Regulation & Engineering<br>
slide50. Why Difficulty Writing Regulatory Standards for Derivatives? Some derivatives are designed to get around the intent (provision of information) of the extant financial reporting standards
How does one write standards for these instruments?
Is it possible to have an equilibrium between design of such instruments and standards for reporting them?
The problem seems to have gone largely unnoticed in the flurry of proposals on financial reforms now on the table
The question is: Are the optimization in financial engineering (relative to prevailing reporting standards), and search for standards that provide useful information to investors mutually consistent goals? 1/18/2013 50 Sunder: Financial Regulation & Engineering<br>
slide51. Standards and Language Standards of financial reporting and regulation must necessarily be specified in language
Language, in order to be useful, must necessarily have certain imprecision around the meaning of words
Can we specify precisely the meaning of a house, or shirt, or table? Instead reliance on usage—a matter of social norms
What happens if we try to do so?
Regulators have tried to counter financial engineering by resorting to the fiction that more precise definitions of words, e.g., assets, liabilities, income, regulatory capital, etc. will solve the problem
But they have not, and they cannot; bound to fail 1/18/2013 51 Sunder: Financial Regulation & Engineering<br>
slide52. A Newspaper Example (of Too-Big-to-Fail) Among a number of sensible amendments under development, Senator Sherrod Brown (D., OH) proposes the following language:
"LIMIT ON LIABILITIES FOR BANK HOLDING COMPANIES AND FINANCIAL COMPANIES.--No bank holding company may possess non-deposit liabilities exceeding 3 percent of the annual gross domestic product of the United States."
A few paragraphs later, the language considers derivatives:
"OFF-BALANCE-SHEET LIABILITIES.--The computation of the limit established under subsection (a) shall take into account off-balance-sheet liabilities." 1/18/2013 52 Sunder: Financial Regulation & Engineering<br>
slide53. Regulatory Language as a Constraint A strong provision for requiring prompt corrective action if any bank exceeds this hard size cap.
How many financial engineers and accountants think that this is a hard cap on size, or if it is a cap at all?
What will happen if this language became the law to cap the size of financial institutions? (independent of whether you think their size should be capped) 1/18/2013 53 Sunder: Financial Regulation & Engineering<br>
slide54. Yet the Debate Goes On Naturally, the Federal Reserve is pushing back.
The Fed's argument is that any kind of size limitation would be too blunt an instrument - successful regulation requires nuance and subtlety.
Perhaps, but there's a big problem with relying on subtle regulators. Over the past thirty years, almost all our regulators and supervisors have become either sleepy or captured - in a cognitive sense - by the very people they are supposed to be watching over. (Chapters 3 and 4 in 13 Bankers document this in detail) 1/18/2013 54 Sunder: Financial Regulation & Engineering<br>
slide55. These are Good Points, but Largely Irrelevant … Or just think about this. The New York Fed is run by a senior executive of Goldman Sachs. At the same time, the former head of the New York Fed holds a top position at Goldman - where he is responsible for interacting with regulators around the world. And the practices, if not the explicit rules, of the New York Fed apparently permit its board members to buy stock in companies that the Fed oversees. Please explain exactly how this web of arrangements will help keep regulation strong and effective moving forward.
The point is: Can regulatory and accounting rules written in English words serve as effective constraints on financial engineering?
My answer is no. I hope this is not true. 1/18/2013 55 Sunder: Financial Regulation & Engineering<br>
slide56. Social Norms of Accounting and Finance I personally doubt that a non-cooperative game between financial engineers and regulators has led us to a socially efficient outcome
Regulators have, over the past eight decades, increasingly come to rely on written rules as opposed to their judgment and social norms of their profession
Financial engineers, on the other hand consider it their own professional duty to design whatever instruments/transactions/organizations will best serve the immediate interests of their clients under the prevailing written standards of financial reporting
Social norms play a diminishing, if any, role on either side
Is it possible that some part of the blame for the systemic failures of the recent years may be linked to this diminishing role? 1/18/2013 56 Sunder: Financial Regulation & Engineering<br>
slide57. Ethics and Moral Code in Business Programs Shiller: “Many schools now offer a course in business ethics, and some even try to integrate business ethics into their other courses. But nowhere is ethics seen as the centerpiece or even integral part of the curriculum. And even when business students do take an ethics course, the theoretical framework of the core courses tends to be so devoid of any moral content that the discussion of ethics must seem like some side order of overcooked vegetable”.
If the role of ethics in curriculum is minimal, what is the role of ethics (i.e., social consequences of our work) in choosing the substantive topics of our research
Identifying mispricing of securities, for example, may help move prices to more efficient levels
What about identifying a way of redesigning a transaction so a financial obligation will not show up on the balance sheet under the prevailing regulatory standards? 1/18/2013 57 Sunder: Financial Regulation & Engineering<br>
slide58. In Summary With the development of mathematical finance, financial engineers rapidly redesign transactions, instruments, and business entities to render prudential and reporting regulation in the financial services ineffective.
This new reality has been a key element of the celebrated regulatory and reporting crises of the past dozen years.
Band-aid solutions for this new fundamental reality (such as Basel III and IFRS fair value accounting) have little prospect of success
What, if any thing, should we, and can we do about this?
Are there some alternatives to bringing in a sense of social responsibility for the consequences of our research agendas? If so, let us explore them. 1/18/2013 58 Sunder: Financial Regulation & Engineering<br>
slide59. Good Banking is Boring Our lives depend on efficient functioning of many systems (e.g., electrical wiring, plumbing, foundations of our buildings, telephones, and computer networks)
All such essential and critical systems are made efficient and routine to the point of being boring, low paying jobs, following pre-specified procedures and codes.
Innovations are slow, but made only after much experience and regulatory deliberation.
Excitement in such essential fields portends disaster (e.g., electrical wiring of Boeing 787 Dreamliner) 1/18/2013 59 Sunder: Financial Regulation & Engineering<br>
slide60. Creativity in Finance These consequences of financial engineering suggest that the social consequences of creativity in finance can be as socially detrimental as creativity in accounting
Objects of finance consist of (are defined) entirely by the relevant covenants and the accounting system
To the extent financial institutions have significant social externalities, and receive special support in form access to borrowing from the central banks
Their transactions have to confined to those conforming to a pre-approved template. 1/18/2013 60 Sunder: Financial Regulation & Engineering<br>
slide61. A Lesson from History Financial services became exciting and high-paying in the 1920s, and dropped to a low level after the great crash of 1929.
After half-a-century of excitement and high paying jobs and finance, we have seen another global crisis.
We need to assess the contribution of the new finance to GDP and social welfare, and assess if it is better to return it to a boring trade which is confined to a small set of pre-approved transactions.
Remuneration of people working in such an industry will return to low levels, but the rest of society may be safer and prosperous. 1/18/2013 61 Sunder: Financial Regulation & Engineering<br>
slide62. New Problems, New Solutions We may often assume that financial regulation and governance problems originated in the 20th century
History tells us otherwise 1/18/2013 62 Sunder: Financial Regulation & Engineering<br>
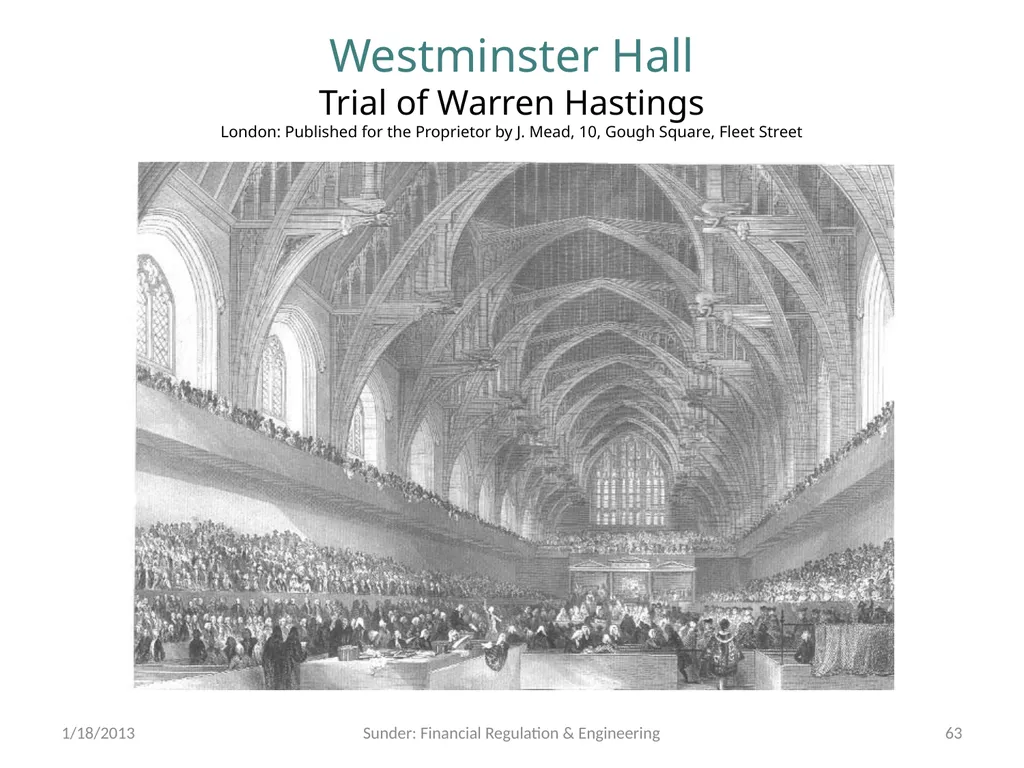
slide63. 1/18/2013 Westminster Hall
Trial of Warren Hastings
London: Published for the Proprietor by J. Mead, 10, Gough Square, Fleet Street 63 Sunder: Financial Regulation & Engineering<br>
slide64. Thank You. Shyam.sunder@yale.edu
www.som.yale.edu\faculty\sunder 1/18/2013 64 Sunder: Financial Regulation & Engineering<br>
slide65. References Hans J. Blommestein, “The Financial Crisis as a symbol of failure of academic finance (a methodological digression), The Journal of Financial Transformation, Fall 2009.
G. Gorton and N. Souleles, “Special Purpose Vehicles and Securitization,” FRB Philadelphia Working Paper, 2005.
Henry, David, Heather Timmons, Steve Rosenbush, and Michael Arndt (2002), “Who else is hiding debt?,” Business Week (January 28), 36-37.
J. Huber, M. Shubik, and S. Sunder, “Default penalty as disciplinary and selection mechanism in presence of multiple equilibria,” Cowles Foundation Working Paper 1730, October 2009.
K. Klee and B. Butler, “Asset-Backed Securitization, Special Purpose Vehicles
and Other Securitization Issues,” Uniform Commercial Code Law Journal 35 (2002), 23-67.
J. Mason, E. Higgins and A. Mordel, “Asset Sales, Recourse, and Investor Reactions to Initial Securitizations: Evidence Why Off-balance Sheet Accounting Treatment Does not Remove On-balance Sheet Financial Risk” LSU Working Paper, 2009.
Robert J. Shiller, “How Wall Street learns to look the other way,” The New York Times, Feb. 8, 2005.
Shyam Sunder. Theory of Accounting and Control. Southwestern Publishing, 1997.
Shyam Sunder, “Determinants of Economic Interaction: Behavior or Structure.” Journal of Economic Interaction and Coordination 1, no. 1 (May 2006): 21-32.
Shyam Sunder, “’True and Fair’ as the Moral Compass of Financial Reporting,” in Cynthia Jeffrey, ed., Research in Professional Responsibility and Ethics in Accounting (Forthcoming 2009). 1/18/2013 65 Sunder: Financial Regulation & Engineering<br>
Journal of Accounting and Public Policy Conference on
Accounting and the World Economic Crisis
IE University, June 14, 2013
Segovia, Spain 1/18/2013 1 Sunder: Financial Regulation & Engineering<br>
slide2. An Overview Great efforts made to write effective regulatory standards—accounting as well as prudential—for financial services industry.
Events of the recent decade show that these efforts have largely failed to achieve their stated objectives, both globally as well as in major economies of the world.
Why?
What can be done? 1/18/2013 2 Sunder: Financial Regulation & Engineering<br>
slide3. Overview (Contd.) A root cause of these regulatory weaknesses and failures lies in inability of regulation to deal with the challenge presented by financial engineering.
Regulators, constrained by governments, business and profession, take years to write the rules and standards.
Their labor of love—carefully drafted regulations—is soon rendered ineffective when financial engineers and lawyers design of new instruments, transactions and organizations to bypass the regulations.
No amount of wisdom and hard work by regulators, whether located in Basel, Norwalk, or London, has or can overcome this disadvantage. 1/18/2013 3 Sunder: Financial Regulation & Engineering<br>
slide4. Overview (Contd.) Modern mathematical finance and financial engineering can bypass just about all written regulations without difficulty.
Written regulations, as an instrument of regulating financial services industry, do not work.
What are the alternatives, and their pros and cons?
No easy solutions. 1/18/2013 4 Sunder: Financial Regulation & Engineering<br>
slide5. Some Maintained Premises of Financial Reporting and Regulation 1/18/2013 5 Sunder: Financial Regulation & Engineering<br>
slide6. 1. Global Standards General standards of financial reporting and regulation applied across time, economies, industries and corporate size and organizational forms best serve the society (e.g., Basel, IFRS, FAS).
Standardization does save costs and effort, (electrical plugs, clothing, cars, street grids, commercial codes)
Becomes counterproductive beyond certain limits when environments to which they are applied are diverse
How do we know the limit of standardization?
Rhetoric of universal accounting standards and universal language (Esperanto?) 1/18/2013 6 Sunder: Financial Regulation & Engineering<br>
slide7. 2. Written Standards It is fair and efficient to write down the regulatory standards for everyone to know and comply with (e.g., the Code of Hamurabi).
Written standards promote our sense of fair play in a democratic society to avoid arbitrariness and partiality
But all contingencies cannot be anticipated and written down.
Written standards constrain discretion in enforcement
They also serve as “road maps for evasion” and gaming to take advantage of the rules 1/18/2013 7 Sunder: Financial Regulation & Engineering<br>
slide8. 3. Clear Standards Clear standards make it easier to know what is permitted and what is not permitted.
No standard can be made “perfectly clear”
No matter how much detail we put in the rules, there will always be demand for further clarification and “guidance”; rule books grow
Do additional details in standards reduce or increase the loopholes?
3 percent rule for Special Purpose Entities => Enron 1/18/2013 8 Sunder: Financial Regulation & Engineering<br>
slide9. 4. The Static Ideal There exists an ideal set of written reporting and regulatory standards that, once discovered and implemented, will induce corporations and banks to function efficiently in conformity with the regulations
Dynamics of the game between managers and standard setters makes any such static ideal all but impossible
Regulatees see standards as constraints and modify their decisions to seek their own goals 1/18/2013 9 Sunder: Financial Regulation & Engineering<br>
slide10. 5. People or Structure If we select knowledgeable, experienced, self-less, public-spirited, and wise individuals to constitute bodies that devise regulatory standards through deliberation and due process, we can improve the functioning of the economy.
Yes, but individuals stand where they sit.
We place much emphasis on the quality of individuals;
Insufficient attention given to the structure of game that regulators and regulatees play 1/18/2013 10 Sunder: Financial Regulation & Engineering<br>
slide11. 6. Crafting Standards through Deliberation It is possible to construct or discover better written regulatory standards through deliberation in properly organized corporate entities (Basel Committee, Federal Reserve, IASB, etc.).
Assumes that such bodies can know the consequences of their actions (Cartesian perspective on the problem)
Little evidence in history to support this proposition
Written standards by authoritative bodies have repeatedly failed to yield their stated outcomes (e.g., global financial crisis) 1/18/2013 11 Sunder: Financial Regulation & Engineering<br>
slide12. 7. Specialization in Setting Standards Specialist standard setting bodies, standing ready to address new problems, inquiries and requests for clarifications help improve regulation
Their existence encourages a new “clarification” game targeted at them
They must keep a full agenda (performance)
Revenue and budget pressures
Over time, their written output must accumulate to a thick rule book (e.g., Basel I, II, III; IFRS) 1/18/2013 12 Sunder: Financial Regulation & Engineering<br>
slide13. 8. Distinguishing Good from Bad? Standard setters can tell which written standards are better, and why; and what would happen if a rule were left unwritten
Little evidence that they know, or can know
For example, cost-of-capital is the result of complex interactions among many factors
These influences cannot be sorted out by ex ante analysis
Ex post analysis of data to assess the impact of regulatory standards is confounded with other factors which may have changed simultaneously (collinearity) 1/18/2013 13 Sunder: Financial Regulation & Engineering<br>
slide14. 9. Regulatory Monopolies Granting monopoly power in a given jurisdiction to standards written by a given body can help improve regulation
Informational disadvantage of a monopoly
No opportunity for experimentation
No opportunity to learn from the experience of alternatives; arrogance
No pressure to do better, or to correct errors
Pros and cons of regulatory competition 1/18/2013 14 Sunder: Financial Regulation & Engineering<br>
slide15. 11. Competition and Race to the Bottom A regime that encourages reporting entities to choose among the standards written by competing organizations (and paying them a royalty for the privilege) induces a “race to the bottom” to devise less demanding standards
Many counter examples (Stock exchanges, bond rating services, appliance standards, college accreditation, bank regulation, corporate charters across 50 states in U.S., etc.) 1/18/2013 15 Sunder: Financial Regulation & Engineering<br>
slide16. 12. Force and Effectiveness Increase in the power of enforcement behind authoritative standards improves compliance and quality of regulation and reporting
Increased enforcement also increases resources devoted to evasion
Draconian punishments do not necessarily induce better behavior
Crime, alcohol and drug abuse (recent report on failure of the War on Drugs)
Cutting hands of thieves may not be an efficient way to reduce theft 1/18/2013 16 Sunder: Financial Regulation & Engineering<br>
slide17. 13. Statutory Approach Dominates Common Law The quasi-statutory approach to setting regulatory standards (writing everything down) dominates a common law approach to financial reporting (leave significant parts unwritten, and subject to professional judgment)
Evidence?
Constitution (U.K., U.S., Singapore) 1/18/2013 17 Sunder: Financial Regulation & Engineering<br>
slide18. 14. Written Standards are Better than Social Norms Written standards backed by power of enforcement work better than unwritten social norms backed only by internal and external informal sanctions
Social norms govern great parts of our lives including many aspects of law
Insider trading example
Guilty beyond reasonable doubt
Private commercial codes (cotton, diamond trades in U.S.) 1/18/2013 18 Sunder: Financial Regulation & Engineering<br>
slide19. 15. Who defends the middle ground? The ideal regulatory regime consists of either all written standards or all social norms
Easier to make the extreme cases for standards or norms alone
Difficulty of defending the middle ground where both written and unwritten standards may co-exist, as they do in many other aspects of our lives 1/18/2013 19 Sunder: Financial Regulation & Engineering<br>
slide20. 16. Financial Regulation and Reporting is Improving 100 years of U.S. federal bank regulation and 80 years of federal regulation of securities and financial reporting has helped improve the quality of regulation.
Evidence?
Is a thicker rulebook indication of better regulation?
Perfect correlation between financial reports and stock returns?
How do we judge if regulations are getting better? 1/18/2013 20 Sunder: Financial Regulation & Engineering<br>
slide21. 17. Permitting Fewer Alternatives Yield Better Outcomes Fewer the alternatives permitted to the regulatees, the better the quality of regulation.
Fewer alternatives also tie the hands of the management of well-run companies who may wish to signal their confidence, competence and prospects by choosing reporting practices others find difficult to emulate.
Permitting fewer choices reduce information through signaling 1/18/2013 21 Sunder: Financial Regulation & Engineering<br>
slide22. 18. Monitor’s Bargaining Power Well-specified standards enhance the bargaining power of the monitor/auditor vis-à-vis the regulated organization
Standards also encourage regulatee to demand: show me the rule
Reduced reliance on judgment
More detailed the standards, greater the part of monitor’s work that can be replaced by a computer, and lower the value of the service 1/18/2013 22 Sunder: Financial Regulation & Engineering<br>
slide23. 19. Individual responsibility Written regulatory standards strengthen the individual responsibility of managers, regulators, auditors, and investment bankers for fair representation
On the contrary, they may undermine individual responsibility for fair representation and the big picture by shifting attention to meeting the letter, not spirit, of the specific provisions and their wording; check-box mentality 1/18/2013 23 Sunder: Financial Regulation & Engineering<br>
slide24. 20. Education Written standards help improve education and attract talent to the profession
Written standards degrade the class room from reasoning and intellectual debate to rote memorization
They make it less attractive to young talent 1/18/2013 24 Sunder: Financial Regulation & Engineering<br>
slide25. Emphasis on Written Regulations Reasonable arguments for written regulations
But also, reasonable limitations and criticisms of excessive dependence on written regulations
Examine some consequences of increasing dependence 1/18/2013 25 Sunder: Financial Regulation & Engineering<br>
slide26. Credit Rating Agency Reforms Efforts to reform credit agencies: require shift from issuer to investor pays model.
“Rocked by public and political distaste for the role they played in the global crisis, the big three credit rating agencies were expected to make profound changes—but efforts to reform have come unstuck.”
Stephen Foley in “Outlook Unchanged,” The Financial Times, p. 5, January 15, 2013 1/18/2013 26 Sunder: Financial Regulation & Engineering<br>
slide27. Taxation of Multinational Firms Tax rates of multinational have dropped in the recent decades far more than the drop in national tax rates.
“Governments want to close loopholes that help multinationals avoid tax but will have to balance any crackdown against their need to attract big foreign investors.”
Venessa Houlder, “Unsafe Offshore,” The Financial Times, p. 5, January 14, 2013. 1/18/2013 27 Sunder: Financial Regulation & Engineering<br>
slide28. Yen Libor Manipulation If you keep the six-month Japanese yen Libor unchanged for the day, “I’ll pay you $50,000, $100,000 …whatever you want …I’m a man of my word.” Hayes of UBS AG.
“I dun mind helping on your fixings, but I am not setting libor 7 points away from the truth (69 points). I’ll get UBS banned if I do that.” Darin
He submitted 67.
William D. Cohan, UBS Libor Manipulation Deserves the Death Penalty,” in Bloomberg News, December 23, 2012. 1/18/2013 28 Sunder: Financial Regulation & Engineering<br>
slide29. No Free Lunch in Bank Capital Regulation Basel II raised the bank capital requirement
Bank responded by getting their loans off their books through securitization so they will have to hold less capital (and earn a higher return on it)
“Capital regulation based on risk-weighted assets encourages innovation designed to circumvent regulatory requirements and shifts banks' focus away from their core economic functions.” "Systemically Important Banks and Capital Regulation Challenges". OECD Publishing. December 2011.
Banks misclassified the risk of their assets to avoid holding more capital 1/18/2013 29 Sunder: Financial Regulation & Engineering<br>
slide30. Basel II Bank Capital Regulation 2007: Capital was 11 percent of risk-weighted assets for 10 largest US banks
But if you excluded goodwill, intangibles and deferred tax assets (which tend to become worthless under financial stress), their capital was only 2.8 percent 1/18/2013 30 Sunder: Financial Regulation & Engineering<br>
slide31. How Does Basel III Address this Problem? More arcane and complex rules for calculating bank capital (opening more loopholes for financial engineering your way around the capital standards
Set the capital/asset requirement to 3 percent (about the same as the actual 2007 level) 1/18/2013 31 Sunder: Financial Regulation & Engineering<br>
slide32. Basel I, II, III, … and Counting “Each new Basel (bank capital) standard attempts to correct the errors and unintended consequences of earlier versions. But instead of resulting in better outcomes, each do-over has been more complicated and less effective than the last. Most disturbingly, each fails to provide enough real capital to absorb unexpected shocks to the economy.”
Thomas M. Hoenig (Vice-Chairman FDIC), “Get Basel III Right and Avoid Basel IV,” The Financial Times, December 12, 2012. 1/18/2013 32 Sunder: Financial Regulation & Engineering<br>
slide33. Consequences of Deposit Insurance Shifted the burden of ensuring bank capital adequacy to regulators from depositors
Regulators must have written rules to avoid appearing arbitrary or biased
Written rules also serve as “roadmaps for evasion”
Post-FDIC, depositor disinterest in monitoring cut bank capital from an average of 10 to about 3 percent (about 2 percent for some large EU banks)
Is it better to shift some (e.g., 50%) or all of the responsibility for monitoring banks back to depositors 1/18/2013 33 Sunder: Financial Regulation & Engineering<br>
slide34. Financial Engineering and Financial Regulation These are just a few examples of the conflict between financial regulation and financial engineering.
How long can the regulatory walls hold?
Basel I proposed in 1988, and lasted for 16 years
Basel II proposed in 2004 and lasted less than half-a-dozen years (until the financial crisis 2007-10)
Basel III proposed in 2010, and has already been hollowed under industry pressure by the end of 2012, even before its implementation began 1/18/2013 34 Sunder: Financial Regulation & Engineering<br>
slide35. Regulation as a Social Phenomenon Social phenomena exist macroeconomic, organizational, and individual levels
At each level, agents (individuals, organizations, and government):
Interact with one another,
Learn over time,
Resulting in feedback and endogeneity (X affects Y, as well as Y affects X)
I would like to discuss one aspect of such interactions between financial regulation and financial engineering, and its consequences 1/18/2013 35 Sunder: Financial Regulation & Engineering<br>
slide36. Why Regulation of Financial Services? Financial regulation is a form of regulation or supervision, which subjects financial institutions to certain requirements, restrictions and guidelines, aiming to maintain the integrity of the financial system:
to sustain systemic stability,
to maintain the safety and soundness of financial institutions, and
to protect the consumer. 1/18/2013 36 Sunder: Financial Regulation & Engineering<br>
slide37. Regulatory Performance Lindgren et al., 1996: In recent years, bank failures around the world have been common, large and expensive.
Llewellyn (1998a) concludes that three common elements emerge in banking crises: bad incentive structures, weak management and control systems within banks, and poor regulation, monitoring and supervision.
Why such poor performance?
Because of interplay with financial engineering 1/18/2013 37 Sunder: Financial Regulation & Engineering<br>
slide38. Objectives of Financial Engineering Objective in corporate financial engineering: to design transactions to optimize from the point of view of the organization, e.g., increase assessed creditworthiness and lower risk based on facts and appearances of its financial reports 1/18/2013 38 Sunder: Financial Regulation & Engineering<br>
slide39. Objectives in Financial Engineering “The Financial Engineering Concentration encompasses the design, analysis, and construction of financial contracts to meet the needs of enterprises.” (Cornell’s ORIE M.S. concentration in financial engineering)
What are these needs?
In at least some cases, these needs consist of finding ways of
Reducing indebtedness on the balance sheet, or
Reducing expense on income statement, or
Increasing revenue on income statement, or
Increasing deductions on tax returns 1/18/2013 39 Sunder: Financial Regulation & Engineering<br>
slide40. Securitization • A form of off-balance sheet financing which involves the pooling of financial assets
• Risk transfer mechanism that allows loan originators to optimize balance sheet management
• Allows highly rated securities to be created from less credit worthy assets
• Can be in local or foreign currency, depending on client needs
• A rapidly growing asset class with proven benefit for emerging market borrowers
• For summaries of prior deals, please visit www.ifc.org/structured finance
International Finance Corporation 1/18/2013 40 Sunder: Financial Regulation & Engineering<br>
slide41. What is Off-Balance Sheet Financing • Borrow money in such a way so under the regulatory standards, it does not show up as a liability on the balance sheet.
That is, find a way around written standards so an obligation to pay does not show up as a liability in the financial reports. 1/18/2013 41 Sunder: Financial Regulation & Engineering<br>
slide42. How and Why Do Loan Originators Optimize Balance Sheet Management • Loan originators (e.g., banks) are exposed to risk when they give loans
Inclusion of the loan in assets of the firm reflects this exposure to risk, and limits bank’s ability to make further loans under prudential regulation
By devising securitization so the risk exposure is reduced just below the written regulatory threshold, bank can exclude the asset from the balance sheet
This exclusion allows the bank to more more loans than prudential regulation would otherwise permit
This is the risk transfer mechanism that allows loan originators to optimize balance sheet management 1/18/2013 42 Sunder: Financial Regulation & Engineering<br>
slide43. Does Financial Engineering Create Value • Allows highly rated securities to be created from less credit worthy assets
•Payoffs of any asset can be partitioned into parts, some of which are more risky (and yield high return) and others are less risky and yield lower return
Can the sum of the values of these parts systematically exceed the value of the unpartitioned asset in absence of mis-information, mis-estimation, or extraneous cash consequences such as taxes? 1/18/2013 43 Sunder: Financial Regulation & Engineering<br>
slide44. Financial Regulatory Standards as Constraints on Financial Optimization In such optimization, standards of financial regulation are treated as constraints
Most optimization problems have hard constraints—their violation brings well-specified penalties (dual prices)
With optimization confined by the production possibilities set and other such physical limitations, external constraints make a real difference to the final actions and outcomes
What kind of constraints do standards offer?
I am going to argue that these standards offer softer constraints because the forms of contracts, transactions, as well as organizational forms that businessmen can devise and use are beyond the scope of accounting standards 1/18/2013 44 Sunder: Financial Regulation & Engineering<br>
slide45. Redesigning Contracts A manufacturer needs to buy a machine for the factory
Borrowing is an option, but the manufacturer does not want more debt on its balance sheet
The leasing subsidiary of a bank buys the machine and gives it to the manufacturer on a long term lease—machine is in the factory but no debt on balance sheet!
FASB writes Standard 13: leases >90%V and >75%T must be treated as capital leases (debt is back on BS)
The bank revises the lease to levels below the thresholds specified in the standard (debt is off the BS)
FASB goes back to work, and so on … until the leases rulebook grows to over a 1,000 pages with no end to this growth in sight 1/18/2013 45 Sunder: Financial Regulation & Engineering<br>
slide46. Redesigning Transactions Depending on the current standards of financial reporting, transactions can be redesigned to achieve the desired consequences for revenues, expenses and taxes 1/18/2013 46 Sunder: Financial Regulation & Engineering<br>
slide47. Redesigning the Organization When design of contracts and transactions is not sufficient, organizations themselves can be redesigned, or new ones created in order to have the desired consequences for balance sheets, income statements and tax returns
Special purpose entities (SPEs and SPVs) are examples of organizations created for this purpose (see Klee and Butler 2002 and Gorton and Souleles 2005)
“Hundreds of respected U.S. companies are ferreting away trillions of dollars in debt in off-balance sheet subsidiaries, partnerships, and assorted obligations” (Henry et al. 2002) 1/18/2013 47 Sunder: Financial Regulation & Engineering<br>
slide48. Asymmetric Game Note that financial reporting standards neither have, nor can have, any say in any of these “business” decisions of the management
The role of the accountant and auditor is limited to preparing financial reports given all these decisions
While these decisions clearly consider what the accounting standards are, accountants have little freedom to take into account how and why these decisions were taken in the first place
There is great asymmetry between the freedom available to the business decision makers and constraints on the accountant who must abide by relatively rigid written standards in deciding how to report the performance and financial status of an organization 1/18/2013 48 Sunder: Financial Regulation & Engineering<br>
slide49. The Net Effect The decision to write an accounting standard is a matter of social policy that calls for a deliberative due process; it typically takes years to determine which rules might best serve investors and others. Inevitably, these standards are written on the assumption that the current forms of contracts, transactions, and organizations will continue to be used in the future when these standards are applied
The decision to change contracts, transactions and organization is an individual decision that may be taken within days if not hours. Further, the scope of these decisions is virtually unbounded (except by the imagination of the businessmen). Soon after the standards are issued, the environment to which they are applied changes relative to the what the standards were written for
The net effect: Financial reporting standards serve as relatively weak constraints (if at all) on what businesses can do and on what they report (relative to their underlying economics) 1/18/2013 49 Sunder: Financial Regulation & Engineering<br>
slide50. Why Difficulty Writing Regulatory Standards for Derivatives? Some derivatives are designed to get around the intent (provision of information) of the extant financial reporting standards
How does one write standards for these instruments?
Is it possible to have an equilibrium between design of such instruments and standards for reporting them?
The problem seems to have gone largely unnoticed in the flurry of proposals on financial reforms now on the table
The question is: Are the optimization in financial engineering (relative to prevailing reporting standards), and search for standards that provide useful information to investors mutually consistent goals? 1/18/2013 50 Sunder: Financial Regulation & Engineering<br>
slide51. Standards and Language Standards of financial reporting and regulation must necessarily be specified in language
Language, in order to be useful, must necessarily have certain imprecision around the meaning of words
Can we specify precisely the meaning of a house, or shirt, or table? Instead reliance on usage—a matter of social norms
What happens if we try to do so?
Regulators have tried to counter financial engineering by resorting to the fiction that more precise definitions of words, e.g., assets, liabilities, income, regulatory capital, etc. will solve the problem
But they have not, and they cannot; bound to fail 1/18/2013 51 Sunder: Financial Regulation & Engineering<br>
slide52. A Newspaper Example (of Too-Big-to-Fail) Among a number of sensible amendments under development, Senator Sherrod Brown (D., OH) proposes the following language:
"LIMIT ON LIABILITIES FOR BANK HOLDING COMPANIES AND FINANCIAL COMPANIES.--No bank holding company may possess non-deposit liabilities exceeding 3 percent of the annual gross domestic product of the United States."
A few paragraphs later, the language considers derivatives:
"OFF-BALANCE-SHEET LIABILITIES.--The computation of the limit established under subsection (a) shall take into account off-balance-sheet liabilities." 1/18/2013 52 Sunder: Financial Regulation & Engineering<br>
slide53. Regulatory Language as a Constraint A strong provision for requiring prompt corrective action if any bank exceeds this hard size cap.
How many financial engineers and accountants think that this is a hard cap on size, or if it is a cap at all?
What will happen if this language became the law to cap the size of financial institutions? (independent of whether you think their size should be capped) 1/18/2013 53 Sunder: Financial Regulation & Engineering<br>
slide54. Yet the Debate Goes On Naturally, the Federal Reserve is pushing back.
The Fed's argument is that any kind of size limitation would be too blunt an instrument - successful regulation requires nuance and subtlety.
Perhaps, but there's a big problem with relying on subtle regulators. Over the past thirty years, almost all our regulators and supervisors have become either sleepy or captured - in a cognitive sense - by the very people they are supposed to be watching over. (Chapters 3 and 4 in 13 Bankers document this in detail) 1/18/2013 54 Sunder: Financial Regulation & Engineering<br>
slide55. These are Good Points, but Largely Irrelevant … Or just think about this. The New York Fed is run by a senior executive of Goldman Sachs. At the same time, the former head of the New York Fed holds a top position at Goldman - where he is responsible for interacting with regulators around the world. And the practices, if not the explicit rules, of the New York Fed apparently permit its board members to buy stock in companies that the Fed oversees. Please explain exactly how this web of arrangements will help keep regulation strong and effective moving forward.
The point is: Can regulatory and accounting rules written in English words serve as effective constraints on financial engineering?
My answer is no. I hope this is not true. 1/18/2013 55 Sunder: Financial Regulation & Engineering<br>
slide56. Social Norms of Accounting and Finance I personally doubt that a non-cooperative game between financial engineers and regulators has led us to a socially efficient outcome
Regulators have, over the past eight decades, increasingly come to rely on written rules as opposed to their judgment and social norms of their profession
Financial engineers, on the other hand consider it their own professional duty to design whatever instruments/transactions/organizations will best serve the immediate interests of their clients under the prevailing written standards of financial reporting
Social norms play a diminishing, if any, role on either side
Is it possible that some part of the blame for the systemic failures of the recent years may be linked to this diminishing role? 1/18/2013 56 Sunder: Financial Regulation & Engineering<br>
slide57. Ethics and Moral Code in Business Programs Shiller: “Many schools now offer a course in business ethics, and some even try to integrate business ethics into their other courses. But nowhere is ethics seen as the centerpiece or even integral part of the curriculum. And even when business students do take an ethics course, the theoretical framework of the core courses tends to be so devoid of any moral content that the discussion of ethics must seem like some side order of overcooked vegetable”.
If the role of ethics in curriculum is minimal, what is the role of ethics (i.e., social consequences of our work) in choosing the substantive topics of our research
Identifying mispricing of securities, for example, may help move prices to more efficient levels
What about identifying a way of redesigning a transaction so a financial obligation will not show up on the balance sheet under the prevailing regulatory standards? 1/18/2013 57 Sunder: Financial Regulation & Engineering<br>
slide58. In Summary With the development of mathematical finance, financial engineers rapidly redesign transactions, instruments, and business entities to render prudential and reporting regulation in the financial services ineffective.
This new reality has been a key element of the celebrated regulatory and reporting crises of the past dozen years.
Band-aid solutions for this new fundamental reality (such as Basel III and IFRS fair value accounting) have little prospect of success
What, if any thing, should we, and can we do about this?
Are there some alternatives to bringing in a sense of social responsibility for the consequences of our research agendas? If so, let us explore them. 1/18/2013 58 Sunder: Financial Regulation & Engineering<br>
slide59. Good Banking is Boring Our lives depend on efficient functioning of many systems (e.g., electrical wiring, plumbing, foundations of our buildings, telephones, and computer networks)
All such essential and critical systems are made efficient and routine to the point of being boring, low paying jobs, following pre-specified procedures and codes.
Innovations are slow, but made only after much experience and regulatory deliberation.
Excitement in such essential fields portends disaster (e.g., electrical wiring of Boeing 787 Dreamliner) 1/18/2013 59 Sunder: Financial Regulation & Engineering<br>
slide60. Creativity in Finance These consequences of financial engineering suggest that the social consequences of creativity in finance can be as socially detrimental as creativity in accounting
Objects of finance consist of (are defined) entirely by the relevant covenants and the accounting system
To the extent financial institutions have significant social externalities, and receive special support in form access to borrowing from the central banks
Their transactions have to confined to those conforming to a pre-approved template. 1/18/2013 60 Sunder: Financial Regulation & Engineering<br>
slide61. A Lesson from History Financial services became exciting and high-paying in the 1920s, and dropped to a low level after the great crash of 1929.
After half-a-century of excitement and high paying jobs and finance, we have seen another global crisis.
We need to assess the contribution of the new finance to GDP and social welfare, and assess if it is better to return it to a boring trade which is confined to a small set of pre-approved transactions.
Remuneration of people working in such an industry will return to low levels, but the rest of society may be safer and prosperous. 1/18/2013 61 Sunder: Financial Regulation & Engineering<br>
slide62. New Problems, New Solutions We may often assume that financial regulation and governance problems originated in the 20th century
History tells us otherwise 1/18/2013 62 Sunder: Financial Regulation & Engineering<br>
slide63. 1/18/2013 Westminster Hall
Trial of Warren Hastings
London: Published for the Proprietor by J. Mead, 10, Gough Square, Fleet Street 63 Sunder: Financial Regulation & Engineering<br>
slide64. Thank You. Shyam.sunder@yale.edu
www.som.yale.edu\faculty\sunder 1/18/2013 64 Sunder: Financial Regulation & Engineering<br>
slide65. References Hans J. Blommestein, “The Financial Crisis as a symbol of failure of academic finance (a methodological digression), The Journal of Financial Transformation, Fall 2009.
G. Gorton and N. Souleles, “Special Purpose Vehicles and Securitization,” FRB Philadelphia Working Paper, 2005.
Henry, David, Heather Timmons, Steve Rosenbush, and Michael Arndt (2002), “Who else is hiding debt?,” Business Week (January 28), 36-37.
J. Huber, M. Shubik, and S. Sunder, “Default penalty as disciplinary and selection mechanism in presence of multiple equilibria,” Cowles Foundation Working Paper 1730, October 2009.
K. Klee and B. Butler, “Asset-Backed Securitization, Special Purpose Vehicles
and Other Securitization Issues,” Uniform Commercial Code Law Journal 35 (2002), 23-67.
J. Mason, E. Higgins and A. Mordel, “Asset Sales, Recourse, and Investor Reactions to Initial Securitizations: Evidence Why Off-balance Sheet Accounting Treatment Does not Remove On-balance Sheet Financial Risk” LSU Working Paper, 2009.
Robert J. Shiller, “How Wall Street learns to look the other way,” The New York Times, Feb. 8, 2005.
Shyam Sunder. Theory of Accounting and Control. Southwestern Publishing, 1997.
Shyam Sunder, “Determinants of Economic Interaction: Behavior or Structure.” Journal of Economic Interaction and Coordination 1, no. 1 (May 2006): 21-32.
Shyam Sunder, “’True and Fair’ as the Moral Compass of Financial Reporting,” in Cynthia Jeffrey, ed., Research in Professional Responsibility and Ethics in Accounting (Forthcoming 2009). 1/18/2013 65 Sunder: Financial Regulation & Engineering<br>