Fixed Assets Implementation Movable Equipment New Natural Accounts CapitalizationFinancial Reporting : Current vs. Proposed Process 1 The Purpose Implementing Oracle Fixed Assets to manage fixed assets and capitalization of capital
"Fixed Assets Implementation – Movable Equipment" is the property of its rightful owner. Permission is granted to
download and print the materials on this website for personal, non-commercial use only, and to display it
on your personal computer provided you do not modify the materials and that you retain all copyright
notices contained in the materials. By downloading content from our website, you accept the terms of this
agreement.
Presentation Transcript
01
Fixed Assets Implementation – Movable Equipment New Natural Accounts Capitalization/Financial Reporting :
Current vs. Proposed Process 1<br>
02
The Purpose Implementing Oracle Fixed Assets to manage fixed assets and capitalization of capital projects
We have analyzed the current process and are planning to implement improvements to the process for financial reporting and operation controls
Currently the Plant Funds team must look at every purchase to every account to determine whether to account for it as an asset or not
The new process will improve reporting controls between both general ledger and sub-ledger activities, support the units by providing more detailed financial data, improve the reporting on equipment for F&A where it is critical to know what costs are capitalized vs expensed.
Accounts will be organized better for capitalized ME (over $5,000) and for capital budgeting, know what costs are being capitalized (i.e. for F&A reasons), and will help PF team reconcile
Capital purchase definition = $5,000 or more, Rutgers owned, and has a future benefit of over 12 months
We have organized the accounts based on the capital asset categories which are sometimes required by external and internal reporting (Lab equipment vs. farm equipment), (IT equipment vs. medical equipment)
PF team will record which UDO owns each asset and reports will be available to units so that you can report on your assets
The new process will be implemented for FY2021 budget<br>
03
Current Process The current process for ME Capitalization:
Users in the field purchase items capitalized of nature to expense natural accounts 5/6XXXX.
Plant Funds then capitalizes ME by debiting the asset cost to Central’s balance sheet and by crediting natural account 67040 on a Central Finance UDO, with FT 900. This eliminates the expense at the university consolidated level
Initial natural account charged by department is not reduced - today it is too hard to eliminate by account, this is what we want to do going forward – we want to ensure the charge to the unit is the same account as the credit to Central
Currently true expenses are comingled with the capital costs and it is difficult to separate them
We will able to know what costs are expenses vs. what costs are capitalized<br>
04
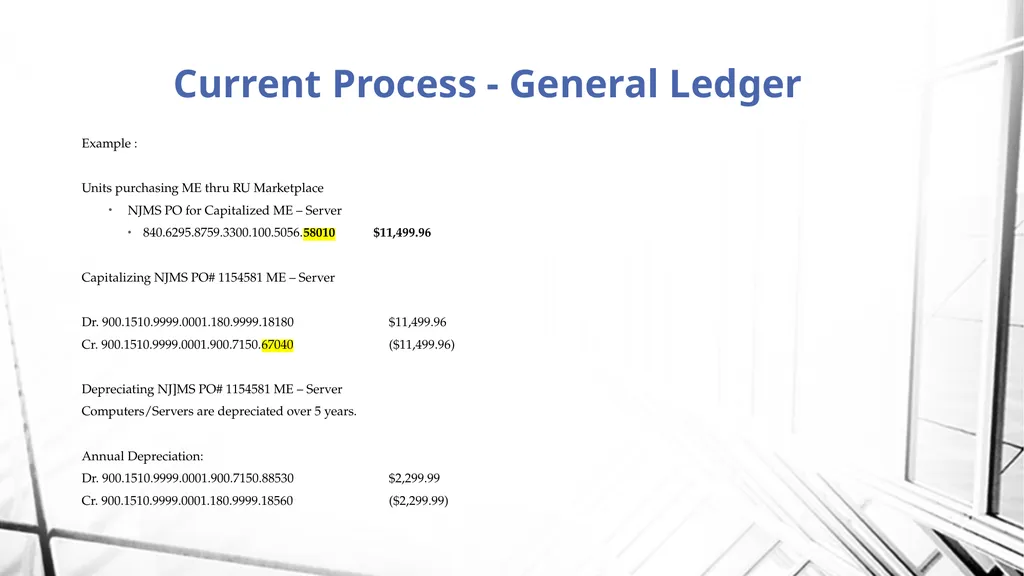
Current Process - General Ledger Example :
Units purchasing ME thru RU Marketplace
NJMS PO for Capitalized ME – Server
840.6295.8759.3300.100.5056.58010 $11,499.96
Capitalizing NJMS PO# 1154581 ME – Server
Dr. 900.1510.9999.0001.180.9999.18180 $11,499.96
Cr. 900.1510.9999.0001.900.7150.67040 ($11,499.96)
Depreciating NJ]MS PO# 1154581 ME – Server
Computers/Servers are depreciated over 5 years.
Annual Depreciation:
Dr. 900.1510.9999.0001.900.7150.88530 $2,299.99
Cr. 900.1510.9999.0001.180.9999.18560 ($2,299.99)<br>
05
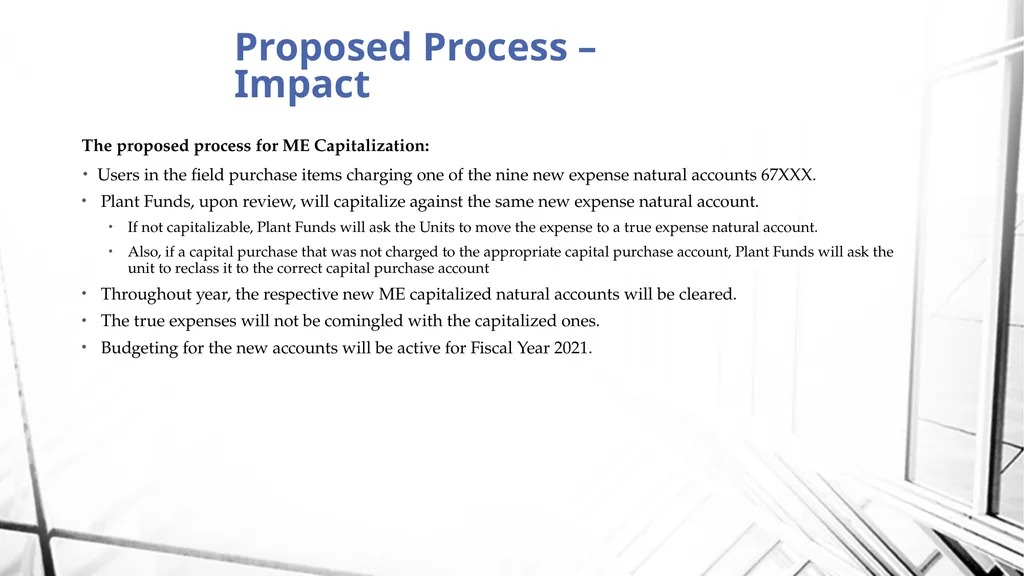
Proposed Process – Impact The proposed process for ME Capitalization:
Users in the field purchase items charging one of the nine new expense natural accounts 67XXX.
Plant Funds, upon review, will capitalize against the same new expense natural account.
If not capitalizable, Plant Funds will ask the Units to move the expense to a true expense natural account.
Also, if a capital purchase that was not charged to the appropriate capital purchase account, Plant Funds will ask the unit to reclass it to the correct capital purchase account
Throughout year, the respective new ME capitalized natural accounts will be cleared.
The true expenses will not be comingled with the capitalized ones.
Budgeting for the new accounts will be active for Fiscal Year 2021.<br>
06
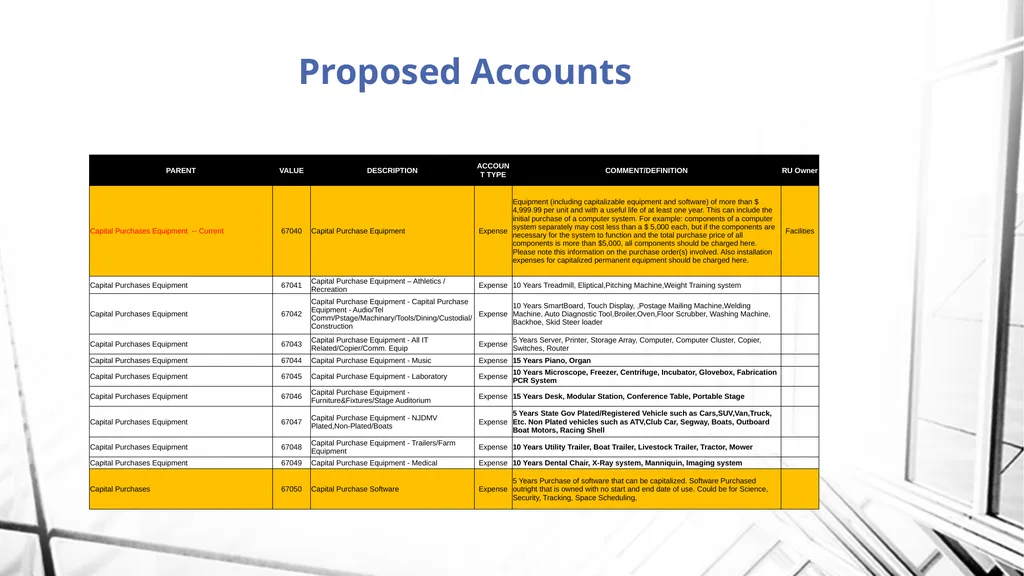
Proposed Accounts<br>
07
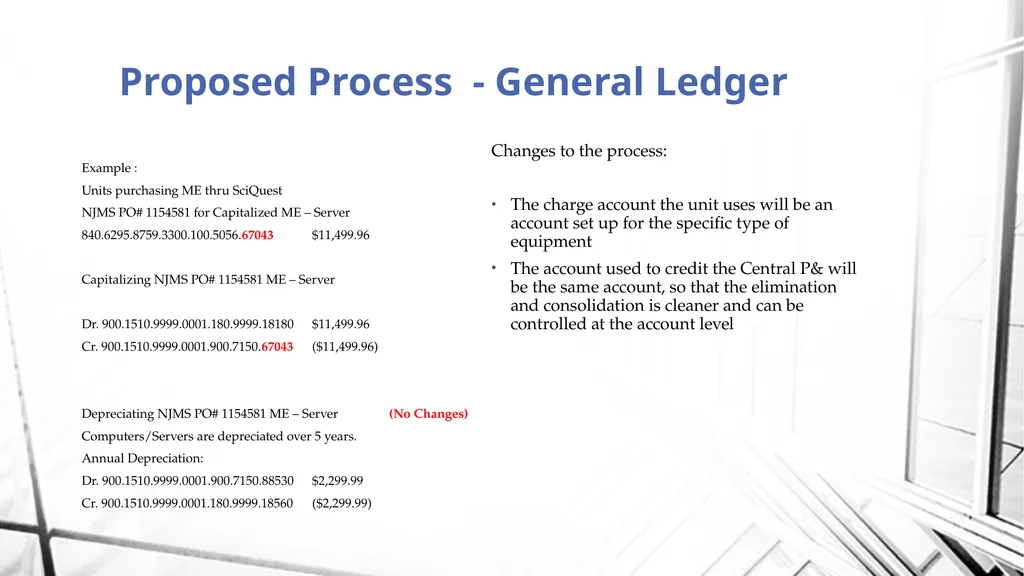
Proposed Process - General Ledger Example :
Units purchasing ME thru SciQuest
NJMS PO# 1154581 for Capitalized ME – Server
840.6295.8759.3300.100.5056.67043 $11,499.96
Capitalizing NJMS PO# 1154581 ME – Server
Dr. 900.1510.9999.0001.180.9999.18180 $11,499.96
Cr. 900.1510.9999.0001.900.7150.67043 ($11,499.96)
Depreciating NJMS PO# 1154581 ME – Server (No Changes)
Computers/Servers are depreciated over 5 years.
Annual Depreciation:
Dr. 900.1510.9999.0001.900.7150.88530 $2,299.99
Cr. 900.1510.9999.0001.180.9999.18560 ($2,299.99) Changes to the process:
The charge account the unit uses will be an account set up for the specific type of equipment
The account used to credit the Central P& will be the same account, so that the elimination and consolidation is cleaner and can be controlled at the account level<br>
08
New Process Benefits Operation Controls, SL to GL Reconciliation, Financial Reporting:
Consistent approach as reporting on Capital Projects CIP natural accounts.
GL reporting is much cleaner not comingling true expense with the capitalized ones.
Units are able to immediately identify their capital expenditures without running other shadow systems for analysis. Now they can benchmark better budget versus actual monthly based on GL activities.
Units still being charged upfront for their ME capital expenditures under “Operating Expenses”.
New Fixed Assets module will be synchronized and reconciled with general ledger. Categories are mirrored between sub-ledger and general ledger enabling for better controls and efficiencies.
Year end accruals will be charged to a separate account, keeping FA Sub-Ledger matching to GL at all times.
Property Management – efficiently reducing time spent searching for equipment to be capitalized.
Facilities &Administration (F&A) rate calculation will be more efficient for the equipment part now that we separated true expense from the capitalized ones.
The monthly additions can also be tracked to the asset cost account on Central linked to the corresponding P&L account
Units can also know their real capital purchases vs. their expense by running reports / queries by accounts, and will also be able to see their actual assets going forward<br>
09
Next Steps New accounts will be in production on or about January 1st, at which point can be used for actuals but not required
Spread 2021 budget to the new accounts according to the budget dates from the budget office
Start using new accounts for actuals starting on July 1, at which point all capital purchases must go to the new accounts and you will need to reclass if coded incorrectly
Look for communications coming out between now and July 1 to keep everyone informed
Training and/or instructional events are also being planned – to be discussed<br>