
FY 2021-2022 MID-TERM REPORT Audit Committee
AM
Published · 22 slides · 0 views

1 / 1

Description
FY 2021-2022 MID-TERM REPORT Audit Committee Activities 1 Art Edwards Audit Committee Chairman April 27, 2022 FY 2021-22 MID-TERM REPORT SBBC Financial Oversight Audit Committee Members Reporting Structure External Auditors Internal
Related Topics
Share
Embed code
Download this presentation From Below
"FY 2021-2022 MID-TERM REPORT Audit Committee" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
FY 2021-2022 MID-TERM REPORT Audit Committee Activities 1 Art Edwards
Audit Committee Chairman
April 27, 2022<br>
Audit Committee Chairman
April 27, 2022<br>
02
FY 2021-22 MID-TERM REPORT SBBC Financial Oversight
Audit Committee Members
Reporting Structure
External Auditors
Internal Auditors
Internal Audit Implementation
Internal Audit Universe
Internal Audit Focus
2021 Highlights - Internal Audits Completed
2022 Internal Audit Objectives
Corrective Actions & Remediation Status
Audit Committee Goals & Highlights 2<br>
03
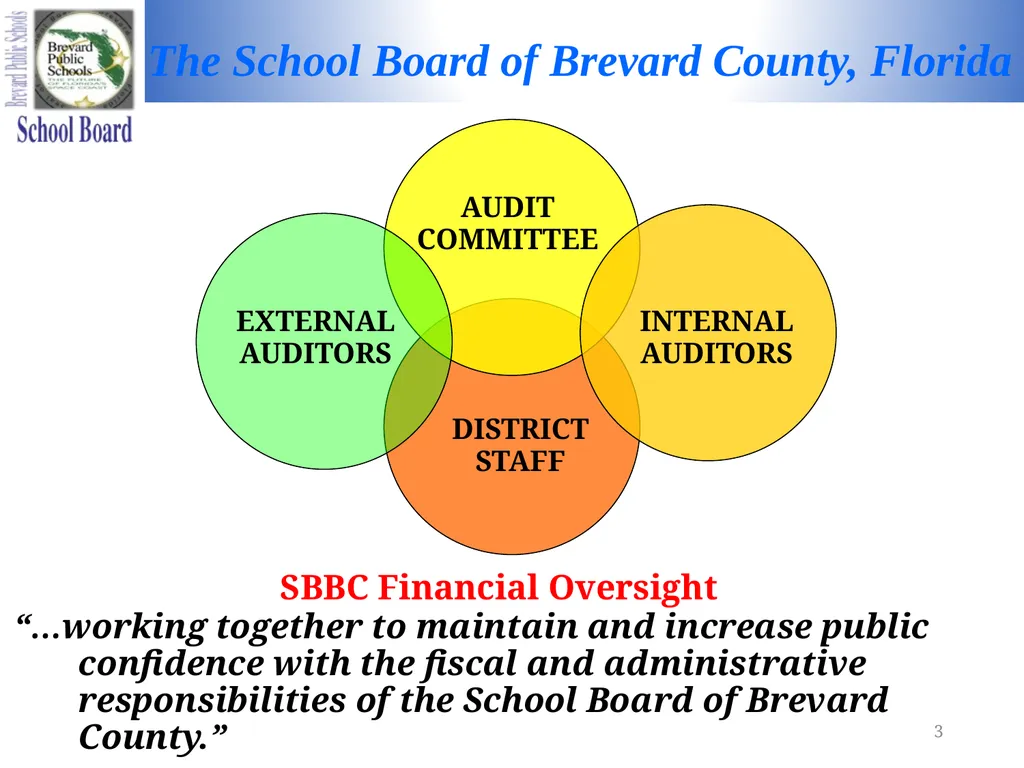
DISTRICT
STAFF AUDIT
COMMITTEE INTERNAL
AUDITORS SBBC Financial Oversight
“…working together to maintain and increase public confidence with the fiscal and administrative responsibilities of the School Board of Brevard County.” EXTERNAL
AUDITORS 3<br>
STAFF AUDIT
COMMITTEE INTERNAL
AUDITORS SBBC Financial Oversight
“…working together to maintain and increase public confidence with the fiscal and administrative responsibilities of the School Board of Brevard County.” EXTERNAL
AUDITORS 3<br>
04
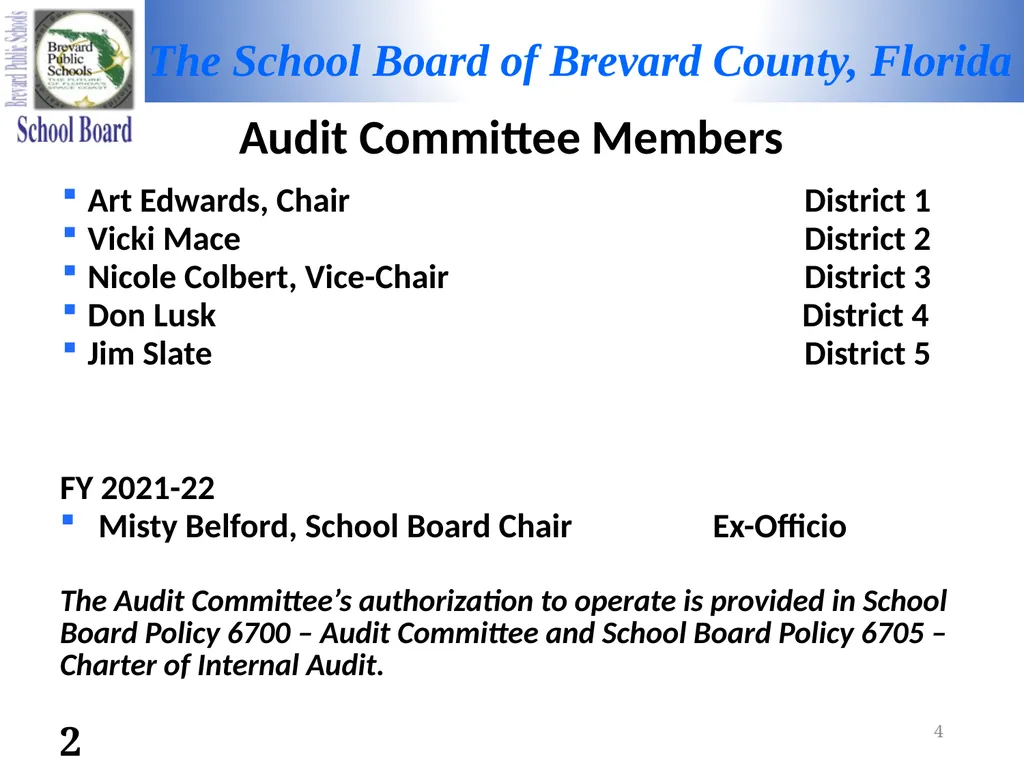
Audit Committee Members Art Edwards, Chair District 1
Vicki Mace District 2
Nicole Colbert, Vice-Chair District 3
Don Lusk District 4
Jim Slate District 5 4 FY 2021-22
Misty Belford, School Board Chair Ex-Officio
The Audit Committee’s authorization to operate is provided in School Board Policy 6700 – Audit Committee and School Board Policy 6705 – Charter of Internal Audit.
2<br>
05
Audit Committee Members Art Edwards, Chairman – Retired Aerospace Corporate Safety Manager. Background includes Engineering, Construction-General Contractor, Project Management and Safety. Presently, Senior Partner in a Safety Consulting firm and President/CEO Edwards Media Group. Committee member for over 13 years.
Don Lusk – Retired County administrator with 30+ years of local government experience. Certified Workforce Development Professional. Presently, Senior Policy and Program Officer with local non-profit workforce investment agency. Background includes Health & Human Services, Public Safety, Emergency Management and Community Service programs. Committee member for 8 years.
Nicole Colbert, Vice Chairman – Controller with 15+ years of experience in public/private industry accounting. Working in construction and development, has supervised jobs from high-tech industrial manufacturing facilities to restaurant build-outs, with her primary focus being financial advisory and construction/real estate development. Committee member for 4 years.
Vicki Mace – Retired educator with over 30 years of experience with BPS. Extensive experience with charter school law, evaluation and oversight as well as leadership, strategic planning, and operations expertise. Serves as a consultant to other school districts on charter school processes. Committee member since April 2020.
Jim Slate – Accounting/Finance professional with 40 years experience, including Internal Audit and Compliance. Certified Public Accountant in the State of Florida. Committee member since December 2019. 5 The School Board of Brevard County, Florida<br>
06
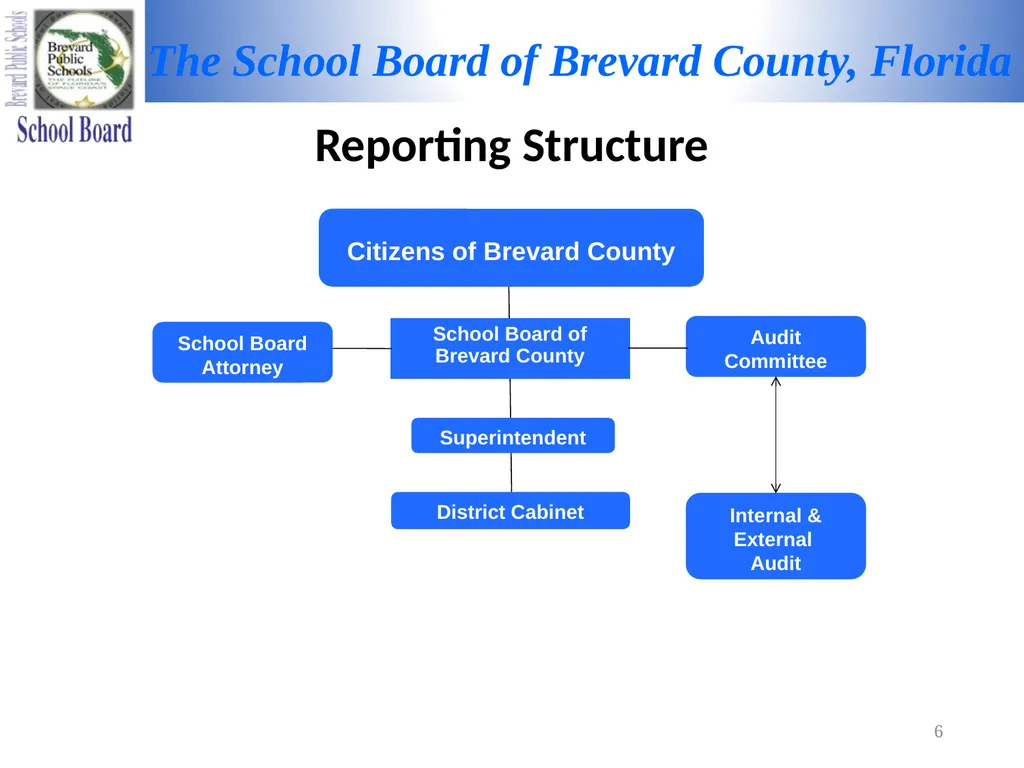
Reporting Structure School Board of Brevard County 6 Citizens of Brevard County Superintendent District Cabinet Audit Committee Internal &
External
Audit School Board Attorney<br>
External
Audit School Board Attorney<br>
07
7 External Auditors In 2014, the Audit Committee’s recommendation to the School Board for Moore Stephens Lovelace, (MSL) P.A. to be selected as the District’s external auditor was the culmination of an extensive RFP process.
MSL performed superbly on the base three-year contract and as a results MSL was awarded four optional one-year extensions.
The Florida Auditor General (AG) is responsible for performing an external audit every three years. The most recent AG audit was for FY2019.
Based on a 2016 recommendation from the Audit Committee, the BPS Board has exercised one-year options to engage MSL to work with the Auditor General in conjunction with the AG 3-year Audits. This arrangement has proven to be beneficial to both BPS and the Auditor General.
External Audits have been thorough and timely. MSL provided the District with an unqualified ( “clean”) audit opinion for the 2021 fiscal year. Audit Committee members completed a fraud awareness questionnaire as part of the Internal Audit process.<br>
08
Internal Auditors In 2018, the Audit Committee recommended to the School Board that RSM US LLP be selected as the District’s internal auditor. The recommendation was the culmination of an extensive RFP process.
A three-year contract was awarded with three optional one-year extensions based on the recommendation of the Audit Committee.
Because of RSM’s sustained outstanding performance, in July 2021 the Audit Committee recommended execution of the first year of the three one-year options (of the 2018 contract).
The Internal Audit services contract for Fiscal year 2021-22 was approved by the BPS Board for $199,500. The Internal Accounts services contract was approved for $116,625.00.
The Internal Auditors have historically met all Audit Committee requests with no budget changes.
The Internal Auditors provide regular reporting at quarterly Audit Committee meetings. The Internal Auditors also provide timely response to special requests for audits.. 8<br>
09
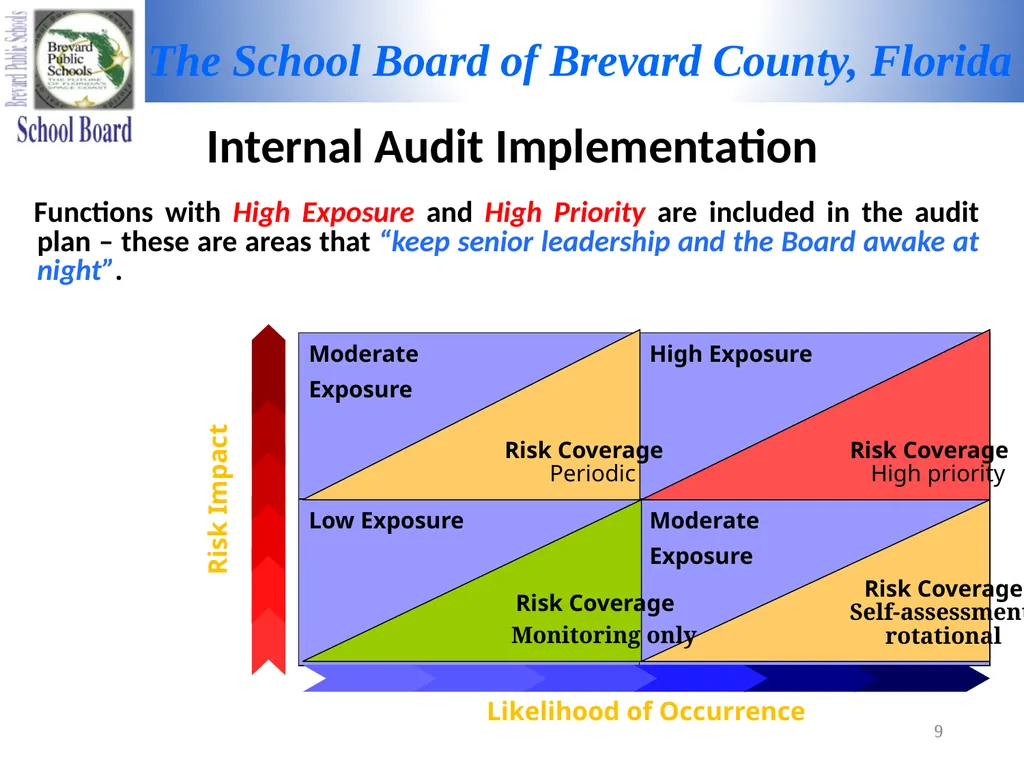
Internal Audit Implementation Functions with High Exposure and High Priority are included in the audit plan – these are areas that “keep senior leadership and the Board awake at night”. 9<br>
10
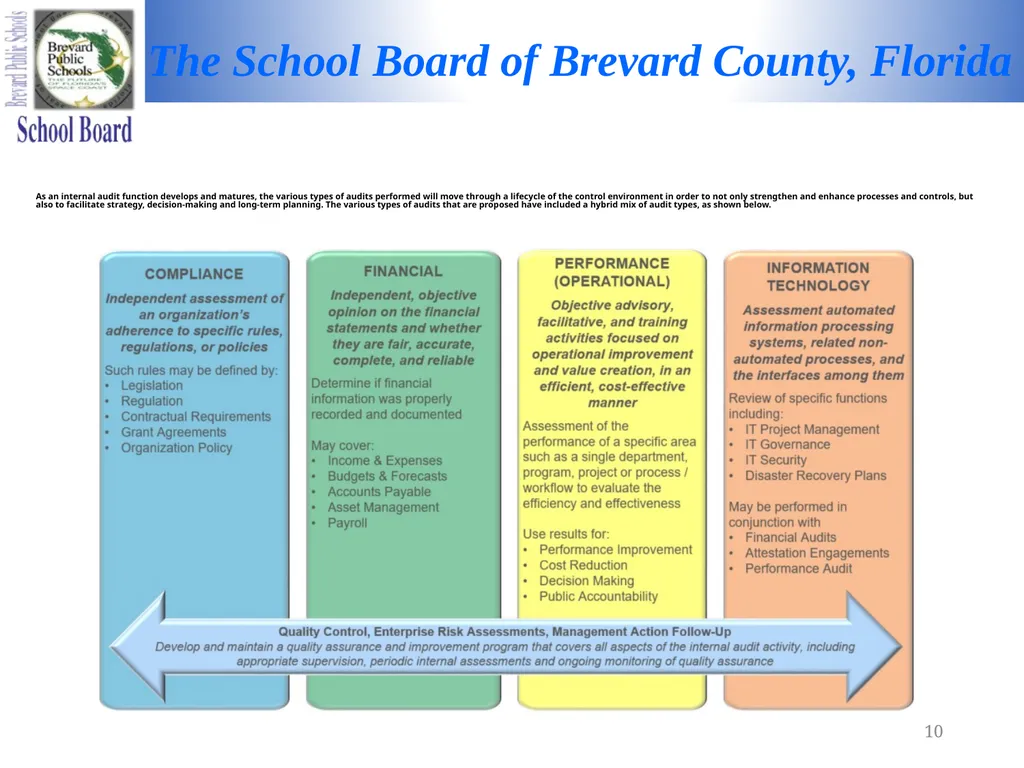
As an internal audit function develops and matures, the various types of audits performed will move through a lifecycle of the control environment in order to not only strengthen and enhance processes and controls, but also to facilitate strategy, decision-making and long-term planning. The various types of audits that are proposed have included a hybrid mix of audit types, as shown below. 10<br>
11
Internal Audit Universe See handout 11<br>
12
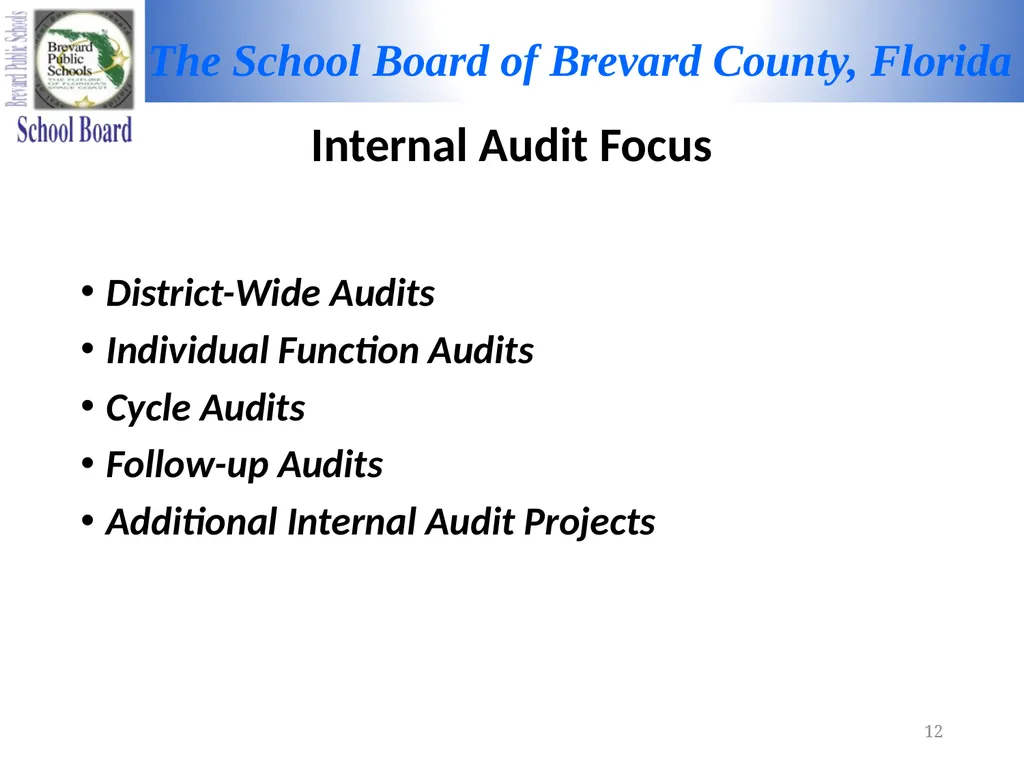
Internal Audit Focus District-Wide Audits
Individual Function Audits
Cycle Audits
Follow-up Audits
Additional Internal Audit Projects 12<br>
Individual Function Audits
Cycle Audits
Follow-up Audits
Additional Internal Audit Projects 12<br>
13
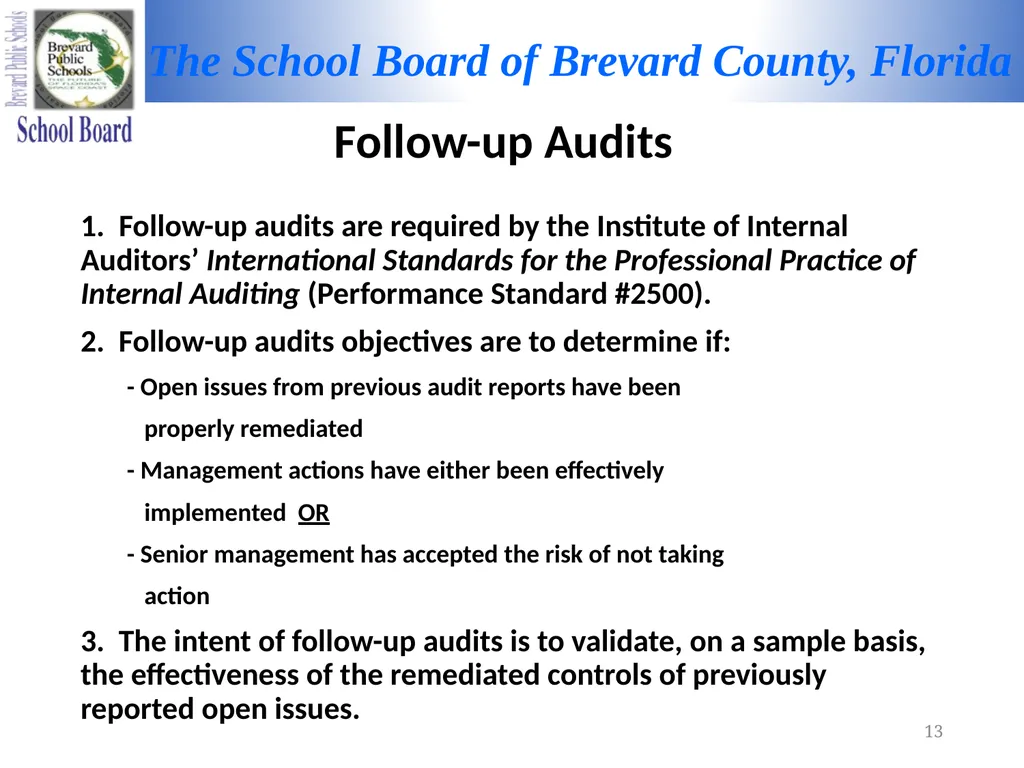
Follow-up Audits 1. Follow-up audits are required by the Institute of Internal Auditors’ International Standards for the Professional Practice of Internal Auditing (Performance Standard #2500).
2. Follow-up audits objectives are to determine if:
- Open issues from previous audit reports have been
properly remediated
- Management actions have either been effectively
implemented OR
- Senior management has accepted the risk of not taking
action
3. The intent of follow-up audits is to validate, on a sample basis, the effectiveness of the remediated controls of previously reported open issues. 13<br>
14
District-Wide Audits 1. District-wide audits address processes and/or functions that:
- Touch all District departments or
- Touch most departments within the District
2. District-wide audits are designed to gain economies of scale by:
- Taking a District-wide view
- Evaluating the implementation of policies, procedures, and
standards as well as Best Practices across the District as a
whole
For Example: A district-wide audit of Purchasing Cards will focus on the overall process for the District, including Purchasing Cards issued to schools and departments. 14<br>
15
Individual Function Audits 1. Individual Function audits focus on unique scenarios or processes within a specific department.
2. Individual Function audits may also focus on unique scenarios or processes within several departments (but not target all departments in the District).
For example: A Purchasing Card audit of Food Services would focus on the risks and controls for transactions related only to Food Services. 15<br>
16
Cycle Audits 1. Cycle audits are narrower in scope than District-wide and Individual Function audits.
2. The scope of a Cycle audit will be very specific to inherently high-risk, decentralized functions and processes.
3. Generally, Cycle audits provide testing and reassurance that:
- Policies and procedures are being followed within different departments.
- Controls continue to be effective once it has been determined that they have been appropriately designed and implemented.
For example: Property Control 16<br>
17
Additional Internal Audit Projects 1. Internal Audit Projects focuses internal audit resources on areas or functions that are (1) high exposure and (2) high priority based on Risk Ranking.
2. Internal Audit Projects address situations/potential situations (outside of the existing audit plan) that the Board, Audit Committee or Management may become aware of.
3. Internal Audit Special Projects and Requests are generally specifically defined and narrowly focused.
For example: 2011 Maintenance Department Allegations; 2019 Legacy Academy Closeout; 2020 Health Care & Wellness Analysis; 2020 Adult & Community Education Operations 17<br>
18
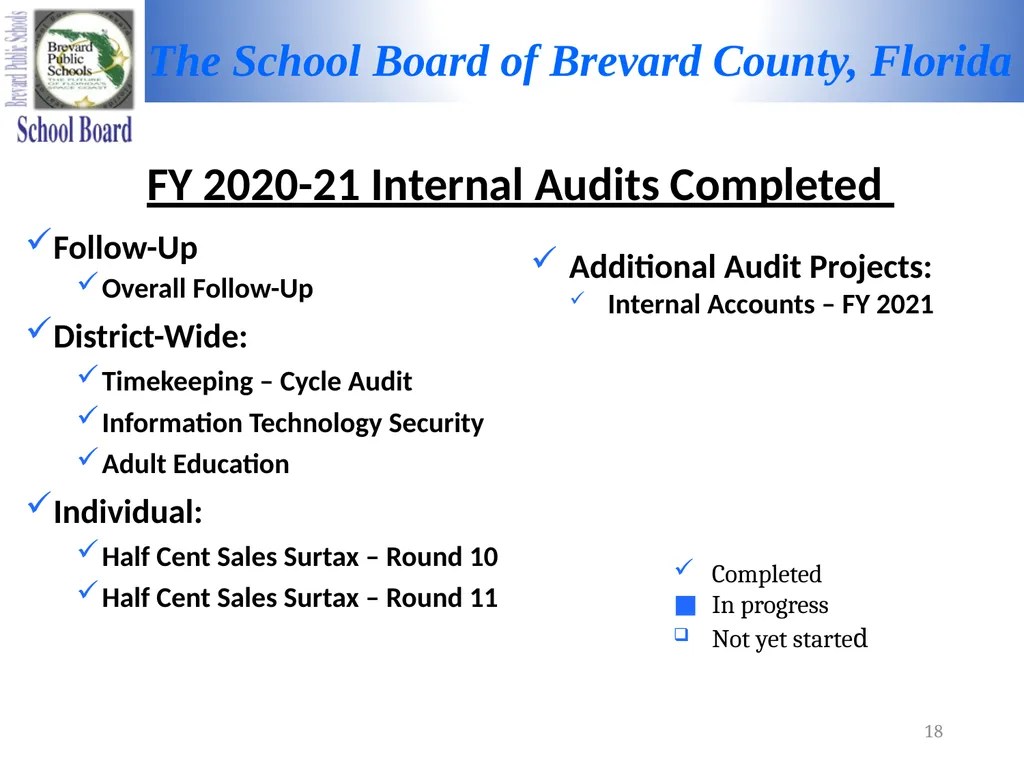
18 FY 2020-21 Internal Audits Completed Follow-Up
Overall Follow-Up
District-Wide:
Timekeeping – Cycle Audit
Information Technology Security
Adult Education
Individual:
Half Cent Sales Surtax – Round 10
Half Cent Sales Surtax – Round 11 Additional Audit Projects:
Internal Accounts – FY 2021 Completed
In progress
Not yet started<br>
Overall Follow-Up
District-Wide:
Timekeeping – Cycle Audit
Information Technology Security
Adult Education
Individual:
Half Cent Sales Surtax – Round 10
Half Cent Sales Surtax – Round 11 Additional Audit Projects:
Internal Accounts – FY 2021 Completed
In progress
Not yet started<br>
19
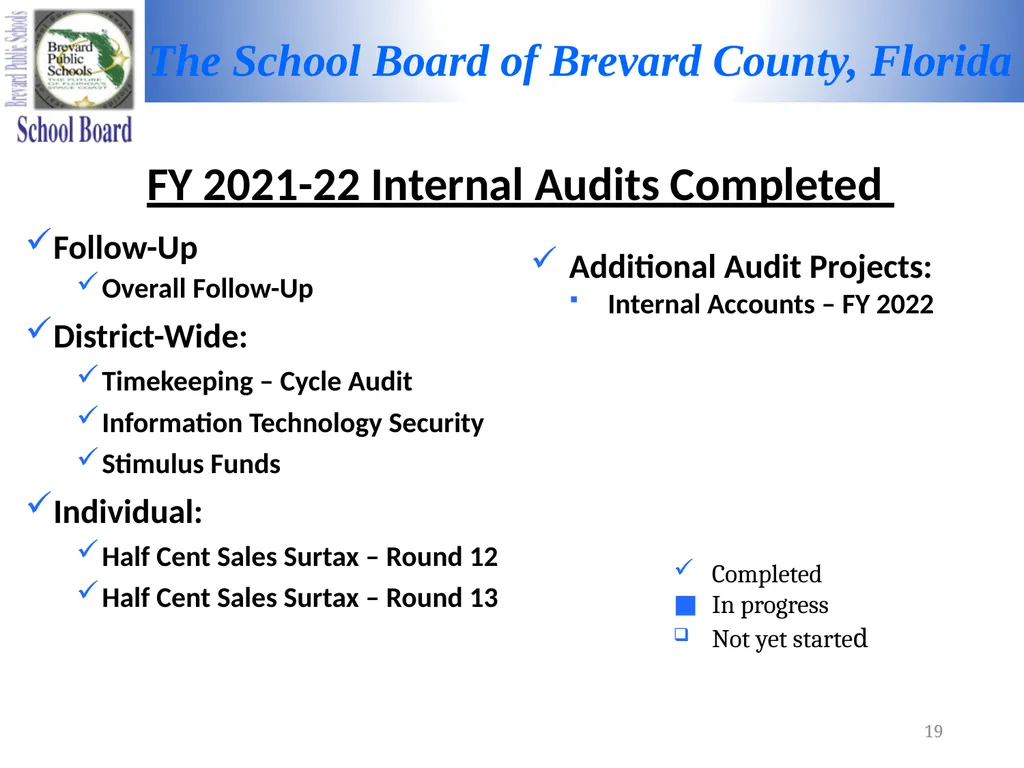
19 FY 2021-22 Internal Audits Completed Follow-Up
Overall Follow-Up
District-Wide:
Timekeeping – Cycle Audit
Information Technology Security
Stimulus Funds
Individual:
Half Cent Sales Surtax – Round 12
Half Cent Sales Surtax – Round 13 Additional Audit Projects:
Internal Accounts – FY 2022 Completed
In progress
Not yet started<br>
Overall Follow-Up
District-Wide:
Timekeeping – Cycle Audit
Information Technology Security
Stimulus Funds
Individual:
Half Cent Sales Surtax – Round 12
Half Cent Sales Surtax – Round 13 Additional Audit Projects:
Internal Accounts – FY 2022 Completed
In progress
Not yet started<br>
20
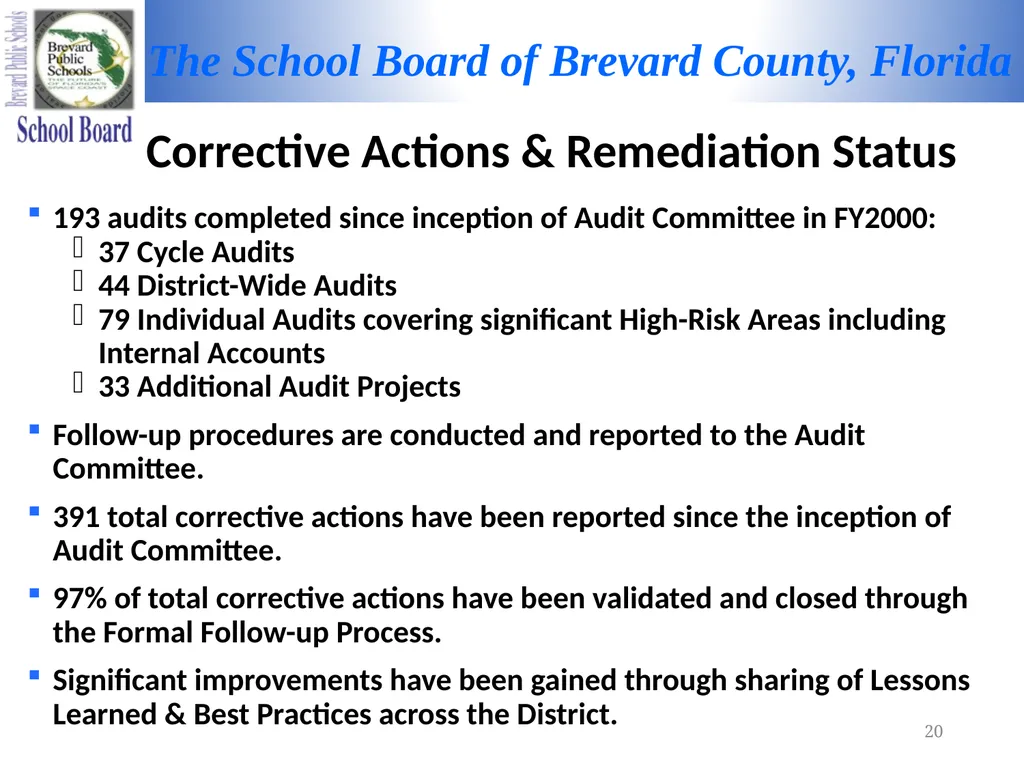
20 193 audits completed since inception of Audit Committee in FY2000:
37 Cycle Audits
44 District-Wide Audits
79 Individual Audits covering significant High-Risk Areas including Internal Accounts
33 Additional Audit Projects
Follow-up procedures are conducted and reported to the Audit Committee.
391 total corrective actions have been reported since the inception of Audit Committee.
97% of total corrective actions have been validated and closed through the Formal Follow-up Process.
Significant improvements have been gained through sharing of Lessons Learned & Best Practices across the District. Corrective Actions & Remediation Status<br>
21
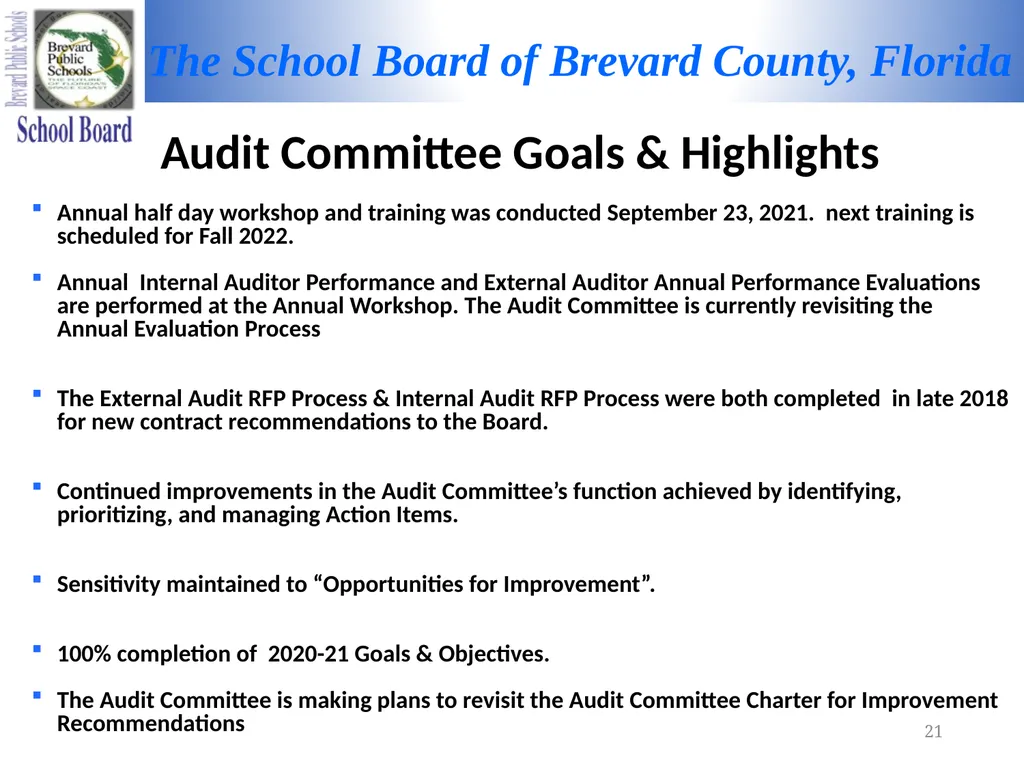
21 Audit Committee Goals & Highlights Annual half day workshop and training was conducted September 23, 2021. next training is scheduled for Fall 2022.
Annual Internal Auditor Performance and External Auditor Annual Performance Evaluations are performed at the Annual Workshop. The Audit Committee is currently revisiting the Annual Evaluation Process
The External Audit RFP Process & Internal Audit RFP Process were both completed in late 2018 for new contract recommendations to the Board.
Continued improvements in the Audit Committee’s function achieved by identifying, prioritizing, and managing Action Items.
Sensitivity maintained to “Opportunities for Improvement”.
100% completion of 2020-21 Goals & Objectives.
The Audit Committee is making plans to revisit the Audit Committee Charter for Improvement Recommendations<br>
22
Questions ? 22<br>