
Global Economy Outlook*: A Healthy Backdrop for




Description: Global Economy Outlook: A Healthy Backdrop for Semiconductors Business of Cleans April 9, 2018 Duncan Meldrum Chief Economist, Hilltop Economics, LLC duncan.meldrumhilltopeconomics.com 610-709-7951 A global outlook based on Consensus
Related Topics
Download Presentation
"Global Economy Outlook*: A Healthy Backdrop for" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Global Economy Outlook*: A Healthy Backdrop for Semiconductors Business of Cleans
April 9, 2018
Duncan Meldrum
Chief Economist, Hilltop Economics, LLC
duncan.meldrum@hilltopeconomics.com
610-709-7951 *A global outlook based on Consensus Economics, Inc.
CONSENSUS FORECASTS®<br>
slide2. Outline Metrics
Global outlook
Semiconductor outlook
MSI outlook
Wafer fab equipment/capacity
Risks<br>
slide3. Metrics Real GDP: Gross Domestic Product (final demand for goods and services, in the largest 85 countries measured in Billions of 2010 US$ - that is, inflation removed, so a “real” or “volume” measure)
Real consumer spending (for key 45 countries)
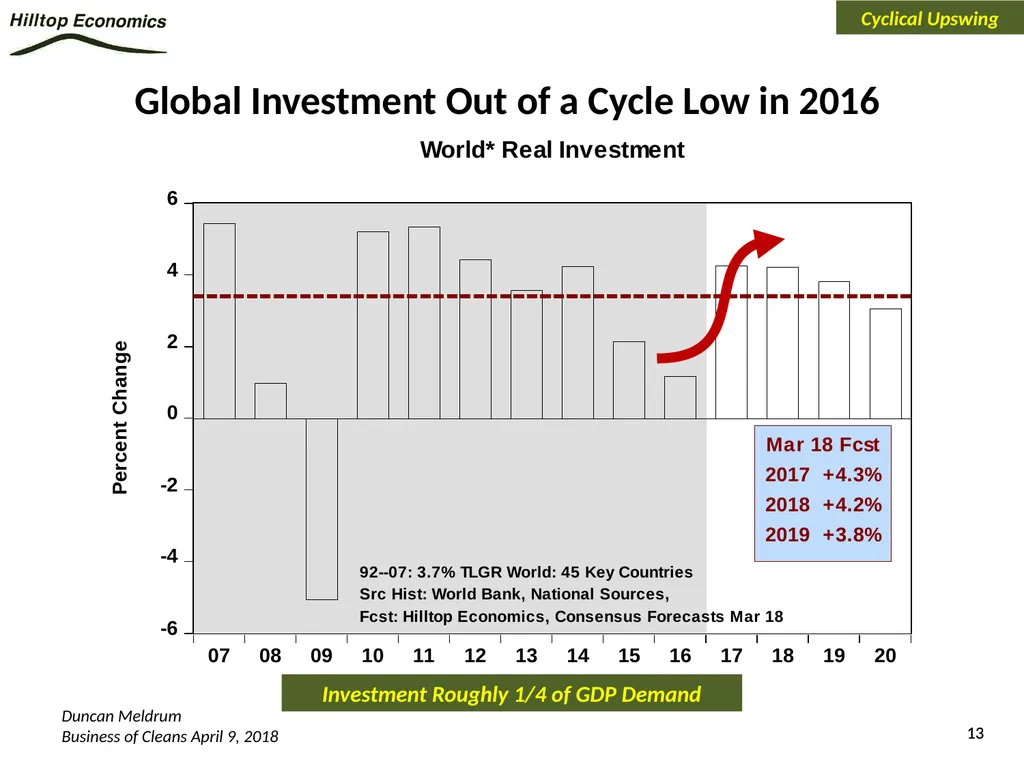
Real business investment (for key 45 countries)
Million Square Inches (MSI) of silicon wafers shipped to semiconductor manufacturers (Source: SEMI.ORG)
WSTS semiconductor revenue (World Semiconductor Trade Statistics) - $000 sales by major region reported by WSTS.ORG
Semiconductor Equipment Billings (~90% of worldwide semiconductor equipment sales)
Reported for North America by SEMI.ORG
Reported for Japan by SEAJ.ORG<br>
slide4. Summary Overview: 2018-19 In the accelerating phase of the economic cycle
Healthy consumer
Investment upsurge driving the global economy stronger
Slightly higher inflation, diverging interest rates
Currency unsettled
Potential for much higher economic policy uncertainty: trade, geopolitics the current wild cards
Healthy backdrop for semiconductor industry:
Demand for semiconductors grows above trend
Wafer Fab Equipment investment strong
Risks: excess capacity expansion, supply chain imbalances (wafers?) and final demand uncertainty (5G, AI, mobile and computing devices)<br>
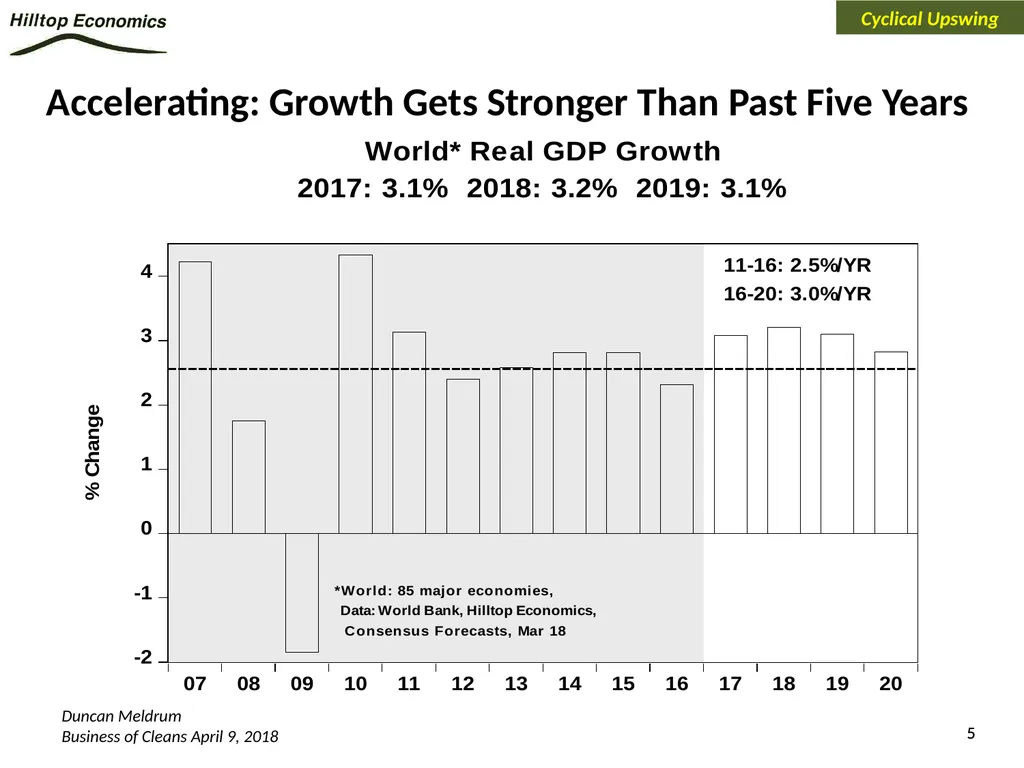
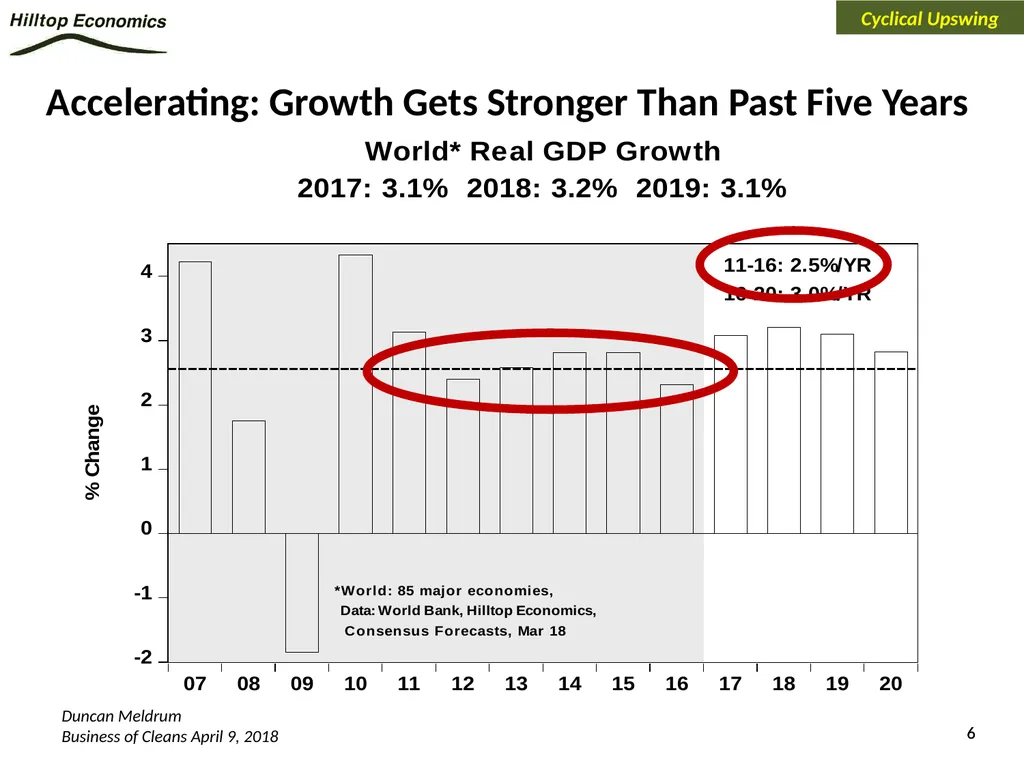
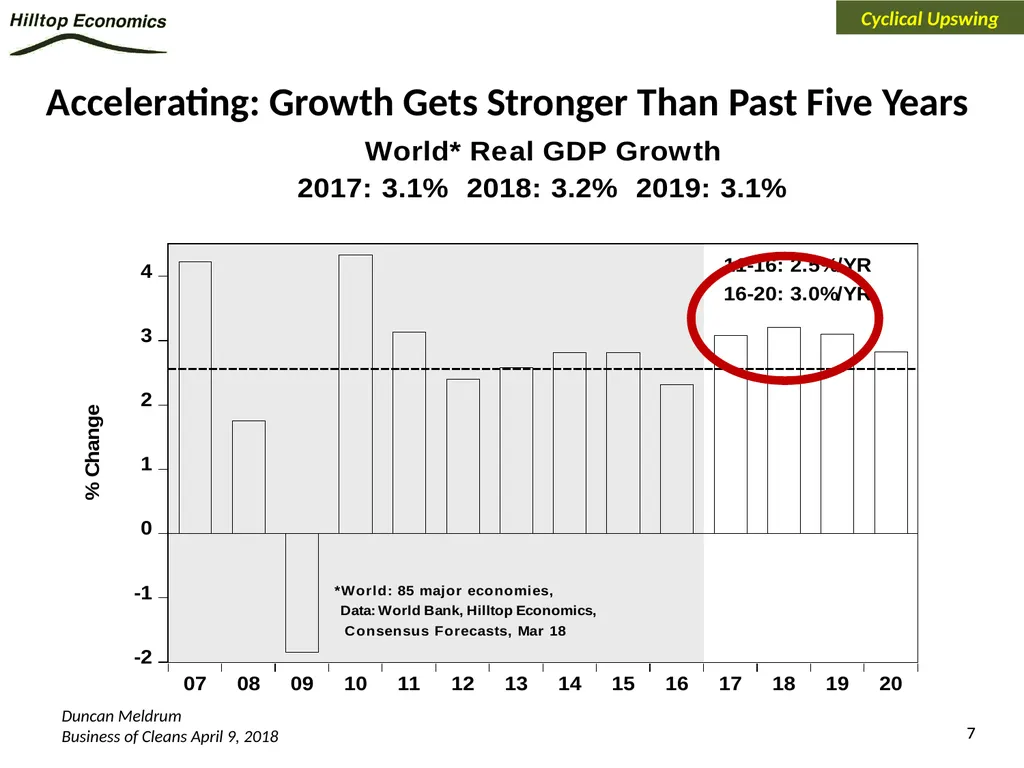
slide5. Accelerating: Growth Gets Stronger Than Past Five Years Cyclical Upswing<br>
slide6. Accelerating: Growth Gets Stronger Than Past Five Years Cyclical Upswing<br>
slide7. Accelerating: Growth Gets Stronger Than Past Five Years Cyclical Upswing<br>
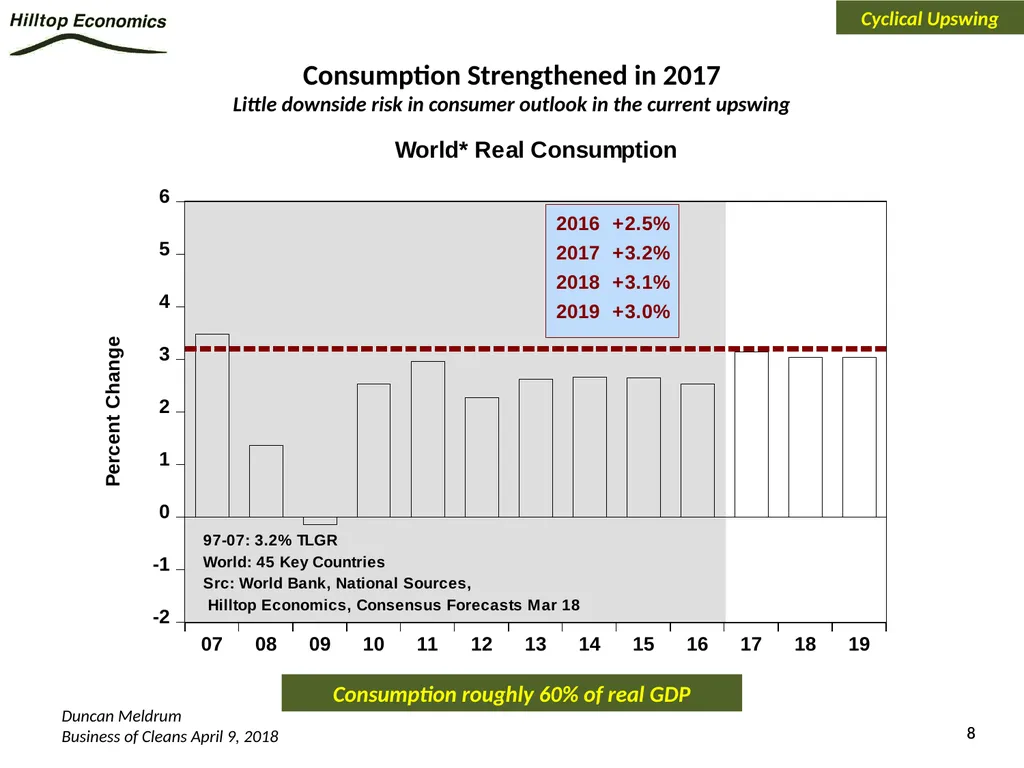
slide8. Consumption Strengthened in 2017 Little downside risk in consumer outlook in the current upswing Cyclical Upswing Consumption roughly 60% of real GDP<br>
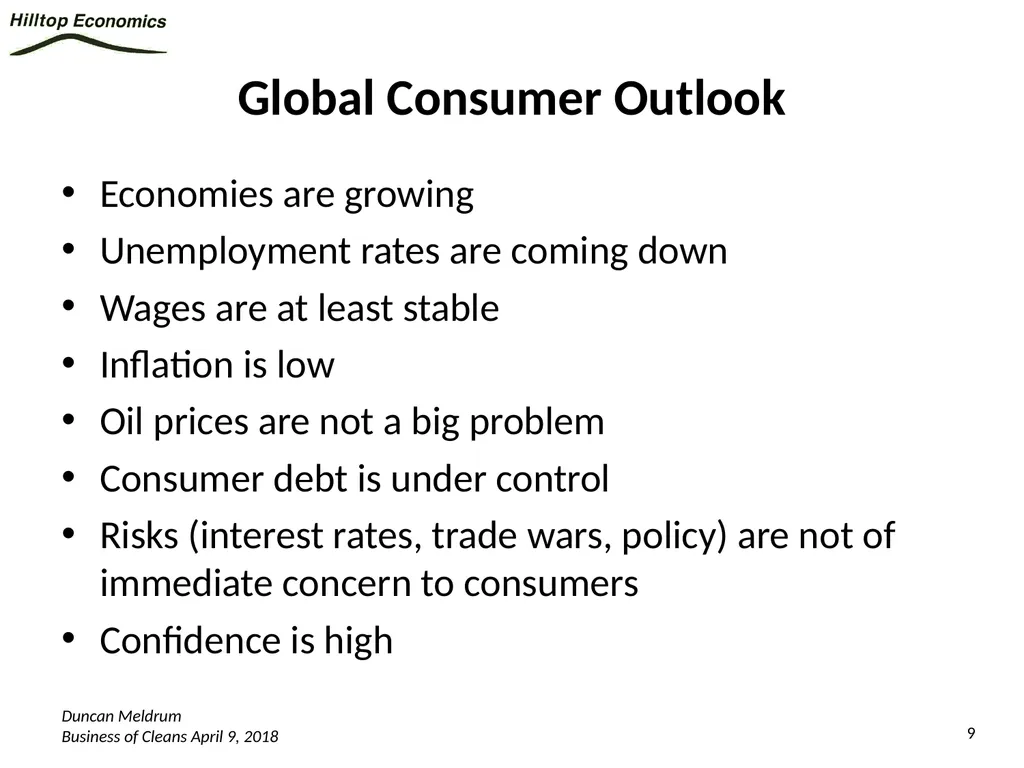
slide9. Global Consumer Outlook Economies are growing
Unemployment rates are coming down
Wages are at least stable
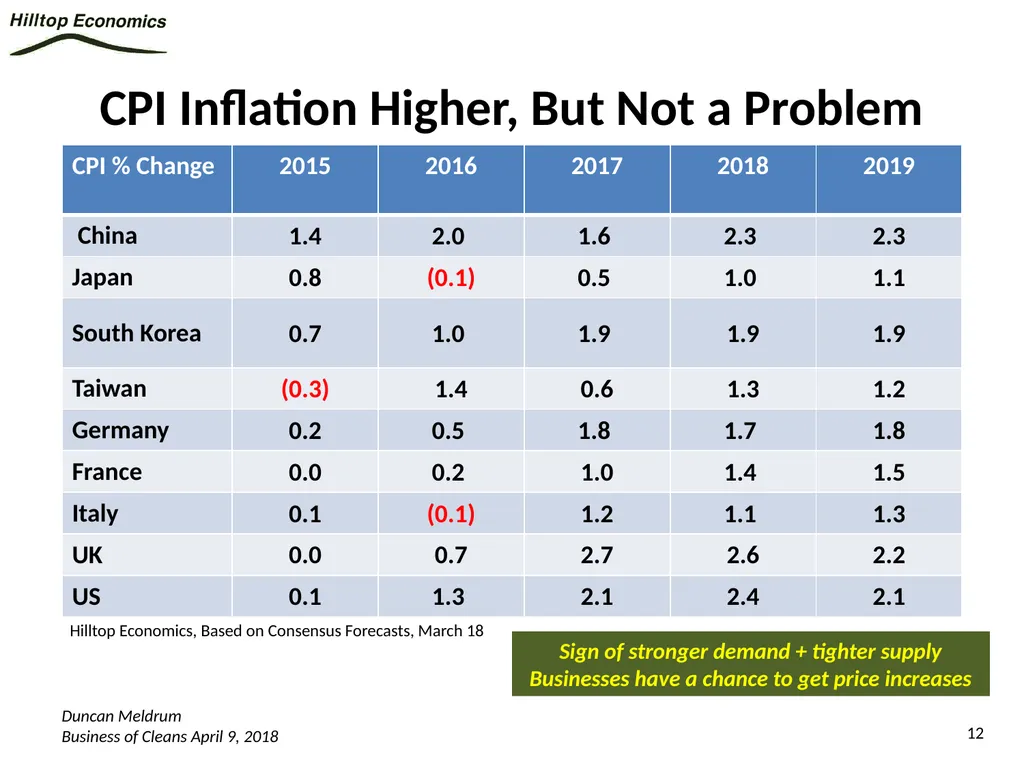
Inflation is low
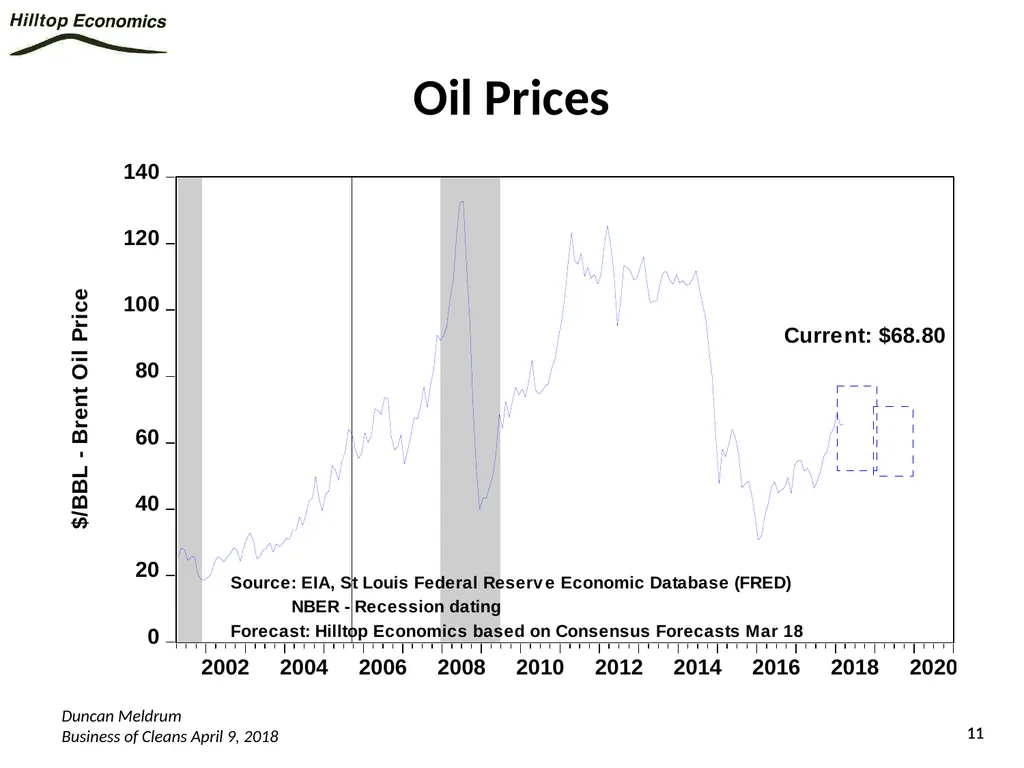
Oil prices are not a big problem
Consumer debt is under control
Risks (interest rates, trade wars, policy) are not of immediate concern to consumers
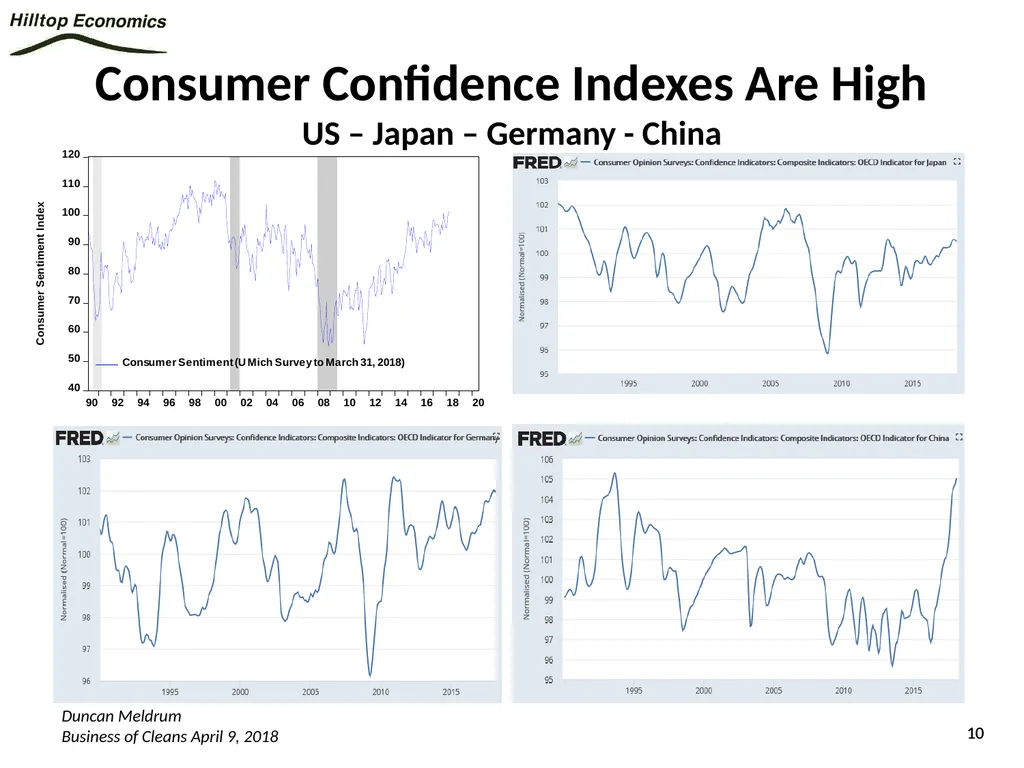
Confidence is high<br>
slide10. Consumer Confidence Indexes Are High US – Japan – Germany - China<br>
slide11. Oil Prices<br>
slide12. CPI Inflation Higher, But Not a Problem Hilltop Economics, Based on Consensus Forecasts, March 18 Sign of stronger demand + tighter supply
Businesses have a chance to get price increases<br>
slide13. Global Investment Out of a Cycle Low in 2016 Investment Roughly 1/4 of GDP Demand Cyclical Upswing<br>
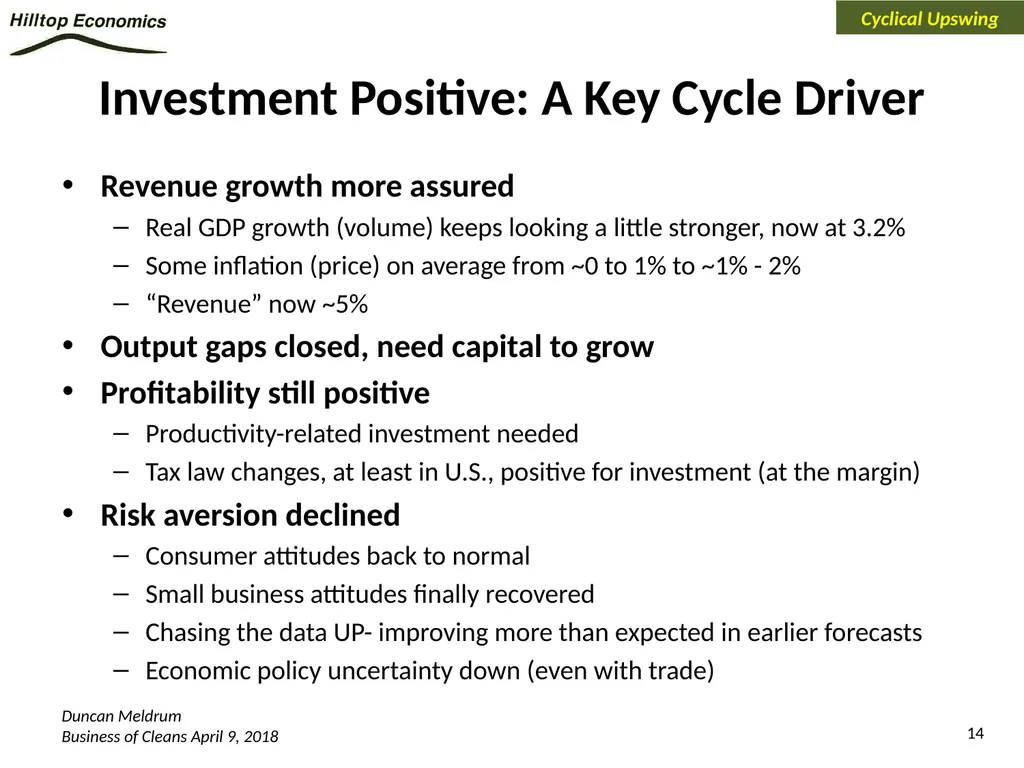
slide14. Investment Positive: A Key Cycle Driver Revenue growth more assured
Real GDP growth (volume) keeps looking a little stronger, now at 3.2%
Some inflation (price) on average from ~0 to 1% to ~1% - 2%
“Revenue” now ~5%
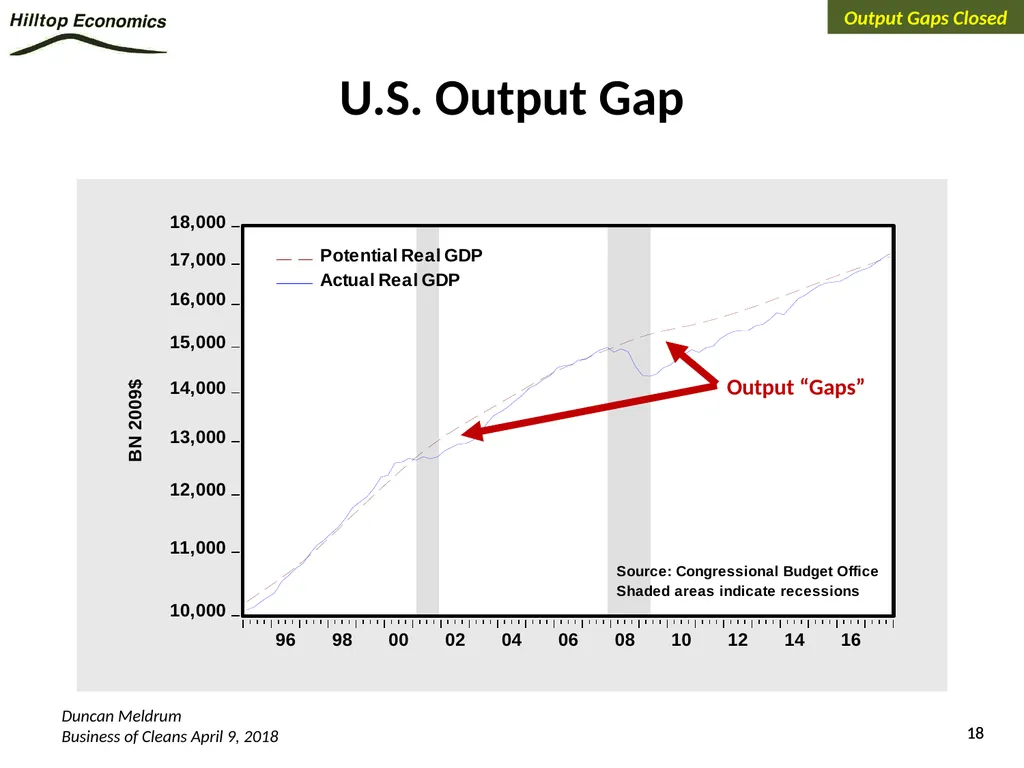
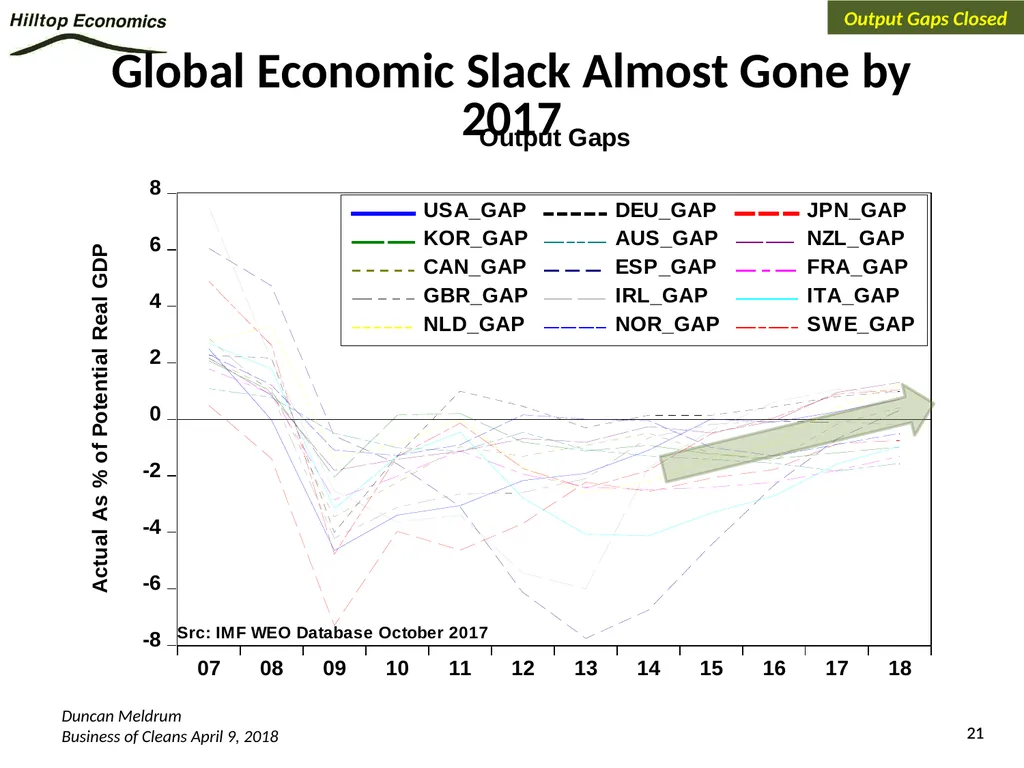
Output gaps closed, need capital to grow
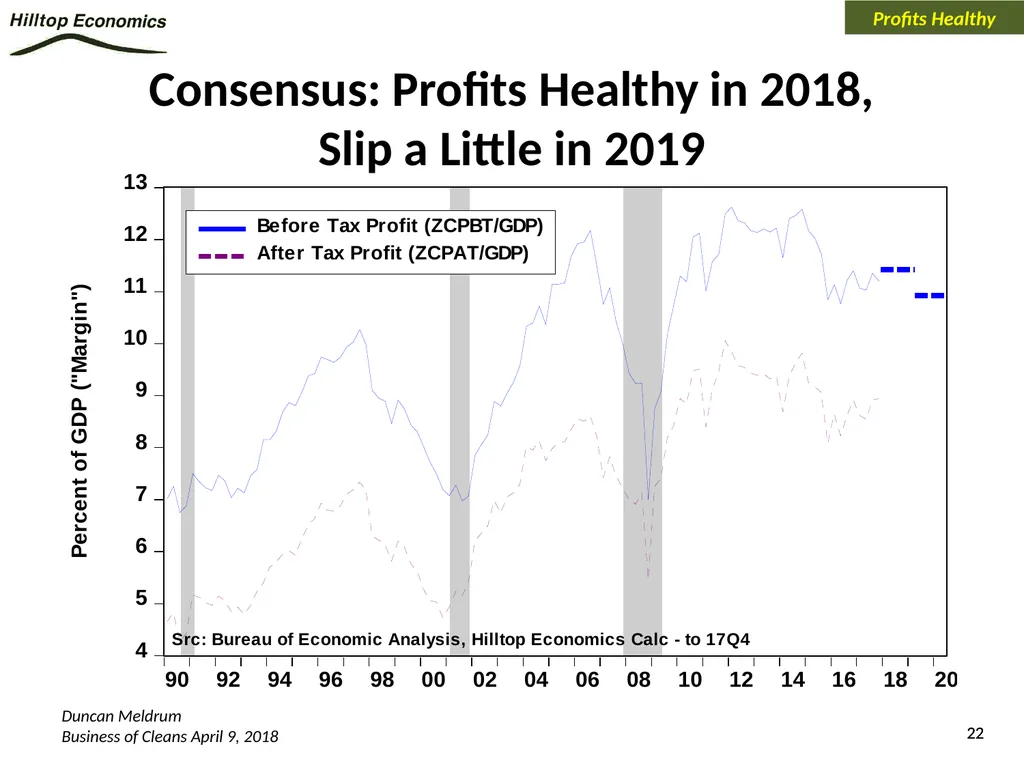
Profitability still positive
Productivity-related investment needed
Tax law changes, at least in U.S., positive for investment (at the margin)
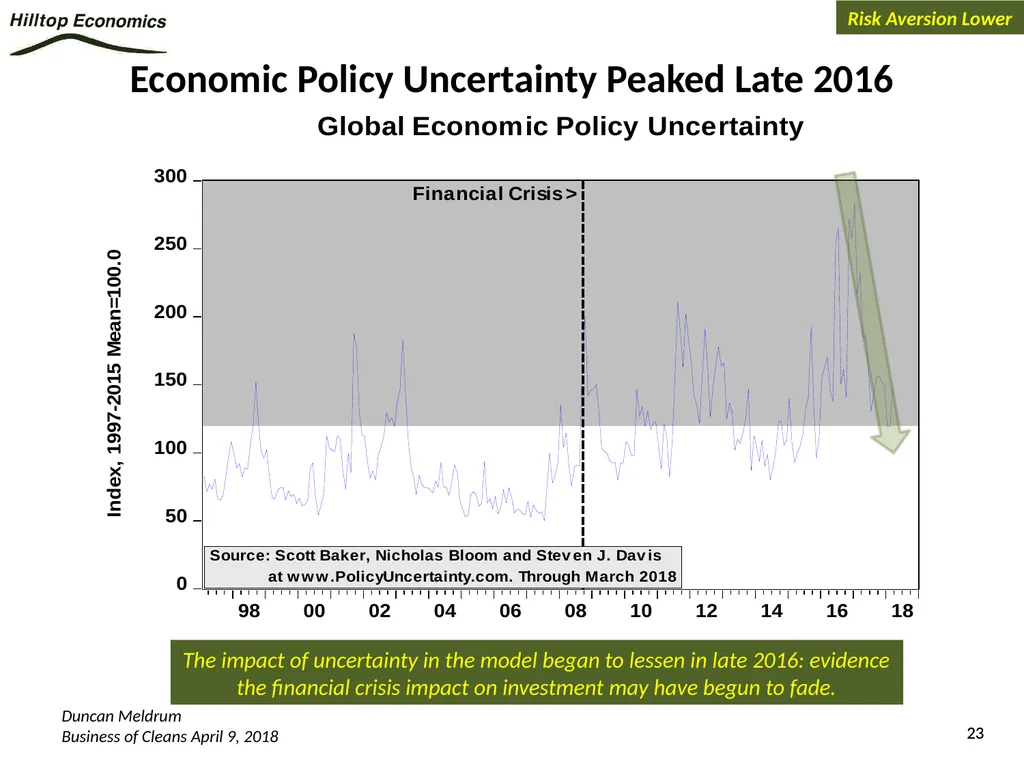
Risk aversion declined
Consumer attitudes back to normal
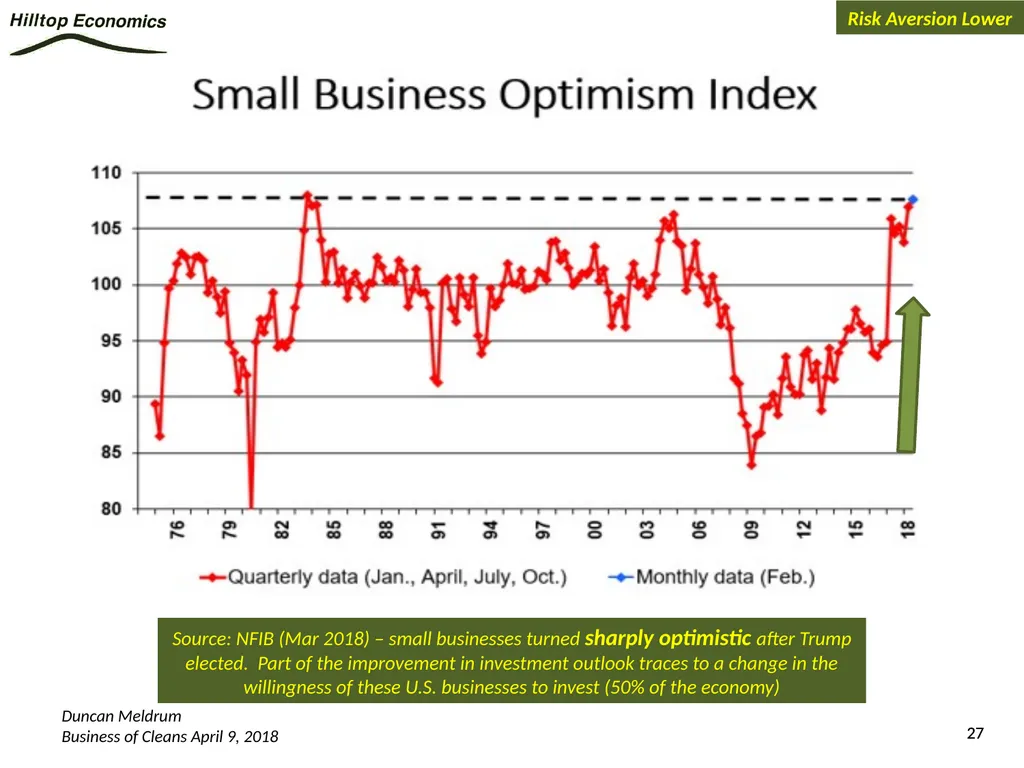
Small business attitudes finally recovered
Chasing the data UP- improving more than expected in earlier forecasts
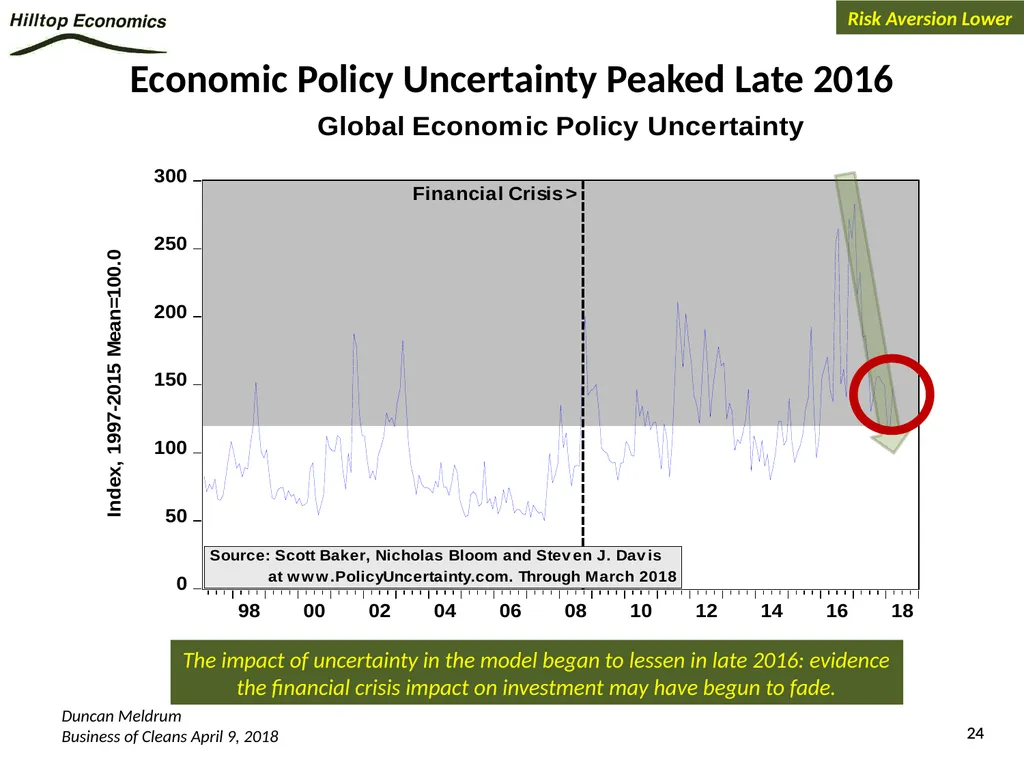
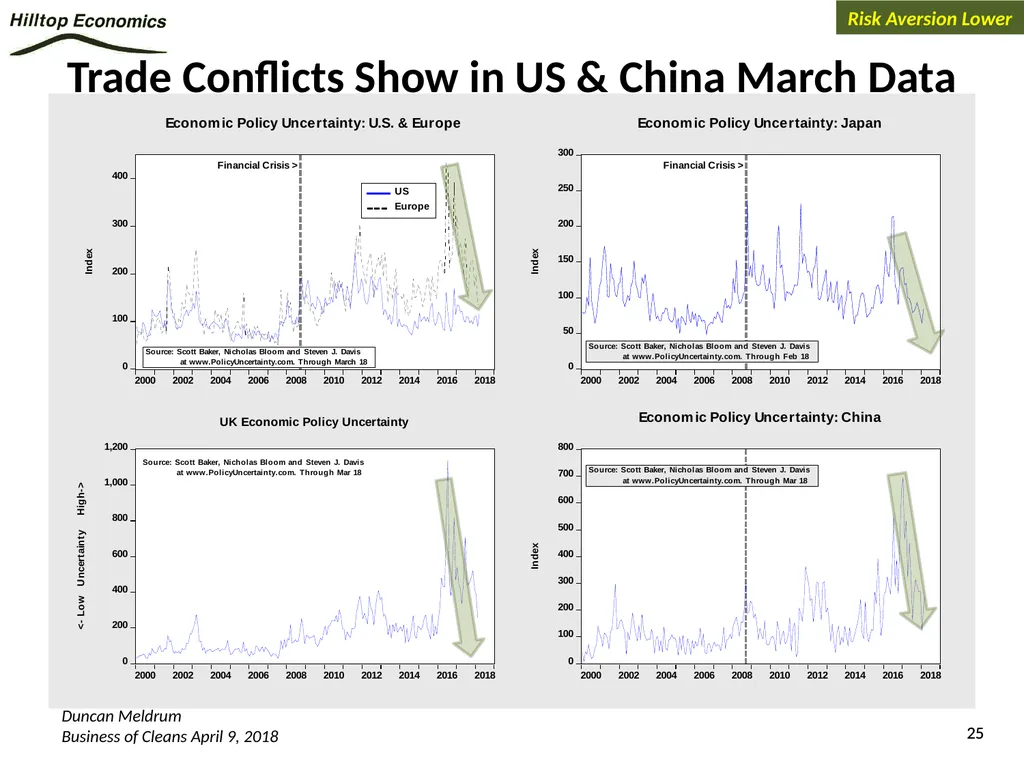
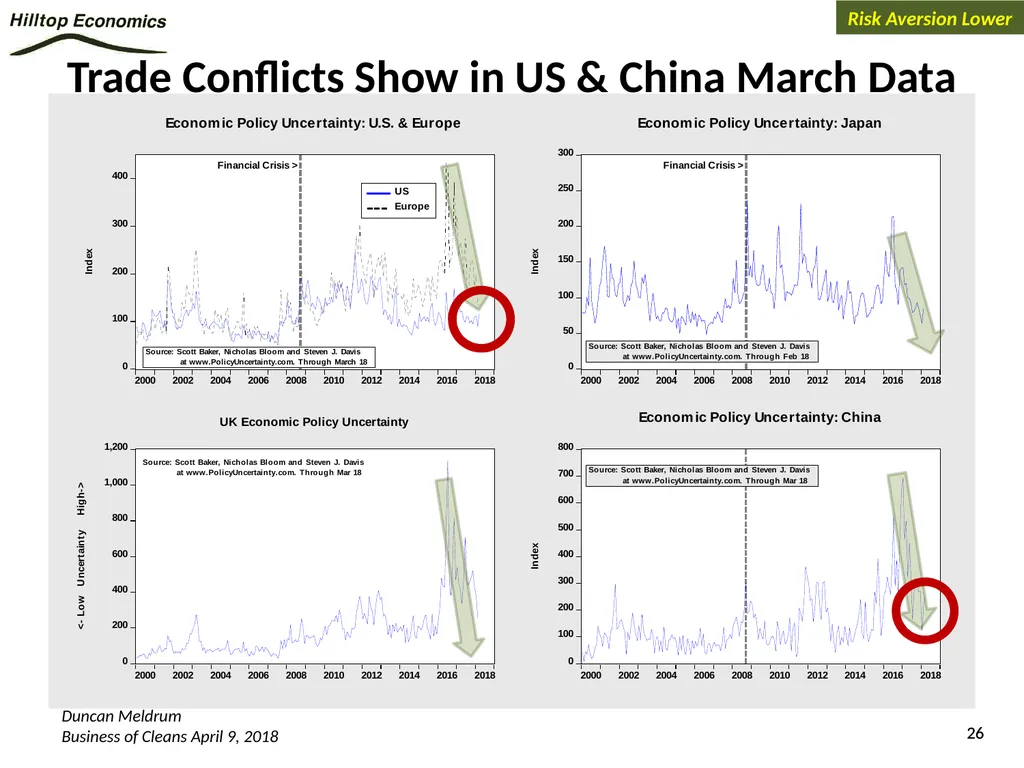
Economic policy uncertainty down (even with trade) Cyclical Upswing<br>
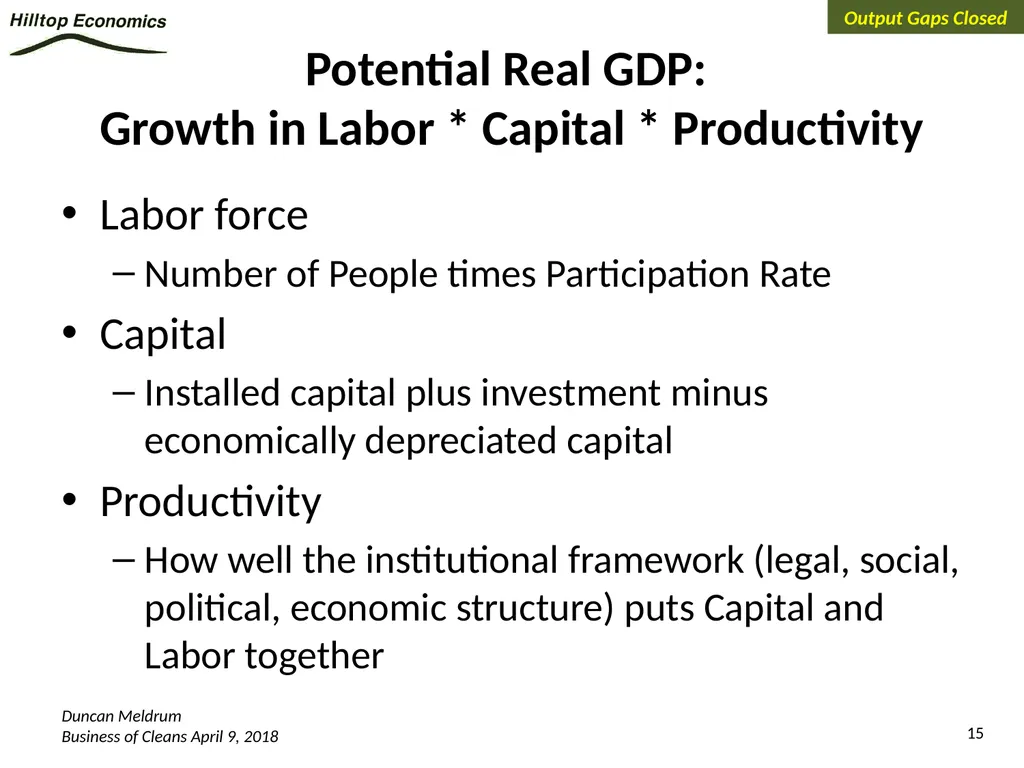
slide15. Potential Real GDP: Growth in Labor * Capital * Productivity Labor force
Number of People times Participation Rate
Capital
Installed capital plus investment minus economically depreciated capital
Productivity
How well the institutional framework (legal, social, political, economic structure) puts Capital and Labor together Output Gaps Closed<br>
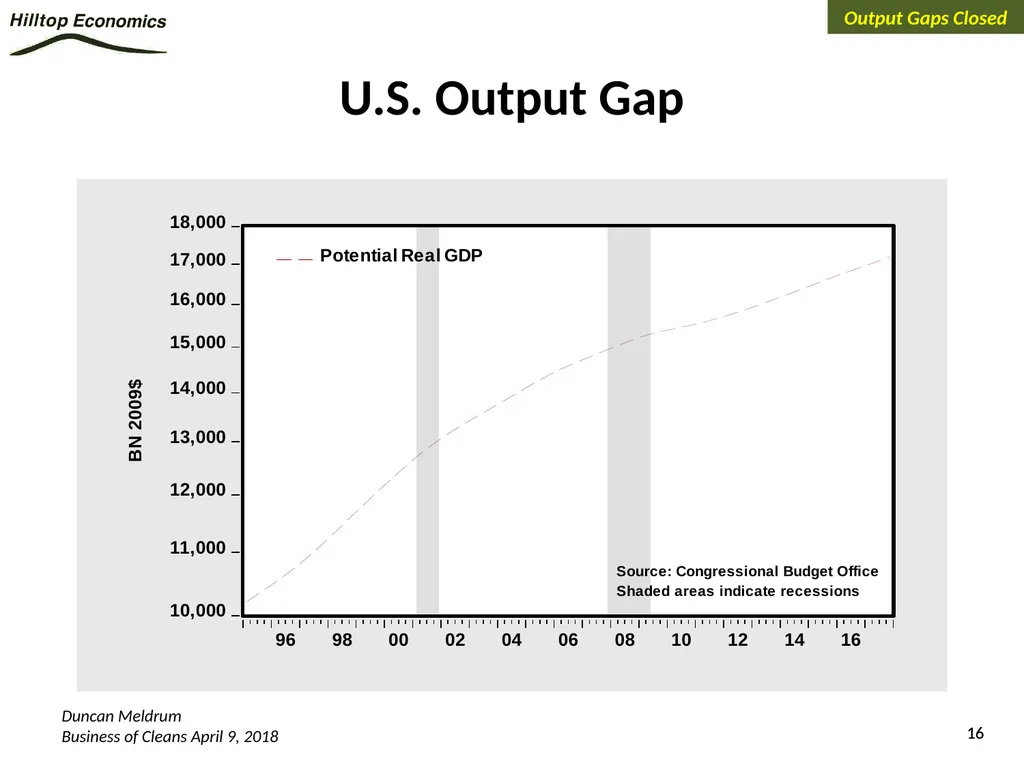
slide16. U.S. Output Gap Output Gaps Closed<br>
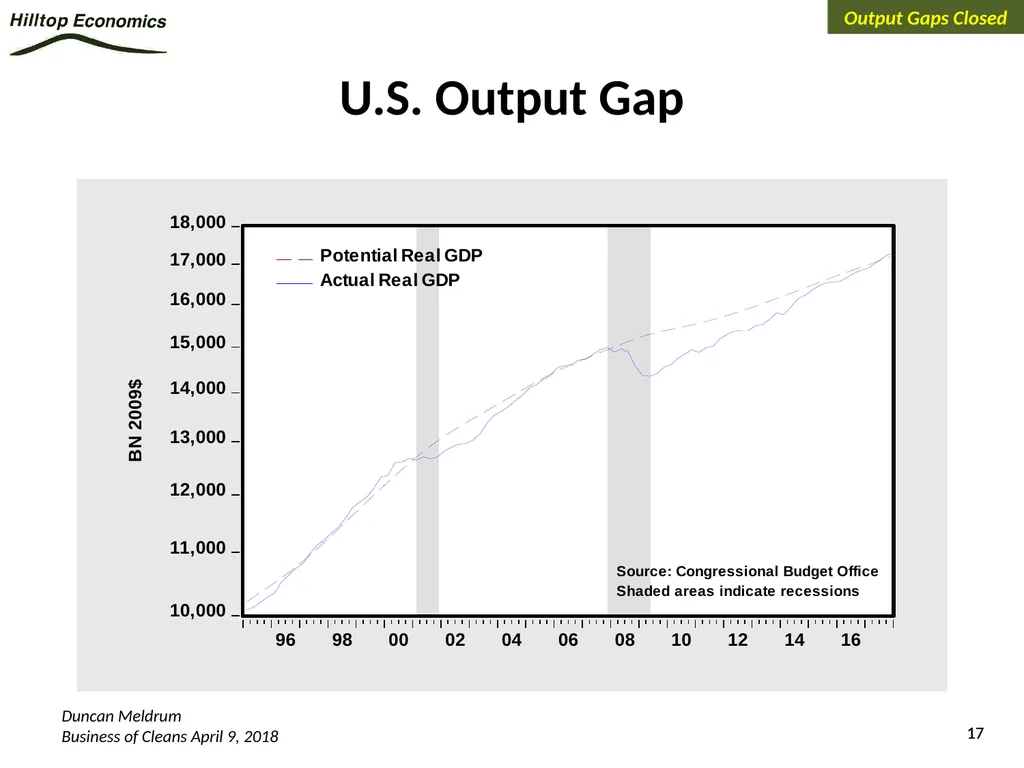
slide17. U.S. Output Gap Output Gaps Closed<br>
slide18. U.S. Output Gap Output “Gaps” Output Gaps Closed<br>
slide19. The US (global) Economy NEEDS Investment Output Gaps Closed<br>
slide20. The US (global) Economy NEEDS Investment Output Gaps Closed<br>
slide21. Global Economic Slack Almost Gone by 2017 Output Gaps Closed<br>
slide22. Consensus: Profits Healthy in 2018, Slip a Little in 2019 Profits Healthy<br>
slide23. Economic Policy Uncertainty Peaked Late 2016 The impact of uncertainty in the model began to lessen in late 2016: evidence the financial crisis impact on investment may have begun to fade. Risk Aversion Lower<br>
slide24. Economic Policy Uncertainty Peaked Late 2016 The impact of uncertainty in the model began to lessen in late 2016: evidence the financial crisis impact on investment may have begun to fade. Risk Aversion Lower<br>
slide25. Trade Conflicts Show in US & China March Data Risk Aversion Lower<br>
slide26. Trade Conflicts Show in US & China March Data Risk Aversion Lower<br>
slide27. Source: NFIB (Mar 2018) – small businesses turned sharply optimistic after Trump elected. Part of the improvement in investment outlook traces to a change in the willingness of these U.S. businesses to invest (50% of the economy) Risk Aversion Lower<br>
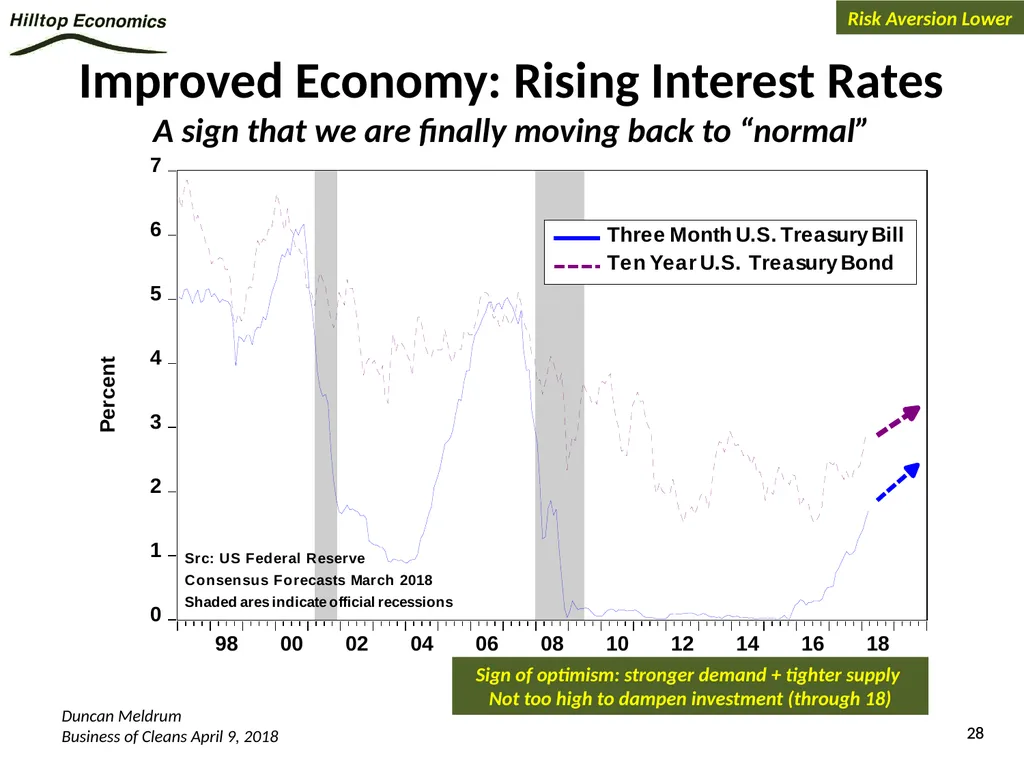
slide28. Improved Economy: Rising Interest Rates A sign that we are finally moving back to “normal” Sign of optimism: stronger demand + tighter supply
Not too high to dampen investment (through 18) Risk Aversion Lower<br>
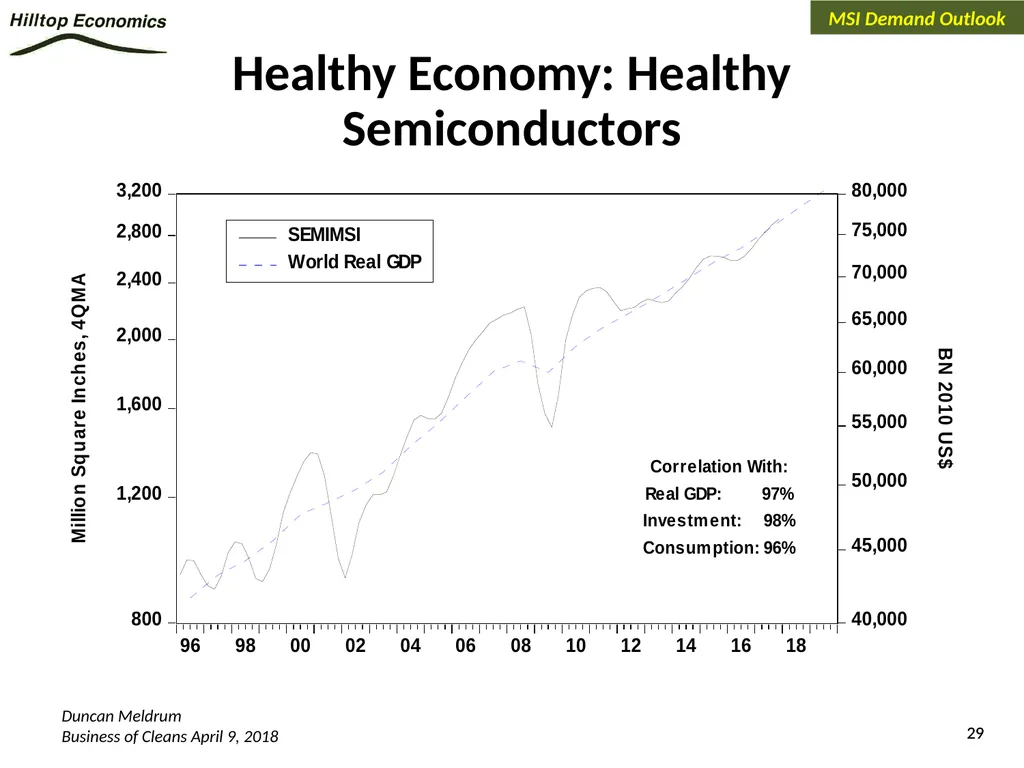
slide29. Healthy Economy: Healthy Semiconductors MSI Demand Outlook<br>
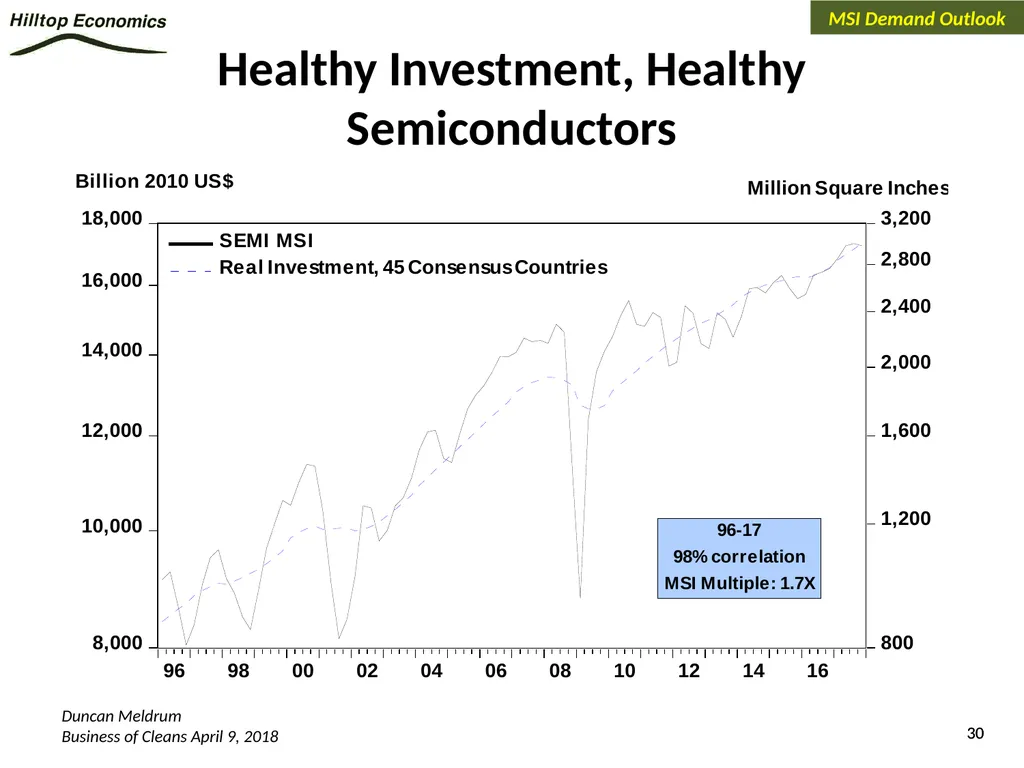
slide30. Healthy Investment, Healthy Semiconductors MSI Demand Outlook<br>
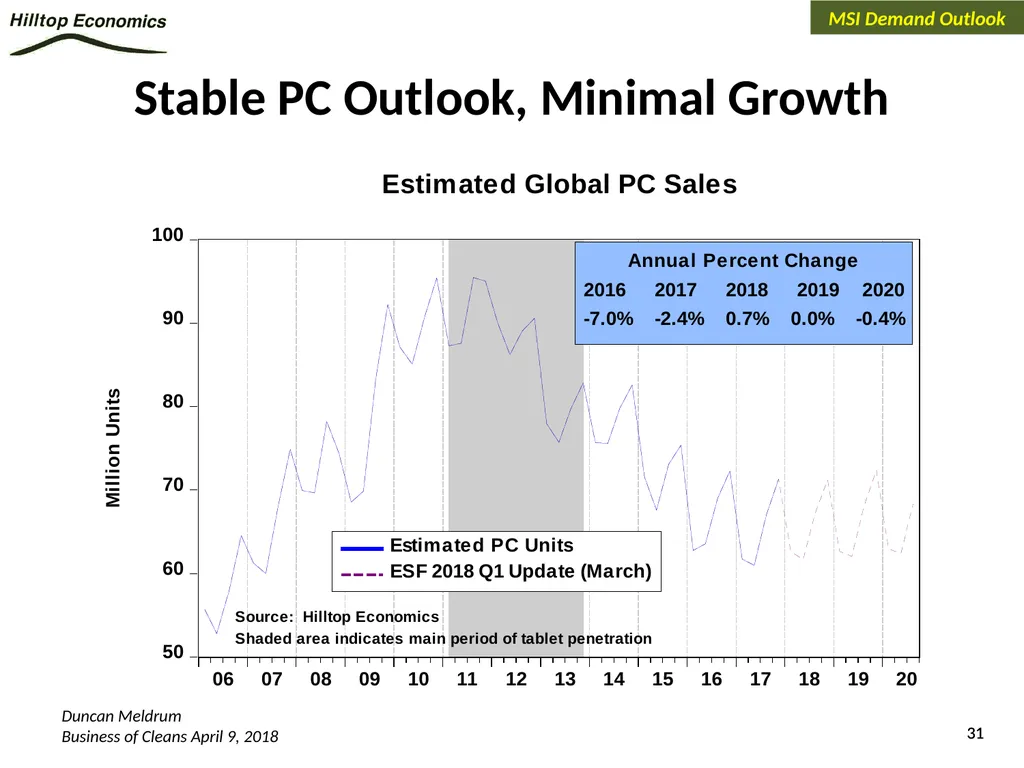
slide31. Stable PC Outlook, Minimal Growth MSI Demand Outlook<br>
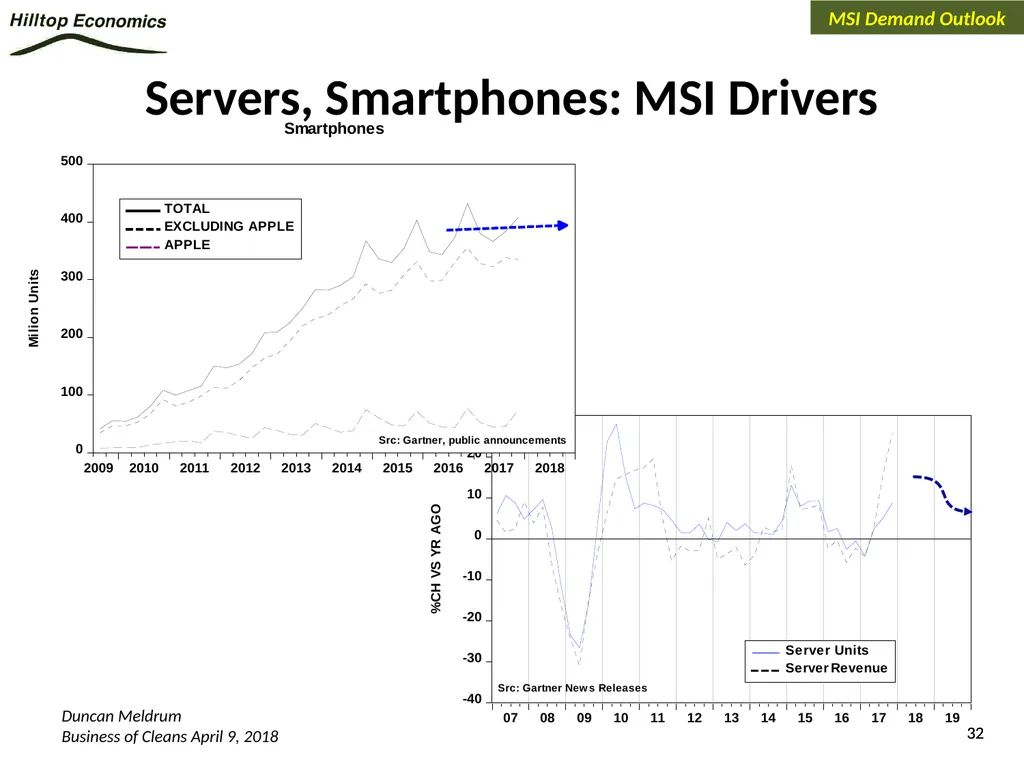
slide32. Servers, Smartphones: MSI Drivers MSI Demand Outlook<br>
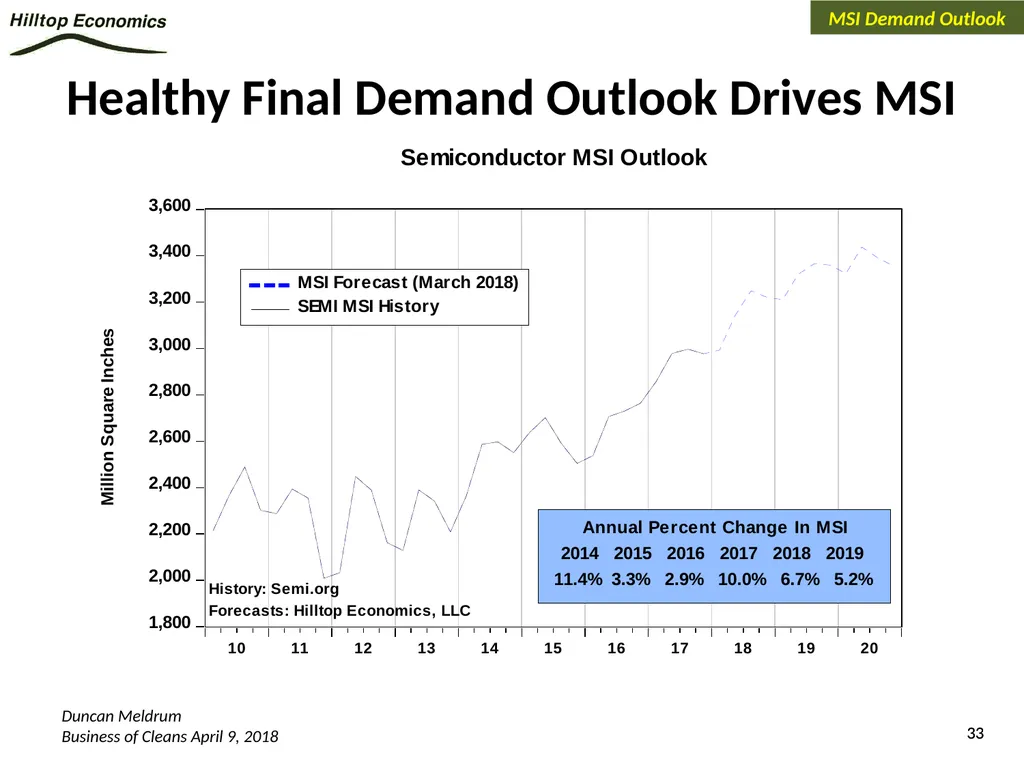
slide33. Healthy Final Demand Outlook Drives MSI MSI Demand Outlook<br>
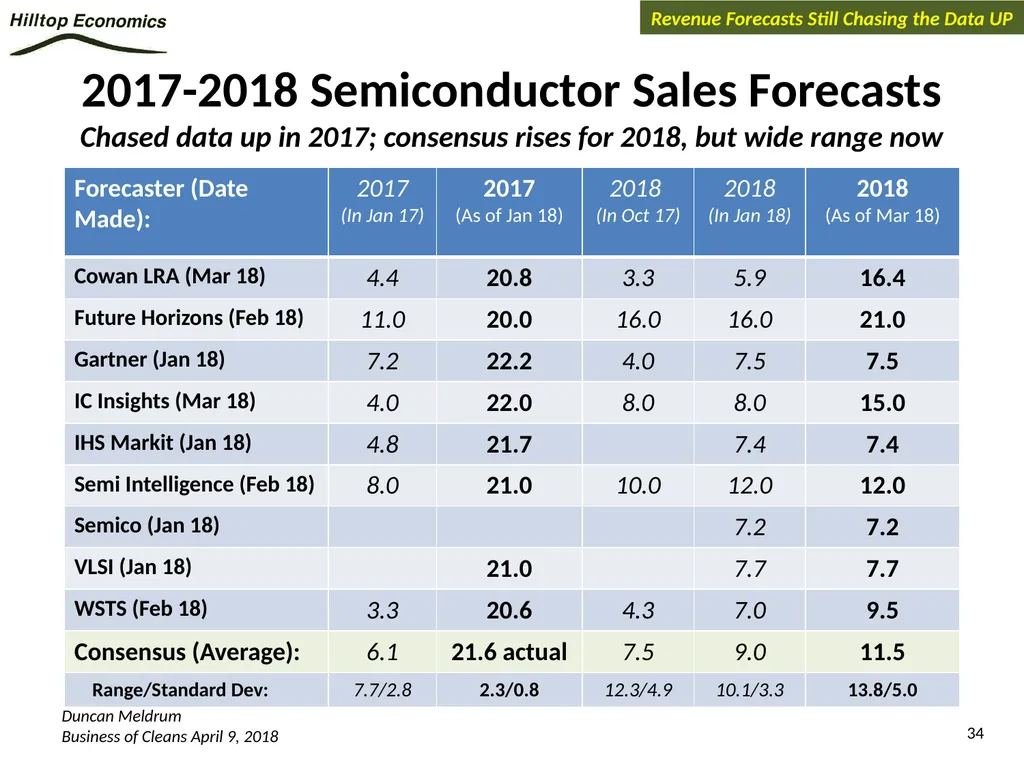
slide34. 2017-2018 Semiconductor Sales Forecasts Chased data up in 2017; consensus rises for 2018, but wide range now Revenue Forecasts Still Chasing the Data UP<br>
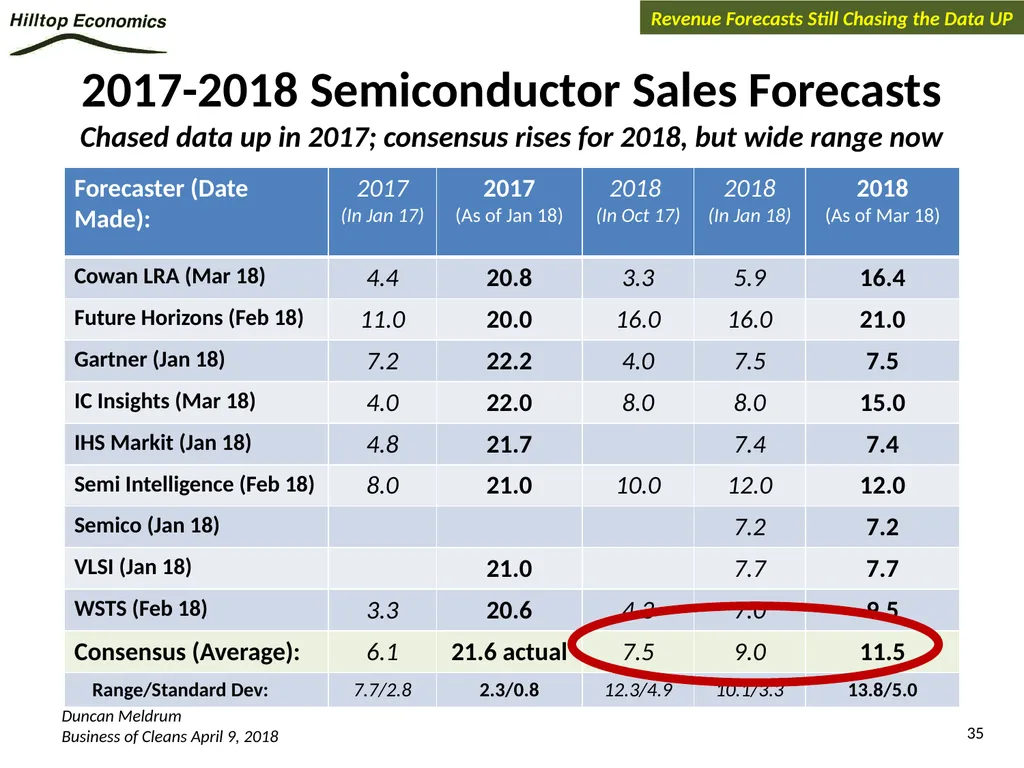
slide35. 2017-2018 Semiconductor Sales Forecasts Chased data up in 2017; consensus rises for 2018, but wide range now Revenue Forecasts Still Chasing the Data UP<br>
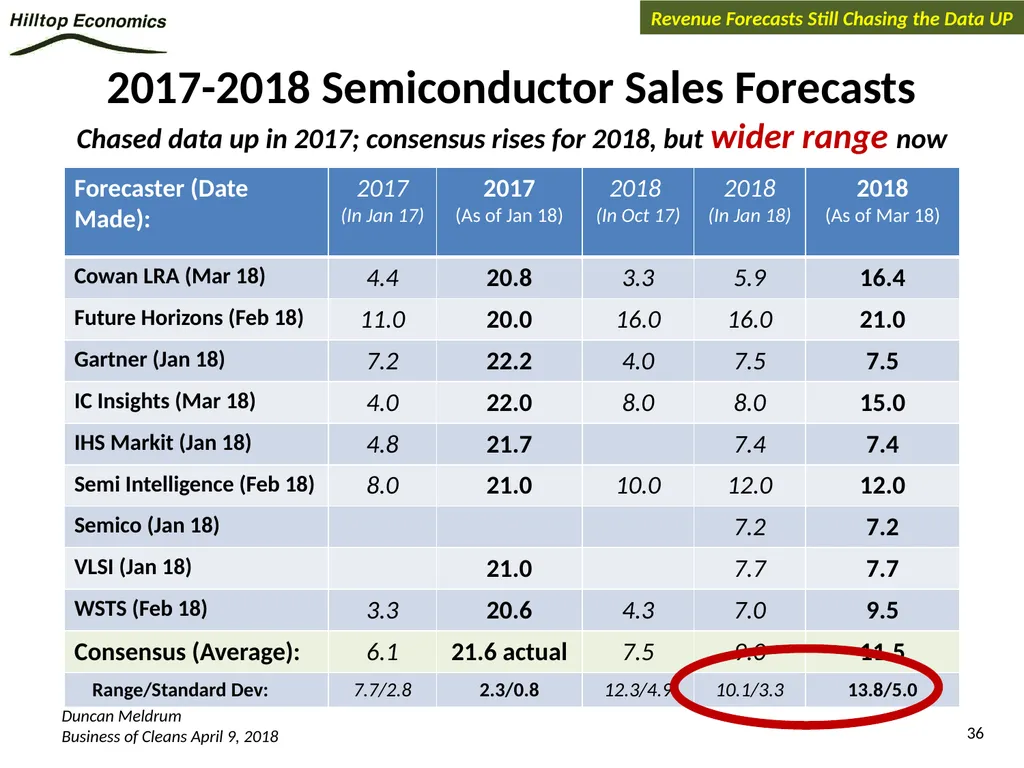
slide36. 2017-2018 Semiconductor Sales Forecasts Chased data up in 2017; consensus rises for 2018, but wider range now Revenue Forecasts Still Chasing the Data UP<br>
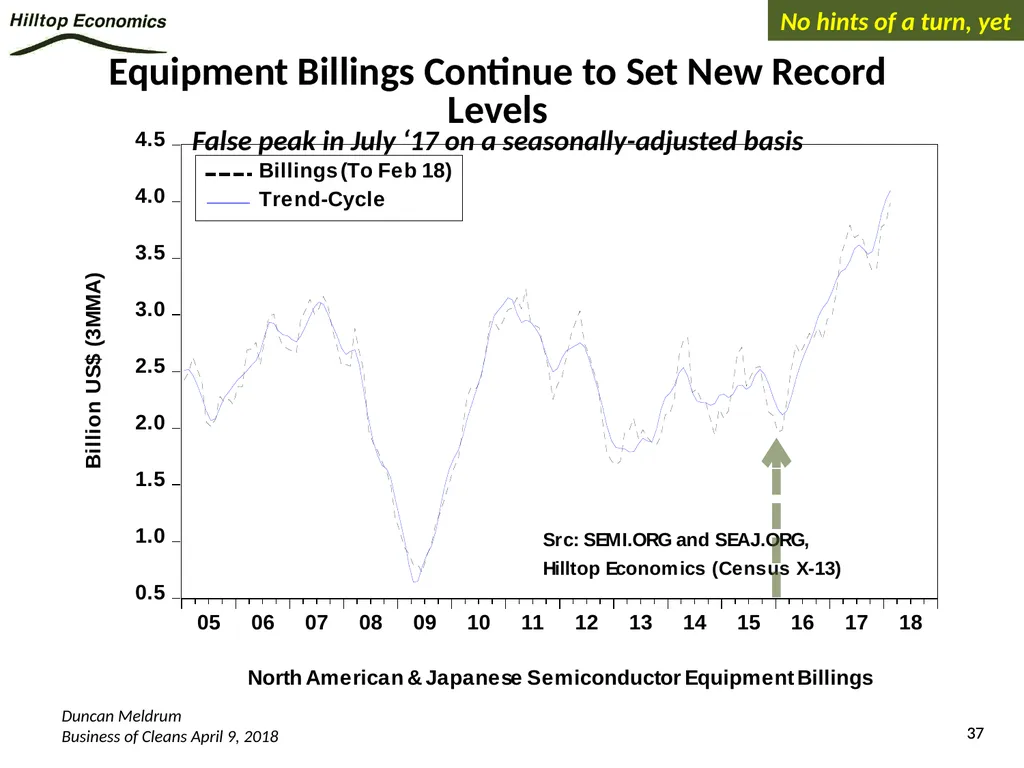
slide37. Equipment Billings Continue to Set New Record Levels False peak in July ‘17 on a seasonally-adjusted basis No hints of a turn, yet<br>
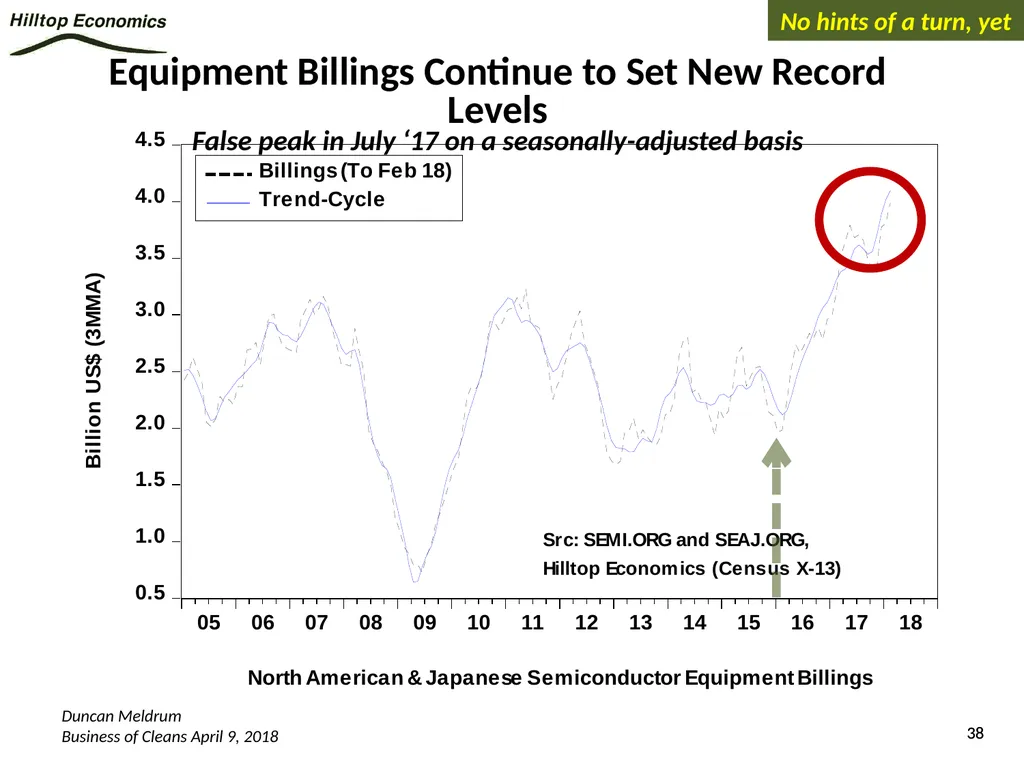
slide38. Equipment Billings Continue to Set New Record Levels False peak in July ‘17 on a seasonally-adjusted basis No hints of a turn, yet<br>
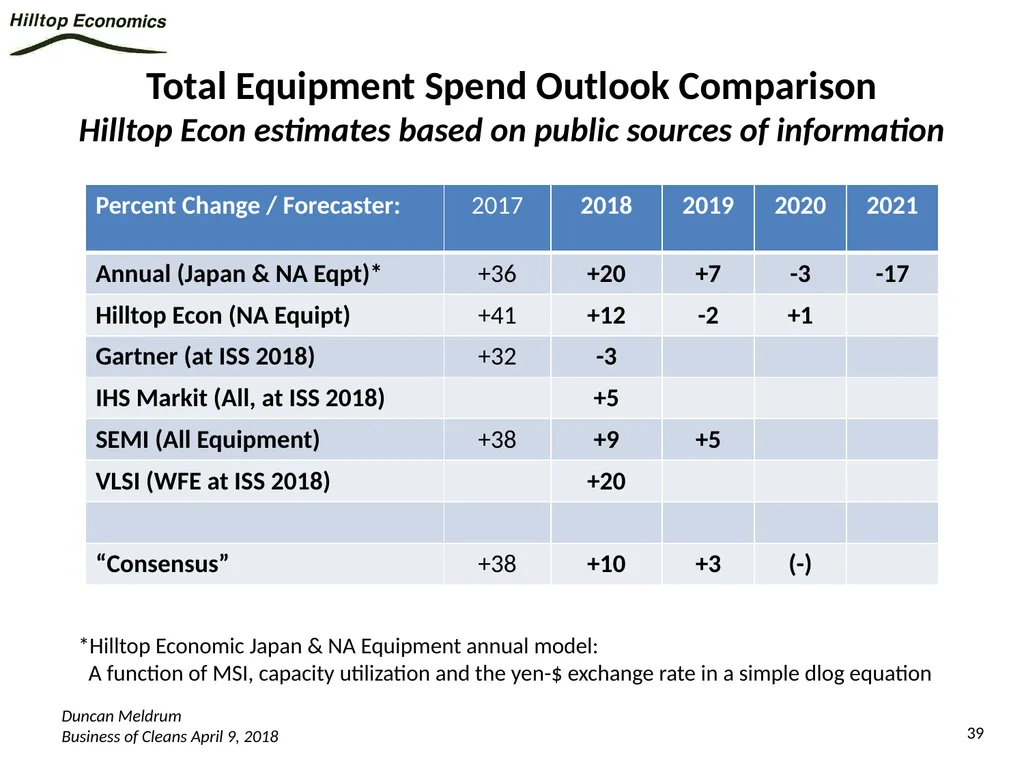
slide39. Total Equipment Spend Outlook Comparison Hilltop Econ estimates based on public sources of information *Hilltop Economic Japan & NA Equipment annual model:
A function of MSI, capacity utilization and the yen-$ exchange rate in a simple dlog equation<br>
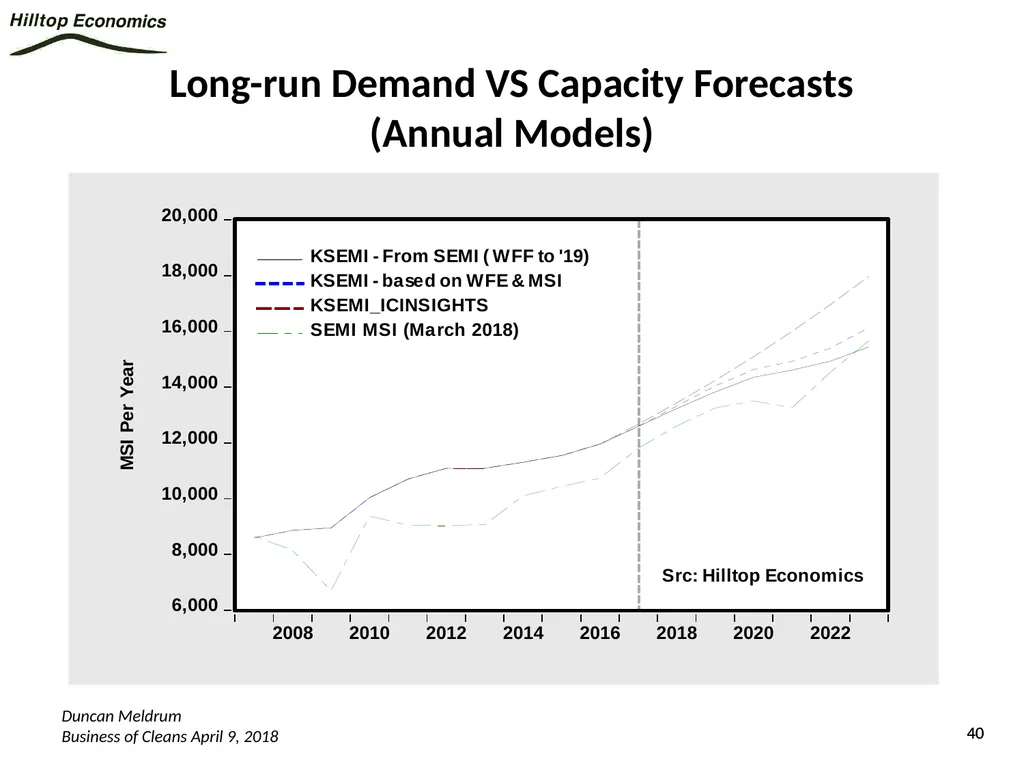
slide40. Long-run Demand VS Capacity Forecasts (Annual Models)<br>
slide41. Economy Risks One positive, many negative Forecasters under-anticipate business investment and consumer spending: actual data is better than the expectation
Global trade protectionism
Differential global monetary policy
Interest rates (U.S. tightens as others still easing/loose)
Currency & financial asset turmoil
U.S. yield curve flattening
China post 19th Party Congress (geopolitical, debt, property market bubble, etc.)
Political extremism (US & EU)
Geopolitical
N. Korea, Middle East
Global terrorism
Oil Risks<br>
slide42. Semiconductor Risks China
Trade
Industry Upswing leading global
Likely to turn down before global
CONCERN: Momentum has turned
Issues in supply chain:
Selected areas of underinvestment, eg wafers
Uncertainty about speed new manufacturing processes can come online – 7nm
Inventory questions (mobile devices especially iPhone X?)
Overall underinvestment in technology by the rest of the economy (the productivity issue)
End of the roadmap Risks<br>
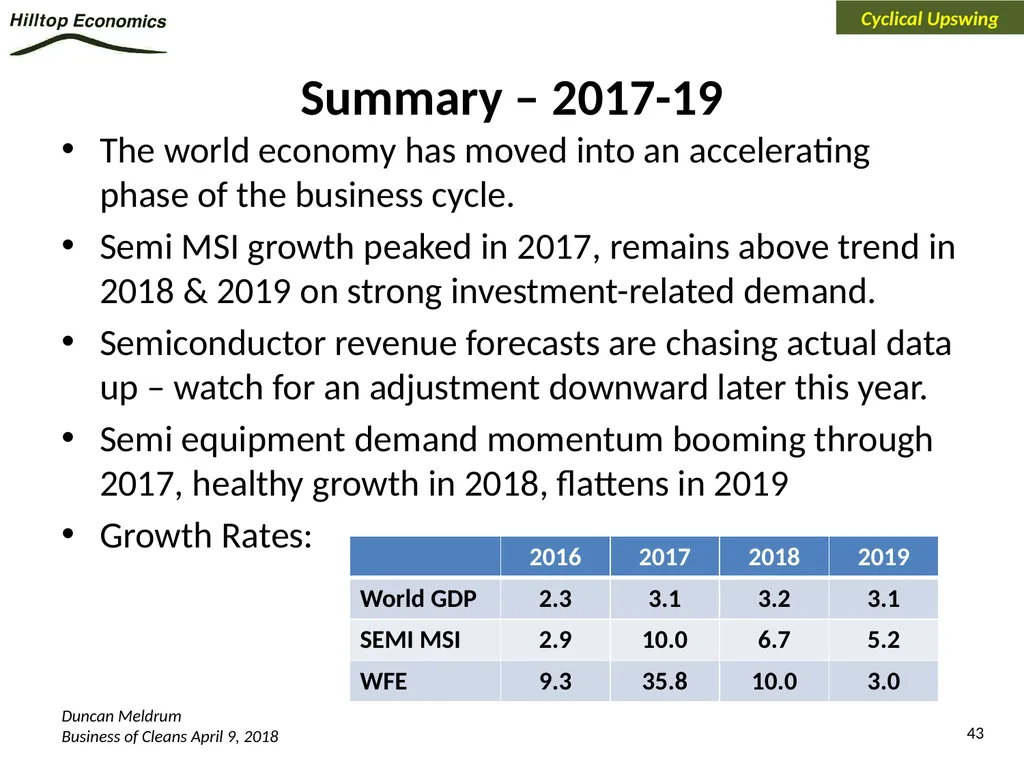
slide43. Summary – 2017-19 The world economy has moved into an accelerating phase of the business cycle.
Semi MSI growth peaked in 2017, remains above trend in 2018 & 2019 on strong investment-related demand.
Semiconductor revenue forecasts are chasing actual data up – watch for an adjustment downward later this year.
Semi equipment demand momentum booming through 2017, healthy growth in 2018, flattens in 2019
Growth Rates: Cyclical Upswing<br>
slide44. Duncan Meldrum Chief Economist Hilltop Economics, LLC duncan.meldrum@hilltopeconomics.com 610.709.7951<br>
April 9, 2018
Duncan Meldrum
Chief Economist, Hilltop Economics, LLC
duncan.meldrum@hilltopeconomics.com
610-709-7951 *A global outlook based on Consensus Economics, Inc.
CONSENSUS FORECASTS®<br>
slide2. Outline Metrics
Global outlook
Semiconductor outlook
MSI outlook
Wafer fab equipment/capacity
Risks<br>
slide3. Metrics Real GDP: Gross Domestic Product (final demand for goods and services, in the largest 85 countries measured in Billions of 2010 US$ - that is, inflation removed, so a “real” or “volume” measure)
Real consumer spending (for key 45 countries)
Real business investment (for key 45 countries)
Million Square Inches (MSI) of silicon wafers shipped to semiconductor manufacturers (Source: SEMI.ORG)
WSTS semiconductor revenue (World Semiconductor Trade Statistics) - $000 sales by major region reported by WSTS.ORG
Semiconductor Equipment Billings (~90% of worldwide semiconductor equipment sales)
Reported for North America by SEMI.ORG
Reported for Japan by SEAJ.ORG<br>
slide4. Summary Overview: 2018-19 In the accelerating phase of the economic cycle
Healthy consumer
Investment upsurge driving the global economy stronger
Slightly higher inflation, diverging interest rates
Currency unsettled
Potential for much higher economic policy uncertainty: trade, geopolitics the current wild cards
Healthy backdrop for semiconductor industry:
Demand for semiconductors grows above trend
Wafer Fab Equipment investment strong
Risks: excess capacity expansion, supply chain imbalances (wafers?) and final demand uncertainty (5G, AI, mobile and computing devices)<br>
slide5. Accelerating: Growth Gets Stronger Than Past Five Years Cyclical Upswing<br>
slide6. Accelerating: Growth Gets Stronger Than Past Five Years Cyclical Upswing<br>
slide7. Accelerating: Growth Gets Stronger Than Past Five Years Cyclical Upswing<br>
slide8. Consumption Strengthened in 2017 Little downside risk in consumer outlook in the current upswing Cyclical Upswing Consumption roughly 60% of real GDP<br>
slide9. Global Consumer Outlook Economies are growing
Unemployment rates are coming down
Wages are at least stable
Inflation is low
Oil prices are not a big problem
Consumer debt is under control
Risks (interest rates, trade wars, policy) are not of immediate concern to consumers
Confidence is high<br>
slide10. Consumer Confidence Indexes Are High US – Japan – Germany - China<br>
slide11. Oil Prices<br>
slide12. CPI Inflation Higher, But Not a Problem Hilltop Economics, Based on Consensus Forecasts, March 18 Sign of stronger demand + tighter supply
Businesses have a chance to get price increases<br>
slide13. Global Investment Out of a Cycle Low in 2016 Investment Roughly 1/4 of GDP Demand Cyclical Upswing<br>
slide14. Investment Positive: A Key Cycle Driver Revenue growth more assured
Real GDP growth (volume) keeps looking a little stronger, now at 3.2%
Some inflation (price) on average from ~0 to 1% to ~1% - 2%
“Revenue” now ~5%
Output gaps closed, need capital to grow
Profitability still positive
Productivity-related investment needed
Tax law changes, at least in U.S., positive for investment (at the margin)
Risk aversion declined
Consumer attitudes back to normal
Small business attitudes finally recovered
Chasing the data UP- improving more than expected in earlier forecasts
Economic policy uncertainty down (even with trade) Cyclical Upswing<br>
slide15. Potential Real GDP: Growth in Labor * Capital * Productivity Labor force
Number of People times Participation Rate
Capital
Installed capital plus investment minus economically depreciated capital
Productivity
How well the institutional framework (legal, social, political, economic structure) puts Capital and Labor together Output Gaps Closed<br>
slide16. U.S. Output Gap Output Gaps Closed<br>
slide17. U.S. Output Gap Output Gaps Closed<br>
slide18. U.S. Output Gap Output “Gaps” Output Gaps Closed<br>
slide19. The US (global) Economy NEEDS Investment Output Gaps Closed<br>
slide20. The US (global) Economy NEEDS Investment Output Gaps Closed<br>
slide21. Global Economic Slack Almost Gone by 2017 Output Gaps Closed<br>
slide22. Consensus: Profits Healthy in 2018, Slip a Little in 2019 Profits Healthy<br>
slide23. Economic Policy Uncertainty Peaked Late 2016 The impact of uncertainty in the model began to lessen in late 2016: evidence the financial crisis impact on investment may have begun to fade. Risk Aversion Lower<br>
slide24. Economic Policy Uncertainty Peaked Late 2016 The impact of uncertainty in the model began to lessen in late 2016: evidence the financial crisis impact on investment may have begun to fade. Risk Aversion Lower<br>
slide25. Trade Conflicts Show in US & China March Data Risk Aversion Lower<br>
slide26. Trade Conflicts Show in US & China March Data Risk Aversion Lower<br>
slide27. Source: NFIB (Mar 2018) – small businesses turned sharply optimistic after Trump elected. Part of the improvement in investment outlook traces to a change in the willingness of these U.S. businesses to invest (50% of the economy) Risk Aversion Lower<br>
slide28. Improved Economy: Rising Interest Rates A sign that we are finally moving back to “normal” Sign of optimism: stronger demand + tighter supply
Not too high to dampen investment (through 18) Risk Aversion Lower<br>
slide29. Healthy Economy: Healthy Semiconductors MSI Demand Outlook<br>
slide30. Healthy Investment, Healthy Semiconductors MSI Demand Outlook<br>
slide31. Stable PC Outlook, Minimal Growth MSI Demand Outlook<br>
slide32. Servers, Smartphones: MSI Drivers MSI Demand Outlook<br>
slide33. Healthy Final Demand Outlook Drives MSI MSI Demand Outlook<br>
slide34. 2017-2018 Semiconductor Sales Forecasts Chased data up in 2017; consensus rises for 2018, but wide range now Revenue Forecasts Still Chasing the Data UP<br>
slide35. 2017-2018 Semiconductor Sales Forecasts Chased data up in 2017; consensus rises for 2018, but wide range now Revenue Forecasts Still Chasing the Data UP<br>
slide36. 2017-2018 Semiconductor Sales Forecasts Chased data up in 2017; consensus rises for 2018, but wider range now Revenue Forecasts Still Chasing the Data UP<br>
slide37. Equipment Billings Continue to Set New Record Levels False peak in July ‘17 on a seasonally-adjusted basis No hints of a turn, yet<br>
slide38. Equipment Billings Continue to Set New Record Levels False peak in July ‘17 on a seasonally-adjusted basis No hints of a turn, yet<br>
slide39. Total Equipment Spend Outlook Comparison Hilltop Econ estimates based on public sources of information *Hilltop Economic Japan & NA Equipment annual model:
A function of MSI, capacity utilization and the yen-$ exchange rate in a simple dlog equation<br>
slide40. Long-run Demand VS Capacity Forecasts (Annual Models)<br>
slide41. Economy Risks One positive, many negative Forecasters under-anticipate business investment and consumer spending: actual data is better than the expectation
Global trade protectionism
Differential global monetary policy
Interest rates (U.S. tightens as others still easing/loose)
Currency & financial asset turmoil
U.S. yield curve flattening
China post 19th Party Congress (geopolitical, debt, property market bubble, etc.)
Political extremism (US & EU)
Geopolitical
N. Korea, Middle East
Global terrorism
Oil Risks<br>
slide42. Semiconductor Risks China
Trade
Industry Upswing leading global
Likely to turn down before global
CONCERN: Momentum has turned
Issues in supply chain:
Selected areas of underinvestment, eg wafers
Uncertainty about speed new manufacturing processes can come online – 7nm
Inventory questions (mobile devices especially iPhone X?)
Overall underinvestment in technology by the rest of the economy (the productivity issue)
End of the roadmap Risks<br>
slide43. Summary – 2017-19 The world economy has moved into an accelerating phase of the business cycle.
Semi MSI growth peaked in 2017, remains above trend in 2018 & 2019 on strong investment-related demand.
Semiconductor revenue forecasts are chasing actual data up – watch for an adjustment downward later this year.
Semi equipment demand momentum booming through 2017, healthy growth in 2018, flattens in 2019
Growth Rates: Cyclical Upswing<br>
slide44. Duncan Meldrum Chief Economist Hilltop Economics, LLC duncan.meldrum@hilltopeconomics.com 610.709.7951<br>