
India Maize Summit New Delhi 20th March 2014 A


Description: India Maize Summit New Delhi 20th March 2014 A Little about Noble Global Corn Trade and its likely impact on India By Major Rajiv Yadav What do we do? Founded in 1987 Operates from over 140 locations and 35 countries Three Business
Related Topics
Download Presentation
"India Maize Summit New Delhi 20th March 2014 A" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. India Maize Summit
New Delhi
20th March 2014<br>
slide2. A Little about Noble +
Global Corn Trade and its likely impact on India
By Major Rajiv Yadav<br>
slide3. What do we do? Founded in 1987
Operates from over 140 locations and 35 countries
Three Business divisions (percentage of revenue)
Energy (68%)
Agriculture (16%)
Metals, Minerals and Ores (16%)
Owns assets and participates along the supply chain
Focuses on low cost sourcing to high growth markets
Noble is listed in Singapore , with headquarters in Hong Kong.
We are ranked number 76 in the 2013 Fortune 500<br>
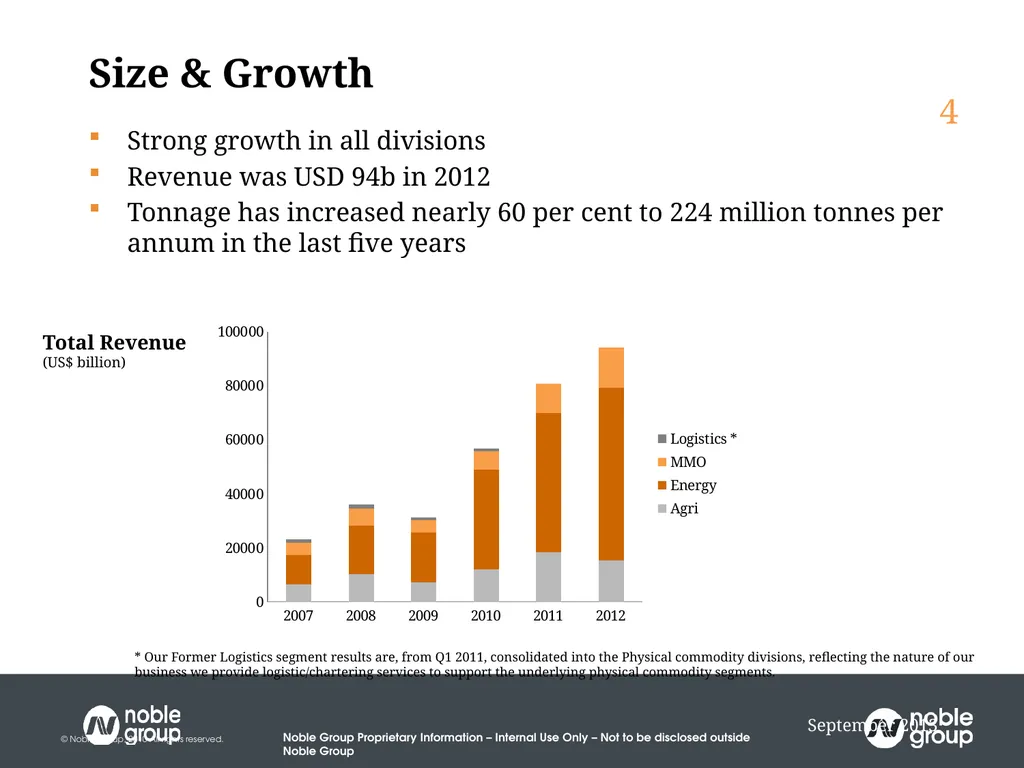
slide4. Size & Growth Strong growth in all divisions
Revenue was USD 94b in 2012
Tonnage has increased nearly 60 per cent to 224 million tonnes per annum in the last five years Total Revenue
(US$ billion) * Our Former Logistics segment results are, from Q1 2011, consolidated into the Physical commodity divisions, reflecting the nature of our business we provide logistic/chartering services to support the underlying physical commodity segments.<br>
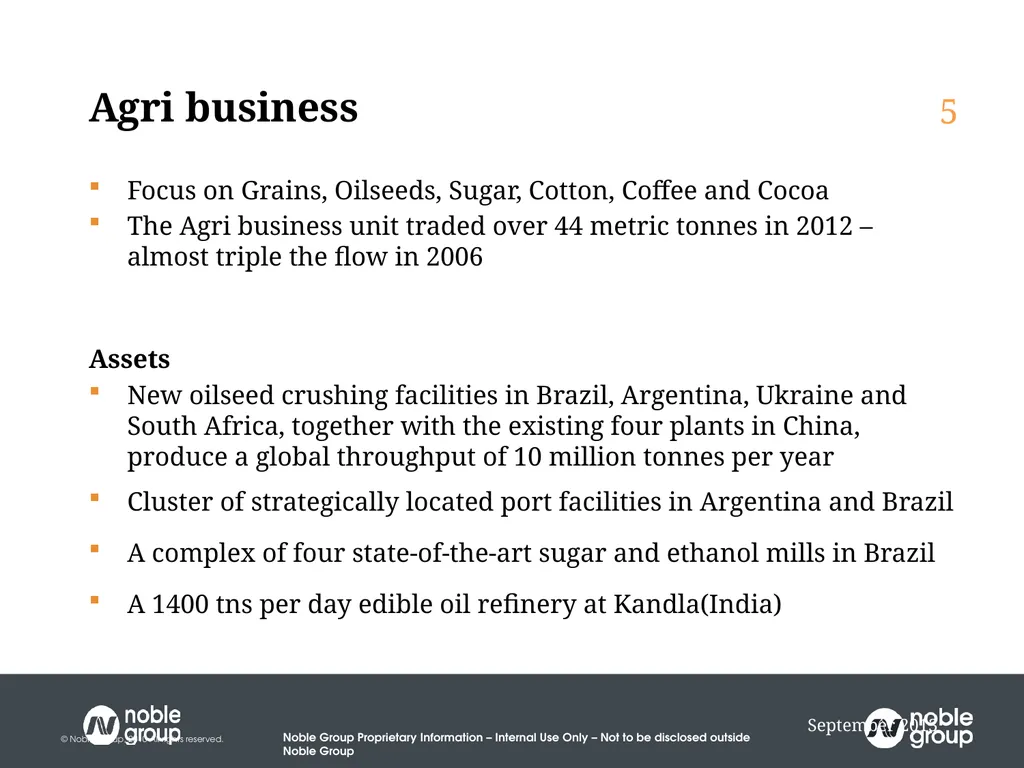
slide5. Agri business Focus on Grains, Oilseeds, Sugar, Cotton, Coffee and Cocoa
The Agri business unit traded over 44 metric tonnes in 2012 – almost triple the flow in 2006
Assets
New oilseed crushing facilities in Brazil, Argentina, Ukraine and South Africa, together with the existing four plants in China, produce a global throughput of 10 million tonnes per year
Cluster of strategically located port facilities in Argentina and Brazil
A complex of four state-of-the-art sugar and ethanol mills in Brazil
A 1400 tns per day edible oil refinery at Kandla(India)<br>
slide6. INDEX Production estimates – 2013/14
SND Snapshot
India
Exports
Growth
Destination markets
Price behavior
World Corn Yields Vs Indian Corn Yields
Future challenges<br>
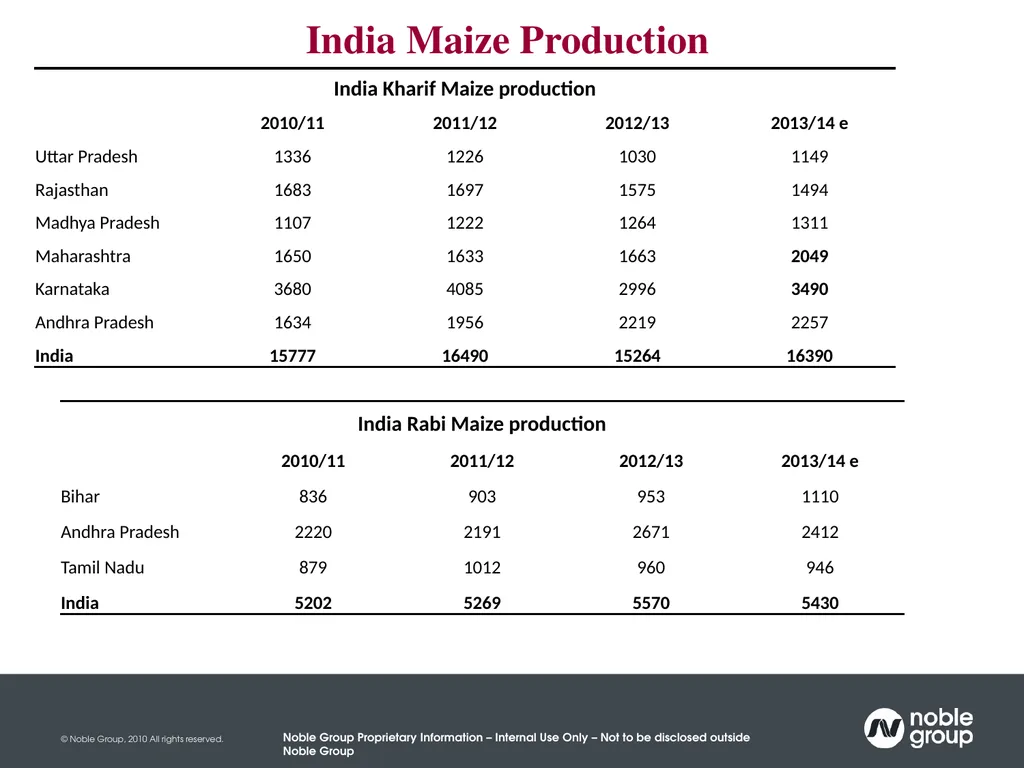
slide7. India Maize Production<br>
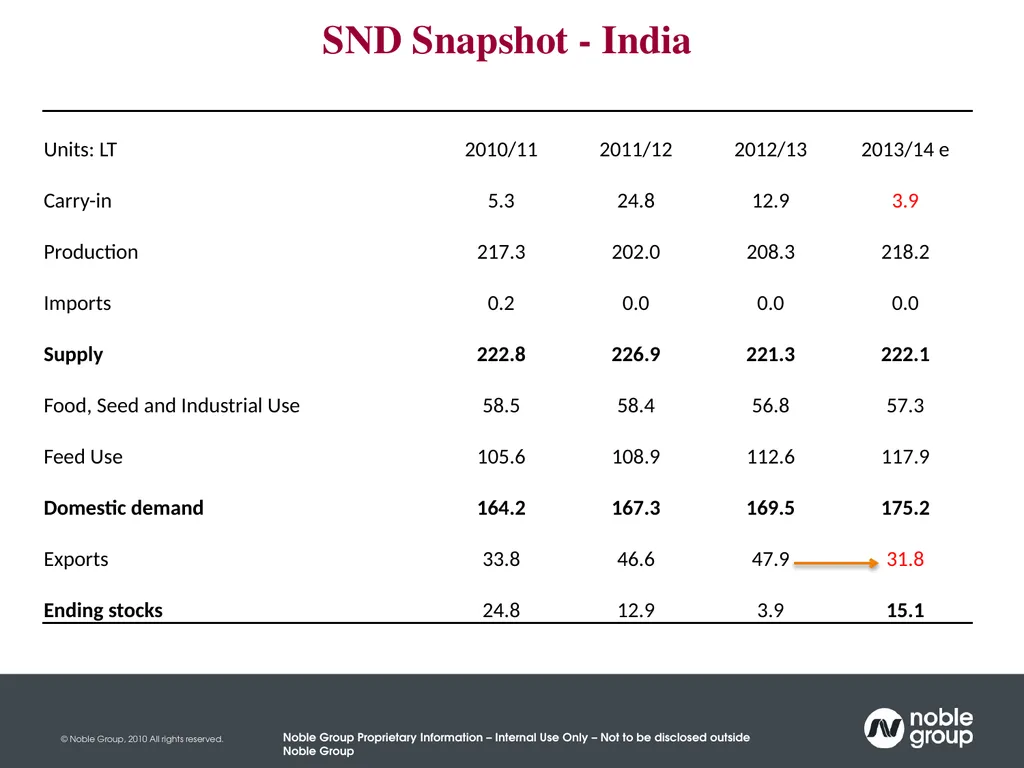
slide8. SND Snapshot - India<br>
slide9. Current Scenario – Indian Corn Increase in Kharif crop production by almost 1.1 MMT vs. last year (Maharashtra and Karnataka).
Non-competitive Indian corn prices vs. other origins kept Indian corn exports miniscule in first quarter, however with Ukraine crisis (and thus steep rise in world corn prices), Indian corn could find its way into export market.
Ending stocks to revive from last year exceptionally low levels with higher output + limited exports in Q1.
Alternate usages of corn increasing in starch/distillery/biofuel.
Poultry growth has been stagnant……
Still catching up with last year export volumes look unachievable till now….unless something major change happens across globe.<br>
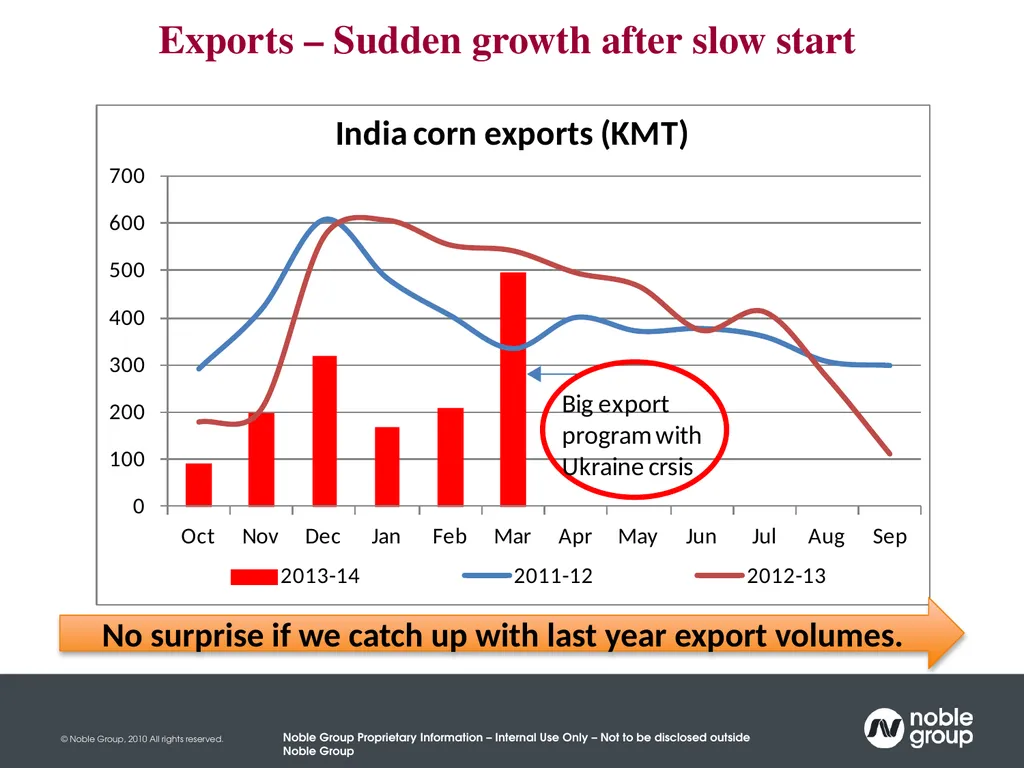
slide10. Exports – Sudden growth after slow start No surprise if we catch up with last year export volumes.<br>
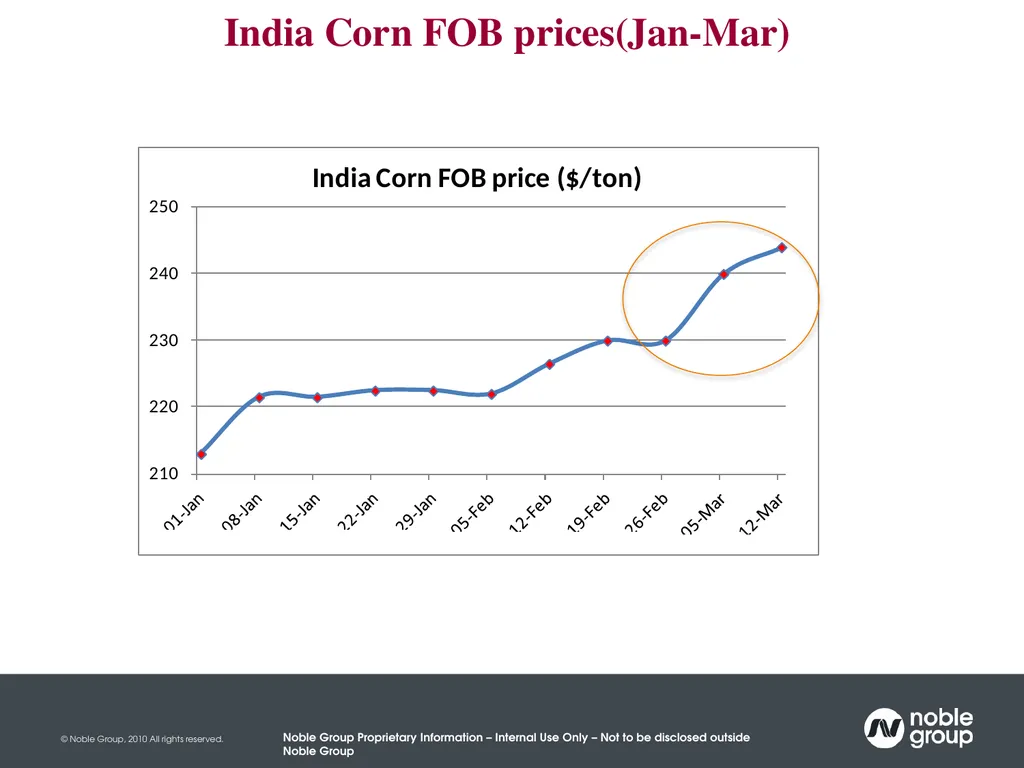
slide11. India Corn FOB prices(Jan-Mar)<br>
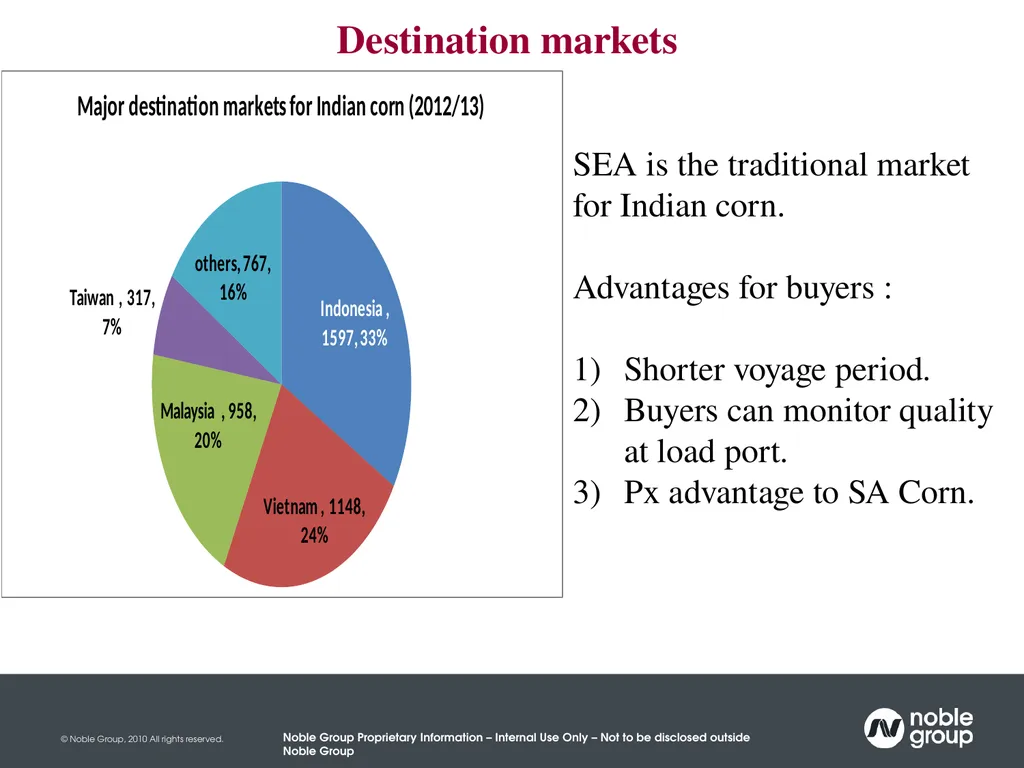
slide12. Destination markets SEA is the traditional market for Indian corn.
Advantages for buyers :
Shorter voyage period.
Buyers can monitor quality at load port.
Px advantage to SA Corn.<br>
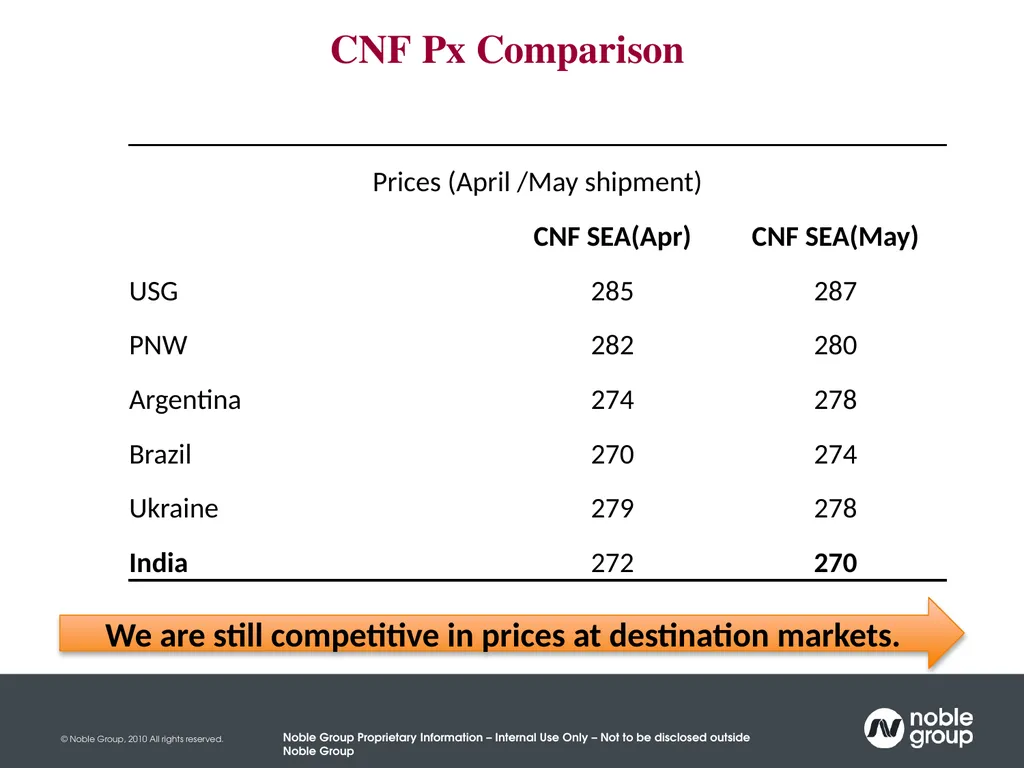
slide13. CNF Px Comparison We are still competitive in prices at destination markets.<br>
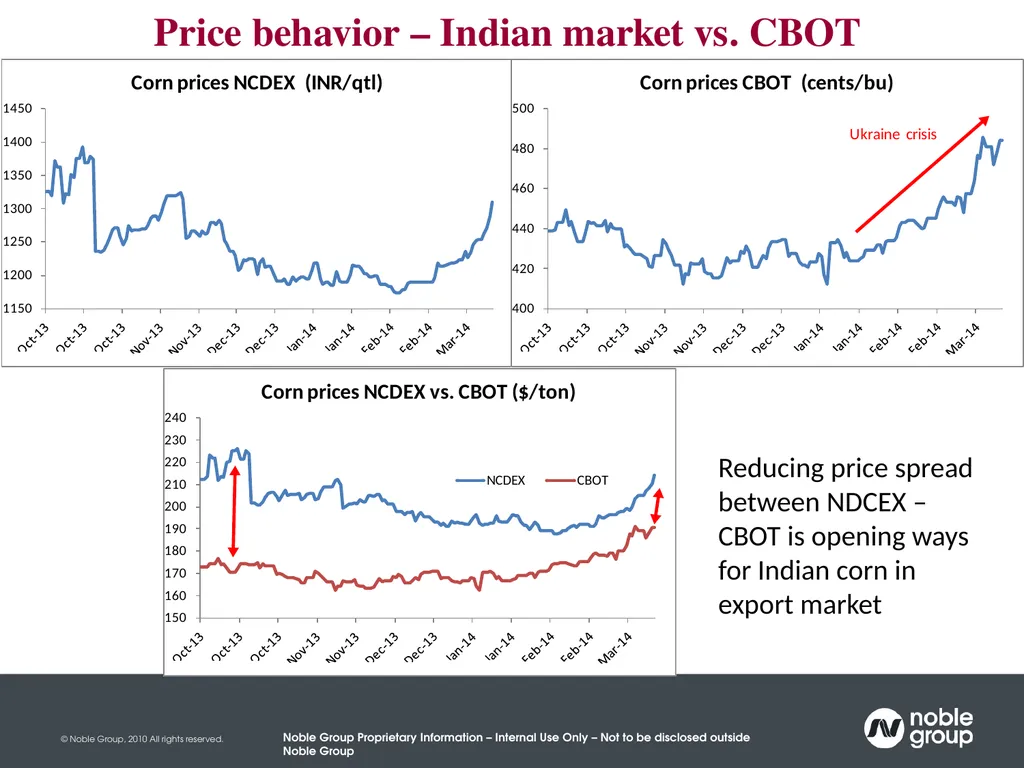
slide14. Price behavior – Indian market vs. CBOT Reducing price spread between NDCEX – CBOT is opening ways for Indian corn in export market<br>
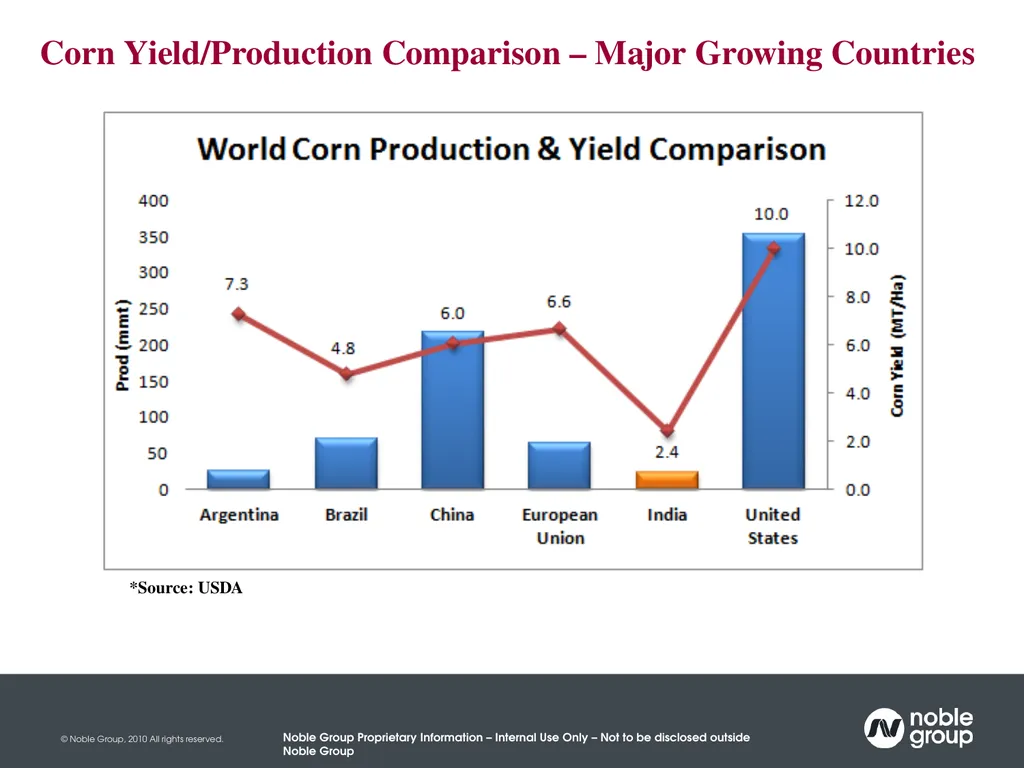
slide15. Corn Yield/Production Comparison – Major Growing Countries *Source: USDA<br>
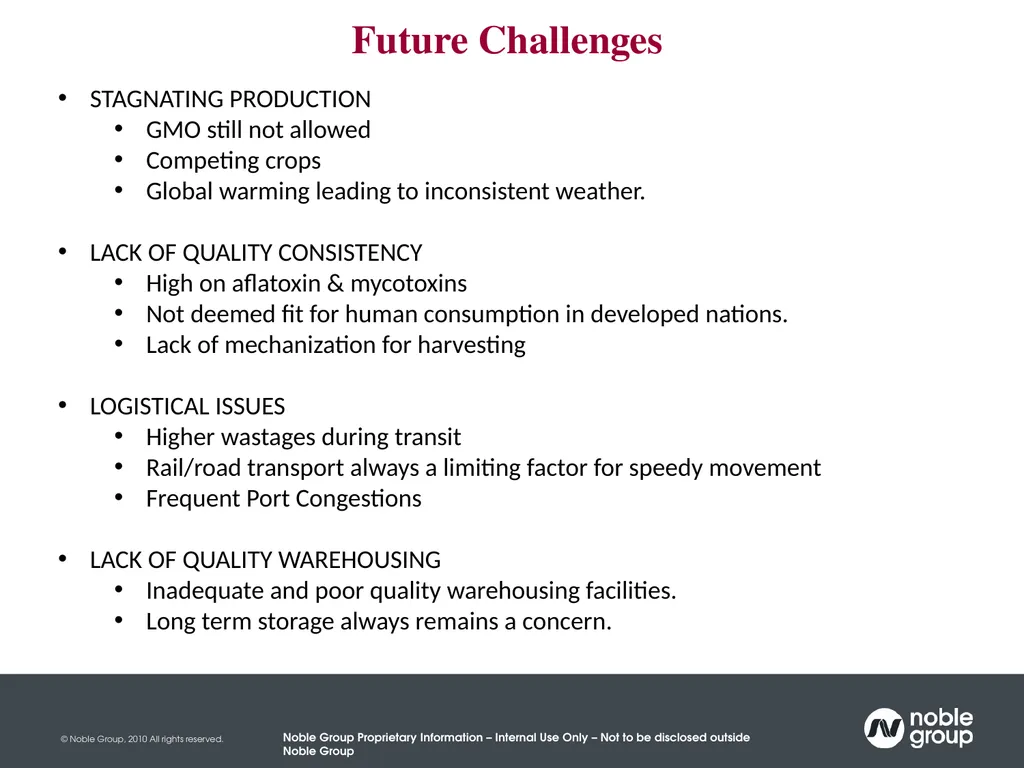
slide16. Future Challenges STAGNATING PRODUCTION
GMO still not allowed
Competing crops
Global warming leading to inconsistent weather.
LACK OF QUALITY CONSISTENCY
High on aflatoxin & mycotoxins
Not deemed fit for human consumption in developed nations.
Lack of mechanization for harvesting
LOGISTICAL ISSUES
Higher wastages during transit
Rail/road transport always a limiting factor for speedy movement
Frequent Port Congestions
LACK OF QUALITY WAREHOUSING
Inadequate and poor quality warehousing facilities.
Long term storage always remains a concern.<br>
slide17. Factors to watched in near future ? BLACK SEA CRISIS
Impact of US/Europe sanctions on Russia.
Logistics constraints emerging out
No other substitute to globally cheapest feed wheat & corn
US DRY WEATHER CONCERNS
Beginning has not been great .
More clarity to come in April.
FALL OUT OF INDIAN ELECTIONS
Rupee will strengthen in case new Government comes with clear majority.
Strong dollar could make exports all the more difficult.
LIKELY DELAYED MONSOON THIS YEAR.
Good for Bihar corn exports.
Next year crop sowing could have adverse impact.<br>
slide18. Thank You<br>
slide2. A Little about Noble +
Global Corn Trade and its likely impact on India
By Major Rajiv Yadav<br>
slide3. What do we do? Founded in 1987
Operates from over 140 locations and 35 countries
Three Business divisions (percentage of revenue)
Energy (68%)
Agriculture (16%)
Metals, Minerals and Ores (16%)
Owns assets and participates along the supply chain
Focuses on low cost sourcing to high growth markets
Noble is listed in Singapore , with headquarters in Hong Kong.
We are ranked number 76 in the 2013 Fortune 500<br>
slide4. Size & Growth Strong growth in all divisions
Revenue was USD 94b in 2012
Tonnage has increased nearly 60 per cent to 224 million tonnes per annum in the last five years Total Revenue
(US$ billion) * Our Former Logistics segment results are, from Q1 2011, consolidated into the Physical commodity divisions, reflecting the nature of our business we provide logistic/chartering services to support the underlying physical commodity segments.<br>
slide5. Agri business Focus on Grains, Oilseeds, Sugar, Cotton, Coffee and Cocoa
The Agri business unit traded over 44 metric tonnes in 2012 – almost triple the flow in 2006
Assets
New oilseed crushing facilities in Brazil, Argentina, Ukraine and South Africa, together with the existing four plants in China, produce a global throughput of 10 million tonnes per year
Cluster of strategically located port facilities in Argentina and Brazil
A complex of four state-of-the-art sugar and ethanol mills in Brazil
A 1400 tns per day edible oil refinery at Kandla(India)<br>
slide6. INDEX Production estimates – 2013/14
SND Snapshot
India
Exports
Growth
Destination markets
Price behavior
World Corn Yields Vs Indian Corn Yields
Future challenges<br>
slide7. India Maize Production<br>
slide8. SND Snapshot - India<br>
slide9. Current Scenario – Indian Corn Increase in Kharif crop production by almost 1.1 MMT vs. last year (Maharashtra and Karnataka).
Non-competitive Indian corn prices vs. other origins kept Indian corn exports miniscule in first quarter, however with Ukraine crisis (and thus steep rise in world corn prices), Indian corn could find its way into export market.
Ending stocks to revive from last year exceptionally low levels with higher output + limited exports in Q1.
Alternate usages of corn increasing in starch/distillery/biofuel.
Poultry growth has been stagnant……
Still catching up with last year export volumes look unachievable till now….unless something major change happens across globe.<br>
slide10. Exports – Sudden growth after slow start No surprise if we catch up with last year export volumes.<br>
slide11. India Corn FOB prices(Jan-Mar)<br>
slide12. Destination markets SEA is the traditional market for Indian corn.
Advantages for buyers :
Shorter voyage period.
Buyers can monitor quality at load port.
Px advantage to SA Corn.<br>
slide13. CNF Px Comparison We are still competitive in prices at destination markets.<br>
slide14. Price behavior – Indian market vs. CBOT Reducing price spread between NDCEX – CBOT is opening ways for Indian corn in export market<br>
slide15. Corn Yield/Production Comparison – Major Growing Countries *Source: USDA<br>
slide16. Future Challenges STAGNATING PRODUCTION
GMO still not allowed
Competing crops
Global warming leading to inconsistent weather.
LACK OF QUALITY CONSISTENCY
High on aflatoxin & mycotoxins
Not deemed fit for human consumption in developed nations.
Lack of mechanization for harvesting
LOGISTICAL ISSUES
Higher wastages during transit
Rail/road transport always a limiting factor for speedy movement
Frequent Port Congestions
LACK OF QUALITY WAREHOUSING
Inadequate and poor quality warehousing facilities.
Long term storage always remains a concern.<br>
slide17. Factors to watched in near future ? BLACK SEA CRISIS
Impact of US/Europe sanctions on Russia.
Logistics constraints emerging out
No other substitute to globally cheapest feed wheat & corn
US DRY WEATHER CONCERNS
Beginning has not been great .
More clarity to come in April.
FALL OUT OF INDIAN ELECTIONS
Rupee will strengthen in case new Government comes with clear majority.
Strong dollar could make exports all the more difficult.
LIKELY DELAYED MONSOON THIS YEAR.
Good for Bihar corn exports.
Next year crop sowing could have adverse impact.<br>
slide18. Thank You<br>