
INTERMEDIATE FINANCIAL ACCOUNTING CHAPTER 20 1
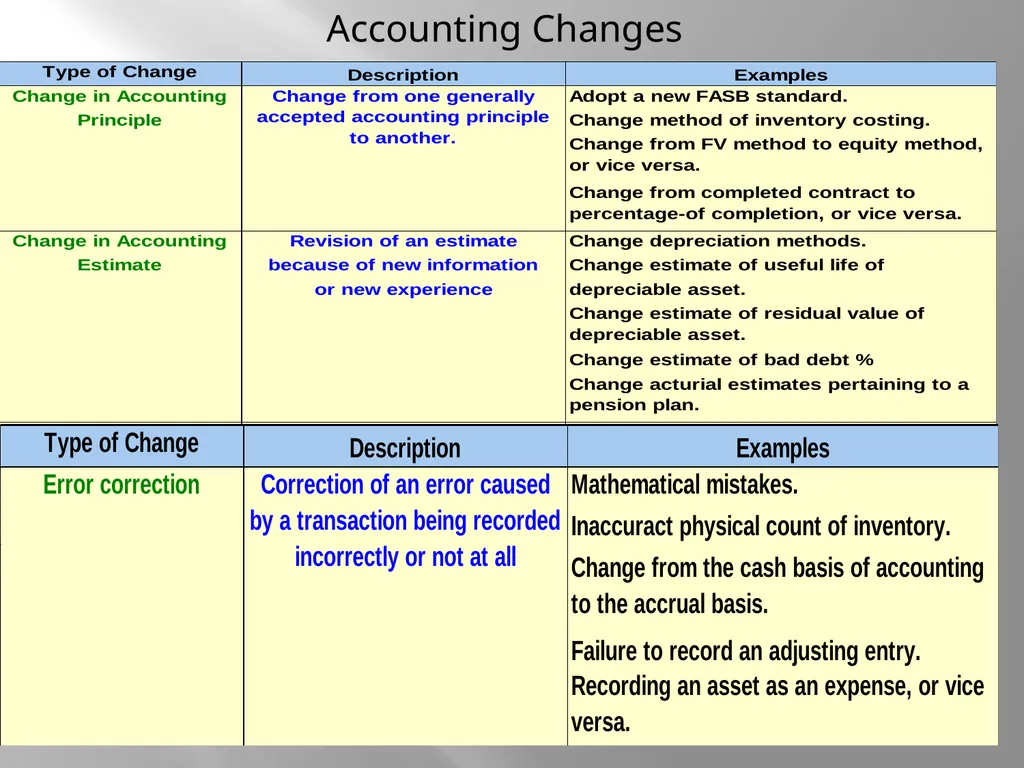
Description: INTERMEDIATE FINANCIAL ACCOUNTING CHAPTER 20 1 Accounting changes Accounting Errors Learning Objectives Recognize: a change in accounting estimate a change in accounting principle, and An error that needs correction how above reflected in
Related Topics
Download Presentation
"INTERMEDIATE FINANCIAL ACCOUNTING CHAPTER 20 1" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. INTERMEDIATE
FINANCIAL ACCOUNTING
CHAPTER 20 1 Accounting changes
&
Accounting Errors<br>
slide2. Learning Objectives Recognize:
a change in accounting estimate
a change in accounting principle, and
An error that needs correction
how above reflected in the financial statements
The presentation: & F/S disclosures<br>
slide3. ACCOUNTING CHANGES & ERRORS CORRECTIONS SFAS No. 154 :Accounting Changes and Error Correction
IFRS 8:… January 10, 2014 3<br>
slide4. Accounting Changes<br>
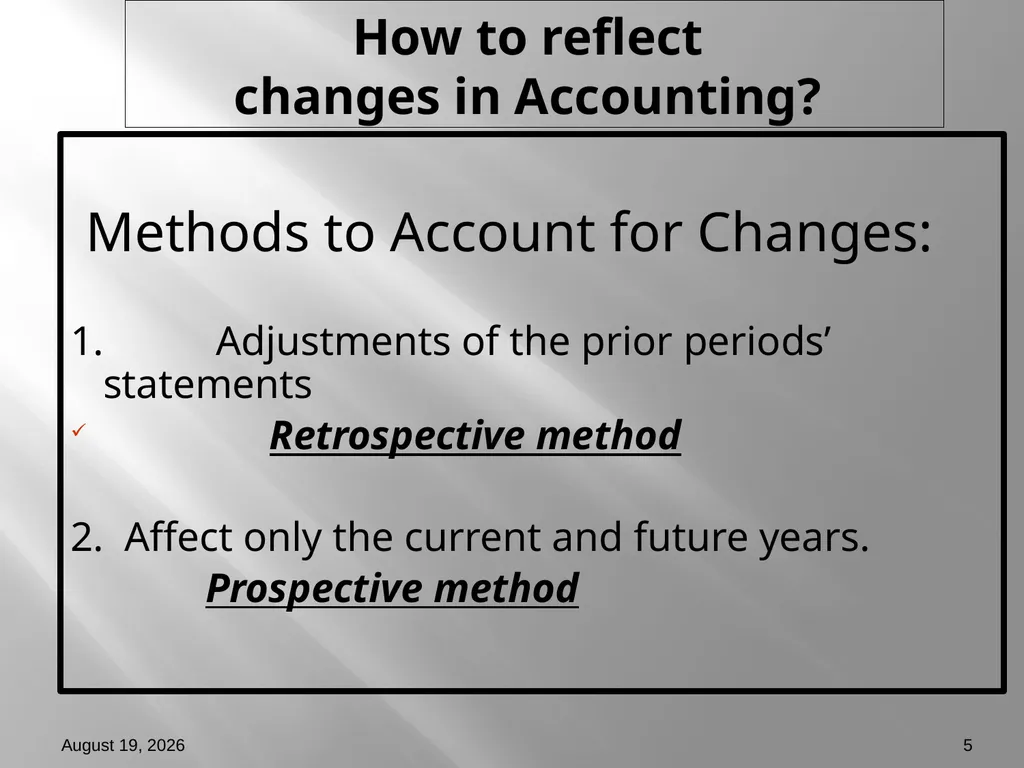
slide5. How to reflect changes in Accounting? Methods to Account for Changes:
1. Adjustments of the prior periods’ statements
Retrospective method
2. Affect only the current and future years.
Prospective method January 10, 2014 5<br>
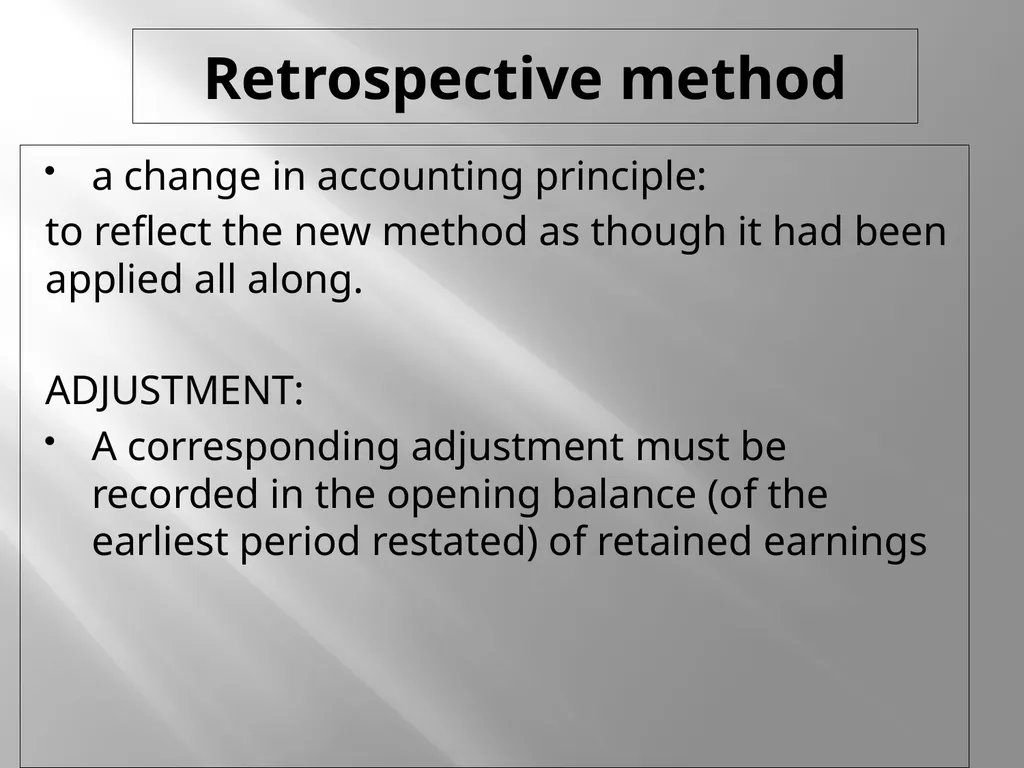
slide6. Retrospective method a change in accounting principle:
to reflect the new method as though it had been applied all along.
ADJUSTMENT:
A corresponding adjustment must be recorded in the opening balance (of the earliest period restated) of retained earnings<br>
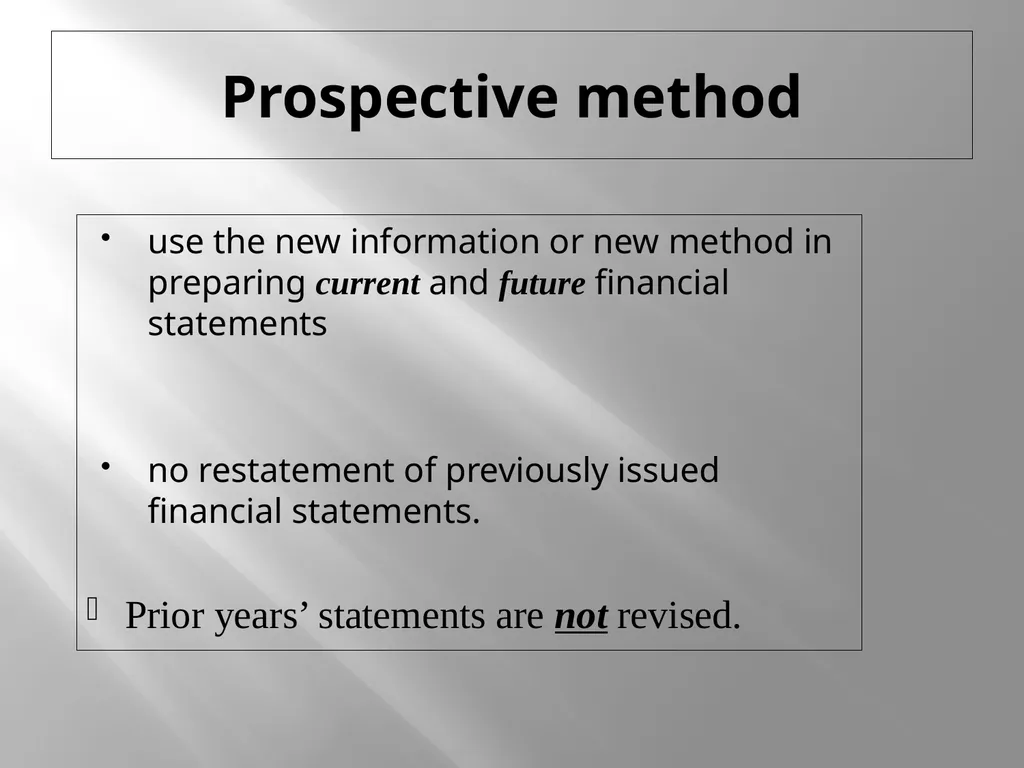
slide7. Prospective method use the new information or new method in preparing current and future financial statements
no restatement of previously issued financial statements.
Prior years’ statements are not revised.<br>
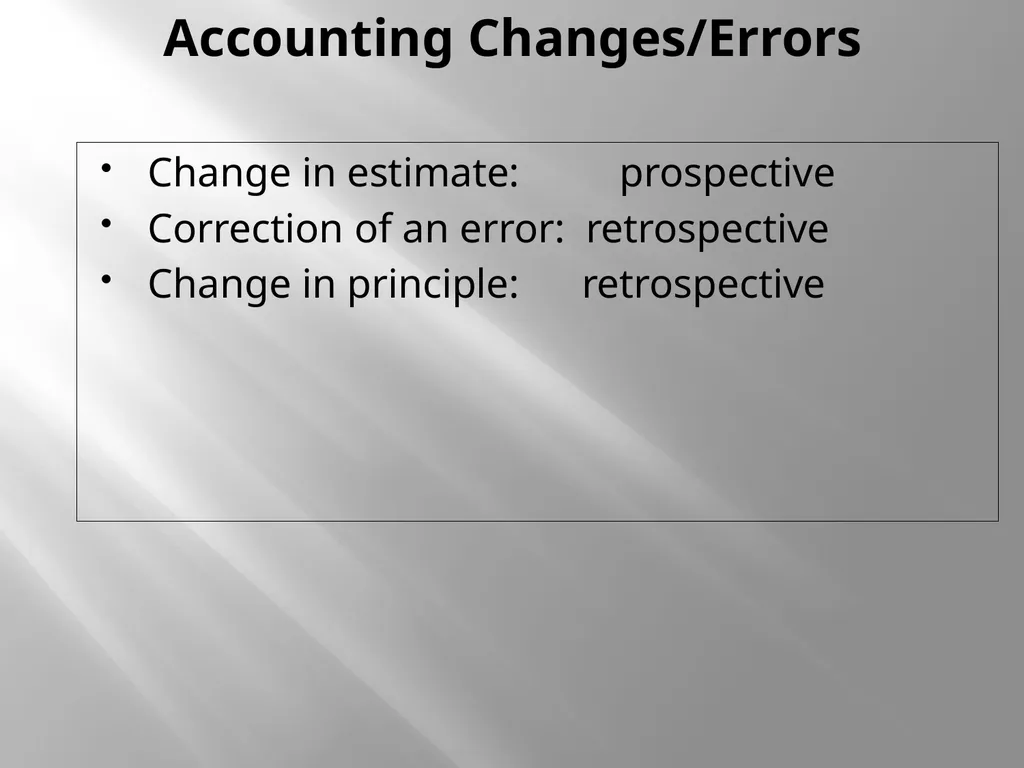
slide8. Accounting Changes/Errors Change in estimate: prospective
Correction of an error: retrospective
Change in principle: retrospective<br>
slide9. CHANGE IN ESTIMATE January 10, 2014 9 Uncollectible receivables
Inventory obsolescence
Useful lives
Salvage value
Warranty costs
Recoverable reserves
Change in depreciation method<br>
slide10. Change in Accounting Estimate/Principle Can a change in accounting principle effect change in estimate?
One type of change in accounting estimate affected by changes in accounting principle (estimates is inseparable from the effect of a related change in accounting principle)
Change in Depreciation Method January 10, 2014 10<br>
slide11. ERROR CORRECTIONS January 10, 2014 11 Errors discovered currently in the course of normal accounting procedures. Math errors
Posting to the wrong account
Misstating an account
Omitting an account from the trial balance
…….Accounts effected<br>
slide12. Error Corrections If detected in current period, before books are closed:
Correct the account through normal accounting adjustment.
If detected in subsequent period, after books are closed:
make adjustment directly to Retained Earnings
Disclosure note. January 10, 2014 12<br>
slide13. DISCLOSURE NOTES After the change is made, a disclosure note is needed:
Provide JUSTIFICATION for the change
Identify that COMPARATIVE INFORMATION has been revised
Report any EPS affected for the current and Prior periods. January 10, 2014 13<br>
slide14. CHANGE IN ACCOUNTING METHODS PART II:
Change from one GAAP to another January 10, 2014 14<br>
&
Accounting Errors<br>
slide2. Learning Objectives Recognize:
a change in accounting estimate
a change in accounting principle, and
An error that needs correction
how above reflected in the financial statements
The presentation: & F/S disclosures<br>
slide3. ACCOUNTING CHANGES & ERRORS CORRECTIONS SFAS No. 154 :Accounting Changes and Error Correction
IFRS 8:… January 10, 2014 3<br>
slide4. Accounting Changes<br>
slide5. How to reflect changes in Accounting? Methods to Account for Changes:
1. Adjustments of the prior periods’ statements
Retrospective method
2. Affect only the current and future years.
Prospective method January 10, 2014 5<br>
slide6. Retrospective method a change in accounting principle:
to reflect the new method as though it had been applied all along.
ADJUSTMENT:
A corresponding adjustment must be recorded in the opening balance (of the earliest period restated) of retained earnings<br>
slide7. Prospective method use the new information or new method in preparing current and future financial statements
no restatement of previously issued financial statements.
Prior years’ statements are not revised.<br>
slide8. Accounting Changes/Errors Change in estimate: prospective
Correction of an error: retrospective
Change in principle: retrospective<br>
slide9. CHANGE IN ESTIMATE January 10, 2014 9 Uncollectible receivables
Inventory obsolescence
Useful lives
Salvage value
Warranty costs
Recoverable reserves
Change in depreciation method<br>
slide10. Change in Accounting Estimate/Principle Can a change in accounting principle effect change in estimate?
One type of change in accounting estimate affected by changes in accounting principle (estimates is inseparable from the effect of a related change in accounting principle)
Change in Depreciation Method January 10, 2014 10<br>
slide11. ERROR CORRECTIONS January 10, 2014 11 Errors discovered currently in the course of normal accounting procedures. Math errors
Posting to the wrong account
Misstating an account
Omitting an account from the trial balance
…….Accounts effected<br>
slide12. Error Corrections If detected in current period, before books are closed:
Correct the account through normal accounting adjustment.
If detected in subsequent period, after books are closed:
make adjustment directly to Retained Earnings
Disclosure note. January 10, 2014 12<br>
slide13. DISCLOSURE NOTES After the change is made, a disclosure note is needed:
Provide JUSTIFICATION for the change
Identify that COMPARATIVE INFORMATION has been revised
Report any EPS affected for the current and Prior periods. January 10, 2014 13<br>
slide14. CHANGE IN ACCOUNTING METHODS PART II:
Change from one GAAP to another January 10, 2014 14<br>