
Introduction to Investing Take Charge of Your

Description: Introduction to Investing Take Charge of Your Finances Family Economics and Financial Education Saving vs. Investing Savings is for short-term goals and emergencies Investing is for long-term goals, such as college or retirement. Remember:
Related Topics
Download Presentation
"Introduction to Investing Take Charge of Your" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Introduction to Investing Take Charge of Your Finances
Family Economics and Financial Education<br>
slide2. Saving vs. Investing Savings is for short-term goals and emergencies Investing is for long-term goals, such as college or retirement. Remember: The purpose of savings is to develop financial security. You should have 3 – 6 months of salary in savings BEFORE you start investing.<br>
slide3. What is Investing? The purchase of assets with the goal of increasing future income
Focuses on wealth accumulation
Appropriate for long-term goals What are examples of long-term goals that can be accomplished by investing?<br>
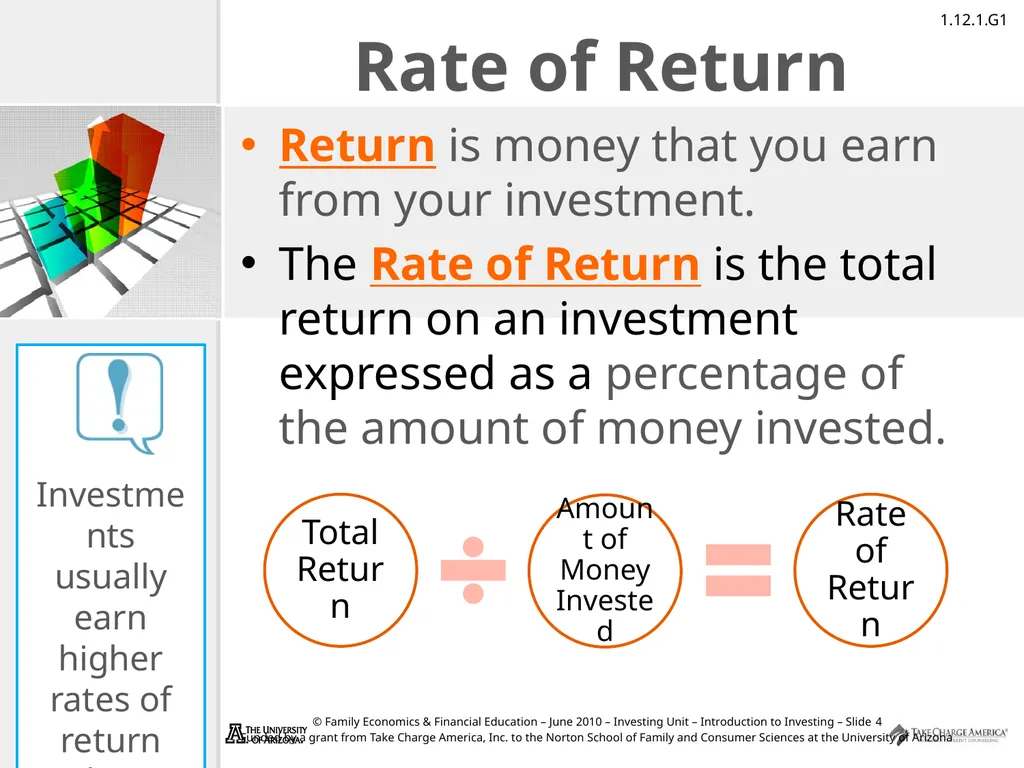
slide4. Rate of Return Return is money that you earn from your investment.
The Rate of Return is the total return on an investment expressed as a percentage of the amount of money invested. Investments usually earn higher rates of return than savings tools.<br>
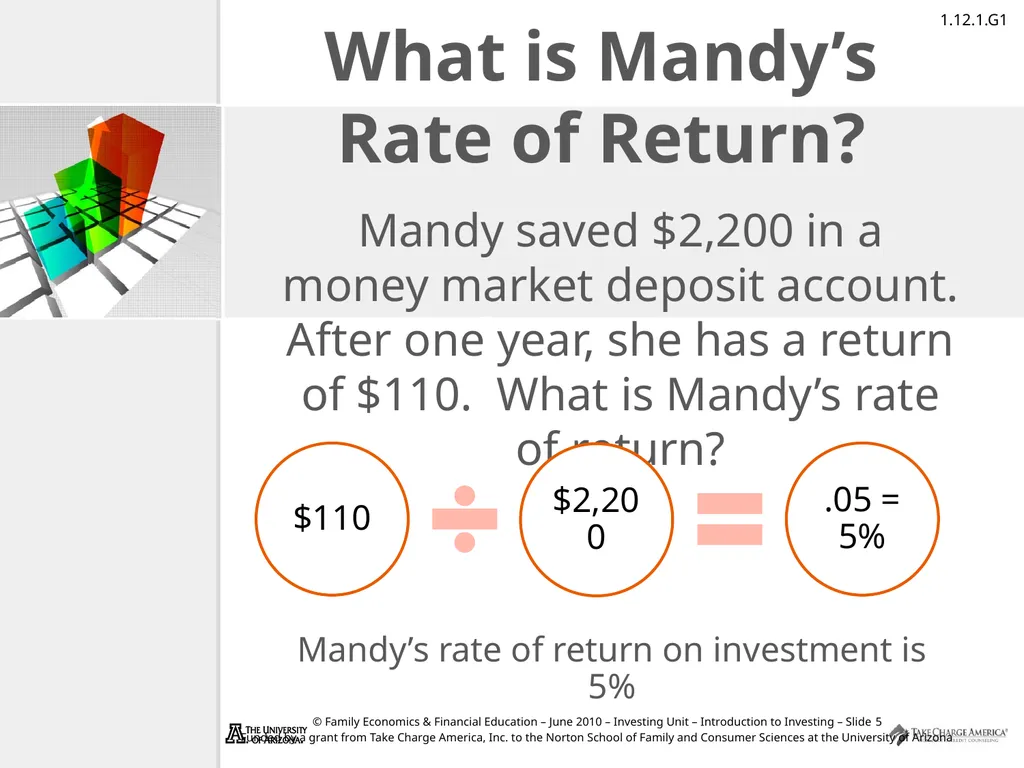
slide5. What is Mandy’s Rate of Return? Mandy saved $2,200 in a money market deposit account. After one year, she has a return of $110. What is Mandy’s rate of return? Mandy’s rate of return on investment is 5%<br>
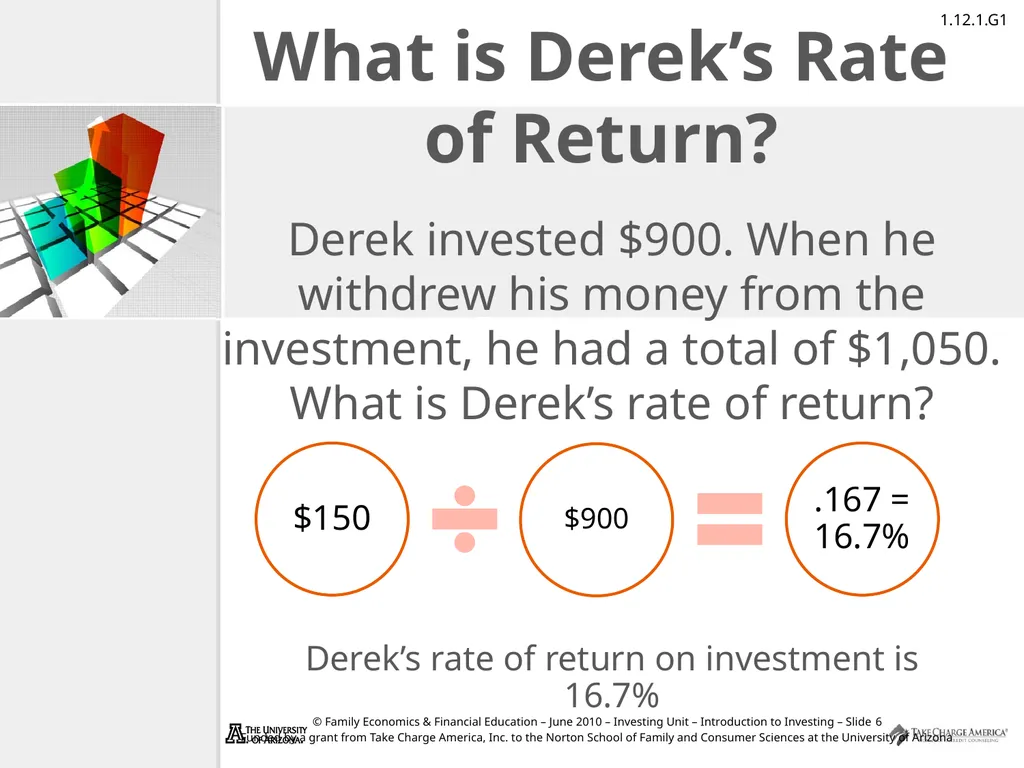
slide6. What is Derek’s Rate of Return? Derek invested $900. When he withdrew his money from the investment, he had a total of $1,050. What is Derek’s rate of return? Derek’s rate of return on investment is 16.7%<br>
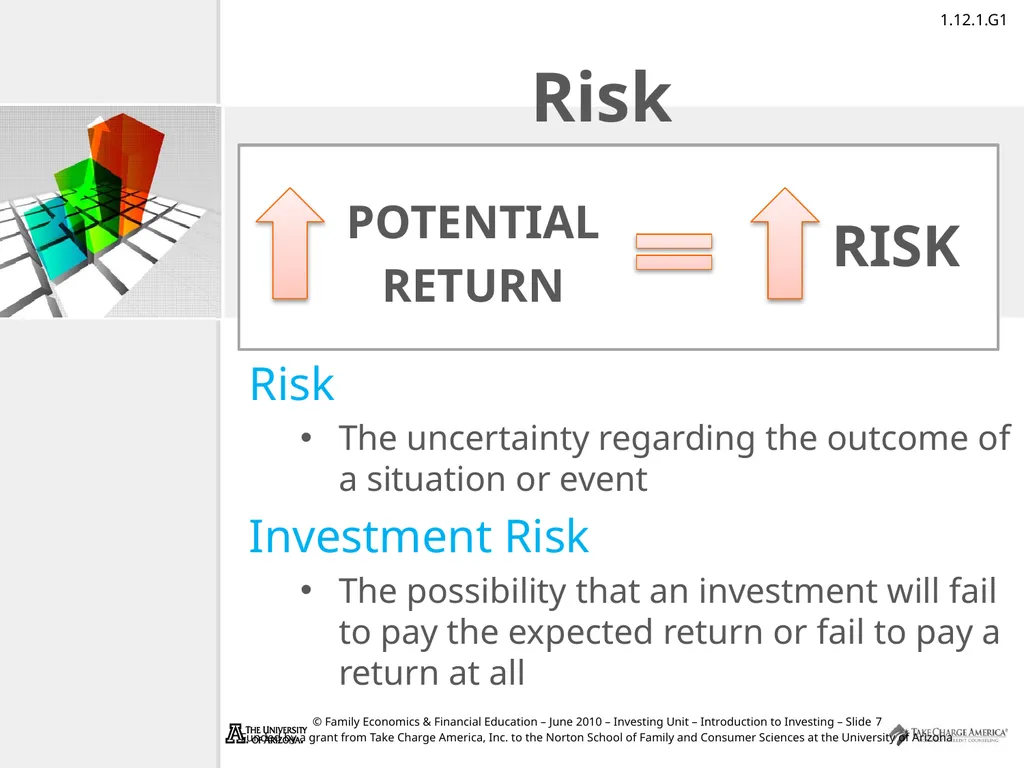
slide7. Risk POTENTIAL
RETURN RISK Risk
The uncertainty regarding the outcome of a situation or event
Investment Risk
The possibility that an investment will fail to pay the expected return or fail to pay a return at all<br>
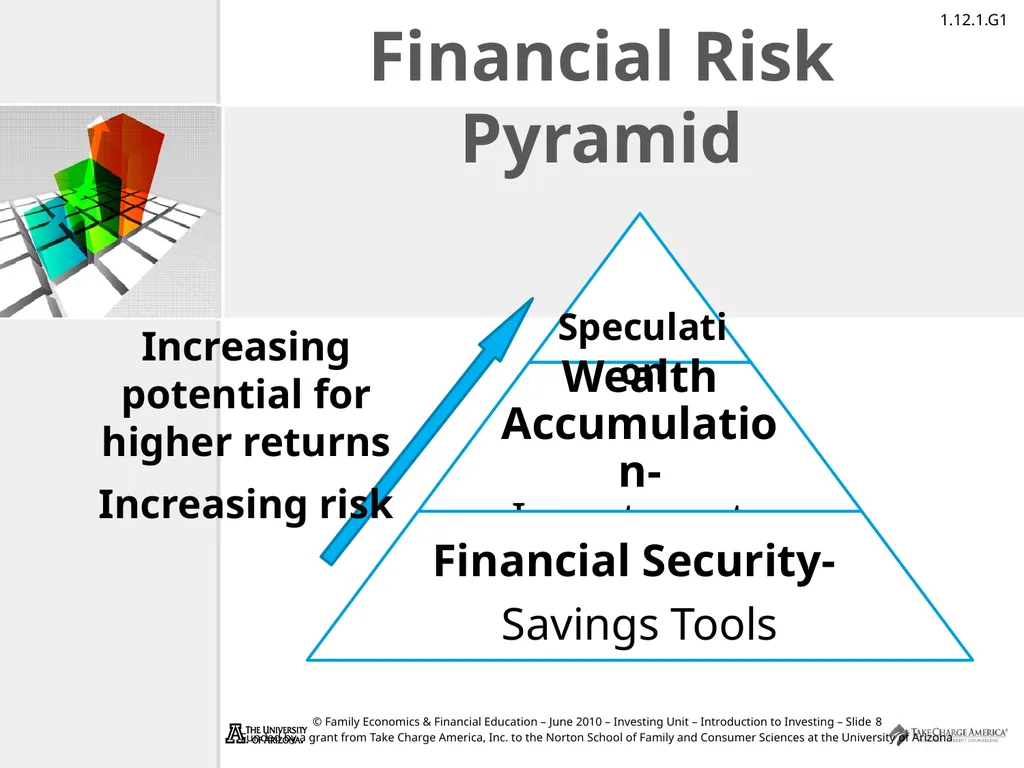
slide8. Financial Risk Pyramid Speculation Increasing potential for higher returns
Increasing risk<br>
slide9. Inflation Inflation
The rise in the general level of prices Inflation Risk
The danger that money won’t be worth as much in the future as it is today Inflation risk should not be a concern with savings since the goal of savings is to provide current financial security The rate of return on an investment should be higher than the rate of inflation.<br>
slide10. Investment Philosophy Each individual has a tolerance level for the amount of risk they are willing to take on Investment Philosophy
An individual’s general approach to investment risk The greater the risk a person is willing to make on an investment, the greater the potential return will be. Generally divided into three categories: conservative, moderate, and aggressive<br>
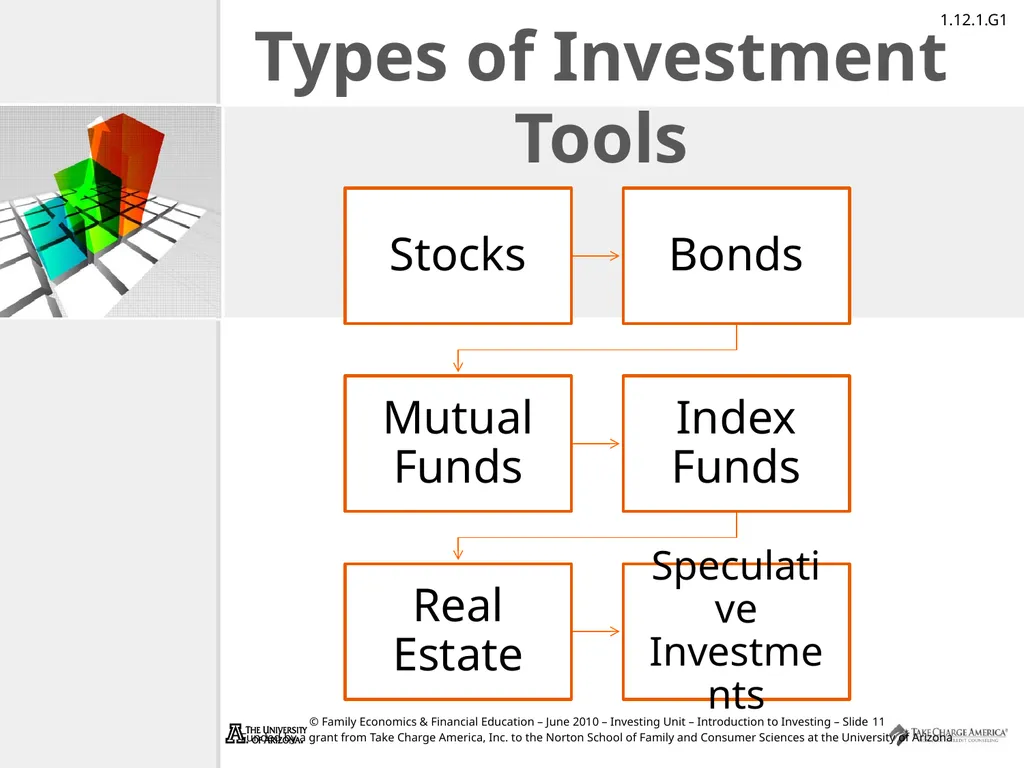
slide11. Types of Investment Tools<br>
slide12. Stocks Stock
A share of ownership in a company
Stockholder or shareholder
Owner of the stock Usually a stockholder owns a very small part of a company.<br>
slide13. Return on Stocks There are two ways people can make money on stocks:
Dividends
Dividends are the share of profits distributed in cash to stockholders
Market Price
The current price that a buyer is willing to pay for stock<br>
slide14. Return on Stocks If stock is sold for a market price higher than what was paid, stockholder will receive a return (make money).
If stock is sold for a market price lower than what was paid, stockholder will lose money<br>
slide15. Stock Markets Stocks are bought and sold on stock markets by people called brokers.
The main stock markets in the U.S. are:
New York Stock Exchange (NYSE)
NASDAQ<br>
slide16. Stock Activity We are going to learn about stocks using McDonald’s as an example.<br>
slide17. Bonds Bonds are loans.
A company or government will borrow money from investors by issuing bonds.
Example: The Crazy Hat Co. wants to build a new distribution center in Louisville, KY which will cost $7,000,000. They can issue 7,000 bonds at $1,000 each.
7,000 x $1,000 = $7,000,000 Bonds are less risky than stocks but do not have the potential to earn as much as a stock.<br>
slide18. Bonds The company or government pays annual interest to the investor until the maturity date is reached
The maturity date is the specified time in the future when the principal is repaid to the bondholder.
Bonds issued by a company are called corporate bonds.
Bonds issued by a government are called:
Treasury bonds (federal government)
Municipal bonds (local governments)<br>
slide19. Example The Crazy Hat Co. issues $1,000 bonds that pay 4.5% interest with a maturity date of 11/22/2012 (2 years from today).
You buy the bond for $1,000.
Each year you will receive a payment of $1,000 x .045 = $45
On 11/22/2012, you will also get your $1,000 back.<br>
slide20. Stocks vs. Bonds Stocks are equity.
The stockholder actually owns a piece of the company.
Equity is the value of the company.
For example, if a company has 10 million shares of stock, and each share is worth $5, then the company’s equity is:
10,000,000 x $5 = $50,000,000<br>
slide21. Stocks vs. Bonds Bonds are debt.
Debt means the bondholder has lent money to the company that the company will repay with interest.
Companies must repay debt before they pay anything to stockholders.
Therefore, bonds are less risky than stocks.<br>
slide22. Portfolio Diversification Portfolio Diversification- reduces risk by spreading investment money among different investment tools Creates a collection of investments that will increase return while reducing risk The main goal of diversification is to reduce risk. Referred to as “Building a Portfolio.”<br>
slide23. Mutual Funds Mutual fund- invests money in a diversified portfolio of stocks and bonds Always research the fees charged by a mutual fund. Reduces investment risk by helping people diversify their portfolio Fees can be high Saves investors time<br>
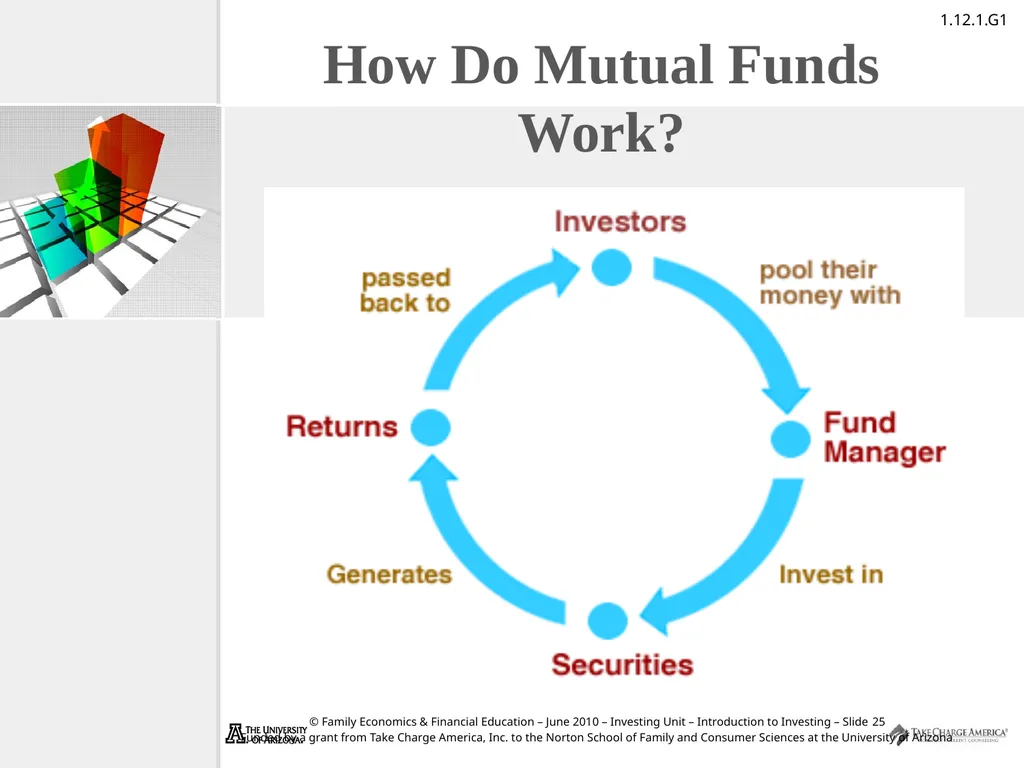
slide24. How Do Mutual Funds Work? Individuals buy shares
The money is used to purchase stocks, bonds, and other investments.
Profits returned to shareholders monthly, quarterly, or semi-annually in the form of dividends.<br>
slide25. How Do Mutual Funds Work?<br>
slide26. What is the Advantage of Investing in a Mutual Fund? Allows small investors to get professional account management and diversification normally only available to large investors.
This allows investors with a little bit of money to be able to invest in a variety of stocks, bonds, & other investments.<br>
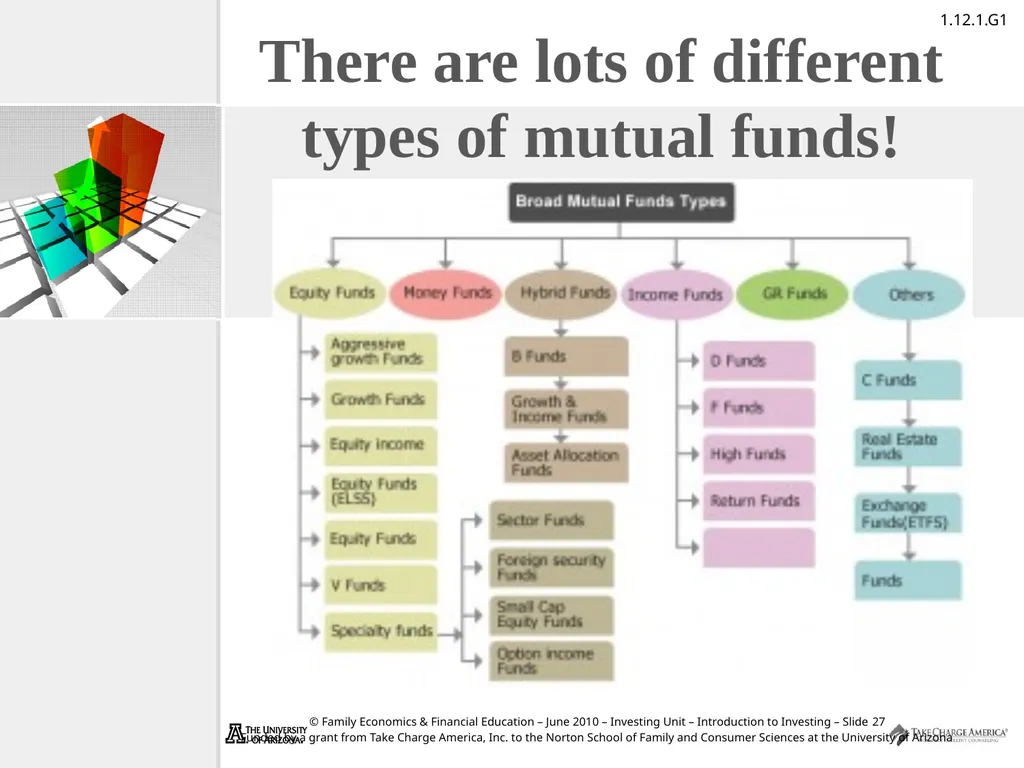
slide27. There are lots of different types of mutual funds!<br>
slide28. Market Indexes A market index is the value of a group of stocks or other investments.
Market indexes are intended to represent an entire stock market and thus track the market's changes over time.<br>
slide29. Market Indexes Dow Jones Industrial Average (DJIA or “The Dow”)
30 large companies traded on NYSE or NASDAQ
Standard & Poors 500 Index (S&P 500)
An index of 500 large companies selected by a committee
Others
Russell 2000, Wilshire 5000<br>
slide30. Index Fund A mutual fund that was designed to reduce fees by investing in the stocks and bonds that make up an index.
Offers high diversification with low fees.<br>
slide31. Real Estate Includes any residential or commercial property or land as well as the rights accompanying that land
A family home is not considered an investment asset
Can be risky and more time consuming but has potential for large returns Examples of real estate investments include rental units and commercial property.<br>
slide32. Speculative Investments Have the potential for significant fluctuations in return over a short period of time
Examples- future, options, commercial paper, collectibles
Recommended for people with an aggressive investment philosophy and a high level of financial security<br>
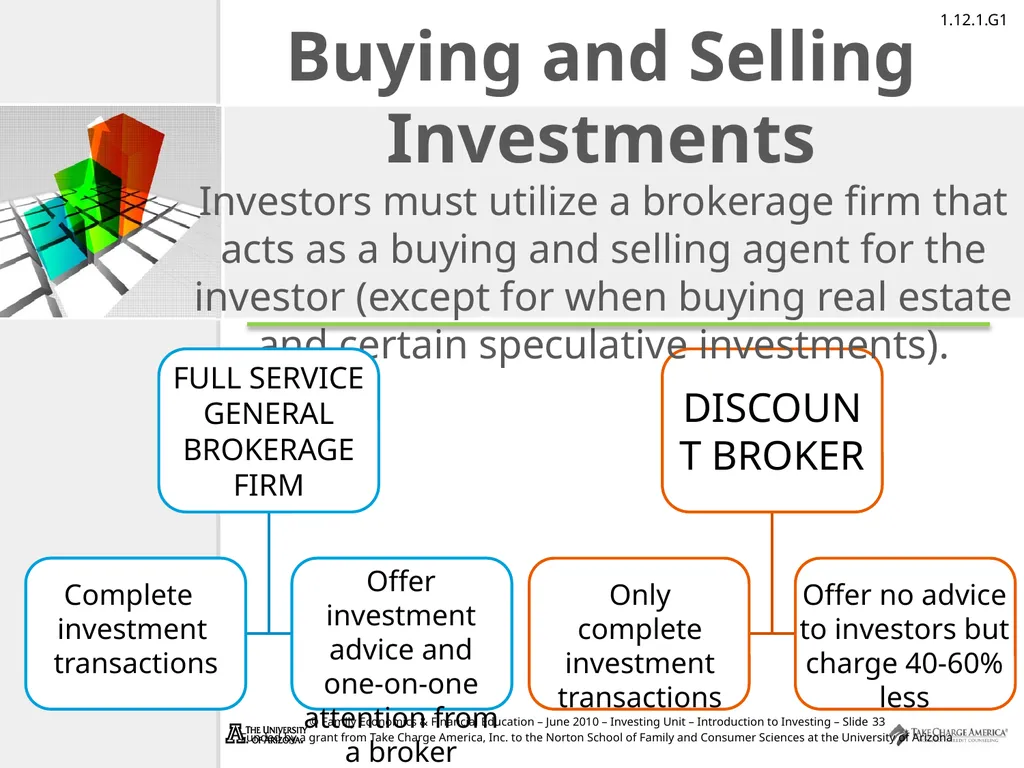
slide33. Buying and Selling Investments Investors must utilize a brokerage firm that acts as a buying and selling agent for the investor (except for when buying real estate and certain speculative investments). Complete
investment
transactions Offer investment advice and one-on-one attention from a broker Only complete investment transactions Offer no advice to investors but charge 40-60% less<br>
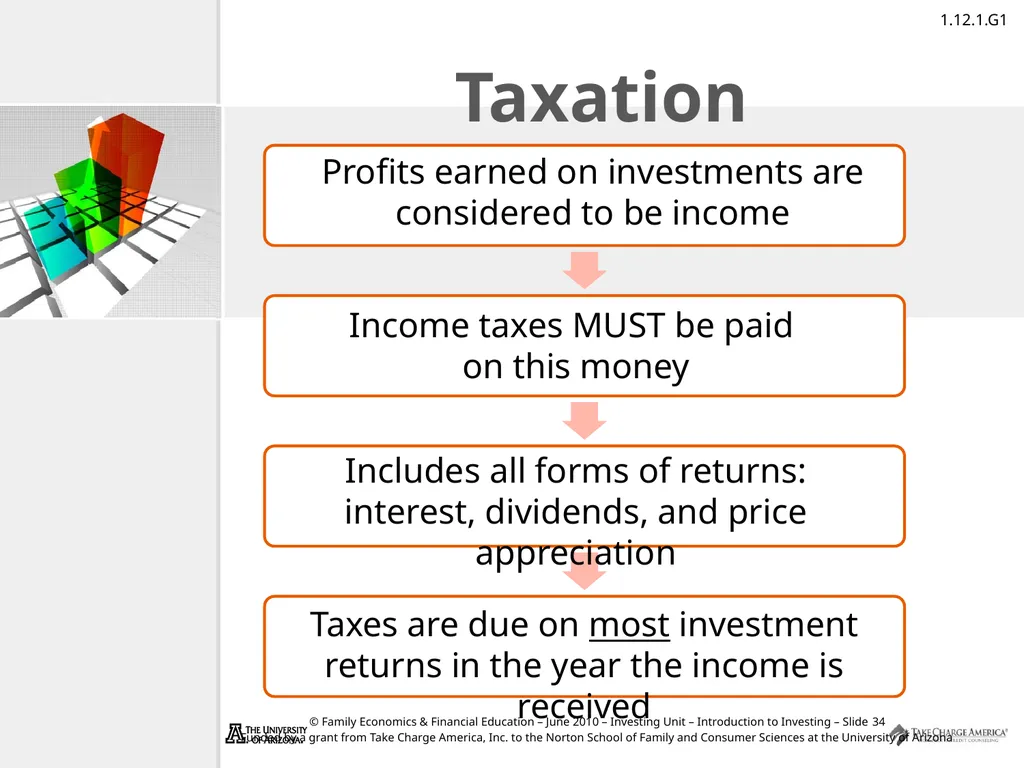
slide34. Taxation Profits earned on investments are considered to be income Income taxes MUST be paid
on this money Includes all forms of returns: interest, dividends, and price appreciation Taxes are due on most investment returns in the year the income is received<br>
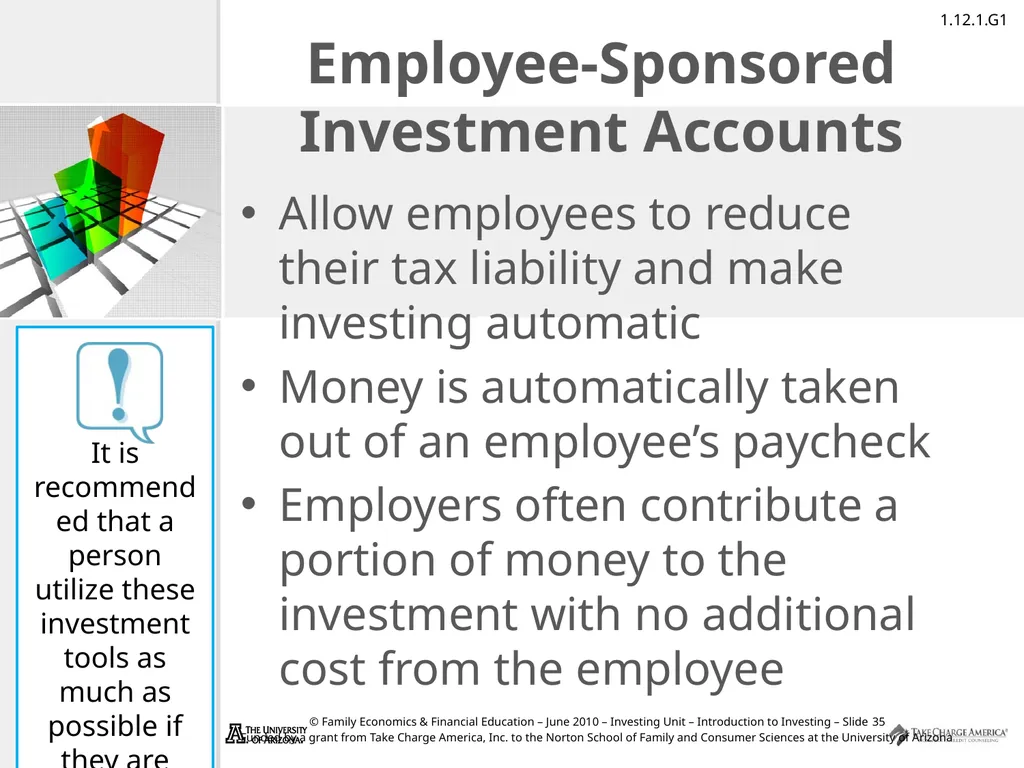
slide35. Employee-Sponsored Investment Accounts Allow employees to reduce their tax liability and make investing automatic
Money is automatically taken out of an employee’s paycheck
Employers often contribute a portion of money to the investment with no additional cost from the employee It is recommended that a person utilize these investment tools as much as possible if they are offered.<br>
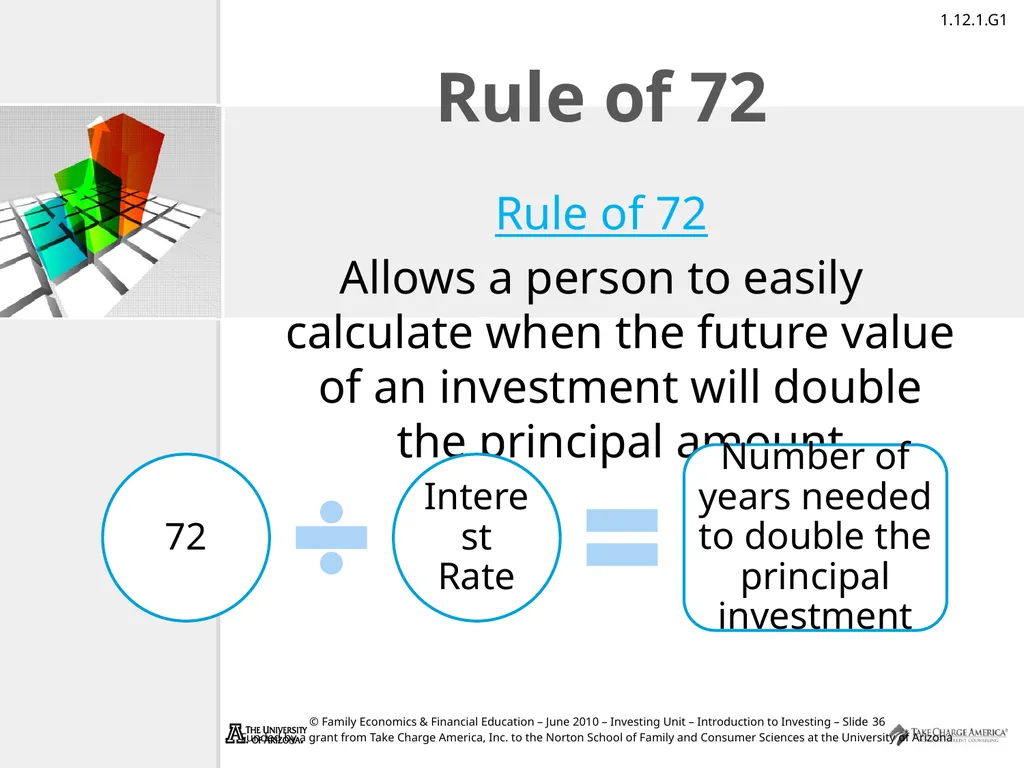
slide36. Rule of 72 Rule of 72
Allows a person to easily calculate when the future value of an investment will double the principal amount<br>
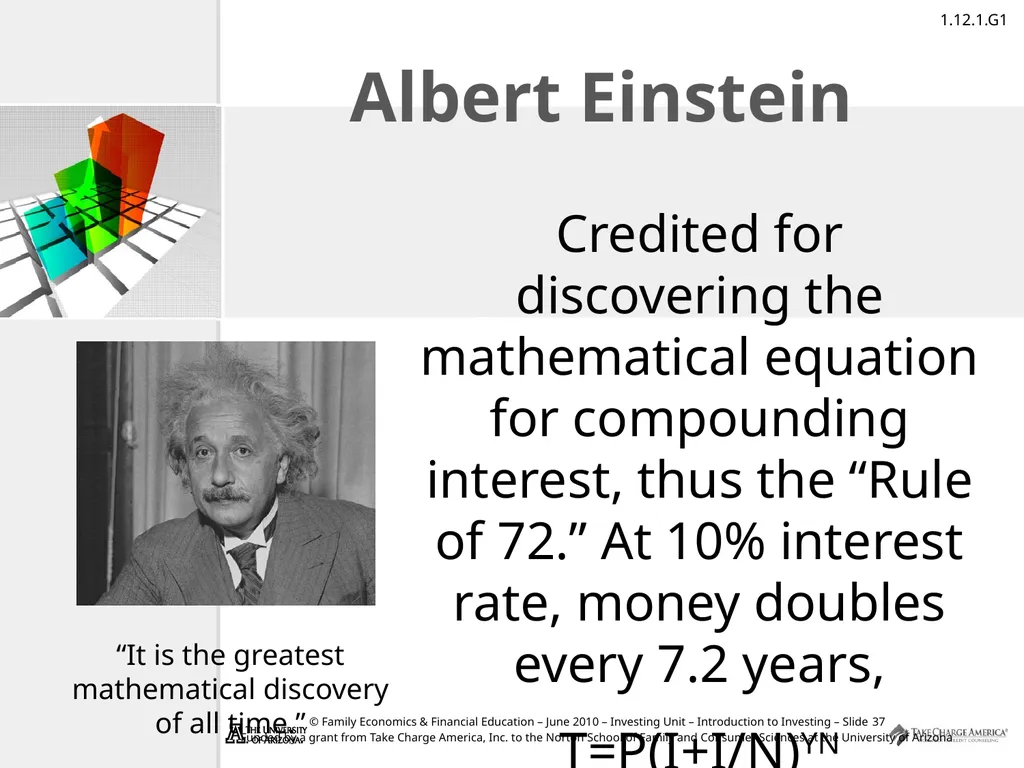
slide37. Albert Einstein Credited for discovering the mathematical equation for compounding interest, thus the “Rule of 72.” At 10% interest rate, money doubles every 7.2 years,
T=P(I+I/N)YN “It is the greatest mathematical discovery of all time.”<br>
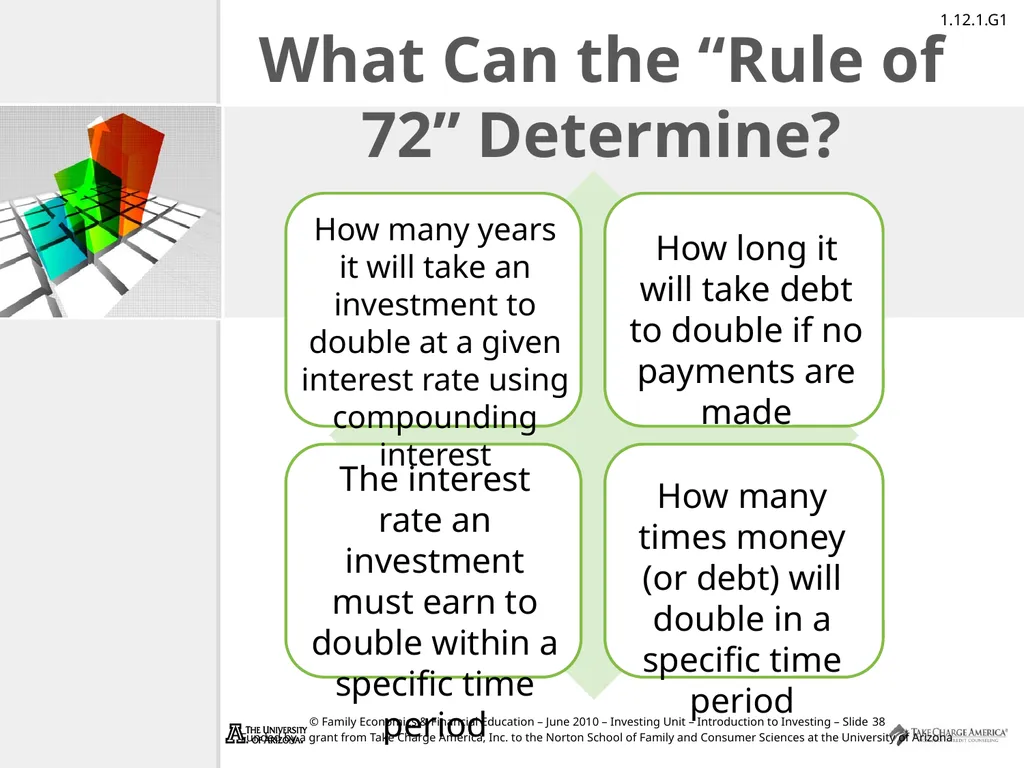
slide38. What Can the “Rule of 72” Determine? How many years it will take an investment to double at a given interest rate using compounding interest How long it will take debt to double if no payments are made The interest rate an investment must earn to double within a specific time period How many times money (or debt) will double in a specific time period<br>
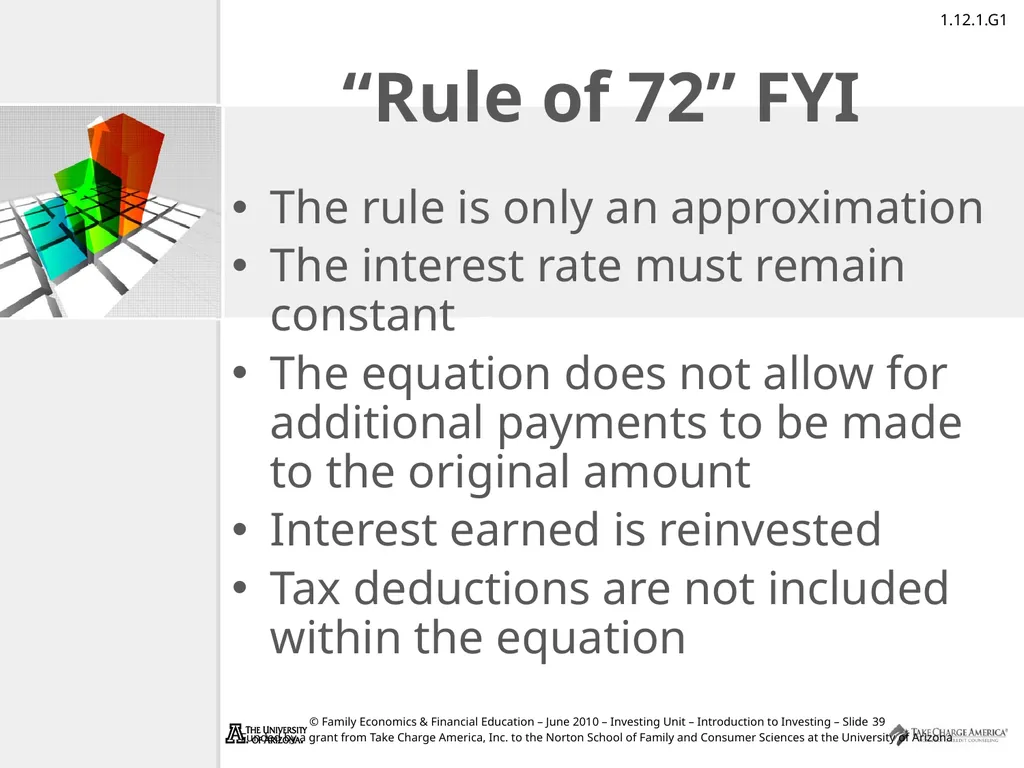
slide39. “Rule of 72” FYI The rule is only an approximation
The interest rate must remain constant
The equation does not allow for additional payments to be made to the original amount
Interest earned is reinvested
Tax deductions are not included within the equation<br>
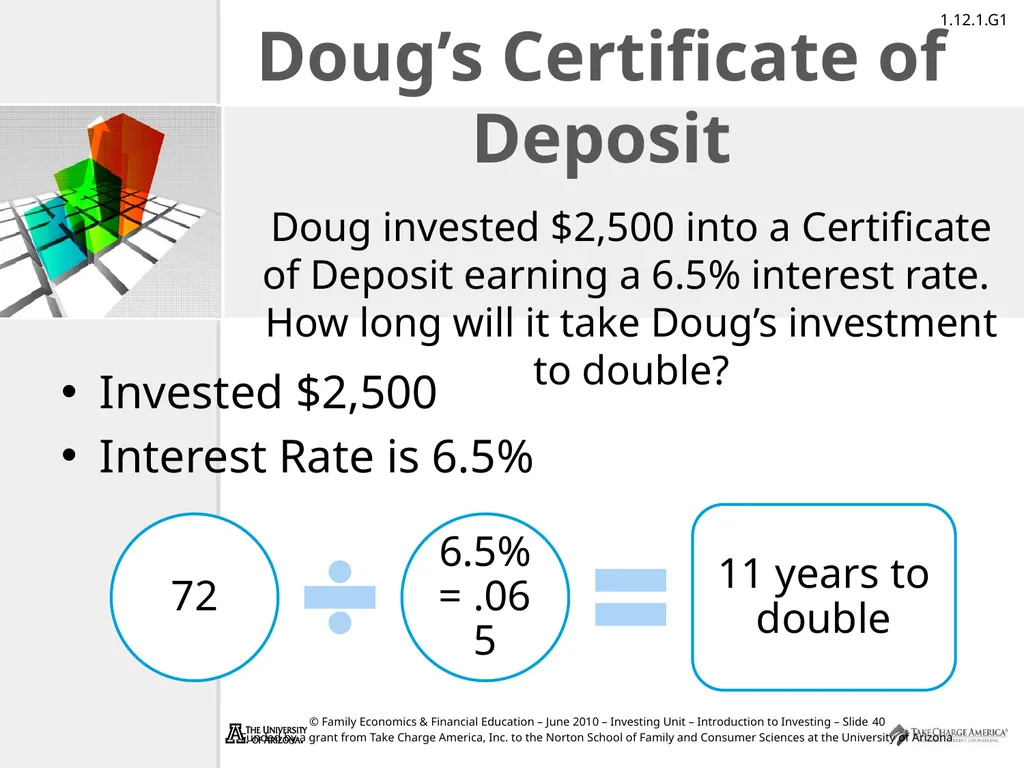
slide40. Doug’s Certificate of Deposit Invested $2,500
Interest Rate is 6.5% Doug invested $2,500 into a Certificate of Deposit earning a 6.5% interest rate. How long will it take Doug’s investment to double?<br>
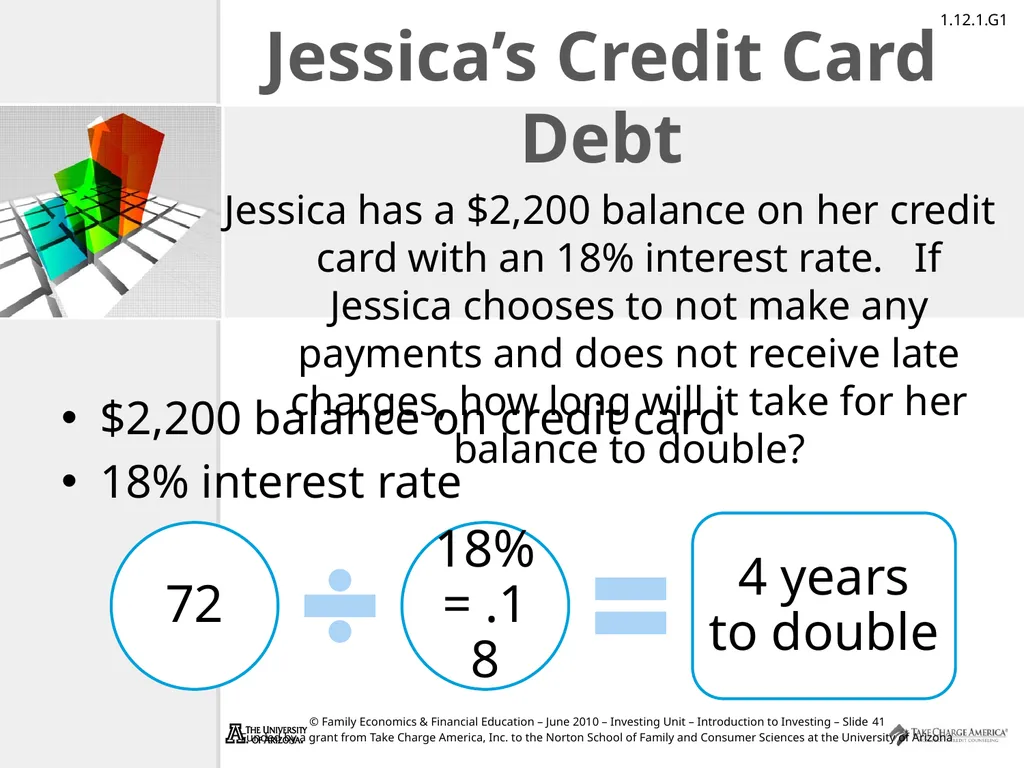
slide41. Jessica’s Credit Card Debt $2,200 balance on credit card
18% interest rate Jessica has a $2,200 balance on her credit card with an 18% interest rate. If Jessica chooses to not make any payments and does not receive late charges, how long will it take for her balance to double?<br>
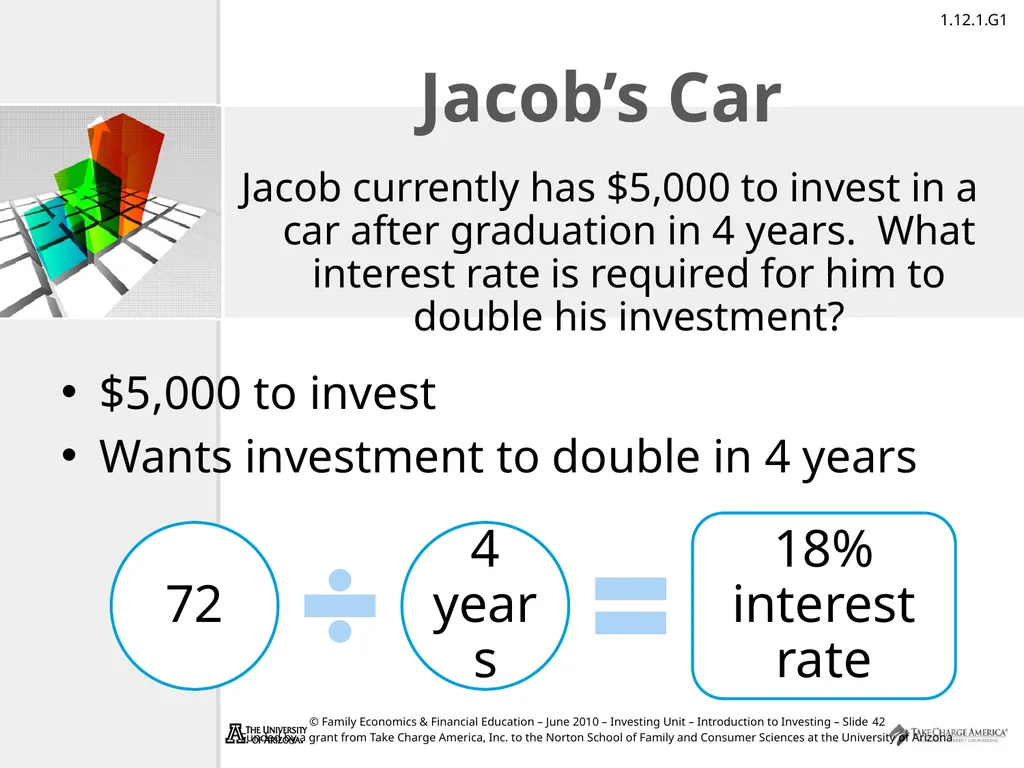
slide42. Jacob’s Car $5,000 to invest
Wants investment to double in 4 years Jacob currently has $5,000 to invest in a car after graduation in 4 years. What interest rate is required for him to double his investment?<br>
slide43. Any Questions?<br>
Family Economics and Financial Education<br>
slide2. Saving vs. Investing Savings is for short-term goals and emergencies Investing is for long-term goals, such as college or retirement. Remember: The purpose of savings is to develop financial security. You should have 3 – 6 months of salary in savings BEFORE you start investing.<br>
slide3. What is Investing? The purchase of assets with the goal of increasing future income
Focuses on wealth accumulation
Appropriate for long-term goals What are examples of long-term goals that can be accomplished by investing?<br>
slide4. Rate of Return Return is money that you earn from your investment.
The Rate of Return is the total return on an investment expressed as a percentage of the amount of money invested. Investments usually earn higher rates of return than savings tools.<br>
slide5. What is Mandy’s Rate of Return? Mandy saved $2,200 in a money market deposit account. After one year, she has a return of $110. What is Mandy’s rate of return? Mandy’s rate of return on investment is 5%<br>
slide6. What is Derek’s Rate of Return? Derek invested $900. When he withdrew his money from the investment, he had a total of $1,050. What is Derek’s rate of return? Derek’s rate of return on investment is 16.7%<br>
slide7. Risk POTENTIAL
RETURN RISK Risk
The uncertainty regarding the outcome of a situation or event
Investment Risk
The possibility that an investment will fail to pay the expected return or fail to pay a return at all<br>
slide8. Financial Risk Pyramid Speculation Increasing potential for higher returns
Increasing risk<br>
slide9. Inflation Inflation
The rise in the general level of prices Inflation Risk
The danger that money won’t be worth as much in the future as it is today Inflation risk should not be a concern with savings since the goal of savings is to provide current financial security The rate of return on an investment should be higher than the rate of inflation.<br>
slide10. Investment Philosophy Each individual has a tolerance level for the amount of risk they are willing to take on Investment Philosophy
An individual’s general approach to investment risk The greater the risk a person is willing to make on an investment, the greater the potential return will be. Generally divided into three categories: conservative, moderate, and aggressive<br>
slide11. Types of Investment Tools<br>
slide12. Stocks Stock
A share of ownership in a company
Stockholder or shareholder
Owner of the stock Usually a stockholder owns a very small part of a company.<br>
slide13. Return on Stocks There are two ways people can make money on stocks:
Dividends
Dividends are the share of profits distributed in cash to stockholders
Market Price
The current price that a buyer is willing to pay for stock<br>
slide14. Return on Stocks If stock is sold for a market price higher than what was paid, stockholder will receive a return (make money).
If stock is sold for a market price lower than what was paid, stockholder will lose money<br>
slide15. Stock Markets Stocks are bought and sold on stock markets by people called brokers.
The main stock markets in the U.S. are:
New York Stock Exchange (NYSE)
NASDAQ<br>
slide16. Stock Activity We are going to learn about stocks using McDonald’s as an example.<br>
slide17. Bonds Bonds are loans.
A company or government will borrow money from investors by issuing bonds.
Example: The Crazy Hat Co. wants to build a new distribution center in Louisville, KY which will cost $7,000,000. They can issue 7,000 bonds at $1,000 each.
7,000 x $1,000 = $7,000,000 Bonds are less risky than stocks but do not have the potential to earn as much as a stock.<br>
slide18. Bonds The company or government pays annual interest to the investor until the maturity date is reached
The maturity date is the specified time in the future when the principal is repaid to the bondholder.
Bonds issued by a company are called corporate bonds.
Bonds issued by a government are called:
Treasury bonds (federal government)
Municipal bonds (local governments)<br>
slide19. Example The Crazy Hat Co. issues $1,000 bonds that pay 4.5% interest with a maturity date of 11/22/2012 (2 years from today).
You buy the bond for $1,000.
Each year you will receive a payment of $1,000 x .045 = $45
On 11/22/2012, you will also get your $1,000 back.<br>
slide20. Stocks vs. Bonds Stocks are equity.
The stockholder actually owns a piece of the company.
Equity is the value of the company.
For example, if a company has 10 million shares of stock, and each share is worth $5, then the company’s equity is:
10,000,000 x $5 = $50,000,000<br>
slide21. Stocks vs. Bonds Bonds are debt.
Debt means the bondholder has lent money to the company that the company will repay with interest.
Companies must repay debt before they pay anything to stockholders.
Therefore, bonds are less risky than stocks.<br>
slide22. Portfolio Diversification Portfolio Diversification- reduces risk by spreading investment money among different investment tools Creates a collection of investments that will increase return while reducing risk The main goal of diversification is to reduce risk. Referred to as “Building a Portfolio.”<br>
slide23. Mutual Funds Mutual fund- invests money in a diversified portfolio of stocks and bonds Always research the fees charged by a mutual fund. Reduces investment risk by helping people diversify their portfolio Fees can be high Saves investors time<br>
slide24. How Do Mutual Funds Work? Individuals buy shares
The money is used to purchase stocks, bonds, and other investments.
Profits returned to shareholders monthly, quarterly, or semi-annually in the form of dividends.<br>
slide25. How Do Mutual Funds Work?<br>
slide26. What is the Advantage of Investing in a Mutual Fund? Allows small investors to get professional account management and diversification normally only available to large investors.
This allows investors with a little bit of money to be able to invest in a variety of stocks, bonds, & other investments.<br>
slide27. There are lots of different types of mutual funds!<br>
slide28. Market Indexes A market index is the value of a group of stocks or other investments.
Market indexes are intended to represent an entire stock market and thus track the market's changes over time.<br>
slide29. Market Indexes Dow Jones Industrial Average (DJIA or “The Dow”)
30 large companies traded on NYSE or NASDAQ
Standard & Poors 500 Index (S&P 500)
An index of 500 large companies selected by a committee
Others
Russell 2000, Wilshire 5000<br>
slide30. Index Fund A mutual fund that was designed to reduce fees by investing in the stocks and bonds that make up an index.
Offers high diversification with low fees.<br>
slide31. Real Estate Includes any residential or commercial property or land as well as the rights accompanying that land
A family home is not considered an investment asset
Can be risky and more time consuming but has potential for large returns Examples of real estate investments include rental units and commercial property.<br>
slide32. Speculative Investments Have the potential for significant fluctuations in return over a short period of time
Examples- future, options, commercial paper, collectibles
Recommended for people with an aggressive investment philosophy and a high level of financial security<br>
slide33. Buying and Selling Investments Investors must utilize a brokerage firm that acts as a buying and selling agent for the investor (except for when buying real estate and certain speculative investments). Complete
investment
transactions Offer investment advice and one-on-one attention from a broker Only complete investment transactions Offer no advice to investors but charge 40-60% less<br>
slide34. Taxation Profits earned on investments are considered to be income Income taxes MUST be paid
on this money Includes all forms of returns: interest, dividends, and price appreciation Taxes are due on most investment returns in the year the income is received<br>
slide35. Employee-Sponsored Investment Accounts Allow employees to reduce their tax liability and make investing automatic
Money is automatically taken out of an employee’s paycheck
Employers often contribute a portion of money to the investment with no additional cost from the employee It is recommended that a person utilize these investment tools as much as possible if they are offered.<br>
slide36. Rule of 72 Rule of 72
Allows a person to easily calculate when the future value of an investment will double the principal amount<br>
slide37. Albert Einstein Credited for discovering the mathematical equation for compounding interest, thus the “Rule of 72.” At 10% interest rate, money doubles every 7.2 years,
T=P(I+I/N)YN “It is the greatest mathematical discovery of all time.”<br>
slide38. What Can the “Rule of 72” Determine? How many years it will take an investment to double at a given interest rate using compounding interest How long it will take debt to double if no payments are made The interest rate an investment must earn to double within a specific time period How many times money (or debt) will double in a specific time period<br>
slide39. “Rule of 72” FYI The rule is only an approximation
The interest rate must remain constant
The equation does not allow for additional payments to be made to the original amount
Interest earned is reinvested
Tax deductions are not included within the equation<br>
slide40. Doug’s Certificate of Deposit Invested $2,500
Interest Rate is 6.5% Doug invested $2,500 into a Certificate of Deposit earning a 6.5% interest rate. How long will it take Doug’s investment to double?<br>
slide41. Jessica’s Credit Card Debt $2,200 balance on credit card
18% interest rate Jessica has a $2,200 balance on her credit card with an 18% interest rate. If Jessica chooses to not make any payments and does not receive late charges, how long will it take for her balance to double?<br>
slide42. Jacob’s Car $5,000 to invest
Wants investment to double in 4 years Jacob currently has $5,000 to invest in a car after graduation in 4 years. What interest rate is required for him to double his investment?<br>
slide43. Any Questions?<br>