05
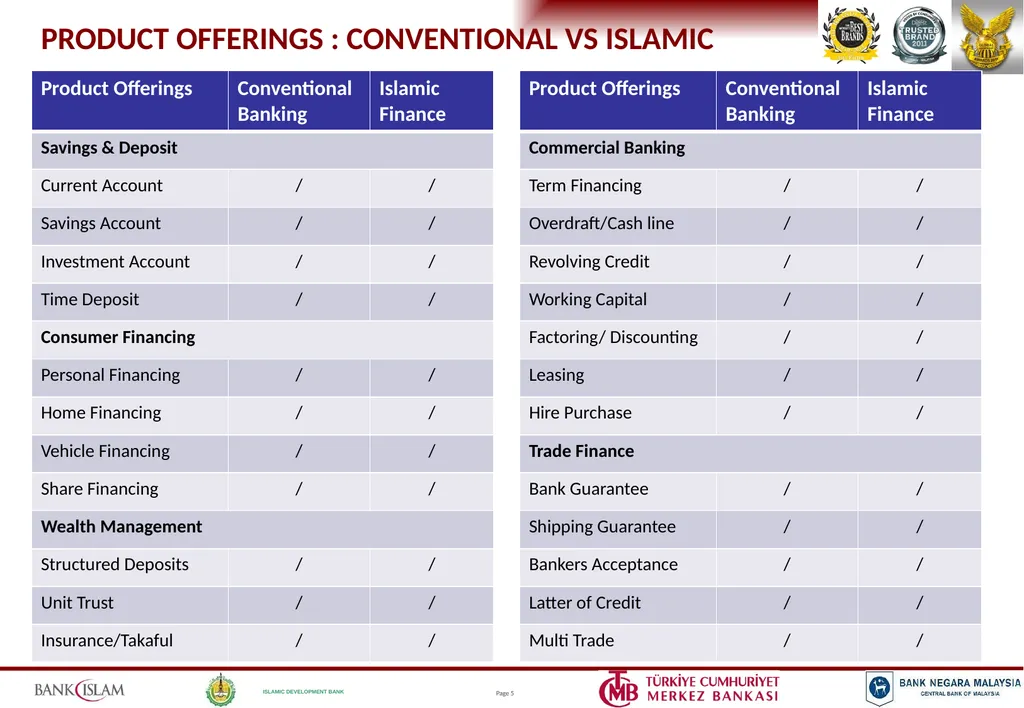
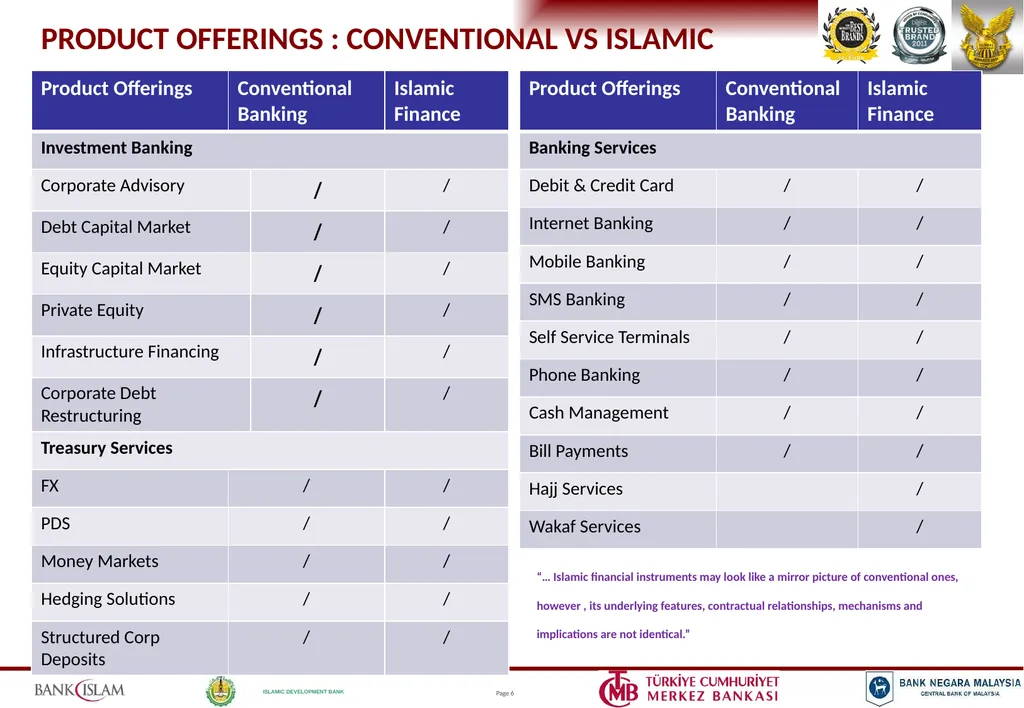
PRODUCT OFFERINGS : CONVENTIONAL VS ISLAMIC<br>
06
PRODUCT OFFERINGS : CONVENTIONAL VS ISLAMIC “… Islamic financial instruments may look like a mirror picture of conventional ones, however , its underlying features, contractual relationships, mechanisms and implications are not identical.”<br>
07
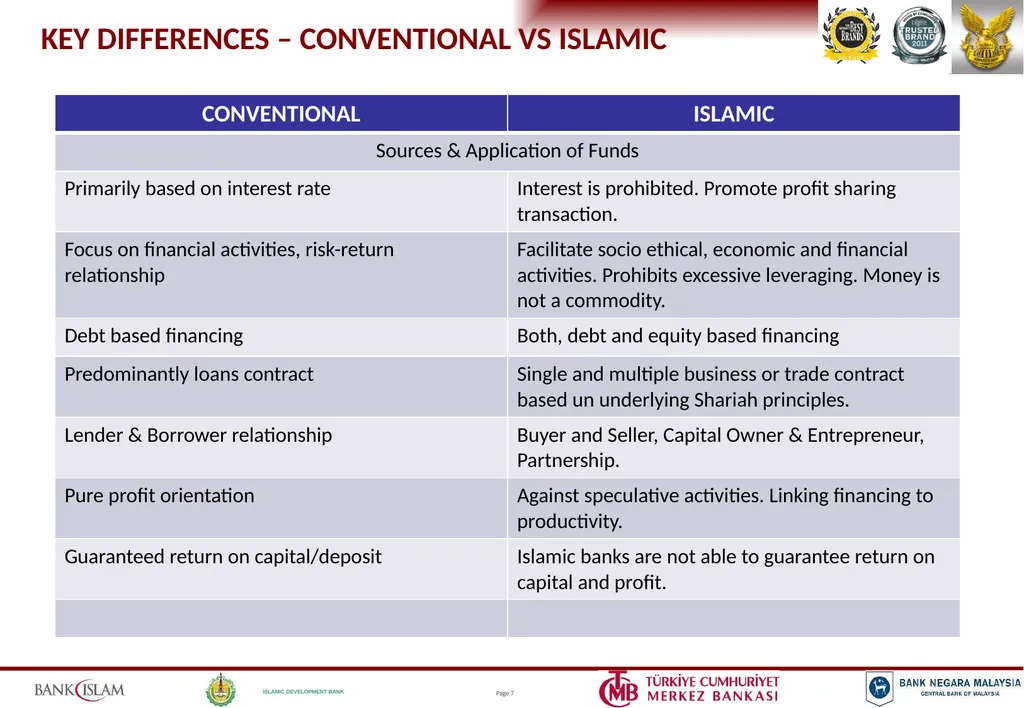
KEY DIFFERENCES – CONVENTIONAL VS ISLAMIC<br>
08
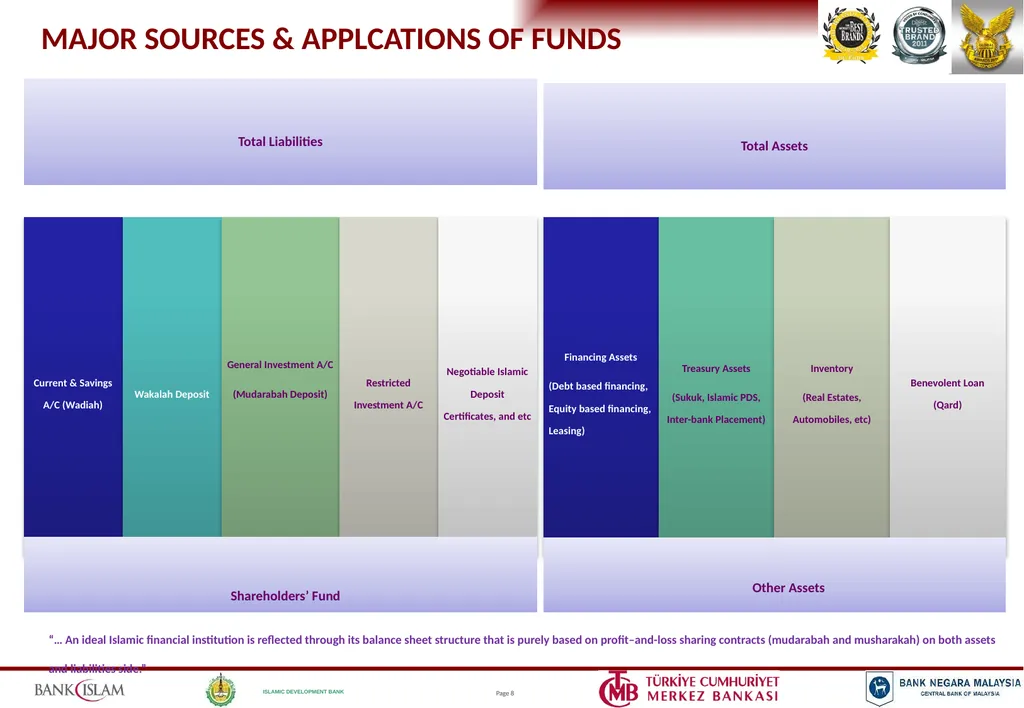
MAJOR SOURCES & APPLCATIONS OF FUNDS Shareholders’ Fund Other Assets “… An ideal Islamic financial institution is reflected through its balance sheet structure that is purely based on profit–and-loss sharing contracts (mudarabah and musharakah) on both assets and liabilities side.”<br>
09
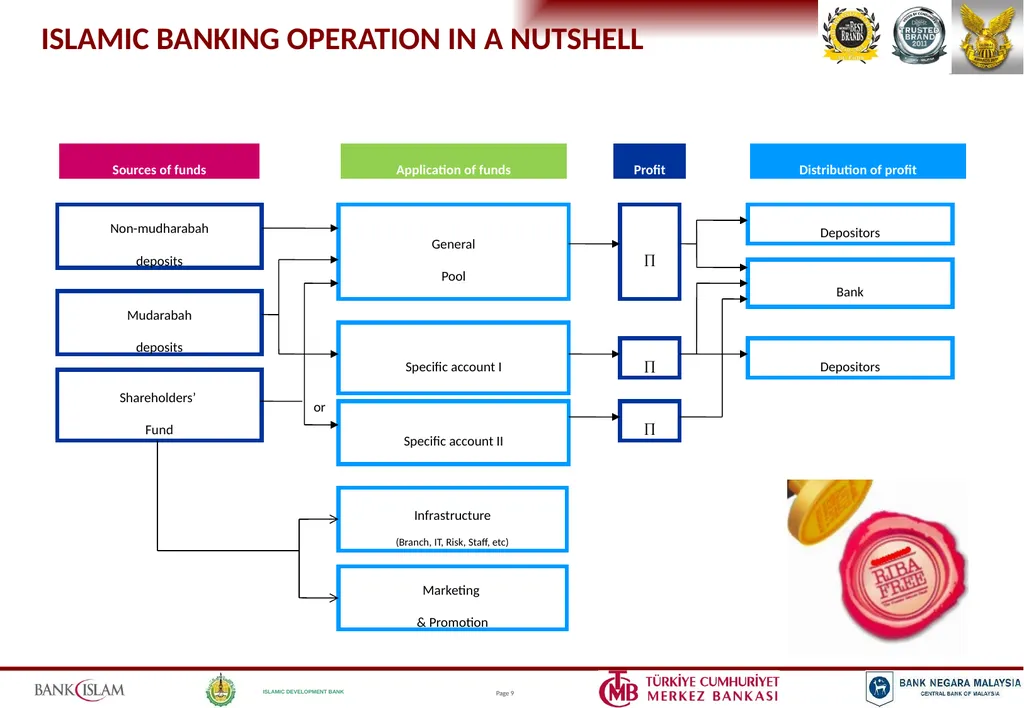
ISLAMIC BANKING OPERATION IN A NUTSHELL Sources of funds Non-mudharabah
deposits Mudarabah
deposits Shareholders’
Fund Application of funds General
Pool Specific account I Specific account II Profit Distribution of profit Depositors Bank Depositors or Marketing
& Promotion Infrastructure
(Branch, IT, Risk, Staff, etc)<br>
10
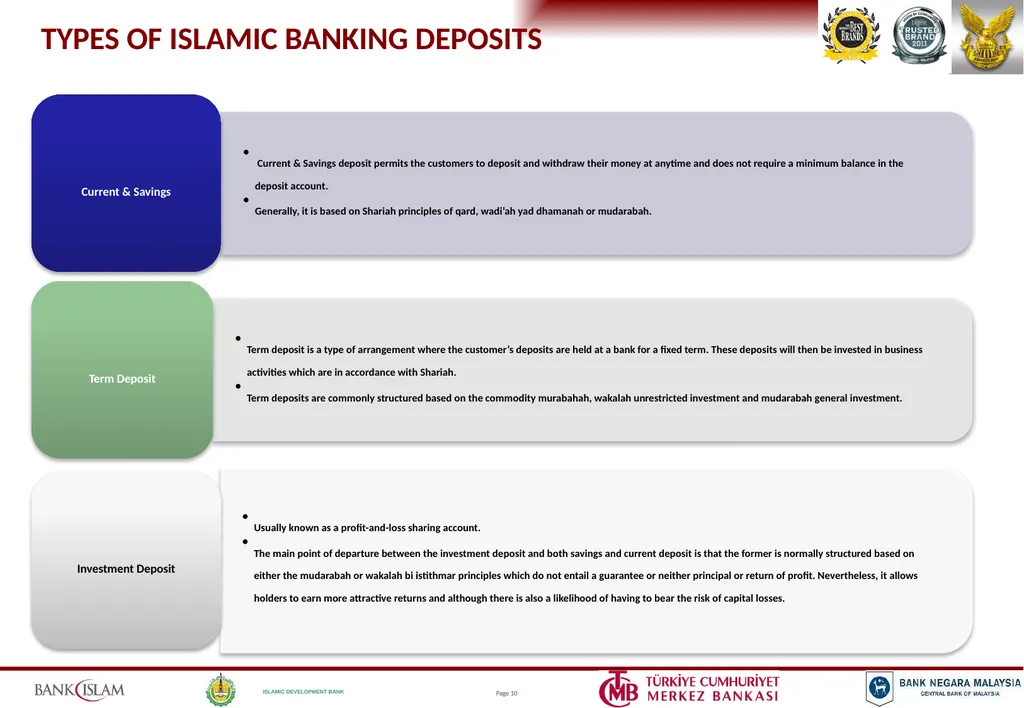
TYPES OF ISLAMIC BANKING DEPOSITS<br>
11
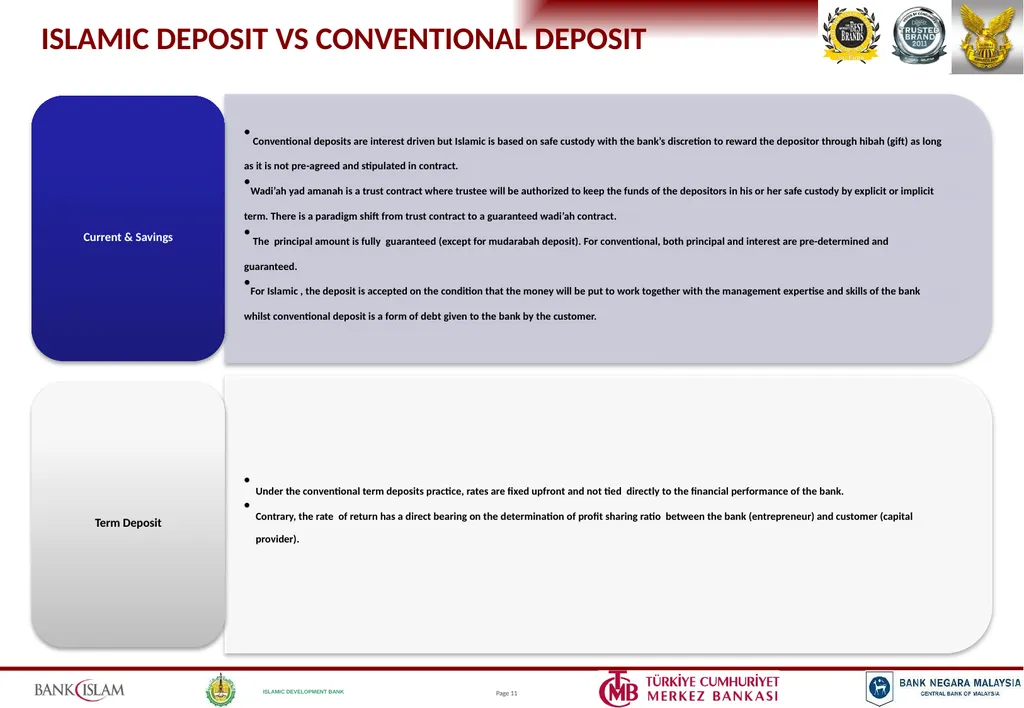
ISLAMIC DEPOSIT VS CONVENTIONAL DEPOSIT<br>
12
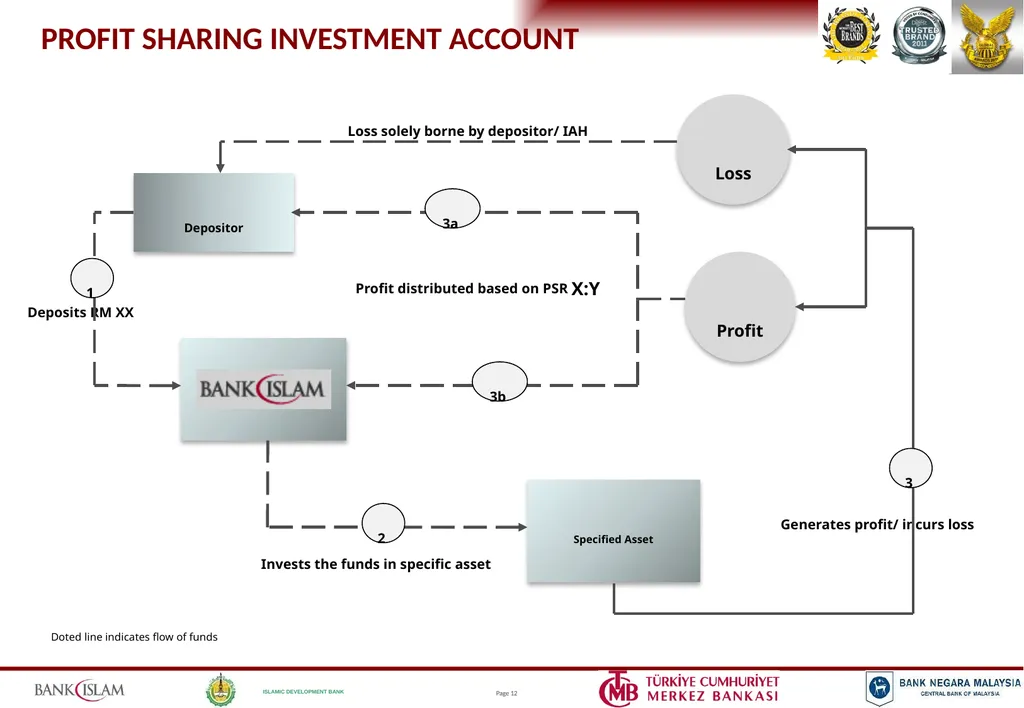
Depositor 3a 3b Profit distributed based on PSR X:Y Doted line indicates flow of funds Invests the funds in specific asset Deposits RM XX Specified Asset Profit Generates profit/ incurs loss 1 2 Loss Loss solely borne by depositor/ IAH 3 PROFIT SHARING INVESTMENT ACCOUNT<br>
13
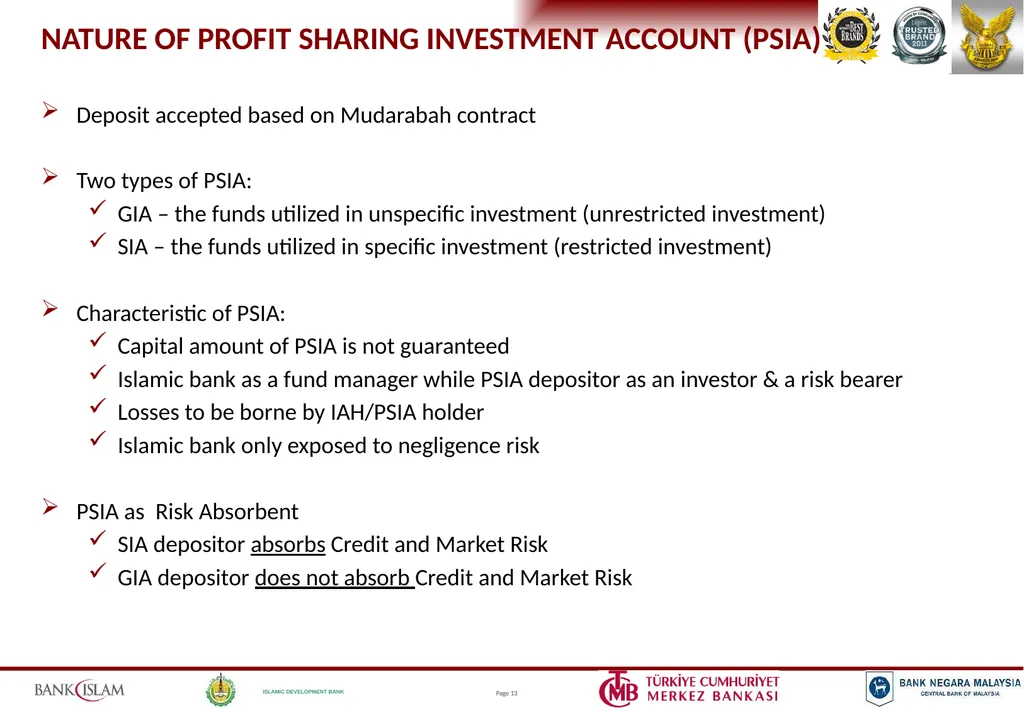
NATURE OF PROFIT SHARING INVESTMENT ACCOUNT (PSIA) Deposit accepted based on Mudarabah contract
Two types of PSIA:
GIA – the funds utilized in unspecific investment (unrestricted investment)
SIA – the funds utilized in specific investment (restricted investment)
Characteristic of PSIA:
Capital amount of PSIA is not guaranteed
Islamic bank as a fund manager while PSIA depositor as an investor & a risk bearer
Losses to be borne by IAH/PSIA holder
Islamic bank only exposed to negligence risk
PSIA as Risk Absorbent
SIA depositor absorbs Credit and Market Risk
GIA depositor does not absorb Credit and Market Risk<br>
16
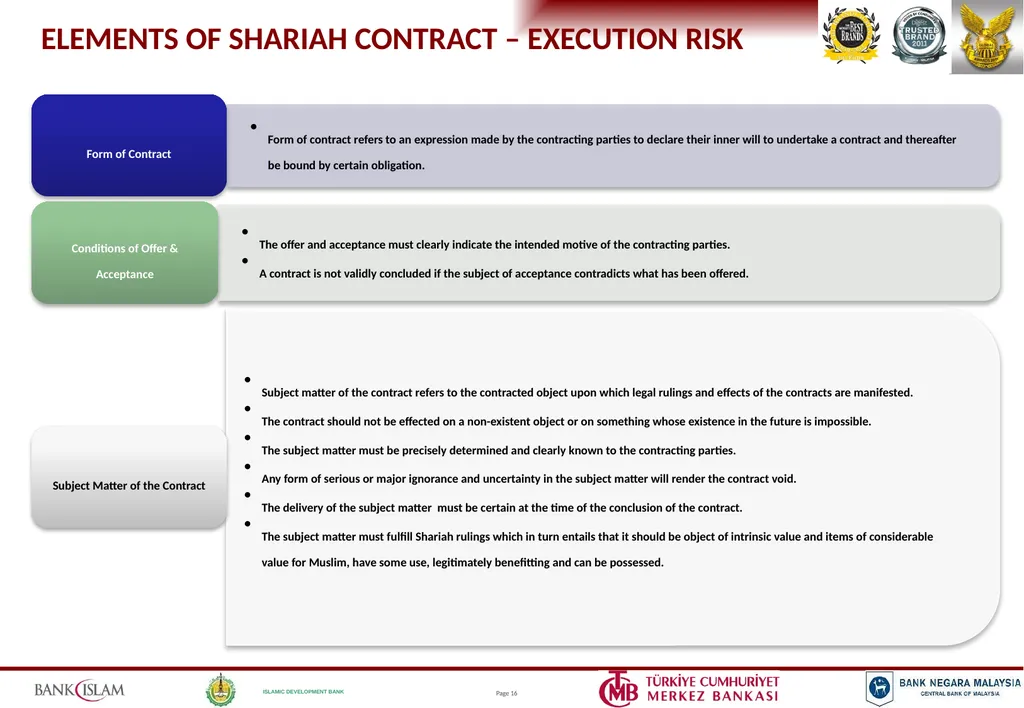
ELEMENTS OF SHARIAH CONTRACT – EXECUTION RISK<br>
17
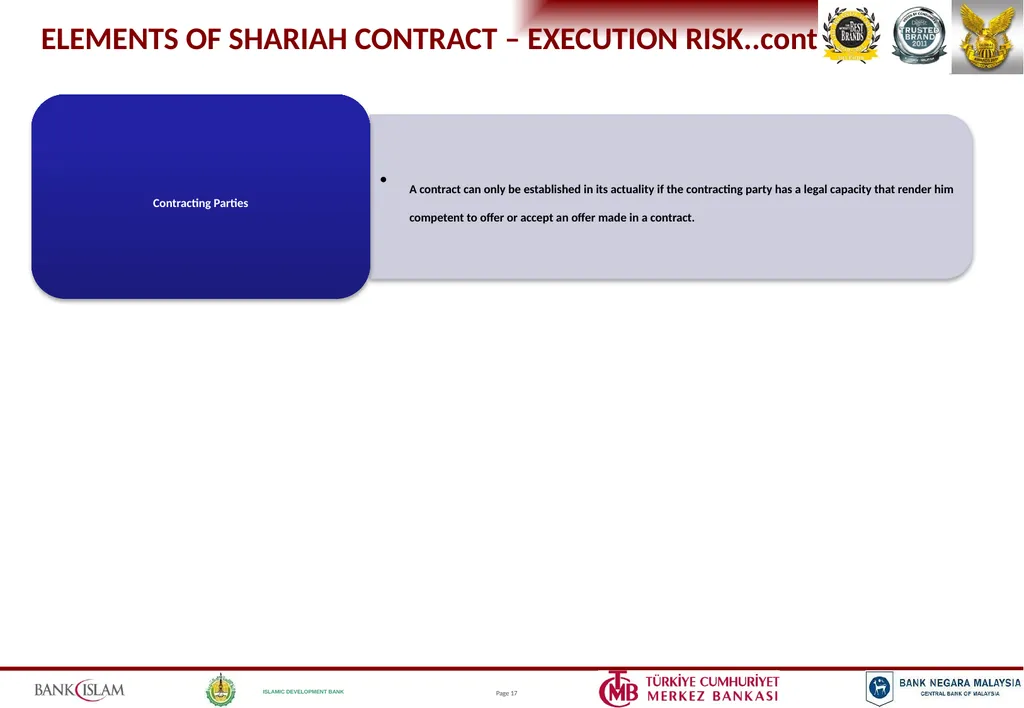
ELEMENTS OF SHARIAH CONTRACT – EXECUTION RISK..cont<br>
18
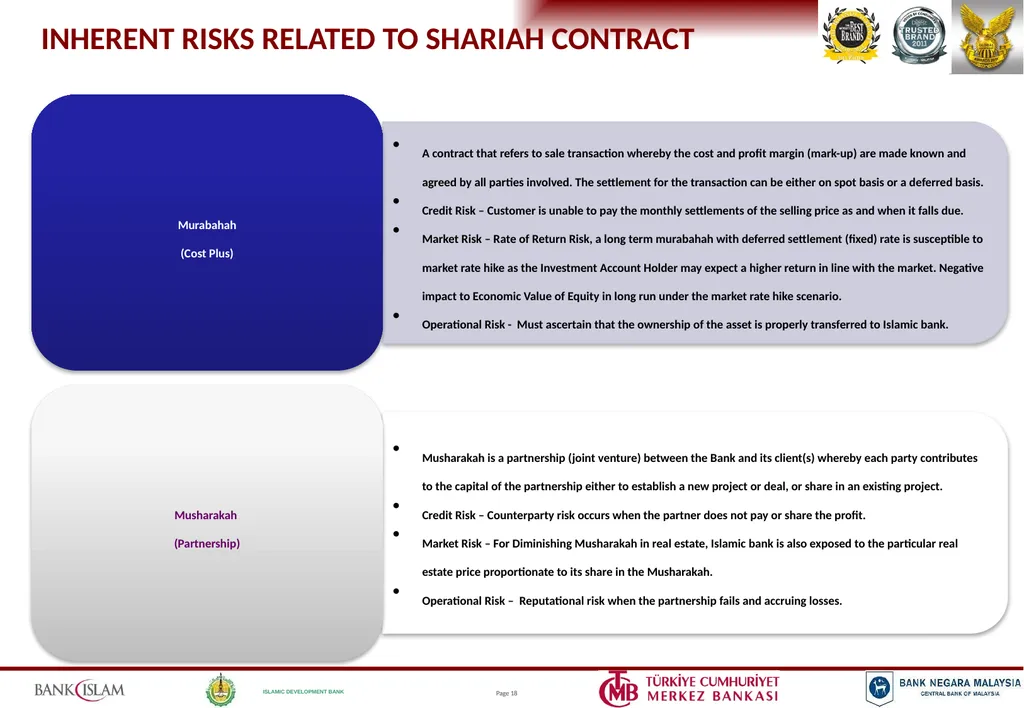
INHERENT RISKS RELATED TO SHARIAH CONTRACT<br>
19
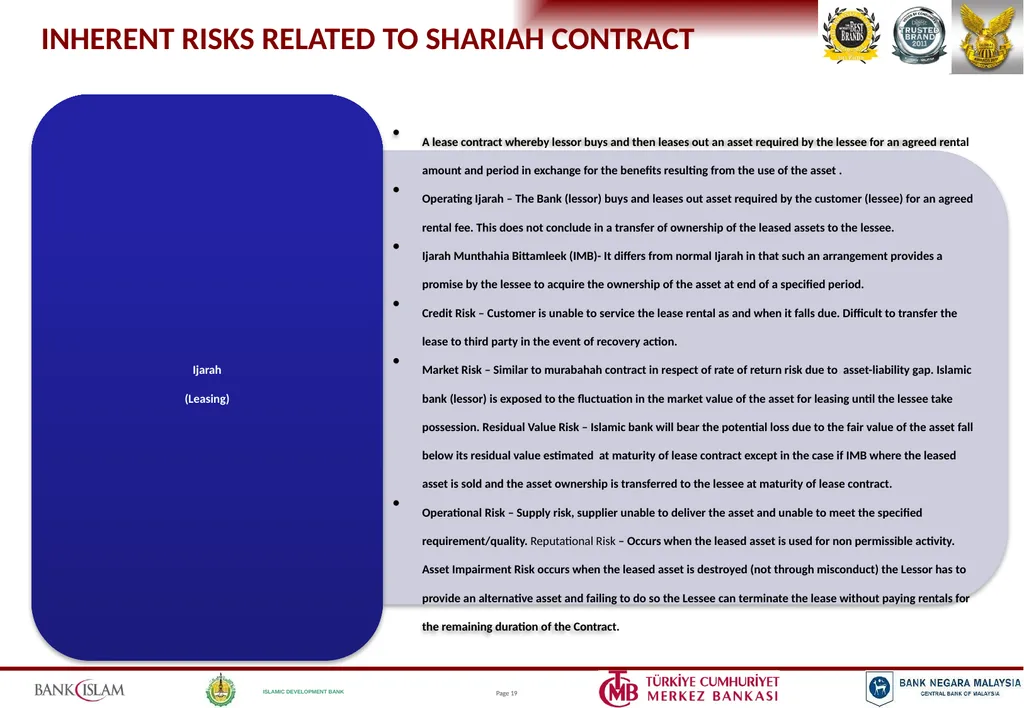
INHERENT RISKS RELATED TO SHARIAH CONTRACT<br>
20
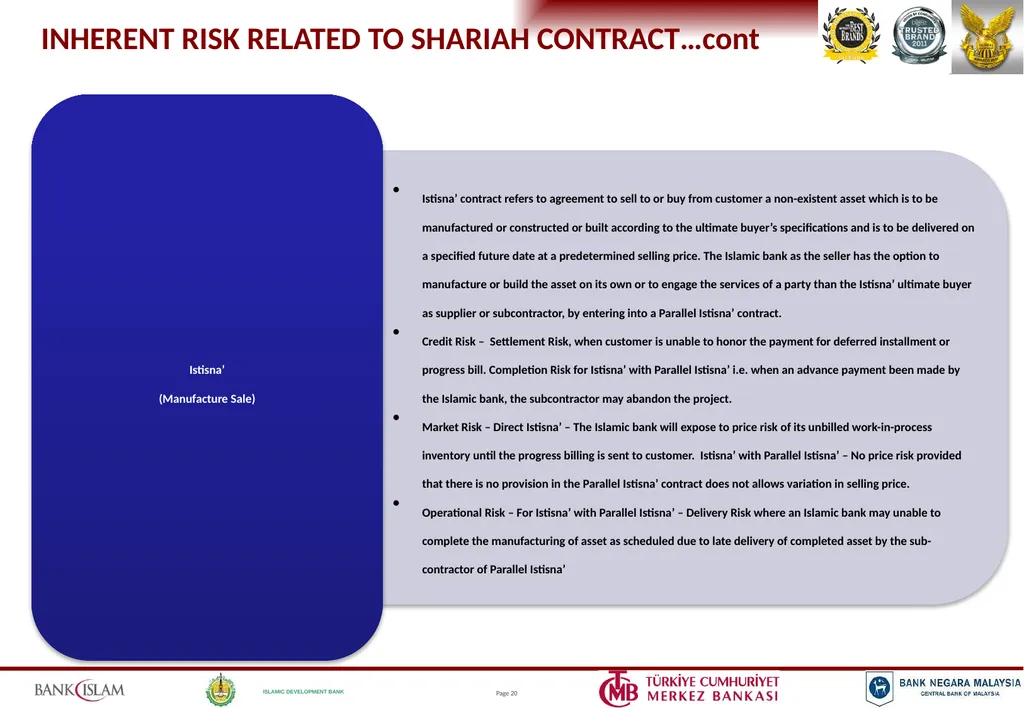
INHERENT RISK RELATED TO SHARIAH CONTRACT…cont<br>
21
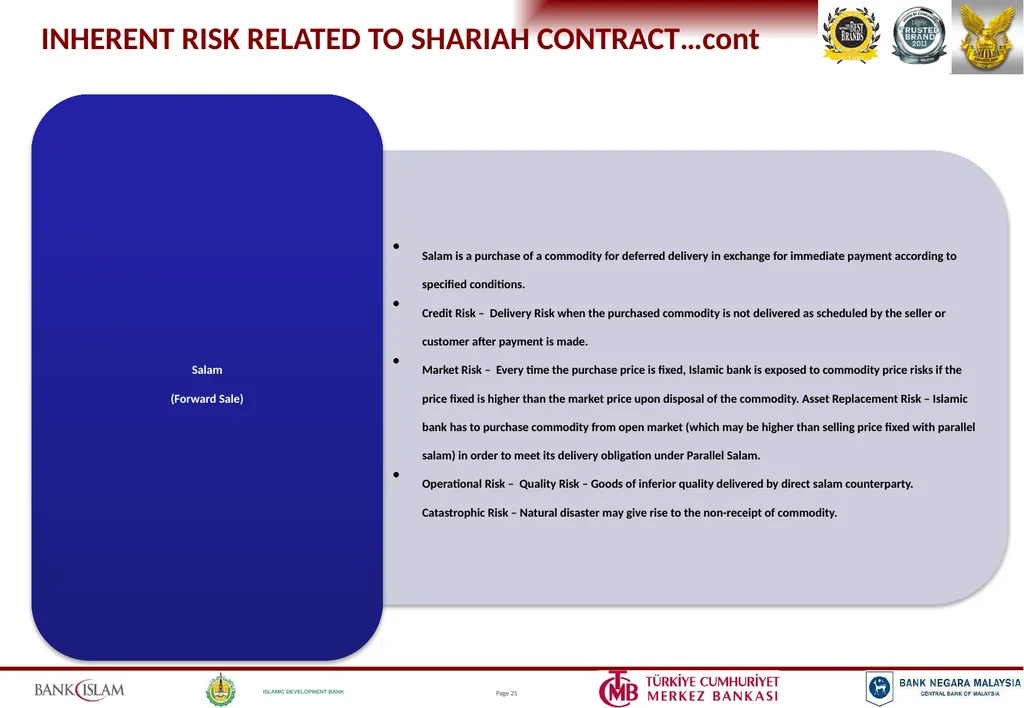
INHERENT RISK RELATED TO SHARIAH CONTRACT…cont<br>
22
KEY CHALLENGES IN EQUITY-BASED FINANCING IN MALAYSIA<br>
23
ISLAMIC BANKING �OPERATION & MODALITIES<br>
24
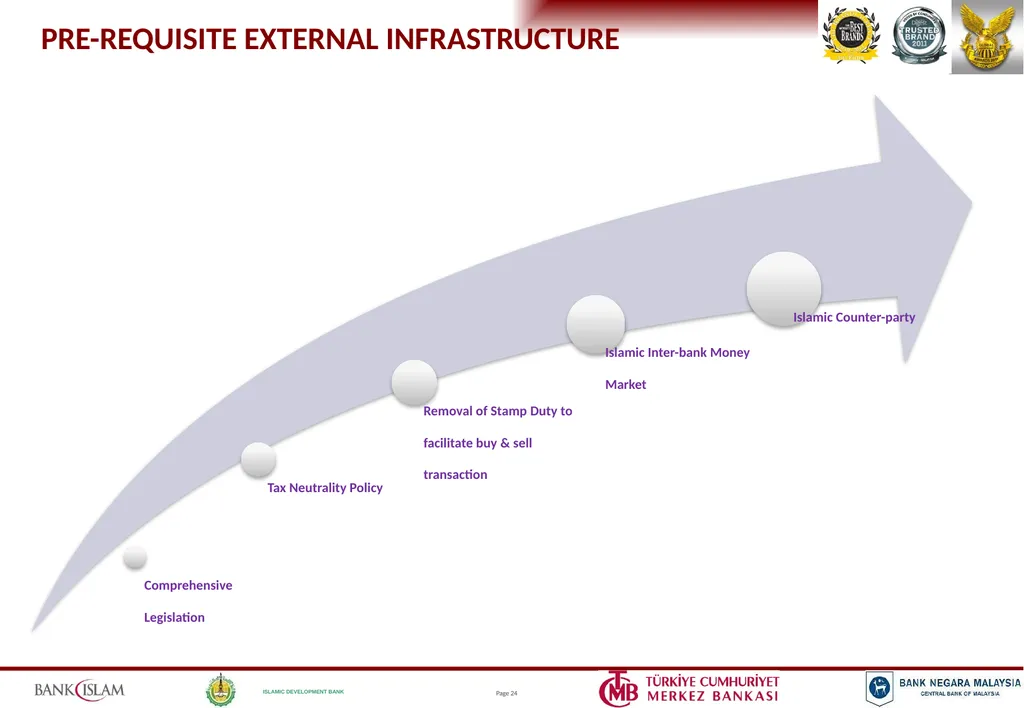
PRE-REQUISITE EXTERNAL INFRASTRUCTURE<br>
25
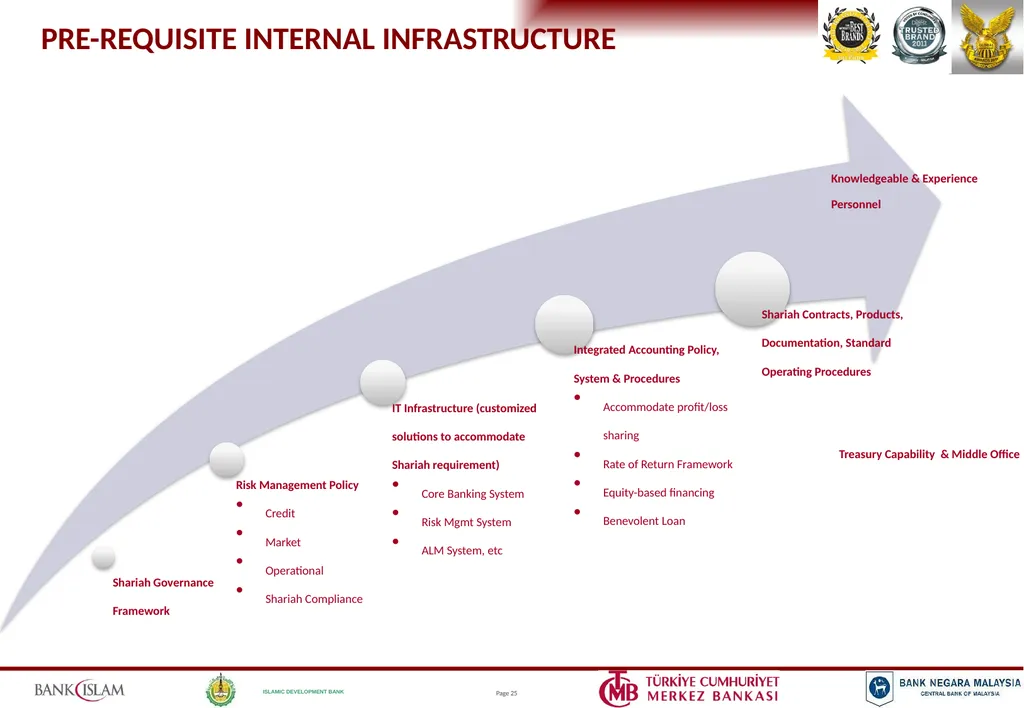
PRE-REQUISITE INTERNAL INFRASTRUCTURE<br>
26
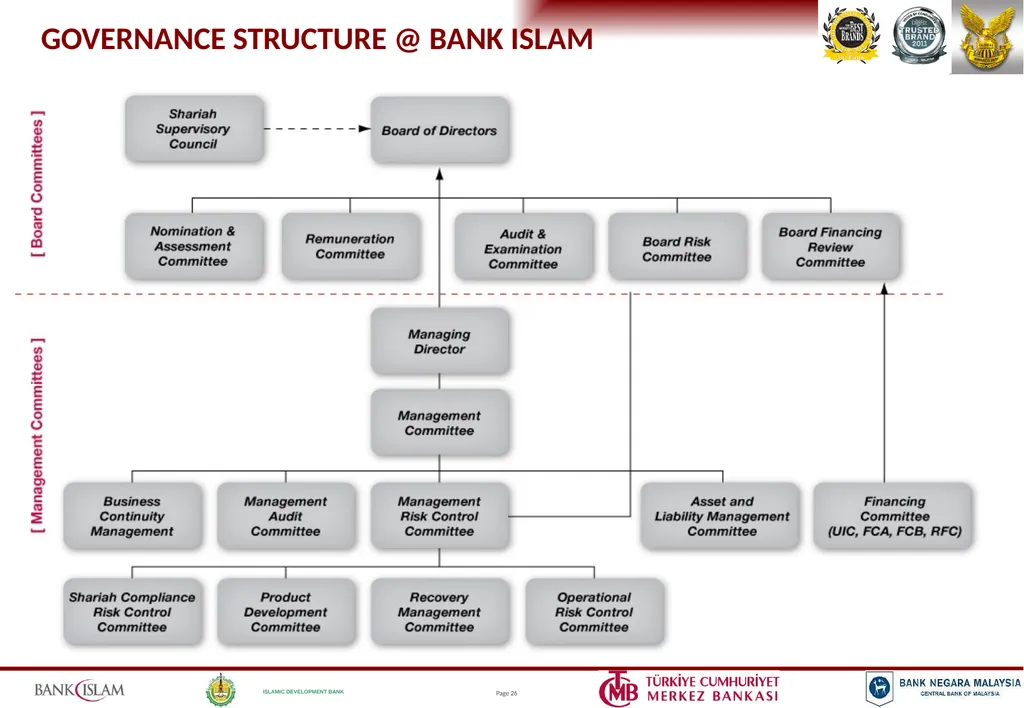
GOVERNANCE STRUCTURE @ BANK ISLAM<br>
27
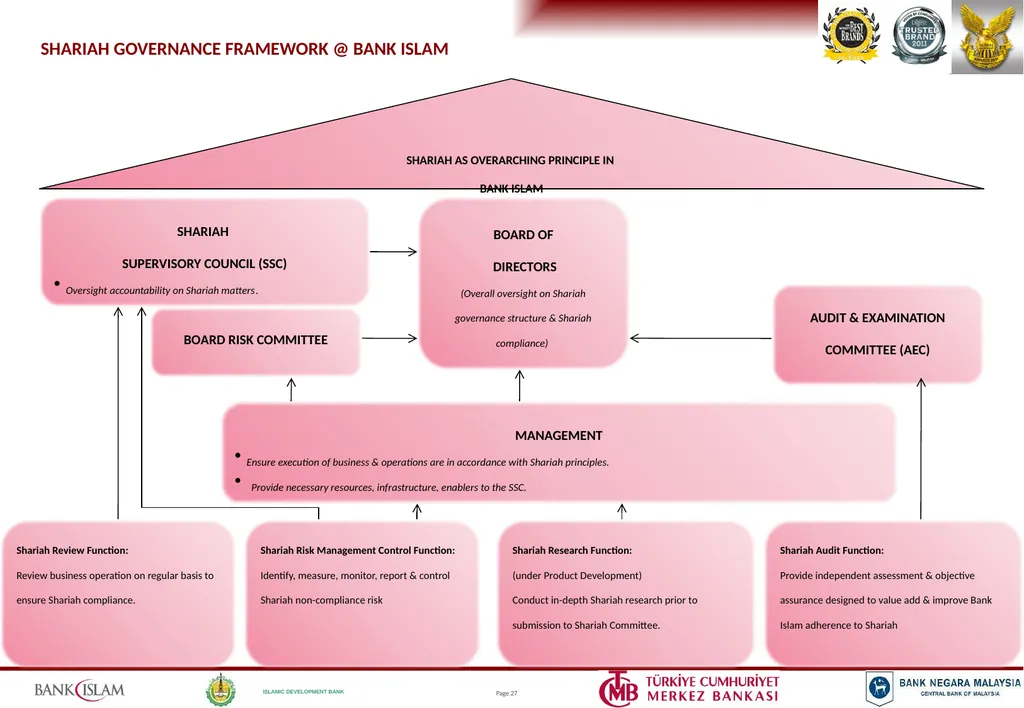
SHARIAH GOVERNANCE FRAMEWORK @ BANK ISLAM Shariah as overarching principle in
Bank Islam SHARIAH
SUPERVISORY COUNCIL (SSC)
Oversight accountability on Shariah matters. BOARD OF
DIRECTORS
(Overall oversight on Shariah governance structure & Shariah compliance) Board Risk Committee AUDIT & EXAMINATION COMMITTEE (AEC) MANAGEMENT
Ensure execution of business & operations are in accordance with Shariah principles.
Provide necessary resources, infrastructure, enablers to the SSC. Shariah Risk Management Control Function:
Identify, measure, monitor, report & control Shariah non-compliance risk Shariah Review Function:
Review business operation on regular basis to ensure Shariah compliance. Shariah Research Function:
(under Product Development)
Conduct in-depth Shariah research prior to submission to Shariah Committee. Shariah Audit Function:
Provide independent assessment & objective assurance designed to value add & improve Bank Islam adherence to Shariah<br>
28
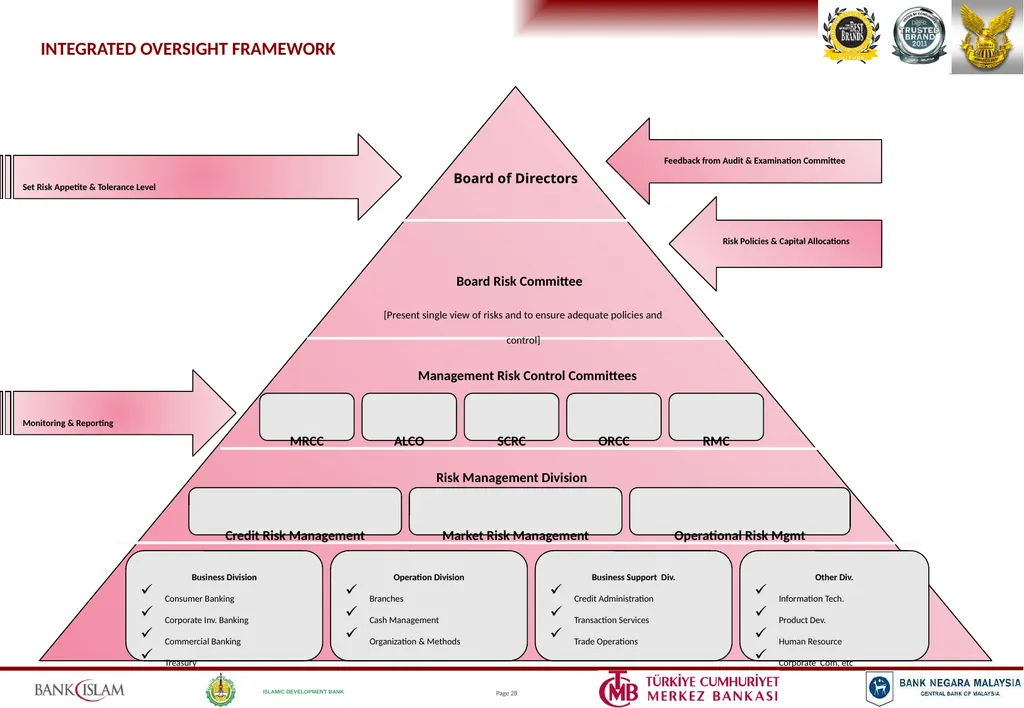
INTEGRATED OVERSIGHT FRAMEWORK Board of Directors Set Risk Appetite & Tolerance Level Board Risk Committee Management Risk Control Committees [Present single view of risks and to ensure adequate policies and control] MRCC ALCO SCRC ORCC RMC Risk Management Division Credit Risk Management Market Risk Management Operational Risk Mgmt Monitoring & Reporting Business Division
Consumer Banking
Corporate Inv. Banking
Commercial Banking
Treasury Operation Division
Branches
Cash Management
Organization & Methods Business Support Div.
Credit Administration
Transaction Services
Trade Operations Other Div.
Information Tech.
Product Dev.
Human Resource
Corporate Com, etc Risk Policies & Capital Allocations Feedback from Audit & Examination Committee<br>
29
ISLAMIC BANKING JOURNEY – MALAYSIAN EXPERIENCE<br>
30
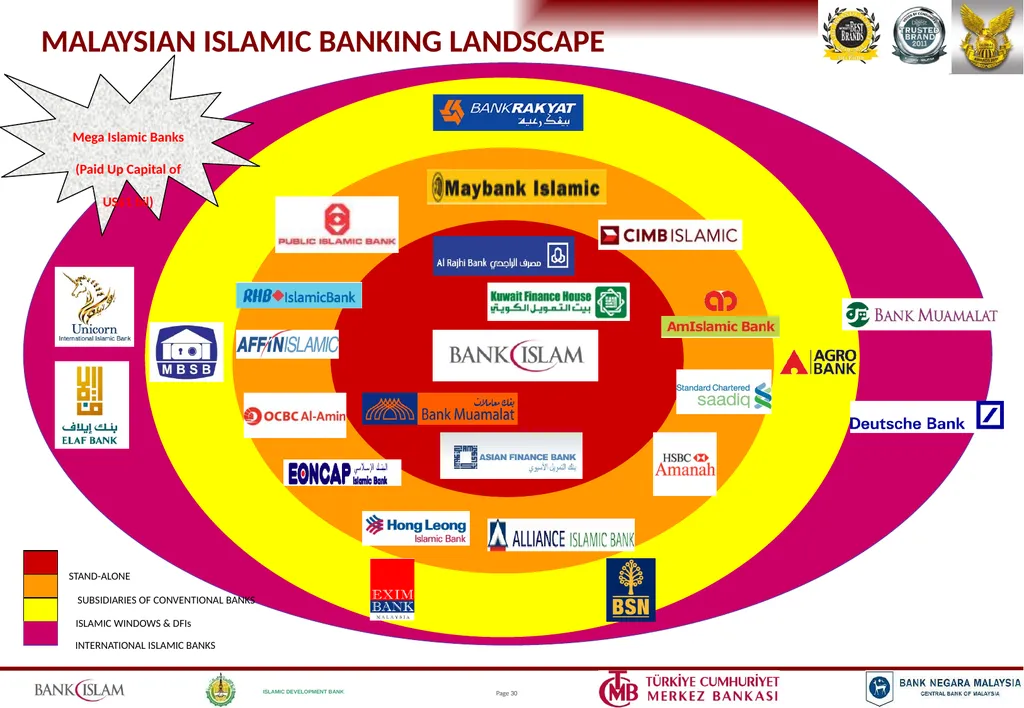
STAND-ALONE SUBSIDIARIES OF CONVENTIONAL BANKS ISLAMIC WINDOWS & DFIs MALAYSIAN ISLAMIC BANKING LANDSCAPE INTERNATIONAL ISLAMIC BANKS Mega Islamic Banks (Paid Up Capital of US$1 bil)<br>
31
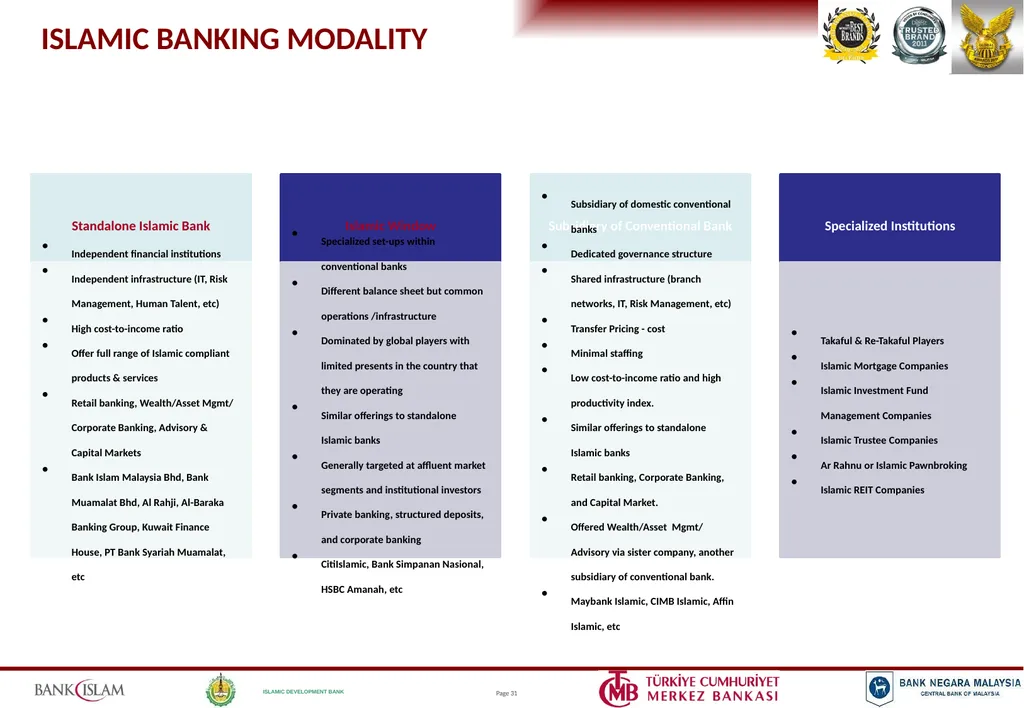
ISLAMIC BANKING MODALITY<br>
32
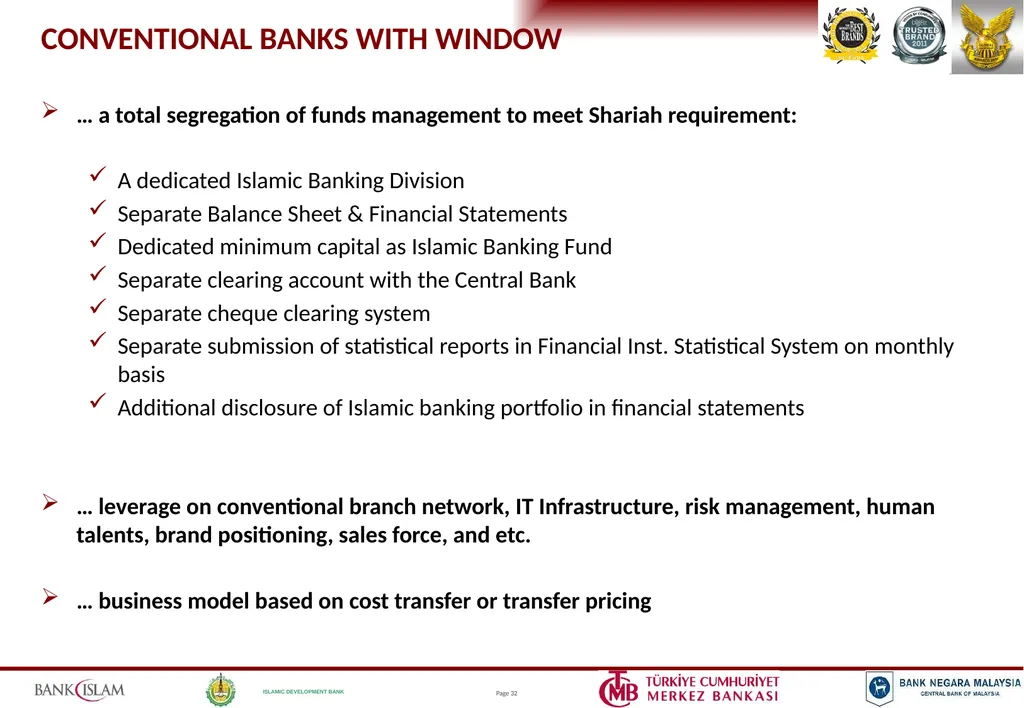
CONVENTIONAL BANKS WITH WINDOW … a total segregation of funds management to meet Shariah requirement:
A dedicated Islamic Banking Division
Separate Balance Sheet & Financial Statements
Dedicated minimum capital as Islamic Banking Fund
Separate clearing account with the Central Bank
Separate cheque clearing system
Separate submission of statistical reports in Financial Inst. Statistical System on monthly basis
Additional disclosure of Islamic banking portfolio in financial statements
… leverage on conventional branch network, IT Infrastructure, risk management, human talents, brand positioning, sales force, and etc.
… business model based on cost transfer or transfer pricing<br>
33
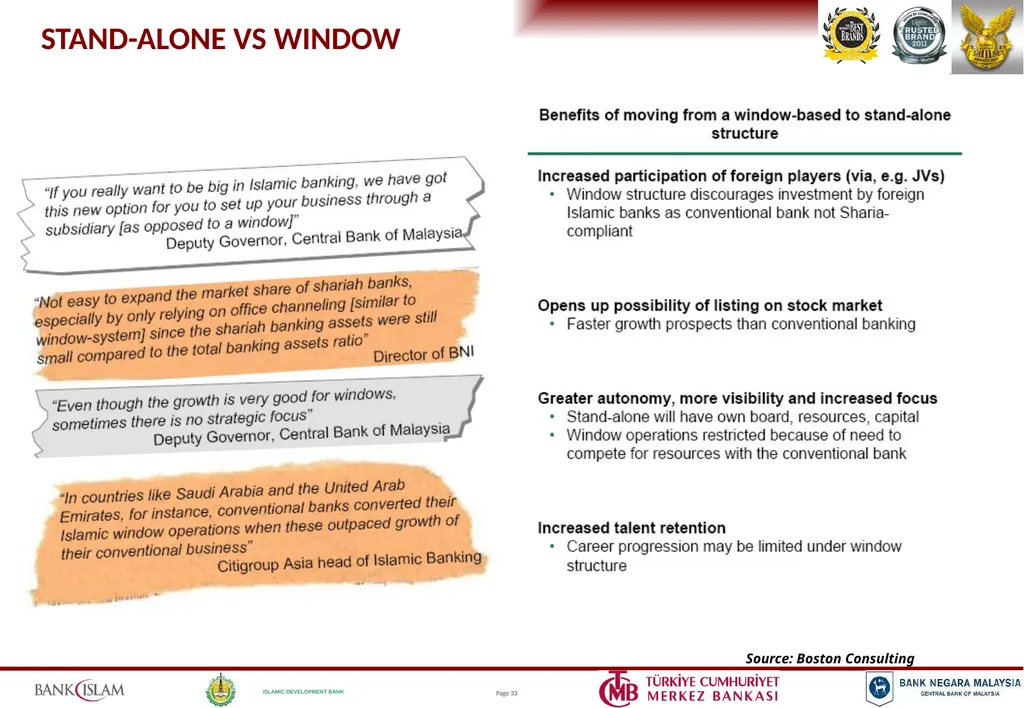
STAND-ALONE VS WINDOW Source: Boston Consulting<br>
34
شُكْرًا جَزِيْلاً وَالْسَلاَم Disclaimer: This presentation material has been prepared by Bank Islam Malaysia Berhad (the Bank”) for information purposes only and does not purport to contain all the information that may be required to evaluate the Bank or its financial position. No representation or warranty, express r implied, is given by or on behalf of the Bank as to the accuracy of the information or opinions contained in this presentation. The presentation does not constitute or form part of an offer, solicitation or invitation of any offer, to buy or subscribe for any securities , nor should it or any part of it form the basis of, or be relied in any connection with, any contract, investment decision or commitment whatsoever. The Bank does not accept any liability whatsoever for any loss howsoever arising from any use of this presentation or their contents or otherwise arising in connection therewith. BANK ISLAM MALAYSIA BERHAD
11th Floor, Wisma Bank Islam
Jalan Dungun, Bukit Damansara
50490 Kuala Lumpur
Tel: 603 2088 8222
www.bankislam.com.my Jeroen P.M.M. Thijs
Chief Risk Officer
Contact: 603 2088 8027
Email: jeroen@bankislam.com.my Hizamuddin Jamalluddin
AGM, Strategic Planning
Contact: 603 2088 8077
Email: hizamuddin@bankislam.com.my<br>