04
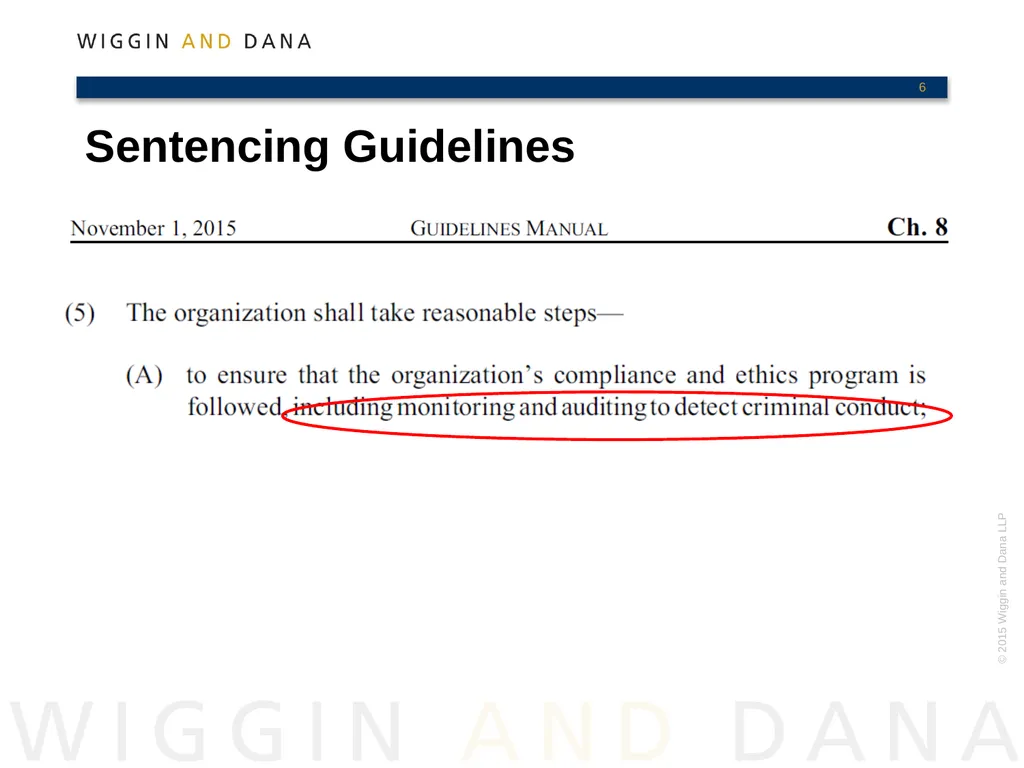
Sentencing Guidelines<br>
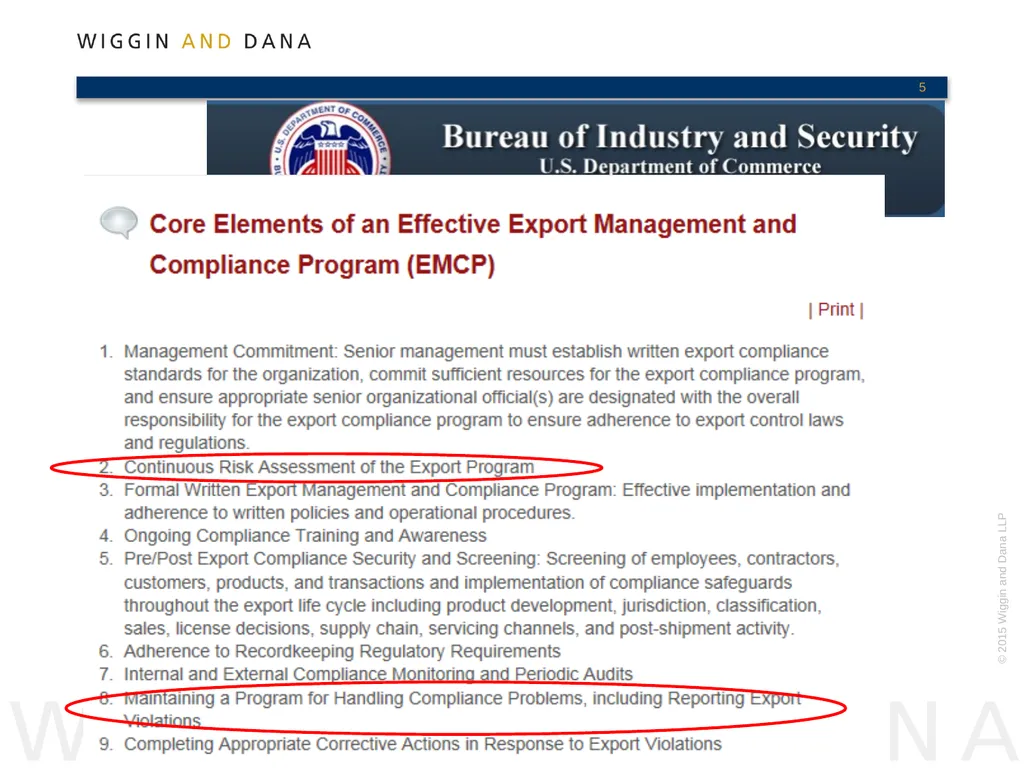
05
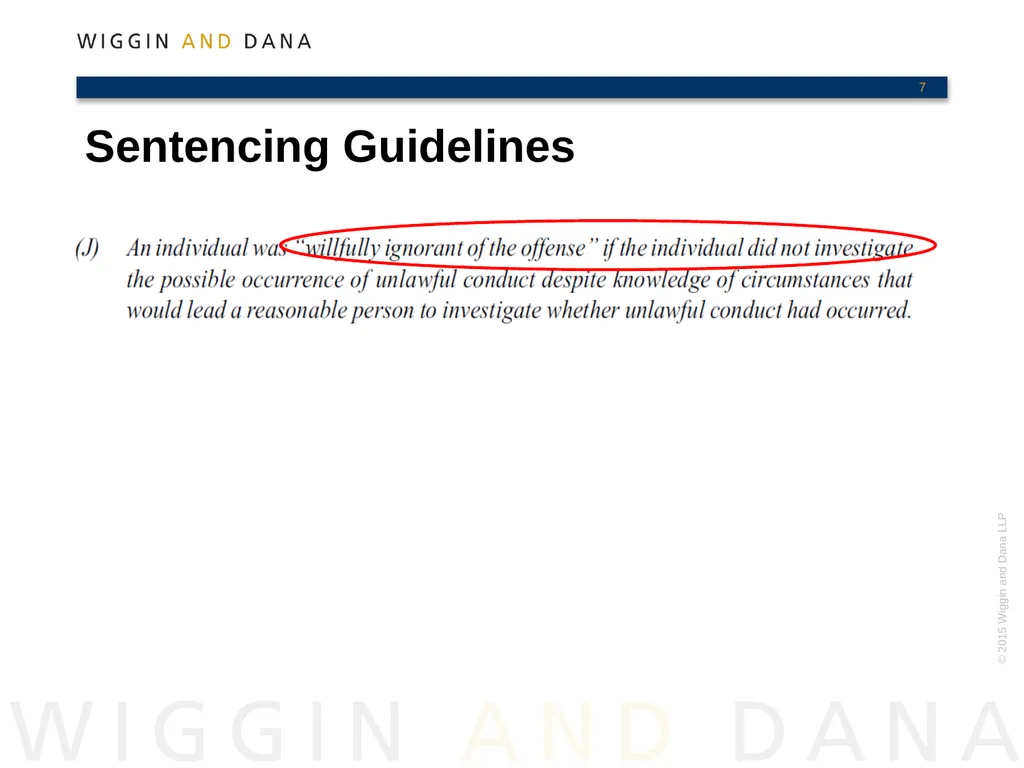
Sentencing Guidelines<br>
07
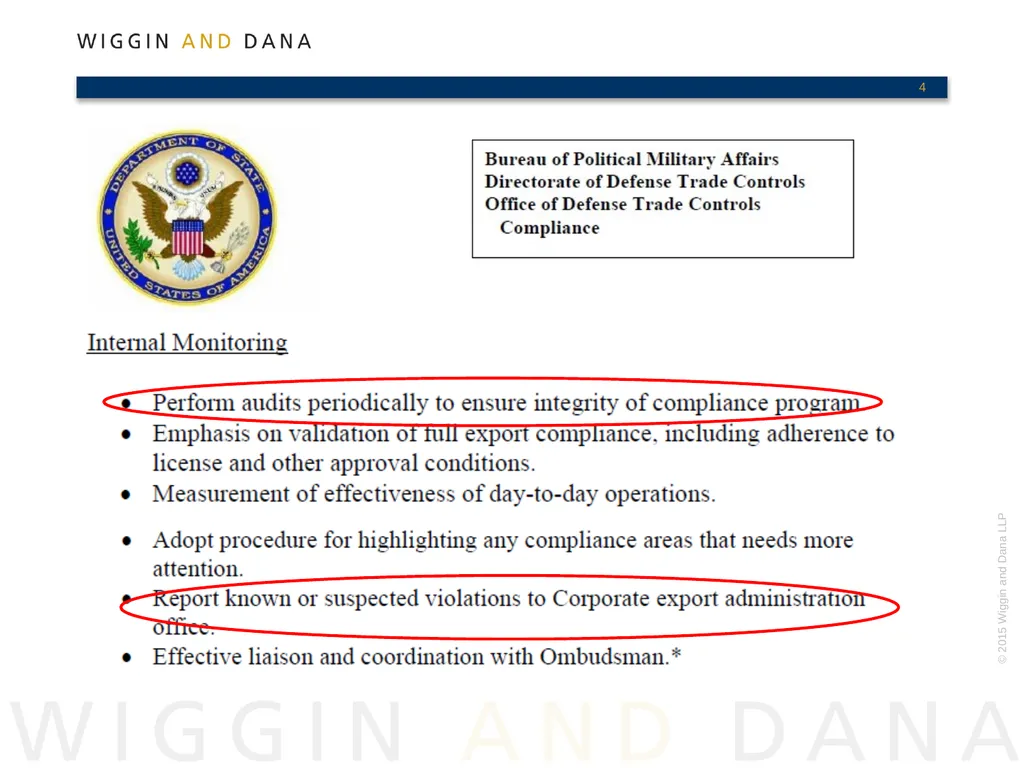
Why audit?
USG expectations
Risk mgmt - if it isn’t audited, it isn’t done
Culture and awareness
Who should perform the audit?
Business or legal?
Internal or external?
Scope & frequency
Risk profile
Manageability
Prevention, detection, & cure Preliminary considerations<br>
08
Volume of hardware exports
Exports to known transshipment hubs (e.g., UAE, Turkey …)
Exports to countries with high numbers of SDNs/Entity List parties (e.g., China, Pakistan, Russia, Singapore …)
Sensitivity of technology (e.g., aerospace, electronics, high-tech materials, semi-conductors, nuclear-related machinery …)
Volume of foreign suppliers
External access to IT systems (supplier portals, etc.)
Foreign subsidiaries/offices (conflicts between sanctions regimes; awareness of re-export obligations)
Volume of foreign employees
Mergers and acquisitions (integration, culture, successor liability) Factors Affecting Risk Level<br>
09
Perform under legal direction
Think carefully about scope & frequency
Have a written audit process & timetable
Review BIS’ online EMCP Audit Module Self-Assessment Tool
Document carefully
Act promptly on findings
Assign owners and track completion (with proof!)
Create mechanisms for accountability
Watch out for recidivism Tips for successful audits<br>
10
Internal Investigations<br>
11
Audit finding
Employee report
Third party report
M&A due diligence
Government inquiry, direction, subpoena, or search
Data mining
Competitor/whistleblower
Border seizure
Disclosure/other investigation How do investigations start?<br>
12
Determine whether a violation occurred
If so:
Identify who, what, when, and where of violation
Determine root cause
Implement corrective actions
Disclose in appropriate cases
If no:
Document conclusion of no violation
Identify and address the causes of the near-miss
Demonstrate commitment to compliance Goals<br>
13
Who should perform the investigation?
How should it be scoped?
Should we disclose? Considerations<br>
14
Mandatory when ITAR 126.1 implicated
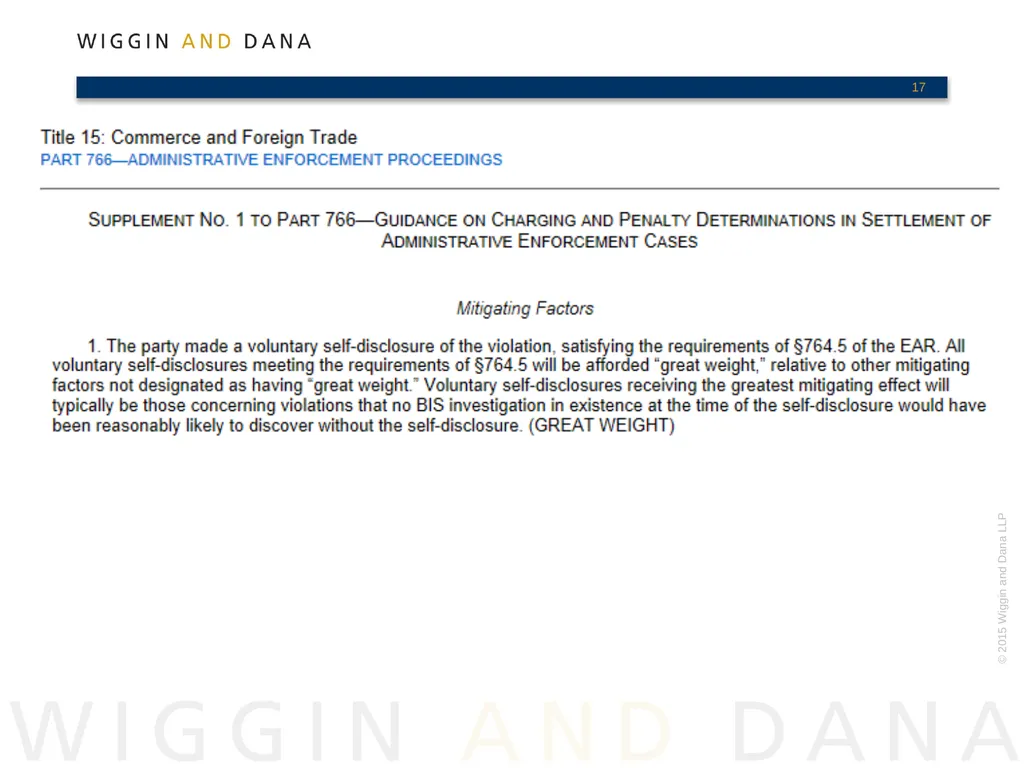
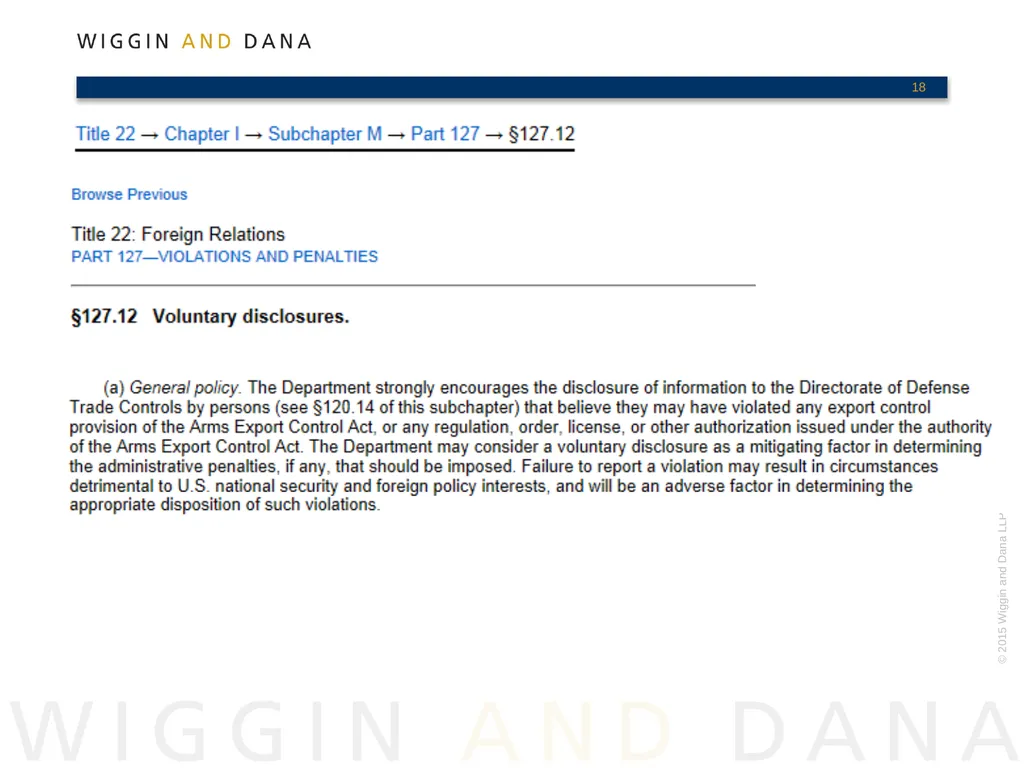
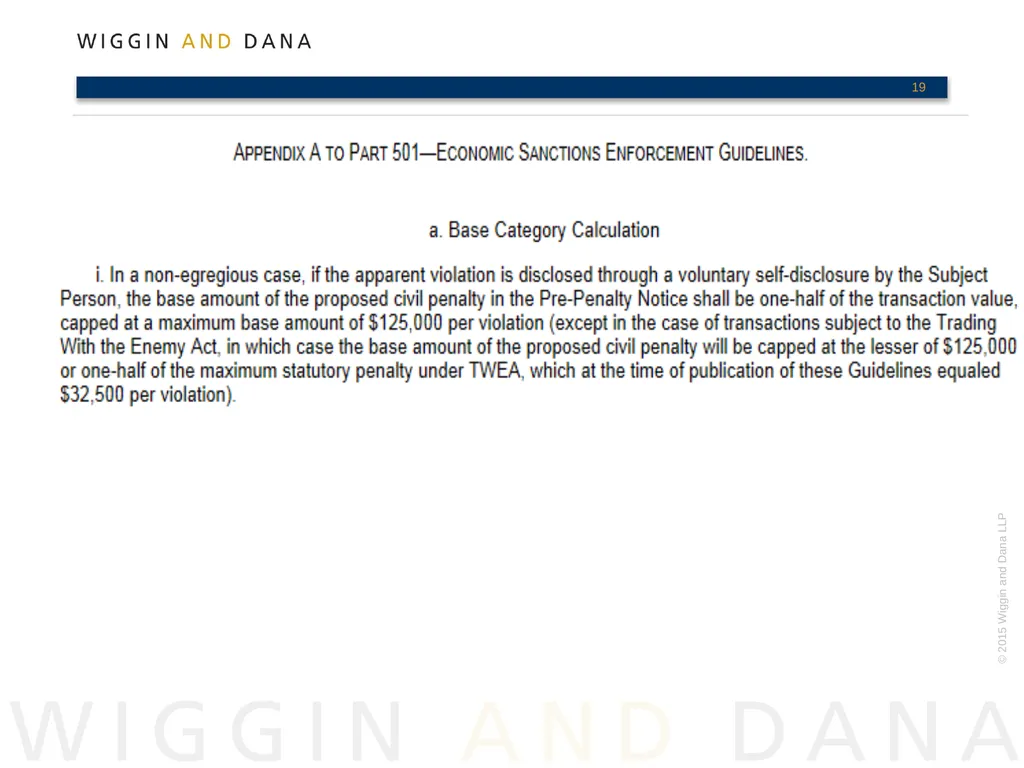
Mitigation of penalties
15 CFR 766, Supp. 1 – “great weight”
22 CFR 127.12 “may be considered”
31 CFR Part 501 “important factor”; 50% penalty reduction (Appx A)
Credit only given if submitted before USG learns elsewhere (IVD?)
Failure to disclose will be considered “an adverse factor” (ITAR); “deliberate concealment” is an aggravating factor (EAR)
Most disclosures result in a warning letter but no guarantee
Resources, penalties & public relations risks must be weighed Whether and when to disclose<br>
15
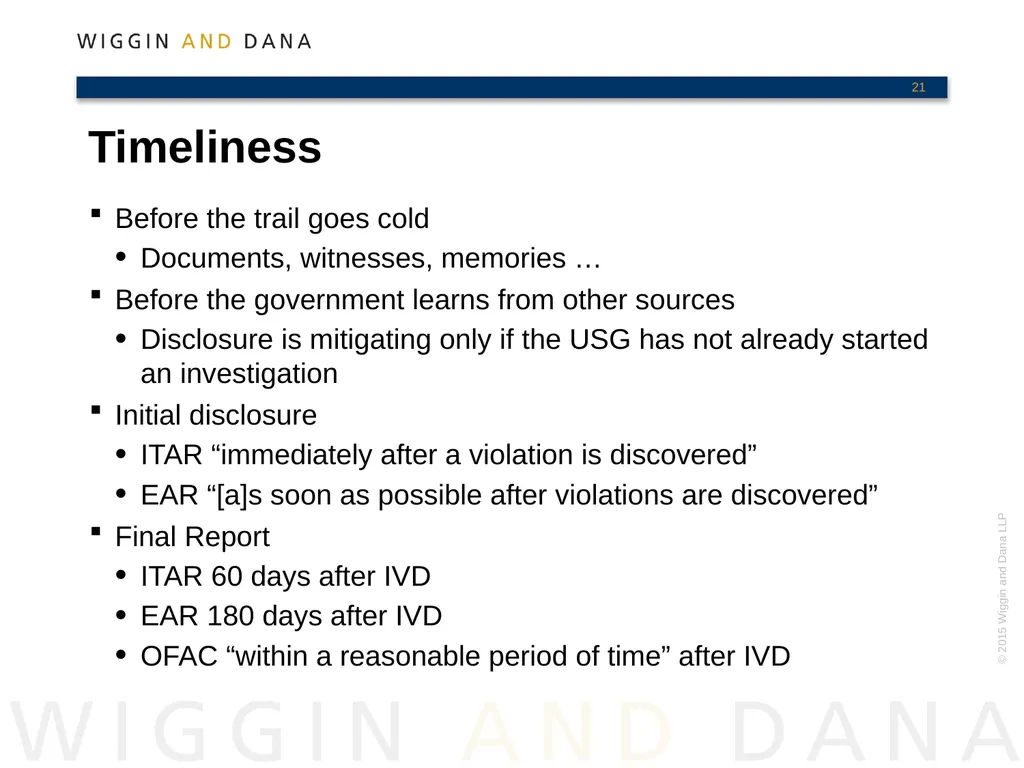
Timely
Accurate
Complete
Convincingly corrected Cardinal Rules<br>
16
Before the trail goes cold
Documents, witnesses, memories …
Before the government learns from other sources
Disclosure is mitigating only if the USG has not already started an investigation
Initial disclosure
ITAR “immediately after a violation is discovered”
EAR “[a]s soon as possible after violations are discovered”
Final Report
ITAR 60 days after IVD
EAR 180 days after IVD
OFAC “within a reasonable period of time” after IVD Timeliness<br>
17
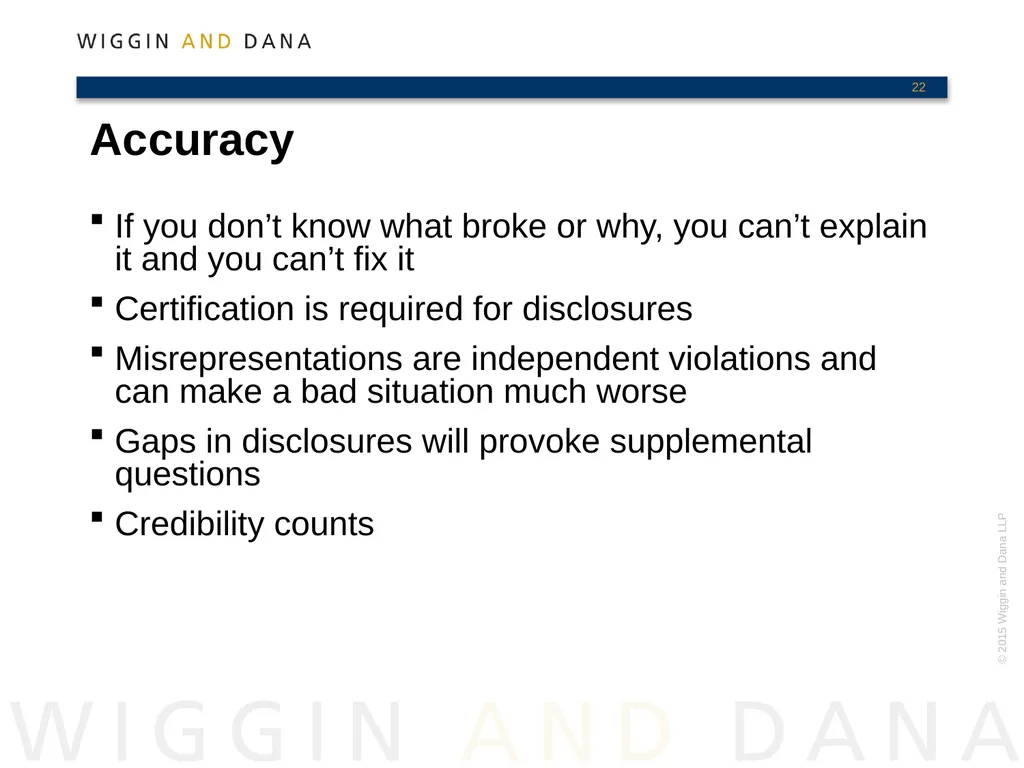
If you don’t know what broke or why, you can’t explain it and you can’t fix it
Certification is required for disclosures
Misrepresentations are independent violations and can make a bad situation much worse
Gaps in disclosures will provoke supplemental questions
Credibility counts Accuracy<br>
18
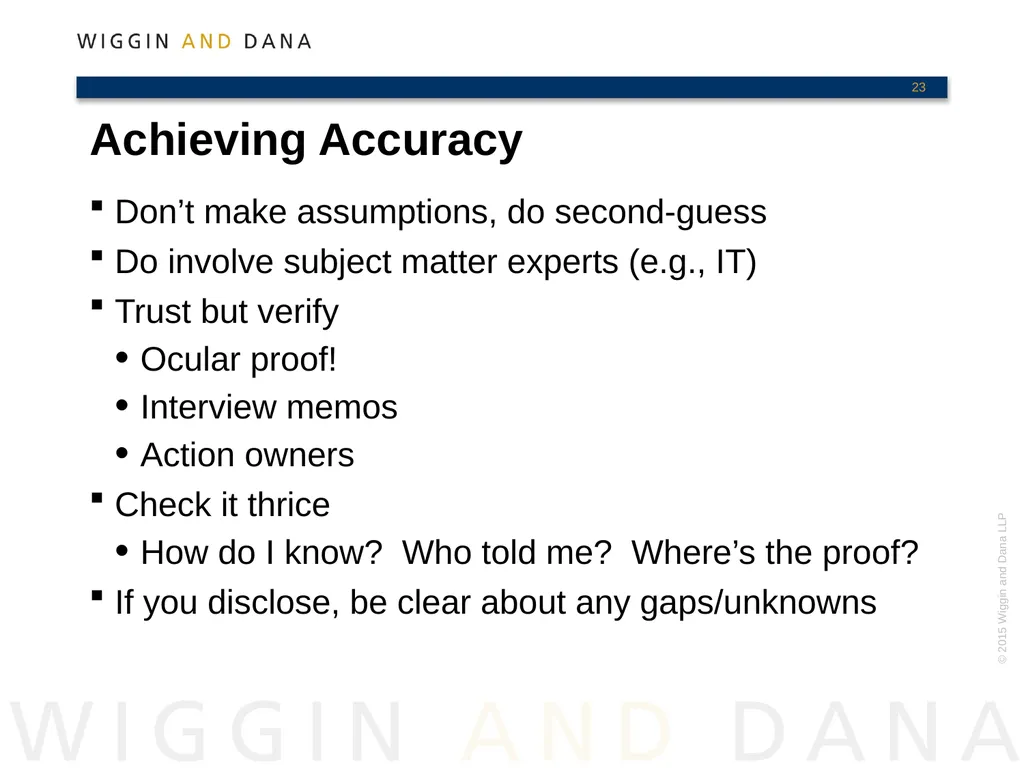
Don’t make assumptions, do second-guess
Do involve subject matter experts (e.g., IT)
Trust but verify
Ocular proof!
Interview memos
Action owners
Check it thrice
How do I know? Who told me? Where’s the proof?
If you disclose, be clear about any gaps/unknowns Achieving Accuracy<br>
19
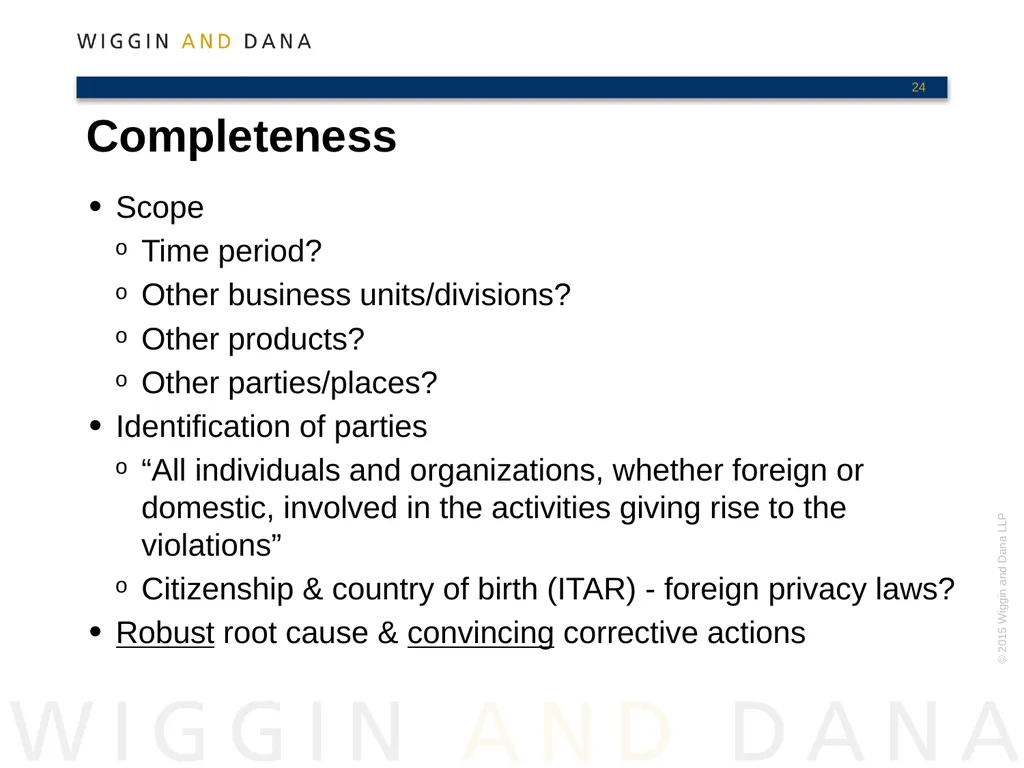
Scope
Time period?
Other business units/divisions?
Other products?
Other parties/places?
Identification of parties
“All individuals and organizations, whether foreign or domestic, involved in the activities giving rise to the violations”
Citizenship & country of birth (ITAR) - foreign privacy laws?
Robust root cause & convincing corrective actions Completeness<br>
20
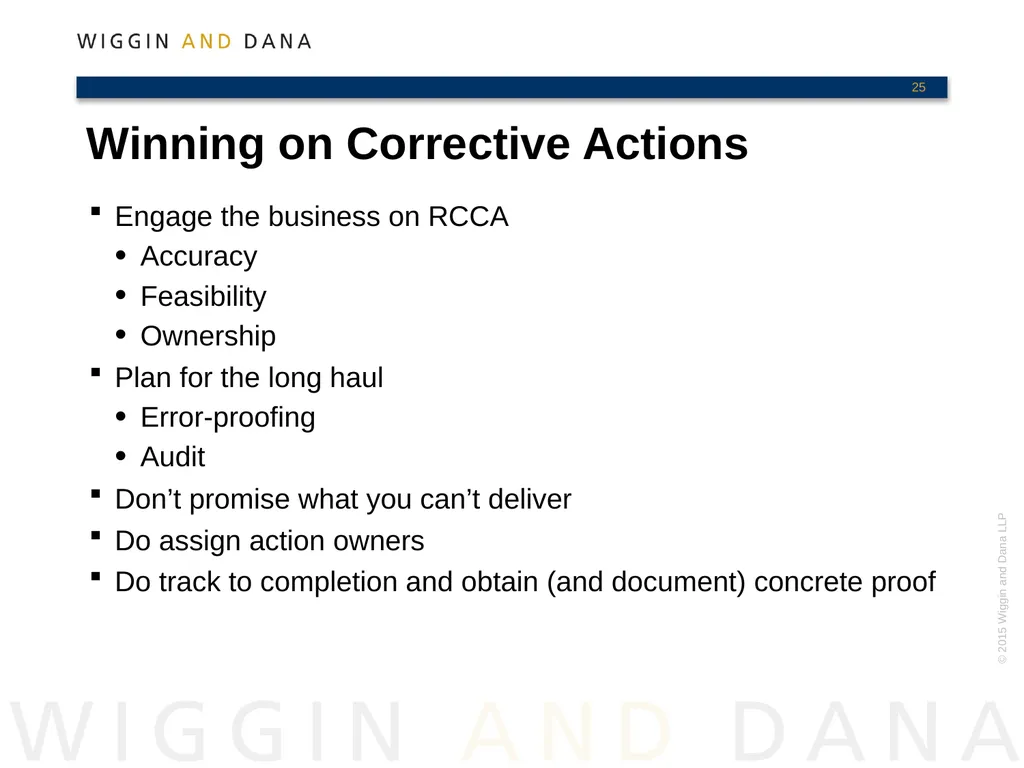
Engage the business on RCCA
Accuracy
Feasibility
Ownership
Plan for the long haul
Error-proofing
Audit
Don’t promise what you can’t deliver
Do assign action owners
Do track to completion and obtain (and document) concrete proof Winning on Corrective Actions<br>
21
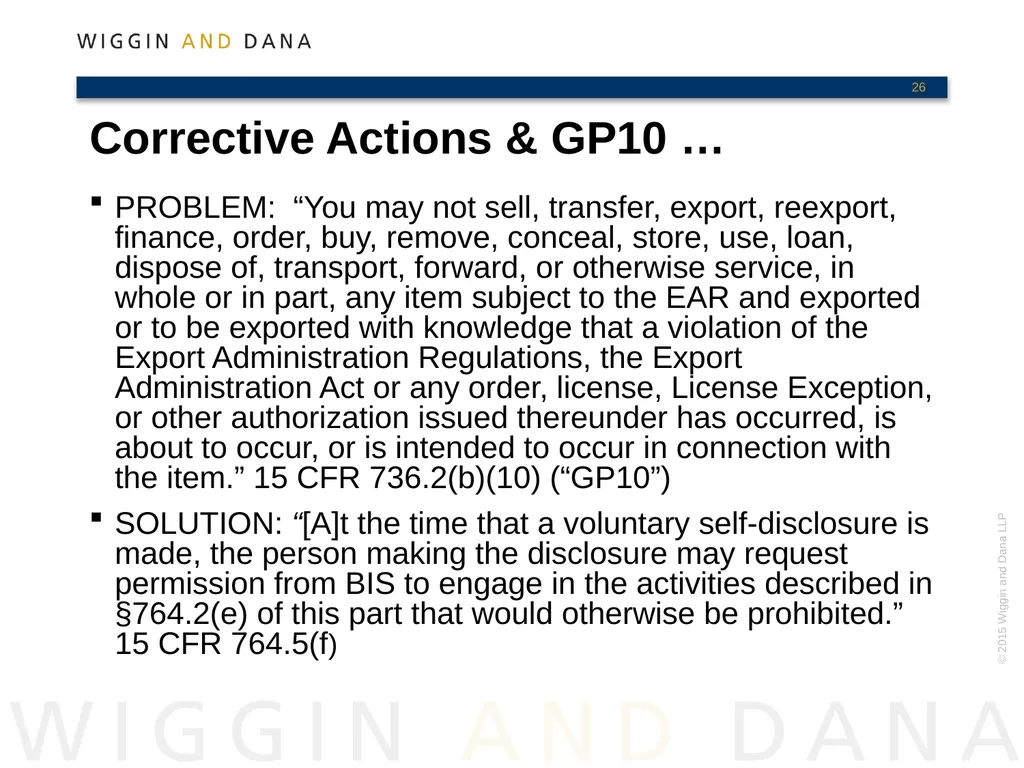
PROBLEM: “You may not sell, transfer, export, reexport, finance, order, buy, remove, conceal, store, use, loan, dispose of, transport, forward, or otherwise service, in whole or in part, any item subject to the EAR and exported or to be exported with knowledge that a violation of the Export Administration Regulations, the Export Administration Act or any order, license, License Exception, or other authorization issued thereunder has occurred, is about to occur, or is intended to occur in connection with the item.” 15 CFR 736.2(b)(10) (“GP10”)
SOLUTION: “[A]t the time that a voluntary self-disclosure is made, the person making the disclosure may request permission from BIS to engage in the activities described in §764.2(e) of this part that would otherwise be prohibited.” 15 CFR 764.5(f) Corrective Actions & GP10 …<br>
22
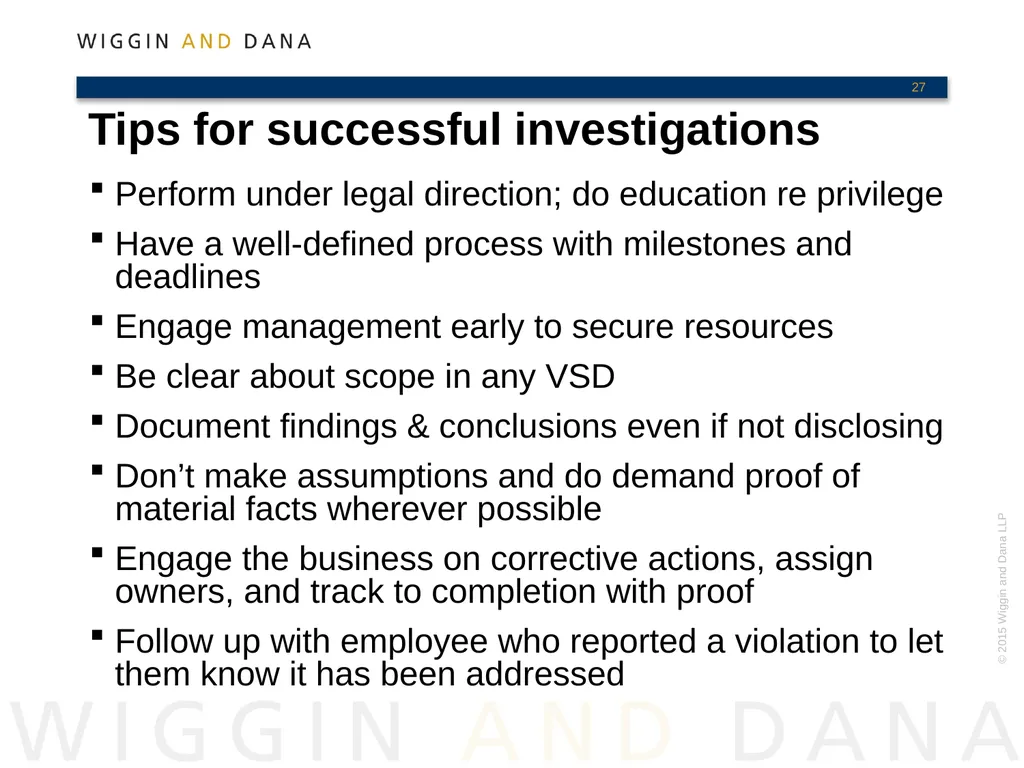
Perform under legal direction; do education re privilege
Have a well-defined process with milestones and deadlines
Engage management early to secure resources
Be clear about scope in any VSD
Document findings & conclusions even if not disclosing
Don’t make assumptions and do demand proof of material facts wherever possible
Engage the business on corrective actions, assign owners, and track to completion with proof
Follow up with employee who reported a violation to let them know it has been addressed Tips for successful investigations<br>
23
Government Investigations<br>
24
Hold notice
Deadline
Scope
Protection of privileged information
Record of production
Internal investigation Responding to a Subpoena<br>
25
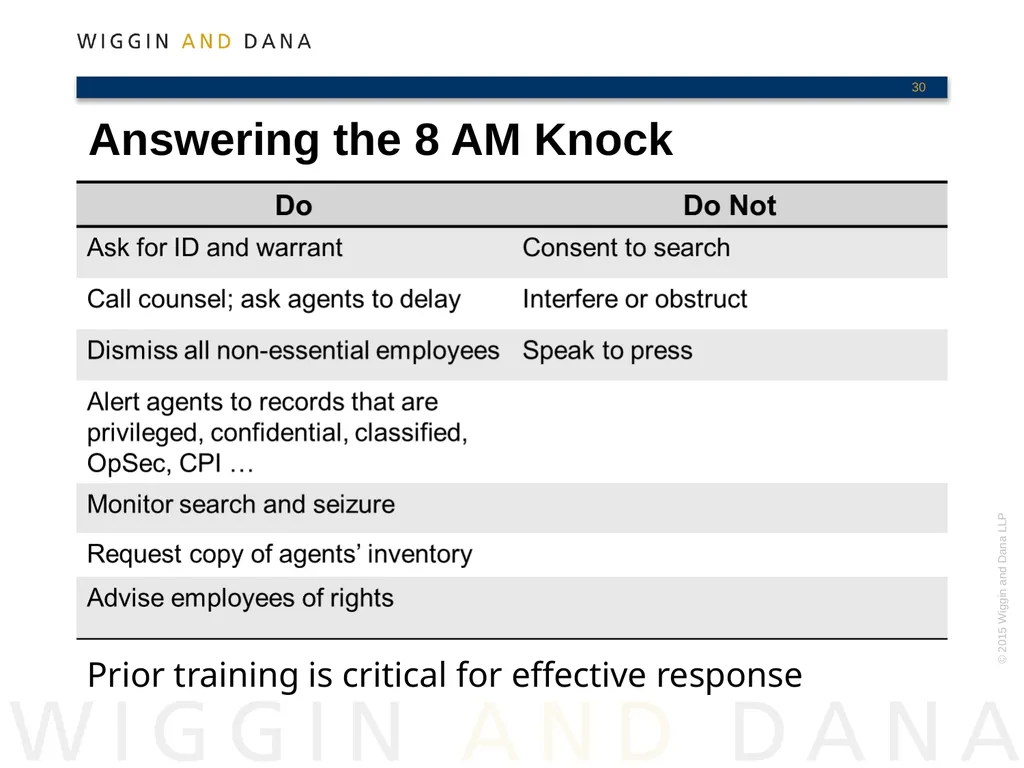
Answering the 8 AM Knock Prior training is critical for effective response<br>
26
Clarify nature of investigation and scope of search
Assert representation of corporation and employees; instruct agents not to interview employees without counsel present
Assist in advising employees of rights and dismissing non-essential employees
Monitor search
Minimize business disruption (computers etc.)
Alert agents to privileged, classified, otherwise sensitive documents
Liaise with case agent / agency lawyer
Timely launch internal investigation Why call counsel?<br>
27
TELL THE TRUTH
Describe nature of investigation
No obligation to assist in search, but may do so
Government may ask to interview employees, at home or work
Employees have the right to consult with attorney before consenting to an interview, and have right to speak to investigator with counsel present, without counsel present, or to not to speak at all
Employees have the right to understand the questions asked and to fully explain their answers. Employees are not required to speculate or answer a question they do not understand.
The company has retained counsel; the company may also arrange for counsel for employees and will/will not advance fees/costs of counsel
Employees should not provide company documents to investigators without notifying company counsel Employee Advice of Rights<br>
28
Don’t think it’s over!
Conduct internal investigation
Hold notice
Document collection
Witness interviews
Voluntary disclosure
Corrective actions
Manage dialogue with DOJ After the Search<br>
29
Tone from top – visible management commitment
Easy internal reporting – no retaliation
Thorough investigation – robust response
Meaningful corrective actions
Regular audit
Records of compliance activities
Adequate resources
Meaningful, function-specific training
Clear marking of privileged, confidential, classified, export-controlled, and other sensitive documents
Smoking gun prevention (email, memos, social media …) An Ounce of Prevention …<br>
30
This presentation is a summary of legal principles. Nothing in this presentation constitutes legal advice, which can only be obtained as a result of a personal consultation with an attorney. The information published here is believed accurate at the time of publication, but is subject to change and does not purport to be a complete statement of all relevant issues. Wiggin and Dana’s International Trade Compliance Team Practice Contact: Tahlia Townsend, ttownsend@wiggin.com, 203 498 4339<br>