
March 2021 Canada’s Pandemic & Post Pandemic

Description: March 2021 Canadas Pandemic Post Pandemic Challenges Opportunities Craig Alexander Chief Economist and Executive Advisor Canadas Economic Recovery set to Slow in the Near Term Sources: Deloitte, Statistics Canada Real GDP,
Related Topics
Download Presentation
"March 2021 Canada’s Pandemic & Post Pandemic" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. March 2021 Canada’s Pandemic & Post Pandemic Challenges & Opportunities
Craig Alexander
Chief Economist and Executive Advisor<br>
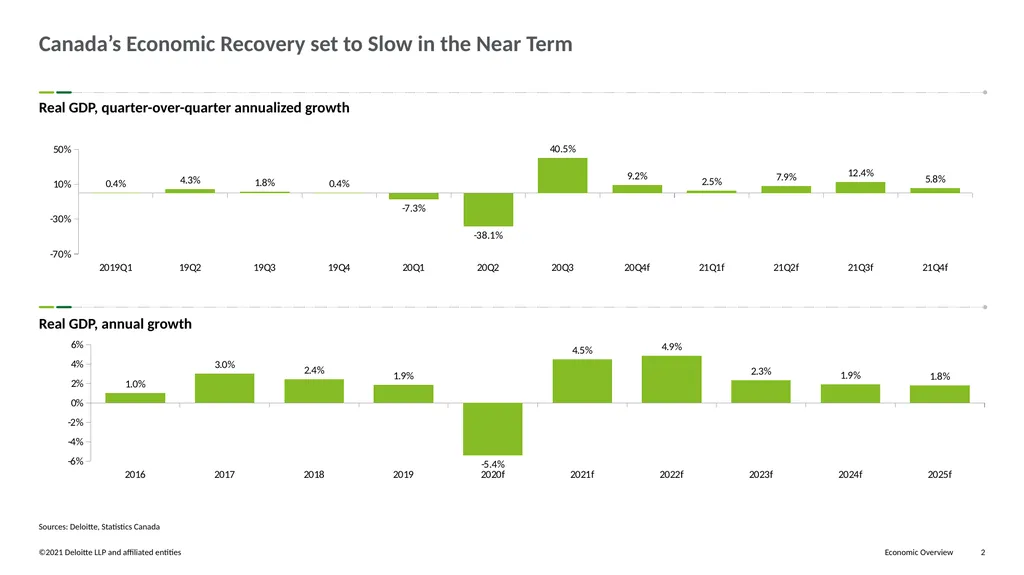
slide2. Canada’s Economic Recovery set to Slow in the Near Term Sources: Deloitte, Statistics Canada Real GDP, quarter-over-quarter annualized growth Real GDP, annual growth<br>
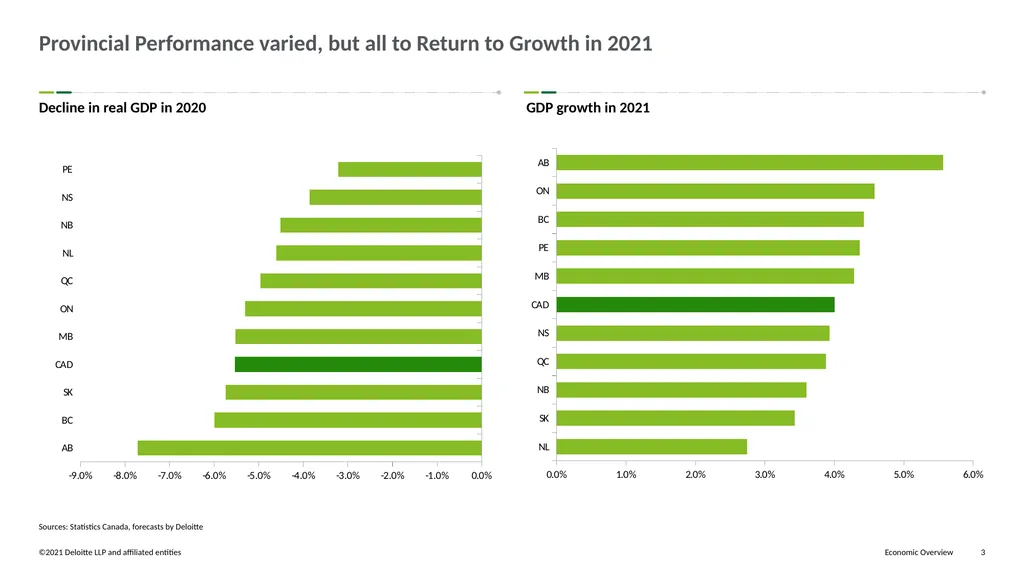
slide3. Provincial Performance varied, but all to Return to Growth in 2021 Decline in real GDP in 2020 GDP growth in 2021 Sources: Statistics Canada, forecasts by Deloitte<br>
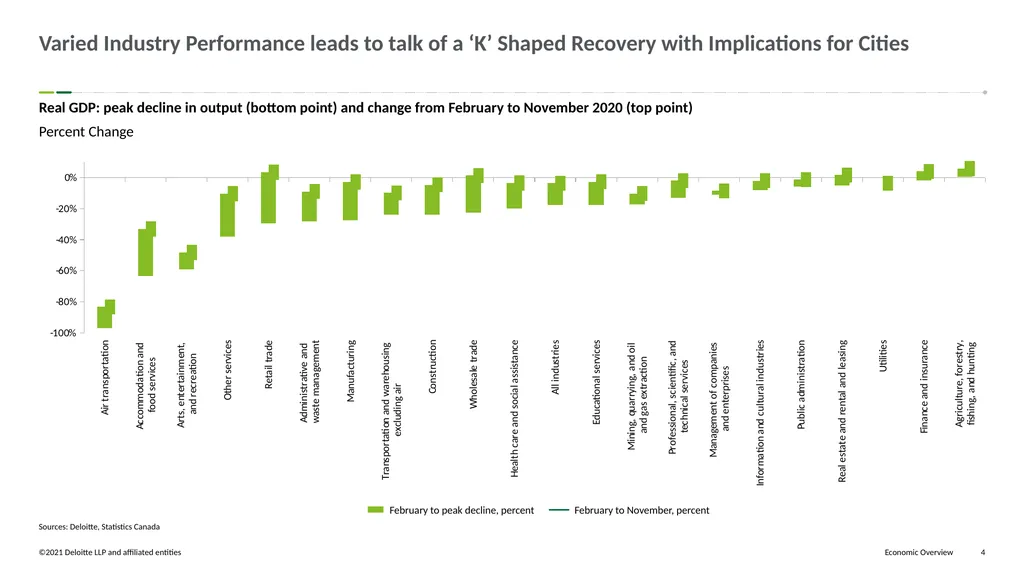
slide4. Varied Industry Performance leads to talk of a ‘K’ Shaped Recovery with Implications for Cities Sources: Deloitte, Statistics Canada Real GDP: peak decline in output (bottom point) and change from February to November 2020 (top point)
Percent Change<br>
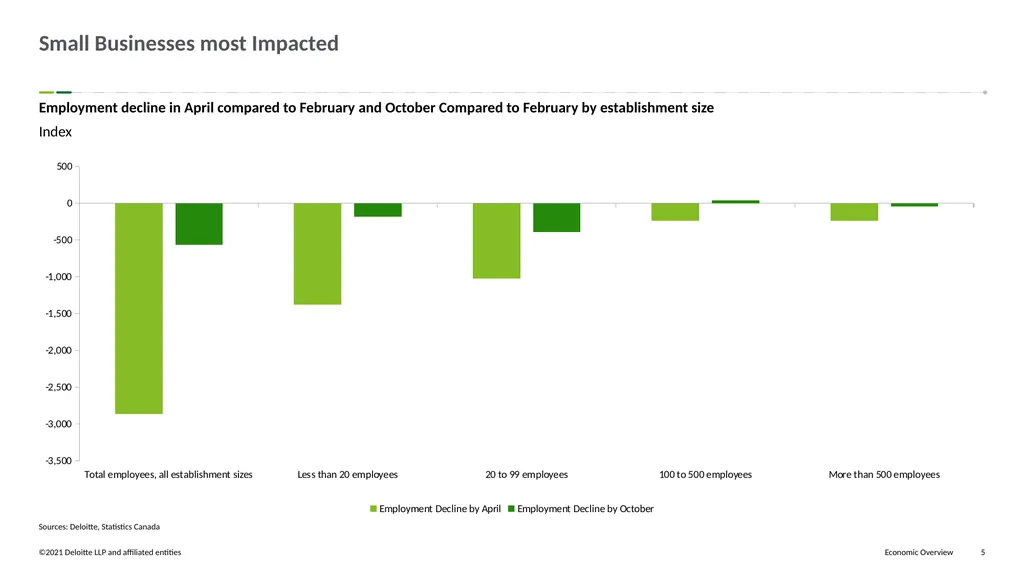
slide5. Small Businesses most Impacted Sources: Deloitte, Statistics Canada Employment decline in April compared to February and October Compared to February by establishment size
Index<br>
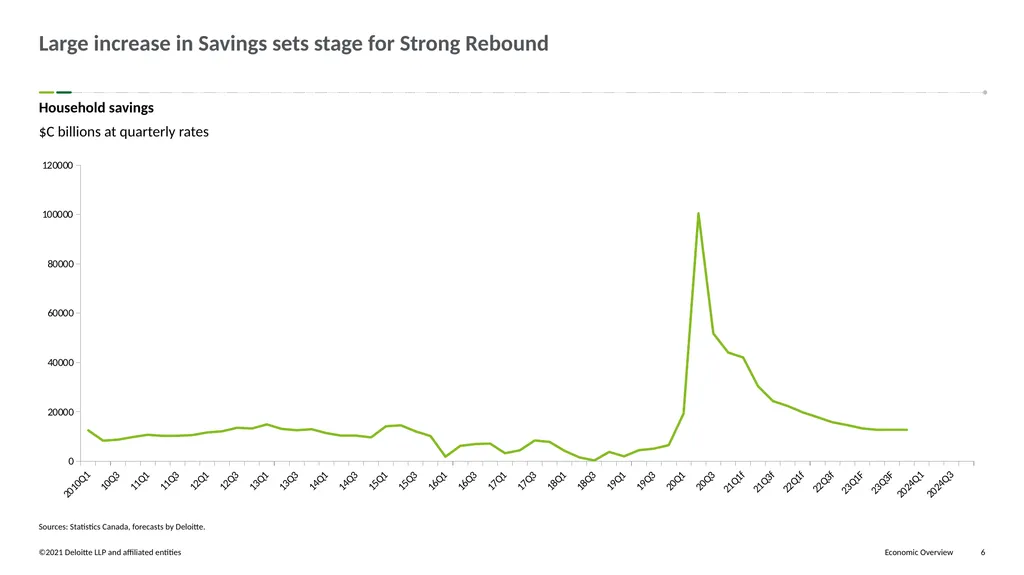
slide6. Large increase in Savings sets stage for Strong Rebound Sources: Statistics Canada, forecasts by Deloitte. Household savings
$C billions at quarterly rates<br>
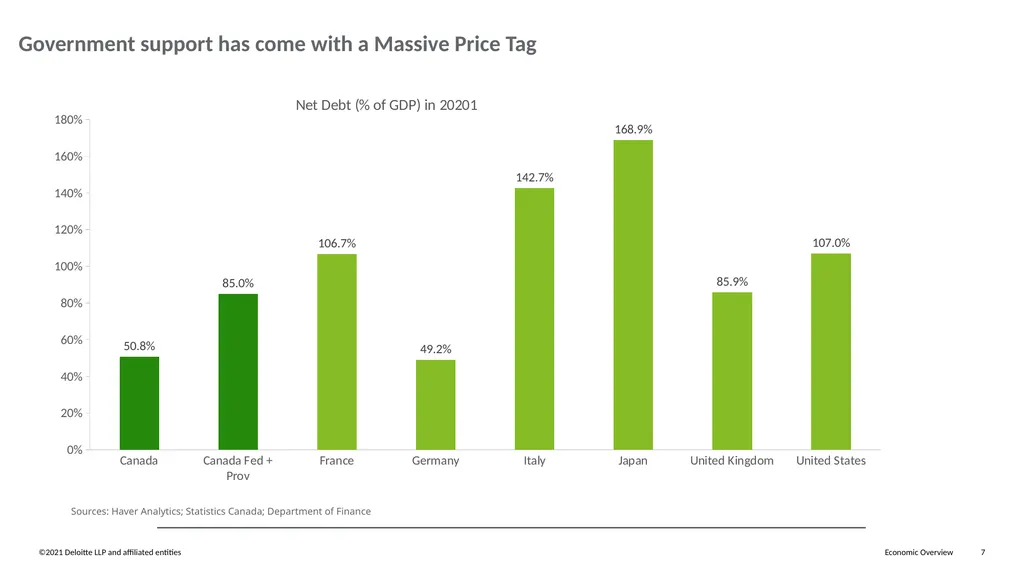
slide7. Government support has come with a Massive Price Tag Sources: Haver Analytics; Statistics Canada; Department of Finance<br>
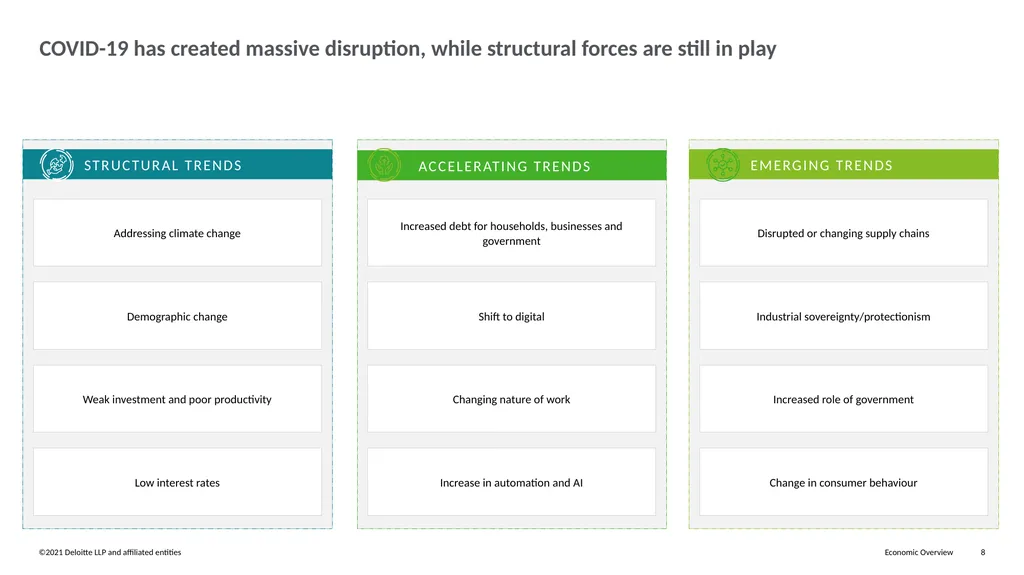
slide8. COVID-19 has created massive disruption, while structural forces are still in play EMERGING TRENDS ACCELERATING TRENDS STRUCTURAL TRENDS<br>
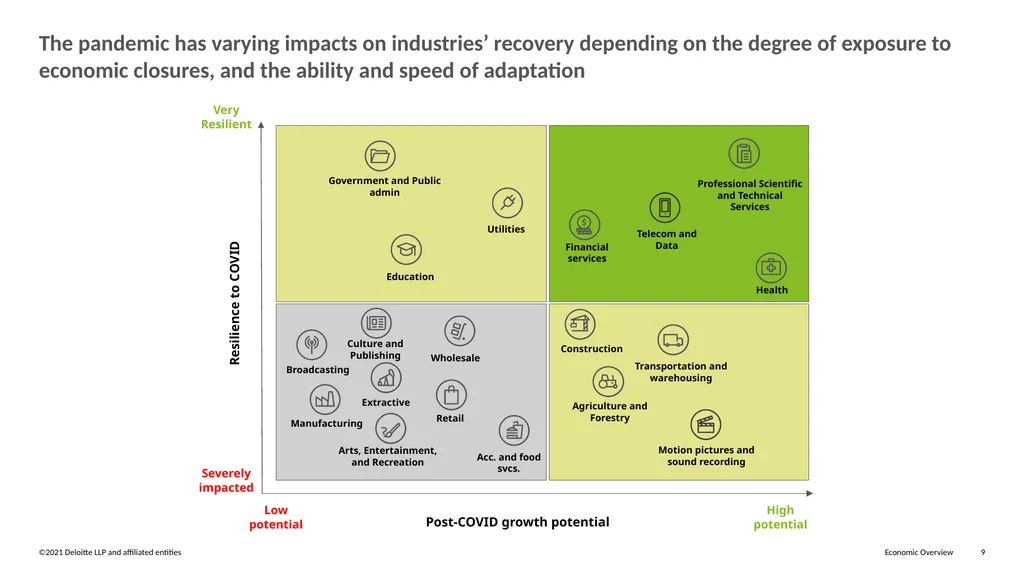
slide9. Resilience to COVID The pandemic has varying impacts on industries’ recovery depending on the degree of exposure to economic closures, and the ability and speed of adaptation Post-COVID growth potential Professional Scientific and Technical Services Health Education Financial services Utilities Wholesale Arts, Entertainment, and Recreation Manufacturing Acc. and food svcs. Culture and Publishing Retail Extractive Construction Agriculture and Forestry Transportation and warehousing Government and Public admin Very Resilient Severely impacted Low potential High potential Motion pictures and sound recording Broadcasting Telecom and Data<br>
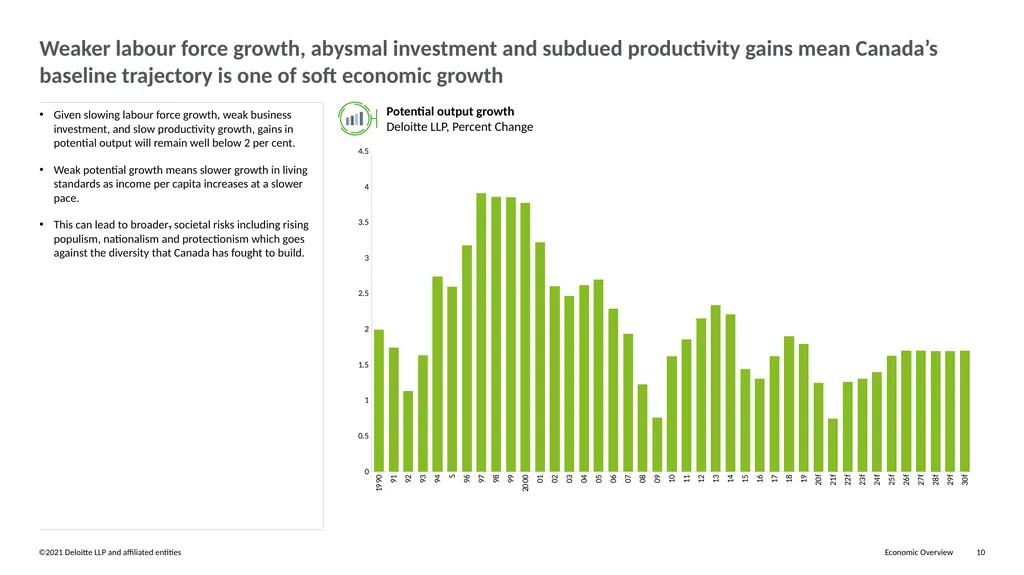
slide10. Weaker labour force growth, abysmal investment and subdued productivity gains mean Canada’s baseline trajectory is one of soft economic growth Given slowing labour force growth, weak business investment, and slow productivity growth, gains in potential output will remain well below 2 per cent.
Weak potential growth means slower growth in living standards as income per capita increases at a slower pace.
This can lead to broader, societal risks including rising populism, nationalism and protectionism which goes against the diversity that Canada has fought to build.<br>
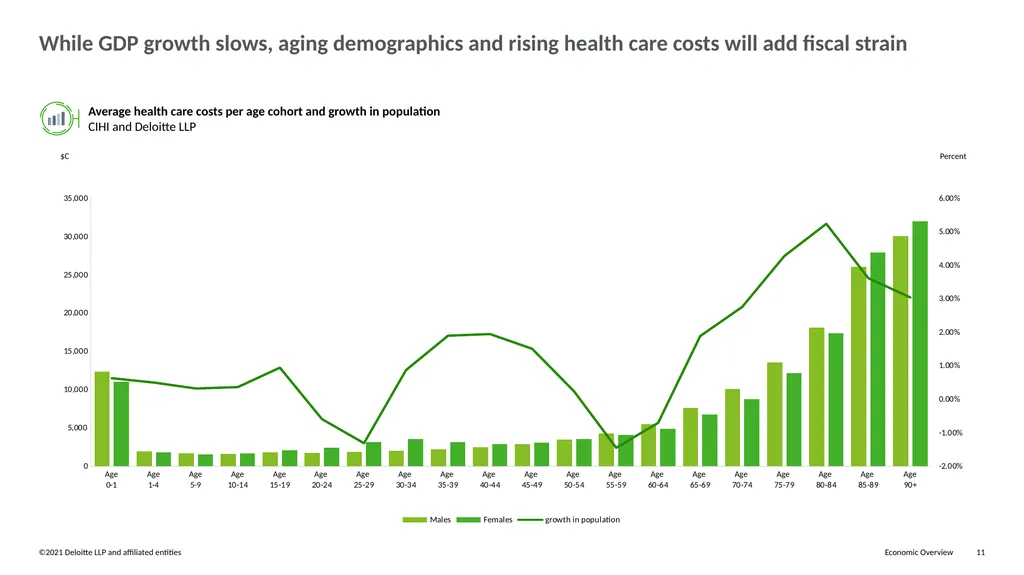
slide11. While GDP growth slows, aging demographics and rising health care costs will add fiscal strain $C Percent<br>
slide12. Pandemic is a Perfect Storm for Municipalities Greatest health crisis and deepest recession in modern history
Large cities more impacted than smaller cities and rural areas
The greater urban impact reflects industry distribution, with hardest hit industries more concentrated in larger cities
Job losses concentrated in the most vulnerable workers: low income, women, visible monitories, people of colour – again due to the occupational distribution of workers
Dramatic shift to digital and move to remote work is more disruptive to urban centres with particular impact on housing and transit
Commercial real estate weakened by recession but also the industry distributional impact and shift to digital and remote work
The result has been lower revenues but also increased demand for selected public services resulting from the economic and labour market shock
This decline and revenues and increases demand for public services is a perfect storm for urban centres
Pandemic and recession revealed inadequacies pre-COVID: inequality. income security, childcare, seniors, affordable housing challenge, infrastructure gap<br>
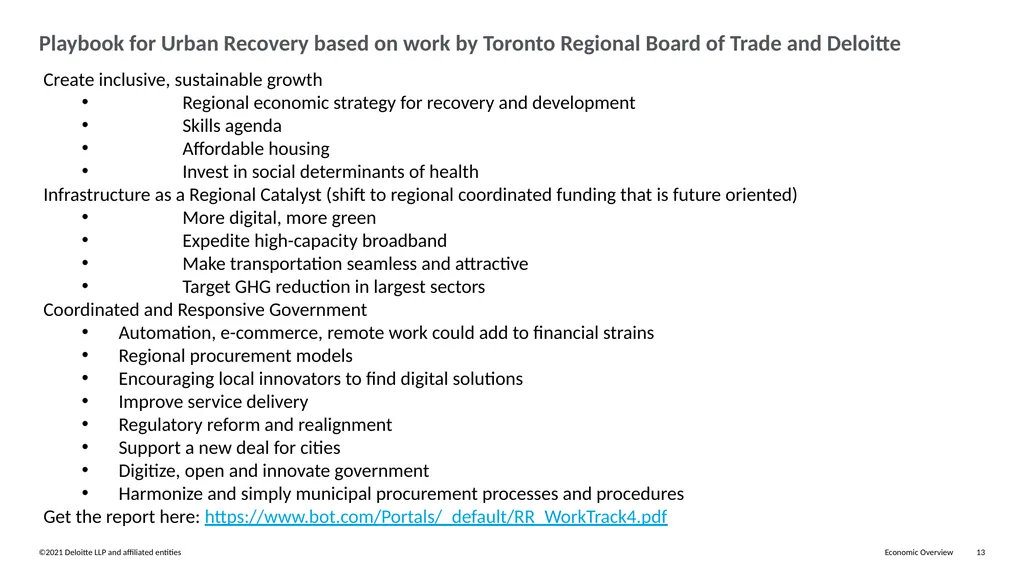
slide13. Playbook for Urban Recovery based on work by Toronto Regional Board of Trade and Deloitte Create inclusive, sustainable growth
Regional economic strategy for recovery and development
Skills agenda
Affordable housing
Invest in social determinants of health
Infrastructure as a Regional Catalyst (shift to regional coordinated funding that is future oriented)
More digital, more green
Expedite high-capacity broadband
Make transportation seamless and attractive
Target GHG reduction in largest sectors
Coordinated and Responsive Government
Automation, e-commerce, remote work could add to financial strains
Regional procurement models
Encouraging local innovators to find digital solutions
Improve service delivery
Regulatory reform and realignment
Support a new deal for cities
Digitize, open and innovate government
Harmonize and simply municipal procurement processes and procedures
Get the report here: https://www.bot.com/Portals/_default/RR_WorkTrack4.pdf<br>
slide14. Deloitte, one of Canada's leading professional services firms, provides audit, tax, consulting, and financial advisory services. Deloitte LLP, an Ontario limited liability partnership, is the Canadian member firm of Deloitte Touche Tohmatsu Limited.
Deloitte refers to one or more of Deloitte Touche Tohmatsu Limited, a UK private company limited by guarantee, and its network of member firms, each of which is a legally separate and independent entity. Please see www.deloitte.com/about for a detailed description of the legal structure of Deloitte Touche Tohmatsu Limited and its member firms.
The information contained herein is not intended to substitute for competent professional advice.
© 2021 Deloitte LLP and affiliated entities.<br>
slide2. Canada’s Economic Recovery set to Slow in the Near Term Sources: Deloitte, Statistics Canada Real GDP, quarter-over-quarter annualized growth Real GDP, annual growth<br>
slide3. Provincial Performance varied, but all to Return to Growth in 2021 Decline in real GDP in 2020 GDP growth in 2021 Sources: Statistics Canada, forecasts by Deloitte<br>
slide4. Varied Industry Performance leads to talk of a ‘K’ Shaped Recovery with Implications for Cities Sources: Deloitte, Statistics Canada Real GDP: peak decline in output (bottom point) and change from February to November 2020 (top point)
Percent Change<br>
slide5. Small Businesses most Impacted Sources: Deloitte, Statistics Canada Employment decline in April compared to February and October Compared to February by establishment size
Index<br>
slide6. Large increase in Savings sets stage for Strong Rebound Sources: Statistics Canada, forecasts by Deloitte. Household savings
$C billions at quarterly rates<br>
slide7. Government support has come with a Massive Price Tag Sources: Haver Analytics; Statistics Canada; Department of Finance<br>
slide8. COVID-19 has created massive disruption, while structural forces are still in play EMERGING TRENDS ACCELERATING TRENDS STRUCTURAL TRENDS<br>
slide9. Resilience to COVID The pandemic has varying impacts on industries’ recovery depending on the degree of exposure to economic closures, and the ability and speed of adaptation Post-COVID growth potential Professional Scientific and Technical Services Health Education Financial services Utilities Wholesale Arts, Entertainment, and Recreation Manufacturing Acc. and food svcs. Culture and Publishing Retail Extractive Construction Agriculture and Forestry Transportation and warehousing Government and Public admin Very Resilient Severely impacted Low potential High potential Motion pictures and sound recording Broadcasting Telecom and Data<br>
slide10. Weaker labour force growth, abysmal investment and subdued productivity gains mean Canada’s baseline trajectory is one of soft economic growth Given slowing labour force growth, weak business investment, and slow productivity growth, gains in potential output will remain well below 2 per cent.
Weak potential growth means slower growth in living standards as income per capita increases at a slower pace.
This can lead to broader, societal risks including rising populism, nationalism and protectionism which goes against the diversity that Canada has fought to build.<br>
slide11. While GDP growth slows, aging demographics and rising health care costs will add fiscal strain $C Percent<br>
slide12. Pandemic is a Perfect Storm for Municipalities Greatest health crisis and deepest recession in modern history
Large cities more impacted than smaller cities and rural areas
The greater urban impact reflects industry distribution, with hardest hit industries more concentrated in larger cities
Job losses concentrated in the most vulnerable workers: low income, women, visible monitories, people of colour – again due to the occupational distribution of workers
Dramatic shift to digital and move to remote work is more disruptive to urban centres with particular impact on housing and transit
Commercial real estate weakened by recession but also the industry distributional impact and shift to digital and remote work
The result has been lower revenues but also increased demand for selected public services resulting from the economic and labour market shock
This decline and revenues and increases demand for public services is a perfect storm for urban centres
Pandemic and recession revealed inadequacies pre-COVID: inequality. income security, childcare, seniors, affordable housing challenge, infrastructure gap<br>
slide13. Playbook for Urban Recovery based on work by Toronto Regional Board of Trade and Deloitte Create inclusive, sustainable growth
Regional economic strategy for recovery and development
Skills agenda
Affordable housing
Invest in social determinants of health
Infrastructure as a Regional Catalyst (shift to regional coordinated funding that is future oriented)
More digital, more green
Expedite high-capacity broadband
Make transportation seamless and attractive
Target GHG reduction in largest sectors
Coordinated and Responsive Government
Automation, e-commerce, remote work could add to financial strains
Regional procurement models
Encouraging local innovators to find digital solutions
Improve service delivery
Regulatory reform and realignment
Support a new deal for cities
Digitize, open and innovate government
Harmonize and simply municipal procurement processes and procedures
Get the report here: https://www.bot.com/Portals/_default/RR_WorkTrack4.pdf<br>
slide14. Deloitte, one of Canada's leading professional services firms, provides audit, tax, consulting, and financial advisory services. Deloitte LLP, an Ontario limited liability partnership, is the Canadian member firm of Deloitte Touche Tohmatsu Limited.
Deloitte refers to one or more of Deloitte Touche Tohmatsu Limited, a UK private company limited by guarantee, and its network of member firms, each of which is a legally separate and independent entity. Please see www.deloitte.com/about for a detailed description of the legal structure of Deloitte Touche Tohmatsu Limited and its member firms.
The information contained herein is not intended to substitute for competent professional advice.
© 2021 Deloitte LLP and affiliated entities.<br>