
Materiality and Risk Chapter 9 Learning Objective
A
Published · 48 slides · 0 views
1 / 1
Description
Materiality and Risk Chapter 9 Learning Objective 1 Apply the concept of materiality to the audit. Materiality The auditors responsibility is to determine whether financial statements are materially misstated. If there is a material
Related Topics
Share
Embed code
Download this presentation From Below
"Materiality and Risk Chapter 9 Learning Objective" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
Materiality and Risk Chapter 9<br>
02
Learning Objective 1 Apply the concept of
materiality to the audit.<br>
materiality to the audit.<br>
03
Materiality The auditor’s responsibility is to
determine whether financial
statements are materially misstated. If there is a material misstatement,
the auditor will bring it to the client’s
attention so that a correction can be made.<br>
determine whether financial
statements are materially misstated. If there is a material misstatement,
the auditor will bring it to the client’s
attention so that a correction can be made.<br>
04
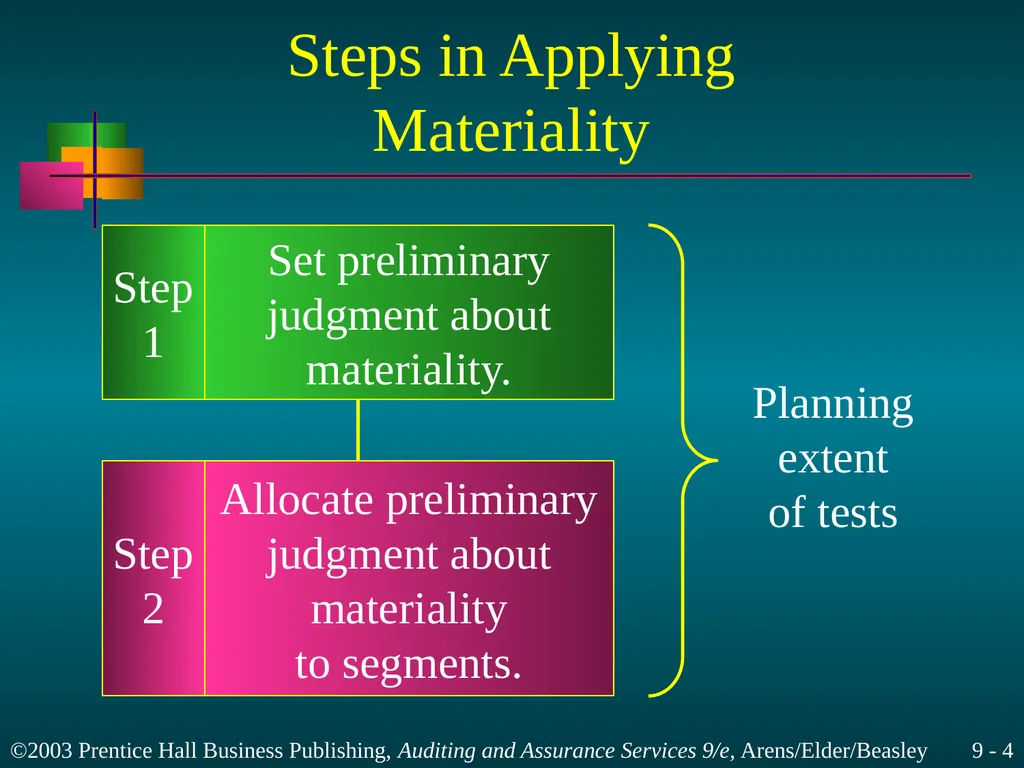
Steps in Applying
Materiality Step
1 Set preliminary
judgment about
materiality. Step
2 Allocate preliminary
judgment about
materiality
to segments. Planning
extent
of tests<br>
1 Set preliminary
judgment about
materiality. Step
2 Allocate preliminary
judgment about
materiality
to segments. Planning
extent
of tests<br>
05
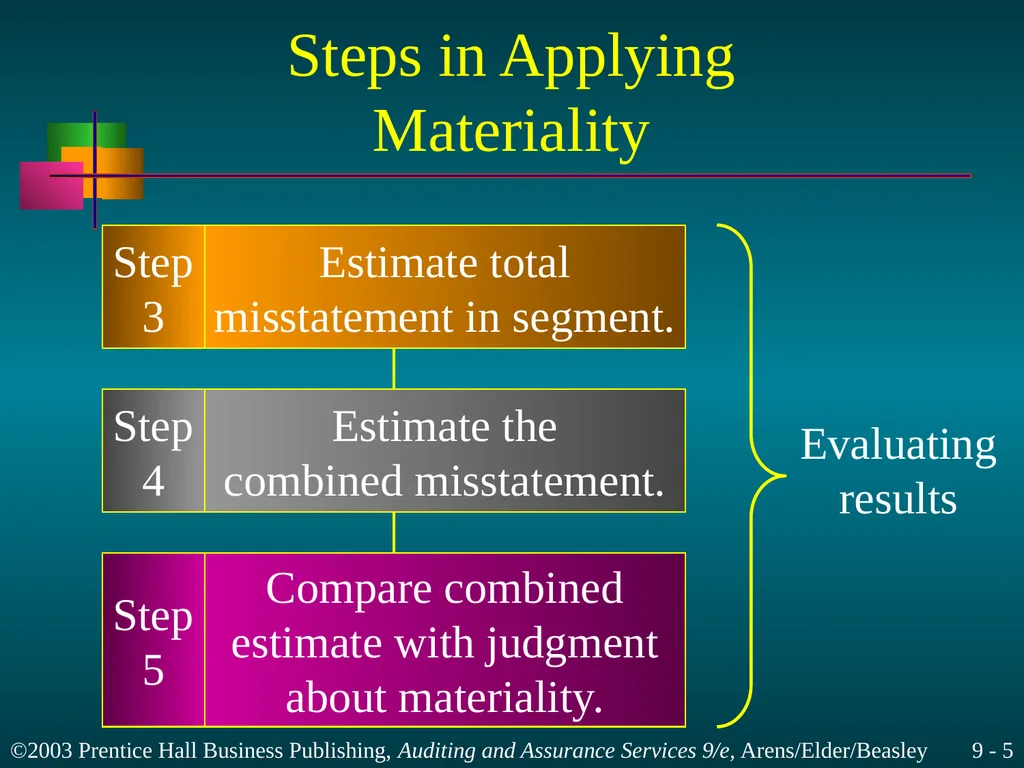
Steps in Applying
Materiality Step
3 Estimate total
misstatement in segment. Step
4 Estimate the
combined misstatement. Evaluating
results Compare combined
estimate with judgment
about materiality. Step
5<br>
3 Estimate total
misstatement in segment. Step
4 Estimate the
combined misstatement. Evaluating
results Compare combined
estimate with judgment
about materiality. Step
5<br>
06
Learning Objective 2 Make a preliminary judgment
about what amounts to
consider material.<br>
about what amounts to
consider material.<br>
07
Set Preliminary Judgment This preliminary judgment is the maximum
amount by which the auditor believes the
statements could be misstated and still not
affect the decisions of reasonable users. Ideally, auditors decide early in the audit
the combined amount of misstatements
of the financial statements that would
be considered material.<br>
amount by which the auditor believes the
statements could be misstated and still not
affect the decisions of reasonable users. Ideally, auditors decide early in the audit
the combined amount of misstatements
of the financial statements that would
be considered material.<br>
08
Factors Affecting Judgment Materiality is a relative rather
than an absolute concept. Bases are needed for
evaluating materiality. Qualitative factors also
affect materiality.<br>
than an absolute concept. Bases are needed for
evaluating materiality. Qualitative factors also
affect materiality.<br>
09
Learning Objective 3 Allocate preliminary materiality
to segments of the audit
during planning.<br>
to segments of the audit
during planning.<br>
10
Allocate Preliminary Judgment About Materiality to Segments This is necessary because evidence is
accumulated by segments rather than
for the financial statements as a whole. Most practitioners allocate materiality
to balance sheet accounts. SAS 39 (AU 350)<br>
accumulated by segments rather than
for the financial statements as a whole. Most practitioners allocate materiality
to balance sheet accounts. SAS 39 (AU 350)<br>
11
Learning Objective 4 Use materiality to evaluate
audit findings.<br>
audit findings.<br>
12
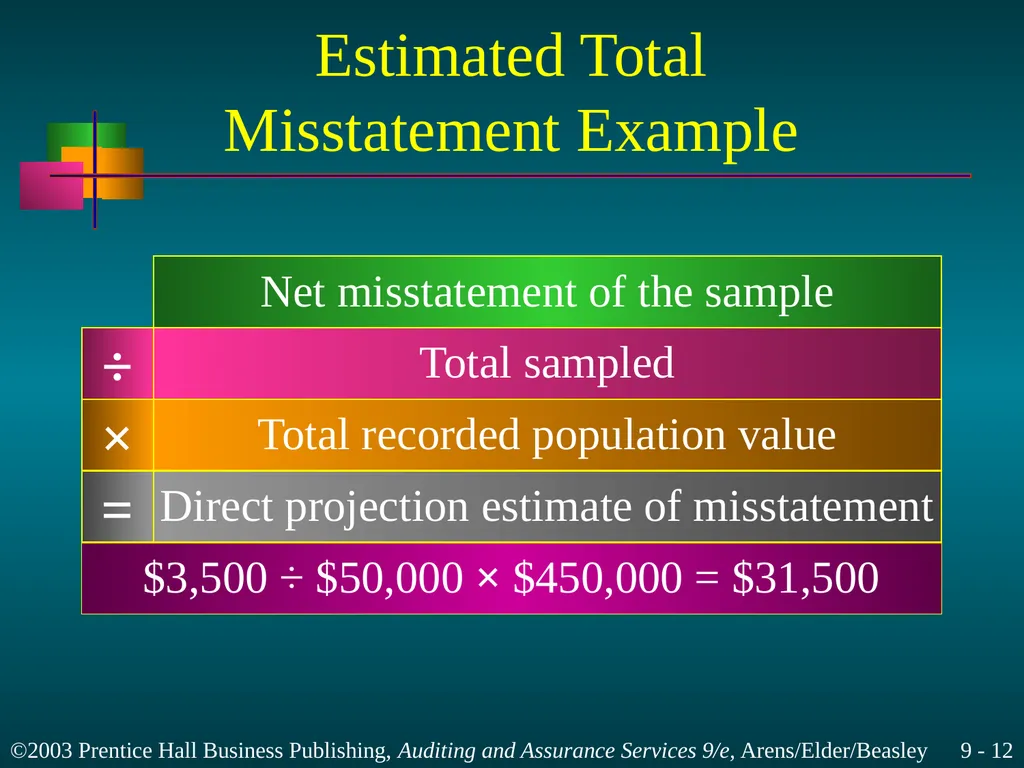
Estimated Total
Misstatement Example Net misstatement of the sample $3,500 ÷ $50,000 × $450,000 = $31,500 Total sampled Total recorded population value Direct projection estimate of misstatement × ÷ =<br>
13
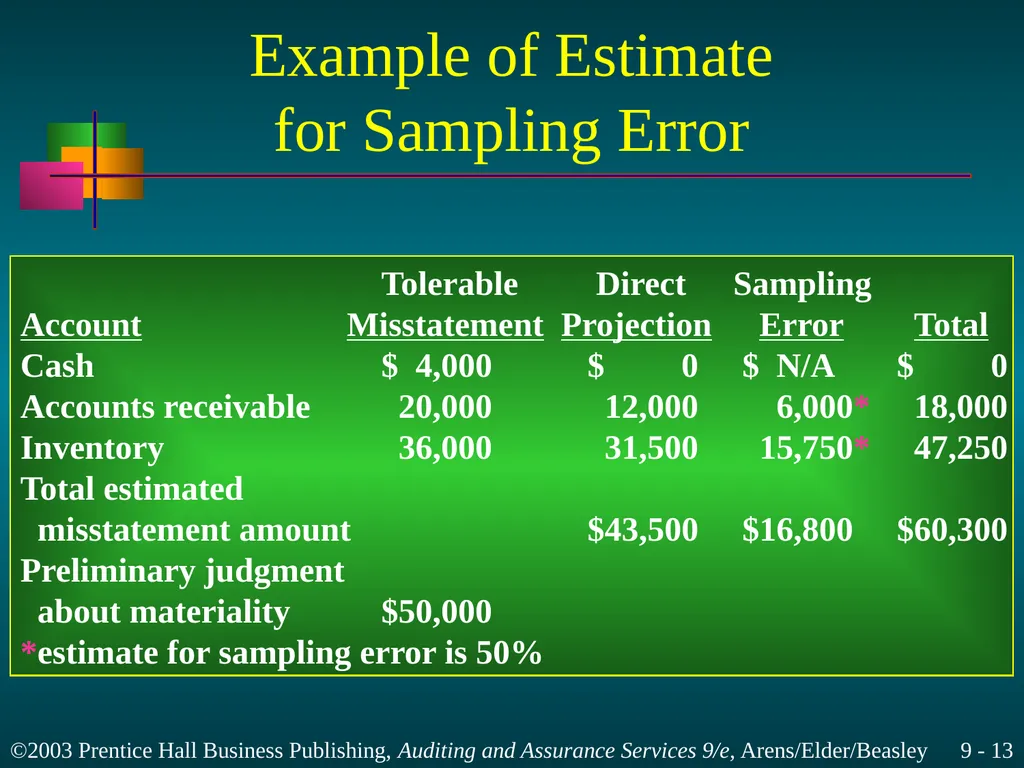
Example of Estimate
for Sampling Error Tolerable Direct Sampling
Account Misstatement Projection Error Total
Cash $ 4,000 $ 0 $ N/A $ 0
Accounts receivable 20,000 12,000 6,000* 18,000
Inventory 36,000 31,500 15,750* 47,250
Total estimated
misstatement amount $43,500 $16,800 $60,300
Preliminary judgment
about materiality $50,000
*estimate for sampling error is 50%<br>
14
Learning Objective 5 Define risk in auditing.<br>
15
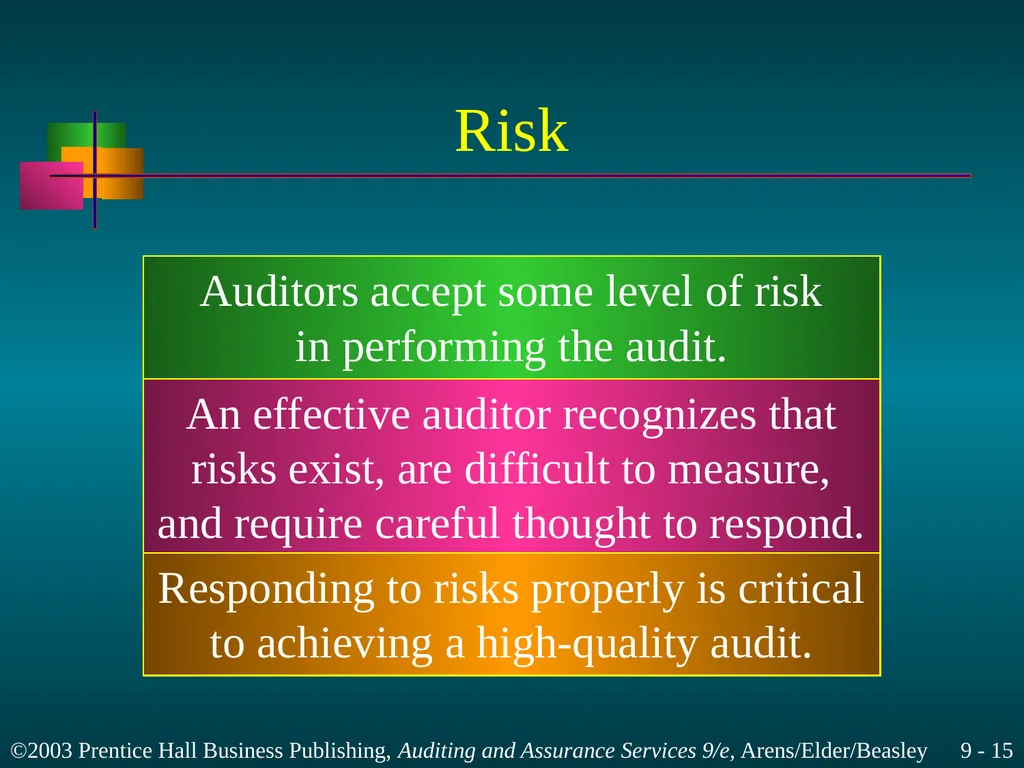
Risk Auditors accept some level of risk
in performing the audit. An effective auditor recognizes that
risks exist, are difficult to measure,
and require careful thought to respond. Responding to risks properly is critical
to achieving a high-quality audit.<br>
in performing the audit. An effective auditor recognizes that
risks exist, are difficult to measure,
and require careful thought to respond. Responding to risks properly is critical
to achieving a high-quality audit.<br>
16
Risk and Evidence Auditors gain an understanding of the
client’s business and industry and
assess client business risk. Auditors use the audit risk model to further
identify the potential for misstatements
and where they are most likely to occur.<br>
client’s business and industry and
assess client business risk. Auditors use the audit risk model to further
identify the potential for misstatements
and where they are most likely to occur.<br>
17
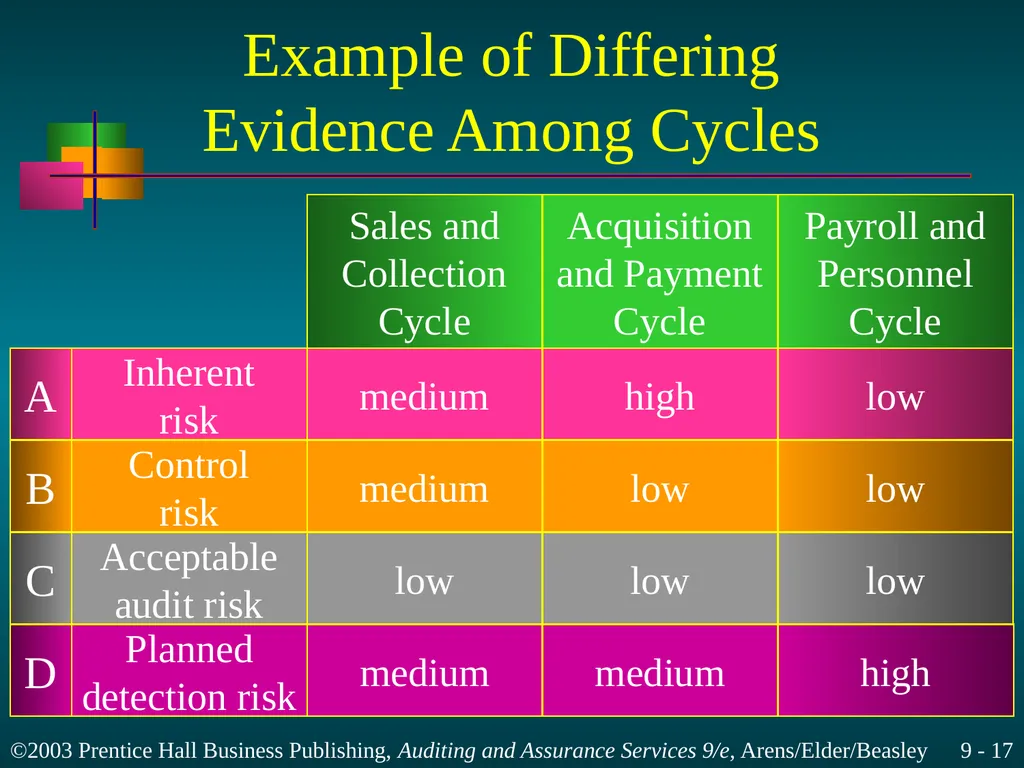
Example of Differing
Evidence Among Cycles Sales and
Collection
Cycle Acquisition
and Payment
Cycle Payroll and
Personnel
Cycle Inherent
risk Control
risk Acceptable
audit risk Planned
detection risk A B C D medium high low medium low low low low low medium medium high<br>
Collection
Cycle Acquisition
and Payment
Cycle Payroll and
Personnel
Cycle Inherent
risk Control
risk Acceptable
audit risk Planned
detection risk A B C D medium high low medium low low low low low medium medium high<br>
18
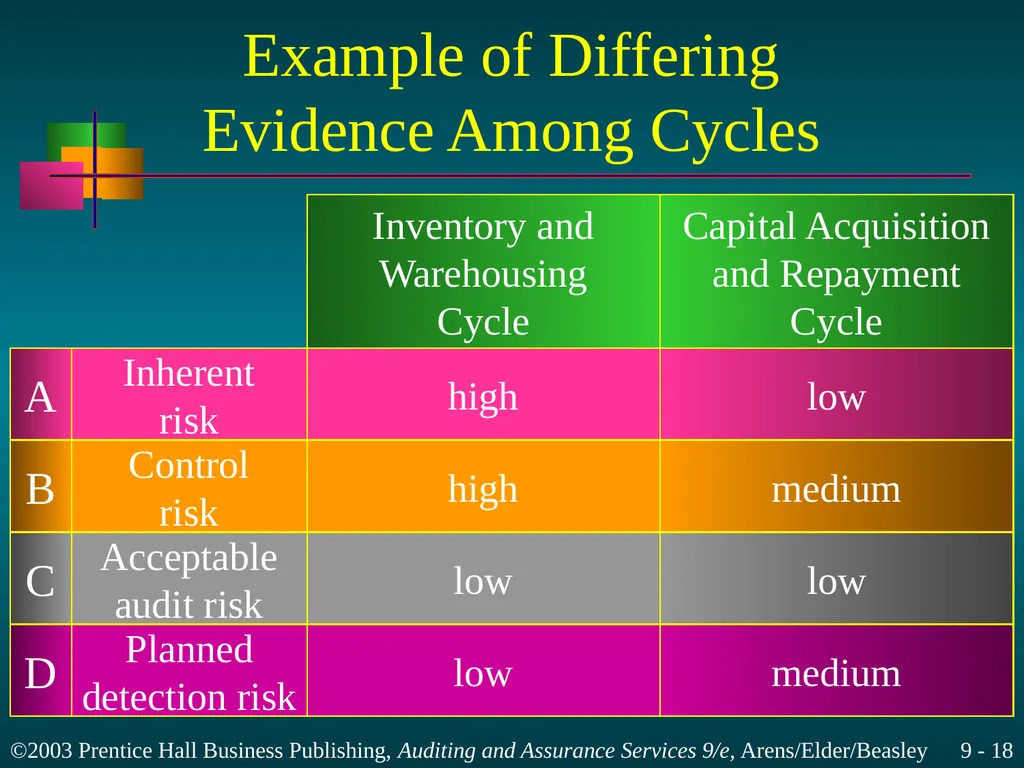
Example of Differing
Evidence Among Cycles Inventory and
Warehousing
Cycle Capital Acquisition
and Repayment
Cycle Inherent
risk Control
risk Acceptable
audit risk Planned
detection risk A B C D high low high medium low low low medium<br>
Warehousing
Cycle Capital Acquisition
and Repayment
Cycle Inherent
risk Control
risk Acceptable
audit risk Planned
detection risk A B C D high low high medium low low low medium<br>
19
Learning Objective 6 Describe the audit risk
model and its components.<br>
model and its components.<br>
20
Audit Risk Model
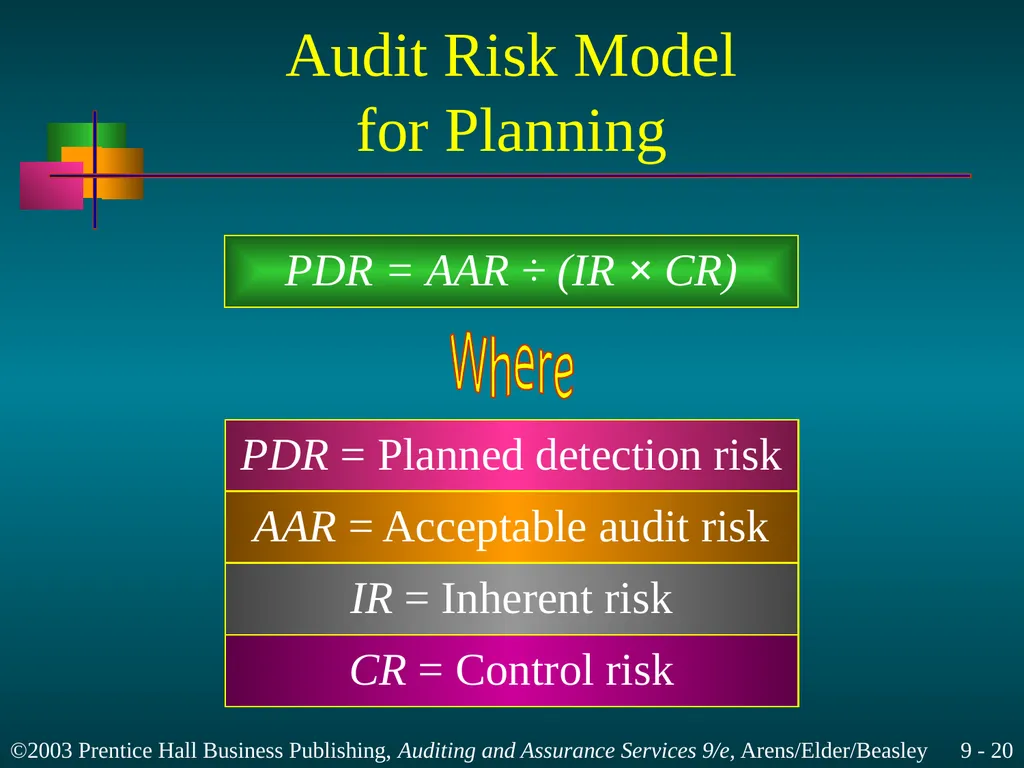
for Planning PDR = AAR ÷ (IR × CR) Where PDR = Planned detection risk AAR = Acceptable audit risk IR = Inherent risk CR = Control risk<br>
21
Learning Objective 7 Consider the impact of risk
on acceptable audit risk.<br>
on acceptable audit risk.<br>
22
Impact of Engagement Risk
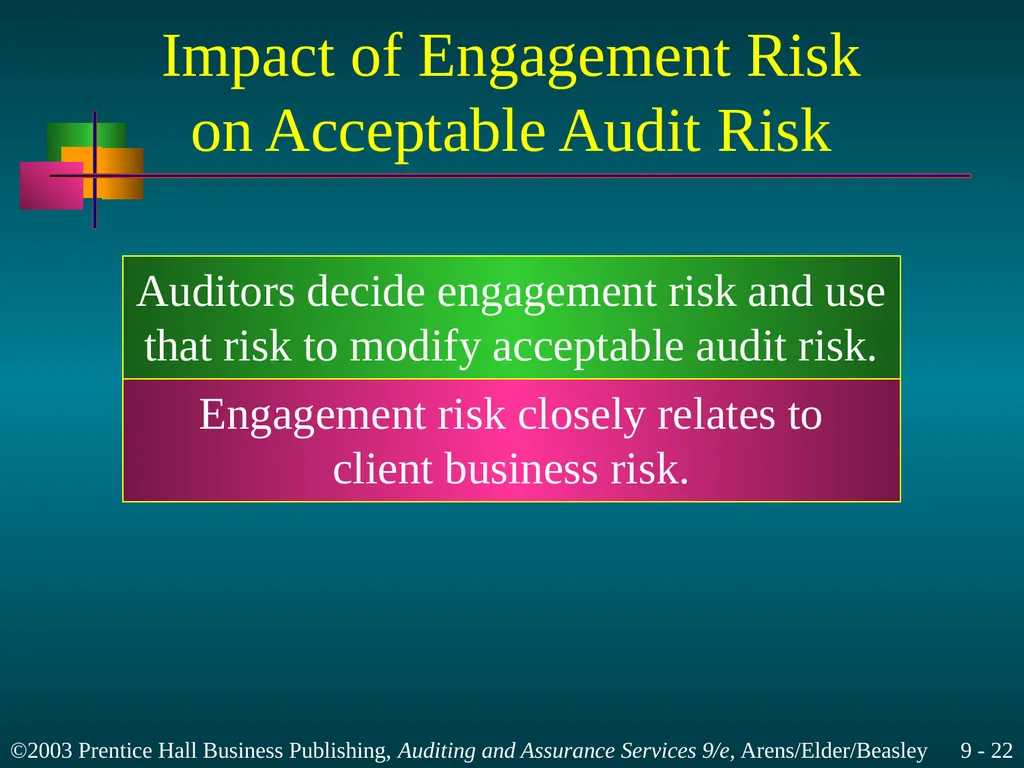
on Acceptable Audit Risk Auditors decide engagement risk and use
that risk to modify acceptable audit risk. Engagement risk closely relates to
client business risk.<br>
that risk to modify acceptable audit risk. Engagement risk closely relates to
client business risk.<br>
23
Factors Affecting
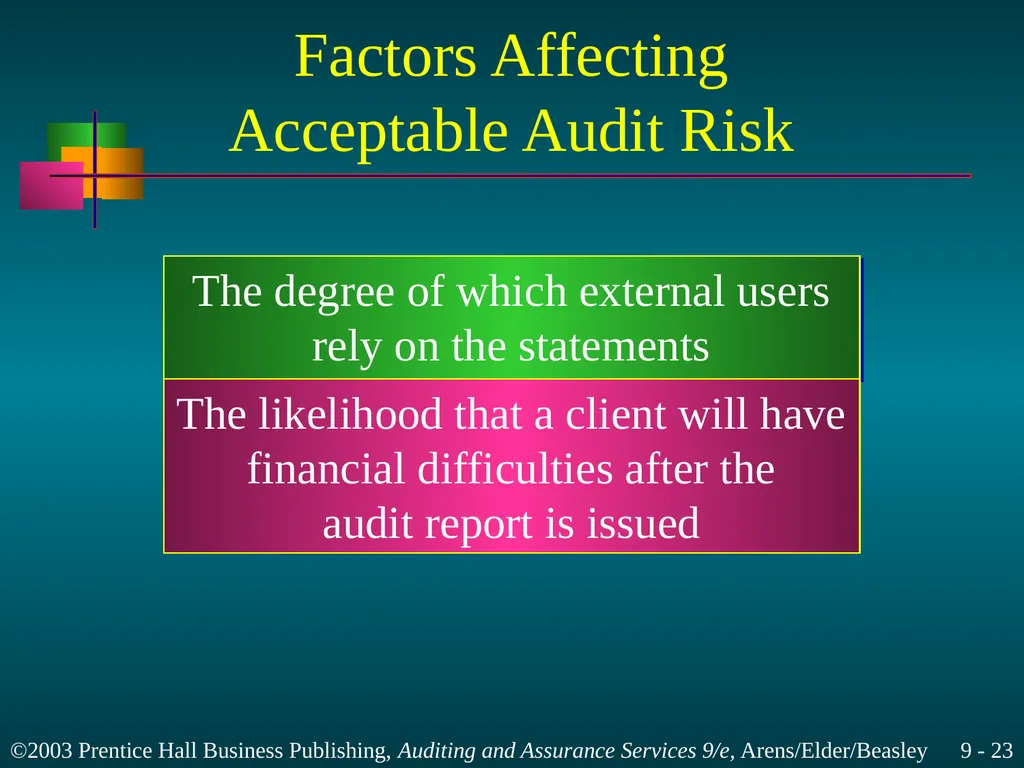
Acceptable Audit Risk The degree of which external users
rely on the statements The likelihood that a client will have
financial difficulties after the
audit report is issued<br>
rely on the statements The likelihood that a client will have
financial difficulties after the
audit report is issued<br>
24
Factors Affecting
Acceptable Audit Risk The auditor’s evaluation of
management’s integrity<br>
management’s integrity<br>
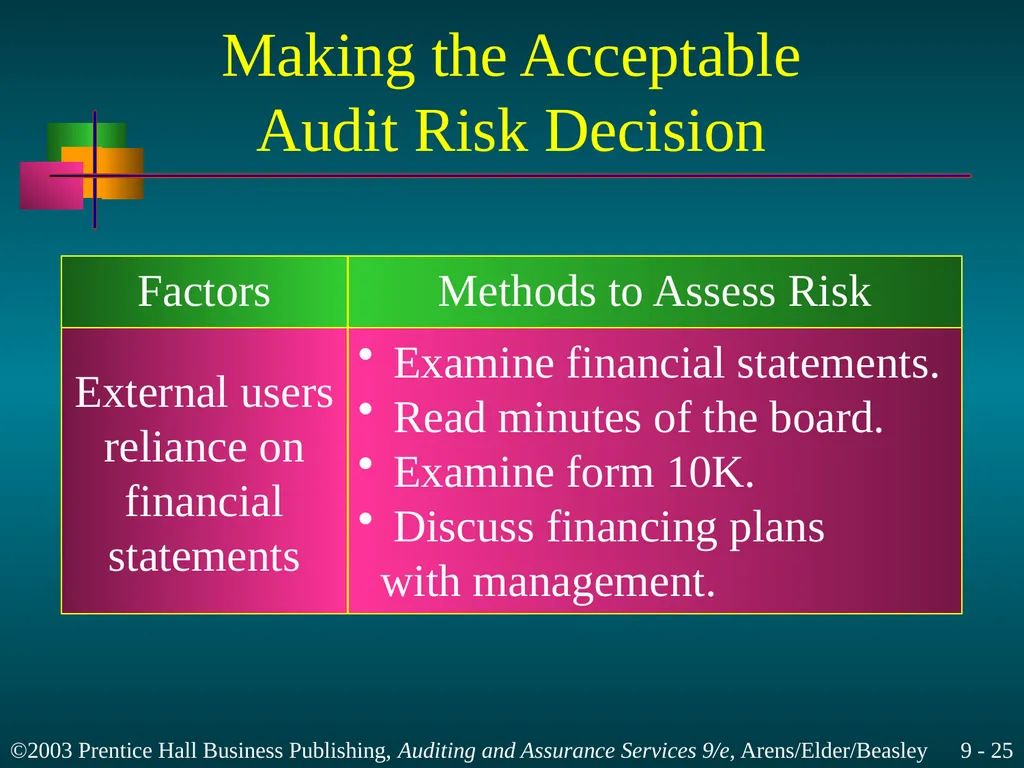
25
Making the Acceptable
Audit Risk Decision Methods to Assess Risk External users
reliance on
financial
statements Examine financial statements.
Read minutes of the board.
Examine form 10K.
Discuss financing plans
with management. Factors<br>
reliance on
financial
statements Examine financial statements.
Read minutes of the board.
Examine form 10K.
Discuss financing plans
with management. Factors<br>
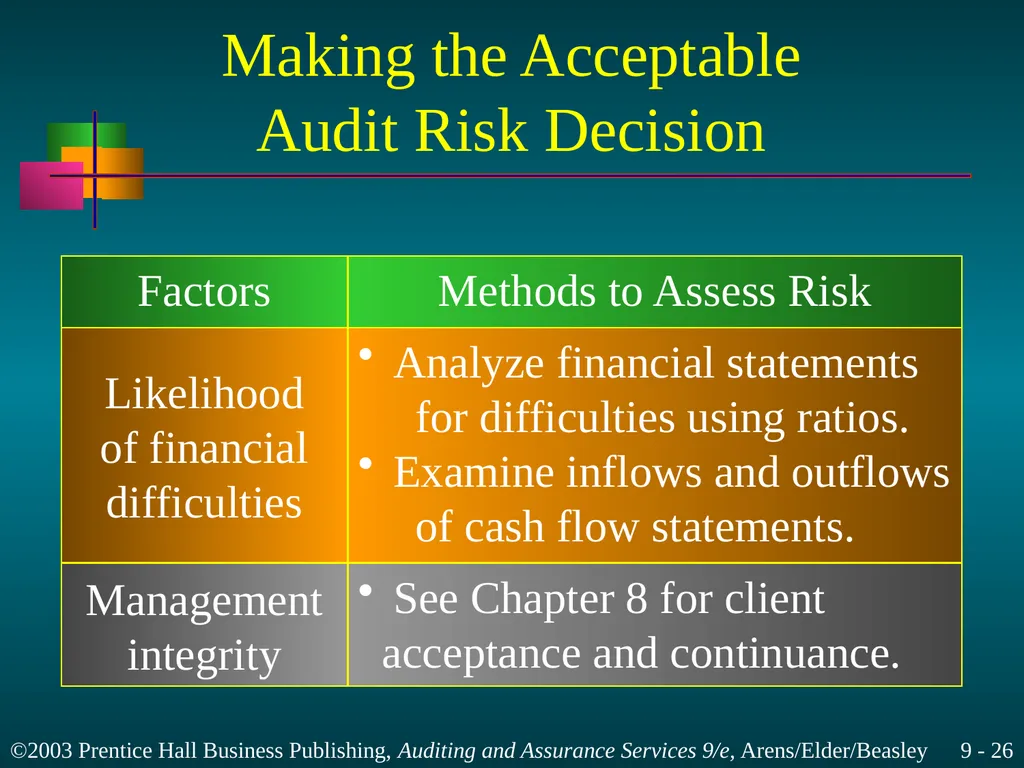
26
Making the Acceptable
Audit Risk Decision Methods to Assess Risk Likelihood
of financial
difficulties Analyze financial statements for difficulties using ratios.
Examine inflows and outflows of cash flow statements. Factors Management
integrity See Chapter 8 for client acceptance and continuance.<br>
of financial
difficulties Analyze financial statements for difficulties using ratios.
Examine inflows and outflows of cash flow statements. Factors Management
integrity See Chapter 8 for client acceptance and continuance.<br>
27
Learning Objective 8 Consider the impact of several
factors on the assessment
of inherent risk.<br>
factors on the assessment
of inherent risk.<br>
28
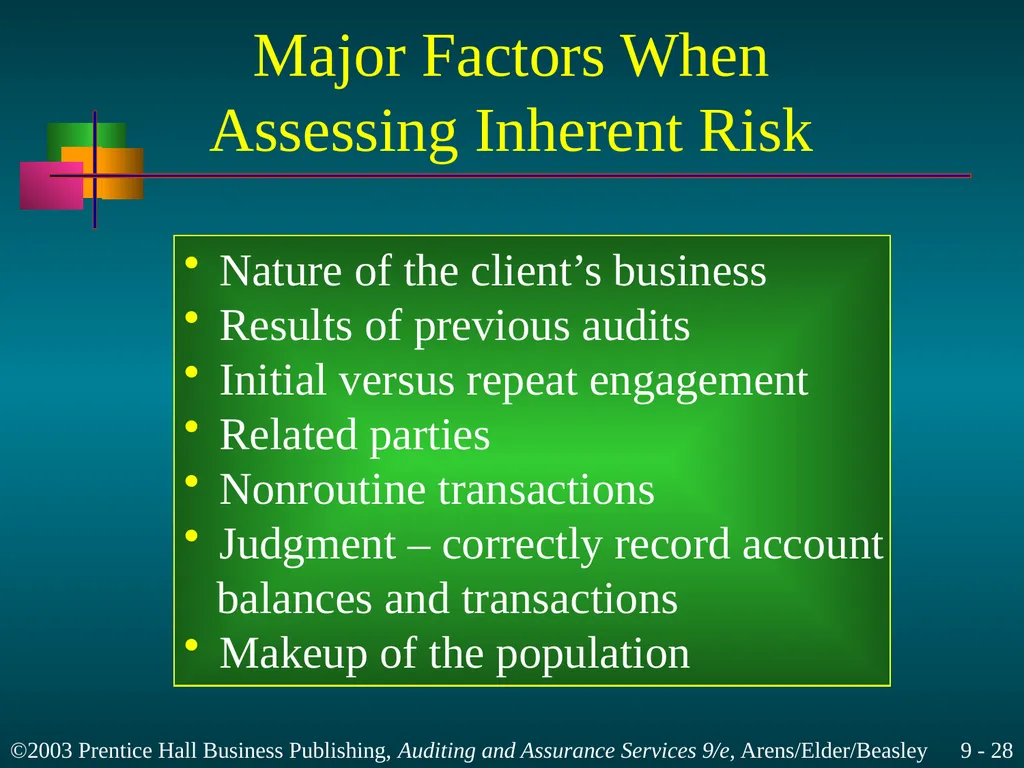
Major Factors When
Assessing Inherent Risk Nature of the client’s business
Results of previous audits
Initial versus repeat engagement
Related parties
Nonroutine transactions
Judgment – correctly record account
balances and transactions
Makeup of the population<br>
Results of previous audits
Initial versus repeat engagement
Related parties
Nonroutine transactions
Judgment – correctly record account
balances and transactions
Makeup of the population<br>
29
Learning Objective 9 Consider information
gathered to assess the
likelihood of fraud.<br>
gathered to assess the
likelihood of fraud.<br>
30
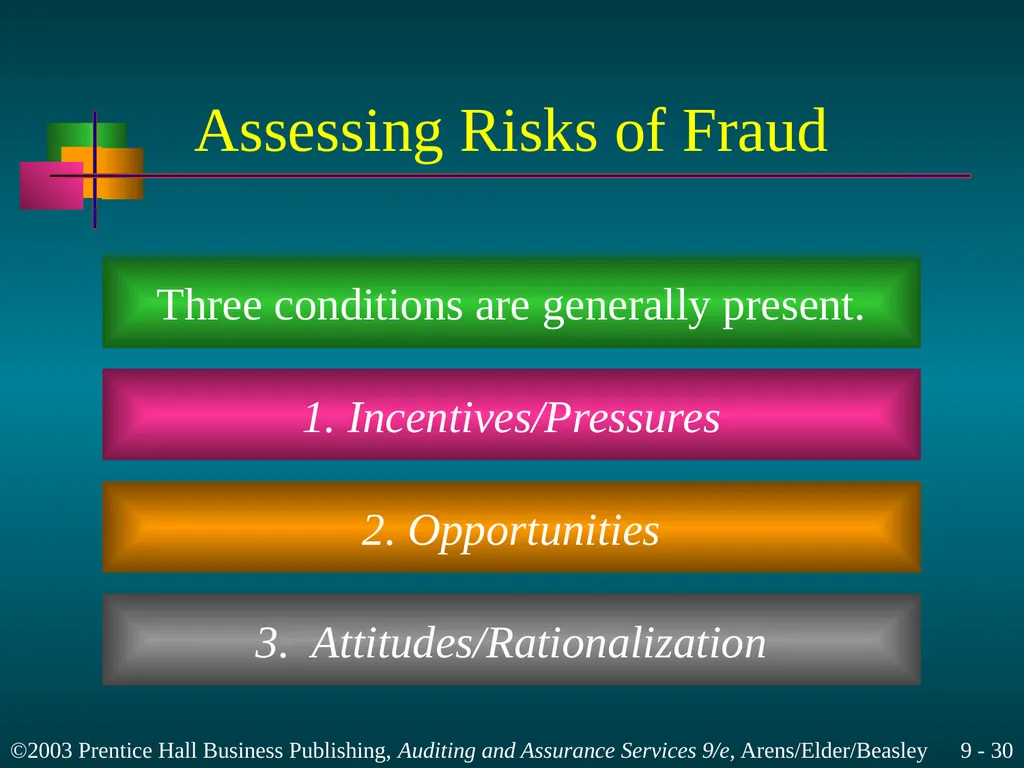
Assessing Risks of Fraud Three conditions are generally present. 1. Incentives/Pressures 2. Opportunities 3. Attitudes/Rationalization<br>
31
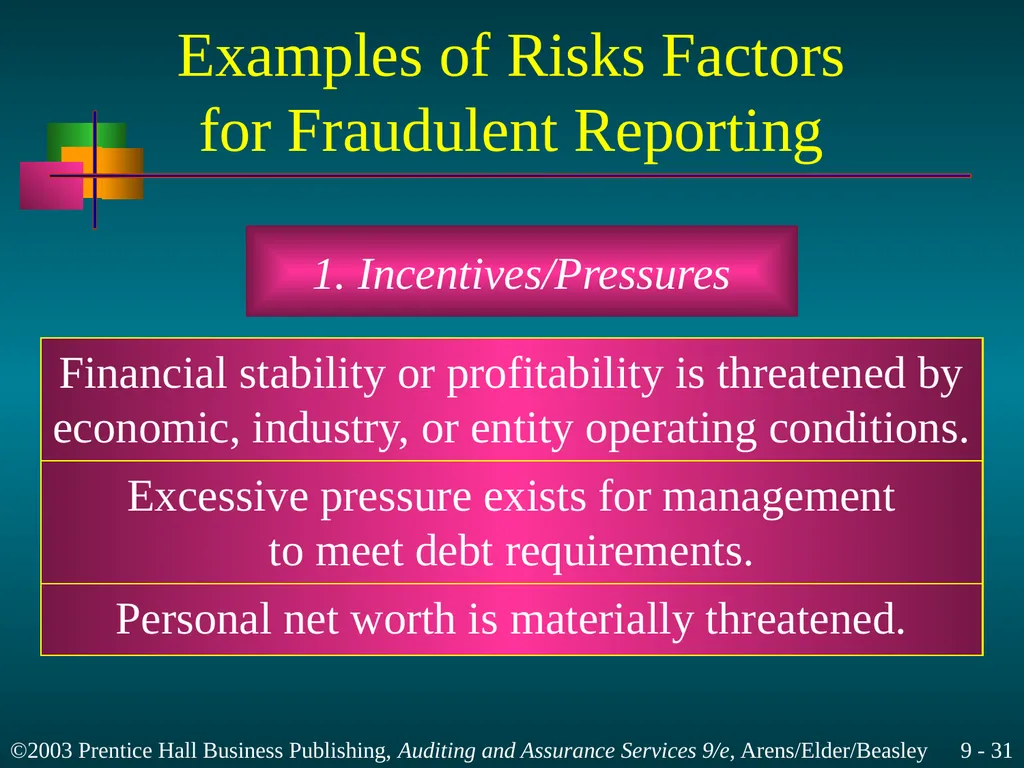
Examples of Risks Factors
for Fraudulent Reporting 1. Incentives/Pressures Financial stability or profitability is threatened by
economic, industry, or entity operating conditions. Excessive pressure exists for management
to meet debt requirements. Personal net worth is materially threatened.<br>
economic, industry, or entity operating conditions. Excessive pressure exists for management
to meet debt requirements. Personal net worth is materially threatened.<br>
32
Examples of Risks Factors
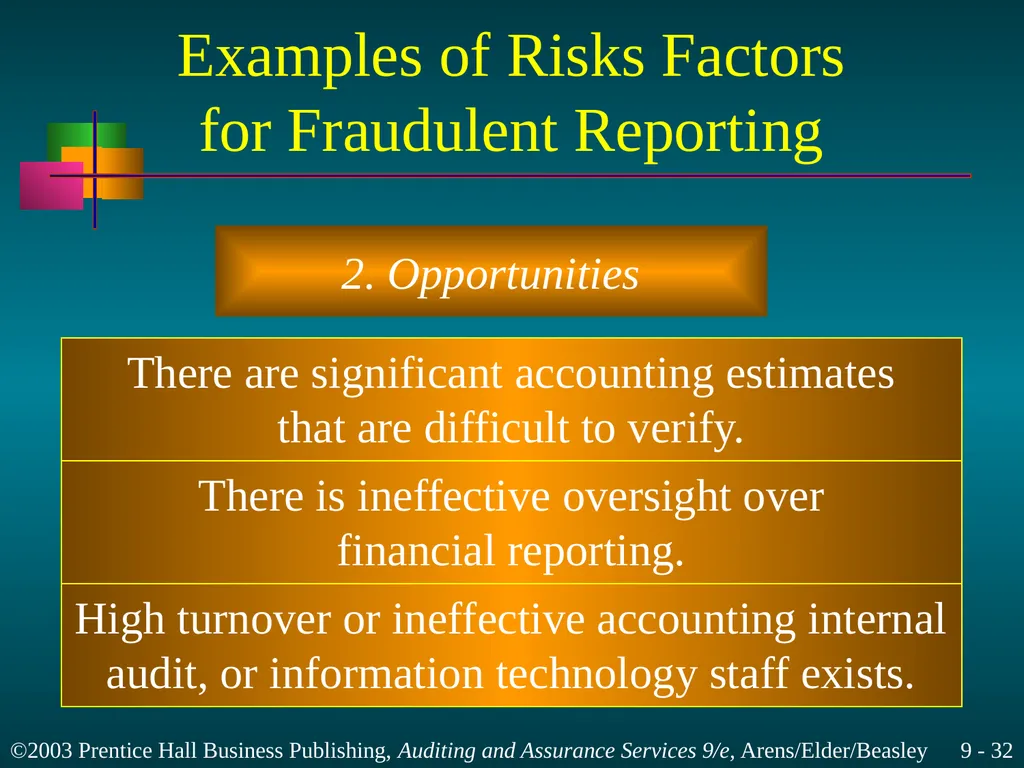
for Fraudulent Reporting 2. Opportunities There are significant accounting estimates
that are difficult to verify. There is ineffective oversight over
financial reporting. High turnover or ineffective accounting internal
audit, or information technology staff exists.<br>
that are difficult to verify. There is ineffective oversight over
financial reporting. High turnover or ineffective accounting internal
audit, or information technology staff exists.<br>
33
Examples of Risks Factors
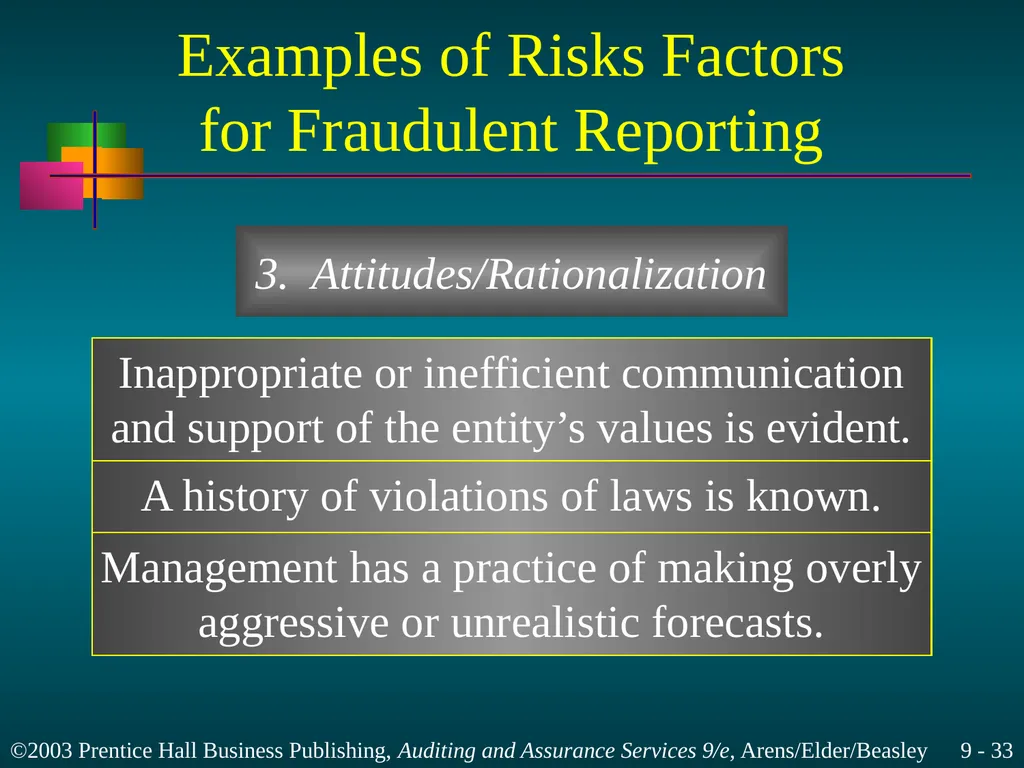
for Fraudulent Reporting 3. Attitudes/Rationalization Inappropriate or inefficient communication
and support of the entity’s values is evident. A history of violations of laws is known. Management has a practice of making overly
aggressive or unrealistic forecasts.<br>
and support of the entity’s values is evident. A history of violations of laws is known. Management has a practice of making overly
aggressive or unrealistic forecasts.<br>
34
Responding to the
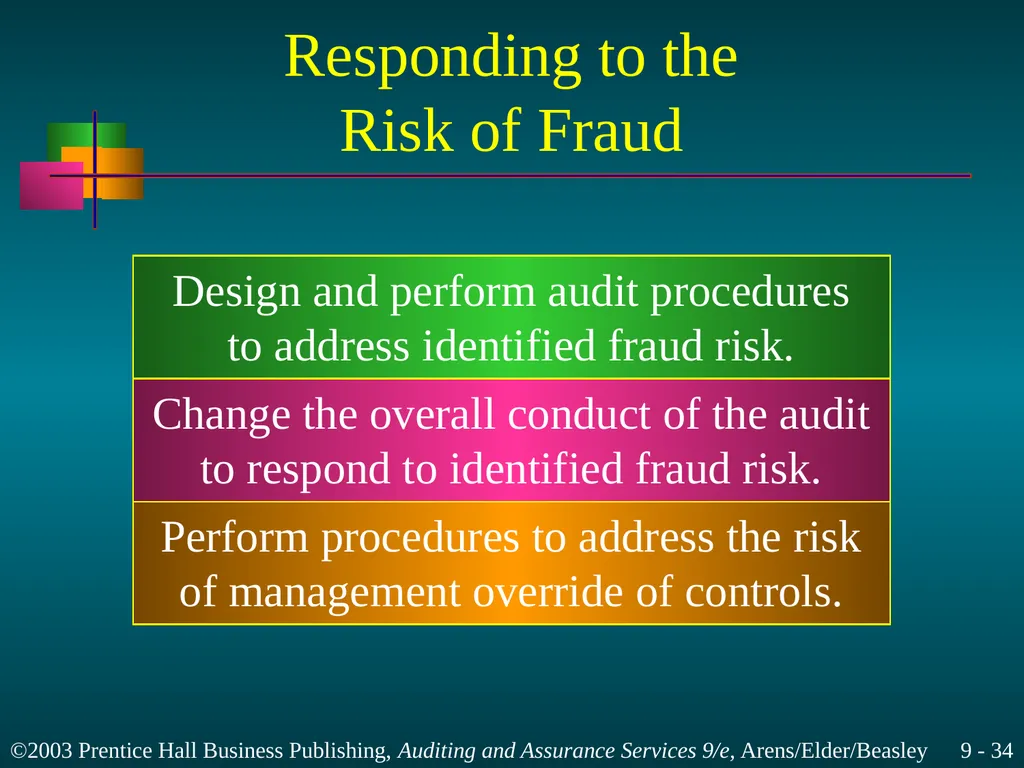
Risk of Fraud Design and perform audit procedures
to address identified fraud risk. Change the overall conduct of the audit
to respond to identified fraud risk. Perform procedures to address the risk
of management override of controls.<br>
to address identified fraud risk. Change the overall conduct of the audit
to respond to identified fraud risk. Perform procedures to address the risk
of management override of controls.<br>
35
Learning Objective 10 Discuss the relationship
of risks to audit evidence.<br>
of risks to audit evidence.<br>
36
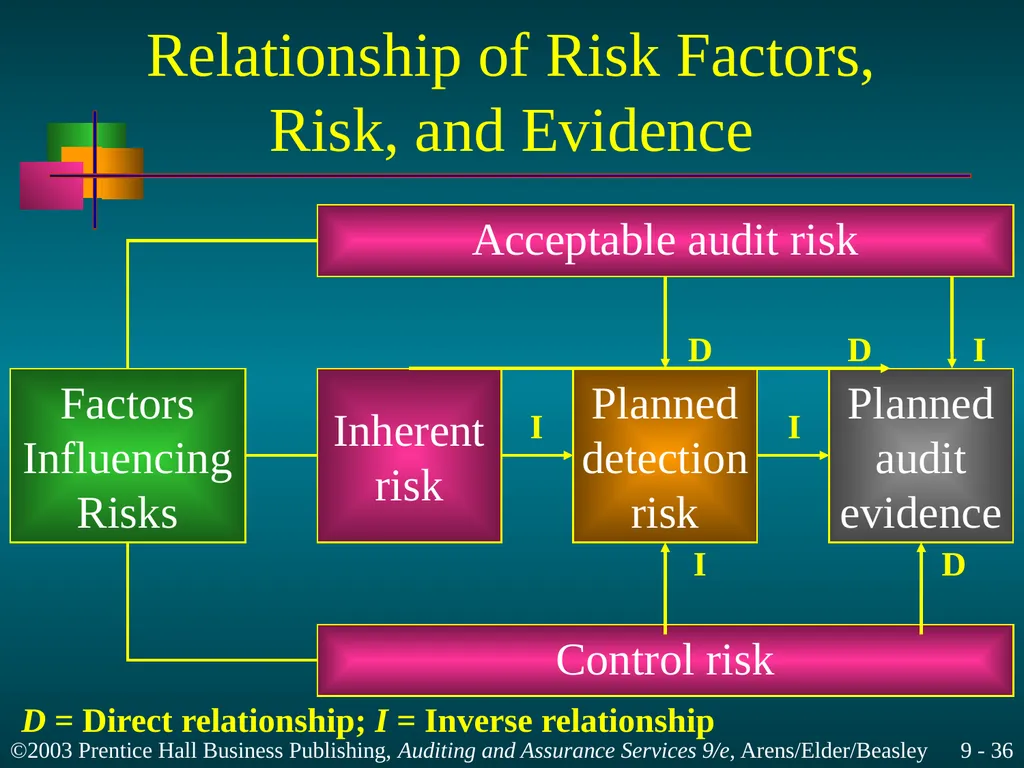
Relationship of Risk Factors,
Risk, and Evidence Factors
Influencing
Risks Acceptable audit risk Planned
detection
risk Planned
audit
evidence Inherent
risk Control risk I D I I D I D D = Direct relationship; I = Inverse relationship<br>
Influencing
Risks Acceptable audit risk Planned
detection
risk Planned
audit
evidence Inherent
risk Control risk I D I I D I D D = Direct relationship; I = Inverse relationship<br>
37
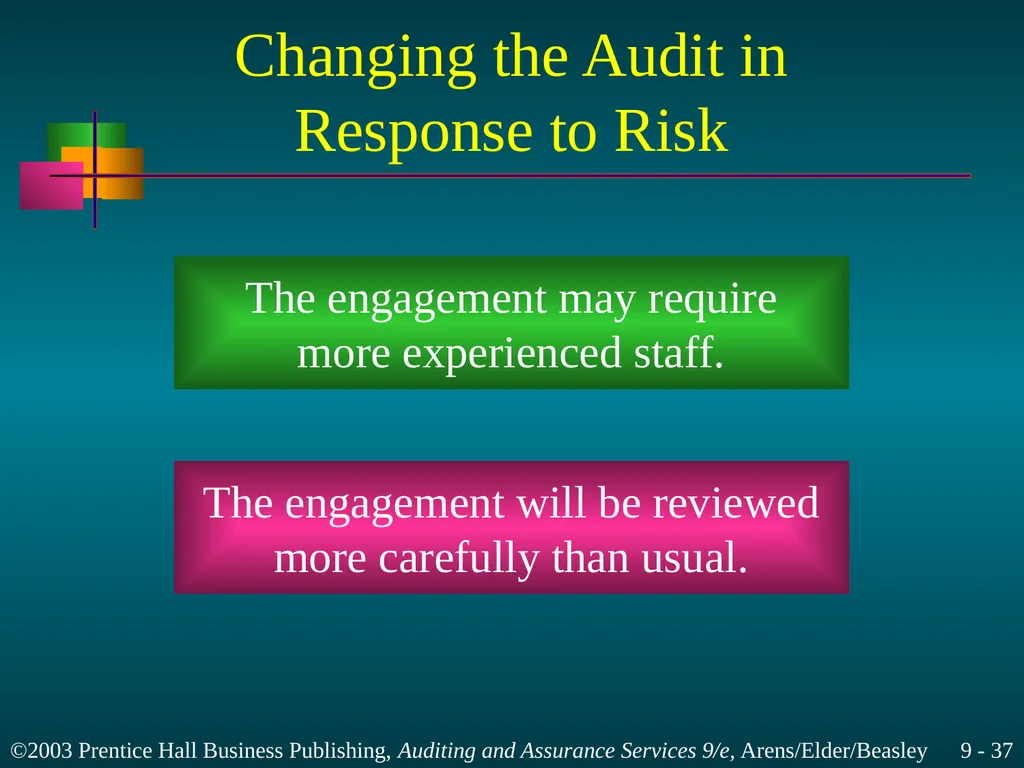
Changing the Audit in Response to Risk The engagement may require
more experienced staff. The engagement will be reviewed
more carefully than usual.<br>
more experienced staff. The engagement will be reviewed
more carefully than usual.<br>
38
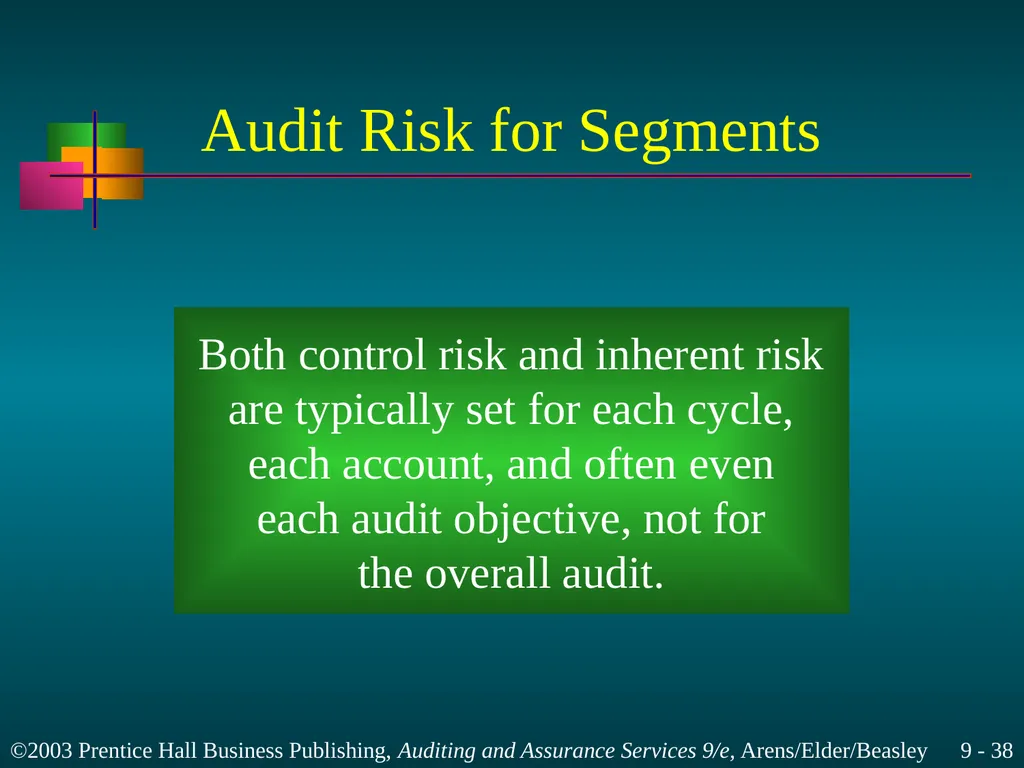
Audit Risk for Segments Both control risk and inherent risk
are typically set for each cycle,
each account, and often even
each audit objective, not for
the overall audit.<br>
are typically set for each cycle,
each account, and often even
each audit objective, not for
the overall audit.<br>
39
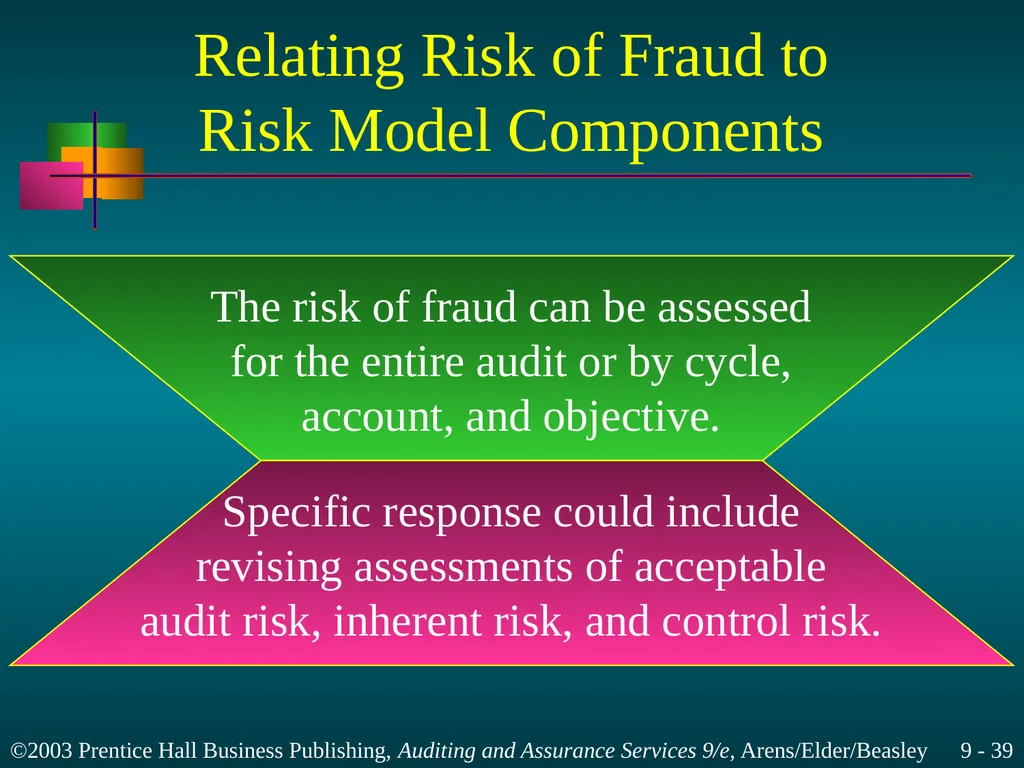
Relating Risk of Fraud to
Risk Model Components The risk of fraud can be assessed
for the entire audit or by cycle,
account, and objective. Specific response could include
revising assessments of acceptable
audit risk, inherent risk, and control risk.<br>
for the entire audit or by cycle,
account, and objective. Specific response could include
revising assessments of acceptable
audit risk, inherent risk, and control risk.<br>
40
Tolerable Misstatement, Risks,
and Balance-related Objectives It is common to assess inherent and control
risk for each balance-related audit objective. It is not common to allocate
materiality to objectives.<br>
risk for each balance-related audit objective. It is not common to allocate
materiality to objectives.<br>
41
Measurement Limitations One major limitation in the application
of the audit risk model is the difficulty
of measuring the components of the model.<br>
of the audit risk model is the difficulty
of measuring the components of the model.<br>
42
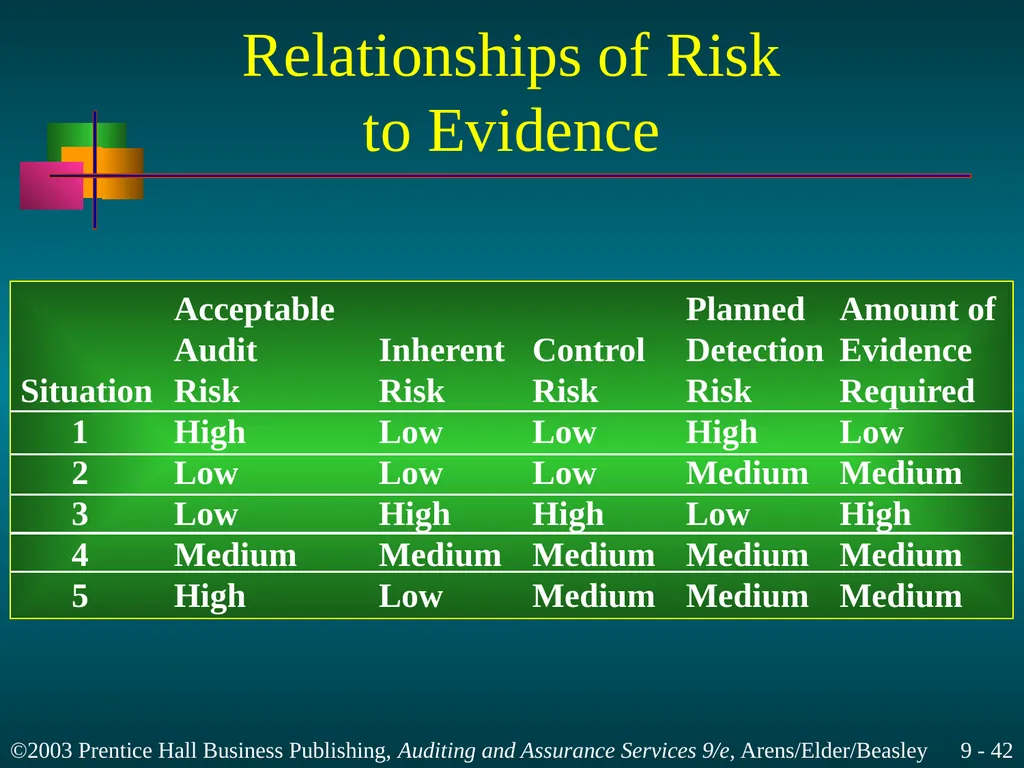
Relationships of Risk
to Evidence Acceptable Planned Amount of
Audit Inherent Control Detection Evidence
Situation Risk Risk Risk Risk Required
1 High Low Low High Low
2 Low Low Low Medium Medium
3 Low High High Low High
4 Medium Medium Medium Medium Medium
5 High Low Medium Medium Medium<br>
Audit Inherent Control Detection Evidence
Situation Risk Risk Risk Risk Required
1 High Low Low High Low
2 Low Low Low Medium Medium
3 Low High High Low High
4 Medium Medium Medium Medium Medium
5 High Low Medium Medium Medium<br>
43
Tests of Details of Balances Evidence Planning Worksheet Auditors develop various types of worksheets to
aid in relating the considerations affecting audit
evidence to the appropriate evidence to accumulate.<br>
aid in relating the considerations affecting audit
evidence to the appropriate evidence to accumulate.<br>
44
Learning Objective 11 Discuss how materiality and risk
are related and integrated into
the audit process.<br>
are related and integrated into
the audit process.<br>
45
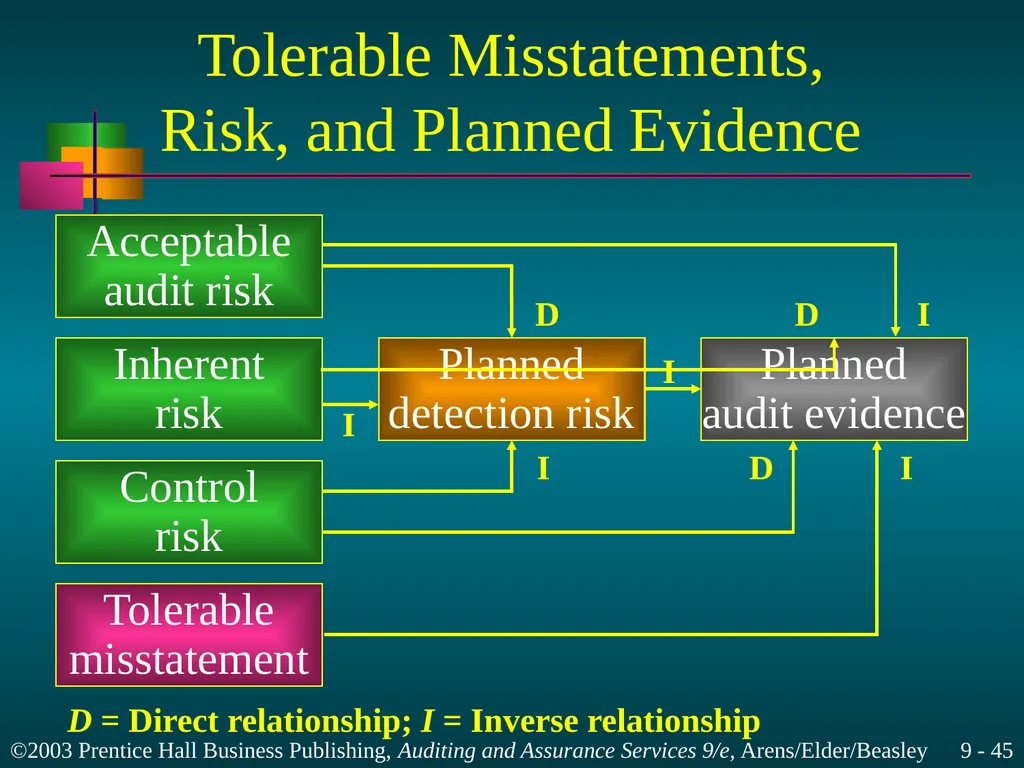
Tolerable Misstatements,
Risk, and Planned Evidence Acceptable
audit risk Inherent
risk Control
risk Tolerable
misstatement Planned
detection risk Planned
audit evidence D = Direct relationship; I = Inverse relationship I D I I I I D D<br>
audit risk Inherent
risk Control
risk Tolerable
misstatement Planned
detection risk Planned
audit evidence D = Direct relationship; I = Inverse relationship I D I I I I D D<br>
46
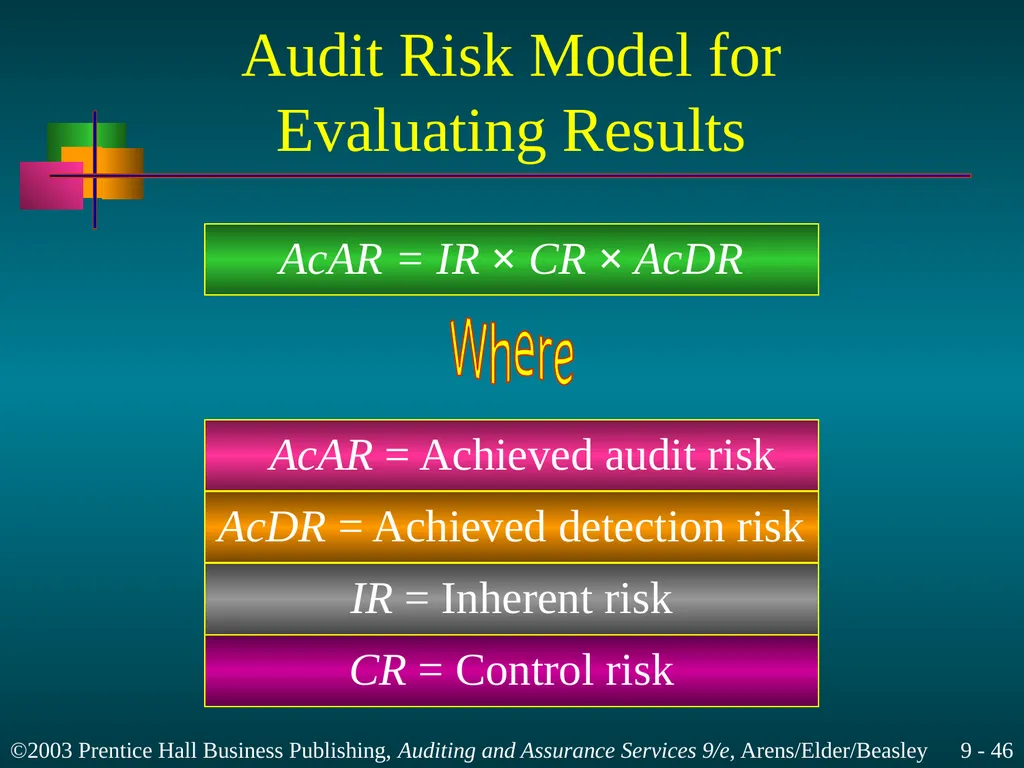
Audit Risk Model for Evaluating Results AcAR = IR × CR × AcDR Where AcAR = Achieved audit risk AcDR = Achieved detection risk IR = Inherent risk CR = Control risk<br>
47
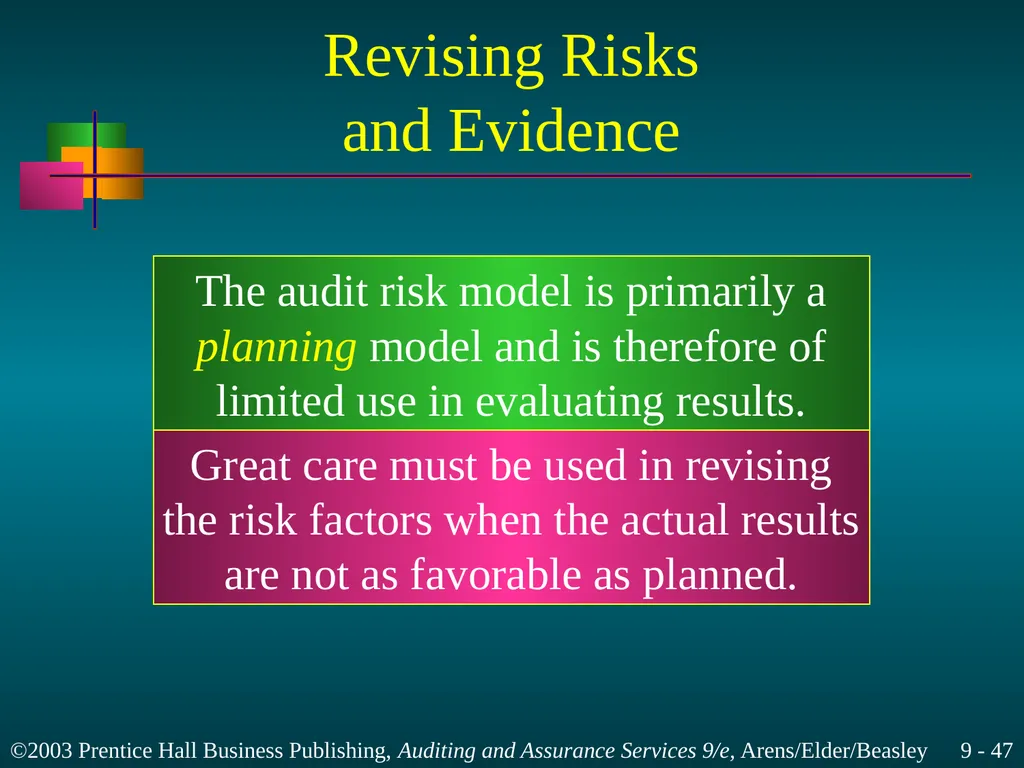
Revising Risks
and Evidence The audit risk model is primarily a
planning model and is therefore of
limited use in evaluating results. Great care must be used in revising
the risk factors when the actual results
are not as favorable as planned.<br>
planning model and is therefore of
limited use in evaluating results. Great care must be used in revising
the risk factors when the actual results
are not as favorable as planned.<br>
48
End of Chapter 9<br>