
Mining & Minerals in UP Presentation By State Tax
PM
Published · 27 slides · 0 views

1 / 1

Description
Mining Minerals in UP Presentation By State Tax Department, UP Jhansi Presentation Plan Introduction Minerals Revenue Receipts Mining-Royalty-Services GST on Royalty GST on Royalty- Dispute Analytics of Royalty GST Data Base of Mine
Related Topics
Share
Embed code
Download this presentation From Below
"Mining & Minerals in UP Presentation By State Tax" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
Mining & Minerals in UP Presentation By State Tax Department, UP
Jhansi<br>
Jhansi<br>
02
Presentation Plan Introduction
Minerals
Revenue Receipts
Mining-Royalty-Services
GST on Royalty
GST on Royalty- Dispute
Analytics of Royalty & GST Data Base of Mine Lease Holders
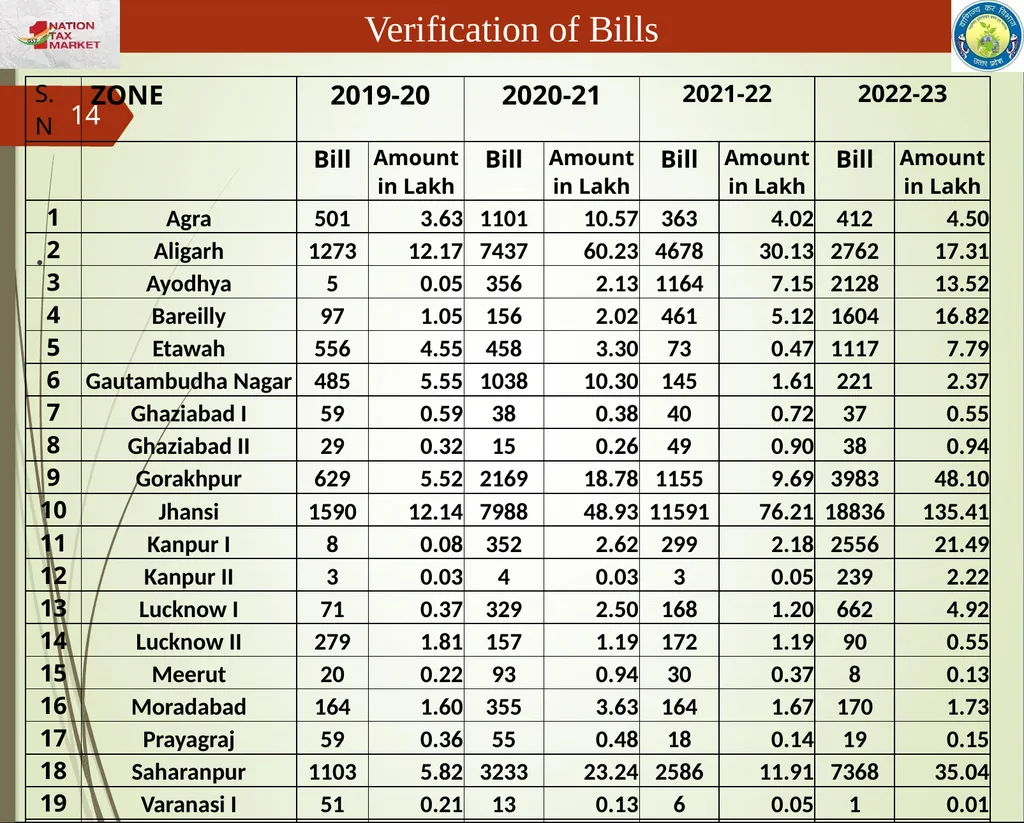
Verification of Bills
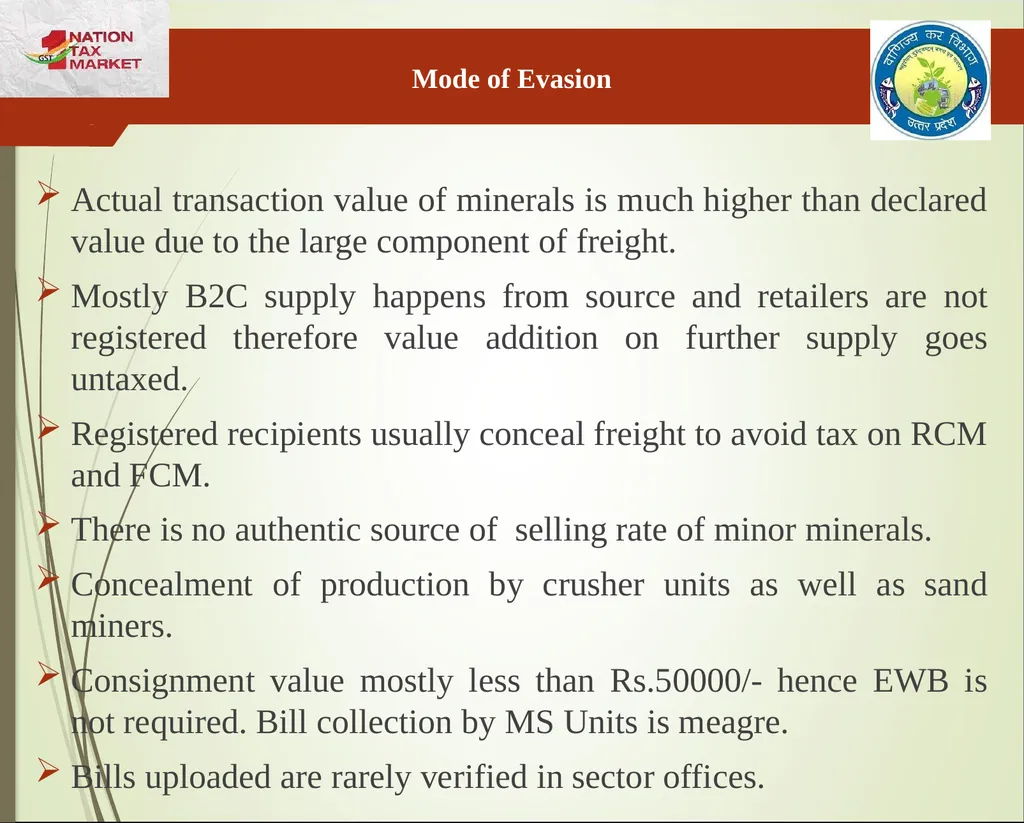
Mode of Evasion
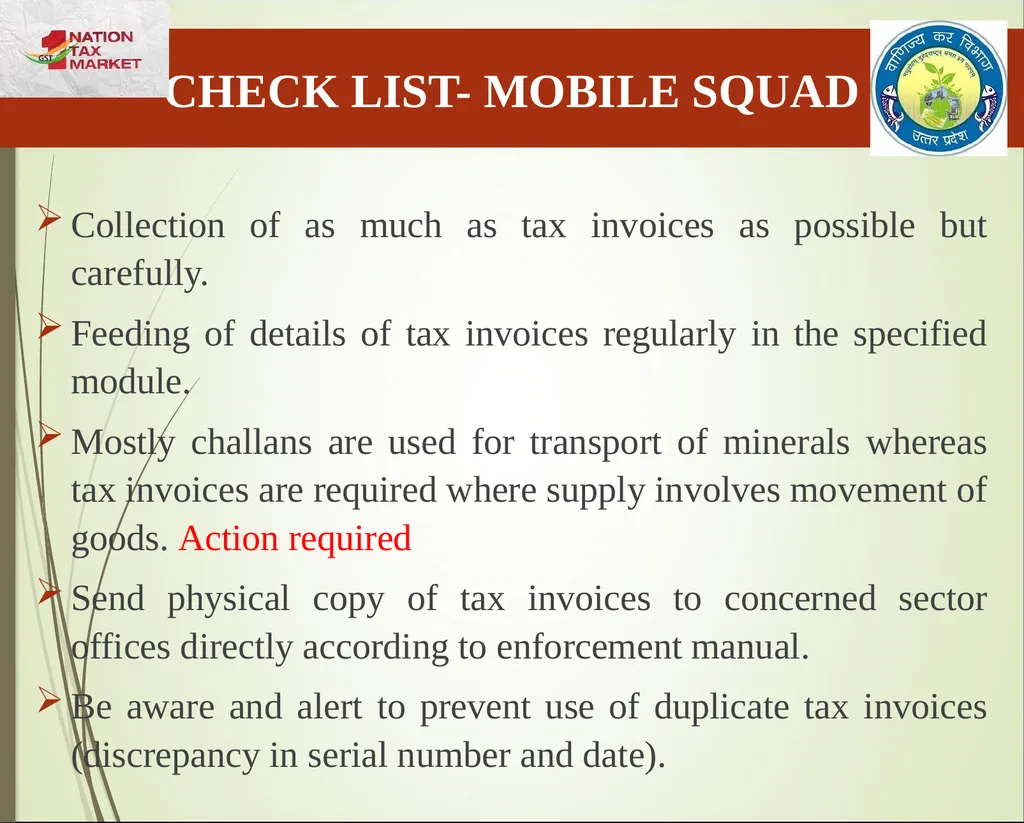
Checklist- Mobile Squad
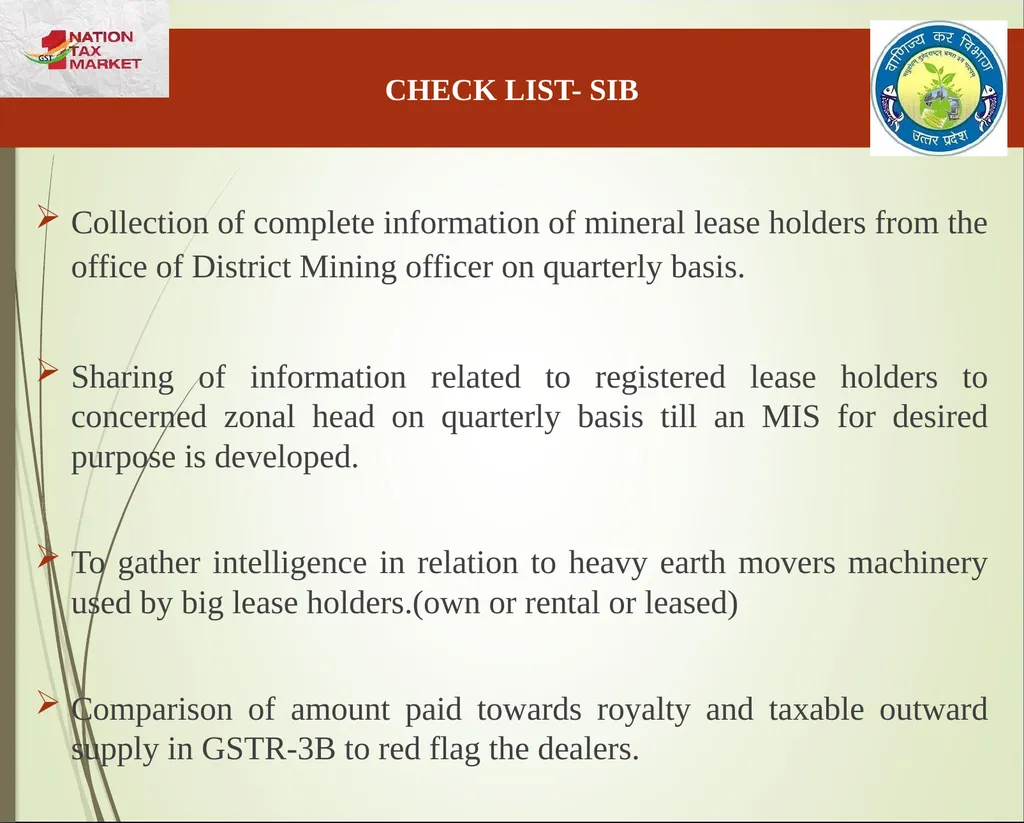
Checklist- SIB
Checklist- Adjudication
Steps to be taken 2<br>
Minerals
Revenue Receipts
Mining-Royalty-Services
GST on Royalty
GST on Royalty- Dispute
Analytics of Royalty & GST Data Base of Mine Lease Holders
Verification of Bills
Mode of Evasion
Checklist- Mobile Squad
Checklist- SIB
Checklist- Adjudication
Steps to be taken 2<br>
03
Introduction Parliament has enacted Mines & Minerals (Development & Regulation) Act,1957 to achieve sustainable development. [Article 246-Schedule VII-List I-Entry No 54]
State Government regulates minerals under Entry No 23, 49 and 50 of List II of VII Schedule.
Principal Secretary, Geology & mining is administrative head of mining Department ,UP.
Director, Geology & mining is the H.O.D.
District Mining officer is responsible for determining royalty, dead rent and permit fee.
ADM(F&R) is in-charge of collection and accounting of minerals receipts under the overall control of District Collector. 3<br>
04
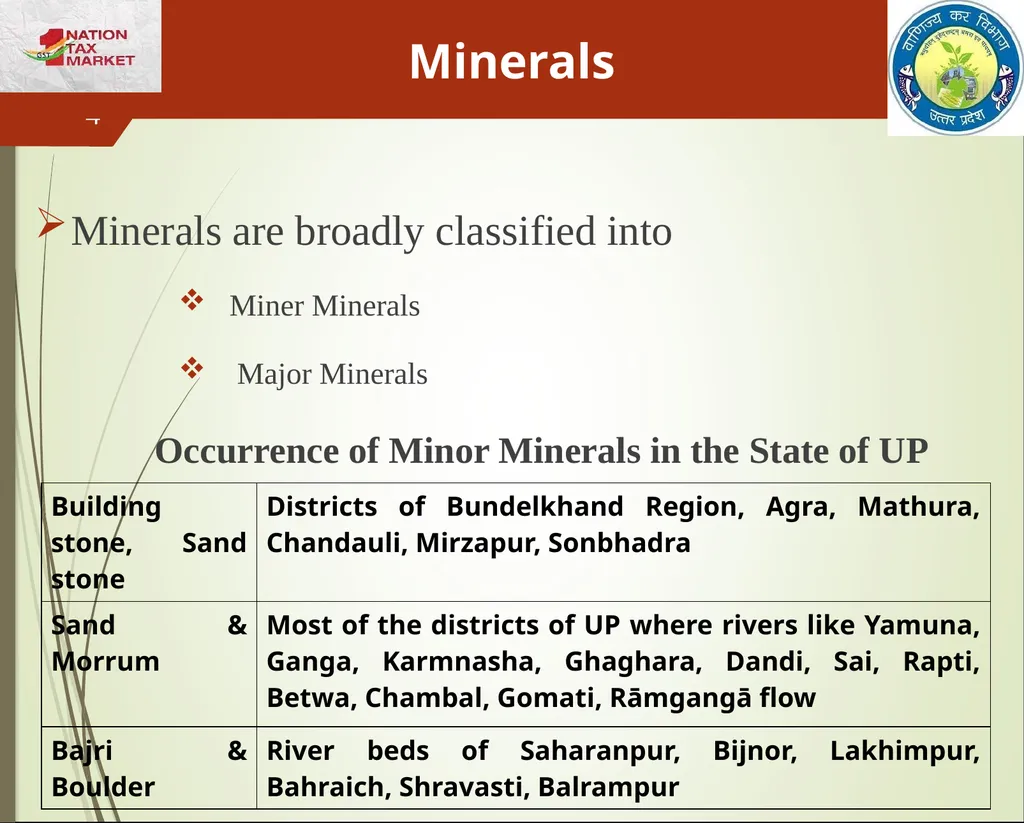
Minerals Minerals are broadly classified into
Miner Minerals
Major Minerals
Occurrence of Minor Minerals in the State of UP 4<br>
Miner Minerals
Major Minerals
Occurrence of Minor Minerals in the State of UP 4<br>
05
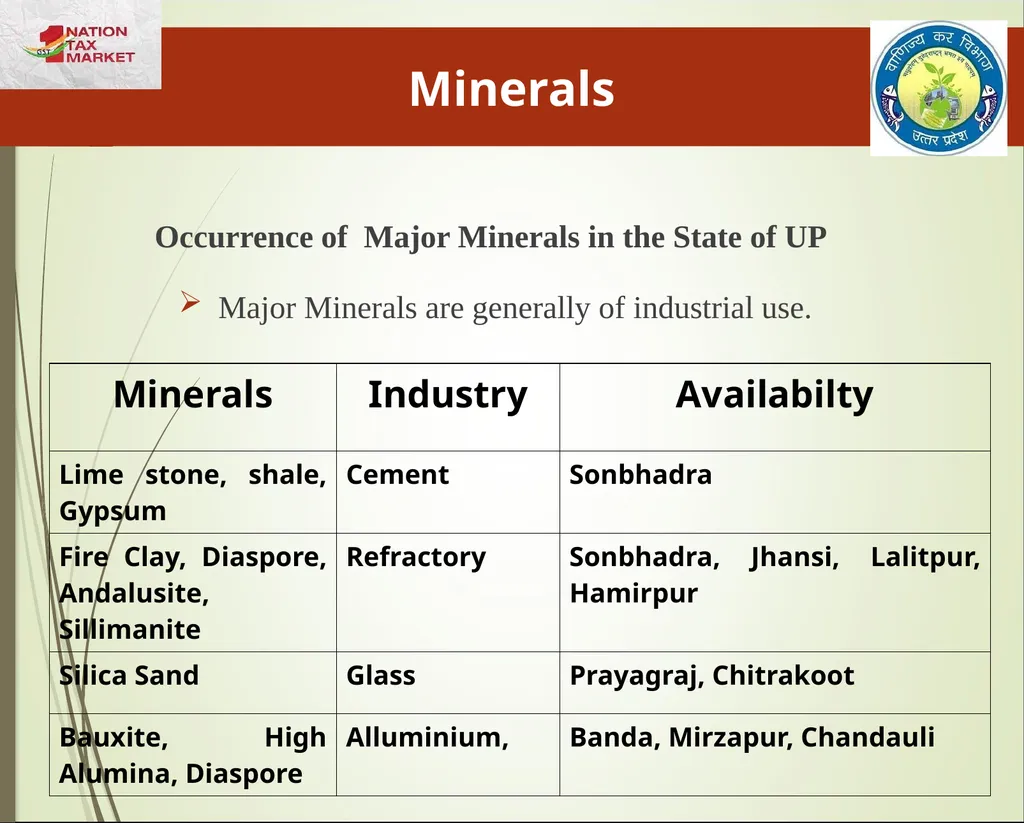
Minerals Occurrence of Major Minerals in the State of UP
Major Minerals are generally of industrial use. 5<br>
Major Minerals are generally of industrial use. 5<br>
06
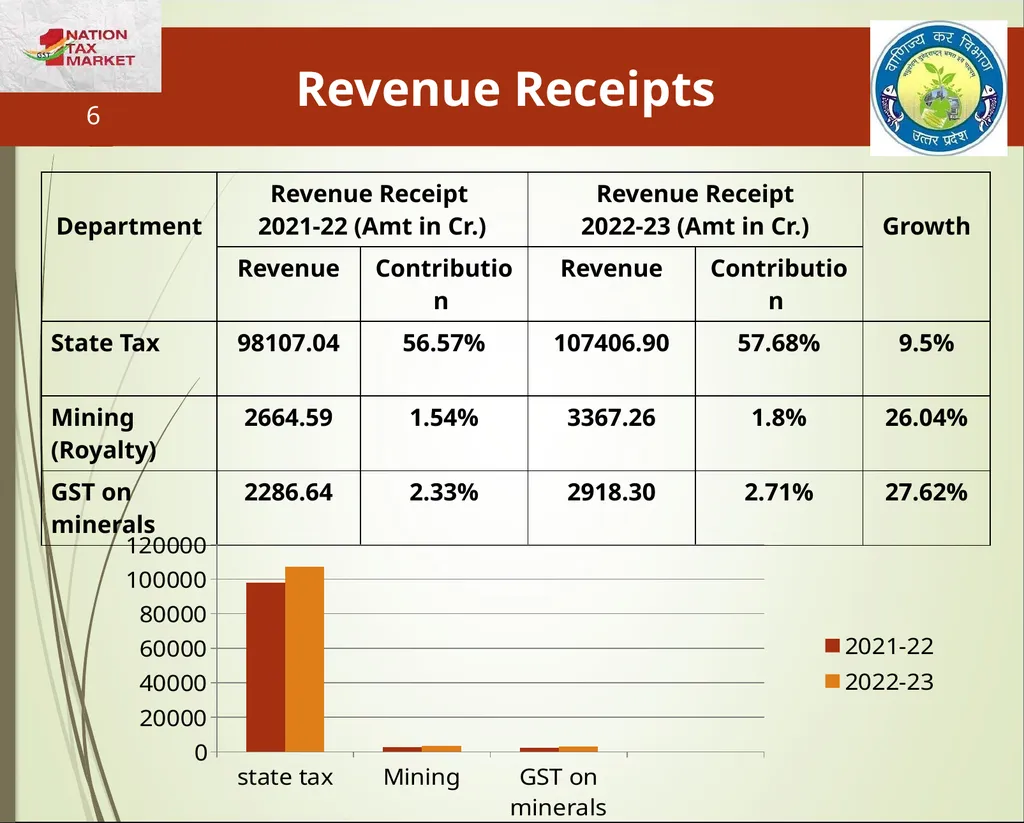
Revenue Receipts 6<br>
07
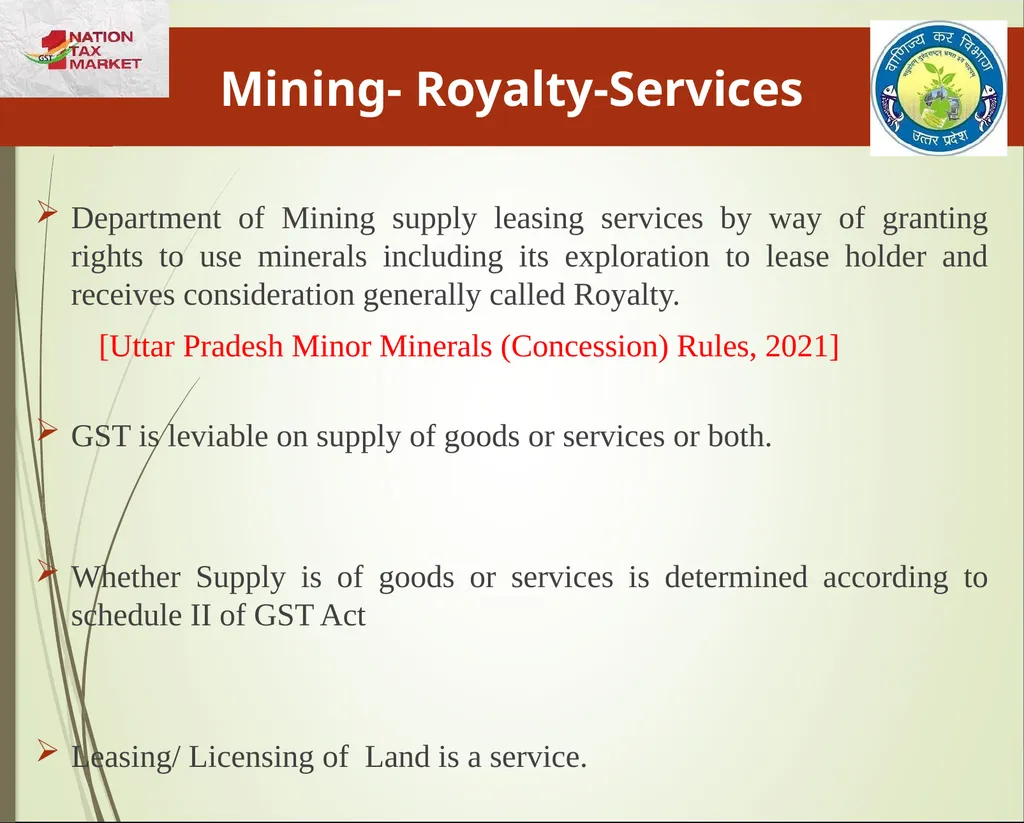
Mining- Royalty-Services Department of Mining supply leasing services by way of granting rights to use minerals including its exploration to lease holder and receives consideration generally called Royalty.
[Uttar Pradesh Minor Minerals (Concession) Rules, 2021]
GST is leviable on supply of goods or services or both.
Whether Supply is of goods or services is determined according to schedule II of GST Act
Leasing/ Licensing of Land is a service. 7<br>
[Uttar Pradesh Minor Minerals (Concession) Rules, 2021]
GST is leviable on supply of goods or services or both.
Whether Supply is of goods or services is determined according to schedule II of GST Act
Leasing/ Licensing of Land is a service. 7<br>
08
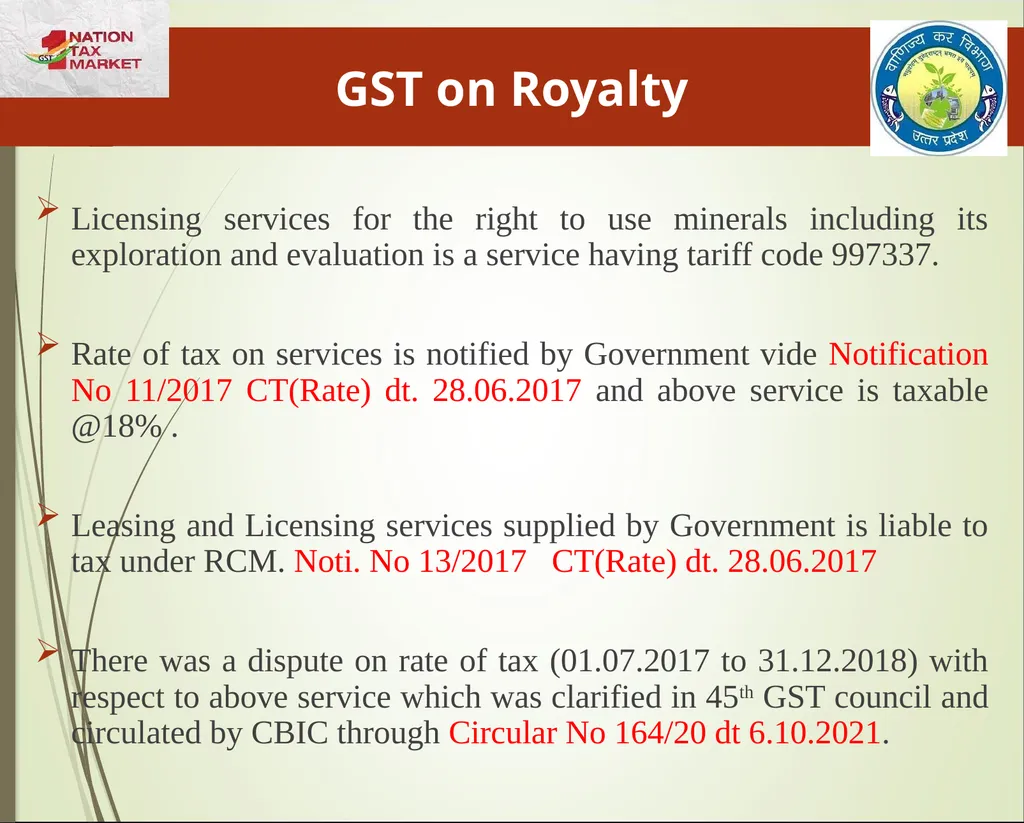
GST on Royalty Licensing services for the right to use minerals including its exploration and evaluation is a service having tariff code 997337.
Rate of tax on services is notified by Government vide Notification No 11/2017 CT(Rate) dt. 28.06.2017 and above service is taxable @18% .
Leasing and Licensing services supplied by Government is liable to tax under RCM. Noti. No 13/2017 CT(Rate) dt. 28.06.2017
There was a dispute on rate of tax (01.07.2017 to 31.12.2018) with respect to above service which was clarified in 45th GST council and circulated by CBIC through Circular No 164/20 dt 6.10.2021. 8<br>
09
GST on Royalty- Disputes Before implementation of GST, service tax was levied against lease holders under RCM who were engaged in the business of Mining.
Udaipur chamber of Commerce challenged levy of service tax before Hon. High Court, Rajasthan(W.P. 14758/2016) which was dismissed.
Udaipur chamber of Commerce filed SLP(C)No. 37326/2017 before Hon. Supreme Court which is still pending.
After implementation of GST many dealers filed W.P. before Hon. Supreme Court against levy of GST on royalty paid to Government. 9<br>
10
GST on Royalty- Disputes Hon. Supreme Court dismissed all W.P. on the ground of availability of alternate remedy before concerned H.C.
Hon. H.C. has granted Stay on proceeding initiated by Proper officers for demand of tax on Royalty paid to the Government for receiving services (997337).
Information of lease holders who have paid royalty to the Mining Department, UP but have not owned tax liability on RCM has been sent to concerned proper officers for initiation of proceedings.
Demand notices u/s 73 may be issued till 30.09.2023 for the A.Y. 2017-18. 10<br>
11
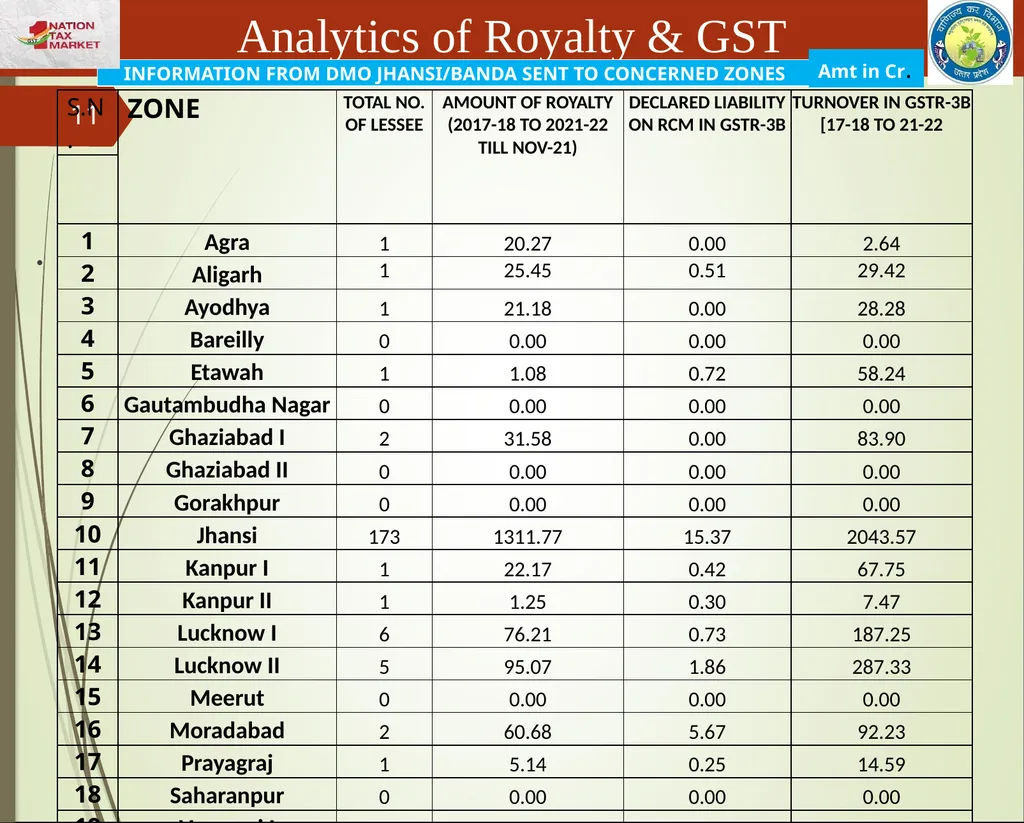
Analytics of Royalty & GST . 11 Amt in Cr.<br>
12
Tax on Supply of Minerals (HSN 2505, 2506, 2517) . 12<br>
13
Data Base of Mine Lease Holders Mining of minerals is spread all over UP.
Persons paying royalty for mining are liable to pay tax on RCM and are required to be registered mandatorily. (Sec.24)
State Tax Department has no data base of lease holders engaged in the mining of minerals.
Data obtained from Department of Mining is not workable because details of GSTIN or PAN is missing and not traceable on mobile No. provided
It is need of the hour to collect information of lease holders from every District Mining officer through SIB units, Entry of Data in the new module to develop an MIS for desired purposes. 13<br>
14
Verification of Bills . 14<br>
15
Mode of Evasion Actual transaction value of minerals is much higher than declared value due to the large component of freight.
Mostly B2C supply happens from source and retailers are not registered therefore value addition on further supply goes untaxed.
Registered recipients usually conceal freight to avoid tax on RCM and FCM.
There is no authentic source of selling rate of minor minerals.
Concealment of production by crusher units as well as sand miners.
Consignment value mostly less than Rs.50000/- hence EWB is not required. Bill collection by MS Units is meagre.
Bills uploaded are rarely verified in sector offices. 15<br>
16
CHECK LIST- MOBILE SQUAD Collection of as much as tax invoices as possible but carefully.
Feeding of details of tax invoices regularly in the specified module.
Mostly challans are used for transport of minerals whereas tax invoices are required where supply involves movement of goods. Action required
Send physical copy of tax invoices to concerned sector offices directly according to enforcement manual.
Be aware and alert to prevent use of duplicate tax invoices (discrepancy in serial number and date). 16<br>
17
CHECK LIST- SIB Collection of complete information of mineral lease holders from the office of District Mining officer on quarterly basis.
Sharing of information related to registered lease holders to concerned zonal head on quarterly basis till an MIS for desired purpose is developed.
To gather intelligence in relation to heavy earth movers machinery used by big lease holders.(own or rental or leased)
Comparison of amount paid towards royalty and taxable outward supply in GSTR-3B to red flag the dealers. 17<br>
18
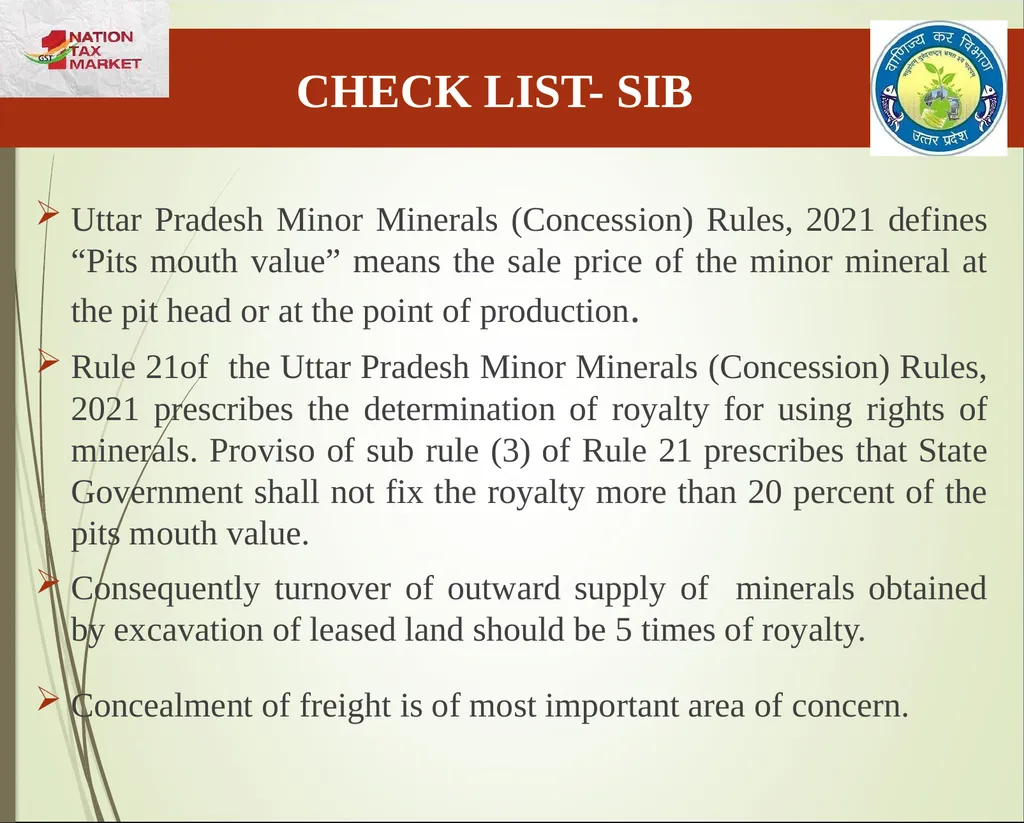
CHECK LIST- SIB Uttar Pradesh Minor Minerals (Concession) Rules, 2021 defines “Pits mouth value” means the sale price of the minor mineral at the pit head or at the point of production.
Rule 21of the Uttar Pradesh Minor Minerals (Concession) Rules, 2021 prescribes the determination of royalty for using rights of minerals. Proviso of sub rule (3) of Rule 21 prescribes that State Government shall not fix the royalty more than 20 percent of the pits mouth value.
Consequently turnover of outward supply of minerals obtained by excavation of leased land should be 5 times of royalty.
Concealment of freight is of most important area of concern. 18<br>
19
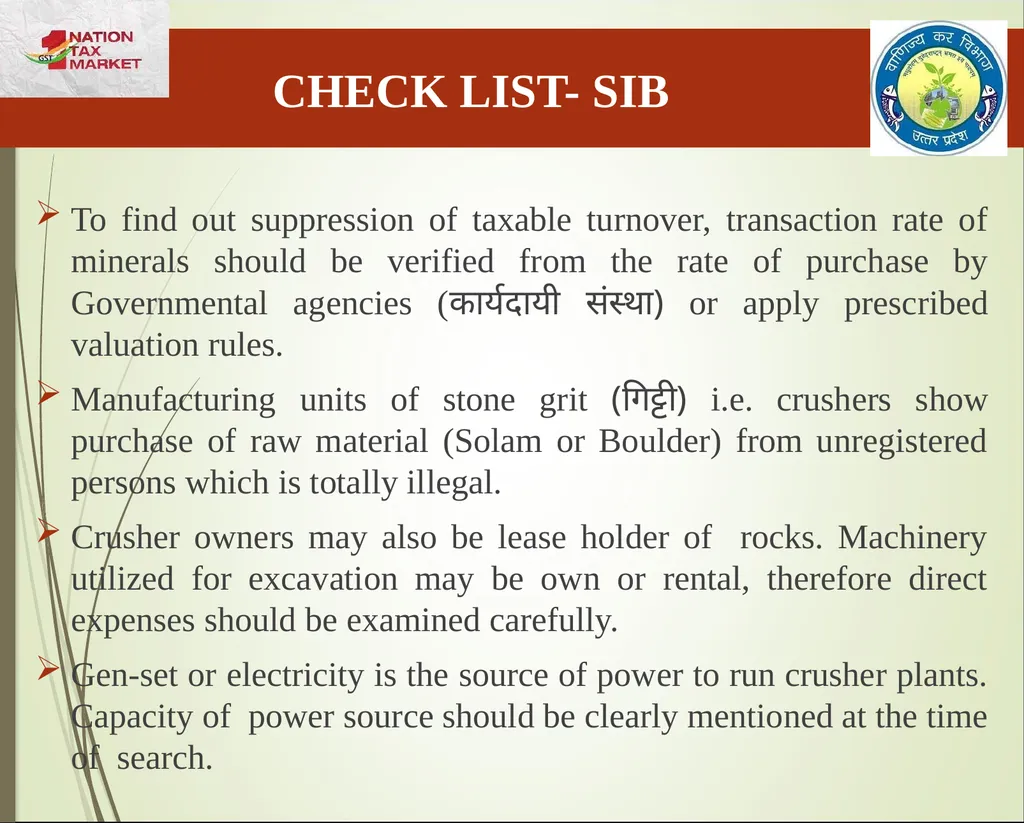
CHECK LIST- SIB To find out suppression of taxable turnover, transaction rate of minerals should be verified from the rate of purchase by Governmental agencies (कार्यदायी संस्था) or apply prescribed valuation rules.
Manufacturing units of stone grit (गिट्टी) i.e. crushers show purchase of raw material (Solam or Boulder) from unregistered persons which is totally illegal.
Crusher owners may also be lease holder of rocks. Machinery utilized for excavation may be own or rental, therefore direct expenses should be examined carefully.
Gen-set or electricity is the source of power to run crusher plants. Capacity of power source should be clearly mentioned at the time of search. 19<br>
20
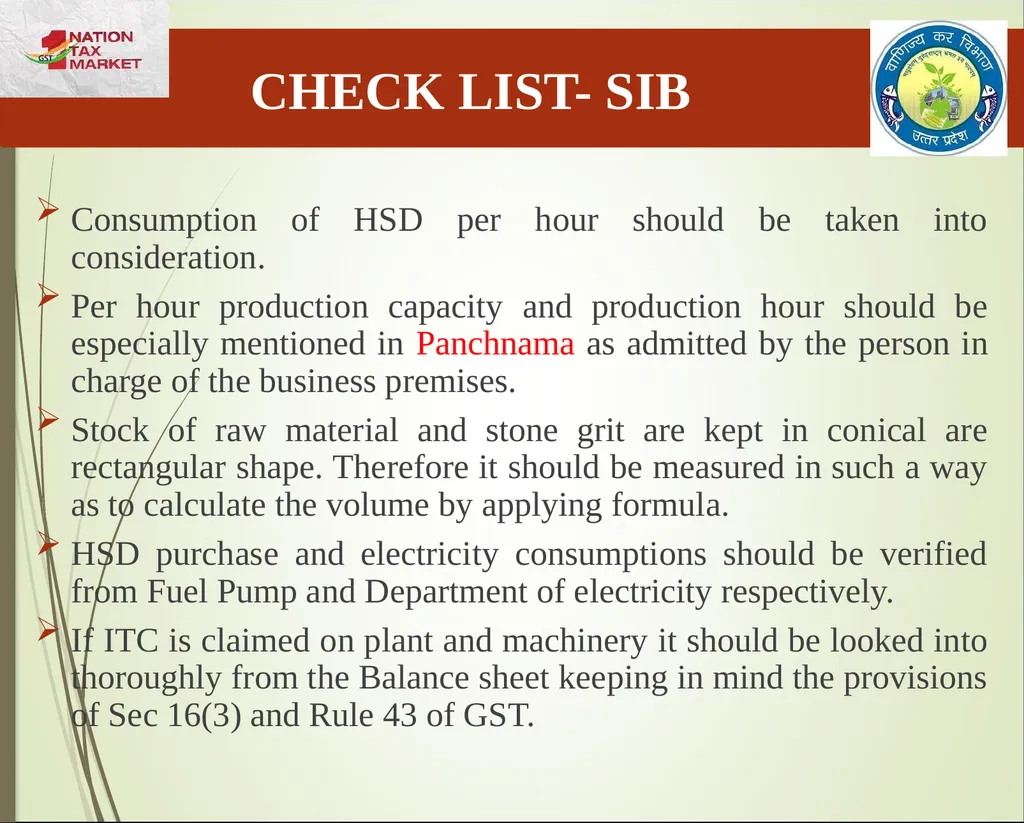
CHECK LIST- SIB Consumption of HSD per hour should be taken into consideration.
Per hour production capacity and production hour should be especially mentioned in Panchnama as admitted by the person in charge of the business premises.
Stock of raw material and stone grit are kept in conical are rectangular shape. Therefore it should be measured in such a way as to calculate the volume by applying formula.
HSD purchase and electricity consumptions should be verified from Fuel Pump and Department of electricity respectively.
If ITC is claimed on plant and machinery it should be looked into thoroughly from the Balance sheet keeping in mind the provisions of Sec 16(3) and Rule 43 of GST. 20<br>
21
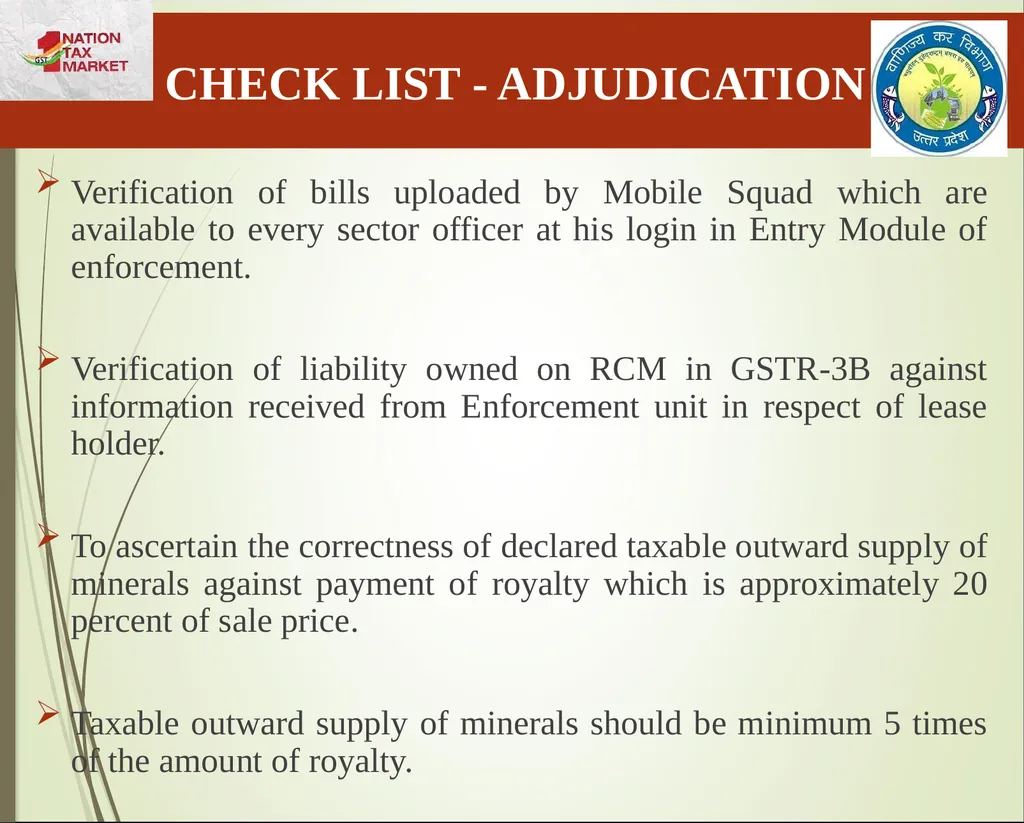
CHECK LIST - ADJUDICATION Verification of bills uploaded by Mobile Squad which are available to every sector officer at his login in Entry Module of enforcement.
Verification of liability owned on RCM in GSTR-3B against information received from Enforcement unit in respect of lease holder.
To ascertain the correctness of declared taxable outward supply of minerals against payment of royalty which is approximately 20 percent of sale price.
Taxable outward supply of minerals should be minimum 5 times of the amount of royalty. 21<br>
22
CHECK LIST - ADJUDICATION Distance between place of dispatch and delivery of minerals should be kept in mind for the determination of freight.
Concealment or suppression of turnover may be detected on the basis of transaction rate prevalent in the Government agencies.
HSD purchased against Form D and its use for the manufacturing purposes only.
Electricity or HSD consumption vis-à-vis production in previous and current years. 22<br>
Concealment or suppression of turnover may be detected on the basis of transaction rate prevalent in the Government agencies.
HSD purchased against Form D and its use for the manufacturing purposes only.
Electricity or HSD consumption vis-à-vis production in previous and current years. 22<br>
23
Checklist- SIB If a manufacturer shows receipts from supply of minerals and freight of own vehicle separately then the supply shall be treated as composite supply and determine turnover accordingly.
GST on transportation of boulders/ Solum from mining pits head to beneficiation plant by vehicles with or without driver for specific duration of time.(Clarified by CBIC circular no 177/09/2022 dt 3.08.2022)
Stone grit manufacturers and sand mine holders purchase heavy earth movers, plant and machinery and claim ITC. Along with their own use or operation they also provide it on hire charges and receipts are concealed. It should also be looked thoroughly. 23 CHECK LIST - ADJUDICATION 23<br>
24
STEPS TO BE TAKEN At Government Level
Persons participating in e-bidding of minor minerals must be registered in GST in UP.
Successful bidders shall have to file self declaration of GST return filing at the time of every payment of lease installment.
Effort for seamless flow of digital data at HQ level between both Departments.
Prayer application before Hon. S.C. for early fixation of SLP(C) 37326/2017, with details of pending WP and revenue involved in stay orders granted by Hon. H.C. Allahabad. 24<br>
25
STEPS TO BE TAKEN At H.O.D Level
Director Mining is required to issue directions to District Mining Officers to provide complete data of minor/ major mineral lease holders on quarterly basis to the Nodal Officer of State Tax Department in districts.
Director Mining is required to make necessary arrangements to provide filled of GSTIN, Tax invoice No./ date of the supplier, name of mineral, GSTIN or PAN of the recipient in e-MM-11, e-ISTP and e-Form C to facilitate data sharing with State Tax Department.
Nodal Officer at HQ level for single point of contact. 25<br>
26
STEPS TO BE TAKEN Commissioner State Tax is required to designate Nodal Officer at HQ and District level to coordinate data collection from Mining Department till it become digitally seamless.
IT section at HQ, State Tax is required to develop an Entry Module for feeding of data obtained from the Department of Mining and provide it on respective proper officer’s login.
Existing MIS of Revenue from Business Sector wise collection report and MIS of HSN/ SAC wise collection report needs to be updated by field Officers. 26<br>
27
. 27<br>