
NAVIGATING YOUR NEAG FINANCIAL ACCOUNTS Reviewing

Description: NAVIGATING YOUR NEAG FINANCIAL ACCOUNTS Reviewing this information will be time well spent Created by Leah Ward 01 Account Overview Lions and tigers and bears, oh my! -Wizard of OZ 03 Reports Did you see the memo about the TPS report?
Related Topics
Download Presentation
"NAVIGATING YOUR NEAG FINANCIAL ACCOUNTS Reviewing" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. NAVIGATING YOUR NEAG FINANCIAL
ACCOUNTS Reviewing this information will be time well spent
~Created by Leah Ward<br>
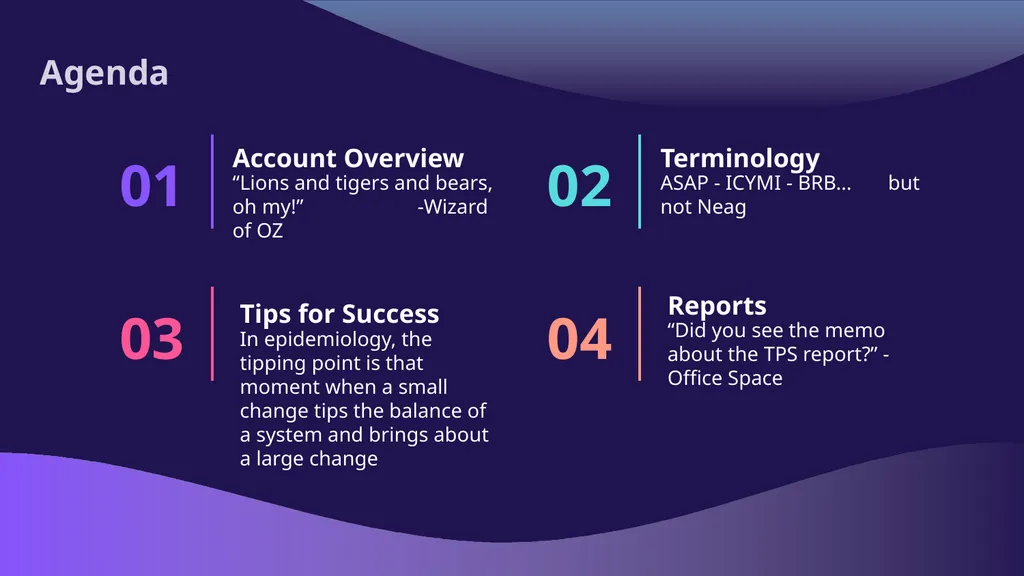
slide2. 01 Account Overview “Lions and tigers and bears, oh my!” -Wizard of OZ 03 Reports “Did you see the memo about the TPS report?” -Office Space 02 Terminology ASAP - ICYMI - BRB… but not Neag 04 Tips for Success In epidemiology, the tipping point is that moment when a small change tips the balance of a system and brings about a large change Agenda<br>
slide3. 01 ACCOUNT OVERVIEW<br>
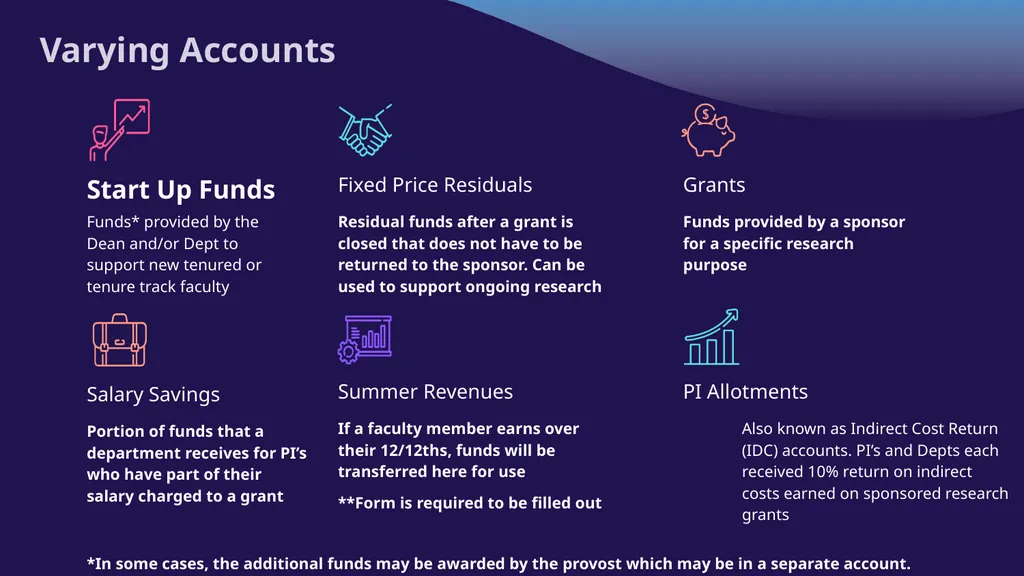
slide4. Varying Accounts Start Up Funds Funds* provided by the Dean and/or Dept to support new tenured or tenure track faculty *In some cases, the additional funds may be awarded by the provost which may be in a separate account. Fixed Price Residuals Residual funds after a grant is closed that does not have to be returned to the sponsor. Can be used to support ongoing research Grants Funds provided by a sponsor for a specific research purpose Salary Savings Portion of funds that a department receives for PI’s who have part of their salary charged to a grant Summer Revenues If a faculty member earns over their 12/12ths, funds will be transferred here for use
**Form is required to be filled out PI Allotments Also known as Indirect Cost Return (IDC) accounts. PI’s and Depts each received 10% return on indirect costs earned on sponsored research grants<br>
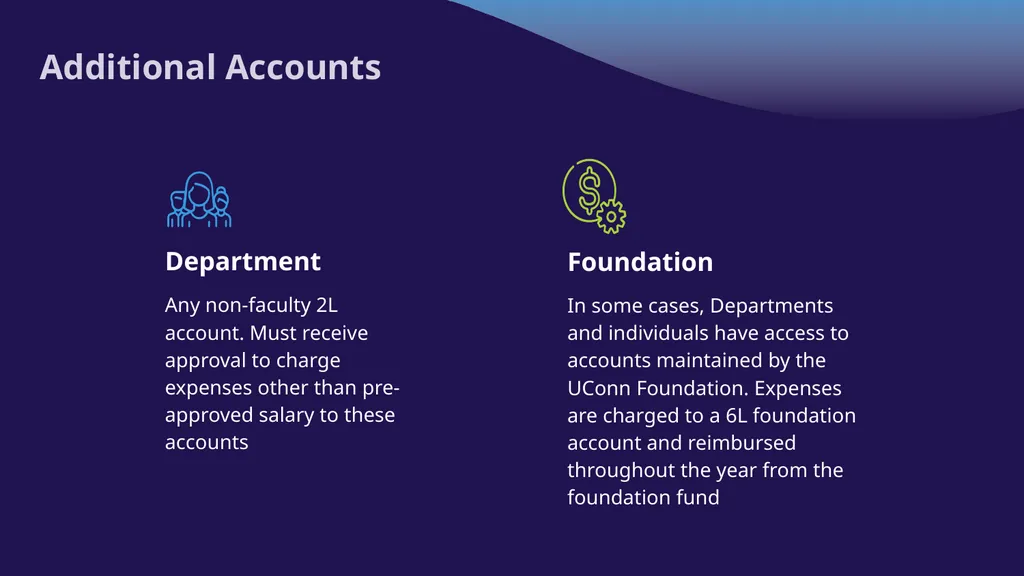
slide5. Additional Accounts Foundation In some cases, Departments and individuals have access to accounts maintained by the UConn Foundation. Expenses are charged to a 6L foundation account and reimbursed throughout the year from the foundation fund Department Any non-faculty 2L account. Must receive approval to charge expenses other than pre-approved salary to these accounts<br>
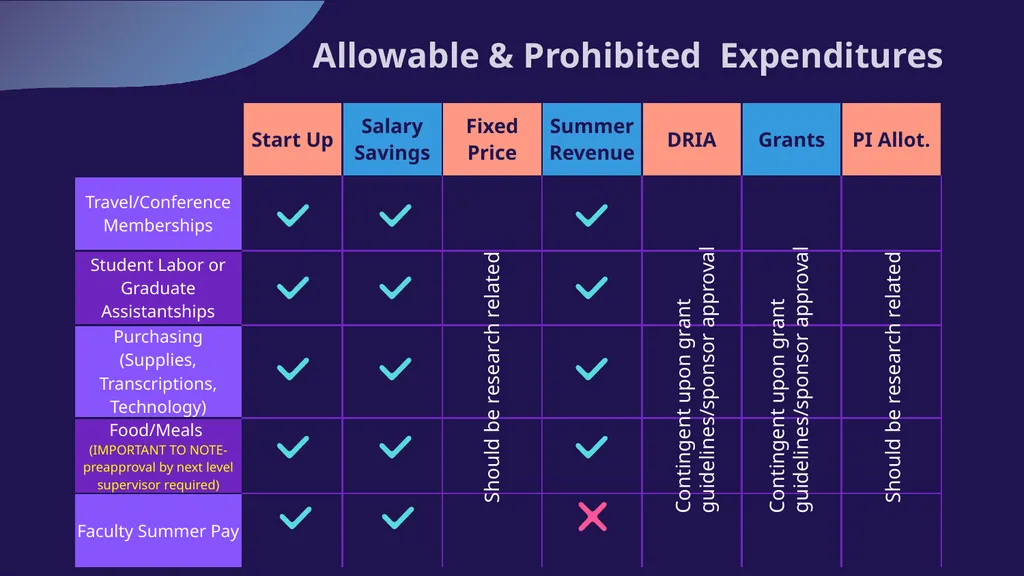
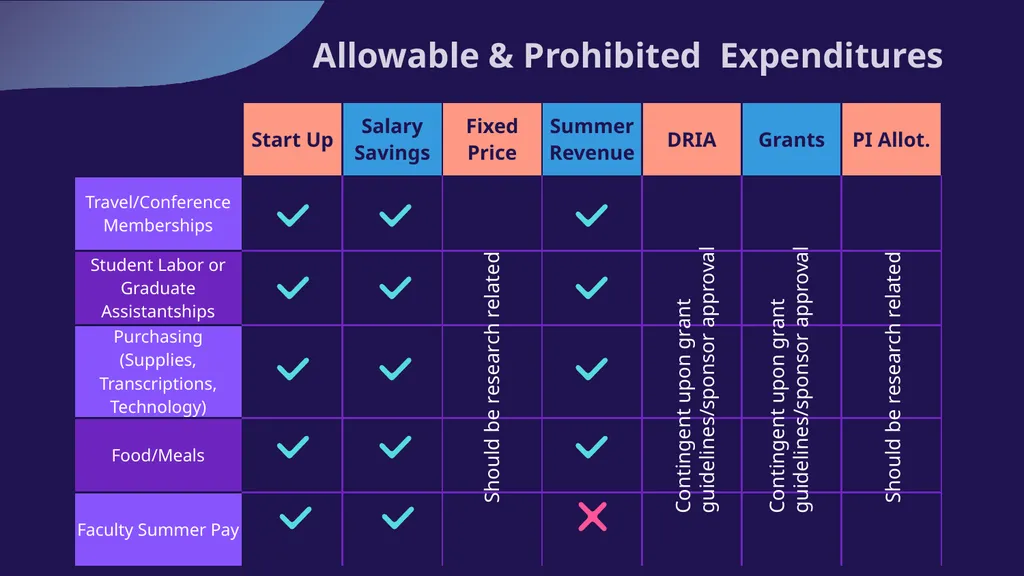
slide6. Allowable & Prohibited Expenditures Contingent upon grant guidelines/sponsor approval Contingent upon grant guidelines/sponsor approval Should be research related Should be research related<br>
slide7. 02 TERMINOLOGY<br>
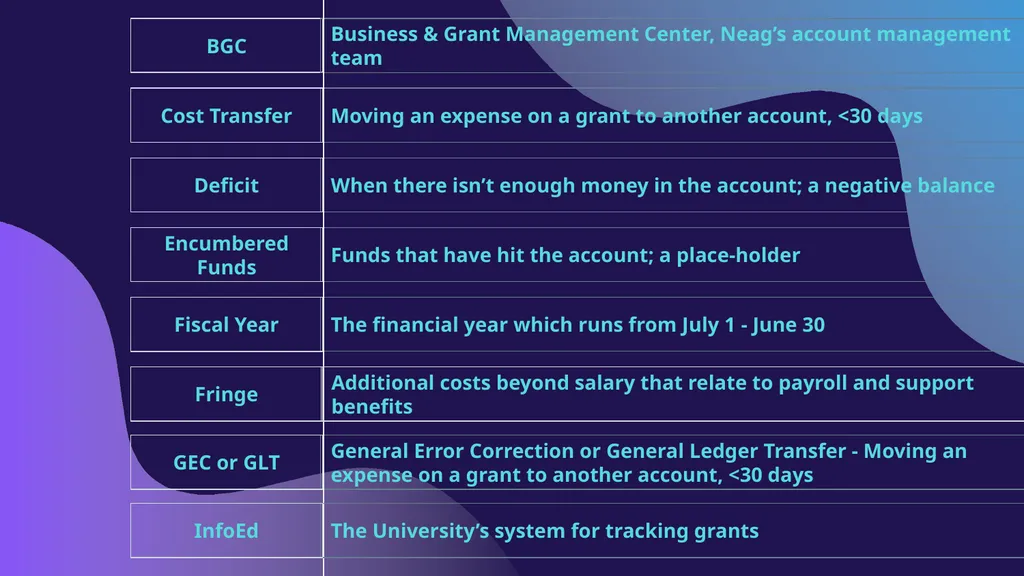
slide8. General Error Correction or General Ledger Transfer - Moving an expense on a grant to another account, <30 days GEC or GLT The financial year which runs from July 1 - June 30 BGC Funds that have hit the account; a place-holder Encumbered Funds When there isn’t enough money in the account; a negative balance Deficit Moving an expense on a grant to another account, <30 days Cost Transfer Business & Grant Management Center, Neag’s account management team Fiscal Year Fringe Additional costs beyond salary that relate to payroll and support benefits The University’s system for tracking grants InfoEd<br>
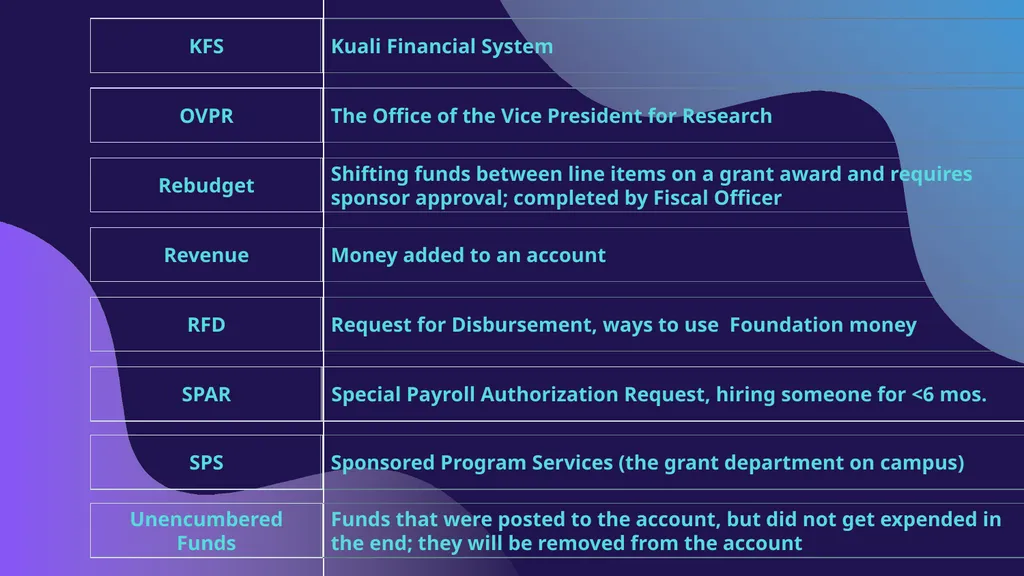
slide9. Sponsored Program Services (the grant department on campus) SPS Request for Disbursement, ways to use Foundation money RFD Money added to an account Revenue Shifting funds between line items on a grant award and requires sponsor approval; completed by Fiscal Officer Rebudget The Office of the Vice President for Research OVPR Kuali Financial System KFS SPAR Special Payroll Authorization Request, hiring someone for <6 mos. Funds that were posted to the account, but did not get expended in
the end; they will be removed from the account Unencumbered Funds<br>
slide10. 03 TIPS FOR SUCCESS<br>
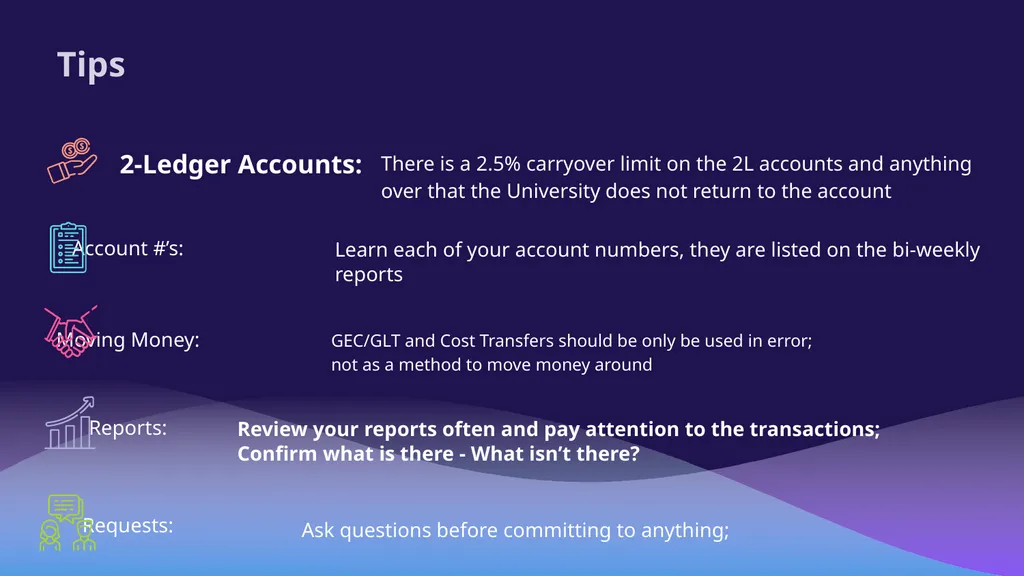
slide11. 2-Ledger Accounts: There is a 2.5% carryover limit on the 2L accounts and anything over that the University does not return to the account Review your reports often and pay attention to the transactions; Confirm what is there - What isn’t there? GEC/GLT and Cost Transfers should be only be used in error; not as a method to move money around Tips Account #’s: Learn each of your account numbers, they are listed on the bi-weekly reports Reports: Requests: Moving Money: Ask questions before committing to anything;<br>
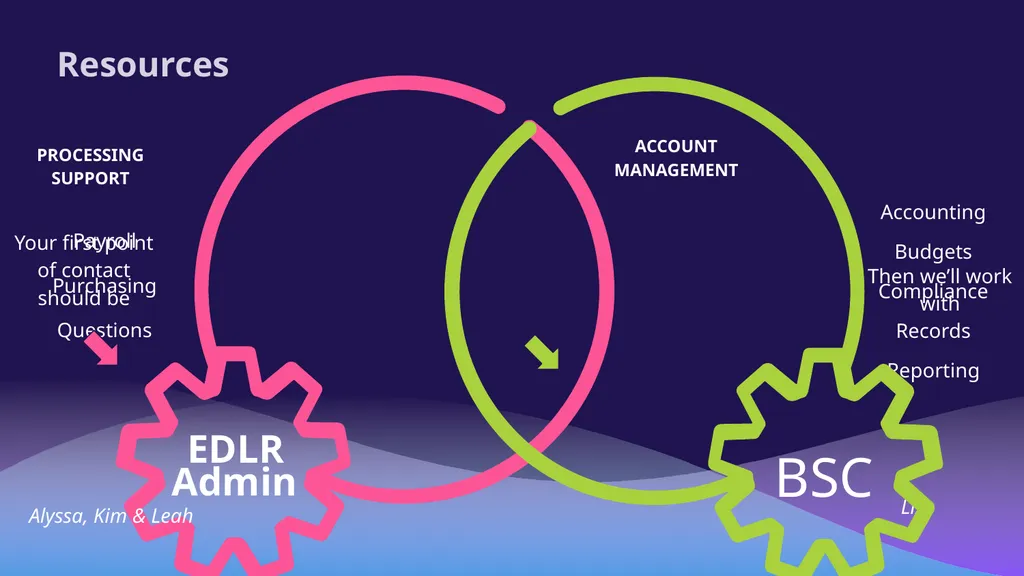
slide12. EDLR BSC Admin ACCOUNT MANAGEMENT Resources PROCESSING SUPPORT Payroll
Purchasing
Questions Accounting
Budgets
Compliance
Records
Reporting Alyssa, Kim & Leah Liz Your first point of contact should be Then we’ll work with<br>
slide13. 04 FINANCIAL REPORTS<br>
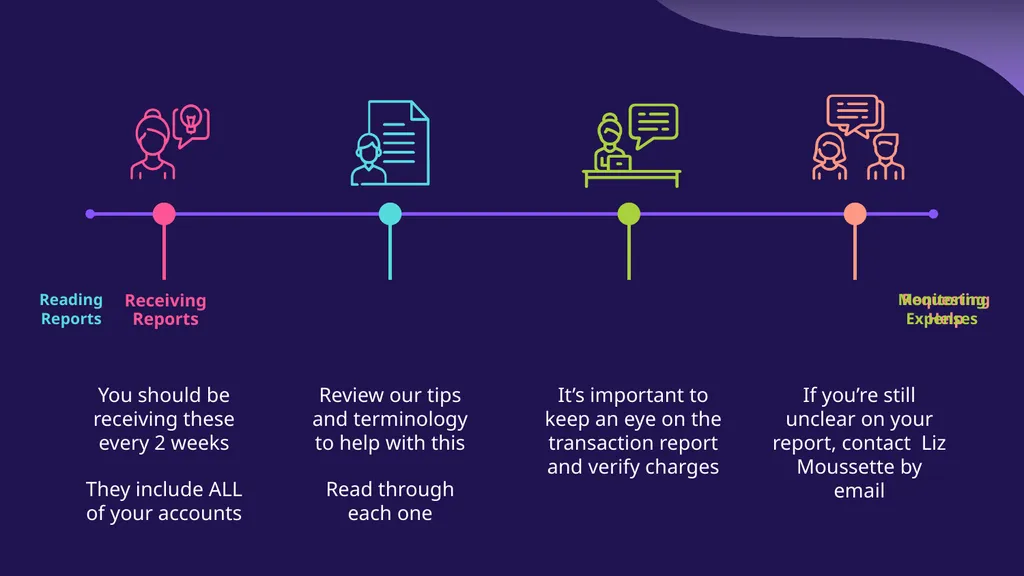
slide14. Receiving Reports Reading Reports Requesting
Help Monitoring Expenses You should be receiving these every 2 weeks
They include ALL of your accounts Review our tips and terminology to help with this
Read through each one It’s important to keep an eye on the transaction report and verify charges If you’re still unclear on your report, contact Liz Moussette by email<br>
slide15. Q&A with Liz Moussette
(recorded session)<br>
slide16. Question: How do I see how much is in my account?<br>
slide17. Answer: Everyone that has an account should be getting a report and on that first page you should see a balance. If you have any questions, you can always reach out to your Fiscal Officer and they can look that up for you.<br>
slide18. Question: How do I know what account number is which?<br>
slide19. Answer: You should have a list of all your accounts - on the report each will be listed by account # and name.<br>
slide20. Question: Where can I find all my account numbers?<br>
slide21. Answer: This is available on the bi-weekly reports. If you have accounts, you should be getting the reports. If you are not, please let your fiscal officer know.<br>
slide22. Question: I know I have money, but HOW do I spend it?<br>
slide23. Answer: Work with the Department Admin to make purchases.
Out of pocket reimbursements go through Concur and trainings are available for Faculty.<br>
slide24. Question: Are there limitations on what I can buy?<br>
slide25. Answer: Some limitations but not many.
If research approved, purchases should be research related.
Use up 2-ledger salary savings funds first.<br>
slide26. Allowable & Prohibited Expenditures Contingent upon grant guidelines/sponsor approval Contingent upon grant guidelines/sponsor approval Should be research related Should be research related<br>
slide27. Question: Why isn’t my money all in one place?<br>
slide28. Answer: Some fund transfers on campus require accounts with the same attributes which is why Faculty may have more than one account to manage.
It’s not ideal, but mandated by the University and/or funder.<br>
slide29. Question: What does it mean when I see an ‘encumbrance’ on my account?
What happens if I don’t use the full encumbered amount?<br>
slide30. Answer: Encumbered expenses cover costs already committed and associated with Payroll or a Purchase Order.
Encumberances get reduced as they are paid/invoiced.<br>
~Created by Leah Ward<br>
slide2. 01 Account Overview “Lions and tigers and bears, oh my!” -Wizard of OZ 03 Reports “Did you see the memo about the TPS report?” -Office Space 02 Terminology ASAP - ICYMI - BRB… but not Neag 04 Tips for Success In epidemiology, the tipping point is that moment when a small change tips the balance of a system and brings about a large change Agenda<br>
slide3. 01 ACCOUNT OVERVIEW<br>
slide4. Varying Accounts Start Up Funds Funds* provided by the Dean and/or Dept to support new tenured or tenure track faculty *In some cases, the additional funds may be awarded by the provost which may be in a separate account. Fixed Price Residuals Residual funds after a grant is closed that does not have to be returned to the sponsor. Can be used to support ongoing research Grants Funds provided by a sponsor for a specific research purpose Salary Savings Portion of funds that a department receives for PI’s who have part of their salary charged to a grant Summer Revenues If a faculty member earns over their 12/12ths, funds will be transferred here for use
**Form is required to be filled out PI Allotments Also known as Indirect Cost Return (IDC) accounts. PI’s and Depts each received 10% return on indirect costs earned on sponsored research grants<br>
slide5. Additional Accounts Foundation In some cases, Departments and individuals have access to accounts maintained by the UConn Foundation. Expenses are charged to a 6L foundation account and reimbursed throughout the year from the foundation fund Department Any non-faculty 2L account. Must receive approval to charge expenses other than pre-approved salary to these accounts<br>
slide6. Allowable & Prohibited Expenditures Contingent upon grant guidelines/sponsor approval Contingent upon grant guidelines/sponsor approval Should be research related Should be research related<br>
slide7. 02 TERMINOLOGY<br>
slide8. General Error Correction or General Ledger Transfer - Moving an expense on a grant to another account, <30 days GEC or GLT The financial year which runs from July 1 - June 30 BGC Funds that have hit the account; a place-holder Encumbered Funds When there isn’t enough money in the account; a negative balance Deficit Moving an expense on a grant to another account, <30 days Cost Transfer Business & Grant Management Center, Neag’s account management team Fiscal Year Fringe Additional costs beyond salary that relate to payroll and support benefits The University’s system for tracking grants InfoEd<br>
slide9. Sponsored Program Services (the grant department on campus) SPS Request for Disbursement, ways to use Foundation money RFD Money added to an account Revenue Shifting funds between line items on a grant award and requires sponsor approval; completed by Fiscal Officer Rebudget The Office of the Vice President for Research OVPR Kuali Financial System KFS SPAR Special Payroll Authorization Request, hiring someone for <6 mos. Funds that were posted to the account, but did not get expended in
the end; they will be removed from the account Unencumbered Funds<br>
slide10. 03 TIPS FOR SUCCESS<br>
slide11. 2-Ledger Accounts: There is a 2.5% carryover limit on the 2L accounts and anything over that the University does not return to the account Review your reports often and pay attention to the transactions; Confirm what is there - What isn’t there? GEC/GLT and Cost Transfers should be only be used in error; not as a method to move money around Tips Account #’s: Learn each of your account numbers, they are listed on the bi-weekly reports Reports: Requests: Moving Money: Ask questions before committing to anything;<br>
slide12. EDLR BSC Admin ACCOUNT MANAGEMENT Resources PROCESSING SUPPORT Payroll
Purchasing
Questions Accounting
Budgets
Compliance
Records
Reporting Alyssa, Kim & Leah Liz Your first point of contact should be Then we’ll work with<br>
slide13. 04 FINANCIAL REPORTS<br>
slide14. Receiving Reports Reading Reports Requesting
Help Monitoring Expenses You should be receiving these every 2 weeks
They include ALL of your accounts Review our tips and terminology to help with this
Read through each one It’s important to keep an eye on the transaction report and verify charges If you’re still unclear on your report, contact Liz Moussette by email<br>
slide15. Q&A with Liz Moussette
(recorded session)<br>
slide16. Question: How do I see how much is in my account?<br>
slide17. Answer: Everyone that has an account should be getting a report and on that first page you should see a balance. If you have any questions, you can always reach out to your Fiscal Officer and they can look that up for you.<br>
slide18. Question: How do I know what account number is which?<br>
slide19. Answer: You should have a list of all your accounts - on the report each will be listed by account # and name.<br>
slide20. Question: Where can I find all my account numbers?<br>
slide21. Answer: This is available on the bi-weekly reports. If you have accounts, you should be getting the reports. If you are not, please let your fiscal officer know.<br>
slide22. Question: I know I have money, but HOW do I spend it?<br>
slide23. Answer: Work with the Department Admin to make purchases.
Out of pocket reimbursements go through Concur and trainings are available for Faculty.<br>
slide24. Question: Are there limitations on what I can buy?<br>
slide25. Answer: Some limitations but not many.
If research approved, purchases should be research related.
Use up 2-ledger salary savings funds first.<br>
slide26. Allowable & Prohibited Expenditures Contingent upon grant guidelines/sponsor approval Contingent upon grant guidelines/sponsor approval Should be research related Should be research related<br>
slide27. Question: Why isn’t my money all in one place?<br>
slide28. Answer: Some fund transfers on campus require accounts with the same attributes which is why Faculty may have more than one account to manage.
It’s not ideal, but mandated by the University and/or funder.<br>
slide29. Question: What does it mean when I see an ‘encumbrance’ on my account?
What happens if I don’t use the full encumbered amount?<br>
slide30. Answer: Encumbered expenses cover costs already committed and associated with Payroll or a Purchase Order.
Encumberances get reduced as they are paid/invoiced.<br>