
Office of Management and Budget (OMB) CIRCULAR

Description: Office of Management and Budget (OMB) CIRCULAR A-21 Principles for determining costs applicable to grants, contracts, and other agreements with educational institutions CReATE ver. 0513 2013 Florida State University. All rights reserved
Related Topics
Download Presentation
"Office of Management and Budget (OMB) CIRCULAR" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Office of Management and Budget (OMB) CIRCULAR A-21 Principles for determining costs applicable to grants, contracts, and other agreements
with educational institutions CReATE ver. 05/13 © 2013 Florida State University. All rights reserved<br>
slide2. OMB Circular A-21 THE PRIMARY ACCOUNTING REFERENCE FOR FEDERAL SPONSORED AGREEMENTS 2<br>
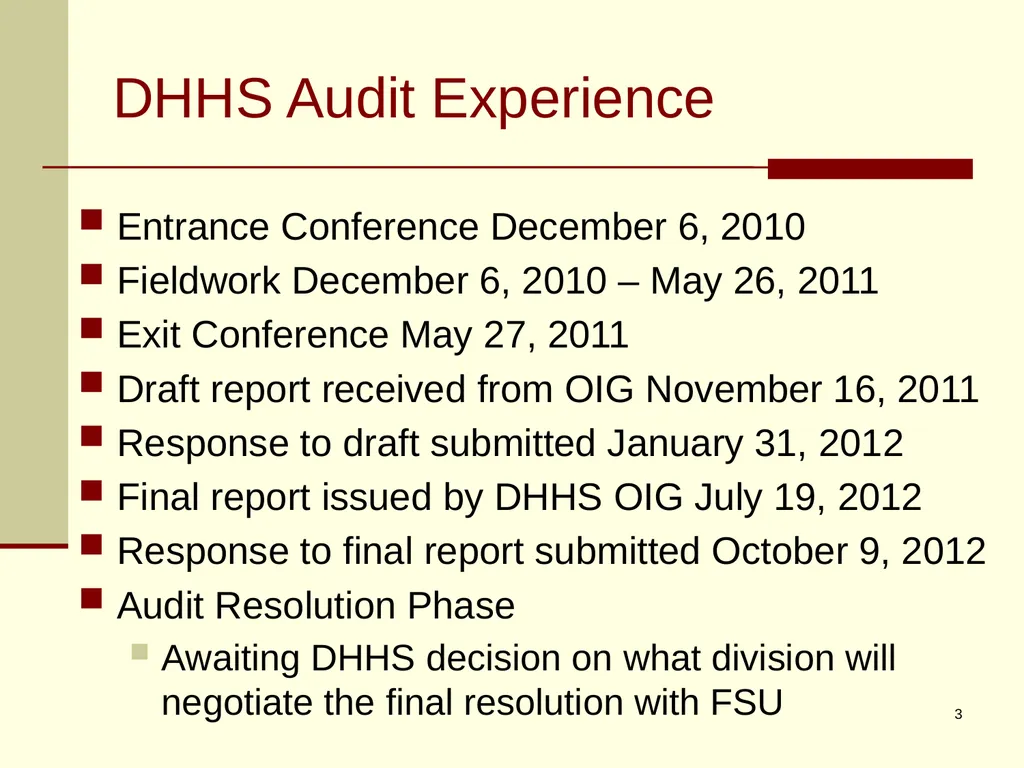
slide3. DHHS Audit Experience Entrance Conference December 6, 2010
Fieldwork December 6, 2010 – May 26, 2011
Exit Conference May 27, 2011
Draft report received from OIG November 16, 2011
Response to draft submitted January 31, 2012
Final report issued by DHHS OIG July 19, 2012
Response to final report submitted October 9, 2012
Audit Resolution Phase
Awaiting DHHS decision on what division will negotiate the final resolution with FSU 3<br>
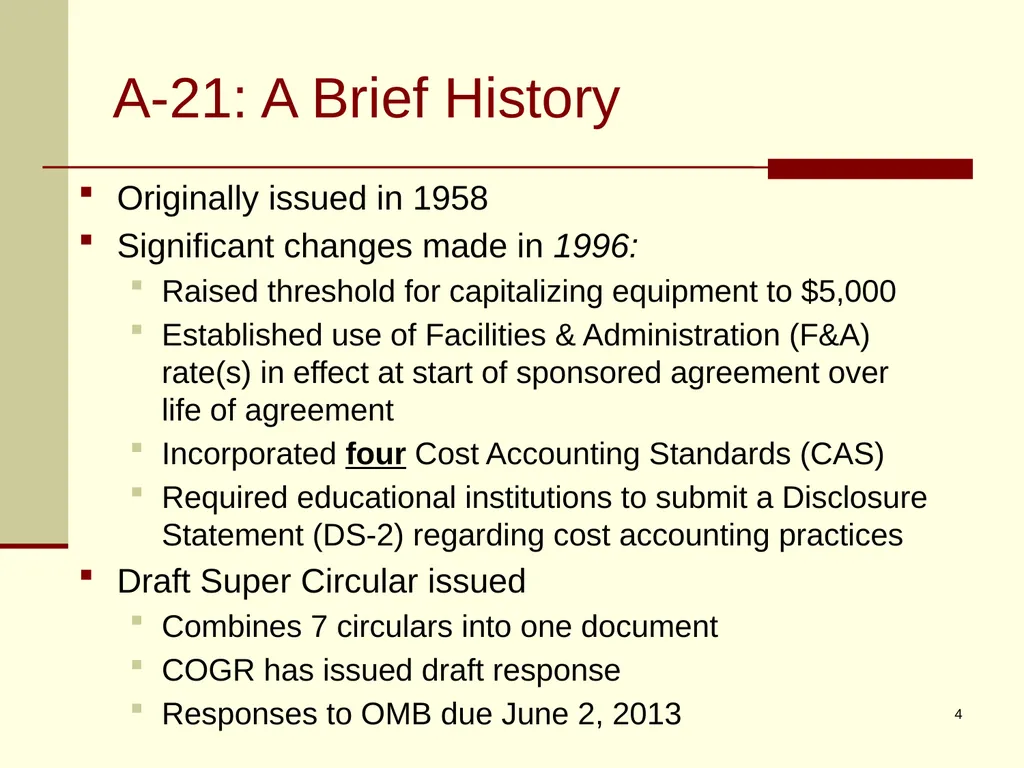
slide4. A-21: A Brief History Originally issued in 1958
Significant changes made in 1996:
Raised threshold for capitalizing equipment to $5,000
Established use of Facilities & Administration (F&A) rate(s) in effect at start of sponsored agreement over life of agreement
Incorporated four Cost Accounting Standards (CAS)
Required educational institutions to submit a Disclosure Statement (DS-2) regarding cost accounting practices
Draft Super Circular issued
Combines 7 circulars into one document
COGR has issued draft response
Responses to OMB due June 2, 2013 4<br>
slide5. Why talk about OMB Circular A-21? SRS and SRAS employees need to refer to OMB Circulars A-21 and A-110 (next presentation) on a daily basis
Every decision on federally funded agreements is guided by these pronouncements 5<br>
slide6. A-21: Applicability To all research and development, training and other work funded with federal funds at educational institutions
Principles used only as guide in pricing of fixed price or lump sum agreements
The Proposal budget on a fixed price agreement is subject to audit for compliance with A-21
Basis for requiring a detailed budget on a fixed price award
Actual expenditures on a fixed price agreement are not subject to audit 6<br>
slide7. Major Functions Instruction
Teaching and training activities
Not research training
Departmental research
Not organized research
Not separately budgeted
Not considered major function
Organized Research
Research and development activities
Separately budgeted
Includes research training 7<br>
slide8. Major Functions Other Sponsored Activities
Programs and projects that are service oriented
Not instruction or organized research
Examples
Head Start program
WFSU activities
Other Institutional Activities
All activities not otherwise classified
Dorms
Dining facilities
F&A costs
Specialized Service Facilities 8<br>
slide9. A-21: Direct Costs Can be identified specifically with a particular sponsored project, an instructional activity, or any other institutional activity, or can be directly assigned to such activities relatively easily with a high degree of accuracy
Where an institution treats a particular type of cost as direct cost of sponsored agreements, all costs incurred for same purpose in like circumstances must be treated as direct costs of all institutional activities 9<br>
slide10. Direct Costs – Personnel Costs Salaries and fringe benefits
Faculty and other non administrative/clerical and student employees working on the sponsored project
Job titles (not all inclusive)
Researcher
Lab Assistant/Researcher
Graduate Research Assistant 10<br>
slide11. Direct Costs – Non Personnel Other direct costs:
Animals
Animal care
Audio-visual supplies (chemicals, glassware, etc.)
Books and periodicals
Specialized & technical svcs
Consulting services
Lab equipment & equipment maintenance
Computer equipment and supplies - research purpose
Laboratory supplies
Long distance telephone
Publication costs
Rent & other off-campus facilities costs
Scientific reprints
Subawards
Travel
Tuition 11<br>
slide12. Facilities & Administrative (F&A) Costs Costs incurred for common or joint objectives and, therefore, cannot be identified readily and specifically with a particular sponsored project, instructional activity, or any other institutional activity 12<br>
slide13. Computer Purchases Deemed to be “general purpose equipment” per A-21 J18a(4)
Generally unallowable as direct charges (J18b(1))
Requires approval in advance by awarding agency
Refer to guidance issued in June 2012
http://www.research.fsu.edu/contractsgrants/documents/ITguide.pdf
Included in proposal – adequate justification
Not included in proposal – seek approval
Prior to purchase 13<br>
slide14. A-21: Cost Accounting Standards CAS 501- Consistency in estimating, accumulating and reporting costs
Basis used in estimating costs in proposal budget, charging costs to sponsored agreement and reporting costs to sponsor must be consistent with one another
CAS 502- Consistency in allocating costs incurred for same purpose
All costs incurred for same purpose, in like circumstances, are either direct costs only or indirect costs only 14<br>
slide15. A-21: Cost Accounting Standards CAS 505 - Accounting for unallowable costs
Unallowable costs must be identified in accounting system or identifiable from departmental records
CAS 506 - Cost accounting period
FSU’s fiscal year – July 1, xxxx – June 30, xxxx 15<br>
slide16. A-21: Disclosure Statement Large educational institutions
$25 million per year or more in federally funded awards
To cognitive agency (DHHS) for review and approval
FSU Disclosure Statement (DS-2) History
Submitted – June 1998
FSU submitted revisions – September 2006, April 2009 and January 2010
Received approval March 2010
Revised capitalization threshold to $5,000 approved with most recent negotiated F&A rate agreement in July 2012 16<br>
slide17. Key FSU Practices Accounting system description: cash basis
Cost accounting period: 7/1 to 6/30
Capitalization of non-expendable tangible personal property
$5,000/useful life greater than one year
Treatment of costs – direct and indirect declared 17<br>
slide18. FSU Policies Related to DS-2 Issued a policy on Direct and Indirect Costs of Sponsored Agreements
Issued a policy on Cost Sharing
Issued a policy on Unallowable Costs of Federally Sponsored Projects
Policies can be found on Sponsored Research Web site ( http://www.research.fsu.edu ) 18<br>
slide19. A-21 Cost Principles Allowability Factors
Reasonableness
Allocability
Consistency of treatment
Conformity to limitations or exclusions 19<br>
slide20. Reasonableness 1 - Reasonable
Prudent person would have paid the stated amount for the goods/services
Cost necessary to accomplish objectives of sponsored award
Restraints or requirements imposed by arm’s-length bargaining/Federal & State laws/sponsored award terms & conditions
Due prudence
Consistent with institutional policies 20<br>
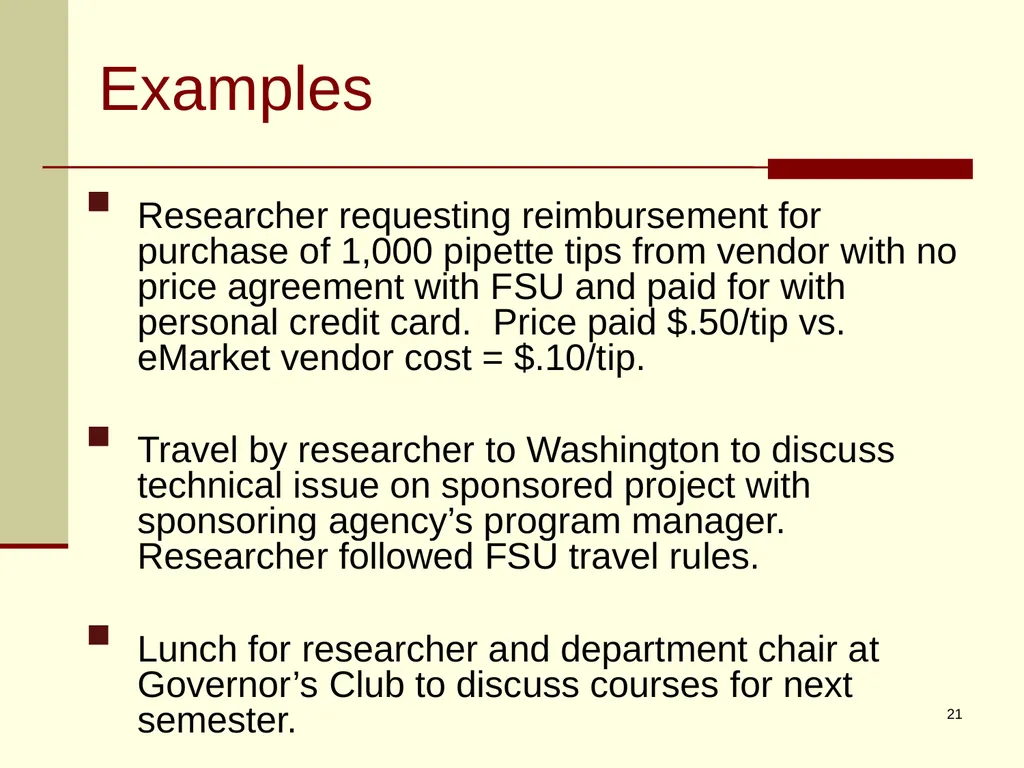
slide21. Researcher requesting reimbursement for purchase of 1,000 pipette tips from vendor with no price agreement with FSU and paid for with personal credit card. Price paid $.50/tip vs. eMarket vendor cost = $.10/tip.
Travel by researcher to Washington to discuss technical issue on sponsored project with sponsoring agency’s program manager. Researcher followed FSU travel rules.
Lunch for researcher and department chair at Governor’s Club to discuss courses for next semester. 21 Examples<br>
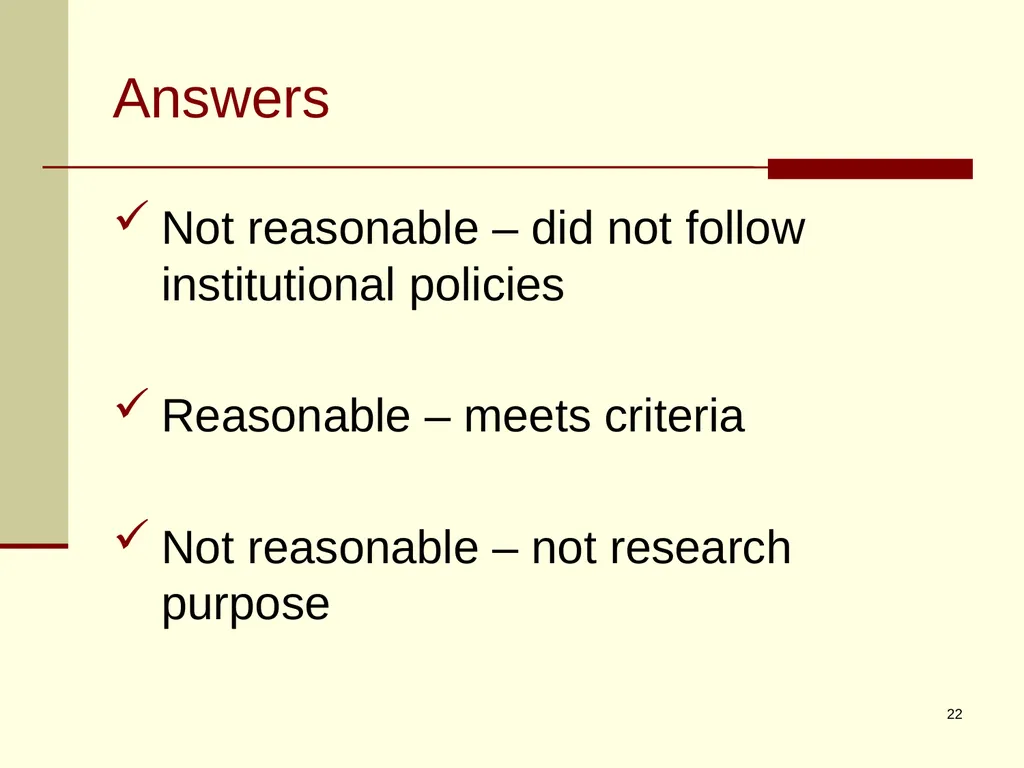
slide22. Answers Not reasonable – did not follow institutional policies
Reasonable – meets criteria
Not reasonable – not research purpose 22<br>
slide23. Allocability 2 - Allocable
Goods or services involved can be charged in accordance with relative benefits received
Identifiable to a sponsored award
Incurred solely to advance work under sponsored agreement
Benefits more than one sponsored project or other institutional activity, the cost must be shared
Necessary for operation of sponsored and/or other institutional activity 23<br>
slide24. Allocability Equipment specifically authorized under sponsored agreement, is assignable to sponsored agreement regardless of any use that may subsequently be made 24<br>
slide25. Allocability - Lab Manager In multi award lab general duties must be allocated across awards on a reasonable basis. Examples,
Training of students, other researchers in lab protocols and procedures
Animal care that may not be specific to one project
Performing or supervising others in the preparation of experiments, equipment maintenance, and lab inventory
Staying abreast of animal care developments 25<br>
slide26. Example – Lab Manager Dr. Gold performs retinal research with zebra fish on 2 R01 NIH awards and conducts some departmental research.
Ms. Seminole trains all students in lab techniques and protocols (10%), orders supplies for the lab (5%), cares for the fish colonies (25%), performs experiments assigned by Dr. Gold (60%)
How allocate? 26<br>
slide27. Answer 40% general duties
Both R01 grants
Non sponsored source for the departmental research
% as determined by Dr. Gold
60% directly related to performing experiments allocated (Dr. Gold estimate) 27<br>
slide28. Example – Salary Charges Research associate’s salary for month of July 2008 charged to sponsored project for actual work performed on project in January 2008
Research associate’s effort in July 2008 did not pertain to sponsored project
Sponsored project period was 1/1/08 to 12/31/08 28<br>
slide29. Answer Charge is unallowable because research associate’s effort in July did not benefit sponsored project
This practice is referred to as “cost substitution” and does not conform to A-21 requirements 29<br>
slide30. Allocability – General Lab Supplies In multi award lab general lab supplies (pipettes, gloves, etc.) must be allocated across awards on a reasonable basis. Considerations,
Can/will items be used by all awards in lab? Specialized items?
Is item used for general lab upkeep?
What are the lab supply and ordering practices?
Is there non sponsored research occurring in the lab?
Length of awards using items?
What type of experiments are being conducted? 30<br>
slide31. Example – General Lab Supplies Dr. Tomahawk performs sense of smell research with rats and has 1 R01 NIH and 2 NSF grants all in the same lab. The aims do not overlap but all of the grants use similar research techniques and equipment.
The lab manager requests for purchase 5000 pipette tips ($500), 300 glass test tubes ($150) and 1 gustometer ($6,000) that will be used only on the R01 award.
How should the items purchased be charged to each award? 31<br>
slide32. Answer 1 The pipette tips and test tubes should be allocated to all awards:
PI estimate % of usage on each award
Charge 100% of gustometer to the R01 award. 32<br>
slide33. Answer 2 Each researcher works on only 1 award and requests supplies from lab manager monthly:
Grad Student A (R01) 2000 pipette tips = $200
Grad Student B (NSF A) 2000 pipette tips 200 test tubes = $300
Grad Student C (NSF B) 1000 pipette tips and 100 test tubes = $150
Charge 100% of gustometer to the R01 award = $6,000 33<br>
slide34. Allocability – Service Agreements In multi award lab service agreements for equipment must be allocated across awards on a reasonable basis. Considerations,
When was the equipment purchased? Source of funding? Source active?
What is the equipment used for? What projects require the use of the equipment for the svc agmt period
Is there non sponsored research occurring in the lab?
Length of awards using items?
What type of experiments are being conducted? 34<br>
slide35. Example – Service Agreement Dr. Tomahawk performs sense of smell research with rats and has 1 R01 NIH (ends 6/30/2012) and 2 NSF grants (both end 12/31/2013) all in the same lab. The aims do not overlap but all of the grants use similar research techniques and equipment.
There are 5 centrifuges in the lab. The R01 uses the 3 large centrifuges and the 2 NSF awards use the 2 smaller ones with equal usage.
Each service agreement costs $500 for period 1/1/2012-12/31/2012
How should the service agreements’ costs be charged to each award? 35<br>
slide36. Answer R01 = $750
NSF A = $500
NSF B = $500
Non sponsored source = $750
Total = $2,500
Note rotation among awards generally not acceptable method 36<br>
slide37. Example – Equipment Dr. Garnett purchased a microscope costing $10,000 on an NSF-funded project during last month of a one-year grant period. The microscope has a 5 year life.
The microscope was included in the budget approved by the agency.
The equipment was required to complete the analysis phase of research. 37<br>
slide38. Answer Charge for this equipment is allowable as it was purchased during grant period.
Even though equipment had five year useful life and was used only one month of grant period, it conforms to A-21 provision
“specifically authorized in grant… regardless of subsequent use”. 38<br>
slide39. Allocability – Cost Transfer Policy Effective April 1, 2008; revised July 1, 2010
http://www.research.fsu.edu/contractsgrants/documents/costtranspolicy.pdf
Expenditure transfers to or between sponsored projects
Red flags
Frequent transfers
Transfers close to end of project
Inadequate documentation to support transfer 39<br>
slide40. Cost Transfers Improper cost transfers
Cover overruns
Spend available balance close to end of project
Transfer of unallowable cost from one project to another
Circumvention of award limitation/restriction
Charge costs to one project that belong to an award not yet executed
Advance policy enacted for this reason! 40<br>
slide41. Cost Transfers Allowable transfers
Correct erroneous charge
Allocate portion of charge that applies to the project (e.g. split purchases)
Cost Transfer Justification Form at http://www.research.fsu.edu/contractsgrants/forms.html
Must be received by SRAS as follows:
Within 90 calendar days from the end of the month in which the error occurred (personnel and non-personnel)
Retroactive Distribution of Funding
Moving salary between or onto projects reallocating original ePAF distribution as a result of the effort certified is acceptable justification for salary cost transfers 41<br>
slide42. Cost Transfers Cost transfers not received by SRAS by deadline will only be approved in extenuating circumstances, which does not include:
Absences of PI or project administrators
Non qualified staff
Shortage of staff
SRAS Compliance Committee reviews on weekly basis
SRAS Director approves >$25,000 or > 90 days
Monthly reconciliations needed to detect and correct errors within established timeframes
Controller’s Office offers training:
BTFA03 - General Ledger Reconciliation 42<br>
slide43. Cost Transfers Justifications – what not to say!
“Charged to NSF grant waiting for NIH grant to get set up.”
“Reconciliations were not performed for 6 months because of support staff turnover.”
“There are funds left on Project Aaa and we want to spend the balance. We charged the costs to Project Bee but now that there is funding left so we need to move the costs.” 43<br>
slide44. Example – Cost Transfers A graduate assistant worked and was paid 50% on grant from US Dept. of Agriculture (USDA) and 50% on grant from National Science Foundation (NSF). Each grant was charged 50% of tuition. Since USDA policy does not permit charges for tuition, the PI requested that the tuition charge be transferred from USDA account to NSF account.
Would you approve this cost transfer?? Why or Why not?? 44<br>
slide45. Answer Tuition charge transferred to NSF account is unallowable because
Charge to NSF grant (now at 100%) was not proportional to effort devoted to NSF grant (50%)
Transfer was made to avoid restriction of USDA policy. 45<br>
slide46. Example – Cost Transfers At the start of Fall 2011 semester, Dr. Nole was appointed as follows:
E&G funding = 65%
NIH P01 award = 20%
NSF award = 15%
Dr. Nole certified his Fall 2011 effort report as follows:
E&G funding = 65%
NIH P01 award = 15% (Error occurred <20% paid)
NSF award = 20%
How do we resolve the effort error?? 46<br>
slide47. Answer An RDF is required to move 5% from the NIH to the NSF award.
Allowable because it “trues” up to actual
Meets time criterion because as a result of actual effort
Requesting the PI to change his/her effort certification “to get rid of the error” IS NOT the solution!!!! 47<br>
slide48. Cost Transfers - NIH Policy The NIH Grants Policy Statement
Cost Transfers to NIH grants by grantees…should be accomplished within 90 days…
Transfers must be supported by documentation that fully explains how error occurred and certification of correctness of new charge by responsible University official …
Stating that transfer was made “to correct error” or “to transfer to correct project” is not sufficient.
Transfers of costs solely to cover cost overruns are not allowable. 48<br>
slide49. Cost Transfers - NIH policy Grantee’s must maintain prescribed documentation of cost transfers and must make it available for audit…
Frequent errors in recording costs may indicate need for accounting system improvements and/or enhanced internal controls.
If such errors occur, grantees are encouraged to evaluate need for improvements and to make whatever improvements are deemed necessary to prevent reoccurrence.
NIH also may require a grantee to take corrective action by imposing additional terms and conditions on an award. 49<br>
slide50. Allocation & Documentation Standard - Internal Controls An institution's financial management system must provide that no one person has complete control over all aspects of a financial transaction 50<br>
slide51. Example – Internal Control PI (also department chair) prepares TAR for PI’s travel and signs as traveler, PI and PI’s supervisor.
PI prepares travel reimbursement and reconciles departmental accounting records.
Is this appropriate? 51<br>
slide52. Answer No
This would be an unacceptable practice and would not meet the criteria of A-21
FSU’s signature requirements on accounting documents prevents an internal control violation such as this from occurring 52<br>
slide53. Allocation & Documentation Standard - Applicable Credits Applicable credits must be applied to related expenditures
Typical examples of applicable credits are: purchase discounts, rebates, or allowances; and adjustments of overpayments or erroneous charges 53<br>
slide54. Example – Applicable Credits Lab equipment was purchased in July 2011 for $2,000 on Dr. Gold’s R01 grant that ended September 30, 2011.
In September 2011 it was discovered that the vendor overcharged for the equipment by $500.
A credit was received and the department charged the credit to Dr. Gold’s P01 award because it was the only award open.
Is this appropriate? 54<br>
slide55. Answer The $500 credit should have been applied against Dr. Gold’s R01 grant that was closed
SRAS is supposed to receive all refund checks when related to sponsored projects
Department submits refund form that includes chartfield information where the original charge was posted
SRAS verifies chartfields to ensure the appropriate sponsored project is credited even if project is closed 55<br>
slide56. Limitations on Allowance of Costs Sponsored agreements may be subject to statutory requirements that limit allowance of costs
When maximum amount allowable under limitation is less than total amount allowed in A-21, amount not recoverable under sponsored agreement may not be charged to other sponsored agreements
Must be funded by a non-sponsored source of funds 56<br>
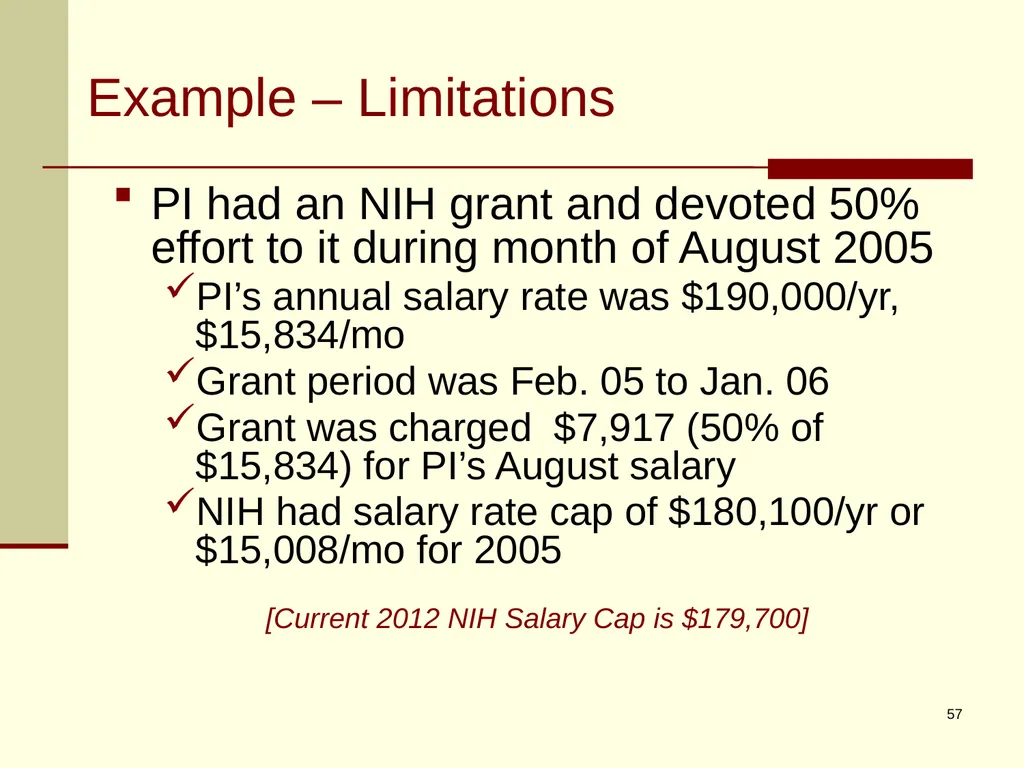
slide57. Example – Limitations PI had an NIH grant and devoted 50% effort to it during month of August 2005
PI’s annual salary rate was $190,000/yr, $15,834/mo
Grant period was Feb. 05 to Jan. 06
Grant was charged $7,917 (50% of $15,834) for PI’s August salary
NIH had salary rate cap of $180,100/yr or $15,008/mo for 2005
[Current 2012 NIH Salary Cap is $179,700] 57<br>
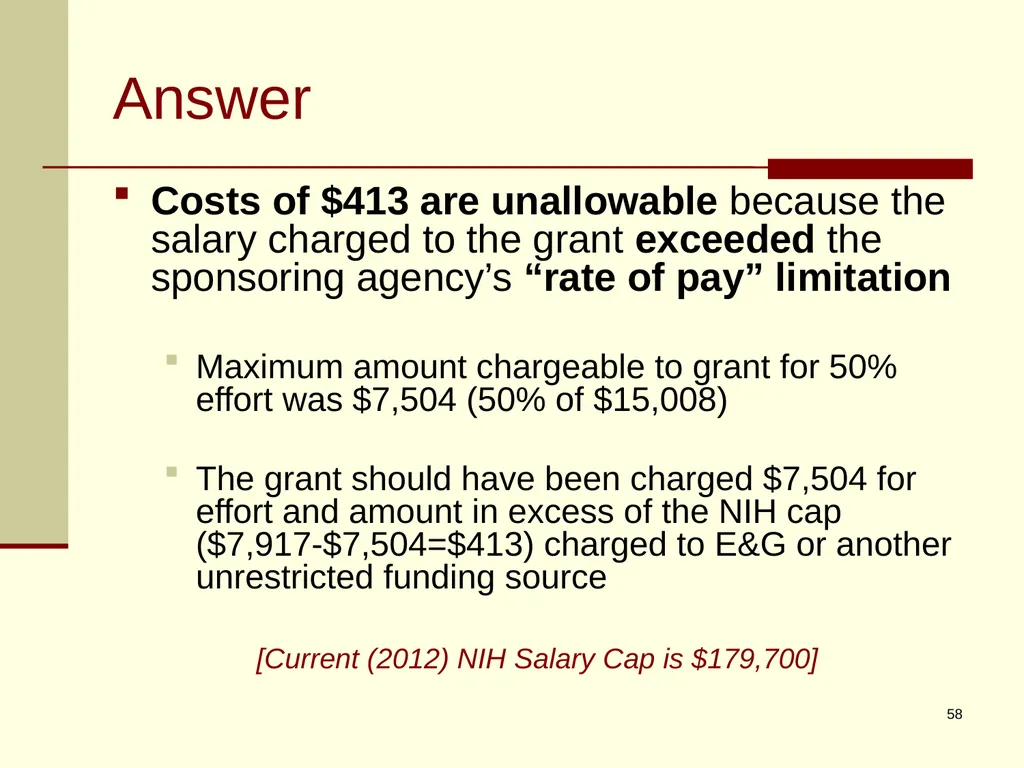
slide58. Answer Costs of $413 are unallowable because the salary charged to the grant exceeded the sponsoring agency’s “rate of pay” limitation
Maximum amount chargeable to grant for 50% effort was $7,504 (50% of $15,008)
The grant should have been charged $7,504 for effort and amount in excess of the NIH cap ($7,917-$7,504=$413) charged to E&G or another unrestricted funding source
[Current (2012) NIH Salary Cap is $179,700] 58<br>
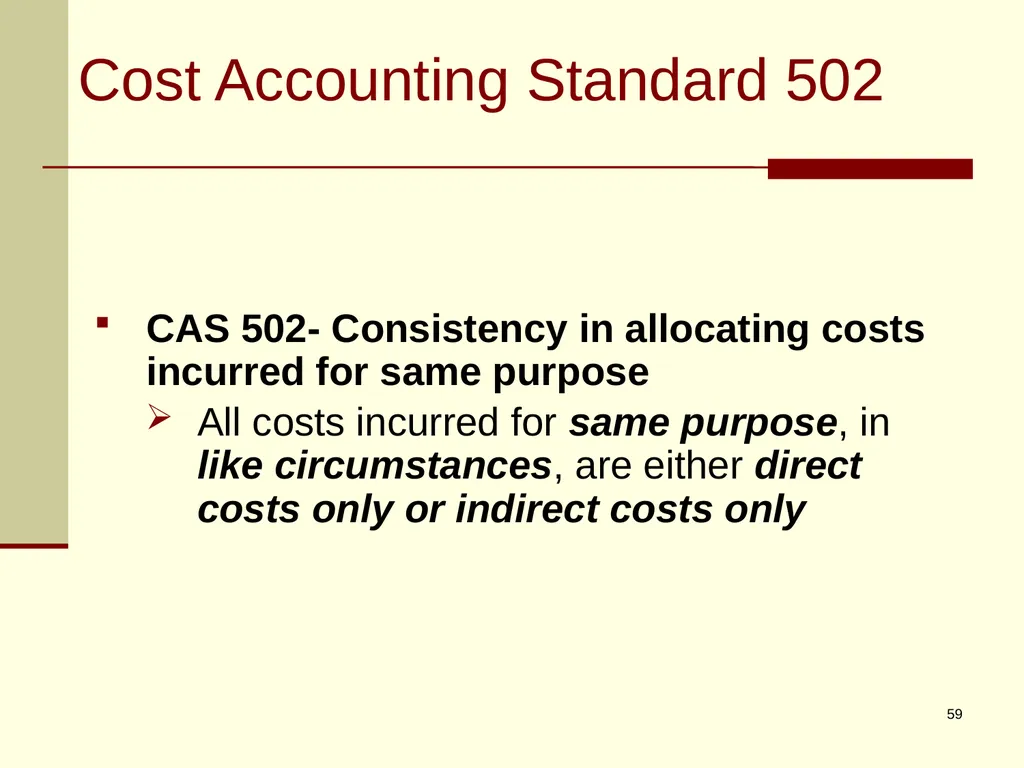
slide59. Cost Accounting Standard 502 CAS 502- Consistency in allocating costs incurred for same purpose
All costs incurred for same purpose, in like circumstances, are either direct costs only or indirect costs only 59<br>
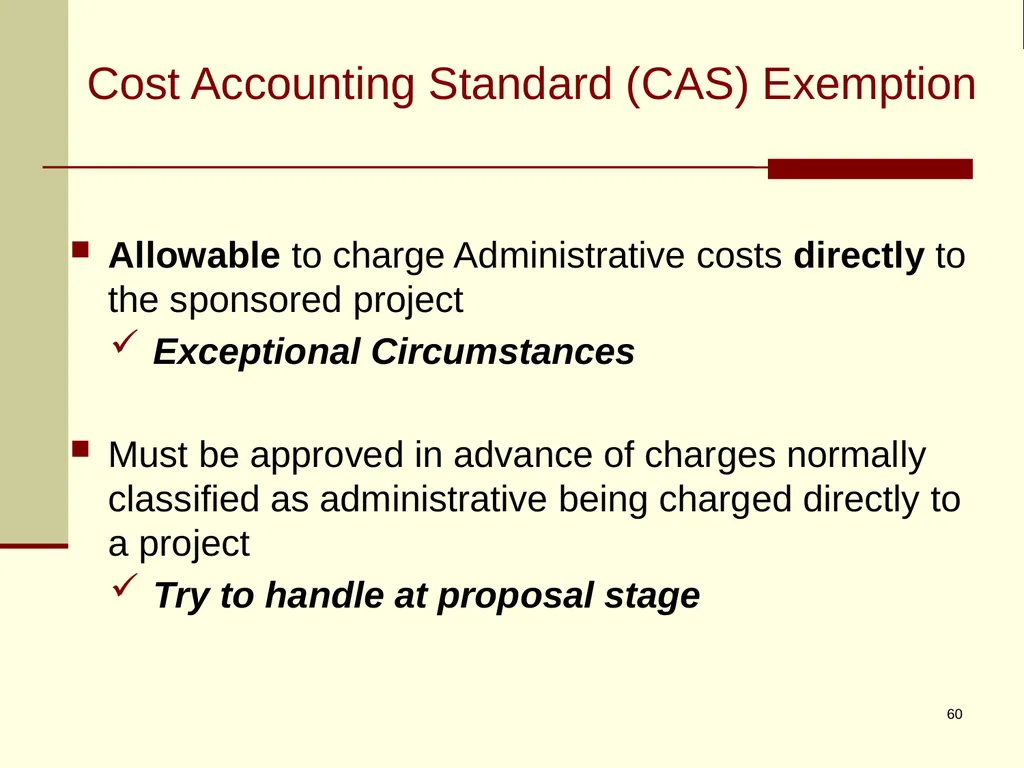
slide60. Cost Accounting Standard (CAS) Exemption Allowable to charge Administrative costs directly to the sponsored project
Exceptional Circumstances
Must be approved in advance of charges normally classified as administrative being charged directly to a project
Try to handle at proposal stage 60<br>
slide61. Exceptional Circumstances – Definition If the nature of a sponsored project requires an extensive amount of administrative and/or clerical support or goods/services significantly greater than the routine level provided by an academic department, then the effort is deemed an exceptional circumstance and such costs can be accounted for as direct 61<br>
slide62. Exceptional Circumstances – Other conditions required Be specifically identifiable to a particular sponsored project
Meet A-21 requirements for reasonableness, allowability and allocability
Be specified in the proposal budget and approved by the sponsoring agency 62<br>
slide63. Exceptional Circumstances - Documentation Requirements CAS Form
Complete and submit to SRS
Salaries:
Title(s), FTE, and salary amount(s) for the clerical/administrative position(s)
What it is about the scope of the project that requires this extensive effort
Other Costs (office supplies, memberships, postage, local telephone, cell phones, etc.):
Description and cost of supplies/services
What it is about the scope of the project that requires these goods/services to further the research or other sponsored activity 63<br>
slide64. Exceptional circumstances – Examples Large, complex programs, such as Clinical Research Centers, program projects, environmental research & engineering research centers & projects that entail assembling & managing teams of investigators from a number of institutions
Projects which involve extensive data accumulation, analysis & data entry, surveying, tabulation, cataloging, searching literature, & reporting, such as epidemiological studies & clinical records
Projects that require making travel & meeting arrangements for large numbers of participants, such as conferences and seminars 64<br>
slide65. Exceptional circumstances – Examples (cont’d) Projects whose principal focus is the preparation & production of manuals & large reports, books & monographs (excluding routine progress & technical reports).
Projects that are geographically inaccessible to normal departmental administrative services, such as seagoing research vessels, radio astronomy projects, & other research field sites that are remote from campus.
Individual projects requiring project-specific database management; individualized graphics or manuscript preparation; human or animal protocols; and multiple project-related investigator coordination and communications. 65<br>
slide66. Example - CAS Exemption Professor Washington is awarded a $5,000,000 (5 year) grant to coordinate Medical teams from all Florida universities to train medical professionals on new geriatric caretaking techniques. Training meetings are to be conducted 4 times per year at different locations across the state.
Professor Washington is requesting a CAS exemption for two administrative positions to coordinate the training teams, organize training conferences including travel arrangements for the University teams and to do outreach to the bring/entice the professionals to participate in the training. These positions were included in the budget approved by the agency.
Approve or Deny???? 66<br>
slide67. Example - CAS Exemption Professor Adams is awarded a $50,000 (1 year) grant to write and produce training materials for the US Dept of Education’s early childhood education program. The materials will be used to train childcare professionals.
Professor Adams is requesting a CAS exemption to charge $25,000 for printing/reproduction of 1,000 manuals. These costs were included in the budget approved by the agency.
Approve or Deny???? 67<br>
slide68. F&A Costs and Rate Agreement F&A costs defined as those incurred for common or joint objectives and, therefore, cannot be identified readily and specifically with a particular sponsored project, instructional activity, or any other institutional activity
F&A a.k.a. Overhead a.k.a. Indirect Costs
FSU negotiates F&A rates with the FSU’s cognitive agency – Department of Health and Human Services (DHHS) Division of Cost Allocation (DCA)
Negotiations culminate in a Rate Agreement at http://www.research.fsu.edu/contractsgrants/documents/rateagreement.pdf 68<br>
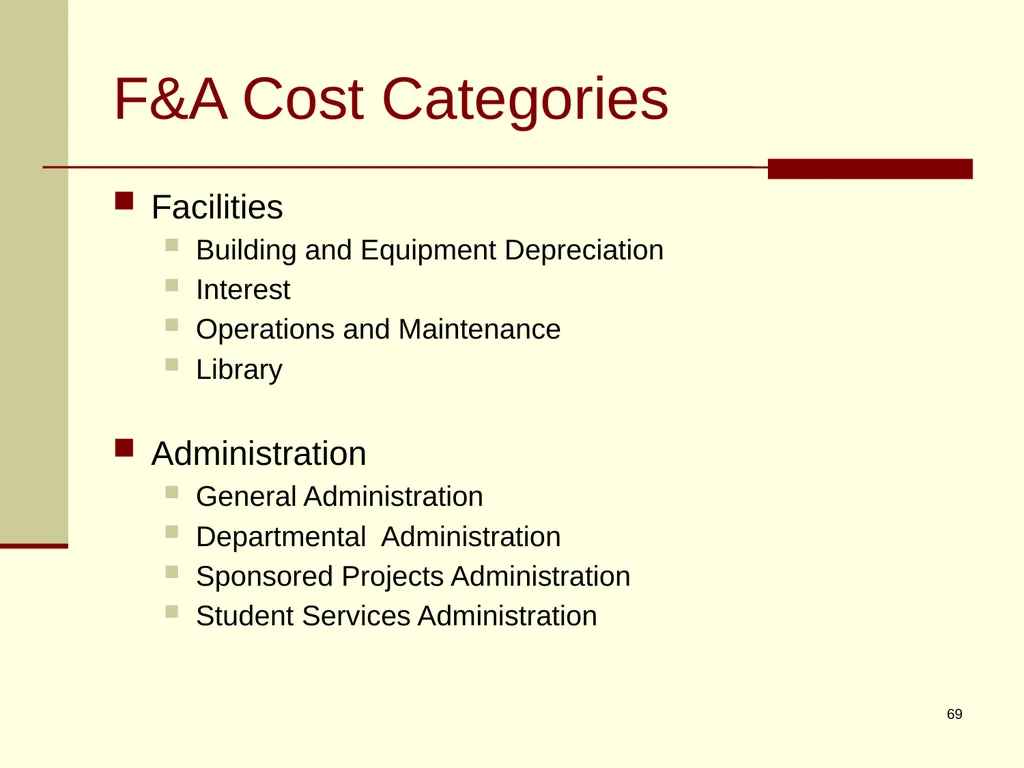
slide69. F&A Cost Categories Facilities
Building and Equipment Depreciation
Interest
Operations and Maintenance
Library
Administration
General Administration
Departmental Administration
Sponsored Projects Administration
Student Services Administration 69<br>
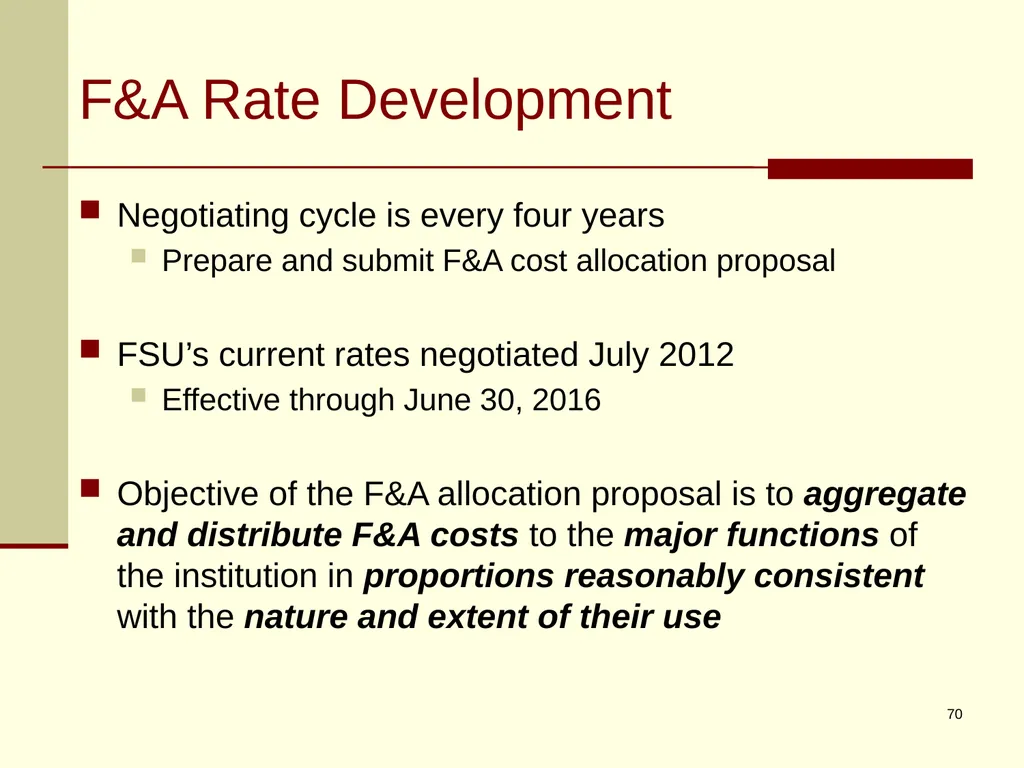
slide70. F&A Rate Development Negotiating cycle is every four years
Prepare and submit F&A cost allocation proposal
FSU’s current rates negotiated July 2012
Effective through June 30, 2016
Objective of the F&A allocation proposal is to aggregate and distribute F&A costs to the major functions of the institution in proportions reasonably consistent with the nature and extent of their use 70<br>
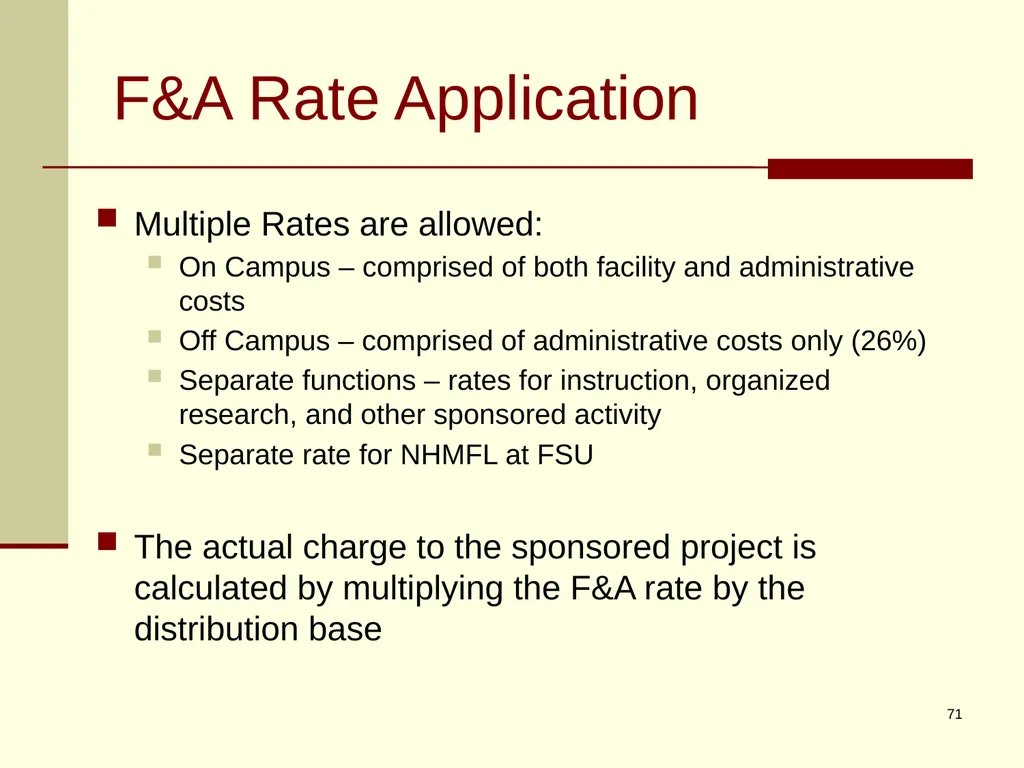
slide71. F&A Rate Application Multiple Rates are allowed:
On Campus – comprised of both facility and administrative costs
Off Campus – comprised of administrative costs only (26%)
Separate functions – rates for instruction, organized research, and other sponsored activity
Separate rate for NHMFL at FSU
The actual charge to the sponsored project is calculated by multiplying the F&A rate by the distribution base 71<br>
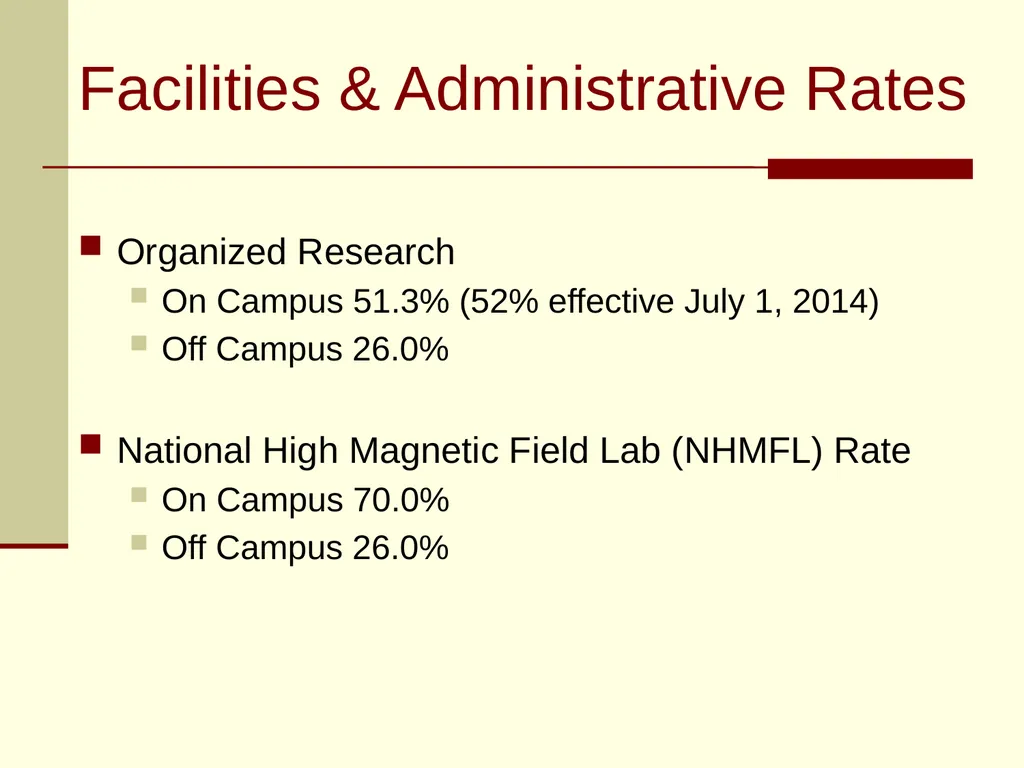
slide72. Facilities & Administrative Rates Organized Research
On Campus 51.3% (52% effective July 1, 2014)
Off Campus 26.0%
National High Magnetic Field Lab (NHMFL) Rate
On Campus 70.0%
Off Campus 26.0%<br>
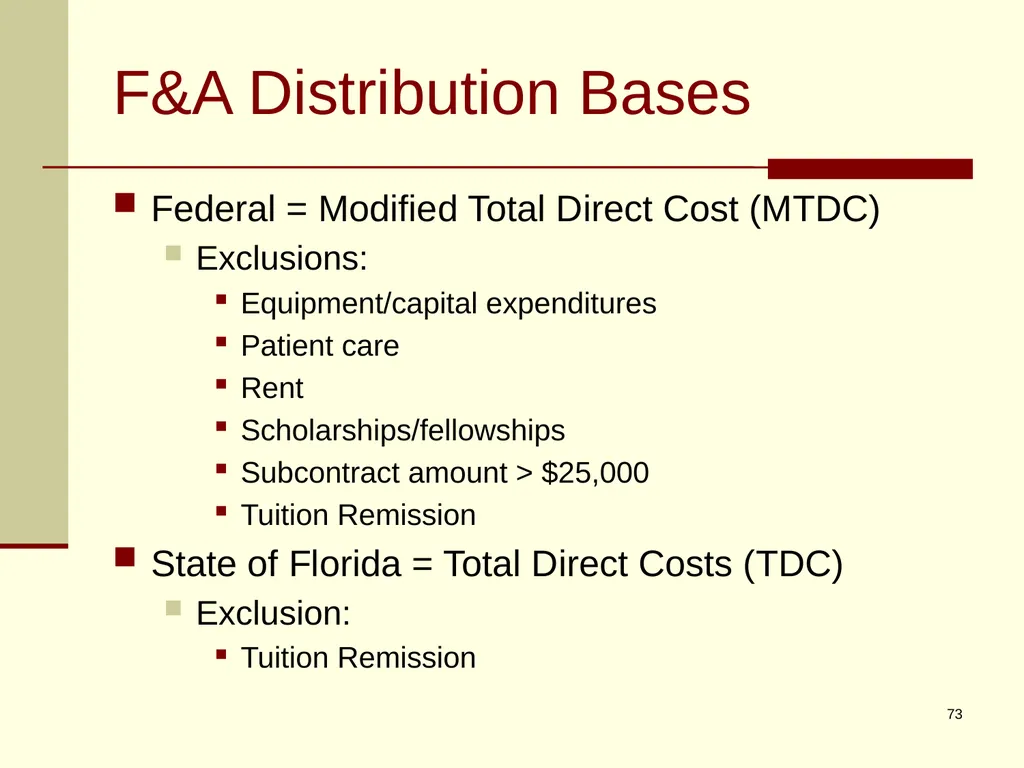
slide73. F&A Distribution Bases Federal = Modified Total Direct Cost (MTDC)
Exclusions:
Equipment/capital expenditures
Patient care
Rent
Scholarships/fellowships
Subcontract amount > $25,000
Tuition Remission
State of Florida = Total Direct Costs (TDC)
Exclusion:
Tuition Remission 73<br>
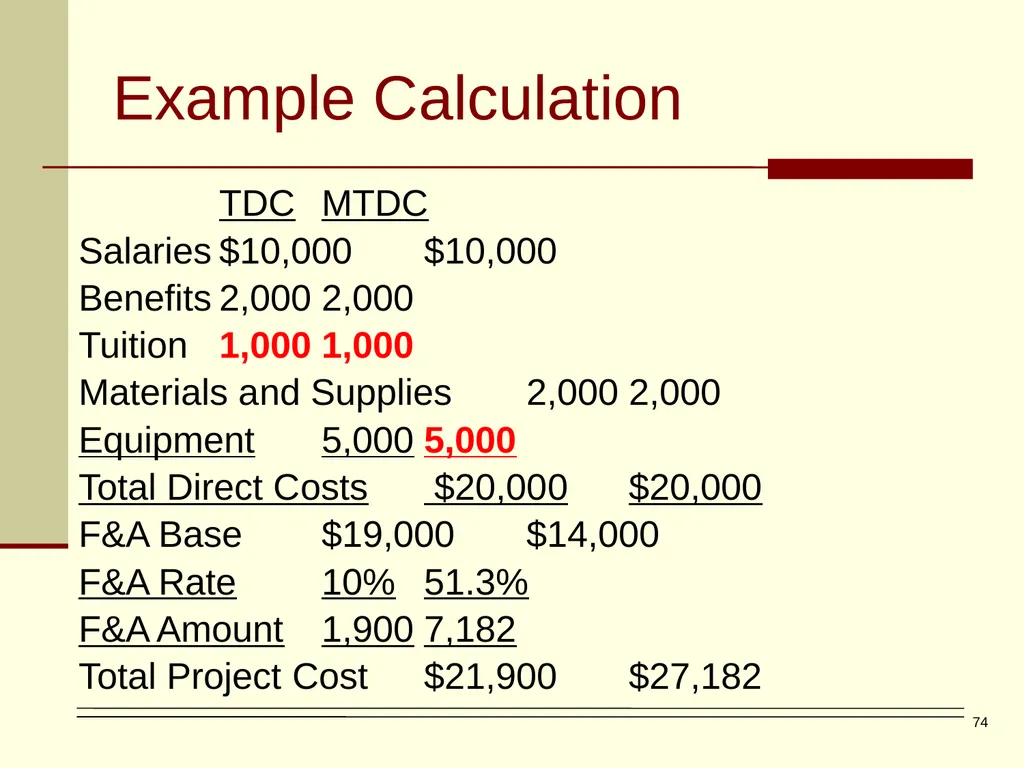
slide74. Example Calculation TDC MTDC
Salaries $10,000 $10,000
Benefits 2,000 2,000
Tuition 1,000 1,000
Materials and Supplies 2,000 2,000
Equipment 5,000 5,000
Total Direct Costs $20,000 $20,000
F&A Base $19,000 $14,000
F&A Rate 10% 51.3%
F&A Amount 1,900 7,182
Total Project Cost $21,900 $27,182 74<br>
slide75. F&A Costs Recovered The F&A costs recovered by the University from charges made to sponsored projects are placed into the Sponsored Research and Development (SRAD) Fund
Presentation on the SRAD recovery and distribution later 75<br>
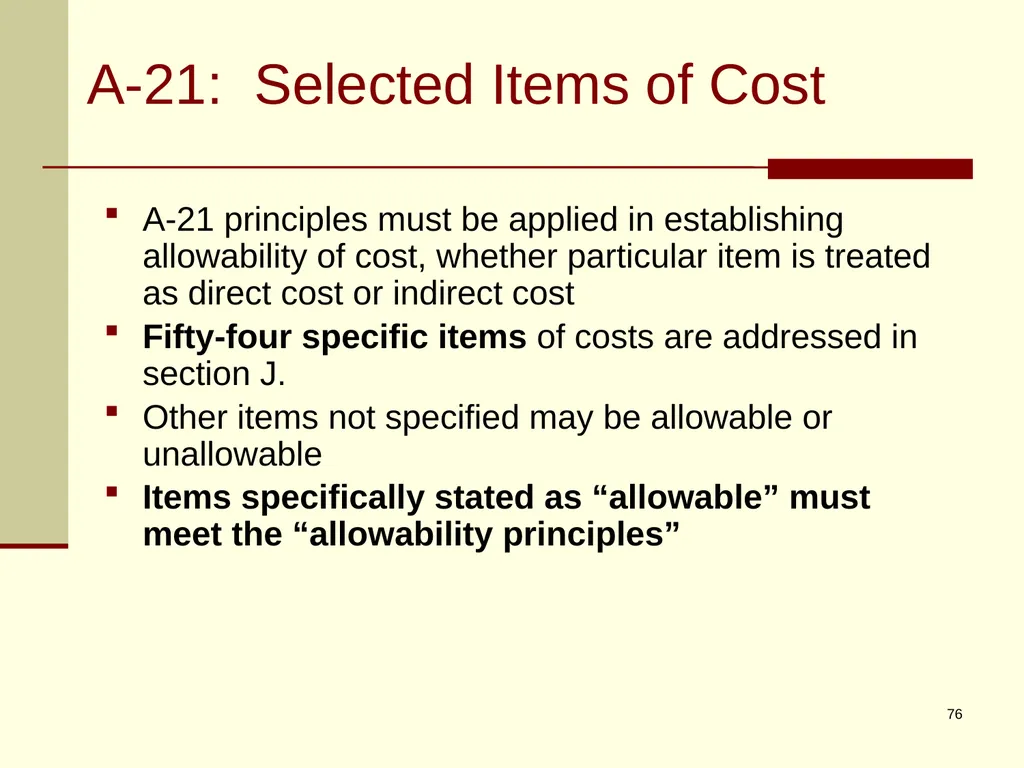
slide76. A-21: Selected Items of Cost A-21 principles must be applied in establishing allowability of cost, whether particular item is treated as direct cost or indirect cost
Fifty-four specific items of costs are addressed in section J.
Other items not specified may be allowable or unallowable
Items specifically stated as “allowable” must meet the “allowability principles” 76<br>
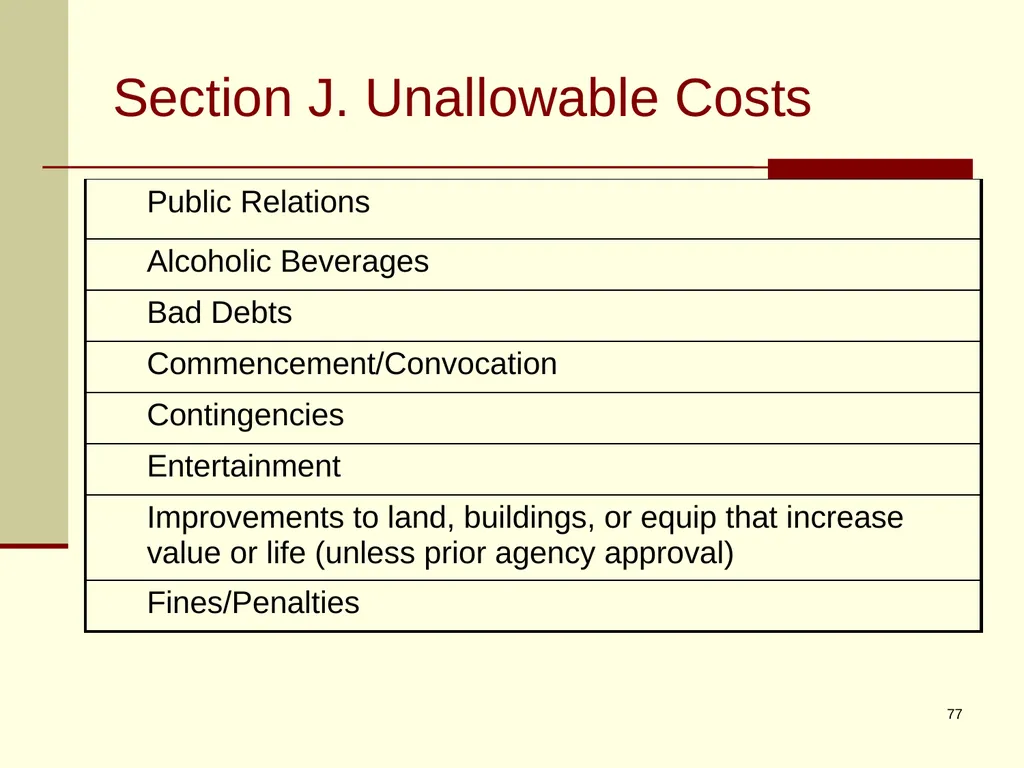
slide77. Section J. Unallowable Costs 77<br>
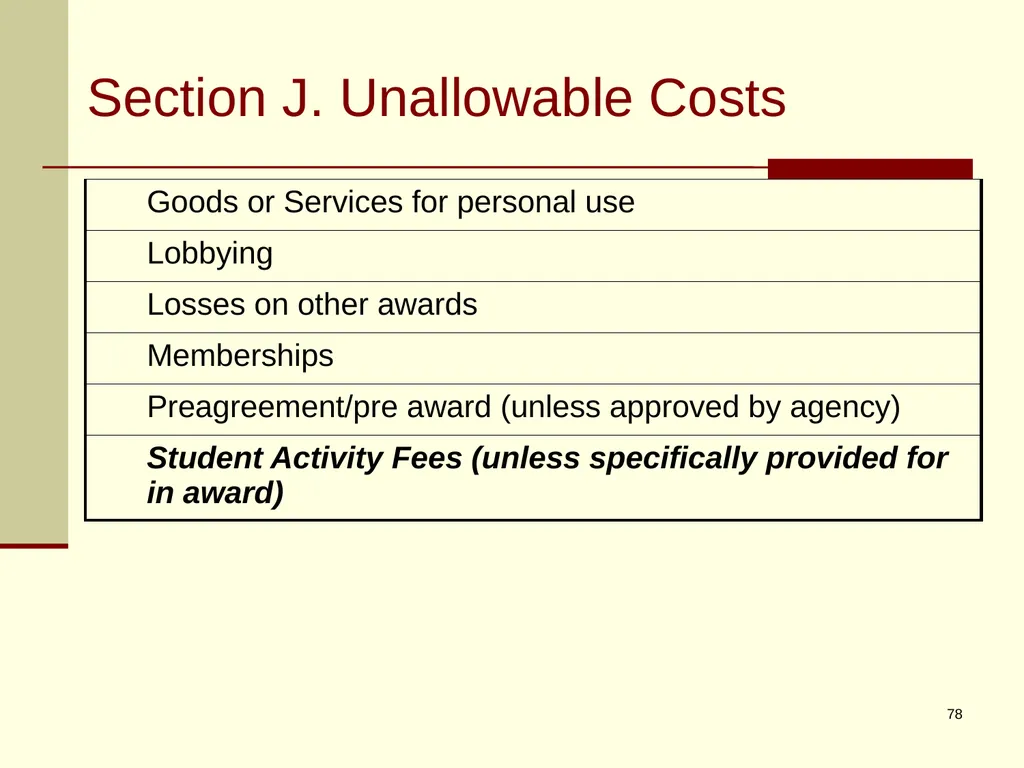
slide78. Section J. Unallowable Costs 78<br>
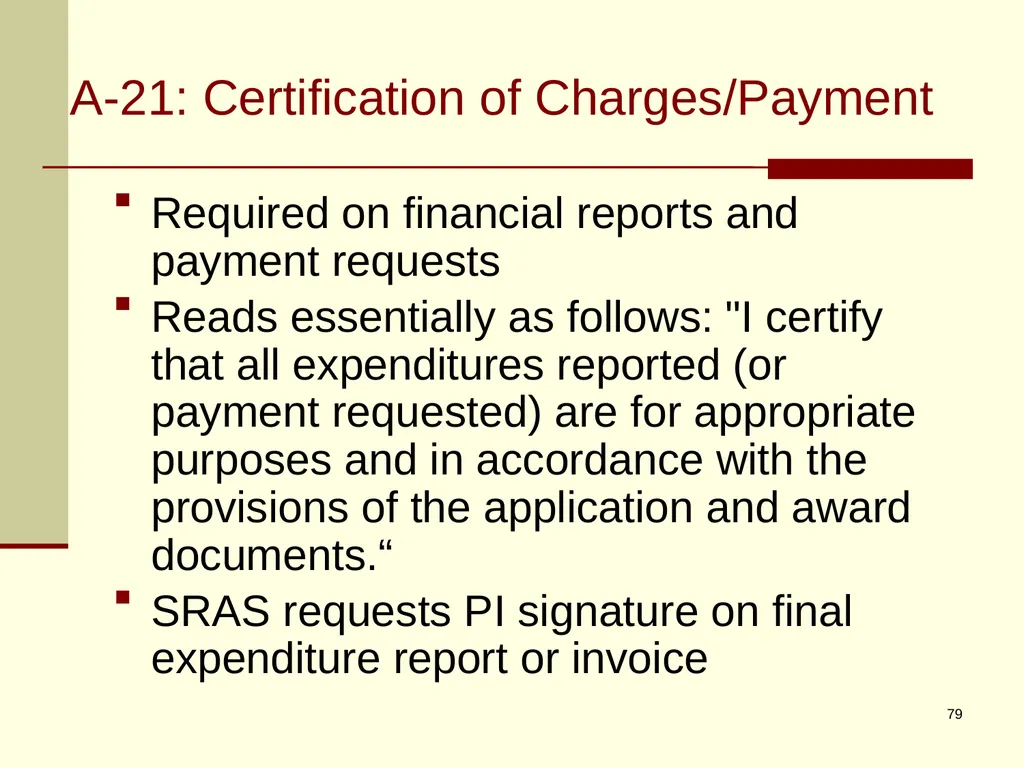
slide79. A-21: Certification of Charges/Payment Required on financial reports and payment requests
Reads essentially as follows: "I certify that all expenditures reported (or payment requested) are for appropriate purposes and in accordance with the provisions of the application and award documents.“
SRAS requests PI signature on final expenditure report or invoice 79<br>
slide80. QUESTIONS 80<br>
with educational institutions CReATE ver. 05/13 © 2013 Florida State University. All rights reserved<br>
slide2. OMB Circular A-21 THE PRIMARY ACCOUNTING REFERENCE FOR FEDERAL SPONSORED AGREEMENTS 2<br>
slide3. DHHS Audit Experience Entrance Conference December 6, 2010
Fieldwork December 6, 2010 – May 26, 2011
Exit Conference May 27, 2011
Draft report received from OIG November 16, 2011
Response to draft submitted January 31, 2012
Final report issued by DHHS OIG July 19, 2012
Response to final report submitted October 9, 2012
Audit Resolution Phase
Awaiting DHHS decision on what division will negotiate the final resolution with FSU 3<br>
slide4. A-21: A Brief History Originally issued in 1958
Significant changes made in 1996:
Raised threshold for capitalizing equipment to $5,000
Established use of Facilities & Administration (F&A) rate(s) in effect at start of sponsored agreement over life of agreement
Incorporated four Cost Accounting Standards (CAS)
Required educational institutions to submit a Disclosure Statement (DS-2) regarding cost accounting practices
Draft Super Circular issued
Combines 7 circulars into one document
COGR has issued draft response
Responses to OMB due June 2, 2013 4<br>
slide5. Why talk about OMB Circular A-21? SRS and SRAS employees need to refer to OMB Circulars A-21 and A-110 (next presentation) on a daily basis
Every decision on federally funded agreements is guided by these pronouncements 5<br>
slide6. A-21: Applicability To all research and development, training and other work funded with federal funds at educational institutions
Principles used only as guide in pricing of fixed price or lump sum agreements
The Proposal budget on a fixed price agreement is subject to audit for compliance with A-21
Basis for requiring a detailed budget on a fixed price award
Actual expenditures on a fixed price agreement are not subject to audit 6<br>
slide7. Major Functions Instruction
Teaching and training activities
Not research training
Departmental research
Not organized research
Not separately budgeted
Not considered major function
Organized Research
Research and development activities
Separately budgeted
Includes research training 7<br>
slide8. Major Functions Other Sponsored Activities
Programs and projects that are service oriented
Not instruction or organized research
Examples
Head Start program
WFSU activities
Other Institutional Activities
All activities not otherwise classified
Dorms
Dining facilities
F&A costs
Specialized Service Facilities 8<br>
slide9. A-21: Direct Costs Can be identified specifically with a particular sponsored project, an instructional activity, or any other institutional activity, or can be directly assigned to such activities relatively easily with a high degree of accuracy
Where an institution treats a particular type of cost as direct cost of sponsored agreements, all costs incurred for same purpose in like circumstances must be treated as direct costs of all institutional activities 9<br>
slide10. Direct Costs – Personnel Costs Salaries and fringe benefits
Faculty and other non administrative/clerical and student employees working on the sponsored project
Job titles (not all inclusive)
Researcher
Lab Assistant/Researcher
Graduate Research Assistant 10<br>
slide11. Direct Costs – Non Personnel Other direct costs:
Animals
Animal care
Audio-visual supplies (chemicals, glassware, etc.)
Books and periodicals
Specialized & technical svcs
Consulting services
Lab equipment & equipment maintenance
Computer equipment and supplies - research purpose
Laboratory supplies
Long distance telephone
Publication costs
Rent & other off-campus facilities costs
Scientific reprints
Subawards
Travel
Tuition 11<br>
slide12. Facilities & Administrative (F&A) Costs Costs incurred for common or joint objectives and, therefore, cannot be identified readily and specifically with a particular sponsored project, instructional activity, or any other institutional activity 12<br>
slide13. Computer Purchases Deemed to be “general purpose equipment” per A-21 J18a(4)
Generally unallowable as direct charges (J18b(1))
Requires approval in advance by awarding agency
Refer to guidance issued in June 2012
http://www.research.fsu.edu/contractsgrants/documents/ITguide.pdf
Included in proposal – adequate justification
Not included in proposal – seek approval
Prior to purchase 13<br>
slide14. A-21: Cost Accounting Standards CAS 501- Consistency in estimating, accumulating and reporting costs
Basis used in estimating costs in proposal budget, charging costs to sponsored agreement and reporting costs to sponsor must be consistent with one another
CAS 502- Consistency in allocating costs incurred for same purpose
All costs incurred for same purpose, in like circumstances, are either direct costs only or indirect costs only 14<br>
slide15. A-21: Cost Accounting Standards CAS 505 - Accounting for unallowable costs
Unallowable costs must be identified in accounting system or identifiable from departmental records
CAS 506 - Cost accounting period
FSU’s fiscal year – July 1, xxxx – June 30, xxxx 15<br>
slide16. A-21: Disclosure Statement Large educational institutions
$25 million per year or more in federally funded awards
To cognitive agency (DHHS) for review and approval
FSU Disclosure Statement (DS-2) History
Submitted – June 1998
FSU submitted revisions – September 2006, April 2009 and January 2010
Received approval March 2010
Revised capitalization threshold to $5,000 approved with most recent negotiated F&A rate agreement in July 2012 16<br>
slide17. Key FSU Practices Accounting system description: cash basis
Cost accounting period: 7/1 to 6/30
Capitalization of non-expendable tangible personal property
$5,000/useful life greater than one year
Treatment of costs – direct and indirect declared 17<br>
slide18. FSU Policies Related to DS-2 Issued a policy on Direct and Indirect Costs of Sponsored Agreements
Issued a policy on Cost Sharing
Issued a policy on Unallowable Costs of Federally Sponsored Projects
Policies can be found on Sponsored Research Web site ( http://www.research.fsu.edu ) 18<br>
slide19. A-21 Cost Principles Allowability Factors
Reasonableness
Allocability
Consistency of treatment
Conformity to limitations or exclusions 19<br>
slide20. Reasonableness 1 - Reasonable
Prudent person would have paid the stated amount for the goods/services
Cost necessary to accomplish objectives of sponsored award
Restraints or requirements imposed by arm’s-length bargaining/Federal & State laws/sponsored award terms & conditions
Due prudence
Consistent with institutional policies 20<br>
slide21. Researcher requesting reimbursement for purchase of 1,000 pipette tips from vendor with no price agreement with FSU and paid for with personal credit card. Price paid $.50/tip vs. eMarket vendor cost = $.10/tip.
Travel by researcher to Washington to discuss technical issue on sponsored project with sponsoring agency’s program manager. Researcher followed FSU travel rules.
Lunch for researcher and department chair at Governor’s Club to discuss courses for next semester. 21 Examples<br>
slide22. Answers Not reasonable – did not follow institutional policies
Reasonable – meets criteria
Not reasonable – not research purpose 22<br>
slide23. Allocability 2 - Allocable
Goods or services involved can be charged in accordance with relative benefits received
Identifiable to a sponsored award
Incurred solely to advance work under sponsored agreement
Benefits more than one sponsored project or other institutional activity, the cost must be shared
Necessary for operation of sponsored and/or other institutional activity 23<br>
slide24. Allocability Equipment specifically authorized under sponsored agreement, is assignable to sponsored agreement regardless of any use that may subsequently be made 24<br>
slide25. Allocability - Lab Manager In multi award lab general duties must be allocated across awards on a reasonable basis. Examples,
Training of students, other researchers in lab protocols and procedures
Animal care that may not be specific to one project
Performing or supervising others in the preparation of experiments, equipment maintenance, and lab inventory
Staying abreast of animal care developments 25<br>
slide26. Example – Lab Manager Dr. Gold performs retinal research with zebra fish on 2 R01 NIH awards and conducts some departmental research.
Ms. Seminole trains all students in lab techniques and protocols (10%), orders supplies for the lab (5%), cares for the fish colonies (25%), performs experiments assigned by Dr. Gold (60%)
How allocate? 26<br>
slide27. Answer 40% general duties
Both R01 grants
Non sponsored source for the departmental research
% as determined by Dr. Gold
60% directly related to performing experiments allocated (Dr. Gold estimate) 27<br>
slide28. Example – Salary Charges Research associate’s salary for month of July 2008 charged to sponsored project for actual work performed on project in January 2008
Research associate’s effort in July 2008 did not pertain to sponsored project
Sponsored project period was 1/1/08 to 12/31/08 28<br>
slide29. Answer Charge is unallowable because research associate’s effort in July did not benefit sponsored project
This practice is referred to as “cost substitution” and does not conform to A-21 requirements 29<br>
slide30. Allocability – General Lab Supplies In multi award lab general lab supplies (pipettes, gloves, etc.) must be allocated across awards on a reasonable basis. Considerations,
Can/will items be used by all awards in lab? Specialized items?
Is item used for general lab upkeep?
What are the lab supply and ordering practices?
Is there non sponsored research occurring in the lab?
Length of awards using items?
What type of experiments are being conducted? 30<br>
slide31. Example – General Lab Supplies Dr. Tomahawk performs sense of smell research with rats and has 1 R01 NIH and 2 NSF grants all in the same lab. The aims do not overlap but all of the grants use similar research techniques and equipment.
The lab manager requests for purchase 5000 pipette tips ($500), 300 glass test tubes ($150) and 1 gustometer ($6,000) that will be used only on the R01 award.
How should the items purchased be charged to each award? 31<br>
slide32. Answer 1 The pipette tips and test tubes should be allocated to all awards:
PI estimate % of usage on each award
Charge 100% of gustometer to the R01 award. 32<br>
slide33. Answer 2 Each researcher works on only 1 award and requests supplies from lab manager monthly:
Grad Student A (R01) 2000 pipette tips = $200
Grad Student B (NSF A) 2000 pipette tips 200 test tubes = $300
Grad Student C (NSF B) 1000 pipette tips and 100 test tubes = $150
Charge 100% of gustometer to the R01 award = $6,000 33<br>
slide34. Allocability – Service Agreements In multi award lab service agreements for equipment must be allocated across awards on a reasonable basis. Considerations,
When was the equipment purchased? Source of funding? Source active?
What is the equipment used for? What projects require the use of the equipment for the svc agmt period
Is there non sponsored research occurring in the lab?
Length of awards using items?
What type of experiments are being conducted? 34<br>
slide35. Example – Service Agreement Dr. Tomahawk performs sense of smell research with rats and has 1 R01 NIH (ends 6/30/2012) and 2 NSF grants (both end 12/31/2013) all in the same lab. The aims do not overlap but all of the grants use similar research techniques and equipment.
There are 5 centrifuges in the lab. The R01 uses the 3 large centrifuges and the 2 NSF awards use the 2 smaller ones with equal usage.
Each service agreement costs $500 for period 1/1/2012-12/31/2012
How should the service agreements’ costs be charged to each award? 35<br>
slide36. Answer R01 = $750
NSF A = $500
NSF B = $500
Non sponsored source = $750
Total = $2,500
Note rotation among awards generally not acceptable method 36<br>
slide37. Example – Equipment Dr. Garnett purchased a microscope costing $10,000 on an NSF-funded project during last month of a one-year grant period. The microscope has a 5 year life.
The microscope was included in the budget approved by the agency.
The equipment was required to complete the analysis phase of research. 37<br>
slide38. Answer Charge for this equipment is allowable as it was purchased during grant period.
Even though equipment had five year useful life and was used only one month of grant period, it conforms to A-21 provision
“specifically authorized in grant… regardless of subsequent use”. 38<br>
slide39. Allocability – Cost Transfer Policy Effective April 1, 2008; revised July 1, 2010
http://www.research.fsu.edu/contractsgrants/documents/costtranspolicy.pdf
Expenditure transfers to or between sponsored projects
Red flags
Frequent transfers
Transfers close to end of project
Inadequate documentation to support transfer 39<br>
slide40. Cost Transfers Improper cost transfers
Cover overruns
Spend available balance close to end of project
Transfer of unallowable cost from one project to another
Circumvention of award limitation/restriction
Charge costs to one project that belong to an award not yet executed
Advance policy enacted for this reason! 40<br>
slide41. Cost Transfers Allowable transfers
Correct erroneous charge
Allocate portion of charge that applies to the project (e.g. split purchases)
Cost Transfer Justification Form at http://www.research.fsu.edu/contractsgrants/forms.html
Must be received by SRAS as follows:
Within 90 calendar days from the end of the month in which the error occurred (personnel and non-personnel)
Retroactive Distribution of Funding
Moving salary between or onto projects reallocating original ePAF distribution as a result of the effort certified is acceptable justification for salary cost transfers 41<br>
slide42. Cost Transfers Cost transfers not received by SRAS by deadline will only be approved in extenuating circumstances, which does not include:
Absences of PI or project administrators
Non qualified staff
Shortage of staff
SRAS Compliance Committee reviews on weekly basis
SRAS Director approves >$25,000 or > 90 days
Monthly reconciliations needed to detect and correct errors within established timeframes
Controller’s Office offers training:
BTFA03 - General Ledger Reconciliation 42<br>
slide43. Cost Transfers Justifications – what not to say!
“Charged to NSF grant waiting for NIH grant to get set up.”
“Reconciliations were not performed for 6 months because of support staff turnover.”
“There are funds left on Project Aaa and we want to spend the balance. We charged the costs to Project Bee but now that there is funding left so we need to move the costs.” 43<br>
slide44. Example – Cost Transfers A graduate assistant worked and was paid 50% on grant from US Dept. of Agriculture (USDA) and 50% on grant from National Science Foundation (NSF). Each grant was charged 50% of tuition. Since USDA policy does not permit charges for tuition, the PI requested that the tuition charge be transferred from USDA account to NSF account.
Would you approve this cost transfer?? Why or Why not?? 44<br>
slide45. Answer Tuition charge transferred to NSF account is unallowable because
Charge to NSF grant (now at 100%) was not proportional to effort devoted to NSF grant (50%)
Transfer was made to avoid restriction of USDA policy. 45<br>
slide46. Example – Cost Transfers At the start of Fall 2011 semester, Dr. Nole was appointed as follows:
E&G funding = 65%
NIH P01 award = 20%
NSF award = 15%
Dr. Nole certified his Fall 2011 effort report as follows:
E&G funding = 65%
NIH P01 award = 15% (Error occurred <20% paid)
NSF award = 20%
How do we resolve the effort error?? 46<br>
slide47. Answer An RDF is required to move 5% from the NIH to the NSF award.
Allowable because it “trues” up to actual
Meets time criterion because as a result of actual effort
Requesting the PI to change his/her effort certification “to get rid of the error” IS NOT the solution!!!! 47<br>
slide48. Cost Transfers - NIH Policy The NIH Grants Policy Statement
Cost Transfers to NIH grants by grantees…should be accomplished within 90 days…
Transfers must be supported by documentation that fully explains how error occurred and certification of correctness of new charge by responsible University official …
Stating that transfer was made “to correct error” or “to transfer to correct project” is not sufficient.
Transfers of costs solely to cover cost overruns are not allowable. 48<br>
slide49. Cost Transfers - NIH policy Grantee’s must maintain prescribed documentation of cost transfers and must make it available for audit…
Frequent errors in recording costs may indicate need for accounting system improvements and/or enhanced internal controls.
If such errors occur, grantees are encouraged to evaluate need for improvements and to make whatever improvements are deemed necessary to prevent reoccurrence.
NIH also may require a grantee to take corrective action by imposing additional terms and conditions on an award. 49<br>
slide50. Allocation & Documentation Standard - Internal Controls An institution's financial management system must provide that no one person has complete control over all aspects of a financial transaction 50<br>
slide51. Example – Internal Control PI (also department chair) prepares TAR for PI’s travel and signs as traveler, PI and PI’s supervisor.
PI prepares travel reimbursement and reconciles departmental accounting records.
Is this appropriate? 51<br>
slide52. Answer No
This would be an unacceptable practice and would not meet the criteria of A-21
FSU’s signature requirements on accounting documents prevents an internal control violation such as this from occurring 52<br>
slide53. Allocation & Documentation Standard - Applicable Credits Applicable credits must be applied to related expenditures
Typical examples of applicable credits are: purchase discounts, rebates, or allowances; and adjustments of overpayments or erroneous charges 53<br>
slide54. Example – Applicable Credits Lab equipment was purchased in July 2011 for $2,000 on Dr. Gold’s R01 grant that ended September 30, 2011.
In September 2011 it was discovered that the vendor overcharged for the equipment by $500.
A credit was received and the department charged the credit to Dr. Gold’s P01 award because it was the only award open.
Is this appropriate? 54<br>
slide55. Answer The $500 credit should have been applied against Dr. Gold’s R01 grant that was closed
SRAS is supposed to receive all refund checks when related to sponsored projects
Department submits refund form that includes chartfield information where the original charge was posted
SRAS verifies chartfields to ensure the appropriate sponsored project is credited even if project is closed 55<br>
slide56. Limitations on Allowance of Costs Sponsored agreements may be subject to statutory requirements that limit allowance of costs
When maximum amount allowable under limitation is less than total amount allowed in A-21, amount not recoverable under sponsored agreement may not be charged to other sponsored agreements
Must be funded by a non-sponsored source of funds 56<br>
slide57. Example – Limitations PI had an NIH grant and devoted 50% effort to it during month of August 2005
PI’s annual salary rate was $190,000/yr, $15,834/mo
Grant period was Feb. 05 to Jan. 06
Grant was charged $7,917 (50% of $15,834) for PI’s August salary
NIH had salary rate cap of $180,100/yr or $15,008/mo for 2005
[Current 2012 NIH Salary Cap is $179,700] 57<br>
slide58. Answer Costs of $413 are unallowable because the salary charged to the grant exceeded the sponsoring agency’s “rate of pay” limitation
Maximum amount chargeable to grant for 50% effort was $7,504 (50% of $15,008)
The grant should have been charged $7,504 for effort and amount in excess of the NIH cap ($7,917-$7,504=$413) charged to E&G or another unrestricted funding source
[Current (2012) NIH Salary Cap is $179,700] 58<br>
slide59. Cost Accounting Standard 502 CAS 502- Consistency in allocating costs incurred for same purpose
All costs incurred for same purpose, in like circumstances, are either direct costs only or indirect costs only 59<br>
slide60. Cost Accounting Standard (CAS) Exemption Allowable to charge Administrative costs directly to the sponsored project
Exceptional Circumstances
Must be approved in advance of charges normally classified as administrative being charged directly to a project
Try to handle at proposal stage 60<br>
slide61. Exceptional Circumstances – Definition If the nature of a sponsored project requires an extensive amount of administrative and/or clerical support or goods/services significantly greater than the routine level provided by an academic department, then the effort is deemed an exceptional circumstance and such costs can be accounted for as direct 61<br>
slide62. Exceptional Circumstances – Other conditions required Be specifically identifiable to a particular sponsored project
Meet A-21 requirements for reasonableness, allowability and allocability
Be specified in the proposal budget and approved by the sponsoring agency 62<br>
slide63. Exceptional Circumstances - Documentation Requirements CAS Form
Complete and submit to SRS
Salaries:
Title(s), FTE, and salary amount(s) for the clerical/administrative position(s)
What it is about the scope of the project that requires this extensive effort
Other Costs (office supplies, memberships, postage, local telephone, cell phones, etc.):
Description and cost of supplies/services
What it is about the scope of the project that requires these goods/services to further the research or other sponsored activity 63<br>
slide64. Exceptional circumstances – Examples Large, complex programs, such as Clinical Research Centers, program projects, environmental research & engineering research centers & projects that entail assembling & managing teams of investigators from a number of institutions
Projects which involve extensive data accumulation, analysis & data entry, surveying, tabulation, cataloging, searching literature, & reporting, such as epidemiological studies & clinical records
Projects that require making travel & meeting arrangements for large numbers of participants, such as conferences and seminars 64<br>
slide65. Exceptional circumstances – Examples (cont’d) Projects whose principal focus is the preparation & production of manuals & large reports, books & monographs (excluding routine progress & technical reports).
Projects that are geographically inaccessible to normal departmental administrative services, such as seagoing research vessels, radio astronomy projects, & other research field sites that are remote from campus.
Individual projects requiring project-specific database management; individualized graphics or manuscript preparation; human or animal protocols; and multiple project-related investigator coordination and communications. 65<br>
slide66. Example - CAS Exemption Professor Washington is awarded a $5,000,000 (5 year) grant to coordinate Medical teams from all Florida universities to train medical professionals on new geriatric caretaking techniques. Training meetings are to be conducted 4 times per year at different locations across the state.
Professor Washington is requesting a CAS exemption for two administrative positions to coordinate the training teams, organize training conferences including travel arrangements for the University teams and to do outreach to the bring/entice the professionals to participate in the training. These positions were included in the budget approved by the agency.
Approve or Deny???? 66<br>
slide67. Example - CAS Exemption Professor Adams is awarded a $50,000 (1 year) grant to write and produce training materials for the US Dept of Education’s early childhood education program. The materials will be used to train childcare professionals.
Professor Adams is requesting a CAS exemption to charge $25,000 for printing/reproduction of 1,000 manuals. These costs were included in the budget approved by the agency.
Approve or Deny???? 67<br>
slide68. F&A Costs and Rate Agreement F&A costs defined as those incurred for common or joint objectives and, therefore, cannot be identified readily and specifically with a particular sponsored project, instructional activity, or any other institutional activity
F&A a.k.a. Overhead a.k.a. Indirect Costs
FSU negotiates F&A rates with the FSU’s cognitive agency – Department of Health and Human Services (DHHS) Division of Cost Allocation (DCA)
Negotiations culminate in a Rate Agreement at http://www.research.fsu.edu/contractsgrants/documents/rateagreement.pdf 68<br>
slide69. F&A Cost Categories Facilities
Building and Equipment Depreciation
Interest
Operations and Maintenance
Library
Administration
General Administration
Departmental Administration
Sponsored Projects Administration
Student Services Administration 69<br>
slide70. F&A Rate Development Negotiating cycle is every four years
Prepare and submit F&A cost allocation proposal
FSU’s current rates negotiated July 2012
Effective through June 30, 2016
Objective of the F&A allocation proposal is to aggregate and distribute F&A costs to the major functions of the institution in proportions reasonably consistent with the nature and extent of their use 70<br>
slide71. F&A Rate Application Multiple Rates are allowed:
On Campus – comprised of both facility and administrative costs
Off Campus – comprised of administrative costs only (26%)
Separate functions – rates for instruction, organized research, and other sponsored activity
Separate rate for NHMFL at FSU
The actual charge to the sponsored project is calculated by multiplying the F&A rate by the distribution base 71<br>
slide72. Facilities & Administrative Rates Organized Research
On Campus 51.3% (52% effective July 1, 2014)
Off Campus 26.0%
National High Magnetic Field Lab (NHMFL) Rate
On Campus 70.0%
Off Campus 26.0%<br>
slide73. F&A Distribution Bases Federal = Modified Total Direct Cost (MTDC)
Exclusions:
Equipment/capital expenditures
Patient care
Rent
Scholarships/fellowships
Subcontract amount > $25,000
Tuition Remission
State of Florida = Total Direct Costs (TDC)
Exclusion:
Tuition Remission 73<br>
slide74. Example Calculation TDC MTDC
Salaries $10,000 $10,000
Benefits 2,000 2,000
Tuition 1,000 1,000
Materials and Supplies 2,000 2,000
Equipment 5,000 5,000
Total Direct Costs $20,000 $20,000
F&A Base $19,000 $14,000
F&A Rate 10% 51.3%
F&A Amount 1,900 7,182
Total Project Cost $21,900 $27,182 74<br>
slide75. F&A Costs Recovered The F&A costs recovered by the University from charges made to sponsored projects are placed into the Sponsored Research and Development (SRAD) Fund
Presentation on the SRAD recovery and distribution later 75<br>
slide76. A-21: Selected Items of Cost A-21 principles must be applied in establishing allowability of cost, whether particular item is treated as direct cost or indirect cost
Fifty-four specific items of costs are addressed in section J.
Other items not specified may be allowable or unallowable
Items specifically stated as “allowable” must meet the “allowability principles” 76<br>
slide77. Section J. Unallowable Costs 77<br>
slide78. Section J. Unallowable Costs 78<br>
slide79. A-21: Certification of Charges/Payment Required on financial reports and payment requests
Reads essentially as follows: "I certify that all expenditures reported (or payment requested) are for appropriate purposes and in accordance with the provisions of the application and award documents.“
SRAS requests PI signature on final expenditure report or invoice 79<br>
slide80. QUESTIONS 80<br>