
PRINCIPLES OF ISLAMIC BANKING Mustafa Dereci Group







Description: PRINCIPLES OF ISLAMIC BANKING Mustafa Dereci Group Manager Retail and Business Banking Marketing and Product Development OCTOBER 2011 CALIBRI BOLD 42 pt Islamic Economy and Other Practices What is economics? To utilize the limited
Related Topics
Download Presentation
"PRINCIPLES OF ISLAMIC BANKING Mustafa Dereci Group" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. PRINCIPLES OF ISLAMIC BANKING
Mustafa Dereci
Group Manager
Retail and Business Banking Marketing and Product Development OCTOBER 2011<br>
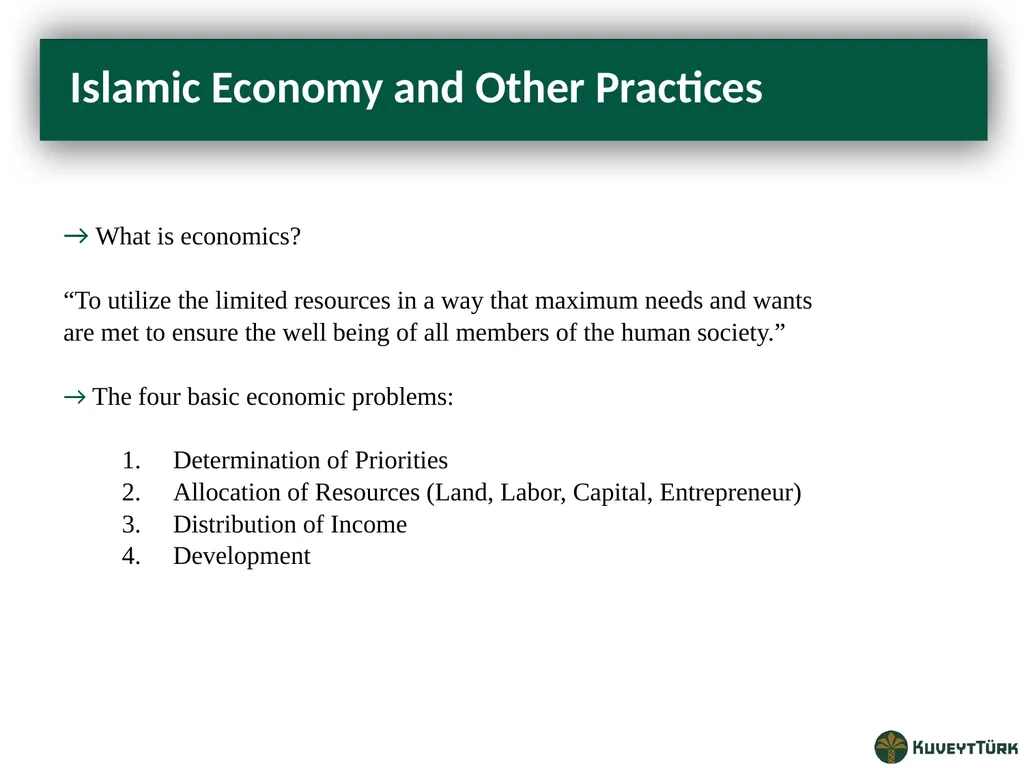
slide2. CALIBRI BOLD 42 pt Islamic Economy and Other Practices → What is economics?
“To utilize the limited resources in a way that maximum needs and wants
are met to ensure the well being of all members of the human society.”
→ The four basic economic problems:
Determination of Priorities
Allocation of Resources (Land, Labor, Capital, Entrepreneur)
Distribution of Income
Development<br>
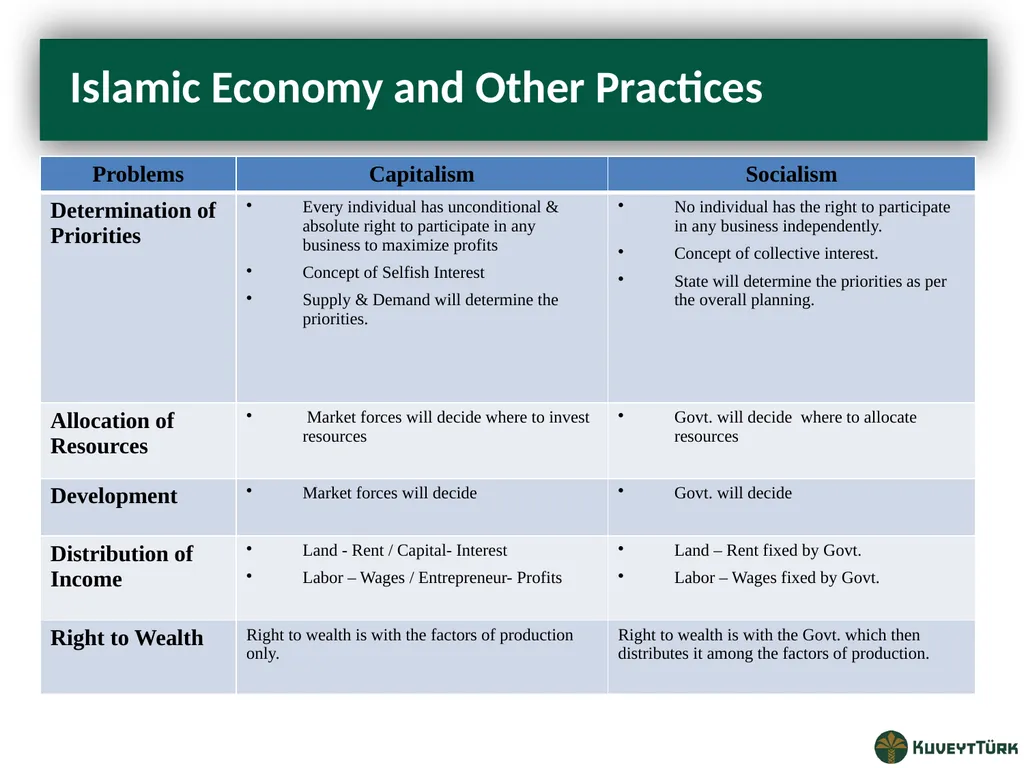
slide3. CALIBRI BOLD 42 pt Islamic Economy and Other Practices<br>
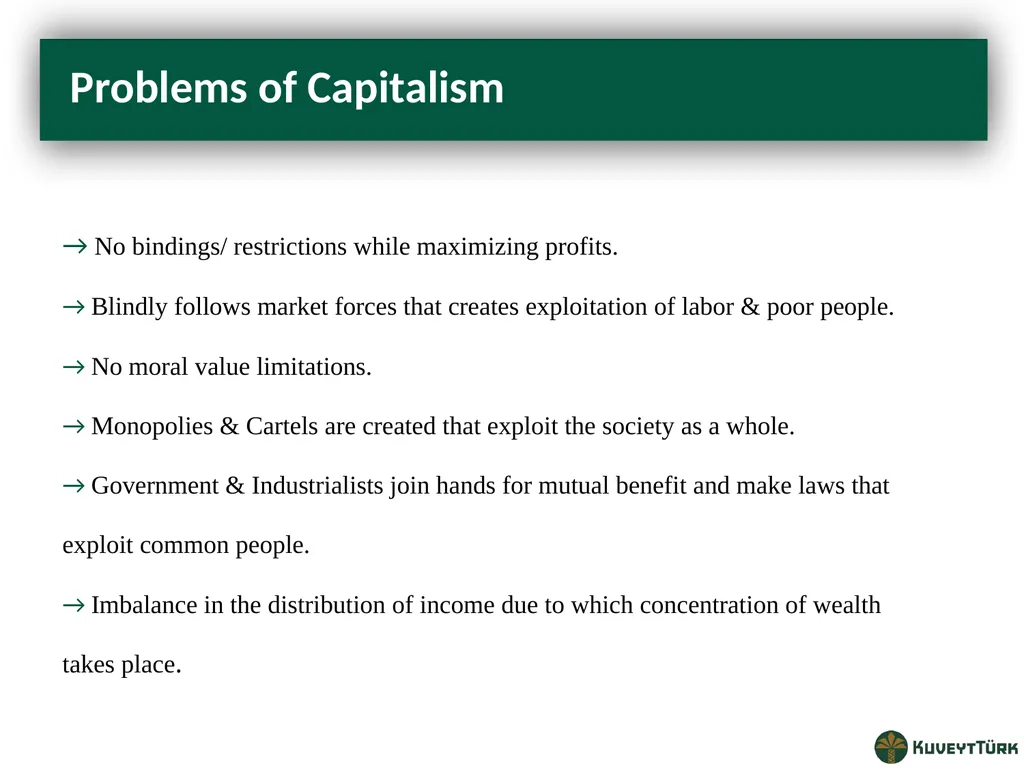
slide4. CALIBRI BOLD 42 pt Problems of Capitalism → No bindings/ restrictions while maximizing profits.
→ Blindly follows market forces that creates exploitation of labor & poor people.
→ No moral value limitations.
→ Monopolies & Cartels are created that exploit the society as a whole.
→ Government & Industrialists join hands for mutual benefit and make laws that
exploit common people.
→ Imbalance in the distribution of income due to which concentration of wealth
takes place.<br>
slide5. CALIBRI BOLD 42 pt Problems of Socialism → The other extreme of not even giving the natural freedom.
→ Perfect Planning is assumed to be the “Cure of all ills”.
→ Governments are assumed to be angels which can’t commit a deliberate
mistake.
→ Cannot work without forceful dictatorship.
→ Creates overall inefficiency in the society. There is no incentive to work
efficiently as there is no individual profit motive.<br>
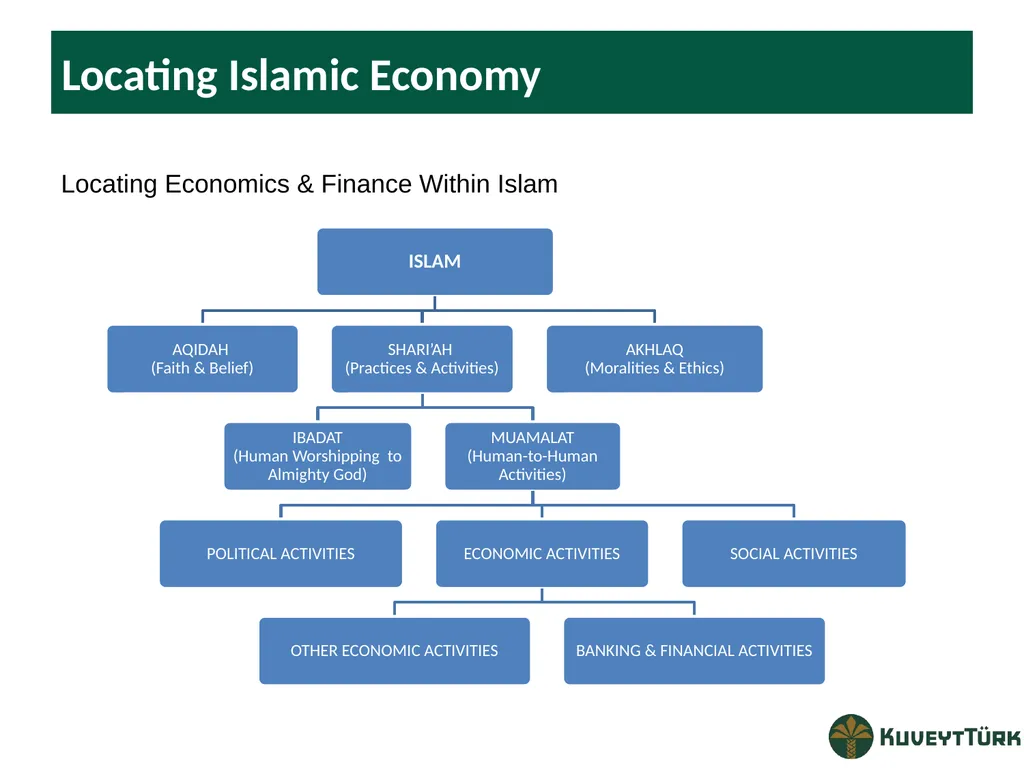
slide6. CALIBRI BOLD 42 pt Islamic Economy → Islam is a Deen which gives guidance for Aqaid, Ibadat, Mu’ashrat, Akhlaq &
Mu’amalat.
→ Hidaya- famous nook of Fiqh has 70 % portion dedicated to Mu’amalat.
→ The humanitarian goal of achieving the well being of all members of the human
family cannot be attained by concentrating primarily on the material constituents
of well-being and making maximization of wealth as the main objective of
Economics.<br>
slide7. CALIBRI BOLD 42 pt Islamic Economy → It is also necessary to raise the spiritual content of well being and reduce all the
symptoms of anomie, like family disintegration, heavy interest based debt
payments, conflict and tensions, crime, alcoholism, drug addiction, and mental
illness, all indicating lack of inner happiness and contentment in the life of
individuals.
→ Optimization of human well-being as per the divine guidelines of Allah.
→ Islam accepts the market forces of supply and demand- Reference of Holy Quran.
→ Islam accepts the right to private property and accepts the right to maximize profits.
But these rights are not unbridled and un conditional rather there are some prohibitions.<br>
slide8. CALIBRI BOLD 42 pt Islamic Economy → In Islam there are three factors of production
1.Land 2. Labor 3. Entrepreneur
→ Entrepreneur & Capital is a single factor of production.
→ As interest is Haram hence the risk of profit & loss is with the capital.
→ Anyone investing capital must also take the risk of the investment.
→ In both Capitalism & Socialism the right to wealth is with those factors of production
only that have taken part directly in the process of production.
→ Islam believes that the original ownership of everything is with Allah and without
Allah’s “Taufeeq” no factor of production can produce anything.<br>
slide9. Locating Islamic Economy Locating Economics & Finance Within Islam<br>
slide10. Basic Principles of Islam The Islamic worldview is based on tahwid (the oneness of God), risalah (God’s prophets as the source of Divine Guidance), akhirah (life-after-death, that is the continuity of life beyond death and a system of accountability based on Divine Law)
It provides for freedom of action whereby each individual is viewed as an integral part of the whole. Individuals are expected to establish justice (‘adl) and promote beneficence (ihsan), resulting in attaining high levels of good life (hayat al-tayyebah) , both individual and collective.
It aims to strike an appropriate balance between the needs of present and future generations (need fulfillment; respectable source of living; equitable distribution of income and wealth; growth and stability)<br>
slide11. Accountibility before Allah
Free-will (Ihsan)
Responsibility (Fard)
Divine arrangements (Rububiyya)
Purification (tazkiyya) Basic Principles of Islam<br>
slide12. Implications of the Basic Principles Human beings can only proclaim credit for what he/she produces.. The needy and society have a right too; zakah, etc…
Responsible use of rightful earnings by keeping the moral purposes of human beings in view;
Individuals must not prevent others in society and nature from meeting their basic biological needs
All people should have equal opportunities, without discrimination, to benefit from environmental and public resources.
The creation of wealth, work, earning and production is necessary and good. What makes wealth bad is firstly, its single-minded pursuit; its misuse, abuse, conspicuous consumption, wastage or israf; and squandering or tabhdir; its exclusiveness to oneself and denial of the share of the society (zakah and other forms of sharing); and the use of socially and ethically wrong or unjust means to produce it – the immoral, prohibited modes, oppressive exploitation of human beings and creation of ecological imbalance or environmental disruption.<br>
slide13. The Operational Impacts Of Islamic Economy Islamic economic and financial system, on the one hand, aims to guarantee individual liberty, freedom of choice, private property and enterprise.
On the other hand, it seeks to provide effective moral filters at different levels of life and activity and established institiutions in the voluntary sector, as well as through state apparatus to ensure economic development and social justice in the society.
Islam does not prescribe a particular economic system but provides the core elements and principles, which form the basic philosophy of a system or an economy.
Islam provides primarily normative principles for economics and finance.<br>
slide14. CALIBRI BOLD 42 pt Islamic Finance-Main Considerations →Divine Prohibitions
Islam has prohibited some economic activities that are not allowed
at any time at any place.( interest, gambling, hoarding, adultry,
alcohol etc.)
→Govermental Restrictions
Islam allows Govt. to intervene where it feels appropriate ,
but these restrictions are temporary as per the need of the time.
→Moral Considerations & Restrictions
Life in this world is temporary and there is an eternal life hereafter.<br>
slide15. CALIBRI BOLD 42 pt Islamic Finance-Main Considerations →As interest is prohibited the risk of profit & loss is with
the capital.
→ Anyone investing capital must also take the risk of the
investment.
→ Islam ensures equitable distribution of wealth through
the concept of primary and secondary ownership<br>
slide16. CALIBRI BOLD 42 pt Islamic Banking Islamic Banking is interest free Asset Backed banking governed by
the principles of Islamic Shariah
→ Islamic Banking distinguishes from Conventional Banking in four basic principles:
Interest Free Transactions
Risk Sharing
Asset & Service Backing
Contractual Certainty( Gharar free contracts)<br>
slide17. CALIBRI BOLD 42 pt Islamic Banking → Financiers are linked to the underlying transaction
→ Money is not a “Commodity” in itself, merely reflecting
“Time Value” for a return
→ Gold and silver are not commodities, they are
considered as money<br>
slide18. Core Basic Tenets Of Islamic Finance If something is immoral, one cannot profit from it
To share reward, one must also share risk
One cannot sell what one does not own
In any transaction, one must clearly specify what he/she is buying or selling and what price is being paid;
Haram + Haram ≠ Halal
Haram + Halal ≠ Halal
Thus:
Islamic finance aims at removing speculation and ensuring value-enhancing activity<br>
slide19. Islamic Finance as an Ethical Solution Thus, Islamic finance in essence a value and moral proposition and more than financial contracts.<br>
slide20. Islamic Banking Positive Impacts Promoting the investment mindset as opposed to the banking mindset:
Investing in real assets rather than promoting speculation and leverage
Making meaningful real economy impact
Investing in asset-backed instruments and real economy values
Engagement of an under-served and previously un-banked market
Providing an ethical banking solution to local communities to deepen the banking market
Attracting foreign investment and cross-border partnership from Islamic financial institutions
Attractive source of cross-market ventures and cross-border lines from Muslim countries<br>
slide21. Prohibited Activities Conventional banking & Insurance
Alcohol
Pork
Defence
Gambling
Adult Entertainment
Tobacco
Other non-accepted activities as defined by the Sheri’ah Board<br>
slide22. Controversies In Sheriah Governance Conflicts of interest
Confidentiality
Fees (Scholars for dollars?)
Scarcity of scholars Vs. High Demand
Finding problems or finding solutions
Dialogue between the deaf?
Consistency issues
Who takes the blame?
Expectation management
Resource planning<br>
slide23. Challanges In Sheriah Governance The scholars of different schools of thoughts (Madhabs) with different interpretations and opinions
The number of scholars qualified in the jurisprudence of dealings (Fiqh-ul-muamalat) relatively limited
The level of familiarity of the scholars with modern day financial services is limited
Most of the management of IFI’s coming from conventional backgrounds with no or very little understanding of Shariah
The expectations of the stakeholders (regulators, shareholders, customers & the management of IFI’s) from Islamic finance are very unrealistic<br>
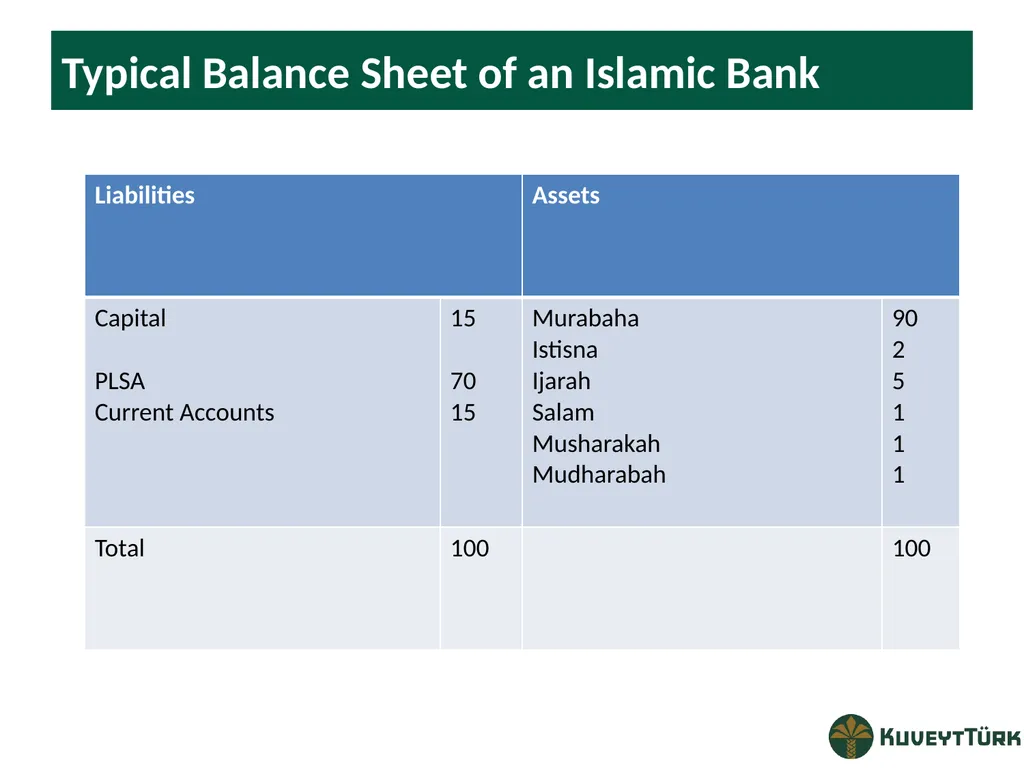
slide24. Typical Balance Sheet of an Islamic Bank<br>
slide25. How is Islamic Finance Different from Conventional Finance? Conventional financial institutions operate within a system based on debt and transfer of risk
This raises the probability of disconnecting financial instruments from their underlying assets
Some of the financial tools created to share risk actually resulted in a concentration and intensification of risk
In contrast, Islamic finance emphasizes asset-backing for transactions and is anchored on the principle of risk sharing
Shariah principles ensures a direct link between financial transactions and real sector activities
Shariah principles also prohibit (Gharar), the use of excessive leverage and avoids many forms of controversial complex securitization<br>
slide26. Performance of Islamic Finance During the Crisis Islamic banks escaped the direct impact of the crisis, as they were not exposed to sub-prime and toxic assets
A recent IMF Working Paper* found that the business model of Islamic banks helped them to mitigate the impact of the crisis
As Islamic banking services are more connected to the real sector, initially performed well during the crisis yet were severely hit by the second round effects:<br>
slide27. BÖLÜM BAŞLIĞI
CALIBRI BOLD 42 pt RETAIL BANKING PRODUCTS & SERVICES PRODUCTS & SERVICES<br>
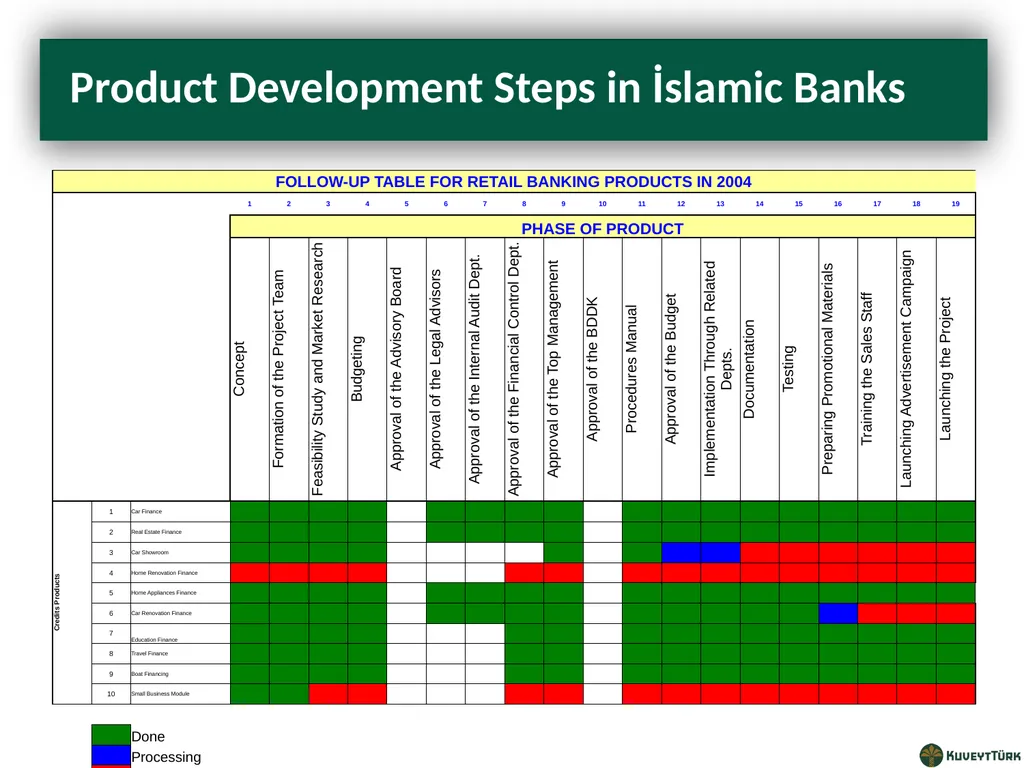
slide28. CALIBRI BOLD 42 pt Product Development Steps in İslamic Banks<br>
slide29. BÖLÜM BAŞLIĞI
CALIBRI BOLD 42 pt DEPOSIT PRODUCTS<br>
slide30. CALIBRI BOLD 42 pt Deposits<br>
slide31. CALIBRI BOLD 42 pt Current Accounts No tenor
No profit or loss
No minimum cap
Withdraw and deposit any time
Any currency denomination
Based on Kard Al Hasen structure<br>
slide32. CALIBRI BOLD 42 pt Profit and Loss Sharing Accounts Flexible account tenors
Profit or loss distribution
Minimum cap applied
Withdraw and deposit at maturity only
TRL, USD, EUR denomination
No preset yield guaranteed
Based on Mudaraba agreement
No capital guarantee<br>
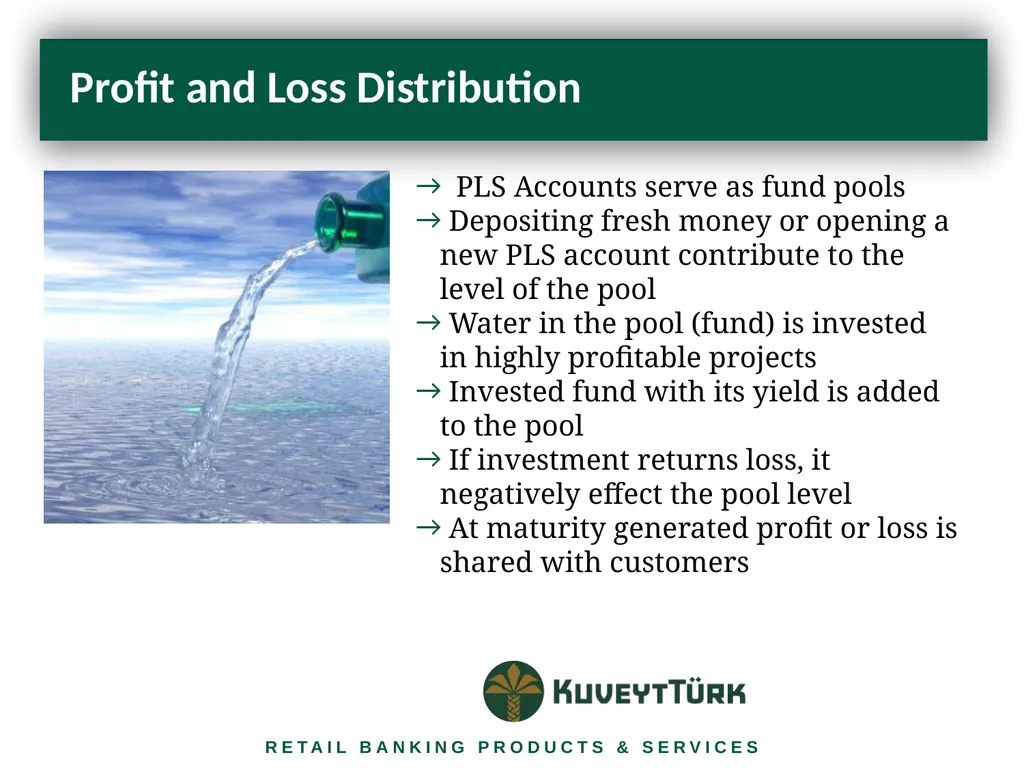
slide33. CALIBRI BOLD 42 pt Profit and Loss Distribution RETAIL BANKING PRODUCTS & SERVICES PLS Accounts serve as fund pools
Depositing fresh money or opening a new PLS account contribute to the level of the pool
Water in the pool (fund) is invested in highly profitable projects
Invested fund with its yield is added to the pool
If investment returns loss, it negatively effect the pool level
At maturity generated profit or loss is shared with customers<br>
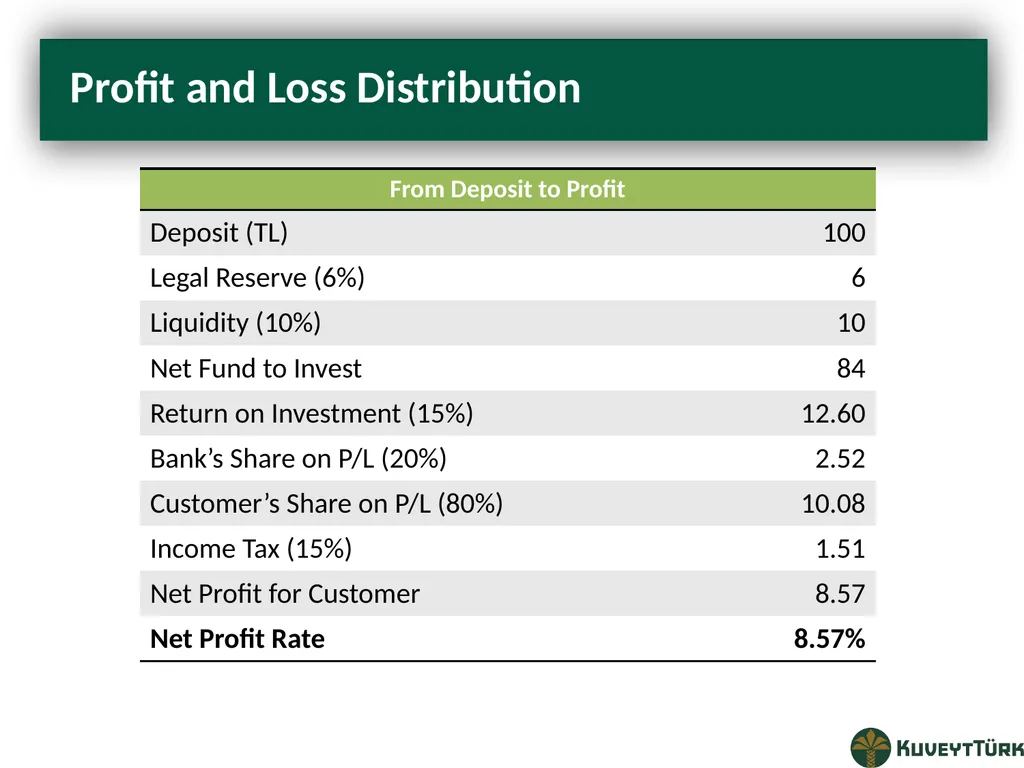
slide34. CALIBRI BOLD 42 pt Profit and Loss Distribution<br>
slide35. CALIBRI BOLD 42 pt Profit and Loss Generation Unit Value: the coefficient which is assumed as 100 for the first day of the participation bank that accepts fund to ist participation accounts.
Unit value changes when profit or loss is made.
Account Value: the coefficient colculated by dividing the amount deposited to the unit value.
Unit Account Value: The value determining the the current value of the participation account and calculated through multiplying the unit value by the account value and the amount on which the account holder may lay claim to.<br>
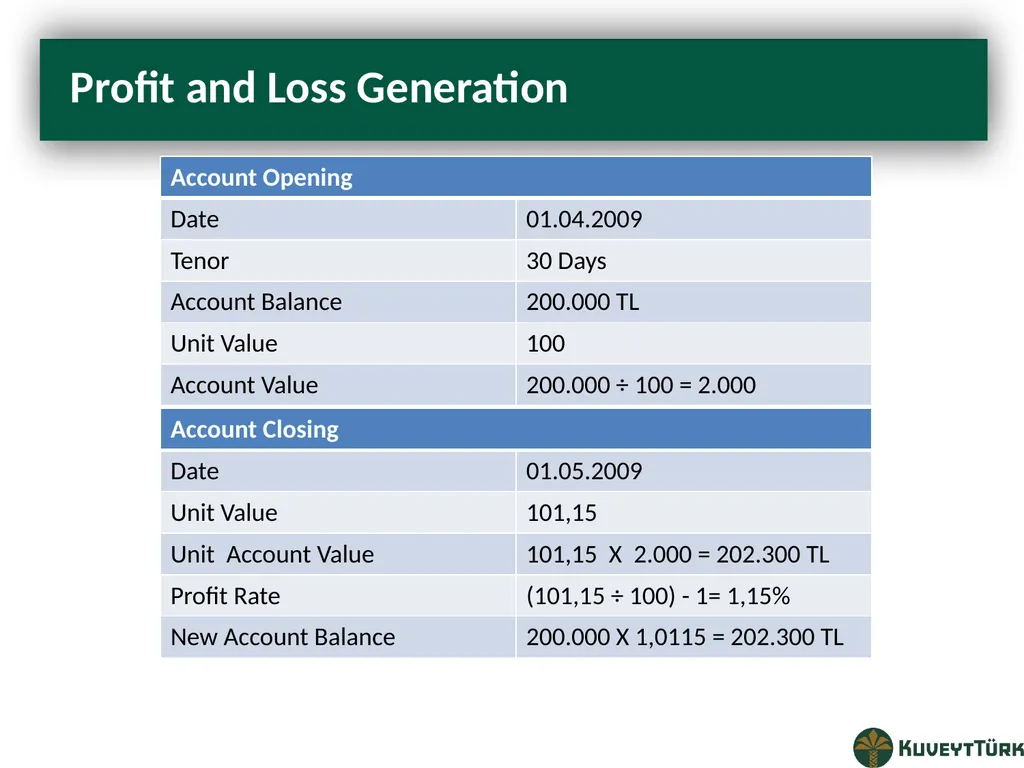
slide36. CALIBRI BOLD 42 pt Profit and Loss Generation<br>
slide37. CALIBRI BOLD 42 pt Fund Collection Products Current Account
Participation Account (Classic, Silver, Gold, Platinum, Platinum+ Accounts)
Savings Account ( Family, Youth and Child Savings Account)
Precious Metals Current Accounts
Precious Metals Participation Accounts
Investment Account
Flexible Maturity Participation Accounts
Salary Account
Gold denominated gift cheque
Tenant’s Accounts<br>
slide38. CALIBRI BOLD 42 pt Banking Services VIP Package
Special Fund Pool
Forward transactions
Foreign currency buy and sell
Check services
Promissory Note services
Safe box
International and local money transfers
Moneygram
Gold bullion<br>
slide39. BÖLÜM BAŞLIĞI
CALIBRI BOLD 42 pt LOAN PRODUCTS<br>
slide40. CALIBRI BOLD 42 pt Main Islamic Loan Products Murabaha
Musharaka
Icara (Leasing)
Mudaraba
Istisna’
Kard Al Hasen
Salam
Tawarruq<br>
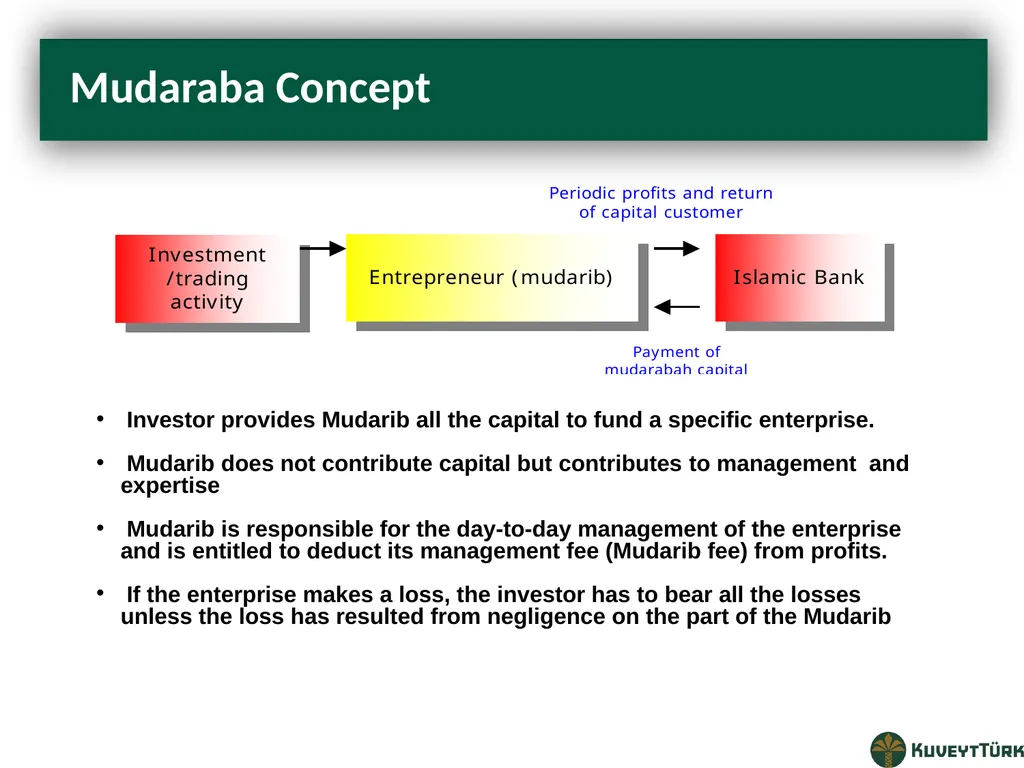
slide41. CALIBRI BOLD 42 pt Mudaraba Concept Investor provides Mudarib all the capital to fund a specific enterprise.
Mudarib does not contribute capital but contributes to management and expertise
Mudarib is responsible for the day-to-day management of the enterprise and is entitled to deduct its management fee (Mudarib fee) from profits.
If the enterprise makes a loss, the investor has to bear all the losses unless the loss has resulted from negligence on the part of the Mudarib<br>
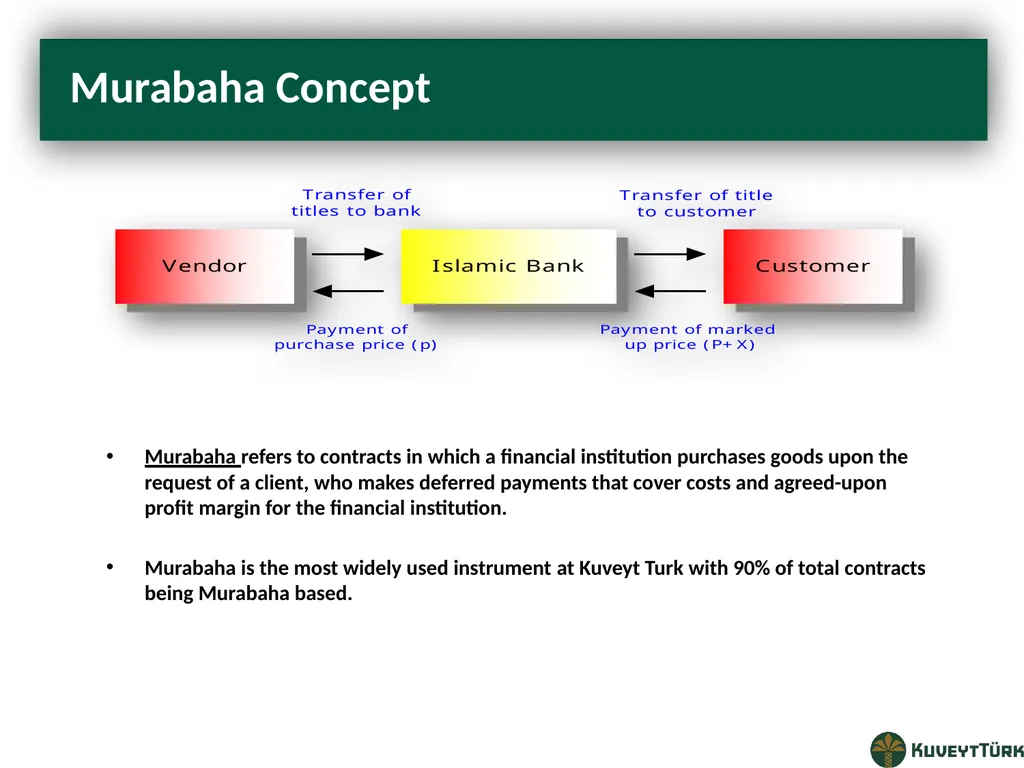
slide42. CALIBRI BOLD 42 pt Murabaha Concept Murabaha refers to contracts in which a financial institution purchases goods upon the request of a client, who makes deferred payments that cover costs and agreed-upon profit margin for the financial institution.
Murabaha is the most widely used instrument at Kuveyt Turk with 90% of total contracts being Murabaha based.<br>
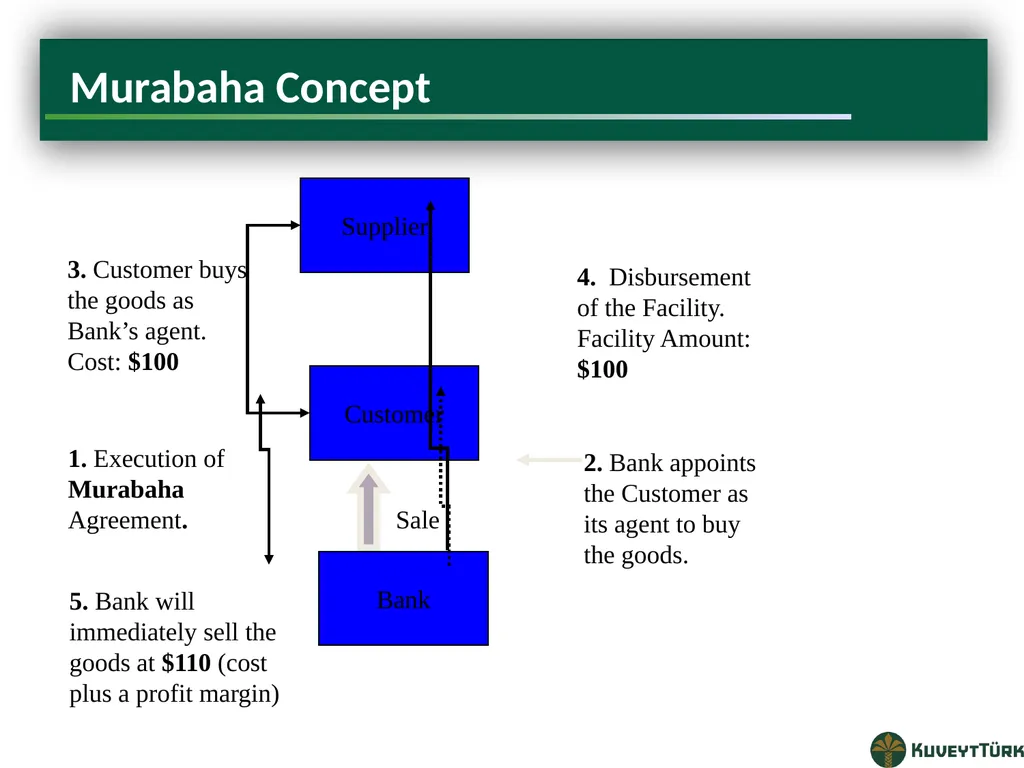
slide43. CALIBRI BOLD 42 pt Murabaha Concept Supplier Customer Bank 3. Customer buys the goods as Bank’s agent. Cost: $100 1. Execution of Murabaha Agreement. 4. Disbursement of the Facility. Facility Amount: $100 2. Bank appoints the Customer as its agent to buy the goods. 5. Bank will immediately sell the goods at $110 (cost plus a profit margin) Sale<br>
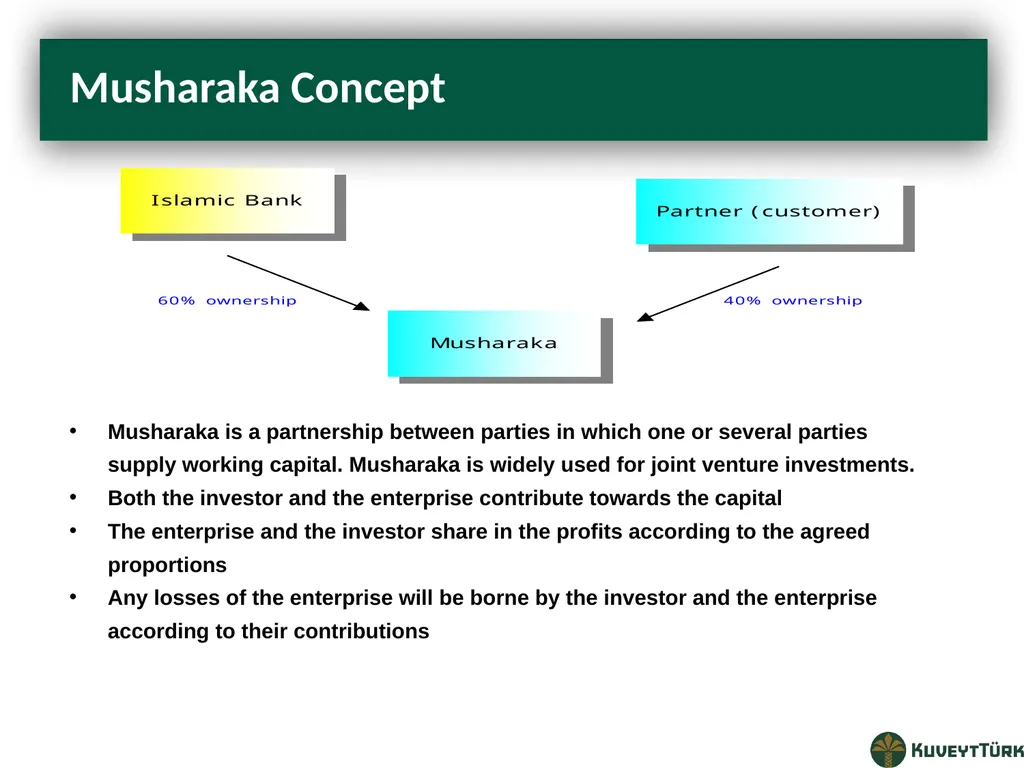
slide44. CALIBRI BOLD 42 pt Musharaka Concept Musharaka is a partnership between parties in which one or several parties supply working capital. Musharaka is widely used for joint venture investments.
Both the investor and the enterprise contribute towards the capital
The enterprise and the investor share in the profits according to the agreed proportions
Any losses of the enterprise will be borne by the investor and the enterprise according to their contributions<br>
slide45. Musharakah Shirkah or sharing
Musharakah involves a mutual contract to participate in a commercial enterprise
Determination of returns
Proportional distribution agreed in advence, usually relating to investment shares
Net profits of the business
Losses must be shared in proportion to amounts invested
Management
All partners may be involved in the management of the business
May agree in advance that one party a sleeping partner<br>
slide46. Musharakah versus equity investment Musharakah
Venture of limited duration
Partnership with joint ownership
No exit without agreement of partners
Investors obtain profit share
Little probability of asset gains when venture terminates Equity Investment
Company exists in perpetuity
Exclusive ownership by shareholders
Exit at any time if company listed
Investors get dividends
Focus on capital gains and market value of equity<br>
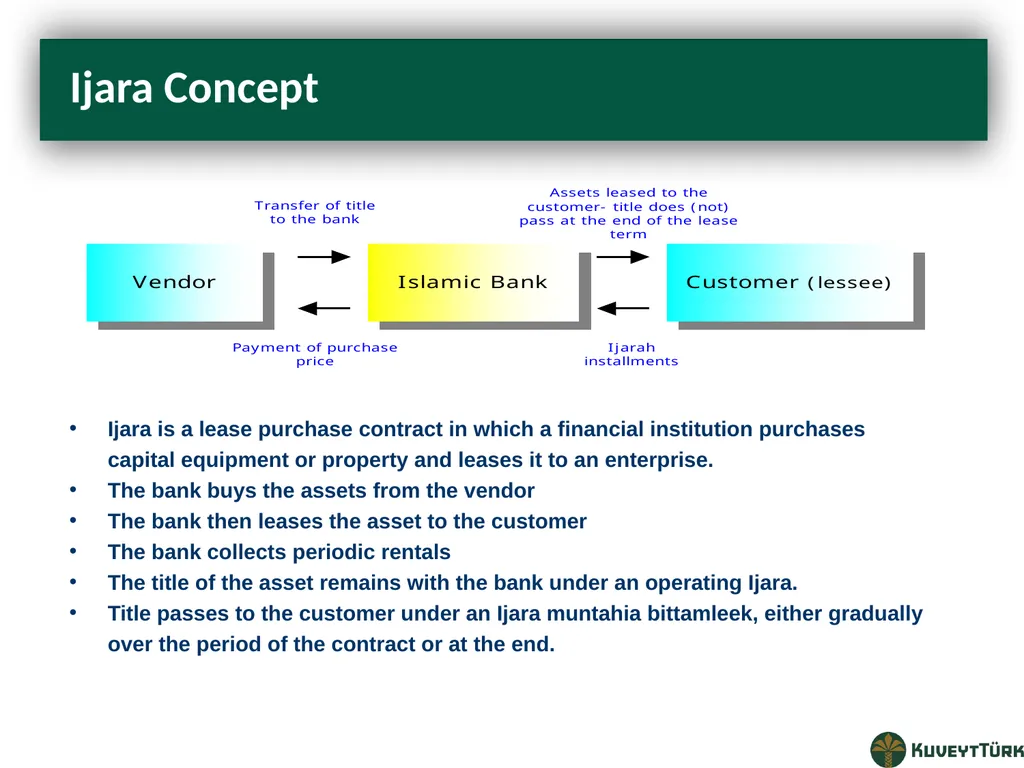
slide47. CALIBRI BOLD 42 pt Ijara Concept Ijara is a lease purchase contract in which a financial institution purchases capital equipment or property and leases it to an enterprise.
The bank buys the assets from the vendor
The bank then leases the asset to the customer
The bank collects periodic rentals
The title of the asset remains with the bank under an operating Ijara.
Title passes to the customer under an Ijara muntahia bittamleek, either gradually over the period of the contract or at the end.<br>
slide48. Operating ijara is a pure leasing arrangement
- Two parties to the contract, lessor and lessee
- Rental payment provides an income stream
- Contract of fixed duration but renewal possible
Owner and lessee responsibilities
- The lessee can be requiered to maintain equipment on a periodic basis
- Owner responsible for loss or damage to asset beyond control of lessee
-Lessee can indemnify owner against misuse or negligence caused by lessee Ijara Concept<br>
slide49. Conditions & Limitations of Ijara Property being leased must have a valuable use
House or business premises should be occupied, not a mere speculative purchase
Leased property cannot be used for purposes other than specified in the leasing department
Non halal use would contravene shariah
Restrictive covenants may be included in new leases but uncertainties of conversion with existing leases<br>
slide50. Hire Purchase Ijara wa iqtina or ijara muntahia bittamleek is a hire purchase contract
Leased asset passes as a gift or a sale at the end of the lease period
Purchase possible during the lease period if the remaining rental installments paid
Gradual transfer of ownership also possible rather than an outright sale
Lower risk as lessee has ownership stake<br>
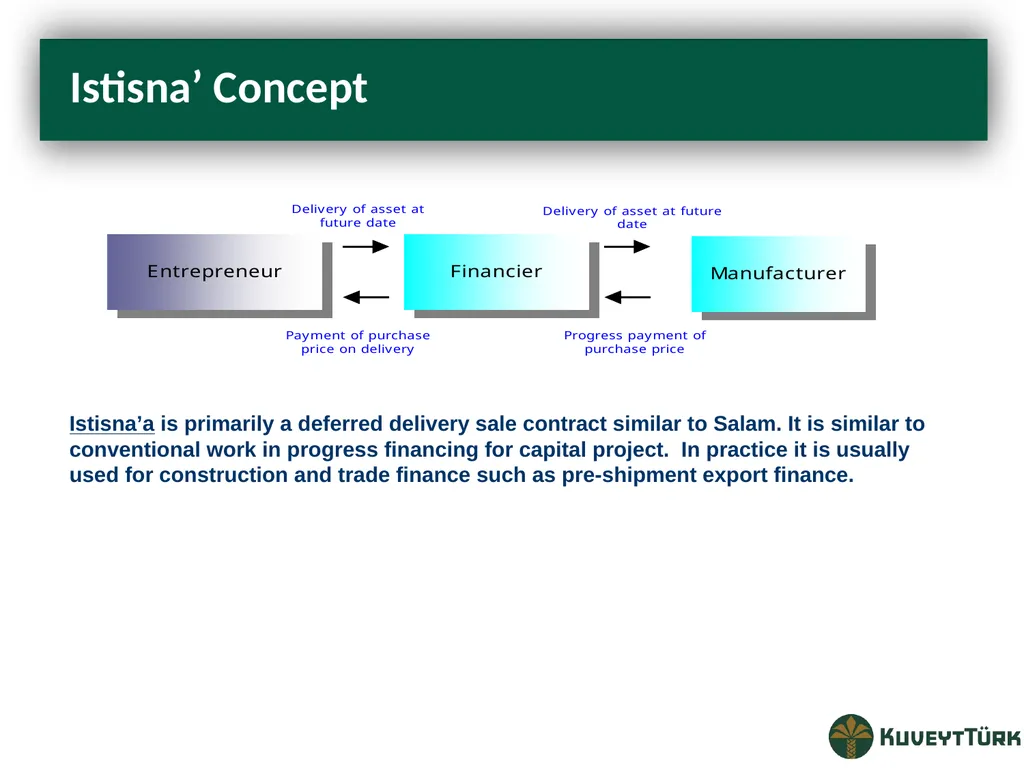
slide51. CALIBRI BOLD 42 pt Istisna’ Concept Istisna’a is primarily a deferred delivery sale contract similar to Salam. It is similar to conventional work in progress financing for capital project. In practice it is usually used for construction and trade finance such as pre-shipment export finance.<br>
slide52. Contract to acquire goods on behalf of a third party
Price paid to a manufacturer in advance of goods being purchased
Payments received cover wages and costs of input supplies
Applied to production of specific times
Delivery at an agreed date Istisna’ Concept<br>
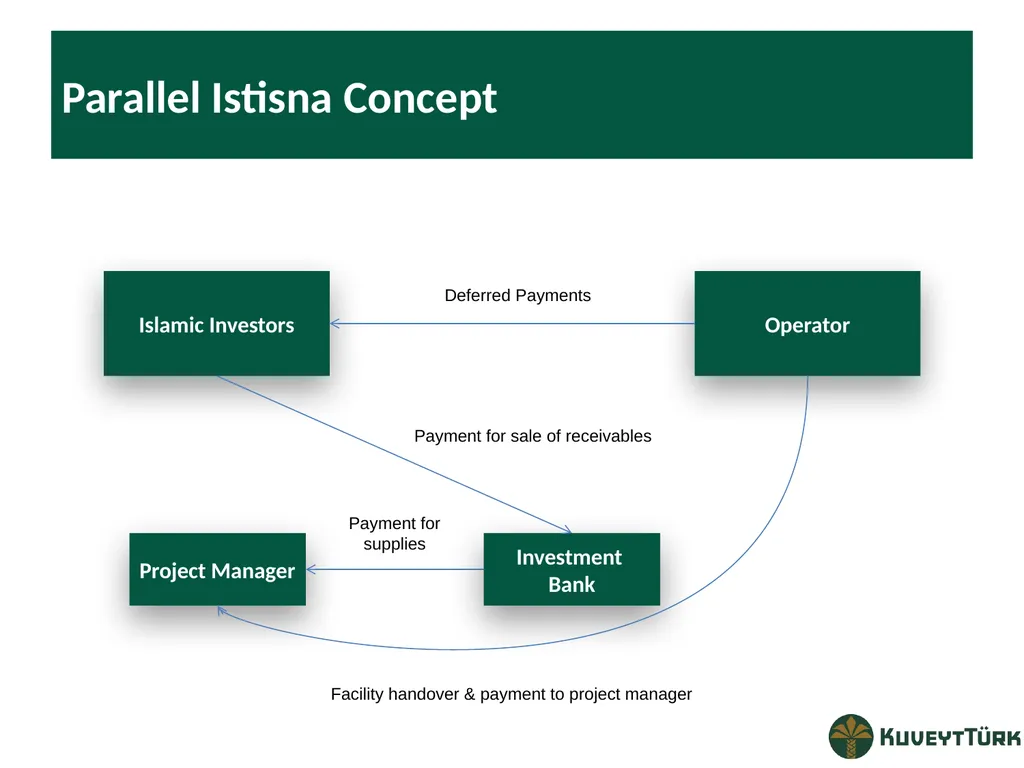
slide53. Parallel Istisna Concept Islamic Investors Operator Project Manager Investment Bank Deferred Payments Payment for sale of receivables Payment for supplies Facility handover & payment to project manager<br>
slide54. Tawarruq Concept Bank buys and owns the commodity
Commodity sold to the client at a mark-up
Purchaser can authorise bank to sell commodity for a service commission
Sale value deposited into clients account
Client repays amount plus mark-up as deferred lump sun or in installments<br>
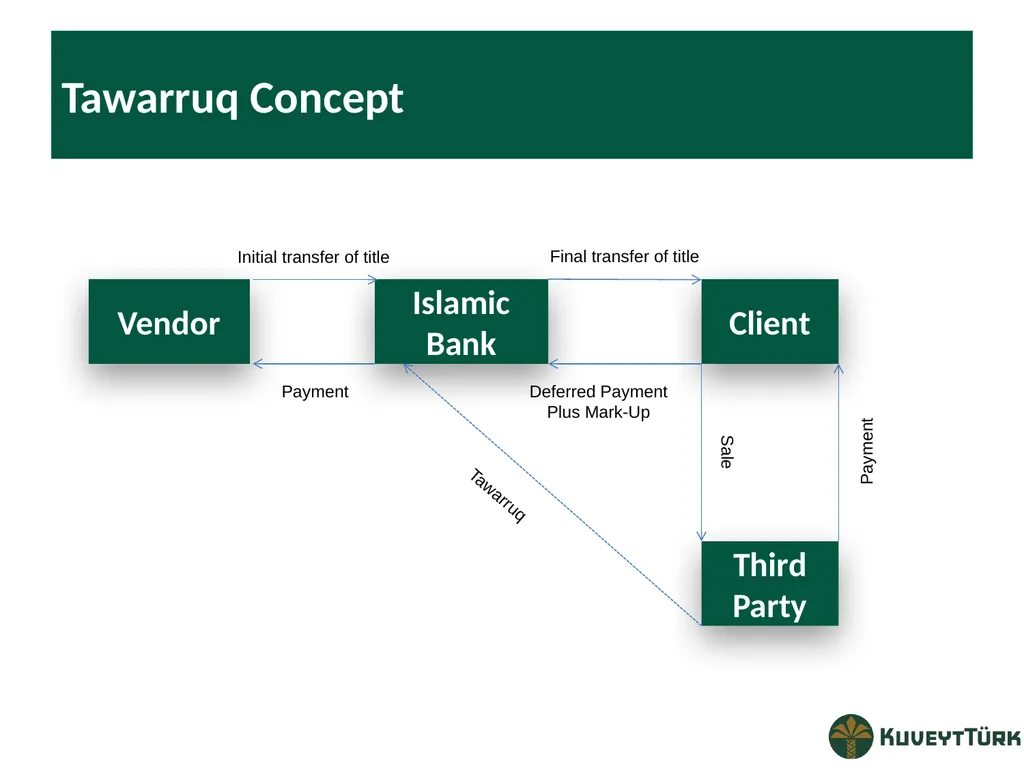
slide55. Tawarruq Concept Vendor Islamic Bank Client Third Party Initial transfer of title Payment Final transfer of title Payment Sale Deferred Payment Plus Mark-Up Tawarruq<br>
slide56. Salam Concept Financier pays price of commodity in advance in full
Quantity and delivery date and place specified
Financier may enter parallel salam to sell commodity at a slightly higher price if period shorter to delivery
Price differential represents financier’s profit
Risk involved to justify profit as time period of contracts may not coincide and financier exposed<br>
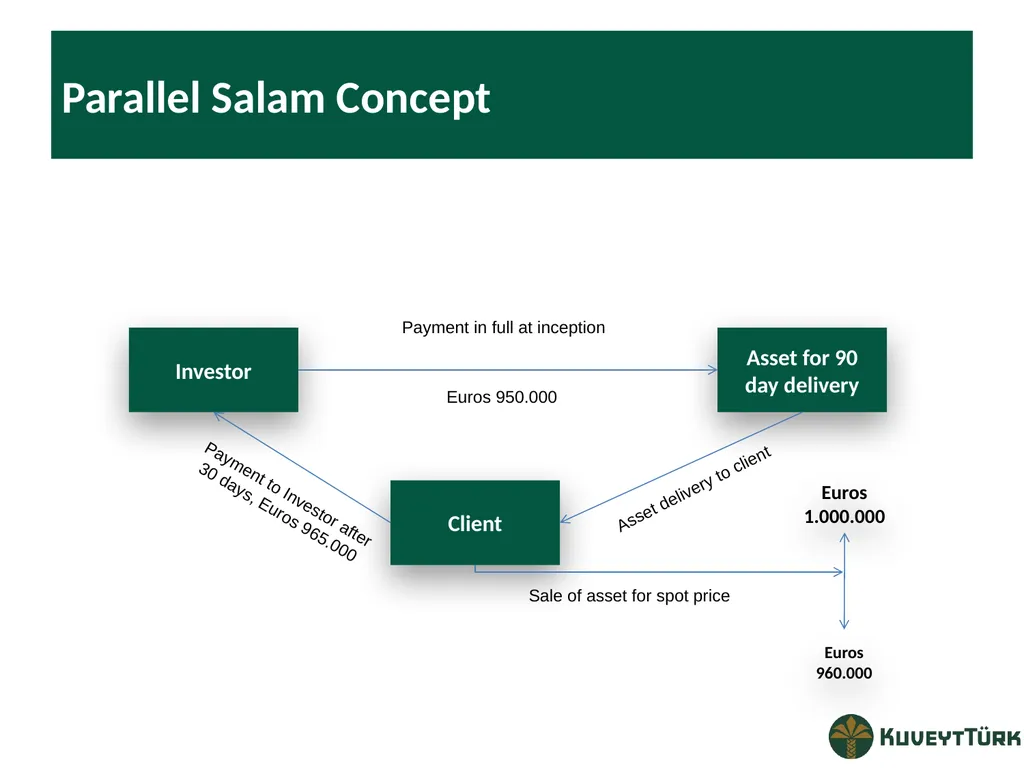
slide57. Parallel Salam Concept Investor Asset for 90 day delivery Client Payment in full at inception Euros 950.000 Asset delivery to client Payment to Investor after 30 days, Euros 965.000 Euros 1.000.000 Euros 960.000 Sale of asset for spot price<br>
slide58. Wakala Concept A contract appointing an agent to act on behalf of a principal party
Parallel with granting a power of attorney or an enduring power of attorney
Wakil may be paid a fee, rather than sharing in profit as with mudarabah<br>
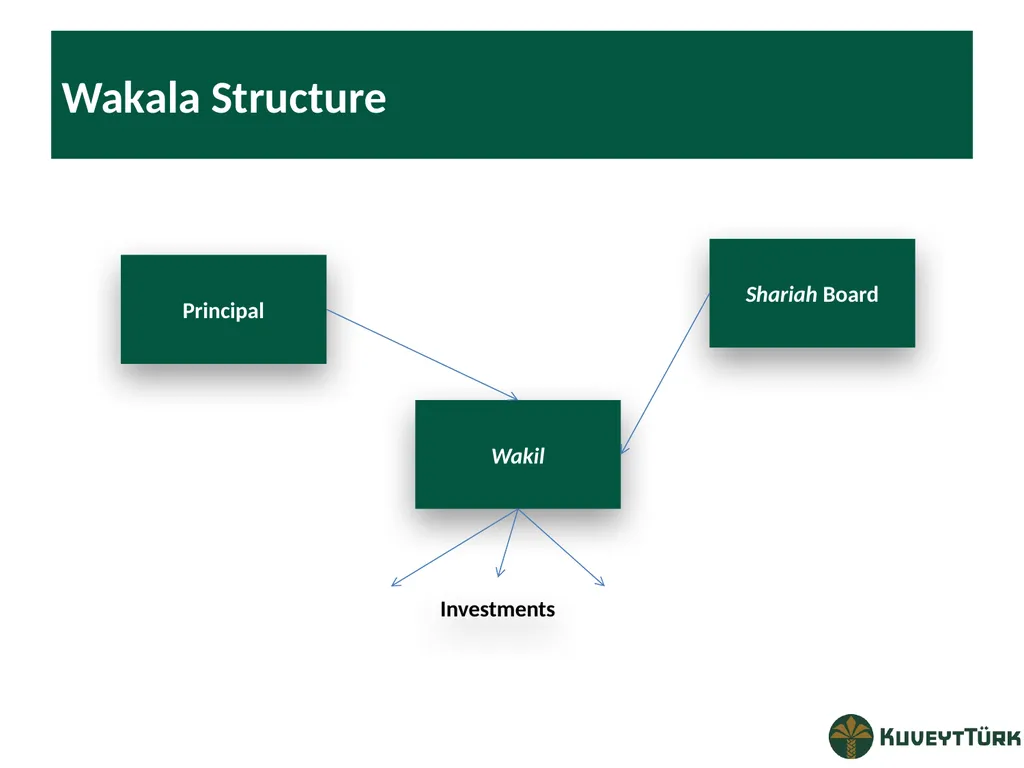
slide59. Wakala Structure Principal Shariah Board Wakil Investments<br>
slide60. CALIBRI BOLD 42 pt Fund Utilization Products Home Equity Loan
Mortgage Loan
Auto Loan
Personal Loan (Home renovation, Education, Travel, Home/Office equipment loans)
Small Business Loan
Decreasing installment home loan
Consumer Price Indexed loan
Rent Finance
Leasing
Letter of Guarantee
Letter of Credit<br>
slide61. BÖLÜM BAŞLIĞI
CALIBRI BOLD 42 pt CARD PRODUCTS<br>
slide62. CALIBRI BOLD 42 pt Card Products Principal Member of
Principal Member of
Member of<br>
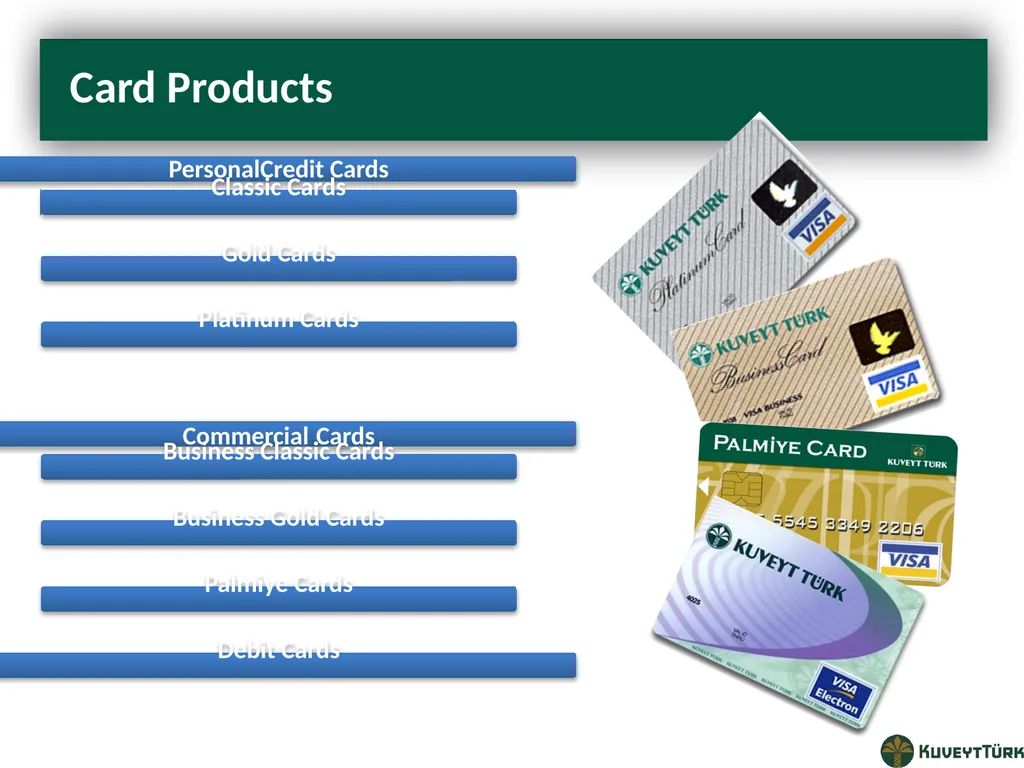
slide63. CALIBRI BOLD 42 pt Card Products<br>
slide64. BÖLÜM BAŞLIĞI
CALIBRI BOLD 42 pt ADC PRODUCTS<br>
slide65. CALIBRI BOLD 42 pt ADC Products POS Services
Internet Branch Banking
ATM Services
Kiosk Services
SMS Banking
Telephone Banking
Mobile Banking
Bill Payment
Tax Payment
Customs Payment
Salary Payment
Social Security Payment
Corporate website management<br>
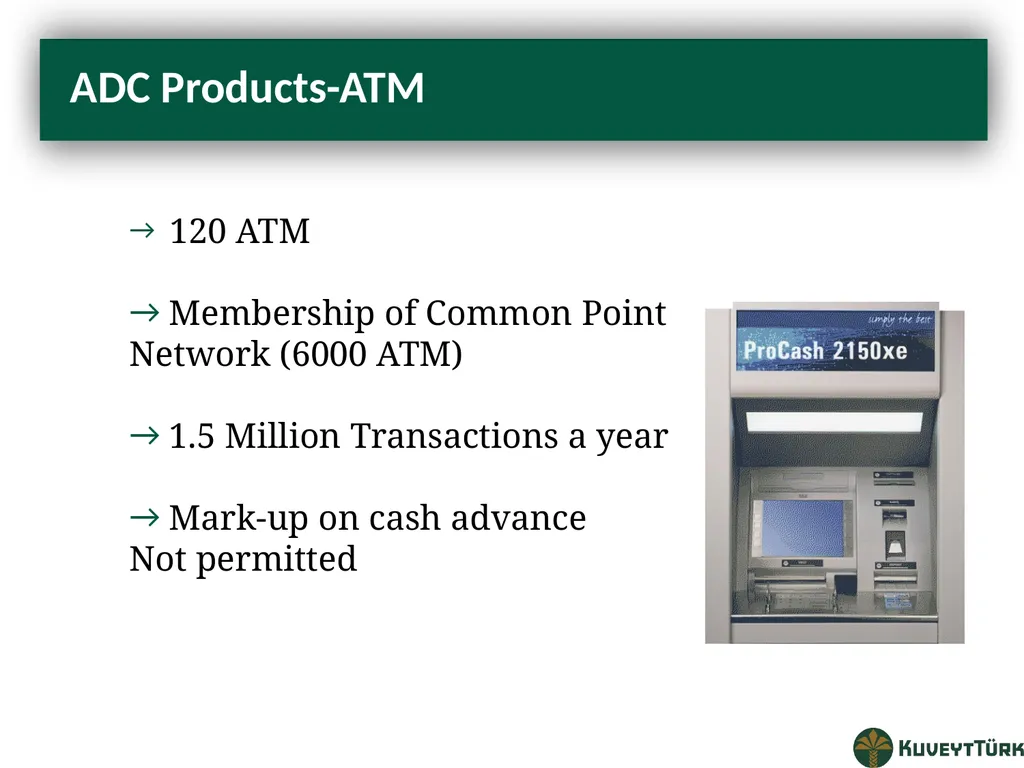
slide66. CALIBRI BOLD 42 pt ADC Products-ATM 120 ATM
Membership of Common Point
Network (6000 ATM)
1.5 Million Transactions a year
Mark-up on cash advance
Not permitted<br>
slide67. CALIBRI BOLD 42 pt ADC Products-POS 120 ATM
Membership of Common Point
Network (6000 ATM)
1.5 Million Transactions a year
Mark-up on cash advance
Not permitted<br>
slide68. BÖLÜM BAŞLIĞI
CALIBRI BOLD 42 pt Thank You<br>
Mustafa Dereci
Group Manager
Retail and Business Banking Marketing and Product Development OCTOBER 2011<br>
slide2. CALIBRI BOLD 42 pt Islamic Economy and Other Practices → What is economics?
“To utilize the limited resources in a way that maximum needs and wants
are met to ensure the well being of all members of the human society.”
→ The four basic economic problems:
Determination of Priorities
Allocation of Resources (Land, Labor, Capital, Entrepreneur)
Distribution of Income
Development<br>
slide3. CALIBRI BOLD 42 pt Islamic Economy and Other Practices<br>
slide4. CALIBRI BOLD 42 pt Problems of Capitalism → No bindings/ restrictions while maximizing profits.
→ Blindly follows market forces that creates exploitation of labor & poor people.
→ No moral value limitations.
→ Monopolies & Cartels are created that exploit the society as a whole.
→ Government & Industrialists join hands for mutual benefit and make laws that
exploit common people.
→ Imbalance in the distribution of income due to which concentration of wealth
takes place.<br>
slide5. CALIBRI BOLD 42 pt Problems of Socialism → The other extreme of not even giving the natural freedom.
→ Perfect Planning is assumed to be the “Cure of all ills”.
→ Governments are assumed to be angels which can’t commit a deliberate
mistake.
→ Cannot work without forceful dictatorship.
→ Creates overall inefficiency in the society. There is no incentive to work
efficiently as there is no individual profit motive.<br>
slide6. CALIBRI BOLD 42 pt Islamic Economy → Islam is a Deen which gives guidance for Aqaid, Ibadat, Mu’ashrat, Akhlaq &
Mu’amalat.
→ Hidaya- famous nook of Fiqh has 70 % portion dedicated to Mu’amalat.
→ The humanitarian goal of achieving the well being of all members of the human
family cannot be attained by concentrating primarily on the material constituents
of well-being and making maximization of wealth as the main objective of
Economics.<br>
slide7. CALIBRI BOLD 42 pt Islamic Economy → It is also necessary to raise the spiritual content of well being and reduce all the
symptoms of anomie, like family disintegration, heavy interest based debt
payments, conflict and tensions, crime, alcoholism, drug addiction, and mental
illness, all indicating lack of inner happiness and contentment in the life of
individuals.
→ Optimization of human well-being as per the divine guidelines of Allah.
→ Islam accepts the market forces of supply and demand- Reference of Holy Quran.
→ Islam accepts the right to private property and accepts the right to maximize profits.
But these rights are not unbridled and un conditional rather there are some prohibitions.<br>
slide8. CALIBRI BOLD 42 pt Islamic Economy → In Islam there are three factors of production
1.Land 2. Labor 3. Entrepreneur
→ Entrepreneur & Capital is a single factor of production.
→ As interest is Haram hence the risk of profit & loss is with the capital.
→ Anyone investing capital must also take the risk of the investment.
→ In both Capitalism & Socialism the right to wealth is with those factors of production
only that have taken part directly in the process of production.
→ Islam believes that the original ownership of everything is with Allah and without
Allah’s “Taufeeq” no factor of production can produce anything.<br>
slide9. Locating Islamic Economy Locating Economics & Finance Within Islam<br>
slide10. Basic Principles of Islam The Islamic worldview is based on tahwid (the oneness of God), risalah (God’s prophets as the source of Divine Guidance), akhirah (life-after-death, that is the continuity of life beyond death and a system of accountability based on Divine Law)
It provides for freedom of action whereby each individual is viewed as an integral part of the whole. Individuals are expected to establish justice (‘adl) and promote beneficence (ihsan), resulting in attaining high levels of good life (hayat al-tayyebah) , both individual and collective.
It aims to strike an appropriate balance between the needs of present and future generations (need fulfillment; respectable source of living; equitable distribution of income and wealth; growth and stability)<br>
slide11. Accountibility before Allah
Free-will (Ihsan)
Responsibility (Fard)
Divine arrangements (Rububiyya)
Purification (tazkiyya) Basic Principles of Islam<br>
slide12. Implications of the Basic Principles Human beings can only proclaim credit for what he/she produces.. The needy and society have a right too; zakah, etc…
Responsible use of rightful earnings by keeping the moral purposes of human beings in view;
Individuals must not prevent others in society and nature from meeting their basic biological needs
All people should have equal opportunities, without discrimination, to benefit from environmental and public resources.
The creation of wealth, work, earning and production is necessary and good. What makes wealth bad is firstly, its single-minded pursuit; its misuse, abuse, conspicuous consumption, wastage or israf; and squandering or tabhdir; its exclusiveness to oneself and denial of the share of the society (zakah and other forms of sharing); and the use of socially and ethically wrong or unjust means to produce it – the immoral, prohibited modes, oppressive exploitation of human beings and creation of ecological imbalance or environmental disruption.<br>
slide13. The Operational Impacts Of Islamic Economy Islamic economic and financial system, on the one hand, aims to guarantee individual liberty, freedom of choice, private property and enterprise.
On the other hand, it seeks to provide effective moral filters at different levels of life and activity and established institiutions in the voluntary sector, as well as through state apparatus to ensure economic development and social justice in the society.
Islam does not prescribe a particular economic system but provides the core elements and principles, which form the basic philosophy of a system or an economy.
Islam provides primarily normative principles for economics and finance.<br>
slide14. CALIBRI BOLD 42 pt Islamic Finance-Main Considerations →Divine Prohibitions
Islam has prohibited some economic activities that are not allowed
at any time at any place.( interest, gambling, hoarding, adultry,
alcohol etc.)
→Govermental Restrictions
Islam allows Govt. to intervene where it feels appropriate ,
but these restrictions are temporary as per the need of the time.
→Moral Considerations & Restrictions
Life in this world is temporary and there is an eternal life hereafter.<br>
slide15. CALIBRI BOLD 42 pt Islamic Finance-Main Considerations →As interest is prohibited the risk of profit & loss is with
the capital.
→ Anyone investing capital must also take the risk of the
investment.
→ Islam ensures equitable distribution of wealth through
the concept of primary and secondary ownership<br>
slide16. CALIBRI BOLD 42 pt Islamic Banking Islamic Banking is interest free Asset Backed banking governed by
the principles of Islamic Shariah
→ Islamic Banking distinguishes from Conventional Banking in four basic principles:
Interest Free Transactions
Risk Sharing
Asset & Service Backing
Contractual Certainty( Gharar free contracts)<br>
slide17. CALIBRI BOLD 42 pt Islamic Banking → Financiers are linked to the underlying transaction
→ Money is not a “Commodity” in itself, merely reflecting
“Time Value” for a return
→ Gold and silver are not commodities, they are
considered as money<br>
slide18. Core Basic Tenets Of Islamic Finance If something is immoral, one cannot profit from it
To share reward, one must also share risk
One cannot sell what one does not own
In any transaction, one must clearly specify what he/she is buying or selling and what price is being paid;
Haram + Haram ≠ Halal
Haram + Halal ≠ Halal
Thus:
Islamic finance aims at removing speculation and ensuring value-enhancing activity<br>
slide19. Islamic Finance as an Ethical Solution Thus, Islamic finance in essence a value and moral proposition and more than financial contracts.<br>
slide20. Islamic Banking Positive Impacts Promoting the investment mindset as opposed to the banking mindset:
Investing in real assets rather than promoting speculation and leverage
Making meaningful real economy impact
Investing in asset-backed instruments and real economy values
Engagement of an under-served and previously un-banked market
Providing an ethical banking solution to local communities to deepen the banking market
Attracting foreign investment and cross-border partnership from Islamic financial institutions
Attractive source of cross-market ventures and cross-border lines from Muslim countries<br>
slide21. Prohibited Activities Conventional banking & Insurance
Alcohol
Pork
Defence
Gambling
Adult Entertainment
Tobacco
Other non-accepted activities as defined by the Sheri’ah Board<br>
slide22. Controversies In Sheriah Governance Conflicts of interest
Confidentiality
Fees (Scholars for dollars?)
Scarcity of scholars Vs. High Demand
Finding problems or finding solutions
Dialogue between the deaf?
Consistency issues
Who takes the blame?
Expectation management
Resource planning<br>
slide23. Challanges In Sheriah Governance The scholars of different schools of thoughts (Madhabs) with different interpretations and opinions
The number of scholars qualified in the jurisprudence of dealings (Fiqh-ul-muamalat) relatively limited
The level of familiarity of the scholars with modern day financial services is limited
Most of the management of IFI’s coming from conventional backgrounds with no or very little understanding of Shariah
The expectations of the stakeholders (regulators, shareholders, customers & the management of IFI’s) from Islamic finance are very unrealistic<br>
slide24. Typical Balance Sheet of an Islamic Bank<br>
slide25. How is Islamic Finance Different from Conventional Finance? Conventional financial institutions operate within a system based on debt and transfer of risk
This raises the probability of disconnecting financial instruments from their underlying assets
Some of the financial tools created to share risk actually resulted in a concentration and intensification of risk
In contrast, Islamic finance emphasizes asset-backing for transactions and is anchored on the principle of risk sharing
Shariah principles ensures a direct link between financial transactions and real sector activities
Shariah principles also prohibit (Gharar), the use of excessive leverage and avoids many forms of controversial complex securitization<br>
slide26. Performance of Islamic Finance During the Crisis Islamic banks escaped the direct impact of the crisis, as they were not exposed to sub-prime and toxic assets
A recent IMF Working Paper* found that the business model of Islamic banks helped them to mitigate the impact of the crisis
As Islamic banking services are more connected to the real sector, initially performed well during the crisis yet were severely hit by the second round effects:<br>
slide27. BÖLÜM BAŞLIĞI
CALIBRI BOLD 42 pt RETAIL BANKING PRODUCTS & SERVICES PRODUCTS & SERVICES<br>
slide28. CALIBRI BOLD 42 pt Product Development Steps in İslamic Banks<br>
slide29. BÖLÜM BAŞLIĞI
CALIBRI BOLD 42 pt DEPOSIT PRODUCTS<br>
slide30. CALIBRI BOLD 42 pt Deposits<br>
slide31. CALIBRI BOLD 42 pt Current Accounts No tenor
No profit or loss
No minimum cap
Withdraw and deposit any time
Any currency denomination
Based on Kard Al Hasen structure<br>
slide32. CALIBRI BOLD 42 pt Profit and Loss Sharing Accounts Flexible account tenors
Profit or loss distribution
Minimum cap applied
Withdraw and deposit at maturity only
TRL, USD, EUR denomination
No preset yield guaranteed
Based on Mudaraba agreement
No capital guarantee<br>
slide33. CALIBRI BOLD 42 pt Profit and Loss Distribution RETAIL BANKING PRODUCTS & SERVICES PLS Accounts serve as fund pools
Depositing fresh money or opening a new PLS account contribute to the level of the pool
Water in the pool (fund) is invested in highly profitable projects
Invested fund with its yield is added to the pool
If investment returns loss, it negatively effect the pool level
At maturity generated profit or loss is shared with customers<br>
slide34. CALIBRI BOLD 42 pt Profit and Loss Distribution<br>
slide35. CALIBRI BOLD 42 pt Profit and Loss Generation Unit Value: the coefficient which is assumed as 100 for the first day of the participation bank that accepts fund to ist participation accounts.
Unit value changes when profit or loss is made.
Account Value: the coefficient colculated by dividing the amount deposited to the unit value.
Unit Account Value: The value determining the the current value of the participation account and calculated through multiplying the unit value by the account value and the amount on which the account holder may lay claim to.<br>
slide36. CALIBRI BOLD 42 pt Profit and Loss Generation<br>
slide37. CALIBRI BOLD 42 pt Fund Collection Products Current Account
Participation Account (Classic, Silver, Gold, Platinum, Platinum+ Accounts)
Savings Account ( Family, Youth and Child Savings Account)
Precious Metals Current Accounts
Precious Metals Participation Accounts
Investment Account
Flexible Maturity Participation Accounts
Salary Account
Gold denominated gift cheque
Tenant’s Accounts<br>
slide38. CALIBRI BOLD 42 pt Banking Services VIP Package
Special Fund Pool
Forward transactions
Foreign currency buy and sell
Check services
Promissory Note services
Safe box
International and local money transfers
Moneygram
Gold bullion<br>
slide39. BÖLÜM BAŞLIĞI
CALIBRI BOLD 42 pt LOAN PRODUCTS<br>
slide40. CALIBRI BOLD 42 pt Main Islamic Loan Products Murabaha
Musharaka
Icara (Leasing)
Mudaraba
Istisna’
Kard Al Hasen
Salam
Tawarruq<br>
slide41. CALIBRI BOLD 42 pt Mudaraba Concept Investor provides Mudarib all the capital to fund a specific enterprise.
Mudarib does not contribute capital but contributes to management and expertise
Mudarib is responsible for the day-to-day management of the enterprise and is entitled to deduct its management fee (Mudarib fee) from profits.
If the enterprise makes a loss, the investor has to bear all the losses unless the loss has resulted from negligence on the part of the Mudarib<br>
slide42. CALIBRI BOLD 42 pt Murabaha Concept Murabaha refers to contracts in which a financial institution purchases goods upon the request of a client, who makes deferred payments that cover costs and agreed-upon profit margin for the financial institution.
Murabaha is the most widely used instrument at Kuveyt Turk with 90% of total contracts being Murabaha based.<br>
slide43. CALIBRI BOLD 42 pt Murabaha Concept Supplier Customer Bank 3. Customer buys the goods as Bank’s agent. Cost: $100 1. Execution of Murabaha Agreement. 4. Disbursement of the Facility. Facility Amount: $100 2. Bank appoints the Customer as its agent to buy the goods. 5. Bank will immediately sell the goods at $110 (cost plus a profit margin) Sale<br>
slide44. CALIBRI BOLD 42 pt Musharaka Concept Musharaka is a partnership between parties in which one or several parties supply working capital. Musharaka is widely used for joint venture investments.
Both the investor and the enterprise contribute towards the capital
The enterprise and the investor share in the profits according to the agreed proportions
Any losses of the enterprise will be borne by the investor and the enterprise according to their contributions<br>
slide45. Musharakah Shirkah or sharing
Musharakah involves a mutual contract to participate in a commercial enterprise
Determination of returns
Proportional distribution agreed in advence, usually relating to investment shares
Net profits of the business
Losses must be shared in proportion to amounts invested
Management
All partners may be involved in the management of the business
May agree in advance that one party a sleeping partner<br>
slide46. Musharakah versus equity investment Musharakah
Venture of limited duration
Partnership with joint ownership
No exit without agreement of partners
Investors obtain profit share
Little probability of asset gains when venture terminates Equity Investment
Company exists in perpetuity
Exclusive ownership by shareholders
Exit at any time if company listed
Investors get dividends
Focus on capital gains and market value of equity<br>
slide47. CALIBRI BOLD 42 pt Ijara Concept Ijara is a lease purchase contract in which a financial institution purchases capital equipment or property and leases it to an enterprise.
The bank buys the assets from the vendor
The bank then leases the asset to the customer
The bank collects periodic rentals
The title of the asset remains with the bank under an operating Ijara.
Title passes to the customer under an Ijara muntahia bittamleek, either gradually over the period of the contract or at the end.<br>
slide48. Operating ijara is a pure leasing arrangement
- Two parties to the contract, lessor and lessee
- Rental payment provides an income stream
- Contract of fixed duration but renewal possible
Owner and lessee responsibilities
- The lessee can be requiered to maintain equipment on a periodic basis
- Owner responsible for loss or damage to asset beyond control of lessee
-Lessee can indemnify owner against misuse or negligence caused by lessee Ijara Concept<br>
slide49. Conditions & Limitations of Ijara Property being leased must have a valuable use
House or business premises should be occupied, not a mere speculative purchase
Leased property cannot be used for purposes other than specified in the leasing department
Non halal use would contravene shariah
Restrictive covenants may be included in new leases but uncertainties of conversion with existing leases<br>
slide50. Hire Purchase Ijara wa iqtina or ijara muntahia bittamleek is a hire purchase contract
Leased asset passes as a gift or a sale at the end of the lease period
Purchase possible during the lease period if the remaining rental installments paid
Gradual transfer of ownership also possible rather than an outright sale
Lower risk as lessee has ownership stake<br>
slide51. CALIBRI BOLD 42 pt Istisna’ Concept Istisna’a is primarily a deferred delivery sale contract similar to Salam. It is similar to conventional work in progress financing for capital project. In practice it is usually used for construction and trade finance such as pre-shipment export finance.<br>
slide52. Contract to acquire goods on behalf of a third party
Price paid to a manufacturer in advance of goods being purchased
Payments received cover wages and costs of input supplies
Applied to production of specific times
Delivery at an agreed date Istisna’ Concept<br>
slide53. Parallel Istisna Concept Islamic Investors Operator Project Manager Investment Bank Deferred Payments Payment for sale of receivables Payment for supplies Facility handover & payment to project manager<br>
slide54. Tawarruq Concept Bank buys and owns the commodity
Commodity sold to the client at a mark-up
Purchaser can authorise bank to sell commodity for a service commission
Sale value deposited into clients account
Client repays amount plus mark-up as deferred lump sun or in installments<br>
slide55. Tawarruq Concept Vendor Islamic Bank Client Third Party Initial transfer of title Payment Final transfer of title Payment Sale Deferred Payment Plus Mark-Up Tawarruq<br>
slide56. Salam Concept Financier pays price of commodity in advance in full
Quantity and delivery date and place specified
Financier may enter parallel salam to sell commodity at a slightly higher price if period shorter to delivery
Price differential represents financier’s profit
Risk involved to justify profit as time period of contracts may not coincide and financier exposed<br>
slide57. Parallel Salam Concept Investor Asset for 90 day delivery Client Payment in full at inception Euros 950.000 Asset delivery to client Payment to Investor after 30 days, Euros 965.000 Euros 1.000.000 Euros 960.000 Sale of asset for spot price<br>
slide58. Wakala Concept A contract appointing an agent to act on behalf of a principal party
Parallel with granting a power of attorney or an enduring power of attorney
Wakil may be paid a fee, rather than sharing in profit as with mudarabah<br>
slide59. Wakala Structure Principal Shariah Board Wakil Investments<br>
slide60. CALIBRI BOLD 42 pt Fund Utilization Products Home Equity Loan
Mortgage Loan
Auto Loan
Personal Loan (Home renovation, Education, Travel, Home/Office equipment loans)
Small Business Loan
Decreasing installment home loan
Consumer Price Indexed loan
Rent Finance
Leasing
Letter of Guarantee
Letter of Credit<br>
slide61. BÖLÜM BAŞLIĞI
CALIBRI BOLD 42 pt CARD PRODUCTS<br>
slide62. CALIBRI BOLD 42 pt Card Products Principal Member of
Principal Member of
Member of<br>
slide63. CALIBRI BOLD 42 pt Card Products<br>
slide64. BÖLÜM BAŞLIĞI
CALIBRI BOLD 42 pt ADC PRODUCTS<br>
slide65. CALIBRI BOLD 42 pt ADC Products POS Services
Internet Branch Banking
ATM Services
Kiosk Services
SMS Banking
Telephone Banking
Mobile Banking
Bill Payment
Tax Payment
Customs Payment
Salary Payment
Social Security Payment
Corporate website management<br>
slide66. CALIBRI BOLD 42 pt ADC Products-ATM 120 ATM
Membership of Common Point
Network (6000 ATM)
1.5 Million Transactions a year
Mark-up on cash advance
Not permitted<br>
slide67. CALIBRI BOLD 42 pt ADC Products-POS 120 ATM
Membership of Common Point
Network (6000 ATM)
1.5 Million Transactions a year
Mark-up on cash advance
Not permitted<br>
slide68. BÖLÜM BAŞLIĞI
CALIBRI BOLD 42 pt Thank You<br>