04
Real Options 2019 4 INTRODUCTION Real Options:
Why Options?
Because the holder is given the right but not the obligation to choose the alternative that best suits her interest;
Why “Real”?
Because they relate to real assets instead of financial assets
Often concerns “intangibles” of corporation =no immediate +cash flow<br>
05
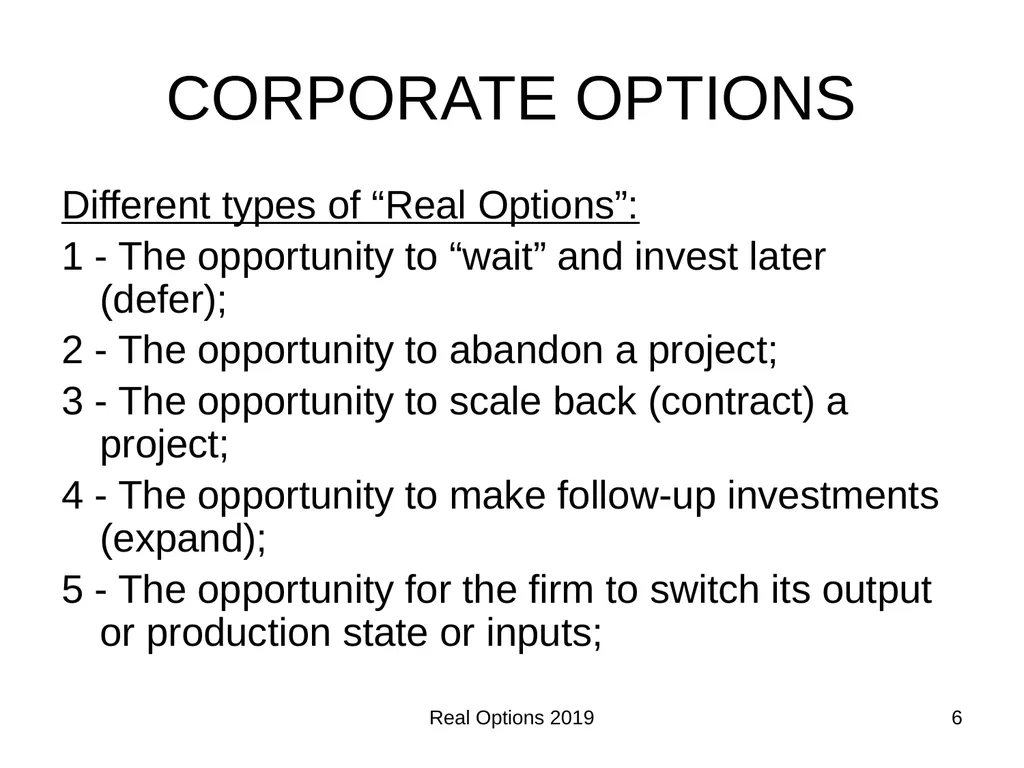
Real Options 2019 5 INTRODUCTION The value of real options depends on six variables:
Value of the underlying asset;
Investment cost;
Time to maturity (expiration);
Volatility in the value of the underlying asset;
Risk free interest rate; and
Expected dividends paid on the underlying asset, or other “deemed” payouts during project.<br>
06
Real Options 2019 6 CORPORATE OPTIONS Different types of “Real Options”:
1 - The opportunity to “wait” and invest later (defer);
2 - The opportunity to abandon a project;
3 - The opportunity to scale back (contract) a project;
4 - The opportunity to make follow-up investments (expand);
5 - The opportunity for the firm to switch its output or production state or inputs;<br>
07
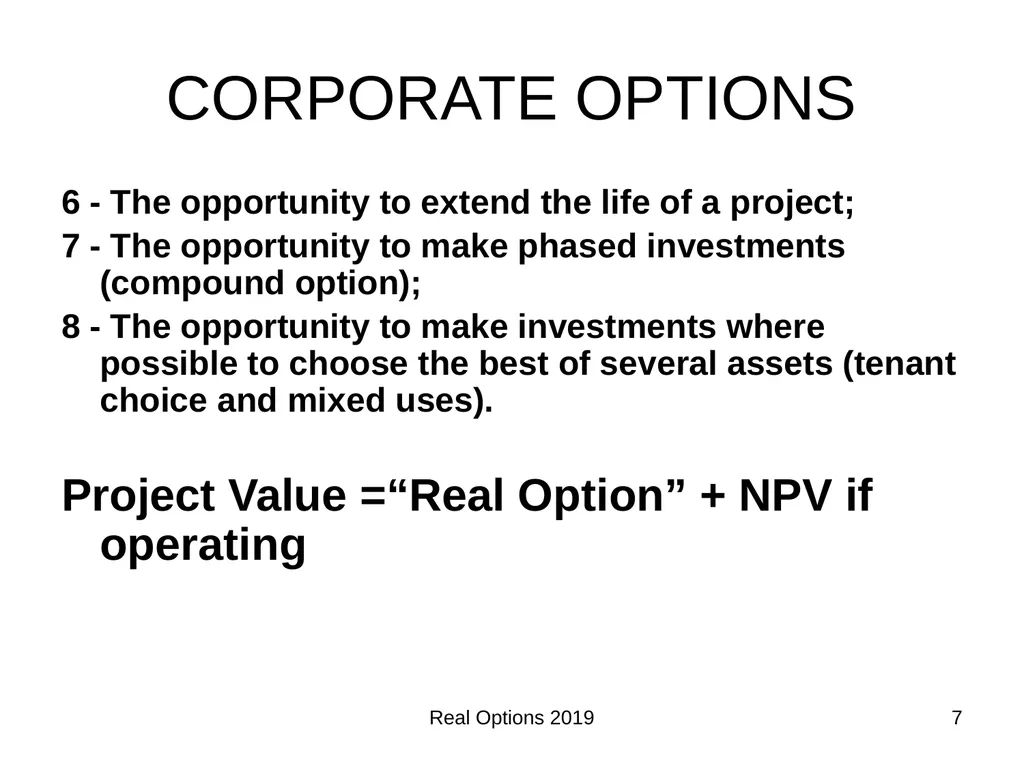
Real Options 2019 7 CORPORATE OPTIONS 6 - The opportunity to extend the life of a project;
7 - The opportunity to make phased investments (compound option);
8 - The opportunity to make investments where possible to choose the best of several assets (tenant choice and mixed uses).
Project Value =“Real Option” + NPV if operating<br>
08
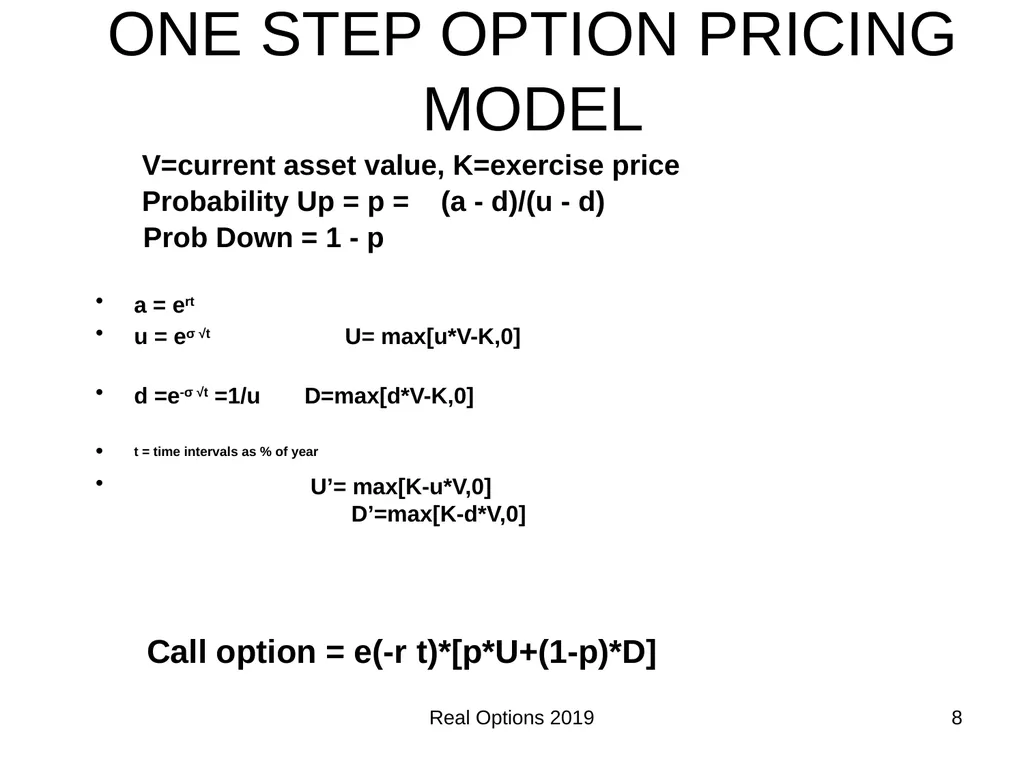
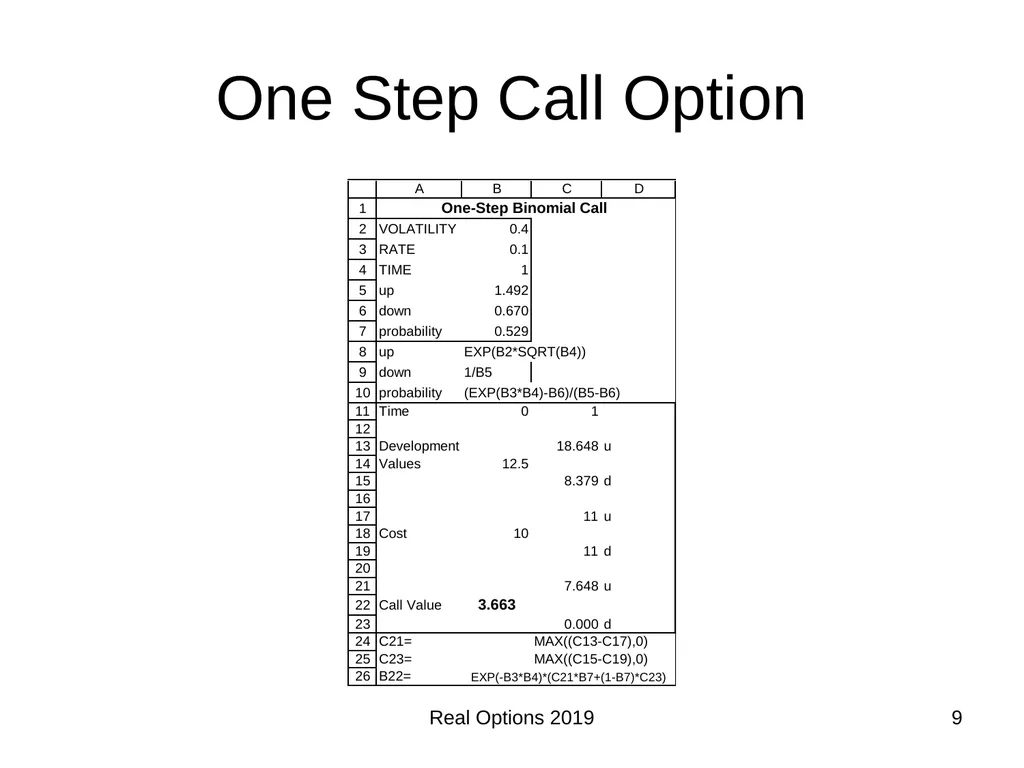
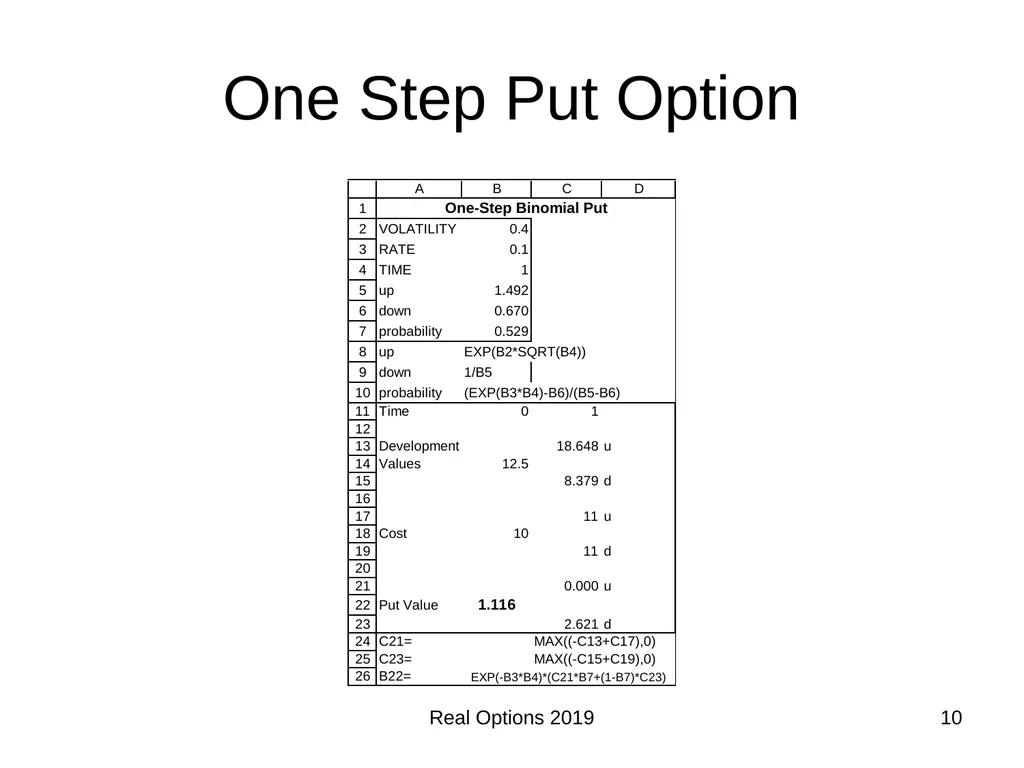
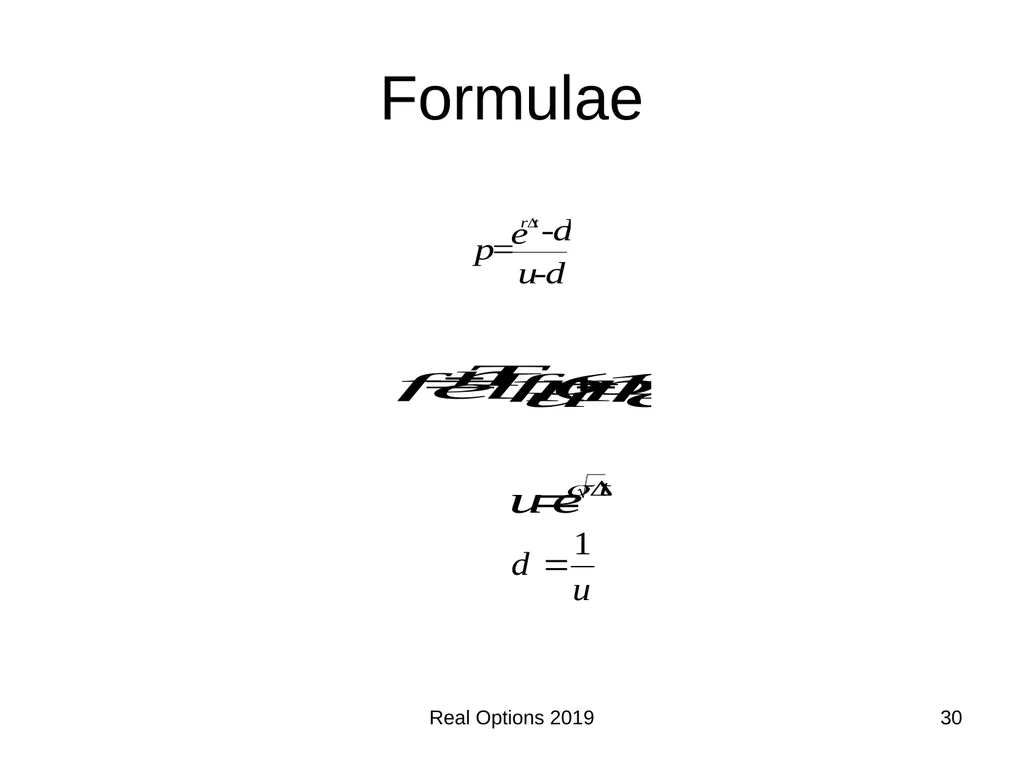
Real Options 2019 8 V=current asset value, K=exercise price
Probability Up = p = (a - d)/(u - d)
Prob Down = 1 - p
a = ert
u = eσ √t U= max[u*V-K,0]
d =e-σ √t =1/u D=max[d*V-K,0]
t = time intervals as % of year
U’= max[K-u*V,0] D’=max[K-d*V,0]
Call option = e(-r t)*[p*U+(1-p)*D]
Put option = e(-r t)*[p*U’+(1-p)*D’] ONE STEP OPTION PRICING MODEL<br>
09
Real Options 2019 9 One Step Call Option<br>
10
Real Options 2019 10 One Step Put Option<br>
11
Real Options 2019 11 CONSTRÓI CASE STUDY CONSTRÓI, SA, a real estate developer based in the north of Portugal, can start a housing development on a farm close to Almada. The farm is derelict; it is not possible to carry on any type of farming on the site.
Immediate development of the project cost €10 million (in present value terms).
Gross present value of the development is €12.5 million. The volatility of real estate developments has been 40% in Portugal.<br>
12
Real Options 2019 12 CONSTRÓI CASE STUDY During the next year, it is expected that house prices will increase by u%, or alternatively, prices might drop by approximately d%.
The risk free interest rate is 10% p.a.
Development costs are expected to grow at 10% p.a.<br>
13
Real Options 2019 13 CONSTRÓI CASE STUDY If the development does not start during the year, it is expected that the area developed in the neighbourhood of the farm will become so dense, that the City Council will declare the farm site a public utility.
The Council has already submitted a proposal to buy the land for €1.2 million at the end of the year.<br>
14
Real Options 2019 14 CONSTRÓI CASE STUDY Call option to invest in developing a site combined with a European put to sell at a fixed price.
CONSTRÓI’s management team is trying to decide whether to start the development now or to wait until the situation in the housing market is clearer.<br>
15
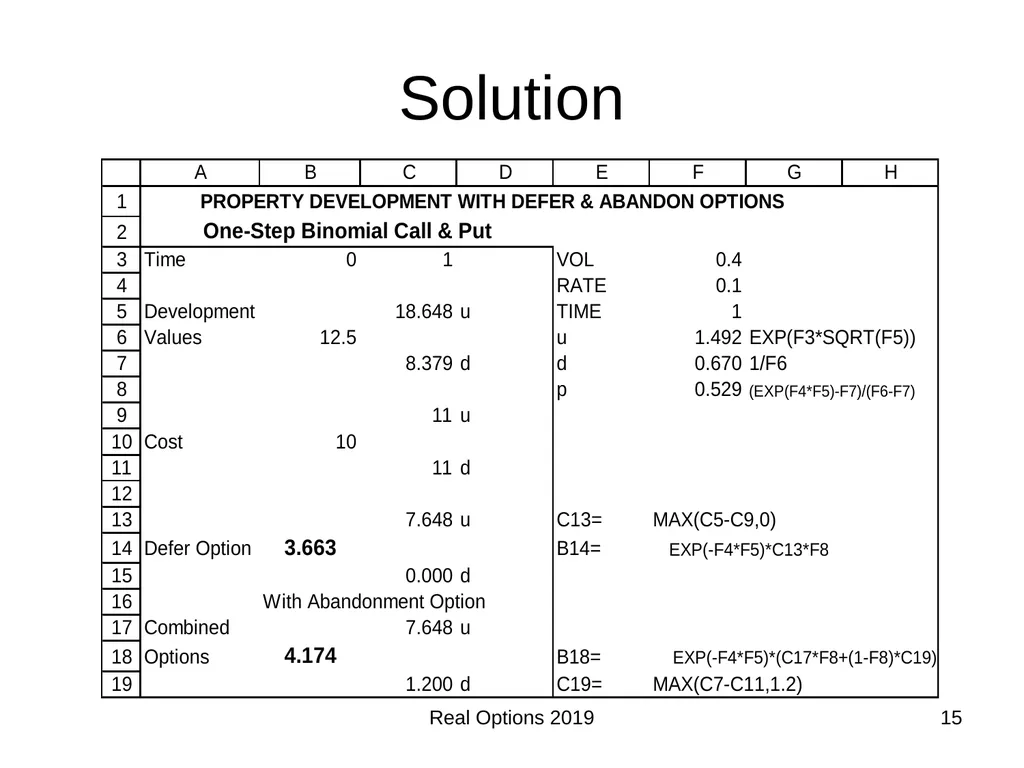
Real Options 2019 15 Solution<br>
16
Real Options 2019 16 CONSTRÓI CASE STUDY Conclusion:
In the current situation, the best solution would be to wait before investing;
Abandonment is also valuable
The value of the option to defer is higher than the expected NPV of investing immediately. Consequently, the current value of the farm is the combined real call and put option value.<br>
17
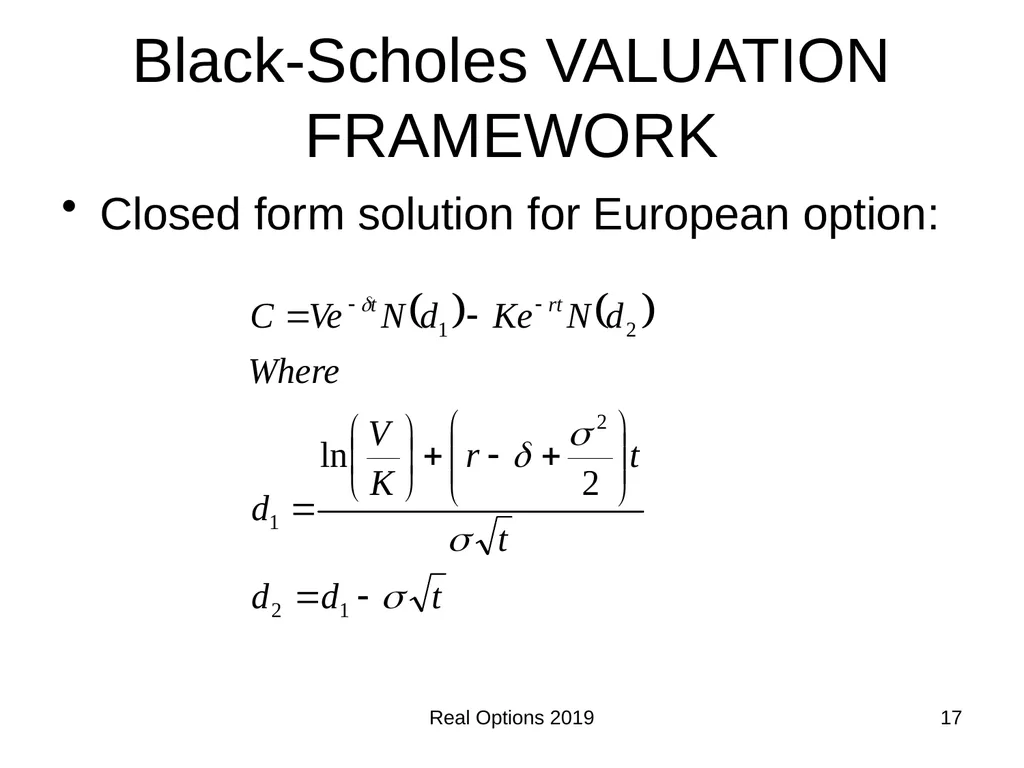
Real Options 2019 17 Black-Scholes VALUATION FRAMEWORK Closed form solution for European option:<br>
18
Real Options 2019 18 Black-Scholes Limitations d is the dividend or convenience yield
Finite, European and Fixed Investment Cost
Doesn’t Yield Best Time to Invest
Thus inappropriate for an improvement over NPV rule for capital budgeting
Yet, easy to use, so rapid check on reality of real option approach
Format used for Finite Collars<br>
19
Real Options 2019 19 DEFERRAL OPTION A deferral option is normally an option found in most projects where the owner holds the right to delay the date at which the project will start to be developed.<br>
20
Real Options 2019 20 DEFERRAL OPTION Example - Defer
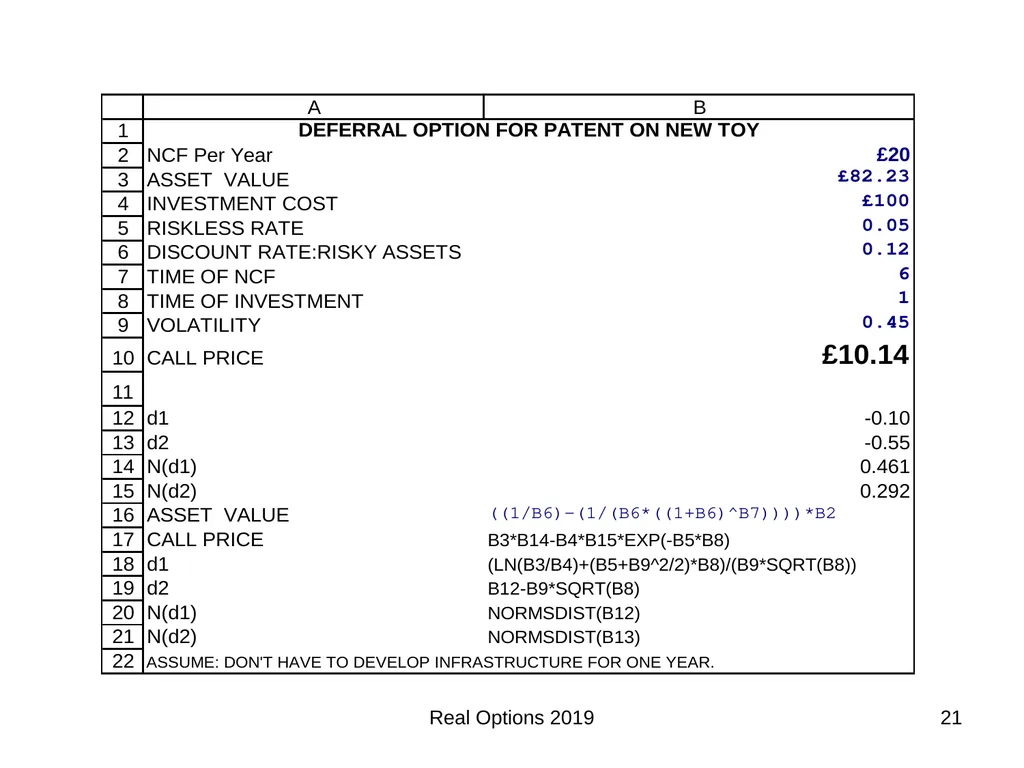
A patent for a new toy can be bought. In order to develop the infrastructure needed to make and sell the product it is necessary to invest £100. Under normal circumstances, the toy should be able to generate net profits of £20 a year for 6 years. Starting in one year, the demand for this type of product is highly uncertain, leading to an annual standard deviation of 45% in net profits. How much should one pay for the patent, if risky capital cost 12% and riskfree rate 5%?<br>
21
Real Options 2019 21<br>
22
Real Options 2019 22 DEFERRAL OPTION Main difficulties:
Definition of the time horizon
Determination of the volatility:
Similar projects;
Based on probabilities assigned to different market scenarios;
Volatility of other companies involved in similar businesses.<br>
23
Real Options 2019 23 GROWTH OPTION An option to expand or make a follow up investment is a call option, giving the corresponding holder the right or ability to enter a market or scale up its operations by paying a certain (exercise) price.<br>
24
Real Options 2019 24 OPTION TO ABANDON An option to abandon is a put option that gives its holder the right to abandon a project or market by paying the corresponding costs (exercise price).
In Constrói Case Study, abandonment at a minimum value is a type of put option.<br>
25
Real Options 2019 25 OPTION TO ABANDON Main difficulties:
Determination of abandonment value;
In some cases, it might change significantly during the life of the project;
Instead of a liquidation value, abandonment might require liquidation costs. Example is scrapping a ship versus decommissioning a nuclear power plant.<br>
26
26 SWITCHING OPTIONS Switching options are options that
allow the holder to change modes of operation at a fixed cost (e.g. switch between the cheapest of two inputs, or to the most profitable of two outputs).
Examples are switching between drilling for natural gas or natural gas liquids (propane) for six U.S. Frackers.
Switching between coal and renewables for Europe, U.S. & China.<br>
27
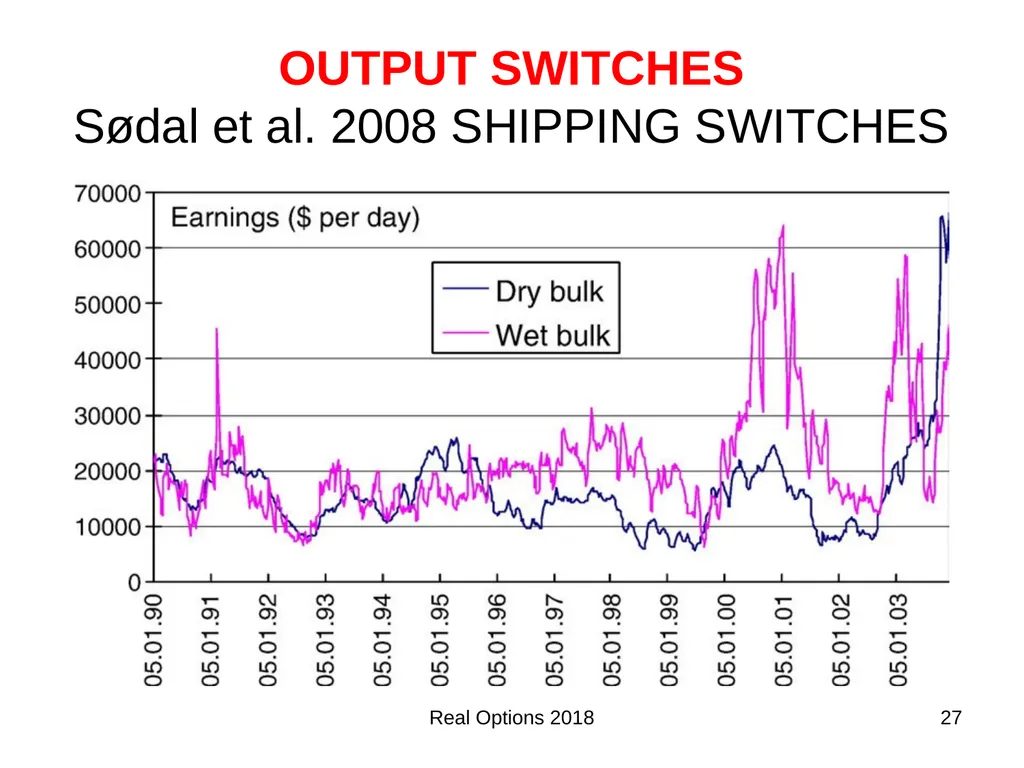
OUTPUT SWITCHES�Sødal et al. 2008 SHIPPING SWITCHES Real Options 2018 27<br>
28
Real Options 2019 28 RELEVANT QUESTION In what circumstances can a real options valuation provide a final decision that is different from a traditional NPV approach?
Real options value tends to be higher when:
Uncertainty is high;
Managers have flexibility;
The NPV is close to zero, little immediate + cash inflow, and time to defer a decision.<br>
29
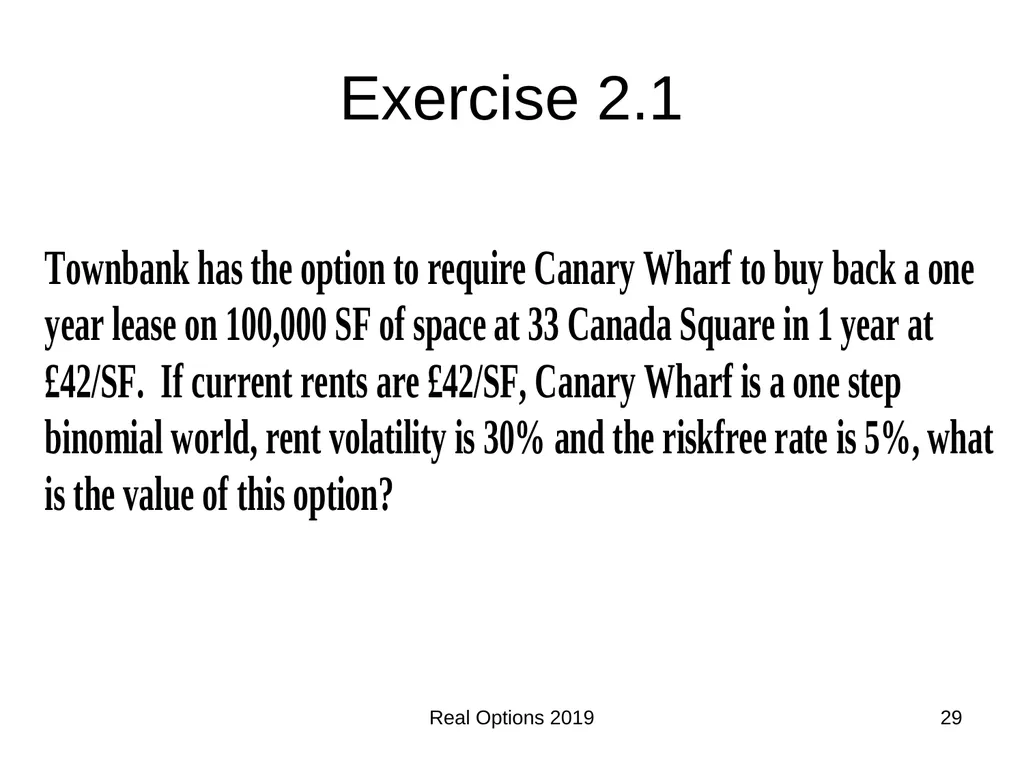
Real Options 2019 29 Exercise 2.1<br>
30
Real Options 2019 30 Formulae<br>
31
Real Options 2019 31 Review of Chapter 2 Use of Real Options
Types of Real Options: Defer, Abandon, Expand, Contract, or Switching
Defer/Abandon in one step binomial model
Defer/Growth option (using European model)<br>
32
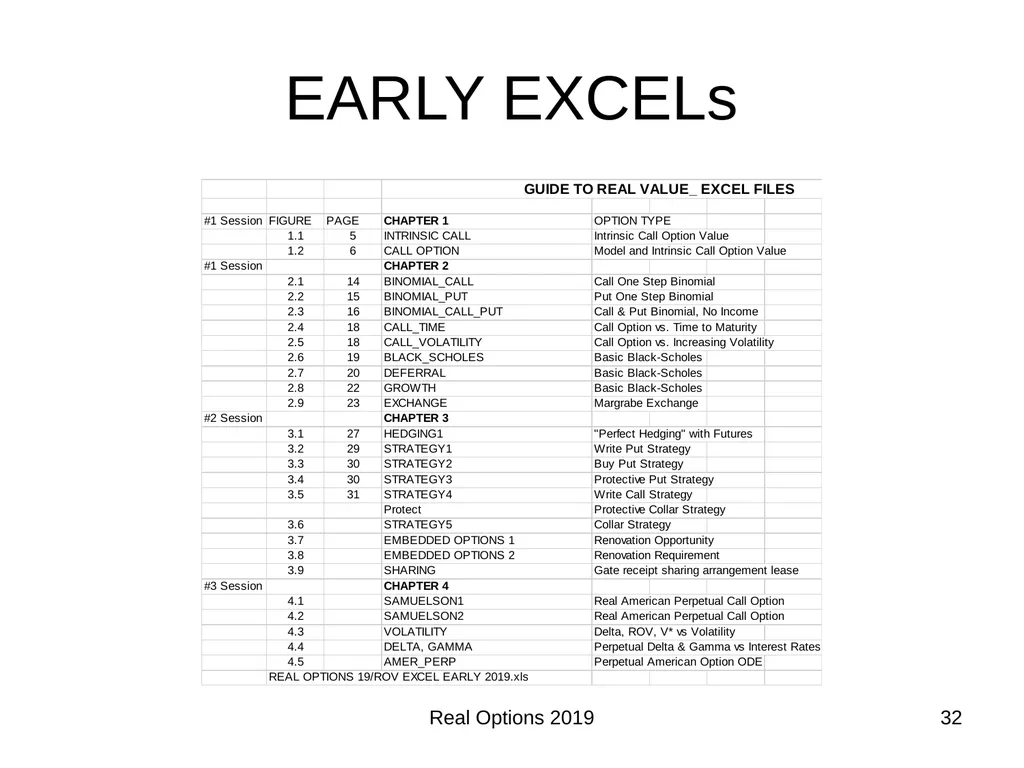
EARLY EXCELs 32 Real Options 2019<br>