
Regulation and Supervision of sukuk markets Abu



Description: Regulation and Supervision of sukuk markets Abu dhabi, UAE 20 April 2015 Sau Ngan Wong, Senior Counsel, Finance and Markets Global Practice The World Bank Group saunganwongworldbank.org Agenda - IOSCO report on Islamic capital markets -
Related Topics
Download Presentation
"Regulation and Supervision of sukuk markets Abu" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Regulation and Supervision of sukuk markets
Abu dhabi, UAE
20 April 2015 Sau Ngan Wong, Senior Counsel,
Finance and Markets Global Practice
The World Bank Group
saunganwong@worldbank.org<br>
slide2. Agenda - IOSCO report on Islamic capital markets - Distinct features of Sukuk regulatory framework - Relevant standards issued by IFSB on Sukuk - Shariah governance framework - Regulation of non-sovereign primary issuance of Sukuk - Regulation of secondary market of Sukuk - Examples of country approaches to regulation of Sukuk - Key challenges to regulation & supervision of Sukuk markets<br>
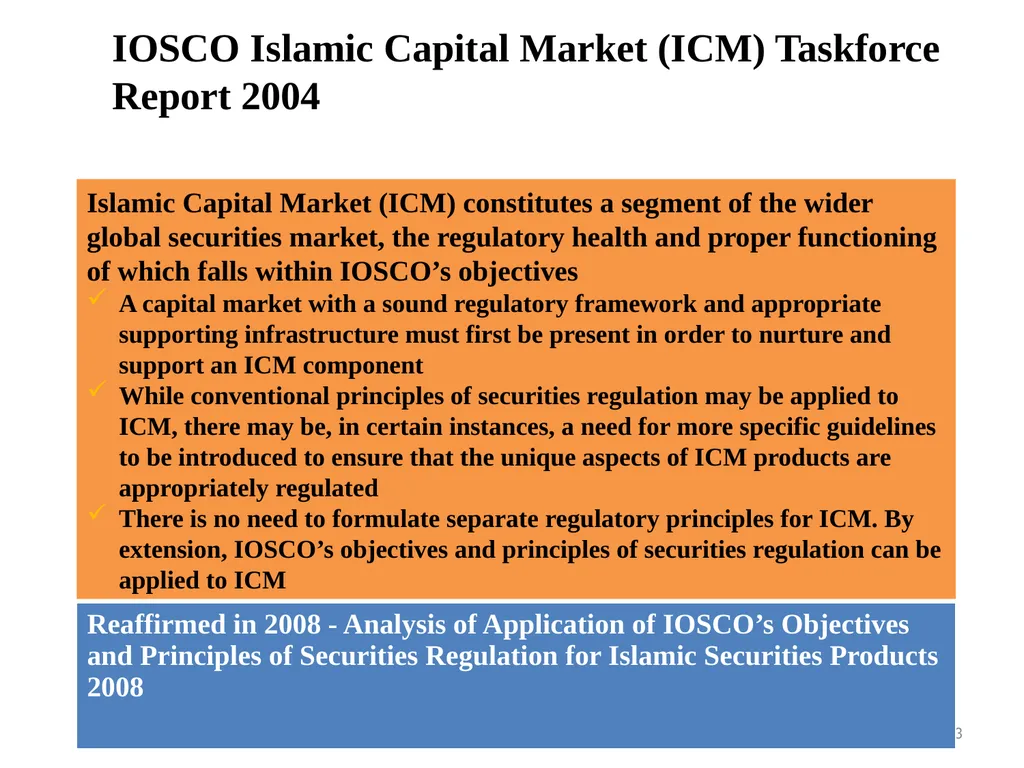
slide3. Islamic Capital Market (ICM) constitutes a segment of the wider global securities market, the regulatory health and proper functioning of which falls within IOSCO’s objectives
A capital market with a sound regulatory framework and appropriate supporting infrastructure must first be present in order to nurture and support an ICM component
While conventional principles of securities regulation may be applied to ICM, there may be, in certain instances, a need for more specific guidelines to be introduced to ensure that the unique aspects of ICM products are appropriately regulated
There is no need to formulate separate regulatory principles for ICM. By extension, IOSCO’s objectives and principles of securities regulation can be applied to ICM IOSCO Islamic Capital Market (ICM) Taskforce Report 2004 3<br>
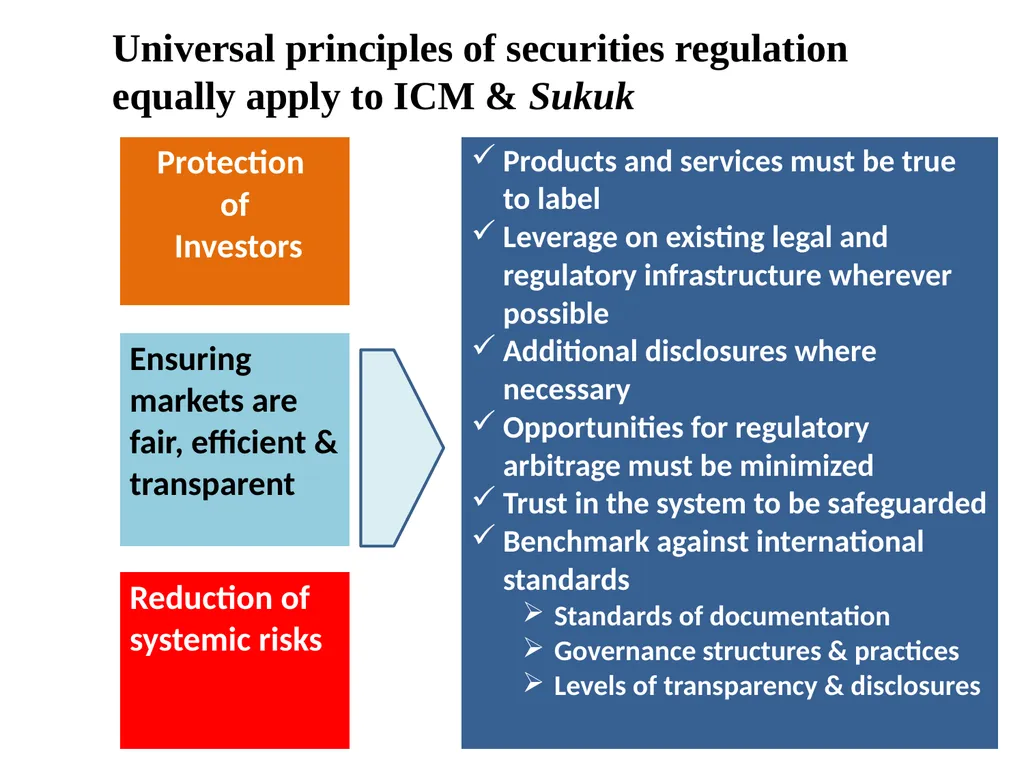
slide4. Universal principles of securities regulation equally apply to ICM & Sukuk 4<br>
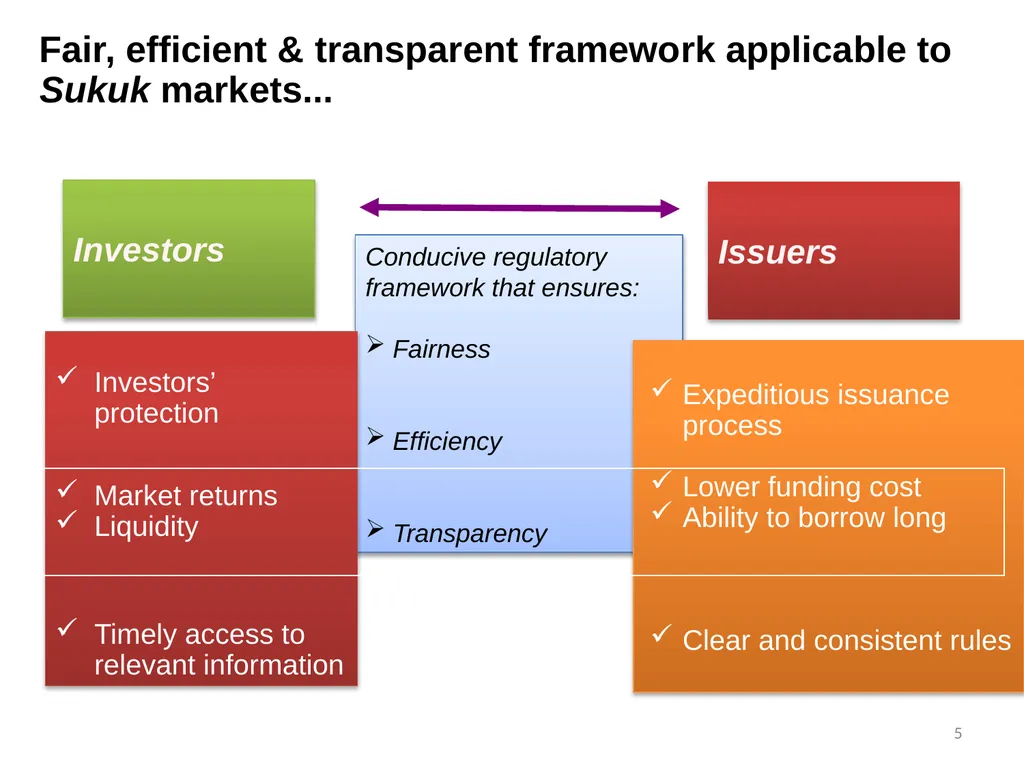
slide5. 5 Fair, efficient & transparent framework applicable to Sukuk markets... Investors Issuers Conducive regulatory framework that ensures:
Fairness
Efficiency
Transparency Investors’ protection
Market returns
Liquidity
Timely access to relevant information Expeditious issuance process
Lower funding cost
Ability to borrow long
Clear and consistent rules<br>
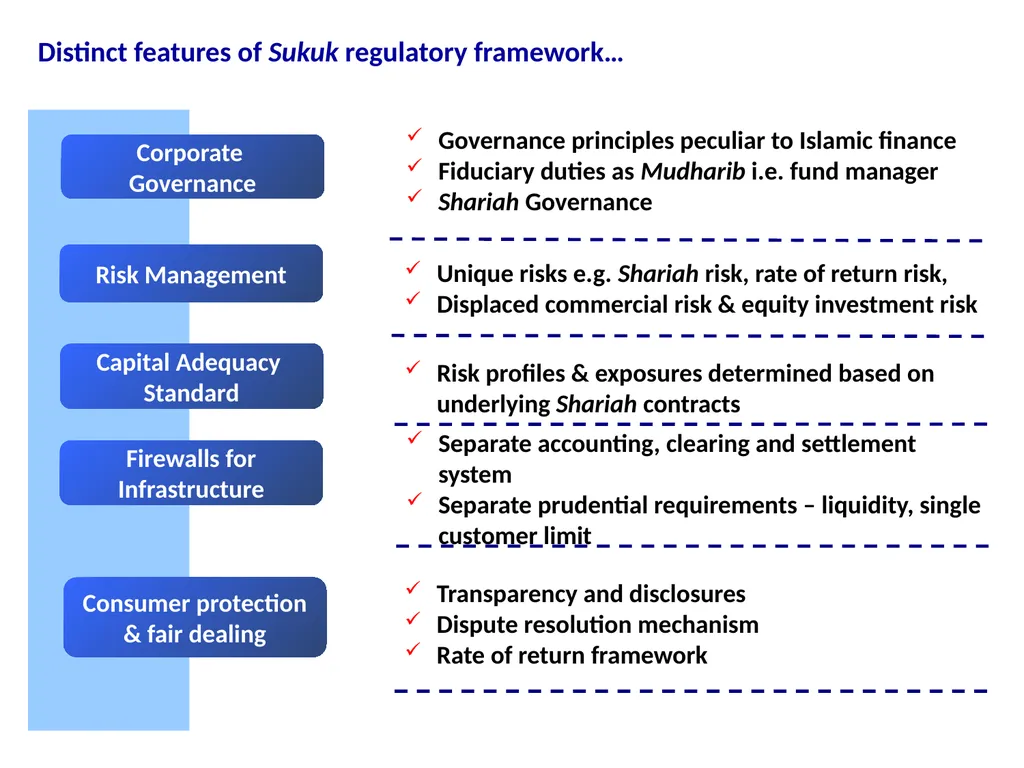
slide6. Governance principles peculiar to Islamic finance
Fiduciary duties as Mudharib i.e. fund manager
Shariah Governance Capital Adequacy
Standard Risk Management Risk profiles & exposures determined based on underlying Shariah contracts Unique risks e.g. Shariah risk, rate of return risk,
Displaced commercial risk & equity investment risk Corporate
Governance Distinct features of Sukuk regulatory framework… Consumer protection & fair dealing Firewalls for Infrastructure Separate accounting, clearing and settlement system
Separate prudential requirements – liquidity, single customer limit Transparency and disclosures
Dispute resolution mechanism
Rate of return framework<br>
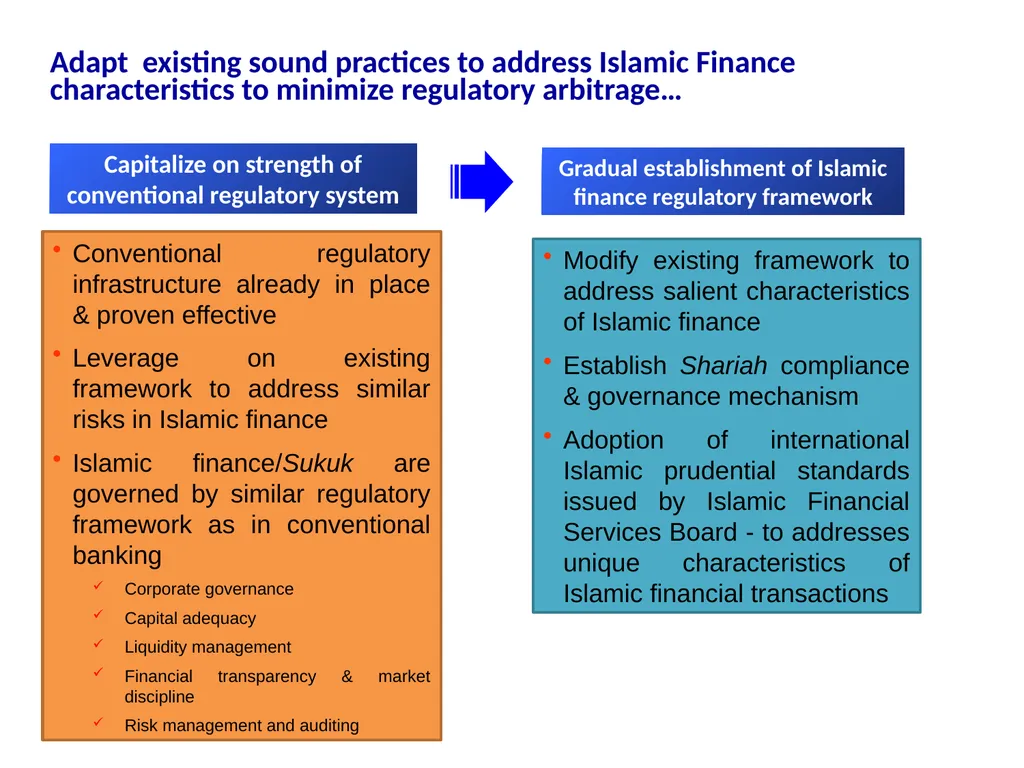
slide7. Adapt existing sound practices to address Islamic Finance
characteristics to minimize regulatory arbitrage… Capitalize on strength of conventional regulatory system Conventional regulatory infrastructure already in place & proven effective
Leverage on existing framework to address similar risks in Islamic finance
Islamic finance/Sukuk are governed by similar regulatory framework as in conventional banking
Corporate governance
Capital adequacy
Liquidity management
Financial transparency & market discipline
Risk management and auditing Gradual establishment of Islamic finance regulatory framework Modify existing framework to address salient characteristics of Islamic finance
Establish Shariah compliance & governance mechanism
Adoption of international Islamic prudential standards issued by Islamic Financial Services Board - to addresses unique characteristics of Islamic financial transactions<br>
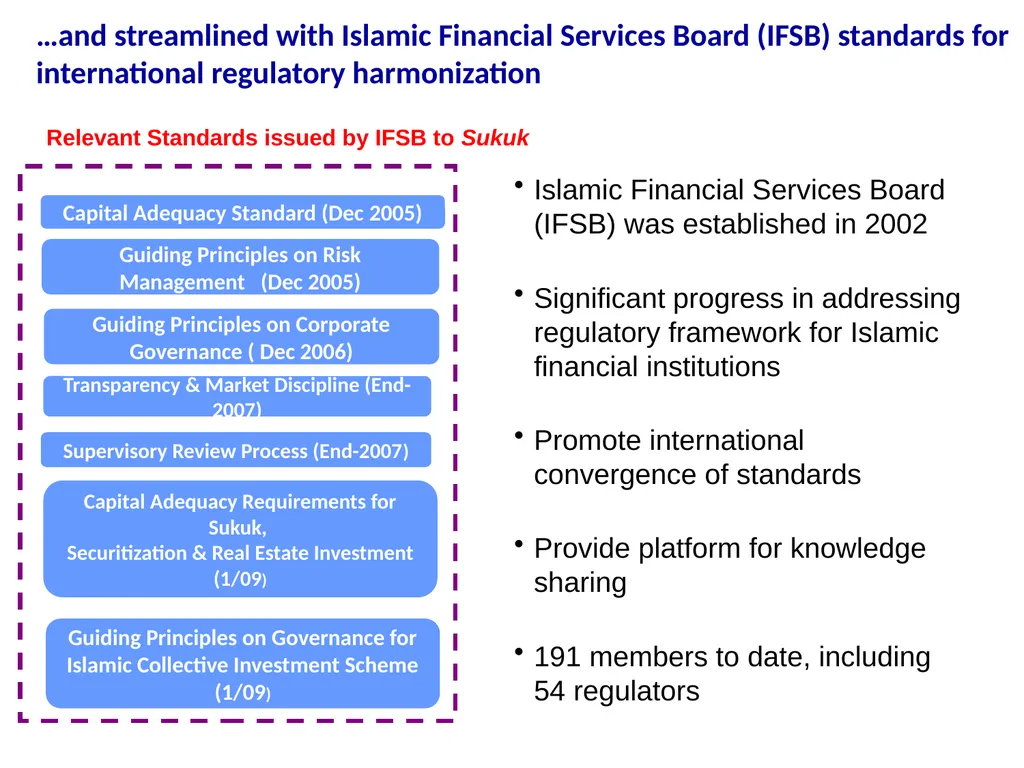
slide8. …and streamlined with Islamic Financial Services Board (IFSB) standards for international regulatory harmonization Relevant Standards issued by IFSB to Sukuk Islamic Financial Services Board (IFSB) was established in 2002
Significant progress in addressing regulatory framework for Islamic financial institutions
Promote international convergence of standards
Provide platform for knowledge sharing
191 members to date, including 54 regulators Capital Adequacy Standard (Dec 2005) Guiding Principles on Risk Management (Dec 2005) Guiding Principles on Corporate Governance ( Dec 2006) Supervisory Review Process (End-2007) Capital Adequacy Requirements for Sukuk,
Securitization & Real Estate Investment (1/09) Transparency & Market Discipline (End-2007) Guiding Principles on Governance for Islamic Collective Investment Scheme (1/09)<br>
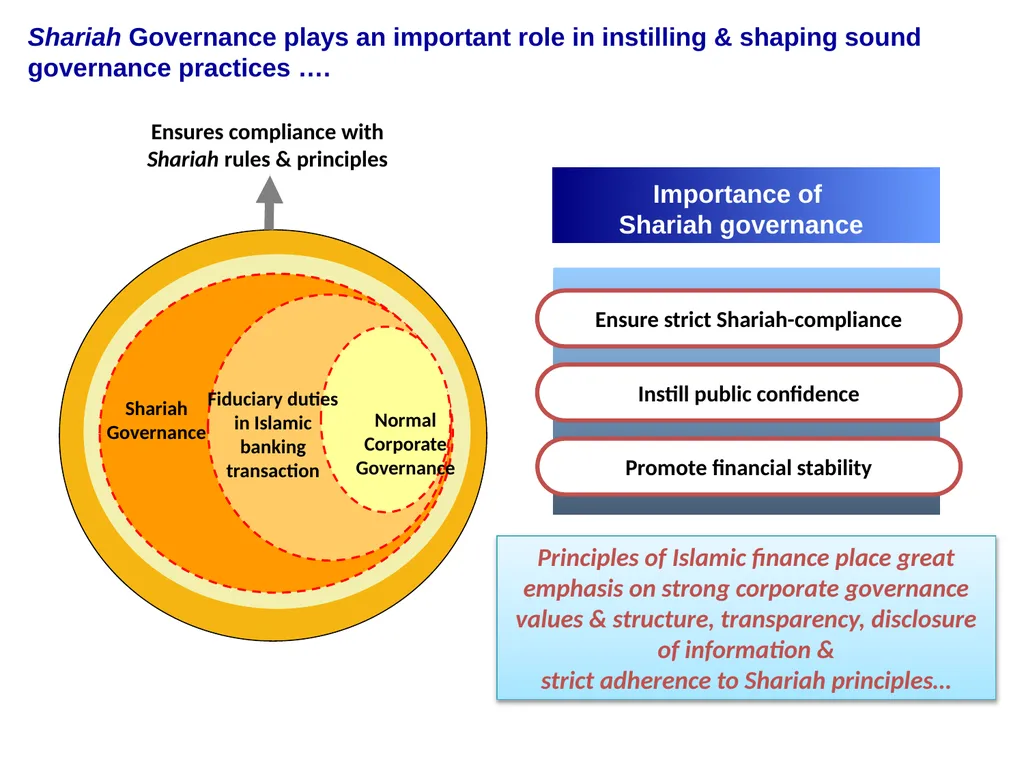
slide9. Shariah Governance plays an important role in instilling & shaping sound governance practices …. Principles of Islamic finance place great emphasis on strong corporate governance values & structure, transparency, disclosure of information &
strict adherence to Shariah principles… Fiduciary duties in Islamic banking transaction Normal
Corporate
Governance Shariah Governance Ensures compliance with Shariah rules & principles Instill public confidence Promote financial stability Ensure strict Shariah-compliance Importance of
Shariah governance<br>
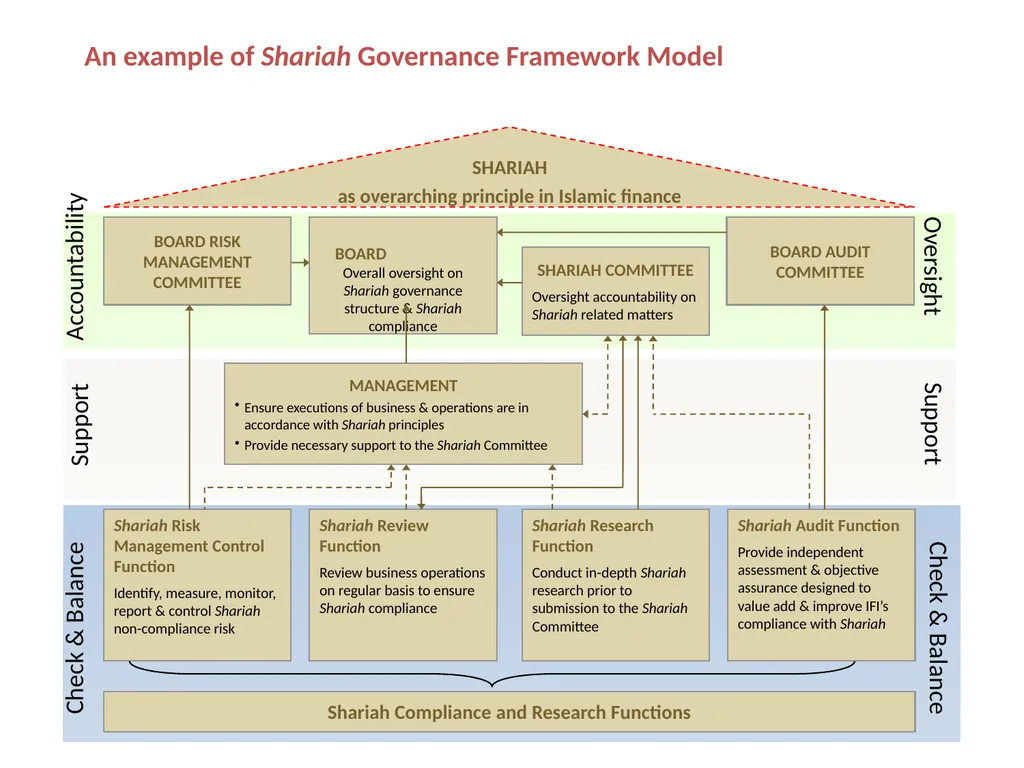
slide10. SHARIAH
as overarching principle in Islamic finance An example of Shariah Governance Framework Model BOARD RISK MANAGEMENT COMMITTEE BOARD Overall oversight on Shariah governance structure & Shariah compliance SHARIAH COMMITTEE
Oversight accountability on Shariah related matters BOARD AUDIT COMMITTEE MANAGEMENT
Ensure executions of business & operations are in accordance with Shariah principles
Provide necessary support to the Shariah Committee Shariah Risk Management Control Function
Identify, measure, monitor, report & control Shariah non-compliance risk Shariah Review Function
Review business operations on regular basis to ensure Shariah compliance Shariah Research Function
Conduct in-depth Shariah research prior to submission to the Shariah Committee Shariah Audit Function
Provide independent assessment & objective assurance designed to value add & improve IFI’s compliance with Shariah Shariah Compliance and Research Functions Accountability Oversight Support Support Check & Balance Check & Balance<br>
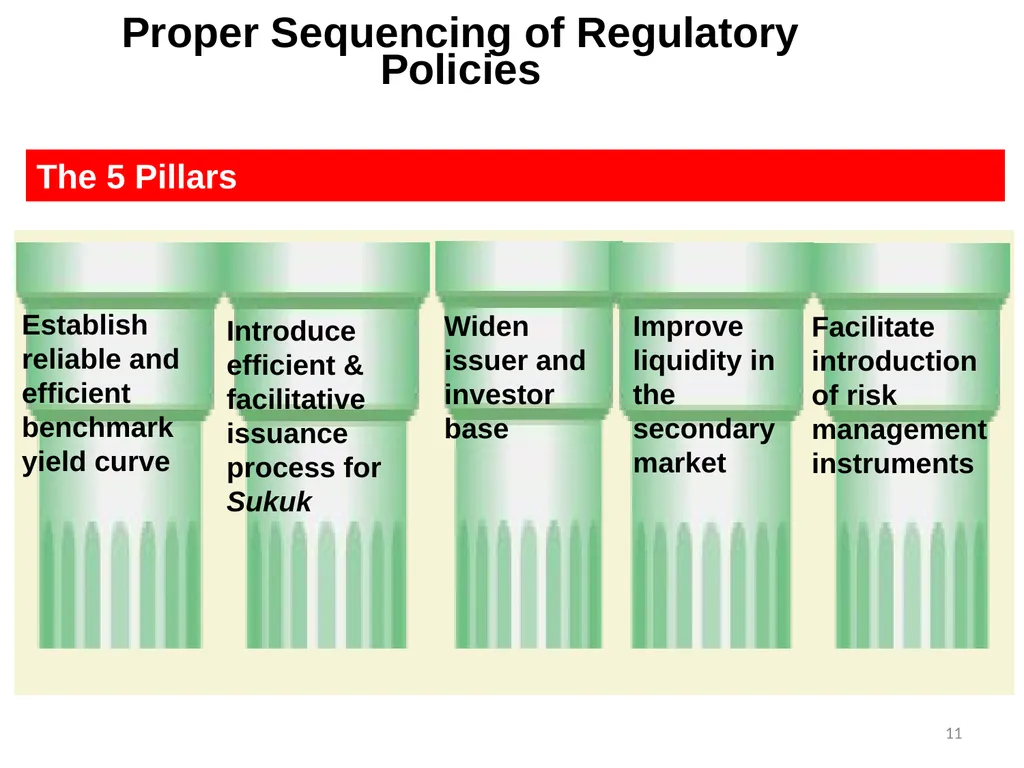
slide11. 11 Proper Sequencing of Regulatory Policies Introduce efficient & facilitative issuance process for Sukuk Widen issuer and investor base Improve liquidity in the secondary market Establish reliable and efficient benchmark yield curve Facilitate introduction of risk management instruments The 5 Pillars<br>
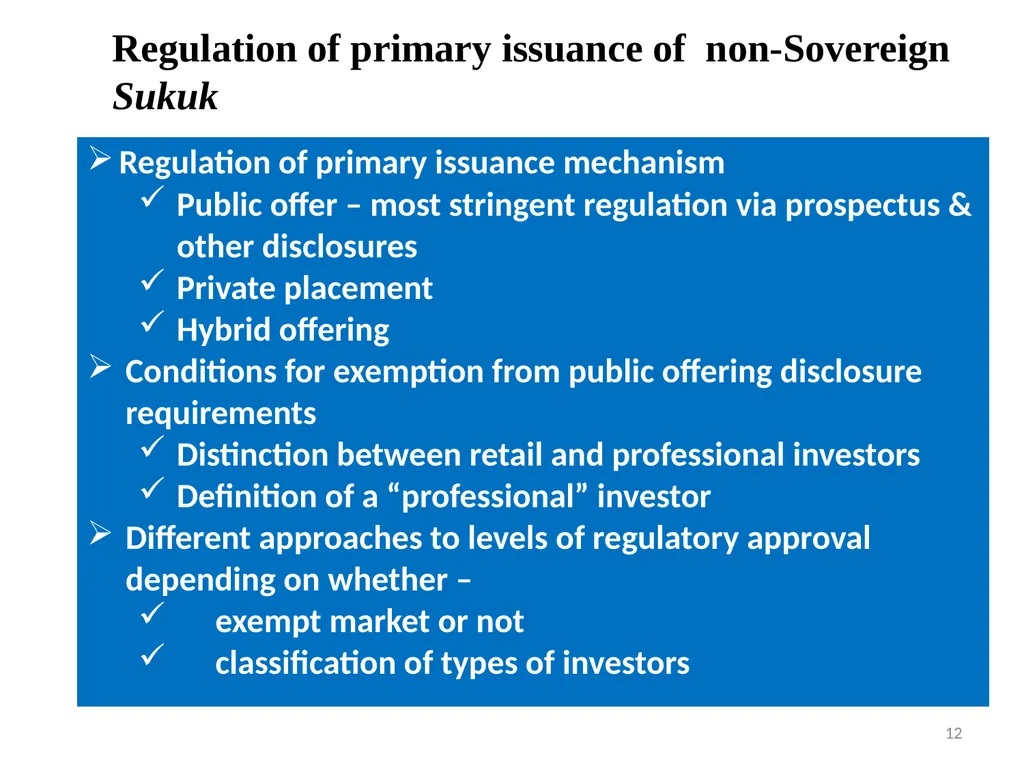
slide12. Regulation of primary issuance of non-Sovereign Sukuk 12<br>
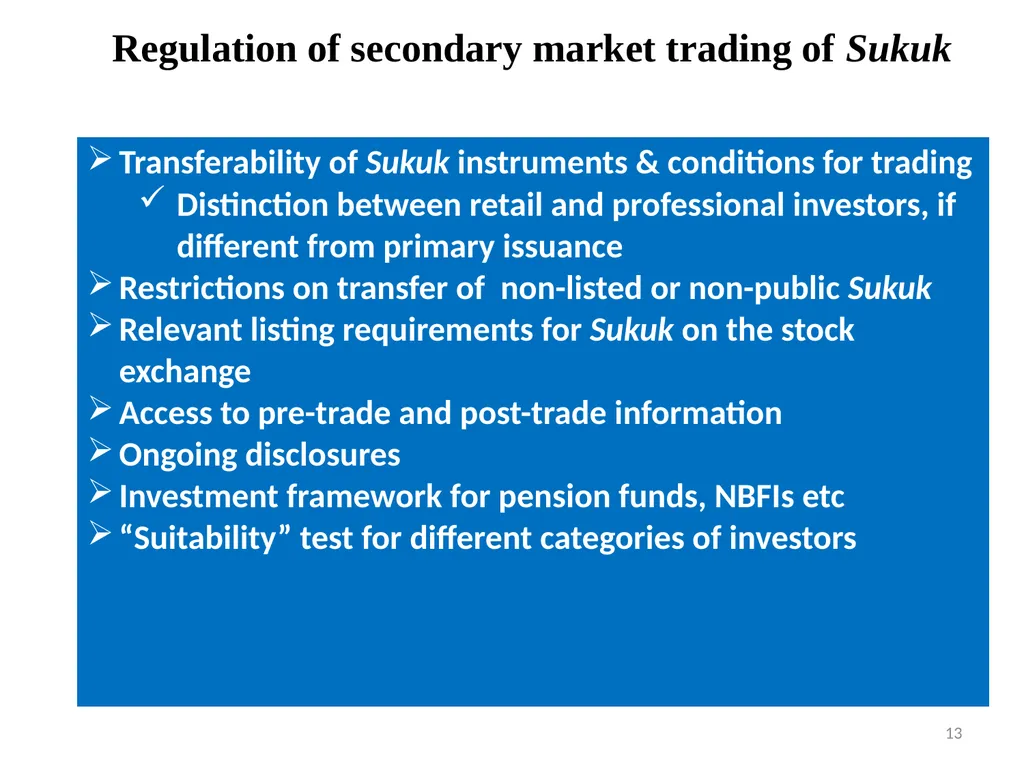
slide13. Regulation of secondary market trading of Sukuk 13<br>
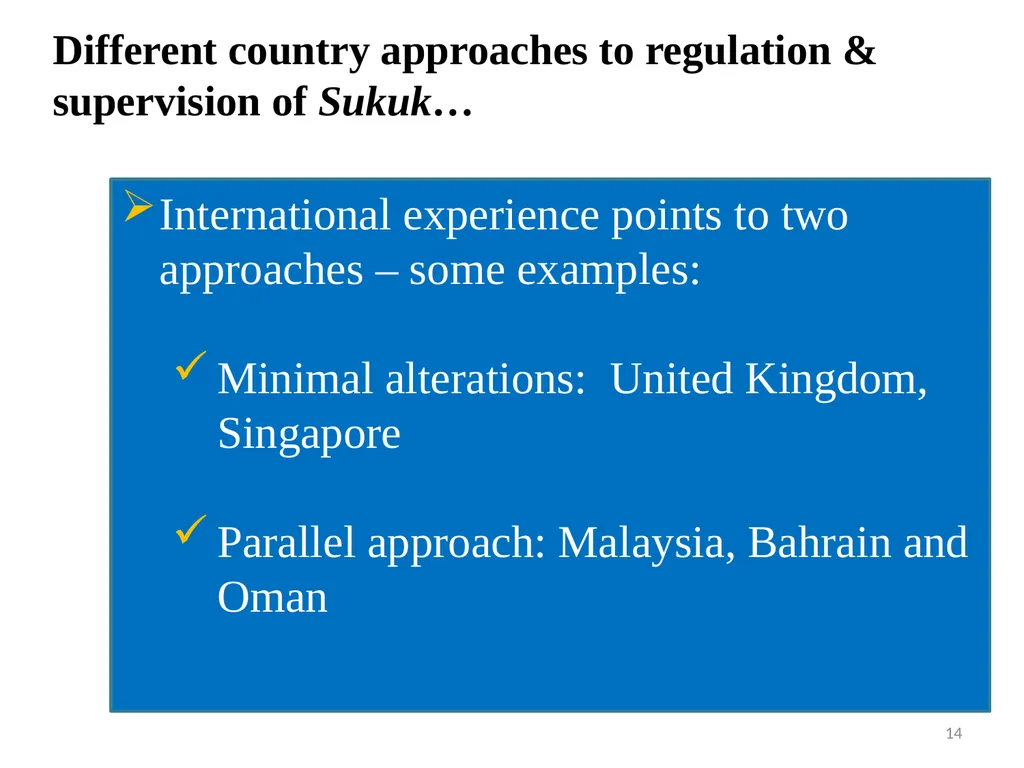
slide14. Different country approaches to regulation & supervision of Sukuk… 14 International experience points to two approaches – some examples:
Minimal alterations: United Kingdom, Singapore
Parallel approach: Malaysia, Bahrain and Oman<br>
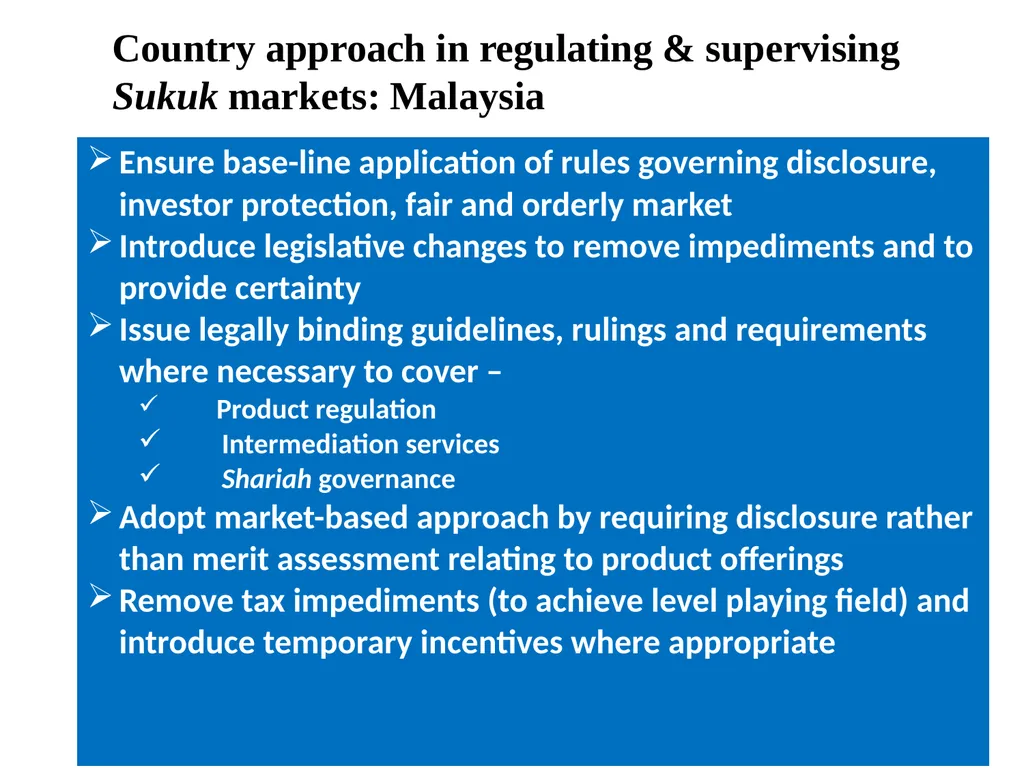
slide15. Country approach in regulating & supervising Sukuk markets: Malaysia 15<br>
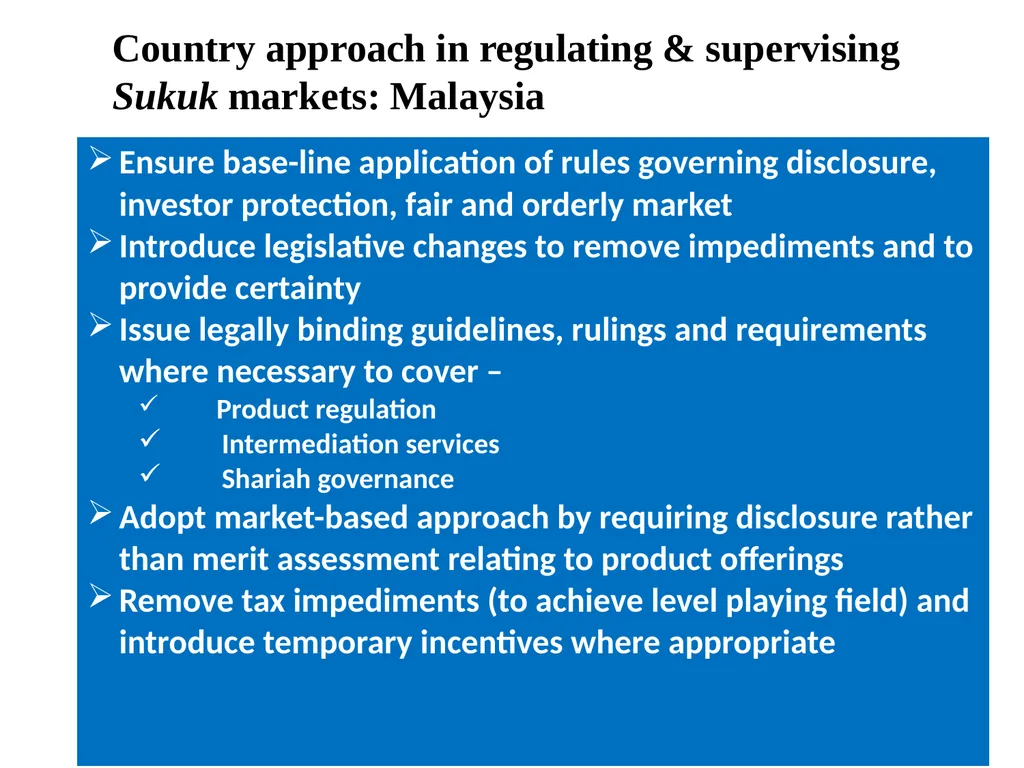
slide16. Country approach in regulating & supervising Sukuk markets: Malaysia 16<br>
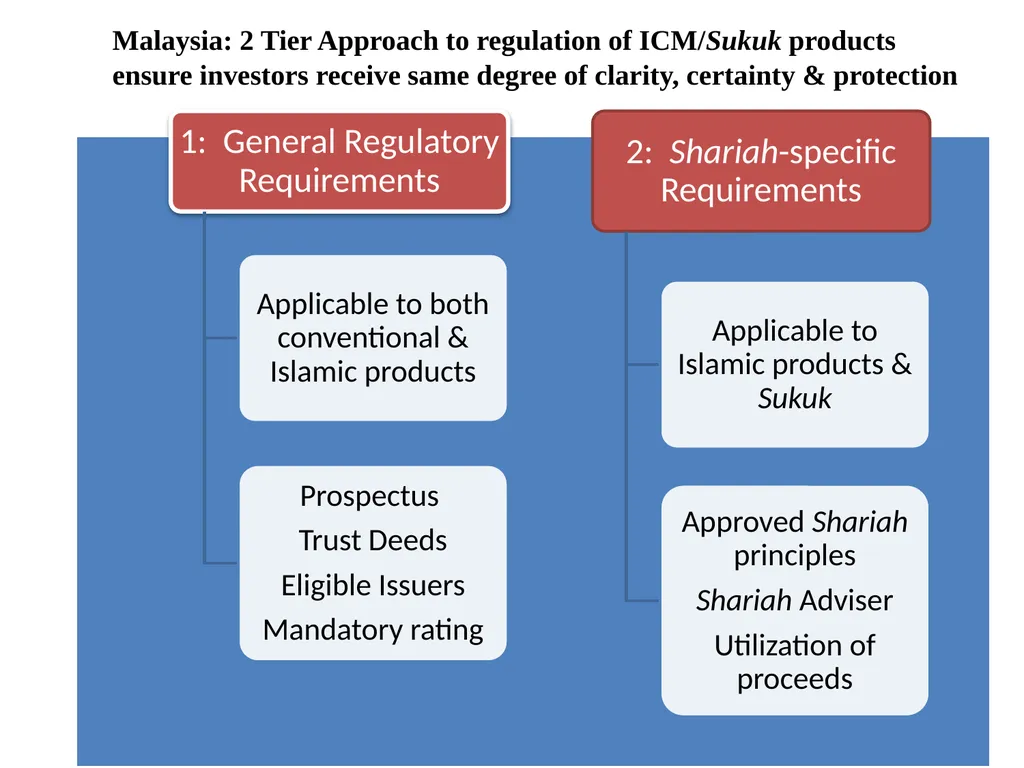
slide17. Malaysia: 2 Tier Approach to regulation of ICM/Sukuk products ensure investors receive same degree of clarity, certainty & protection 17<br>
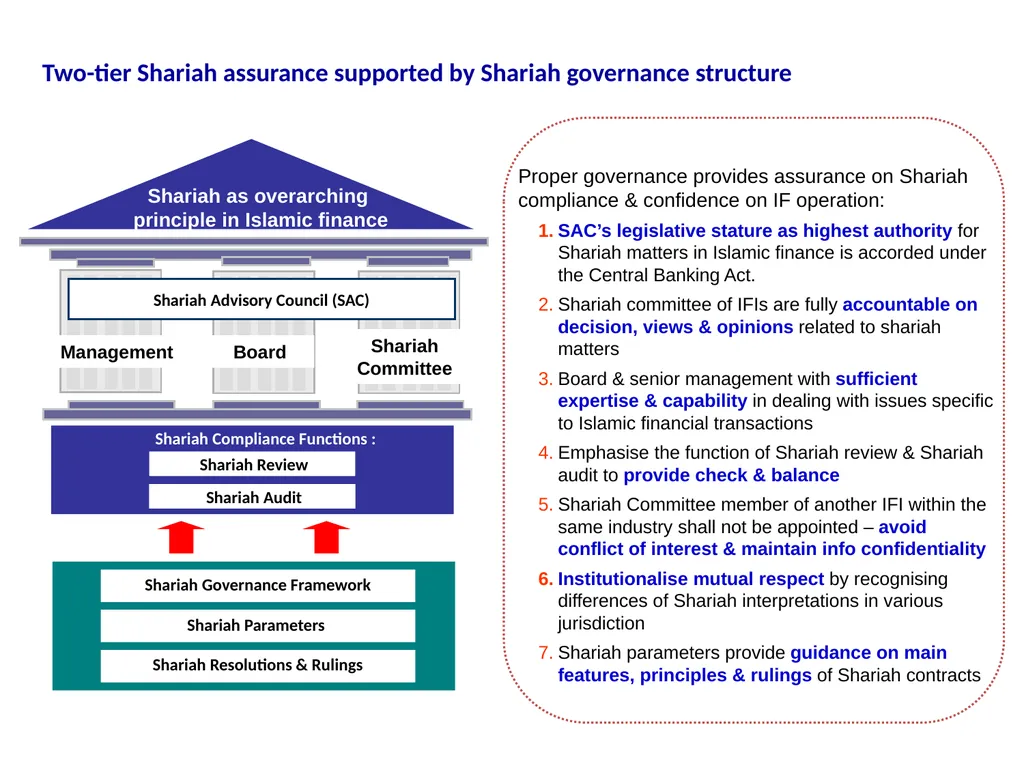
slide18. Proper governance provides assurance on Shariah compliance & confidence on IF operation:
SAC’s legislative stature as highest authority for Shariah matters in Islamic finance is accorded under the Central Banking Act.
Shariah committee of IFIs are fully accountable on decision, views & opinions related to shariah matters
Board & senior management with sufficient expertise & capability in dealing with issues specific to Islamic financial transactions
Emphasise the function of Shariah review & Shariah audit to provide check & balance
Shariah Committee member of another IFI within the same industry shall not be appointed – avoid conflict of interest & maintain info confidentiality
Institutionalise mutual respect by recognising differences of Shariah interpretations in various jurisdiction
Shariah parameters provide guidance on main features, principles & rulings of Shariah contracts Two-tier Shariah assurance supported by Shariah governance structure Shariah as overarching
principle in Islamic finance Shariah Compliance Functions : Shariah Review Shariah Audit Management Shariah Governance Framework Board Shariah Committee Shariah Advisory Council (SAC) Shariah Parameters Shariah Resolutions & Rulings<br>
slide19. Bringing regulatory framework and oversight in line with international best practices
Rebalancing tax treatment
Strengthening insolvency frameworks
Promoting standardization
Ensuring adequate liquidity for long term financing
Establishing sound risk-management practices Key Challenges to regulation & supervision of ICM/Sukuk 19<br>
slide20. Rebalancing tax treatment 20 Conventional debt often receives advantageous tax treatment (encouraging leverage), while some Islamic finance products face double taxation.
Examples of Malaysia and Thailand took steps to ensure that Islamic financial transactions operate on a level playing field:
In Malaysia, this principle has extended to ensuring that profits, asset transfers, and expatriation of profits by foreigners are treated equally, whether occurring under conventional or Islamic financial contracts.
In Thailand, a package of proposed tax changes for Sukuk issuances is making its way through the legislative process to address the main hurdles faced by Sukuk issuers.<br>
slide21. Promoting standardization 21 Lack of standardization and cohesion, especially in Sukuk products, hinders the growth potential of Islamic finance
The industry would benefit from more widely accepted benchmarks and indices.
Innovation and knowledge sharing between various market players are essential to facilitate the standardization and unification of global markets for Islamic financial products.<br>
slide22. Need to strengthen insolvency frameworks… 22 More work is needed to ensure convergence between best insolvency practices on the conventional and Shariah-compliant sides.
The need to establish reliable mechanisms for dealing with Sukuk defaults, and addressing adverse outcomes, with special adaptations for risk sharing.
Setting up these mechanisms requires the specification of parties’ rights under Shariah-compliant finance, especially in the case of cross-border transactions.<br>
slide23. 23<br>
slide24. THANK YOU Sau Ngan Wong, Senior Counsel,
Finance and Markets Global Practice
The World Bank Group
saunganwong@worldbank.org<br>
slide25. 25 II. Capital adequacy RWA 6 : Sukuk Sukūk is certificates that represent the holder’s proportionate ownership in an undivided part of an underlying asset where the holder assumes all rights and obligations to such asset ultimate customer.
Externally Rated Sukūk
Applicable risk weight will be based on the ECAI ratings in accordance with the Standardised Approach
Non Rated Sukūk
Applicable risk weight will be based on the underlying contract or on that of the issuer if there is recourse to the issuer<br>
slide26. 26 II. Capital adequacy RWA 6 : Sukuk Sukūk is certificates that represent the holder’s proportionate ownership in an undivided part of an underlying asset where the holder assumes all rights and obligations to such asset ultimate customer.
Externally Rated Sukūk
Applicable risk weight will be based on the ECAI ratings in accordance with the Standardised Approach
Non Rated Sukūk
Applicable risk weight will be based on the underlying contract or on that of the issuer if there is recourse to the issuer<br>
slide27. 27 II. Capital adequacy RWA 5 : Mudharabah Muḍārabah Investment in Project Finance
Prior to certification where funds are already advanced by the IIFS to the Muḍārib :
- Risk weight is based on the rating of either the ultimate customer or the Muḍārib
- Otherwise, 400% RW is applied to unrated Muḍārib.
After certification where amount receivable by the IIFS from the Muḍārib in respect of progress payment due to the Muḍārib from the ultimate customer:
- Risk weight is based on the credit standing of the ultimate customer on the amounts receivable by the IIFS from the Muḍārib
- Otherwise, 100% RW for unrated ultimate customer.<br>
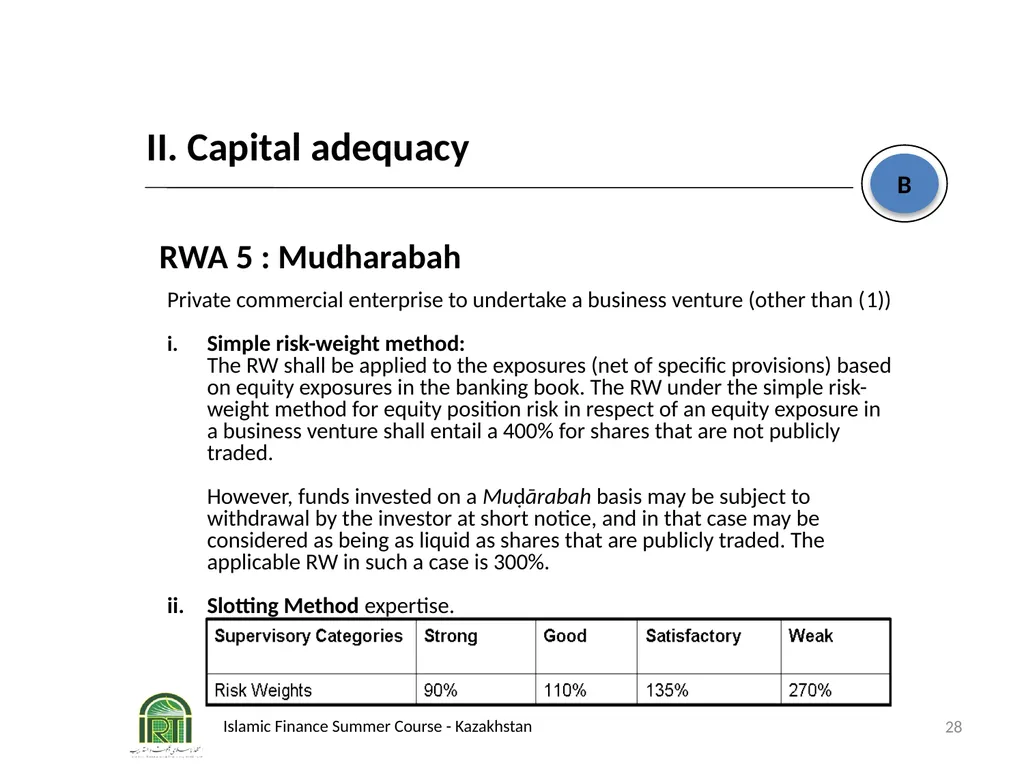
slide28. 28 II. Capital adequacy RWA 5 : Mudharabah Private commercial enterprise to undertake a business venture (other than (1))
Simple risk-weight method:
The RW shall be applied to the exposures (net of specific provisions) based on equity exposures in the banking book. The RW under the simple risk-weight method for equity position risk in respect of an equity exposure in a business venture shall entail a 400% for shares that are not publicly traded.
However, funds invested on a Muḍārabah basis may be subject to withdrawal by the investor at short notice, and in that case may be considered as being as liquid as shares that are publicly traded. The applicable RW in such a case is 300%.
Slotting Method expertise.<br>
slide29. 29 II. Capital adequacy RWA 5 : Musharakah 1. Private commercial enterprise to undertake trading activities in the foreign exchange, share and/or commodity
- The RW of a Mushārakah that invests in quoted shares shall be measured according to the equity position risk approach where positions in assets tradable in markets will qualify for treatment as equity position risk in the trading book, which would incur a total capital charge of 16% (equivalent to 200% RW).
- The capital charge can be reduced to 12% (equivalent to 150% RW) for a portfolio that is both liquid and well-diversified, subject to meeting the criteria as determined by the supervisory authorities<br>
Finance and Markets Global Practice
The World Bank Group
saunganwong@worldbank.org<br>
slide2. Agenda - IOSCO report on Islamic capital markets - Distinct features of Sukuk regulatory framework - Relevant standards issued by IFSB on Sukuk - Shariah governance framework - Regulation of non-sovereign primary issuance of Sukuk - Regulation of secondary market of Sukuk - Examples of country approaches to regulation of Sukuk - Key challenges to regulation & supervision of Sukuk markets<br>
slide3. Islamic Capital Market (ICM) constitutes a segment of the wider global securities market, the regulatory health and proper functioning of which falls within IOSCO’s objectives
A capital market with a sound regulatory framework and appropriate supporting infrastructure must first be present in order to nurture and support an ICM component
While conventional principles of securities regulation may be applied to ICM, there may be, in certain instances, a need for more specific guidelines to be introduced to ensure that the unique aspects of ICM products are appropriately regulated
There is no need to formulate separate regulatory principles for ICM. By extension, IOSCO’s objectives and principles of securities regulation can be applied to ICM IOSCO Islamic Capital Market (ICM) Taskforce Report 2004 3<br>
slide4. Universal principles of securities regulation equally apply to ICM & Sukuk 4<br>
slide5. 5 Fair, efficient & transparent framework applicable to Sukuk markets... Investors Issuers Conducive regulatory framework that ensures:
Fairness
Efficiency
Transparency Investors’ protection
Market returns
Liquidity
Timely access to relevant information Expeditious issuance process
Lower funding cost
Ability to borrow long
Clear and consistent rules<br>
slide6. Governance principles peculiar to Islamic finance
Fiduciary duties as Mudharib i.e. fund manager
Shariah Governance Capital Adequacy
Standard Risk Management Risk profiles & exposures determined based on underlying Shariah contracts Unique risks e.g. Shariah risk, rate of return risk,
Displaced commercial risk & equity investment risk Corporate
Governance Distinct features of Sukuk regulatory framework… Consumer protection & fair dealing Firewalls for Infrastructure Separate accounting, clearing and settlement system
Separate prudential requirements – liquidity, single customer limit Transparency and disclosures
Dispute resolution mechanism
Rate of return framework<br>
slide7. Adapt existing sound practices to address Islamic Finance
characteristics to minimize regulatory arbitrage… Capitalize on strength of conventional regulatory system Conventional regulatory infrastructure already in place & proven effective
Leverage on existing framework to address similar risks in Islamic finance
Islamic finance/Sukuk are governed by similar regulatory framework as in conventional banking
Corporate governance
Capital adequacy
Liquidity management
Financial transparency & market discipline
Risk management and auditing Gradual establishment of Islamic finance regulatory framework Modify existing framework to address salient characteristics of Islamic finance
Establish Shariah compliance & governance mechanism
Adoption of international Islamic prudential standards issued by Islamic Financial Services Board - to addresses unique characteristics of Islamic financial transactions<br>
slide8. …and streamlined with Islamic Financial Services Board (IFSB) standards for international regulatory harmonization Relevant Standards issued by IFSB to Sukuk Islamic Financial Services Board (IFSB) was established in 2002
Significant progress in addressing regulatory framework for Islamic financial institutions
Promote international convergence of standards
Provide platform for knowledge sharing
191 members to date, including 54 regulators Capital Adequacy Standard (Dec 2005) Guiding Principles on Risk Management (Dec 2005) Guiding Principles on Corporate Governance ( Dec 2006) Supervisory Review Process (End-2007) Capital Adequacy Requirements for Sukuk,
Securitization & Real Estate Investment (1/09) Transparency & Market Discipline (End-2007) Guiding Principles on Governance for Islamic Collective Investment Scheme (1/09)<br>
slide9. Shariah Governance plays an important role in instilling & shaping sound governance practices …. Principles of Islamic finance place great emphasis on strong corporate governance values & structure, transparency, disclosure of information &
strict adherence to Shariah principles… Fiduciary duties in Islamic banking transaction Normal
Corporate
Governance Shariah Governance Ensures compliance with Shariah rules & principles Instill public confidence Promote financial stability Ensure strict Shariah-compliance Importance of
Shariah governance<br>
slide10. SHARIAH
as overarching principle in Islamic finance An example of Shariah Governance Framework Model BOARD RISK MANAGEMENT COMMITTEE BOARD Overall oversight on Shariah governance structure & Shariah compliance SHARIAH COMMITTEE
Oversight accountability on Shariah related matters BOARD AUDIT COMMITTEE MANAGEMENT
Ensure executions of business & operations are in accordance with Shariah principles
Provide necessary support to the Shariah Committee Shariah Risk Management Control Function
Identify, measure, monitor, report & control Shariah non-compliance risk Shariah Review Function
Review business operations on regular basis to ensure Shariah compliance Shariah Research Function
Conduct in-depth Shariah research prior to submission to the Shariah Committee Shariah Audit Function
Provide independent assessment & objective assurance designed to value add & improve IFI’s compliance with Shariah Shariah Compliance and Research Functions Accountability Oversight Support Support Check & Balance Check & Balance<br>
slide11. 11 Proper Sequencing of Regulatory Policies Introduce efficient & facilitative issuance process for Sukuk Widen issuer and investor base Improve liquidity in the secondary market Establish reliable and efficient benchmark yield curve Facilitate introduction of risk management instruments The 5 Pillars<br>
slide12. Regulation of primary issuance of non-Sovereign Sukuk 12<br>
slide13. Regulation of secondary market trading of Sukuk 13<br>
slide14. Different country approaches to regulation & supervision of Sukuk… 14 International experience points to two approaches – some examples:
Minimal alterations: United Kingdom, Singapore
Parallel approach: Malaysia, Bahrain and Oman<br>
slide15. Country approach in regulating & supervising Sukuk markets: Malaysia 15<br>
slide16. Country approach in regulating & supervising Sukuk markets: Malaysia 16<br>
slide17. Malaysia: 2 Tier Approach to regulation of ICM/Sukuk products ensure investors receive same degree of clarity, certainty & protection 17<br>
slide18. Proper governance provides assurance on Shariah compliance & confidence on IF operation:
SAC’s legislative stature as highest authority for Shariah matters in Islamic finance is accorded under the Central Banking Act.
Shariah committee of IFIs are fully accountable on decision, views & opinions related to shariah matters
Board & senior management with sufficient expertise & capability in dealing with issues specific to Islamic financial transactions
Emphasise the function of Shariah review & Shariah audit to provide check & balance
Shariah Committee member of another IFI within the same industry shall not be appointed – avoid conflict of interest & maintain info confidentiality
Institutionalise mutual respect by recognising differences of Shariah interpretations in various jurisdiction
Shariah parameters provide guidance on main features, principles & rulings of Shariah contracts Two-tier Shariah assurance supported by Shariah governance structure Shariah as overarching
principle in Islamic finance Shariah Compliance Functions : Shariah Review Shariah Audit Management Shariah Governance Framework Board Shariah Committee Shariah Advisory Council (SAC) Shariah Parameters Shariah Resolutions & Rulings<br>
slide19. Bringing regulatory framework and oversight in line with international best practices
Rebalancing tax treatment
Strengthening insolvency frameworks
Promoting standardization
Ensuring adequate liquidity for long term financing
Establishing sound risk-management practices Key Challenges to regulation & supervision of ICM/Sukuk 19<br>
slide20. Rebalancing tax treatment 20 Conventional debt often receives advantageous tax treatment (encouraging leverage), while some Islamic finance products face double taxation.
Examples of Malaysia and Thailand took steps to ensure that Islamic financial transactions operate on a level playing field:
In Malaysia, this principle has extended to ensuring that profits, asset transfers, and expatriation of profits by foreigners are treated equally, whether occurring under conventional or Islamic financial contracts.
In Thailand, a package of proposed tax changes for Sukuk issuances is making its way through the legislative process to address the main hurdles faced by Sukuk issuers.<br>
slide21. Promoting standardization 21 Lack of standardization and cohesion, especially in Sukuk products, hinders the growth potential of Islamic finance
The industry would benefit from more widely accepted benchmarks and indices.
Innovation and knowledge sharing between various market players are essential to facilitate the standardization and unification of global markets for Islamic financial products.<br>
slide22. Need to strengthen insolvency frameworks… 22 More work is needed to ensure convergence between best insolvency practices on the conventional and Shariah-compliant sides.
The need to establish reliable mechanisms for dealing with Sukuk defaults, and addressing adverse outcomes, with special adaptations for risk sharing.
Setting up these mechanisms requires the specification of parties’ rights under Shariah-compliant finance, especially in the case of cross-border transactions.<br>
slide23. 23<br>
slide24. THANK YOU Sau Ngan Wong, Senior Counsel,
Finance and Markets Global Practice
The World Bank Group
saunganwong@worldbank.org<br>
slide25. 25 II. Capital adequacy RWA 6 : Sukuk Sukūk is certificates that represent the holder’s proportionate ownership in an undivided part of an underlying asset where the holder assumes all rights and obligations to such asset ultimate customer.
Externally Rated Sukūk
Applicable risk weight will be based on the ECAI ratings in accordance with the Standardised Approach
Non Rated Sukūk
Applicable risk weight will be based on the underlying contract or on that of the issuer if there is recourse to the issuer<br>
slide26. 26 II. Capital adequacy RWA 6 : Sukuk Sukūk is certificates that represent the holder’s proportionate ownership in an undivided part of an underlying asset where the holder assumes all rights and obligations to such asset ultimate customer.
Externally Rated Sukūk
Applicable risk weight will be based on the ECAI ratings in accordance with the Standardised Approach
Non Rated Sukūk
Applicable risk weight will be based on the underlying contract or on that of the issuer if there is recourse to the issuer<br>
slide27. 27 II. Capital adequacy RWA 5 : Mudharabah Muḍārabah Investment in Project Finance
Prior to certification where funds are already advanced by the IIFS to the Muḍārib :
- Risk weight is based on the rating of either the ultimate customer or the Muḍārib
- Otherwise, 400% RW is applied to unrated Muḍārib.
After certification where amount receivable by the IIFS from the Muḍārib in respect of progress payment due to the Muḍārib from the ultimate customer:
- Risk weight is based on the credit standing of the ultimate customer on the amounts receivable by the IIFS from the Muḍārib
- Otherwise, 100% RW for unrated ultimate customer.<br>
slide28. 28 II. Capital adequacy RWA 5 : Mudharabah Private commercial enterprise to undertake a business venture (other than (1))
Simple risk-weight method:
The RW shall be applied to the exposures (net of specific provisions) based on equity exposures in the banking book. The RW under the simple risk-weight method for equity position risk in respect of an equity exposure in a business venture shall entail a 400% for shares that are not publicly traded.
However, funds invested on a Muḍārabah basis may be subject to withdrawal by the investor at short notice, and in that case may be considered as being as liquid as shares that are publicly traded. The applicable RW in such a case is 300%.
Slotting Method expertise.<br>
slide29. 29 II. Capital adequacy RWA 5 : Musharakah 1. Private commercial enterprise to undertake trading activities in the foreign exchange, share and/or commodity
- The RW of a Mushārakah that invests in quoted shares shall be measured according to the equity position risk approach where positions in assets tradable in markets will qualify for treatment as equity position risk in the trading book, which would incur a total capital charge of 16% (equivalent to 200% RW).
- The capital charge can be reduced to 12% (equivalent to 150% RW) for a portfolio that is both liquid and well-diversified, subject to meeting the criteria as determined by the supervisory authorities<br>