
Reverse Charge Mechanism (RCM) under GST Basics

Description: Reverse Charge Mechanism (RCM) under GST Basics and Intricacies of RCM Presented by CA. Deepa Praveen, B.Com, FCA, DISA(ICAI) Introduction Introduction Reverse Charge means the liability to pay tax is on the recipient of supply instead of
Related Topics
Download Presentation
"Reverse Charge Mechanism (RCM) under GST Basics" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Reverse Charge Mechanism (RCM) under GST
Basics and Intricacies of RCM Presented by
CA. Deepa Praveen, B.Com, FCA, DISA(ICAI)<br>
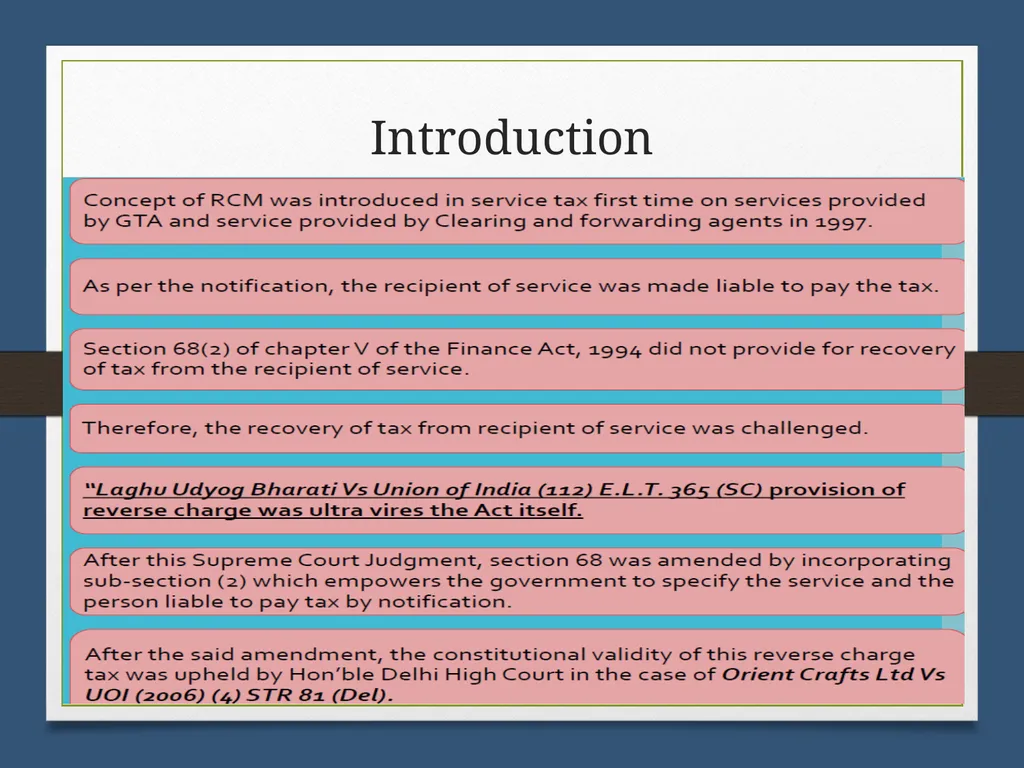
slide2. Introduction<br>
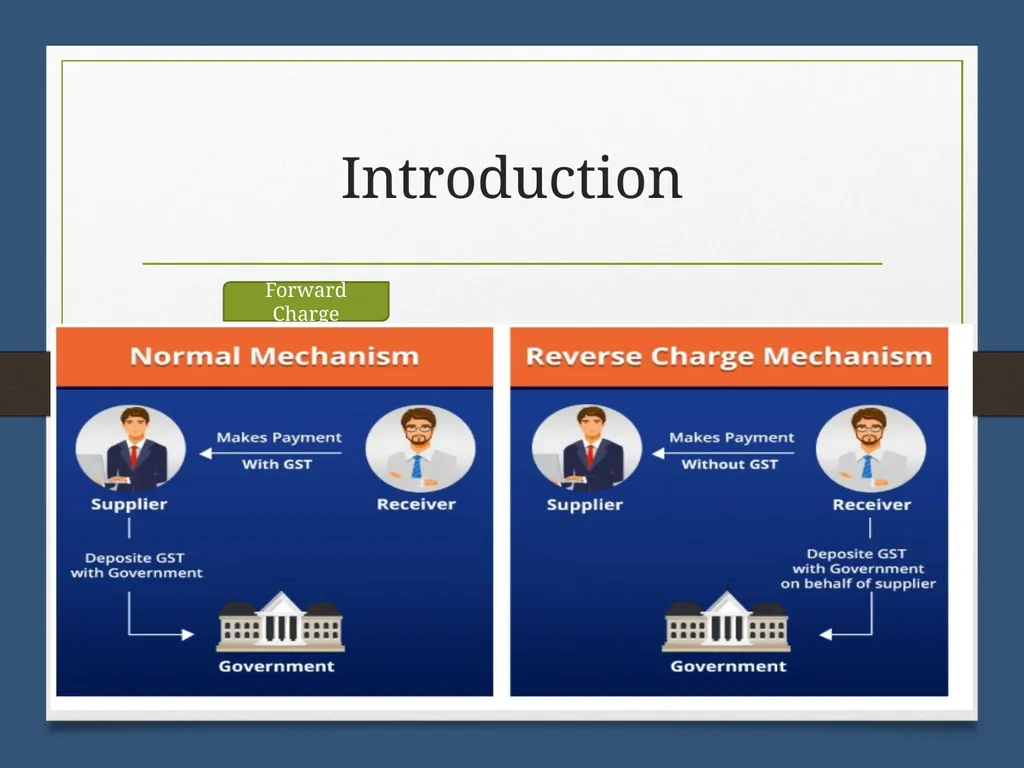
slide3. Introduction Reverse Charge means the liability to pay tax is on the recipient of supply instead of the supplier.
Applicable under sections 9(3), 9(4) of CGST Act and 5(3), 5(4) of IGST Act. Forward Charge<br>
slide4. Points to be noted RCM liability to be disclosed in the monthly/quarterly return
RCM liability can be paid only by cash
Self-invoice to be generated when supply received from Unregistered persons
ITC can be claimed if the outward supply is not exempt/Nil rated<br>
slide5. What is the objective of Shifting the burden to Recipient of supply To widen the tax base.
To increase tax compliance
To ensure tax compliance from unregistered or non-compliant supplier.<br>
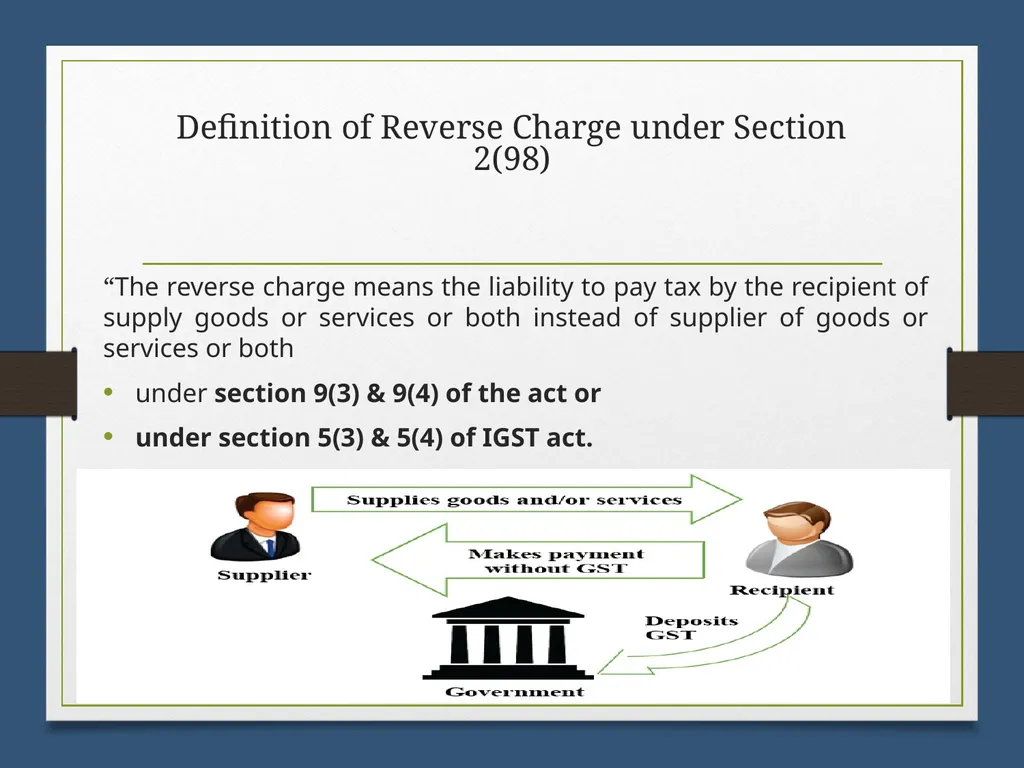
slide6. Definition of Reverse Charge under Section 2(98) “The reverse charge means the liability to pay tax by the recipient of supply goods or services or both instead of supplier of goods or services or both
under section 9(3) & 9(4) of the act or
under section 5(3) & 5(4) of IGST act.<br>
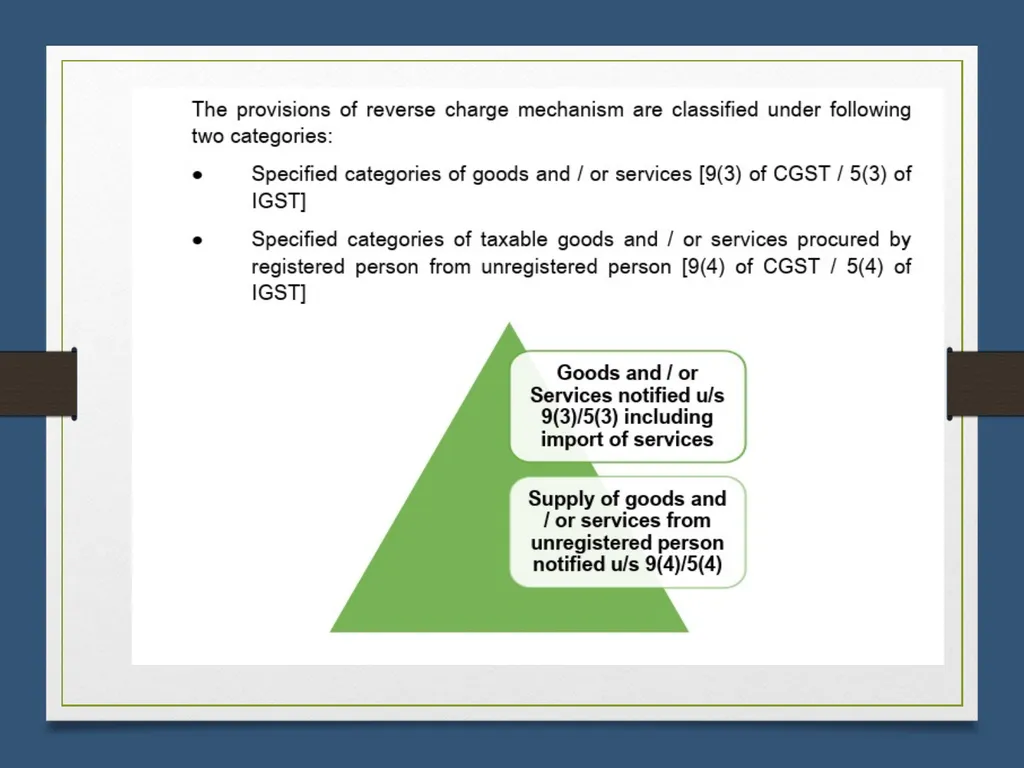
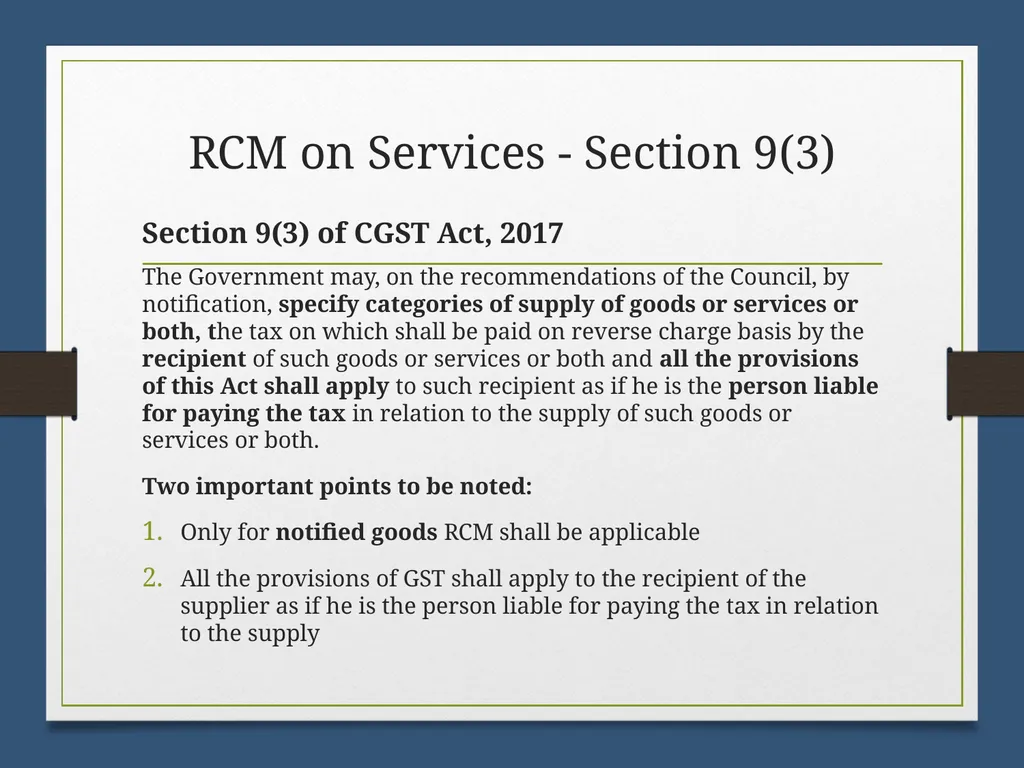
slide8. RCM on Services - Section 9(3) Section 9(3) of CGST Act, 2017
The Government may, on the recommendations of the Council, by notification, specify categories of supply of goods or services or both, the tax on which shall be paid on reverse charge basis by the recipient of such goods or services or both and all the provisions of this Act shall apply to such recipient as if he is the person liable for paying the tax in relation to the supply of such goods or services or both.
Two important points to be noted:
Only for notified goods RCM shall be applicable
All the provisions of GST shall apply to the recipient of the supplier as if he is the person liable for paying the tax in relation to the supply<br>
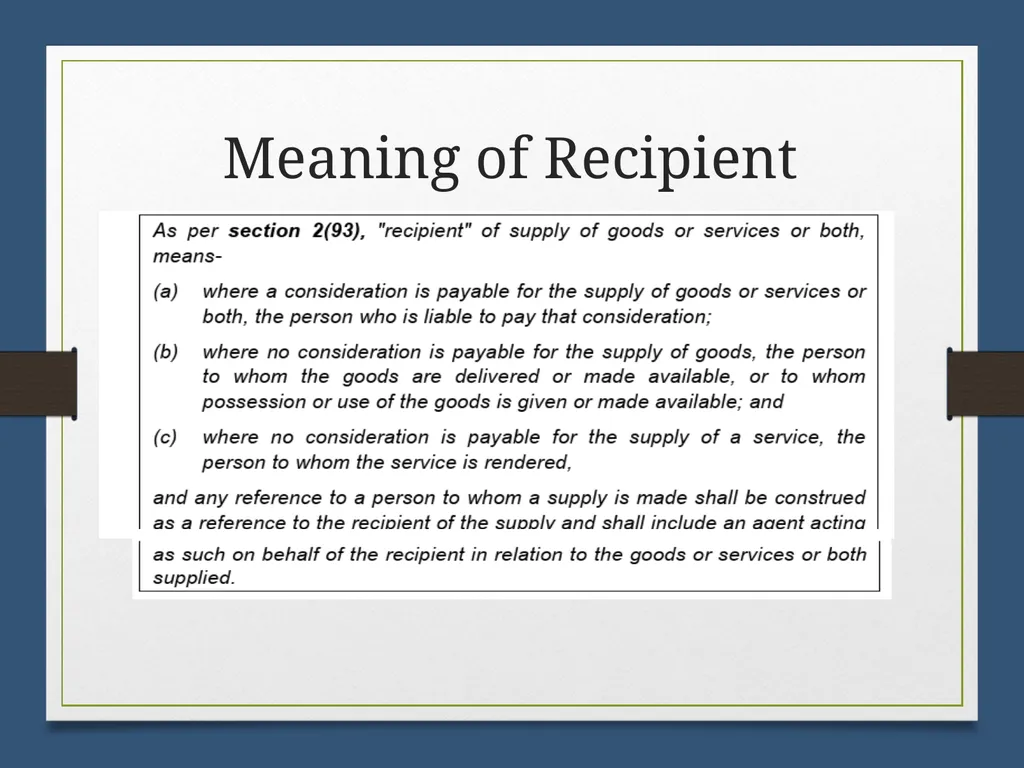
slide9. Meaning of Recipient<br>
slide10. When a registered person supplies notified goods to an unregistered Person, Is he liable to pay under RCM?<br>
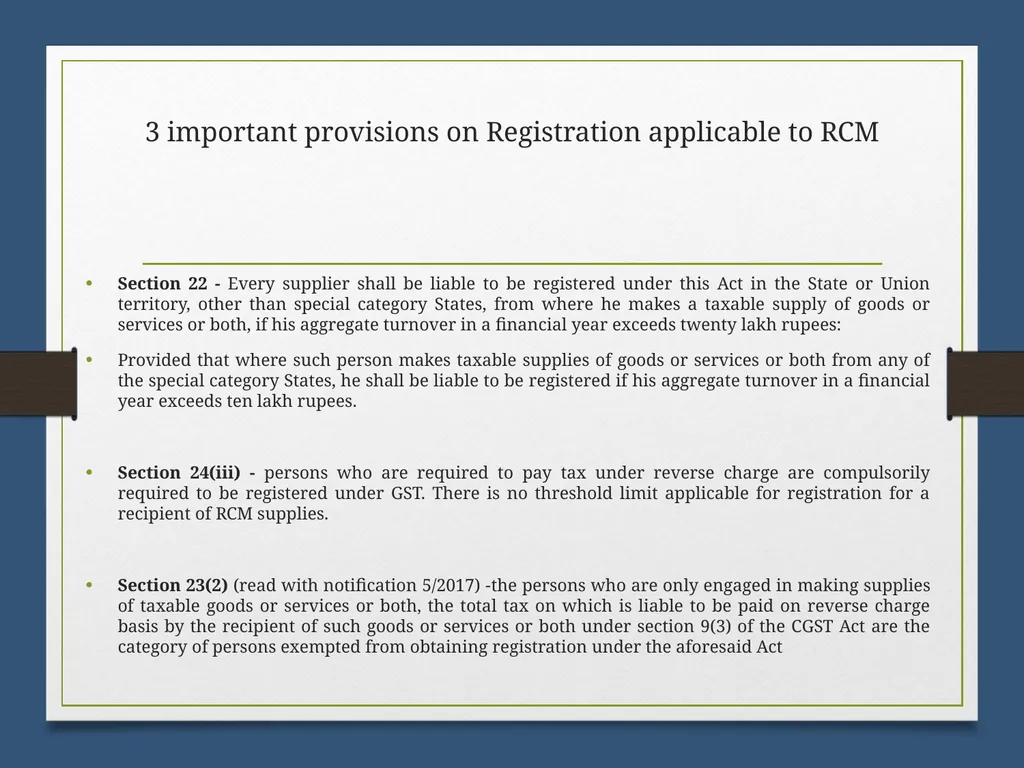
slide11. 3 important provisions on Registration applicable to RCM Section 22 - Every supplier shall be liable to be registered under this Act in the State or Union territory, other than special category States, from where he makes a taxable supply of goods or services or both, if his aggregate turnover in a financial year exceeds twenty lakh rupees:
Provided that where such person makes taxable supplies of goods or services or both from any of the special category States, he shall be liable to be registered if his aggregate turnover in a financial year exceeds ten lakh rupees.
Section 24(iii) - persons who are required to pay tax under reverse charge are compulsorily required to be registered under GST. There is no threshold limit applicable for registration for a recipient of RCM supplies.
Section 23(2) (read with notification 5/2017) -the persons who are only engaged in making supplies of taxable goods or services or both, the total tax on which is liable to be paid on reverse charge basis by the recipient of such goods or services or both under section 9(3) of the CGST Act are the category of persons exempted from obtaining registration under the aforesaid Act<br>
slide12. Is SEZ unit liable to pay GST under reverse charge mechanism?<br>
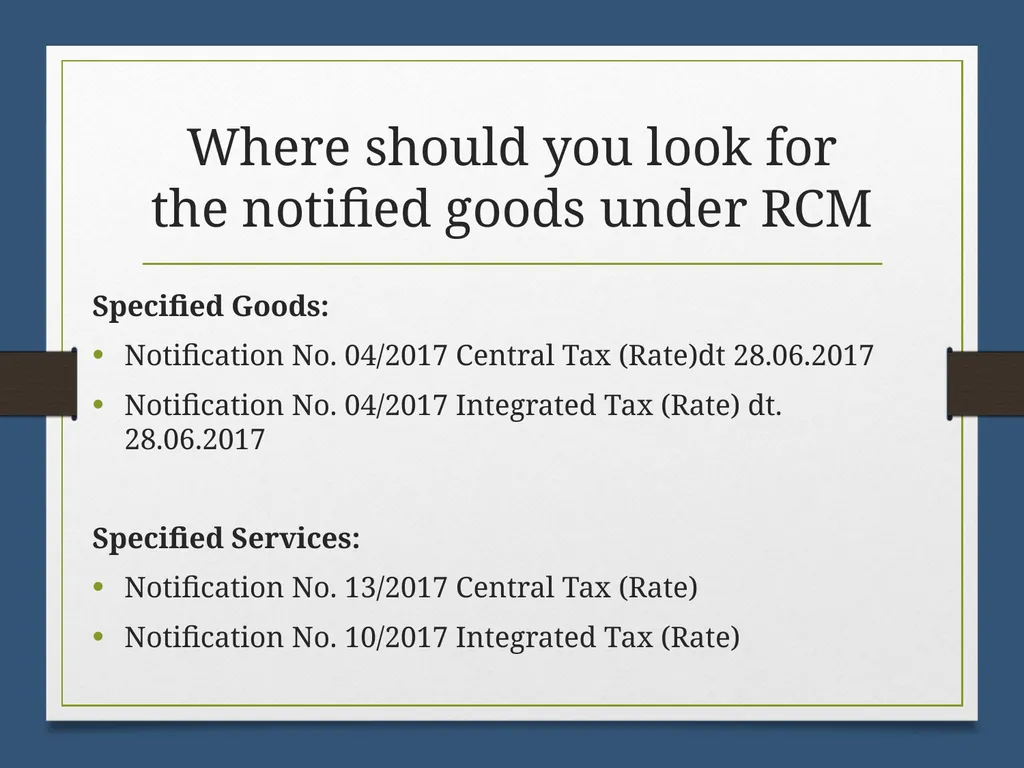
slide13. Where should you look for the notified goods under RCM Specified Goods:
Notification No. 04/2017 Central Tax (Rate)dt 28.06.2017
Notification No. 04/2017 Integrated Tax (Rate) dt. 28.06.2017
Specified Services:
Notification No. 13/2017 Central Tax (Rate)
Notification No. 10/2017 Integrated Tax (Rate)<br>
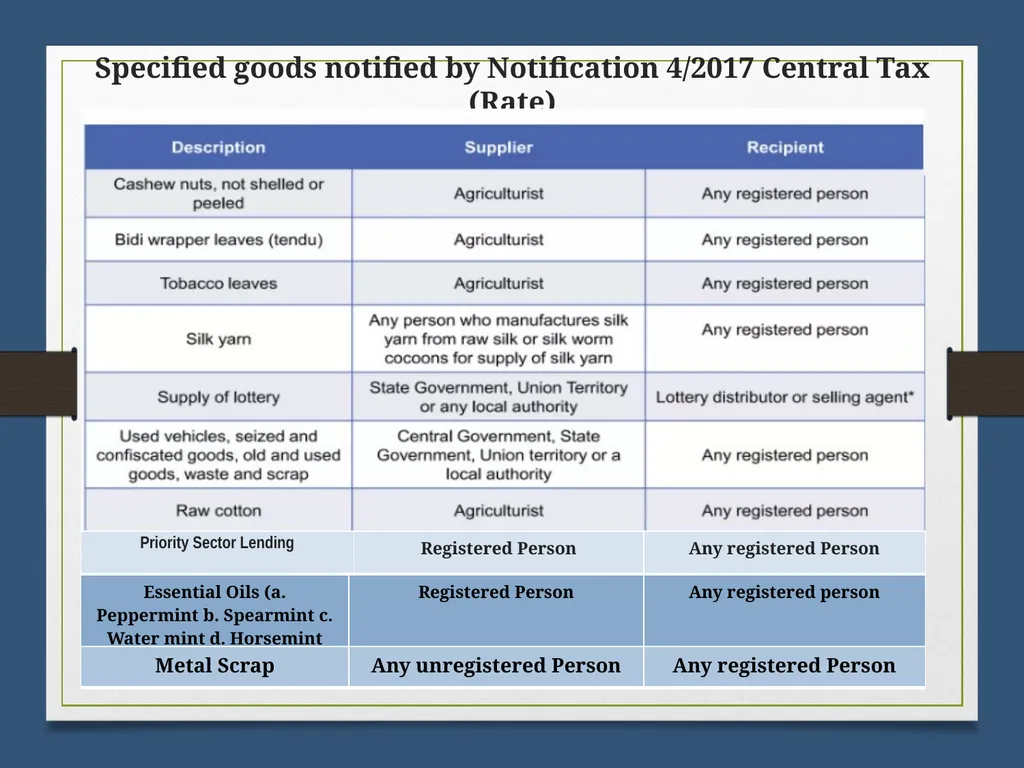
slide14. Specified goods notified by Notification 4/2017 Central Tax (Rate)<br>
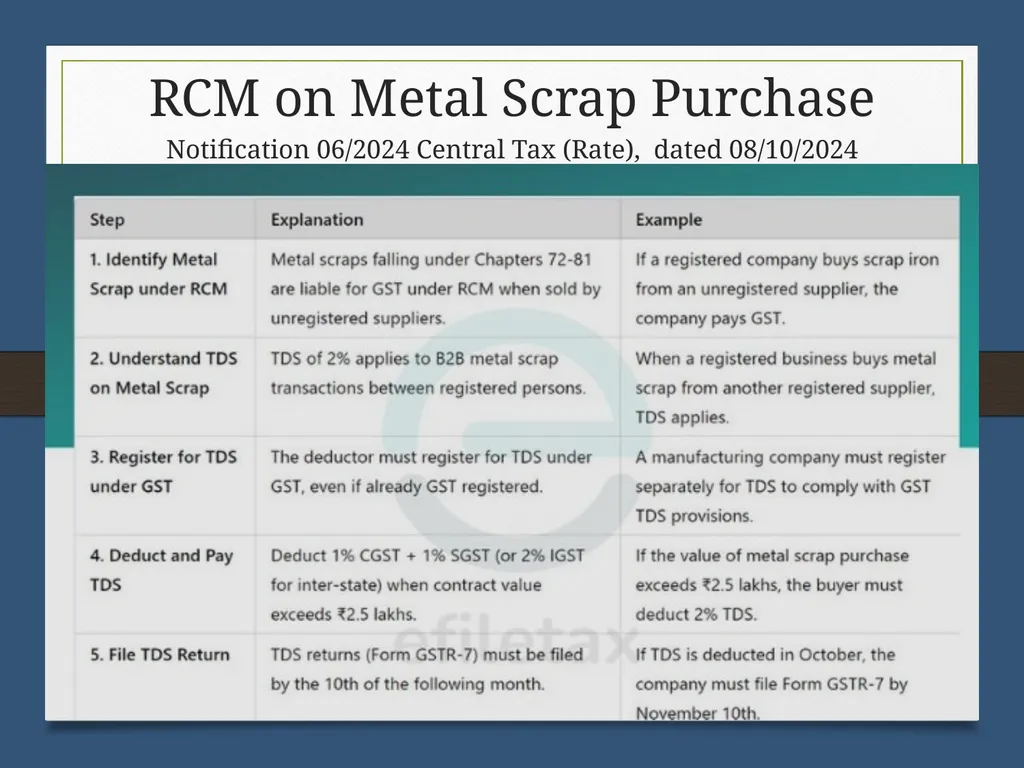
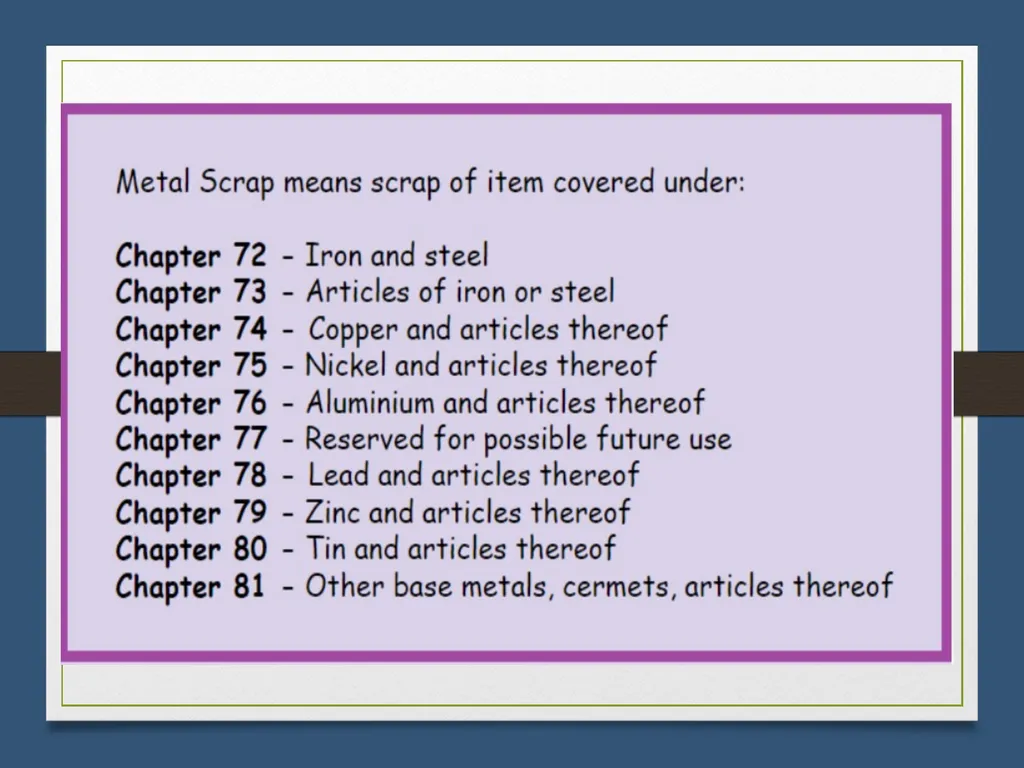
slide15. RCM on Metal Scrap Purchase Notification 06/2024 Central Tax (Rate), dated 08/10/2024<br>
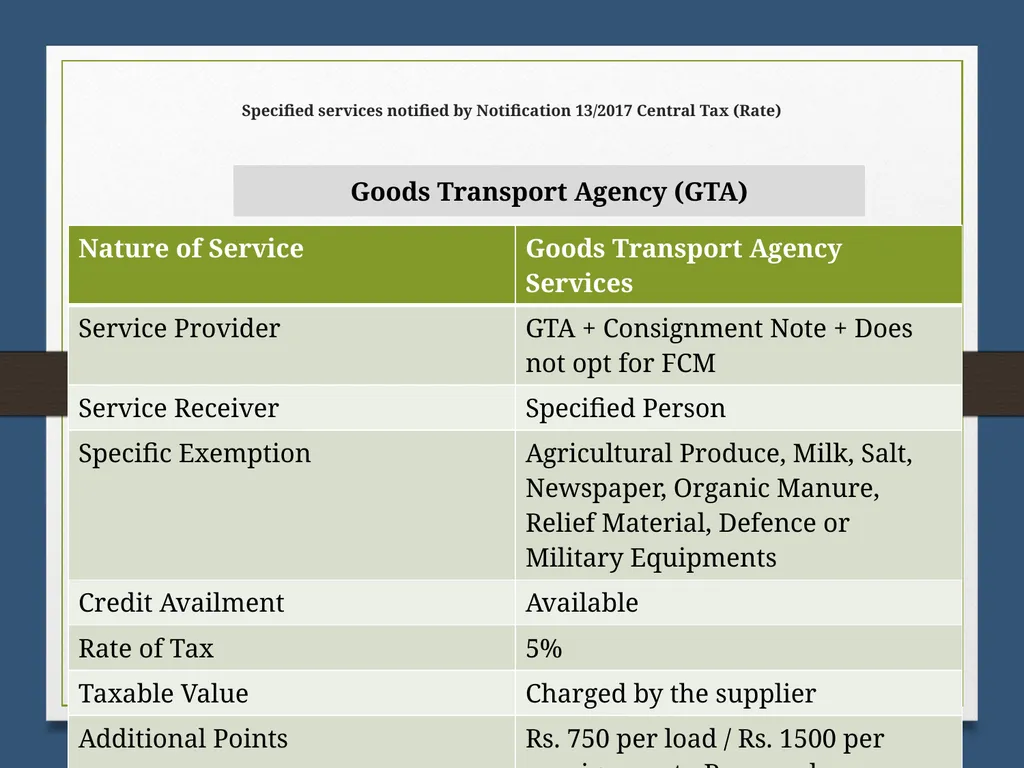
slide17. Specified services notified by Notification 13/2017 Central Tax (Rate) Goods Transport Agency (GTA)<br>
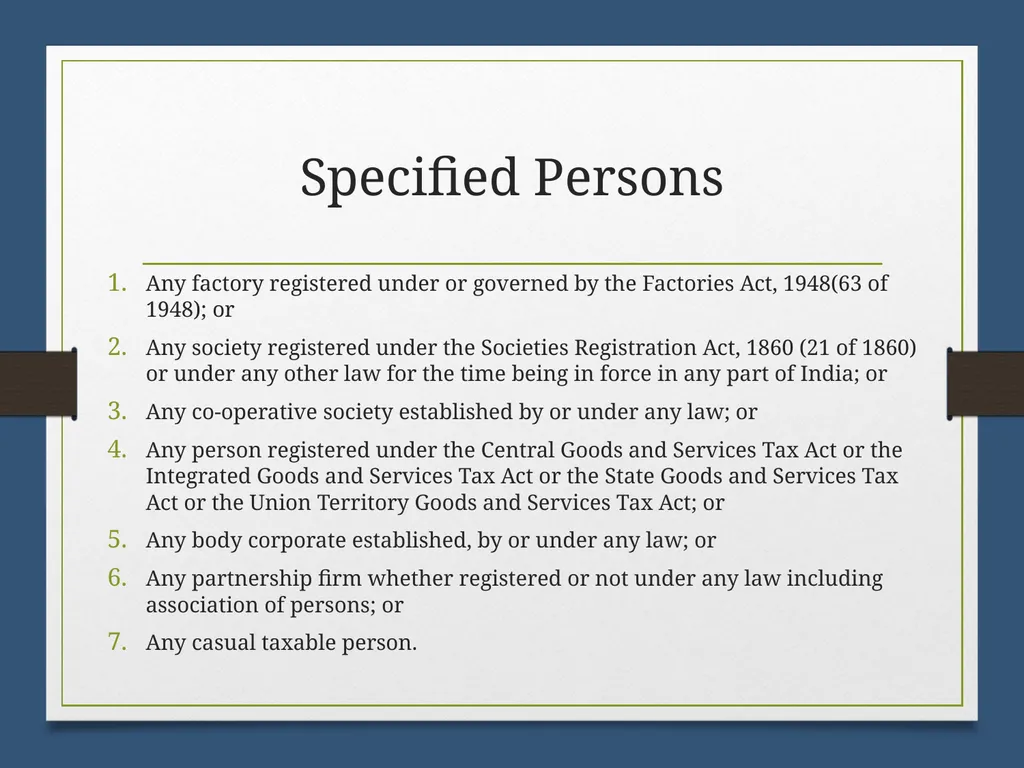
slide18. Specified Persons Any factory registered under or governed by the Factories Act, 1948(63 of 1948); or
Any society registered under the Societies Registration Act, 1860 (21 of 1860) or under any other law for the time being in force in any part of India; or
Any co-operative society established by or under any law; or
Any person registered under the Central Goods and Services Tax Act or the Integrated Goods and Services Tax Act or the State Goods and Services Tax Act or the Union Territory Goods and Services Tax Act; or
Any body corporate established, by or under any law; or
Any partnership firm whether registered or not under any law including association of persons; or
Any casual taxable person.<br>
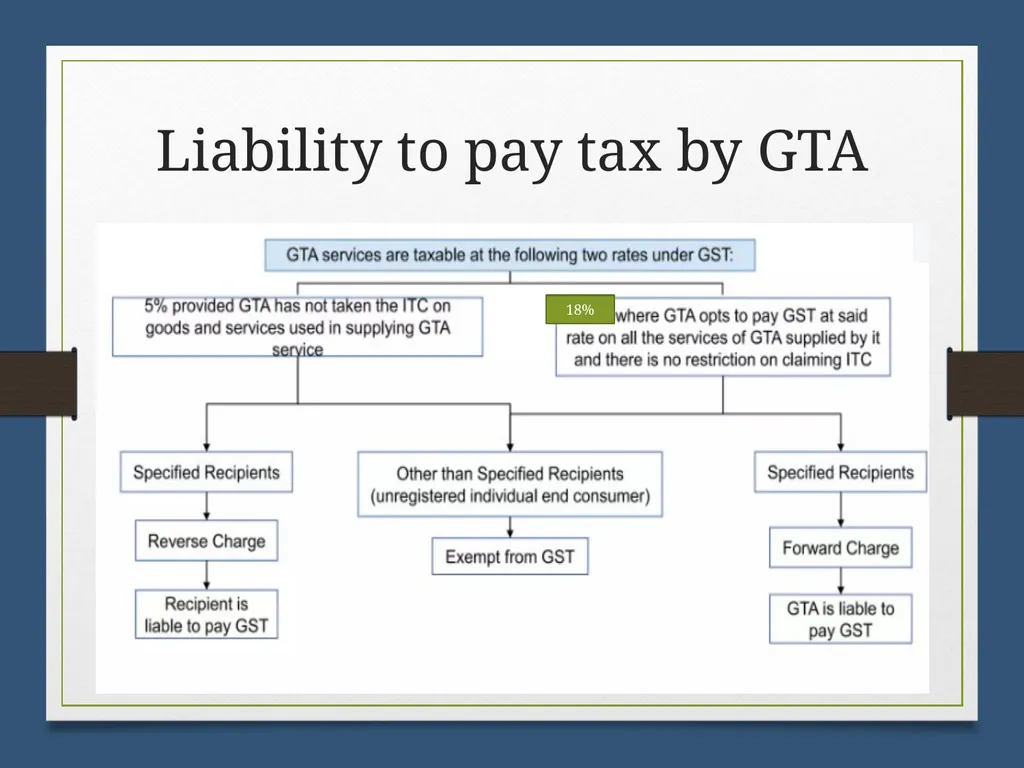
slide19. Liability to pay tax by GTA 18%<br>
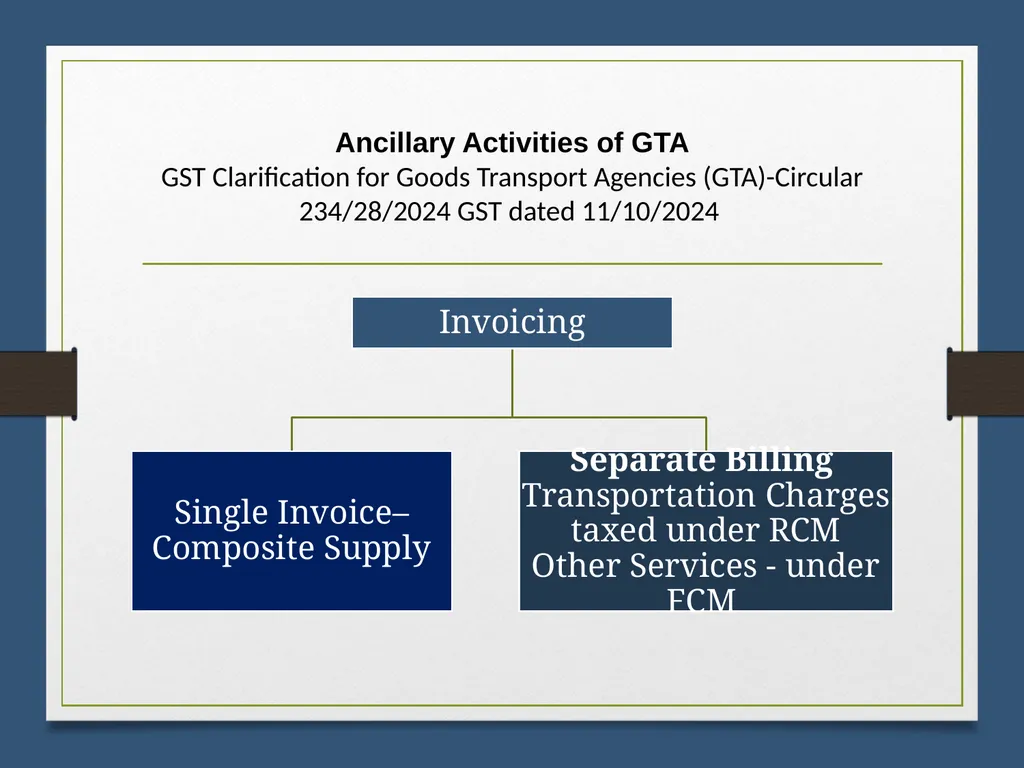
slide20. Ancillary Activities of GTA GST Clarification for Goods Transport Agencies (GTA)-Circular 234/28/2024 GST dated 11/10/2024<br>
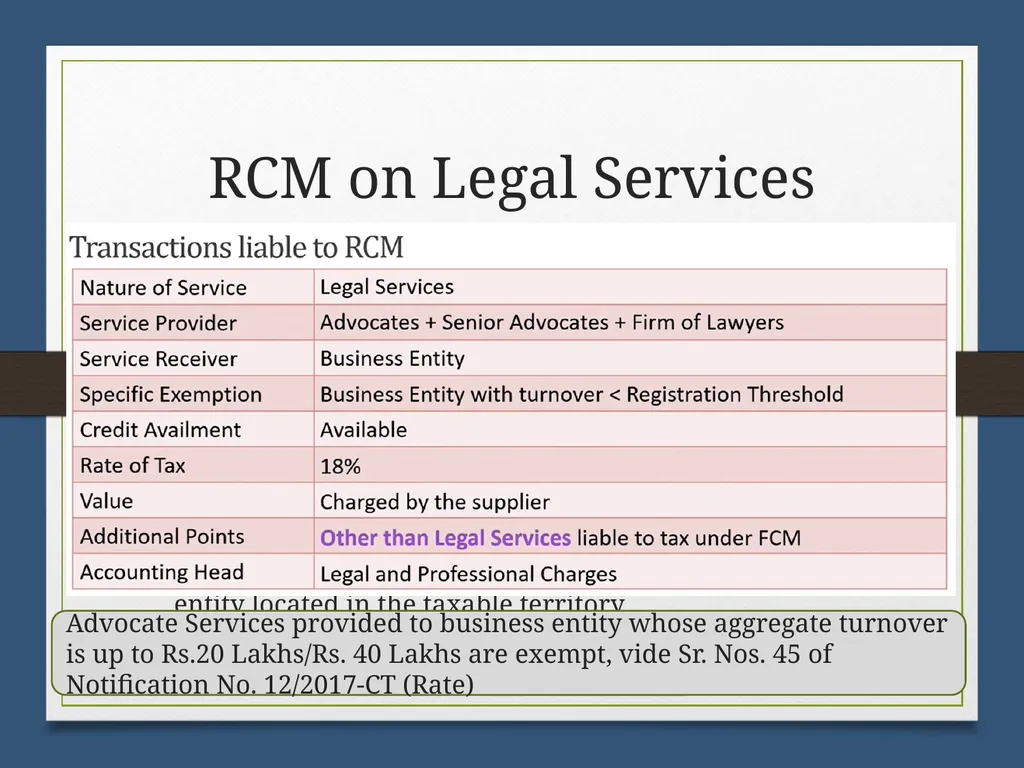
slide21. RCM on Legal Services “Legal Services” – means any service provided in relation to advice, consultancy or assistance in any branch of law, in any manner and includes representational services before any court, tribunal or authority
Supplier of the Service – An individual advocate including a Senior Advocate of Firm of advocates
Scope of Service – Representational services before any court, tribunal or authority, directly or indirectly
Recipient of Service liable to pay RCM: Any business entity located in the taxable territory Advocate Services provided to business entity whose aggregate turnover is up to Rs.20 Lakhs/Rs. 40 Lakhs are exempt, vide Sr. Nos. 45 of Notification No. 12/2017-CT (Rate)<br>
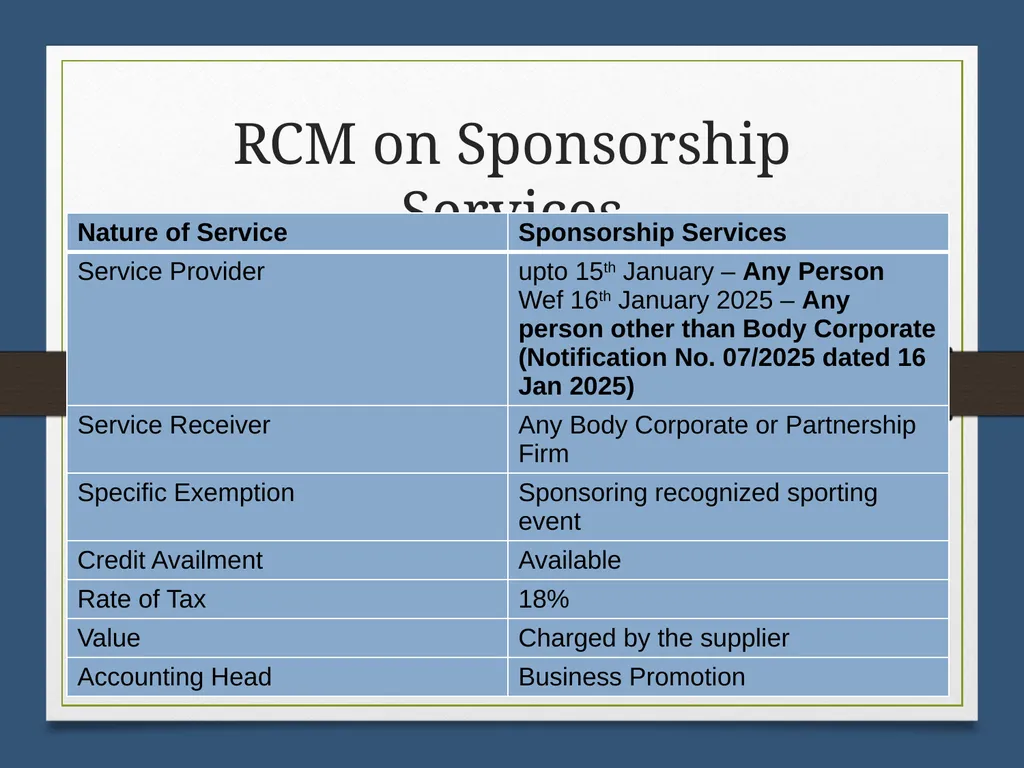
slide22. RCM on Sponsorship Services<br>
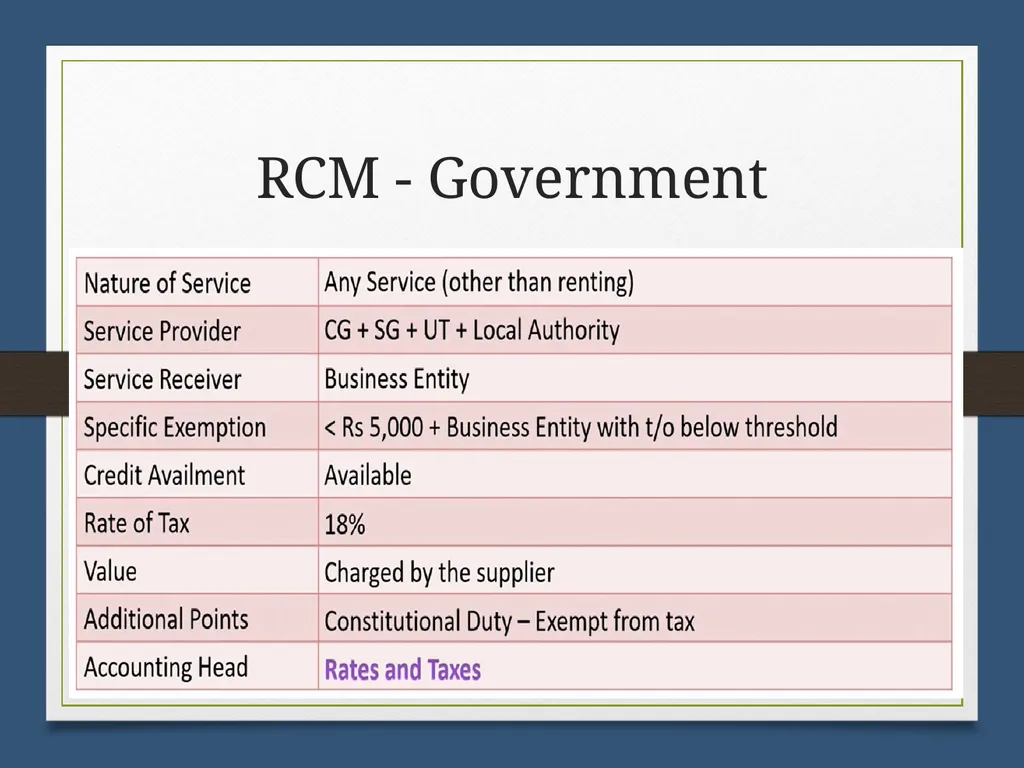
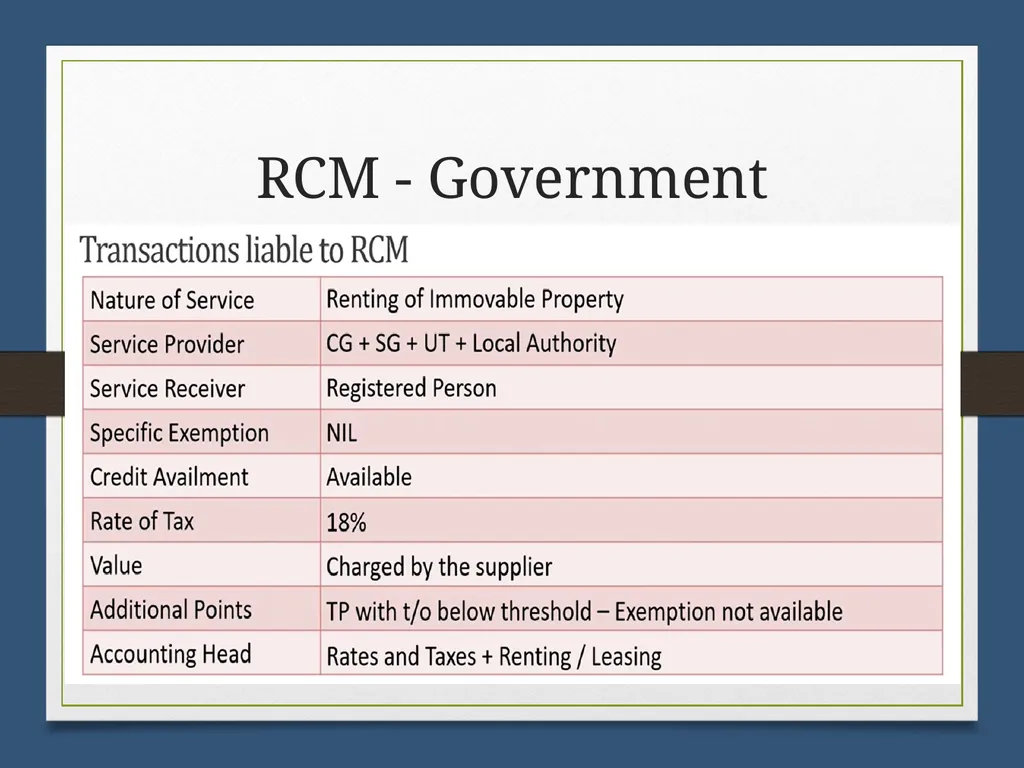
slide23. RCM - Government Supplier of the Service – Central Government, State Government, Union Territory or Local Authority
Scope of Service – All services supplied by CG, SG, UT or Local Authority except:
Renting of immovable property
Services of Department of posts (speed posts, express parcel post, life insurance, and agency services) provided to a person other than Govt.
Services in relation to an aircraft or a vessel
Transport of goods or passengers
Recipient of Service liable to pay RCM: Any business entity located in the taxable territory
Note: In case of service of renting of immovable property provided by the CG, SG/UT, Local Authority to any registered person under CGST, then such registered person is liable to pay tax under RCM w.e.f 25/01/2018<br>
slide24. RCM - Government Supplier of the Service – Central Government, State Government, Union Territory or Local Authority
Scope of Service – All services supplied by CG, SG, UT or Local Authority except:
Renting of immovable property
Services of Department of posts (speed posts, express parcel post, life insurance, and agency services) provided to a person other than Govt.
Services in relation to an aircraft or a vessel
Transport of goods or passengers
Recipient of Service liable to pay RCM: Any business entity located in the taxable territory
Note: In case of service of renting of immovable property provided by the CG, SG/UT, Local Authority to any registered person under CGST, then such registered person is liable to pay tax under RCM w.e.f 25/01/2018<br>
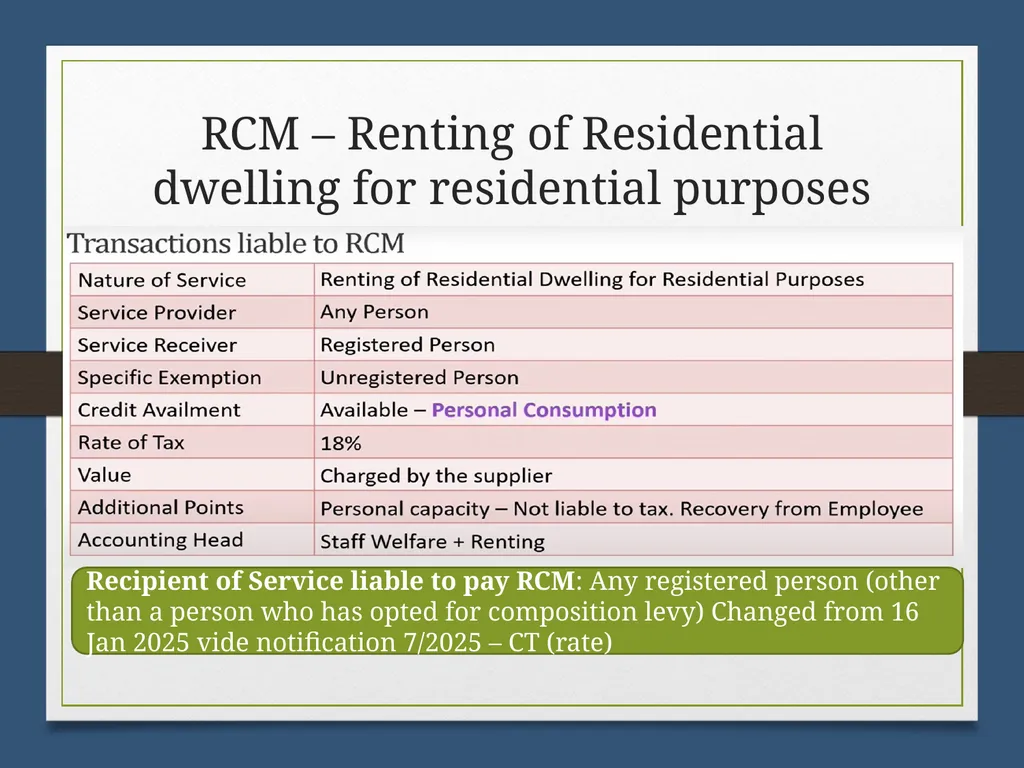
slide25. RCM – Renting of Residential dwelling for residential purposes Supplier of the Service – Central Government, State Government, Union Territory or Local Authority
Scope of Service – All services supplied by CG, SG, UT or Local Authority except:
Renting of immovable property
Services of Department of posts (speed posts, express parcel post, life insurance, and agency services) provided to a person other than Govt.
Services in relation to an aircraft or a vessel
Transport of goods or passengers
Recipient of Service liable to pay RCM: Any business entity located in the taxable territory
Note: In case of service of renting of immovable property provided by the CG, SG/UT, Local Authority to any registered person under CGST, then such registered person is liable to pay tax under RCM w.e.f 25/01/2018 Recipient of Service liable to pay RCM: Any registered person (other than a person who has opted for composition levy) Changed from 16 Jan 2025 vide notification 7/2025 – CT (rate)<br>
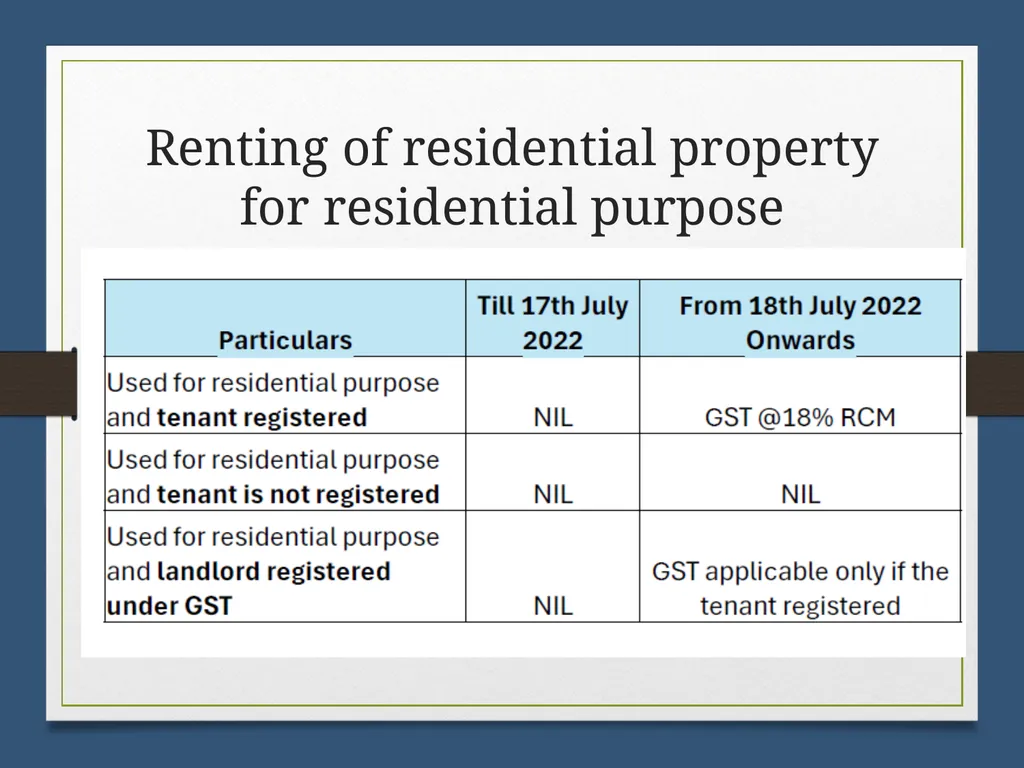
slide26. Renting of residential property for residential purpose<br>
slide27. RCM on Renting of Residential Property for Commercial purpose<br>
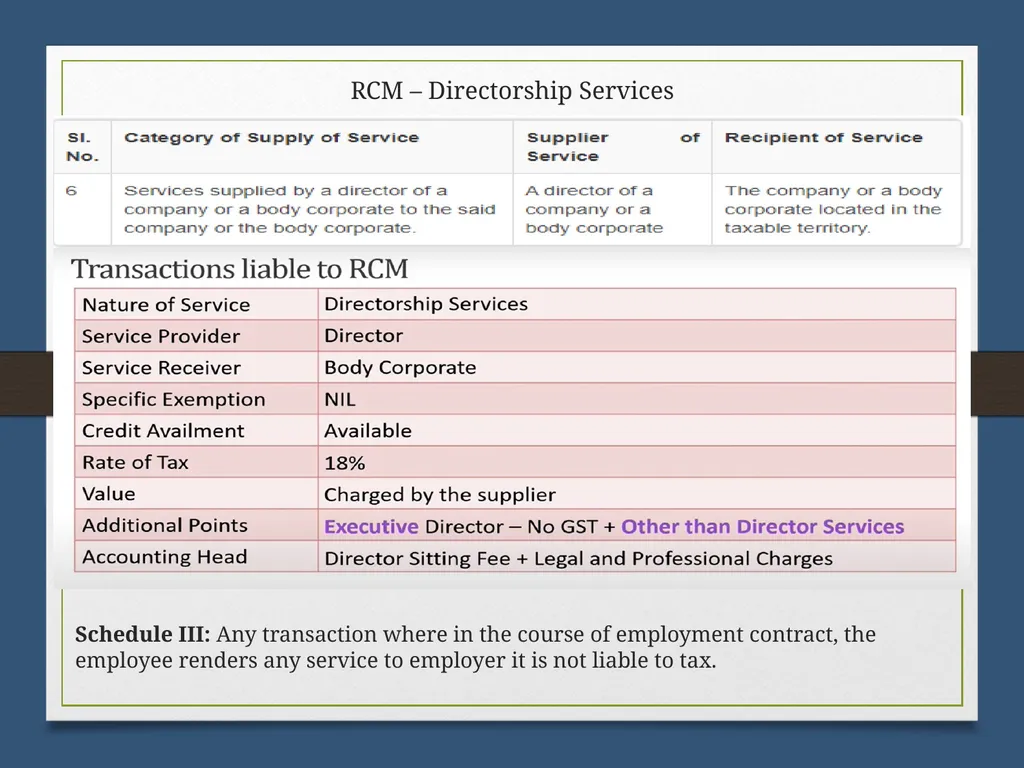
slide28. RCM – Directorship Services Supplier of the Service – Central Government, State Government, Union Territory or Local Authority
Scope of Service – All services supplied by CG, SG, UT or Local Authority except:
Renting of immovable property
Services of Department of posts (speed posts, express parcel post, life insurance, and agency services) provided to a person other than Govt.
Services in relation to an aircraft or a vessel
Transport of goods or passengers
Recipient of Service liable to pay RCM: Any business entity located in the taxable territory
Schedule III: Any transaction where in the course of employment contract, the employee renders any service to employer it is not liable to tax.<br>
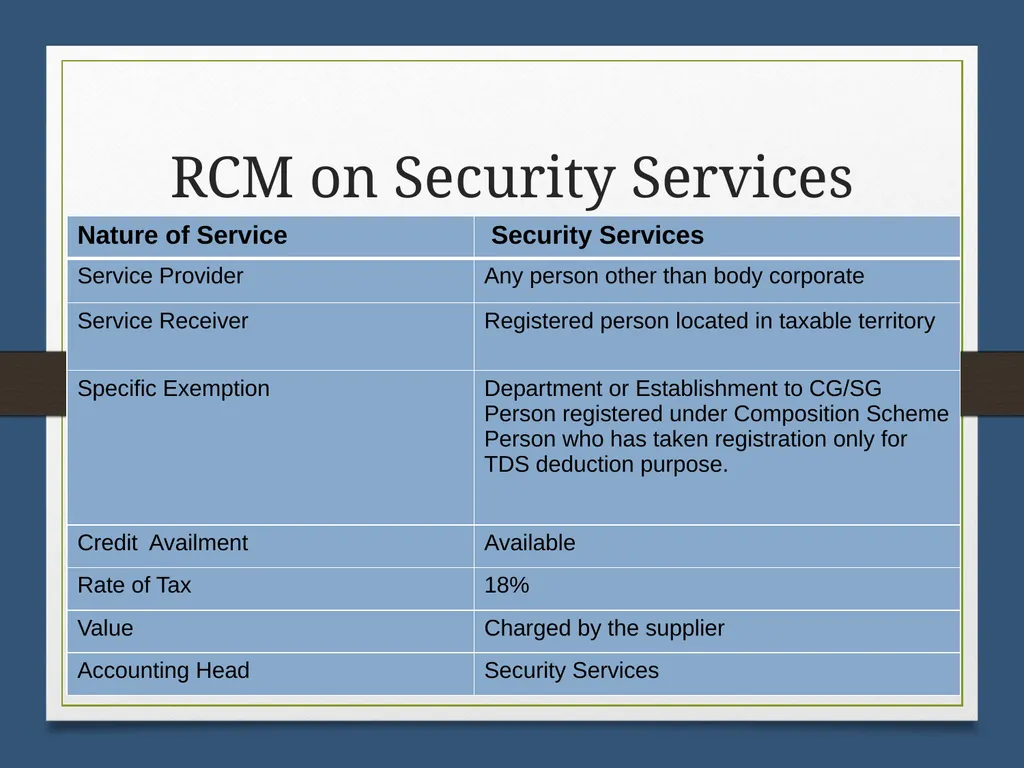
slide29. RCM on Security Services<br>
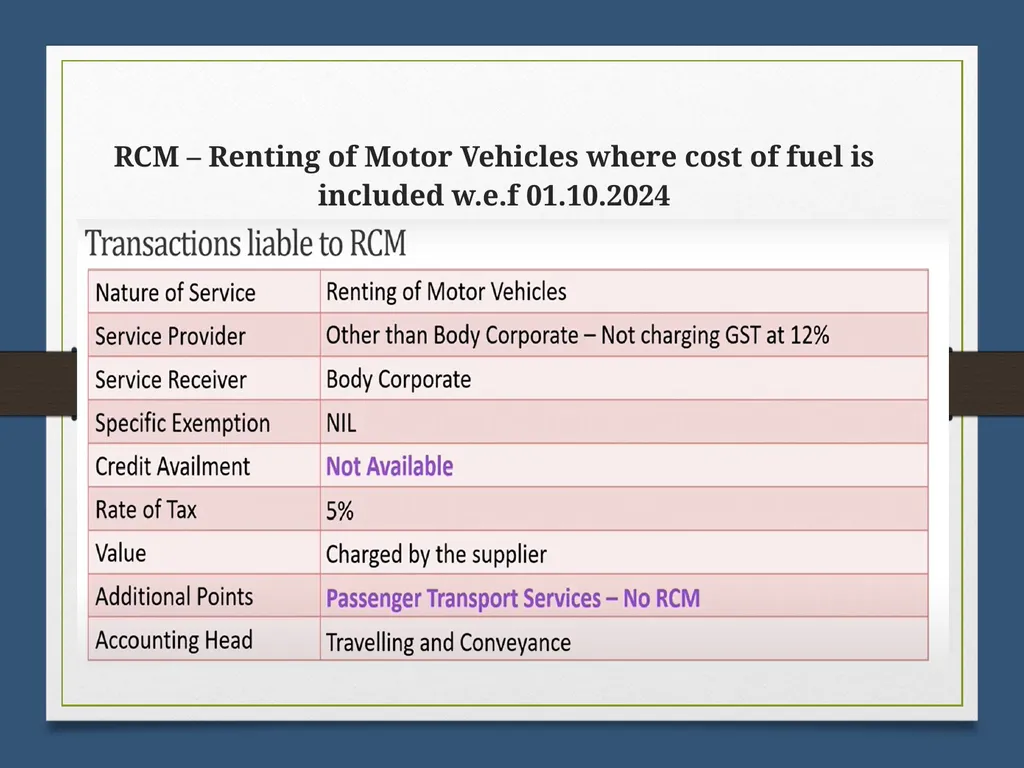
slide30. RCM – Renting of Motor Vehicles where cost of fuel is included w.e.f 01.10.2024<br>
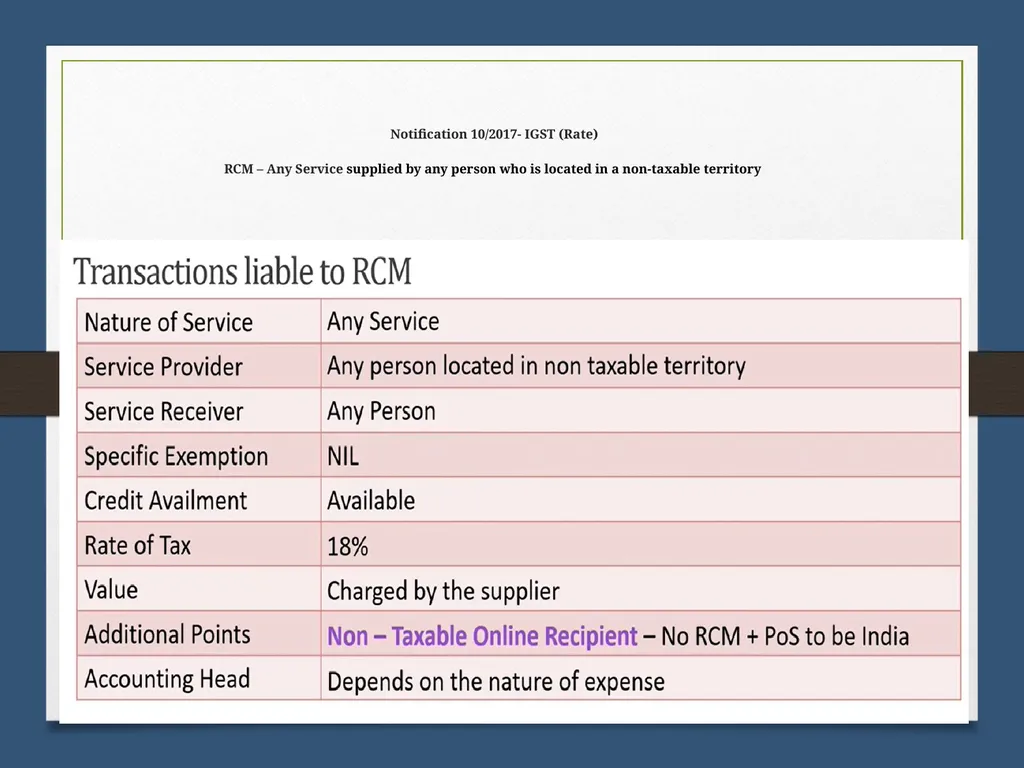
slide31. Notification 10/2017- IGST (Rate) RCM – Any Service supplied by any person who is located in a non-taxable territory<br>
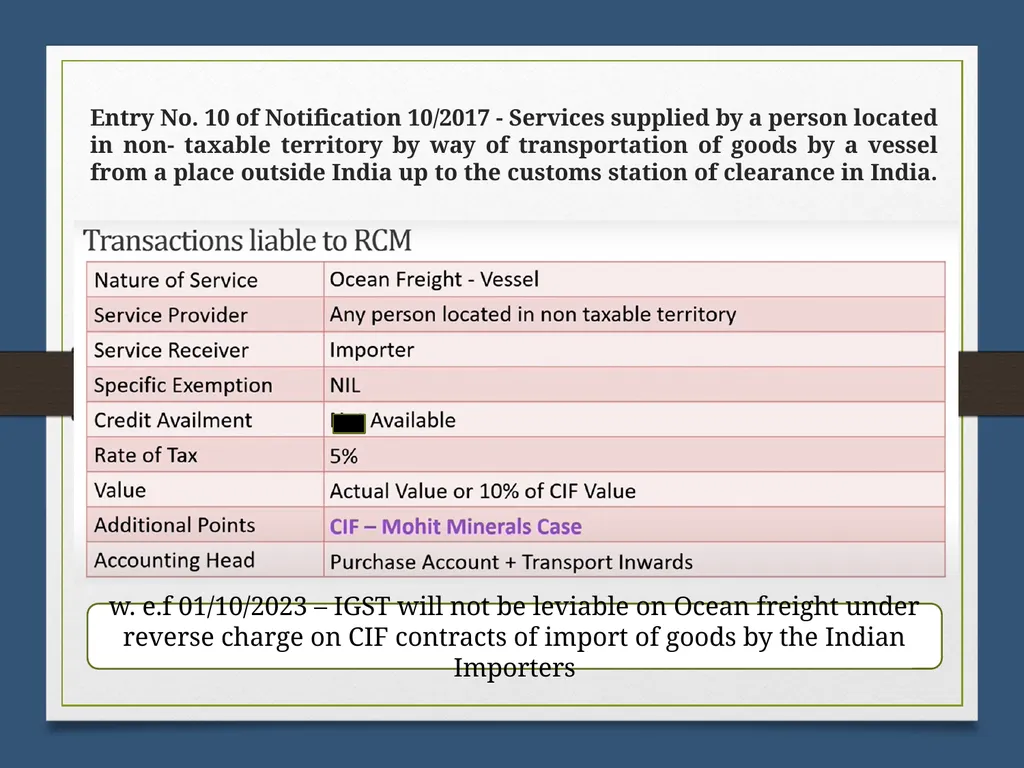
slide32. Entry No. 10 of Notification 10/2017 - Services supplied by a person located in non- taxable territory by way of transportation of goods by a vessel from a place outside India up to the customs station of clearance in India. w. e.f 01/10/2023 – IGST will not be leviable on Ocean freight under reverse charge on CIF contracts of import of goods by the Indian Importers<br>
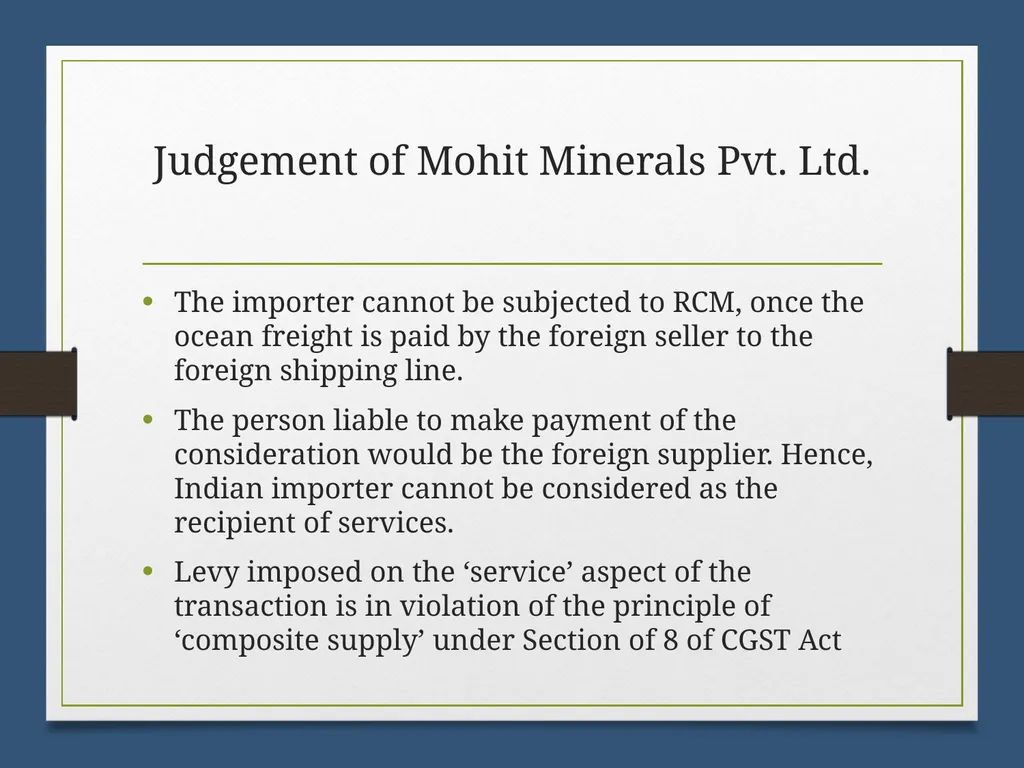
slide33. Judgement of Mohit Minerals Pvt. Ltd. The importer cannot be subjected to RCM, once the ocean freight is paid by the foreign seller to the foreign shipping line.
The person liable to make payment of the consideration would be the foreign supplier. Hence, Indian importer cannot be considered as the recipient of services.
Levy imposed on the ‘service’ aspect of the transaction is in violation of the principle of ‘composite supply’ under Section of 8 of CGST Act<br>
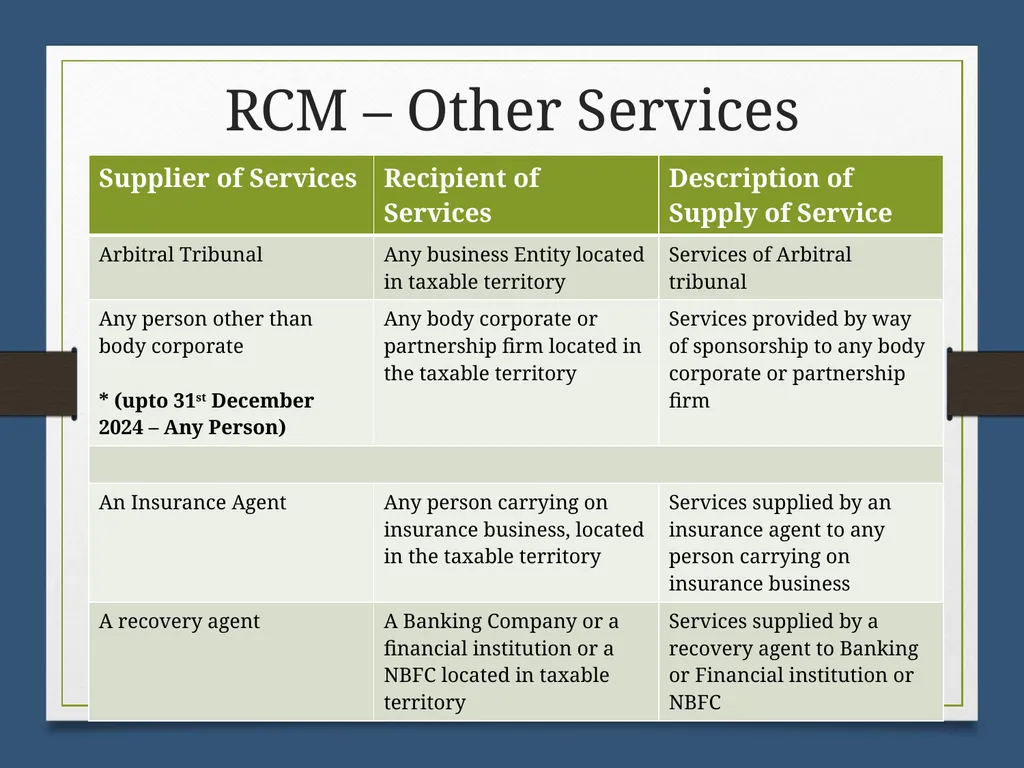
slide34. RCM – Other Services<br>
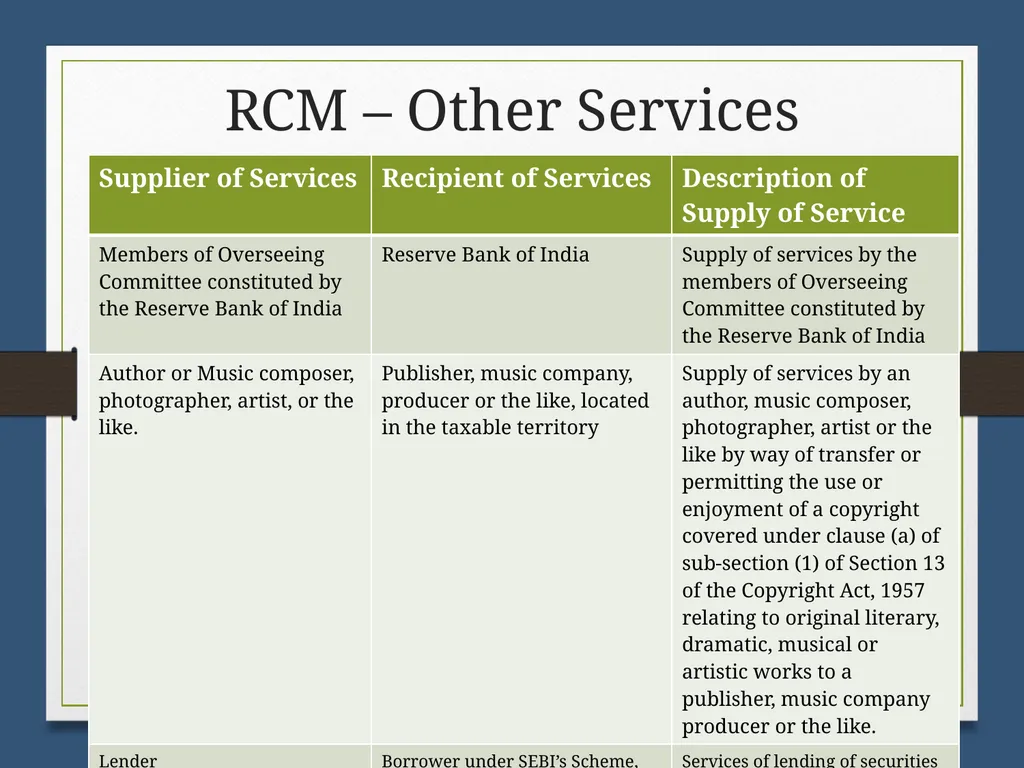
slide35. RCM – Other Services<br>
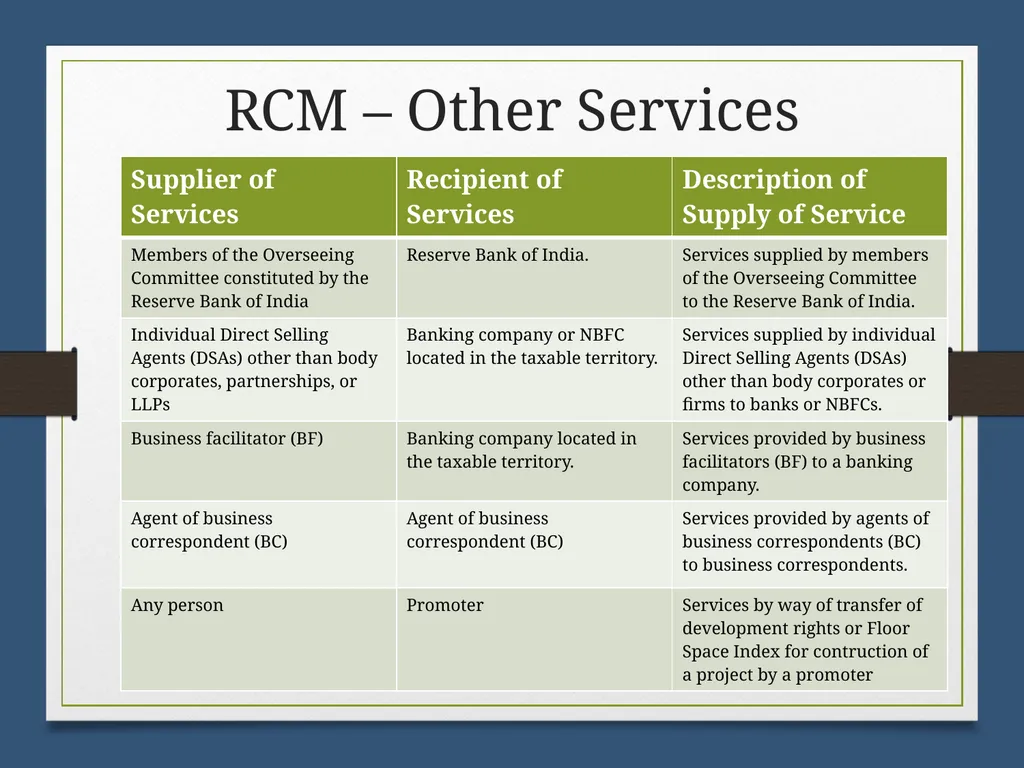
slide36. RCM – Other Services<br>
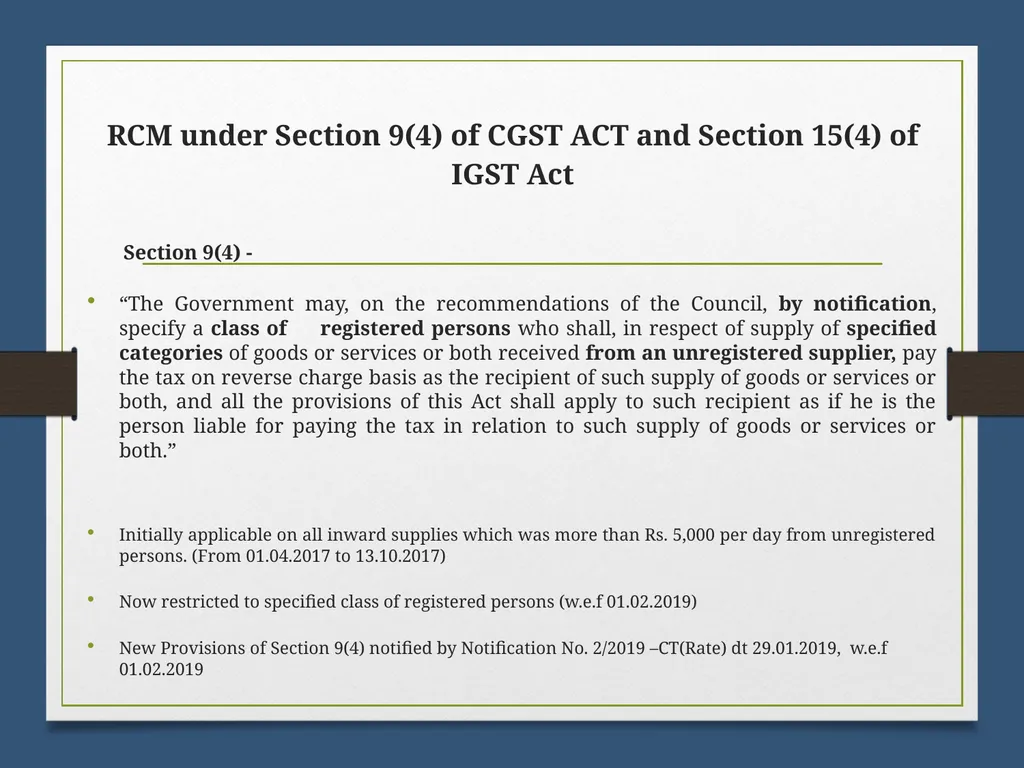
slide37. RCM under Section 9(4) of CGST ACT and Section 15(4) of IGST Act Section 9(4) -
“The Government may, on the recommendations of the Council, by notification, specify a class of registered persons who shall, in respect of supply of specified categories of goods or services or both received from an unregistered supplier, pay the tax on reverse charge basis as the recipient of such supply of goods or services or both, and all the provisions of this Act shall apply to such recipient as if he is the person liable for paying the tax in relation to such supply of goods or services or both.”
Initially applicable on all inward supplies which was more than Rs. 5,000 per day from unregistered persons. (From 01.04.2017 to 13.10.2017)
Now restricted to specified class of registered persons (w.e.f 01.02.2019)
New Provisions of Section 9(4) notified by Notification No. 2/2019 –CT(Rate) dt 29.01.2019, w.e.f 01.02.2019<br>
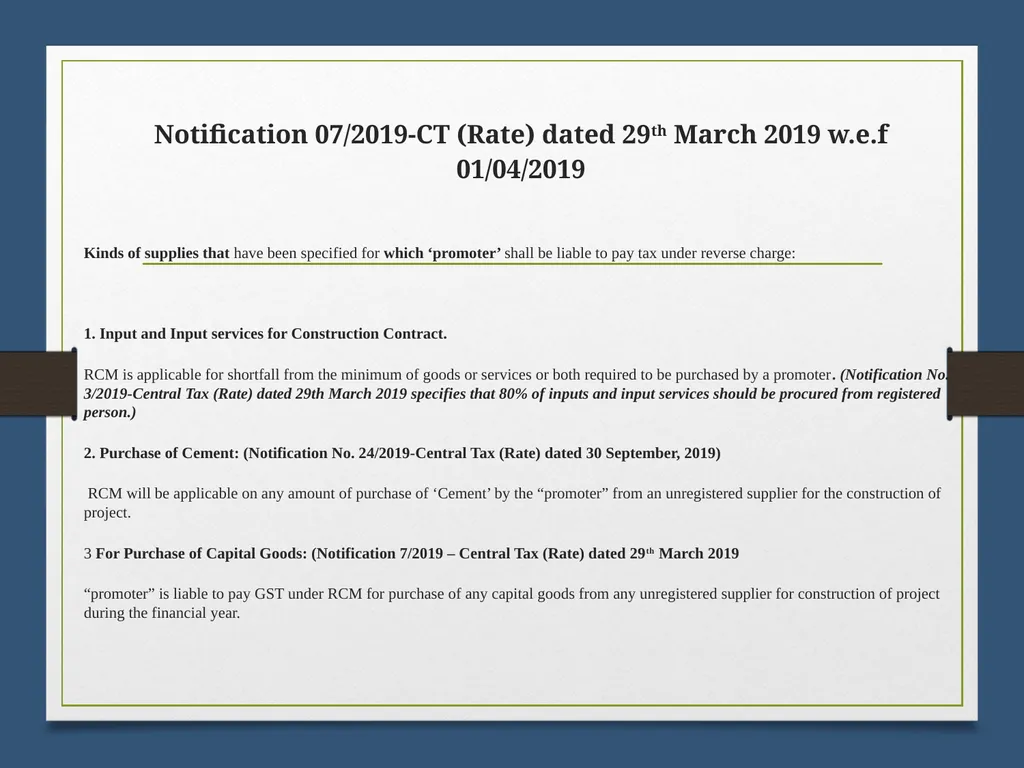
slide38. Notification 07/2019-CT (Rate) dated 29th March 2019 w.e.f 01/04/2019 Kinds of supplies that have been specified for which ‘promoter’ shall be liable to pay tax under reverse charge:
1. Input and Input services for Construction Contract.
RCM is applicable for shortfall from the minimum of goods or services or both required to be purchased by a promoter. (Notification No. 3/2019-Central Tax (Rate) dated 29th March 2019 specifies that 80% of inputs and input services should be procured from registered person.)
2. Purchase of Cement: (Notification No. 24/2019-Central Tax (Rate) dated 30 September, 2019)
RCM will be applicable on any amount of purchase of ‘Cement’ by the “promoter” from an unregistered supplier for the construction of project.
3 For Purchase of Capital Goods: (Notification 7/2019 – Central Tax (Rate) dated 29th March 2019
“promoter” is liable to pay GST under RCM for purchase of any capital goods from any unregistered supplier for construction of project during the financial year.<br>
slide39. Time of Supply Why is it so relevant???
The time of supply is the point when the supply is liable to GST.<br>
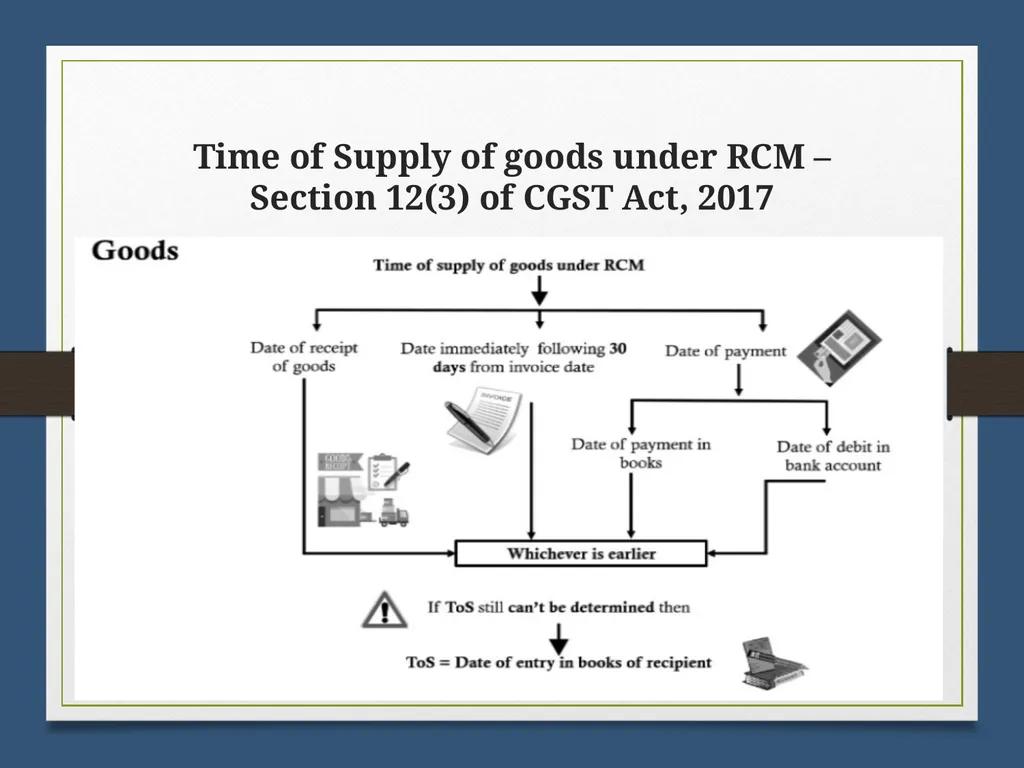
slide40. Time of Supply of goods under RCM – Section 12(3) of CGST Act, 2017<br>
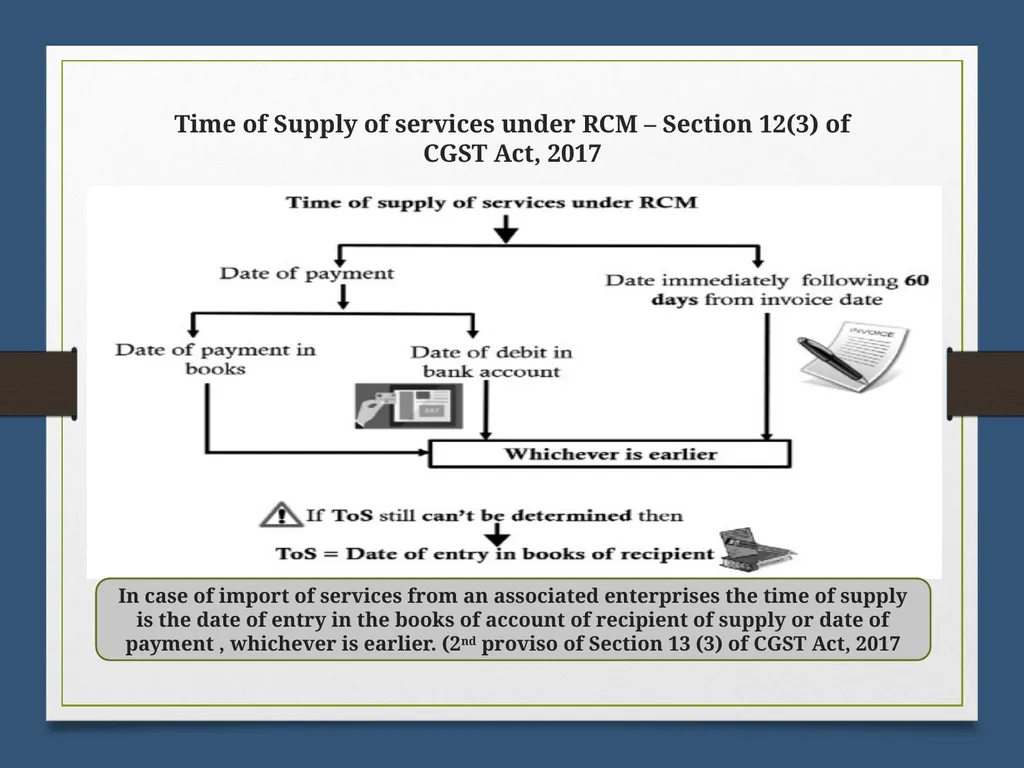
slide41. Time of Supply of services under RCM – Section 12(3) of CGST Act, 2017 In case of import of services from an associated enterprises the time of supply is the date of entry in the books of account of recipient of supply or date of payment , whichever is earlier. (2nd proviso of Section 13 (3) of CGST Act, 2017<br>
slide42. Invoice under RCM Invoice is required to be issued under Section 31(3)(f) of CGST Act, 2017
Notification 20/2024 dated 8th October 2024 (we.f 1st November 2024)
Rule 47A is inserted prescribing the time limit for issuing self-invoice:
“Notwithstanding anything contained in rule 47, where an invoice referred to in rule 46 is required to be issued under clause (f) of sub-section (3) of section 31 by a registered person, who is liable to pay tax under sub-section (3) or sub-section (4) of section 9, he shall issue the said invoice within a period of thirty days from the date of receipt of the said supply of goods or services, or both, as the case may be.<br>
slide43. Clarification giving major relief regarding applicability of provisions of Section 16(4) of CGST Act 2017 (Circular No. 211/5/2024 dated 26th June 2024) The relevant financial year for calculation of time limit for availment of input tax credit under the provisions of Section 16(4) of CGST Act is the financial year in which the invoice has been issued by the recipient.<br>
slide44. Place of Supply in RCM 1. Recipient’s Location: Where the recipient is registered under GST
2. Supplier’s Location: When recipient is not registered or when the location of the supplier is not available.
3. Intra-State RCM: If the location of Supplier and Recipient is in the same state
4. Inter-State RCM: If the location of Supplier and Recipient is in different states<br>
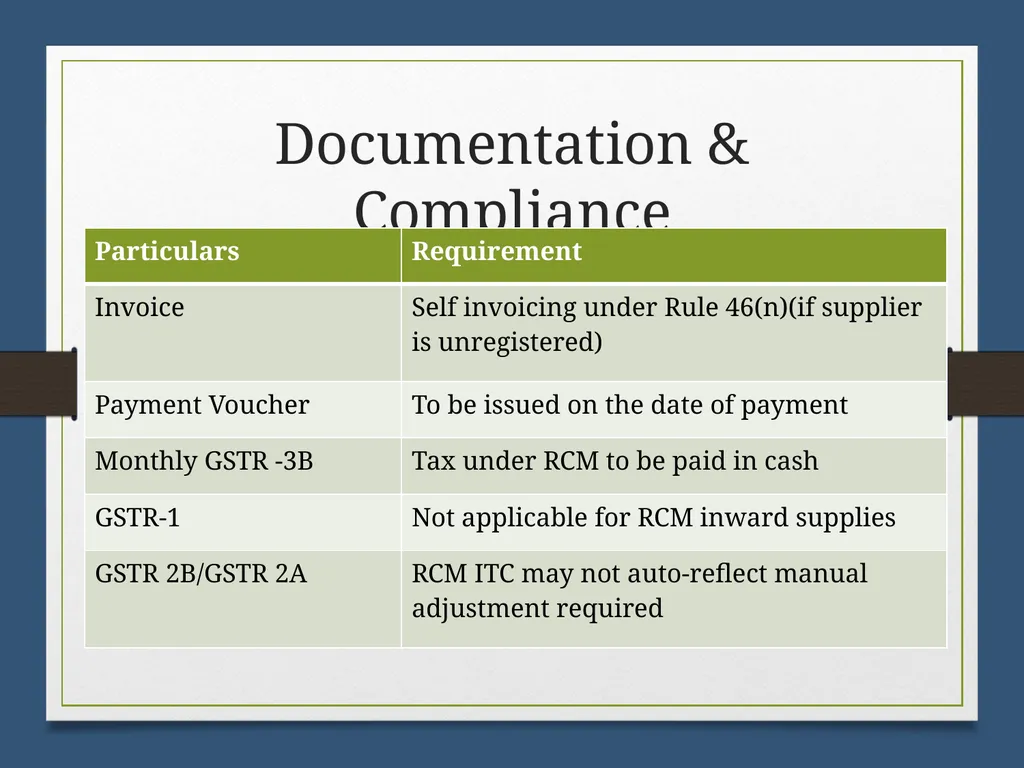
slide45. Documentation & Compliance<br>
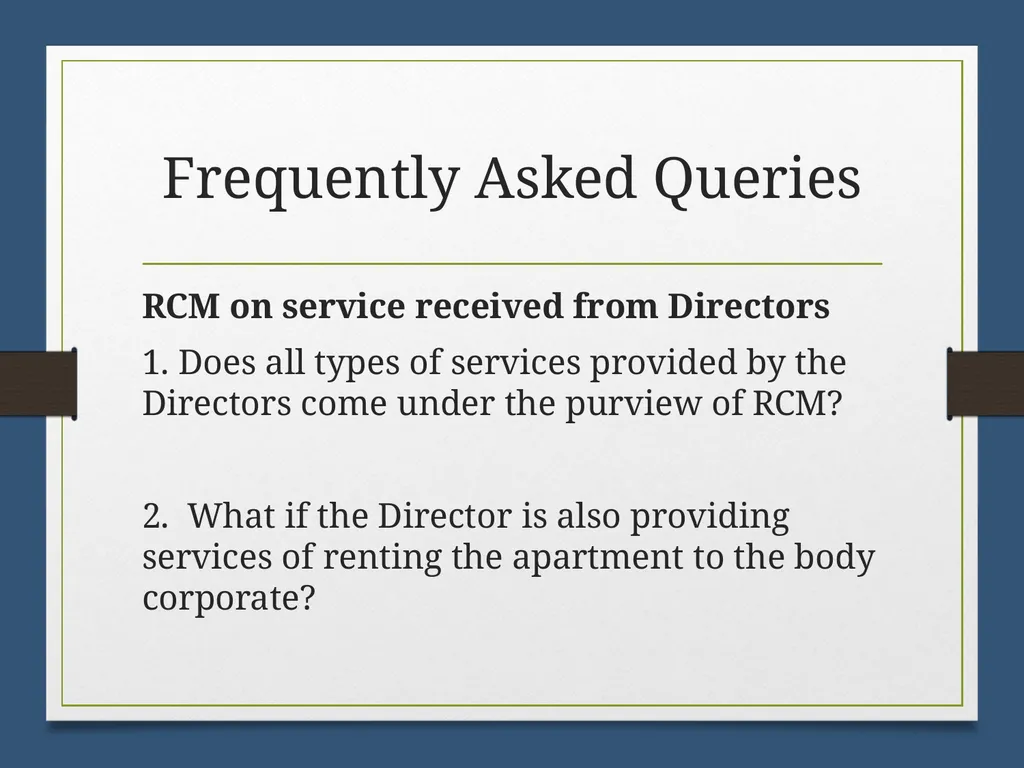
slide46. Frequently Asked Queries RCM on service received from Directors
1. Does all types of services provided by the Directors come under the purview of RCM?
2. What if the Director is also providing services of renting the apartment to the body corporate?<br>
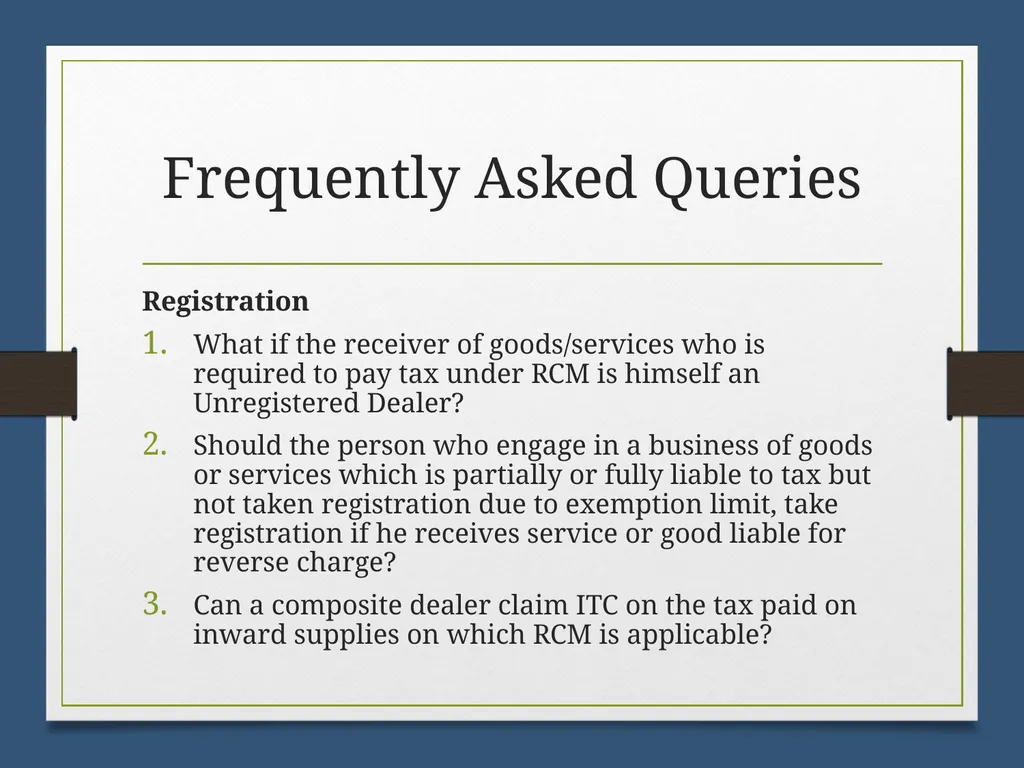
slide47. Frequently Asked Queries Registration
What if the receiver of goods/services who is required to pay tax under RCM is himself an Unregistered Dealer?
Should the person who engage in a business of goods or services which is partially or fully liable to tax but not taken registration due to exemption limit, take registration if he receives service or good liable for reverse charge?
Can a composite dealer claim ITC on the tax paid on inward supplies on which RCM is applicable?<br>
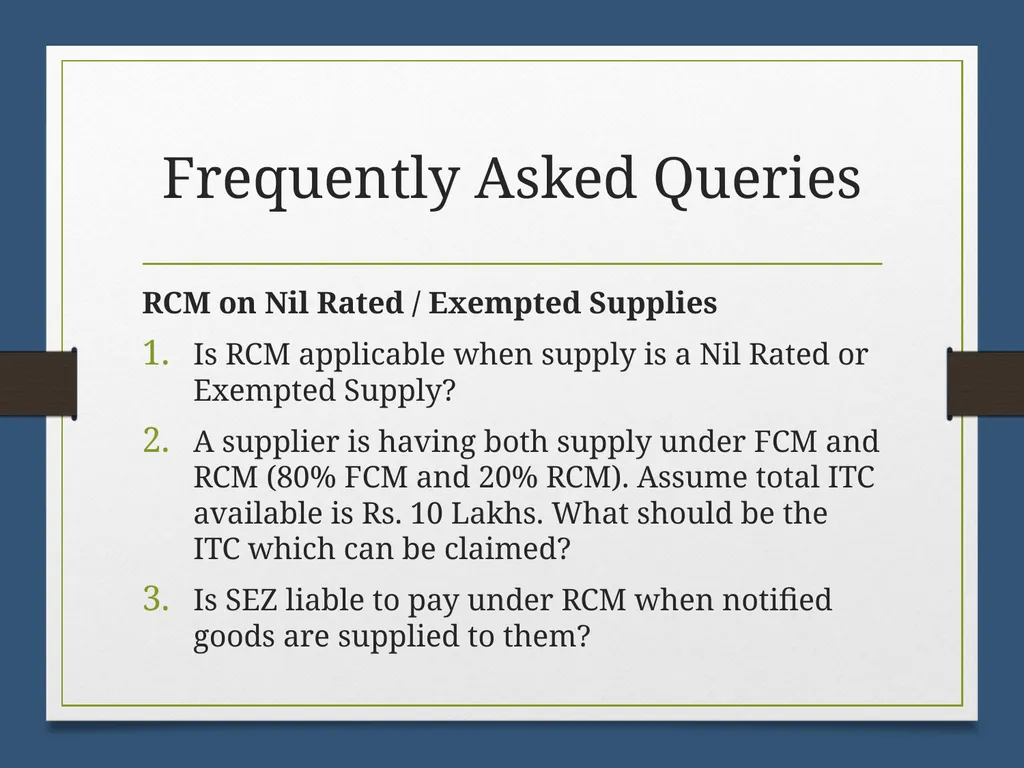
slide48. Frequently Asked Queries RCM on Nil Rated / Exempted Supplies
Is RCM applicable when supply is a Nil Rated or Exempted Supply?
A supplier is having both supply under FCM and RCM (80% FCM and 20% RCM). Assume total ITC available is Rs. 10 Lakhs. What should be the ITC which can be claimed?
Is SEZ liable to pay under RCM when notified goods are supplied to them?<br>
slide49. Frequently Asked Queries Common Queries
When Payment is made under reverse charge is ITC available in the same month?<br>
CA. Deepa Praveen, B.Com, FCA, DISA(ICAI)<br>
slide2. Introduction<br>
slide3. Introduction Reverse Charge means the liability to pay tax is on the recipient of supply instead of the supplier.
Applicable under sections 9(3), 9(4) of CGST Act and 5(3), 5(4) of IGST Act. Forward Charge<br>
slide4. Points to be noted RCM liability to be disclosed in the monthly/quarterly return
RCM liability can be paid only by cash
Self-invoice to be generated when supply received from Unregistered persons
ITC can be claimed if the outward supply is not exempt/Nil rated<br>
slide5. What is the objective of Shifting the burden to Recipient of supply To widen the tax base.
To increase tax compliance
To ensure tax compliance from unregistered or non-compliant supplier.<br>
slide6. Definition of Reverse Charge under Section 2(98) “The reverse charge means the liability to pay tax by the recipient of supply goods or services or both instead of supplier of goods or services or both
under section 9(3) & 9(4) of the act or
under section 5(3) & 5(4) of IGST act.<br>
slide8. RCM on Services - Section 9(3) Section 9(3) of CGST Act, 2017
The Government may, on the recommendations of the Council, by notification, specify categories of supply of goods or services or both, the tax on which shall be paid on reverse charge basis by the recipient of such goods or services or both and all the provisions of this Act shall apply to such recipient as if he is the person liable for paying the tax in relation to the supply of such goods or services or both.
Two important points to be noted:
Only for notified goods RCM shall be applicable
All the provisions of GST shall apply to the recipient of the supplier as if he is the person liable for paying the tax in relation to the supply<br>
slide9. Meaning of Recipient<br>
slide10. When a registered person supplies notified goods to an unregistered Person, Is he liable to pay under RCM?<br>
slide11. 3 important provisions on Registration applicable to RCM Section 22 - Every supplier shall be liable to be registered under this Act in the State or Union territory, other than special category States, from where he makes a taxable supply of goods or services or both, if his aggregate turnover in a financial year exceeds twenty lakh rupees:
Provided that where such person makes taxable supplies of goods or services or both from any of the special category States, he shall be liable to be registered if his aggregate turnover in a financial year exceeds ten lakh rupees.
Section 24(iii) - persons who are required to pay tax under reverse charge are compulsorily required to be registered under GST. There is no threshold limit applicable for registration for a recipient of RCM supplies.
Section 23(2) (read with notification 5/2017) -the persons who are only engaged in making supplies of taxable goods or services or both, the total tax on which is liable to be paid on reverse charge basis by the recipient of such goods or services or both under section 9(3) of the CGST Act are the category of persons exempted from obtaining registration under the aforesaid Act<br>
slide12. Is SEZ unit liable to pay GST under reverse charge mechanism?<br>
slide13. Where should you look for the notified goods under RCM Specified Goods:
Notification No. 04/2017 Central Tax (Rate)dt 28.06.2017
Notification No. 04/2017 Integrated Tax (Rate) dt. 28.06.2017
Specified Services:
Notification No. 13/2017 Central Tax (Rate)
Notification No. 10/2017 Integrated Tax (Rate)<br>
slide14. Specified goods notified by Notification 4/2017 Central Tax (Rate)<br>
slide15. RCM on Metal Scrap Purchase Notification 06/2024 Central Tax (Rate), dated 08/10/2024<br>
slide17. Specified services notified by Notification 13/2017 Central Tax (Rate) Goods Transport Agency (GTA)<br>
slide18. Specified Persons Any factory registered under or governed by the Factories Act, 1948(63 of 1948); or
Any society registered under the Societies Registration Act, 1860 (21 of 1860) or under any other law for the time being in force in any part of India; or
Any co-operative society established by or under any law; or
Any person registered under the Central Goods and Services Tax Act or the Integrated Goods and Services Tax Act or the State Goods and Services Tax Act or the Union Territory Goods and Services Tax Act; or
Any body corporate established, by or under any law; or
Any partnership firm whether registered or not under any law including association of persons; or
Any casual taxable person.<br>
slide19. Liability to pay tax by GTA 18%<br>
slide20. Ancillary Activities of GTA GST Clarification for Goods Transport Agencies (GTA)-Circular 234/28/2024 GST dated 11/10/2024<br>
slide21. RCM on Legal Services “Legal Services” – means any service provided in relation to advice, consultancy or assistance in any branch of law, in any manner and includes representational services before any court, tribunal or authority
Supplier of the Service – An individual advocate including a Senior Advocate of Firm of advocates
Scope of Service – Representational services before any court, tribunal or authority, directly or indirectly
Recipient of Service liable to pay RCM: Any business entity located in the taxable territory Advocate Services provided to business entity whose aggregate turnover is up to Rs.20 Lakhs/Rs. 40 Lakhs are exempt, vide Sr. Nos. 45 of Notification No. 12/2017-CT (Rate)<br>
slide22. RCM on Sponsorship Services<br>
slide23. RCM - Government Supplier of the Service – Central Government, State Government, Union Territory or Local Authority
Scope of Service – All services supplied by CG, SG, UT or Local Authority except:
Renting of immovable property
Services of Department of posts (speed posts, express parcel post, life insurance, and agency services) provided to a person other than Govt.
Services in relation to an aircraft or a vessel
Transport of goods or passengers
Recipient of Service liable to pay RCM: Any business entity located in the taxable territory
Note: In case of service of renting of immovable property provided by the CG, SG/UT, Local Authority to any registered person under CGST, then such registered person is liable to pay tax under RCM w.e.f 25/01/2018<br>
slide24. RCM - Government Supplier of the Service – Central Government, State Government, Union Territory or Local Authority
Scope of Service – All services supplied by CG, SG, UT or Local Authority except:
Renting of immovable property
Services of Department of posts (speed posts, express parcel post, life insurance, and agency services) provided to a person other than Govt.
Services in relation to an aircraft or a vessel
Transport of goods or passengers
Recipient of Service liable to pay RCM: Any business entity located in the taxable territory
Note: In case of service of renting of immovable property provided by the CG, SG/UT, Local Authority to any registered person under CGST, then such registered person is liable to pay tax under RCM w.e.f 25/01/2018<br>
slide25. RCM – Renting of Residential dwelling for residential purposes Supplier of the Service – Central Government, State Government, Union Territory or Local Authority
Scope of Service – All services supplied by CG, SG, UT or Local Authority except:
Renting of immovable property
Services of Department of posts (speed posts, express parcel post, life insurance, and agency services) provided to a person other than Govt.
Services in relation to an aircraft or a vessel
Transport of goods or passengers
Recipient of Service liable to pay RCM: Any business entity located in the taxable territory
Note: In case of service of renting of immovable property provided by the CG, SG/UT, Local Authority to any registered person under CGST, then such registered person is liable to pay tax under RCM w.e.f 25/01/2018 Recipient of Service liable to pay RCM: Any registered person (other than a person who has opted for composition levy) Changed from 16 Jan 2025 vide notification 7/2025 – CT (rate)<br>
slide26. Renting of residential property for residential purpose<br>
slide27. RCM on Renting of Residential Property for Commercial purpose<br>
slide28. RCM – Directorship Services Supplier of the Service – Central Government, State Government, Union Territory or Local Authority
Scope of Service – All services supplied by CG, SG, UT or Local Authority except:
Renting of immovable property
Services of Department of posts (speed posts, express parcel post, life insurance, and agency services) provided to a person other than Govt.
Services in relation to an aircraft or a vessel
Transport of goods or passengers
Recipient of Service liable to pay RCM: Any business entity located in the taxable territory
Schedule III: Any transaction where in the course of employment contract, the employee renders any service to employer it is not liable to tax.<br>
slide29. RCM on Security Services<br>
slide30. RCM – Renting of Motor Vehicles where cost of fuel is included w.e.f 01.10.2024<br>
slide31. Notification 10/2017- IGST (Rate) RCM – Any Service supplied by any person who is located in a non-taxable territory<br>
slide32. Entry No. 10 of Notification 10/2017 - Services supplied by a person located in non- taxable territory by way of transportation of goods by a vessel from a place outside India up to the customs station of clearance in India. w. e.f 01/10/2023 – IGST will not be leviable on Ocean freight under reverse charge on CIF contracts of import of goods by the Indian Importers<br>
slide33. Judgement of Mohit Minerals Pvt. Ltd. The importer cannot be subjected to RCM, once the ocean freight is paid by the foreign seller to the foreign shipping line.
The person liable to make payment of the consideration would be the foreign supplier. Hence, Indian importer cannot be considered as the recipient of services.
Levy imposed on the ‘service’ aspect of the transaction is in violation of the principle of ‘composite supply’ under Section of 8 of CGST Act<br>
slide34. RCM – Other Services<br>
slide35. RCM – Other Services<br>
slide36. RCM – Other Services<br>
slide37. RCM under Section 9(4) of CGST ACT and Section 15(4) of IGST Act Section 9(4) -
“The Government may, on the recommendations of the Council, by notification, specify a class of registered persons who shall, in respect of supply of specified categories of goods or services or both received from an unregistered supplier, pay the tax on reverse charge basis as the recipient of such supply of goods or services or both, and all the provisions of this Act shall apply to such recipient as if he is the person liable for paying the tax in relation to such supply of goods or services or both.”
Initially applicable on all inward supplies which was more than Rs. 5,000 per day from unregistered persons. (From 01.04.2017 to 13.10.2017)
Now restricted to specified class of registered persons (w.e.f 01.02.2019)
New Provisions of Section 9(4) notified by Notification No. 2/2019 –CT(Rate) dt 29.01.2019, w.e.f 01.02.2019<br>
slide38. Notification 07/2019-CT (Rate) dated 29th March 2019 w.e.f 01/04/2019 Kinds of supplies that have been specified for which ‘promoter’ shall be liable to pay tax under reverse charge:
1. Input and Input services for Construction Contract.
RCM is applicable for shortfall from the minimum of goods or services or both required to be purchased by a promoter. (Notification No. 3/2019-Central Tax (Rate) dated 29th March 2019 specifies that 80% of inputs and input services should be procured from registered person.)
2. Purchase of Cement: (Notification No. 24/2019-Central Tax (Rate) dated 30 September, 2019)
RCM will be applicable on any amount of purchase of ‘Cement’ by the “promoter” from an unregistered supplier for the construction of project.
3 For Purchase of Capital Goods: (Notification 7/2019 – Central Tax (Rate) dated 29th March 2019
“promoter” is liable to pay GST under RCM for purchase of any capital goods from any unregistered supplier for construction of project during the financial year.<br>
slide39. Time of Supply Why is it so relevant???
The time of supply is the point when the supply is liable to GST.<br>
slide40. Time of Supply of goods under RCM – Section 12(3) of CGST Act, 2017<br>
slide41. Time of Supply of services under RCM – Section 12(3) of CGST Act, 2017 In case of import of services from an associated enterprises the time of supply is the date of entry in the books of account of recipient of supply or date of payment , whichever is earlier. (2nd proviso of Section 13 (3) of CGST Act, 2017<br>
slide42. Invoice under RCM Invoice is required to be issued under Section 31(3)(f) of CGST Act, 2017
Notification 20/2024 dated 8th October 2024 (we.f 1st November 2024)
Rule 47A is inserted prescribing the time limit for issuing self-invoice:
“Notwithstanding anything contained in rule 47, where an invoice referred to in rule 46 is required to be issued under clause (f) of sub-section (3) of section 31 by a registered person, who is liable to pay tax under sub-section (3) or sub-section (4) of section 9, he shall issue the said invoice within a period of thirty days from the date of receipt of the said supply of goods or services, or both, as the case may be.<br>
slide43. Clarification giving major relief regarding applicability of provisions of Section 16(4) of CGST Act 2017 (Circular No. 211/5/2024 dated 26th June 2024) The relevant financial year for calculation of time limit for availment of input tax credit under the provisions of Section 16(4) of CGST Act is the financial year in which the invoice has been issued by the recipient.<br>
slide44. Place of Supply in RCM 1. Recipient’s Location: Where the recipient is registered under GST
2. Supplier’s Location: When recipient is not registered or when the location of the supplier is not available.
3. Intra-State RCM: If the location of Supplier and Recipient is in the same state
4. Inter-State RCM: If the location of Supplier and Recipient is in different states<br>
slide45. Documentation & Compliance<br>
slide46. Frequently Asked Queries RCM on service received from Directors
1. Does all types of services provided by the Directors come under the purview of RCM?
2. What if the Director is also providing services of renting the apartment to the body corporate?<br>
slide47. Frequently Asked Queries Registration
What if the receiver of goods/services who is required to pay tax under RCM is himself an Unregistered Dealer?
Should the person who engage in a business of goods or services which is partially or fully liable to tax but not taken registration due to exemption limit, take registration if he receives service or good liable for reverse charge?
Can a composite dealer claim ITC on the tax paid on inward supplies on which RCM is applicable?<br>
slide48. Frequently Asked Queries RCM on Nil Rated / Exempted Supplies
Is RCM applicable when supply is a Nil Rated or Exempted Supply?
A supplier is having both supply under FCM and RCM (80% FCM and 20% RCM). Assume total ITC available is Rs. 10 Lakhs. What should be the ITC which can be claimed?
Is SEZ liable to pay under RCM when notified goods are supplied to them?<br>
slide49. Frequently Asked Queries Common Queries
When Payment is made under reverse charge is ITC available in the same month?<br>