
Revisiting the Bright and Dark Sides of Capital

Description: Revisiting the Bright and Dark Sides of Capital Flows in Business Groups Joseph P. H. Fan The Chinese University of Hong Kong Li Jin Oxford University Peiking University Guojian Zheng Sun Yat-sen University Basic Business Group Structures
Related Topics
Download Presentation
"Revisiting the Bright and Dark Sides of Capital" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Revisiting the Bright and Dark Sides of Capital Flows in Business Groups Joseph P. H. Fan
The Chinese University of Hong Kong
Li Jin
Oxford University & Peiking University
Guojian Zheng
Sun Yat-sen University<br>
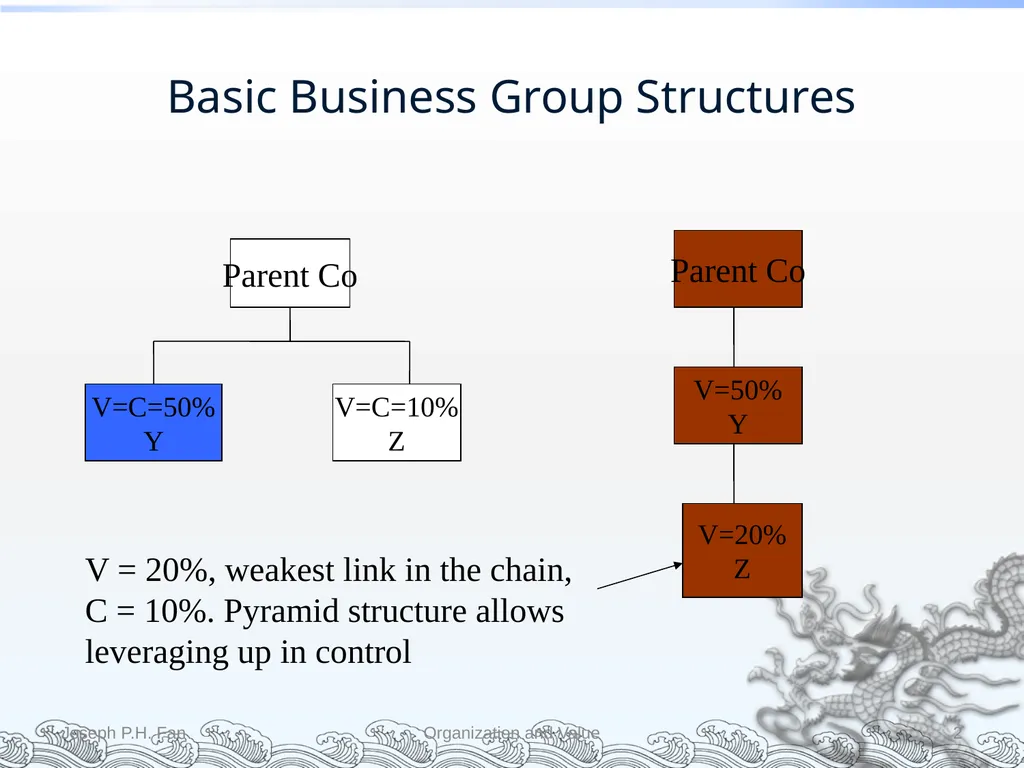
slide2. Basic Business Group Structures Joseph P.H. Fan Organization and Value 2 Parent Co Parent Co V=50%
Y V=20%
Z V=C=10%
Z V=C=50%
Y V = 20%, weakest link in the chain,
C = 10%. Pyramid structure allows
leveraging up in control<br>
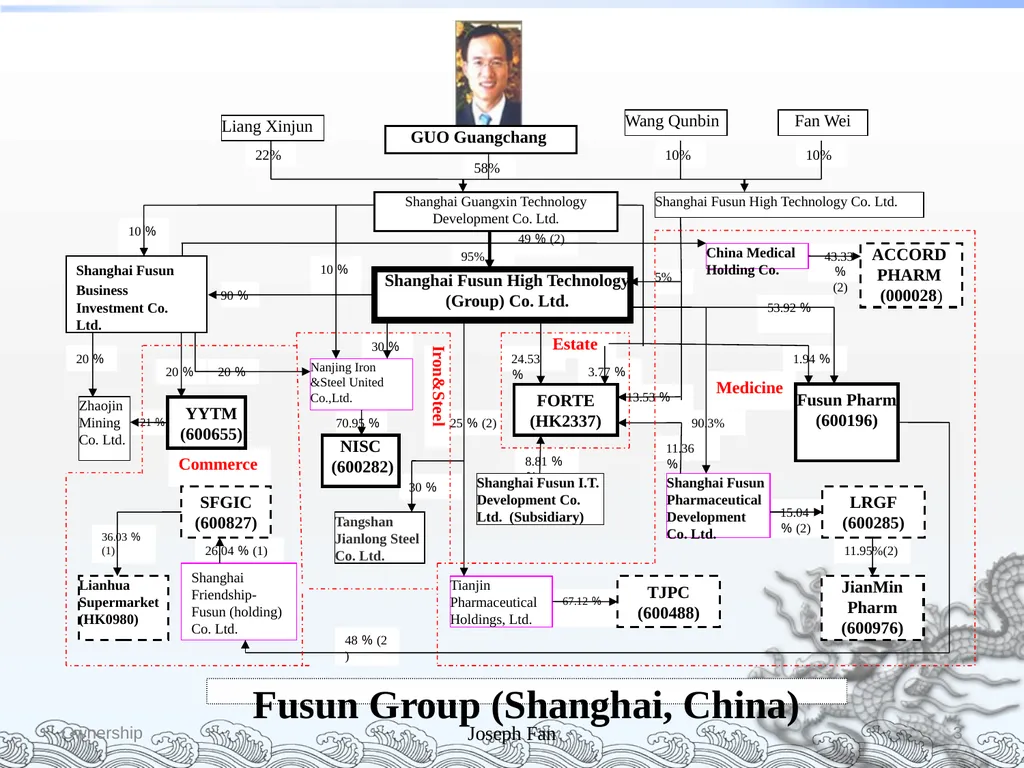
slide3. Ownership Joseph Fan 3 Fusun Group (Shanghai, China) 20% Iron&Steel 25%(2) Commerce Medicine 24.53% Estate 10% 10% 22% 5% 11.95%(2) 10% 58% 95% 13.53% 90.3% 20% 90% 1.94% 10% 49%(2) 15.04%(2) 26.04%(1) 70.95% 11.36% 8.81%% 43.33%
(2) 30% 3.77% 30% 67.12% 36.03%(1) 48%(2) 20% 21% Shanghai Guangxin Technology Development Co. Ltd. Shanghai Fusun High Technology (Group) Co. Ltd. NISC
(600282) FORTE
(HK2337) YYTM
(600655) 53.92% Nanjing Iron &Steel United Co.,Ltd. Shanghai Fusun Pharmaceutical Development Co. Ltd. Shanghai Fusun I.T. Development Co. Ltd. (Subsidiary) LRGF
(600285) Tianjin Pharmaceutical Holdings, Ltd. TJPC
(600488) China Medical Holding Co. ACCORD PHARM
(000028) Shanghai Friendship-Fusun (holding) Co. Ltd. SFGIC
(600827) Tangshan Jianlong Steel Co. Ltd. Lianhua Supermarket
(HK0980) Fusun Pharm
(600196) Zhaojin Mining Co. Ltd. JianMin Pharm
(600976) Shanghai Fusun High Technology Co. Ltd. Shanghai Fusun Business Investment Co. Ltd. Liang Xinjun GUO Guangchang Wang Qunbin Fan Wei<br>
slide4. Business Group Structure v.s. Conglomerate Structure Group-like organizations are commonplace in the world.
Comparing with the conglomerate organization
Similarity: complex internal resource flows
Difference: legal boundaries, top down control as oppose to horizontal control, complex ownership structure
Because divisions are legally separate entities in a business group, intra-group capital flow becomes an issue to outside minority owners<br>
slide5. Costs of the Group Structure Expropriation of minority shareholders by the controlling parent, e.g., tunneling(Johnson et al.,2000)
From the perspective of the whole group, such “tunneling” might not be a zero-sum game.
additional resources to cover up tunneling, potential legal penalties, ex ante distortion of incentives on investments
Investors not systematically fooled, the insider of the business group ultimately bears the welfare loss from tunneling.
Cost of the tunneling is reflected in lower security prices (Claessens et al., 2002; La Porta et al., 2002).<br>
slide6. Firms controlled by Pyramids are traded with a discount across all public traded East Asian Firms (Claessens, Djankov, Fan, Lang, Journal of Finance 2002; Based on 3000 East Asian Firms) Ownership Joseph Fan 6<br>
slide7. Motivation Given the costly group structure, what explains the persistent existence and prevalence of business groups?
For the whole group in under-developed financial markets: tunneling may be a constrained optimum even if not the first-best outcome , if it
alleviates severe financing constraints of member firms, and enables the undertaking of positive NPV projects
Many papers in the conglomerate literature (Stein, 1997…)
Business group literature: Morck, Wolfenzon, Yeung, 2005; Almeida and Wolfenzon, 2006, 2010; Khanna and Yafeh, 2007; Gopalan et al., 2007; Masulis et al., 2012<br>
slide8. Empirical Challenges Key challenge to empirical research demonstrating this tradeoff:
to disentangle the resources diverted to facilitate group efficiency from those diverted to satisfy the private benefits of the controlling shareholder
For minority shareholders: both are tunneling. But from the business group perspective, sacrificing a division may benefit the whole group
Parent firms typically not observable because of non-listed status
Measurement problem (Kaplan and Zingales, 1997, 2000)<br>
slide9. Our attempt In this paper, we make a modest attempt to bypass the above difficulties by
focusing on transfers of financial resources within business groups, and
testing the hypothesis that intra-group capital flow may be motivated by both group capital allocation efficiency and pure expropriation of minority shareholders.<br>
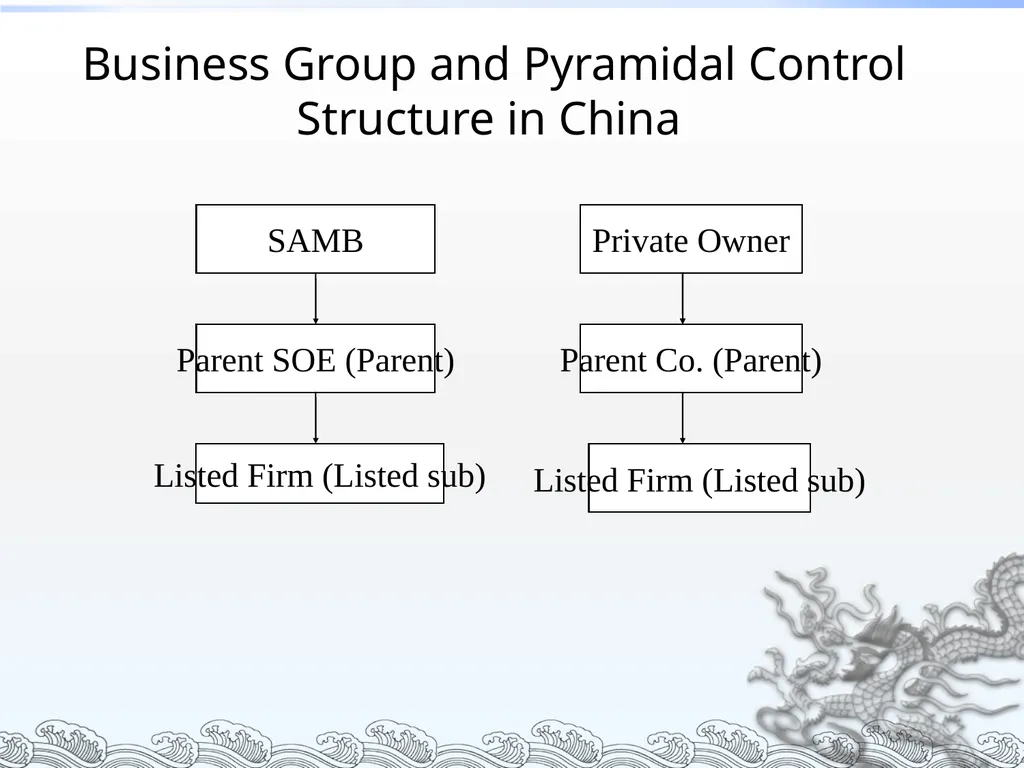
slide10. Business Group and Pyramidal Control Structure in China SAMB Parent Co. (Parent) Parent SOE (Parent) Listed Firm (Listed sub) Listed Firm (Listed sub) Private Owner<br>
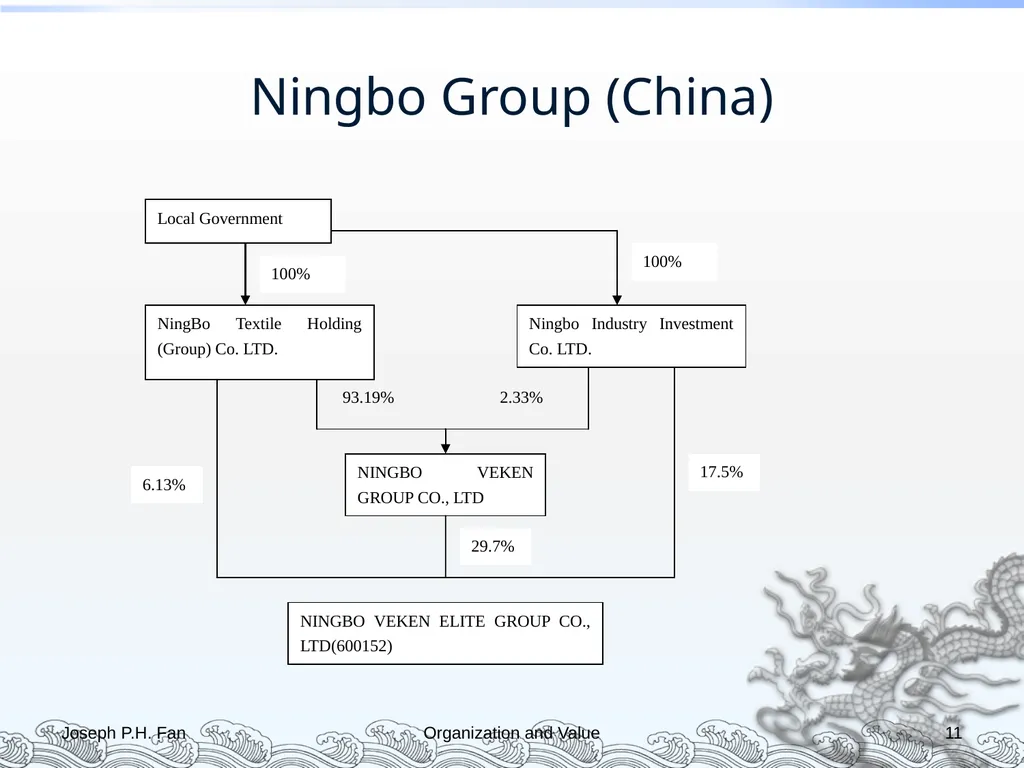
slide11. Joseph P.H. Fan Organization and Value 11 Ningbo Group (China)<br>
slide12. A Model of Financial Tunneling Suppose an owner of a business group carves out a subsidiary and lists it, which results in
pair of a publicly listed sub (listed sub) and a non-listed parent company (parent).
Control is one-directional in the firm pair
The public listing allows the owner to raise external capital and create a class of minority shareholders in the listed subsidiary.<br>
slide13. Assumptions of the Model Financial transactions between the pair serve to
fund investment projects in parent or subsidiary
or be consumed by the controlling owner as private benefits.
Legal environment is unable to fully prevent such tunneling activities (Johnson et al., 2000) .
The parent company cannot effectively commit to refraining from tunneling because of
the opportunity losses from private benefits and investment opportunities, or
the costs of self-imposed corporate governance constraints.
The non-listed parent is much more financially constrained than the listed subsidiary.<br>
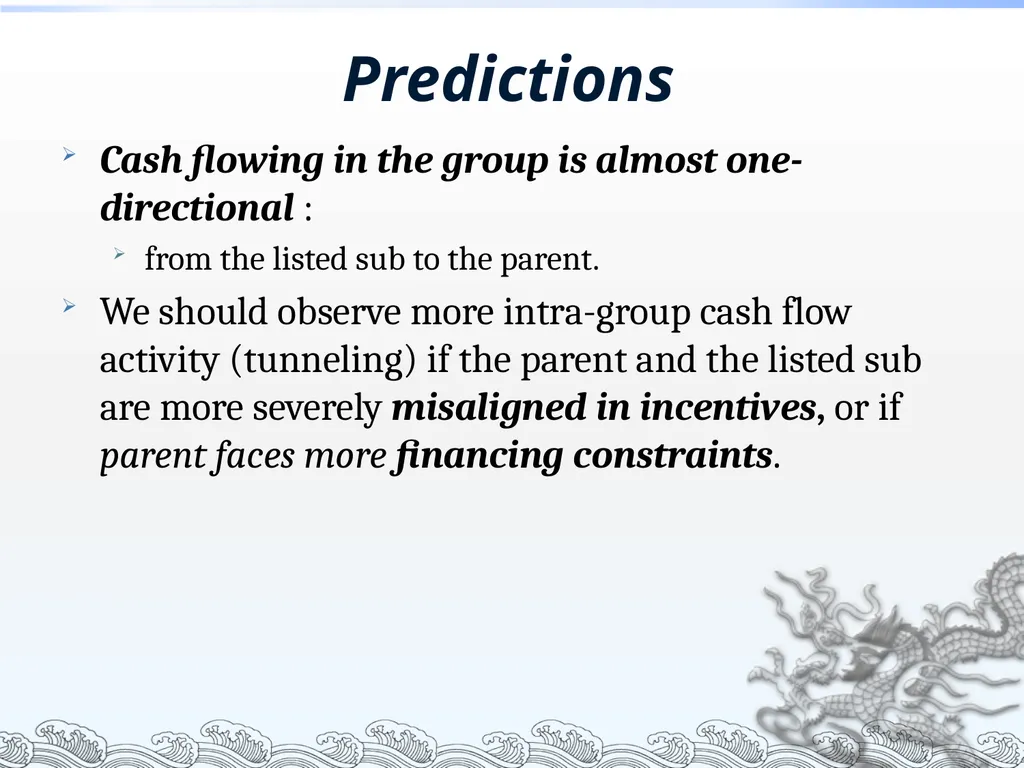
slide14. Predictions Cash flowing in the group is almost one-directional :
from the listed sub to the parent.
We should observe more intra-group cash flow activity (tunneling) if the parent and the listed sub are more severely misaligned in incentives, or if parent faces more financing constraints.<br>
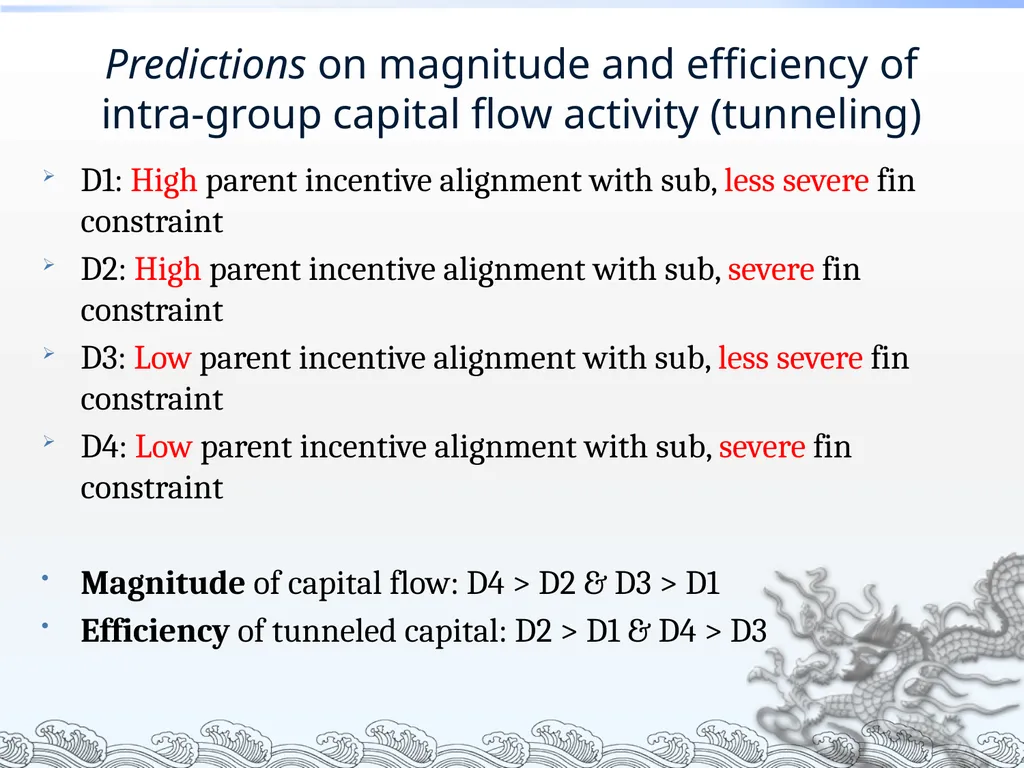
slide15. Predictions on magnitude and efficiency of intra-group capital flow activity (tunneling) D1: High parent incentive alignment with sub, less severe fin constraint
D2: High parent incentive alignment with sub, severe fin constraint
D3: Low parent incentive alignment with sub, less severe fin constraint
D4: Low parent incentive alignment with sub, severe fin constraint
Magnitude of capital flow: D4 > D2 & D3 > D1
Efficiency of tunneled capital: D2 > D1 & D4 > D3<br>
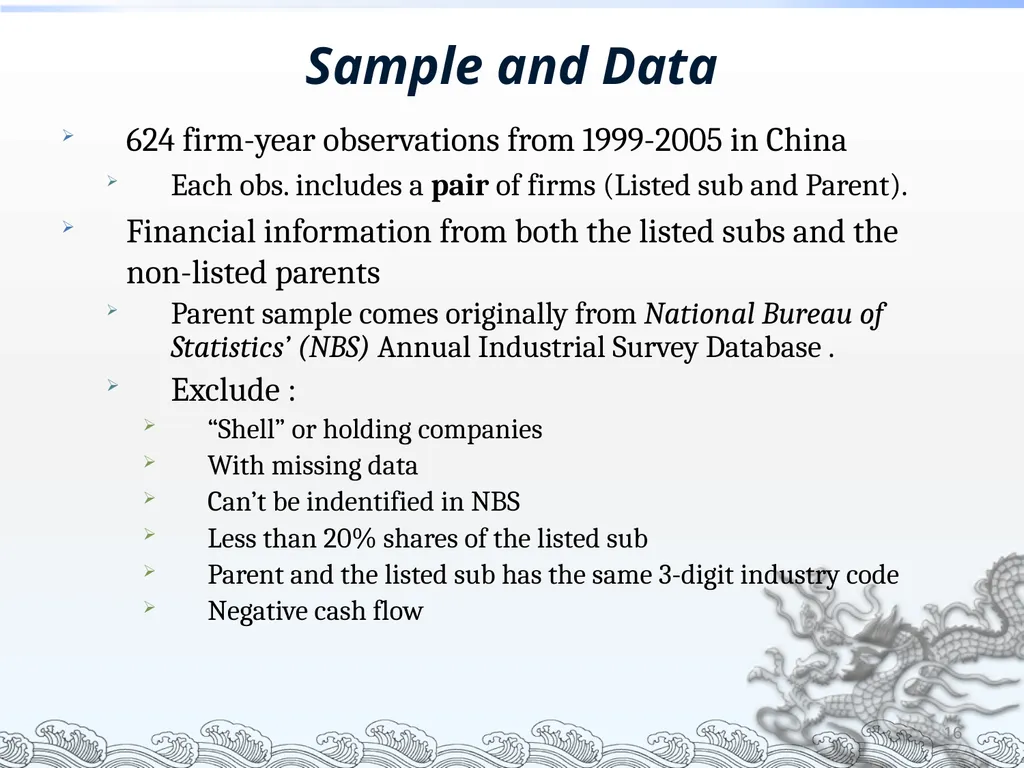
slide16. Sample and Data 624 firm-year observations from 1999-2005 in China
Each obs. includes a pair of firms (Listed sub and Parent).
Financial information from both the listed subs and the non-listed parents
Parent sample comes originally from National Bureau of Statistics’ (NBS) Annual Industrial Survey Database .
Exclude :
“Shell” or holding companies
With missing data
Can’t be indentified in NBS
Less than 20% shares of the listed sub
Parent and the listed sub has the same 3-digit industry code
Negative cash flow 16<br>
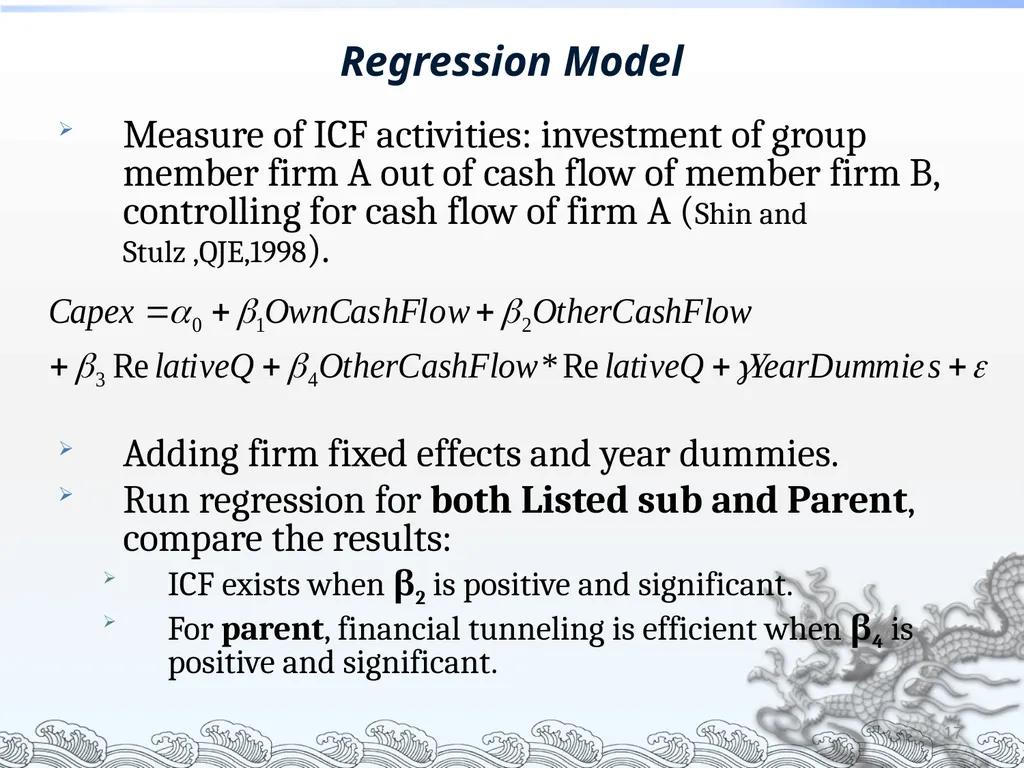
slide17. Regression Model Measure of ICF activities: investment of group member firm A out of cash flow of member firm B, controlling for cash flow of firm A (Shin and Stulz ,QJE,1998).
Adding firm fixed effects and year dummies.
Run regression for both Listed sub and Parent, compare the results:
ICF exists when β2 is positive and significant.
For parent, financial tunneling is efficient when β4 is positive and significant. 17<br>
slide18. Relative investment opportunity Relative Q = difference in industry Tobin’s q between the parent and the sub
Use industry average q because parent is not listed and to mitigate measurement bias if firm level q is otherwise used<br>
slide19. Cash flow measures in the literature Cash flow=income after tax+ depreciation –dividend payments
Hoshi, Kashyap and Scharfstein (QJE,1991 )
Cash flow=earnings before extraordinary items+ depreciation
Kaplan and Zingales (QJE,1997)
Cash flow=earnings before interest and tax +depreciation + amortization (EBITDA)
Kaplan and Zingales (QJE,1997)
Cash flow=operating profit+ depreciation
Shin and Stulz (QJE,1998); Shin and Park(JCF,1999)<br>
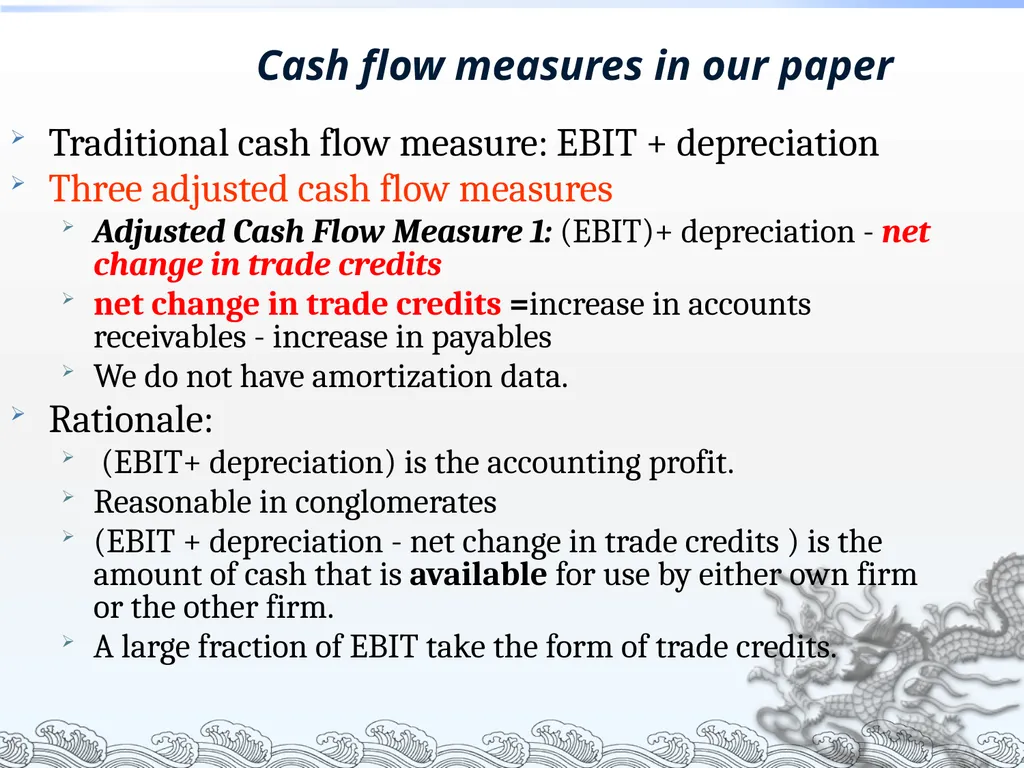
slide20. Cash flow measures in our paper Traditional cash flow measure: EBIT + depreciation
Three adjusted cash flow measures
Adjusted Cash Flow Measure 1: (EBIT)+ depreciation - net change in trade credits
net change in trade credits =increase in accounts receivables - increase in payables
We do not have amortization data.
Rationale:
(EBIT+ depreciation) is the accounting profit.
Reasonable in conglomerates
(EBIT + depreciation - net change in trade credits ) is the amount of cash that is available for use by either own firm or the other firm.
A large fraction of EBIT take the form of trade credits.<br>
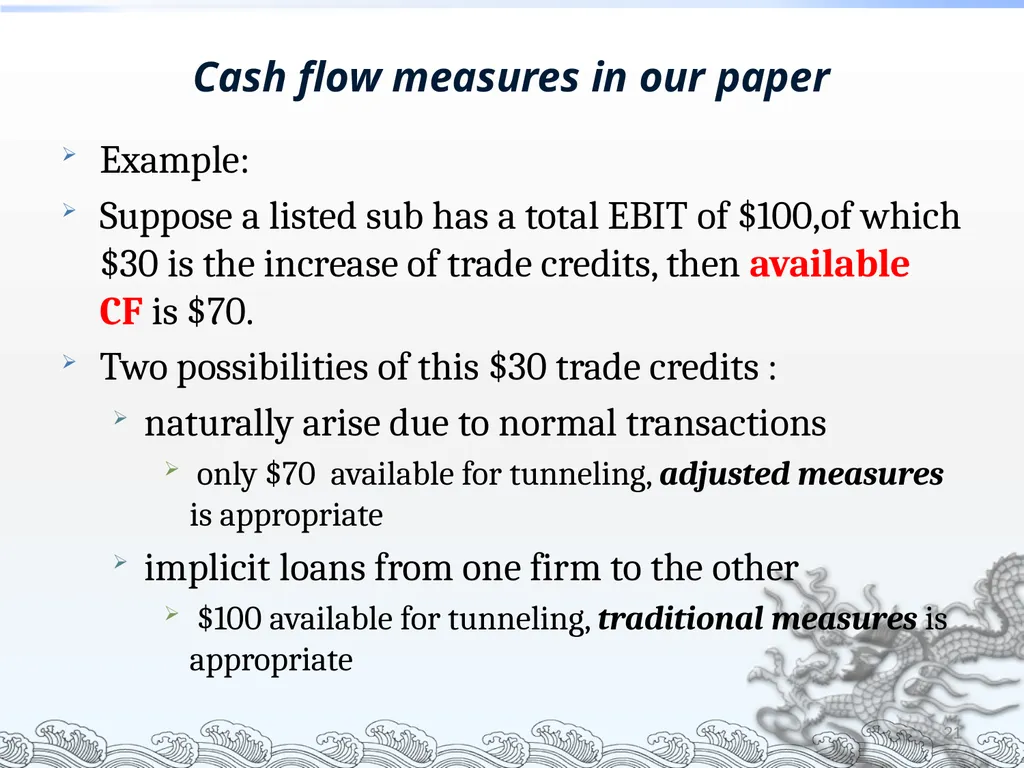
slide21. Cash flow measures in our paper Example:
Suppose a listed sub has a total EBIT of $100,of which $30 is the increase of trade credits, then available CF is $70.
Two possibilities of this $30 trade credits :
naturally arise due to normal transactions
only $70 available for tunneling, adjusted measures is appropriate
implicit loans from one firm to the other
$100 available for tunneling, traditional measures is appropriate 21<br>
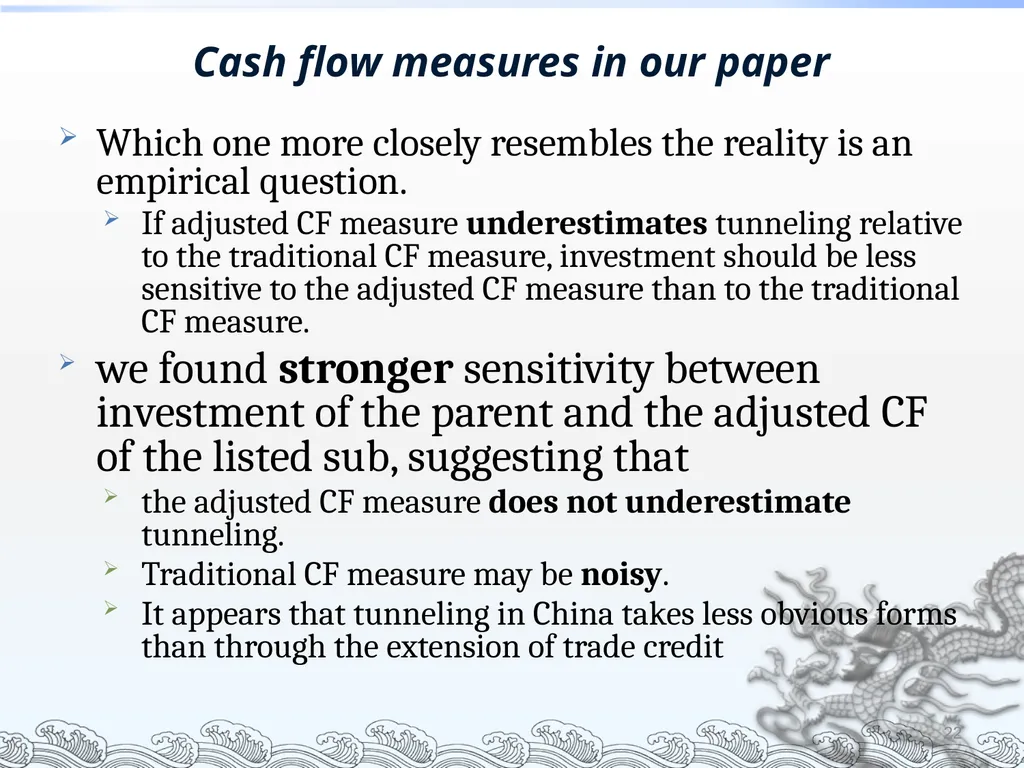
slide22. Cash flow measures in our paper Which one more closely resembles the reality is an empirical question.
If adjusted CF measure underestimates tunneling relative to the traditional CF measure, investment should be less sensitive to the adjusted CF measure than to the traditional CF measure.
we found stronger sensitivity between investment of the parent and the adjusted CF of the listed sub, suggesting that
the adjusted CF measure does not underestimate tunneling.
Traditional CF measure may be noisy.
It appears that tunneling in China takes less obvious forms than through the extension of trade credit 22<br>
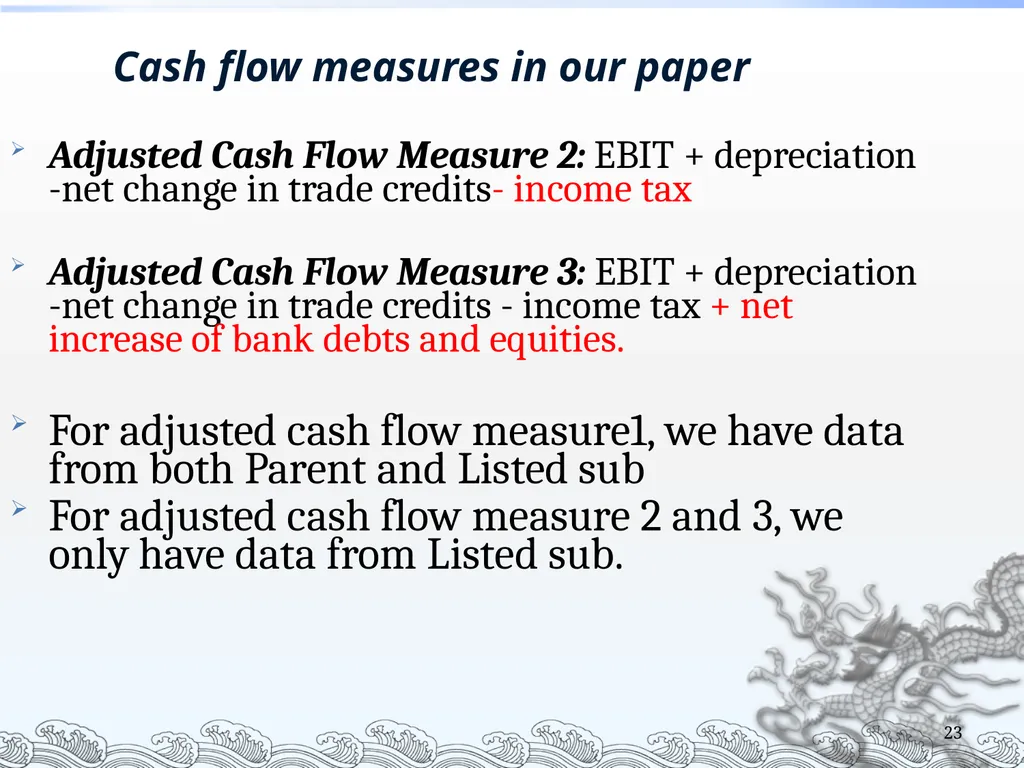
slide23. 23 Cash flow measures in our paper Adjusted Cash Flow Measure 2: EBIT + depreciation -net change in trade credits- income tax
Adjusted Cash Flow Measure 3: EBIT + depreciation -net change in trade credits - income tax + net increase of bank debts and equities.
For adjusted cash flow measure1, we have data from both Parent and Listed sub
For adjusted cash flow measure 2 and 3, we only have data from Listed sub.<br>
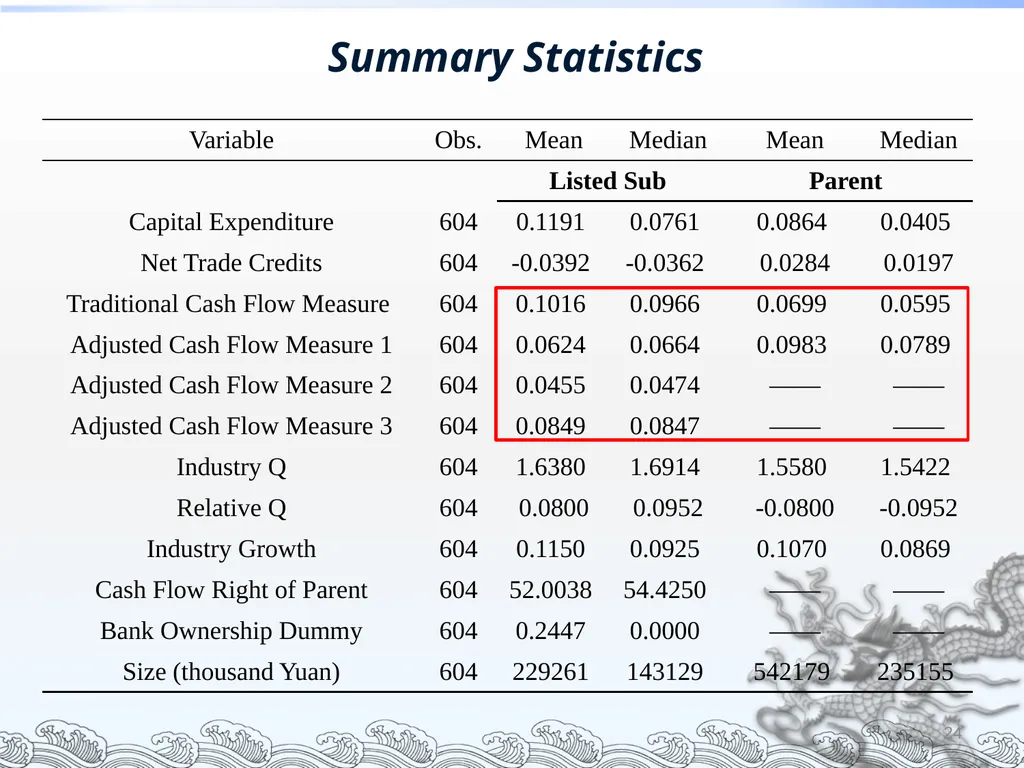
slide24. Summary Statistics 24<br>
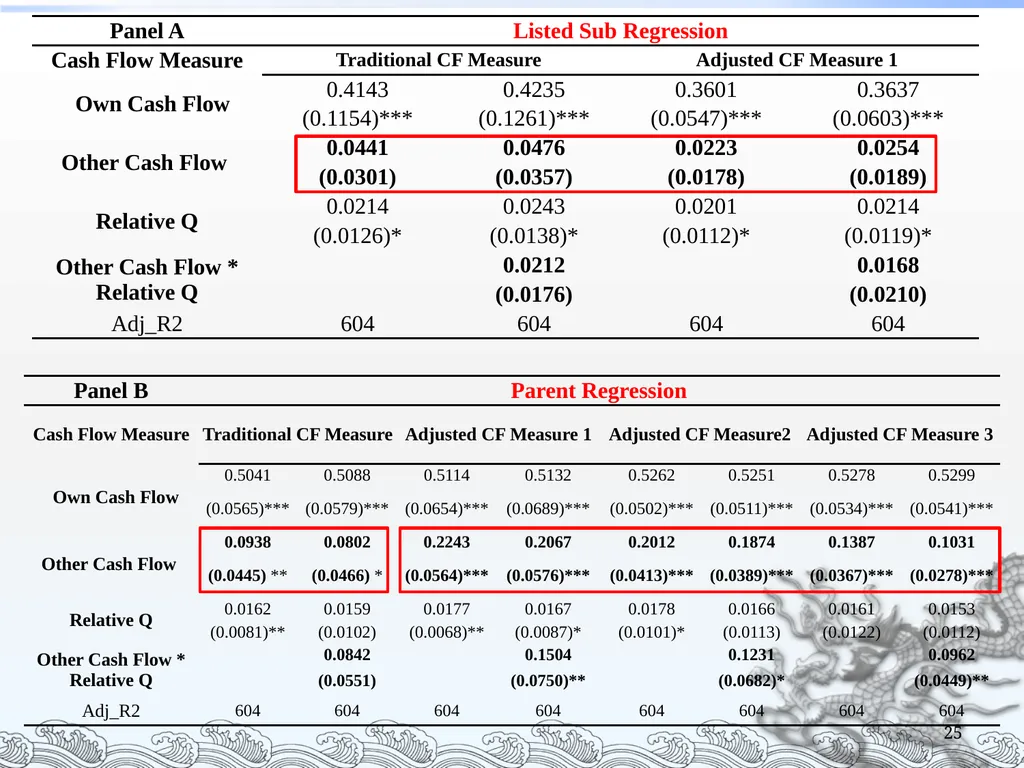
slide25. 25<br>
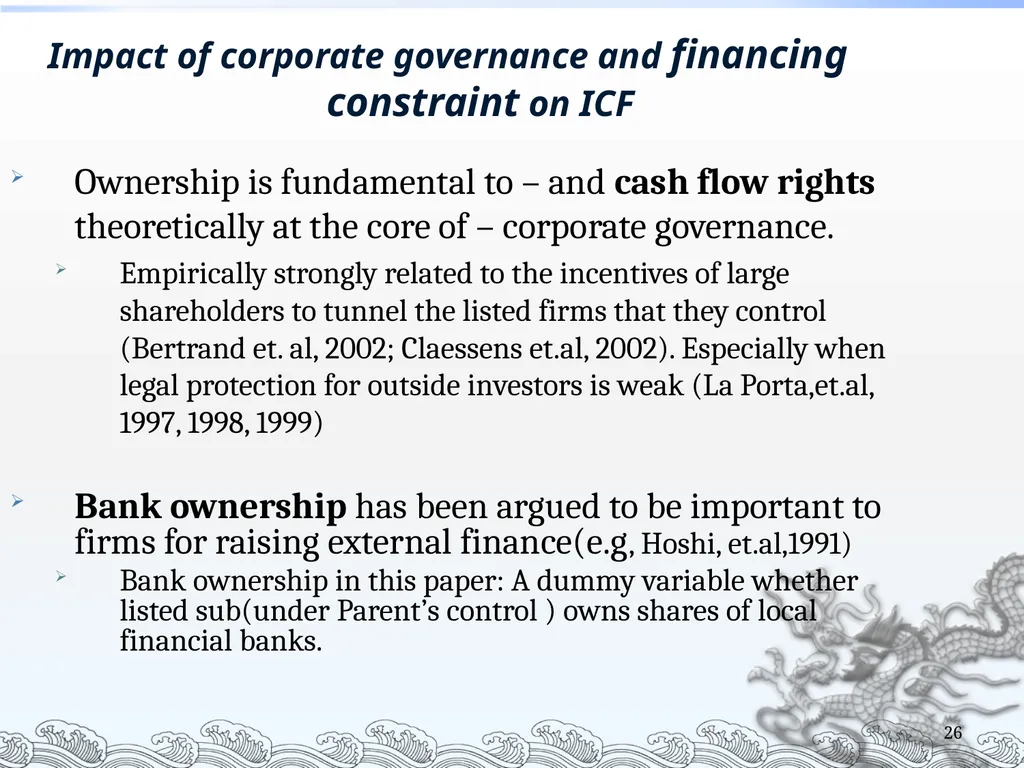
slide26. 26 Impact of corporate governance and financing constraint on ICF Ownership is fundamental to – and cash flow rights theoretically at the core of – corporate governance.
Empirically strongly related to the incentives of large shareholders to tunnel the listed firms that they control (Bertrand et. al, 2002; Claessens et.al, 2002). Especially when legal protection for outside investors is weak (La Porta,et.al, 1997, 1998, 1999)
Bank ownership has been argued to be important to firms for raising external finance(e.g, Hoshi, et.al,1991)
Bank ownership in this paper: A dummy variable whether listed sub(under Parent’s control ) owns shares of local financial banks.<br>
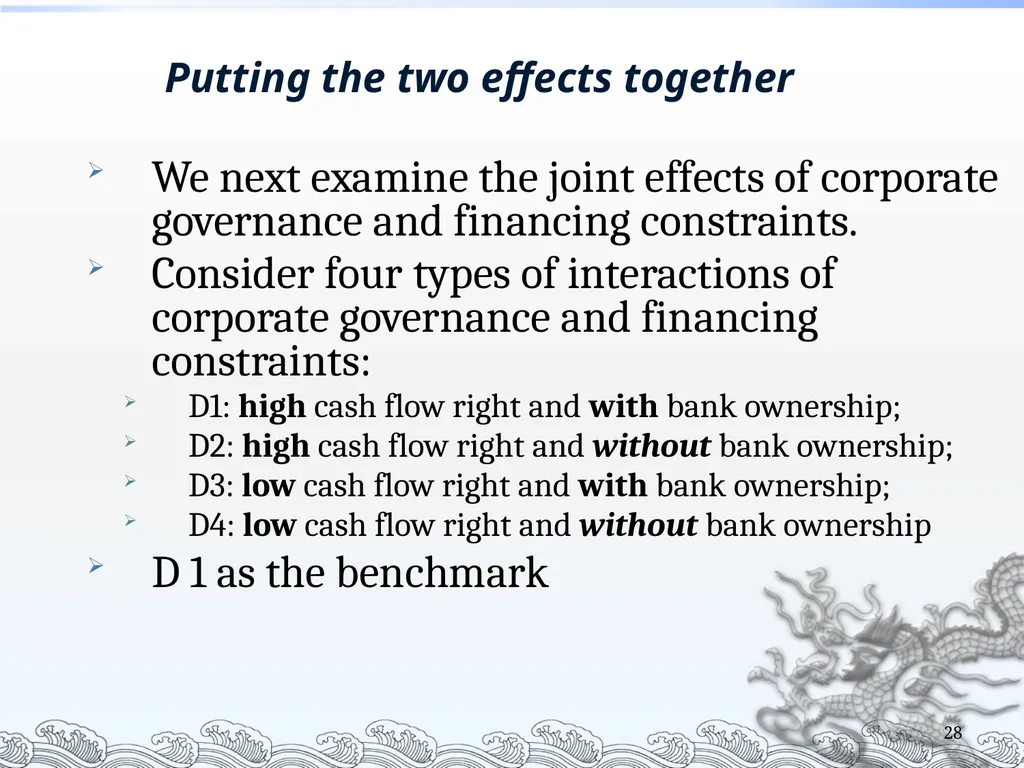
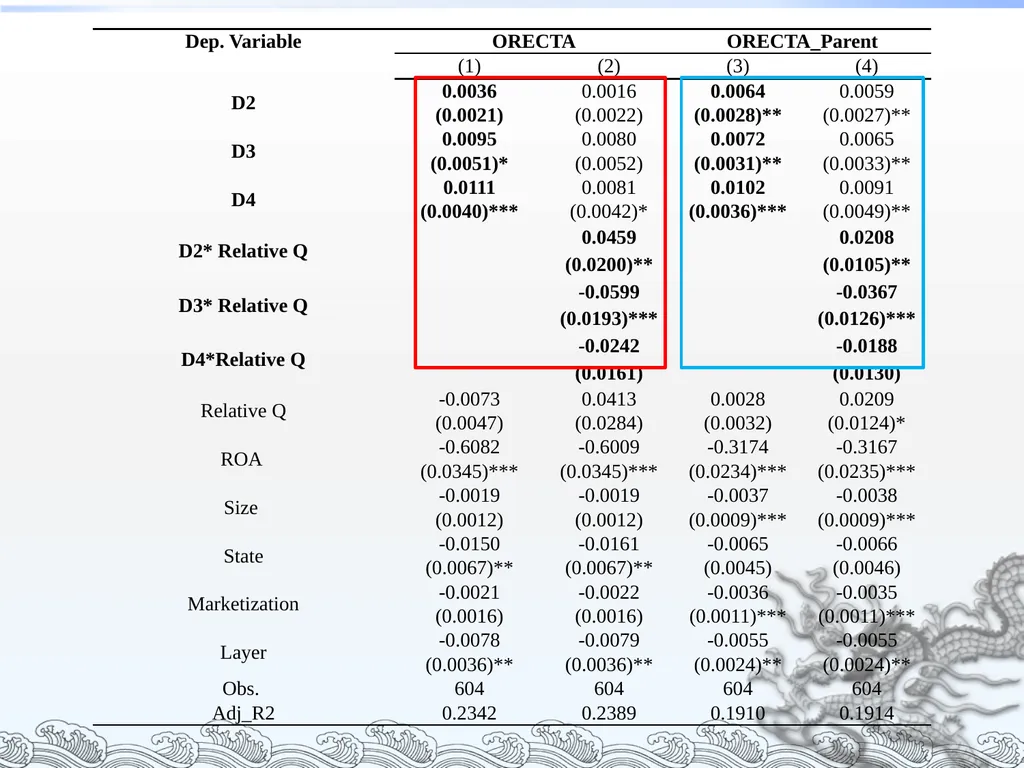
slide28. 28 Putting the two effects together We next examine the joint effects of corporate governance and financing constraints.
Consider four types of interactions of corporate governance and financing constraints:
D1: high cash flow right and with bank ownership;
D2: high cash flow right and without bank ownership;
D3: low cash flow right and with bank ownership;
D4: low cash flow right and without bank ownership
D 1 as the benchmark<br>
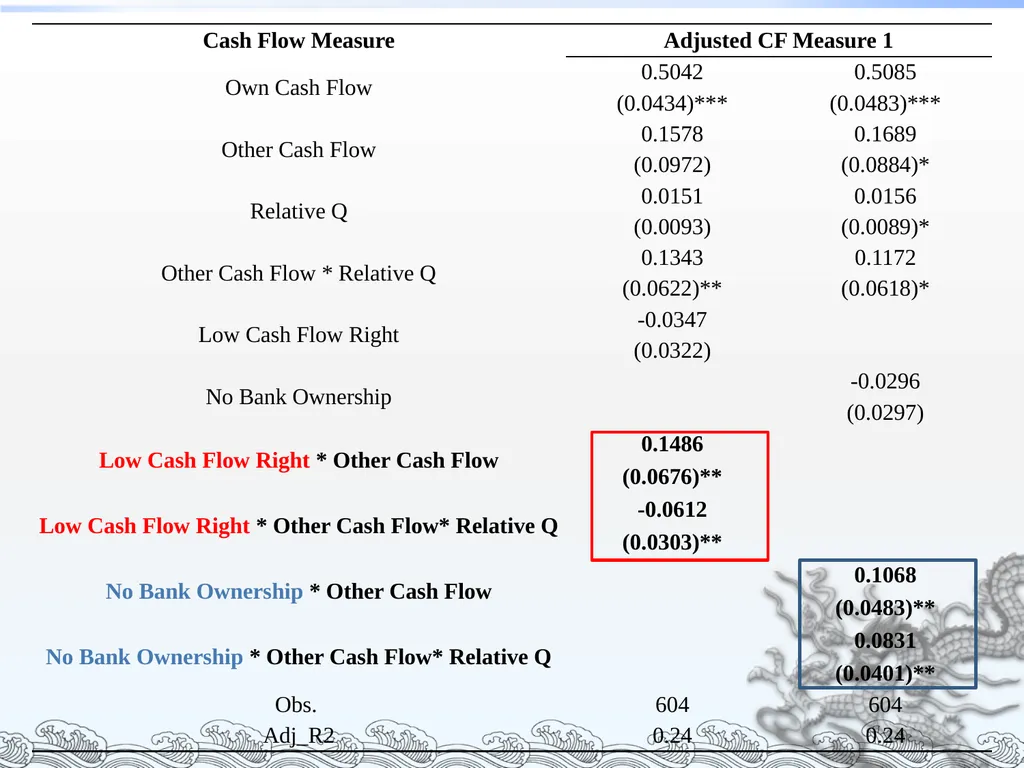
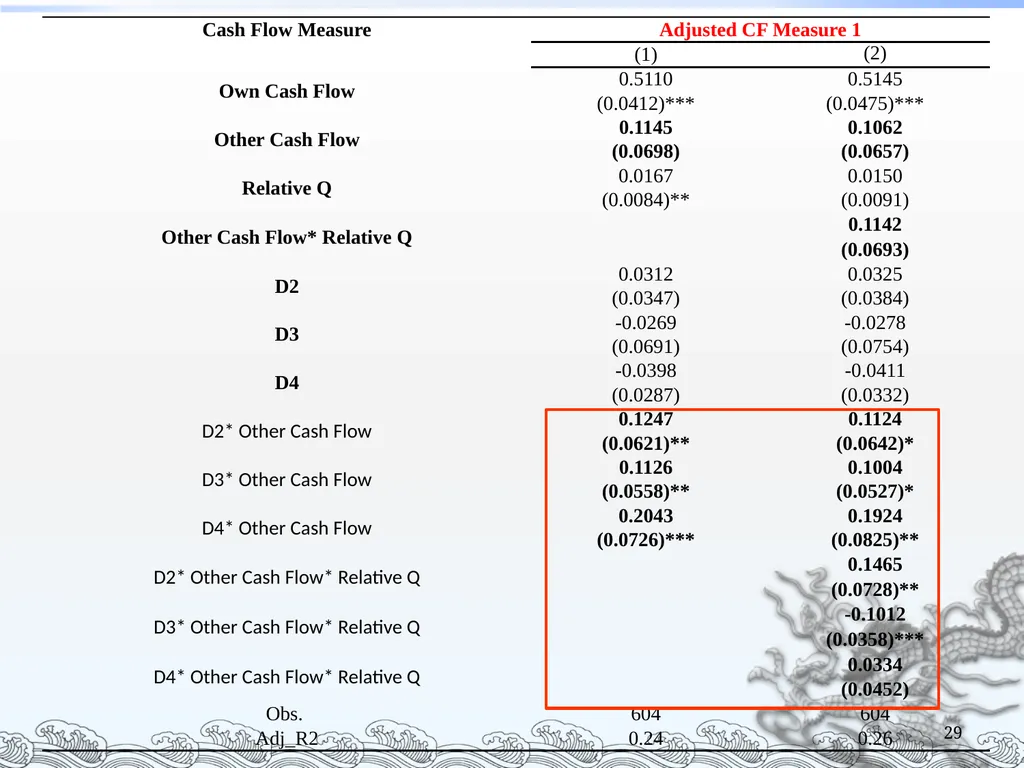
slide29. 29<br>
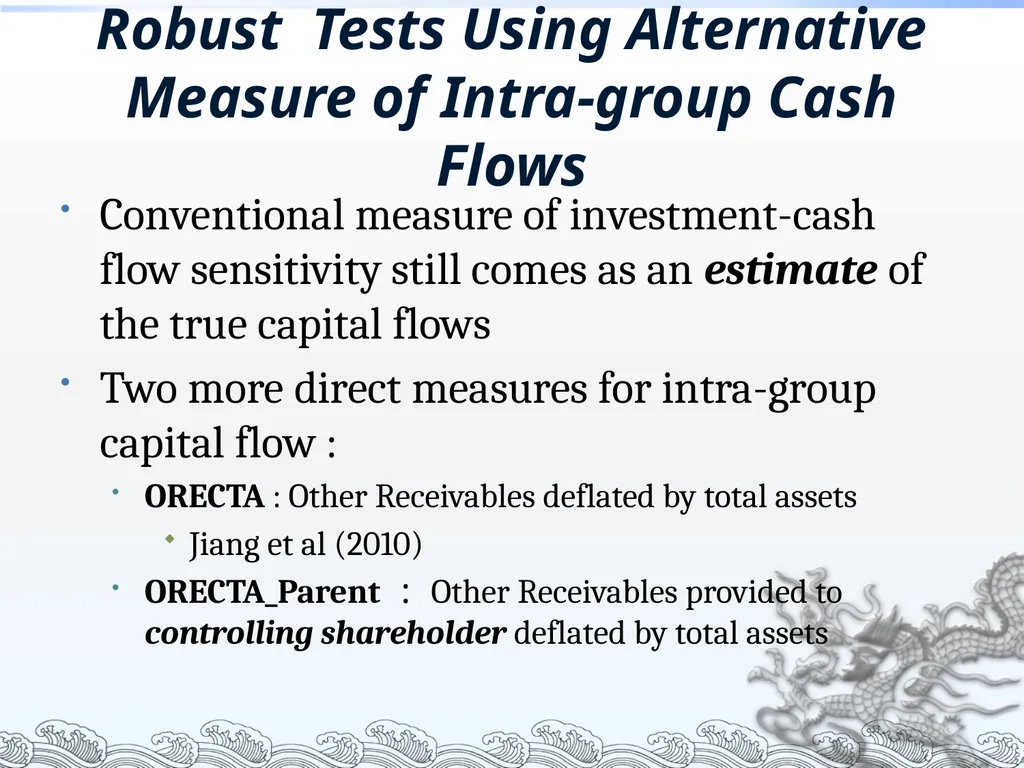
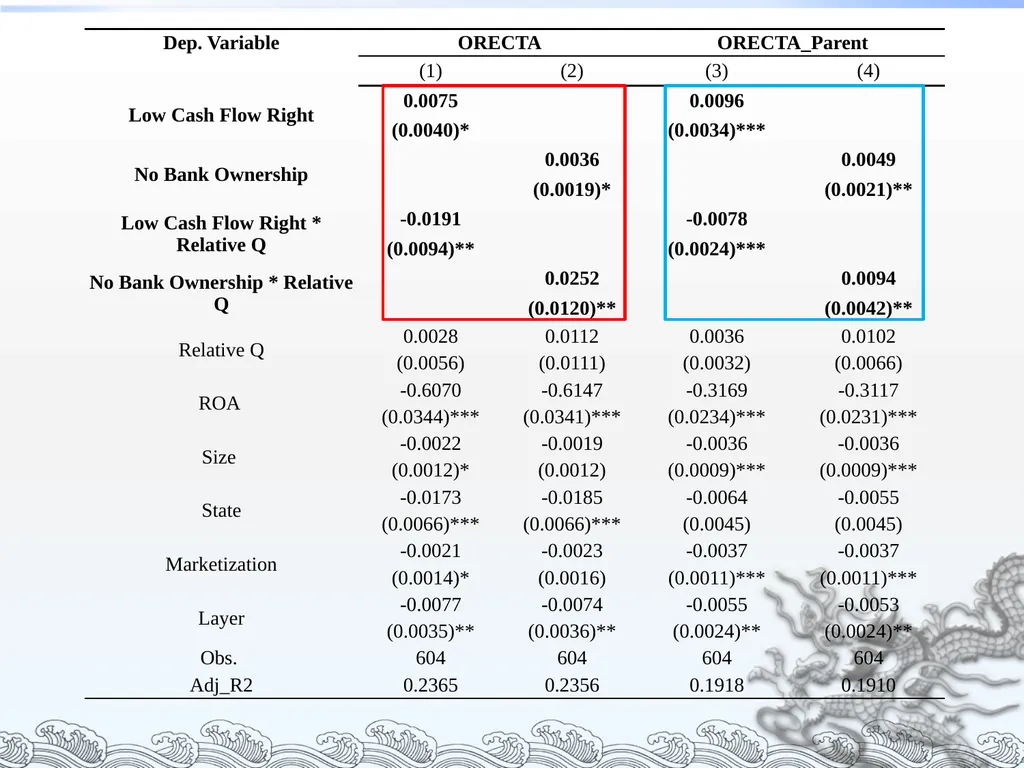
slide30. Robust Tests Using Alternative Measure of Intra-group Cash Flows Conventional measure of investment-cash flow sensitivity still comes as an estimate of the true capital flows
Two more direct measures for intra-group capital flow :
ORECTA : Other Receivables deflated by total assets
Jiang et al (2010)
ORECTA_Parent:Other Receivables provided to controlling shareholder deflated by total assets<br>
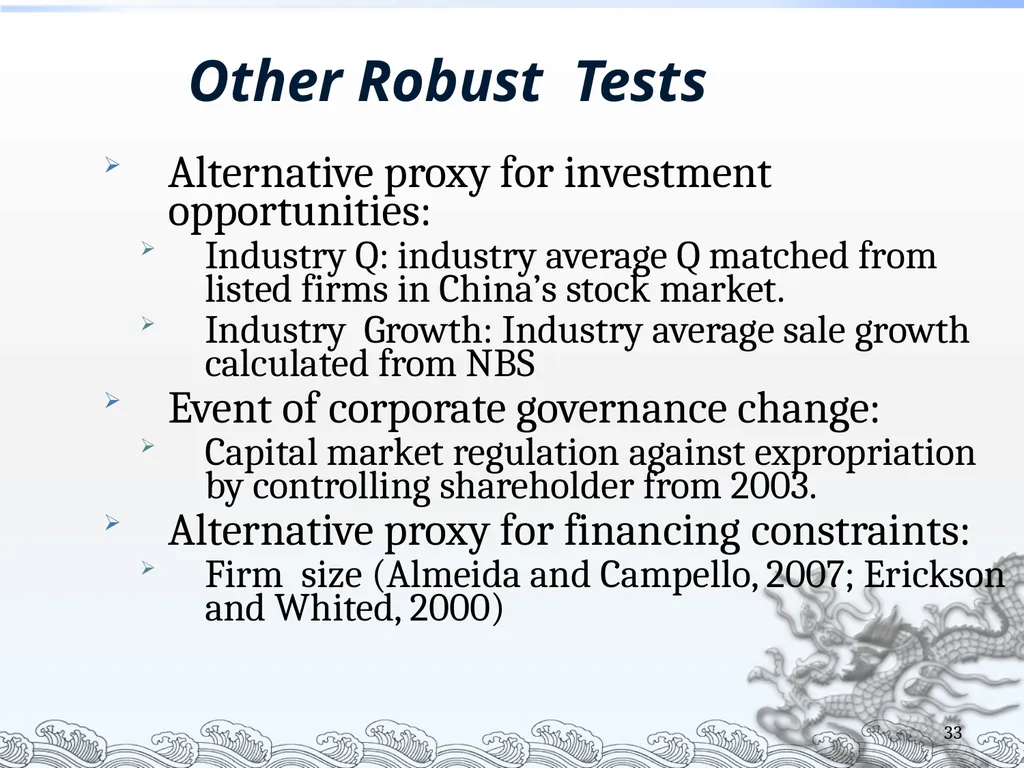
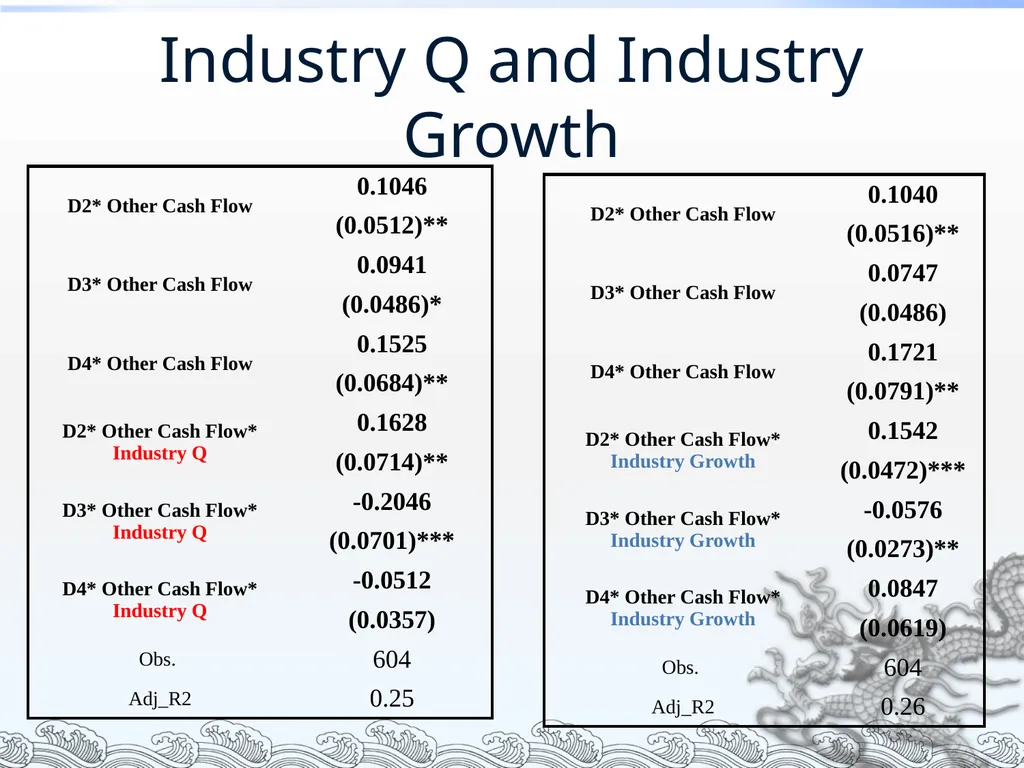
slide33. 33 Other Robust Tests Alternative proxy for investment opportunities:
Industry Q: industry average Q matched from listed firms in China’s stock market.
Industry Growth: Industry average sale growth calculated from NBS
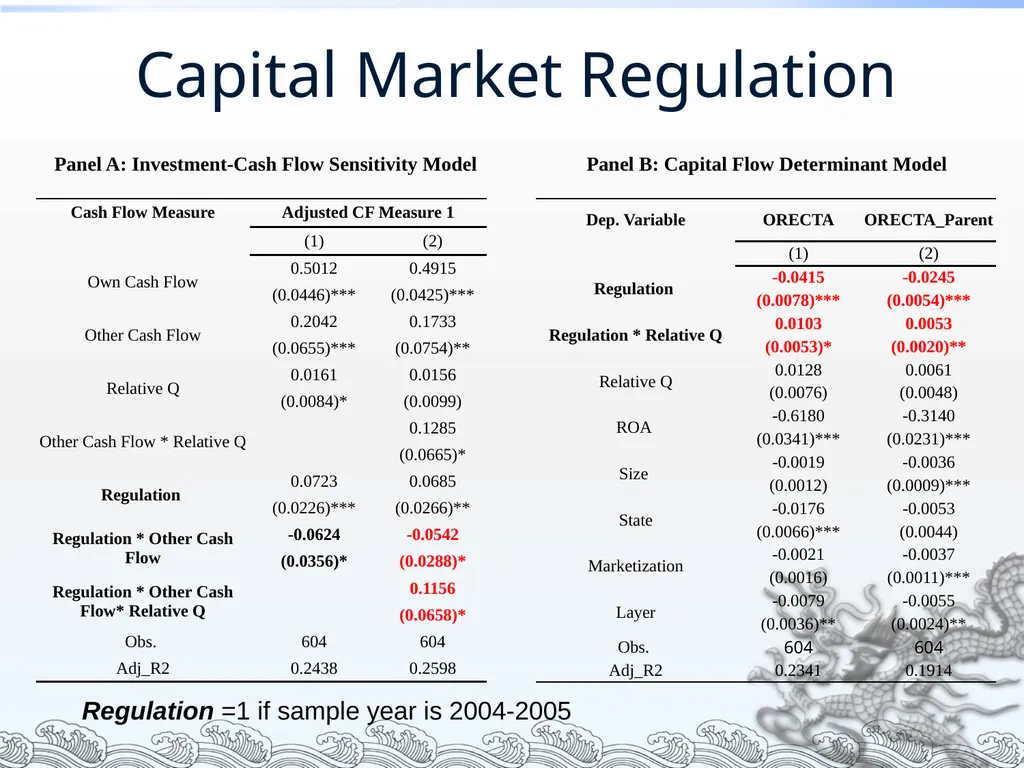
Event of corporate governance change:
Capital market regulation against expropriation by controlling shareholder from 2003.
Alternative proxy for financing constraints:
Firm size (Almeida and Campello, 2007; Erickson and Whited, 2000)<br>
slide34. Industry Q and Industry Growth<br>
slide35. Capital Market Regulation Regulation =1 if sample year is 2004-2005 Panel A: Investment-Cash Flow Sensitivity Model Panel B: Capital Flow Determinant Model<br>
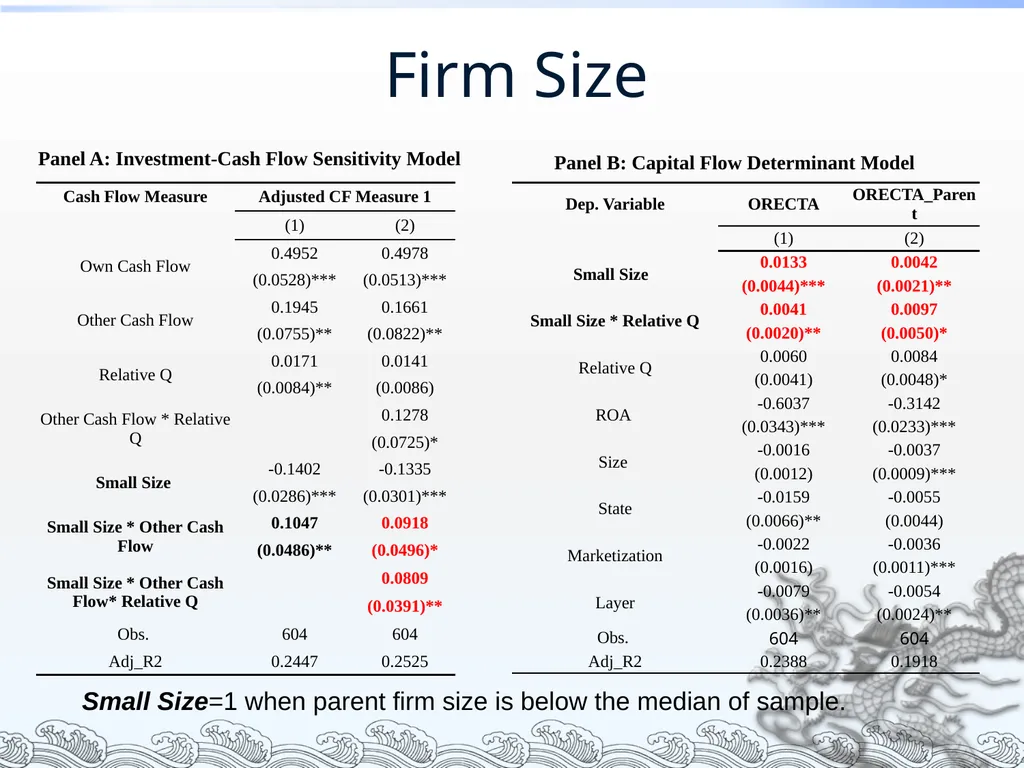
slide36. Firm Size Small Size=1 when parent firm size is below the median of sample. Panel A: Investment-Cash Flow Sensitivity Model Panel B: Capital Flow Determinant Model<br>
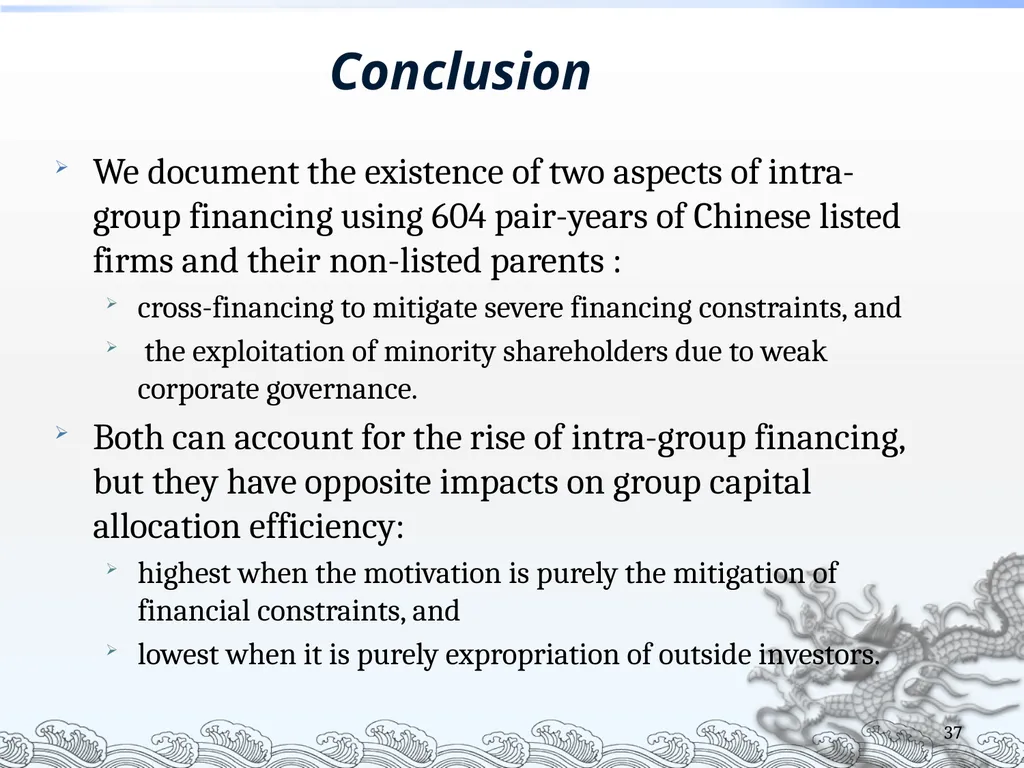
slide37. 37 Conclusion We document the existence of two aspects of intra-group financing using 604 pair-years of Chinese listed firms and their non-listed parents :
cross-financing to mitigate severe financing constraints, and
the exploitation of minority shareholders due to weak corporate governance.
Both can account for the rise of intra-group financing, but they have opposite impacts on group capital allocation efficiency:
highest when the motivation is purely the mitigation of financial constraints, and
lowest when it is purely expropriation of outside investors.<br>
slide38. Thank You!<br>
The Chinese University of Hong Kong
Li Jin
Oxford University & Peiking University
Guojian Zheng
Sun Yat-sen University<br>
slide2. Basic Business Group Structures Joseph P.H. Fan Organization and Value 2 Parent Co Parent Co V=50%
Y V=20%
Z V=C=10%
Z V=C=50%
Y V = 20%, weakest link in the chain,
C = 10%. Pyramid structure allows
leveraging up in control<br>
slide3. Ownership Joseph Fan 3 Fusun Group (Shanghai, China) 20% Iron&Steel 25%(2) Commerce Medicine 24.53% Estate 10% 10% 22% 5% 11.95%(2) 10% 58% 95% 13.53% 90.3% 20% 90% 1.94% 10% 49%(2) 15.04%(2) 26.04%(1) 70.95% 11.36% 8.81%% 43.33%
(2) 30% 3.77% 30% 67.12% 36.03%(1) 48%(2) 20% 21% Shanghai Guangxin Technology Development Co. Ltd. Shanghai Fusun High Technology (Group) Co. Ltd. NISC
(600282) FORTE
(HK2337) YYTM
(600655) 53.92% Nanjing Iron &Steel United Co.,Ltd. Shanghai Fusun Pharmaceutical Development Co. Ltd. Shanghai Fusun I.T. Development Co. Ltd. (Subsidiary) LRGF
(600285) Tianjin Pharmaceutical Holdings, Ltd. TJPC
(600488) China Medical Holding Co. ACCORD PHARM
(000028) Shanghai Friendship-Fusun (holding) Co. Ltd. SFGIC
(600827) Tangshan Jianlong Steel Co. Ltd. Lianhua Supermarket
(HK0980) Fusun Pharm
(600196) Zhaojin Mining Co. Ltd. JianMin Pharm
(600976) Shanghai Fusun High Technology Co. Ltd. Shanghai Fusun Business Investment Co. Ltd. Liang Xinjun GUO Guangchang Wang Qunbin Fan Wei<br>
slide4. Business Group Structure v.s. Conglomerate Structure Group-like organizations are commonplace in the world.
Comparing with the conglomerate organization
Similarity: complex internal resource flows
Difference: legal boundaries, top down control as oppose to horizontal control, complex ownership structure
Because divisions are legally separate entities in a business group, intra-group capital flow becomes an issue to outside minority owners<br>
slide5. Costs of the Group Structure Expropriation of minority shareholders by the controlling parent, e.g., tunneling(Johnson et al.,2000)
From the perspective of the whole group, such “tunneling” might not be a zero-sum game.
additional resources to cover up tunneling, potential legal penalties, ex ante distortion of incentives on investments
Investors not systematically fooled, the insider of the business group ultimately bears the welfare loss from tunneling.
Cost of the tunneling is reflected in lower security prices (Claessens et al., 2002; La Porta et al., 2002).<br>
slide6. Firms controlled by Pyramids are traded with a discount across all public traded East Asian Firms (Claessens, Djankov, Fan, Lang, Journal of Finance 2002; Based on 3000 East Asian Firms) Ownership Joseph Fan 6<br>
slide7. Motivation Given the costly group structure, what explains the persistent existence and prevalence of business groups?
For the whole group in under-developed financial markets: tunneling may be a constrained optimum even if not the first-best outcome , if it
alleviates severe financing constraints of member firms, and enables the undertaking of positive NPV projects
Many papers in the conglomerate literature (Stein, 1997…)
Business group literature: Morck, Wolfenzon, Yeung, 2005; Almeida and Wolfenzon, 2006, 2010; Khanna and Yafeh, 2007; Gopalan et al., 2007; Masulis et al., 2012<br>
slide8. Empirical Challenges Key challenge to empirical research demonstrating this tradeoff:
to disentangle the resources diverted to facilitate group efficiency from those diverted to satisfy the private benefits of the controlling shareholder
For minority shareholders: both are tunneling. But from the business group perspective, sacrificing a division may benefit the whole group
Parent firms typically not observable because of non-listed status
Measurement problem (Kaplan and Zingales, 1997, 2000)<br>
slide9. Our attempt In this paper, we make a modest attempt to bypass the above difficulties by
focusing on transfers of financial resources within business groups, and
testing the hypothesis that intra-group capital flow may be motivated by both group capital allocation efficiency and pure expropriation of minority shareholders.<br>
slide10. Business Group and Pyramidal Control Structure in China SAMB Parent Co. (Parent) Parent SOE (Parent) Listed Firm (Listed sub) Listed Firm (Listed sub) Private Owner<br>
slide11. Joseph P.H. Fan Organization and Value 11 Ningbo Group (China)<br>
slide12. A Model of Financial Tunneling Suppose an owner of a business group carves out a subsidiary and lists it, which results in
pair of a publicly listed sub (listed sub) and a non-listed parent company (parent).
Control is one-directional in the firm pair
The public listing allows the owner to raise external capital and create a class of minority shareholders in the listed subsidiary.<br>
slide13. Assumptions of the Model Financial transactions between the pair serve to
fund investment projects in parent or subsidiary
or be consumed by the controlling owner as private benefits.
Legal environment is unable to fully prevent such tunneling activities (Johnson et al., 2000) .
The parent company cannot effectively commit to refraining from tunneling because of
the opportunity losses from private benefits and investment opportunities, or
the costs of self-imposed corporate governance constraints.
The non-listed parent is much more financially constrained than the listed subsidiary.<br>
slide14. Predictions Cash flowing in the group is almost one-directional :
from the listed sub to the parent.
We should observe more intra-group cash flow activity (tunneling) if the parent and the listed sub are more severely misaligned in incentives, or if parent faces more financing constraints.<br>
slide15. Predictions on magnitude and efficiency of intra-group capital flow activity (tunneling) D1: High parent incentive alignment with sub, less severe fin constraint
D2: High parent incentive alignment with sub, severe fin constraint
D3: Low parent incentive alignment with sub, less severe fin constraint
D4: Low parent incentive alignment with sub, severe fin constraint
Magnitude of capital flow: D4 > D2 & D3 > D1
Efficiency of tunneled capital: D2 > D1 & D4 > D3<br>
slide16. Sample and Data 624 firm-year observations from 1999-2005 in China
Each obs. includes a pair of firms (Listed sub and Parent).
Financial information from both the listed subs and the non-listed parents
Parent sample comes originally from National Bureau of Statistics’ (NBS) Annual Industrial Survey Database .
Exclude :
“Shell” or holding companies
With missing data
Can’t be indentified in NBS
Less than 20% shares of the listed sub
Parent and the listed sub has the same 3-digit industry code
Negative cash flow 16<br>
slide17. Regression Model Measure of ICF activities: investment of group member firm A out of cash flow of member firm B, controlling for cash flow of firm A (Shin and Stulz ,QJE,1998).
Adding firm fixed effects and year dummies.
Run regression for both Listed sub and Parent, compare the results:
ICF exists when β2 is positive and significant.
For parent, financial tunneling is efficient when β4 is positive and significant. 17<br>
slide18. Relative investment opportunity Relative Q = difference in industry Tobin’s q between the parent and the sub
Use industry average q because parent is not listed and to mitigate measurement bias if firm level q is otherwise used<br>
slide19. Cash flow measures in the literature Cash flow=income after tax+ depreciation –dividend payments
Hoshi, Kashyap and Scharfstein (QJE,1991 )
Cash flow=earnings before extraordinary items+ depreciation
Kaplan and Zingales (QJE,1997)
Cash flow=earnings before interest and tax +depreciation + amortization (EBITDA)
Kaplan and Zingales (QJE,1997)
Cash flow=operating profit+ depreciation
Shin and Stulz (QJE,1998); Shin and Park(JCF,1999)<br>
slide20. Cash flow measures in our paper Traditional cash flow measure: EBIT + depreciation
Three adjusted cash flow measures
Adjusted Cash Flow Measure 1: (EBIT)+ depreciation - net change in trade credits
net change in trade credits =increase in accounts receivables - increase in payables
We do not have amortization data.
Rationale:
(EBIT+ depreciation) is the accounting profit.
Reasonable in conglomerates
(EBIT + depreciation - net change in trade credits ) is the amount of cash that is available for use by either own firm or the other firm.
A large fraction of EBIT take the form of trade credits.<br>
slide21. Cash flow measures in our paper Example:
Suppose a listed sub has a total EBIT of $100,of which $30 is the increase of trade credits, then available CF is $70.
Two possibilities of this $30 trade credits :
naturally arise due to normal transactions
only $70 available for tunneling, adjusted measures is appropriate
implicit loans from one firm to the other
$100 available for tunneling, traditional measures is appropriate 21<br>
slide22. Cash flow measures in our paper Which one more closely resembles the reality is an empirical question.
If adjusted CF measure underestimates tunneling relative to the traditional CF measure, investment should be less sensitive to the adjusted CF measure than to the traditional CF measure.
we found stronger sensitivity between investment of the parent and the adjusted CF of the listed sub, suggesting that
the adjusted CF measure does not underestimate tunneling.
Traditional CF measure may be noisy.
It appears that tunneling in China takes less obvious forms than through the extension of trade credit 22<br>
slide23. 23 Cash flow measures in our paper Adjusted Cash Flow Measure 2: EBIT + depreciation -net change in trade credits- income tax
Adjusted Cash Flow Measure 3: EBIT + depreciation -net change in trade credits - income tax + net increase of bank debts and equities.
For adjusted cash flow measure1, we have data from both Parent and Listed sub
For adjusted cash flow measure 2 and 3, we only have data from Listed sub.<br>
slide24. Summary Statistics 24<br>
slide25. 25<br>
slide26. 26 Impact of corporate governance and financing constraint on ICF Ownership is fundamental to – and cash flow rights theoretically at the core of – corporate governance.
Empirically strongly related to the incentives of large shareholders to tunnel the listed firms that they control (Bertrand et. al, 2002; Claessens et.al, 2002). Especially when legal protection for outside investors is weak (La Porta,et.al, 1997, 1998, 1999)
Bank ownership has been argued to be important to firms for raising external finance(e.g, Hoshi, et.al,1991)
Bank ownership in this paper: A dummy variable whether listed sub(under Parent’s control ) owns shares of local financial banks.<br>
slide28. 28 Putting the two effects together We next examine the joint effects of corporate governance and financing constraints.
Consider four types of interactions of corporate governance and financing constraints:
D1: high cash flow right and with bank ownership;
D2: high cash flow right and without bank ownership;
D3: low cash flow right and with bank ownership;
D4: low cash flow right and without bank ownership
D 1 as the benchmark<br>
slide29. 29<br>
slide30. Robust Tests Using Alternative Measure of Intra-group Cash Flows Conventional measure of investment-cash flow sensitivity still comes as an estimate of the true capital flows
Two more direct measures for intra-group capital flow :
ORECTA : Other Receivables deflated by total assets
Jiang et al (2010)
ORECTA_Parent:Other Receivables provided to controlling shareholder deflated by total assets<br>
slide33. 33 Other Robust Tests Alternative proxy for investment opportunities:
Industry Q: industry average Q matched from listed firms in China’s stock market.
Industry Growth: Industry average sale growth calculated from NBS
Event of corporate governance change:
Capital market regulation against expropriation by controlling shareholder from 2003.
Alternative proxy for financing constraints:
Firm size (Almeida and Campello, 2007; Erickson and Whited, 2000)<br>
slide34. Industry Q and Industry Growth<br>
slide35. Capital Market Regulation Regulation =1 if sample year is 2004-2005 Panel A: Investment-Cash Flow Sensitivity Model Panel B: Capital Flow Determinant Model<br>
slide36. Firm Size Small Size=1 when parent firm size is below the median of sample. Panel A: Investment-Cash Flow Sensitivity Model Panel B: Capital Flow Determinant Model<br>
slide37. 37 Conclusion We document the existence of two aspects of intra-group financing using 604 pair-years of Chinese listed firms and their non-listed parents :
cross-financing to mitigate severe financing constraints, and
the exploitation of minority shareholders due to weak corporate governance.
Both can account for the rise of intra-group financing, but they have opposite impacts on group capital allocation efficiency:
highest when the motivation is purely the mitigation of financial constraints, and
lowest when it is purely expropriation of outside investors.<br>
slide38. Thank You!<br>