
SEMINAR ON ACCOUNTING STANDARD Challenges in

Description: SEMINAR ON ACCOUNTING STANDARD Challenges in Auditing Accounting Estimates Sunit Kumar Basu 14 June, 2023 What is an Accounting Estimate Approximation of amount of a business transaction Used where there is no precise means of measurement
Related Topics
Download Presentation
"SEMINAR ON ACCOUNTING STANDARD Challenges in" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. SEMINAR ON ACCOUNTING STANDARD Challenges in Auditing Accounting Estimates Sunit Kumar Basu 14 June, 2023<br>
slide2. What is an Accounting Estimate Approximation of amount of a business transaction
Used where there is no precise means of measurement
Usually anticipates probable future events yet to occur
Makes Financial Statements complete in accrual accounting
May be revised subsequently based on available information
Changes in estimates impact current and future periods.
No impact on prior periods
Involves making assumptions and use of judgements 14 June, 2023 Sunit Kumar Basu<br>
slide3. Challenges in making an Accounting Estimate Estimates ranges from simple to complex
Lacks precision
Often involves forecasting the future
Actual outcomes are likely to be different
Leads to estimation uncertainty 14 June, 2023 Sunit Kumar Basu<br>
slide4. Challenges in making an Accounting Estimate Significant estimation uncertainty may lead to misstatements
Lack of prescriptive guidelines
Includes fair valuation
Measurement impacted by Financial Reporting Framework
Fair Valuation of Government Resources 14 June, 2023 Sunit Kumar Basu<br>
slide5. Accounting for Construction Contracts Estimation of Revenue
Estimation of cost to complete and recognition of margin
Estimation of percentage of completion
Claim estimation
Estimation of expected losses on onerous contracts
Estimation differences adjusted in cost and revenue 14 June, 2023 Sunit Kumar Basu<br>
slide6. Other major areas of Accounting Estimations Impairment of Assets (Including DTA and going concern where applicable)
Biological Assets
Defined Benefit Plans
Fair Valuation of assets in Business Combinations
Fair Valuation of Financial Instruments 14 June, 2023 Sunit Kumar Basu<br>
slide7. Challenges in Auditing an Accounting Estimate May involve management bias
Availability and quality of underlying data
Management not sharing all the information
Often involves determining the fair value
Risk of material misstatements
Risk of Fraud 14 June, 2023 Sunit Kumar Basu<br>
slide8. Indicators of Possible Management Bias Management Bias may not themselves constitute misstatements
May be intentional or unintentional
Susceptibility increases with subjectivity 14 June, 2023 Sunit Kumar Basu<br>
slide9. Complex Accounting Estimates Outcome of litigations
Prediction of future
Fair valuation of derivative financial instruments
Specialised entity developed models
Absence of published price quotations
Considering qualitative factors such as control
Acquisition or swap transactions 14 June, 2023 Sunit Kumar Basu<br>
slide10. Need for Reestimates New transactions/ Events
Change in terms of transactions
Change in Accounting Policy
Regulatory Changes 14 June, 2023 Sunit Kumar Basu<br>
slide11. Reasonability of Assumptions Significant Assumptions
Relevance and Completeness
Internal Consistency
Whether Assumptions under management control – maintenance
Nature and extent of documentation supporting Assumption
Fair Value
Income vs. Market Approach 14 June, 2023 Sunit Kumar Basu<br>
slide12. What Auditor needs to do Evaluate Risk Assessment Procedure and related activities
Management assessment of estimation uncertainty
Whether high estimation uncertainty leads to significant risks
Relevant Controls
Test operating effectiveness of controls
Whether Management used an expert
Change from prior period in making the estimate
Management decision to recognise/ not recognise estimates 14 June, 2023 Sunit Kumar Basu<br>
slide13. What Auditor needs to do Compliance with applicable financial reporting framework
Appropriateness of valuation method – market vs. income approach
Assumptions used are reasonable
Test underlying data for accuracy, completeness and relevance
Use of alternate assumption and sensitivity analysis
Need to review prior period accounting estimates
Need to use an Auditor’s Expert
Point estimate vs. range of estimates to address uncertainty
Additional procedure like physical inspection 14 June, 2023 Sunit Kumar Basu<br>
slide14. What Auditor needs to do Assess risk of material misstatement
Materiality of accounting estimate needs to be qualitatively assessed
Evaluate adequacy of disclosure
Assess Going Concern where needed
Obtain Representation
May require “KAM” or “EOM” in audit report 14 June, 2023 Sunit Kumar Basu<br>
slide15. KAM - Zomato Ltd – March 22 (Deloitte) Fair valuation of investment in other entities (Refer note 38 (b) of the Consolidated financial statement) The Group has made investments in Blink Commerce Private Limited (formerly known as Grofers India Private Limited) and its fellow subsidiary Hands on Trades Private Limited where the aggregate carrying value of these investments as on March 31, 2022 is INR 7,410 million. These investments are measured at Fair Value through Other Comprehensive Income (‘FVTOCI’) as at the year-end. We considered the assumptions relating to future revenue growth and the valuation assumptions, specifically the assumptions relating to weighted average cost of capital and terminal growth rate, used in the fair valuation of these investments as a key audit matter due to the significance of the investment amount and the significant estimates and judgement involved in estimation of fair value Sunit Kumar Basu<br>
slide16. Audit Procedures Performed(Deloitte) Principal audit procedures performed: • Evaluated the design, implementation and tested operating effectiveness of relevant internal controls relating to determination of the fair value of investment in the said entities. • Evaluated the reasonableness of the business assumptions relating to future revenue growth; • Evaluated the objectivity and independence of the specialist engaged by the Company and reviewed the valuation report issued by such specialist; • We have used our valuation specialists to assess overall reasonableness of the assumptions used particularly those relating to the weighted average cost of capital and terminal growth rate. • Performed sensitivity analysis on the key assumptions such as weighted average cost of capital and terminal growth rate; • Assessed the adequacy of the disclosures made in the financial statements<br>
slide17. HCC LTD KAM Mar22 – Walker Chandiok & Co The Company’s revenue primarily arises from construction contracts which, by its nature, is complex given the significant judgements involved in the assessment of current and future contractual performance obligations. The Company recognizes contract revenue and the resultant profit/ loss on the basis of stage of completion determined based on the proportion of contract costs incurred at balance sheet date, relative to the total estimated costs of the contract at completion. The recognition of contract revenue and the resultant profit/ loss therefore rely on estimates in relation to forecast revenue and forecast contract costs.<br>
slide18. HCC LTD KAM Mar22 – Walker Chandiok & Co These contract estimates are reviewed by the management on a periodic basis. In doing so, the management is required to exercise judgement in its assessment of the revenue on contracts which may also include variable considerations that are recognised when the recovery of such consideration is highly probable. The judgment is also required to be exercised to assess the completeness and accuracy of forecast costs to complete. Changes in these judgements, and the related estimates as contracts progress can result in material adjustments to revenue and margins. As a result of the above judgments, complexities involved and material impact on the related financial statement elements, this area has been considered a key audit matter in the audit of the standalone financial statements<br>
slide19. Audit Procedures Performed – HCC Ltd Our audit procedures to address this key audit matter included, but were not limited to the following: • Evaluated the appropriateness of the Company’s accounting policy for revenue recognition in accordance with Ind AS 115 – Revenue from contracts with customers;
• Obtained an understanding of the Company’s processes and evaluated the design and tested the operating effectiveness of key internal financial controls with respect to estimation of forecasted contract revenue and contracts costs<br>
slide20. Audit Procedures Performed – HCC Ltd For a sample of contracts, performed the following procedures: - inspected the underlying documents such as customer contract/ agreement and variation orders, if any, for the significant contract terms and conditions; - evaluated the identification of performance obligations of the contract; - obtained an understanding of and evaluated the reasonableness of the assumptions applied in determining the forecasted revenue and cost to complete; - tested the existence and valuation of variable consideration with respect to the contractual terms and conditions and inspected the correspondence with customers; and - reviewed the legal and contracting experts’ note and/ or legal opinion from independent legal counsel obtained by the management with respect to certain contentious matters<br>
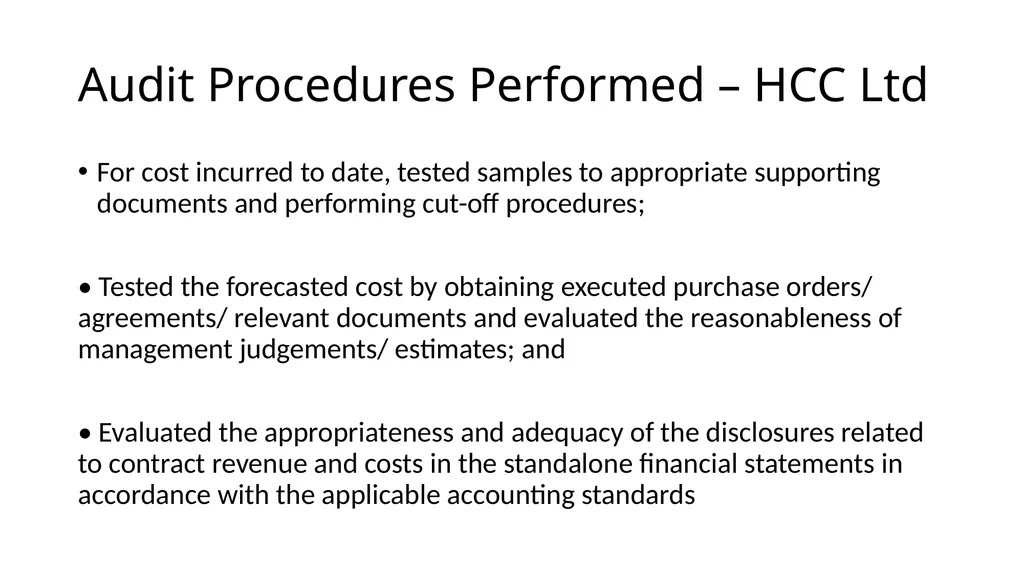
slide21. Audit Procedures Performed – HCC Ltd For cost incurred to date, tested samples to appropriate supporting documents and performing cut-off procedures;
• Tested the forecasted cost by obtaining executed purchase orders/ agreements/ relevant documents and evaluated the reasonableness of management judgements/ estimates; and
• Evaluated the appropriateness and adequacy of the disclosures related to contract revenue and costs in the standalone financial statements in accordance with the applicable accounting standards<br>
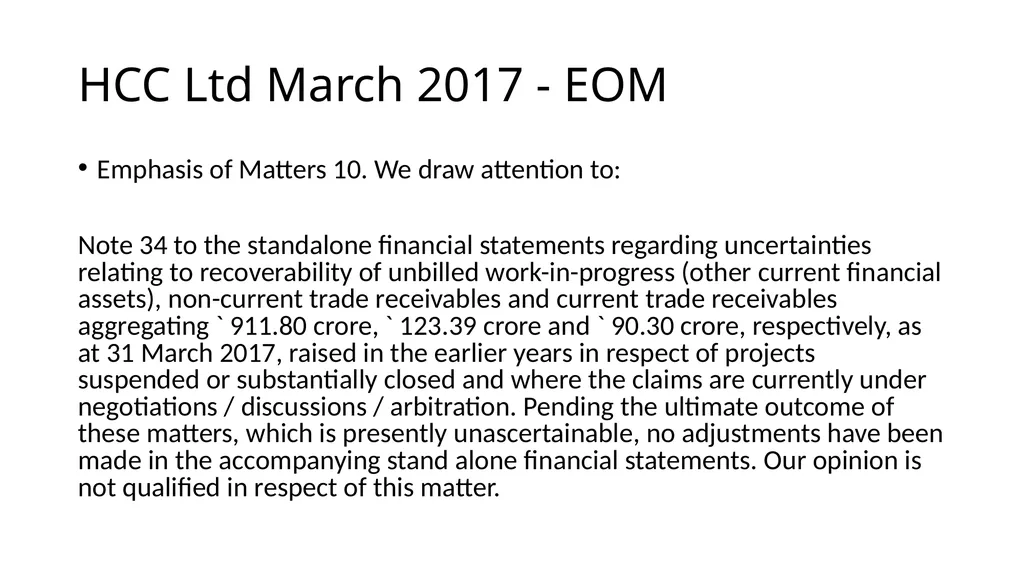
slide22. HCC Ltd March 2017 - EOM Emphasis of Matters 10. We draw attention to:
Note 34 to the standalone financial statements regarding uncertainties relating to recoverability of unbilled work-in-progress (other current financial assets), non-current trade receivables and current trade receivables aggregating ` 911.80 crore, ` 123.39 crore and ` 90.30 crore, respectively, as at 31 March 2017, raised in the earlier years in respect of projects suspended or substantially closed and where the claims are currently under negotiations / discussions / arbitration. Pending the ultimate outcome of these matters, which is presently unascertainable, no adjustments have been made in the accompanying stand alone financial statements. Our opinion is not qualified in respect of this matter.<br>
slide2. What is an Accounting Estimate Approximation of amount of a business transaction
Used where there is no precise means of measurement
Usually anticipates probable future events yet to occur
Makes Financial Statements complete in accrual accounting
May be revised subsequently based on available information
Changes in estimates impact current and future periods.
No impact on prior periods
Involves making assumptions and use of judgements 14 June, 2023 Sunit Kumar Basu<br>
slide3. Challenges in making an Accounting Estimate Estimates ranges from simple to complex
Lacks precision
Often involves forecasting the future
Actual outcomes are likely to be different
Leads to estimation uncertainty 14 June, 2023 Sunit Kumar Basu<br>
slide4. Challenges in making an Accounting Estimate Significant estimation uncertainty may lead to misstatements
Lack of prescriptive guidelines
Includes fair valuation
Measurement impacted by Financial Reporting Framework
Fair Valuation of Government Resources 14 June, 2023 Sunit Kumar Basu<br>
slide5. Accounting for Construction Contracts Estimation of Revenue
Estimation of cost to complete and recognition of margin
Estimation of percentage of completion
Claim estimation
Estimation of expected losses on onerous contracts
Estimation differences adjusted in cost and revenue 14 June, 2023 Sunit Kumar Basu<br>
slide6. Other major areas of Accounting Estimations Impairment of Assets (Including DTA and going concern where applicable)
Biological Assets
Defined Benefit Plans
Fair Valuation of assets in Business Combinations
Fair Valuation of Financial Instruments 14 June, 2023 Sunit Kumar Basu<br>
slide7. Challenges in Auditing an Accounting Estimate May involve management bias
Availability and quality of underlying data
Management not sharing all the information
Often involves determining the fair value
Risk of material misstatements
Risk of Fraud 14 June, 2023 Sunit Kumar Basu<br>
slide8. Indicators of Possible Management Bias Management Bias may not themselves constitute misstatements
May be intentional or unintentional
Susceptibility increases with subjectivity 14 June, 2023 Sunit Kumar Basu<br>
slide9. Complex Accounting Estimates Outcome of litigations
Prediction of future
Fair valuation of derivative financial instruments
Specialised entity developed models
Absence of published price quotations
Considering qualitative factors such as control
Acquisition or swap transactions 14 June, 2023 Sunit Kumar Basu<br>
slide10. Need for Reestimates New transactions/ Events
Change in terms of transactions
Change in Accounting Policy
Regulatory Changes 14 June, 2023 Sunit Kumar Basu<br>
slide11. Reasonability of Assumptions Significant Assumptions
Relevance and Completeness
Internal Consistency
Whether Assumptions under management control – maintenance
Nature and extent of documentation supporting Assumption
Fair Value
Income vs. Market Approach 14 June, 2023 Sunit Kumar Basu<br>
slide12. What Auditor needs to do Evaluate Risk Assessment Procedure and related activities
Management assessment of estimation uncertainty
Whether high estimation uncertainty leads to significant risks
Relevant Controls
Test operating effectiveness of controls
Whether Management used an expert
Change from prior period in making the estimate
Management decision to recognise/ not recognise estimates 14 June, 2023 Sunit Kumar Basu<br>
slide13. What Auditor needs to do Compliance with applicable financial reporting framework
Appropriateness of valuation method – market vs. income approach
Assumptions used are reasonable
Test underlying data for accuracy, completeness and relevance
Use of alternate assumption and sensitivity analysis
Need to review prior period accounting estimates
Need to use an Auditor’s Expert
Point estimate vs. range of estimates to address uncertainty
Additional procedure like physical inspection 14 June, 2023 Sunit Kumar Basu<br>
slide14. What Auditor needs to do Assess risk of material misstatement
Materiality of accounting estimate needs to be qualitatively assessed
Evaluate adequacy of disclosure
Assess Going Concern where needed
Obtain Representation
May require “KAM” or “EOM” in audit report 14 June, 2023 Sunit Kumar Basu<br>
slide15. KAM - Zomato Ltd – March 22 (Deloitte) Fair valuation of investment in other entities (Refer note 38 (b) of the Consolidated financial statement) The Group has made investments in Blink Commerce Private Limited (formerly known as Grofers India Private Limited) and its fellow subsidiary Hands on Trades Private Limited where the aggregate carrying value of these investments as on March 31, 2022 is INR 7,410 million. These investments are measured at Fair Value through Other Comprehensive Income (‘FVTOCI’) as at the year-end. We considered the assumptions relating to future revenue growth and the valuation assumptions, specifically the assumptions relating to weighted average cost of capital and terminal growth rate, used in the fair valuation of these investments as a key audit matter due to the significance of the investment amount and the significant estimates and judgement involved in estimation of fair value Sunit Kumar Basu<br>
slide16. Audit Procedures Performed(Deloitte) Principal audit procedures performed: • Evaluated the design, implementation and tested operating effectiveness of relevant internal controls relating to determination of the fair value of investment in the said entities. • Evaluated the reasonableness of the business assumptions relating to future revenue growth; • Evaluated the objectivity and independence of the specialist engaged by the Company and reviewed the valuation report issued by such specialist; • We have used our valuation specialists to assess overall reasonableness of the assumptions used particularly those relating to the weighted average cost of capital and terminal growth rate. • Performed sensitivity analysis on the key assumptions such as weighted average cost of capital and terminal growth rate; • Assessed the adequacy of the disclosures made in the financial statements<br>
slide17. HCC LTD KAM Mar22 – Walker Chandiok & Co The Company’s revenue primarily arises from construction contracts which, by its nature, is complex given the significant judgements involved in the assessment of current and future contractual performance obligations. The Company recognizes contract revenue and the resultant profit/ loss on the basis of stage of completion determined based on the proportion of contract costs incurred at balance sheet date, relative to the total estimated costs of the contract at completion. The recognition of contract revenue and the resultant profit/ loss therefore rely on estimates in relation to forecast revenue and forecast contract costs.<br>
slide18. HCC LTD KAM Mar22 – Walker Chandiok & Co These contract estimates are reviewed by the management on a periodic basis. In doing so, the management is required to exercise judgement in its assessment of the revenue on contracts which may also include variable considerations that are recognised when the recovery of such consideration is highly probable. The judgment is also required to be exercised to assess the completeness and accuracy of forecast costs to complete. Changes in these judgements, and the related estimates as contracts progress can result in material adjustments to revenue and margins. As a result of the above judgments, complexities involved and material impact on the related financial statement elements, this area has been considered a key audit matter in the audit of the standalone financial statements<br>
slide19. Audit Procedures Performed – HCC Ltd Our audit procedures to address this key audit matter included, but were not limited to the following: • Evaluated the appropriateness of the Company’s accounting policy for revenue recognition in accordance with Ind AS 115 – Revenue from contracts with customers;
• Obtained an understanding of the Company’s processes and evaluated the design and tested the operating effectiveness of key internal financial controls with respect to estimation of forecasted contract revenue and contracts costs<br>
slide20. Audit Procedures Performed – HCC Ltd For a sample of contracts, performed the following procedures: - inspected the underlying documents such as customer contract/ agreement and variation orders, if any, for the significant contract terms and conditions; - evaluated the identification of performance obligations of the contract; - obtained an understanding of and evaluated the reasonableness of the assumptions applied in determining the forecasted revenue and cost to complete; - tested the existence and valuation of variable consideration with respect to the contractual terms and conditions and inspected the correspondence with customers; and - reviewed the legal and contracting experts’ note and/ or legal opinion from independent legal counsel obtained by the management with respect to certain contentious matters<br>
slide21. Audit Procedures Performed – HCC Ltd For cost incurred to date, tested samples to appropriate supporting documents and performing cut-off procedures;
• Tested the forecasted cost by obtaining executed purchase orders/ agreements/ relevant documents and evaluated the reasonableness of management judgements/ estimates; and
• Evaluated the appropriateness and adequacy of the disclosures related to contract revenue and costs in the standalone financial statements in accordance with the applicable accounting standards<br>
slide22. HCC Ltd March 2017 - EOM Emphasis of Matters 10. We draw attention to:
Note 34 to the standalone financial statements regarding uncertainties relating to recoverability of unbilled work-in-progress (other current financial assets), non-current trade receivables and current trade receivables aggregating ` 911.80 crore, ` 123.39 crore and ` 90.30 crore, respectively, as at 31 March 2017, raised in the earlier years in respect of projects suspended or substantially closed and where the claims are currently under negotiations / discussions / arbitration. Pending the ultimate outcome of these matters, which is presently unascertainable, no adjustments have been made in the accompanying stand alone financial statements. Our opinion is not qualified in respect of this matter.<br>