
THE CHALLENGES AND OPPORTUNITIES FOR GROWTH OF









Description: THE CHALLENGES AND OPPORTUNITIES FOR GROWTH OF CHINESE BUSINESSES IN GHANA 12TH AUGUST 2015 Speaker GHANA TAX TRENDS Abdallah Ali-Nakyea (Director) 12.08.2015 2 Placeholder for photo Abdallah Ali-Nakyea FCIT, FICB, FCCE, CEPA, MIIA, MTP
Related Topics
Download Presentation
"THE CHALLENGES AND OPPORTUNITIES FOR GROWTH OF" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. THE CHALLENGES AND OPPORTUNITIES FOR GROWTH OF CHINESE BUSINESSES IN GHANA 12TH AUGUST 2015<br>
slide2. Speaker GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 2 Placeholder for photo Abdallah Ali-Nakyea
FCIT, FICB, FCCE, CEPA, MIIA, MTP (SA), Professional Accountant (SA), CA (Gh), LLB (Hons), BL, MPhil (Econs)
(Managing Consultant) WTS Ghana (Tax Legal Consulting)
P.O. Box KD 66 Kanda-Accra, Ghana Tel +233 (244) 23 5144
+233 (302) 23 6334 Fax +233 (302) 23 6334 E-mail: abdallah.alinakyea@wts.com.gh
Website: www.wts.com.gh<br>
slide3. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 3 In Ghana, the source jurisdiction is applied and this means that income is taxable in Ghana as long as its source is from Ghana. Thus where the source of an income is not from Ghana, it is not taxable in Ghana.
It is to be noted that where the source of an income is not from Ghana, then the income has to be brought in or received in Ghana to make it subject to tax in Ghana.
This position is clearly outlined in section 6 of the Internal Revenue Act, 2000 (Act 592). TAXABLE INCOME<br>
slide4. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 4 In the case of a resident person, the full amount of the person’s income from the business, employment, or investment accruing in, derived from, brought into, or received in Ghana during any basis period of that person ending within the year of assessment;
In the case of a non-resident person, the full amount of the person’s income from the business, employment, or investment accruing in or derived from Ghana during any basis period of the person ending within the year of assessment. ASSESSABLE INCOME The assessable income of a person for a year of assessment from any business, employment, or investment is:<br>
slide5. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 5 A citizen of Ghana who has no permanent home outside Ghana for a whole year of assessment.
Present in Ghana for a period/total of 183 days or more in a year of assessment.
An employee or official of the government of Ghana posted abroad during the year.
A citizen of Ghana who is temporary absent from Ghana for less than 365 continuous days and has a permanent home in Ghana. MEANING OF KEY TAX TERMINOLOGIES Resident Individual: An individual is resident for tax purposes if that individual is:<br>
slide6. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 6 Incorporated under the laws of Ghana, or
Managed and controlled in Ghana at any time in the year of assessment. In other words, if the board of directors meet and take decisions in Ghana then the company is deemed to be resident in Ghana. MEANING OF KEY TAX TERMINOLOGIES Resident Company: A company is resident for tax purposes for a year of assessment if that company is:<br>
slide7. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 7 Is established in Ghana
Has a resident person as a manager at any time during the year of assessment, or
Is controlled directly or indirectly by a resident person or persons at any time during the year of assessment MEANING OF KEY TAX TERMINOLOGIES Resident Body of Persons: A body of persons is a resident body of persons for any year of assessment if it:<br>
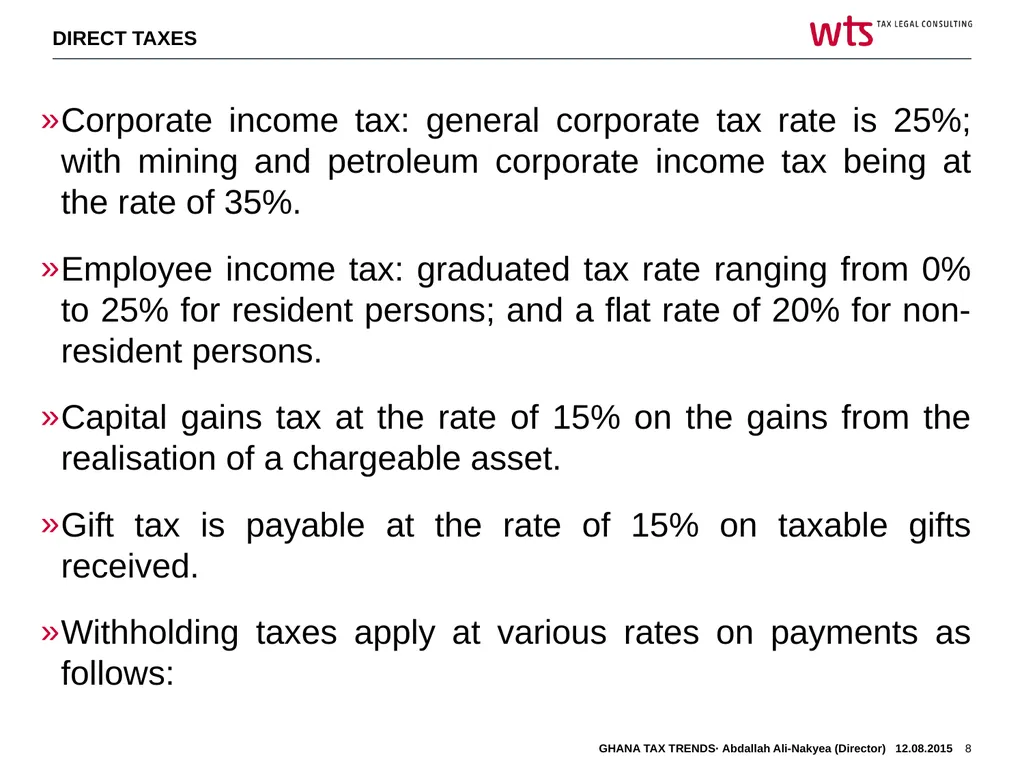
slide8. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 8 Corporate income tax: general corporate tax rate is 25%; with mining and petroleum corporate income tax being at the rate of 35%.
Employee income tax: graduated tax rate ranging from 0% to 25% for resident persons; and a flat rate of 20% for non-resident persons.
Capital gains tax at the rate of 15% on the gains from the realisation of a chargeable asset.
Gift tax is payable at the rate of 15% on taxable gifts received.
Withholding taxes apply at various rates on payments as follows: DIRECT TAXES<br>
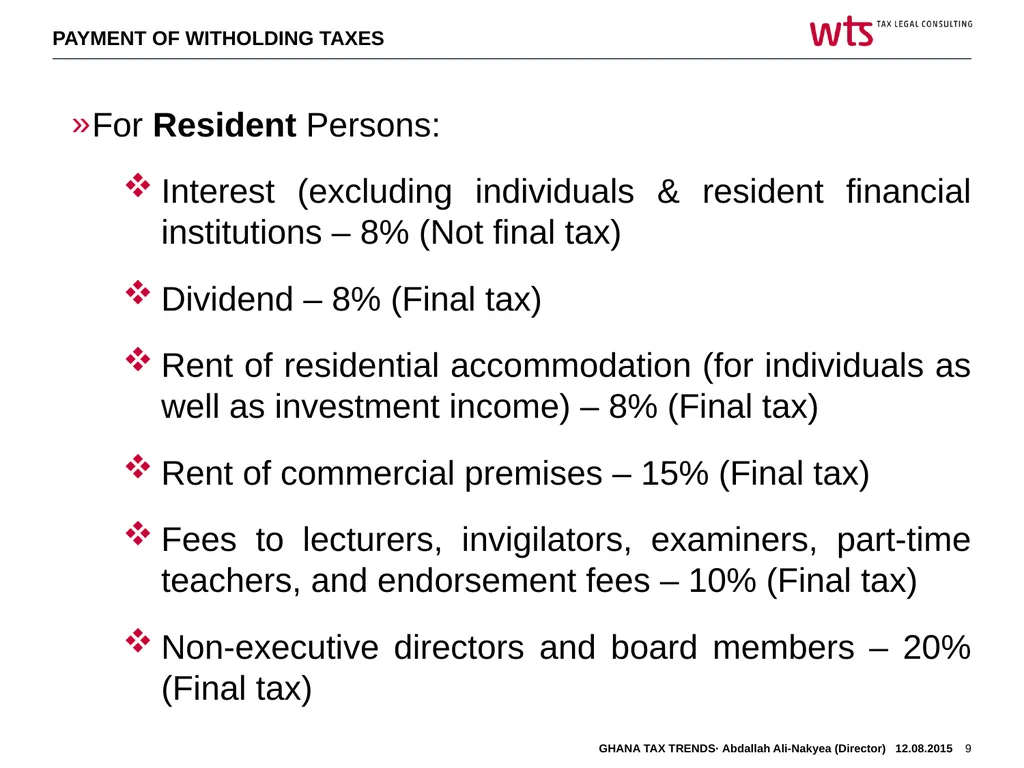
slide9. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 9 For Resident Persons:
Interest (excluding individuals & resident financial institutions – 8% (Not final tax)
Dividend – 8% (Final tax)
Rent of residential accommodation (for individuals as well as investment income) – 8% (Final tax)
Rent of commercial premises – 15% (Final tax)
Fees to lecturers, invigilators, examiners, part-time teachers, and endorsement fees – 10% (Final tax)
Non-executive directors and board members – 20% (Final tax) PAYMENT OF WITHOLDING TAXES<br>
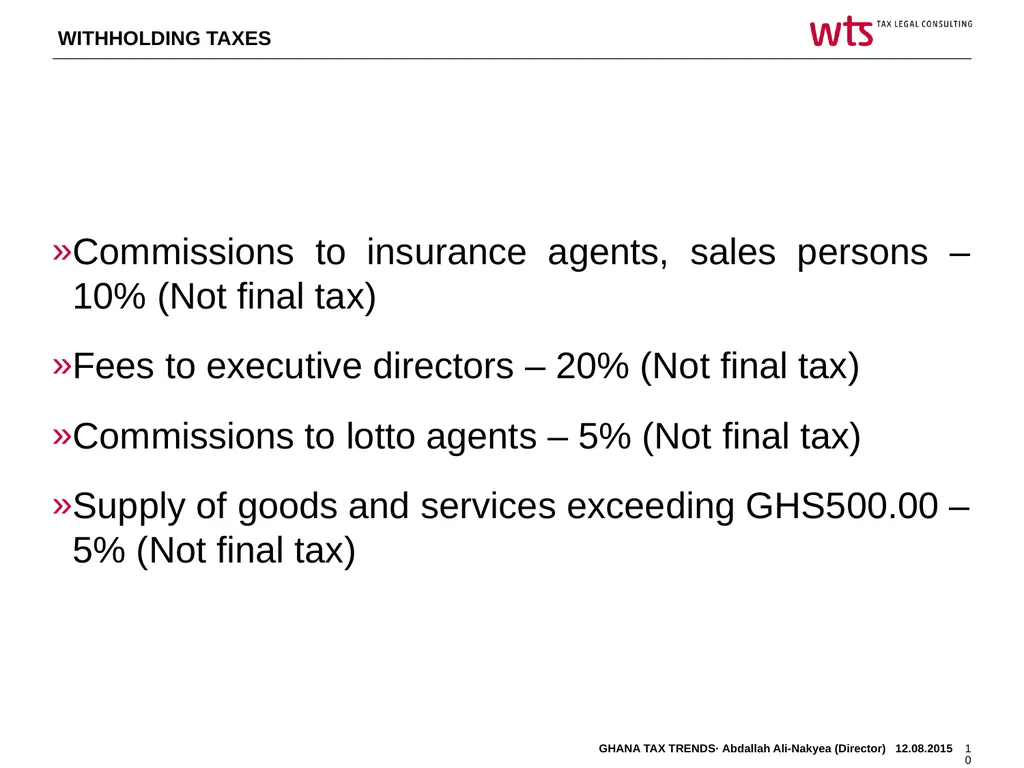
slide10. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 10 Commissions to insurance agents, sales persons – 10% (Not final tax)
Fees to executive directors – 20% (Not final tax)
Commissions to lotto agents – 5% (Not final tax)
Supply of goods and services exceeding GHS500.00 – 5% (Not final tax) WITHHOLDING TAXES<br>
slide11. Withholding tax rates in the case of Non-Resident Persons: Dividend – 8% (Final tax)
Royalties, natural resource payments and rents – 15% (Final tax)
Management, consulting and technical service fee and endorsement fees – 20% (Final tax)
Repatriated Branch after tax profits – 10% (Final tax)
Interest income – 8% (Final tax)
Short term insurance premium – 5% (Final tax)
Receipts of shipping, aircraft, cable radio, optical fibre, satellite communication operations – 15% (Final tax)
Goods and services that gives rise to income accruing in or derived from Ghana – 20% (Final tax) GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 11<br>
slide12. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 12 TAXATION OF EMPLOYMENT INCOME Income from employment is that person’s gain and profits from that employment.
Gains and profits from employment include:
Any allowances, or benefits paid in cash or given in kind
Paid to or on behalf of, that person from that employment
except such employment incomes are specifically exempt from tax by the law
Gains or profits from employment are treated as accruing in or derived from Ghana to the extent they are attributable to employment exercised in Ghana regardless of place of payment.
To exercise employment means to be seen to have taken a position in the employment or hold an office.<br>
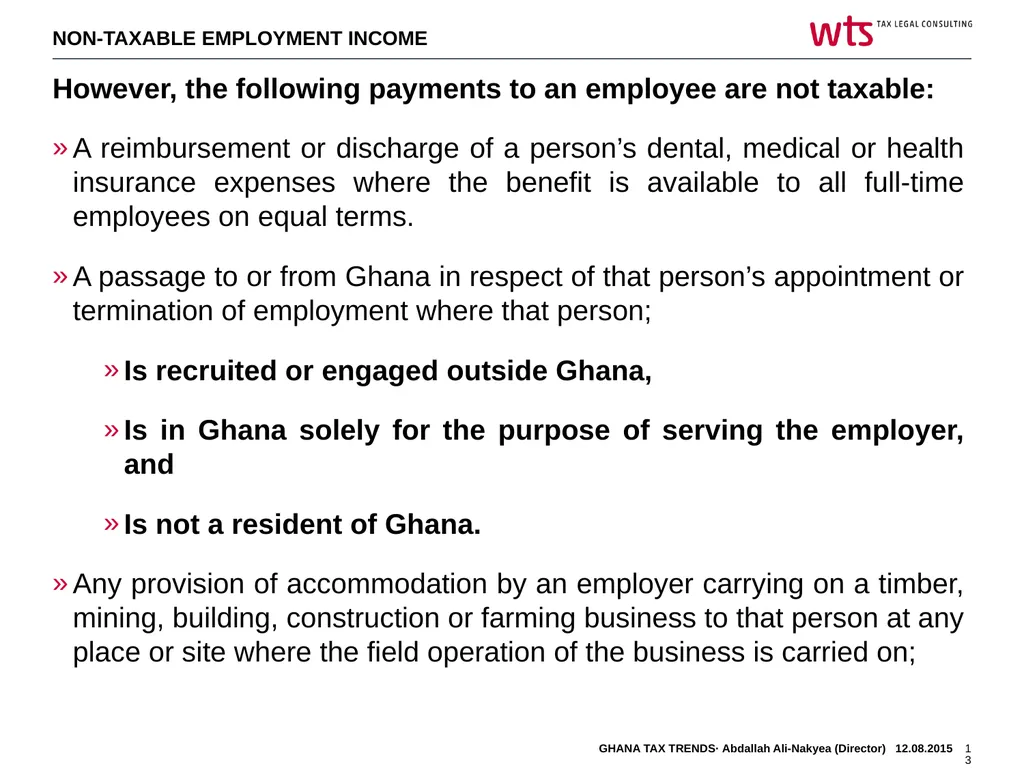
slide13. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 13 NON-TAXABLE EMPLOYMENT INCOME However, the following payments to an employee are not taxable:
A reimbursement or discharge of a person’s dental, medical or health insurance expenses where the benefit is available to all full-time employees on equal terms.
A passage to or from Ghana in respect of that person’s appointment or termination of employment where that person;
Is recruited or engaged outside Ghana,
Is in Ghana solely for the purpose of serving the employer, and
Is not a resident of Ghana.
Any provision of accommodation by an employer carrying on a timber, mining, building, construction or farming business to that person at any place or site where the field operation of the business is carried on;<br>
slide14. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 14 NON-TAXABLE EMPLOYMENT INCOME CONT’D A discharge or reimbursement by an employer of an expenditure incurred by that person on behalf of the employer that serves the proper business purposes of the employer;
Accommodation provided by employer to employee in mining, farming, timber, building or construction enterprise at a place or site where the field operation of the business is carried out.
A severance pay. This is determined by the following indicators:
Closure of business
Liquidation of Company
Merger or amalgamation with another Company
Re-organization such as reduction of share capital or transfer of business to a new company.
A night duty allowance paid to a night shift employee where the amount does not exceed 50% of his basic monthly salary<br>
slide15. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 8.06.2015 15 TAXATION OF OVERTIME & BONUS PAYMENT Where an employer makes a payment during a year of assessment to a qualifying junior employee for overtime work by that employee, and the payment for the overtime work to that employee:
is up 50% of the basic salary of the employee for the month, the employer shall withhold tax at the rate of 5% from the payment.
is more than 50% of the basic salary of the employee for the month, the employer shall withhold tax at the rate of 10% from the payment.
A qualifying junior employee is a junior staff member whose qualifying employment income from the employment for the year does not exceed GHc9,600.00
. OVERTIME PAYMENT<br>
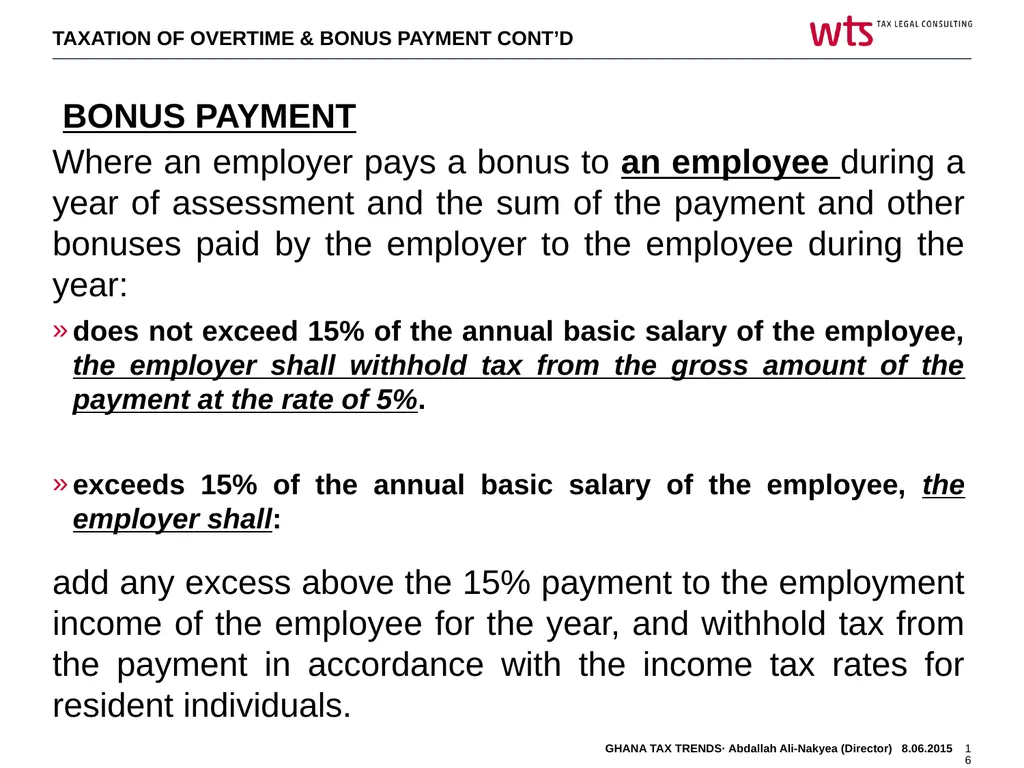
slide16. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 8.06.2015 16 TAXATION OF OVERTIME & BONUS PAYMENT CONT’D Where an employer pays a bonus to an employee during a year of assessment and the sum of the payment and other bonuses paid by the employer to the employee during the year:
does not exceed 15% of the annual basic salary of the employee, the employer shall withhold tax from the gross amount of the payment at the rate of 5%.
exceeds 15% of the annual basic salary of the employee, the employer shall:
add any excess above the 15% payment to the employment income of the employee for the year, and withhold tax from the payment in accordance with the income tax rates for resident individuals.
. BONUS PAYMENT<br>
slide17. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 17 Businesses engaged in the following sectors can carry forward losses incurred in a basis period for a period of the five years following the year in which the loss was incurred:
agro processing;
tourism (must register with the Ghana Tourism Authority)
information and communication technology in software development;
farming;
manufacturing for export;
mining; (petroleum sector – indefinitely);
tax losses incurred from disposal of shares in any venture investment. Tax Incentives – Carry Over of Losses<br>
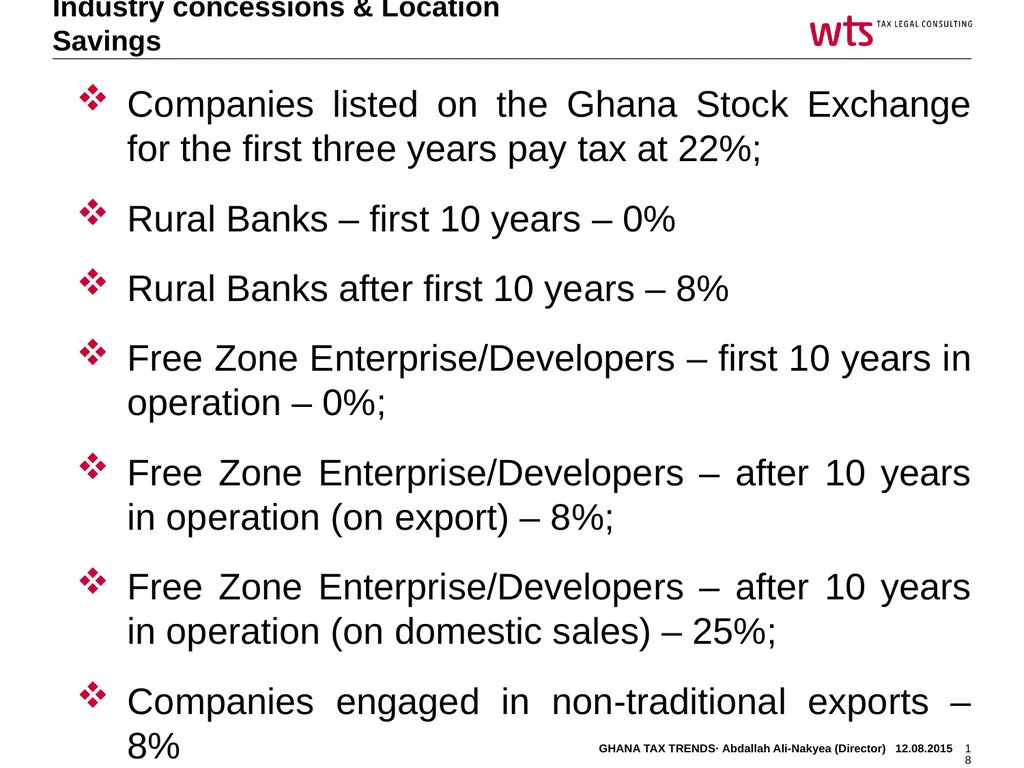
slide18. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 18 Companies listed on the Ghana Stock Exchange for the first three years pay tax at 22%;
Rural Banks – first 10 years – 0%
Rural Banks after first 10 years – 8%
Free Zone Enterprise/Developers – first 10 years in operation – 0%;
Free Zone Enterprise/Developers – after 10 years in operation (on export) – 8%;
Free Zone Enterprise/Developers – after 10 years in operation (on domestic sales) – 25%;
Companies engaged in non-traditional exports – 8% Industry concessions & Location Savings<br>
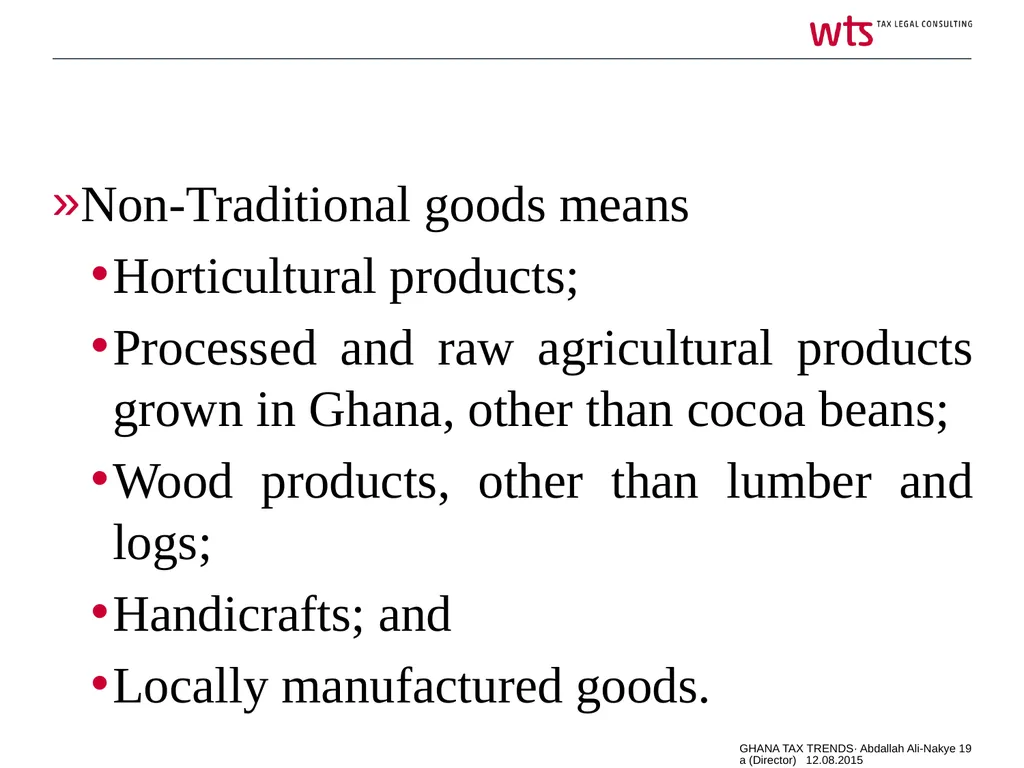
slide19. Non-Traditional goods means
Horticultural products;
Processed and raw agricultural products grown in Ghana, other than cocoa beans;
Wood products, other than lumber and logs;
Handicrafts; and
Locally manufactured goods. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 19<br>
slide20. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 20 Manufacturing companies located in regional capitals other than Accra/Tema – 18.75%;
Manufacturing companies located elsewhere – 12.5%;
Waste management companies – first 7 years – 8%;
Companies that process cocoa waste; livestock farming (excluding cattle), fish and cash crops – first 5 years – 0%;
Cattle farming; farming tree crops – first 10 years – 0%
Real estate approved by government, after first 5 years – 25%
. Industry concessions & Location Savings<br>
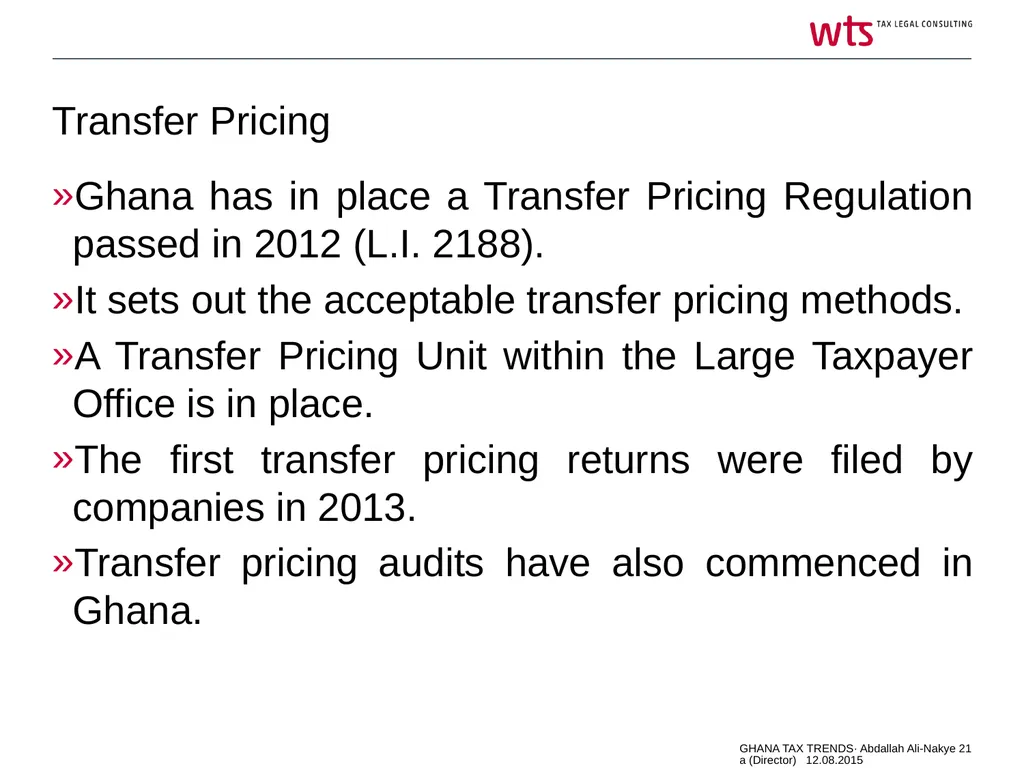
slide21. Transfer Pricing Ghana has in place a Transfer Pricing Regulation passed in 2012 (L.I. 2188).
It sets out the acceptable transfer pricing methods.
A Transfer Pricing Unit within the Large Taxpayer Office is in place.
The first transfer pricing returns were filed by companies in 2013.
Transfer pricing audits have also commenced in Ghana. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 21<br>
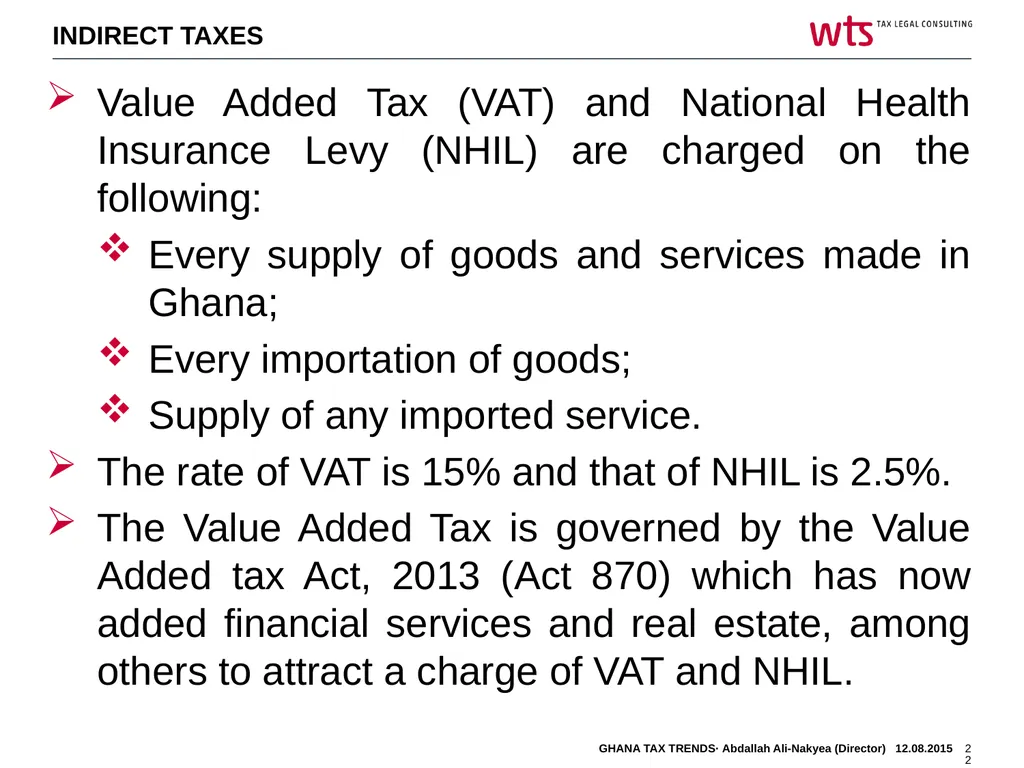
slide22. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 22 INDIRECT TAXES Value Added Tax (VAT) and National Health Insurance Levy (NHIL) are charged on the following:
Every supply of goods and services made in Ghana;
Every importation of goods;
Supply of any imported service.
The rate of VAT is 15% and that of NHIL is 2.5%.
The Value Added Tax is governed by the Value Added tax Act, 2013 (Act 870) which has now added financial services and real estate, among others to attract a charge of VAT and NHIL.<br>
slide23. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 23 TECHNOLOGY TRANSFER AGREEMENT The Technology Transfer Regulations, 1992 (LI 1547) regulates Technology Transfer Agreements in Ghana.
When LI 1547 was passed into law in 1992, the Investment Code, 1985 (P.N.D.C.L. 116) was in force.
Subsequently, GIPC Act, 1994 (Act 478) repealed PNDCL 116 and the current GIPC Act, 2013 (Act 865) also repealed Act 478.
However, LI 1547 passed in 1992 has not seen any major amendments to bring it to conformity with current investment trends<br>
slide24. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 24 TECHNOLOGY TRANSFER AGREEMENT LI 1547 requires that all Technology Transfer Agreements should be registered with GIPC
Regulation 6 of LI 1547 provides that royalties paid for the transfer of technology is subject to tax and this tax shall be paid by the person transferring the technology
Regulation 9 of LI 1547 states that Technology Transfer Agreements shall be for a maximum period of ten years but may be renewed for an additional five year period.<br>
slide25. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 25 TECHNOLOGY TRANSFER AGREEMENT Regulations 14, 15, 16 & 17 of LI 1547 provide the following permissible payments for transfer of technology:
Royalty in respect of know-how patents and other industrial property rights shall range from 0% to 6% of net sales
Fee for Technical Service/Assistance (including know-how) shall range between 0% to 5% of net sales
Fee for know-how shall not exceed 2% of net sales<br>
slide26. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 26 TECHNOLOGY TRANSFER AGREEMENT Management fees shall range between 0% and 2% of profit before tax
Management services of projects for which profit is not anticipated during the early years shall attract a fee ranging from 0% and 2% of net sales during the first 3 to 5 years
Management/ technical services, in addition to patent know-how and trademarks, the total fee shall not exceed 8% of net sales.
The investor can apply to GIPC to request for fees higher than those specified above.<br>
slide27. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 27 TECHNOLOGY TRANSFER AGREEMENT Even though LI 1547 gives permissible margins to be charged for technology transfers, GRA sometimes disallow these charges for income tax purposes.
The argument often put forth by GRA is that these margins do not reflect the arm’s length principle as required by LI 2188.
This poses a huge challenge for investors and there is a need for collaboration between GIPC and GRA to address some of these challenges investors face.<br>
slide28. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 28 END OF PRESENTATION
THANK YOU<br>
slide2. Speaker GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 2 Placeholder for photo Abdallah Ali-Nakyea
FCIT, FICB, FCCE, CEPA, MIIA, MTP (SA), Professional Accountant (SA), CA (Gh), LLB (Hons), BL, MPhil (Econs)
(Managing Consultant) WTS Ghana (Tax Legal Consulting)
P.O. Box KD 66 Kanda-Accra, Ghana Tel +233 (244) 23 5144
+233 (302) 23 6334 Fax +233 (302) 23 6334 E-mail: abdallah.alinakyea@wts.com.gh
Website: www.wts.com.gh<br>
slide3. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 3 In Ghana, the source jurisdiction is applied and this means that income is taxable in Ghana as long as its source is from Ghana. Thus where the source of an income is not from Ghana, it is not taxable in Ghana.
It is to be noted that where the source of an income is not from Ghana, then the income has to be brought in or received in Ghana to make it subject to tax in Ghana.
This position is clearly outlined in section 6 of the Internal Revenue Act, 2000 (Act 592). TAXABLE INCOME<br>
slide4. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 4 In the case of a resident person, the full amount of the person’s income from the business, employment, or investment accruing in, derived from, brought into, or received in Ghana during any basis period of that person ending within the year of assessment;
In the case of a non-resident person, the full amount of the person’s income from the business, employment, or investment accruing in or derived from Ghana during any basis period of the person ending within the year of assessment. ASSESSABLE INCOME The assessable income of a person for a year of assessment from any business, employment, or investment is:<br>
slide5. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 5 A citizen of Ghana who has no permanent home outside Ghana for a whole year of assessment.
Present in Ghana for a period/total of 183 days or more in a year of assessment.
An employee or official of the government of Ghana posted abroad during the year.
A citizen of Ghana who is temporary absent from Ghana for less than 365 continuous days and has a permanent home in Ghana. MEANING OF KEY TAX TERMINOLOGIES Resident Individual: An individual is resident for tax purposes if that individual is:<br>
slide6. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 6 Incorporated under the laws of Ghana, or
Managed and controlled in Ghana at any time in the year of assessment. In other words, if the board of directors meet and take decisions in Ghana then the company is deemed to be resident in Ghana. MEANING OF KEY TAX TERMINOLOGIES Resident Company: A company is resident for tax purposes for a year of assessment if that company is:<br>
slide7. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 7 Is established in Ghana
Has a resident person as a manager at any time during the year of assessment, or
Is controlled directly or indirectly by a resident person or persons at any time during the year of assessment MEANING OF KEY TAX TERMINOLOGIES Resident Body of Persons: A body of persons is a resident body of persons for any year of assessment if it:<br>
slide8. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 8 Corporate income tax: general corporate tax rate is 25%; with mining and petroleum corporate income tax being at the rate of 35%.
Employee income tax: graduated tax rate ranging from 0% to 25% for resident persons; and a flat rate of 20% for non-resident persons.
Capital gains tax at the rate of 15% on the gains from the realisation of a chargeable asset.
Gift tax is payable at the rate of 15% on taxable gifts received.
Withholding taxes apply at various rates on payments as follows: DIRECT TAXES<br>
slide9. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 9 For Resident Persons:
Interest (excluding individuals & resident financial institutions – 8% (Not final tax)
Dividend – 8% (Final tax)
Rent of residential accommodation (for individuals as well as investment income) – 8% (Final tax)
Rent of commercial premises – 15% (Final tax)
Fees to lecturers, invigilators, examiners, part-time teachers, and endorsement fees – 10% (Final tax)
Non-executive directors and board members – 20% (Final tax) PAYMENT OF WITHOLDING TAXES<br>
slide10. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 10 Commissions to insurance agents, sales persons – 10% (Not final tax)
Fees to executive directors – 20% (Not final tax)
Commissions to lotto agents – 5% (Not final tax)
Supply of goods and services exceeding GHS500.00 – 5% (Not final tax) WITHHOLDING TAXES<br>
slide11. Withholding tax rates in the case of Non-Resident Persons: Dividend – 8% (Final tax)
Royalties, natural resource payments and rents – 15% (Final tax)
Management, consulting and technical service fee and endorsement fees – 20% (Final tax)
Repatriated Branch after tax profits – 10% (Final tax)
Interest income – 8% (Final tax)
Short term insurance premium – 5% (Final tax)
Receipts of shipping, aircraft, cable radio, optical fibre, satellite communication operations – 15% (Final tax)
Goods and services that gives rise to income accruing in or derived from Ghana – 20% (Final tax) GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 11<br>
slide12. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 12 TAXATION OF EMPLOYMENT INCOME Income from employment is that person’s gain and profits from that employment.
Gains and profits from employment include:
Any allowances, or benefits paid in cash or given in kind
Paid to or on behalf of, that person from that employment
except such employment incomes are specifically exempt from tax by the law
Gains or profits from employment are treated as accruing in or derived from Ghana to the extent they are attributable to employment exercised in Ghana regardless of place of payment.
To exercise employment means to be seen to have taken a position in the employment or hold an office.<br>
slide13. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 13 NON-TAXABLE EMPLOYMENT INCOME However, the following payments to an employee are not taxable:
A reimbursement or discharge of a person’s dental, medical or health insurance expenses where the benefit is available to all full-time employees on equal terms.
A passage to or from Ghana in respect of that person’s appointment or termination of employment where that person;
Is recruited or engaged outside Ghana,
Is in Ghana solely for the purpose of serving the employer, and
Is not a resident of Ghana.
Any provision of accommodation by an employer carrying on a timber, mining, building, construction or farming business to that person at any place or site where the field operation of the business is carried on;<br>
slide14. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 14 NON-TAXABLE EMPLOYMENT INCOME CONT’D A discharge or reimbursement by an employer of an expenditure incurred by that person on behalf of the employer that serves the proper business purposes of the employer;
Accommodation provided by employer to employee in mining, farming, timber, building or construction enterprise at a place or site where the field operation of the business is carried out.
A severance pay. This is determined by the following indicators:
Closure of business
Liquidation of Company
Merger or amalgamation with another Company
Re-organization such as reduction of share capital or transfer of business to a new company.
A night duty allowance paid to a night shift employee where the amount does not exceed 50% of his basic monthly salary<br>
slide15. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 8.06.2015 15 TAXATION OF OVERTIME & BONUS PAYMENT Where an employer makes a payment during a year of assessment to a qualifying junior employee for overtime work by that employee, and the payment for the overtime work to that employee:
is up 50% of the basic salary of the employee for the month, the employer shall withhold tax at the rate of 5% from the payment.
is more than 50% of the basic salary of the employee for the month, the employer shall withhold tax at the rate of 10% from the payment.
A qualifying junior employee is a junior staff member whose qualifying employment income from the employment for the year does not exceed GHc9,600.00
. OVERTIME PAYMENT<br>
slide16. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 8.06.2015 16 TAXATION OF OVERTIME & BONUS PAYMENT CONT’D Where an employer pays a bonus to an employee during a year of assessment and the sum of the payment and other bonuses paid by the employer to the employee during the year:
does not exceed 15% of the annual basic salary of the employee, the employer shall withhold tax from the gross amount of the payment at the rate of 5%.
exceeds 15% of the annual basic salary of the employee, the employer shall:
add any excess above the 15% payment to the employment income of the employee for the year, and withhold tax from the payment in accordance with the income tax rates for resident individuals.
. BONUS PAYMENT<br>
slide17. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 17 Businesses engaged in the following sectors can carry forward losses incurred in a basis period for a period of the five years following the year in which the loss was incurred:
agro processing;
tourism (must register with the Ghana Tourism Authority)
information and communication technology in software development;
farming;
manufacturing for export;
mining; (petroleum sector – indefinitely);
tax losses incurred from disposal of shares in any venture investment. Tax Incentives – Carry Over of Losses<br>
slide18. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 18 Companies listed on the Ghana Stock Exchange for the first three years pay tax at 22%;
Rural Banks – first 10 years – 0%
Rural Banks after first 10 years – 8%
Free Zone Enterprise/Developers – first 10 years in operation – 0%;
Free Zone Enterprise/Developers – after 10 years in operation (on export) – 8%;
Free Zone Enterprise/Developers – after 10 years in operation (on domestic sales) – 25%;
Companies engaged in non-traditional exports – 8% Industry concessions & Location Savings<br>
slide19. Non-Traditional goods means
Horticultural products;
Processed and raw agricultural products grown in Ghana, other than cocoa beans;
Wood products, other than lumber and logs;
Handicrafts; and
Locally manufactured goods. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 19<br>
slide20. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 20 Manufacturing companies located in regional capitals other than Accra/Tema – 18.75%;
Manufacturing companies located elsewhere – 12.5%;
Waste management companies – first 7 years – 8%;
Companies that process cocoa waste; livestock farming (excluding cattle), fish and cash crops – first 5 years – 0%;
Cattle farming; farming tree crops – first 10 years – 0%
Real estate approved by government, after first 5 years – 25%
. Industry concessions & Location Savings<br>
slide21. Transfer Pricing Ghana has in place a Transfer Pricing Regulation passed in 2012 (L.I. 2188).
It sets out the acceptable transfer pricing methods.
A Transfer Pricing Unit within the Large Taxpayer Office is in place.
The first transfer pricing returns were filed by companies in 2013.
Transfer pricing audits have also commenced in Ghana. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 21<br>
slide22. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 22 INDIRECT TAXES Value Added Tax (VAT) and National Health Insurance Levy (NHIL) are charged on the following:
Every supply of goods and services made in Ghana;
Every importation of goods;
Supply of any imported service.
The rate of VAT is 15% and that of NHIL is 2.5%.
The Value Added Tax is governed by the Value Added tax Act, 2013 (Act 870) which has now added financial services and real estate, among others to attract a charge of VAT and NHIL.<br>
slide23. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 23 TECHNOLOGY TRANSFER AGREEMENT The Technology Transfer Regulations, 1992 (LI 1547) regulates Technology Transfer Agreements in Ghana.
When LI 1547 was passed into law in 1992, the Investment Code, 1985 (P.N.D.C.L. 116) was in force.
Subsequently, GIPC Act, 1994 (Act 478) repealed PNDCL 116 and the current GIPC Act, 2013 (Act 865) also repealed Act 478.
However, LI 1547 passed in 1992 has not seen any major amendments to bring it to conformity with current investment trends<br>
slide24. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 24 TECHNOLOGY TRANSFER AGREEMENT LI 1547 requires that all Technology Transfer Agreements should be registered with GIPC
Regulation 6 of LI 1547 provides that royalties paid for the transfer of technology is subject to tax and this tax shall be paid by the person transferring the technology
Regulation 9 of LI 1547 states that Technology Transfer Agreements shall be for a maximum period of ten years but may be renewed for an additional five year period.<br>
slide25. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 25 TECHNOLOGY TRANSFER AGREEMENT Regulations 14, 15, 16 & 17 of LI 1547 provide the following permissible payments for transfer of technology:
Royalty in respect of know-how patents and other industrial property rights shall range from 0% to 6% of net sales
Fee for Technical Service/Assistance (including know-how) shall range between 0% to 5% of net sales
Fee for know-how shall not exceed 2% of net sales<br>
slide26. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 26 TECHNOLOGY TRANSFER AGREEMENT Management fees shall range between 0% and 2% of profit before tax
Management services of projects for which profit is not anticipated during the early years shall attract a fee ranging from 0% and 2% of net sales during the first 3 to 5 years
Management/ technical services, in addition to patent know-how and trademarks, the total fee shall not exceed 8% of net sales.
The investor can apply to GIPC to request for fees higher than those specified above.<br>
slide27. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 27 TECHNOLOGY TRANSFER AGREEMENT Even though LI 1547 gives permissible margins to be charged for technology transfers, GRA sometimes disallow these charges for income tax purposes.
The argument often put forth by GRA is that these margins do not reflect the arm’s length principle as required by LI 2188.
This poses a huge challenge for investors and there is a need for collaboration between GIPC and GRA to address some of these challenges investors face.<br>
slide28. GHANA TAX TRENDS· Abdallah Ali-Nakyea (Director) 12.08.2015 28 END OF PRESENTATION
THANK YOU<br>