
Update on M&A Environment Spring 2019 Speaker
KL
Published · 13 slides · 0 views
1 / 1
Description
Update on MA Environment Spring 2019 Speaker Biography: Titus Leung Mr. Leung is a Partner of Perella Weinberg Partners and Head of PWPs Financial Institutions Coverage team, which he has led since the firms inception Prior to joining
Related Topics
Share
Embed code
Download this presentation From Below
"Update on M&A Environment Spring 2019 Speaker" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
Update on M&A Environment Spring 2019<br>
02
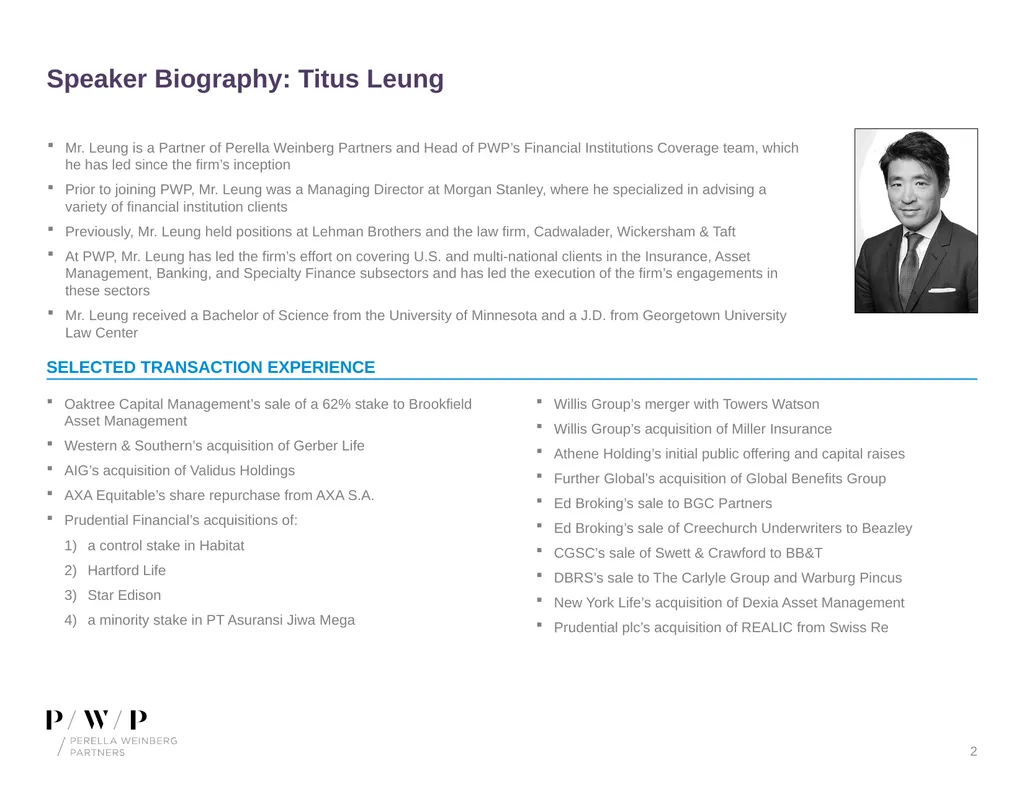
Speaker Biography: Titus Leung Mr. Leung is a Partner of Perella Weinberg Partners and Head of PWP’s Financial Institutions Coverage team, which he has led since the firm’s inception
Prior to joining PWP, Mr. Leung was a Managing Director at Morgan Stanley, where he specialized in advising a variety of financial institution clients
Previously, Mr. Leung held positions at Lehman Brothers and the law firm, Cadwalader, Wickersham & Taft
At PWP, Mr. Leung has led the firm’s effort on covering U.S. and multi-national clients in the Insurance, Asset Management, Banking, and Specialty Finance subsectors and has led the execution of the firm’s engagements in these sectors
Mr. Leung received a Bachelor of Science from the University of Minnesota and a J.D. from Georgetown University Law Center Oaktree Capital Management’s sale of a 62% stake to Brookfield Asset Management
Western & Southern’s acquisition of Gerber Life
AIG’s acquisition of Validus Holdings
AXA Equitable’s share repurchase from AXA S.A.
Prudential Financial’s acquisitions of:
a control stake in Habitat
Hartford Life
Star Edison
a minority stake in PT Asuransi Jiwa Mega Willis Group’s merger with Towers Watson
Willis Group’s acquisition of Miller Insurance
Athene Holding’s initial public offering and capital raises
Further Global’s acquisition of Global Benefits Group
Ed Broking’s sale to BGC Partners
Ed Broking’s sale of Creechurch Underwriters to Beazley
CGSC’s sale of Swett & Crawford to BB&T
DBRS’s sale to The Carlyle Group and Warburg Pincus
New York Life’s acquisition of Dexia Asset Management
Prudential plc’s acquisition of REALIC from Swiss Re Selected Transaction Experience<br>
03
General M&A Update 3<br>
04
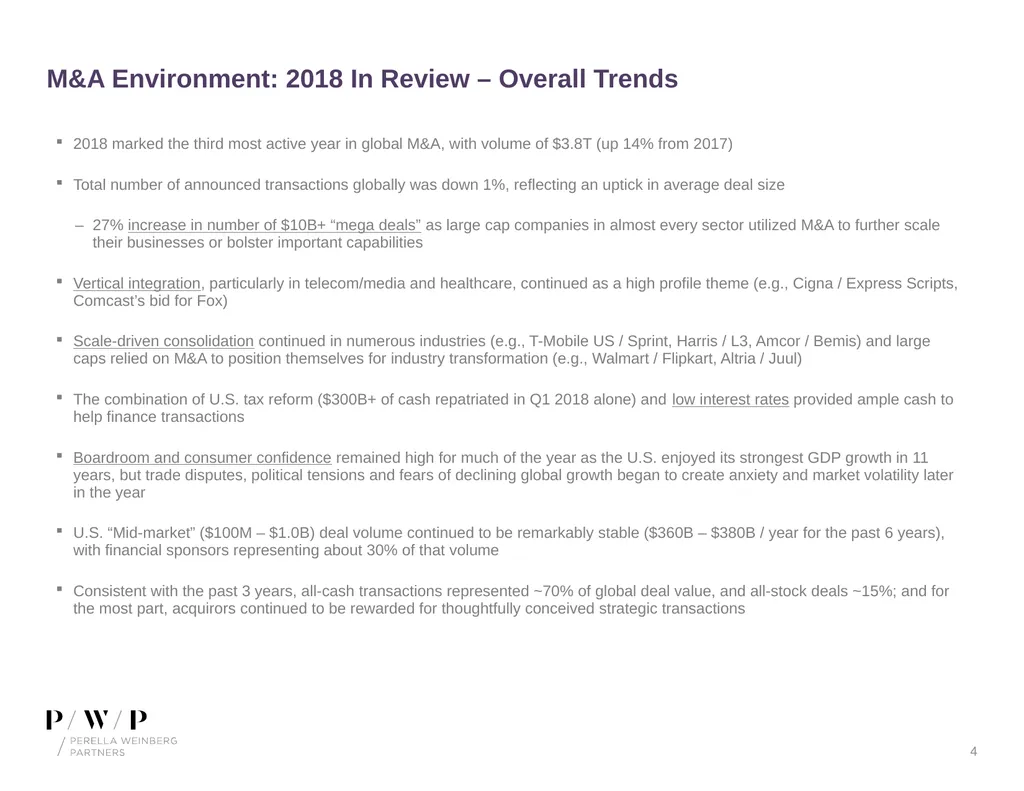
M&A Environment: 2018 In Review – Overall Trends<br>
05
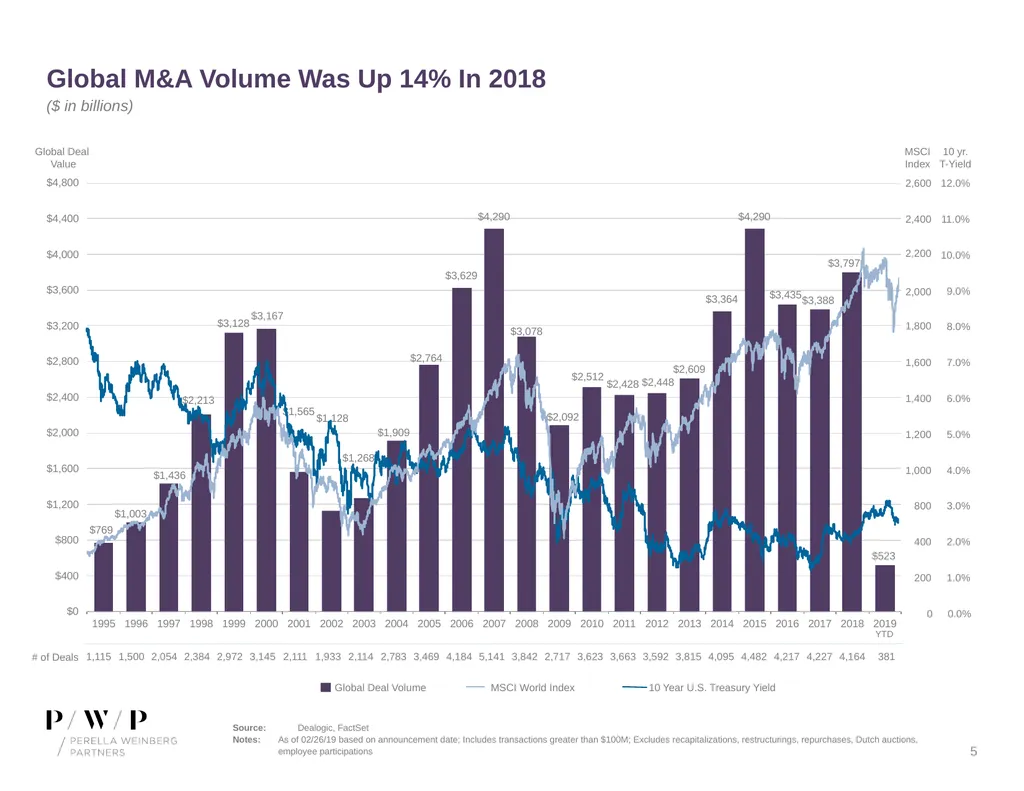
Global M&A Volume Was Up 14% In 2018 Global Deal
Value MSCI
Index 10 yr.
T-Yield 12.0% Source: Dealogic, FactSet
Notes: As of 02/26/19 based on announcement date; Includes transactions greater than $100M; Excludes recapitalizations, restructurings, repurchases, Dutch auctions, employee participations ($ in billions) 8.0% 7.0% 6.0% 5.0% 4.0% 3.0% 2.0% 1.0% 9.0% 0.0% 10.0% 11.0% 2,600 1,800 1,600 1,400 1,200 1,000 800 400 200 2,000 0 2,200 2,400 YTD<br>
Notes: As of 02/26/19 based on announcement date; Includes transactions greater than $100M; Excludes recapitalizations, restructurings, repurchases, Dutch auctions, employee participations ($ in billions) 8.0% 7.0% 6.0% 5.0% 4.0% 3.0% 2.0% 1.0% 9.0% 0.0% 10.0% 11.0% 2,600 1,800 1,600 1,400 1,200 1,000 800 400 200 2,000 0 2,200 2,400 YTD<br>
06
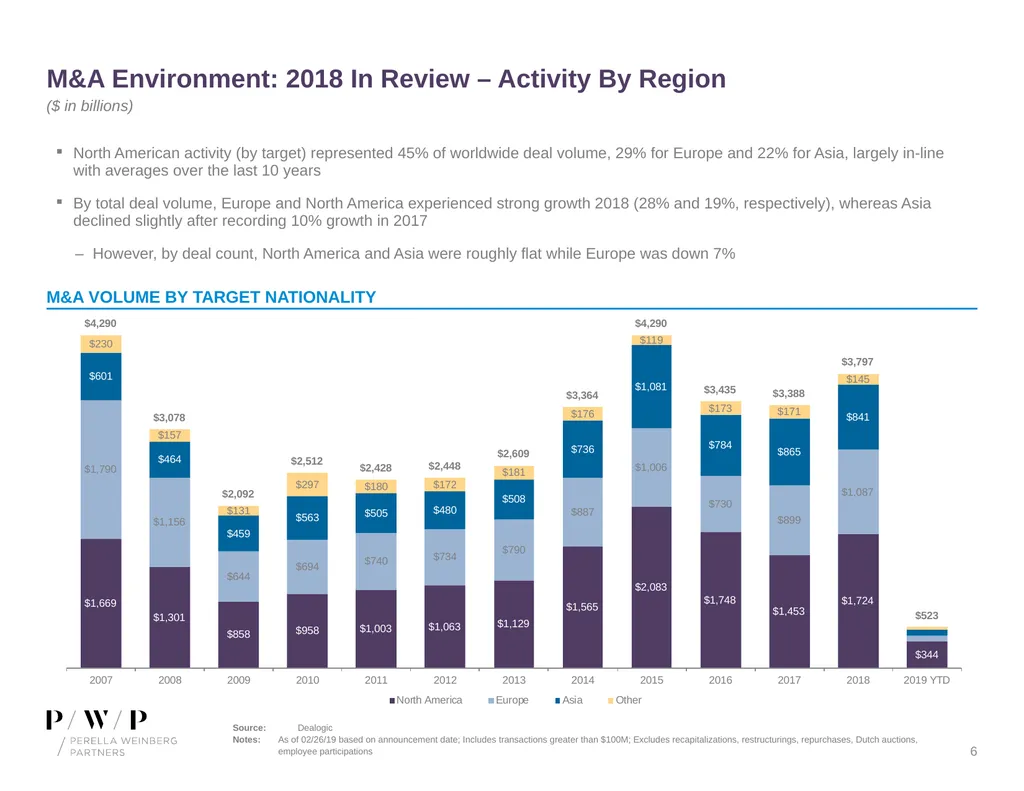
M&A Environment: 2018 In Review – Activity By Region Source: Dealogic
Notes: As of 02/26/19 based on announcement date; Includes transactions greater than $100M; Excludes recapitalizations, restructurings, repurchases, Dutch auctions, employee participations M&A volume by target nationality ($ in billions)<br>
Notes: As of 02/26/19 based on announcement date; Includes transactions greater than $100M; Excludes recapitalizations, restructurings, repurchases, Dutch auctions, employee participations M&A volume by target nationality ($ in billions)<br>
07
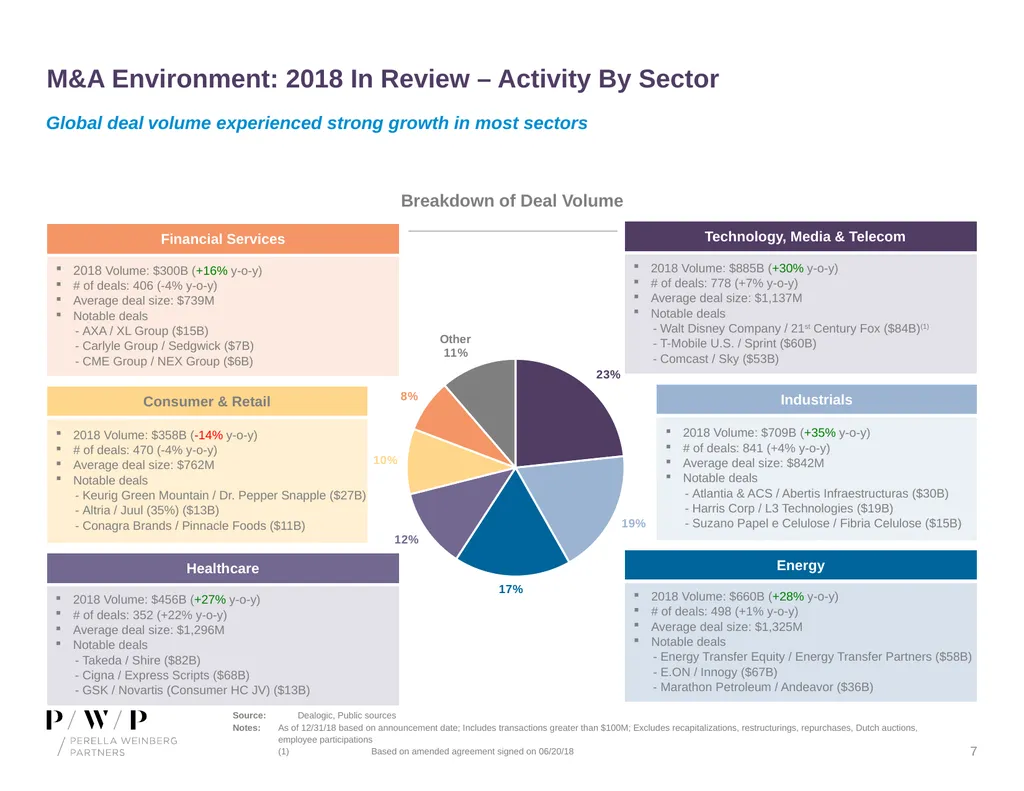
M&A Environment: 2018 In Review – Activity By Sector Breakdown of Deal Volume Source: Dealogic, Public sources
Notes: As of 12/31/18 based on announcement date; Includes transactions greater than $100M; Excludes recapitalizations, restructurings, repurchases, Dutch auctions, employee participations
(1) Based on amended agreement signed on 06/20/18<br>
Notes: As of 12/31/18 based on announcement date; Includes transactions greater than $100M; Excludes recapitalizations, restructurings, repurchases, Dutch auctions, employee participations
(1) Based on amended agreement signed on 06/20/18<br>
08
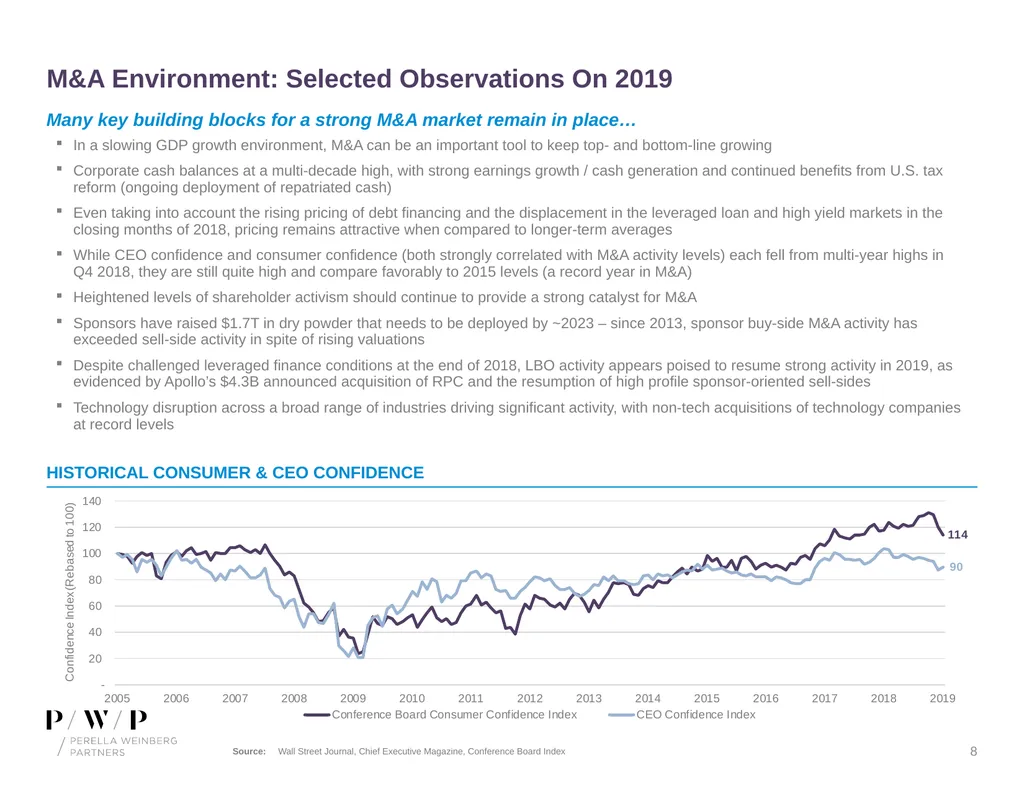
M&A Environment: Selected Observations On 2019 Source: Wall Street Journal, Chief Executive Magazine, Conference Board Index Many key building blocks for a strong M&A market remain in place… Historical Consumer & CEO Confidence<br>
09
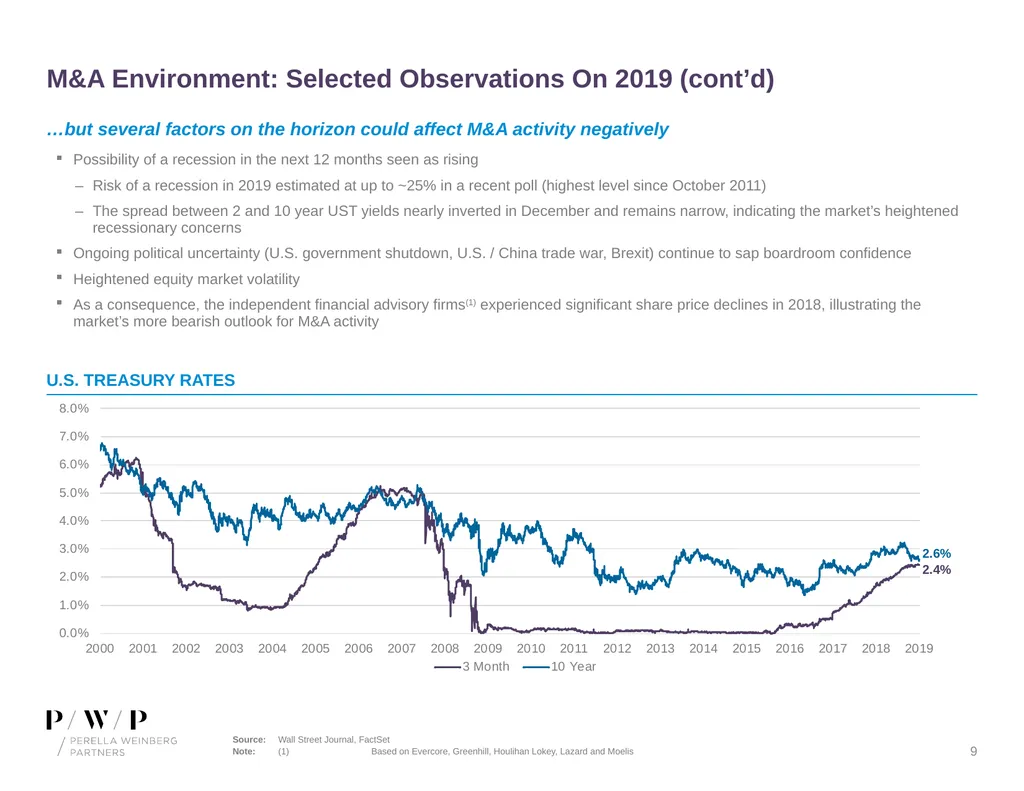
M&A Environment: Selected Observations On 2019 (cont’d) Source: Wall Street Journal, FactSet
Note: (1) Based on Evercore, Greenhill, Houlihan Lokey, Lazard and Moelis …but several factors on the horizon could affect M&A activity negatively U.S. Treasury Rates<br>
Note: (1) Based on Evercore, Greenhill, Houlihan Lokey, Lazard and Moelis …but several factors on the horizon could affect M&A activity negatively U.S. Treasury Rates<br>
10
Insurance Sector M&A Update 10<br>
11
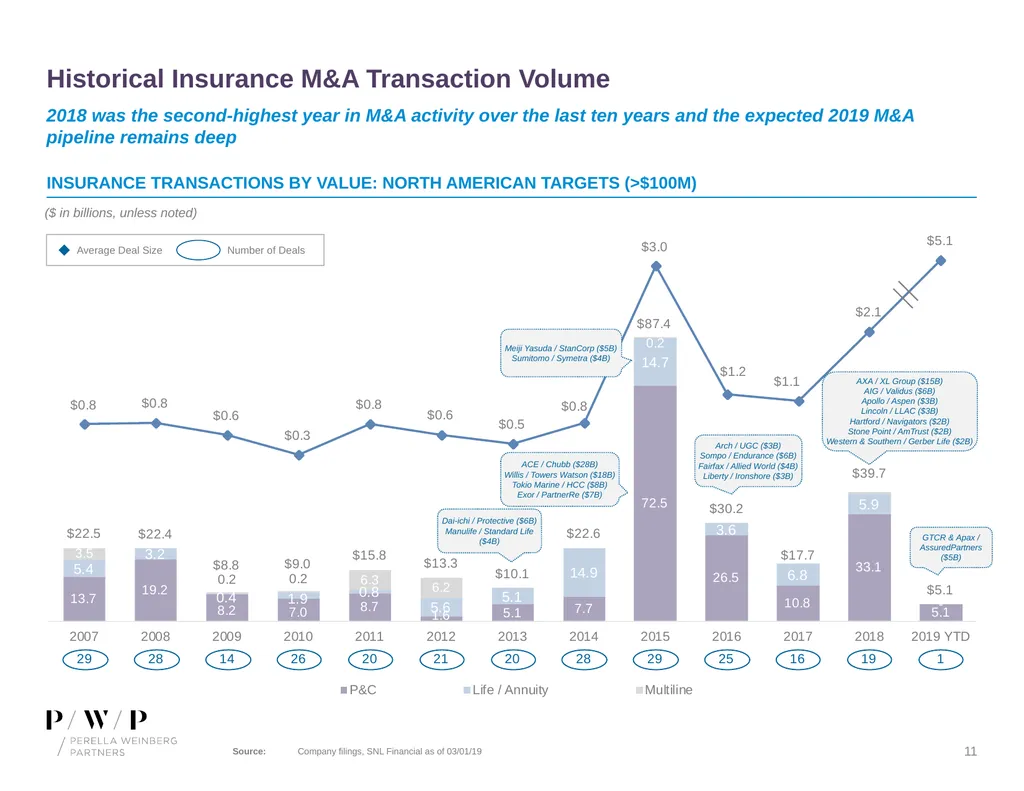
Historical Insurance M&A Transaction Volume Insurance transactions by value: north American targets (>$100M) Source: Company filings, SNL Financial as of 03/01/19 ($ in billions, unless noted) Dai-ichi / Protective ($6B)
Manulife / Standard Life ($4B) Meiji Yasuda / StanCorp ($5B)
Sumitomo / Symetra ($4B) Arch / UGC ($3B)
Sompo / Endurance ($6B)
Fairfax / Allied World ($4B)
Liberty / Ironshore ($3B) AXA / XL Group ($15B)
AIG / Validus ($6B)
Apollo / Aspen ($3B)
Lincoln / LLAC ($3B)
Hartford / Navigators ($2B)
Stone Point / AmTrust ($2B)
Western & Southern / Gerber Life ($2B) ACE / Chubb ($28B)
Willis / Towers Watson ($18B)
Tokio Marine / HCC ($8B)
Exor / PartnerRe ($7B) 2018 was the second-highest year in M&A activity over the last ten years and the expected 2019 M&A pipeline remains deep GTCR & Apax / AssuredPartners ($5B)<br>
12
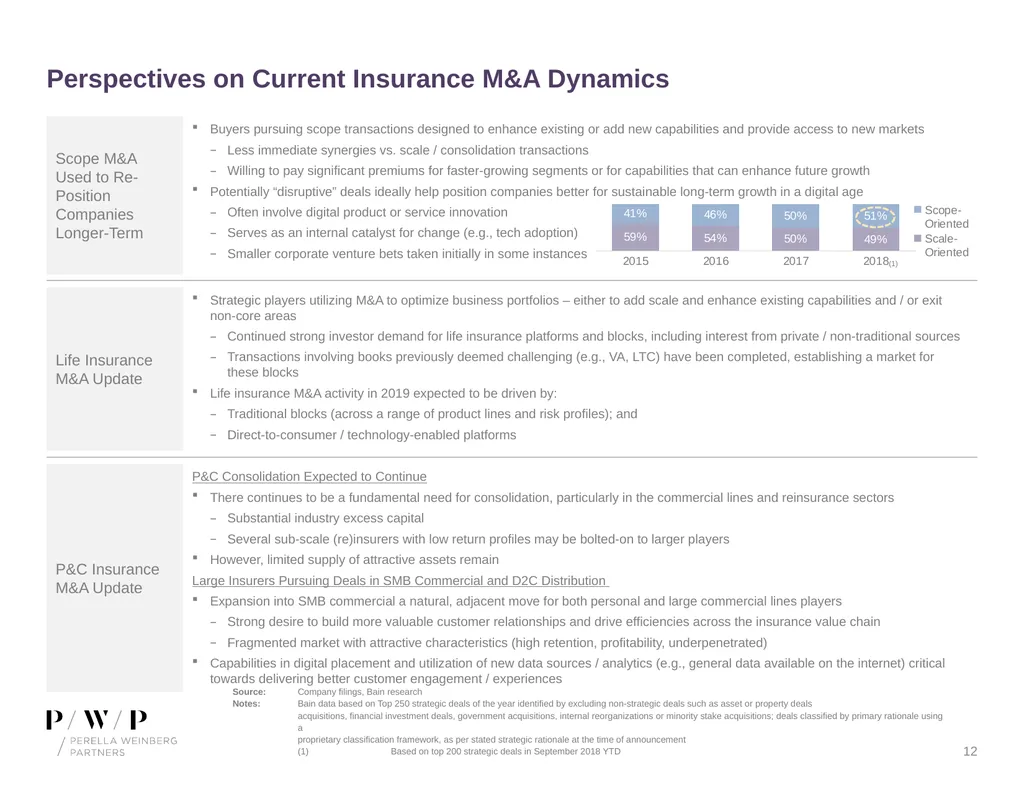
Perspectives on Current Insurance M&A Dynamics Buyers pursuing scope transactions designed to enhance existing or add new capabilities and provide access to new markets
Less immediate synergies vs. scale / consolidation transactions
Willing to pay significant premiums for faster-growing segments or for capabilities that can enhance future growth
Potentially “disruptive” deals ideally help position companies better for sustainable long-term growth in a digital age
Often involve digital product or service innovation
Serves as an internal catalyst for change (e.g., tech adoption)
Smaller corporate venture bets taken initially in some instances Strategic players utilizing M&A to optimize business portfolios – either to add scale and enhance existing capabilities and / or exit non-core areas
Continued strong investor demand for life insurance platforms and blocks, including interest from private / non-traditional sources
Transactions involving books previously deemed challenging (e.g., VA, LTC) have been completed, establishing a market for these blocks
Life insurance M&A activity in 2019 expected to be driven by:
Traditional blocks (across a range of product lines and risk profiles); and
Direct-to-consumer / technology-enabled platforms P&C Consolidation Expected to Continue
There continues to be a fundamental need for consolidation, particularly in the commercial lines and reinsurance sectors
Substantial industry excess capital
Several sub-scale (re)insurers with low return profiles may be bolted-on to larger players
However, limited supply of attractive assets remain
Large Insurers Pursuing Deals in SMB Commercial and D2C Distribution
Expansion into SMB commercial a natural, adjacent move for both personal and large commercial lines players
Strong desire to build more valuable customer relationships and drive efficiencies across the insurance value chain
Fragmented market with attractive characteristics (high retention, profitability, underpenetrated)
Capabilities in digital placement and utilization of new data sources / analytics (e.g., general data available on the internet) critical towards delivering better customer engagement / experiences (1) Source: Company filings, Bain research
Notes: Bain data based on Top 250 strategic deals of the year identified by excluding non-strategic deals such as asset or property deals
acquisitions, financial investment deals, government acquisitions, internal reorganizations or minority stake acquisitions; deals classified by primary rationale using a
proprietary classification framework, as per stated strategic rationale at the time of announcement
(1) Based on top 200 strategic deals in September 2018 YTD Scope M&A Used to Re-Position Companies Longer-Term Life Insurance M&A Update P&C Insurance M&A Update<br>
13
Legal Disclosures This Presentation has been provided to you by Perella Weinberg Partners and its affiliates (collectively “Perella Weinberg Partners” or the “Firm”) and may not be used or relied upon for any purpose without the written consent of Perella Weinberg Partners. The information contained herein (the “Information”) is confidential information. By accepting this Information, you agree that you will, and you will cause your directors, partners, officers, employees, attorney(s), agents and representatives to, use the Information only for your informational purposes and for no other purpose and will not divulge any such Information to any other party. Any reproduction of this Information, in whole or in part, is prohibited. These contents are proprietary information and products of Perella Weinberg Partners. The Information contained herein is not an offer to buy or sell or a solicitation of an offer to buy or sell any corporate advisory services or security or to participate in any corporate advisory services or trading strategy. Any decision regarding corporate advisory services or to invest in the investments described herein should be made after, as applicable, reviewing such definitive offering memorandum, conducting such investigations as you deem necessary and consulting the investor’s own investment, legal, accounting and tax advisors in order to make an independent determination of the suitability and consequences of an investment or service.
Nothing contained herein should be construed as tax, accounting or legal advice. You (and each of your employees, representatives or other agents) may disclose to any and all persons, without limitation of any kind, the tax treatment and tax structure of the transactions contemplated by these materials and all materials of any kind (including opinions or other tax analyses) that are provided to you relating to such tax treatment and structure. For this purpose, the tax treatment of a transaction is the purported or claimed U.S. federal income tax treatment of the transaction and the tax structure of a transaction is any fact that may be relevant to understanding the purported or claimed U.S. federal income tax treatment of the transaction.<br>
Nothing contained herein should be construed as tax, accounting or legal advice. You (and each of your employees, representatives or other agents) may disclose to any and all persons, without limitation of any kind, the tax treatment and tax structure of the transactions contemplated by these materials and all materials of any kind (including opinions or other tax analyses) that are provided to you relating to such tax treatment and structure. For this purpose, the tax treatment of a transaction is the purported or claimed U.S. federal income tax treatment of the transaction and the tax structure of a transaction is any fact that may be relevant to understanding the purported or claimed U.S. federal income tax treatment of the transaction.<br>