
UPDATE ON THE COMPREHENSIVE STUDENT FUNDING MODEL

Description: UPDATE ON THE COMPREHENSIVE STUDENT FUNDING MODEL PHASE 1 Presentation to the Portfolio Committee on Higher Education and Training 20 AUGUST 2024 BACKGROUND A Ministerial Task Team (MTT) was appointed in June 2021 to support the DHET and
Related Topics
Download Presentation
"UPDATE ON THE COMPREHENSIVE STUDENT FUNDING MODEL" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. UPDATE ON THE COMPREHENSIVE STUDENT FUNDING MODEL PHASE 1 Presentation to the Portfolio Committee on Higher Education and Training
20 AUGUST 2024<br>
slide2. BACKGROUND A Ministerial Task Team (MTT) was appointed in June 2021 to support the DHET and National Treasury to configure a new student financial funding model for the higher education and training sector and 18 recommendations were tabled to Cabinet in June 2022 and three options were proposed:
Option 1 (Status Quo) - Government fully subsidised model for poor.
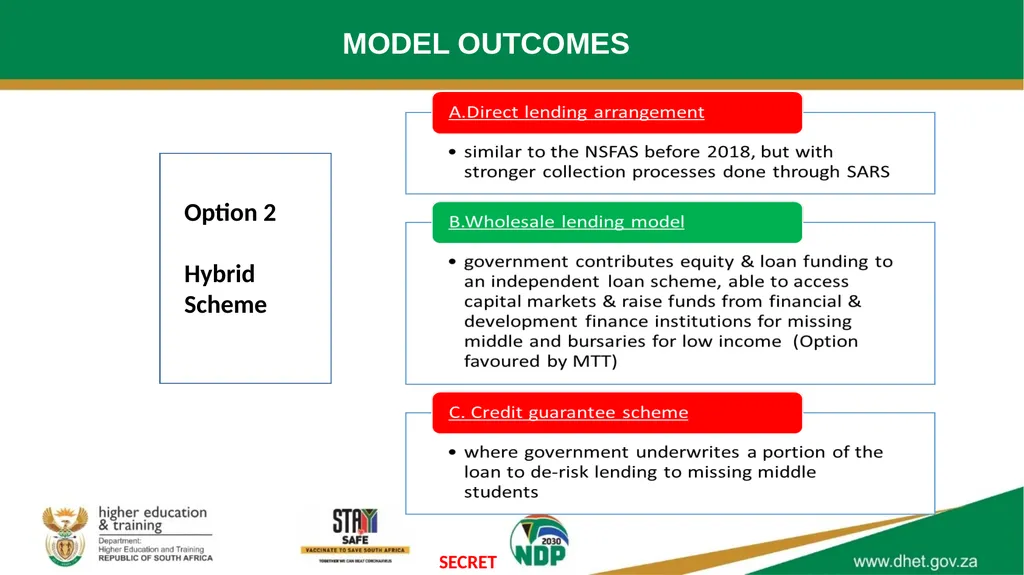
Option 2 (Hybrid) - Combination of a loan/bursary model that uses income thresholds to determine for which financial instrument a student qualifies. This model would explore different loan models, including a direct lending model (2a), wholesale lending model (2b) and credit guarantees (2c).
Option 3 (Modified Status Quo) - fully subsidised model with a range of controls that limit the number of students funded
MTT supported Option 2 favouring a wholesale lending model (loan scheme supported by public and private funds) SECRET 2<br>
slide3. The MTT explored three high level policy models, supported by financial models, to guide the decision-making about its final recommendations.
Option 1 (Status Quo) models the funding requirement if Government continues with the fully subsidised model. As a result of additional funding made available to NSFAS in the 2022/23 MTEF, expenditure matches funding.
Option 2 (Hybrid) estimates the use of a combined loan/bursary model that uses income thresholds to determine for which financial instrument a student qualifies. Different loan models are explored in the models, including a direct lending model, wholesale lending model and credit guarantees.
Option 3 (Modified Status Quo) models the fully subsidised model but with a range of controls that limit the number of students funded and focus on efficiency. This option estimates the implications of higher course pass rates, capped accommodation allowances, constrained growth in other allowances, and slower than inflation increases.
Option 2 is the option being explored BACKGROUND (2)<br>
slide4. MODEL OUTCOMES SECRET 4 Option 2
Hybrid Scheme<br>
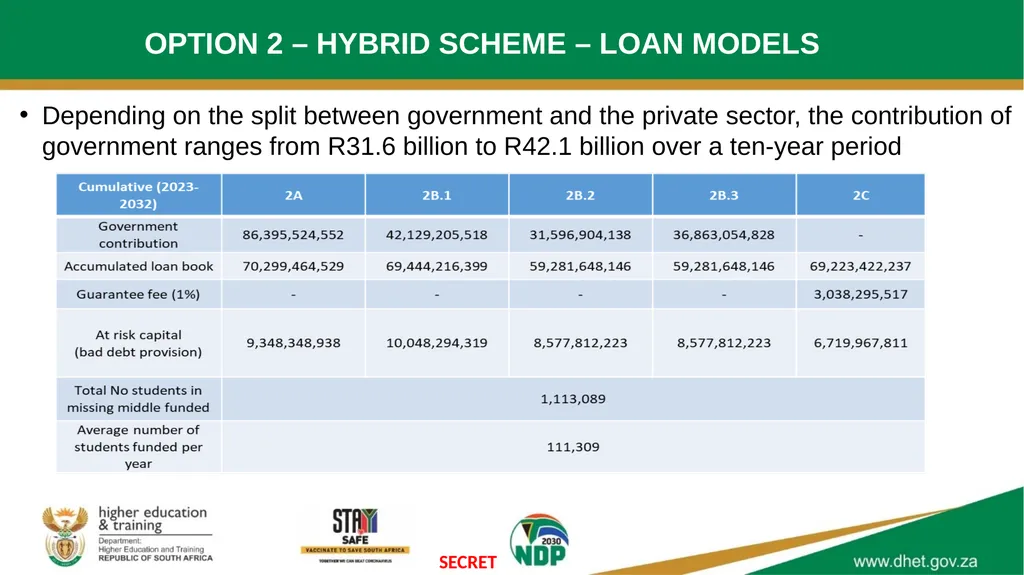
slide5. OPTION 2 – HYBRID SCHEME – LOAN MODELS Depending on the split between government and the private sector, the contribution of government ranges from R31.6 billion to R42.1 billion over a ten-year period SECRET 5<br>
slide6. Diagrammatic Representation of Option 2 6<br>
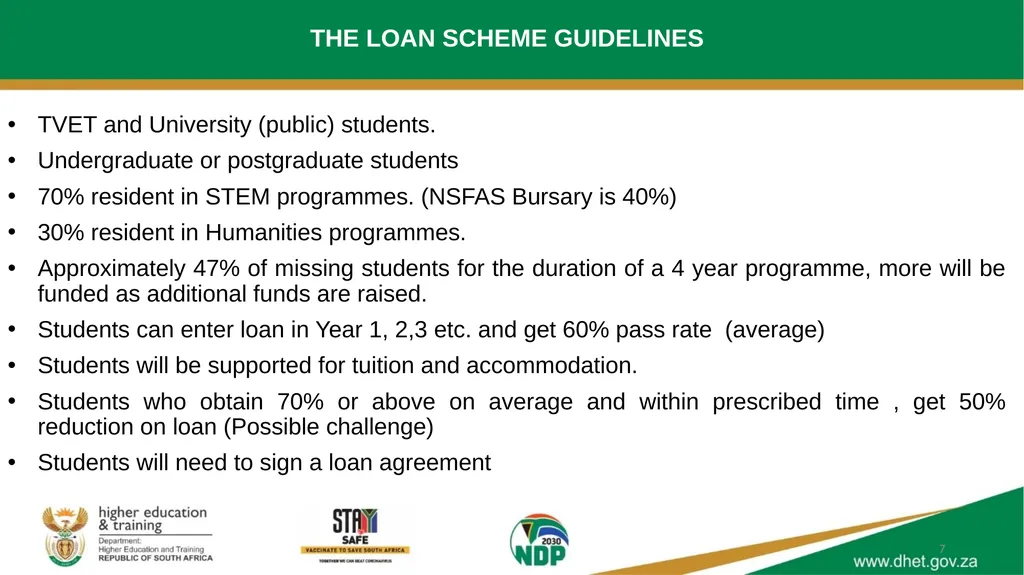
slide7. THE LOAN SCHEME GUIDELINES TVET and University (public) students.
Undergraduate or postgraduate students
70% resident in STEM programmes. (NSFAS Bursary is 40%)
30% resident in Humanities programmes.
Approximately 47% of missing students for the duration of a 4 year programme, more will be funded as additional funds are raised.
Students can enter loan in Year 1, 2,3 etc. and get 60% pass rate (average)
Students will be supported for tuition and accommodation.
Students who obtain 70% or above on average and within prescribed time , get 50% reduction on loan (Possible challenge)
Students will need to sign a loan agreement 7<br>
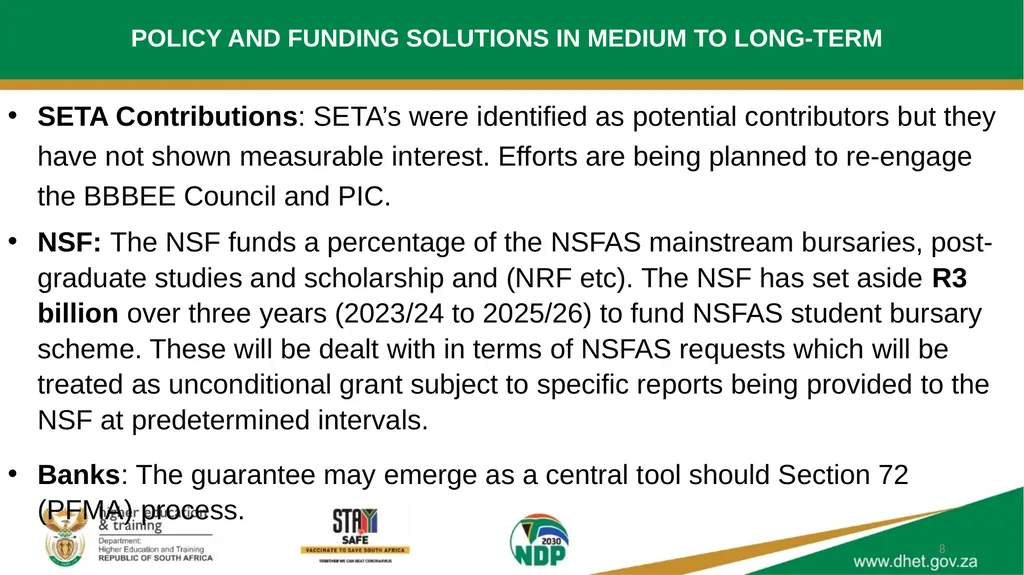
slide8. POLICY AND FUNDING SOLUTIONS IN MEDIUM TO LONG-TERM SETA Contributions: SETA’s were identified as potential contributors but they have not shown measurable interest. Efforts are being planned to re-engage the BBBEE Council and PIC.
NSF: The NSF funds a percentage of the NSFAS mainstream bursaries, post-graduate studies and scholarship and (NRF etc). The NSF has set aside R3 billion over three years (2023/24 to 2025/26) to fund NSFAS student bursary scheme. These will be dealt with in terms of NSFAS requests which will be treated as unconditional grant subject to specific reports being provided to the NSF at predetermined intervals.
Banks: The guarantee may emerge as a central tool should Section 72 (PFMA) process. 8<br>
slide9. CONSULTATIONS WITH THE BANKS Given the fiscal constraints, the Department also consulted the Banking Industry, specifically the Banking Association of South Africa (BASA).
NT Officials advised that BASA must engage with the Department and explained that it is the DHET who will submit a formal proposal to the Fiscal Liability Committee (FLC) in the NT. A decision would then taken by the Minister of Finance after recommendations by the FLC. Once approved, NT will conduct oversight on the execution of the project.
Based on these discussions, BASA developed an NDA which has been signed by the Department to protect the data shared by the banks.<br>
slide10. PROGRESS TO DATE Loan scheme guidelines were finalized in January 2024 following cabinet approval of the scheme and after extensive consultations with several stakeholders. The stakeholders in 2023 included:
Public Investment Corporation, Department of Trade Industry and Competition, NT, BASA, NEDLAC, ISFAP, Public Protector, COSATU, SADTU, SAUS, USAF, DTIC, BBBEE Commission, COGTA, Chancellors Forum, SAHRC, and Nehawu.
On 2 February 2024, NSFAS opened loan applications.
On 15 February 2024, NSFAS applications were closed.
More than 31000 applications were received , 6700 SASSA applications were withdrawn as they did not meet the criteria.<br>
slide11. CRITERIA Accepting the NSFAS loan funding will require a beneficiary to pay back the funds in monetary terms. The beneficiary must maintain certain academic conditions/criteria requirements for the duration of the study period. The loan is renewed annually based on the student meeting the academic requirements as set and to the extent that there is available budget.
NSFAS seeks to provide ongoing financial aid in the form of a loan to students only if the criteria for continued support are met and there is sufficient budget available. As such, continued funding is NOT guaranteed and students who are funded by NSFAS are expected to meet ongoing eligibility criteria to continue receiving financial aid loan support from NSFAS.
Loans are interest-free during the study period and will start accruing 12 months after the date of exit. The term of the loan repayment is determined at maximum period of (60) months from the date of employment. Interest rate will be charged at rate calculated as the prime lending rate prevailing at 01 April annually less 100 basis points..
Loans may be allocated to cover the study-related costs and may include students’ course/ tuition fees, accommodation and learning material allowance.<br>
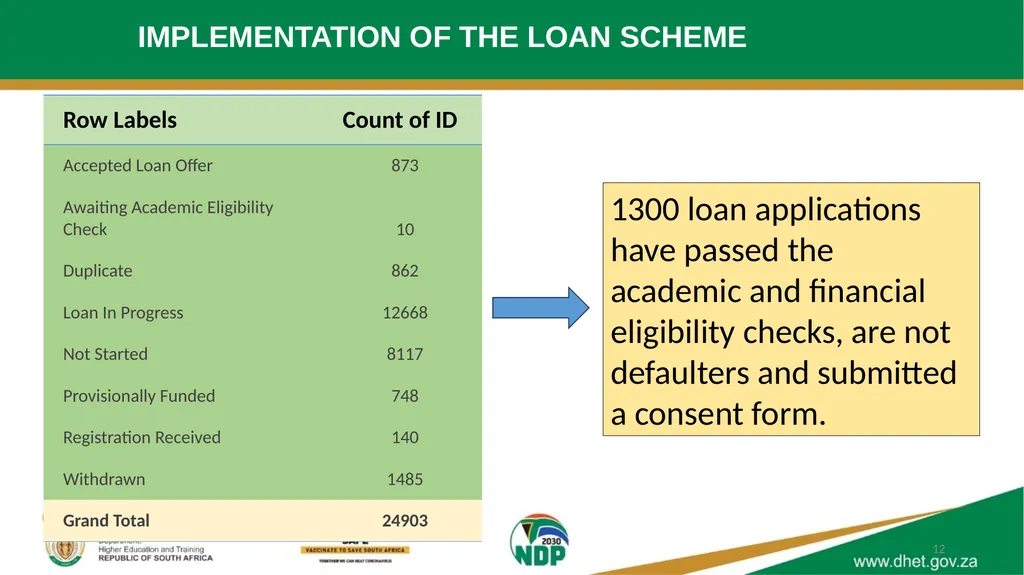
slide12. Progress reported to date IMPLEMENTATION OF THE LOAN SCHEME 12 1300 loan applications have passed the academic and financial eligibility checks, are not defaulters and submitted a consent form.<br>
slide13. NSFAS NEXT STEPS 1 300 applicants will be shared with Universities and TVET Colleges.
Once institutions have processed the list of applicants, they will be returned to NSFAS.
NSFAS will start funding those who have been validated.
The above processes are dependent on signing of an MOU between NSFAS and Universities; and signing of an agreement between applicant and NSFAS.
Target for the 2024 financial year is 15 000 loan beneficiaries split as follows:
10 000 University applicant
5 000 TVET College applicant
Cost is 950 000 000 for 2024<br>
slide14. NATIONAL TREASURY PROCESSES: SECTION 72 STEP 1:
Applicant submits request for a guarantee to its Executive Authority/the responsible Minister. Upon approval, the responsible Minister forwards request to the Minister of Finance. Request must cover the following issues:
A description of the project and profile of applicant; Proposal; Rationale; Financial analysis; Impact of activity to be supported by guarantee or transaction on the applicant; Industry/Sector analysis; Broader government imperatives such as economic development, employment and economic growth; Legal implications, if any; and the duration of the financing, guarantee or transaction must be specified.<br>
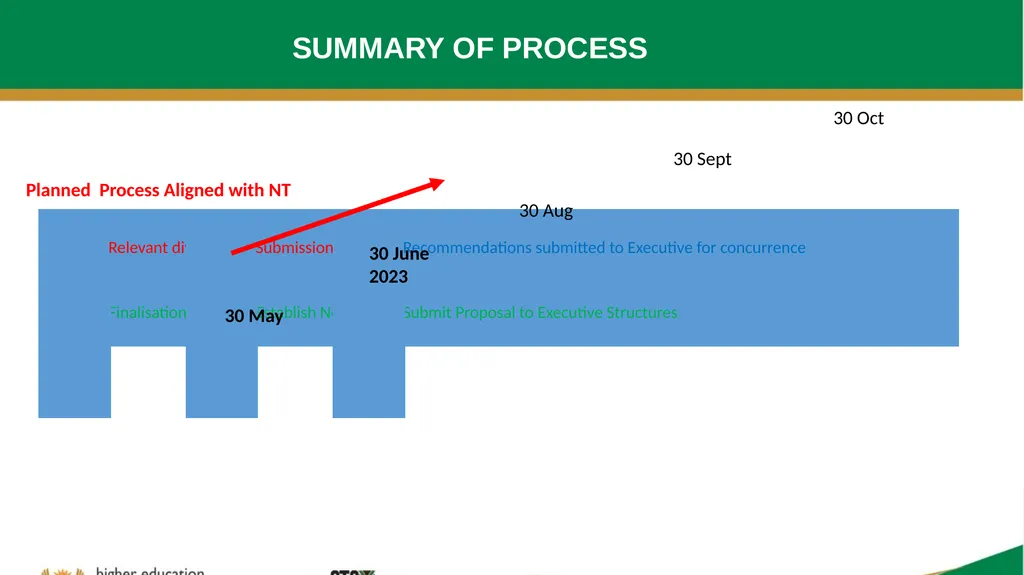
slide15. SUMMARY OF PROCESS 30 May 30 June 2023 30 Aug Planned Process Aligned with NT 30 Sept 30 Oct<br>
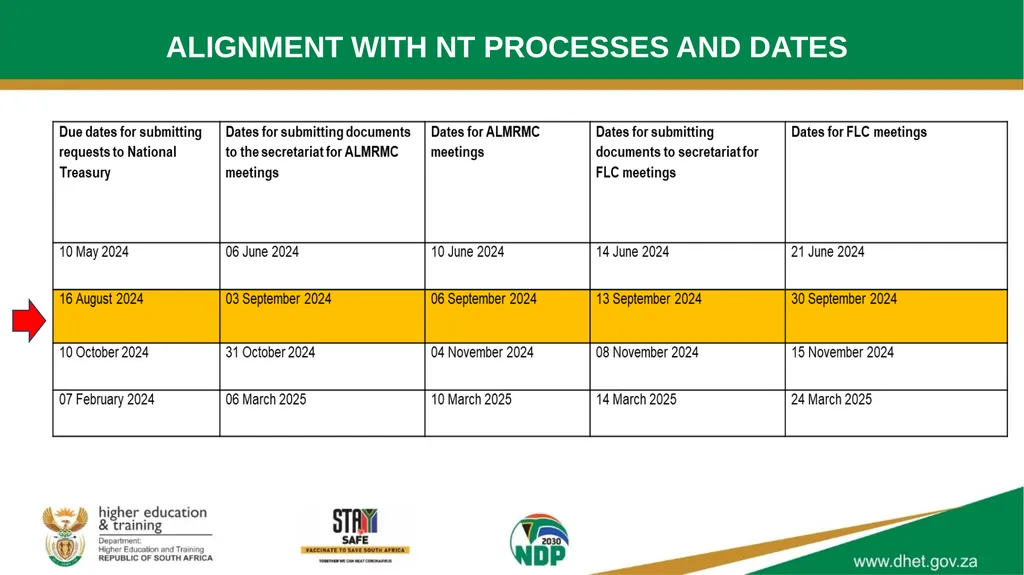
slide16. ALIGNMENT WITH NT PROCESSES AND DATES<br>
20 AUGUST 2024<br>
slide2. BACKGROUND A Ministerial Task Team (MTT) was appointed in June 2021 to support the DHET and National Treasury to configure a new student financial funding model for the higher education and training sector and 18 recommendations were tabled to Cabinet in June 2022 and three options were proposed:
Option 1 (Status Quo) - Government fully subsidised model for poor.
Option 2 (Hybrid) - Combination of a loan/bursary model that uses income thresholds to determine for which financial instrument a student qualifies. This model would explore different loan models, including a direct lending model (2a), wholesale lending model (2b) and credit guarantees (2c).
Option 3 (Modified Status Quo) - fully subsidised model with a range of controls that limit the number of students funded
MTT supported Option 2 favouring a wholesale lending model (loan scheme supported by public and private funds) SECRET 2<br>
slide3. The MTT explored three high level policy models, supported by financial models, to guide the decision-making about its final recommendations.
Option 1 (Status Quo) models the funding requirement if Government continues with the fully subsidised model. As a result of additional funding made available to NSFAS in the 2022/23 MTEF, expenditure matches funding.
Option 2 (Hybrid) estimates the use of a combined loan/bursary model that uses income thresholds to determine for which financial instrument a student qualifies. Different loan models are explored in the models, including a direct lending model, wholesale lending model and credit guarantees.
Option 3 (Modified Status Quo) models the fully subsidised model but with a range of controls that limit the number of students funded and focus on efficiency. This option estimates the implications of higher course pass rates, capped accommodation allowances, constrained growth in other allowances, and slower than inflation increases.
Option 2 is the option being explored BACKGROUND (2)<br>
slide4. MODEL OUTCOMES SECRET 4 Option 2
Hybrid Scheme<br>
slide5. OPTION 2 – HYBRID SCHEME – LOAN MODELS Depending on the split between government and the private sector, the contribution of government ranges from R31.6 billion to R42.1 billion over a ten-year period SECRET 5<br>
slide6. Diagrammatic Representation of Option 2 6<br>
slide7. THE LOAN SCHEME GUIDELINES TVET and University (public) students.
Undergraduate or postgraduate students
70% resident in STEM programmes. (NSFAS Bursary is 40%)
30% resident in Humanities programmes.
Approximately 47% of missing students for the duration of a 4 year programme, more will be funded as additional funds are raised.
Students can enter loan in Year 1, 2,3 etc. and get 60% pass rate (average)
Students will be supported for tuition and accommodation.
Students who obtain 70% or above on average and within prescribed time , get 50% reduction on loan (Possible challenge)
Students will need to sign a loan agreement 7<br>
slide8. POLICY AND FUNDING SOLUTIONS IN MEDIUM TO LONG-TERM SETA Contributions: SETA’s were identified as potential contributors but they have not shown measurable interest. Efforts are being planned to re-engage the BBBEE Council and PIC.
NSF: The NSF funds a percentage of the NSFAS mainstream bursaries, post-graduate studies and scholarship and (NRF etc). The NSF has set aside R3 billion over three years (2023/24 to 2025/26) to fund NSFAS student bursary scheme. These will be dealt with in terms of NSFAS requests which will be treated as unconditional grant subject to specific reports being provided to the NSF at predetermined intervals.
Banks: The guarantee may emerge as a central tool should Section 72 (PFMA) process. 8<br>
slide9. CONSULTATIONS WITH THE BANKS Given the fiscal constraints, the Department also consulted the Banking Industry, specifically the Banking Association of South Africa (BASA).
NT Officials advised that BASA must engage with the Department and explained that it is the DHET who will submit a formal proposal to the Fiscal Liability Committee (FLC) in the NT. A decision would then taken by the Minister of Finance after recommendations by the FLC. Once approved, NT will conduct oversight on the execution of the project.
Based on these discussions, BASA developed an NDA which has been signed by the Department to protect the data shared by the banks.<br>
slide10. PROGRESS TO DATE Loan scheme guidelines were finalized in January 2024 following cabinet approval of the scheme and after extensive consultations with several stakeholders. The stakeholders in 2023 included:
Public Investment Corporation, Department of Trade Industry and Competition, NT, BASA, NEDLAC, ISFAP, Public Protector, COSATU, SADTU, SAUS, USAF, DTIC, BBBEE Commission, COGTA, Chancellors Forum, SAHRC, and Nehawu.
On 2 February 2024, NSFAS opened loan applications.
On 15 February 2024, NSFAS applications were closed.
More than 31000 applications were received , 6700 SASSA applications were withdrawn as they did not meet the criteria.<br>
slide11. CRITERIA Accepting the NSFAS loan funding will require a beneficiary to pay back the funds in monetary terms. The beneficiary must maintain certain academic conditions/criteria requirements for the duration of the study period. The loan is renewed annually based on the student meeting the academic requirements as set and to the extent that there is available budget.
NSFAS seeks to provide ongoing financial aid in the form of a loan to students only if the criteria for continued support are met and there is sufficient budget available. As such, continued funding is NOT guaranteed and students who are funded by NSFAS are expected to meet ongoing eligibility criteria to continue receiving financial aid loan support from NSFAS.
Loans are interest-free during the study period and will start accruing 12 months after the date of exit. The term of the loan repayment is determined at maximum period of (60) months from the date of employment. Interest rate will be charged at rate calculated as the prime lending rate prevailing at 01 April annually less 100 basis points..
Loans may be allocated to cover the study-related costs and may include students’ course/ tuition fees, accommodation and learning material allowance.<br>
slide12. Progress reported to date IMPLEMENTATION OF THE LOAN SCHEME 12 1300 loan applications have passed the academic and financial eligibility checks, are not defaulters and submitted a consent form.<br>
slide13. NSFAS NEXT STEPS 1 300 applicants will be shared with Universities and TVET Colleges.
Once institutions have processed the list of applicants, they will be returned to NSFAS.
NSFAS will start funding those who have been validated.
The above processes are dependent on signing of an MOU between NSFAS and Universities; and signing of an agreement between applicant and NSFAS.
Target for the 2024 financial year is 15 000 loan beneficiaries split as follows:
10 000 University applicant
5 000 TVET College applicant
Cost is 950 000 000 for 2024<br>
slide14. NATIONAL TREASURY PROCESSES: SECTION 72 STEP 1:
Applicant submits request for a guarantee to its Executive Authority/the responsible Minister. Upon approval, the responsible Minister forwards request to the Minister of Finance. Request must cover the following issues:
A description of the project and profile of applicant; Proposal; Rationale; Financial analysis; Impact of activity to be supported by guarantee or transaction on the applicant; Industry/Sector analysis; Broader government imperatives such as economic development, employment and economic growth; Legal implications, if any; and the duration of the financing, guarantee or transaction must be specified.<br>
slide15. SUMMARY OF PROCESS 30 May 30 June 2023 30 Aug Planned Process Aligned with NT 30 Sept 30 Oct<br>
slide16. ALIGNMENT WITH NT PROCESSES AND DATES<br>