
Week 33 Review We saw a lot of negative sentiment

Description: Week 33 Review We saw a lot of negative sentiment last week USChina trade war, possible Chinese intervention in Honk Kong; Italian elections and a possible show-down with EU; the risk of an Argentinian default; US 2- and 10- year yield
Related Topics
Download Presentation
"Week 33 Review We saw a lot of negative sentiment" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
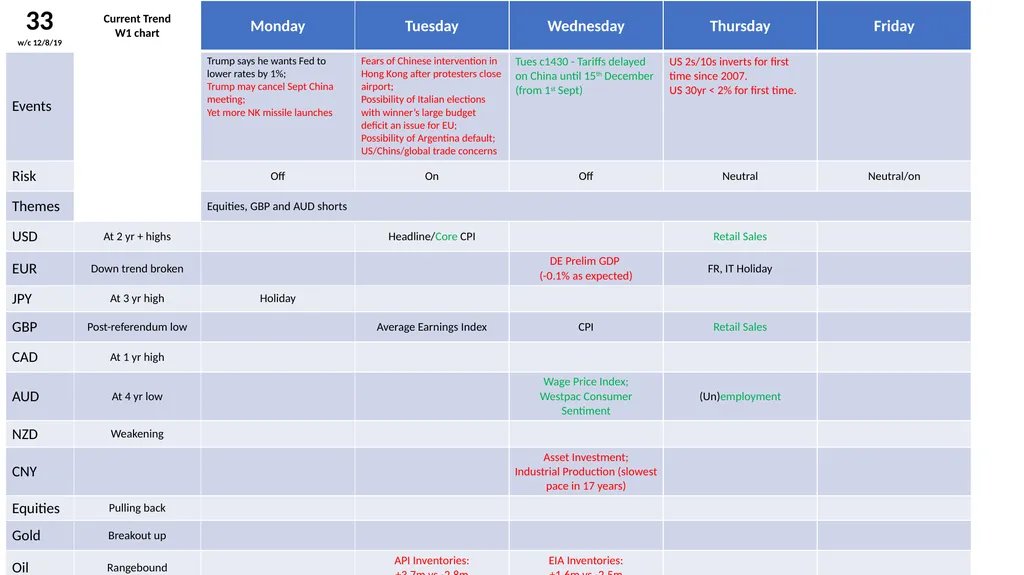
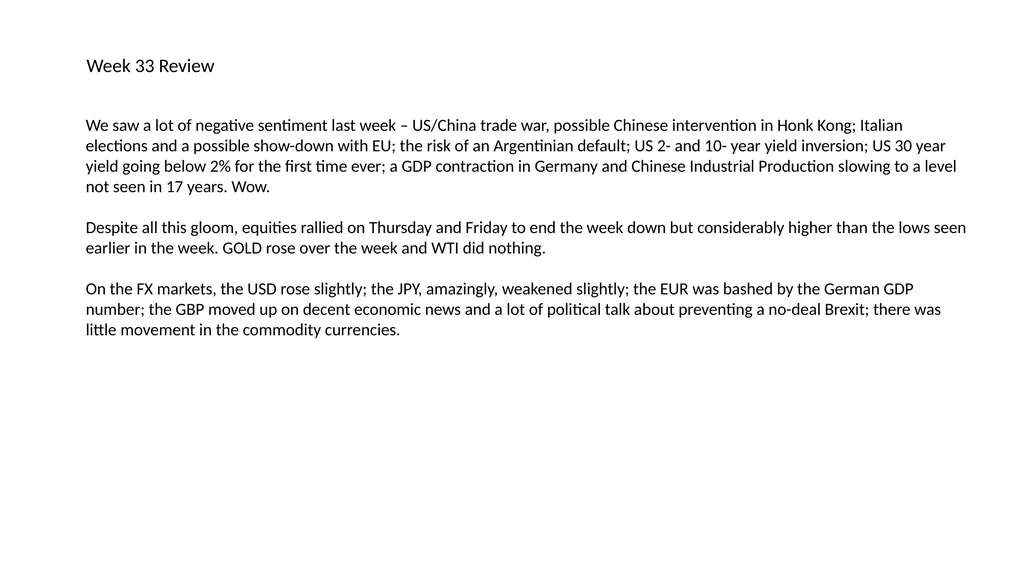
slide2. Week 33 Review We saw a lot of negative sentiment last week – US/China trade war, possible Chinese intervention in Honk Kong; Italian elections and a possible show-down with EU; the risk of an Argentinian default; US 2- and 10- year yield inversion; US 30 year yield going below 2% for the first time ever; a GDP contraction in Germany and Chinese Industrial Production slowing to a level not seen in 17 years. Wow.
Despite all this gloom, equities rallied on Thursday and Friday to end the week down but considerably higher than the lows seen earlier in the week. GOLD rose over the week and WTI did nothing.
On the FX markets, the USD rose slightly; the JPY, amazingly, weakened slightly; the EUR was bashed by the German GDP number; the GBP moved up on decent economic news and a lot of political talk about preventing a no-deal Brexit; there was little movement in the commodity currencies.<br>
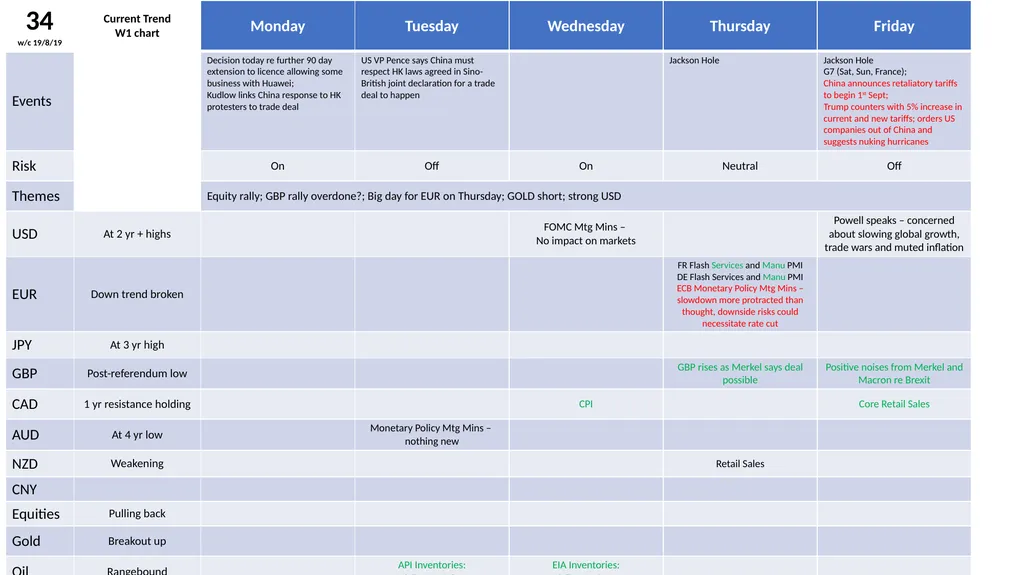
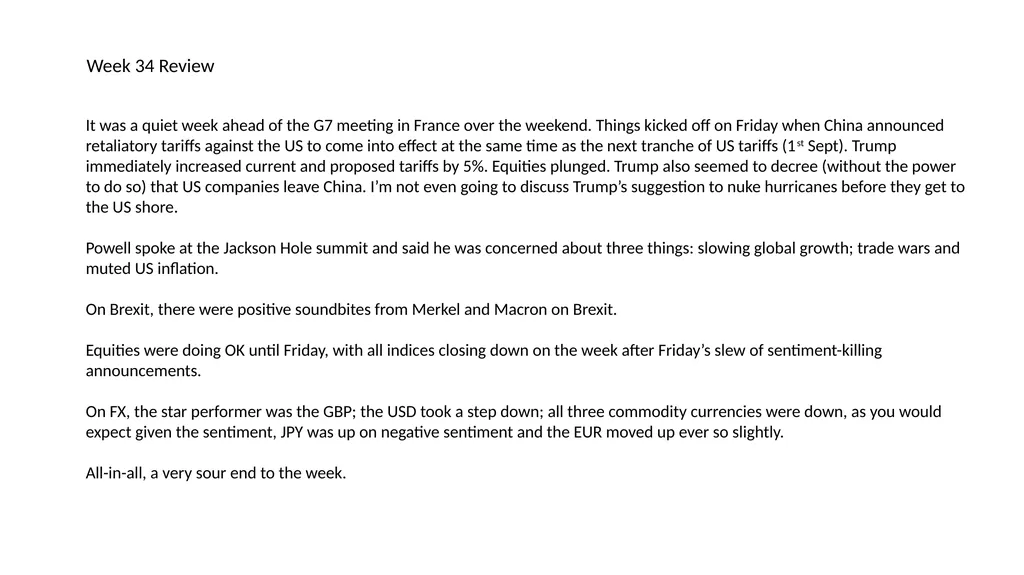
slide4. Week 34 Review It was a quiet week ahead of the G7 meeting in France over the weekend. Things kicked off on Friday when China announced retaliatory tariffs against the US to come into effect at the same time as the next tranche of US tariffs (1st Sept). Trump immediately increased current and proposed tariffs by 5%. Equities plunged. Trump also seemed to decree (without the power to do so) that US companies leave China. I’m not even going to discuss Trump’s suggestion to nuke hurricanes before they get to the US shore.
Powell spoke at the Jackson Hole summit and said he was concerned about three things: slowing global growth; trade wars and muted US inflation.
On Brexit, there were positive soundbites from Merkel and Macron on Brexit.
Equities were doing OK until Friday, with all indices closing down on the week after Friday’s slew of sentiment-killing announcements.
On FX, the star performer was the GBP; the USD took a step down; all three commodity currencies were down, as you would expect given the sentiment, JPY was up on negative sentiment and the EUR moved up ever so slightly.
All-in-all, a very sour end to the week.<br>
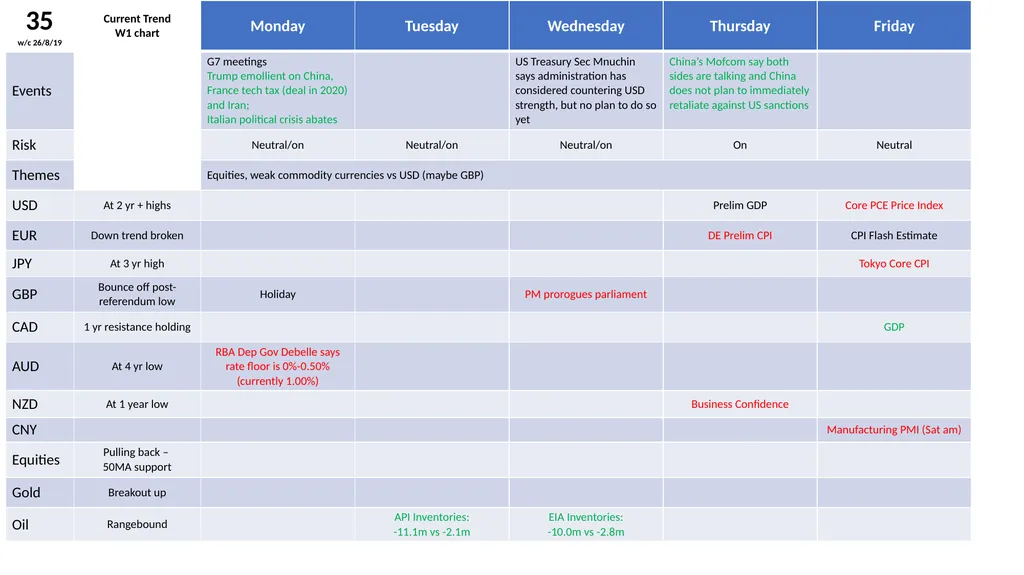
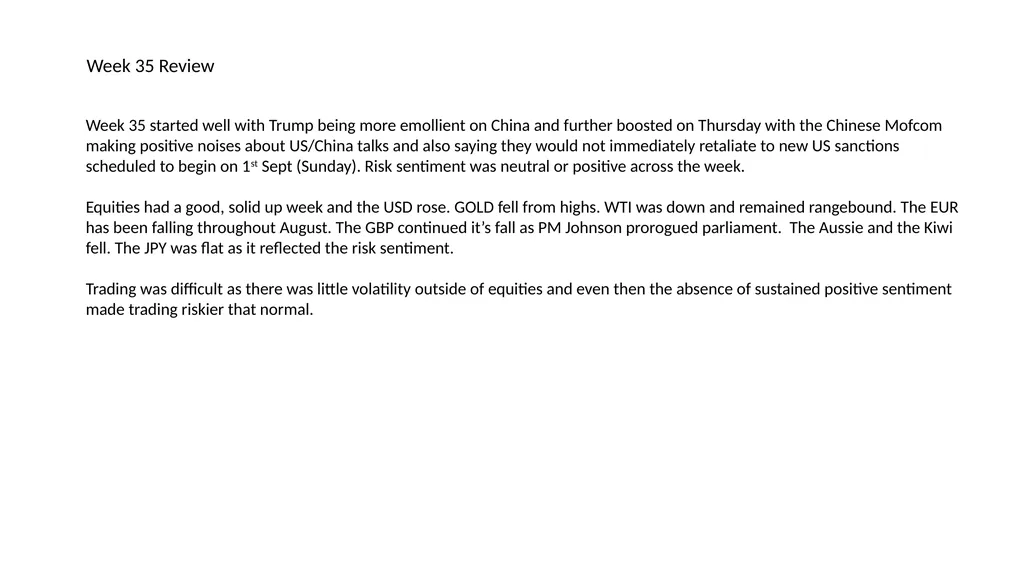
slide6. Week 35 Review Week 35 started well with Trump being more emollient on China and further boosted on Thursday with the Chinese Mofcom making positive noises about US/China talks and also saying they would not immediately retaliate to new US sanctions scheduled to begin on 1st Sept (Sunday). Risk sentiment was neutral or positive across the week.
Equities had a good, solid up week and the USD rose. GOLD fell from highs. WTI was down and remained rangebound. The EUR has been falling throughout August. The GBP continued it’s fall as PM Johnson prorogued parliament. The Aussie and the Kiwi fell. The JPY was flat as it reflected the risk sentiment.
Trading was difficult as there was little volatility outside of equities and even then the absence of sustained positive sentiment made trading riskier that normal.<br>
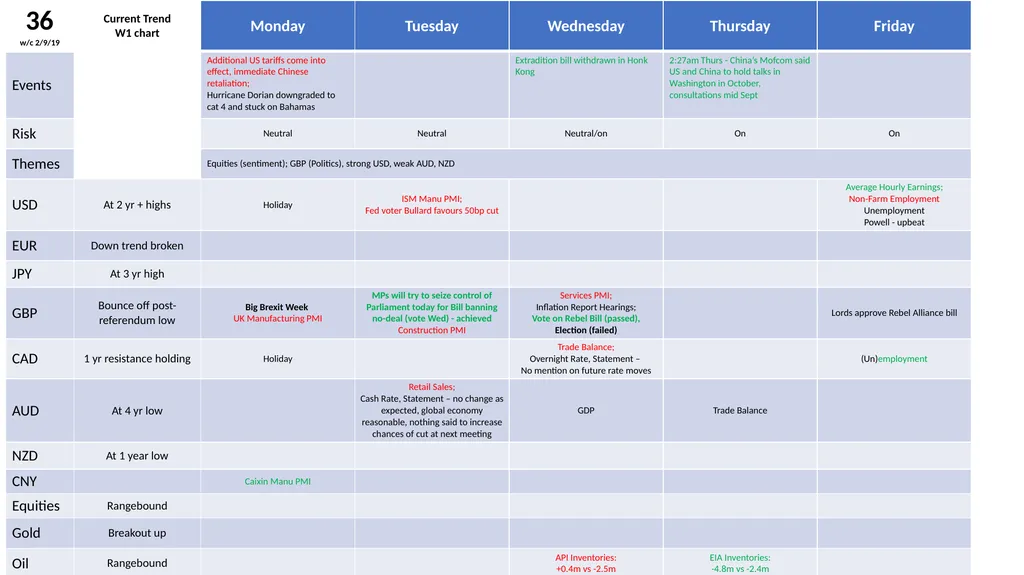
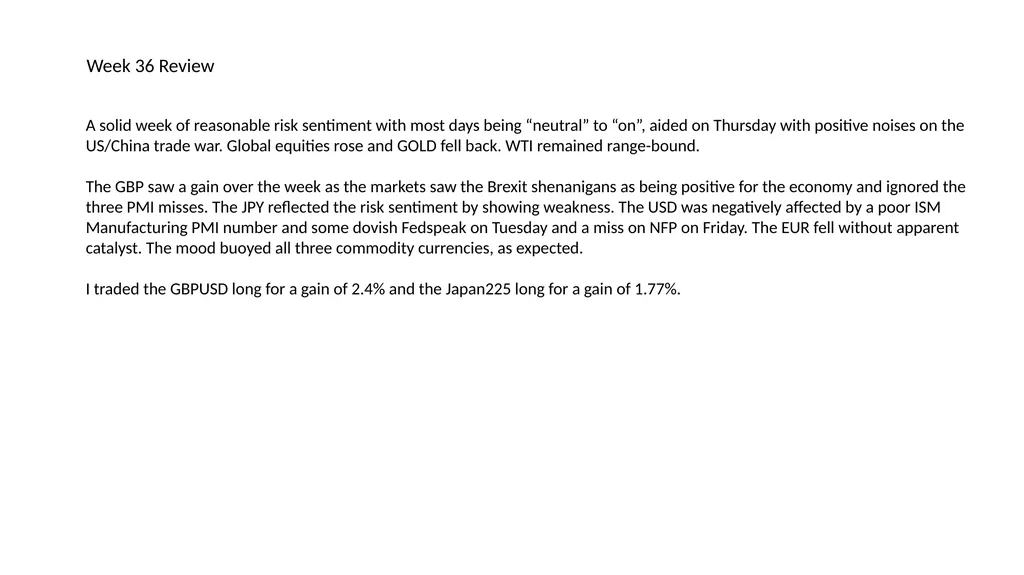
slide8. Week 36 Review A solid week of reasonable risk sentiment with most days being “neutral” to “on”, aided on Thursday with positive noises on the US/China trade war. Global equities rose and GOLD fell back. WTI remained range-bound.
The GBP saw a gain over the week as the markets saw the Brexit shenanigans as being positive for the economy and ignored the three PMI misses. The JPY reflected the risk sentiment by showing weakness. The USD was negatively affected by a poor ISM Manufacturing PMI number and some dovish Fedspeak on Tuesday and a miss on NFP on Friday. The EUR fell without apparent catalyst. The mood buoyed all three commodity currencies, as expected.
I traded the GBPUSD long for a gain of 2.4% and the Japan225 long for a gain of 1.77%.<br>
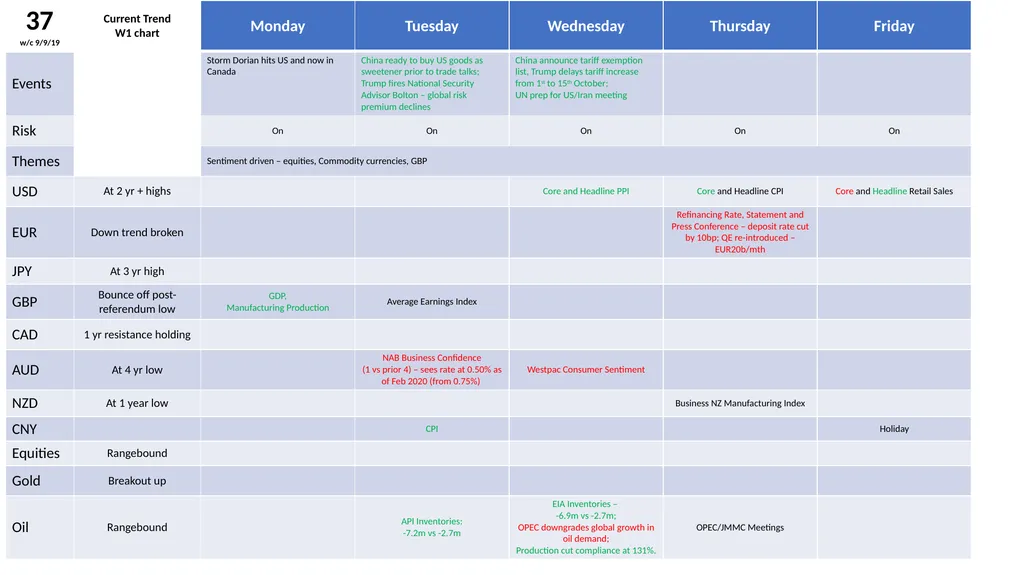
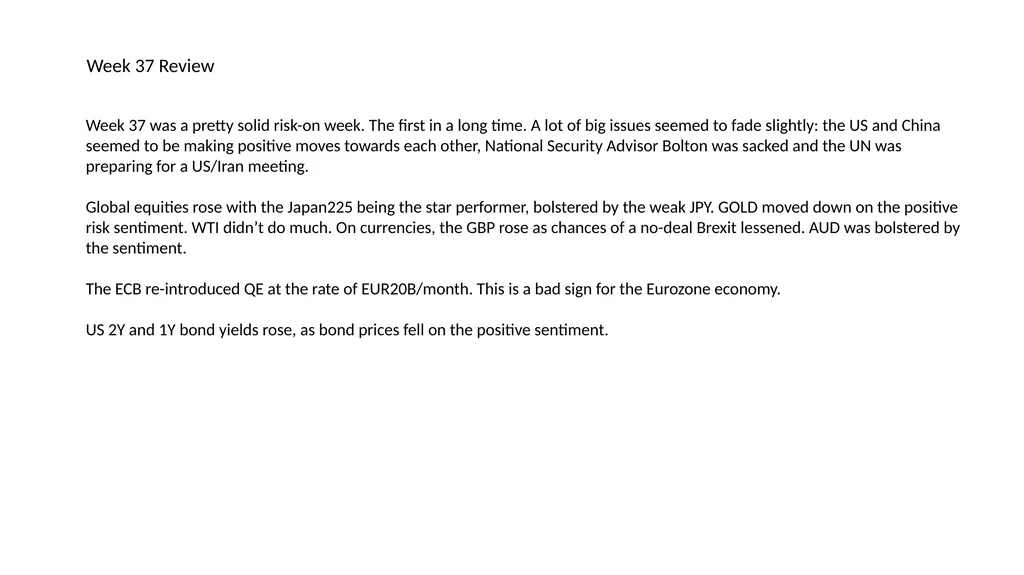
slide10. Week 37 Review Week 37 was a pretty solid risk-on week. The first in a long time. A lot of big issues seemed to fade slightly: the US and China seemed to be making positive moves towards each other, National Security Advisor Bolton was sacked and the UN was preparing for a US/Iran meeting.
Global equities rose with the Japan225 being the star performer, bolstered by the weak JPY. GOLD moved down on the positive risk sentiment. WTI didn’t do much. On currencies, the GBP rose as chances of a no-deal Brexit lessened. AUD was bolstered by the sentiment.
The ECB re-introduced QE at the rate of EUR20B/month. This is a bad sign for the Eurozone economy.
US 2Y and 1Y bond yields rose, as bond prices fell on the positive sentiment.<br>
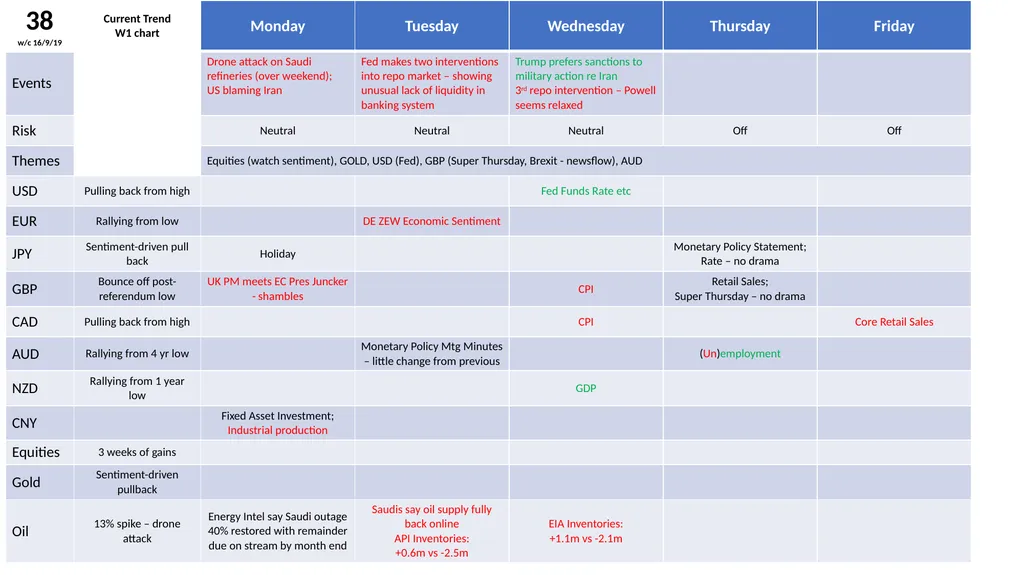
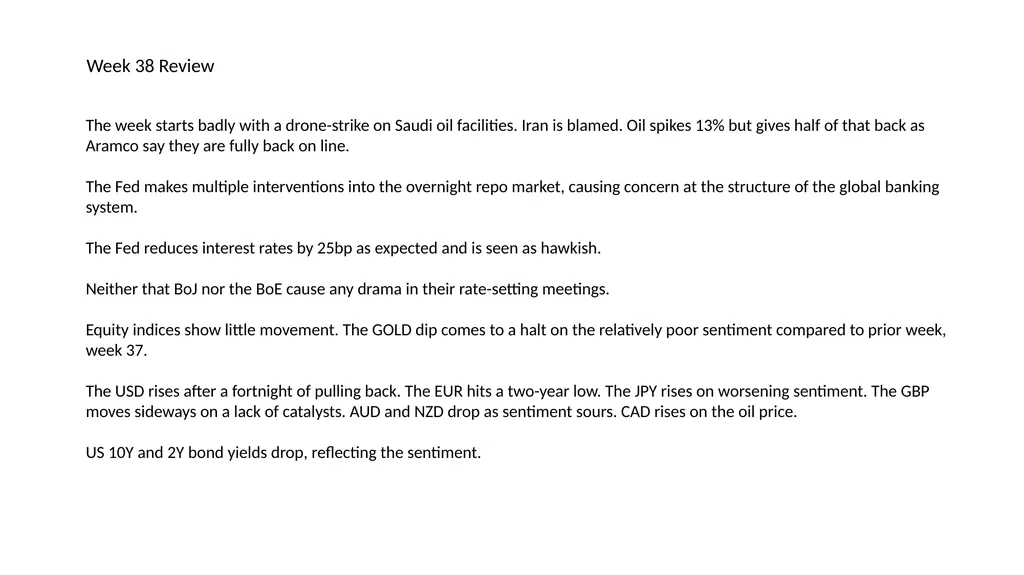
slide13. Week 38 Review The week starts badly with a drone-strike on Saudi oil facilities. Iran is blamed. Oil spikes 13% but gives half of that back as Aramco say they are fully back on line.
The Fed makes multiple interventions into the overnight repo market, causing concern at the structure of the global banking system.
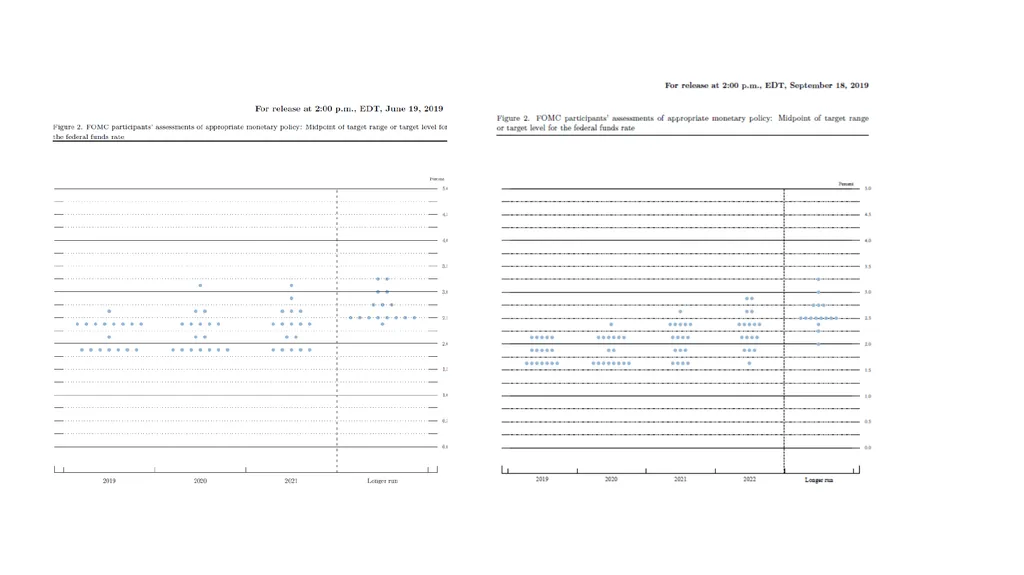
The Fed reduces interest rates by 25bp as expected and is seen as hawkish.
Neither that BoJ nor the BoE cause any drama in their rate-setting meetings.
Equity indices show little movement. The GOLD dip comes to a halt on the relatively poor sentiment compared to prior week, week 37.
The USD rises after a fortnight of pulling back. The EUR hits a two-year low. The JPY rises on worsening sentiment. The GBP moves sideways on a lack of catalysts. AUD and NZD drop as sentiment sours. CAD rises on the oil price.
US 10Y and 2Y bond yields drop, reflecting the sentiment.<br>
Despite all this gloom, equities rallied on Thursday and Friday to end the week down but considerably higher than the lows seen earlier in the week. GOLD rose over the week and WTI did nothing.
On the FX markets, the USD rose slightly; the JPY, amazingly, weakened slightly; the EUR was bashed by the German GDP number; the GBP moved up on decent economic news and a lot of political talk about preventing a no-deal Brexit; there was little movement in the commodity currencies.<br>
slide4. Week 34 Review It was a quiet week ahead of the G7 meeting in France over the weekend. Things kicked off on Friday when China announced retaliatory tariffs against the US to come into effect at the same time as the next tranche of US tariffs (1st Sept). Trump immediately increased current and proposed tariffs by 5%. Equities plunged. Trump also seemed to decree (without the power to do so) that US companies leave China. I’m not even going to discuss Trump’s suggestion to nuke hurricanes before they get to the US shore.
Powell spoke at the Jackson Hole summit and said he was concerned about three things: slowing global growth; trade wars and muted US inflation.
On Brexit, there were positive soundbites from Merkel and Macron on Brexit.
Equities were doing OK until Friday, with all indices closing down on the week after Friday’s slew of sentiment-killing announcements.
On FX, the star performer was the GBP; the USD took a step down; all three commodity currencies were down, as you would expect given the sentiment, JPY was up on negative sentiment and the EUR moved up ever so slightly.
All-in-all, a very sour end to the week.<br>
slide6. Week 35 Review Week 35 started well with Trump being more emollient on China and further boosted on Thursday with the Chinese Mofcom making positive noises about US/China talks and also saying they would not immediately retaliate to new US sanctions scheduled to begin on 1st Sept (Sunday). Risk sentiment was neutral or positive across the week.
Equities had a good, solid up week and the USD rose. GOLD fell from highs. WTI was down and remained rangebound. The EUR has been falling throughout August. The GBP continued it’s fall as PM Johnson prorogued parliament. The Aussie and the Kiwi fell. The JPY was flat as it reflected the risk sentiment.
Trading was difficult as there was little volatility outside of equities and even then the absence of sustained positive sentiment made trading riskier that normal.<br>
slide8. Week 36 Review A solid week of reasonable risk sentiment with most days being “neutral” to “on”, aided on Thursday with positive noises on the US/China trade war. Global equities rose and GOLD fell back. WTI remained range-bound.
The GBP saw a gain over the week as the markets saw the Brexit shenanigans as being positive for the economy and ignored the three PMI misses. The JPY reflected the risk sentiment by showing weakness. The USD was negatively affected by a poor ISM Manufacturing PMI number and some dovish Fedspeak on Tuesday and a miss on NFP on Friday. The EUR fell without apparent catalyst. The mood buoyed all three commodity currencies, as expected.
I traded the GBPUSD long for a gain of 2.4% and the Japan225 long for a gain of 1.77%.<br>
slide10. Week 37 Review Week 37 was a pretty solid risk-on week. The first in a long time. A lot of big issues seemed to fade slightly: the US and China seemed to be making positive moves towards each other, National Security Advisor Bolton was sacked and the UN was preparing for a US/Iran meeting.
Global equities rose with the Japan225 being the star performer, bolstered by the weak JPY. GOLD moved down on the positive risk sentiment. WTI didn’t do much. On currencies, the GBP rose as chances of a no-deal Brexit lessened. AUD was bolstered by the sentiment.
The ECB re-introduced QE at the rate of EUR20B/month. This is a bad sign for the Eurozone economy.
US 2Y and 1Y bond yields rose, as bond prices fell on the positive sentiment.<br>
slide13. Week 38 Review The week starts badly with a drone-strike on Saudi oil facilities. Iran is blamed. Oil spikes 13% but gives half of that back as Aramco say they are fully back on line.
The Fed makes multiple interventions into the overnight repo market, causing concern at the structure of the global banking system.
The Fed reduces interest rates by 25bp as expected and is seen as hawkish.
Neither that BoJ nor the BoE cause any drama in their rate-setting meetings.
Equity indices show little movement. The GOLD dip comes to a halt on the relatively poor sentiment compared to prior week, week 37.
The USD rises after a fortnight of pulling back. The EUR hits a two-year low. The JPY rises on worsening sentiment. The GBP moves sideways on a lack of catalysts. AUD and NZD drop as sentiment sours. CAD rises on the oil price.
US 10Y and 2Y bond yields drop, reflecting the sentiment.<br>