
A New Crew, Falling Rates, Old Questions and New



Description: A New Crew, Falling Rates, Old Questions and New Challenges Inland Northwest Partners October 29, 2024 Spokane Valley, Washington John W. Mitchell Late October Halfway Through Year Five Not The Election We Thought in June-A summer to Tell
Related Topics
Download Presentation
"A New Crew, Falling Rates, Old Questions and New" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. A New Crew, Falling Rates, Old Questions and New Challenges Inland Northwest Partners
October 29, 2024
Spokane Valley, Washington
John W. Mitchell<br>
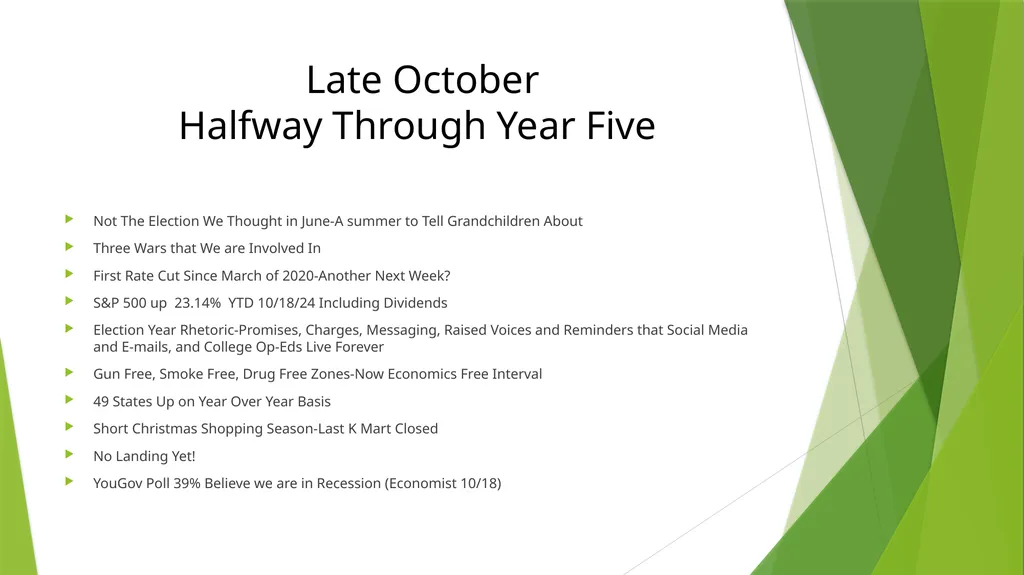
slide2. Late October Halfway Through Year Five Not The Election We Thought in June-A summer to Tell Grandchildren About
Three Wars that We are Involved In
First Rate Cut Since March of 2020-Another Next Week?
S&P 500 up 23.14% YTD 10/18/24 Including Dividends
Election Year Rhetoric-Promises, Charges, Messaging, Raised Voices and Reminders that Social Media and E-mails, and College Op-Eds Live Forever
Gun Free, Smoke Free, Drug Free Zones-Now Economics Free Interval
49 States Up on Year Over Year Basis
Short Christmas Shopping Season-Last K Mart Closed
No Landing Yet!
YouGov Poll 39% Believe we are in Recession (Economist 10/18)<br>
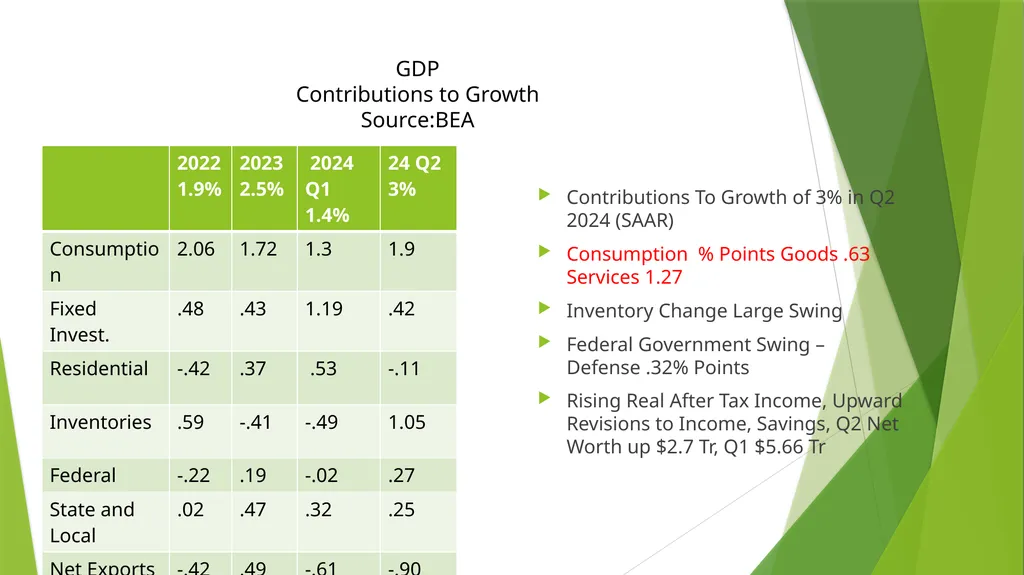
slide3. GDP Contributions to Growth Source:BEA Contributions To Growth of 3% in Q2 2024 (SAAR)
Consumption % Points Goods .63 Services 1.27
Inventory Change Large Swing
Federal Government Swing –Defense .32% Points
Rising Real After Tax Income, Upward Revisions to Income, Savings, Q2 Net Worth up $2.7 Tr, Q1 $5.66 Tr<br>
slide4. Employment 54 Months Up and 1 Down Since May 2020 September 2024 254,000 Net Job Gain-July and August revised up by 77,000
Unemployment at 4.1% up From 3.5% Over the Year
Participation Rate 62.7% Versus 63.3% February 2020
September 150,000 Gain in Labor Force
Beige Book 10/23/24-little change, less wage pressure, Labor Availability Improved, Price Sensitivity Increasing, SE Weather Impacts
JOLTS August 8 Million Openings- up 330,000 over the month and down 1.3 million over the year Quit rate at 1.9% in April 2022 3%
1.2 Vacancies per Unemployed Person<br>
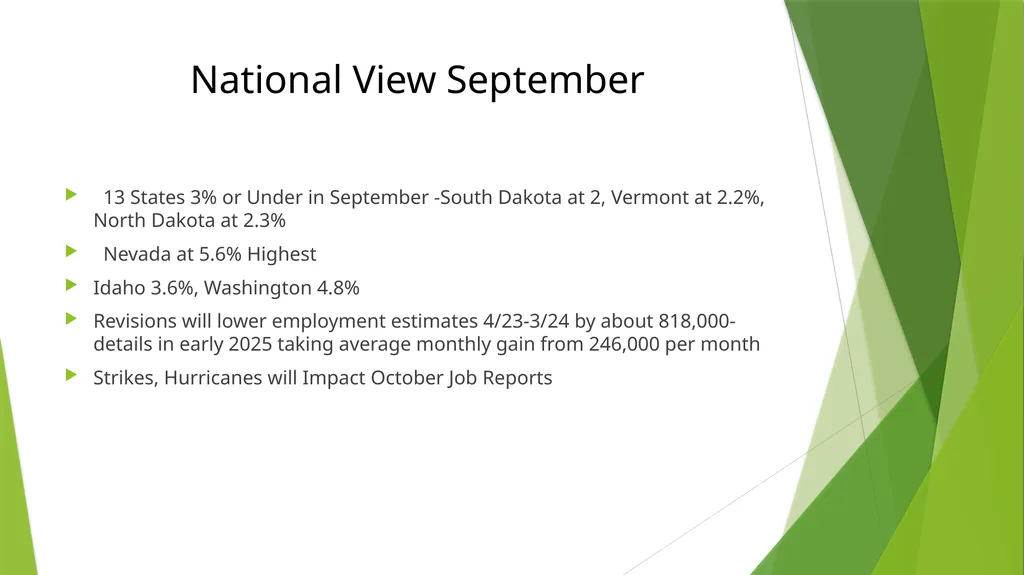
slide5. National View September 13 States 3% or Under in September -South Dakota at 2, Vermont at 2.2%, North Dakota at 2.3%
Nevada at 5.6% Highest
Idaho 3.6%, Washington 4.8%
Revisions will lower employment estimates 4/23-3/24 by about 818,000-details in early 2025 taking average monthly gain from 246,000 per month
Strikes, Hurricanes will Impact October Job Reports<br>
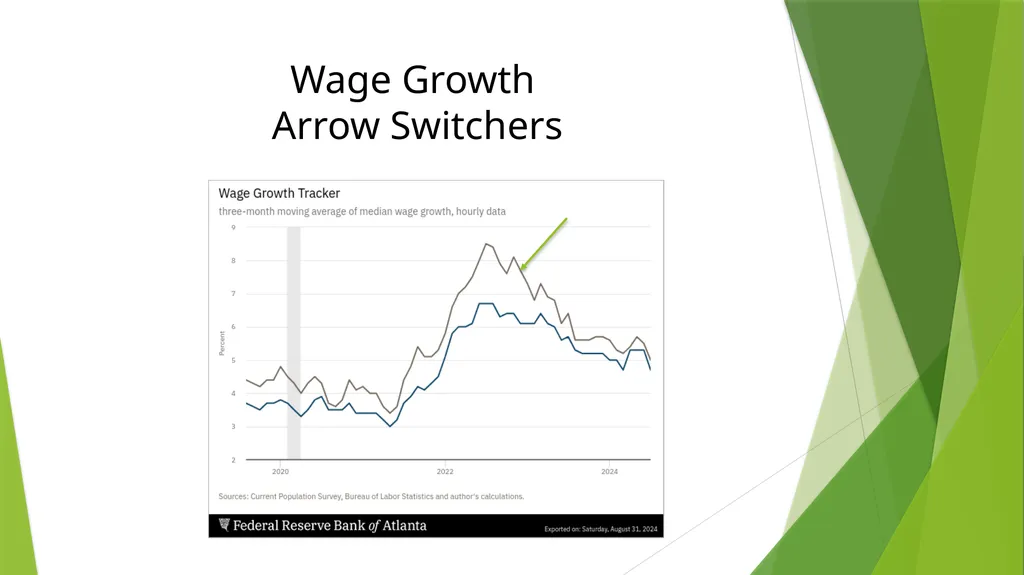
slide6. Wage Growth Arrow Switchers<br>
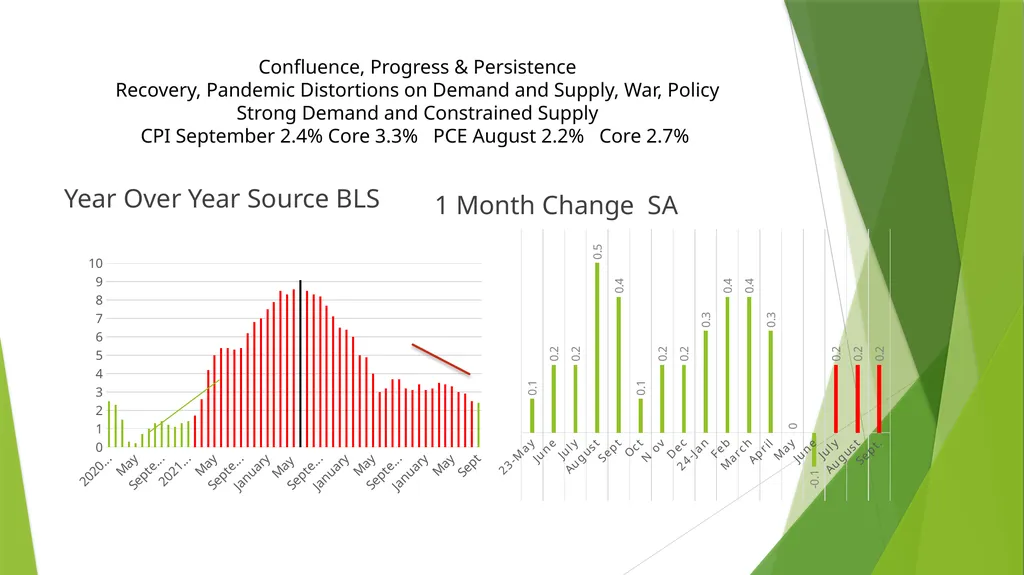
slide7. Confluence, Progress & Persistence Recovery, Pandemic Distortions on Demand and Supply, War, Policy Strong Demand and Constrained Supply CPI September 2.4% Core 3.3% PCE August 2.2% Core 2.7% Year Over Year Source BLS 1 Month Change SA<br>
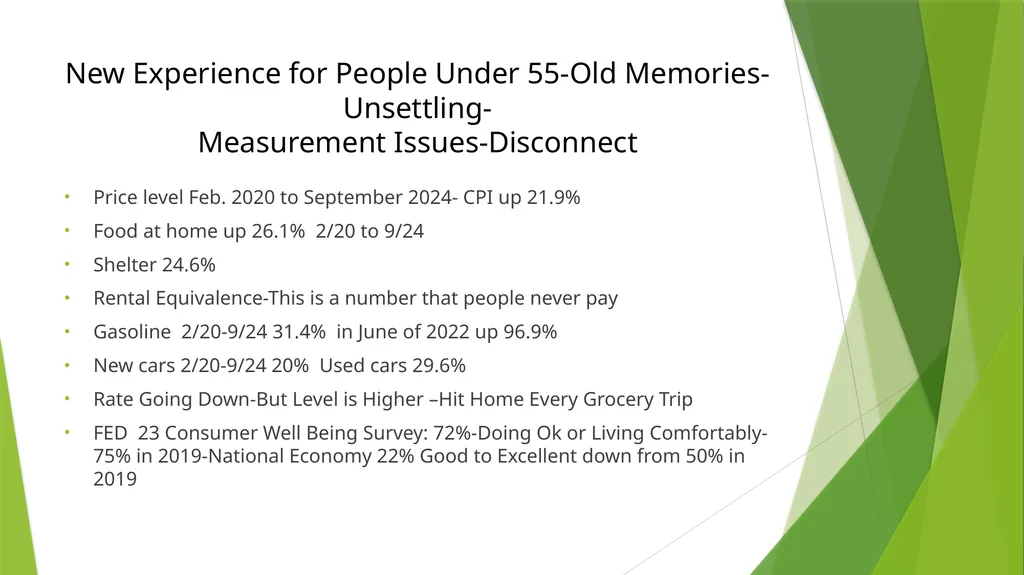
slide8. New Experience for People Under 55-Old Memories-Unsettling- Measurement Issues-Disconnect Price level Feb. 2020 to September 2024- CPI up 21.9%
Food at home up 26.1% 2/20 to 9/24
Shelter 24.6%
Rental Equivalence-This is a number that people never pay
Gasoline 2/20-9/24 31.4% in June of 2022 up 96.9%
New cars 2/20-9/24 20% Used cars 29.6%
Rate Going Down-But Level is Higher –Hit Home Every Grocery Trip
FED 23 Consumer Well Being Survey: 72%-Doing Ok or Living Comfortably-75% in 2019-National Economy 22% Good to Excellent down from 50% in 2019<br>
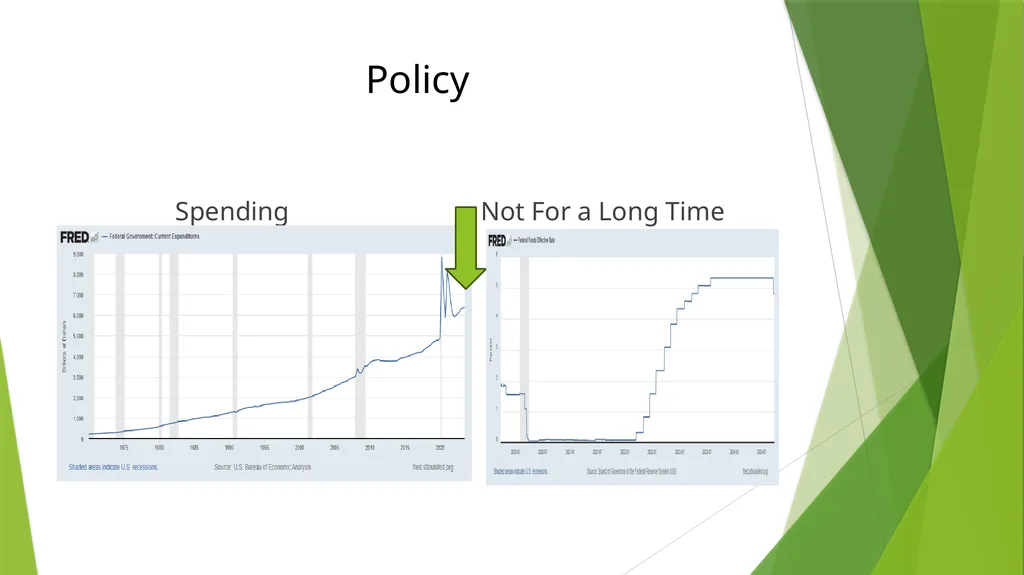
slide9. Policy Responses to Pandemic, Inflation & Climate Monetary Policy Fiscal Policy 11 Increases in the Federal Funds Rate Target-March 2022 until July 2023 0-.25% to 5.25-5.5% - after cutting Rate to .0-.25% in March of 2020
QE-Buying $120 Billion to QT-Letting Bond Portfolio Run off $95 billion per Month
Effective June 1, 2024-Slower Pace of QT-$25 Billion in Treasuries and $35 Billion in Mortgage Backed Cares Act 2020
Consolidated Appropriations Act 2020
American Rescue Plan 2021
Infrastructure Bill 2021
Chips Act 2022
Inflation Reduction Act 2022<br>
slide10. Policy Spending Not For a Long Time<br>
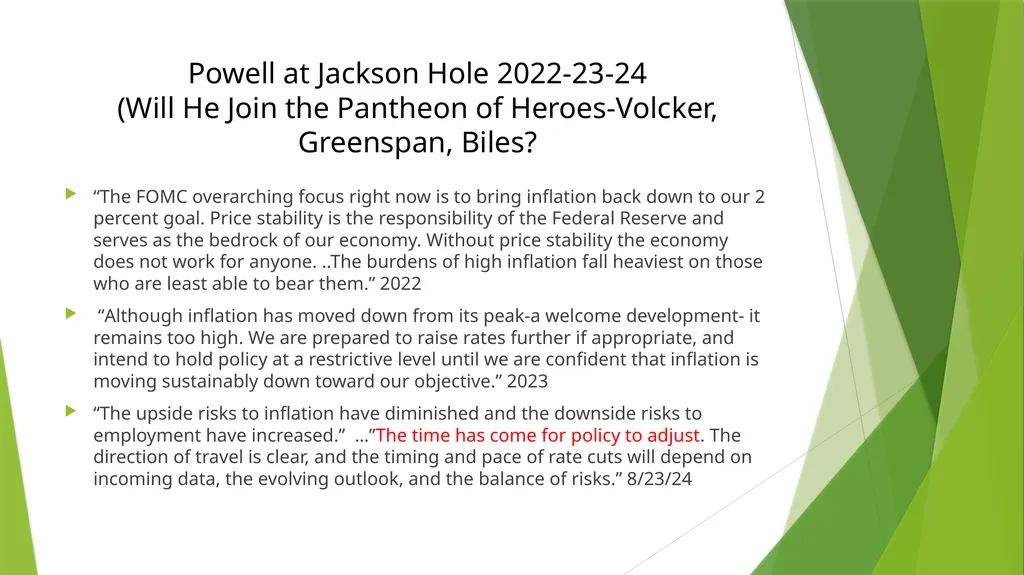
slide11. Powell at Jackson Hole 2022-23-24 (Will He Join the Pantheon of Heroes-Volcker, Greenspan, Biles? “The FOMC overarching focus right now is to bring inflation back down to our 2 percent goal. Price stability is the responsibility of the Federal Reserve and serves as the bedrock of our economy. Without price stability the economy does not work for anyone. ..The burdens of high inflation fall heaviest on those who are least able to bear them.” 2022
“Although inflation has moved down from its peak-a welcome development- it remains too high. We are prepared to raise rates further if appropriate, and intend to hold policy at a restrictive level until we are confident that inflation is moving sustainably down toward our objective.” 2023
“The upside risks to inflation have diminished and the downside risks to employment have increased.” …”The time has come for policy to adjust. The direction of travel is clear, and the timing and pace of rate cuts will depend on incoming data, the evolving outlook, and the balance of risks.” 8/23/24<br>
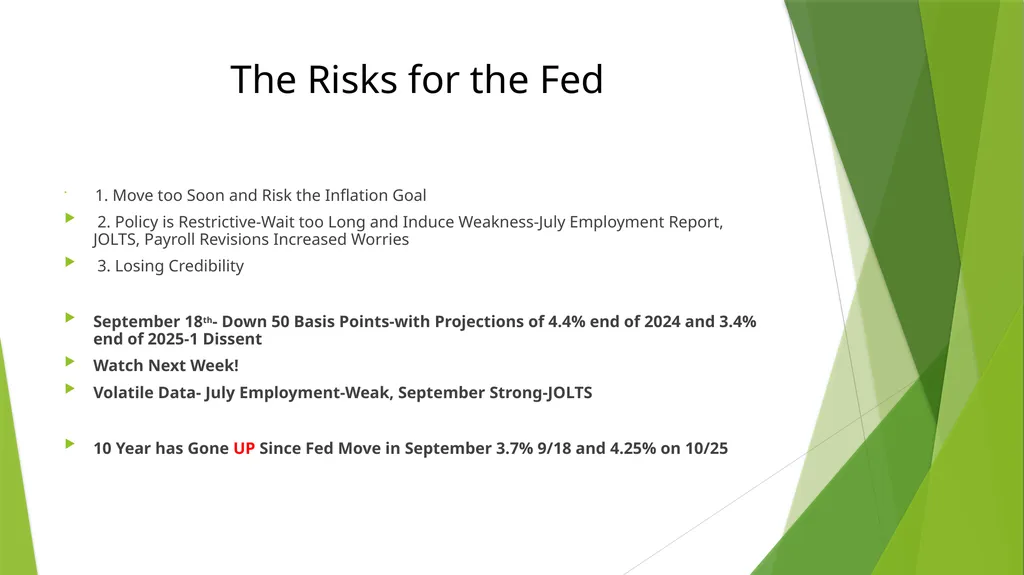
slide12. The Risks for the Fed 1. Move too Soon and Risk the Inflation Goal
2. Policy is Restrictive-Wait too Long and Induce Weakness-July Employment Report, JOLTS, Payroll Revisions Increased Worries
3. Losing Credibility
September 18th- Down 50 Basis Points-with Projections of 4.4% end of 2024 and 3.4% end of 2025-1 Dissent
Watch Next Week!
Volatile Data- July Employment-Weak, September Strong-JOLTS
10 Year has Gone UP Since Fed Move in September 3.7% 9/18 and 4.25% on 10/25<br>
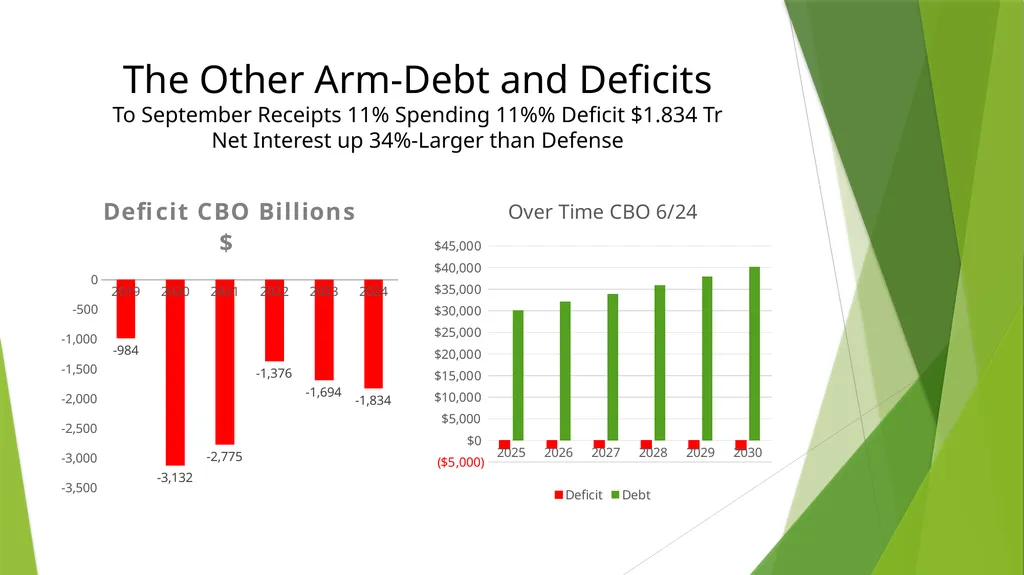
slide13. The Other Arm-Debt and Deficits To September Receipts 11% Spending 11%% Deficit $1.834 Tr Net Interest up 34%-Larger than Defense<br>
slide14. Rhetoric-Ideas-Proposals Campaigns No Tax on Tips
Child Tax Credits-Refundable? Income Limits?
Exempt All Social Security Income from Taxes
Expand Medicare
Mass Deportation
Taxes-Tariffs
Implications for Debt, Deficits, Incentives, Price Level, Participation Rates, Output<br>
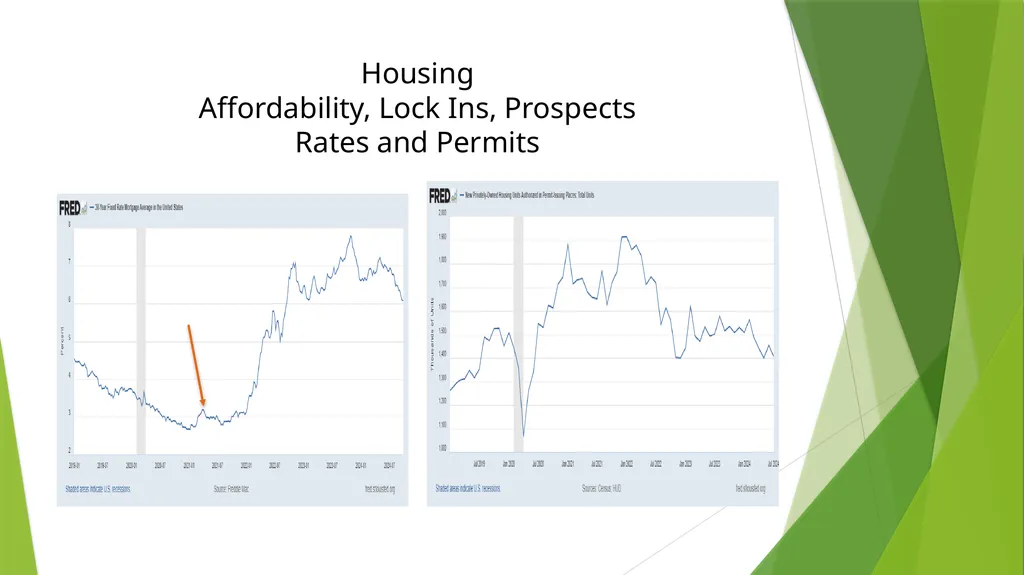
slide15. Housing Affordability, Lock Ins, Prospects Rates and Permits<br>
slide16. Deafening Silence and Invisible Elephants Missed Chicago and Milwaukee
Trust Fund Exhaustion-Looming SS 2033 Medicare Hospital 2036
How Do You Spend without Taxes?
Create New Money? Requires Compliant Monetary Authority-Inflation Risk
Borrow from Savers here or Abroad-Crowding Out Risk
Institutions and People want to Hold Dollar Assets-Reserve Currency Advantage
“This makes America’s fiscal woes a festering problem, but not an imminent hazard.” Economist 10/18/214
Soaring Interest Burden--Rising Rates and More Debt
Aging Population, Global Pressures to Expand Defense, Election Promises
Herb Stein-Ben’s Father-Ferris Bueller’s Day Off<br>
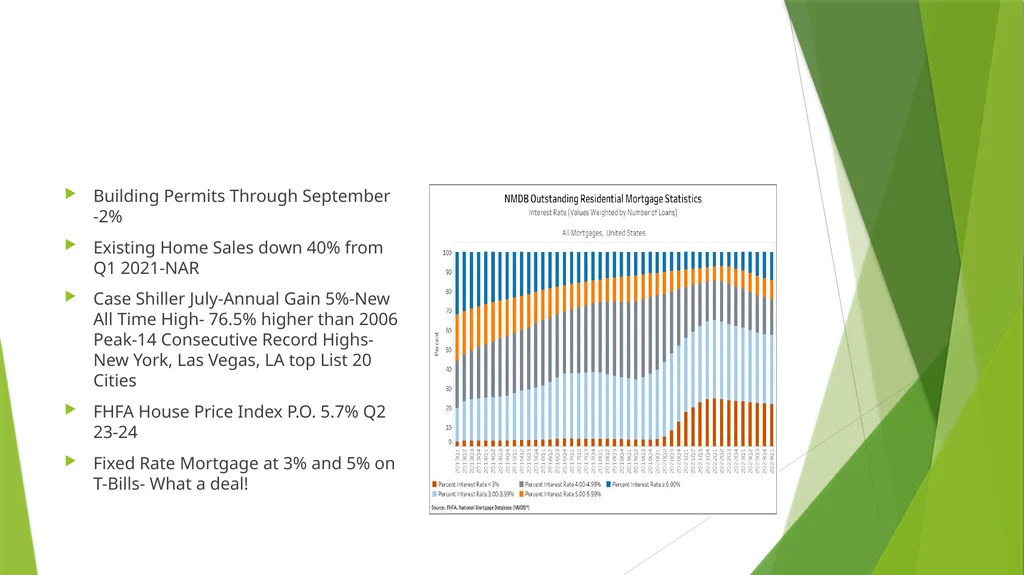
slide17. Building Permits Through September -2%
Existing Home Sales down 40% from Q1 2021-NAR
Case Shiller July-Annual Gain 5%-New All Time High- 76.5% higher than 2006 Peak-14 Consecutive Record Highs-New York, Las Vegas, LA top List 20 Cities
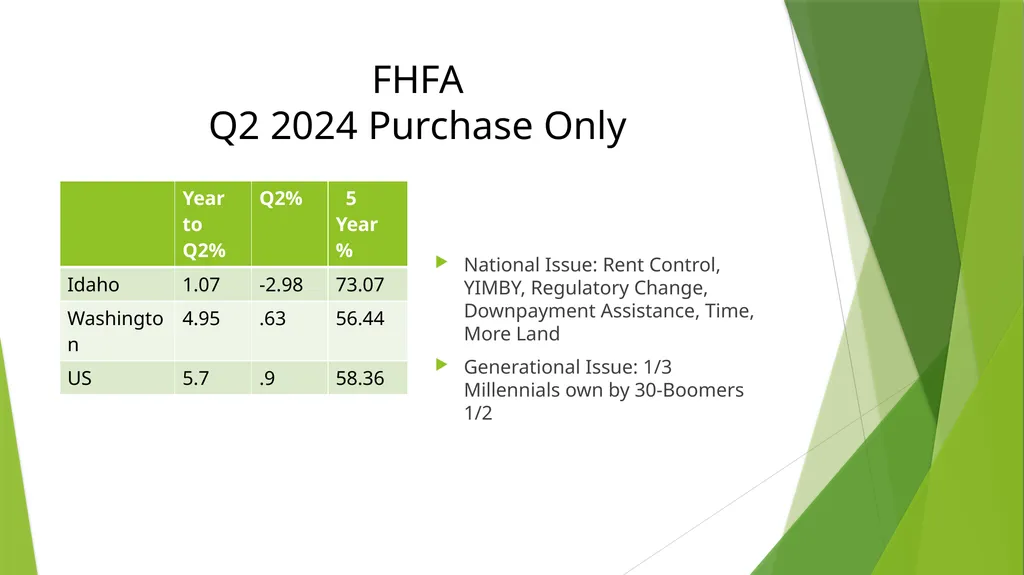
FHFA House Price Index P.O. 5.7% Q2 23-24
Fixed Rate Mortgage at 3% and 5% on T-Bills- What a deal!<br>
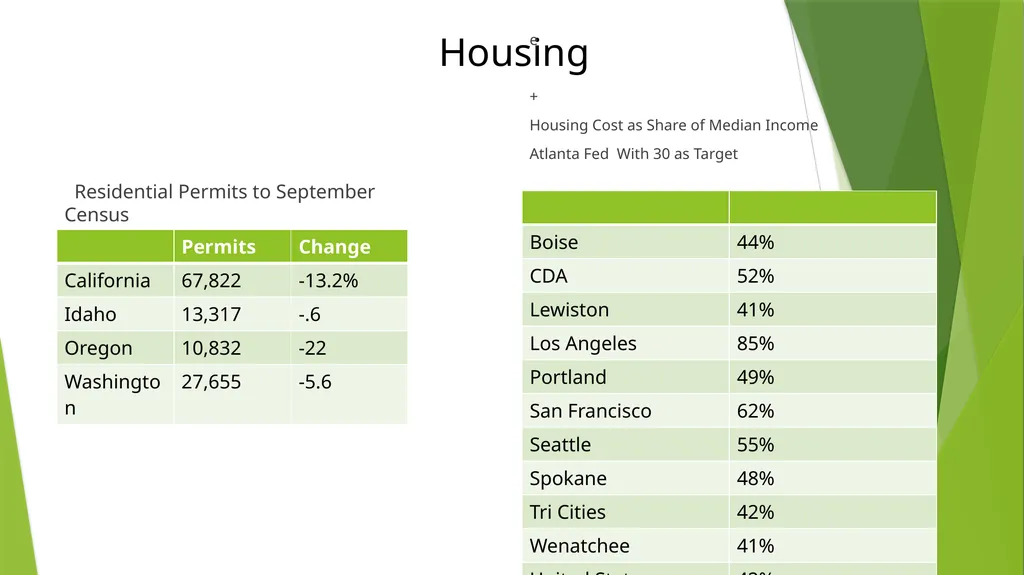
slide18. Housing Residential Permits to September Census e
+
Housing Cost as Share of Median Income
Atlanta Fed With 30 as Target<br>
slide19. FHFA Q2 2024 Purchase Only National Issue: Rent Control, YIMBY, Regulatory Change, Downpayment Assistance, Time, More Land
Generational Issue: 1/3 Millennials own by 30-Boomers 1/2<br>
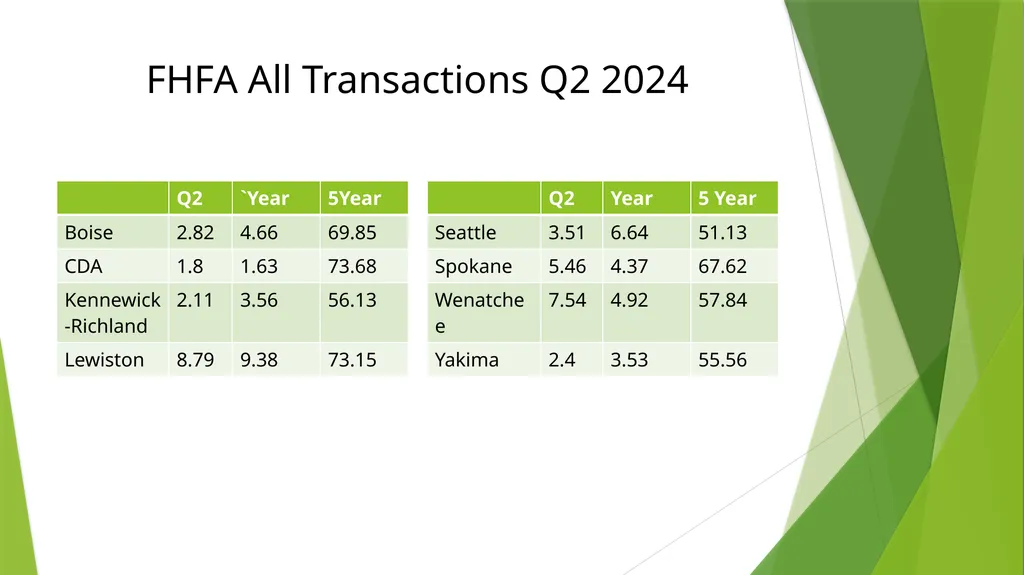
slide20. FHFA All Transactions Q2 2024<br>
slide21. Montana 1
Idaho 2
South Carolina 3
Missouri 4
Alaska 5
Nebraska 6
North Dakota 7
Texas 8
Florida 9
Arizona 10
Vermont 11
New Hampshire 12
Alabama 13
Utah14
Indiana 15
Alabama 16 Job Growth Update September 2024 Data Year over Year Change 49 States Up Source: BLS, ASU Colorado17
Rhode Island 18
Washington 19
Georgia 20
North Carolina 21
New Mexico 22
Pennsylvania 23
Hawaii 24
Virginia 25
New York 26
California 27
Kansas 28
Arkansas 29
Minnesota 30
Oklahoma 31
New Jersey 32 Maine 33
Wisconsin 34
Kentucky 35
Ohio 36
Tennessee 37
Delaware 38
Massachusetts 39
Illinois 40
Michigan 41
Connecticut42
Maryland 43
Mississippi 44
Wyoming 45
Oregon 46
Iowa 47
West Virginia 48
South Dakota 49
Louisiana 50<br>
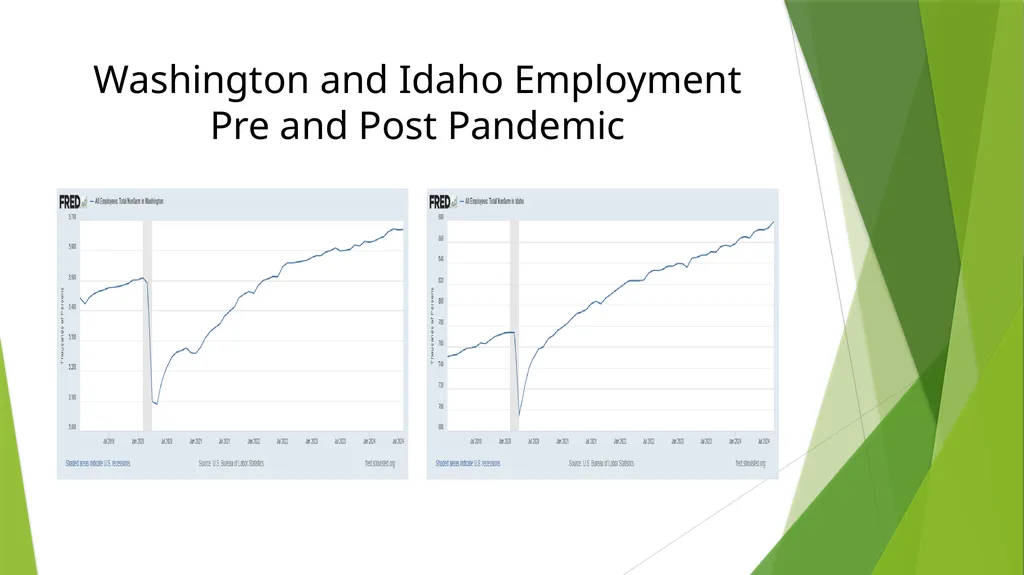
slide22. Washington and Idaho Employment Pre and Post Pandemic<br>
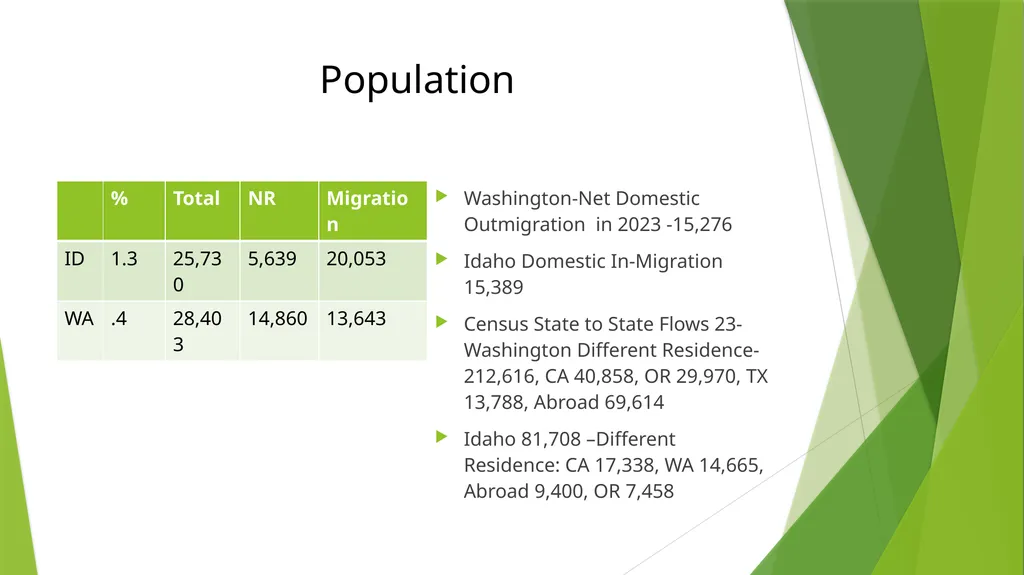
slide23. Population Washington-Net Domestic Outmigration in 2023 -15,276
Idaho Domestic In-Migration 15,389
Census State to State Flows 23-Washington Different Residence-212,616, CA 40,858, OR 29,970, TX 13,788, Abroad 69,614
Idaho 81,708 –Different Residence: CA 17,338, WA 14,665, Abroad 9,400, OR 7,458<br>
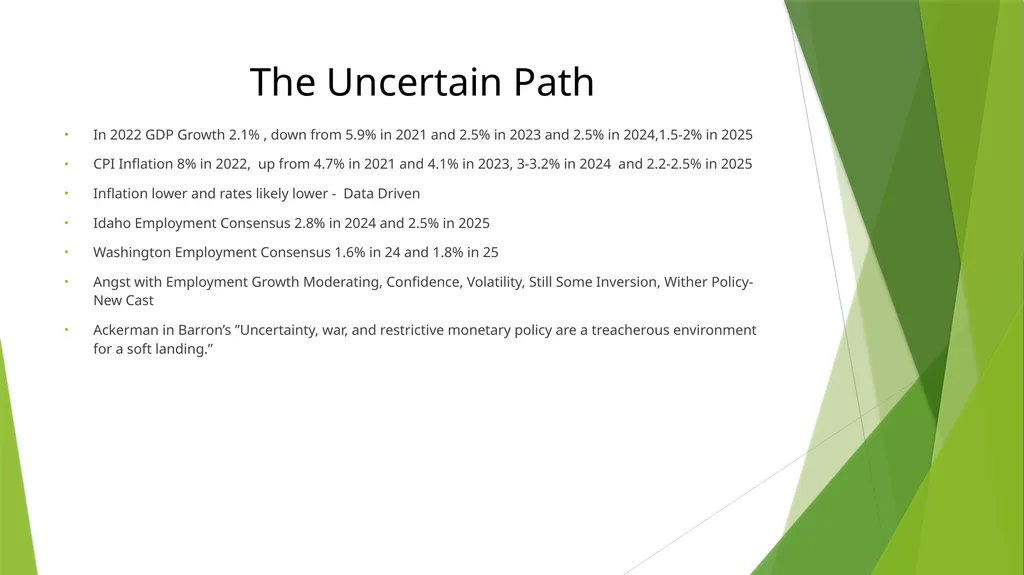
slide24. The Uncertain Path In 2022 GDP Growth 2.1% , down from 5.9% in 2021 and 2.5% in 2023 and 2.5% in 2024,1.5-2% in 2025
CPI Inflation 8% in 2022, up from 4.7% in 2021 and 4.1% in 2023, 3-3.2% in 2024 and 2.2-2.5% in 2025
Inflation lower and rates likely lower - Data Driven
Idaho Employment Consensus 2.8% in 2024 and 2.5% in 2025
Washington Employment Consensus 1.6% in 24 and 1.8% in 25
Angst with Employment Growth Moderating, Confidence, Volatility, Still Some Inversion, Wither Policy-New Cast
Ackerman in Barron’s ”Uncertainty, war, and restrictive monetary policy are a treacherous environment for a soft landing.”<br>
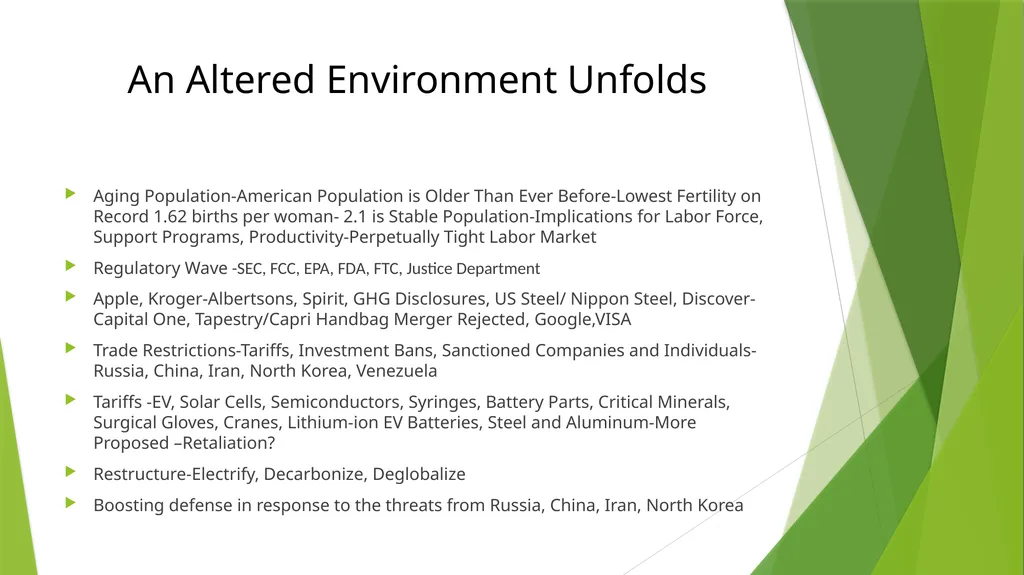
slide25. An Altered Environment Unfolds Aging Population-American Population is Older Than Ever Before-Lowest Fertility on Record 1.62 births per woman- 2.1 is Stable Population-Implications for Labor Force, Support Programs, Productivity-Perpetually Tight Labor Market
Regulatory Wave -SEC, FCC, EPA, FDA, FTC, Justice Department
Apple, Kroger-Albertsons, Spirit, GHG Disclosures, US Steel/ Nippon Steel, Discover-Capital One, Tapestry/Capri Handbag Merger Rejected, Google,VISA
Trade Restrictions-Tariffs, Investment Bans, Sanctioned Companies and Individuals-Russia, China, Iran, North Korea, Venezuela
Tariffs -EV, Solar Cells, Semiconductors, Syringes, Battery Parts, Critical Minerals, Surgical Gloves, Cranes, Lithium-ion EV Batteries, Steel and Aluminum-More Proposed –Retaliation?
Restructure-Electrify, Decarbonize, Deglobalize
Boosting defense in response to the threats from Russia, China, Iran, North Korea<br>
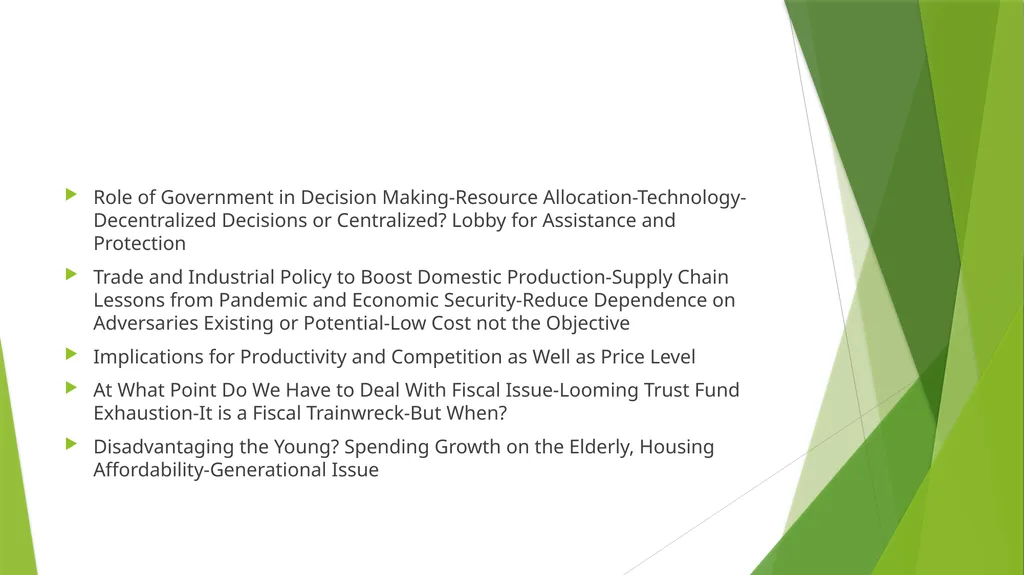
slide26. Role of Government in Decision Making-Resource Allocation-Technology-Decentralized Decisions or Centralized? Lobby for Assistance and Protection
Trade and Industrial Policy to Boost Domestic Production-Supply Chain Lessons from Pandemic and Economic Security-Reduce Dependence on Adversaries Existing or Potential-Low Cost not the Objective
Implications for Productivity and Competition as Well as Price Level
At What Point Do We Have to Deal With Fiscal Issue-Looming Trust Fund Exhaustion-It is a Fiscal Trainwreck-But When?
Disadvantaging the Young? Spending Growth on the Elderly, Housing Affordability-Generational Issue<br>
slide27. Policy Path Depends on House, Senate and Courts-Margins-Very Small Numbers to Control!
Federal Reserve Board Members Appointed by President and Confirmed by Senate-Fed Independence?
Are we headed for a period of higher inflationary pressures? Trade Barriers, Restructuring-Energy, Regulatory, Altered Labor Market, Fiscal Fantasies
Election Season-Ask or Contemplate- How do you do that? What are the implications?
Who Pays Corporate and other Business Taxes? Tariffs? How do we fund Pensions and Retirement Plans?
Region-Ag Sector-International Trade Environment, Energy policy Dams?, Competing for Federal Funds-Hubs-Decisions made Elsewhere- Search for lower housing costs
The Recent Experience: Big Run Up in Rates-no Recession, Inflation Down with No Decline in Employment, Money Supply weakness no Recession, Disconnect or Change in traditional economic measures and Performance and Confidence
Reality is a few months away! Debt Ceiling 1/1/25 , Tax Expiration 2025<br>
October 29, 2024
Spokane Valley, Washington
John W. Mitchell<br>
slide2. Late October Halfway Through Year Five Not The Election We Thought in June-A summer to Tell Grandchildren About
Three Wars that We are Involved In
First Rate Cut Since March of 2020-Another Next Week?
S&P 500 up 23.14% YTD 10/18/24 Including Dividends
Election Year Rhetoric-Promises, Charges, Messaging, Raised Voices and Reminders that Social Media and E-mails, and College Op-Eds Live Forever
Gun Free, Smoke Free, Drug Free Zones-Now Economics Free Interval
49 States Up on Year Over Year Basis
Short Christmas Shopping Season-Last K Mart Closed
No Landing Yet!
YouGov Poll 39% Believe we are in Recession (Economist 10/18)<br>
slide3. GDP Contributions to Growth Source:BEA Contributions To Growth of 3% in Q2 2024 (SAAR)
Consumption % Points Goods .63 Services 1.27
Inventory Change Large Swing
Federal Government Swing –Defense .32% Points
Rising Real After Tax Income, Upward Revisions to Income, Savings, Q2 Net Worth up $2.7 Tr, Q1 $5.66 Tr<br>
slide4. Employment 54 Months Up and 1 Down Since May 2020 September 2024 254,000 Net Job Gain-July and August revised up by 77,000
Unemployment at 4.1% up From 3.5% Over the Year
Participation Rate 62.7% Versus 63.3% February 2020
September 150,000 Gain in Labor Force
Beige Book 10/23/24-little change, less wage pressure, Labor Availability Improved, Price Sensitivity Increasing, SE Weather Impacts
JOLTS August 8 Million Openings- up 330,000 over the month and down 1.3 million over the year Quit rate at 1.9% in April 2022 3%
1.2 Vacancies per Unemployed Person<br>
slide5. National View September 13 States 3% or Under in September -South Dakota at 2, Vermont at 2.2%, North Dakota at 2.3%
Nevada at 5.6% Highest
Idaho 3.6%, Washington 4.8%
Revisions will lower employment estimates 4/23-3/24 by about 818,000-details in early 2025 taking average monthly gain from 246,000 per month
Strikes, Hurricanes will Impact October Job Reports<br>
slide6. Wage Growth Arrow Switchers<br>
slide7. Confluence, Progress & Persistence Recovery, Pandemic Distortions on Demand and Supply, War, Policy Strong Demand and Constrained Supply CPI September 2.4% Core 3.3% PCE August 2.2% Core 2.7% Year Over Year Source BLS 1 Month Change SA<br>
slide8. New Experience for People Under 55-Old Memories-Unsettling- Measurement Issues-Disconnect Price level Feb. 2020 to September 2024- CPI up 21.9%
Food at home up 26.1% 2/20 to 9/24
Shelter 24.6%
Rental Equivalence-This is a number that people never pay
Gasoline 2/20-9/24 31.4% in June of 2022 up 96.9%
New cars 2/20-9/24 20% Used cars 29.6%
Rate Going Down-But Level is Higher –Hit Home Every Grocery Trip
FED 23 Consumer Well Being Survey: 72%-Doing Ok or Living Comfortably-75% in 2019-National Economy 22% Good to Excellent down from 50% in 2019<br>
slide9. Policy Responses to Pandemic, Inflation & Climate Monetary Policy Fiscal Policy 11 Increases in the Federal Funds Rate Target-March 2022 until July 2023 0-.25% to 5.25-5.5% - after cutting Rate to .0-.25% in March of 2020
QE-Buying $120 Billion to QT-Letting Bond Portfolio Run off $95 billion per Month
Effective June 1, 2024-Slower Pace of QT-$25 Billion in Treasuries and $35 Billion in Mortgage Backed Cares Act 2020
Consolidated Appropriations Act 2020
American Rescue Plan 2021
Infrastructure Bill 2021
Chips Act 2022
Inflation Reduction Act 2022<br>
slide10. Policy Spending Not For a Long Time<br>
slide11. Powell at Jackson Hole 2022-23-24 (Will He Join the Pantheon of Heroes-Volcker, Greenspan, Biles? “The FOMC overarching focus right now is to bring inflation back down to our 2 percent goal. Price stability is the responsibility of the Federal Reserve and serves as the bedrock of our economy. Without price stability the economy does not work for anyone. ..The burdens of high inflation fall heaviest on those who are least able to bear them.” 2022
“Although inflation has moved down from its peak-a welcome development- it remains too high. We are prepared to raise rates further if appropriate, and intend to hold policy at a restrictive level until we are confident that inflation is moving sustainably down toward our objective.” 2023
“The upside risks to inflation have diminished and the downside risks to employment have increased.” …”The time has come for policy to adjust. The direction of travel is clear, and the timing and pace of rate cuts will depend on incoming data, the evolving outlook, and the balance of risks.” 8/23/24<br>
slide12. The Risks for the Fed 1. Move too Soon and Risk the Inflation Goal
2. Policy is Restrictive-Wait too Long and Induce Weakness-July Employment Report, JOLTS, Payroll Revisions Increased Worries
3. Losing Credibility
September 18th- Down 50 Basis Points-with Projections of 4.4% end of 2024 and 3.4% end of 2025-1 Dissent
Watch Next Week!
Volatile Data- July Employment-Weak, September Strong-JOLTS
10 Year has Gone UP Since Fed Move in September 3.7% 9/18 and 4.25% on 10/25<br>
slide13. The Other Arm-Debt and Deficits To September Receipts 11% Spending 11%% Deficit $1.834 Tr Net Interest up 34%-Larger than Defense<br>
slide14. Rhetoric-Ideas-Proposals Campaigns No Tax on Tips
Child Tax Credits-Refundable? Income Limits?
Exempt All Social Security Income from Taxes
Expand Medicare
Mass Deportation
Taxes-Tariffs
Implications for Debt, Deficits, Incentives, Price Level, Participation Rates, Output<br>
slide15. Housing Affordability, Lock Ins, Prospects Rates and Permits<br>
slide16. Deafening Silence and Invisible Elephants Missed Chicago and Milwaukee
Trust Fund Exhaustion-Looming SS 2033 Medicare Hospital 2036
How Do You Spend without Taxes?
Create New Money? Requires Compliant Monetary Authority-Inflation Risk
Borrow from Savers here or Abroad-Crowding Out Risk
Institutions and People want to Hold Dollar Assets-Reserve Currency Advantage
“This makes America’s fiscal woes a festering problem, but not an imminent hazard.” Economist 10/18/214
Soaring Interest Burden--Rising Rates and More Debt
Aging Population, Global Pressures to Expand Defense, Election Promises
Herb Stein-Ben’s Father-Ferris Bueller’s Day Off<br>
slide17. Building Permits Through September -2%
Existing Home Sales down 40% from Q1 2021-NAR
Case Shiller July-Annual Gain 5%-New All Time High- 76.5% higher than 2006 Peak-14 Consecutive Record Highs-New York, Las Vegas, LA top List 20 Cities
FHFA House Price Index P.O. 5.7% Q2 23-24
Fixed Rate Mortgage at 3% and 5% on T-Bills- What a deal!<br>
slide18. Housing Residential Permits to September Census e
+
Housing Cost as Share of Median Income
Atlanta Fed With 30 as Target<br>
slide19. FHFA Q2 2024 Purchase Only National Issue: Rent Control, YIMBY, Regulatory Change, Downpayment Assistance, Time, More Land
Generational Issue: 1/3 Millennials own by 30-Boomers 1/2<br>
slide20. FHFA All Transactions Q2 2024<br>
slide21. Montana 1
Idaho 2
South Carolina 3
Missouri 4
Alaska 5
Nebraska 6
North Dakota 7
Texas 8
Florida 9
Arizona 10
Vermont 11
New Hampshire 12
Alabama 13
Utah14
Indiana 15
Alabama 16 Job Growth Update September 2024 Data Year over Year Change 49 States Up Source: BLS, ASU Colorado17
Rhode Island 18
Washington 19
Georgia 20
North Carolina 21
New Mexico 22
Pennsylvania 23
Hawaii 24
Virginia 25
New York 26
California 27
Kansas 28
Arkansas 29
Minnesota 30
Oklahoma 31
New Jersey 32 Maine 33
Wisconsin 34
Kentucky 35
Ohio 36
Tennessee 37
Delaware 38
Massachusetts 39
Illinois 40
Michigan 41
Connecticut42
Maryland 43
Mississippi 44
Wyoming 45
Oregon 46
Iowa 47
West Virginia 48
South Dakota 49
Louisiana 50<br>
slide22. Washington and Idaho Employment Pre and Post Pandemic<br>
slide23. Population Washington-Net Domestic Outmigration in 2023 -15,276
Idaho Domestic In-Migration 15,389
Census State to State Flows 23-Washington Different Residence-212,616, CA 40,858, OR 29,970, TX 13,788, Abroad 69,614
Idaho 81,708 –Different Residence: CA 17,338, WA 14,665, Abroad 9,400, OR 7,458<br>
slide24. The Uncertain Path In 2022 GDP Growth 2.1% , down from 5.9% in 2021 and 2.5% in 2023 and 2.5% in 2024,1.5-2% in 2025
CPI Inflation 8% in 2022, up from 4.7% in 2021 and 4.1% in 2023, 3-3.2% in 2024 and 2.2-2.5% in 2025
Inflation lower and rates likely lower - Data Driven
Idaho Employment Consensus 2.8% in 2024 and 2.5% in 2025
Washington Employment Consensus 1.6% in 24 and 1.8% in 25
Angst with Employment Growth Moderating, Confidence, Volatility, Still Some Inversion, Wither Policy-New Cast
Ackerman in Barron’s ”Uncertainty, war, and restrictive monetary policy are a treacherous environment for a soft landing.”<br>
slide25. An Altered Environment Unfolds Aging Population-American Population is Older Than Ever Before-Lowest Fertility on Record 1.62 births per woman- 2.1 is Stable Population-Implications for Labor Force, Support Programs, Productivity-Perpetually Tight Labor Market
Regulatory Wave -SEC, FCC, EPA, FDA, FTC, Justice Department
Apple, Kroger-Albertsons, Spirit, GHG Disclosures, US Steel/ Nippon Steel, Discover-Capital One, Tapestry/Capri Handbag Merger Rejected, Google,VISA
Trade Restrictions-Tariffs, Investment Bans, Sanctioned Companies and Individuals-Russia, China, Iran, North Korea, Venezuela
Tariffs -EV, Solar Cells, Semiconductors, Syringes, Battery Parts, Critical Minerals, Surgical Gloves, Cranes, Lithium-ion EV Batteries, Steel and Aluminum-More Proposed –Retaliation?
Restructure-Electrify, Decarbonize, Deglobalize
Boosting defense in response to the threats from Russia, China, Iran, North Korea<br>
slide26. Role of Government in Decision Making-Resource Allocation-Technology-Decentralized Decisions or Centralized? Lobby for Assistance and Protection
Trade and Industrial Policy to Boost Domestic Production-Supply Chain Lessons from Pandemic and Economic Security-Reduce Dependence on Adversaries Existing or Potential-Low Cost not the Objective
Implications for Productivity and Competition as Well as Price Level
At What Point Do We Have to Deal With Fiscal Issue-Looming Trust Fund Exhaustion-It is a Fiscal Trainwreck-But When?
Disadvantaging the Young? Spending Growth on the Elderly, Housing Affordability-Generational Issue<br>
slide27. Policy Path Depends on House, Senate and Courts-Margins-Very Small Numbers to Control!
Federal Reserve Board Members Appointed by President and Confirmed by Senate-Fed Independence?
Are we headed for a period of higher inflationary pressures? Trade Barriers, Restructuring-Energy, Regulatory, Altered Labor Market, Fiscal Fantasies
Election Season-Ask or Contemplate- How do you do that? What are the implications?
Who Pays Corporate and other Business Taxes? Tariffs? How do we fund Pensions and Retirement Plans?
Region-Ag Sector-International Trade Environment, Energy policy Dams?, Competing for Federal Funds-Hubs-Decisions made Elsewhere- Search for lower housing costs
The Recent Experience: Big Run Up in Rates-no Recession, Inflation Down with No Decline in Employment, Money Supply weakness no Recession, Disconnect or Change in traditional economic measures and Performance and Confidence
Reality is a few months away! Debt Ceiling 1/1/25 , Tax Expiration 2025<br>