
& Al Duhaime, Audit Principal Jeff Wheeler, Audit
JO
Published · 44 slides · 0 views

1 / 1

Description
Al Duhaime, Audit Principal Jeff Wheeler, Audit Principal RECENTLY ISSUED AND UPCOMING ACCOUNTING PRONOUNCEMENTS FINANCIAL REPORTING DEVELOPMENTS (Fiscal Year 2019) A Brief Overview of ALAN DUHAIME Audit Principal 603.626.2240
Related Topics
Share
Embed code
Download this presentation From Below
"& Al Duhaime, Audit Principal Jeff Wheeler, Audit" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
& Al Duhaime, Audit Principal
Jeff Wheeler, Audit Principal RECENTLY ISSUED AND UPCOMING ACCOUNTING PRONOUNCEMENTS FINANCIAL REPORTING DEVELOPMENTS (Fiscal Year 2019) A Brief Overview of<br>
Jeff Wheeler, Audit Principal RECENTLY ISSUED AND UPCOMING ACCOUNTING PRONOUNCEMENTS FINANCIAL REPORTING DEVELOPMENTS (Fiscal Year 2019) A Brief Overview of<br>
02
ALAN DUHAIME
Audit Principal
603.626.2240
aduhaime@bnncpa.com JEFF WHEELER
Audit Principal
603.626.2215
jwheeler@bnncpa.com TODAY’S PRESENTERS<br>
Audit Principal
603.626.2240
aduhaime@bnncpa.com JEFF WHEELER
Audit Principal
603.626.2215
jwheeler@bnncpa.com TODAY’S PRESENTERS<br>
03
TODAY’S OBJECTIVES you with an update on accounting and reporting changes impacting you for 2019, and share best practices to prepare, plan, and implement. a brief overview of new and upcoming accounting and reporting pronouncements that have been issued that will be effective in years subsequent to 2019. a bit about potential accounting and reporting changes that are in discussion phases / comment phase.<br>
04
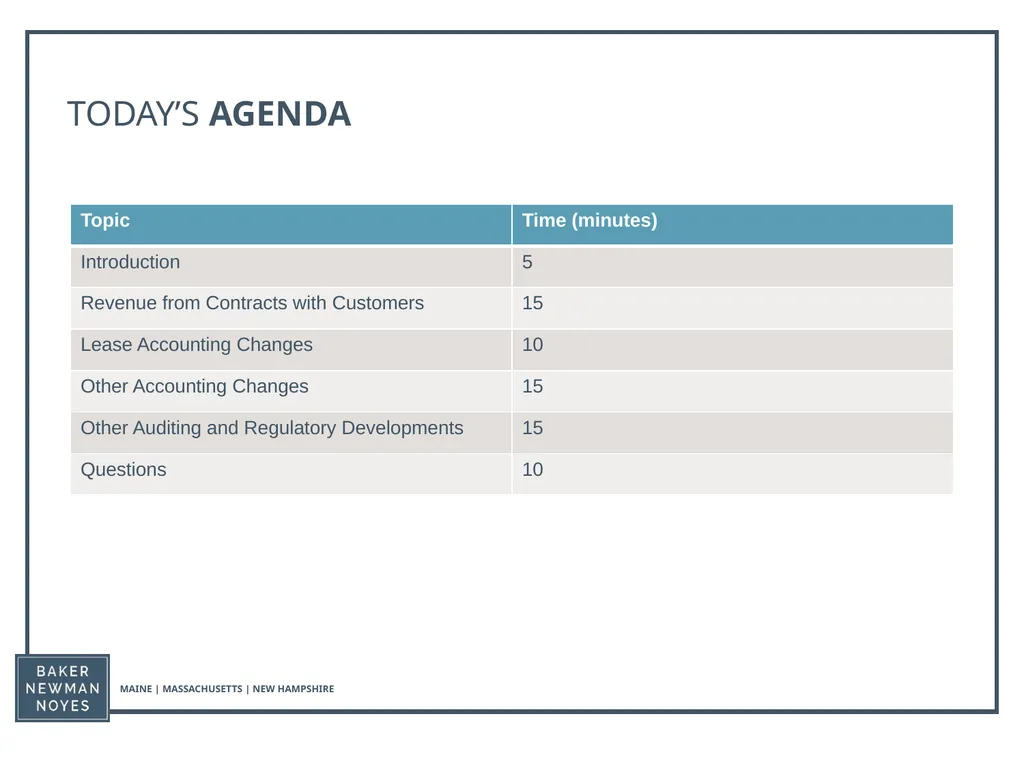
TODAY’S AGENDA<br>
05
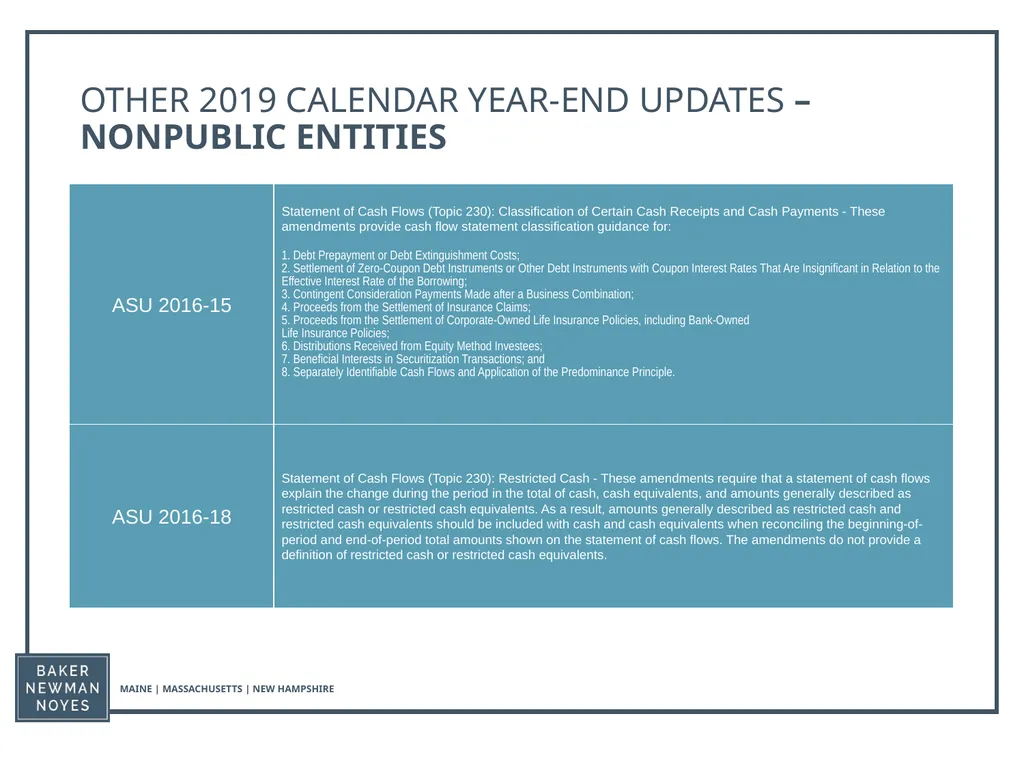
OTHER 2019 CALENDAR YEAR-END UPDATES – NONPUBLIC ENTITIES<br>
06
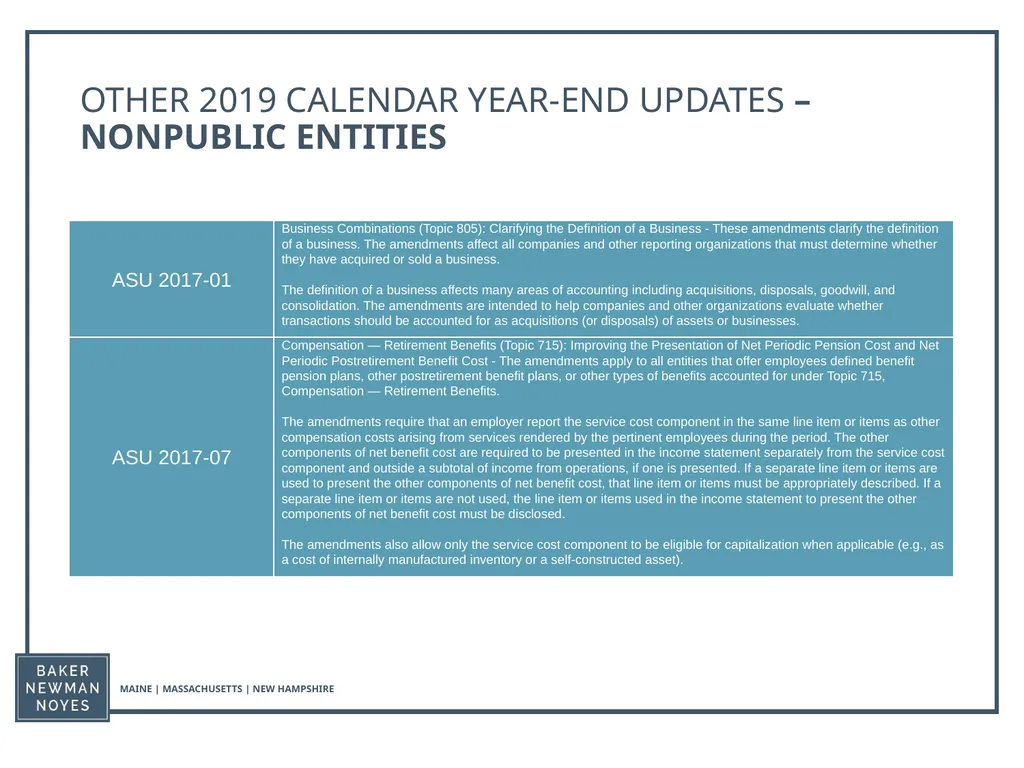
OTHER 2019 CALENDAR YEAR-END UPDATES – NONPUBLIC ENTITIES<br>
07
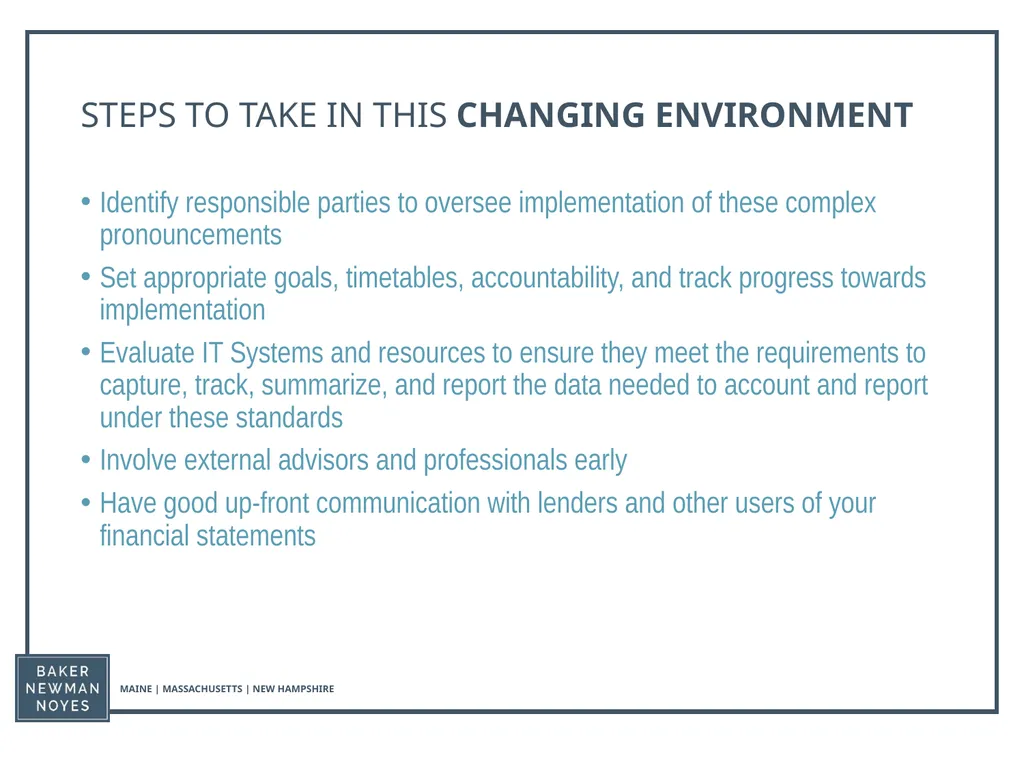
STEPS TO TAKE IN THIS CHANGING ENVIRONMENT Identify responsible parties to oversee implementation of these complex pronouncements
Set appropriate goals, timetables, accountability, and track progress towards implementation
Evaluate IT Systems and resources to ensure they meet the requirements to capture, track, summarize, and report the data needed to account and report under these standards
Involve external advisors and professionals early
Have good up-front communication with lenders and other users of your financial statements<br>
Set appropriate goals, timetables, accountability, and track progress towards implementation
Evaluate IT Systems and resources to ensure they meet the requirements to capture, track, summarize, and report the data needed to account and report under these standards
Involve external advisors and professionals early
Have good up-front communication with lenders and other users of your financial statements<br>
08
REVENUE FROM CONTRACTS WITH CUSTOMERS (TOPIC 606) Effective for non-public fiscal years beginning after December 15, 2018 (calendar 2019)
The core premise is that an entity should recognize the amount of revenue it expects to be entitled to for the transfer of promised goods or services to customers.<br>
The core premise is that an entity should recognize the amount of revenue it expects to be entitled to for the transfer of promised goods or services to customers.<br>
09
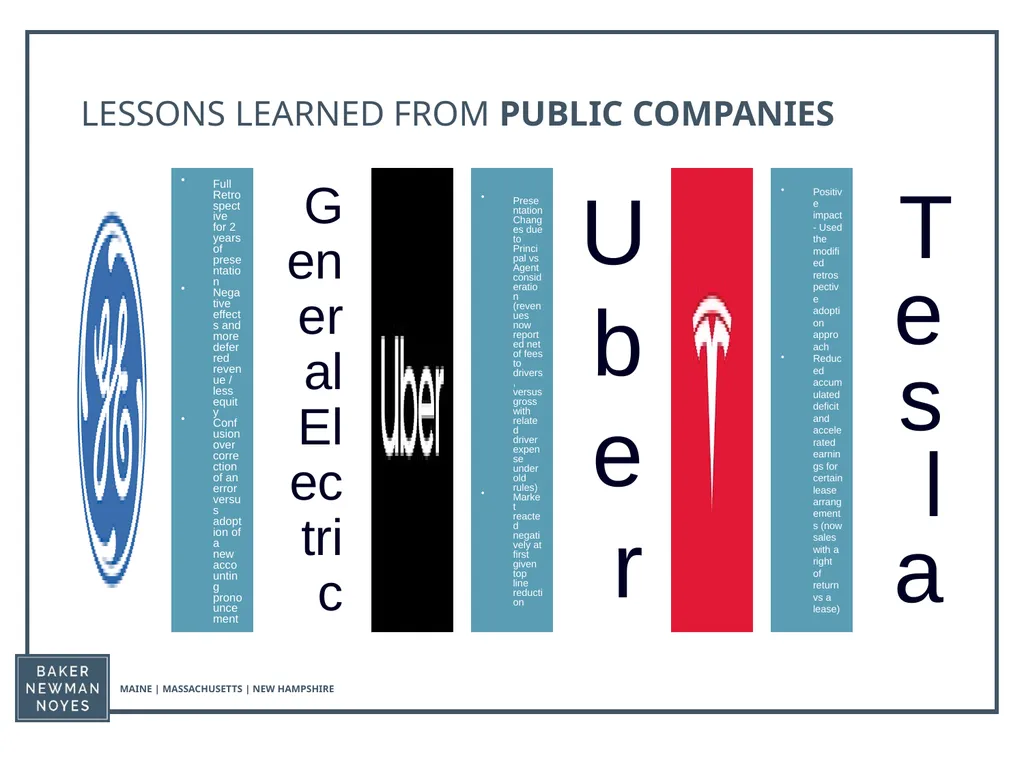
LESSONS LEARNED FROM PUBLIC COMPANIES<br>
10
REVENUE RECOGNITION - WHAT SHOULD YOU BE DOING NOW Ensure records and files containing customer contracts and specifics on terms of product and service sales are accurate and complete
Review standard contracts to fully understand the nuances of your product and service deliverables
Consider the impact of other items impacted by the new pronouncement, such as contract acquisition costs, setup costs, fulfillment, and sales commissions
Decide on an adoption approach<br>
Review standard contracts to fully understand the nuances of your product and service deliverables
Consider the impact of other items impacted by the new pronouncement, such as contract acquisition costs, setup costs, fulfillment, and sales commissions
Decide on an adoption approach<br>
11
REVENUE RECOGNITION – FROM RULES BASED TO PRINCIPLES BASED Old rules were very specific, and industry focused
New rules are principles based, and require more evaluation, judgement, and estimation
Examples include contract duration (especially with termination provisions), renewals, variable consideration provisions, and allocation of transaction price to each performance obligation based on stand-alone selling prices<br>
New rules are principles based, and require more evaluation, judgement, and estimation
Examples include contract duration (especially with termination provisions), renewals, variable consideration provisions, and allocation of transaction price to each performance obligation based on stand-alone selling prices<br>
12
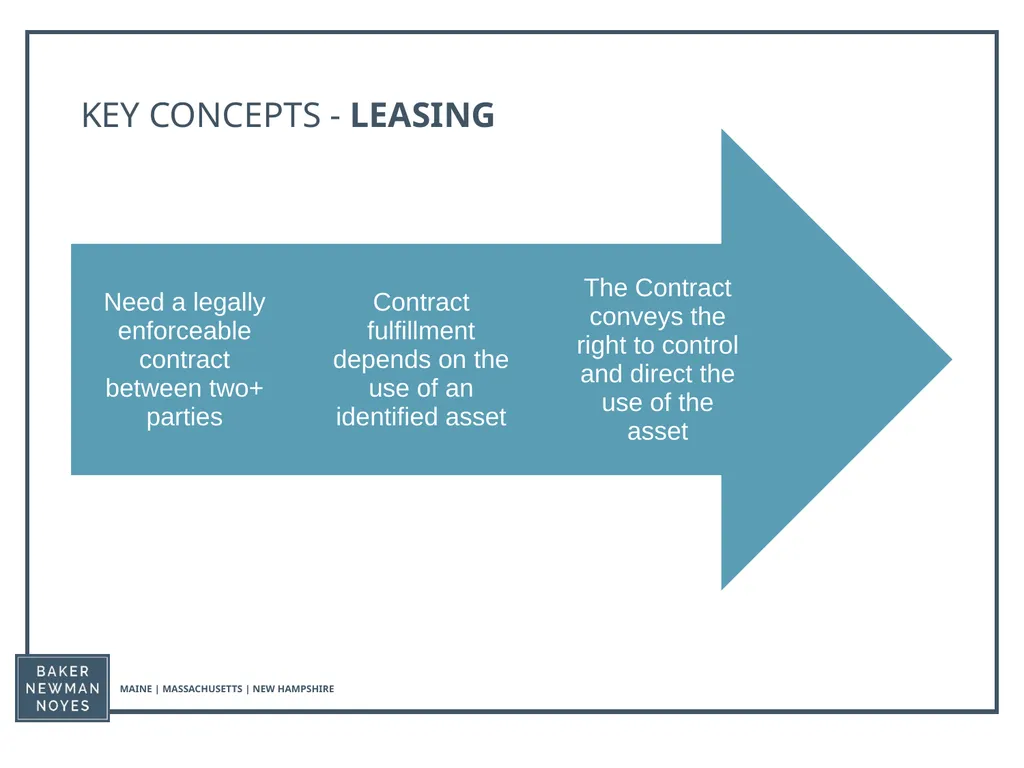
STEP ONE: IDENTIFY CONTRACT(S) A contract is defined in ASC 606 as an agreement between two or more parties that creates enforceable rights and obligations
Enforceability of rights and obligations in a contract is a matter of law
Contracts can be written, oral or implied by an entity’s customary business practices
Practices and processes for establishing contracts may vary within a business
Companies have to consider processes and practices when determining whether an agreement creates enforceable rights and obligations<br>
Enforceability of rights and obligations in a contract is a matter of law
Contracts can be written, oral or implied by an entity’s customary business practices
Practices and processes for establishing contracts may vary within a business
Companies have to consider processes and practices when determining whether an agreement creates enforceable rights and obligations<br>
13
STEP ONE: IDENTIFY CONTRACT(S) Arrangement must meet all these criteria to be a contract further evaluated for revenue recognition under the overall model in ASC 606:
Parties have approved the contract and are committed to perform
The Company can identify each party’s rights regarding the goods or services to be transferred
The contract’s payment terms can be identified
Contract has commercial substance
It is probable that the Company will collect substantially all of the consideration to which it will be entitled in exchange for the goods or services that will be transferred to the customer. In evaluating whether collectability is probable, an entity shall consider only the customer’s ability and intention to pay that amount when it is due<br>
Parties have approved the contract and are committed to perform
The Company can identify each party’s rights regarding the goods or services to be transferred
The contract’s payment terms can be identified
Contract has commercial substance
It is probable that the Company will collect substantially all of the consideration to which it will be entitled in exchange for the goods or services that will be transferred to the customer. In evaluating whether collectability is probable, an entity shall consider only the customer’s ability and intention to pay that amount when it is due<br>
14
STEP TWO: IDENTIFY THE PERFORMANCE OBLIGATIONS IN THE CONTRACT Definition of performance obligation
At contract inception, an entity shall assess the goods or services promised in a contract with a customer and shall identify as a performance obligation each promise to transfer to the customer either:
A good or service (or a bundle of goods or services) that is distinct
A series of distinct goods or services that are substantially the same and that have the same pattern of transfer to the customer.<br>
At contract inception, an entity shall assess the goods or services promised in a contract with a customer and shall identify as a performance obligation each promise to transfer to the customer either:
A good or service (or a bundle of goods or services) that is distinct
A series of distinct goods or services that are substantially the same and that have the same pattern of transfer to the customer.<br>
15
STEP TWO: TWO DISTINCT CRITERIA Are promised goods or services distinct from other goods and services in the contract?
To be distinct, a promised good or service must meet the following two criteria:
It must be capable of being distinct
It must be separable from other promises in the contract
Is the contract to deliver multiple promised goods or services or
a combined item(s) that comprises the individual goods or services promised in the contract (may require significant judgement)<br>
To be distinct, a promised good or service must meet the following two criteria:
It must be capable of being distinct
It must be separable from other promises in the contract
Is the contract to deliver multiple promised goods or services or
a combined item(s) that comprises the individual goods or services promised in the contract (may require significant judgement)<br>
16
STEP THREE: DETERMINE THE TRANSACTION PRICE Transaction price is the amount of consideration a party in the contract expects to be entitled to
Be on the lookout for:
Variable consideration
Non-cash consideration
Consideration payable to the customer (for example coupons, vouchers) that can be applied against amounts owed
Loyalty or Rewards Programs
Volume discounts
A contract’s enforceable rights and obligations at inception influence whether it includes customer options or variable consideration<br>
Be on the lookout for:
Variable consideration
Non-cash consideration
Consideration payable to the customer (for example coupons, vouchers) that can be applied against amounts owed
Loyalty or Rewards Programs
Volume discounts
A contract’s enforceable rights and obligations at inception influence whether it includes customer options or variable consideration<br>
17
STEP FOUR: ALLOCATE THE TRANSACTION PRICE TO THE PERFORMANCE OBLIGATIONS IN THE CONTRACT Allocate the transaction price to each performance obligation on the basis of its stand-alone selling price
Allocate discounts proportionally to all performance obligations<br>
Allocate discounts proportionally to all performance obligations<br>
18
STEP FIVE: RECOGNIZE REVENUE WHEN (OR AS) THE ENTITY SATISFIES A PERFORMANCE OBLIGATION A performance obligation is satisfied when a customer obtains control of the good or service
Control is “the ability to direct the use of, and obtain substantially all of the remaining benefits from the asset”
Control can transfer over time, or at a point in time<br>
Control is “the ability to direct the use of, and obtain substantially all of the remaining benefits from the asset”
Control can transfer over time, or at a point in time<br>
19
RECOGNITION OF REVENUE AND TRACKING PROGRESS Measuring Progress – use a method that best depicts the transfer of goods or services (output and input methods)
If unable to reasonably recognize progress, recognize revenues to the extent of costs incurred
A change from prior rules – for industries like construction, completed contract method is no longer allowed
Indicators that control has transferred
You have a present right to payment
Customer has taken legal title to an asset
Physical possession of an asset has transferred
Customer has significant risks and rewards of ownership
Customer has accepted the asset (however acceptance clauses may be an informality)
If you sell with trial / evaluation periods, control does not transfer until customer acceptance<br>
If unable to reasonably recognize progress, recognize revenues to the extent of costs incurred
A change from prior rules – for industries like construction, completed contract method is no longer allowed
Indicators that control has transferred
You have a present right to payment
Customer has taken legal title to an asset
Physical possession of an asset has transferred
Customer has significant risks and rewards of ownership
Customer has accepted the asset (however acceptance clauses may be an informality)
If you sell with trial / evaluation periods, control does not transfer until customer acceptance<br>
20
REVENUE RECOGNITION – THINGS TO WATCH OUT FOR Contract modifications
Warranties (could be a separate performance obligation or cost accrual)
Rights of return (not a separate performance obligation, but gives rise to variable consideration, and requires recognition of estimated refund liabilities and assets for expected product returns upon sale)
Costs to obtain a contract (old GAAP, expensed as incurred ; new rules recognize as an asset if you are expected to recover them)<br>
Warranties (could be a separate performance obligation or cost accrual)
Rights of return (not a separate performance obligation, but gives rise to variable consideration, and requires recognition of estimated refund liabilities and assets for expected product returns upon sale)
Costs to obtain a contract (old GAAP, expensed as incurred ; new rules recognize as an asset if you are expected to recover them)<br>
21
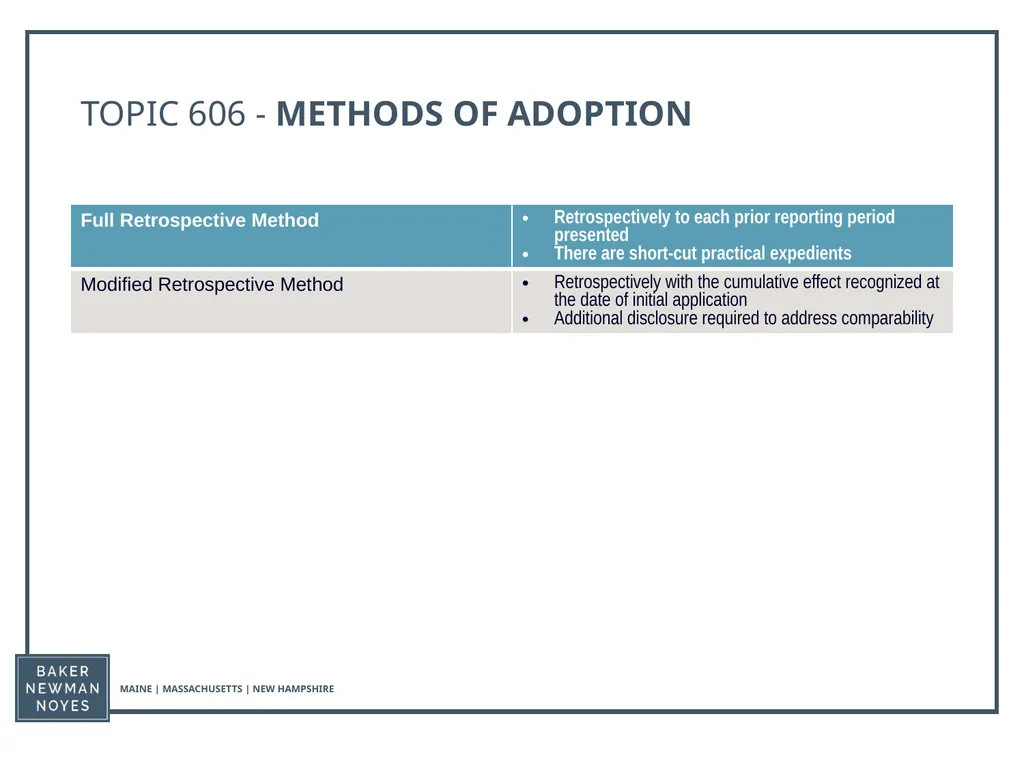
TOPIC 606 - METHODS OF ADOPTION<br>
22
TOPIC 842 - LEASE ACCOUNTING CHANGE<br>
23
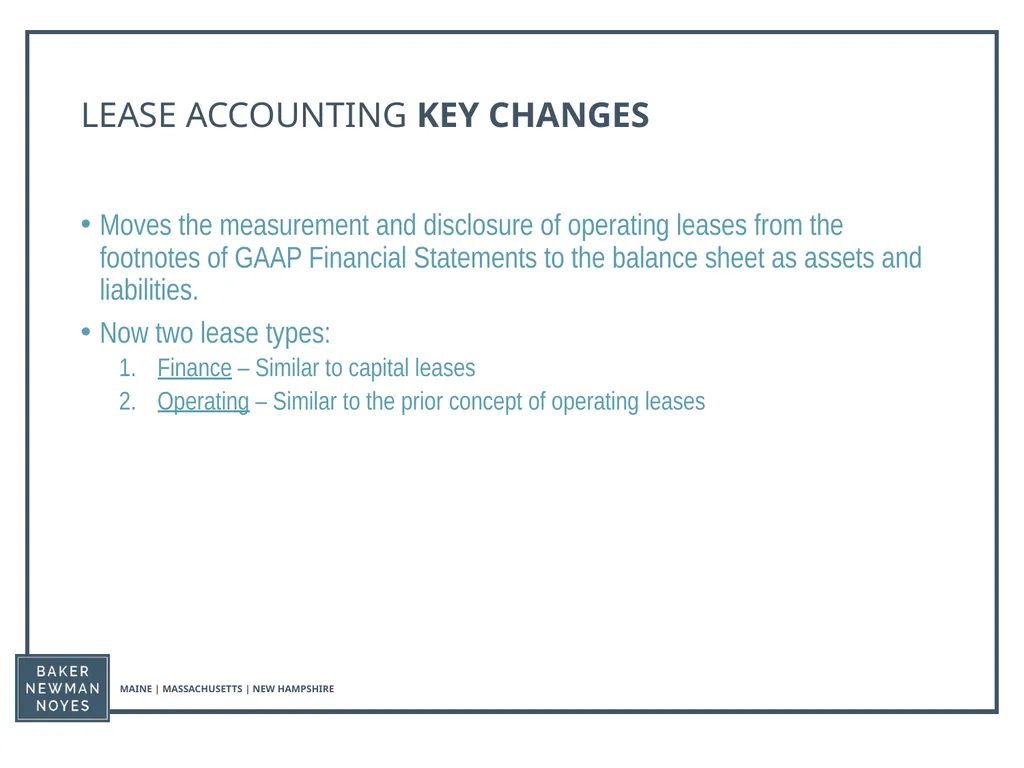
LEASE ACCOUNTING KEY CHANGES Moves the measurement and disclosure of operating leases from the footnotes of GAAP Financial Statements to the balance sheet as assets and liabilities.
Now two lease types:
Finance – Similar to capital leases
Operating – Similar to the prior concept of operating leases<br>
Now two lease types:
Finance – Similar to capital leases
Operating – Similar to the prior concept of operating leases<br>
24
LEASES – WHAT TO BE DOING NOW<br>
25
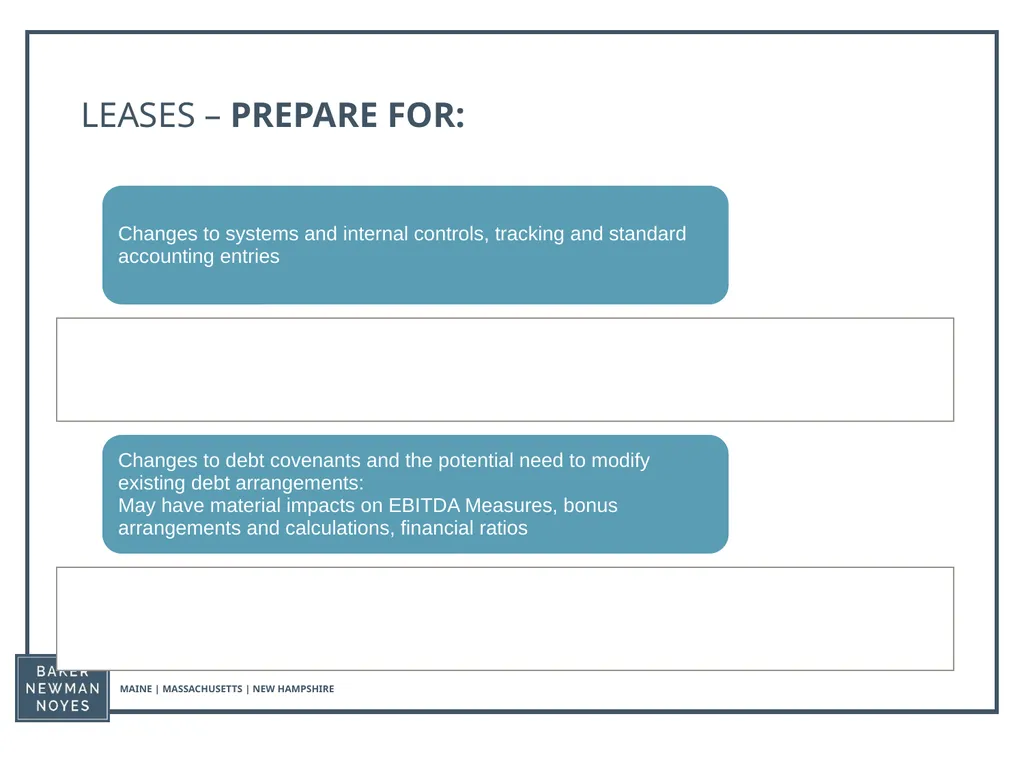
LEASES – PREPARE FOR:<br>
26
KEY CONCEPTS - LEASING<br>
27
ACCOUNTING FOR THE LEASE Recognition of long-term leases as assets and liabilities
Lease payment liability
Right to use asset
Measurements include (if reasonably certain)
Options to extend
Options to purchase
Operating leases – cash payments as operating activities
Finance Leases – cash payments as financing activities
Initial direct costs are included in the lease payments and capitalized
Discount rates can be:
Rate implicit in the lease unless the rate cannot be easily determined or
An incremental borrowing rate or
Private companies can make an accounting policy election to use a risk-free discount rate for the lease<br>
Lease payment liability
Right to use asset
Measurements include (if reasonably certain)
Options to extend
Options to purchase
Operating leases – cash payments as operating activities
Finance Leases – cash payments as financing activities
Initial direct costs are included in the lease payments and capitalized
Discount rates can be:
Rate implicit in the lease unless the rate cannot be easily determined or
An incremental borrowing rate or
Private companies can make an accounting policy election to use a risk-free discount rate for the lease<br>
28
SHORT-TERM LEASES Lessees can make a measurement exception accounting policy election for short-term leases with a term of 12 months or less that does not contain an option to purchase the underlying asset that the lessee is reasonably certain to exercise.<br>
29
ASU 2016-18: CASH FLOWS AND RESTRICTED CASH These amendments require that a statement of cash flows explain the change during the period in the total of cash, cash equivalents, and amounts generally described as restricted cash or restricted cash equivalents.
As a result, amounts generally described as restricted cash and restricted cash equivalents should be included with cash and cash equivalents when reconciling the beginning-of-period and end-of-period total amounts shown on the statement of cash flows.
The amendments do not provide a definition of restricted cash or restricted cash equivalents.<br>
As a result, amounts generally described as restricted cash and restricted cash equivalents should be included with cash and cash equivalents when reconciling the beginning-of-period and end-of-period total amounts shown on the statement of cash flows.
The amendments do not provide a definition of restricted cash or restricted cash equivalents.<br>
30
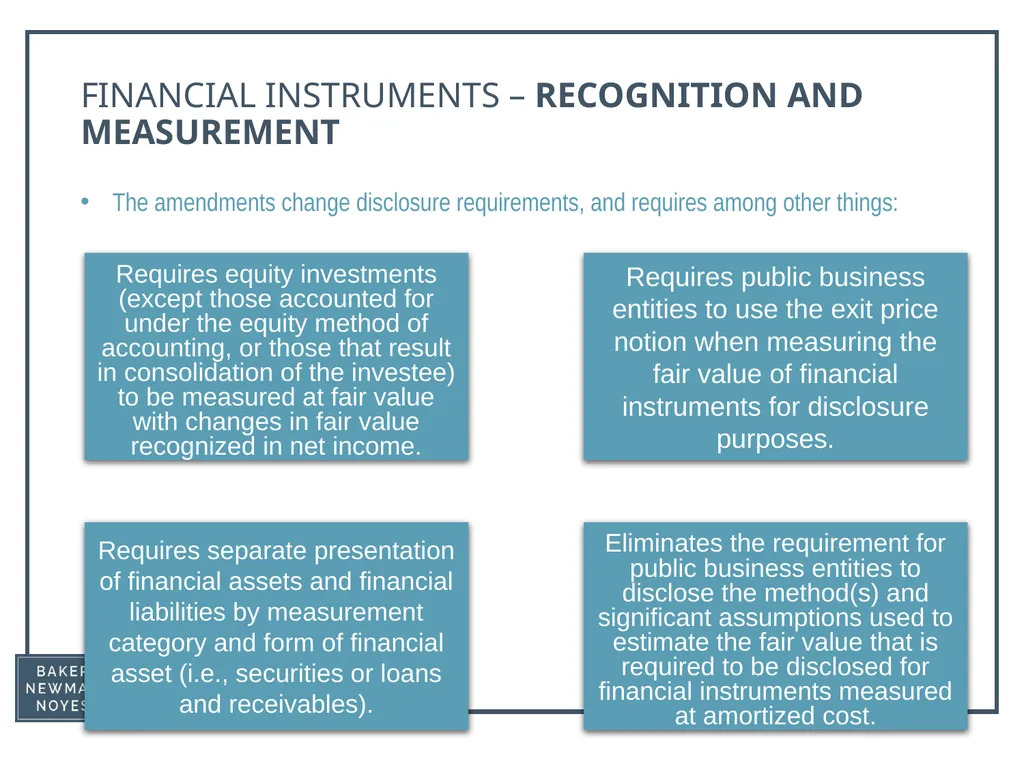
FINANCIAL INSTRUMENTS – RECOGNITION AND MEASUREMENT The amendments change disclosure requirements, and requires among other things:<br>
31
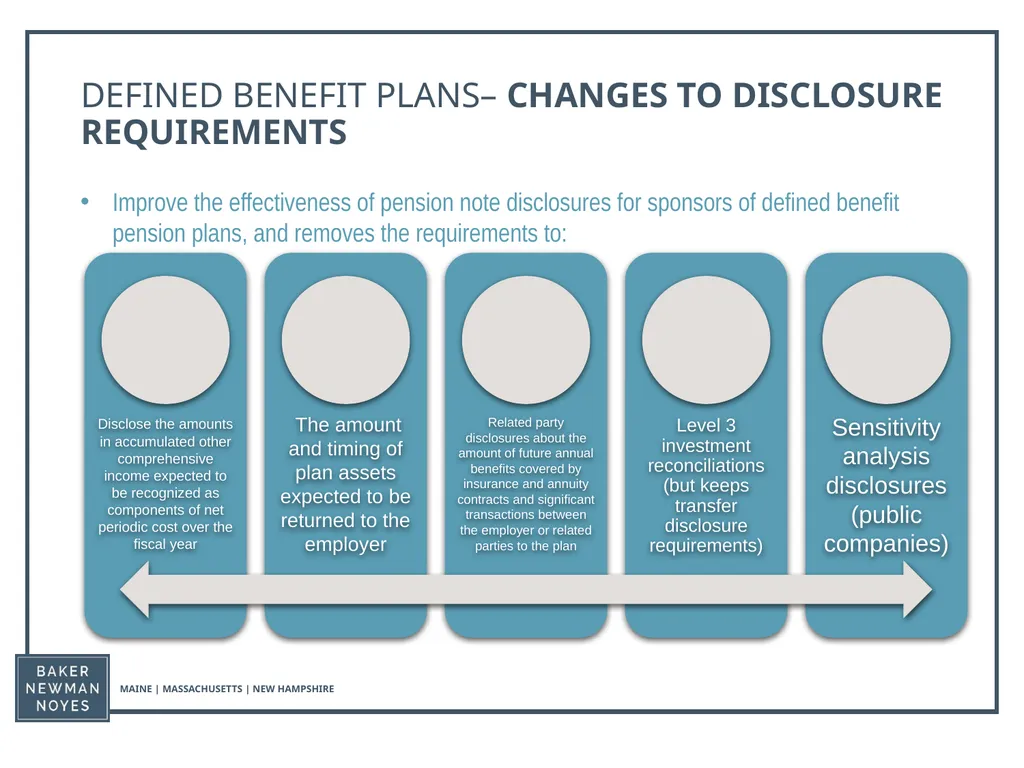
DEFINED BENEFIT PLANS– CHANGES TO DISCLOSURE REQUIREMENTS Improve the effectiveness of pension note disclosures for sponsors of defined benefit pension plans, and removes the requirements to:<br>
32
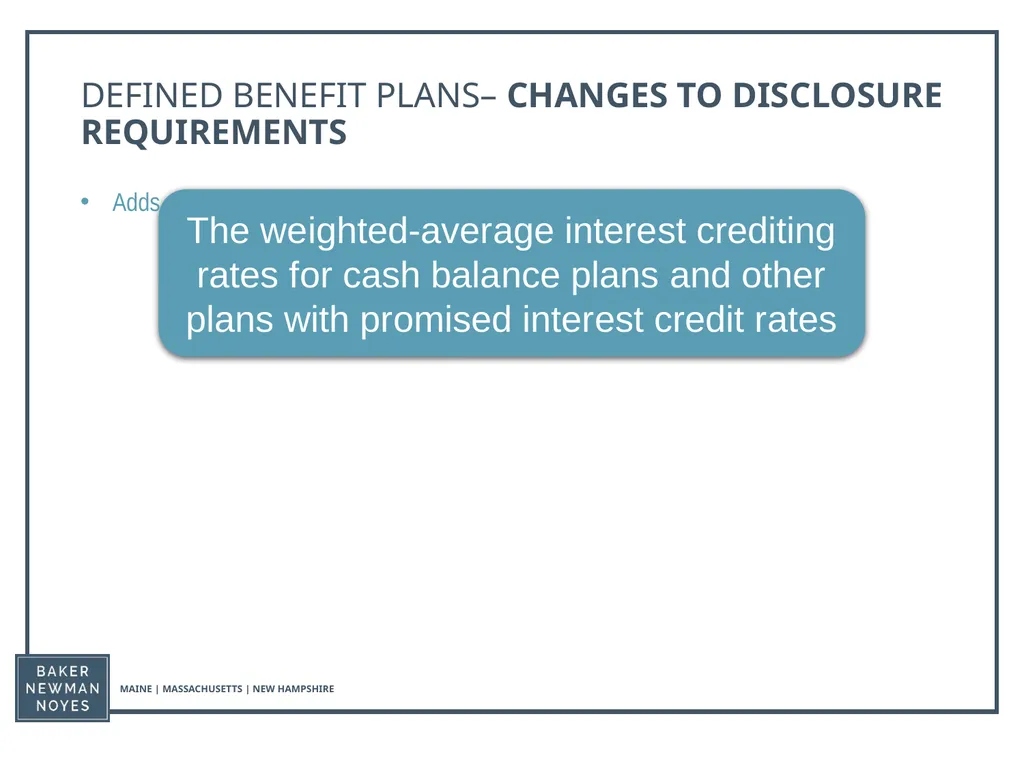
DEFINED BENEFIT PLANS– CHANGES TO DISCLOSURE REQUIREMENTS Adds requirements to disclose:<br>
33
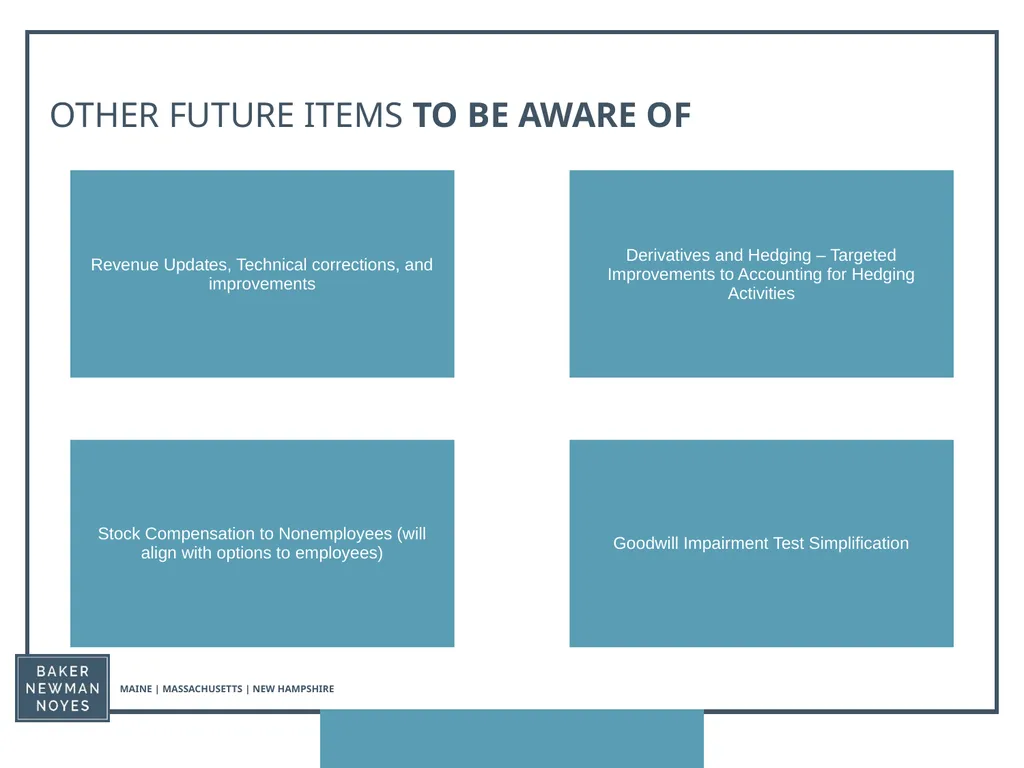
OTHER FUTURE ITEMS TO BE AWARE OF<br>
34
REGULATORY - SALES TAXES AND THE WAYFAIR DECISION For many years, the Quill decision limited states’ ability to tax sales made to customers in their states by out-of-state companies.
In 2018, the US Supreme Court eliminated the physical presence requirement for states to require businesses to collect and remit state sales tax, and established economic nexus as the sales tax nexus standard.
This means there is a responsibility for businesses to collect and remit sales taxes properly and in accordance with state and local jurisdiction laws (10,000 different jurisdictions in the U.S. each with different rates, rules, and regulations).<br>
In 2018, the US Supreme Court eliminated the physical presence requirement for states to require businesses to collect and remit state sales tax, and established economic nexus as the sales tax nexus standard.
This means there is a responsibility for businesses to collect and remit sales taxes properly and in accordance with state and local jurisdiction laws (10,000 different jurisdictions in the U.S. each with different rates, rules, and regulations).<br>
35
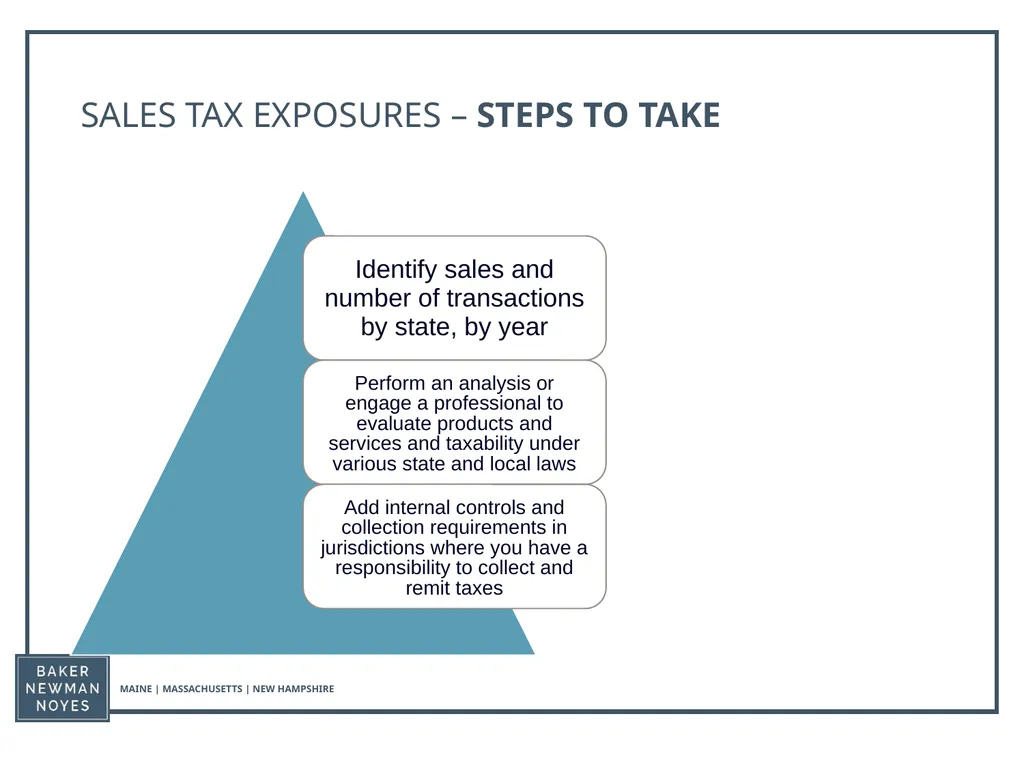
SALES TAX EXPOSURES – STEPS TO TAKE<br>
36
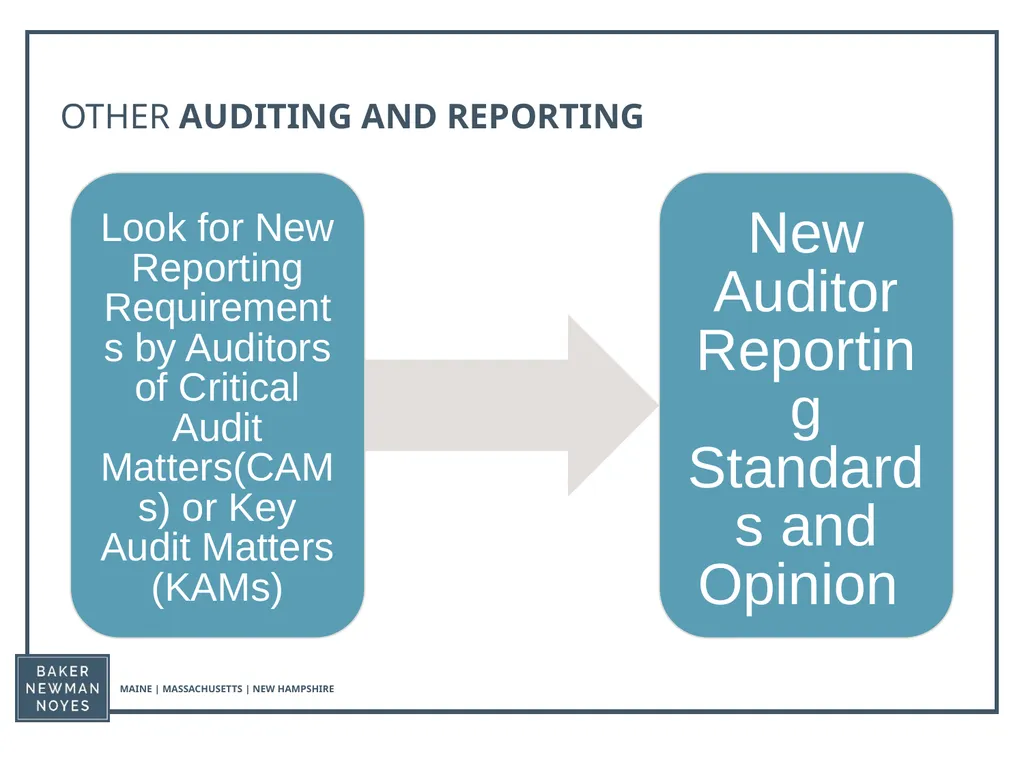
OTHER AUDITING AND REPORTING<br>
37
ABOUT US More than 250 employees
Strong reputation in our markets as a trusted business advisor
Ranked in Accounting Today and INSIDE Public Accounting’s lists of the top 100 firms in the U.S
Named one of the top 10 accounting firms in Boston by AdvisoryHQ
Our banking practice works with financial institutions across New England and beyond, including commercial and savings banks, community banks, SEC registered banks, credit unions, trust companies, non-depository trust companies and registered investment advisors.
Four offices located in Maine, Massachusetts, and New Hampshire
Through our membership in Baker Tilly International, a network of independent accounting and advisory firms, we have access to global resources with a seamless service approach delivered by a BNN lead principal<br>
Strong reputation in our markets as a trusted business advisor
Ranked in Accounting Today and INSIDE Public Accounting’s lists of the top 100 firms in the U.S
Named one of the top 10 accounting firms in Boston by AdvisoryHQ
Our banking practice works with financial institutions across New England and beyond, including commercial and savings banks, community banks, SEC registered banks, credit unions, trust companies, non-depository trust companies and registered investment advisors.
Four offices located in Maine, Massachusetts, and New Hampshire
Through our membership in Baker Tilly International, a network of independent accounting and advisory firms, we have access to global resources with a seamless service approach delivered by a BNN lead principal<br>
38
KEY INDUSTRIES Banking & Financial Services
Construction
Craft Beverage
Family-Owned Businesses
Governmental Agencies Healthcare
Manufacturing, Retail & Distribution
Not-for-profit & Foundations
Professional Services
Real Estate<br>
Construction
Craft Beverage
Family-Owned Businesses
Governmental Agencies Healthcare
Manufacturing, Retail & Distribution
Not-for-profit & Foundations
Professional Services
Real Estate<br>
39
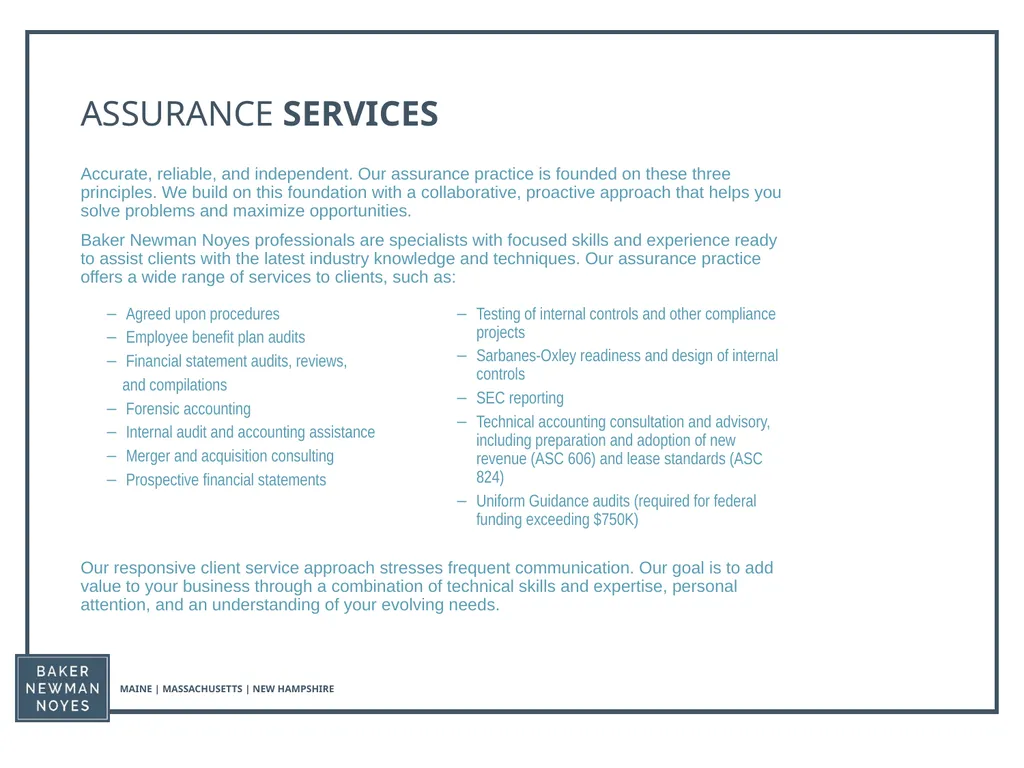
ASSURANCE SERVICES Accurate, reliable, and independent. Our assurance practice is founded on these three principles. We build on this foundation with a collaborative, proactive approach that helps you solve problems and maximize opportunities.
Baker Newman Noyes professionals are specialists with focused skills and experience ready to assist clients with the latest industry knowledge and techniques. Our assurance practice offers a wide range of services to clients, such as:
Our responsive client service approach stresses frequent communication. Our goal is to add value to your business through a combination of technical skills and expertise, personal attention, and an understanding of your evolving needs. Testing of internal controls and other compliance projects
Sarbanes-Oxley readiness and design of internal controls
SEC reporting
Technical accounting consultation and advisory, including preparation and adoption of new revenue (ASC 606) and lease standards (ASC 824)
Uniform Guidance audits (required for federal funding exceeding $750K) Agreed upon procedures
Employee benefit plan audits
Financial statement audits, reviews,
and compilations
Forensic accounting
Internal audit and accounting assistance
Merger and acquisition consulting
Prospective financial statements<br>
Baker Newman Noyes professionals are specialists with focused skills and experience ready to assist clients with the latest industry knowledge and techniques. Our assurance practice offers a wide range of services to clients, such as:
Our responsive client service approach stresses frequent communication. Our goal is to add value to your business through a combination of technical skills and expertise, personal attention, and an understanding of your evolving needs. Testing of internal controls and other compliance projects
Sarbanes-Oxley readiness and design of internal controls
SEC reporting
Technical accounting consultation and advisory, including preparation and adoption of new revenue (ASC 606) and lease standards (ASC 824)
Uniform Guidance audits (required for federal funding exceeding $750K) Agreed upon procedures
Employee benefit plan audits
Financial statement audits, reviews,
and compilations
Forensic accounting
Internal audit and accounting assistance
Merger and acquisition consulting
Prospective financial statements<br>
40
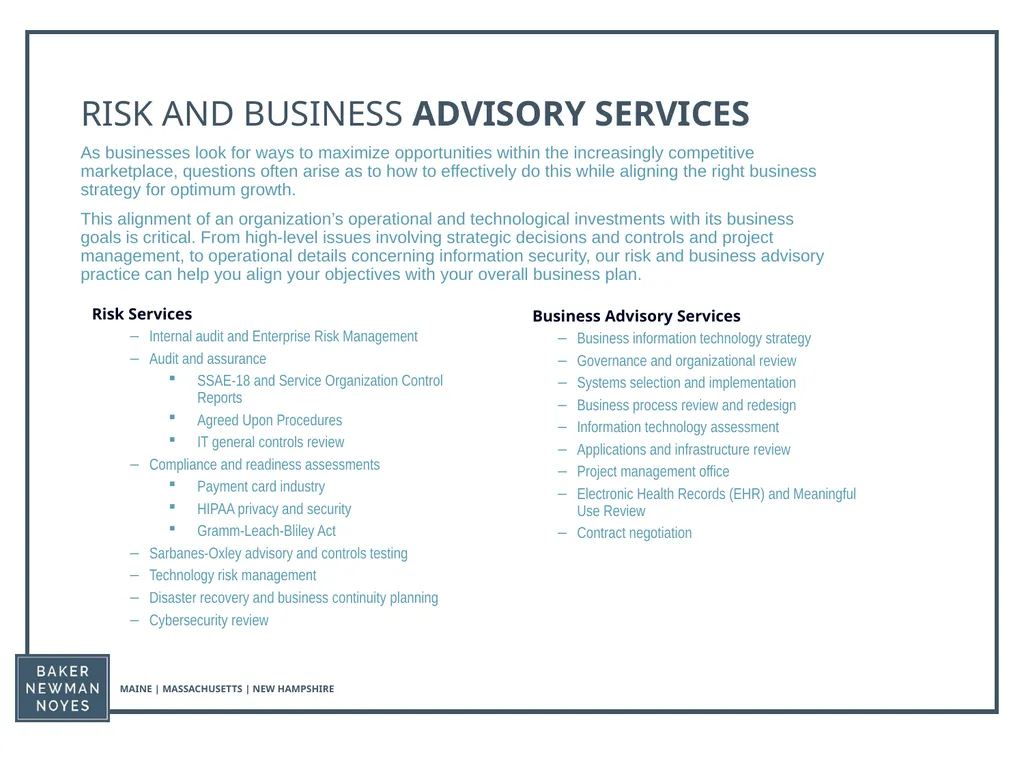
RISK AND BUSINESS ADVISORY SERVICES As businesses look for ways to maximize opportunities within the increasingly competitive marketplace, questions often arise as to how to effectively do this while aligning the right business strategy for optimum growth.
This alignment of an organization’s operational and technological investments with its business goals is critical. From high-level issues involving strategic decisions and controls and project management, to operational details concerning information security, our risk and business advisory practice can help you align your objectives with your overall business plan. Business Advisory Services
Business information technology strategy
Governance and organizational review
Systems selection and implementation
Business process review and redesign
Information technology assessment
Applications and infrastructure review
Project management office
Electronic Health Records (EHR) and Meaningful Use Review
Contract negotiation Risk Services
Internal audit and Enterprise Risk Management
Audit and assurance
SSAE-18 and Service Organization Control Reports
Agreed Upon Procedures
IT general controls review
Compliance and readiness assessments
Payment card industry
HIPAA privacy and security
Gramm-Leach-Bliley Act
Sarbanes-Oxley advisory and controls testing
Technology risk management
Disaster recovery and business continuity planning
Cybersecurity review<br>
This alignment of an organization’s operational and technological investments with its business goals is critical. From high-level issues involving strategic decisions and controls and project management, to operational details concerning information security, our risk and business advisory practice can help you align your objectives with your overall business plan. Business Advisory Services
Business information technology strategy
Governance and organizational review
Systems selection and implementation
Business process review and redesign
Information technology assessment
Applications and infrastructure review
Project management office
Electronic Health Records (EHR) and Meaningful Use Review
Contract negotiation Risk Services
Internal audit and Enterprise Risk Management
Audit and assurance
SSAE-18 and Service Organization Control Reports
Agreed Upon Procedures
IT general controls review
Compliance and readiness assessments
Payment card industry
HIPAA privacy and security
Gramm-Leach-Bliley Act
Sarbanes-Oxley advisory and controls testing
Technology risk management
Disaster recovery and business continuity planning
Cybersecurity review<br>
41
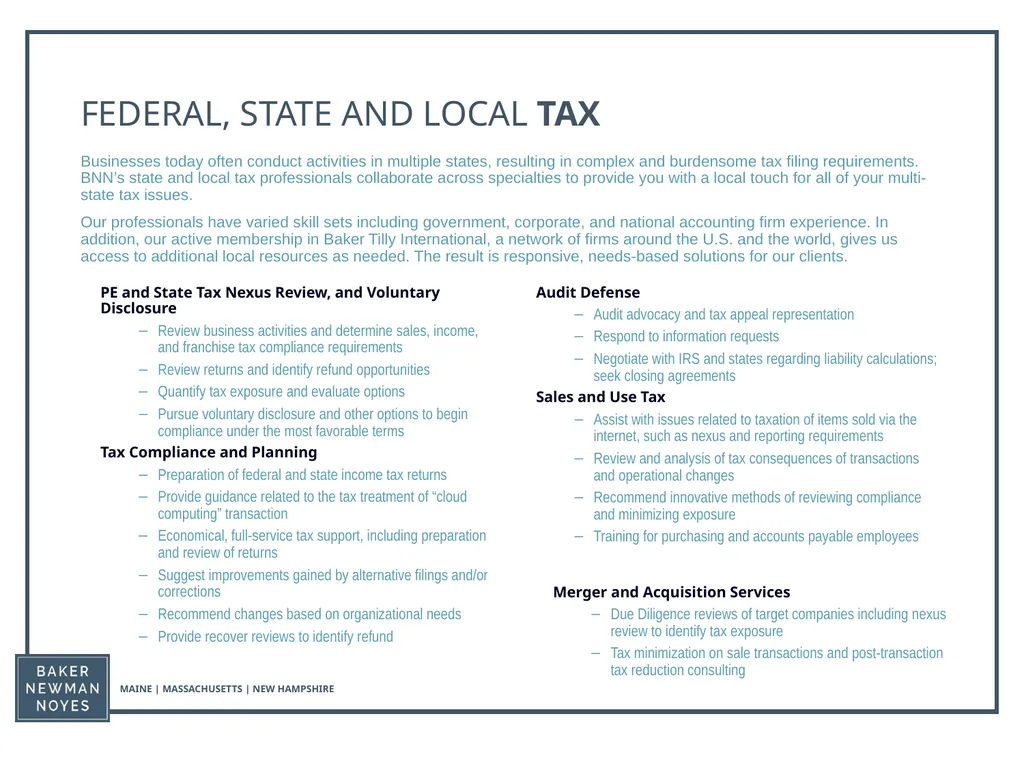
FEDERAL, STATE AND LOCAL TAX Businesses today often conduct activities in multiple states, resulting in complex and burdensome tax filing requirements. BNN’s state and local tax professionals collaborate across specialties to provide you with a local touch for all of your multi-state tax issues.
Our professionals have varied skill sets including government, corporate, and national accounting firm experience. In addition, our active membership in Baker Tilly International, a network of firms around the U.S. and the world, gives us access to additional local resources as needed. The result is responsive, needs-based solutions for our clients. PE and State Tax Nexus Review, and Voluntary Disclosure
Review business activities and determine sales, income, and franchise tax compliance requirements
Review returns and identify refund opportunities
Quantify tax exposure and evaluate options
Pursue voluntary disclosure and other options to begin compliance under the most favorable terms
Tax Compliance and Planning
Preparation of federal and state income tax returns
Provide guidance related to the tax treatment of “cloud computing” transaction
Economical, full-service tax support, including preparation and review of returns
Suggest improvements gained by alternative filings and/or corrections
Recommend changes based on organizational needs
Provide recover reviews to identify refund Audit Defense
Audit advocacy and tax appeal representation
Respond to information requests
Negotiate with IRS and states regarding liability calculations; seek closing agreements
Sales and Use Tax
Assist with issues related to taxation of items sold via the internet, such as nexus and reporting requirements
Review and analysis of tax consequences of transactions and operational changes
Recommend innovative methods of reviewing compliance and minimizing exposure
Training for purchasing and accounts payable employees Merger and Acquisition Services
Due Diligence reviews of target companies including nexus review to identify tax exposure
Tax minimization on sale transactions and post-transaction tax reduction consulting<br>
Our professionals have varied skill sets including government, corporate, and national accounting firm experience. In addition, our active membership in Baker Tilly International, a network of firms around the U.S. and the world, gives us access to additional local resources as needed. The result is responsive, needs-based solutions for our clients. PE and State Tax Nexus Review, and Voluntary Disclosure
Review business activities and determine sales, income, and franchise tax compliance requirements
Review returns and identify refund opportunities
Quantify tax exposure and evaluate options
Pursue voluntary disclosure and other options to begin compliance under the most favorable terms
Tax Compliance and Planning
Preparation of federal and state income tax returns
Provide guidance related to the tax treatment of “cloud computing” transaction
Economical, full-service tax support, including preparation and review of returns
Suggest improvements gained by alternative filings and/or corrections
Recommend changes based on organizational needs
Provide recover reviews to identify refund Audit Defense
Audit advocacy and tax appeal representation
Respond to information requests
Negotiate with IRS and states regarding liability calculations; seek closing agreements
Sales and Use Tax
Assist with issues related to taxation of items sold via the internet, such as nexus and reporting requirements
Review and analysis of tax consequences of transactions and operational changes
Recommend innovative methods of reviewing compliance and minimizing exposure
Training for purchasing and accounts payable employees Merger and Acquisition Services
Due Diligence reviews of target companies including nexus review to identify tax exposure
Tax minimization on sale transactions and post-transaction tax reduction consulting<br>
42
INTERNATIONAL TAX Baker Newman Noyes’ professionals direct and advise clients regarding international taxation and business matters allowing them to negotiate challenges in the global marketplace and take advantage of tax planning opportunities. WE CAN HELP YOU WITH: Business entity selection and structuring
Transfer pricing planning and studies
Subpart F income determinations
Foreign tax reduction and credit planning
Income tax treaty planning
Repatriation tax consequences
U.S. income tax deferral planning
Foreign tax withholding obligations
Foreign investment in U.S. real property
Estate tax planning for non-U.S. persons
Foreign persons working in the U.S. U.S. employees working abroad
Export incentives including IC-DISC appropriateness
Earnings stripping limitation calculations and other interest rules
Comprehensive services for individuals including expatriates and foreign nationals
U.S. withholding tax obligations on payments to foreign businesses and persons
Planning for international transaction taxes such as VAT, GST and HST
Compliance for U.S. international tax reporting for IRS Forms 5471, 5472, 8858, 8865, 926<br>
Transfer pricing planning and studies
Subpart F income determinations
Foreign tax reduction and credit planning
Income tax treaty planning
Repatriation tax consequences
U.S. income tax deferral planning
Foreign tax withholding obligations
Foreign investment in U.S. real property
Estate tax planning for non-U.S. persons
Foreign persons working in the U.S. U.S. employees working abroad
Export incentives including IC-DISC appropriateness
Earnings stripping limitation calculations and other interest rules
Comprehensive services for individuals including expatriates and foreign nationals
U.S. withholding tax obligations on payments to foreign businesses and persons
Planning for international transaction taxes such as VAT, GST and HST
Compliance for U.S. international tax reporting for IRS Forms 5471, 5472, 8858, 8865, 926<br>
43
THOUGHT LEADERSHIP We publish a variety of service and industry-related newsletters and blogs, including our BNN Briefing, which includes audit, tax and general business updates. For more information, visit www.bnncpa.com/resources.<br>
44
Thank You for Your Time<br>