
ALTERNATIVE TAX REGIME BY CMA S VENKANNA COST


Description: ALTERNATIVE TAX REGIME BY CMA S VENKANNA COST ACCOUNTANT 18052021 ICMAI Behind Every Successful Business Decision, There Is Always A CMA Introduction A progressive tax is a tax system that increases rates as the taxable income goes up. It
Related Topics
Download Presentation
"ALTERNATIVE TAX REGIME BY CMA S VENKANNA COST" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. ALTERNATIVE TAX REGIME BY
CMA S VENKANNA
COST ACCOUNTANT 18/05/2021 ICMAI Behind Every Successful Business Decision, There Is Always A CMA<br>
slide2. Introduction A progressive tax is a tax system that increases rates as the taxable income goes up.
It is divided into tax brackets that progress to successively higher rates.
For example, a progressive tax rate may move from the lowest and highest brackets, as the taxable amount increases.
In a progressive tax system, a taxpayer’s marginal tax rate is higher than their average tax rate. 18/05/2021 ICMAI<br>
slide3. Methods Various tax methods that governments may use include progressive, regressive, digressive, or proportional.
The Progressive Tax System is one where the tax burden increases as taxable income increases.
In some cases, there is a minimum tax-free income where individuals earning less than the stated minimum taxable amount are not liable for any payments to tax authorities.
The opposite of the progressive system is the regressive tax rate
Here tax liability reduces as the taxable amount increases.
Regardless of the rate used, the government aims to collect money from citizens. 18/05/2021 ICMAI<br>
slide4. Economist’s View Progressive tax imposes a higher percentage rate on taxpayers who have higher incomes.
The U.S. income tax system is an example.
A regressive tax imposes the same rate on all taxpayers, regardless of ability to pay.
GST is an example. 18/05/2021 ICMAI<br>
slide5. Alternative Tax Regime At present available to both
Corporate Sector - from the year AY 2017-18
Required Corporate Tax Planning
Sec.115BA
Sec.115BAA
Section BAB
Non corporate sector
From AY 201-22
Tax Planning to Non Corporate Sector
Sec.115BAC
Sec.115BAD 18/05/2021 ICMAI<br>
slide6. Maximum Marginal Rate of Tax All assesses
30% Plus Applicable Surcharge Plus HEC at 4% 18/05/2021 ICMAI<br>
slide7. Corporate Sector – Part I Section 115BA - Conditions
Applicable to Domestic Company
Company in the manufacturing or production of articles or things
Company Registered or afte lst March 2016
First Assessment Year - from the Assessment Year 2017-18
Gross Receipts or Turnover should not exceed Rs.400 crores in in the year 2017-28 (Rs.250 crores for the year 2016-17)
However MAT under section 115JB Applicable
Companie does not opt for section 115BAA then it shall be chargeable to tax at the rate of 25% plus applicable surcharge and health & education cess.
The surcharge in such a case shall be 7% or 12% when the total income of the company exceeds Rs. 1 crores or Rs. 10 crores, respectively. 18/05/2021 ICMAI<br>
slide8. Sec.115 BA Conditions Total Income is computed without claiming the following:
Section 10AA – 100% profit exemption for an undertaking in SEZ
Sec.32AC – Additional deduction of 15% Investment Allowance on investment in new Plant and Machinery Investment more than Rs.25 crores)
This section is not applicable from the 2018-19.
Sec.32AD- 15% deduction in backward states in AP, Bihar, Telengarana and West Bengal.
Sec.33AB – Deduction upto 40% on deposit of profit in a special account at NABARD – Applicable to Companies, in Coffee, Tea and Rubber Development 18/05/2021 ICMAI<br>
slide9. Sec.33ABA – deduction upto 20% of the profit in special account at SBI – Site Restorate Fund. (Miners Oil extraction)
Sec.35(1)
(ii) (iia) (iii) – 100% deduction of payment made to approved Scientific Research
Sec.35(2AA) and (2AB) – payment made to National Laboratory or University or Indian Institute of Technology.
Sec.35AC – deduction on payment to another public company for eligible project or scheme.
Sec.35AD- deduction available towards any capital expenditure, wholly and exclusively, incurred for carrying on a specified business 18/05/2021 ICMAI<br>
slide10. Sec.35CCC – Deduction for Expenditure incurred on Notified Agricultural Extension Project
Sec.35CCD – provides deduction towards expenditure incurred on the skill development project
However Deduction under section 80JJAA available regarding deduction of salaries paid to newly recruited employees.
Losses: Brought Forward losses not available for deductions
Option cannot be withdrawn. But can be shifted to Sec.115BAA 18/05/2021 ICMAI<br>
slide11. Section 80H : Deduction in case of new industrial undertakings employing displaced persons, etc.
Section 80HH : Deduction in respect of profits and gains from newly established industrial undertakings or hotel business in backward areas
Section 80HHA : Deduction in respect of profits and gains from newly established small-scale industrial undertakings in certain areas
Section 80HHB : Deduction in respect of profits and gains from projects outside India
Section 80HHBA : Deduction in respect of profits and gains from housing projects in certain cases
Section 80HHC : Deduction in respect of profits retained for export business
Section 80HHD : Deduction in respect of earnings in convertible foreign exchange
Section 80HHE : Deduction in respect of profits from export of computer software, etc.
Section 80HHF : Deduction in respect of profits and gains from export or transfer of film software, etc.
Section 80I : Deduction in respect of profits and gains from industrial undertakings after a certain date, et
Section 80IA : Deductions in respect of profits and gains from industrial undertakings or enterprises engaged in infrastructure development, etc.
Section 80IAB : Deductions in respect of profits and gains by an undertaking or enterprise engaged in development of Special Economic Zone
Section 80IAC : Special provision in respect of specified business.
Section 80IB : Deduction in respect of profits and gains from certain industrial undertakings other than infrastructure development undertakings
Section 80IBA : Deductions in respect of profits and gains from housing projects.
Section 80IC : Special provisions in respect of certain undertakings or enterprises in certain special category of states
Section 80ID : Deduction in respect of profits and gains from business of hotels and convention centres in specified area 18/05/2021 ICMAI<br>
slide12. Section 80IE : Special provisions in respect of certain undertakings in North-Eastern States
Section 80JJA : Deduction in respect of profits and gains from business of collecting and processing of bio-degradable waste
Section 80JJAA : Deduction in respect of employment of new employees
Section 80LA : Deductions in respect of certain incomes of Offshore Banking Units and International Financial Services Centre
Section 80O : Deduction in respect of royalties, etc., from certain foreign enterprises
Section 80P : Deduction in respect of income of co-operative societies
Section 80Q : Deduction in respect of profits and gains from the business of publication of books
Section 80QQA : Deduction in respect of professional income of authors of text books in Indian languages
Section 80QQB : Deduction in respect of royalty income, etc., of authors of certain books other than text-books
Section 80R : Deduction in respect of remuneration from certain foreign sources in the case of professors, teachers, etc.
Section 80RR : Deduction in respect of professional income from foreign sources in certain cases
Section 80RRA : Deduction in respect of remuneration received for services rendered outside India
Section 80RRB : Deduction in respect of royalty on patents 18/05/2021 ICMAI<br>
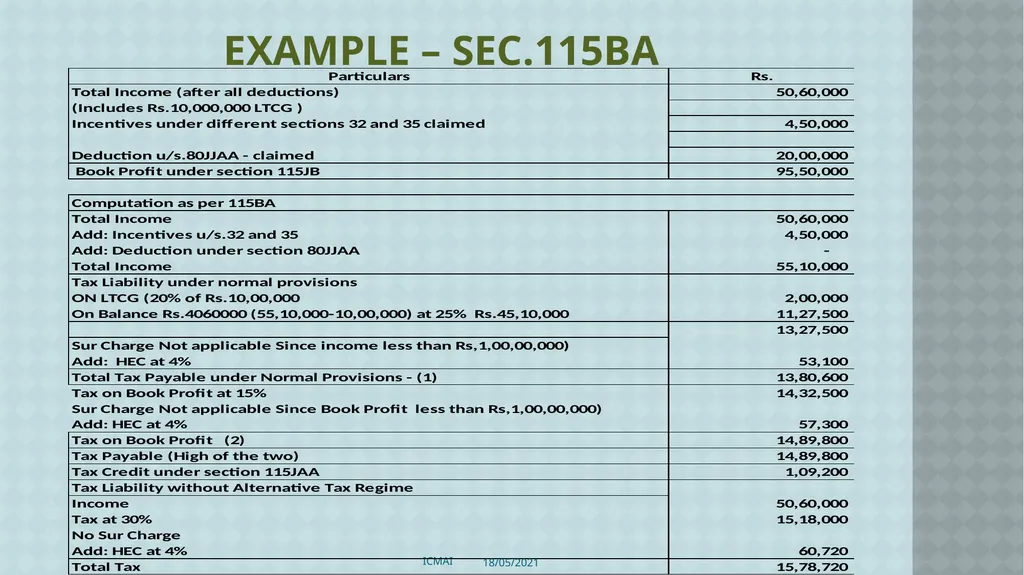
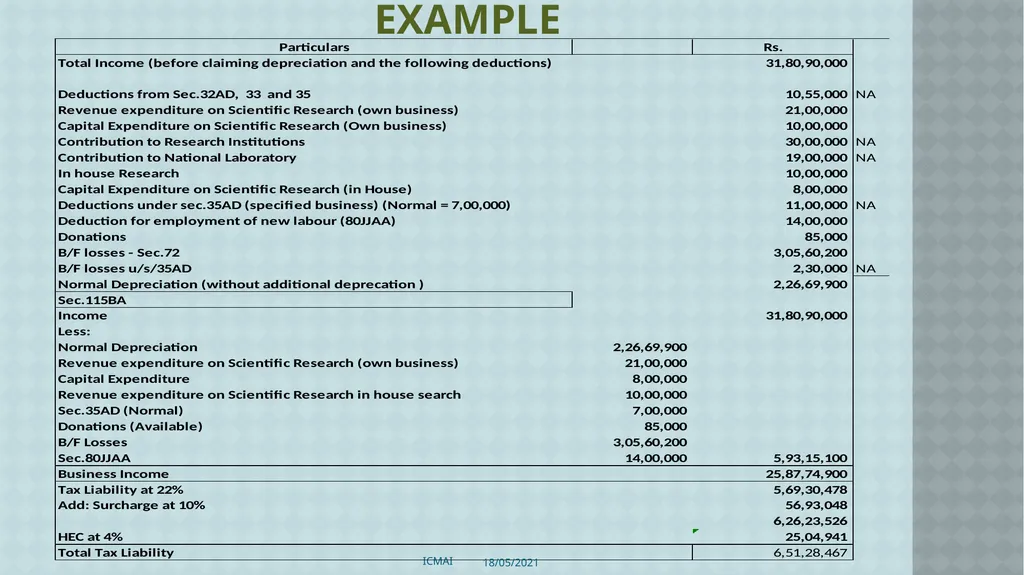
slide13. Example – Sec.115BA 18/05/2021 ICMAI<br>
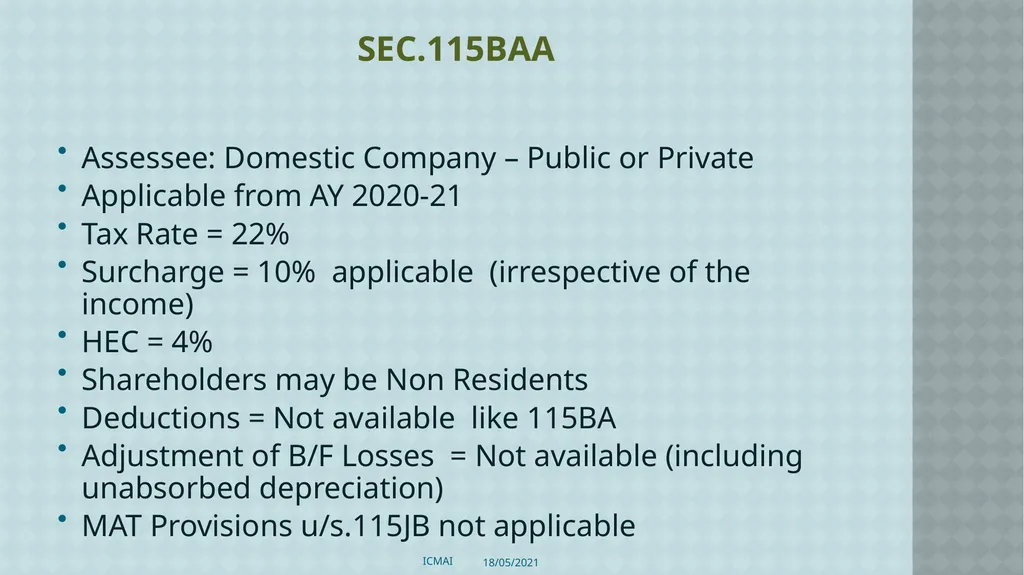
slide14. Sec.115BAA Assessee: Domestic Company – Public or Private
Applicable from AY 2020-21
Tax Rate = 22%
Surcharge = 10% applicable (irrespective of the income)
HEC = 4%
Shareholders may be Non Residents
Deductions = Not available like 115BA
Adjustment of B/F Losses = Not available (including unabsorbed depreciation)
MAT Provisions u/s.115JB not applicable 18/05/2021 ICMAI<br>
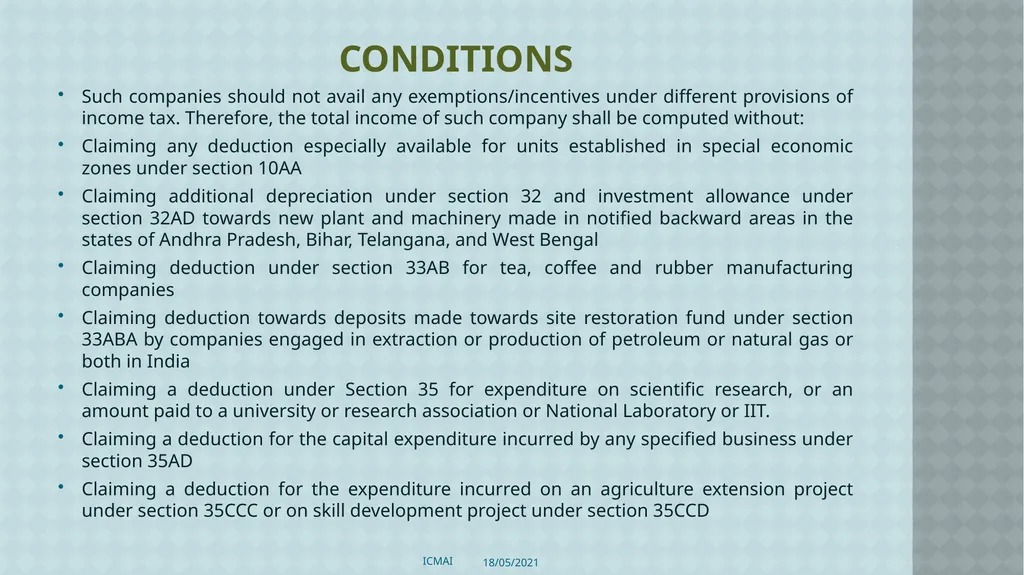
slide15. Conditions Such companies should not avail any exemptions/incentives under different provisions of income tax. Therefore, the total income of such company shall be computed without:
Claiming any deduction especially available for units established in special economic zones under section 10AA
Claiming additional depreciation under section 32 and investment allowance under section 32AD towards new plant and machinery made in notified backward areas in the states of Andhra Pradesh, Bihar, Telangana, and West Bengal
Claiming deduction under section 33AB for tea, coffee and rubber manufacturing companies
Claiming deduction towards deposits made towards site restoration fund under section 33ABA by companies engaged in extraction or production of petroleum or natural gas or both in India
Claiming a deduction under Section 35 for expenditure on scientific research, or an amount paid to a university or research association or National Laboratory or IIT.
Claiming a deduction for the capital expenditure incurred by any specified business under section 35AD
Claiming a deduction for the expenditure incurred on an agriculture extension project under section 35CCC or on skill development project under section 35CCD 18/05/2021 ICMAI<br>
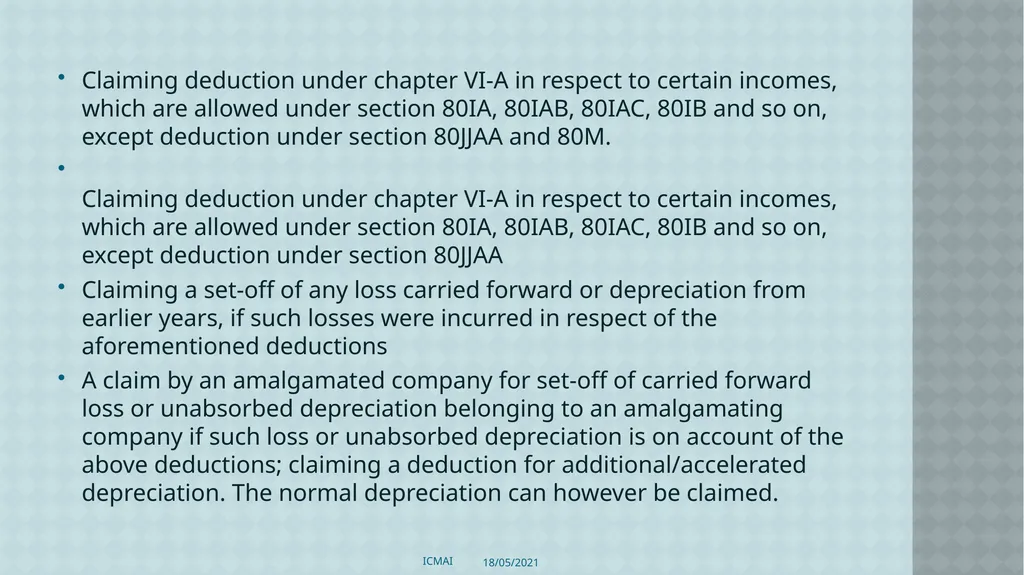
slide16. Claiming deduction under chapter VI-A in respect to certain incomes, which are allowed under section 80IA, 80IAB, 80IAC, 80IB and so on, except deduction under section 80JJAA and 80M.
Claiming deduction under chapter VI-A in respect to certain incomes, which are allowed under section 80IA, 80IAB, 80IAC, 80IB and so on, except deduction under section 80JJAA
Claiming a set-off of any loss carried forward or depreciation from earlier years, if such losses were incurred in respect of the aforementioned deductions
A claim by an amalgamated company for set-off of carried forward loss or unabsorbed depreciation belonging to an amalgamating company if such loss or unabsorbed depreciation is on account of the above deductions; claiming a deduction for additional/accelerated depreciation. The normal depreciation can however be claimed. 18/05/2021 ICMAI<br>
slide17. Carry forward of losses The above losses shall be deemed to have been allowed and shall not be eligible for carry forward and set off in subsequent years this means that if the company opts for 115BAA then the opportunity for claiming set off is lost forever;
There is no restriction on turnover and the company need not be a new company, any existing company can migrate into this section at any point. 18/05/2021 ICMAI<br>
slide18. Opting out The domestic companies who do not wish to avail this concessional rate immediately can opt for the same after the expiry of their tax holiday period or exemptions/incentives.
However, once such a company opts for the concessional tax rate under section 115BAA of the Income Tax Act,1961, it cannot be subsequently withdrawn. 18/05/2021 ICMAI<br>
slide19. Example 18/05/2021 ICMAI<br>
slide20. Sec.115BAB Tax Rate = 15% on income from manufacturing activity
Tax Rate = Non manufacturing Activity = 22%
STCG = non depreciable assets = 22%
STCG = Depreciable Asset = 15%
Any other Income = 30%
Surcharge at 10% plus HEC
Applicable to Domestic Company Registered after 1.10.2019
Manufacturing Company only (new Company only)(not formed under Reconstruction Scheme)
Does not use old plant and machinery (but imported second machinery allowed)
Manufacture does not include
Software
Mining
Marble
Gas bottling
Printing
Any other notified
No adjustment for B/F losses 18/05/2021 ICMAI<br>
slide21. Others If the Company does not opt in the first year
Ineligible in the next year
Option cannot be withdrawn
If there is a default in the conditions, no option in subsequent year 18/05/2021 ICMAI<br>
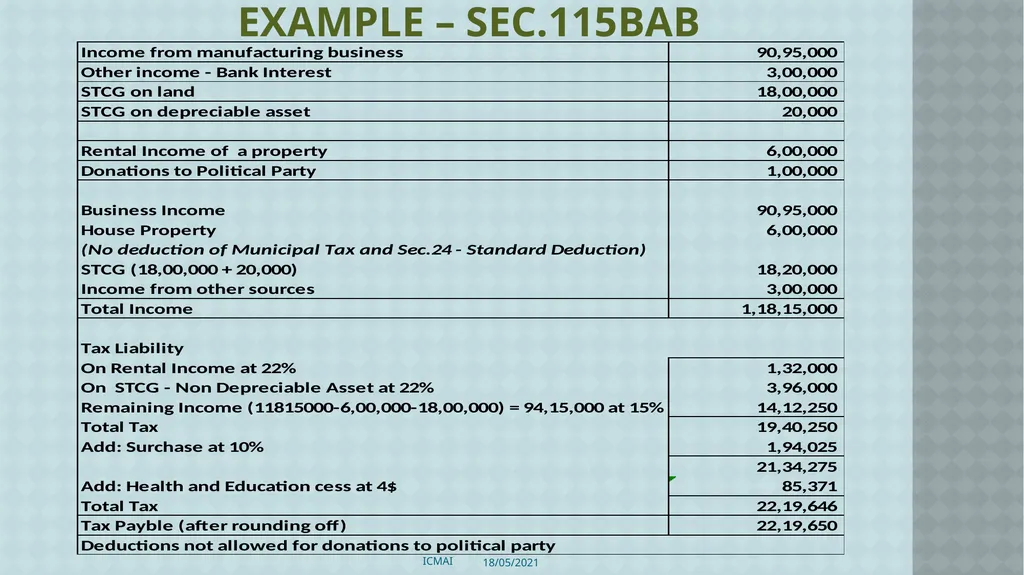
slide22. Example – Sec.115BAB 18/05/2021 ICMAI<br>
slide23. Non Corporate Sector – Part II Sec.115BAC
Applicable to Individuals and HUF
From Assessment year 2021-22
Sec.115BAD
Applicable to Co-Operative Societies
From Assessment Year 2021-22 18/05/2021 ICMAI<br>
slide24. Sec.115BAC – Income from Individuals and HUF Normal Tax Rate
Upto Rs.2,50,000 = Nil
Upto Rs.5,00,000 = 5%%
Upto Rs.10,00,000 = 20%
Tax Rebate = 87A (if the income is less than Rs.5,00,000) 100% Rs.12,500
Surcharge upto income of Rs.50 lakhs = Nil
Surcharge at 10% above Income of Rs.50.00 upto Rs.1.00 Crore
Surcharge at 15% From Rs.1 crore to Rs.2.00 crore
Surcharge at 25% from Rs.2 crores to 5 Crores
Surcharge at 37% if the income exceeds Rs.5,00,000 (u/s.115BAC)
Health and Education at 4%
Exemption to Resident Senior Citizen = Rs.3,00,000 and Resident Super Citizen Rs.5,00,000 available. 18/05/2021 ICMAI<br>
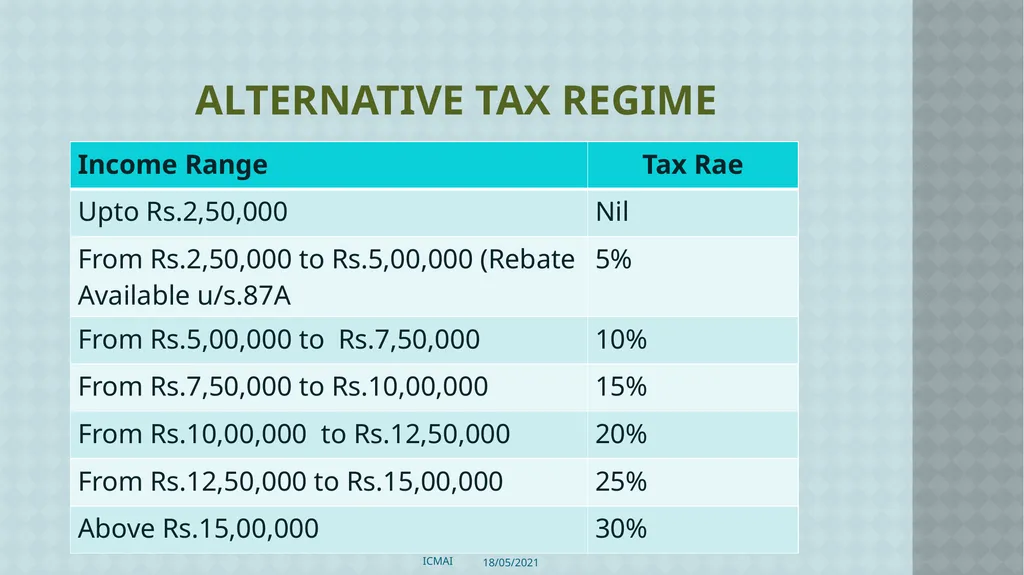
slide25. Alternative Tax Regime 18/05/2021 ICMAI<br>
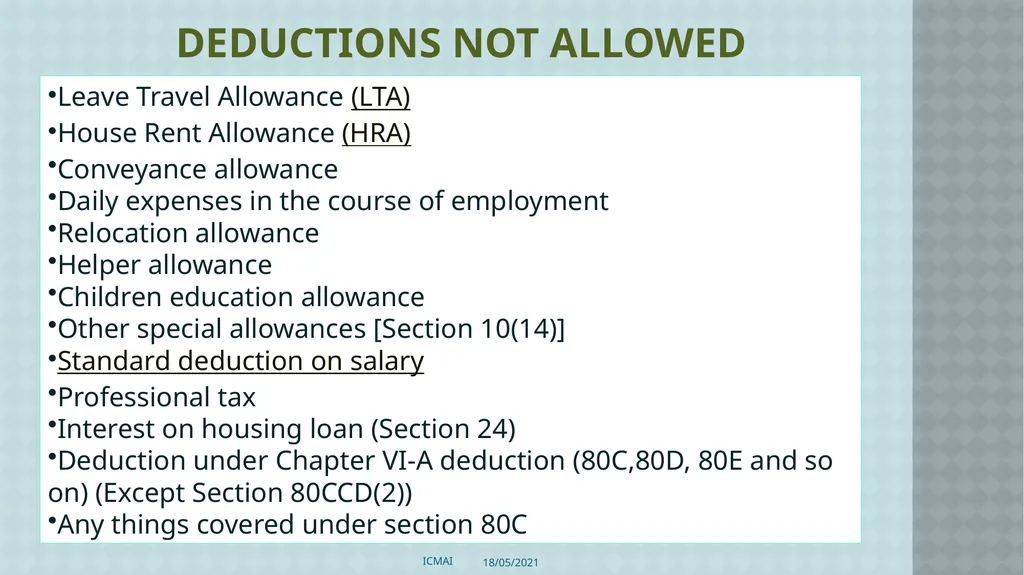
slide26. Deductions not allowed Leave Travel Allowance (LTA)
House Rent Allowance (HRA)
Conveyance allowance
Daily expenses in the course of employment
Relocation allowance
Helper allowance
Children education allowance
Other special allowances [Section 10(14)]
Standard deduction on salary
Professional tax
Interest on housing loan (Section 24)
Deduction under Chapter VI-A deduction (80C,80D, 80E and so on) (Except Section 80CCD(2))
Any things covered under section 80C 18/05/2021 ICMAI<br>
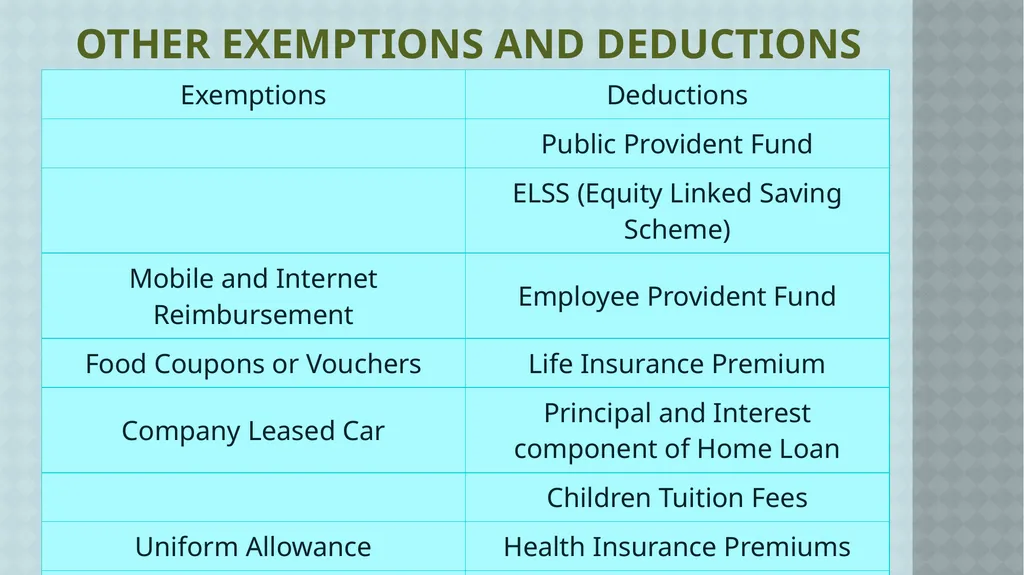
slide27. Other Exemptions and Deductions 18/05/2021 ICMAI<br>
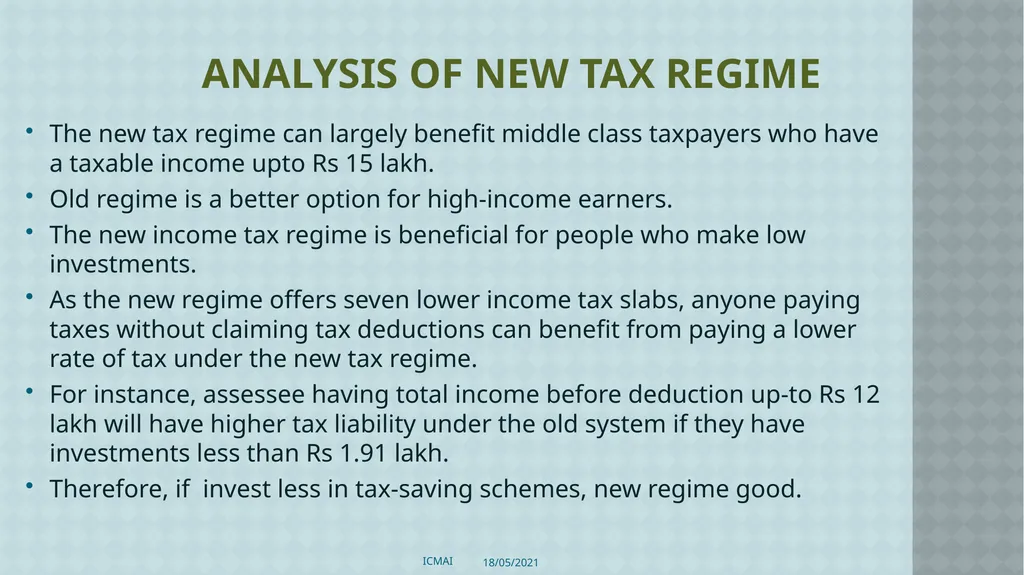
slide28. Analysis of New Tax Regime The new tax regime can largely benefit middle class taxpayers who have a taxable income upto Rs 15 lakh.
Old regime is a better option for high-income earners.
The new income tax regime is beneficial for people who make low investments.
As the new regime offers seven lower income tax slabs, anyone paying taxes without claiming tax deductions can benefit from paying a lower rate of tax under the new tax regime.
For instance, assessee having total income before deduction up-to Rs 12 lakh will have higher tax liability under the old system if they have investments less than Rs 1.91 lakh.
Therefore, if invest less in tax-saving schemes, new regime good. 18/05/2021 ICMAI<br>
slide29. Time of Selection Employees
An employee can opt the new tax regime and intimate their employer in the beginning of FY 2020-21 .
Employees can change the option of selecting the tax regime every year
However if new tax slab regime is opted at the begning of the year, it cannot be changed anytime during the year for TDS purpose.
However the option can be changed at the time of filing of Income-tax return.
Assessees with business or profession
the option to choose between the new tax regimes is available only once for a particular business. 18/05/2021 ICMAI<br>
slide30. Which one is better No one Answer
Calculate all the exemptions that you are availing:
Claiming HRA is the important salary exemption.
Apart from that, other tax-free components include LTA, Food Bill, Phone Bills, etc. All these will become taxable if you choose to shift to the new tax regime.
Look at the deductions that you claim:
A salaried employee, two deductions that you automatically get are
Standard deduction of Rs 50,000 and
Contribution towards your Employee Provident Fund (EPF).
In the new regime, cannot claim these deductions.
Cannot claim deductions against home loan or insurance policies, which till now has helped to reduce your taxable income. 18/05/2021 ICMAI<br>
slide31. New Regime The new tax regime is only useful for those who have liquidity problem and are not able to avail full benefits of Section 80 C and who do not have any health insurance as well as do not have any home loan running.
The new regime may be suitable for only a handful of self-employed or an HUF.
The self-employed do not have the choice to come back to old tax regime once the new one is opted unless they stop having business income.
Hence the person with business income has to be very careful while migrating to new regime as it is only one way. 18/05/2021 ICMAI<br>
slide32. Person with business income The new tax regime is optional for tax payers, they can evaluate their tax liability under both regime and can choose more beneficial regime from A.Y.2021-22 or any subsequent year.
However, for the taxpayers having income from business or profession cannot switch between the new tax regime and regular tax regimes every year.
If the taxpayer having income from business or profession opts for the new tax regime, such taxpayers get only one chance in their lifetime to come back to the regular tax regime and will not be eligible for opting new tax regime again, unless the taxpayer’s business income ceases to exist. 18/05/2021 ICMAI<br>
slide33. Assessment proceedings Tax payers are now free to formulate better investment and insurance strategies rather than depending on tax saving instruments for the purpose of saving taxes.
In case of assessment proceedings before the tax authorities, documentation and proof of investments is required to be retained in the old regime, which may not be required in the new regime. 18/05/2021 ICMAI<br>
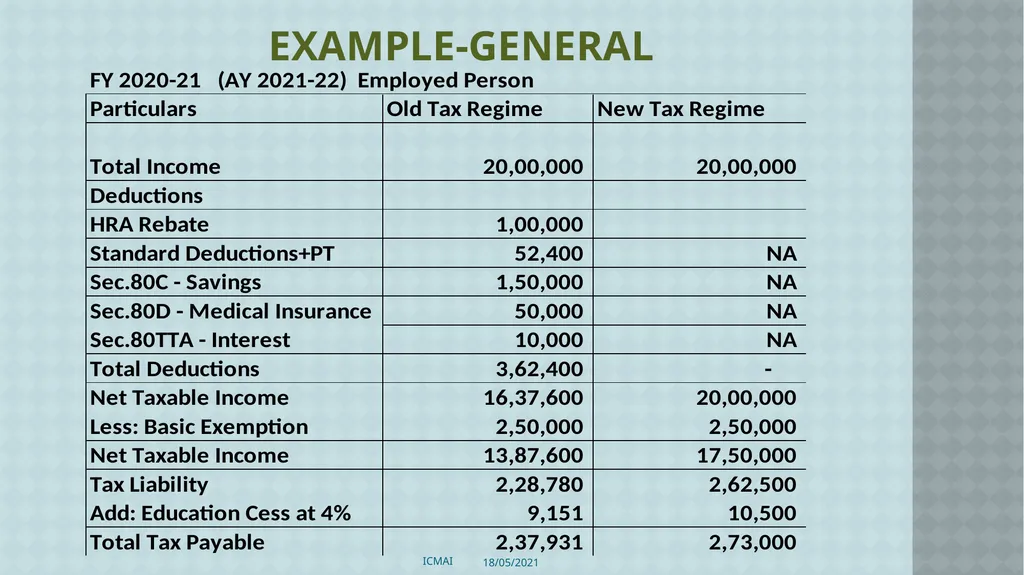
slide34. Example-General 18/05/2021 ICMAI<br>
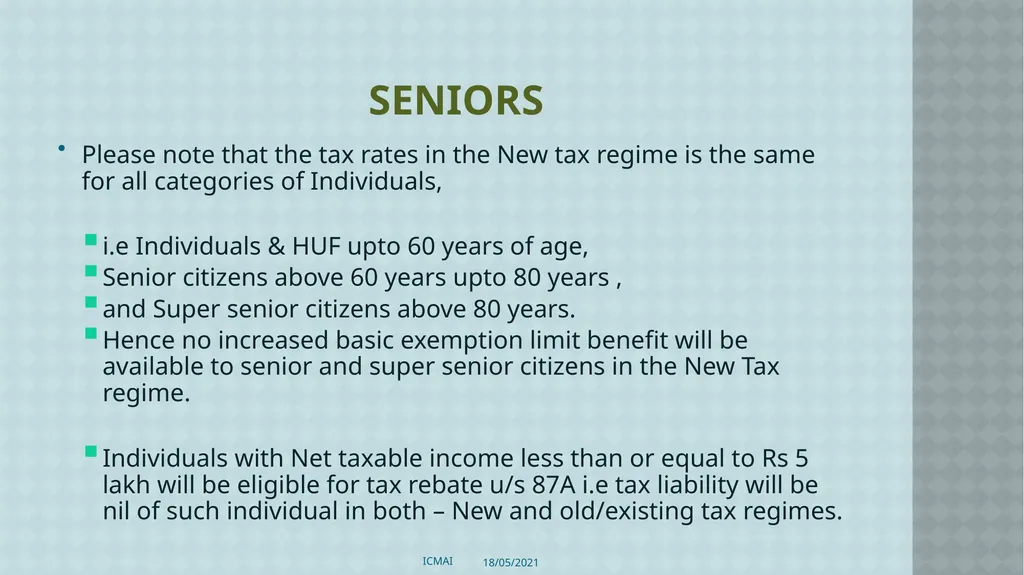
slide35. Seniors Please note that the tax rates in the New tax regime is the same for all categories of Individuals,
i.e Individuals & HUF upto 60 years of age,
Senior citizens above 60 years upto 80 years ,
and Super senior citizens above 80 years.
Hence no increased basic exemption limit benefit will be available to senior and super senior citizens in the New Tax regime.
Individuals with Net taxable income less than or equal to Rs 5 lakh will be eligible for tax rebate u/s 87A i.e tax liability will be nil of such individual in both – New and old/existing tax regimes. 18/05/2021 ICMAI<br>
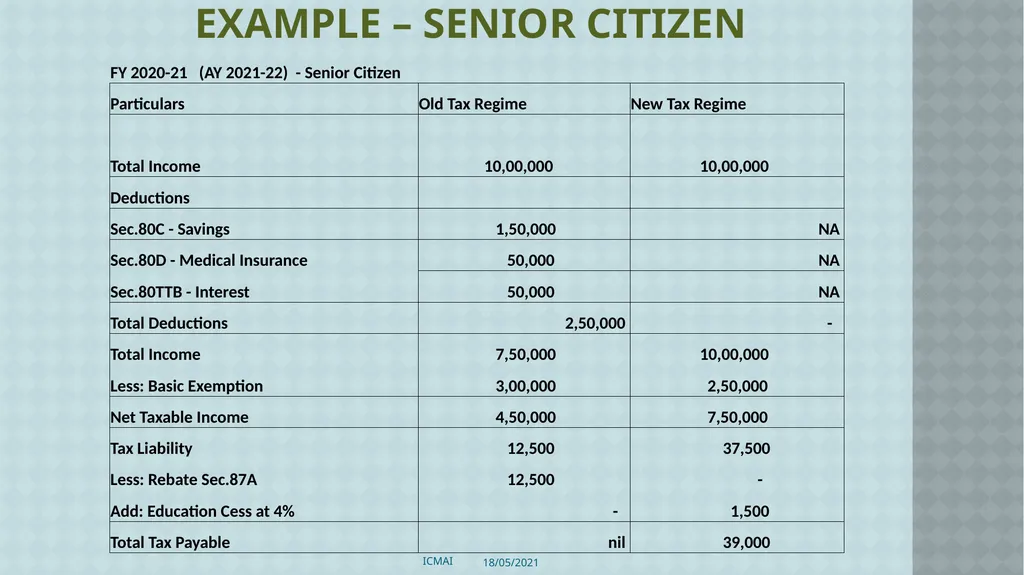
slide36. Example – Senior Citizen 18/05/2021 ICMAI<br>
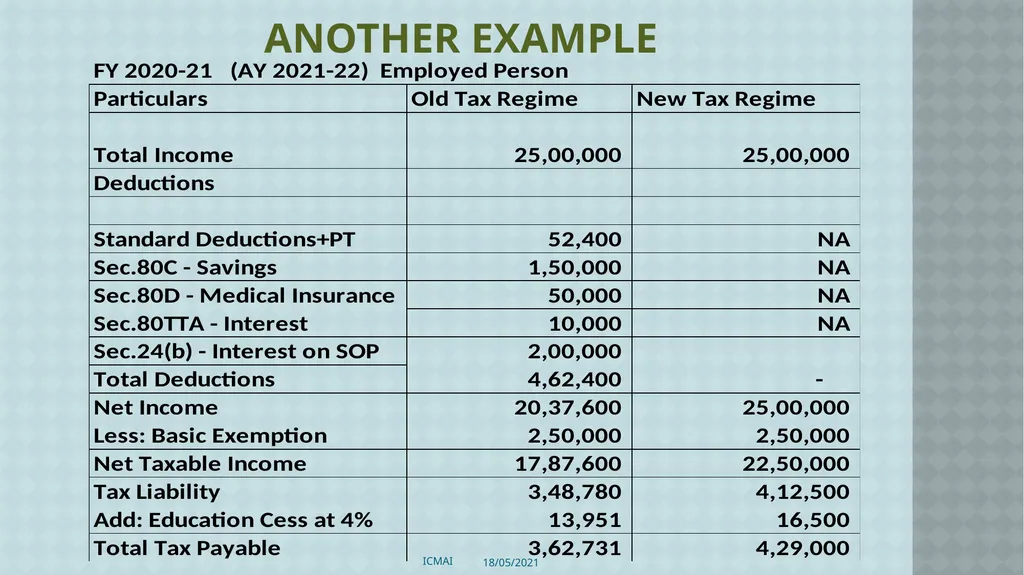
slide37. Another Example 18/05/2021 ICMAI<br>
slide38. House Property in New Tax Regime In case of a self-occupied property, does not allow to claim a deduction on interest for a housing loan. The deduction of Rs 2 lakh allowed in the existing system is not available in the new tax regime.
Also, the set-off of the loss of Rs 2 lakh from house property from salary income is not allowed.
In case of let-out a house property, the deductions on municipal tax, standard deduction of 30% and interest paid on housing loan is restricted till the rental income.
Hence, the excess interest paid on housing loan will result in loss under the head income from house property.
However, this loss cannot be set-off against any other head of income. Also, cannot carry forward the loss from house property to future years for set off. 18/05/2021 ICMAI<br>
slide39. Sec.115BAD – Co-operative Societies Currently, the co-operative societies are taxed at the slab rates and the highest slab rate is 30% which applies when income exceeds Rs. 20,000.
To bring parity between the co-operative societies and domestic companies, section 115BAD has been proposed to be inserted in Income-tax Act to provide an option to the co-operative societies to get taxed at the rate of 22% plus 10% surcharge and 4% cess. 18/05/2021 ICMAI<br>
slide40. Provisions in brief without providing for specified exemption, deduction or incentive available under the Act.
The societies opting for this section have been kept out of the purview of Alternate Minimum Tax (AMT).
Further, the provision relating to computation, carry forward and set-off of AMT credit shall not apply to these assessees.
Where a co-operative society exercises option for availing benefit of lower tax rate under section 115BAD, it shall not be allowed to claim set-off of any brought forward losses or depreciation attributable to any restricted exemption or deduction in the Assessment Year for which the option has been exercised and for any subsequent Assessment Year. 18/05/2021 ICMAI<br>
slide41. Filing Filing of Form no. 10-IF The Resident Co-Operative Society exercising the option to apply section 115BAD in computing its income is required to furnish in Form no. 10-IF. Such form shall be furnished electronically using the digital signature or Electronic Verification Code(EVC).
************************************************************************** Behind Every Successful Business Decision, There Is Always A CMA<br>
CMA S VENKANNA
COST ACCOUNTANT 18/05/2021 ICMAI Behind Every Successful Business Decision, There Is Always A CMA<br>
slide2. Introduction A progressive tax is a tax system that increases rates as the taxable income goes up.
It is divided into tax brackets that progress to successively higher rates.
For example, a progressive tax rate may move from the lowest and highest brackets, as the taxable amount increases.
In a progressive tax system, a taxpayer’s marginal tax rate is higher than their average tax rate. 18/05/2021 ICMAI<br>
slide3. Methods Various tax methods that governments may use include progressive, regressive, digressive, or proportional.
The Progressive Tax System is one where the tax burden increases as taxable income increases.
In some cases, there is a minimum tax-free income where individuals earning less than the stated minimum taxable amount are not liable for any payments to tax authorities.
The opposite of the progressive system is the regressive tax rate
Here tax liability reduces as the taxable amount increases.
Regardless of the rate used, the government aims to collect money from citizens. 18/05/2021 ICMAI<br>
slide4. Economist’s View Progressive tax imposes a higher percentage rate on taxpayers who have higher incomes.
The U.S. income tax system is an example.
A regressive tax imposes the same rate on all taxpayers, regardless of ability to pay.
GST is an example. 18/05/2021 ICMAI<br>
slide5. Alternative Tax Regime At present available to both
Corporate Sector - from the year AY 2017-18
Required Corporate Tax Planning
Sec.115BA
Sec.115BAA
Section BAB
Non corporate sector
From AY 201-22
Tax Planning to Non Corporate Sector
Sec.115BAC
Sec.115BAD 18/05/2021 ICMAI<br>
slide6. Maximum Marginal Rate of Tax All assesses
30% Plus Applicable Surcharge Plus HEC at 4% 18/05/2021 ICMAI<br>
slide7. Corporate Sector – Part I Section 115BA - Conditions
Applicable to Domestic Company
Company in the manufacturing or production of articles or things
Company Registered or afte lst March 2016
First Assessment Year - from the Assessment Year 2017-18
Gross Receipts or Turnover should not exceed Rs.400 crores in in the year 2017-28 (Rs.250 crores for the year 2016-17)
However MAT under section 115JB Applicable
Companie does not opt for section 115BAA then it shall be chargeable to tax at the rate of 25% plus applicable surcharge and health & education cess.
The surcharge in such a case shall be 7% or 12% when the total income of the company exceeds Rs. 1 crores or Rs. 10 crores, respectively. 18/05/2021 ICMAI<br>
slide8. Sec.115 BA Conditions Total Income is computed without claiming the following:
Section 10AA – 100% profit exemption for an undertaking in SEZ
Sec.32AC – Additional deduction of 15% Investment Allowance on investment in new Plant and Machinery Investment more than Rs.25 crores)
This section is not applicable from the 2018-19.
Sec.32AD- 15% deduction in backward states in AP, Bihar, Telengarana and West Bengal.
Sec.33AB – Deduction upto 40% on deposit of profit in a special account at NABARD – Applicable to Companies, in Coffee, Tea and Rubber Development 18/05/2021 ICMAI<br>
slide9. Sec.33ABA – deduction upto 20% of the profit in special account at SBI – Site Restorate Fund. (Miners Oil extraction)
Sec.35(1)
(ii) (iia) (iii) – 100% deduction of payment made to approved Scientific Research
Sec.35(2AA) and (2AB) – payment made to National Laboratory or University or Indian Institute of Technology.
Sec.35AC – deduction on payment to another public company for eligible project or scheme.
Sec.35AD- deduction available towards any capital expenditure, wholly and exclusively, incurred for carrying on a specified business 18/05/2021 ICMAI<br>
slide10. Sec.35CCC – Deduction for Expenditure incurred on Notified Agricultural Extension Project
Sec.35CCD – provides deduction towards expenditure incurred on the skill development project
However Deduction under section 80JJAA available regarding deduction of salaries paid to newly recruited employees.
Losses: Brought Forward losses not available for deductions
Option cannot be withdrawn. But can be shifted to Sec.115BAA 18/05/2021 ICMAI<br>
slide11. Section 80H : Deduction in case of new industrial undertakings employing displaced persons, etc.
Section 80HH : Deduction in respect of profits and gains from newly established industrial undertakings or hotel business in backward areas
Section 80HHA : Deduction in respect of profits and gains from newly established small-scale industrial undertakings in certain areas
Section 80HHB : Deduction in respect of profits and gains from projects outside India
Section 80HHBA : Deduction in respect of profits and gains from housing projects in certain cases
Section 80HHC : Deduction in respect of profits retained for export business
Section 80HHD : Deduction in respect of earnings in convertible foreign exchange
Section 80HHE : Deduction in respect of profits from export of computer software, etc.
Section 80HHF : Deduction in respect of profits and gains from export or transfer of film software, etc.
Section 80I : Deduction in respect of profits and gains from industrial undertakings after a certain date, et
Section 80IA : Deductions in respect of profits and gains from industrial undertakings or enterprises engaged in infrastructure development, etc.
Section 80IAB : Deductions in respect of profits and gains by an undertaking or enterprise engaged in development of Special Economic Zone
Section 80IAC : Special provision in respect of specified business.
Section 80IB : Deduction in respect of profits and gains from certain industrial undertakings other than infrastructure development undertakings
Section 80IBA : Deductions in respect of profits and gains from housing projects.
Section 80IC : Special provisions in respect of certain undertakings or enterprises in certain special category of states
Section 80ID : Deduction in respect of profits and gains from business of hotels and convention centres in specified area 18/05/2021 ICMAI<br>
slide12. Section 80IE : Special provisions in respect of certain undertakings in North-Eastern States
Section 80JJA : Deduction in respect of profits and gains from business of collecting and processing of bio-degradable waste
Section 80JJAA : Deduction in respect of employment of new employees
Section 80LA : Deductions in respect of certain incomes of Offshore Banking Units and International Financial Services Centre
Section 80O : Deduction in respect of royalties, etc., from certain foreign enterprises
Section 80P : Deduction in respect of income of co-operative societies
Section 80Q : Deduction in respect of profits and gains from the business of publication of books
Section 80QQA : Deduction in respect of professional income of authors of text books in Indian languages
Section 80QQB : Deduction in respect of royalty income, etc., of authors of certain books other than text-books
Section 80R : Deduction in respect of remuneration from certain foreign sources in the case of professors, teachers, etc.
Section 80RR : Deduction in respect of professional income from foreign sources in certain cases
Section 80RRA : Deduction in respect of remuneration received for services rendered outside India
Section 80RRB : Deduction in respect of royalty on patents 18/05/2021 ICMAI<br>
slide13. Example – Sec.115BA 18/05/2021 ICMAI<br>
slide14. Sec.115BAA Assessee: Domestic Company – Public or Private
Applicable from AY 2020-21
Tax Rate = 22%
Surcharge = 10% applicable (irrespective of the income)
HEC = 4%
Shareholders may be Non Residents
Deductions = Not available like 115BA
Adjustment of B/F Losses = Not available (including unabsorbed depreciation)
MAT Provisions u/s.115JB not applicable 18/05/2021 ICMAI<br>
slide15. Conditions Such companies should not avail any exemptions/incentives under different provisions of income tax. Therefore, the total income of such company shall be computed without:
Claiming any deduction especially available for units established in special economic zones under section 10AA
Claiming additional depreciation under section 32 and investment allowance under section 32AD towards new plant and machinery made in notified backward areas in the states of Andhra Pradesh, Bihar, Telangana, and West Bengal
Claiming deduction under section 33AB for tea, coffee and rubber manufacturing companies
Claiming deduction towards deposits made towards site restoration fund under section 33ABA by companies engaged in extraction or production of petroleum or natural gas or both in India
Claiming a deduction under Section 35 for expenditure on scientific research, or an amount paid to a university or research association or National Laboratory or IIT.
Claiming a deduction for the capital expenditure incurred by any specified business under section 35AD
Claiming a deduction for the expenditure incurred on an agriculture extension project under section 35CCC or on skill development project under section 35CCD 18/05/2021 ICMAI<br>
slide16. Claiming deduction under chapter VI-A in respect to certain incomes, which are allowed under section 80IA, 80IAB, 80IAC, 80IB and so on, except deduction under section 80JJAA and 80M.
Claiming deduction under chapter VI-A in respect to certain incomes, which are allowed under section 80IA, 80IAB, 80IAC, 80IB and so on, except deduction under section 80JJAA
Claiming a set-off of any loss carried forward or depreciation from earlier years, if such losses were incurred in respect of the aforementioned deductions
A claim by an amalgamated company for set-off of carried forward loss or unabsorbed depreciation belonging to an amalgamating company if such loss or unabsorbed depreciation is on account of the above deductions; claiming a deduction for additional/accelerated depreciation. The normal depreciation can however be claimed. 18/05/2021 ICMAI<br>
slide17. Carry forward of losses The above losses shall be deemed to have been allowed and shall not be eligible for carry forward and set off in subsequent years this means that if the company opts for 115BAA then the opportunity for claiming set off is lost forever;
There is no restriction on turnover and the company need not be a new company, any existing company can migrate into this section at any point. 18/05/2021 ICMAI<br>
slide18. Opting out The domestic companies who do not wish to avail this concessional rate immediately can opt for the same after the expiry of their tax holiday period or exemptions/incentives.
However, once such a company opts for the concessional tax rate under section 115BAA of the Income Tax Act,1961, it cannot be subsequently withdrawn. 18/05/2021 ICMAI<br>
slide19. Example 18/05/2021 ICMAI<br>
slide20. Sec.115BAB Tax Rate = 15% on income from manufacturing activity
Tax Rate = Non manufacturing Activity = 22%
STCG = non depreciable assets = 22%
STCG = Depreciable Asset = 15%
Any other Income = 30%
Surcharge at 10% plus HEC
Applicable to Domestic Company Registered after 1.10.2019
Manufacturing Company only (new Company only)(not formed under Reconstruction Scheme)
Does not use old plant and machinery (but imported second machinery allowed)
Manufacture does not include
Software
Mining
Marble
Gas bottling
Printing
Any other notified
No adjustment for B/F losses 18/05/2021 ICMAI<br>
slide21. Others If the Company does not opt in the first year
Ineligible in the next year
Option cannot be withdrawn
If there is a default in the conditions, no option in subsequent year 18/05/2021 ICMAI<br>
slide22. Example – Sec.115BAB 18/05/2021 ICMAI<br>
slide23. Non Corporate Sector – Part II Sec.115BAC
Applicable to Individuals and HUF
From Assessment year 2021-22
Sec.115BAD
Applicable to Co-Operative Societies
From Assessment Year 2021-22 18/05/2021 ICMAI<br>
slide24. Sec.115BAC – Income from Individuals and HUF Normal Tax Rate
Upto Rs.2,50,000 = Nil
Upto Rs.5,00,000 = 5%%
Upto Rs.10,00,000 = 20%
Tax Rebate = 87A (if the income is less than Rs.5,00,000) 100% Rs.12,500
Surcharge upto income of Rs.50 lakhs = Nil
Surcharge at 10% above Income of Rs.50.00 upto Rs.1.00 Crore
Surcharge at 15% From Rs.1 crore to Rs.2.00 crore
Surcharge at 25% from Rs.2 crores to 5 Crores
Surcharge at 37% if the income exceeds Rs.5,00,000 (u/s.115BAC)
Health and Education at 4%
Exemption to Resident Senior Citizen = Rs.3,00,000 and Resident Super Citizen Rs.5,00,000 available. 18/05/2021 ICMAI<br>
slide25. Alternative Tax Regime 18/05/2021 ICMAI<br>
slide26. Deductions not allowed Leave Travel Allowance (LTA)
House Rent Allowance (HRA)
Conveyance allowance
Daily expenses in the course of employment
Relocation allowance
Helper allowance
Children education allowance
Other special allowances [Section 10(14)]
Standard deduction on salary
Professional tax
Interest on housing loan (Section 24)
Deduction under Chapter VI-A deduction (80C,80D, 80E and so on) (Except Section 80CCD(2))
Any things covered under section 80C 18/05/2021 ICMAI<br>
slide27. Other Exemptions and Deductions 18/05/2021 ICMAI<br>
slide28. Analysis of New Tax Regime The new tax regime can largely benefit middle class taxpayers who have a taxable income upto Rs 15 lakh.
Old regime is a better option for high-income earners.
The new income tax regime is beneficial for people who make low investments.
As the new regime offers seven lower income tax slabs, anyone paying taxes without claiming tax deductions can benefit from paying a lower rate of tax under the new tax regime.
For instance, assessee having total income before deduction up-to Rs 12 lakh will have higher tax liability under the old system if they have investments less than Rs 1.91 lakh.
Therefore, if invest less in tax-saving schemes, new regime good. 18/05/2021 ICMAI<br>
slide29. Time of Selection Employees
An employee can opt the new tax regime and intimate their employer in the beginning of FY 2020-21 .
Employees can change the option of selecting the tax regime every year
However if new tax slab regime is opted at the begning of the year, it cannot be changed anytime during the year for TDS purpose.
However the option can be changed at the time of filing of Income-tax return.
Assessees with business or profession
the option to choose between the new tax regimes is available only once for a particular business. 18/05/2021 ICMAI<br>
slide30. Which one is better No one Answer
Calculate all the exemptions that you are availing:
Claiming HRA is the important salary exemption.
Apart from that, other tax-free components include LTA, Food Bill, Phone Bills, etc. All these will become taxable if you choose to shift to the new tax regime.
Look at the deductions that you claim:
A salaried employee, two deductions that you automatically get are
Standard deduction of Rs 50,000 and
Contribution towards your Employee Provident Fund (EPF).
In the new regime, cannot claim these deductions.
Cannot claim deductions against home loan or insurance policies, which till now has helped to reduce your taxable income. 18/05/2021 ICMAI<br>
slide31. New Regime The new tax regime is only useful for those who have liquidity problem and are not able to avail full benefits of Section 80 C and who do not have any health insurance as well as do not have any home loan running.
The new regime may be suitable for only a handful of self-employed or an HUF.
The self-employed do not have the choice to come back to old tax regime once the new one is opted unless they stop having business income.
Hence the person with business income has to be very careful while migrating to new regime as it is only one way. 18/05/2021 ICMAI<br>
slide32. Person with business income The new tax regime is optional for tax payers, they can evaluate their tax liability under both regime and can choose more beneficial regime from A.Y.2021-22 or any subsequent year.
However, for the taxpayers having income from business or profession cannot switch between the new tax regime and regular tax regimes every year.
If the taxpayer having income from business or profession opts for the new tax regime, such taxpayers get only one chance in their lifetime to come back to the regular tax regime and will not be eligible for opting new tax regime again, unless the taxpayer’s business income ceases to exist. 18/05/2021 ICMAI<br>
slide33. Assessment proceedings Tax payers are now free to formulate better investment and insurance strategies rather than depending on tax saving instruments for the purpose of saving taxes.
In case of assessment proceedings before the tax authorities, documentation and proof of investments is required to be retained in the old regime, which may not be required in the new regime. 18/05/2021 ICMAI<br>
slide34. Example-General 18/05/2021 ICMAI<br>
slide35. Seniors Please note that the tax rates in the New tax regime is the same for all categories of Individuals,
i.e Individuals & HUF upto 60 years of age,
Senior citizens above 60 years upto 80 years ,
and Super senior citizens above 80 years.
Hence no increased basic exemption limit benefit will be available to senior and super senior citizens in the New Tax regime.
Individuals with Net taxable income less than or equal to Rs 5 lakh will be eligible for tax rebate u/s 87A i.e tax liability will be nil of such individual in both – New and old/existing tax regimes. 18/05/2021 ICMAI<br>
slide36. Example – Senior Citizen 18/05/2021 ICMAI<br>
slide37. Another Example 18/05/2021 ICMAI<br>
slide38. House Property in New Tax Regime In case of a self-occupied property, does not allow to claim a deduction on interest for a housing loan. The deduction of Rs 2 lakh allowed in the existing system is not available in the new tax regime.
Also, the set-off of the loss of Rs 2 lakh from house property from salary income is not allowed.
In case of let-out a house property, the deductions on municipal tax, standard deduction of 30% and interest paid on housing loan is restricted till the rental income.
Hence, the excess interest paid on housing loan will result in loss under the head income from house property.
However, this loss cannot be set-off against any other head of income. Also, cannot carry forward the loss from house property to future years for set off. 18/05/2021 ICMAI<br>
slide39. Sec.115BAD – Co-operative Societies Currently, the co-operative societies are taxed at the slab rates and the highest slab rate is 30% which applies when income exceeds Rs. 20,000.
To bring parity between the co-operative societies and domestic companies, section 115BAD has been proposed to be inserted in Income-tax Act to provide an option to the co-operative societies to get taxed at the rate of 22% plus 10% surcharge and 4% cess. 18/05/2021 ICMAI<br>
slide40. Provisions in brief without providing for specified exemption, deduction or incentive available under the Act.
The societies opting for this section have been kept out of the purview of Alternate Minimum Tax (AMT).
Further, the provision relating to computation, carry forward and set-off of AMT credit shall not apply to these assessees.
Where a co-operative society exercises option for availing benefit of lower tax rate under section 115BAD, it shall not be allowed to claim set-off of any brought forward losses or depreciation attributable to any restricted exemption or deduction in the Assessment Year for which the option has been exercised and for any subsequent Assessment Year. 18/05/2021 ICMAI<br>
slide41. Filing Filing of Form no. 10-IF The Resident Co-Operative Society exercising the option to apply section 115BAD in computing its income is required to furnish in Form no. 10-IF. Such form shall be furnished electronically using the digital signature or Electronic Verification Code(EVC).
************************************************************************** Behind Every Successful Business Decision, There Is Always A CMA<br>